

- Market Size (2026)
- USD 7.4 Bn
- Forecast (2036)
- USD 14.3 Bn
- CAGR (2026 to 2036)
- 6.8%
How big is Coconut Oil Market in 2026?
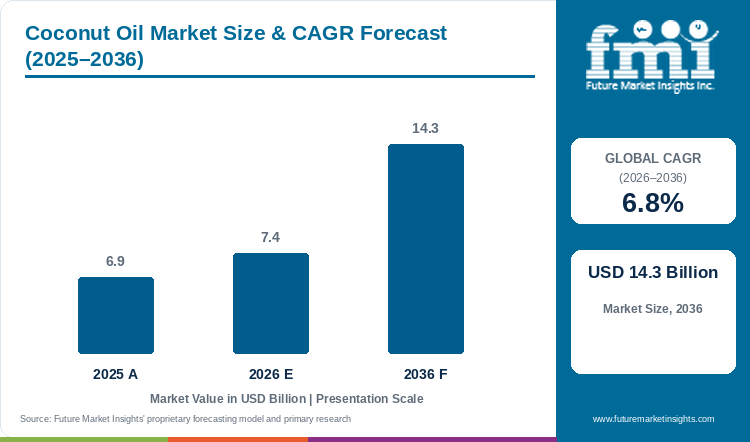
The coconut oil market is expected to increase from USD 6.9 billion in 2025 to USD 7.4 billion in 2026 and reach USD 14.3 billion by 2036. A CAGR of 6.8% is supported by its use across food and beverages, personal care and industrial formulations, although crop movement and biodiesel demand can keep supply and prices uneven.
According to Future Market Insights analysis, commercial food processors and cosmetic formulators face persistent lipid supply constraints, as shifting away from palm kernel oils requires a functional lauric fat that solidifies at ambient temperatures without chemical hydrogenation. Sourcing for specialty vegetable oils fulfills this technical requirement by delivering high lauric acid concentrations for plant-based fats, confectionery coatings, and personal care surfactants. The global coconut oil market stands at USD 6.9 billion in 2025 and rises to USD 7.4 billion in 2026. Industry valuation is projected to reach USD 14.3 billion by 2036, expanding at a 6.8% CAGR and generating USD 6.9 billion in added revenue.
Key Market Trends & Insights
- By nature: Conventional coconut oil led with 73.6% share in 2026, supported by mass availability, cost efficiency, and neutral sensory properties.
- By product type: Virgin or extra virgin oil led with 45.8% share in 2026, driven by minimal processing and clean-label consumer demand.
- By end-use sector: Food and beverages held 57.2% in 2026, remaining the largest consumption base across bakery, confectionery, dairy alternatives, and cooking oils.
- By distribution channel: Business-to-business supply accounted for 65.4% in 2026, anchoring industrial volume through bulk procurement contracts.
Regional Highlights
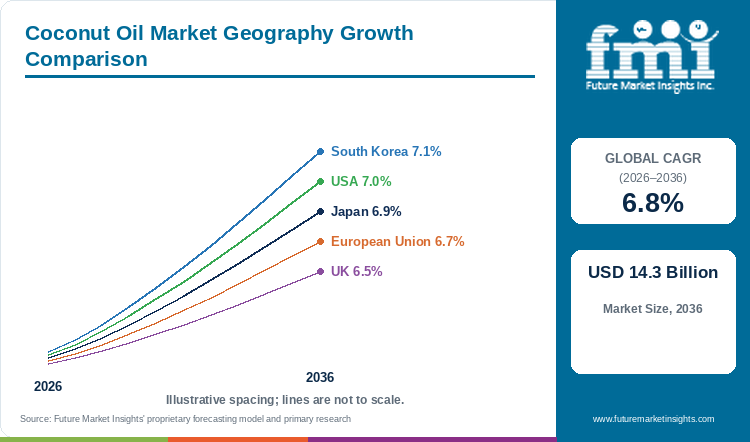
- Fastest-growing disclosed country: South Korea at 7.1% CAGR from 2026 to 2036.
- The USA follows at 7.0%, Japan at 6.9%, the European Union at 6.7%, and the UK at 6.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Coconut Oil Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 6.9 billion |
| Estimated Market Size in 2026 | USD 7.4 billion |
| Projected Market Size by 2036 | USD 14.3 billion |
| CAGR, 2026 to 2036 | 6.8% |
| Added Revenue, 2026 to 2036 | USD 6.9 billion |
Country commercial conditions differ as tropical crushing capacity does not automatically guarantee export availability for international food manufacturers. Copra drying and milling infrastructure must maintain narrow free fatty acid and peroxide thresholds to prevent off-flavor development in refined bakery fats. In government agricultural data, the Philippine Statistics Authority recorded national coconut output at 14.51 million metric tons in 2025 [2]. Procurement teams sourcing certified edible oils and fats establish multi-origin hedging contracts to insulate plant operations from weather disruptions and regional biofuel diversion.
Supply, Processing, and Revenue Sizing
Table 2: Supply and Commercial Sizing Indicators for the Coconut Oil Market, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 6.9 | 7.4 | 14.3 |
| Philippine coconut output (million metric tons) | 14.5 | 14.6 to 14.8 | 15.8 to 16.5 |
| Indicative oil-equivalent throughput (million metric tons) | 3.1 to 3.4 | 3.2 to 3.5 | 4.1 to 4.7 |
| Revenue per oil-equivalent kg (USD) | 2.04 to 2.23 | 2.11 to 2.31 | 3.04 to 3.48 |
Per Capita and Industrial Demand Sizing
The retail jar gives coconut oil visibility, although the larger movement comes through industrial lots used in food, soap and personal care. Refined grades are selected when flavor should not pass into the final product, whereas virgin oil is useful when coconut character itself supports the label. Processing streams yield fractionated medium-chain triglycerides and specialized coconut-derived natural surfactants, improving crush margins while tightening supplies for conventional edible oil buyers.
Table 3: Per Capita Spending Indicators for the Coconut Oil Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.84 | 0.89 | 1.60 |
| Spend per 1,000 people (USD) | 841.5 | 891.2 | 1595.7 |
| Incremental spend per capita (USD) | - | 0.05 | 0.76 |
Table 4: Industrial Channel and Revenue Indicators for the Coconut Oil Market, 2026
| Metric | Value | |
|---|---|---|
| Market size, 2026 | 57.2% share | |
| Food and beverage position | 45.8% share | |
| Virgin / extra virgin position | Leading premium product type | |
| Company cohort | 8 notable suppliers |
Analyst Perspective
“Coconut oil suppliers must pair reliable tropical sourcing with product-grade consistency. Certified traceability and differentiated processing will shape premium contracts across food and personal care.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Coconut Oil Market segmented?
The coconut oil market is segmented by nature, product type, end-use sector, and distribution channel. In 2026, conventional coconut oil is projected at 73.6%, virgin or extra virgin at 45.8%, food and beverages at 57.2%, and business-to-business at 65.4%.
By nature: Organic Coconut Oil; Conventional Coconut Oil.
By product type: Virgin or Extra Virgin; Refined; Partially Hydrogenated.
By end-use sector: Food and Beverages; Cosmetics and Personal Care; Pharmaceutical; Household / Retail; Others.
By distribution channel: Business to Business; Business to Consumer; Hypermarkets / Supermarkets; Traditional Grocery Stores; Convenience Stores; Specialty Stores; Online Retail.
Why does Virgin or Extra Virgin lead the product type category?
Virgin or extra virgin coconut oil represents 45.8% of product type in 2026, balancing minimal processing appeal with strong culinary and cosmetic demand.
Table 5: Product Type Share for the Coconut Oil Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Virgin or Extra Virgin | 45.8% |
| Other Segments Combined | 54.2%* |
| Total | 100.0 |
Table 6: Product Type Leadership and Market Growth for the Coconut Oil Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.8% |
| Leading Segment | Virgin or Extra Virgin |
Virgin or extra virgin coconut oil is projected to hold 45.8% of product type demand in 2026 because cold-pressed extraction preserves natural lauric aroma, essential antioxidants, and distinct culinary flavor without chemical refining. Premium wellness and cosmetic brands formulate virgin oil to substantiate unrefined clean-label claims on retail shelves, justifying higher per-kilogram acquisition costs over standard industrial grades. Nutiva markets cold-pressed organic virgin coconut oil without deodorizing, bleaching, or refining to capture health-conscious culinary buyers [3]. However, elevated price differentials over bulk refined copra oil limit virgin usage in cost-sensitive industrial frying applications.
- Virgin or extra virgin coconut oil represents 45.8% of product type in 2026 because consumers and specialty formulators prioritize cold-pressed purity, natural lauric aroma, and unrefined clean-label positioning.
What keeps Conventional Coconut Oil central by nature?
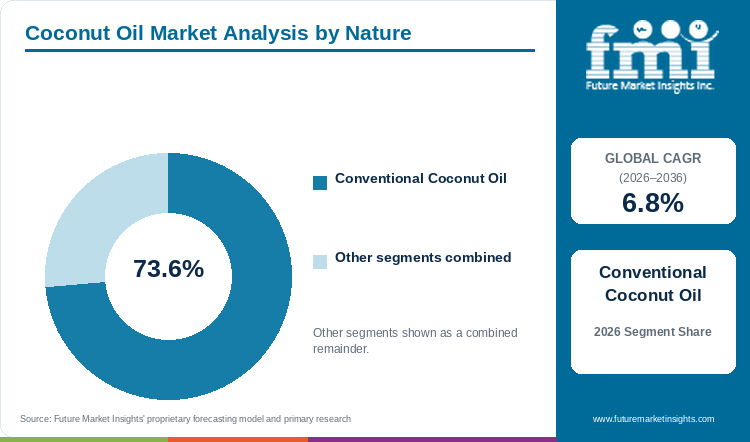
Conventional coconut oil accounts for 73.6% of nature in 2026, supported by cost efficiency, mass availability, and established industrial crushing capacity.
Conventional coconut oil remains central because most industrial users buy performance before they buy a premium claim. Large-scale processors sourcing commercial bakery fats and soap bases require standardized delivery at competitive bulk pricing. Established copra crushing and refining capacity makes conventional oil easier to contract in bulk, while the neutral profile of refined oil allows a manufacturer to use it without altering the finished recipe. Cargill operates across coconut buying, crushing, sourcing, trading and refining [4], providing integrated supply security.
- Conventional coconut oil accounts for 73.6% of nature in 2026 because large-scale food processors, oleochemical plants, and soap manufacturers require standardized bulk deliveries at competitive pricing.
- In 2025, Cargill maintained extensive conventional copra crushing and refining operations across Southeast Asia to secure reliable commercial feedstock [4].
How does Food and Beverages maintain end-use leadership?
Food and beverages holds 57.2% of end-use sector in 2026, driven by extensive utilization across baking, confectionery coatings, and cooking oils.
Food and beverages holds the largest consumption base because coconut oil serves diverse formulation needs without leaving the category. In confectionery fat systems and plant-based dairy alternatives, sharp melting curves deliver clean mouthfeel. Bunge documented Bunge Coco 76 in a 2025 plant-based food concept to support texture and succulence [5]. However, substitution remains possible when coconut oil prices rise significantly above alternative palm kernel fats.
- Food and beverages accounts for 57.2% of end-use sector in 2026 because sharp melting profiles and lauric fat functionality make coconut oil indispensable across confectionery, baking, and dairy-free formulations.
- In 2025, Bunge documented Bunge Coco 76 in a plant-based food concept to support texture and mouthfeel in commercial formulations [5].
Why do Business-to-Business channels control industrial volume?
Business-to-business represents 65.4% of distribution channel in 2026, reflecting direct flexibag logistics, bulk contract procurement, and commercial supply agreements.
Business-to-business supply controls industrial volume because commercial manufacturing plants require certified physical specifications, bulk packaging, and synchronized delivery schedules. In clean beauty formulations and packaged foods, missed deliveries or off-spec free fatty acids disrupt factory uptime. Cargill lists coconut oil supply options ranging from 17-kilogram tins to 20-metric-ton flexibags and isotankers [6]. Such broad delivery scope allows integrated suppliers to satisfy diverse customer scales.
- Business-to-business supply represents 65.4% of distribution channel in 2026 because commercial food and cosmetic processors procure high-volume ingredient lots directly through dedicated industrial supply agreements.
- In 2025, Cargill documented flexible bulk delivery options ranging from 17-kilogram tins to 20-metric-ton flexibags and isotankers for industrial processors [6].
What are the drivers, restraints, and opportunities in the Coconut Oil Market?
Plant-based formulation broadens demand, while crop and freight volatility constrain margins, and traceable premium grades create value across food, wellness, and personal care.
- Driver: Food, beauty, household, and wellness applications create diversified demand across industrial and consumer channels.
- Restraint: Weather-sensitive yields and biodiesel policy can tighten export availability and raise delivered ingredient costs.
- Opportunity: Certified virgin oils, functional fractions, and verified smallholder sourcing support premium product development.
Growth Analysis and Future Potential: Multi-Application Demand Catalysts
Coconut oil demand extends across multiple manufacturing sectors. Bakery producers require refined grades for neutral flavor and crisp melting. Personal care formulators value emollient properties and foaming performance. In oleochemical surfactant bases, natural lauric acid provides superior lather. Government science reporting placed Philippine coconut harvest at 14.5 million metric tons [2]. This supply scale underpins export processing and downstream value addition across global markets.
Risk Assessment of the Coconut Oil Market: Supply and Price Friction
Coconut oil remains vulnerable to raw-material supply shocks that cannot be resolved in a single growing cycle. Typhoons, prolonged droughts, and senile palm trees constrain copra yields before millers can adapt. The USDA projects marginal Philippine copra recovery in 2025/26, but elevated domestic biodiesel blending mandates will absorb local oil supplies, holding export shipments flat [1]. When coconut oil prices rise significantly above alternative palm kernel and soybean oils, industrial food processors reformulate away from coconut fats.
Commercial Opportunity Analysis: Processing Differentiation and Value-Add Formats
Commercial upside centers on value-added fractionation and specialized formulation rather than bulk commodity trading. Virgin oils capture retail premiums through aroma and unrefined positioning, while fractionated MCT oils serve sports nutrition. Nutiva offers virgin, refined, liquid, and culinary formats [3], while Marico introduced an olive-enriched coconut-based hair oil in September 2025 [7]. Differentiating formats enables suppliers to preserve healthy margins against raw copra price swings.
Coconut Oil Market by Country (2026 to 2036)
As per Future Market Insights, South Korea represents the fastest-growing disclosed country market at 7.1% CAGR from 2026 to 2036, while the UK records 6.5%. Across the five covered markets, commercial success depends on premium positioning, clean-label procurement, and reliable imported supply.
Table 7: Country CAGR and Primary Growth Levers for the Coconut Oil Market, 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 7.1% | K-beauty, plant-based wellness, and premium organic retail |
| USA | 7.0% | Natural food, personal care, and functional nutrition demand |
| Japan | 6.9% | Functional foods and high-purity personal care formulations |
| European Union | 6.7% | Organic certification and sustainable ingredient procurement |
| UK | 6.5% | Vegan food, clean beauty, and specialty retail demand |
Source: Future Market Insights analysis
South Korea Coconut Oil Market Outlook (2026 to 2036)
South Korea presents a different route from the global food-led market, advancing at a leading 7.1% CAGR through 2036. Cosmetic formulations, cleansing balms and scalp treatments give coconut oil a higher-value entry point, while wellness retail supports certified virgin grades in premium compact jars. However, complete dependence on imported tropical feedstock exposes domestic cosmetic laboratories to currency fluctuations and maritime freight spikes. Local buyers prioritize deodorized refined grades for beauty bases and traceable virgin oils for organic marketing.
Key takeaway: In South Korea, k-beauty, plant-based wellness, and premium organic retail shape supplier positioning and purchasing outcomes.
USA Coconut Oil Market Outlook (2026 to 2036)
The USA market represents broad multi-sector consumption, supporting a projected 7.0% CAGR through 2036. The ingredient flows simultaneously through natural foods, commercial bakeries, personal care, and functional nutrition channels. Organic extra virgin jars maintain strong retail shelf presence, while refined bulk oils supply dairy-alternative spreads and keto snacks. Ongoing nutritional scrutiny regarding saturated fat limits everyday cooking substitution, keeping demand focused on specialized plant-based and cosmetic formulations.
Key takeaway: In USA, natural food, personal care, and functional nutrition demand shape supplier positioning and purchasing outcomes.
Japan Coconut Oil Market Outlook (2026 to 2036)
Japan is projected to expand at 6.9% CAGR through 2036, rewarding processing discipline and analytical purity over volume. Functional beverages, clinical nutrition, and premium personal care brands enforce strict limits on oxidation parameters, residual moisture, and color variation. This creates stable commercial opportunities for highly refined, neutral-flavor oils and pharmaceutical-grade fractions. Importers establish dedicated quality assurance protocols at origin to eliminate shipment rejections.
Key takeaway: In Japan, functional foods and high-purity personal care formulations shape supplier positioning and purchasing outcomes.
European Union Coconut Oil Market Outlook (2026 to 2036)
European Union demand expands at 6.7% CAGR through 2036, governed by rigorous deforestation due diligence and organic chain-of-custody verification. Processors supplying the EU must provide auditable smallholder origin tracking alongside strict pesticide residue analyses. These regulatory mandates favor established international traders with certified segregated supply chains. Certified organic virgin oils capture premium pricing across specialty bio-retailers, whereas conventional industrial oils face competition from sustainable palm alternatives.
Key takeaway: In European Union, organic certification and sustainable ingredient procurement shape supplier positioning and purchasing outcomes.
UK Coconut Oil Market Outlook (2026 to 2036)
The UK market advances at an estimated 6.5% CAGR through 2036, driven by mature vegan food manufacturing and clean-label cosmetic formulations. Plant-based bakeries and dairy-free cheese producers rely on refined coconut oil to achieve firm melting textures without trans fats. In retail, branded virgin jars face intense price competition from private-label grocery offerings. Suppliers that document ethical sourcing and provide technical bakery support maintain dependable multi-year contracts.
Key takeaway: In UK, vegan food, clean beauty, and specialty retail demand shape supplier positioning and purchasing outcomes.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Coconut Oil Market?
Cargill, ADM, Bunge, Marico, Nutiva, Barlean’s Organic Oils, Celebes Coconut Corporation, and SC Global Coco Products are notable companies operating in this market.
Competition divides by processing integration and customer tier. Global agribusiness conglomerates dominate bulk copra crushing, chemical refining, and multinational supply contracts. Consumer brands compete on cold-pressing claims, virgin aroma, and retail bottle design. Origin-based tropical processors maintain cost advantages near copra collection hubs but must satisfy rigorous international quality specifications to secure direct export agreements.
- Global ingredient processors: Cargill, ADM, and Bunge supply edible or specialty oil solutions for industrial applications.
- Branded consumer platforms: Marico, Nutiva, and Barlean’s market coconut-based food, wellness, or personal care products.
- Origin processors: Celebes Coconut Corporation and SC Global Coco Products connect tropical processing with export demand.
Competitive Benchmarking: Coconut Oil Market
Table 8: Competitive Benchmarking for the Coconut Oil Market (qualitative capability ratings), 2026
| Company | Industrial Oil Breadth | Premium / Certified Formats | Retail / Brand Access | Geographic Reach |
|---|---|---|---|---|
| Cargill | High | High | High | High |
| ADM | High | High | High | High |
| Bunge | High | High | High | High |
| Marico | Medium | High | High | Medium |
| Nutiva | Medium | High | High | Medium |
| Barlean's Organic Oils | Medium | High | Medium | Medium |
| Celebes Coconut Corporation | High | Medium | Medium | Medium |
| SC Global Coco Products | High | Medium | Medium | Medium |
Scoring basis: High indicates broad public evidence of capability across the named dimension. Medium indicates a narrower or more regionally concentrated position. Ratings summarize verified public offerings and do not represent financial market share.
Key Developments in the Coconut Oil Market
- In September 2025, Marico launched Parachute Advansed Olive Enriched Coconut Hair Oil to capture premium personal care demand [7].
- In 2025, Bunge commercialized Bunge Coco 76 for plant-based savory food applications to enhance succulence and mouthfeel [5].
- In 2025, Cargill published its annual sustainability audit documenting expanded smallholder certification programs across Philippine and Indonesian coconut supply chains [8].
Key Players in the Coconut Oil Market
Global Ingredient and Refining Platforms
- Cargill
- ADM
- Bunge
Branded Consumer Coconut Oil Platforms
- Marico
- Nutiva
- Barlean's Organic Oils
Origin-Based Coconut Processors
- Celebes Coconut Corporation
- SC Global Coco Products
Coconut Oil Market - Report Scope
Table 9: Report Scope for the Coconut Oil Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Coverage field | Report scope |
| Market breakdown | Nature; Product Type; End-use Sector; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Supplier revenue from virgin, refined, organic, conventional, and in-scope coconut oil formats sold into food, personal care, pharmaceutical, household, and retail uses. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Disclosed | USA; UK; European Union; Japan; South Korea |
| Key Companies Covered | Cargill; ADM; Bunge; Marico; Nutiva; Barlean’s Organic Oils; Celebes Coconut Corporation; SC Global Coco Products |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with data triangulation. |
Coconut Oil Market - Research Methodology
Table 10: Research Methodology for the Coconut Oil Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with manufacturers, suppliers, distributors, food processors, personal care formulators, industry experts, and key opinion leaders validate demand dynamics and purchasing decisions. |
| Secondary Research | Company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public sources support the assessment. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess revenue, channel demand, price points, and adoption from 2026 to 2036. |
| Data Triangulation and Validation | Data is validated against agricultural output, trade conditions, regulatory changes, end-use demand, and historical trends to improve accuracy. |
Coconut Oil Market by Segments
Coconut Oil Market segmented by Nature:
- Organic Coconut Oil
- Conventional Coconut Oil
Coconut Oil Market segmented by Product Type:
- Virgin or Extra Virgin
- Refined
- Partially Hydrogenated
Coconut Oil Market segmented by End-use Sector:
- Food and Beverages
- Cosmetics and Personal Care
- Pharmaceutical
- Household / Retail
- Others
Coconut Oil Market segmented by Distribution Channel:
- Business to Business
- Business to Consumer
- Hypermarkets / Supermarkets
- Traditional Grocery Stores
- Convenience Stores
- Specialty Stores
- Online Retail
Coconut Oil Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Agriculture, Foreign Agricultural Service. (2025, April 8). Oilseeds and products annual: Philippines (RP2025-0022). Global Agricultural Information Network.
- [2] Philippine Council for Agriculture, Aquatic and Natural Resources Research and Development. (2026). Coconut industry profile and 2025 production statistics. Department of Science and Technology.
- [3] Nutiva. (2026). Organic virgin coconut oil: Product specifications and processing description. Commercial Technical Bulletins.
- [4] Cargill. (2026). Sustainable coconut oil supply chain and sourcing program. Corporate Sustainability Disclosures.
- [5] Bunge. (2025). Plant-based katsu chicken concept featuring Bunge Coco 76. Technical Application Guides.
- [6] Cargill. (2026). Coconut oil: Fats and oils, Asia Pacific product information. Product Specifications.
- [7] Marico Limited. (2025, September 9). Marico launches Parachute Advansed Olive Enriched Coconut Hair Oil. Corporate Press Releases.
- [8] Cargill. (2025). Impact report 2025. Corporate Sustainability Publications.
- [9] Food and Agriculture Organization of the United Nations. (2025). World food and agricultural statistics yearbook: Production and trade of vegetable oils. FAO Statistical Reports.
- [10] U.S. Food and Drug Administration. (2025). Guidance for industry: Tropical oils and food fat labeling. Center for Food Safety and Applied Nutrition.
- [11] ADM. (2025). Global consumer trend report 2025. Industry Trend Briefings.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the coconut oil market in 2026 and what is forecast for 2036?
- Which supply and end-use pressures support coconut oil demand across food and cosmetics?
- Why does virgin or extra virgin oil lead premium product demand?
- Why does food and beverages remain the largest end-use sector?
- How do growth rates differ across South Korea, the USA, Japan, the European Union, and the UK?
- Which companies supply coconut oil across industrial and consumer channels?
- What limits adoption or supplier switching in the coconut oil market?
- What should buyers evaluate before purchasing bulk coconut oil?
Frequently Asked Questions
How big is the coconut oil market in 2026, and what is forecast for 2036?
Future Market Insights estimates the global market at USD 7.4 billion in 2026. It is projected to reach USD 14.3 billion by 2036, expanding at a 6.8% CAGR.
What is the CAGR from 2026 to 2036?
The market is projected to expand at 6.8% CAGR. Growth reflects food, personal care, wellness, and industrial ingredient demand.
Which product type segment leads the coconut oil market?
Future Market Insights projects that virgin or extra virgin coconut oil will hold 45.8% share in 2026. The segment benefits from clean-label appeal, cold-pressed extraction, and minimal processing.
Which end-use sector leads the coconut oil market?
Food and beverages accounts for 57.2% share in 2026, driven by extensive utilization across baking, confectionery coatings, and cooking oils.
Which disclosed country has the fastest growth outlook?
FMI data suggests that South Korea has the country CAGR at 7.1% from 2026 to 2036, driven by k-beauty personal care formulations.
Who are the key players in the market?
Key participants include Cargill, ADM, Bunge, Marico, Nutiva, Barlean’s Organic Oils, Celebes Coconut Corporation, and SC Global Coco Products.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Organic Coconut Oil
- Conventional Coconut Oil
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Virgin or Extra Virgin
- Refined
- Partially Hydrogenated
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End-use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-use Sector, 2026 to 2036
- Food and Beverages
- Cosmetics and Personal Care
- Pharmaceutical
- Household / Retail
- Others
- Y-o-Y Growth Trend Analysis By End-use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Business to Business
- Business to Consumer
- Hypermarkets / Supermarkets
- Traditional Grocery Stores
- Convenience Stores
- Specialty Stores
- Online Retail
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Nature
- By Product Type
- By End-use Sector
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cargill
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- ADM
- Bunge
- Marico
- Nutiva
- Barlean's Organic Oils
- Celebes Coconut Corporation
- SC Global Coco Products
- Cargill
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


