

- Market Size (2026)
- USD 1.2 Bn
- Forecast (2036)
- USD 4.6 Bn
- CAGR (2026 to 2036)
- 14.2%
How big is Conchas & Pan Dulce Market in 2026?
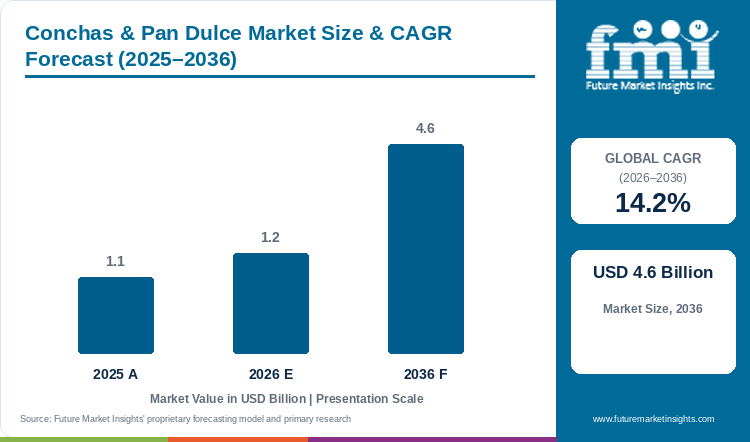
Having recorded a market size of USD 1.1 billion in 2025 and moving to USD 1.2 billion in 2026, the conchas & pan dulce market is projected to scale up to USD 4.6 billion by the end of 2036, maintaining a 14.2% CAGR.
Supermarket in-store bakeries are converting panadería recipes into clamshell multipacks and thaw-and-bake frozen trays, and that format shift decides conchas consumption more than any flavor calendar. The global conchas & pan dulce market was valued at USD 1.1 billion in 2025 and is estimated to reach USD 1.2 billion in 2026. The market is projected to reach USD 4.6 billion by 2036, expanding at a compound annual growth rate (CAGR) of 14.2% between 2026 and 2036. Vanilla conchas are projected to capture 32.0% of 2026 type demand, since white sugar-shell scoring gives bakery cases a universal visual cue at the lowest decoration cost. Demand growth runs roughly three times the bakery products market at 4.5% CAGR, as Hispanic demographic expansion feeds a dedicated perimeter program that ordinary bakery shelves do not carry [1]. The growth in pan dulce consumption is also reflected in corporate commitment, with Grupo Bimbo opening its first El Globo flagship in Mexico City in May 2025 featuring the Concha París and pledging July 2025 to strip artificial colorants from 100% of its global portfolio by end-2026 [2] [3]. Europastry meanwhile reported EUR 1.63 billion in 2025 turnover with a EUR 38 million brioche line at Azuqueca and a EUR 50 million pastry line at Carregado [23]. Shelf owners buy the format that survives 48-hour starch retrogradation without preservative labels, and whoever solves the sugar-shell fracture in transit takes the multipack contracts.
Key Market Trends & Insights
- By product type: Vanilla Conchas are projected to capture 32.0% of the product type segment in 2026 because white sugar-shell scoring provides universal visual recognition.
- By claim / nature: Conventional formulations are estimated to command 50.0% of the claim / nature segment in 2026 as egg-and-butter enriched doughs set the sensory benchmark.
- By format: Fresh bakery units are expected to concentrate 33.0% of the format segment in 2026 because same-day crumb softness drives impulse basket additions.
- By packaging format: Multipack configurations are forecast to generate 33.0% of the packaging format segment in 2026 owing to protective thermoformed trays for family breakfast sharing.
- By sales channel: Supermarkets & Hypermarkets are anticipated to account for 38.0% of the sales channel segment in 2026 through consolidated weekly grocery trips.
Regional Highlights
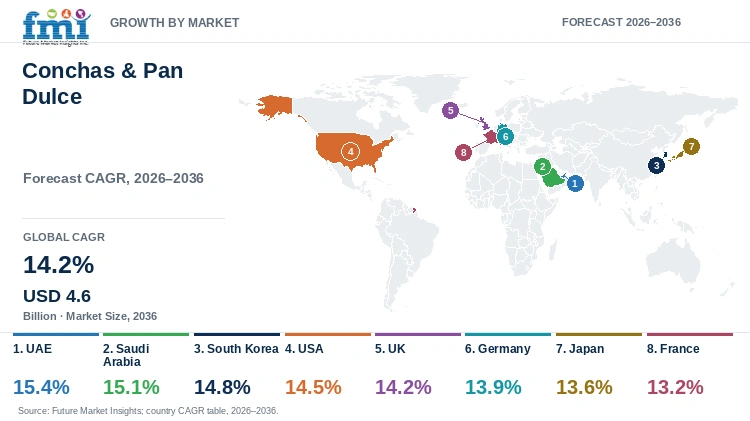
- Top national expansion: The UAE is projected to lead national growth at a 15.4% CAGR through 2036 under hospitality café imports and multicultural retail expansion.
- Broader country progression: Saudi Arabia is expected to expand at a 15.1% CAGR ahead of South Korea at 14.8% and the USA at 14.5%, while France is forecast to advance at a 13.2% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Conchas & Pan Dulce Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.1 billion |
| Estimated Market Size in 2026 | USD 1.2 billion |
| Projected Market Size by 2036 | USD 4.6 billion |
| CAGR, 2026 to 2036 | 14.2% |
| Added Revenue, 2026 to 2036 | USD 3.4 billion |
Shortages of skilled night-shift panaderos are pushing grocery in-store bakeries and café chains to replace scratch dough mixing with centralized frozen dough supply. However, ice crystal growth during frozen storage damages wheat gluten networks and causes the decorative sugar-shortening shell to detach from the bun during final baking. To solve that exact structural failure, an August 2026 rheological study published in Food Chemistry demonstrated that adding 0.6% guar gum into frozen wheat dough preserved starch crystallinity across eight freeze-thaw cycles and lowered baked crumb hardness from 3046.17 N to 2013.07 N [4]. Hydrocolloid stabilization is therefore enabling commercial bakeries to ship pre-topped frozen baked goods that bake uniformly in retail convection ovens without skilled labor.
Household Consumption and Bakery Unit-Volume Sizing
Table 2: Household Consumption and Unit-Volume Sizing for the Conchas & Pan Dulce Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.1 | 1.2 | 4.6 |
| Commercial concha & pan dulce units sold (million pieces) | 1,180 to 1,310 | 1,330 to 1,480 | 4,550 to 5,050 |
| Finished bakery weight volume (thousand MT) | 112.0 to 124.5 | 126.5 to 140.6 | 432.0 to 479.8 |
| Average manufacturer realization per piece (USD) | 0.82 to 0.92 | 0.84 to 0.95 | 0.92 to 1.05 |
Operational note: Unit-volume ranges apply standardized 77-gram raw-frozen and 95-to-113-gram finished-baked concha piece weights across retail multipacks and foodservice cases.
Production scale-up from neighborhood bakery ovens to high-speed industrial lines requires automating how the 18%-to-22% sugar-and-shortening pasta cap is applied onto proofed dough while protecting gluten elasticity during freezing. A February 2025 study in the International Journal of Biological Macromolecules confirmed that adding Dendrobium officinale polysaccharide mitigated disulfide bond cleavage in frozen wheat dough and improved baked loaf specific volume [5], supporting industrial producers that combine long-fermented artisan bread sponge systems with rotary crust-stamping depositors.
Per Capita & Retail Bakery Outlet Indicators
Table 3: Per Capita and Outlet Spending Indicators for the Conchas & Pan Dulce Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per 1,000 people (USD) | 130.0 | 146.6 | 510.2 |
| Annual wholesale spend per retail bakery outlet (USD) | 3,100 to 3,550 | 3,450 to 3,950 | 10,800 to 12,400 |
| Modern grocery & multipack contract share (%) | 54.0% to 58.0% | 56.0% to 60.0% | 65.0% to 69.0% |
Table 4: Retail & Bakery Outlet Spending Indicators for the Conchas & Pan Dulce Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 1.2 billion | 2026 global valuation baseline |
| Stocking grocery & panadería outlets | 335,000 outlets | Global supermarket, convenience, and specialty bakery registry |
| Market spend per stocking outlet | USD 3,632.8 | Annualized wholesale pan dulce turnover per outlet |
| Supermarket & hypermarket allocation, 2026 | USD 0.5 billion | 38.0% sales-channel segment allocation |
Ambient shelf-life extension is critical for manufacturers supplying regional grocery distribution centers where products sit in transit for several days. A January 2025 baking formulation study in Foods showed that blending tiger nut flour into soft wheat dough improved crumb moisture retention and lipid stability [6], helping commercial bakeries pair barrier flow-wrapping with enzyme systems proven in pound and loaf cakes to keep packaged conchas saleable for up to 21 days.
Analyst Perspective
"National supermarket shelf placement in the conchas and pan dulce market requires solving two mechanical problems: keeping the sugar-shell topping intact through palletized warehouse transit and retarding crumb staling without artificial preservatives. Bakers that supply crush-protected multipacks and bake-off-ready frozen dough units will capture mainstream retail growth beyond traditional neighborhood panaderías."
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the conchas & pan dulce market segmented?
The conchas & pan dulce market is segmented by product type, claim / nature, format, packaging format, and sales channel. In 2026, Vanilla Conchas is projected at 32.0%, Conventional at 50.0%, Fresh at 33.0%, Multipack at 33.0%, and Supermarkets & Hypermarkets at 38.0%.
By product type: Vanilla Conchas, Chocolate Conchas, Assorted Pan Dulce, and Mini & Seasonal.
By claim / nature: Conventional, Clean Label, Organic, Gluten-Free, and High-Protein / Fortified.
By format: Fresh, Frozen, Ambient Packaged, Chilled, and Par-Baked / Thaw-and-Serve.
By packaging format: Multipack, Single-Serve, Family / Loaf Pack, and Bulk Foodservice.
By sales channel: Supermarkets & Hypermarkets, Artisan & Specialty Bakeries, Convenience & Forecourt, Online & DTC, and Foodservice Distributors.
Why do Vanilla Conchas lead the product type segment?
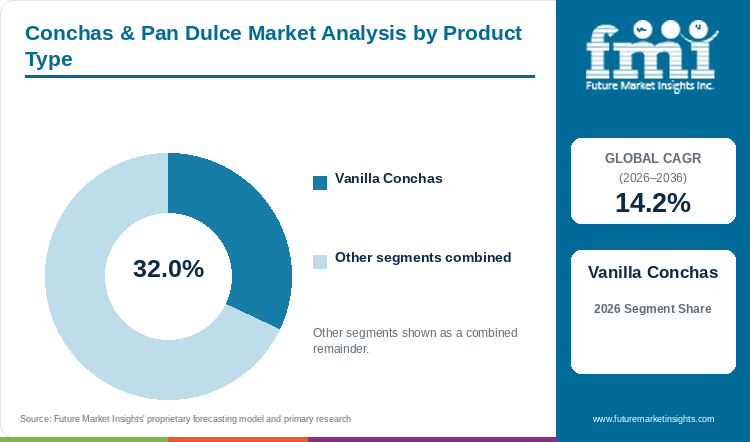
Vanilla Conchas are projected to capture 32.0% of the product type segment in 2026, supported by mainstream flavor familiarity.
Table 5: Product Type Share for the Conchas & Pan Dulce Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Vanilla Conchas | 32.0% |
| Other Segments Combined | 68.0%* |
| Total | 100.0% |
*Note: Remaining product type subsegments sum to 100.0% of 2026 conchas & pan dulce demand.
Table 6: Product Type Leadership and Market Growth for the Conchas & Pan Dulce Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 14.2% |
| Leading Segment | Vanilla Conchas |
Retail grocery buyers consistently select Vanilla Conchas as their core SKU when opening a Latin sweet-bakery section because white vanilla sugar shells appeal to both traditional Hispanic shoppers and first-time trial buyers. From a plant efficiency standpoint, neutral vanilla streusel runs continuously on topping extruders using standardized bakery mixes without the line washdowns required after dark cocoa or colored batches.
- Vanilla Conchas are projected to account for 32.0% of the product type segment in 2026 because broad household appeal minimizes retail unsaleable shrink.
- In May 2025, Grupo Bimbo inaugurated its first El Globo flagship store in Mexico City featuring the signature Concha París and fine pastry lines to elevate specialty pan dulce retail merchandising [2].
Why does Conventional define the largest claim / nature segment?
Conventional formulations are estimated to secure 50.0% of the claim / nature segment in 2026, driven by authentic enriched-crumb texture.
Consumer repeat purchases in the pan dulce category depend on achieving a feathery brioche-style crumb beneath a crisp sugar crust, which relies on conventional wheat gluten and whole-egg emulsification. When formulators attempt to replace wheat flour with pulse proteins or gluten-free starches without specialized bakery ingredients, dough gas retention drops and produces a dense loaf that traditional shoppers reject.
- Conventional options are estimated to command 50.0% of the claim / nature segment in 2026 as shoppers judge conchas on authentic panadería softness.
- A September 2026 study in Foods evaluating faba bean protein concentrate and isolate in gluten-free bread confirmed that protein isolate substitution reduced specific volume from 3.29 mL/g to 1.85 mL/g and increased crumb hardness [7].
What keeps Fresh ahead in the format segment?
Fresh products are expected to command 33.0% of the format segment in 2026, reflecting warm perimeter bakery counter appeal.
Self-service bakery display cases where shoppers use tongs to pick warm pastries remain the primary traffic driver for both independent panaderías and supermarket perimeter bakeries. Daily baking of fresh batches each morning paired with par-baked bread rolls creates visible crust sheen and sweet vanilla aroma that convert higher impulse sales than ambient bagged shelves.
- Fresh is expected to hold 33.0% of the format segment in 2026 because point-of-sale visual inspection and aroma drive immediate basket conversion.
- In May 2026, Grupo Bimbo released its 2025 Integrated Annual Report confirming that 98% of its daily consumption bread and bun portfolio achieved Positive Nutrition standards while 100% eliminated artificial colorants [8].
Why does Multipack lead the packaging format segment?
Multipack formats are forecast to generate 33.0% of the packaging format segment in 2026, owing to crush-resistant household tray design.
Container geometry directly determines whether commercial bakeries can ship conchas through centralized grocery warehouses without high unsaleable returns. While loose single-serve bags allow the brittle sugar shell to shatter during case stacking, rigid 4-count and 6-count thermoformed clamshell Multipack trays suspend each concha in a separate cavity and raise average retail basket value.
- Multipack is forecast to account for 33.0% of the packaging format segment in 2026 because compartmented trays protect delicate streusel toppings during home transport.
- In June 2025, Grupo Bimbo reported under its Zero Waste sustainability strategy that 94% of its global bakery packaging achieved recyclable status on the path toward 100% recyclable or biodegradable packs [9].
What gives Supermarkets & Hypermarkets the leading position in the sales channel segment?
Supermarkets & Hypermarkets are anticipated to account for 38.0% of the sales channel segment in 2026, reinforced by perimeter bake-off expansion.
Supermarkets & Hypermarkets capture the largest share of category sales because national grocery chains combine in-store bake-off tables with branded packaged end-caps beside tortillas and Hispanic dairy items. Consolidated weekly grocery shopping allows supermarkets to move high volumes of multi-count family packs across suburban neighborhoods that lack standalone artisan panaderías.
- Supermarkets & Hypermarkets are anticipated to capture 38.0% of the sales channel segment in 2026 because weekly grocery foot traffic drives recurring household purchases.
- A May 2026 study in Foods demonstrated that adding 6% resistant dextrin to wheat matrices reduced 14-day starch retrogradation from 57.2% to 48.6%, extending softness across supermarket shelf cycles [10].
What are the drivers, restraints, and opportunities in the conchas & pan dulce market?
In the conchas & pan dulce market, demographic expansion and supermarket perimeter bake-off programs propel commercial volume whereas 48-hour starch retrogradation and sugar-shell fracture restrain long-distance shipping and cryo-stabilized frozen doughs create foodservice growth opportunities.
- Driver: Mainstream grocery assortment expansion and cross-cultural coffee-and-pastry occasions convert conchas into year-round retail staples.
- Restraint: Rapid crumb staling and sugar-crust detachment during transit slow cross-border scaling.
- Opportunity: Hydrocolloid-stabilized frozen raw and pre-baked conchas unlock zero-skill bake-off programs across cafés and convenience chains.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
National supermarket chains and coffeehouse operators are expanding Hispanic sweet-bakery assortments to capture higher morning-daypart check averages. Unlike seasonal holiday breads, conchas and assorted pan dulce operate as daily breakfast and afternoon merienda staples that generate high repeat purchase frequency. FMI retail audits show that grocers pairing fresh perimeter bake-off tables with branded packaged aisles achieve higher category velocity than stores relying on dry shelf goods alone, mirroring merchandising patterns in frozen bagels. In July 2025, Grupo Bimbo committed to removing artificial colorants across 100% of its global portfolio by the end of 2026 while noting that 99% of its core bread and breakfast items already exclude artificial dyes [3]. Conversion of decorative yellow and pink concha sugar shells to natural botanical colorants unlocks clean-label placement across premium grocery chains.
Risk Assessment of the Conchas & Pan Dulce Market: Operational and Formulation Friction
Mechanical fragility of the fat-sugar pasta topping and rapid moisture equilibration between the crumb and crust represent the primary operational barriers restricting long-distance trade. When packaged conchas encounter high ambient humidity, water vapor migrates outward from the 35%-moisture bread crumb into the 5%-moisture sugar shell, turning the crisp streusel sticky and prone to delaminating inside the wrapper. A December 2025 Mixolab and FTIR study published in Foods demonstrated that enriching wheat buns with phenolic-rich botanical pomace above 10% shortened dough development time while impairing starch gelatinization and bun shape [11]. Bakers attempting to fortify pan dulce or extend shelf life beside dry cake rusks face narrow rheological tolerances and high retail chargebacks for crushed toppings.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Commercial bakeries unlock high-margin foodservice and export growth by engineering cryo-protected frozen unbaked and fully baked thaw-and-serve conchas. Independent cafés and convenience forecourts lack artisan panaderos capable of mixing enriched doughs and hand-scoring streusel caps at 4:00 AM. Frozen dough pieces formulated with modified cassava starches and natural polysaccharides prevent ice recrystallization during transoceanic container shipping. In November 2025, a Food Chemistry study from Jiangnan University confirmed that acetylated distarch adipate (DS 0.054) lowered frozen-dough water separation to 9.67% after freeze-thaw cycling while lifting tightly bound water by 53% and storage modulus by 42% [12]. Shipment of 24-count frozen foodservice cases that bake to a uniform blister-free shell in 14 minutes enables industrial suppliers to penetrate international café networks.
Conchas & Pan Dulce Market by Country (2026 to 2036)
As per FMI, the UAE is projected to lead conchas & pan dulce expansion across evaluated national markets at a 15.4% CAGR through 2036, whereas France is forecast to advance at a 13.2% CAGR. Commercial growth across Middle Eastern hospitality hubs and East Asian or Western European bake-off counters depends on frozen cold-chain integrity and local allergen-labeling compliance.
Table 7: Country CAGR and Primary Growth Levers for the Conchas & Pan Dulce Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| UAE | 15.4% | USD 17.7 billion consumer-food import base and grocery retail expansion |
| Saudi Arabia | 15.1% | USD 57 billion retail food expansion and SFDA menu nutrition transparency rules |
| South Korea | 14.8% | 98.04% worked-grain TRQ fill rates and specialty café frozen pastry adoption |
| USA | 14.5% | 68 million Hispanic demographic base and 5.3 million Hispanic-owned businesses |
| UK | 14.2% | October 2025 HFSS multipack promotion rules and world-bakery bay expansion |
| Germany | 13.9% | Frozen thaw-and-serve adoption across the United Kingdom grocery retail sector |
| Japan | 13.6% | Single-serve convenience bakery rotation across USD 174 billion processing sector |
| France | 13.2% | 2% in-store food retail growth and European frozen-brioche line investments |
Source: Future Market Insights analysis
UAE Conchas & Pan Dulce Market Outlook (2026 to 2036)
Sales of conchas & pan dulce in the UAE are projected to expand at a leading 15.4% CAGR from 2026 to 2036 across hotel cafés and gourmet supermarkets. Record international tourism and a large expatriate hospitality sector make Dubai and Abu Dhabi reliant on frozen bake-off pastry imports that protect sugar-shell toppings from Gulf humidity. An October 2026 USDA Foreign Agricultural Service report tracked UAE consumer-oriented agricultural imports at USD 17.7 billion, the purchasing base under conchas refrigerated-case expansion. High refrigerated air-freight rates still favor container-shipped frozen bake-off concha doughs across luxury hotel kitchens.
Key takeaway: In the UAE, USD 17.7 billion consumer-food imports are projected to drive frozen bake-off concha adoption.
Saudi Arabia Conchas & Pan Dulce Market Outlook (2026 to 2036)
Rapid coffee-shop proliferation and mandatory Arabic-language menu and allergen disclosures shape imported sweet-bakery onboarding in Saudi Arabia. Commercial conchas & pan dulce revenue in Saudi Arabia is forecast to climb at a 15.1% CAGR between 2026 and 2036 across Riyadh and Jeddah retail chains. According to an August 2026 USDA Foreign Agricultural Service report, food retail sales in Saudi Arabia reached USD 57 billion in 2025 while US retail food exports to the Kingdom rose 22% in the first half of 2026 [15]. In June 2025, the Saudi Food and Drug Authority announced new food transparency and menu labeling rules [16], requiring bakery suppliers to provide verified nutrition records and crush-resistant multipacks.
Key takeaway: In Saudi Arabia, SFDA menu transparency rules and USD 57 billion grocery turnover are forecast to accelerate halal-certified multipack concha listings.
South Korea Conchas & Pan Dulce Market Outlook (2026 to 2036)
Trend-driven café culture and high convenience-store density in South Korea create a receptive urban channel for visually distinctive Mexican sweet breads. An October 2026 USDA Foreign Agricultural Service update on the KORUS Free Trade Agreement documented that worked cereal grain imports reached 98.04% of their agricultural safeguard trigger level amid strong domestic bakery demand [17]. Demand for conchas & pan dulce in South Korea is estimated to advance at a 14.8% CAGR from 2026 through 2036 across metropolitan Seoul bakery cafés and online grocery platforms. Tight grain tariff-rate quotas and strict imported allergen disclosures nonetheless encourage domestic foodservice distributors to bring in finished frozen pre-scored concha cases.
Key takeaway: In South Korea, café dessert innovation and 98.04% worked-grain quota use are estimated to support 14.8% CAGR expansion for frozen conchas.
USA Conchas & Pan Dulce Market Outlook (2026 to 2036)
Unlike export markets where pan dulce remains a novelty pastry, the USA operates a mature dual-channel ecosystem spanning neighborhood panaderías and national supermarket chains. In August 2025, the United States Census Bureau reported 68 million Hispanic residents across the country [1], and a November 2025 Census release documented 5.3 million Hispanic-owned nonemployer businesses generating USD 244.2 billion in annual receipts [18]. That entrepreneurial and consumer density enables national grocers to convert regional panadería favorites into year-round clamshell multipacks, though long-haul staling losses still pressure distributor margins. Commercial conchas & pan dulce turnover in the USA is anticipated to rise at a 14.5% CAGR between 2026 and 2036.
Key takeaway: In the USA, a 68 million Hispanic consumer base and nationwide supermarket bake-off programs are anticipated to anchor recurring multipack volume.
UK Conchas & Pan Dulce Market Outlook (2026 to 2036)
The UK is projected to record a 14.2% CAGR in the conchas & pan dulce market from 2026 to 2036 across national supermarket world-food bakery aisles and urban specialty coffee chains. Major grocery retailers in London and Manchester now test international sweet-bakery formats to differentiate in-store bakery counters while managing persistent shop-floor labor deficits. In October 2025, the UK Department of Health and Social Care updated its implementation guidance restricting volume-price and store-entrance promotions for high-fat and sweet bakery products in England [19]. Those promotional restrictions and prepacked-for-direct-sale allergen labeling obligations compel commercial bakery suppliers to offer portion-controlled mini concha multipacks with compliant front-of-pack nutrition profiles.
Key takeaway: In the UK, October 2025 HFSS promotional rules and world-bakery merchandising are projected to sustain 14.2% CAGR growth in mini multipacks.
Germany Conchas & Pan Dulce Market Outlook (2026 to 2036)
Skilled baker shortages across artisan shops in Germany make frozen pre-topped dough pieces the primary commercial route for introducing labor-intensive Mexican pastries into metropolitan cafés. Commercial retail and foodservice sales of conchas & pan dulce in Germany are expected to climb at a 13.9% CAGR over the 2026 to 2036 forecast period. In October 2026, the USDA Foreign Agricultural Service valued the United Kingdom retail grocery market at USD 343 billion in 2026 with growth toward USD 404 billion by 2031, the supermarket bake-off base carrying frozen concha listings [25]. High commercial oven energy costs and strict artisan crust expectations nonetheless require frozen pastry suppliers to prove zero topping separation after rack-oven baking.
Key takeaway: In Germany, back-of-house bakery labor constraints and frozen bake-off infrastructure are expected to favor thaw-and-bake concha formats.
Japan Conchas & Pan Dulce Market Outlook (2026 to 2036)
Widespread consumer familiarity with cookie-crusted melonpan in Japan lowers sensory trial barriers for seashell-scored Mexican conchas across urban convenience stores and train-station bakeries. An April 2026 USDA Foreign Agricultural Service report confirmed that the USD 174 billion food processing sector in Japan recorded steady growth in frozen foods and shelf-stable convenience items during 2025 [21]. Commercial turnover in the Japan conchas & pan dulce market is slated to expand at a 13.6% CAGR from 2026 to 2036 across ambient single-serve pillow pouches and urban specialty café counters. Strict national food-labeling statutes and low retailer tolerance for scuffed streusel shells still require precision flow-wrapping and localized portion sizing.
Key takeaway: In Japan, structural similarity to cookie-topped melonpan and convenience-store single-serve demand are slated to support specialty concha adoption.
France Conchas & Pan Dulce Market Outlook (2026 to 2036)
Dense domestic boulangerie-pâtisserie competition in France requires concha suppliers to position enriched Mexican sweet breads as a differentiated brioche-style coffee accompaniment. In June 2026, INSEE reported that in-store food retail sales in France rose nearly 2% in volume during 2025 while total commercial volume grew 1.5% in Q1 2026 [22]. In March 2026, Europastry reported EUR 1.63 billion in 2025 revenue (+8% year-on-year) while investing EUR 38 million in a new brioche line in Spain and EUR 50 million in a Portugal pastry facility serving European chains [23]. Revenue in the France conchas & pan dulce market is forecast to grow at a 13.2% CAGR from 2026 to 2036.
Key takeaway: In France, European frozen-brioche manufacturing investments and urban café menu diversification are forecast to support niche pan dulce placement.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the conchas & pan dulce market?
Gruma, Mission Foods, Ole Mexican Foods, Toufayan Bakeries, Kontos Foods, FGF Brands, Signature Flatbreads, Angel Bakeries, Grupo Bimbo, and Europastry are the notable companies evaluated in this market.
FMI analysis indicates that market participation separates into direct industrial concha and pan dulce manufacturers, commercial sweet-bakery specialists, and Hispanic or specialty bread distribution platforms. Grupo Bimbo operates verified packaged vanilla concha lines in Mexico and frozen concha catalogs in North America, whereas adjacent sweet-goods and tortilla companies offer distribution or bakery-line scale without verified standalone concha SKUs.
- Verified Concha & Pan Dulce Producer: Grupo Bimbo manufactures branded packaged conchas, artisan El Globo conchas, and 77-gram raw-frozen as well as 113-gram finished-frozen foodservice concha cases.
- Commercial Sweet-Bakery & Frozen-Pastry Platforms: FGF Brands and Europastry along with Kontos Foods operate high-capacity sweet bakery and frozen pastry lines with adjacent process capability.
- Hispanic Grocery & Specialty Bread Platforms: Gruma, Mission Foods, and Ole Mexican Foods paired with Toufayan Bakeries, Signature Flatbreads, and Angel Bakeries anchor Hispanic grocery aisles without verified concha SKUs.
Competitive Benchmarking: Conchas & Pan Dulce Market
Table 8: Competitive Benchmarking for the Conchas & Pan Dulce Market (qualitative capability ratings), 2026
| Company | Concha Product Evidence | Sweet Goods Capability | Frozen / Thaw Format | Geographic Reach |
|---|---|---|---|---|
| Gruma | Unscored | Unscored | Unscored | Mexico, Americas, Europe, and Asia-Pacific tortilla channels |
| Mission Foods | Unscored | Unscored | Unscored | United States and international Hispanic grocery retail |
| Ole Mexican Foods | Unscored | Unscored | Unscored | United States Mexican food retail and foodservice |
| Toufayan Bakeries | Unscored | Medium | Unscored | United States packaged supermarket bakery channels |
| Kontos Foods | Unscored | Medium | Unscored | United States specialty foodservice and retail bakery |
| FGF Brands | Unscored | High | Unscored | United States and Canada commercial sweet bakery plants |
| Signature Flatbreads | Unscored | Medium | Unscored | UK and India bakery manufacturing and export network |
| Angel Bakeries | Unscored | Unscored | Medium | Israel and international frozen/packaged bread channels |
| Grupo Bimbo | High | High | High | Mexico, USA, Latin America, Europe, and Asia bakery networks |
| Europastry | Unscored | High | High | Europe and Americas frozen sweet pastry and brioche distribution |
Scoring basis: Concha Product Evidence is rated High only where named packaged and frozen concha SKUs are publicly verified. Sweet Goods Capability and Frozen / Thaw Format reflect documented sweet-bakery and frozen-dough manufacturing infrastructure; Unscored entries denote no verified public concha SKU rather than an absence of general baking capability.
Key Developments in the Conchas & Pan Dulce Market
- Grupo Bimbo opened its first El Globo flagship store in Mexico City in May 2025 featuring the Concha París and committed in July 2025 to removing artificial colorants across 100% of its global portfolio by the end of 2026 [2] [3].
- Europastry reported EUR 1.63 billion in 2025 turnover (+8% year-on-year) in March 2026 while investing EUR 38 million in a new brioche line at Azuqueca de Henares and EUR 50 million in a Carregado pastry line in Portugal [23].
- Gruma released third-quarter 2026 operating results in October 2026 documenting resilient demand for its Better-for-You and Hispanic grocery lines across North America and Europe [24].
Key Players in the Conchas & Pan Dulce Market
Directly Documented Concha and Pan Dulce Offerings
- Grupo Bimbo
Adjacent Sweet Bakery and Frozen Pastry Platforms
- FGF Brands
- Europastry
- Kontos Foods
Adjacent Tortilla, Flatbread, and Broader Bread Platforms
- Gruma
- Mission Foods
- Ole Mexican Foods
- Toufayan Bakeries
- Signature Flatbreads
- Angel Bakeries
Conchas & Pan Dulce Market - Report Scope
Table 9: Report Scope for the Conchas & Pan Dulce Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Claim / Nature; Format; Packaging Format; Sales Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer and in-store bakery revenue from named conchas and traditional Mexican pan dulce sold across fresh, frozen, ambient packaged, chilled, and par-baked formats. Category Scope Note: Excludes savory corn and flour tortillas, pita and flatbreads, non-Mexican croissants or cakes, and café beverage sales. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UAE, Saudi Arabia, South Korea, USA, UK, Germany, Japan, France, and additional countries in the full report |
| Key Companies Covered | Gruma, Mission Foods, Ole Mexican Foods, Toufayan Bakeries, Kontos Foods, FGF Brands, Signature Flatbreads, Angel Bakeries, Grupo Bimbo, Europastry |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Conchas & Pan Dulce Market - Research Methodology
Table 10: Research Methodology for the Conchas & Pan Dulce Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with industrial panadería production managers, supermarket in-store bakery buyers, frozen-dough cold-chain distributors, and packaging engineers to validate streusel-shell damage rates and multipack velocity. |
| Secondary Research | Audit of United States Census Bureau demographic series, USDA Foreign Agricultural Service GAIN retail and food-processing filings, peer-reviewed frozen-dough and bread-staling studies indexed in PubMed, and corporate annual disclosures. |
| Market Sizing and Forecasting | Bottom-up unit-volume models tracking 77-gram raw-frozen and 95-to-113-gram finished concha equivalents across 24-unit foodservice cases and 4-to-6-count retail clamshells reconciled against top-down sweet-bakery valuation in USD billion from 2025 to 2036. |
| Country Forecasting Model | Econometric national projections weight Hispanic and expatriate population density, supermarket bake-off penetration, imported-food allergen registration rules, and cold-chain logistics costs across eight national markets. |
| Operational Benchmark Traceability | Unit-volume and outlet spending indicators in Tables 2, 3, and 4 trace to United States Census Bureau population estimates, USDA FAS retail food reports, and peer-reviewed wheat-starch retrogradation and freeze-thaw trials. |
| Data Triangulation and Validation | Commercial sales estimates isolate verified concha and pan dulce SKUs from parent corporate tortilla, flatbread, and general bread revenues to prevent category double counting. |
Conchas & Pan Dulce Market by Segments
Conchas & Pan Dulce Market segmented by Product Type:
- Vanilla Conchas
- Chocolate Conchas
- Assorted Pan Dulce
- Mini & Seasonal
Conchas & Pan Dulce Market segmented by Claim / Nature:
- Conventional
- Clean Label
- Organic
- Gluten-Free
- High-Protein / Fortified
Conchas & Pan Dulce Market segmented by Format:
- Fresh
- Frozen
- Ambient Packaged
- Chilled
- Par-Baked / Thaw-and-Serve
Conchas & Pan Dulce Market segmented by Packaging Format:
- Multipack
- Single-Serve
- Family / Loaf Pack
- Bulk Foodservice
Conchas & Pan Dulce Market segmented by Sales Channel:
- Supermarkets & Hypermarkets
- Artisan & Specialty Bakeries
- Convenience & Forecourt
- Online & DTC
- Foodservice Distributors
Conchas & Pan Dulce Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] United States Census Bureau. (2025, August 27). National Hispanic Heritage Month: 2025. U.S. Department of Commerce, Facts for Features CB25-FF.07.
- [2] Grupo Bimbo, S.A.B. de C.V. (2025, May 6). El Globo inaugura su primera flagship store en la CDMX. Grupo Bimbo Official Press Room.
- [3] Grupo Bimbo, S.A.B. de C.V. (2025, July 29). We are committed to removing artificial colorants from all our products by the end of 2026. Grupo Bimbo Press Releases.
- [4] Xie, D., Zheng, J., Li, X., & Zhao, L. (2026, August 26). Guar gum mitigates freeze-thaw damage in wheat starch through multi-scale structural preservation and improves Chinese steamed bread quality. Food Chemistry, 527, 150868 (PubMed PMID 42673862).
- [5] Su, J.-P., Fang, J.-Q., Liu, C., Liu, S.-P., Tan, C.-P., Wang, P.-P., Fu, X., & Chen, C. (2025, February 6). Alleviative effects of Dendrobium officinale polysaccharide on the quality deterioration of frozen dough and corresponding bread. International Journal of Biological Macromolecules, 304(Pt 1), 140705 (PubMed PMID 39920928).
- [6] Nedviha, S., & Harasym, J. (2025, January 13). Characteristics of Soft Wheat and Tiger Nut (Cyperus esculentus) Composite Flour Bread. Foods, 14(2), 229 (PubMed PMID 39856895).
- [7] Keyes, P., Nyhan, L., Gallagher, E., Zannini, E., & Arendt, E. K. (2026, September 26). Comparative Effects of Faba Bean Flour, Protein Concentrate and Protein Isolate on Gluten-Free Bread Quality: Insights from Techno-Functional Properties. Foods, 15(19), 3440 (PubMed PMID 42883547).
- [8] Bimbo Bakeries USA. (2026, May 15). Grupo Bimbo Releases 2025 Annual Report. Bimbo Bakeries USA News and Press.
- [9] Grupo Bimbo, S.A.B. de C.V. (2025, June 5). Grupo Bimbo reports progress in its sustainability strategy. Grupo Bimbo Press Releases.
- [10] Sun, Y., Wang, L., Li, Y., Bai, X., Yang, R., Wang, L., & Cao, R. (2026, May 7). Molecular Interactions of Resistant Dextrin with Wheat Starch and Gluten: Structural Dynamics and Macromolecular Network Formation. Foods, 15(10), 1620 (PubMed PMID 42195822).
- [11] Dvořáček, V., Jágr, M., Jelínek, M., Jurkaninová, L., & Fraňková, A. (2025, December 10). Processing-Induced Changes in Phenolic Composition and Dough Properties of Grape Pomace-Enriched Wheat Buns. Foods, 14(24), 4256 (PubMed PMID 41464964).
- [12] Zhang, T., Fan, M., Qian, H., Wang, L., & Li, Y. (2025, November 15). Structural and functional properties of acetylated distarch adipate with varying degrees of substitution: Impact on freeze-thaw stability of frozen dough. Food Chemistry, 492(Pt 3), 145604 (PubMed PMID 40684562).
- [13] Government of Dubai Media Office. (2026, February 9). Dubai's tourism industry achieves third successive record-breaking year. Dubai Department of Economy and Tourism Official Release.
- [14] U.S. Department of Agriculture, Foreign Agricultural Service. (2026, October 19). United Arab Emirates: Retail Foods Annual. USDA FAS GAIN Report TC2026-0013.
- [15] U.S. Department of Agriculture, Foreign Agricultural Service. (2026, August 31). Saudi Arabia: Retail Foods Annual. USDA FAS GAIN Report SA2026-0013.
- [16] Saudi Food and Drug Authority. (2025, June 18). SFDA to Implement New Food Rules for Transparency and Consumer Health. Saudi Food and Drug Authority Official News.
- [17] U.S. Department of Agriculture, Foreign Agricultural Service. (2026, October 20). South Korea: KORUS Tariff Rate Quota and Agricultural Safeguard Update. USDA FAS GAIN Report Seoul.
- [18] United States Census Bureau. (2025, November 20). Census Bureau Releases New Data About Characteristics of Businesses and Business Owners. U.S. Department of Commerce Press Release CB25-182.
- [19] Department of Health and Social Care, United Kingdom. (2025, October 1). Restricting promotions of products high in fat, sugar and salt by location and by price: government response to public consultation. UK Government Official Policy Outcome.
- [20] U.S. Department of Agriculture, Foreign Agricultural Service. (2026, March 30). Germany: Food Processing Ingredients Annual. USDA FAS GAIN Report GM2026-0007.
- [21] U.S. Department of Agriculture, Foreign Agricultural Service. (2026, April 1). Japan: Food Processing Ingredients Annual. USDA FAS GAIN Report JA2026-0012.
- [22] Institut national de la statistique et des études économiques (INSEE). (2026, June 18). La situation du commerce en 2025 (éd. juin) - Documents de travail DT2026-08. INSEE Working Paper DT2026-08.
- [23] Europastry, S.A. (2026, March 25). Europastry continues to grow and reaches €1.63 billion in revenue in 2025, an 8% increase compared to 2024. Europastry Corporate Newsroom.
- [24] GRUMA, S.A.B. de C.V. (2026, October 21). GRUMA reports third quarter 2026 results. GRUMA Investor Relations.
- [25] U.S. Department of Agriculture, Foreign Agricultural Service. (2026, October). United Kingdom: Retail Foods Annual. Global Agriculture Information Networkhttps://www.fas.usda.gov/data/gain/2026/10/united-kingdom-retail-foods-annual
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the conchas & pan dulce market in 2026 and what is forecast for 2036?
- Which demographic and supermarket merchandising pressures support demand for conchas & pan dulce?
- Why do Vanilla Conchas lead the product type segment?
- Why does Conventional lead the claim / nature segment globally?
- How do growth rates differ across the UAE, Saudi Arabia, South Korea, and the USA?
- Which leading companies supply verified concha SKUs versus adjacent bakery categories today?
- What limits adoption or long-distance distribution in the conchas & pan dulce market?
- What should retail and foodservice buyers evaluate before contracting a concha supplier?
Frequently Asked Questions
How big is the conchas & pan dulce market in 2026, and what is forecast for 2036?
According to FMI, the global conchas & pan dulce market size is estimated to reach USD 1.2 billion in 2026 from USD 1.1 billion in 2025. Industry valuation is forecast to hit USD 4.6 billion by 2036 as mainstream grocery chains expand packaged multipacks and frozen bake-off tables.
What is the CAGR for the conchas & pan dulce market from 2026 to 2036?
Future Market Insights projects a 14.2% compound annual growth rate between 2026 and 2036, generating an anticipated USD 3.4 billion in added market value across supermarket, panadería, and foodservice channels.
Which product type segment leads the conchas & pan dulce market?
Vanilla Conchas are projected to capture 32.0% of the product type segment in 2026 because recognizable white seashell-scored sugar toppings anchor retail bakery assortments.
Which claim / nature segment leads the conchas & pan dulce market?
Conventional formulations are estimated to secure 50.0% of the claim / nature segment in 2026 as traditional enriched wheat doughs preserve expected crumb softness and sugar-shell snap.
Which country has a notable growth outlook during the assessment period?
The UAE is projected to lead evaluated national growth at a 15.4% CAGR through 2036, supported by USD 17.7 billion in consumer-oriented food imports.
Who are the key players in the market?
Gruma, Mission Foods, Ole Mexican Foods, Toufayan Bakeries, Kontos Foods, FGF Brands, Signature Flatbreads, Angel Bakeries, Grupo Bimbo, and Europastry are evaluated across verified concha production and adjacent sweet-bakery or Hispanic grocery platforms.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Vanilla Conchas
- Chocolate Conchas
- Assorted Pan Dulce
- Mini & Seasonal
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Claim / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Claim / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Claim / Nature, 2026 to 2036
- Conventional
- Clean Label
- Organic
- Gluten-Free
- High-Protein / Fortified
- Y-o-Y Growth Trend Analysis By Claim / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Format, 2026 to 2036
- Fresh
- Frozen
- Ambient Packaged
- Chilled
- Par-Baked / Thaw-and-Serve
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Multipack
- Single-Serve
- Family / Loaf Pack
- Bulk Foodservice
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Artisan & Specialty Bakeries
- Convenience & Forecourt
- Online & DTC
- Foodservice Distributors
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Gruma
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Mission Foods
- Ole Mexican Foods
- Toufayan Bakeries
- Kontos Foods
- FGF Brands
- Signature Flatbreads
- Angel Bakeries
- Grupo Bimbo
- Europastry
- Gruma
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


