

- Market Size (2026)
- USD 61.0 Bn
- Forecast (2036)
- USD 156.9 Bn
- CAGR (2026 to 2036)
- 10.0%
How big is Die Casting Services Market in 2026?
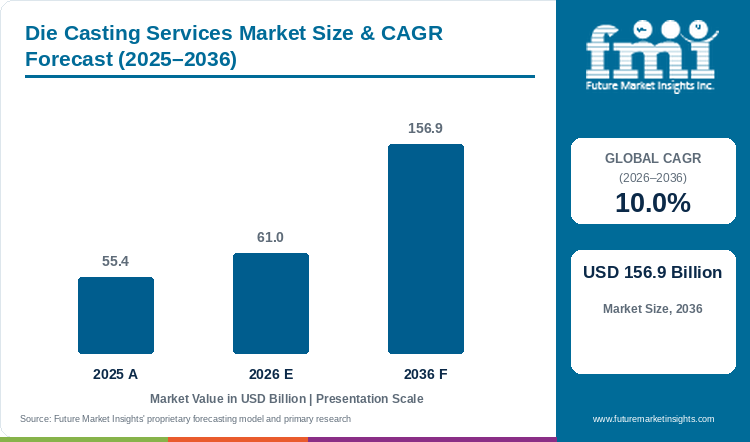
Sales of die casting services will grow at a CAGR of 10% from 2026 to 2036. Market size rose from USD 55.4 billion in 2025 to USD 61.0 billion in 2026 and is projected to reach USD 156.9 billion by 2036.
Die casting services market size rose from USD 55.4 billion in 2025 to USD 61.0 billion in 2026 and is projected to reach USD 156.9 billion by 2036. Sales of die casting services will grow at a CAGR of 10% from 2026 to 2036, according to FMI.
Order timing is the dynamic to watch. Bühler sold 50 megacasting solutions over five years, yet Die Casting orders fell 37.9% in 2025 as large projects materialised more slowly than expected[1]. Bühler adds that megacasting enables the replacement of up to 100 structural parts by a single, large casting[1].
Key drivers of die casting services include part consolidation, as a single large casting replaces many stamped and welded parts. Key challenges faced by casters include the capital needed for large presses and the uneven timing of vehicle programmes. Sales potential is expected to emerge from service providers that offer open press time, tooling and finishing to vehicle makers that have not built own cells. Growth of the market will come in steps, with orders rising as programmes confirm, and casters with spare capacity will take the added volume as programmes land.
Key Market Trends & Insights
- By product type, high-pressure die casting led the market with a share of 55% in 2026, ahead of gravity die casting at an estimated 25% and low-pressure die casting at 20%. Platinadora Baja, acquired by Form Technologies, the parent of Dynacast, combines metal finishing with high-pressure zinc die casting and, more recently, aluminum die casting.[2]
- By application, automotive accounted for 52% of sales in 2026, ahead of electronics at an estimated 17% and telecoms at 11%. Ryobi reported die casting net sales of JPY 274.3 billion for fiscal 2025, supported by a recovery in automobile production.[3]
- Press size keeps rising, with L.K. Technology commercialising a 16,000T ultra-large die-casting unit.[4]
Regional Highlights
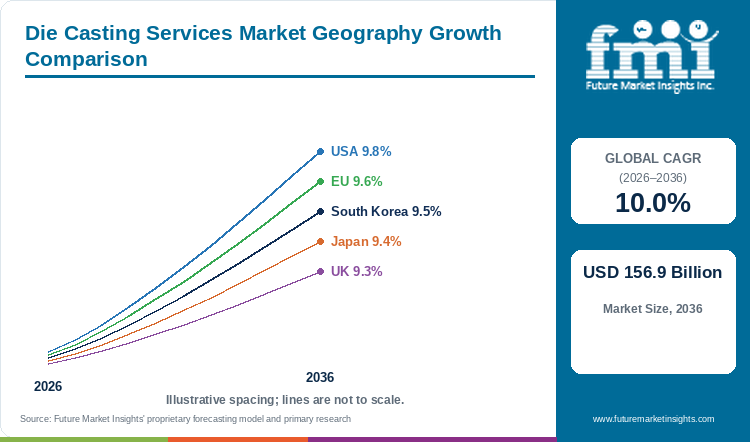
- Fastest-growing profiled country: the USA (9.8% CAGR, 2026 to 2036).
- By country: the EU (9.6%) and South Korea (9.5%) follow, with Japan at 9.4% and the UK recording the lowest profiled CAGR at 9.3%.
- Bühler has supplied 43 die casting systems to Hyundai facilities in South Korea, China and India.[5]
Market Size & Forecast
Table 1: Market Size and Forecast for the Die Casting Services Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 55.4 billion |
| Estimated Market Size in 2026 | USD 61.0 billion |
| Projected Market Size by 2036 | USD 156.9 billion |
| CAGR, 2026 to 2036 | 10% |
| Added Revenue, 2026 to 2036 | USD 95.9 billion |
| Market Expansion Multiple | 2.6x |
Parts consolidation is the design change behind most structural casting programmes. Bühler says megacasting enables the replacement of up to 100 structural parts by a single, large casting.[1] Housings for vehicle controllers are cast too, so the automotive electronics market is an adjacent buyer group. Cast programmes are awarded to casters that can prove die validation and press availability.
Equipment orders show the other side of the cycle. Bühler reported that Die Casting orders fell 37.9% in 2025 as large projects materialised more slowly than expected.[1] L.K. Technology cited downward pressure on new orders for large and extra-large die-casting equipment in the results dated 1 July 2026.[4] Service demand is therefore tied to presses already installed. The open question is who fills them.
Installed Base of Large-Tonnage Casting Machines
Press tonnage now separates structural casters from general casters. Honda invested in six 6,100 t giga-presses at the Anna Engine Plant in Ohio, and Volvo uses two 8,400 t machines in Sweden.[6] Capacity has run ahead of use, as a significant amount of giga-casting capacity installed worldwide is under-utilized.[6] Bühler states that the Carat solution reaches locking forces of up to 92,000 kN.[1] Casters with open presses and validated dies hold the stronger offer to buyers.
Table 2: Large-Tonnage Casting Machine Indicators for the Die Casting Services Market (tonnes, kN, counts and percentage), mixed reporting years from 2020 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Tesla first giga-press, 2020 | 6,000 t locking force | The press size that started the trend. | [6] |
| Largest presses operating | 9,000 t, 12,000 t and 16,000 t; 20,000 t announced | Machine size keeps rising. | [6] |
| Honda, Anna Engine Plant | Six 6,100 t giga-presses | The presses are used for EV components in Ohio. | [6] |
| Volvo | Two 8,400 t machines in Sweden; two 9,000 t machines in Košice, Slovakia | European OEMs are installing large presses. | [6] |
| Bühler megacasting cells | 50 sold over five years; Carat up to 92,000 kN | Cell sales show the scale of structural casting. | [1] |
| Bühler Die Casting orders, 2025 | Down 37.9% | Large projects materialised more slowly than expected. | [1] |
| L.K. Technology, year to March 2026 | 16,000T unit commercialised; first globally by cumulative ultra-large machines delivered | A press builder is supplying the largest machines. | [4] |
| Hyundai Motor Group | 43 Bühler systems; 36 Evolution and 7 Carat | Korean casting is built on long equipment relationships. | [5] |
| Installed capacity use | A significant amount of capacity is under-utilized | Open press time is available for contract work. | [6] |
Analyst Perspective
“Casters with large presses already installed and a record of validated dies are positioned to take structural work first. Idle capacity and cautious equipment orders will make open press time the main selling point through 2036.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the die casting services market segmented?
The die casting services market is segmented into product type and application, and region. In 2026, high-pressure die casting holds 55% of product type sales and automotive holds 52% of application sales.
By product type: high-pressure die casting, gravity die casting, and low-pressure die casting.
By application: automotive, electronics, telecoms, consumer goods, aerospace and defense, and others.
By region: North America, Latin America, Europe, Asia-Pacific, and Middle East and Africa.
Why does high-pressure die casting lead product type?
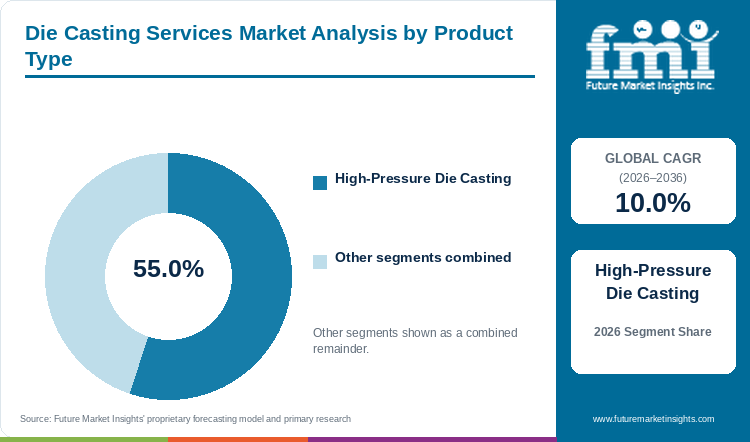
High-pressure die casting accounts for 55% of product type sales in 2026, as engine blocks, transmission housings and electronic enclosures are cast in high volumes.
Table 3: Product Type Share for the Die Casting Services Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| High-Pressure Die Casting | 55% |
| Gravity Die Casting | 25% |
| Low-Pressure Die Casting | 20% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Die Casting Services Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 10% |
| Leading Segment | High-Pressure Die Casting |
A release dated 24 March 2026 describes Platinadora Baja as combining high-pressure zinc die casting and, more recently, aluminum die casting with plating, powder coating and machining.[2] Long runs of thin-walled housings, blocks and enclosures favour the high-pressure route, and FMI names high-pressure die casting the leading product type for 2026. Buyers of lower-load housings can also look at the engineering plastic market.
- Gravity casting holds an estimated 25% and low-pressure casting 20%.
- Tesla started the giga-casting trend in 2020 with 6,000 t machines, and 16,000 t units now operate.[6]
Why does automotive lead demand by application?
Automotive accounts for 52% of application sales in 2026, with use spanning engine parts, gearbox housings, suspension components and EV structural parts.
Table 5: Application Share for the Die Casting Services Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Automotive | 52% |
| Electronics | 17% |
| Telecoms | 11% |
| Consumer Goods | 8% |
| Aerospace and Defense | 7% |
| Others | 5% |
| Total | 100.0% |
Engine, gearbox, suspension and EV structural parts all start as castings, which keeps automotive ahead of the other application groups. Nemak states that about 80% of the portfolio of the newly acquired GF Casting Solutions business is dedicated to e-mobility and structure and chassis applications.[7] Ryobi expects strategic products to recover to around 73% of new orders in 2026, driven by hybrid-related case components.[3] FMI ranks automotive first, ahead of electronics, telecoms, consumer goods, and aerospace and defense. Buyers outside automotive qualify casters on tolerance and finish, not on press size.
- Endurance Technologies supplies machined aluminium castings to four-wheeler OEMs in Europe.[8]
- Electronics and telecoms buyers favour tight tolerance control.
What are the drivers, restraints, and opportunities in the die casting services market?
In the die casting services market, parts consolidation drives large castings, idle press capacity and weak equipment orders constrain growth, and contract programmes that fill existing presses open the principal commercial opportunity.
- Driver: Large aluminium castings replace welded steel assemblies on EV platforms.
- Restraint: Overcapacity, cost pressure and slower projects hold back traditional and structural casting orders.
- Opportunity: Contract programmes fill existing large presses, and downstream finishing widens the services offered.
Large Castings Replace Welded Assemblies
Key drivers of the die casting services market include the move from many stamped parts to a few large castings. Bühler reported on 16 February 2026 the sale of 50 megacasting solutions over five years, and projects were executed in the US, Europe, China and Vietnam.[1] Momentum continued among European OEMs, the same release noted.[1] Aisin is set to invest US$3.4 billion over three years in shifting towards giga-castings.[6] More casting lines mean more demand for dies, finishing and contract casting.
Idle Presses and Weak Equipment Orders Limit Growth
Traditional die casting remained subdued in Europe and North America, as Bühler cited overcapacity and high cost pressures in February 2026.[1] Die Casting orders at Bühler fell 37.9% in 2025.[1] L.K. Technology reported downward pressure on new orders for large and extra-large machines on 1 July 2026.[4] A significant amount of giga-casting capacity is under-utilized worldwide.[6] Smaller casters face the choice between buying a press and renting capacity.
Contract Programmes Can Fill Open Press Time
Open presses create room for casters that sell contract capacity. Form Technologies announced the acquisition of Platinadora Baja in March 2026, expanding the capabilities of Dynacast with downstream processes including plating, powder coating, machining, deburring, impregnation, pad printing and assembly.[2] Coating and plating link casters to the surface protection service market, and deburring links them to the abrasive market. FMI expects casters that bundle finishing with casting to widen the customer base through 2036.
Which country CAGRs are profiled in the die casting services market?
Table 6: Country CAGR Comparison for the Die Casting Services Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| USA | 9.8% |
| EU | 9.6% |
| South Korea | 9.5% |
| Japan | 9.4% |
| UK | 9.3% |
How do country-level CAGRs compare in the die casting services market?
Growth across the five profiled countries is close, with only 0.5 percentage points between the highest and the lowest. As per the analysis from FMI, the USA is projected at 9.8% CAGR from 2026 to 2036, followed by the EU at 9.6% and South Korea at 9.5%. Japan is estimated at 9.4%, and the UK is projected at 9.3%. Vehicle output, press investment and OEM casting strategy set the gaps.
- The USA combines a rising casting sales forecast with subdued traditional casting.
- The EU pairs European OEM momentum in megacasting with subdued traditional casting.
- South Korea links growth to long equipment ties between Hyundai and Bühler.
- Japan draws on Toyota, Honda and Nissan commitments and on Ryobi sales.
- UK growth starts from a low vehicle output base and a recovery outlook.
Full report country CAGRs cover: North America; Latin America; Europe; Asia-Pacific; Middle East and Africa.
Country-wise Analysis
USA Die Casting Services Market Outlook (2026 to 2036)
The American Foundry Society projected on 27 July 2026 an 8 percent increase in casting sales for 2026, year over year.[9] Honda invested in six 6,100 t giga-presses at the Anna Engine Plant in Ohio for EV components.[6] Bühler said traditional die casting remained subdued in North America because of overcapacity and cost pressures.[1] FMI projects the USA at 9.8% CAGR from 2026 to 2036, the highest of the five profiled countries.
Key takeaway: US growth of 9.8% needs casters to move from a strong casting year toward structural programmes, as traditional work stays soft.
EU Die Casting Services Market Outlook (2026 to 2036)
Structural momentum is strongest among European OEMs, Bühler reported in February 2026.[1] Volvo uses two 8,400 t giga-presses in Sweden and is starting with two 9,000 t machines in Košice, Slovakia.[6] Nemak closed the GF Casting Solutions acquisition on 12 February 2026 at an enterprise value of US$336 million, adding nine sites in Austria, China, Germany, Romania and the United States.[7] Endurance Technologies supplies machined aluminium castings to four-wheeler OEMs in Europe, with five of 34 plants in Germany and nine in Italy.[8] FMI projects the EU at 9.6% CAGR from 2026 to 2036.
Key takeaway: EU growth of 9.6% is built on OEM press investment and cross-border casting acquisitions, not on traditional casting volumes.
South Korea Die Casting Services Market Outlook (2026 to 2036)
South Korea is projected at 9.5% CAGR from 2026 to 2036. Hyundai Motor Group and Bühler marked 20 years of die casting collaboration in September 2026.[5] The group runs 43 Bühler systems, 36 Evolution machines and 7 Carat systems, across South Korea, China and India.[5] The first system was an Evolution 270D at the Ulsan complex, and one Carat system is installed in the Ulsan R&D foundry centre. Six Carat systems operate at the Rizhao facility in China, so Korean growth is partly built abroad.
Key takeaway: Korean growth of 9.5% is tied to one OEM group and one press builder, which gives buyers a clear qualification path but a narrow supplier base.
Japan Die Casting Services Market Outlook (2026 to 2036)
Toyota, Honda and Nissan have committed to giga-casting in Japan, and Aisin is set to invest US$3.4 billion over three years.[6] Ryobi reported die casting net sales of JPY 274.3 billion for fiscal 2025, up JPY 16.4 billion, supported by a recovery in automobile production.[3] Ryobi holds an estimated 8% to 12% share of the market. Japan is projected at 9.4% CAGR from 2026 to 2036.
Key takeaway: Japan at 9.4% is carried by OEM giga-casting commitments and a recovering domestic casting base.
UK Die Casting Services Market Outlook (2026 to 2036)
UK vehicle production reached 764,715 units in 2025, the lowest since 1952.[10] The SMMT chief executive said the outlook for 2026 is one of recovery.[10] Jaguar-Land Rover is among the Western carmakers named as customers of the GF Casting Solutions business acquired by Nemak.[7] The UK is projected at 9.3% CAGR from 2026 to 2036, the lowest of the five profiled countries. No UK-specific casting capacity figure is cited here.
Key takeaway: UK growth of 9.3% starts from a low production base, so recovery in vehicle output matters more than new press investment.
Who are the notable companies in the die casting services market?
Dynacast, Endurance Technologies, Gibbs Die Casting, Ryobi, Nemak, Alcast Technologies, Pace Industries, Sandhar Technologies, and Shiloh Industries are notable companies profiled in this market.
Dynacast leads the market with an 18% to 22% share, followed by Endurance Technologies at 12% to 16%, Gibbs Die Casting at 10% to 14%, Ryobi at 8% to 12% and Nemak at 6% to 10%, as per FMI. Other companies together hold 35% to 45%. Endurance reported consolidated total income of INR 14,720 crore for fiscal 2025-26, up 26.1%, and operates 34 plants.[8] Nemak added nine sites through GF Casting Solutions, and Dynacast added Platinadora Baja. Casters differ most by alloy mix and by exposure to structural work.
- Leading share-estimate casters: Dynacast, Endurance Technologies, Gibbs Die Casting, Ryobi, and Nemak.
- Other profiled casters: Alcast Technologies, Pace Industries, Sandhar Technologies, and Shiloh Industries.
- Casters with documented 2026 results or deals: Dynacast, Endurance Technologies, Ryobi, and Nemak.
- Press builders cited in this report: Bühler and L.K. Technology.
Competitive Benchmarking: Die Casting Services Market
Table 7: Competitive Benchmarking for the Die Casting Services Market (qualitative documentation ratings), 2026
| Company | Structural Casting | Financial Results | Recent Activity | Disclosure |
|---|---|---|---|---|
| Nemak | High | Low | High | High |
| Ryobi | Low | High | Medium | High |
| Endurance Technologies | Medium | High | Medium | High |
| Dynacast | Low | Low | High | Medium |
High indicates wider documentation in company filings and releases, Medium indicates limited documentation, and Low indicates less direct documentation. Ratings do not indicate product quality, market share or company rank.
Key Developments in the Die Casting Services Market
- In September 2026, Bühler and Hyundai Motor Group marked 20 years of die casting collaboration, with 43 systems supplied across South Korea, China and India.[5]
- In July 2026, L.K. Technology reported a commercialised 16,000T ultra-large intelligent die-casting unit for the year to March 2026.[4]
- In May 2026, Endurance Technologies reported consolidated total income of INR 14,720 crore for fiscal 2025-26, up 26.1%.[8]
- In March 2026, Form Technologies announced the acquisition of Platinadora Baja, which joins Dynacast.[2]
- In February 2026, Nemak closed the acquisition of GF Casting Solutions at an enterprise value of US$336 million.[7]
- In February 2026, Bühler reported 50 megacasting solutions sold over the past five years.[1]
- In February 2026, Ryobi reported die casting net sales of JPY 274.3 billion for fiscal 2025 at the results briefing.[3]
Key Players in the Die Casting Services Market
Leading Share-estimate Casters
- Dynacast International
- Endurance Technologies Limited
- Gibbs Die Casting
- Ryobi Limited
- Nemak, S.A.B. de C.V.
Other Profiled Casters
- Alcast Technologies
- Pace Industries
- Sandhar Technologies
- Shiloh Industries
Press Builders Cited in This Report
- Bühler
- L.K. Technology
Die Casting Services Market - Report Scope
Table 8: Report Scope for the Die Casting Services Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; application; region |
| Quantitative units | USD billion |
| Market definition | Die casting services market covering high-pressure, gravity and low-pressure die casting for automotive, electronics, telecoms, consumer goods, and aerospace and defense applications. |
| Regions covered | North America; Latin America; Europe; Asia-Pacific; Middle East and Africa |
| Countries covered | USA; EU; South Korea; Japan; UK |
| Key companies profiled | Dynacast, Endurance Technologies, Gibbs Die Casting, Ryobi, Nemak, Alcast Technologies, Pace Industries, Sandhar Technologies, Shiloh Industries |
| Forecast period | 2026 to 2036 |
Die Casting Services Market - Research Methodology
Table 9: Research Methodology for the Die Casting Services Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Market sizes, segment leadership, country CAGRs and company shares come from the forecast model. Machine and company facts come from company filings, press releases and trade press dated May 2025 or later. |
| Desk Research | Desk research covers company filings, official press releases, industry association releases and trade press on die casting and large-tonnage presses. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base market size of USD 55.4 billion and the 10% CAGR. |
| Data Validation | Press tonnage, plant and sales figures are tied to dated filings or releases from the casters and machine builders. |
Die Casting Services Market by Segments
Die Casting Services Market segmented by Product Type:
- High-Pressure Die Casting
- Gravity Die Casting
- Low-Pressure Die Casting
Die Casting Services Market segmented by Application:
- Automotive
- Electronics
- Telecoms
- Consumer Goods
- Aerospace and Defense
- Others
Die Casting Services Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Europe
- Germany
- France
- Italy
- United Kingdom
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Middle East and Africa
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] Engineering News. (2026, February 16). Bühler reports changes in grain milling, cocoa processing and automotive casting production processes. https://www.engineeringnews.co.za/article/bhler-reports-changes-in-grain-milling-cocoa-processing-automotive-casting-production-processes-2026-02-16
- [2] Form Technologies (PR Newswire, via StreetInsider). (2026, March 24). Dynacast expands integrated manufacturing capabilities with addition of Platinadora Baja. https://www.streetinsider.com/PRNewswire/Dynacast+Expands+Integrated+Manufacturing+Capabilities+with+Addition+of+Platinadora+Baja/26206806.html
- [3] Ryobi Limited (LOGMI Finance). (2026, March 2). Ryobi fiscal 2025 results briefing. https://finance.logmi.jp/en/articles/383778
- [4] L.K. Technology Holdings (Zawya). (2026, July 1). L.K. Technology announces 2025/2026 annual results. https://www.zawya.com/en/economy/l.k.-technology-announces-20252026-annual-results-329986
- [5] Autopunditz. (2026, September 21). Bühler and Hyundai mark 20 years of die casting collaboration. https://www.autopunditz.com/post/buhler-hyundai-20-years-die-casting-collaboration
- [6] Alicia Hartlieb and Martin Hartlieb, Light Metal Age. (2025, August 20). Giga-castings in the automotive industry, an updated review. https://www.lightmetalage.com/news/industry-news/automotive/giga-castings-in-the-automotive-industry-an-updated-review/
- [7] Nemak, S.A.B. de C.V. (2026, February 12). Nemak closes the acquisition of GF Casting Solutions. https://www.nemak.com/media/3589/nemak-closing-gfcs-acquisition_eng.pdf
- [8] Endurance Technologies Limited (NSE India). (2026, May 14). Press release on results for fiscal 2025-26. https://nsearchives.nseindia.com/corporate/ENDURANCE_14052026201419_2026_05_14_-_Press_Release.pdf
- [9] American Foundry Society. (2026, July 27). AFS projects 8 percent casting sales growth in 2026. https://www.afsinc.org/news/2026/07/27/afs-projects-8-percent-casting-sales-growth-2026
- [10] Automotive Logistics. (2026, January 29). UK vehicle production in 2025 lowest since 1950s amid JLR cyberattack and new tariffs. https://www.automotivelogistics.media/vehicle-logistics/uk-vehicle-production-in-2025-lowest-since-1950s-amid-jlr-cyberattack-and-new-tariffs-smmt-chief-optimistic-for-recovery-in-2026/2596257
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the die casting services market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which application holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the die casting services market expected in 2026?
Future Market Insights estimates that demand for die casting services reached USD 61.0 billion in 2026. The market is projected to reach USD 156.9 billion by 2036.
What CAGR is projected for the die casting services market through 2036?
As per FMI analysis, die casting services are projected to grow at a 10% CAGR from 2026 to 2036. Parts consolidation on EV platforms supports the outlook.
Which product type holds a notable market share in 2026?
High-pressure die casting accounts for 55% of product type sales in 2026. Engine blocks, transmission housings and electronic enclosures are cast in high volumes.
Which application holds a notable market share in 2026?
Automotive accounts for 52% of application sales in 2026. Use spans engine parts, gearbox housings, suspension components and EV structural parts.
Which country has a notable expansion outlook through 2036?
The USA is projected to record the fastest growth at 9.8% CAGR from 2026 to 2036, according to FMI. The EU, South Korea, Japan and the UK follow within 0.5 percentage points.
Who are the key companies in the die casting services market?
Notable companies include Dynacast, Endurance Technologies, Gibbs Die Casting, Ryobi, Nemak, Alcast Technologies, Pace Industries, Sandhar Technologies, and Shiloh Industries.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- High-Pressure Die Casting
- Gravity Die Casting
- Low-Pressure Die Casting
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Automotive
- Electronics
- Telecoms
- Consumer Goods
- Aerospace and Defense
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- Italy
- United Kingdom
- Asia-Pacific
- China
- India
- Japan
- South Korea
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Product Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- EU
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nemak
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ryobi
- Endurance Technologies
- Dynacast
- Dynacast International
- Endurance Technologies Limited
- Gibbs Die Casting
- Ryobi Limited
- Nemak, S.A.B. de C.V.
- Alcast Technologies
- Pace Industries
- Sandhar Technologies
- Shiloh Industries
- Bühler
- L.K. Technology
- Nemak
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


