
- Market Size (2026)
- USD 50.8 Bn
- Forecast (2036)
- USD 78.9 Bn
- CAGR (2026 to 2036)
- 4.5%
How big is Functional Dairy Products Market in 2026?
Sales in the functional dairy products market are projected to grow at 4.5% CAGR, with market value rising from USD 48.6 billion in 2025 to USD 50.8 billion in 2026 and reaching USD 78.9 billion by 2036.
Daily consumption of fluid milk and cultured dairy represents an established household routine worldwide, owing to which functional dairy does not require consumers to adopt unfamiliar dietary habits to generate demand. By fortifying everyday dairy staples with bioactive peptides, live probiotics, essential vitamins, and minerals, dairy processors convert routine breakfast and snacking occasions into targeted nutritional solutions.
On the back of this dietary integration, the global functional dairy products market stands at USD 48.6 billion in 2025 and rises to USD 50.8 billion in 2026. Industry valuation is projected to reach USD 78.9 billion by 2036, expanding at a 4.5% CAGR and generating USD 28.1 billion in added revenue across the forecast period. Yogurt and milk captures the leading position with 56.8% share in 2026, as both formats preserve high consumer familiarity and support probiotic formulations without altering baseline sensory profiles. A consumer survey cited by Danone in its February 2026 FY2025 presentation indicated that health was named by seven in ten respondents as a reason for routine yogurt consumption. [1]
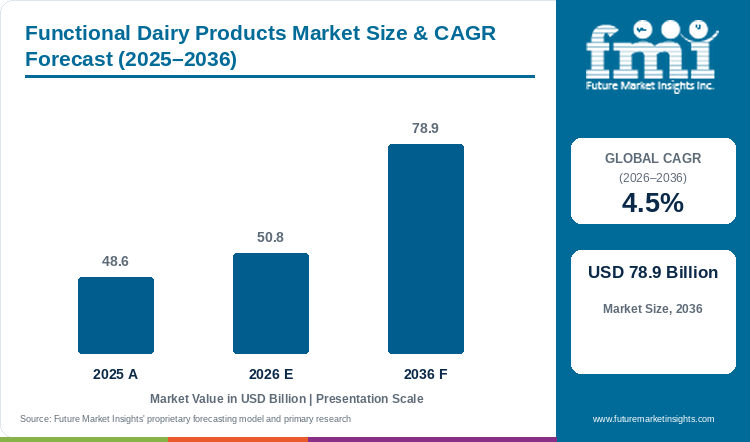
Key Market Trends & Insights
- By product type: Yogurt and milk led with 56.8% share in 2026, supported by daily consumption occasions and established chilled retail distribution.
- By functionality: Digestive health accounted for 44.5% in 2026, remaining the central purchase cue alongside surging high-protein demand.
- By end use: Retail and household held 74.2% in 2026, as functional dairy seamlessly substitutes conventional groceries on weekly shopping lists.
- By distribution channel: Supermarkets and hypermarkets held 61.5% in 2026, providing prime refrigerated shelf visibility for brand comparison.
Regional Highlights
- Fastest-growing listed country: South Korea, at 4.3% CAGR from 2026 to 2036.
- The United States follows at 4.2%, the European Union at 4.1%, the United Kingdom at 3.9%, and Japan at 3.8%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Functional Dairy Products Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 48.6 billion |
| Estimated Market Size in 2026 | USD 50.8 billion |
| Projected Market Size by 2036 | USD 78.9 billion |
| CAGR, 2026 to 2036 | 4.5% |
| Added Revenue, 2026 to 2036 | USD 28.1 billion |
Commercializing functional dairy formulations requires navigating complex biochemical and cold-chain distribution challenges. Adding whey isolates or micellar casein increases viscosity and can cause chalky mouthfeel, while live probiotic cultures exhibit rapid cell degradation when exposed to temperature fluctuations across refrigerated delivery routes. Sourcing scale underpins long-term volume potential, as illustrated by India where the USDA projected 2026 fluid milk consumption at 221.4 million metric tons [2]. Converting even a modest share of this massive liquid milk volume into certified fortified milk products creates immense commercial upside for regional dairy cooperatives. Nonetheless, high initial capital requirements for cold-chain monitoring, automated ultrafiltration skids, and aseptic packaging lines continue to constrain processing margins.
Consumption-Platform and Revenue Sizing
Table 2: Market Revenue and Addressable Dairy Consumption Indicators, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 48.6 | 50.8 | 78.9 |
| Added revenue versus 2026 (USD billion) | - | - | 28.1 |
| Revenue index (2026 = 100) | 95.7 | 100.0 | 155.3 |
| Listed-country CAGR range | 3.8% to 4.3% | 3.8% to 4.3% | 3.8% to 4.3% |
Per Capita and Dairy-System Sizing
Functional dairy is gaining relevance because processors are using the same milk and yogurt occasion for solving a more specific nutrition requirement. A probiotic cup may be purchased for digestion, a higher-protein drink for convenient intake and fortified milk for nutrients already understood by the household. This makes the category easier to repeat than an unfamiliar supplement. Nevertheless, several ingredients in one label does not itself make a stronger product. The benefit has to remain clear, the taste has to stay close to ordinary dairy and the price difference has to appear worth paying, otherwise the larger addressable dairy base will not convert into functional dairy revenue.
Table 3: Global Revenue Intensity Indicators for the Functional Dairy Products Market
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Market revenue per capita (USD) | 5.91 | 6.12 | 8.82 |
| Market revenue per 1,000 people (USD) | 5,905 | 6,120 | 8,816 |
Table 4: Dairy Supply Context and Functional-Dairy Commercial Implications
| Indicator | Verified Value | Commercial Implication |
|---|---|---|
| India fluid milk consumption forecast, 2026 | 221.37 million metric tons | Large routine dairy base for fortified milk and cultured formats |
| EU raw milk output | Approximately 150 million tonnes annually | Deep processing base for value-added dairy innovation |
| Japan raw milk production forecast, 2026 | 7.38 million metric tons | Stable supply but inflation pressures household demand |
| Functional dairy market, 2026 | USD 50.8 billion | Global revenue base for targeted nutrition formats |
Analyst Perspective
“Functional dairy is shifting from broad wellness claims toward defined nutrition outcomes supported by clear formulation evidence. Producers that combine familiar dairy formats with credible benefit communication can strengthen repeat household purchasing.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Functional Dairy Products Market segmented?
The functional dairy products market is segmented by product type, functionality, end use, and distribution channel. In 2026, yogurt and milk is projected at 56.8%, digestive health at 44.5%, retail and household use at 74.2%, and supermarkets and hypermarkets at 61.5%.
By product type: Functional yogurt, fortified milk, functional cheese, fermented dairy beverages, and other dairy-based products.
By functionality: Digestive health, high protein, bone health, immune support, metabolic wellness, and other benefits.
By end use: Retail and household, foodservice, sports nutrition, and medical nutrition.
By distribution channel: Supermarkets and hypermarkets, convenience stores, specialty retail, online, and other channels.
Why do Yogurt and Milk lead the product type category?
Yogurt and milk represent 56.8% of product type in 2026, linking familiar consumption occasions with targeted functional nutrition.
Table 5: Product Type Share for the Functional Dairy Products Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Yogurt and Milk | 56.8% |
| Other Segments Combined | 43.2%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Functional Dairy Products Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.5% |
| Leading Segment | Yogurt and Milk |
| Leading End Use | Retail and Household (74.2%) |
Yogurt and milk lead product demand because consumers already integrate these formats into daily breakfast and snacking occasions. Their liquid and semi-solid matrices allow manufacturers to incorporate bioavailable calcium, dietary fibers, and high-protein yogurt cultures without requiring consumers to alter established preparation routines. This format versatility supports rapid adoption in grab-and-go retail formats. However, high protein loading can induce undesirable textural thickening and astringency, while extended chilled storage can compromise active bacterial counts. Processors able to stabilize texture and maintain pleasant mouthfeel capture strong retail reorders over unfortified commodity dairy.
- Yogurt and milk accounts for 56.8% of product type in 2026 because familiar daily breakfast and snacking habits provide an ideal, repeatable vehicle for probiotic cultures and bioavailable micronutrients.
What supports Gut-Health and High-Protein functionality?
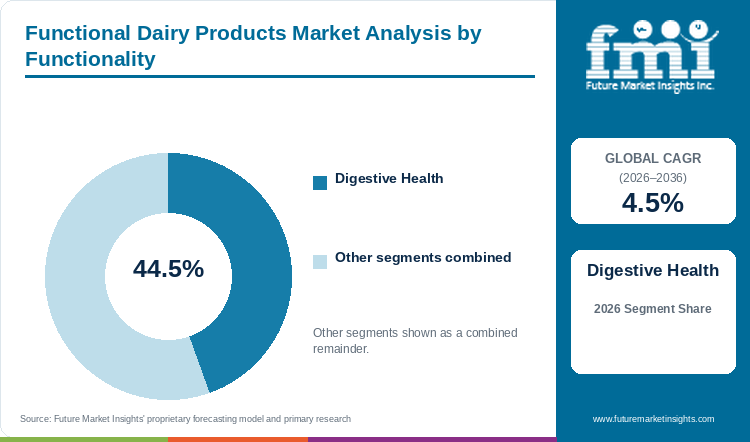
Digestive health accounts for 44.5% of functionality in 2026, driven by probiotic awareness, digestive wellness, and protein enrichment across routine dairy purchases.
Digestive wellness and protein enrichment represent the two fastest-expanding benefit vectors in the functional dairy market. Consumers associate fermented milk with digestive ease, creating strong organic demand for digestive health foods and specialized fermented dairy beverages. Simultaneously, active lifestyle demographics seek accessible dairy proteins to support muscle maintenance without requiring synthetic powder reconstitution. Sourcing high-purity cultures and ultra-filtered milk bases allows processors to deliver clean label declarations. Nevertheless, maintaining probiotic viability through terminal shelf life and preventing bitterness from protein hydrolysis require rigorous batch validation before commercial rollout.
- Digestive health represents 44.5% of functionality demand in 2026 because consumers associate cultured dairy with microbiome balance, while protein enrichment expands adoption across active lifestyle cohorts.
- In November 2025, Akshayakalpa Organic launched lactose-free High Protein Milk containing 25 grams of protein per 250 ml serving [3].
What keeps Retail and Household use ahead by end use?
Retail and household use accounts for 74.2% of end use in 2026, as consumers directly substitute conventional dairy with functional alternatives in everyday meals and snacks.
Retail and household consumers represent the foundational end-use segment because functional dairy directly replaces standard groceries on family shopping lists. Supermarket shoppers readily substitute conventional milk and yogurt with functional alternatives when products communicate clear health outcomes, including bone density support, immune resistance, or digestive comfort. Furthermore, growing integration into sports nutrition products broadens adult consumption across everyday snacking routines. While retail distribution provides high volume visibility, tight family food budgets create strong price sensitivity, forcing brands to justify price differentials through verifiable nutritional quality.
- Retail and household use represents 74.2% of end use in 2026 because fortified milk and functional yogurt formats serve as everyday staples directly replenishing household refrigerators.
- USDA dairy datasets updated in 2026 continue to track large recurring household use across fluid milk and soft dairy categories [4].
Why do Supermarkets and Hypermarkets retain channel leadership?
Supermarkets and hypermarkets account for 61.5% of distribution channel in 2026, enabled by broad chilled assortment, cold-chain integrity, and immediate label comparison.
Supermarkets and hypermarkets remain important because functional dairy needs chilled space, expiry control and regular replenishment, while the buyer usually wants to compare protein, sugar, culture and price on the pack itself. Large stores can place several variants together and generate trial through visibility. Online channels may widen access to specialist or subscription products, but they also add fulfilment and temperature-control requirements. For mainstream volume, the product that is visible beside ordinary dairy and survives the full chilled route has a clearer advantage than a premium format available only through a narrow channel.
- Supermarkets and hypermarkets represent 61.5% of distribution channel in 2026 because extensive refrigerated shelf sets allow shoppers to easily evaluate protein grams, live culture counts, and clean-label claims before purchasing.
What are the drivers, restraints, and opportunities in the Functional Dairy Products Market?
Daily wellness demand supports functional dairy adoption, while claim substantiation and cold-chain costs limit commercialization, and targeted protein or probiotic formats create value.
- Driver: Routine milk and yogurt consumption gives functional ingredients a familiar and repeatable delivery platform.
- Restraint: Diverse health-claim rules and live-culture stability requirements raise validation and distribution costs.
- Opportunity: High-protein, strain-specific, and life-stage products can address defined nutritional needs with clearer differentiation.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Demand expansion accelerates when manufacturers formulate functional dairy around recognizable daily health cues rather than complex nutraceutical claims. Formulating stable matrices using certified functional food ingredients allows brands to command retail premiums while preserving clean taste. Furthermore, expanding distribution of certified organic dairy products provides health-conscious households with verifiable provenance. Consumer survey evidence confirms that digestive comfort remains a primary purchase driver [1]. Retailers consistently allocate prime refrigerated display space to functional lines that demonstrate consistent stock turnover and reliable customer retention.
Risk Assessment of the Functional Dairy Products Market: Validation and Cold-Chain Friction
The market can lose momentum between formulation and consumption. Live cultures may decline during a weak cold chain, added protein may change viscosity and a benefit accepted in one country may require different evidence or wording in another. The European Commission dairy portal shows the size and regular movement of milk production, prices and trade across the regional system [6], but scale also means one formulation can travel through several regulatory and distribution conditions. Producers therefore need shelf-life evidence at the end of the route, not only at factory release. A product failing on texture or claim compliance can lose listing before the broader demand trend has time to support it.[6]
Commercial Opportunity Analysis: Targeted Nutrition and Value-Add Formats
The stronger opportunity is in dairy that performs one clear nutritional job while remaining close to the taste and price expected from its base product. Akshayakalpa Organic's November 2025 lactose-free High Protein Milk, providing 25 grams of protein per 250 ml [3], combines protein intake with digestive tolerance in one everyday format. Meiji's targeted yogurt work also shows movement from general wellness towards specified use. Such products can earn a premium where the quantity, strain or nutrient is visible and credible. The downside is equally direct: a narrow claim, poor sensory quality or inaccessible price can reduce the potential user base even when the underlying health interest is real.[3]
Functional Dairy Products Market by Country (2026 to 2036)
As per Future Market Insights, South Korea represents the fastest-growing functional dairy products market among the five listed economies at 4.3% CAGR from 2026 to 2036, while Japan records 3.8% CAGR. Across these markets, commercial success depends on claim credibility, cold-chain execution, and affordable product differentiation.
Table 7: Country CAGR and Primary Growth Levers for the Functional Dairy Products Market, 2026 to 2036
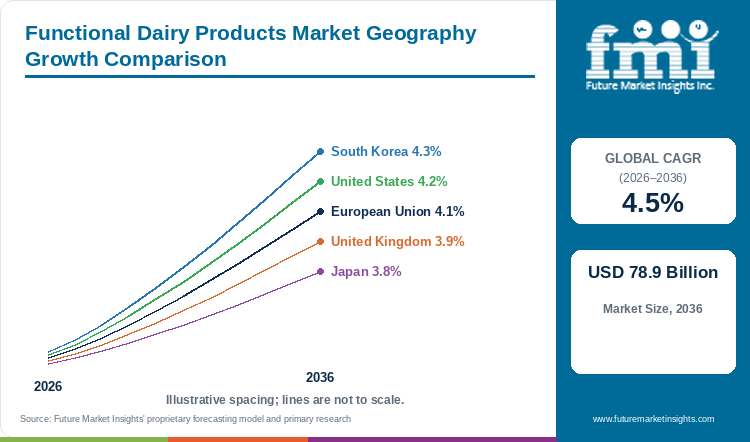
| Country | CAGR | Primary Growth Lever |
|---|---|---|
| South Korea | 4.3% | Interest in gut health, enriched dairy, e-commerce, and convenience retail |
| United States | 4.2% | Established high-protein and probiotic dairy retail categories |
| European Union | 4.1% | Large dairy processing base and structured food-claim regulation |
| United Kingdom | 3.9% | Growing digestive-health awareness and fortified dairy demand |
| Japan | 3.8% | Aging consumers and established functional-food culture |
Source: Future Market Insights analysis
South Korea Functional Dairy Products Market Outlook (2026 to 2036)
South Korea is moving faster than the other listed markets at 4.3% CAGR, and the reason is not dairy volume alone. Dense convenience retail and quick online discovery allow a small probiotic drink or enriched single serve pack to be tried without a large household purchase. Gut-health interest can support this format, while local biotechnology capability can improve strain-led differentiation. The hurdle is a crowded wellness shelf where many products make similar promises. Demand may move in favour of compact products having a recognizable culture, clear daily use and acceptable repeat price; premium products with broad wording but little distinction may attract trial and then lose it.
Key takeaway: In South Korea, Gut-health interest and dense convenience retail create a strong route for enriched dairy formats.
United States Functional Dairy Products Market Outlook (2026 to 2036)
The United States market is projected to expand at a 4.2% CAGR from 2026 to 2036, underpinned by mature chilled supermarket merchandising and extensive consumer adoption of cultured dairy products. Supermarket chains allocate dedicated shelf space for high-protein Greek yogurt, kefir, and ultra-filtered lactose-free milk, allowing functional brands to scale rapidly through existing refrigerated distribution channels. Furthermore, USDA dairy research indicates stable long-term household demand across value-added fluid dairy categories [4]. However, intense brand competition and the proliferation of plant-based dairy substitutes create high promotional expenditure requirements, compelling domestic dairy processors to differentiate through proprietary probiotic strains and reduced-sugar recipes.
Key takeaway: In United States, retail depth supports scale, while clear protein and probiotic differentiation remains necessary.
European Union Functional Dairy Products Market Outlook (2026 to 2036)
The European Union has a deep milk-processing base, with about 150 million tonnes of raw milk produced annually, which gives manufacturers supply, technical capability and chilled distribution for moving functional dairy beyond niche use. Growth at 4.1% CAGR may come from fortified milk, probiotic yogurt and functional cheese where the nutrition statement fits an accepted regulatory route. This market differs from the global picture because the hurdle is not only product development; the wording used on pack can decide whether the benefit can be communicated at all. Companies with evidence, lower-sugar formulations and country-level label discipline may gain, while broad wellness claims can delay launch or weaken differentiation.
Key takeaway: In European Union, Processing depth supports innovation, but regulatory discipline shapes permissible consumer communication.
United Kingdom Functional Dairy Products Market Outlook (2026 to 2036)
The United Kingdom can place probiotic yogurt, higher-protein products and vitamin-fortified milk before mainstream buyers through concentrated supermarket distribution. This supports the 3.9% CAGR because a national listing can bring quick visibility, but household budget pressure keeps the functional premium under close comparison with standard dairy and private label. Adoption may move in favour of multipacks and products combining one understood benefit with a familiar flavour. A product asking the buyer to pay more for language that is difficult to verify may face switching at the next purchase, even when digestive-health interest remains present.
Key takeaway: In United Kingdom, Mainstream supermarket access supports adoption, while value perception controls repeat purchasing.
Japan Functional Dairy Products Market Outlook (2026 to 2036)
Japan's 3.8% CAGR is shaped by value per serving more than conventional milk volume. The country already has a functional-food culture and frequent use of compact fermented drinks, giving targeted products for digestion, skin, sleep or metabolic support a familiar route. USDA forecast 2026 raw milk production at 7.38 million metric tons [9], while inflation and pressure on household milk use limit a volume-led strategy. Suppliers may therefore gain through smaller packs, specified benefits and reliable daily consumption. The risk is over-fragmentation, where too many narrowly positioned products shorten product life and increase the cost of keeping attention on the shelf.
Key takeaway: In Japan, Targeted benefit formats help producers create value despite pressure on conventional milk consumption.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the functional dairy products market?
Danone S.A., Nestle S.A., Yakult Honsha Co., Ltd., Arla Foods amba, Meiji Holdings Co., Ltd., Morinaga Milk Industry Co., Ltd., Inner Mongolia Yili Industrial Group Co., Ltd., and China Mengniu Dairy Company Limited are notable companies operating in this market.
Competition is divided between broad dairy groups, culture specialists and large regional processors. Global groups can place protein, fortified and lactose-managed products through established chilled networks, while Yakult, Meiji and Morinaga use strain recognition and repeated small-format consumption as a stronger point of difference. Yili and Mengniu bring production scale and fast Asian retail access. Market position will therefore depend less on the number of claims in a portfolio and more on whether a company can keep culture viability, taste, evidence and replenishment consistent after launch. A wide portfolio helps distribution, but specialist credibility can still win where the buyer is choosing for one defined benefit.
- Global Dairy and Nutrition Platforms: Danone, Nestle, Arla Foods, and Yili combine broad portfolios with extensive distribution.
- Probiotic and Fermented-Dairy Specialists: Yakult, Meiji, and Morinaga focus on cultures, fermented formats, and targeted health positioning.
- High-Growth Regional Platforms: Mengniu and other large processors extend functional dairy through protein, precision nutrition, and digital retail.
Competitive Benchmarking: Functional Dairy Products Market
Table 8: Competitive Benchmarking for the Functional Dairy Products Market, 2026
| Company | Functional Dairy Breadth | Probiotic / Culture Depth | Retail Reach | Geographic Reach |
|---|---|---|---|---|
| Danone S.A. | High | High | High | High |
| Nestle S.A. | High | Medium | High | High |
| Yakult Honsha Co., Ltd. | Medium | High | High | High |
| Arla Foods amba | High | Medium | High | High |
| Meiji Holdings Co., Ltd. | High | High | High | Medium |
| Morinaga Milk Industry Co., Ltd. | High | High | Medium | Medium |
| Yili Group | High | High | High | High |
| China Mengniu Dairy | High | High | High | High |
Key Developments in the Functional Dairy Products Market
- In June 2026, Yili showcased precision-nutrition dairy products at the 19th Global Dairy Congress in Barcelona, Spain. New products accounted for 16.4% of company revenue in 2025. [7]
- In February 2026, Danone reported stronger strategic emphasis on high protein, gut health, fibers, and specialized nutrition in its FY2025 presentation. [1]
- In November 2025, Akshayakalpa Organic launched lactose-free High Protein Milk delivering 25 grams of protein per 250 ml serving. [3]
- In October 2025, Meiji announced functional yogurt products containing MI-2 lactic acid bacteria for blood-sugar management positioning. [8]
Key Players in the Functional Dairy Products Market
Global Dairy and Nutrition Platforms
- Danone S.A.
- Nestle S.A.
- Arla Foods amba
Probiotic and Fermented-Dairy Specialists
- Yakult Honsha Co., Ltd.
- Meiji Holdings Co., Ltd.
- Morinaga Milk Industry Co., Ltd.
Large Asian Dairy Platforms
- Yili Group
- China Mengniu Dairy
Functional Dairy Products Market - Report Scope
Table 9: Report Scope for the Functional Dairy Products Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Functionality; End Use; Distribution Channel |
| Quantitative units | USD Billion |
| Market definition | Supplier revenue from dairy products formulated or positioned with benefits beyond basic nutrition, including probiotic, high-protein, fortified, and targeted-health dairy formats. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries highlighted | South Korea, United States, European Union, United Kingdom, and Japan |
| Key companies covered | Danone S.A., Nestle S.A., Yakult Honsha Co., Ltd., Arla Foods amba, Meiji Holdings Co., Ltd., Morinaga Milk Industry Co., Ltd., Inner Mongolia Yili Industrial Group Co., Ltd., China Mengniu Dairy Company Limited |
| Forecast period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Functional Dairy Products Market - Research Methodology
Table 10: Research Methodology for the Functional Dairy Products Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with manufacturers, suppliers, distributors, retail buyers, nutrition professionals, industry experts, and key opinion leaders across the value chain. |
| Secondary Research | Company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public data. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess revenue, product demand, channel reach, price points, and adoption from 2026 to 2036. |
| Data Triangulation and Validation | Data is checked against dairy production, consumption, regulation, launches, corporate disclosures, and historical trends to reduce category overlap. |
Functional Dairy Products Market by Segments
Functional Dairy Products Market segmented by Product Type:
- Functional Yogurt
- Fortified Milk
- Functional Cheese
- Fermented Dairy Beverages
- Other Dairy Products
Functional Dairy Products Market segmented by Functionality:
- Digestive Health
- High Protein
- Bone Health
- Immune Support
- Metabolic Wellness
- Other Benefits
Functional Dairy Products Market segmented by End Use:
- Retail and Household
- Foodservice
- Sports Nutrition
- Medical Nutrition
Functional Dairy Products Market segmented by Distribution Channel:
- Supermarkets and Hypermarkets
- Convenience Stores
- Specialty Retail
- Online
- Other Channels
Functional Dairy Products Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Danone S.A. (2026, February 20). FY 2025 presentation. Consumer yogurt-health survey and strategic nutrition disclosures. Danone Investor Relations.
- [2] U.S. Department of Agriculture, Foreign Agricultural Service. (2025, September 29). Dairy and products annual: India. Global Agricultural Information Network.
- [3] Akshayakalpa Organic. (2025, November 4). High Protein Milk launch announcement. Corporate Product Release.
- [4] U.S. Department of Agriculture, Economic Research Service. (2026, September 14). Dairy data. Federal Dairy Statistics.
- [5] Future Market Insights. (2026, February 13). Functional Dairy Products Market Report, 2026-2036. FMI Industry Research.
- [6] European Commission. (2026). Agri-food data portal: Milk and dairy products. European Commission Directorate-General for Agriculture.
- [7] Yili Group. (2026, July 1). Functional dairy and precision-nutrition innovations presented at the Global Dairy Congress. Corporate Press Office.
- [8] Meiji Co., Ltd. (2025, October 1). Functional yogurt products for blood-sugar management announced for nationwide release on October 14, 2025. Meiji Corporate News.
- [9] U.S. Department of Agriculture, Foreign Agricultural Service. (2025, December 8). Dairy and products annual: Japan. Global Agricultural Information Network.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the functional dairy products market in 2026 and what is forecast for 2036?
- Which consumer nutrition priorities support functional dairy demand?
- Why do yogurt and milk lead product demand?
- How do high-protein and gut-health products influence innovation?
- How do listed growth rates differ across South Korea, the United States, Europe, the UK, and Japan?
- Which companies hold relevant functional dairy capabilities?
- What limits adoption or supplier switching?
- What should buyers assess before selecting a functional dairy supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Functional Yogurt
- Fortified Milk
- Functional Cheese
- Fermented Dairy Beverages
- Other Dairy Products
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Functionality, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Functionality, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Functionality, 2026 to 2036
- Digestive Health
- High Protein
- Bone Health
- Immune Support
- Metabolic Wellness
- Other Benefits
- Y-o-Y Growth Trend Analysis By Functionality, 2021 to 2025
- Absolute $ Opportunity Analysis By Functionality, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Retail and Household
- Foodservice
- Sports Nutrition
- Medical Nutrition
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets and Hypermarkets
- Convenience Stores
- Specialty Retail
- Online
- Other Channels
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Functionality
- By End Use
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Danone S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nestle S.A.
- Yakult Honsha Co., Ltd.
- Arla Foods amba
- Meiji Holdings Co., Ltd.
- Morinaga Milk Industry Co., Ltd.
- Yili Group
- China Mengniu Dairy
- Danone S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Functionality, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Functionality, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Functionality, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Functionality, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Functionality, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Functionality, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Functionality, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Functionality, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Functionality, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Functionality, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Functionality
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Product Type
- Figure 29: North America Market Value Share and BPS Analysis by Functionality, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Functionality, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Functionality
- Figure 32: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End Use
- Figure 35: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Distribution Channel
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Product Type
- Figure 42: Latin America Market Value Share and BPS Analysis by Functionality, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Functionality, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Functionality
- Figure 45: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by End Use
- Figure 48: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Product Type
- Figure 55: Western Europe Market Value Share and BPS Analysis by Functionality, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Functionality, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Functionality
- Figure 58: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by End Use
- Figure 61: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Functionality, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Functionality, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Functionality
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Product Type
- Figure 81: East Asia Market Value Share and BPS Analysis by Functionality, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Functionality, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Functionality
- Figure 84: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by End Use
- Figure 87: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Functionality, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Functionality, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Functionality
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Functionality, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Functionality, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Functionality
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the functional dairy products market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the market will reach USD 50.8 billion in 2026 and USD 78.9 billion by 2036.
What is the CAGR from 2026 to 2036?
FMI projects a 4.5% CAGR across the assessment period.
Which product type leads the functional dairy products market?
Future Market Insights projects that yogurt and milk will hold 56.8% share in 2026. The segment benefits from deep household penetration, routine breakfast and snacking integration, and superior matrix compatibility with probiotic cultures.
Which end use leads?
Retail and household use accounts for 74.2% share in 2026 due to recurring everyday family grocery replenishment.
Which listed country grows fastest?
South Korea records the fastest listed outlook at 4.3% CAGR through 2036.
Who are the key players?
Danone, Nestle, Yakult, Arla Foods, Meiji, Morinaga Milk, Yili, and Mengniu are relevant participants.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
