
- Market Size (2026)
- USD 53.8 Bn
- Forecast (2036)
- USD 75.9 Bn
- CAGR (2026 to 2036)
- 3.5%
How big is Lead Acid Battery Market in 2026?
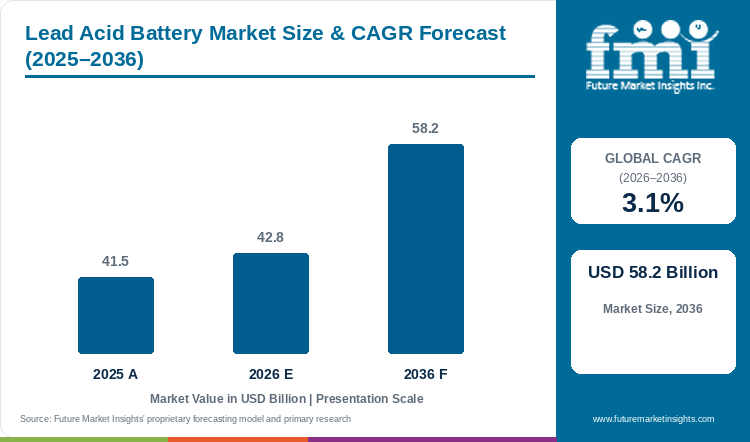
With a valuation of USD 52.0 billion in 2025 and moving to USD 53.8 billion in 2026, the lead acid battery market is positioned to attain USD 75.9 billion by 2036, exhibiting a CAGR of 3.5%.
Automotive aftermarket distributors, data center operators and warehouse fleet managers continue purchasing lead-acid batteries in high volume because no competing electrochemistry matches their cold-cranking reliability, intrinsic thermal safety and 99.0% closed-loop secondary lead recyclability. The global lead acid battery market recorded a market size of USD 52.0 billion in 2025 and is anticipated to reach USD 53.8 billion in 2026, while total industry valuation is forecast to expand to USD 75.9 billion by 2036 at a compound annual growth rate (CAGR) of 3.5% between 2026 and 2036. Flooded wet cell lead acid batteries capture an estimated 58.0% share of battery construction demand in 2026, owing to their economical per-kilowatt-hour manufacturing cost across internal combustion and commercial vehicle starting systems.
Procurement analysis by FMI finds that even as electric vehicle drivetrains scale, automakers retain 12-volt absorbent glass mat lead-acid auxiliary batteries to power functional-safety braking, steering and autonomous sensor networks independently of the high-voltage traction pack. That replacement-driven demand profile differentiates the overall market from specialized forklift battery systems expanding at a 7.6% CAGR, where multi-shift warehouse electrification accelerates deep-cycle motive turnover. Official commodity records from the U.S. Geological Survey published in February 2026 confirm that the lead-acid battery industry accounted for 67.0% of apparent United States lead consumption in 2025, supported by 1.0 million metric tons of domestic secondary lead recovered from spent batteries. Industry shipment data released by Battery Council International in May 2026 further shows that six out of every ten new 2025 model-year vehicles in North America adopted absorbent glass mat batteries, propelling a projected 1.9% rebound in regional automotive lead battery shipments in 2026. Suppliers that combine high-rate AGM plate manufacturing with automated core-return smelting lock in long-term distributor and OEM contracts through 2036.
Key Market Trends & Insights
- By battery construction: Flooded Wet Cell Lead Acid Batteries hold an estimated 58.0% share in 2026 since low-cost vented liquid-electrolyte designs dominate standard passenger car and agricultural tractor replacement channels.
- By sales channel: Aftermarket Replacement Battery Sales represent 78.0% in 2026 as extreme summer heat and winter cold snaps trigger recurring three-to-four-year battery replacements across the global vehicle parc.
- By functional application: SLI (Starting, Lighting and Ignition for Automotive) accounts for 64.0% in 2026 driven by cranking and 12-volt auxiliary safety loads across combustion, hybrid and battery-electric vehicles.
- By grid alloy architecture: Lead-Calcium Maintenance-Free Alloys secure 54.0% in 2026 owing to suppressed water-loss gassing and extended shelf stability in sealed automotive modules.
- By voltage class: 12V Automotive and Auxiliary Modules command 68.0% in 2026 through universal standardization across passenger vehicle starting and electronic control architectures.
Regional Highlights
- Top national expansion: Brazil leads national growth projections at a 4.3% CAGR through 2036 under expanding commercial vehicle fleets, tropical replacement frequency, and telecom tower backup rollouts.
- Broader country progression: Mexico expands at a 4.2% CAGR while India posts 4.0% and Canada reaches 3.6% and Australia records 3.5%, the United States hits 3.3%, the United Kingdom registers 3.1% and Germany tracks at 2.9%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Lead Acid Battery Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 52.0 billion |
| Estimated Market Size in 2026 | USD 53.8 billion |
| Projected Market Size by 2036 | USD 75.9 billion |
| CAGR, 2026 to 2036 | 3.5% |
| Added Revenue, 2026 to 2036 | USD 22.1 billion |
Global artificial intelligence data center buildouts and telecommunications tower expansions are creating substantial new demand for short-duration valve-regulated lead-acid uninterruptible power supply banks. Unlike grid-scale multi-hour storage projects, hyperscale server rooms require non-combustible battery strings that bridge the 30-second to 15-minute gap until backup diesel or gas generators synchronize with the load. As reported in the International Energy Agency Global Energy Review published in March 2026, global battery-based uninterruptible power supply capacity additions surged by 30.0% to reach 45 gigawatts in 2025, led by data center deployments. Consequently, facility engineers specify flame-retardant advanced lead acid battery strings where indoor fire-code compliance outweighs gravimetric energy density.
Refined Lead Feedstock & Circular Smelting Sizing
Table 2: Refined Lead Feedstock and Circular Smelting Indicators for the Lead Acid Battery Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 52.0 | 53.8 | 75.9 |
| Global refined lead metal consumption (million metric tons) | 13.25 | 13.45 | 15.80 |
| Battery industry share of U.S. apparent lead consumption (%) | 67.0% | 67.5% | 71.0% |
| Closed-loop secondary lead recovery rate in regulated markets (%) | 98.5% to 99.0% | 98.5% to 99.0% | 99.0% to 99.5% |
Stable refined lead metal availability and high secondary scrap recovery insulate lead-acid battery manufacturers from the volatile mining supply shocks seen in lithium and cobalt markets. Commodity balance figures published by the International Lead and Zinc Study Group in October 2026 indicate that global refined lead production reached approximately 13.3 million metric tons in 2025 and is projected to exceed global demand by 90,000 metric tons in 2026. This well-supplied secondary metal pool allows producers of automotive lead acid battery modules to maintain predictable toll-smelting core credits with retail auto-parts chains.
Fleet Replacement & Industrial Standby Sizing
Table 3: Fleet Replacement and Industrial Standby Indicators for the Lead Acid Battery Market (units, GW and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global installed motor vehicle & industrial fleet parc (billion units) | 1.48 | 1.52 | 1.85 |
| Global data center & commercial UPS capacity additions (GW) | 45.0 | 51.5 | 96.0 |
| North American new model-year vehicle AGM battery share (%) | 60.0% | 62.5% | 78.0% |
| Average realized industrial & automotive battery price (USD per kWh) | 68.0 to 115.0 | 70.0 to 118.0 | 78.0 to 132.0 |
Table 4: Channel & Application Allocation Indicators for the Lead Acid Battery Market (USD billion and institutional basis), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 53.8 billion | 2026 global market valuation baseline |
| Aftermarket replacement channel allocation, 2026 | USD 42.0 billion | 78.0% sales channel segment share |
| Automotive SLI & auxiliary application allocation, 2026 | USD 34.4 billion | 64.0% functional application segment share |
| U.S. secondary lead production from spent batteries | 1.0 million metric tons (USD 2.4B) | USGS Mineral Commodity Summaries 2026 |
Industrial warehouse operators and telecommunications carriers steadily evaluate total lifecycle ownership costs and domestic tax credits when procuring motive and standby battery fleets. In May 2026, industrial battery leader EnerSys reported fourth-quarter fiscal 2026 net sales of USD 988 million and full-year adjusted diluted earnings of USD 10.56 per share, supported by Section 45X domestic manufacturing credits and strong demand for warehouse and telecom power systems. These earnings demonstrate how suppliers of stationary lead acid battery storage protect operating margins by bundling smart chargers and remote battery telemetry with replacement cells.
Analyst Perspective
"Lead-acid batteries remain the workhorse of automotive starting and mission-critical industrial backup because closed-loop core collection turns every sold battery into future raw material. Manufacturers that shift production mix toward start-stop AGM and thin-plate pure lead modules while automating secondary smelters will steadily expand cash margins through 2036."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Lead Acid Battery Market segmented?
The lead acid battery market is segmented by battery construction, sales channel, functional application, grid alloy architecture, and voltage class. In 2026, Flooded Wet Cell Lead Acid Batteries are projected at 58.0%, Aftermarket Replacement Battery Sales at 78.0%, SLI Automotive at 64.0%, Lead-Calcium Maintenance-Free Alloys at 54.0%, and 12V Automotive and Auxiliary Modules at 68.0%.
By battery construction: Flooded Wet Cell Lead Acid Batteries, Valve Regulated Lead Acid (VRLA) Absorbent Glass Mat (AGM), Valve Regulated Lead Acid (VRLA) Gel Batteries and Enhanced Flooded Battery (EFB) Start-Stop Systems.
By sales channel: Aftermarket Replacement Battery Sales, Original Equipment Manufacturer (OEM) Factory Installed, Industrial Fleet and Warehouse Direct Contracts and Authorized Commercial Distributors and E-Commerce.
By functional application: Automotive starting lighting and ignition and Motive power forklifts and AGVs, Stationary telecom and UPS standby, Off-grid renewable storage and Marine or defense auxiliary power.
By grid alloy architecture: Lead-Calcium Maintenance-Free Alloys, Lead-Antimony Deep-Cycle Industrial Alloys, Pure Lead Thin-Plate (TPPL) High-Rate Grids and Lead-Carbon Bipolar and Hybrid Negative Plates.
By voltage class: 12V Automotive and Auxiliary Modules, 24V to 48V Motive and Mild-Hybrid Packs, 2V Stationary Industrial Cells and String Banks and 6V Deep-Cycle Commercial and Utility Blocks.
Why do Flooded Wet Cell Lead Acid Batteries lead the battery construction category?
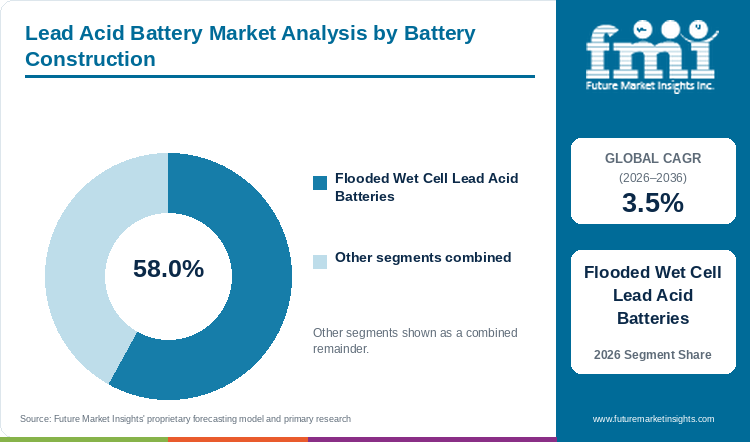
Flooded Wet Cell Lead Acid Batteries hold an estimated 58.0% of battery construction demand in 2026, anchored by economical cold-cranking output across global vehicle replacement fleets.
Table 5: Battery Construction Share for the Lead Acid Battery Market (percentage share), 2026
| Battery Construction | Share (2026) |
|---|---|
| Flooded Wet Cell Lead Acid Batteries | 58.0% |
| Other Segments Combined | 42.0%* |
| Total | 100.0% |
*Note: Remaining battery construction categories including VRLA AGM, VRLA Gel, and Enhanced Flooded Batteries account for the balance of 2026 global demand.
Table 6: Battery Construction Leadership and Market Growth for the Lead Acid Battery Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.5% |
| Leading Segment | Flooded Wet Cell Lead Acid Batteries |
Vented wet cell lead-acid batteries command the largest share of global construction volume because liquid sulfuric acid electrolyte surrounding stamped lead-oxide grids delivers high cold-cranking amperage at the lowest manufacturing cost per amp-hour. Experimental electrochemical testing published in Sensors in January 2026 across 42,000 sample points confirmed that maintaining liquid electrolyte levels within optimal 20 degrees Celsius thermal tolerances prevents premature grid dry-out and capacity loss in flooded cells. Periodic distilled-water topping requirements and acid-spill risks during tilting remain the main operational drawbacks encouraging premium buyers to upgrade toward sealed VRLA formats.
- Within the battery construction segment, Flooded Wet Cell Lead Acid Batteries are projected to account for a leading 58.0% share in 2026, driven by cost-sensitive automotive replacement and heavy agricultural equipment demand.
- Valve-regulated absorbent glass mat and enhanced flooded constructions are forecast to gain share through 2036 as micro-hybrid start-stop vehicles and sealed indoor UPS cabinets expand.
What sustains Aftermarket Replacement Battery Sales leadership in the sales channel segment?
Aftermarket Replacement Battery Sales represent 78.0% of the sales channel category in 2026, supported by recurring three-to-five-year replacement cycles across the global vehicle parc.
Aftermarket replacement battery sales generate more than three-quarters of industry volume because an installed global fleet exceeding 1.4 billion motor vehicles requires a new 12-volt starter battery every three to five years regardless of new car production cycles. Retail auto-parts chains, independent repair garages, and roadside assistance fleets rely on reverse-logistics lead acid battery recycling core-exchange credits where returning a spent battery immediately discounts the customer's replacement invoice.
- In 2026, Aftermarket Replacement Battery Sales are anticipated to capture 78.0% of global sales channel demand, supported by mandatory core-deposit trade-ins and high-heat summer replacement spikes.
- Market tracking published by Battery Council International and CRU in May 2026 documented that North American automotive lead battery shipments are forecast to grow 2.0% annually through 2028 following a 1.6% replacement volume adjustment in 2025.
How does SLI lead the functional application category?
SLI (Starting, Lighting, and Ignition for Automotive) accounts for 64.0% of functional application demand in 2026, driven by combustion cranking and 12V xEV functional-safety circuits.
Starting, lighting and ignition (SLI) applications anchor global lead-acid battery consumption since every internal combustion, hybrid and battery-electric passenger car or commercial truck requires a dedicated low-voltage power source. In battery-electric vehicles where battery-electric models captured 19.4% of European Union new car registrations during the first quarter of 2026 according to April 2026 figures from the International Organization of Motor Vehicle Manufacturers, a 12-volt SLI or auxiliary lead-acid battery remains mandatory to operate hazard lights, door locks and emergency braking if the high-voltage lithium contactor trips.
- By functional application, SLI (Starting, Lighting and Ignition for Automotive) is estimated to hold 64.0% of total demand in 2026 on account of universal 12-volt vehicle electrical architectures.
- Stationary telecom and data center UPS backup as well as electric warehouse forklifts provide steady non-automotive diversification as industrial operators expand multi-shift material handling.
Why do Lead-Calcium Maintenance-Free Alloys lead the grid alloy architecture category?
Lead-Calcium Maintenance-Free Alloys secure 54.0% of grid alloy architecture volume in 2026, supported by low water loss and automated stamped-grid manufacturing.
Lead-calcium-tin grid alloys dominate modern battery manufacturing because replacing traditional antimony hardeners with 0.06% to 0.10% calcium raises the hydrogen and oxygen overvoltage threshold, eliminating the need for drivers to add water over the battery's service life. Fleet operators purchasing adsorbent glass mat battery modules and sealed starter batteries depend on stamped lead-calcium grids to resist positive-plate corrosion during high-temperature under-hood operation.
- Lead-Calcium Maintenance-Free Alloys are predicted to secure 54.0% of grid alloy architecture demand in 2026, supported by automated continuous roll-punching grid lines.
- A post-industrial VRLA ageing study published in Applied Sciences in September 2026 demonstrated that while capacity drops reaching 20.0% after five years require battery replacement, positive lead-grid corrosion and sulfation remain the primary failure modes governing alloy selection.
What gives 12V Automotive and Auxiliary Modules the leading position in voltage class?
12V Automotive and Auxiliary Modules command 68.0% of voltage class share in 2026, anchored by universal 12-volt vehicle electrical buses.
Twelve-volt six-cell monobloc batteries represent the standard voltage architecture across global automotive OEMs, commercial trucking fleets and marine vessels because decades of starter motors, alternators and infotainment modules are engineered around a 12.6-volt nominal bus. At CES 2026 in January 2026, global market leader Clarios showcased its integrated 12-volt to 48-volt low-voltage power management architecture pairing advanced AGM and flooded lead-acid batteries with supercapacitors to support steer-by-wire and autonomous safety loads. High amperage draw from autonomous computing racks is gradually pushing heavy trucks and luxury hybrids toward dual-battery 12-volt and 48-volt setups.
- With a projected 68.0% share of the voltage class segment in 2026, 12V Automotive and Auxiliary Modules remain the primary revenue engine for global battery manufacturers.
- Two-volt industrial cells wired in series strings and 24-volt to 48-volt motive traction packs capture the remaining share across utility substations, telecom towers, and warehouse forklifts.
What are the drivers, restraints, and opportunities in the Lead Acid Battery Market?
In the lead acid battery market, recurring vehicle aftermarket replacement, 12V xEV safety redundancy, and data center UPS installations are projected to drive adoption, whereas lithium-ion cost parity restrains deep-cycle grid storage and thin-plate pure lead and lead-carbon designs open fast-charging industrial avenues.
- Driver: Rising vehicle electronic loads, start-stop micro-hybrid penetration, and hyperscale data center UPS backup installations drive steady conversion toward premium AGM and VRLA batteries.
- Restraint: Falling lithium-iron-phosphate pack costs and sulfation-induced cycle-life limits restrain lead-acid share in long-duration utility grid storage and multi-shift electric forklifts.
- Opportunity: Designation of lead as a federal critical mineral and deployment of lead-carbon bipolar and thin-plate pure lead architectures open high-rate fast-charging industrial and defense opportunities.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Rapidly rising electrical power density inside artificial intelligence data centers and software-defined vehicles acts as the primary commercial driver driving demand for high-reliability lead-acid backup and auxiliary batteries. When a cloud data center experiences even a millisecond grid interruption, uninterruptible power supply strings must instantly carry megawatt server loads without thermal runaway risk. In a January 2026 technical assessment of data center power resilience, EnerSys reported that one in five severe data center outages costs operators more than USD 1.0 million while 54.0% of outages exceed USD 100,000 in direct losses, highlighted by a major cloud outage in October 2025 that caused USD 38 million to USD 581 million in global insured losses. This severe financial exposure compels data center builders and vehicle OEMs to specify redundant absorbent glass mat backup systems.
Risk Assessment of the Lead Acid Battery Market: Operational and Formulation Friction
Lower lithium-ion battery cell prices and lower deep-discharge cycle life in conventional flooded lead-acid batteries restrain expansion across utility-scale renewable storage and high-utilization warehouse fleets. When a battery must undergo deep 80.0% depth-of-discharge cycling over 1,000 times, standard lead-acid plates suffer irreversible lead-sulfate crystallization unless oversized or carefully temperature-controlled. As reported in an August 2026 battery cost benchmark published by Argonne National Laboratory for the U.S. Department of Energy, volume-weighted electric vehicle lithium-ion battery pack costs declined to USD 96 per kilowatt-hour in 2026 across 1,000-cycle, 10-year life specifications. That narrowing upfront price gap intensifies competition in stationary and motive applications.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
The engineering of thin-plate pure lead (TPPL), lead-carbon negative electrodes and standardized predictive maintenance diagnostics unlocks high-margin growth across telecom, defense and automated warehouse accounts. The addition of activated carbon and barium sulfate expanders to the negative lead plate suppresses sulfation during partial-state-of-charge cycling, allowing opportunity fast-charging during 15-minute operator breaks. In November 2025, the IEEE Standards Association approved IEEE Std 1188-2025, establishing updated testing and ohmic-measurement and replacement criteria to optimize the service life of stationary valve-regulated lead-acid batteries. IEEE-compliant impedance telemetry paired with in-vehicle UPS and stationary TPPL banks enables suppliers to sell multi-year uptime guarantees.
Lead Acid Battery Market by Country (2026 to 2036)
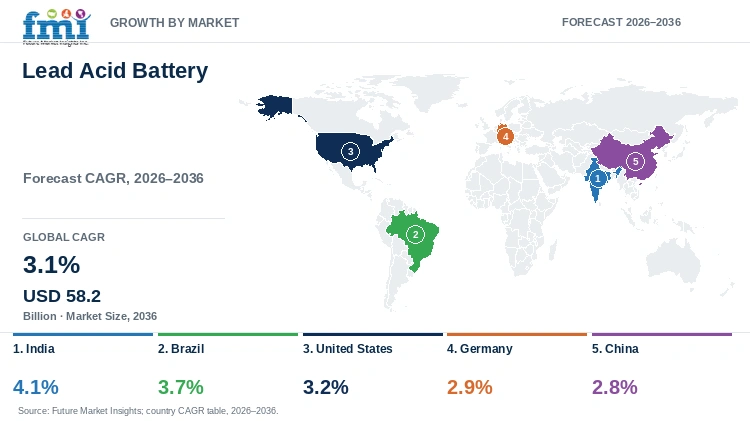
FMI country modeling indicates that Brazil leads national expansion at a 4.3% CAGR through 2036, followed closely by Mexico at 4.2%, India at 4.0% and Canada at 3.6%. Australia tracks at 3.5% ahead of the United States at 3.3%, the United Kingdom at 3.1%, and Germany at 2.9% across automotive and industrial battery channels.
Table 7: Country CAGR and Primary Growth Levers for the Lead Acid Battery Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 4.3% | Heat-accelerated automotive aftermarket replacement cycles and telecom/agribusiness fleets |
| Mexico | 4.2% | OEM passenger car and heavy truck export assembly plus primary/secondary lead refining |
| India | 4.0% | Two-wheeler, tractor, and commercial vehicle replacement fleets plus telecom/inverter backup |
| Canada | 3.6% | Sub-zero winter high-CCA AGM replacement demand and 31% share of US refined lead imports |
| Australia | 3.5% | Mining haul-truck fleets, off-grid outback telecom repeaters, and dual-battery utility vehicles |
| United States | 3.3% | 60% new-vehicle AGM penetration, hyperscale data center UPS expansion, and 45X tax credits |
| United Kingdom | 3.1% | Aftermarket start-stop AGM upgrades and 83GW grid-substation switchgear backup power |
| Germany | 2.9% | OEM 12V AGM auxiliary batteries for electric/hybrid cars and warehouse motive traction fleets |
Source: Future Market Insights analysis
Brazil Lead Acid Battery Market Outlook (2026 to 2036)
Demand for lead acid batteries in Brazil is projected to expand at a leading 4.3% CAGR between 2026 and 2036, driven by an aging national passenger car and agricultural machinery parc as well as 5G telecommunications tower backup installations. What sets Brazil apart from cooler European markets is how high year-round tropical temperatures accelerate positive-grid corrosion in automotive starter batteries, shortening aftermarket replacement cycles to under 36 months. Electrochemical recycling research published in Applied Sciences in August 2026 confirmed that wet-melt quenching recovery of secondary lead from spent lead-acid battery paste preserves high purity and electrochemical cycling stability for new replacement plates. Strict reverse-logistics recycling mandates enforced by Brazil's national environmental council further consolidate volume among licensed domestic battery makers.
Key takeaway: In Brazil, heat-accelerated automotive aftermarket replacement cycles and agribusiness machinery demand are projected to drive a 4.3% CAGR through 2036.
Mexico Lead Acid Battery Market Outlook (2026 to 2036)
Mexico's lead-acid battery demand is anticipated to advance at a 4.2% CAGR from 2026 to 2036 as export-oriented passenger vehicle and heavy truck assembly plants in Nuevo Leon and Guanajuato scale output. Compared with mature replacement-only markets, Mexico benefits from a dual engine of factory-installed original equipment SLI and AGM batteries for North American vehicle exports and cross-border secondary lead refining. Mineral trade publications released by USGS analysts confirm that Mexico supplied 15.0% of United States refined lead imports while ranking among the world's top five primary lead mining nations. Close integration between Monterrey battery plants and Texas automotive corridors sustains high factory utilization.
Key takeaway: In Mexico, expanding OEM vehicle export assembly and integrated North American lead refining are anticipated to support a 4.2% CAGR through 2036.
India Lead Acid Battery Market Outlook (2026 to 2036)
Rapid growth across two-wheeler, commercial three-wheeler, tractor and telecom backup fleets places India on course to record a 4.0% CAGR through 2036. Rather than relying solely on four-wheel passenger cars, Indian battery consumption spans hundreds of millions of motorcycles, residential home-inverter backup units and solar microgrid installations requiring tubular flooded and VRLA batteries. On July 16, 2026, Indian battery manufacturer Amara Raja commissioned its new Customer Qualification Plant in Telangana while reporting 1.0 gigawatt-hour of telecom network storage deployments and 21.0% year-on-year revenue growth in the first quarter of fiscal 2027. Formalization of Extended Producer Responsibility recycling rules continues shifting share from unorganized rebuilders to branded manufacturers.
Key takeaway: In India, massive two-wheeler and tractor replacement fleets as well as home-inverter and telecom backup demand are forecast to sustain a 4.0% CAGR through 2036.
Canada Lead Acid Battery Market Outlook (2026 to 2036)
In Canada, national battery demand is estimated to progress at a 3.6% CAGR between 2026 and 2036. Extreme sub-zero winter cranking requirements and primary and secondary lead smelting in British Columbia and Ontario support domestic sales. Sub-zero winter temperatures across Canadian provinces reduce available battery capacity while increasing engine oil viscosity, compelling vehicle owners to purchase high-cold-cranking-ampere AGM starter batteries. Statistics Canada reported in October 2026 that industrial and non-residential equipment and construction indexes rose across Quebec and Western provinces in the third quarter of 2026. Strong cross-border trade in spent battery cores and refined lead bullion underpins Canadian manufacturing stability.
Key takeaway: In Canada, severe winter cold-cranking replacement demand and leading North American refined lead export capacity are estimated to drive a 3.6% CAGR through 2036.
Australia Lead Acid Battery Market Outlook (2026 to 2036)
Australia's lead acid battery sector is forecast to grow at a 3.5% CAGR over the 2026 to 2036 horizon, supported by heavy mining haul-truck fleets and remote off-grid telecommunications repeaters. What distinguishes Australia from densely populated urban markets is its reliance on deep-cycle AGM and gel batteries capable of withstanding severe outback vibration and high ambient heat across remote Western Australian and Queensland mine sites. In its 2025 Integrated Annual Report, GS Yuasa Corporation highlighted its established Australian aftermarket distribution position and industrial backup power systems serving regional utility and transport infrastructure. High domestic lead mineral reserves further support Australia's role in Asia-Pacific raw material supply chains.
Key takeaway: In Australia, mining equipment auxiliary power, remote telecom off-grid storage and dual-battery utility vehicles are forecast to maintain a 3.5% CAGR through 2036.
United States Lead Acid Battery Market Outlook (2026 to 2036)
Commercial and consumer replacement demand across a 285-million-vehicle domestic fleet positions the United States to expand at a projected 3.3% CAGR from 2026 to 2036. Beyond passenger car and Class 8 truck replacement, hyperscale cloud data centers in Texas and Virginia are driving steady procurement of stationary VRLA UPS banks and stationary battery storage units. The U.S. Energy Information Administration projected in February 2026 that utility-scale battery storage additions across the U.S. grid will reach a record 24 gigawatts in 2026 compared with 15 gigawatts in 2025. Domestic Section 45X manufacturing tax credits further incentivize U.S. cell and plate production.
Key takeaway: In the United States, high AGM penetration across start-stop and electric vehicles as well as data center UPS expansion is projected to support a 3.3% CAGR through 2036.
United Kingdom Lead Acid Battery Market Outlook (2026 to 2036)
British consumption of lead acid batteries is slated to advance at a 3.1% CAGR through 2036 as start-stop AGM vehicle replacements and uninterruptible power supply installations for financial and hospital infrastructure offset mature standard flooded volume. Compared with continental automotive manufacturing hubs, the British market is predominantly aftermarket and service-driven, with substation protection and grid-ancillary backup adding steady industrial orders. On September 17, 2026, UK energy regulator Ofgem announced reforms prioritizing 83 gigawatts of shortlisted grid-level storage projects plus 7 gigawatts of operational battery capacity to secure national clean-power transmission. Every new high-voltage substation and wind interconnect requires dedicated 110-volt or 48-volt stationary lead-acid switchgear tripping batteries.
Key takeaway: In the United Kingdom, aftermarket conversion toward start-stop AGM batteries and grid substation backup systems are slated to sustain a 3.1% CAGR through 2036.
Germany Lead Acid Battery Market Outlook (2026 to 2036)
Germany's automotive and industrial battery sector is predicted to expand at a 2.9% CAGR from 2026 through 2036, supported by premium original equipment 12-volt AGM auxiliary batteries for electric and hybrid vehicles plus industrial warehouse forklift fleets. In contrast to developing markets where conventional flooded batteries dominate, German automakers and logistics operators specify high-rate AGM, gel and thin-plate pure lead designs paired with battery energy storage system power electronics. In January 2026, Exide Technologies showcased its next-generation AGM, enhanced flooded and commercial vehicle xEV auxiliary battery lineup across European aftermarket and OEM channels. Stringent European Union Battery Regulation carbon-footprint declarations and recycled-lead content targets reward integrated European smelter-manufacturers.
Key takeaway: In Germany, OEM auxiliary AGM batteries for electrified vehicle platforms and automated intralogistics motive fleets are predicted to maintain a 2.9% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Lead Acid Battery Market?
Clarios LLC (formerly Johnson Controls Power Solutions), GS Yuasa Corporation, Exide Technologies LLC, EnerSys, East Penn Manufacturing Company Inc., Camel Group Co. Ltd, Amara Raja Energy and Mobility Limited, Exide Industries Limited, and Crown Battery Manufacturing Company are the notable companies in the lead acid battery market.
Competitive structure across the lead acid battery sector divides vertically integrated automotive SLI and AGM power leaders, industrial motive and telecom standby specialists, and deep-cycle commercial battery producers. Clarios, GS Yuasa, Exide Technologies and East Penn operate high-speed automotive grid lines and closed-loop secondary lead smelters. EnerSys and Camel Group, Amara Raja and Exide Industries supply industrial motive traction, data center UPS and Asian automotive fleets while Trojan Battery and Crown Battery anchor deep-cycle golf cart and renewable backup markets.
- Global Automotive SLI and AGM Power Leaders: Clarios and GS Yuasa, Exide Technologies and East Penn manufacture flooded, EFB and AGM automotive starting and auxiliary batteries supported by captive lead recycling.
- Industrial Motive and Regional Fleet Specialists: EnerSys and Camel Group plus Amara Raja and Exide Industries produce thin-plate pure lead UPS banks and warehouse forklift traction packs.
- Deep-Cycle Motive and Telecom Backup Producers: Crown Battery Manufacturing Company engineer thick-plate lead-antimony and AGM deep-cycle batteries for golf carts, aerial work platforms, and off-grid solar storage.
Competitive Benchmarking: Lead Acid Battery Market
Table 8: Competitive Benchmarking for the Lead Acid Battery Market (qualitative capability ratings), 2026
| Company | Automotive AGM & xEV Auxiliary Scale | Industrial Motive & Data Center UPS Reach | Closed-Loop Lead Smelting Integration | Geographic Reach |
|---|---|---|---|---|
| Clarios LLC | High | Low | High | Global leader supplying 1 in 3 automotive batteries globally across North America, LatAm, Europe, and Asia |
| GS Yuasa Corporation | High | High | Medium | Japan, ASEAN, Europe, and Australia automotive SLI/AGM and industrial UPS/substation backup systems |
| Exide Technologies LLC | High | High | High | Pan-European automotive AGM PRO, commercial truck, and GNB/Solition industrial motive and standby power |
| EnerSys | Medium | High | Medium | Global leader in DataSafe/PowerSafe UPS, Hawker/NexSys motive forklift TPPL, and Odyssey AGM batteries |
| East Penn Manufacturing Company Inc. | High | High | High | Largest single-site integrated battery and smelting complex in North America (Lyon Station, PA); Deka brand |
| Camel Group Co. Ltd | High | Medium | High | Largest Chinese automotive SLI, EFB, and AGM starter battery manufacturer with expanding overseas hubs |
| Amara Raja Energy and Mobility Limited | High | High | High | Leading Indian Amaron automotive and PowerZone telecom/UPS battery producer exporting to 50+ countries |
| Exide Industries Limited | High | High | High | Largest Indian automotive, motorcycle, home-inverter, and industrial submarine/rail battery manufacturer |
| Crown Battery Manufacturing Company | Medium | High | Medium | North American manufacturer of heavy-duty deep-cycle motive, rail, marine, and renewable backup batteries |
Key Players in the Lead Acid Battery Market
Global Automotive SLI and AGM Power Leaders
- Clarios LLC (formerly Johnson Controls Power Solutions)
- GS Yuasa Corporation
- Exide Technologies LLC
- East Penn Manufacturing Company Inc.
Industrial Motive, Standby UPS, and Regional Fleet Specialists
- EnerSys
- Camel Group Co. Ltd
- Amara Raja Energy and Mobility Limited
- Exide Industries Limited
Deep-Cycle Motive and Telecom Backup Producers
- Crown Battery Manufacturing Company
Lead Acid Battery Market - Report Scope
Table 9: Report Scope for the Lead Acid Battery Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Battery Construction; Sales Channel; Functional Application; Grid Alloy Architecture; Voltage Class |
| Quantitative Units | USD Billion |
| Market Definition | Includes manufacturer revenue from flooded wet cell, enhanced flooded (EFB), valve-regulated absorbent glass mat (AGM), and VRLA gel lead-acid batteries across automotive SLI/auxiliary, industrial motive power, stationary telecom/UPS standby, and off-grid renewable storage applications. Category Scope Note: Excludes standalone lithium-ion, nickel-cadmium, and sodium-ion battery packs, unrefined secondary lead bullion sales, and external charger hardware. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, Mexico, India, Canada, Australia, United States, United Kingdom, Germany, and additional countries in the full report |
| Key Companies Covered | Clarios LLC, GS Yuasa Corporation, Exide Technologies LLC, EnerSys, East Penn Manufacturing Company Inc., Camel Group Co. Ltd, Amara Raja Energy and Mobility Limited, Exide Industries Limited, Crown Battery Manufacturing Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down refined lead consumption and bottom-up vehicle parc/UPS unit triangulation. |
Lead Acid Battery Market - Research Methodology
Table 10: Research Methodology for the Lead Acid Battery Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with automotive OEM low-voltage electrical architects, retail aftermarket battery buyers, data center UPS engineers, and secondary lead smelter operations directors. |
| Secondary Research | Analysis of USGS Mineral Commodity Summaries (2025 and 2026 Lead circulars), ILZSG lead balances, IEA Global Energy Review 2026 UPS data, Battery Council International shipment reports, and IEEE Std 1188-2025. |
| Market Sizing and Forecasting | Top-down global battery shipments reconciled against bottom-up refined lead consumption (13.45M MT in 2026), vehicle parc replacement rates, and AGM/VRLA unit price mix from 2026 to 2036. |
| Country Forecasting Model | Econometric national models weight motor vehicle fleet growth, climate-adjusted battery replacement intervals, telecom and data center backup installations, and domestic smelting capacity across eight countries. |
| Operational Benchmark Traceability | Feedstock, fleet, and UPS indicators in Tables 2, 3, and 4 trace to USGS 2026 domestic lead consumption records (67% battery share), BCI 2026 AGM vehicle share (60%), and IEA 2025 UPS additions (45 GW). |
| Data Triangulation and Validation | Revenue figures isolate finished lead-acid battery cells, monoblocs, and industrial strings while strictly excluding lithium-ion cells, external charging rectifiers, and raw lead commodity trading. |
Lead Acid Battery Market by Segments
Lead Acid Battery Market segmented by Battery Construction:
- Flooded Wet Cell Lead Acid Batteries
- Valve Regulated Lead Acid (VRLA) Absorbent Glass Mat (AGM)
- Valve Regulated Lead Acid (VRLA) Gel Batteries
- Enhanced Flooded Battery (EFB) Start-Stop Systems
Lead Acid Battery Market segmented by Sales Channel:
- Aftermarket Replacement Battery Sales
- Original Equipment Manufacturer (OEM) Factory Installed
- Industrial Fleet and Warehouse Direct Contracts
- Authorized Commercial Distributors and E-Commerce
Lead Acid Battery Market segmented by Functional Application:
- SLI (Starting, Lighting, and Ignition for Automotive)
- Motive Power (Forklifts, AGVs, and Golf Carts)
- Stationary Standby (Telecommunications Towers and UPS)
- Renewable Energy Off-Grid Storage Backups
- Marine, Commercial Rail, and Defense Auxiliary Power
Lead Acid Battery Market segmented by Grid Alloy Architecture:
- Lead-Calcium Maintenance-Free Alloys
- Lead-Antimony Deep-Cycle Industrial Alloys
- Pure Lead Thin-Plate (TPPL) High-Rate Grids
- Lead-Carbon Bipolar and Hybrid Negative Plates
Lead Acid Battery Market segmented by Voltage Class:
- 12V Automotive and Auxiliary Modules
- 24V to 48V Motive and Mild-Hybrid Packs
- 2V Stationary Industrial Cells and String Banks
- 6V Deep-Cycle Commercial and Utility Blocks
Lead Acid Battery Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Geological Survey. (2026, February 10). Mineral Commodity Summaries 2026: Lead Consumption, Secondary Recycling, and Critical Mineral Addition. U.S. Department of the Interior.
- [2] Battery Council International. (2026, May 11). Lead batteries keep foothold in North American automotive battery market through 2028. BCI & CRU Market Intelligence Report.
- [3] International Energy Agency. (2026, March 18). Global Energy Review 2026: Battery Storage and Uninterruptible Power Supply Capacity Additions. IEA Publications Paris.
- [4] International Lead and Zinc Study Group. (2026, October 19). ILZSG October 2026 Press Release: World Refined Lead Metal Supply and Demand Balance. ILZSG Statistical Bulletin Lisbon.
- [5] EnerSys. (2026, May 20). EnerSys Reports Fourth Quarter and Full Year Fiscal 2026 Results. EnerSys Investor Relations.
- [6] Zhang, L., Wang, Y., & Chen, H. (2026, January 6). A Hybrid Machine Learning Model for Dynamic Electrolyte Level Detection of Lead-Acid Batteries Across Thermal Regimes. Sensors, 26(1), 214 (PubMed Central PMC12846131).
- [7] Battery Council International. (2026, May 12). BCI and CRU publish new report on North American replacement and OE lead battery market trends. Battery Council International Newsroom.
- [8] International Organization of Motor Vehicle Manufacturers. (2026, April 24). New passenger car registrations and electrified vehicle fleet shares in Q1 2026. OICA & ACEA Statistical Releases.
- [9] Siekierski, M. S., Wieczorek, W., & Żukowska, G. Z. (2026, September 18). Industrial Ageing of Field-Deployed Lead-Acid Batteries I: A Case Study of Post-Industrial VRLA Batteries. Applied Sciences, 16(18), 9272 (MDPI Open Access).
- [10] Clarios LLC. (2026, January 6). Clarios Showcases Low-Voltage 12V to 48V AGM, Supercapacitor, and Power Management Systems at CES 2026. Clarios Corporate Technology Releases.
- [11] EnerSys. (2026, January 22). Data Centers in 2026: Five Trends Reshaping Power, Cost, and Backup Battery Resilience. EnerSys Technical Insights.
- [12] Argonne National Laboratory. (2026, August 19). Estimated Cost and Performance Benchmarks of Automotive Battery Packs: 2019 to 2026 GPRA Assessment. U.S. Department of Energy BatPaC Report.
- [13] IEEE Standards Association. (2025, November 14). IEEE Std 1188-2025: Recommended Practice for Maintenance, Testing, and Replacement of Valve-Regulated Lead-Acid (VRLA) Batteries for Stationary Applications. Institute of Electrical and Electronics Engineers.
- [14] Piscoiu, D. N., Rada, S., & Suciu, R. C. (2026, August 4). Industrial Aging and Electrochemical Characterization of Recovered Lead from Lead-Acid Battery Recycling. Applied Sciences, 16(18), 9279 (MDPI Open Access).
- [15] U.S. Geological Survey. (2025, March 15). Mineral Commodity Summaries 2025: Global Mine Production and Refined Lead Trade Flows across Mexico, Canada, and Australia. U.S. Department of the Interior.
- [16] Amara Raja Energy & Mobility Limited. (2026, July 16). Amara Raja Commissions Customer Qualification Plant and Expands Automotive and Telecom Battery Operations. Amara Raja Official Media Releases.
- [17] Statistics Canada. (2026, October 29). Industrial and non-residential construction and equipment price indexes, third quarter 2026. The Daily, Statistics Canada.
- [18] GS Yuasa Corporation. (2025, October 30). GS Yuasa Report 2025: Integrated Annual Report on Automotive Lead-Acid and Industrial Backup Power Systems. GS Yuasa Investor Relations Library.
- [19] U.S. Energy Information Administration. (2026, February 20). New U.S. electric generating and battery storage capacity expected to reach a record high in 2026. Today in Energy, U.S. Department of Energy.
- [20] Office of Gas and Electricity Markets (Ofgem). (2026, September 17). Ofgem moves to free up grid capacity by prioritizing 83GW of operational and shortlisted UK battery storage projects. UK Government Regulatory Press Releases.
- [21] Exide Technologies. (2026, January 14). Exide Technologies showcases next-generation AGM and commercial vehicle batteries at Automässan 2026. Exide Group European Newsroom.
- [22] Exide Technologies. (2026, September 8). Exide introduces updated commercial vehicle AGM PRO range and Solition Powerflex storage at Automechanika Frankfurt 2026. Exide Group Official News Releases.
- [23] EnerSys. (2026, June 10). EnerSys introduces EZSelect Lite real-time industrial motive battery room monitoring system. EnerSys Corporate Newsroom.
- [24] GS Yuasa Corporation. (2026, May 15). Consolidated Earnings Forecast for the Fiscal Year Ending March 2027 and Replacement Battery Price Revisions. GS Yuasa Investor Relations.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the lead acid battery market in 2026 and what is forecast for 2036?
- Which automotive replacement, xEV auxiliary safety, and data center UPS drivers support demand for lead acid batteries?
- Why do Flooded Wet Cell Lead Acid Batteries lead the battery construction category?
- Why do Aftermarket Replacement Battery Sales lead the sales channel category globally?
- How do growth rates differ across Brazil and Mexico and India, Canada, Australia and the United States?
- Which leading companies control closed-loop secondary lead smelting as well as AGM and TPPL production today?
- What sulfation ageing and lithium-ion cost-parity pressures restrain deep-cycle industrial segments?
- What should fleet managers and data center engineers evaluate when selecting between flooded, AGM, and TPPL batteries?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Battery Construction, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Battery Construction, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Battery Construction, 2026 to 2036
- Flooded Wet Cell Lead Acid Batteries
- Valve Regulated Lead Acid (VRLA) Absorbent Glass Mat (AGM)
- Valve Regulated Lead Acid (VRLA) Gel Batteries
- Enhanced Flooded Battery (EFB) Start-Stop Systems
- Y-o-Y Growth Trend Analysis By Battery Construction, 2021 to 2025
- Absolute $ Opportunity Analysis By Battery Construction, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Aftermarket Replacement Battery Sales
- Original Equipment Manufacturer (OEM) Factory Installed
- Industrial Fleet and Warehouse Direct Contracts
- Authorized Commercial Distributors and E-Commerce
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Functional Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Functional Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Functional Application, 2026 to 2036
- SLI (Starting, Lighting, and Ignition for Automotive)
- Motive Power (Forklifts, AGVs, and Golf Carts)
- Stationary Standby (Telecommunications Towers and UPS)
- Renewable Energy Off-Grid Storage Backups
- Marine, Commercial Rail, and Defense Auxiliary Power
- Y-o-Y Growth Trend Analysis By Functional Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Functional Application, 2026 to 2036
- Global Market Analysis and Forecast, By Grid Alloy Architecture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Grid Alloy Architecture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Grid Alloy Architecture, 2026 to 2036
- Lead-Calcium Maintenance-Free Alloys
- Lead-Antimony Deep-Cycle Industrial Alloys
- Pure Lead Thin-Plate (TPPL) High-Rate Grids
- Lead-Carbon Bipolar and Hybrid Negative Plates
- Y-o-Y Growth Trend Analysis By Grid Alloy Architecture, 2021 to 2025
- Absolute $ Opportunity Analysis By Grid Alloy Architecture, 2026 to 2036
- Global Market Analysis and Forecast, By Voltage Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Voltage Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Voltage Class, 2026 to 2036
- 12V Automotive and Auxiliary Modules
- 24V to 48V Motive and Mild-Hybrid Packs
- 2V Stationary Industrial Cells and String Banks
- 6V Deep-Cycle Commercial and Utility Blocks
- Y-o-Y Growth Trend Analysis By Voltage Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Voltage Class, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- By Country
- Market Attractiveness Analysis
- By Country
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Battery Construction
- By Sales Channel
- By Functional Application
- By Grid Alloy Architecture
- By Voltage Class
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Clarios LLC
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- GS Yuasa Corporation
- Exide Technologies LLC
- EnerSys
- East Penn Manufacturing Company Inc.
- Camel Group Co. Ltd
- Amara Raja Energy and Mobility Limited
- Exide Industries Limited
- Crown Battery Manufacturing Company
- Clarios LLC (formerly Johnson Controls Power Solutions)
- Clarios LLC
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Battery Construction, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Functional Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Grid Alloy Architecture, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Voltage Class, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Battery Construction, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Functional Application, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Grid Alloy Architecture, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Voltage Class, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Battery Construction, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Functional Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Grid Alloy Architecture, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Voltage Class, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Battery Construction, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Functional Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Grid Alloy Architecture, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Voltage Class, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Battery Construction, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Functional Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Grid Alloy Architecture, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Voltage Class, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Battery Construction, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Functional Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Grid Alloy Architecture, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Voltage Class, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Battery Construction, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Functional Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Grid Alloy Architecture, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Voltage Class, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Battery Construction, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Functional Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Grid Alloy Architecture, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Voltage Class, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Battery Construction, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Battery Construction, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Battery Construction
- Figure 6: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Sales Channel
- Figure 9: Global Market Value Share and BPS Analysis by Functional Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Functional Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Functional Application
- Figure 12: Global Market Value Share and BPS Analysis by Grid Alloy Architecture, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Grid Alloy Architecture, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Grid Alloy Architecture
- Figure 15: Global Market Value Share and BPS Analysis by Voltage Class, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Voltage Class, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Voltage Class
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Battery Construction, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Battery Construction, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Battery Construction
- Figure 32: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Sales Channel
- Figure 35: North America Market Value Share and BPS Analysis by Functional Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Functional Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Functional Application
- Figure 38: North America Market Value Share and BPS Analysis by Grid Alloy Architecture, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Grid Alloy Architecture, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Grid Alloy Architecture
- Figure 41: North America Market Value Share and BPS Analysis by Voltage Class, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Voltage Class, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Voltage Class
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Battery Construction, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Battery Construction, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Battery Construction
- Figure 48: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 51: Latin America Market Value Share and BPS Analysis by Functional Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Functional Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Functional Application
- Figure 54: Latin America Market Value Share and BPS Analysis by Grid Alloy Architecture, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Grid Alloy Architecture, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Grid Alloy Architecture
- Figure 57: Latin America Market Value Share and BPS Analysis by Voltage Class, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Voltage Class, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Voltage Class
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Battery Construction, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Battery Construction, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Battery Construction
- Figure 64: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 67: Western Europe Market Value Share and BPS Analysis by Functional Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Functional Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Functional Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by Grid Alloy Architecture, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Grid Alloy Architecture, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Grid Alloy Architecture
- Figure 73: Western Europe Market Value Share and BPS Analysis by Voltage Class, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Voltage Class, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Voltage Class
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Battery Construction, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Battery Construction, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Battery Construction
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Functional Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Functional Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Functional Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Grid Alloy Architecture, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Grid Alloy Architecture, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Grid Alloy Architecture
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Voltage Class, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Voltage Class, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Voltage Class
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Battery Construction, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Battery Construction, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Battery Construction
- Figure 96: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 99: East Asia Market Value Share and BPS Analysis by Functional Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Functional Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Functional Application
- Figure 102: East Asia Market Value Share and BPS Analysis by Grid Alloy Architecture, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Grid Alloy Architecture, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Grid Alloy Architecture
- Figure 105: East Asia Market Value Share and BPS Analysis by Voltage Class, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Voltage Class, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Voltage Class
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Battery Construction, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Battery Construction, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Battery Construction
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Functional Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Functional Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Functional Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Grid Alloy Architecture, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Grid Alloy Architecture, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Grid Alloy Architecture
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Voltage Class, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Voltage Class, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Voltage Class
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Battery Construction, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Battery Construction, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Battery Construction
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Functional Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Functional Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Functional Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Grid Alloy Architecture, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Grid Alloy Architecture, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Grid Alloy Architecture
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Voltage Class, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Voltage Class, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Voltage Class
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Lead Acid Battery Market in 2026, and what is forecast for 2036?
FMI estimates that global lead acid battery industry size stood at USD 52.0 billion in 2025 and reached USD 53.8 billion in 2026. Overall sector valuation is projected to hit USD 75.9 billion by 2036 as vehicle aftermarket replacement and data center UPS backup demand expand.
What is the CAGR for the Lead Acid Battery Market from 2026 to 2036?
The lead acid battery sector is projected to expand at a 3.5% CAGR over the 2026 to 2036 forecast window, generating USD 22.1 billion in incremental revenue across automotive, motive and stationary standby applications.
Which battery construction segment leads the Lead Acid Battery Market?
Flooded Wet Cell Lead Acid Batteries hold an estimated 58.0% of battery construction demand in 2026 since low-cost liquid-electrolyte designs remain the standard for global passenger car and commercial truck starting.
Which sales channel segment leads the Lead Acid Battery Market?
Aftermarket Replacement Battery Sales represent 78.0% of the sales channel category in 2026 as recurring three-to-five-year replacement intervals across the installed vehicle parc generate non-cyclical unit turnover.
Which country has a notable growth outlook during the assessment period?
Brazil leads national expansion projections at a 4.3% CAGR through 2036, followed closely by Mexico at a 4.2% CAGR and India at a 4.0% CAGR.
Who are the key players in the market?
Clarios and GS Yuasa and Exide Technologies and EnerSys and East Penn and Camel Group and Amara Raja, Exide Industries, Trojan Battery and Crown Battery lead global supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
