

- Market Size (2026)
- USD 50.0 Bn
- Forecast (2036)
- USD 259.6 Bn
- CAGR (2026 to 2036)
- 17.9%
How big is Plug-in Hybrid Electric Vehicles (PHEV) Market in 2026?
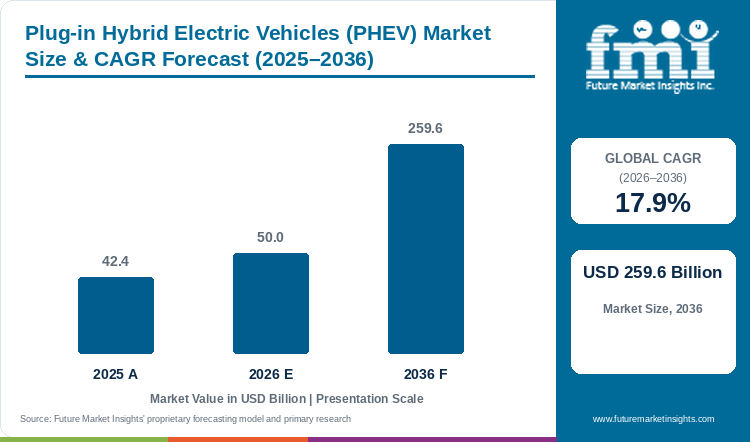
Plug-in hybrid electric vehicle market size stood at USD 42.4 billion in 2025, rising to an estimated USD 50.0 billion in 2026 and projected at USD 259.6 billion by 2036, at 17.9% CAGR from 2026 to 2036.
PHEV registrations across Europe reached 1.27 million units in 2025, a 34 percent year-on-year increase from 0.95 million in 2024, raising the PHEV share of new-car sales to 9.5 percent [1]. The 2025 EU fleet-average target of 93.6 g CO2/km, carrying a fine of EUR 95 per car per gram above the limit, turned PHEVs into a compliance tool that several volume manufacturers accelerated into production [2]. Germany introduced purchase subsidies of up to EUR 4,500 for plug-in hybrids meeting a minimum 80 km electric-range threshold in January 2026, backed by a programme budget of nearly EUR 3 billion [3]. The total cost of ownership and adoption intensity analysis for this report benchmarks PHEV purchase prices, fuel and electricity running costs, government incentives, charging access and annual mileage against battery-electric and internal-combustion alternatives across the profiled countries. When home or workplace charging is available and daily commutes fall within the vehicle's electric range, a PHEV delivers lower per-kilometre energy cost than a comparable ICE model and avoids the range limitation that constrains BEV adoption in markets with sparse fast-charging networks.
Adoption of PHEV powertrains reached 6.86 million units worldwide in 2025, equivalent to 7.5 percent of global new-car sales, up from 6.44 million units and 7.0 percent in 2024 [1]. BYD shipped approximately 2.32 million PHEVs in 2025, representing roughly half of the company's total 4.6 million vehicle output and confirming the commercial weight of dual-mode platforms in the Chinese market. BMW reported 25,351 PHEV deliveries in the United States for 2025, a 30.7 percent increase over 19,398 units in 2024, even as the brand's battery-electric sales declined 16.7 percent in the same period. FMI expects the cost-of-ownership advantage over pure ICE vehicles, combined with OEM portfolio breadth and regulatory pressure, to sustain PHEV demand growth through 2036.
Key Market Trends & Insights
- Passenger cars accounted for 78.4% of PHEV demand in 2026 as personal buyers in Europe and North America chose plug-in hybrids for daily commuting within electric range, keeping combustion backup for longer trips. The Ford Kuga PHEV finished 2024 as the best-selling plug-in hybrid in the Netherlands for a fourth consecutive year with 4,123 units [4].
- Combined (series-parallel) hybrid architectures held the leading share of powertrain demand in 2026, led by high-volume platforms such as BYD's DM-i, which pairs series-style EV-first city driving with parallel-style highway efficiency. FMI notes that this design lets automakers address both urban electric-only use and longer-distance combustion backup from a single platform.
Regional Highlights
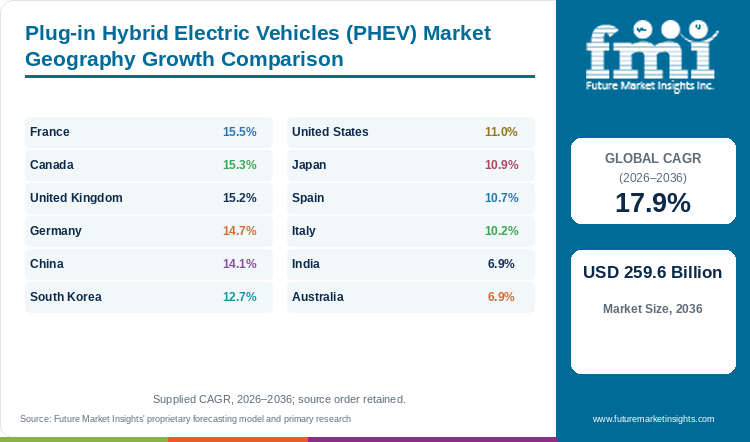
- FMI finds that France recorded the fastest profiled CAGR at 15.5% over 2026 to 2036.
- Canada (15.3%) and the United Kingdom (15.2%) follow. India and Australia register the lowest profiled rates at 6.9% each.
- PHEV registrations in Australia doubled in the first half of 2025 to 25,613 units, reaching 4.1% of new-vehicle sales, led by PHEV utes and SUVs.
Market Size & Forecast
Table 1: Market Size and Forecast for the Plug-in Hybrid Electric Vehicles (PHEV) Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 42.4 billion |
| Estimated Market Size in 2026 | USD 50.0 billion |
| Projected Market Size by 2036 | USD 259.6 billion |
| CAGR, 2026 to 2036 | 17.9% |
| Added Market Value, 2026 to 2036 | USD 209.6 billion |
| Market Expansion Multiple | 5.2x |
Sales of plug-in hybrids are gaining from two reinforcing cycles: regulatory tightening that compels automakers to electrify portfolios, and consumer willingness to pay a premium for vehicles that cut fuel bills without requiring dedicated fast-charging stops. China accounted for 5.23 million PHEV units in 2025, up from 5.1 million in 2024, with the PHEV share of new-car sales climbing from 15 percent in the first half to 20 percent in the second half of the year [1]. However, high upfront purchase prices relative to equivalent ICE models, and the added weight of carrying both a battery pack and an internal combustion engine, remain barriers in price-sensitive markets. FMI projects that lithium-ion battery cost reductions and extended electric-range specifications will widen the addressable buyer pool through 2036.
Total Cost of Ownership and Adoption Intensity Analysis
Under the total cost of ownership and adoption intensity analysis of the plug-in hybrid electric vehicles (PHEV) market, purchase price, fuel and electricity expense, incentive value, charging access and typical annual mileage are evaluated for each profiled country.
Table 2: Total Cost of Ownership and Adoption Intensity Indicators for the Plug-in Hybrid Electric Vehicles (PHEV) Market (mixed units), reporting years from 2024 to 2026
| Indicator | Data Point | Why This Matters | Source |
|---|---|---|---|
| Global PHEV unit sales, 2025 | 6.86 million units (7.5% of new-car sales) | Sets the volume baseline used for market sizing | [1] |
| Germany PHEV purchase subsidy, 2026 | Up to EUR 4,500 per vehicle (80 km minimum electric range) | Lowers effective purchase price, narrowing the TCO gap vs ICE | [3] |
| EU fleet CO2 target, 2025 | 93.6 g CO2/km; EUR 95 fine per car per gram over | Creates compliance demand from OEMs irrespective of retail pull | [2] |
| Europe PHEV registration growth, 2024–2025 | 34% year-on-year (0.95 M to 1.27 M units) | Confirms rising adoption intensity across the largest regulated market | [1] |
| BYD PHEV output, 2025 | Approximately 2.32 million units (50.4% of total output) | Demonstrates scale economics achievable through integrated battery-vehicle manufacturing | - |
Analyst Perspective
"Plug-in hybrid vehicle demand stands at the intersection of regulatory mandates and consumer range confidence. OEMs that match longer electric-only range with competitive sticker prices will capture share as fleet CO2 targets contract further in 2030."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Plug-in Hybrid Electric Vehicles (PHEV) market segmented?
The plug-in hybrid electric vehicles (PHEV) market is segmented by three primary commercial axes and region: vehicle type, powertrain, and region. In 2026, passenger cars are projected at 78.4% of vehicle type demand, and combined (series-parallel) hybrid architectures, led by platforms such as BYD's DM-i, hold the leading share of powertrain demand, with segmentation details for each axis reported below.
By vehicle type: Passenger Car, Light Commercial Vehicle.
By powertrain: Series Hybrid, Parallel Hybrid, Combined Hybrid.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do passenger cars retain a dominant vehicle type share in the PHEV market?
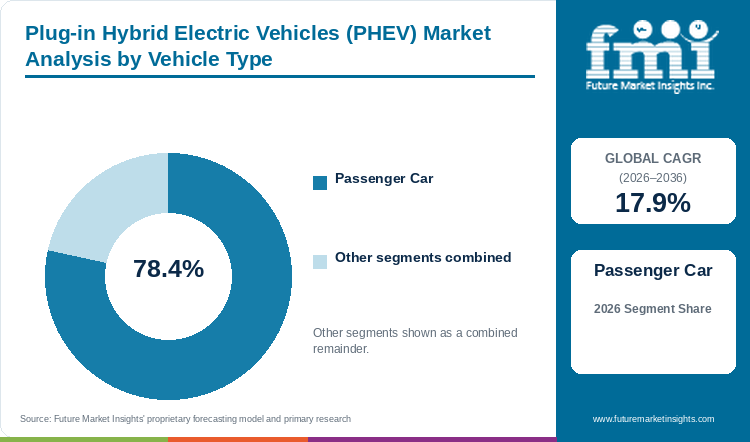
Passenger cars are projected at 78.4% of PHEV vehicle type demand in 2026, supported by broader model availability, consumer incentive eligibility and established home-charging patterns.
Table 3: Vehicle Type Share for the Plug-in Hybrid Electric Vehicles (PHEV) Market (percentage share), 2026
| Vehicle Type | Share (2026) |
|---|---|
| Passenger Car | 78.4% |
| Light Commercial Vehicle (remaining share) | Small remaining share |
| Total | 100% |
*Represents the balance remaining after the leading segment's reported share, which totals 100%.
Table 4: Vehicle Type Leadership and Market Growth for the Plug-in Hybrid Electric Vehicles (PHEV) Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 17.9% |
| Leading Segment | Passenger Car |
Demand for plug-in hybrid passenger cars draws on a combination of personal-use commuting patterns, government incentives structured around retail buyers and expanding model ranges from volume OEMs. In the FMI report, passenger cars account for 78.4% of PHEV revenue in 2026. Toyota rebranded the RAV4 Prime and Prius Prime as RAV4 PHEV and Prius PHEV for the 2025 model year, signalling a deliberate shift in marketing terminology toward the plug-in hybrid designation [5]. Volkswagen launched the Golf eHybrid and Golf GTE with up to 143 km of electric range and 50 kW DC fast-charging capability, positioned from EUR 44,240 in Europe [6]. Passenger car PHEVs are expected to remain the primary revenue segment as EV charging station coverage expands into suburban areas.
- Passenger cars account for 78.4% share in 2026, underpinned by model-range expansion from BMW, Toyota and Volkswagen.
- Incentive programmes in Germany, France and Canada target private buyers of passenger PHEVs, reinforcing the segment's revenue concentration.
What supports combined (series-parallel) hybrid powertrain leadership?
Combined (series-parallel) hybrid powertrains hold the leading share of PHEV powertrain demand in 2026, reflecting their flexibility across urban electric-only and longer-distance driving, as used in high-volume platforms such as BYD's DM-i.
Combined (series-parallel) hybrid systems let the combustion engine act as both a generator and, when efficient, a direct mechanical driver of the wheels, giving automakers flexibility across urban electric-only trips and longer combustion-assisted journeys. This architecture underpins high-volume platforms such as BYD's DM-i and has become the reference layout for mass-market PHEVs.
- Combined (series-parallel) hybrids hold the leading share of powertrain demand in 2026, owing to their flexibility across both urban electric-only and longer-distance driving.
- Manufacturing scale at platforms such as BYD's DM-i has positioned the combined architecture as the reference PHEV powertrain for mid-market vehicles.
Combined (series-parallel) architectures are increasingly the reference PHEV powertrain layout, concentrated in high-volume models designed for both urban electric-only and longer combustion-assisted trips.
What are the drivers, restraints, and opportunities in the Plug-in Hybrid Electric Vehicles (PHEV) market?
Fleet CO2 regulations and zero-emission vehicle mandates compel OEM investment in PHEVs. High battery-plus-engine weight and elevated purchase prices limit adoption in price-sensitive segments. Extended-range PHEV platforms that exceed 100 km of electric-only driving open the next commercial frontier.
- Driver: EU fleet-average CO2 targets and national ZEV mandates create compliance demand for electrified powertrains.
- Restraint: Dual-powertrain weight and battery cost keep PHEV sticker prices above ICE equivalents.
- Opportunity: Next-generation PHEVs with 100 km-plus electric range and DC fast charging narrow the functional gap to battery-electric vehicles.
Regulatory mandates accelerate OEM electrification schedules
Demand for plug-in hybrid platforms accelerated markedly after the EU lowered the fleet CO2 target to 93.6 g/km for 2025, a 15 percent reduction from the 2021 baseline, with a penalty of EUR 95 per gram per vehicle for non-compliance; a 2023 amendment lets manufacturers average compliance across 2025, 2026 and 2027 rather than meet the target in 2025 alone [2]. Automakers that had not scaled battery-electric sales fast enough turned to plug-in hybrid models as a near-term compliance lever. Canada's federal Electric Vehicle Availability Standard had set rising sales quotas that included PHEVs before being paused on September 5, 2025, in a market where 75 percent of ZEV registrations were BEVs and 25 percent were PHEVs through the iZEV incentive programme.
Purchase price premium constrains mass-market penetration
PHEV architectures carry both a combustion engine and a traction battery, adding weight and cost relative to single-powertrain alternatives. In price-sensitive markets such as India, public charging infrastructure remains sparse and mainstream PHEV models are few, and adoption has lagged behind other electrified categories. Gasoline-powered vehicles still accounted for 73 percent of Canada's new-car market in 2025, showing the inertia that price and infrastructure gaps create even in countries with active incentive programmes.
Extended-range platforms open a new adoption corridor
Volkswagen's 2024 Golf GTE delivers up to 143 km of WLTP electric range, compared with under 60 km for earlier-generation PHEVs, and supports 50 kW DC fast charging. Germany's 2026 subsidy programme sets the eligibility floor at 80 km of electric range, effectively requiring next-generation battery packs to qualify [3]. FMI projects that as PHEV electric ranges approach the daily driving distance of a majority of commuters, the vehicle's combustion engine will shift from a frequent-use system to a reserve for occasional long trips, improving both fuel economy and emission outcomes.
Which country CAGRs are profiled in the Plug-in Hybrid Electric Vehicles (PHEV) market?
Table 5: Country CAGR Comparison for the Plug-in Hybrid Electric Vehicles (PHEV) Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| France | 15.5% |
| Canada | 15.3% |
| United Kingdom | 15.2% |
| Germany | 14.7% |
| China | 14.1% |
| South Korea | 12.7% |
| United States | 11% |
| Japan | 10.9% |
| Spain | 10.7% |
| Italy | 10.2% |
| India | 6.9% |
| Australia | 6.9% |
How do country-level CAGRs compare in the Plug-in Hybrid Electric Vehicles (PHEV) market?
Western European countries and Canada cluster at the top of the profiled range. Binding CO2 or ZEV regulations, consumer purchase subsidies and dense charging networks converge there to pull demand forward. Under the total cost of ownership and adoption intensity analysis of the PHEV market, France (15.5%), Canada (15.3%) and the United Kingdom (15.2%) lead, and India and Australia (both 6.9%) sit at the bottom of the range, separated from the fastest market by 8.6 percentage points.
- France registers 15.5% CAGR through 2036 as coup de pouce retrofit incentives and low-emission zone policies accelerate passenger-car electrification.
- Canada posts 15.3% CAGR through 2036; the federal Electric Vehicle Availability Standard was paused on September 5, 2025, but the Mitsubishi Outlander PHEV's long-standing position as the top-selling plug-in hybrid under the iZEV programme continues to anchor demand.
- United Kingdom PHEV demand grows at 15.2% CAGR through 2036, sustained by OEM investment in meeting the UK's post-2030 emission standards.
- Germany records 14.7% CAGR through 2036; the 2026 purchase subsidy of up to EUR 4,500 for PHEVs with at least 80 km electric range refreshes buyer incentives after the 2023 expiry of the previous grant [3].
- China achieves 14.1% CAGR through 2036. PHEV market share climbed from 15 percent in the first half to 20 percent in the second half of 2025, propelled by BYD's DM-i combined hybrid and DM-p performance-oriented all-wheel-drive platforms [1].[1]
- South Korea PHEV demand advances at 12.7% CAGR through 2036, backed by Hyundai and Kia's expanding PHEV portfolio and smart-grid charging initiatives.
- United States PHEV market grows at 11% CAGR through 2036. BMW's US PHEV sales rose 30.7 percent to 25,351 units in 2025, outpacing the brand's own BEV line.
- Japan records 10.9% CAGR through 2036, moderated by the domestic market's stronger preference for non-plug-in hybrids, which accounted for roughly half of Toyota's Japanese sales in 2025.
- Spain posts 10.7% CAGR through 2036 as compact urban PHEVs gain traction among city commuters.
- Italy records 10.2% CAGR through 2036, the lowest among profiled Western European markets.
- India achieves 6.9% CAGR through 2036, constrained by limited public charging infrastructure and a small selection of locally assembled PHEV models.
- Australia matches India at 6.9% CAGR through 2036. PHEV registrations doubled in H1 2025 to 25,613 units, with BYD's Shark PHEV ute contributing significantly to the segment.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- Demand for plug-in hybrids in France is set to expand at 15.5% CAGR through 2036. France's coup de pouce incentive schemes and urban low-emission zones have historically favoured electrified powertrains, including PHEVs, even though the headline bonus ecologique purchase grant is reserved for battery-electric vehicles.[1]
- Adoption of PHEV powertrains in Canada is forecast at 15.3% CAGR through 2036. Canada's federal Electric Vehicle Availability Standard, which had set rising zero-emission vehicle sales quotas including PHEVs, was paused on September 5, 2025; the Mitsubishi Outlander PHEV and Toyota RAV4 Prime nonetheless remained among the five best-selling PHEVs under the iZEV programme from 2020 to 2024, together accounting for roughly 11 percent of total PHEV incentive claims. Long inter-city distances in western provinces continue to reinforce demand for plug-in hybrids with combustion backup.
- Sales of plug-in hybrids in the United Kingdom are anticipated to grow at 15.2% CAGR through 2036. UK OEMs and importers face post-2030 emission mandates that incentivise electrified model launches, and BMW's global PHEV momentum, including a 30.7 percent sales increase in the US in 2025, reflects brand-wide portfolio investment that feeds into the UK range. Expanding workplace and residential charging networks are expected to reduce the charging-access barrier that has limited PHEV adoption outside urban centres.
- PHEV revenue in Germany is projected at 14.7% CAGR through 2036. Germany's January 2026 subsidy programme offers up to EUR 4,500 per PHEV, conditional on a minimum 80 km electric range, backed by a total allocation of nearly EUR 3 billion across electrified vehicles [3]. Volkswagen's Golf eHybrid and GTE, priced from EUR 44,240 with up to 143 km electric range, entered production in 2024 as part of the group's compliance response to the EU's 93.6 g/km fleet target. These incentives and model launches will underpin the German PHEV market through the forecast decade.
- Key trends in PHEV registrations in China point to 14.1% CAGR through 2036. China's PHEV share of new-car sales reached 17.5 percent for full-year 2025, with the second-half share rising to 20 percent, led by BYD's DM-i combined hybrid platform and the performance-oriented, all-wheel-drive DM-p variant.
- Adoption of plug-in hybrid vehicles in South Korea is estimated at 12.7% CAGR through 2036. Hyundai and Kia's domestic market dominance provides a supply-side anchor, and government-backed smart-grid initiatives lower electricity costs for home-charged PHEVs. FMI expects the cost-of-ownership advantage to broaden as automotive electronics integration improves energy management.
- Demand for PHEVs in the United States is forecast at 11% CAGR through 2036. BMW delivered 25,351 PHEVs in the US in 2025, up 30.7 percent, even as the brand's BEV sales declined 16.7 percent to 42,484 units, showing a consumer swing toward dual-powertrain options. Nissan confirmed that the Rogue PHEV, sharing platform technology with the Mitsubishi Outlander PHEV, would reach US dealers in 2025 as the brand's first American-market plug-in hybrid. The federal Section 30D clean vehicle tax credit, which had applied to qualifying PHEVs, ended for vehicles acquired after September 30, 2025; broader model availability is expected to support US PHEV penetration even without this incentive.
- PHEV market growth in Japan is projected at 10.9% CAGR through 2036. Toyota's hybrid and PHEV production combined accounted for 42 percent of the company's 11.3 million global vehicle sales in 2025, and the company targets 6.7 million hybrid and PHEV units per year by 2028. Japan's established preference for non-plug-in hybrids moderates the PHEV-specific growth rate, though tighter domestic fuel-economy standards are expected to shift a share of demand toward plug-in variants.
- Sales of plug-in hybrid vehicles in Spain are projected at 10.7% CAGR through 2036. Spain's urban density and commuter patterns favour compact PHEVs, and automakers have introduced smaller models suited to city parking and low-emission zone access. Continued expansion of public charging points in Madrid and Barcelona is expected to improve daily charge reliability for PHEV owners.
- PHEV market expansion in Italy is projected at 10.2% CAGR through 2036. Italy's eco-bonus incentive system and urban traffic restrictions in Milan and Rome create regulatory pull for low-emission vehicles, though consumer price sensitivity keeps the adoption curve below that of northern European peers.
- Adoption of plug-in hybrids in India is forecast at 6.9% CAGR through 2036. Public charging infrastructure remains limited, and the PM E-DRIVE scheme, which replaced the FAME subsidy programme in 2024, has focused on battery-electric two-wheelers and buses instead of PHEVs. A small selection of locally available models constrains consumer choice, and growth will hinge on OEMs introducing PHEVs at price points competitive with premium ICE SUVs.
- PHEV registrations in Australia are estimated to grow at 6.9% CAGR through 2036. PHEV sales doubled in H1 2025 to 25,613 units, lifting the plug-in hybrid share to 4.1 percent of new-vehicle sales, with PHEV utes accounting for 10,755 units and PHEV SUVs for 14,386 units. Long intercity distances in regional areas and the gradual extension of charging networks will shape the pace of adoption through 2036.
Who are the notable companies in the Plug-in Hybrid Electric Vehicles (PHEV) market?
Toyota Motor Corporation, BMW AG, Volkswagen AG, Ford Motor Company, Renault SA, General Motors, Nissan Motor Corporation, Honda Motor Company, Mercedes-Benz Group AG, Mitsubishi Motors Corporation, BYD Company, Geely Automobile, Chery Automobile, Li Auto, and Seres Group (AITO) are among the companies operating in the global PHEV market.
Competition in the PHEV market spans global OEMs with diversified powertrain strategies, regional champions with dedicated plug-in hybrid platforms, and volume manufacturers building scale through integrated battery-vehicle supply chains. Product differentiation turns on electric range, charging speed, platform flexibility and the breadth of model lines covering sub-compact through full-size SUV segments.
- Global diversified OEMs: Toyota Motor Corporation, Volkswagen AG, General Motors, Mercedes-Benz Group AG, Honda Motor Company.
- European specialists and volume brands: BMW AG, Renault SA, Ford Motor Company.
- Asia-Pacific PHEV platform developers: Nissan Motor Corporation, Mitsubishi Motors Corporation, BYD Company, Geely Automobile, Chery Automobile, Li Auto, and Seres Group (AITO).
Competitive Benchmarking: Plug-in Hybrid Electric Vehicles (PHEV) Market
Table 6: Competitive Benchmarking for the Plug-in Hybrid Electric Vehicles (PHEV) Market (qualitative capability ratings), 2026
| Company | PHEV Model Range | Electric Range Capability | Charging Technology | Reach |
|---|---|---|---|---|
| Toyota Motor Corporation | High | Medium | Medium | High |
| BMW AG | High | High | High | High |
| Volkswagen AG | High | High | High | High |
| Ford Motor Company | Medium | Medium | Medium | High |
| Renault SA | Medium | Medium | Medium | High |
| General Motors | Medium | Medium | Medium | High |
| Nissan Motor Corporation | Low | Medium | Medium | High |
| Honda Motor Company | Low | Low | Medium | High |
| Mercedes-Benz Group AG | High | High | High | High |
| Mitsubishi Motors Corporation | Medium | Medium | Medium | Medium |
High reflects broader publicly documented PHEV model availability or technical specification; Medium reflects a narrower but active PHEV portfolio; Low reflects limited current PHEV presence. Ratings reflect publicly documented model availability and do not indicate product quality or market position.
Key Developments in the Plug-in Hybrid Electric Vehicles (PHEV) Market
- In January 2026, Germany introduced purchase subsidies of up to EUR 4,500 for plug-in hybrid vehicles meeting a minimum 80 km electric-range requirement, as part of a nearly EUR 3 billion electrified-vehicle programme [3].
- In 2025, GM reported 102,459 global PHEV sales for the year, selling primarily in markets outside the United States, and signalled that PHEV variants may return to North America.
- In May 2024, Volkswagen launched the Golf eHybrid and Golf GTE with second-generation plug-in hybrid powertrains offering up to 143 km electric range and 50 kW DC fast-charging capability.
- In January 2025, Ford Authority reported the Kuga PHEV as the best-selling plug-in hybrid in the Netherlands for 2024, a fourth consecutive year at the top, with 4,123 units sold.
Key Players in the Plug-in Hybrid Electric Vehicles (PHEV) Market
Global Diversified OEMs
- Toyota Motor Corporation
- Volkswagen AG
- General Motors
- Mercedes-Benz Group AG
- Honda Motor Company
European Specialists and Volume Brands
- BMW AG
- Renault SA
- Ford Motor Company
Asia-Pacific PHEV Platform Developers
- Nissan Motor Corporation
- Mitsubishi Motors Corporation, BYD Company, Geely Automobile, Chery Automobile, Li Auto, Seres Group (AITO)
Plug-in Hybrid Electric Vehicles (PHEV) Market - Report Scope
Table 7: Report Scope for the Plug-in Hybrid Electric Vehicles (PHEV) Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Vehicle type; powertrain; technology; region |
| Quantitative units | USD billion |
| Market definition | Revenue from the sale of plug-in hybrid electric vehicles, which combine an internal combustion engine with an electric motor powered by an externally chargeable battery, across passenger car and light commercial vehicle categories. Pure battery-electric vehicles, conventional (non-plug-in) hybrids and fuel-cell vehicles are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; France; United Kingdom; Germany; Spain; Italy; China; Japan; South Korea; India; Australia |
| Key companies profiled | Toyota Motor Corporation; BMW AG; Volkswagen AG; Ford Motor Company; Renault SA; General Motors; Nissan Motor Corporation; Honda Motor Company; Mercedes-Benz Group AG; Mitsubishi Motors Corporation |
| Forecast period | 2026 to 2036 |
| Approach | Hybrid bottom-up and top-down sizing reconciling OEM-reported PHEV shipments, national registration data and trade-body statistics within the defined PHEV revenue boundary. |
Plug-in Hybrid Electric Vehicles (PHEV) Market - Research Methodology
Table 8: Research Methodology for the Plug-in Hybrid Electric Vehicles (PHEV) Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with OEM product planners, powertrain engineers, fleet managers and charging infrastructure operators across profiled regions. |
| Desk Research | Review of annual reports, investor presentations, regulatory filings, national vehicle registration databases and trade-body publications. |
| Market Sizing and Forecasting | Bottom-up aggregation of PHEV unit sales by country and segment, cross-referenced with top-down revenue estimation from OEM financial disclosures. |
| Data Validation | Triangulation of unit volumes, average selling prices and revenue totals against independent industry databases and government registration records. |
Plug-in Hybrid Electric Vehicles (PHEV) Market by Segments
Plug-in Hybrid Electric Vehicles (PHEV) Market segmented by Vehicle Type:
- Passenger Car
- Light Commercial Vehicle
Plug-in Hybrid Electric Vehicles (PHEV) Market segmented by Powertrain:
- Series Hybrid
- Parallel Hybrid
- Combined Hybrid
Plug-in Hybrid Electric Vehicles (PHEV) Market segmented by Technology:
- Series
- Parallel
- Series-Parallel
Plug-in Hybrid Electric Vehicles (PHEV) Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Inovev. (2026, February 25). PHEV sales reached 6.86 million units worldwide in 2025. https://inovev.com/index.php/en/market-analyses/category-blog/21801-2026-04-10
- [2] EVBoosters Club. (2024, October). New EU CO2 targets for 2025: Challenges and opportunities for car manufacturers. https://evboosters.com/ev-charging-news/new-eu-co2-targets-for-2025-challenges-and-opportunities-for-car-manufacturers
- [3] DrivingElectric. (2026, January 21). Germany's generous electric car grant includes plug-in hybrids — could the UK follow? https://www.drivingelectric.com/news/42464/germanys-generous-electric-car-grant-includes-plug-in-hybrids-could-the-uk-follow
- [4] Ford Authority. (2025, January). Ford Kuga best-selling PHEV in Netherlands last year. https://fordauthority.com/2025/01/ford-kuga-best-selling-phev-in-netherlands-last-year/
- [5] Autoguide. (2024, September). Toyota removes Prime name from 2025 PHEV models. https://www.autoguide.com/auto/manufacturers/toyota/toyota-removes-prime-name-from-2025-phev-models-44613454
- [6] Notebookcheck. (2024, May 16). Volkswagen Golf eHybrid and GTE debut with more power, less than stellar range. https://www.notebookcheck.net/Volkswagen-Golf-eHybrid-and-GTE-debut-with-more-power-less-than-stellar-range.838550.0.html
- [7] Inovev. (2026, May 7). The BYD group sold 4.6 million vehicles in 2025. https://inovev.com/index.php/en/market-analyses/category-blog/21817-2026-05-7
- [8] BMW Group. (2026, January). BMW of North America reports full year 2025 U.S. sales results. https://www.press.bmwgroup.com/usa/article/detail/T0454803EN_US/bmw-of-north-america-reports-full-year-2025-u-s-sales-results
- [9] NRMA. (2025). Hybrid, PHEV and electric car sales H1 2025. https://www.mynrma.com.au/open-road/news/2025/hybrid-phev-and-electric-car-sales-h1-2025
- [10] GM Authority. (2026, June). GM sold 100,000 PHEVs in 2025 — none of them in the U.S. https://gmauthority.com/blog/2026/06/gm-sold-100000-phevs-in-2025-none-of-them-in-the-u-s/
- [11] Canada Energy Regulator. (2025, August 6). Market Snapshot: Zero emission vehicles in Canada — latest trends, including region- and make/model-level insights. https://cer-rec.gc.ca/en/data-analysis/energy-markets/market-snapshots/2025/market-snapshot-zero-emission-vehicles-in-canada-latest-trends-including-region-and-makemodel-level-insights.html
- [12] Auto123. (2025). Hybrid sales Canada 2025. https://www.auto123.com/en/news/hybrid-sales-canada-2025/73239/
- [13] ChinaEVHome. (2026, February 5). Toyota bets big on hybrids, targets 6.7 million units global production by 2028. https://chinaevhome.com/2026/02/05/toyota-bets-big-on-hybrids-targets-6-7-million-units-global-production-by-2028/
- [14] Green Car Reports. (2024, October). 2026 Nissan Rogue plug-in hybrid will borrow Mitsubishi tech. https://www.greencarreports.com/news/1144763_2026-nissan-rogue-plug-in-hybrid-will-borrow-mitsubishi-tech
This Report Answers
- How big is the plug-in hybrid electric vehicles (PHEV) market during 2026?
- What value is projected by 2036?
- Which vehicle type holds notable share?
- Which powertrain holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the plug-in hybrid electric vehicles (PHEV) market expected in 2026?
FMI projects the plug-in hybrid electric vehicles (PHEV) market at USD 50.0 billion in 2026, up from USD 42.4 billion in 2025. Revenue is projected to reach USD 259.6 billion by 2036, reflecting sustained expansion driven by regulatory mandates and broadening model availability.
What CAGR is projected for the plug-in hybrid electric vehicles (PHEV) market through 2036?
According to FMI, the PHEV market CAGR is projected at 17.9% from 2026 to 2036 on a global revenue basis, a figure that reflects compounding across the full product mix and rapidly scaling markets outside the profiled country set; the profiled countries individually range up to 15.5% CAGR over the same period. Fleet CO2 reduction targets in Europe and ZEV mandates in North America provide the regulatory foundation for this growth trajectory.
Which vehicle type holds a notable market share in 2026?
Passenger cars are projected at 78.4% of PHEV vehicle type revenue in 2026, supported by broader model availability across sub-compact through full-size SUV segments and by consumer incentive structures that target personal-use buyers.
Which powertrain holds a notable share in 2026?
Parallel hybrid powertrains command 82.1% of PHEV powertrain demand in 2026. Platform commonality with existing ICE vehicle architectures and lower integration costs keep parallel systems as the default OEM choice for mid-market plug-in hybrids.
Which country has a notable expansion outlook through 2036?
France leads the profiled countries at 15.5% CAGR from 2026 to 2036. France's coup de pouce incentive schemes, urban low-emission zone policies and strong public charging infrastructure support the fastest profiled PHEV adoption rate; the headline bonus ecologique purchase grant itself applies only to battery-electric vehicles.
Who are the key companies in the plug-in hybrid electric vehicles (PHEV) market?
Notable companies include Toyota Motor Corporation, BMW AG, Volkswagen AG, Ford Motor Company, Renault SA, General Motors, Nissan Motor Corporation, Honda Motor Company, Mercedes-Benz Group AG, Mitsubishi Motors Corporation, BYD Company, Geely Automobile, Chery Automobile, Li Auto, and Seres Group (AITO).
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Car
- Light Commercial Vehicle
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Powertrain, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Powertrain, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Powertrain, 2026 to 2036
- Series Hybrid
- Parallel Hybrid
- Combined Hybrid
- Y-o-Y Growth Trend Analysis By Powertrain, 2021 to 2025
- Absolute $ Opportunity Analysis By Powertrain, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Series
- Parallel
- Series-Parallel
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Vehicle Type
- By Powertrain
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Powertrain
- By Technology
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Vehicle Type
- By Powertrain
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Powertrain
- By Technology
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Vehicle Type
- By Powertrain
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Powertrain
- By Technology
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Vehicle Type
- By Powertrain
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Powertrain
- By Technology
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Vehicle Type
- By Powertrain
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Powertrain
- By Technology
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Vehicle Type
- By Powertrain
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Powertrain
- By Technology
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Vehicle Type
- By Powertrain
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Type
- By Powertrain
- By Technology
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Type
- By Powertrain
- By Technology
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Vehicle Type
- By Powertrain
- By Technology
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Toyota Motor Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- BMW AG
- Volkswagen AG
- Ford Motor Company
- Renault SA
- General Motors
- Nissan Motor Corporation
- Honda Motor Company
- Mercedes-Benz Group AG
- Mitsubishi Motors Corporation
- Mitsubishi Motors Corporation, BYD Company, Geely Automobile, Chery Automobile, Li Auto, Seres Group (AITO)
- Toyota Motor Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


