
- Market Size (2026)
- USD 11.03 Bn
- Forecast (2036)
- USD 17.97 Bn
- CAGR (2026 to 2036)
- 5.0%
How Big Is the High Magnetic Induction Grain-Oriented Silicon Steel Market in 2026?
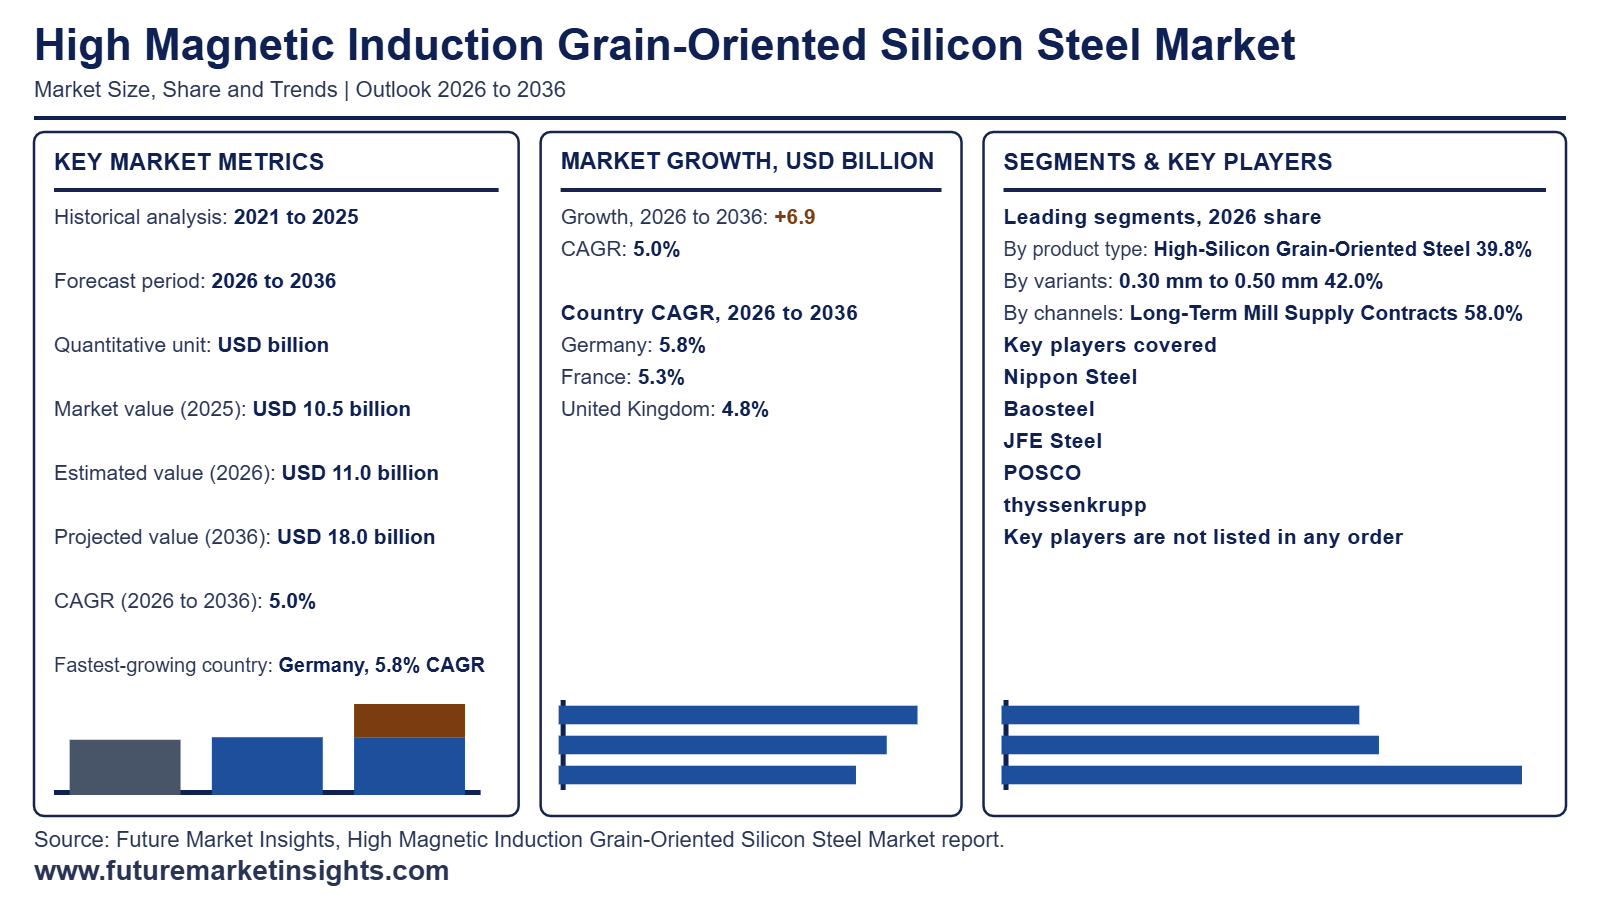
The global high magnetic induction grain-oriented silicon steel market is valued at USD 11.03 billion in 2026, up from USD 10.50 billion in 2025. Future Market Insights (FMI) expects the market to reach USD 17.97 billion by 2036, growing at a 5.0% CAGR from 2026 to 2036 and adding USD 6.94 billion in revenue over the 10-year forecast period.
| Market Metric | Valuation / Share / Forecast Benchmark |
|---|---|
| 2025 Market Size (Historical) | USD 10.50 billion |
| 2026 Market Size (Estimated) | USD 11.03 billion |
| 2036 Market Size (Projected) | USD 17.97 billion |
| Compound Annual Growth Rate (2026 to 2036) | 5.0% CAGR |
| Incremental Dollar Opportunity (2026 to 2036) | USD 6.94 billion |
| Dominant Product Type (2026 to 2036 Share) | High-Silicon Grain-Oriented Steel (39.8% in 2026, rising to 41.0% by 2036) |
| Leading & Fastest-Growing Variants | 0.30 mm to 0.50 mm (42.0% share in 2026; 3.9% CAGR) | 0.20 mm to 0.23 mm (7.4% CAGR) |
| Leading & Fastest-Growing Channels | Long-Term Mill Supply Contracts (58.0% share in 2026) | Core Fabricator Toll Programs (6.4% CAGR) |
| Largest Country Markets (2026 Global Share) | United States (9.0%), Japan (6.5%), Germany (5.0%) |
| Fastest-Growing Country Markets (2026 to 2036) | Germany (5.8% CAGR), France (5.3% CAGR), United Kingdom (4.8% CAGR) |
| Leading Tier-1 Companies | Nippon Steel, Baosteel, JFE Steel, POSCO, thyssenkrupp |
Source: Future Market Insights analysis of the high magnetic induction grain-oriented silicon steel market, 2026.
Executive Market Overview
Revenue from high magnetic induction grain-oriented silicon steel is driven by power and distribution transformer cores, along with grid expansion for renewable power and data centers. High-silicon grain-oriented steel grades account for 39.8% of 2026 revenue, and long-term mill supply contracts make up 58.0% of sales. The United States is likely to hold its place as the largest market, with transformer builders importing much of it because the one domestic mill makes limited Hi-B volumes. Furthermore, Japan and Germany are set to remain important markets, ranking second and third. Germany is expected to grow at the fastest pace through 2036, ahead of France and the United Kingdom, after the federal grid regulator approved about 2,000 kilometers of new power lines in 2025.
Transformer cores are stacked from thin sheets of grain-oriented steel, and thinner sheets with better-aligned grains waste less power as heat during the transformer's years of service. Mills are moving capacity toward thinner laser-scribed gauges that cut core losses and earn more per ton. FMI expects 0.20-0.23 mm gauges to grow at a 7.4% CAGR and 0.23-0.30 mm gauges at a 5.6% CAGR through 2036, ahead of the 5.0% overall market average. 0.30-0.50 mm gauges trail at a 3.9% CAGR. Market sizing covers cold-rolled grain-oriented silicon steel with high magnetic induction sold as coil or slit strip for transformer and reactor cores, along with generator cores. Non-oriented electrical steel and amorphous metal ribbon are excluded, as are finished transformer cores, laminations and transformers themselves.
Analyst Perspective
"Hi-B steel revenue will grow faster than tonnage, because transformer makers pay extra for thin, low-loss grades that help them meet efficiency limits. The risk sits in France, where thyssenkrupp Electrical Steel shut its Isbergues plant from June to September 2026 as low-priced imports took over half of the European market."
Nikhil Kaitwade, Principal Consultant, Future Market Insights (FMI)
High Magnetic Induction Grain-Oriented Silicon Steel Market Definition
High magnetic induction grain-oriented silicon steel is a specialized flat-rolled electrical steel product manufactured through a complex process of cold rolling, decarburization annealing, and secondary recrystallization to produce a crystal texture aligned along the rolling direction. This Goss texture alignment delivers high magnetic permeability and low core loss when magnetized along the rolling direction, making it the preferred core material for power and distribution transformers. Typical silicon content ranges from 3.0% to 3.5%, with final product thicknesses from 0.20 mm to 0.50 mm and above.
High Magnetic Induction Grain-Oriented Silicon Steel Market Inclusions
Market scope includes high-silicon and low-silicon grain-oriented electrical steel across multiple thickness categories. Application segments span transformers, electric motors, generators, and reactors. End-user industries include energy and power, automotive, consumer electronics, and industrial machinery. Coating types include insulated, uncoated, and non-oriented coatings. Regional and country-level market sizing and forecast data are included.
High Magnetic Induction Grain-Oriented Silicon Steel Market Exclusions
Non-oriented electrical steel for rotating machinery, amorphous metal transformer core alloys, and nanocrystalline soft magnetic ribbons are excluded. Silicon steel products with silicon content below 2.5% and conventional cold-rolled carbon steel fall outside analytical parameters.
High Magnetic Induction Grain-Oriented Silicon Steel Market Research Methodology
- Primary Research: Analysts engaged with transformer OEM procurement managers, electrical steel mill commercial directors, and grid infrastructure project planners to map the specification requirements and supply allocation mechanisms driving GOES procurement decisions.
- Desk Research: Data collection aggregated national grid expansion capital expenditure plans, transformer manufacturing capacity databases, and published electrical steel trade flow statistics from steel industry associations.
- Market-Sizing and Forecasting: Baseline values derive from a bottom-up aggregation of product-level shipments and end-use consumption volumes, applying region-specific adoption curves to project future demand velocity.
- Data Validation and Update Cycle: Projections are cross-checked against publicly reported capital expenditure guidance, regulatory compliance timelines, and end-use industry production volume disclosures.
High Magnetic Induction Grain-Oriented Silicon Steel Market Drivers, Restraints, Opportunities

Future Market Insights analysis indicates the grain-oriented silicon steel market is experiencing a sustained demand cycle driven by the convergence of grid expansion, energy transition infrastructure, and transformer fleet replacement programs. Unlike cyclical steel demand tied to construction activity, GOES procurement is anchored to multi-year grid infrastructure programs that provide forward demand visibility extending 3 to 5 years. FMI analysts observe that the current transformer manufacturing backlog across Asia and Europe represents the largest sustained GOES procurement pipeline since the grid electrification investment cycles of the 1990s.
The central tension in this market is the gap between GOES production capacity and transformer industry demand growth. Global GOES production is concentrated among fewer than 15 mills worldwide, with Nippon Steel, Baosteel, JFE, and POSCO accounting for the majority of high-grade output. As per FMI, this supply concentration creates allocation constraints during demand peaks that force transformer OEMs to accept longer lead times or qualify alternative material grades that carry higher core loss penalties. New GOES capacity additions require 3 to 5 year construction and qualification timelines, limiting the supply response to current demand signals.
- Renewable energy grid code efficiency mandates: Wind and solar grid connection standards in the European Union, China, and India specify maximum allowable transformer no-load loss values that can only be achieved with high-induction grain-oriented steel or thinner gauge conventional GOES, pushing procurement specifications toward premium material grades.
- EV charging infrastructure transformer demand: Fast-charging station deployments require dedicated distribution transformers rated at 500 kVA to 2 MVA per site, creating an incremental demand category that did not exist before 2020 and is projected to add 3% to 5% to annual GOES consumption by 2030 in markets with aggressive charging network rollout targets.
- Thinner gauge migration: Transformer designers are specifying 0.23 mm and 0.20 mm GOES grades to reduce core losses by 15% to 25% compared to conventional 0.30 mm material, creating a pricing premium of 20% to 35% per tonne for ultra-thin gauge products that only a subset of global mills can produce.
Segmental Analysis
High Magnetic Induction Grain-Oriented Silicon Steel Market Analysis by Product Type
Based on FMI's High Magnetic Induction Grain-Oriented Silicon Steel market report, consumption of High-Silicon Grain Oriented Steel product type is estimated to hold 39.8% share in 2026. High-silicon grain oriented steel retains the dominant procurement share because power and large distribution transformers require core materials with magnetic induction values above 1.88 Tesla at 800 A/m to meet efficiency specifications published in national transformer performance standards. The higher silicon content in Hi-B grades enables the sharp Goss texture alignment that delivers these induction levels while maintaining core loss values below the thresholds mandated by grid operator procurement specifications.
- Power transformer specification lock-in: Transformer OEMs who have qualified a specific Hi-B GOES grade for a transformer design cannot switch to an alternative supplier without rerunning core loss verification tests, creating a qualification-based switching cost that sustains incumbent material supplier relationships across multi-year grid infrastructure programs [1].
- Electrical steel versatility: Conventional grain-oriented electrical steel grades serve the cost-sensitive distribution transformer segment where efficiency regulations are less stringent than power transformer specifications, allowing manufacturers to optimize material cost per unit rather than lifetime energy savings [2].
- Low-silicon niche positioning: Low-silicon grain-oriented steel is specified in reactor and inductor applications where the magnetic saturation characteristics differ from transformer core requirements, creating a stable but smaller demand segment that is relatively insensitive to transformer industry demand cycles [3].
High Magnetic Induction Grain-Oriented Silicon Steel Market Analysis by Application

Based on FMI's High Magnetic Induction Grain-Oriented Silicon Steel market report, the Transformers application is estimated to hold 41.8% share in 2026. Transformers absorb the largest GOES procurement volume because power and distribution transformer cores account for over 90% of global grain-oriented silicon steel consumption. The non-substitutability of GOES in transformer core construction is the fundamental demand anchor: no alternative material can match the combination of magnetic permeability, core loss performance, and manufacturing processability that grain-oriented silicon steel provides at the flux densities required for grid-frequency transformer operation.
- Electric motor lamination growth: Grain-oriented steel is gaining specification traction in premium efficiency industrial motor stator laminations where the directional magnetic properties can be exploited through segmented core construction techniques that align the rolling direction with the primary flux path [4].
- Generator core applications: Large hydroelectric and thermal power plant generators use GOES for stator core laminations in configurations where the directional permeability advantage outweighs the cost premium over non-oriented electrical steel [5].
- Reactor and inductor demand: Current-limiting reactors and harmonic filter inductors in power quality equipment use GOES cores where the controlled B-H curve characteristics of grain-oriented material provide more predictable inductance values across varying load conditions [6].
Why is the High Magnetic Induction Grain-Oriented Silicon Steel Market Growing?
The high magnetic induction grain-oriented silicon steel market is experiencing robust growth, supported by the increasing global demand for energy-efficient electrical equipment and infrastructure. Its adoption is being driven by the critical role it plays in enhancing transformer efficiency, reducing core losses, and meeting stringent international energy performance standards. Growing investments in power grid modernization, coupled with the accelerated integration of renewable energy sources, are increasing the need for high-performance electrical steels capable of handling higher loads with minimal losses.
Technological advancements in precision rolling and coating techniques are improving material performance, ensuring superior magnetic flux density and mechanical strength. Governments and regulatory bodies in major economies are implementing policies that encourage the use of premium-grade materials to improve energy transmission and distribution efficiency.
The ability of high magnetic induction grades to offer consistent performance, durability, and adaptability across varied electrical applications is reinforcing their adoption As energy infrastructure expands and efficiency requirements tighten, the market is positioned to experience sustained growth, with manufacturers focusing on product innovation and capacity expansion to meet rising global demand.
What are the Drivers, Restraints, and Key Trends of the High Magnetic Induction Grain-Oriented Silicon Steel Market?
The high magnetic induction grain-oriented silicon steel market is growing due to increasing demand for efficient transformers, motors, and electrical grids. These steels offer low core loss, high permeability, and superior magnetic performance, making them critical in power generation, distribution, and industrial machinery. Demand is driven by modernization of electrical infrastructure, renewable energy integration, and industrial motor applications. Asia-Pacific leads production and consumption, while Europe and North America emphasize high-quality grades for power efficiency. Manufacturers focus on precision rolling, coating quality, and optimized grain orientation to meet stringent electrical standards.
Transformer and Power Equipment Applications
High magnetic induction grain-oriented silicon steel is widely used in transformers for power generation and distribution due to its ability to reduce energy losses. Utilities require high-efficiency materials to comply with grid regulations and reduce operational costs. The steel’s low hysteresis and core loss properties improve transformer efficiency, especially in high-capacity and high-voltage applications. Manufacturers supplying steels with precise thickness, smooth coatings, and consistent grain orientation gain preference. Until alternative magnetic materials can achieve similar performance at scale, transformer and power equipment applications will remain the primary growth driver.
Industrial Motor and Generator Use
Industrial motors and generators rely on high-performance silicon steel for magnetic cores, rotor, and stator laminations. The steel improves efficiency, reduces heat generation, and ensures reliable operation under high-load conditions. Demand is driven by industries requiring continuous operation, including manufacturing, mining, and heavy machinery. Grades with optimized magnetic induction and low core loss are preferred for large motors and generators. Manufacturers providing tailored products to meet specific motor designs, load requirements, and operational conditions can capture niche market segments. Until alternative materials match efficiency and cost parameters, motors and generators will continue to drive demand.
Production Quality and Process Control Challenges
Producing high magnetic induction grain-oriented silicon steel requires precise control of chemical composition, rolling, annealing, and coating processes. Variations in grain orientation, surface finish, or coating thickness can reduce magnetic performance and core efficiency. Manufacturers must maintain strict quality control, testing, and measurement protocols to deliver consistent performance. Investments in modern rolling mills, continuous annealing, and coating equipment enhance reliability. Until process standardization is globally consistent, product quality and manufacturing precision will remain critical factors influencing adoption and market competitiveness.
Growth in Renewable Energy and Electrification
The transition to renewable energy and widespread electrification of transportation and industrial applications increases demand for efficient transformers and motors. Wind turbines, solar power inverters, and electric vehicle charging infrastructure require high-performance silicon steel to minimize energy losses. Companies supplying steels compatible with variable operating conditions, high flux densities, and compact designs can capture emerging opportunities. Regional investment in grid modernization and clean energy projects further supports market growth. Until new magnetic materials or composites achieve comparable performance, high magnetic induction grain-oriented silicon steel will remain central to energy-efficient electrical systems.
Analysis of High Magnetic Induction Grain-Oriented Silicon Steel Market By Key Countries

| Country | CAGR |
|---|---|
| China | 6.8% |
| India | 6.3% |
| Germany | 5.8% |
| France | 5.3% |
| UK | 4.8% |
| USA | 4.3% |
| Brazil | 3.8% |

The global High Magnetic Induction Grain-Oriented Silicon Steel Market is projected to grow at a CAGR of 5.0% through 2035, supported by increasing demand across electrical, transformer, and industrial applications. Among BRICS nations, China has been recorded with 6.8% growth, driven by large-scale production and deployment in transformers and electrical equipment, while India has been observed at 6.3%, supported by rising utilization in power generation and industrial applications. In the OECD region, Germany has been measured at 5.8%, where production and adoption for electrical and industrial applications have been steadily maintained. The United Kingdom has been noted at 4.8%, reflecting consistent use in transformer and electrical equipment manufacturing, while the U.S. has been recorded at 4.3%, with production and utilization across industrial, electrical, and power generation sectors being steadily increased. This report includes insights on 40+ countries; the top five markets are shown here for reference.
High Magnetic Induction Grain-Oriented Silicon Steel Market Analysis in China
The high magnetic induction grain-oriented silicon steel market in China is growing at a CAGR of 6.8%, driven by the country’s rapid industrialization, expanding electrical infrastructure, and rising demand for energy-efficient transformers and motors. Grain-oriented silicon steel is critical in power generation, transmission, and distribution systems due to its low core loss, high permeability, and superior magnetic performance. China’s government initiatives to modernize electrical grids, promote renewable energy integration, and enhance industrial energy efficiency are accelerating adoption. Technological improvements in steel manufacturing, precision rolling, and annealing processes improve magnetic properties and product quality. The increasing production of electric vehicles and industrial automation equipment further boosts demand. Export opportunities and domestic consumption of high-performance electrical steel support consistent market growth in China.
- Industrial expansion fuels transformer and motor demand
- Advanced manufacturing improves magnetic performance
- Government initiatives promote energy-efficient infrastructure
High Magnetic Induction Grain-Oriented Silicon Steel Market Insights in India
The high magnetic induction grain-oriented silicon steel market in India is expanding at a CAGR of 6.3%, supported by growing investments in power generation, transmission, and renewable energy projects. Demand is fueled by the need for energy-efficient transformers, motors, and industrial equipment. Indian manufacturers are increasingly adopting advanced rolling, annealing, and coating technologies to enhance steel properties, reduce core losses, and improve energy efficiency. Government initiatives promoting smart grids, renewable energy integration, and industrial electrification drive adoption. The market benefits from growing urbanization, industrial automation, and the rising production of electric vehicles. Export potential of high-quality grain-oriented silicon steel from India further encourages domestic production expansion and technological upgrades.
- Energy-efficient transformers drive steel demand
- Advanced manufacturing reduces core losses
- Government initiatives support grid modernizatio
High Magnetic Induction Grain-Oriented Silicon Steel Market Review in Germany
The high magnetic induction grain-oriented silicon steel market in Germany is growing at a CAGR of 5.8%, influenced by the country’s focus on renewable energy, industrial automation, and energy-efficient electrical equipment. Transformers, motors, and power electronics increasingly rely on high-quality grain-oriented silicon steel for reduced energy loss and improved performance. Germany emphasizes precision manufacturing, high-purity steel, and advanced annealing techniques to achieve superior magnetic properties. Strict energy-efficiency standards and environmental regulations further boost demand. Research and development efforts target innovative coatings, optimized grain structures, and sustainable steel production. Adoption across industrial, energy, and transportation sectors ensures steady market growth and positions Germany as a technologically advanced market for high magnetic induction silicon steel.
- Renewable energy drives transformer and motor demand
- Precision manufacturing enhances magnetic performance
- Energy-efficiency standards support market growth
High Magnetic Induction Grain-Oriented Silicon Steel Market Outlook in United Kingdom
The high magnetic induction grain-oriented silicon steel market in the United Kingdom is expanding at a CAGR of 4.8%, driven by investments in electrical infrastructure, energy-efficient transformers, and industrial automation. Demand is fueled by efforts to reduce energy losses in power systems and meet environmental regulations. Advanced manufacturing techniques, such as precision rolling, coating, and annealing, improve the magnetic properties and reliability of silicon steel. Adoption in renewable energy, smart grids, and industrial machinery contributes to consistent market growth. Government policies promoting sustainable energy, carbon reduction, and energy-efficient technologies encourage wider adoption. The UK market benefits from technological advancements, skilled workforce, and R&D initiatives aimed at producing high-performance grain-oriented silicon steel.
- Transformer and industrial applications boost demand
- Precision techniques enhance magnetic properties
- Government policies support energy-efficient infrastructure
High Magnetic Induction Grain-Oriented Silicon Steel Market Trends in United States

The high magnetic induction grain-oriented silicon steel market in the United States is growing at a CAGR of 4.3%, supported by industrial electrification, power infrastructure modernization, and renewable energy adoption. Transformers, motors, and generators increasingly utilize high-performance silicon steel for low energy losses and enhanced magnetic properties. U.S. manufacturers are focusing on precision rolling, annealing, and coating technologies to improve steel efficiency and reliability. Government incentives for smart grids, energy efficiency, and sustainable infrastructure drive market expansion. Adoption in industrial, energy, and transportation sectors further strengthens demand. The market is also influenced by R&D efforts to optimize grain orientation, reduce core losses, and produce eco-friendly steel, ensuring sustained growth in high magnetic induction silicon steel across the United States.
- Industrial and energy sectors drive market demand
- Advanced rolling and annealing improve efficiency
- Government incentives promote energy-efficient transformers
Competitive Landscape of High Magnetic Induction Grain-Oriented Silicon Steel Market

The High Magnetic Induction Grain-Oriented Silicon Steel (Hi-B GOES) Market is expanding rapidly, driven by the rising global demand for energy-efficient transformers, motors, and generators. This specialized electrical steel offers superior magnetic permeability, low core loss, and high induction properties, making it an essential material for modern power transmission and distribution infrastructure. Market growth is being propelled by grid modernization initiatives, renewable energy integration, and increasing adoption of high-efficiency electrical equipment in industrial and utility applications.
Leading producers such as Nippon Steel Corporation, Baosteel Group Corporation, and JFE Steel Corporation dominate the global Hi-B GOES market through continuous innovation in thin-gauge, high-performance steel grades that enhance transformer efficiency and reduce energy losses. Nippon Steel remains a technological frontrunner with its ZDKH series of Hi-B GOES products, offering superior core performance for ultra-high voltage transformers. Baosteel Group continues to expand its production capacity to meet surging demand in China’s renewable and smart grid sectors, while JFE Steel Corporation focuses on precision processing technologies for low-noise transformer cores.
Thyssenkrupp AG and POSCO contribute significantly to the European and Asia-Pacific markets, respectively, with advanced Hi-B GOES materials that combine low magnetostriction and high magnetic flux density. AK Steel International (Cleveland-Cliffs Inc.) is a major North American supplier, providing energy-efficient GOES grades used in power and industrial transformer applications. Cogent Power Limited, a subsidiary of Tata Steel, strengthens Europe’s supply chain with coated Hi-B GOES laminations for transformer core manufacturing. Arnold Magnetic Technologies Corp. plays a key role in supplying specialized magnetic alloys and engineered components for precision power applications and electromagnetics research.
Key Players in the High Magnetic Induction Grain-Oriented Silicon Steel Market
- Nippon Steel Corporation
- Baosteel Group Corporation
- JFE Steel Corporation
- Thyssenkrupp AG
- POSCO
- AK Steel International (Cleveland-Cliffs Inc.)
- Cogent Power Limited
- Arnold Magnetic Technologies Corp.
Scope of the Report

| Metric | Value |
|---|---|
| Quantitative Units | USD 11.03 billion to USD 17.96 billion, at a CAGR of 5.00% |
| Market Definition | High magnetic induction grain-oriented silicon steel is a Goss-textured electrical steel for transformer cores, offering high permeability and low core loss at thicknesses from 0.20 mm to above 0.50 mm. |
| Product Type Segmentation | High-Silicon Grain Oriented Steel, Electrical Steel, Low-Silicon Grain Oriented Steel |
| Application Segmentation | Transformers, Electric Motors, Generators, Reactors |
| Thickness Segmentation | 0.30 mm - 0.50 mm, 0.20 mm - 0.30 mm, Above 0.50 mm |
| End-User Industry Segmentation | Energy and Power, Automotive, Consumer Electronics, Industrial Machinery |
| Coating Type Segmentation | Insulated Coating, Uncoated Steel, Non-oriented Coating |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia, Oceania, Middle East & Africa |
| Countries Covered | China, India, Germany, France, UK, USA, Brazil, and 40 plus countries |
| Key Companies Profiled | Nippon Steel Corporation, Baosteel Group Corporation, JFE Steel Corporation, Thyssenkrupp AG, POSCO, AK Steel International (Cleveland-Cliffs Inc.), Cogent Power Limited, Arnold Magnetic Technologies Corp. |
| Forecast Period | 2026 to 2036 |
| Approach | Forecasting models apply a bottom-up methodology starting with end-use consumption metrics and projecting adoption rates based on regulatory and industry investment timelines. |
High Magnetic Induction Grain-Oriented Silicon Steel Market by Segments
Product Type:
- High-Silicon Grain Oriented Steel
- Electrical Steel
- Low-Silicon Grain Oriented Steel
Application:
- Transformers
- Electric Motors
- Generators
- Reactors
Thickness:
- 0.30 mm - 0.50 mm
- 0.20 mm - 0.30 mm
- Above 0.50 mm
End-User Industry:
- Energy and Power
- Automotive
- Consumer Electronics
- Industrial Machinery
Coating Type:
- Insulated Coating
- Uncoated Steel
- Non-oriented Coating
Region:
- North America
- USA
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Rest of Latin America
- Western Europe
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- Middle East & Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Bibliography
- Bundesnetzagentur. (2026, January 2). Energiewende nimmt entscheidende Hürde: 2025 zeigt deutliche Fortschritte beim Stromnetzausbau.
- EUROMETAL. (2026, March 30). Thyssenkrupp Electrical Steel stops production in France.
- Magnetics Magazine. (2026, July 9). Price War in Grain-Oriented Electrical Steel Ripples Through Producers.
- National Laboratory of the Rockies. (2026, May). Large Power Transformer Supply Chain Gap Analysis and Domestic Content Strategies for Hydropower Rehabilitation: Supplemental Report.
- Recycling Today. (2025, December 15). Thyssenkrupp idles capacity in Europe.
Table of Content
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
Read More...
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Company Annual and Sustainability Reports
- Peer-reviewed Journals and Academic Literature
- Corporate Websites, Product Literature, and Technical Notes
- Earnings Decks and Investor Briefings
- Statutory Filings and Regulatory Disclosures
- Technical White Papers and Standards Notes
- Trade Journals, Industry Magazines, and Analyst Briefs
- Conference Proceedings, Webinars, and Seminar Materials
- Government Statistics Portals and Public Data Releases
- Press Releases and Reputable Media Coverage
- Specialist Newsletters and Curated Briefings
- Sector Databases and Reference Repositories
- FMI Internal Proprietary Databases and Historical Market Datasets
- Subscription Datasets and Paid Sources
- Social Channels, Communities, and Digital Listening Inputs
- Additional Desk Sources
- Expert Input and Fieldwork (Primary Evidence)
- Primary Modes
- Qualitative Interviews and Expert Elicitation
- Quantitative Surveys and Structured Data Capture
- Blended Approach
- Why Primary Evidence is Used
- Field Techniques
- Interviews
- Surveys
- Focus Groups
- Observational and In-context Research
- Social and Community Interactions
- Stakeholder Universe Engaged
- C-suite Leaders
- Board Members
- Presidents and Vice Presidents
- R&D and Innovation Heads
- Technical Specialists
- Domain Subject-matter Experts
- Scientists
- Physicians and Other Healthcare Professionals
- Governance, Ethics, and Data Stewardship
- Research Ethics
- Data Integrity and Handling
- Primary Modes
- Tooling, Models, and Reference Databases
- Desk Research Programme (Secondary Evidence)
- Data Engineering and Model Build
- Data Acquisition and Ingestion
- Cleaning, Normalisation, and Verification
- Synthesis, Triangulation, and Analysis
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics
- Drivers
- Restraints
- Opportunity
- Trends
- Scenario Forecast
- Demand in Optimistic Scenario
- Demand in Likely Scenario
- Demand in Conservative Scenario
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter’s Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Market Dynamics
- Global Market Analysis 2021 to 2025 and Forecast, 2026 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis 2021 to 2025 and Forecast 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Product Type
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type , 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type , 2026 to 2036
- High-Silicon Grain Oriented Steel
- Electrical Steel
- Low-Silicon Grain Oriented Steel
- High-Silicon Grain Oriented Steel
- Y-o-Y Growth Trend Analysis By Product Type , 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type , 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Application
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Transformers
- Electric Motors
- Generators
- Reactors
- Transformers
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Thickness
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Thickness, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Thickness, 2026 to 2036
- 0.30 mm - 0.50 mm
- 0.20 mm - 0.30 mm
- Above 0.50 mm
- 0.30 mm - 0.50 mm
- Y-o-Y Growth Trend Analysis By Thickness, 2021 to 2025
- Absolute $ Opportunity Analysis By Thickness, 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By End-User Industry
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-User Industry, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-User Industry, 2026 to 2036
- Energy and Power
- Automotive
- Consumer Electronics
- Industrial Machinery
- Energy and Power
- Y-o-Y Growth Trend Analysis By End-User Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-User Industry, 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Coating Type
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Coating Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Coating Type, 2026 to 2036
- Insulated Coating
- Uncoated Steel
- Non-oriented Coating
- Insulated Coating
- Y-o-Y Growth Trend Analysis By Coating Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Coating Type, 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Region
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- Mexico
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Key Takeaways
- Latin America Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Key Takeaways
- Western Europe Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Key Takeaways
- Eastern Europe Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Key Takeaways
- East Asia Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Key Takeaways
- South Asia and Pacific Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Key Takeaways
- Middle East & Africa Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Turkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- By Thickness
- By End-User Industry
- By Coating Type
- Competition Analysis
- Competition Deep Dive
- Nippon Steel Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments (Product/Age /Sales Channel/Region)
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Baosteel Group Corporation
- JFE Steel Corporation
- Thyssenkrupp AG
- POSCO
- AK Steel International (Cleveland-Cliffs Inc.)
- Cogent Power Limited
- Arnold Magnetic Technologies Corp.
- Nippon Steel Corporation
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Product Type , 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Thickness, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 6: Global Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Product Type , 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Thickness, 2021 to 2036
- Table 11: North America Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 12: North America Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by Product Type , 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 16: Latin America Market Value (USD Million) Forecast by Thickness, 2021 to 2036
- Table 17: Latin America Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 18: Latin America Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by Product Type , 2021 to 2036
- Table 21: Western Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 22: Western Europe Market Value (USD Million) Forecast by Thickness, 2021 to 2036
- Table 23: Western Europe Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 24: Western Europe Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Million) Forecast by Product Type , 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Million) Forecast by Thickness, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 31: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Million) Forecast by Product Type , 2021 to 2036
- Table 33: East Asia Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 34: East Asia Market Value (USD Million) Forecast by Thickness, 2021 to 2036
- Table 35: East Asia Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 36: East Asia Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Million) Forecast by Product Type , 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Million) Forecast by Thickness, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
- Table 43: Middle East & Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 44: Middle East & Africa Market Value (USD Million) Forecast by Product Type , 2021 to 2036
- Table 45: Middle East & Africa Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 46: Middle East & Africa Market Value (USD Million) Forecast by Thickness, 2021 to 2036
- Table 47: Middle East & Africa Market Value (USD Million) Forecast by End-User Industry, 2021 to 2036
- Table 48: Middle East & Africa Market Value (USD Million) Forecast by Coating Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type , 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type , 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by Thickness, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Thickness, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Thickness
- Figure 12: Global Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-User Industry
- Figure 15: Global Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Coating Type
- Figure 18: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East & Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Type , 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Type , 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Type
- Figure 32: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Application
- Figure 35: North America Market Value Share and BPS Analysis by Thickness, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Thickness, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Thickness
- Figure 38: North America Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End-User Industry
- Figure 41: North America Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Coating Type
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Type , 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Type , 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Application
- Figure 51: Latin America Market Value Share and BPS Analysis by Thickness, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Thickness, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Thickness
- Figure 54: Latin America Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by End-User Industry
- Figure 57: Latin America Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Coating Type
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Type , 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Type , 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Application
- Figure 67: Western Europe Market Value Share and BPS Analysis by Thickness, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Thickness, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Thickness
- Figure 70: Western Europe Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by End-User Industry
- Figure 73: Western Europe Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Coating Type
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Type , 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Type , 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Application
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Thickness, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Thickness, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Thickness
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by End-User Industry
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Coating Type
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Type , 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Type , 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Application
- Figure 99: East Asia Market Value Share and BPS Analysis by Thickness, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Thickness, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Thickness
- Figure 102: East Asia Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by End-User Industry
- Figure 105: East Asia Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Coating Type
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Type , 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type , 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Thickness, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Thickness, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Thickness
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by End-User Industry
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Coating Type
- Figure 124: Middle East & Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East & Africa Market Value Share and BPS Analysis by Product Type , 2026 and 2036
- Figure 126: Middle East & Africa Market Y-o-Y Growth Comparison by Product Type , 2026-2036
- Figure 127: Middle East & Africa Market Attractiveness Analysis by Product Type
- Figure 128: Middle East & Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 129: Middle East & Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 130: Middle East & Africa Market Attractiveness Analysis by Application
- Figure 131: Middle East & Africa Market Value Share and BPS Analysis by Thickness, 2026 and 2036
- Figure 132: Middle East & Africa Market Y-o-Y Growth Comparison by Thickness, 2026-2036
- Figure 133: Middle East & Africa Market Attractiveness Analysis by Thickness
- Figure 134: Middle East & Africa Market Value Share and BPS Analysis by End-User Industry, 2026 and 2036
- Figure 135: Middle East & Africa Market Y-o-Y Growth Comparison by End-User Industry, 2026-2036
- Figure 136: Middle East & Africa Market Attractiveness Analysis by End-User Industry
- Figure 137: Middle East & Africa Market Value Share and BPS Analysis by Coating Type, 2026 and 2036
- Figure 138: Middle East & Africa Market Y-o-Y Growth Comparison by Coating Type, 2026-2036
- Figure 139: Middle East & Africa Market Attractiveness Analysis by Coating Type
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the high magnetic induction grain-oriented silicon steel market in 2026?
Future Market Insights estimates the global high magnetic induction grain-oriented silicon steel market at USD 11.03 billion in 2026, up from USD 10.50 billion in 2025.
How fast is the high magnetic induction grain-oriented silicon steel market expected to grow through 2036?
FMI projects a 5.0% CAGR from 2026 to 2036, taking the global high magnetic induction grain-oriented silicon steel market to USD 17.97 billion by 2036 and generating USD 6.94 billion in incremental revenue.
Which product type leads the high magnetic induction grain-oriented silicon steel market?
High-silicon grain-oriented steel grades lead with 39.8% of 2026 revenue, and their global revenue share is projected to rise to 41.0% by 2036 as utilities specify lower-loss transformer cores.
Which variant leads the high magnetic induction grain-oriented silicon steel market?
0.30-0.50 mm gauges hold 42.0% of 2026 revenue (expanding at a 3.9% CAGR), while 0.20-0.23 mm gauges are projected to grow fastest at 7.4% per year, followed by 0.23-0.30 mm gauges at 5.6%.
Which distribution channel leads the high magnetic induction grain-oriented silicon steel market?
Long-term mill supply contracts account for 58.0% of 2026 sales, whereas core fabricator toll programs are expected to grow fastest at 6.4% per year from 2026 to 2036.
Which country is the largest high magnetic induction grain-oriented silicon steel market?
The United States leads the high magnetic induction grain-oriented silicon steel market, capturing 9.0% of global revenue in 2026 (USD 992.7 million), followed by Japan at 6.5% (USD 717.0 million) and Germany at 5.0% (USD 551.5 million).
Which countries are expected to grow fastest in the high magnetic induction grain-oriented silicon steel market?
Germany and France are projected to grow fastest, expanding at 5.8% and 5.3% CAGRs from 2026 to 2036, followed by the United Kingdom at 4.8%.
What drives demand for high magnetic induction grain-oriented silicon steel?
Demand for high magnetic induction grain-oriented silicon steel rests on power and distribution transformer cores along with generator cores, and a five-year US defense supply contract awarded to the sole American producer in September 2025 added to it.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
