
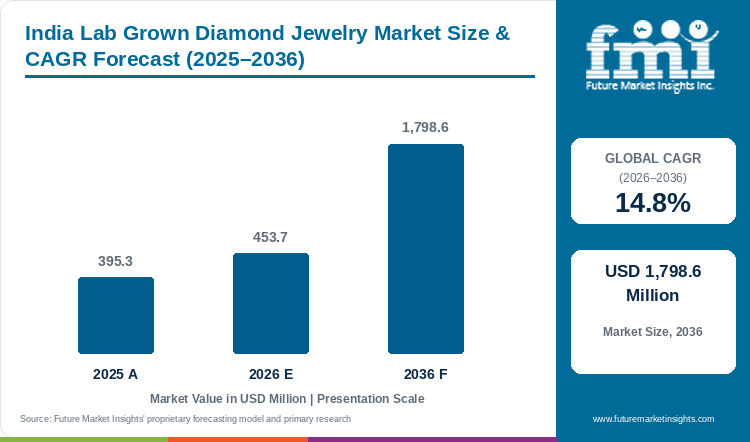
- Market Size (2026)
- USD 453.7 Mn
- Forecast (2036)
- USD 1798.6 Mn
- CAGR (2026 to 2036)
- 14.8%
How big is the India lab grown diamond jewelry market in 2026?
The market was estimated at USD 395.3 million in 2025 and is expected to reach USD 453.7 million in 2026. It is forecast to grow at a CAGR of 14.8% from 2026 to 2036 and reach USD 1,798.6 million by 2036.
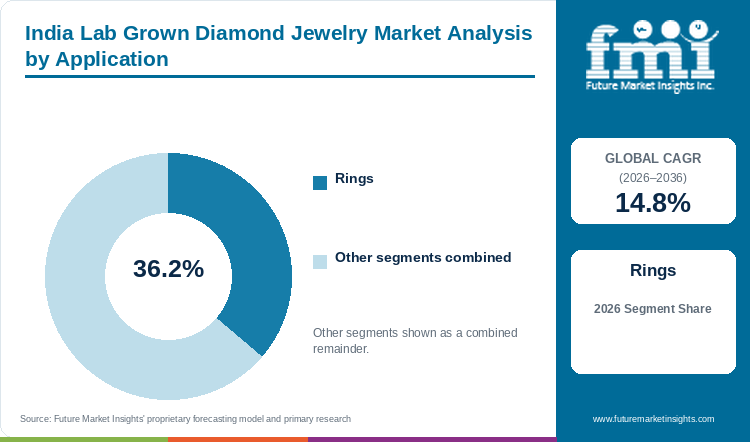
The India lab-grown diamond jewellery market was valued at USD 395.3 million in 2025 and is estimated to reach USD 453.7 million in 2026. The market is projected to reach USD 1,798.6 million by 2036, expanding at a compound annual growth rate (CAGR) of 14.8% between 2026 and 2036. Rings accounted for 36.2% of application demand in 2026, while chemical vapour deposition (CVD) accounted for 58.7% of growth technique volume. The demand for lab-grown diamond jewellery is supported by the way Indian buyers choose a finished piece, weighing budget, occasion and appearance, with the setting, metal, fit and service shaping the final purchase. The growth in the category is also reflected in trade figures. In FY 2025-26, India’s exports of gold jewellery containing lab-grown diamonds rose 31.3% to approximately USD 1,425.5 million, while exports of polished lab-grown diamonds fell 10.6% in value to approximately USD 1.1 billion. The shift suggests that finished jewellery is gaining ground over loose polished stones. Manufacturers and retailers are also strengthening their position in the category. For instance, Titan announced the first Mumbai store of its lab-grown jewellery brand beYon for December 2025, and IIT Madras’s InCent-LGD programme is developing indigenous diamond technologies for gem-quality and electronic-grade material.
Key Market Trends & Insights
- Rings are projected to represent 36.2% of application demand in 2026, linking assortment planning to engagement, bridal and personal purchases.
- Chemical vapour deposition is expected to account for 58.7% of growth technique volume in 2026; high-pressure, high-temperature growth remains another production route. [3]
- One-carat stones are forecast to hold 29.4% by size, while faceted cuts are expected to represent 64.1% by volume in 2026.
Regional Highlights
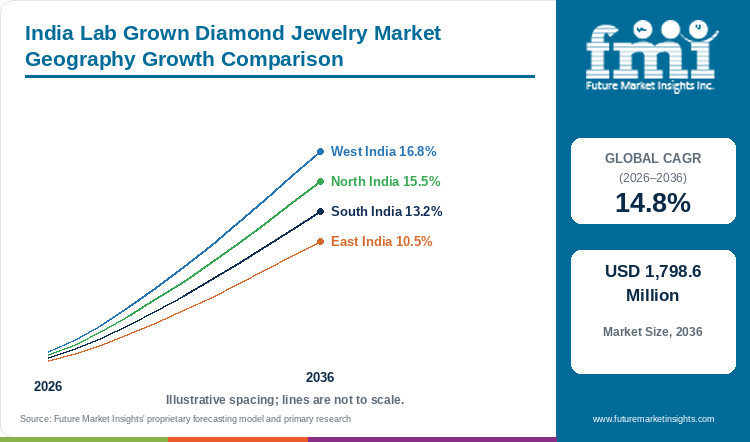
- West India leads the regional forecast at 16.8% CAGR from 2026 to 2036, followed by North India at 15.5%.
- South India is forecast at 13.2% CAGR and East India at 10.5% over the same period, with physical access illustrated by specialist stores in southern cities and Kolkata. [10][14]
Market Size & Forecast
Table 1: India Lab Grown Diamond Jewelry Market Size and Forecast (USD million), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 Value | USD 395.3 million |
| Estimated market size in 2026 | USD 453.7 million |
| Projected market size by 2036 | USD 1,798.6 million |
| CAGR (2026-2036) | 14.8% |
Finished jewellery combines several sources of value. A polished stone enters a piece with a metal setting, manufacturing work, design and the retailer’s service. The market’s growth therefore concerns the sale of that combined product. A supplier that improves availability of a particular diamond shape may help a manufacturer complete a collection, while a retailer can increase the range of purchase occasions addressed by changing the jewellery built around the stone. These decisions link the upstream production base with the amount a customer ultimately spends. A broad supply of loose material becomes commercially useful when it can be translated into pieces with clear specifications and dependable fulfilment.
India’s export figures illustrate the different economics within that chain. Exports of polished lab-grown diamonds fell by 10.6% in value to approximately USD 1.1 billion in FY 2025-26, while gold jewellery containing lab-grown diamonds rose by 31.3% to approximately USD 1,425.5 million. [2] The jewellery series includes gold and other inputs as well as stones. Changes in its value can consequently reflect the composition of the finished product and its markets. For manufacturers, the contrast makes the choice of business model consequential: selling polished stones exposes revenue directly to that product’s trading conditions, whereas completing jewellery introduces design, metal purchasing and customer fulfilment into the commercial equation.
The industry also has a technical development path beyond retail. IIT Madras’s InCent-LGD programme is developing indigenous diamond technologies relevant to gem-quality and electronic-grade material. [1] Jewellery businesses may benefit when suitable technologies, skills and process understanding become available to industry, although scientific activity reaches a saleable collection through further manufacturing work. The wider synthetic diamond market includes uses beyond jewellery, so a producer’s technical breadth can serve different customers. A jewellery order still requires stones that match the design brief, with preparation and documentation completed before setting. This makes the connection between process capability and the finished specification central to supplier selection.
Table 2: Supporting Industry Indicators
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| Finished jewellery exports | Gold jewellery containing lab-grown diamonds rose to approximately USD 1,425.5 million in FY 2025-26 | Combines stone and metal value within an exported finished product | [2] |
| Polished-stone exports | Approximately USD 1.1 billion in FY 2025-26 | Describes the loose polished-stone trade | [2] |
| Domestic research | InCent-LGD develops indigenous diamond technologies | Connects process development with potential industrial adoption | [1] |
| Branded category entry | Titan announced beYon’s first Mumbai store for December 2025 | Adds a dedicated lab-grown jewellery brand within Titan’s portfolio | [8] |
| Retail access | Specialist stores listed in northern, western, southern and eastern cities | Provides places to examine complete jewellery | [10][11][14] |
Demand Intensity Analysis
The projected increase of USD 1,344.9 million in annual market value between 2026 and 2036 concerns finished jewellery. Demand intensity is consequently expressed through the value of pieces bought and the range of uses they serve. A centre-stone ring, a pair of earrings and a pendant require different combinations of stones and metalwork. The purchasing decision may also involve several versions of the same design. These differences affect the manufacturer’s order book and the retailer’s working capital even when products share a common growth technique. Assortment depth becomes productive when it helps a customer complete a purchase without leaving the business with many slow-moving variations.
A retailer’s collection has to connect what can be displayed with what can be supplied after the customer chooses a size, metal colour or setting. Emori’s engagement-ring catalogue allows selection across diamond shape, carat weight, metal type and gold karat. [7] Such choices broaden the offer while also increasing the number of possible finished specifications. The operational response is to manage the relationship between display stock, available stones and manufacturing commitments. A well-defined order can pass from sales to production with fewer revisions. Unclear specifications create the opposite effect: a customer may see an attractive price but receive a final quotation or delivery arrangement that differs from the initial expectation.
Repeat purchasing creates a different planning task from an engagement order. A retailer developing everyday jewellery needs pieces that can be replenished consistently and shown as part of a recognisable collection. An occasion purchase can tolerate a longer design discussion when the customer seeks a particular appearance. Both routes require service after the first sale, especially when fit or a setting needs attention. The commercial opportunity lies in coordinating these activities at a cost the selling price can support. Stock movement, completion of orders and the work involved in serving each piece determine how much of the selling value remains after those commitments are met.
Table 3: Demand Measures and Their Stated Bases
| Demand intensity metric | Value | Basis |
|---|---|---|
| Prior-year market value | USD 395.3 million | Estimated prior-year market value, 2025 |
| Market outlook | USD 453.7 million to USD 1,798.6 million | Finished jewellery, 2026 to 2036 |
| Market growth | 14.8% CAGR | 2026 to 2036 |
| Application leadership | Rings: 36.2% | Application demand, 2026 |
| Growth technique | CVD: 58.7% | Growth technique volume, 2026 |
| Size and cut | 1.00 carat: 29.4%; faceted cuts: 64.1% | Demand by size and cut volume respectively, 2026 |
Analyst Perspective
India’s lab-grown diamond jewellery businesses build a dependable retail offer when displayed designs match available stones and the service promised at sale. Carrying extensive stock alongside extensive customization raises the sales needed to support the business, making a coherent collection and manageable custom commitments central to preserving margins.
- Rahul Pandita, Principal Consultant, FMI
How is the India lab grown diamond jewelry market segmented?
The market is organised by application, growth technique, cut and shape, carat size, and region. Applications comprise rings, earrings, pendants, necklaces, bangles and other jewellery. Growth techniques comprise chemical vapour deposition and high-pressure, high-temperature. Cut coverage separates faceted cuts from other cuts and shapes, while carat-size coverage identifies the 1.00 carat category and other carat sizes. These axes describe different aspects of one product: a ring can contain a CVD-grown, faceted diamond within a specified weight category. Retail collections bring those classifications together in pieces selected for particular uses.
Why do rings lead application demand for lab-grown diamond jewellery?
Rings are expected to account for 36.2% of application demand in 2026.
A ring makes the relationship between stone and setting especially visible. The centre stone may be the starting point, but the band, mounting height and surrounding design determine the complete appearance. An engagement order also requires a usable fit and a finished piece available for the intended date. The retailer therefore has a role in translating a visual preference into a specification that can be made and worn. Within the wider diamond jewelry market, that service accompanies the choice of stone origin and the information supplied about the product.
Ring collections can address several purchasing needs without treating every customer as a bridal buyer. Emori lists solitaire, halo, three-stone and cluster styles alongside options for diamond shape and metal. [7] The practical challenge is to give each design a clear identity while managing how many variants are held in stock. A retailer can display a representative piece and complete an order to the selected specification, provided the quotation and manufacturing schedule are settled. This approach connects the emotional importance of a ring with the operational work required to deliver it.
- Ring assortments benefit from showing how the setting changes the appearance of a comparable centre-stone specification.
- Sizing and delivery commitments form part of the purchase proposition, particularly when an order is linked to an occasion.
Why does CVD lead the growth technique mix for jewellery diamonds?
CVD is projected to represent 58.7% of growth technique volume in 2026.
Chemical vapour deposition and high-pressure, high-temperature growth are the principal production routes for laboratory-grown diamonds. GIA describes their different growth conditions and the use of post-growth processing for some material. [3] The CVD lab-grown diamond market consequently connects a controlled growth process with later cutting, polishing and preparation. For jewellery makers, the purchase concerns the finished stone’s suitability for a mounting as well as its growth history. Suppliers need to turn rough output into a consistent set of commercially useful specifications.
Greenlab describes seed placement, growth in a plasma reactor and subsequent processing of rough CVD diamonds. [5] The business implication is that production planning has several linked stages before a stone is ready for jewellery. A growth operation supplying a collection needs feedback on required shapes and dimensions, while the jewellery maker needs realistic availability. CVD production capacity becomes more useful when those requirements are communicated before stones are selected for individual orders. The alternative HPHT route remains part of the supply base; the choice of supplier ultimately depends on the material and service needed for the intended piece.
- Stone specifications connect growth output to cutting, polishing and the dimensions required by a jewellery setting.
- Reliable availability supports collection replenishment and reduces the need to redesign a piece around an unexpected substitute.
How does the 1.00 carat segment lead demand by carat size?
The 1.00 carat segment is projected to account for 29.4% of demand by size in 2026.
A specified weight gives the buyer a recognisable point of comparison, although the finished piece still depends on shape and setting. Two designs built around the same weight category can create quite different impressions on the hand. The retailer’s task is to connect the stated stone specification with what the customer sees in the complete piece. A collection organised around that category can make design differences easier to compare, particularly when metal colour and mounting style are also presented clearly.
For a jewellery manufacturer, a defined weight category helps establish the starting point of a collection. The remaining decisions concern proportions, construction and the range of styles to offer. Buying stones only because their weight matches the brief can leave a mismatch at the setting stage if dimensions vary from the design requirement. A purchasing specification therefore needs to describe the stone in enough detail for the intended mounting. Other carat sizes expand the available assortment, giving the retailer room to address a different budget or appearance without treating weight as the complete description of value.
- A recognisable weight category can support several designs when stone dimensions and mounting requirements are planned together.
- Finished examples help customers compare visual presence, metalwork and fit alongside the stated carat weight.
Why do faceted cuts lead the cut and shape mix for jewellery?
Faceted cuts are expected to represent 64.1% by volume in 2026 under the separate cut and shape classification.
Cut and shape influence how a stone sits within a design and how the complete piece is perceived. Titan’s beYon range includes cushion, marquise, radiant, half-moon and oval forms, set in yellow, white and rose gold. [9] That offer illustrates how a brand can use stone shape to establish variety across a collection. The design decision then moves into manufacturing: the setting must accommodate the stone’s outline and dimensions while retaining the intended appearance.
A retailer presenting shapes through finished jewellery can show differences that are less obvious in a loose-stone description. An elongated shape, for example, changes the outline of a ring, whereas a design using surrounding metal may draw attention to the mounting. These are choices within the complete piece, and their appeal depends on the customer’s intended use. For manufacturers, keeping a coherent range of shapes can simplify the development of related designs. Other cuts and shapes remain within the report’s coverage and provide further scope for collections whose identity depends on their overall form.
- Distinctive shapes give brands a design vocabulary that can carry across several finished jewellery forms.
- Matching the stone outline to the mounting protects both the intended appearance and the efficiency of manufacture.
How do earrings, pendants and other applications broaden the offer?
Earrings, pendants, necklaces, bangles and other jewellery extend the application coverage beyond rings.
Earrings and pendants place different demands on a collection from rings. Paired pieces require a coordinated appearance, while a pendant needs to work with its chain and the way the piece is worn. Necklaces, bangles and other jewellery introduce further construction and styling choices. These applications allow a retailer to address gifting and everyday use through designs that do not depend on a ring purchase. The opportunity also changes stock planning: a business can develop related pieces around a recognisable design rather than multiplying unrelated products. The gemstones market offers a wider context for such design choices, including jewellery that uses other stone categories. Within this report, the commercial focus remains jewellery incorporating laboratory-grown diamonds.
- Related applications let a retailer develop a collection for several uses while maintaining a recognisable design identity.
- Paired stones, chains and the construction of larger pieces create application-specific requirements for purchasing and manufacture.
What are the drivers, restraints and opportunities in the India lab grown diamond jewelry market?
Everyday and bridal designs give retailers several routes to a sale, while custom orders let them serve specific preferences without stocking every design. Changing stone and metal costs can squeeze margins during fulfilment, so the opportunity depends on agreeing product specifications and managing the additional work of sourcing and production.
How does design widen the range of purchase occasions?
Design gives the manufacturer a way to connect a stone with an intended use. A simple pendant can serve a different purchase occasion from a prominent ring even where both contain laboratory-grown diamonds. Titan positions beYon around contemporary, everyday expression, while specialist catalogues also include engagement and bridal jewellery. [9][11] This breadth gives retailers several routes to a sale. The challenge is to organise those routes into a comprehensible collection, with a clear relationship between appearance, specifications and price. When a range answers different needs coherently, the business can serve customers returning for another occasion without rebuilding the entire offer around each individual order.
Why can loose-stone trading conditions restrain jewellery businesses?
The contrasting export movements reported for polished stones and finished gold jewellery in FY 2025-26 show that related businesses can experience different trading conditions. [2] A jewellery company still has to purchase stones and metal while carrying the cost of work already completed. If a quotation is left open during that process, changes in replacement cost can make an order harder to fulfil profitably. Businesses selling a finished collection also face the risk that customers focus on the stone alone when comparing prices. A clear product specification and a stable quotation process help align the selling promise with the work included. Design and service can distinguish an offer, but they have to be delivered within workable margins.
How does origin disclosure affect confidence at purchase?
Laboratory-grown origin is a material part of the product description. GIA's current service provides a quality assessment for eligible loose laboratory-grown diamonds and laser inscription identifying the origin and assessment number. [4] That information connects a stone with its documentation through the supply chain. For a jewellery business, the operational task is to preserve the association when stones are selected, set and sold. A customer's order record can carry the assessment reference alongside the metal, size and setting selected. Staff then have a description of both the assessed stone and the completed piece when explaining the quotation or handling a later service request. The retail offer brings that product information together with manufacturing and service commitments.
Where does customization create an opportunity and a cost?
Customization can convert a preferred design into an order when a standard piece does not meet the customer’s needs. Avira advertises bespoke jewellery alongside its ready collections, and Ouros includes custom rings within its catalogue. [10][12] The commercial benefit comes from addressing a specific requirement without committing every possible design to stock. The cost is the additional work of agreeing the specification, sourcing suitable stones and completing production. Changes late in the process can add further work for both the retailer and maker. A disciplined custom offer therefore needs an agreed design and a clear fulfilment sequence. This is particularly relevant when customers expect the appearance of a pictured piece to carry through into their selected stone and metal.
How can research support the manufacturing opportunity?
The InCent-LGD programme connects process development with the aim of making indigenous technologies available to Indian start-ups and industry. Its March 2026 conference included monitoring and optimisation of diamond growth. [1] Such work matters commercially when it improves the ability to produce material suited to an order or reduces avoidable process variation. Adoption involves adapting technical learning to the producer's equipment, staff and downstream requirements. Producers able to translate process understanding into repeatable output can develop a stronger relationship with cutters and jewellery makers, whose own schedules depend on receiving usable material.
How do the regional outlooks compare?
The report profiles West, North, South and East India, with each regional rate covering the same forecast period. The regional opportunity combines manufacturing relationships, retail access and the ability to complete orders. Current official company pages illustrate actual points of access: Greenlab lists Surat and Mumbai locations, Limelight lists cities across the four profiled regions, and Avira identifies stores in southern India. [6][10][11] These footprints show how businesses reach customers and suppliers within the national market.
Table 4: Regional Growth Outlook, 2026 to 2036
| Region | CAGR, 2026 to 2036 and operating context |
|---|---|
| West India | 16.8% Greenlab locations in Surat and Mumbai [6] |
| North India | 15.5% Limelight lists Delhi NCR and other northern cities [11] |
| South India | 13.2% Avira lists Chennai, Bengaluru and Puducherry stores [10] |
| East India | 10.5% Jewelbox operates Kolkata stores; Limelight lists Kolkata [11][14] |
Why does West India have the fastest profiled regional growth outlook?
West India’s connection between stone supply and finished jewellery supports its fastest profiled outlook at 16.8% CAGR from 2026 to 2036. Greenlab’s official contact page lists a Surat location and an office at Mumbai’s Bharat Diamond Bourse. [6] Those locations place a named producer within the region’s commercial diamond network. For a jewellery maker, access to suppliers matters when a collection requires consistent specifications or a customer requests a different shape. The useful relationship extends beyond finding a stone to agreeing how and when it will reach the setting stage.
Mumbai also provides a retail setting for category development. Titan’s first beYon store was launched there in December 2025. [15] A dedicated branded store can present complete designs and collect direct feedback on what customers choose. The regional opportunity consequently runs in both directions: suppliers can respond to the requirements of finished collections, and retailers can use available production relationships to develop their ranges. Coordination becomes valuable when a design requires replacement stones or a repeat order needs to match an earlier piece.
How can organised jewellery retail support demand in North India?
Physical access gives North India a practical route to category development within its forecast 15.5% CAGR from 2026 to 2036. Limelight lists Delhi NCR, Jaipur, Lucknow and Chandigarh among its store cities. [11] The locations give customers places to see finished jewellery and discuss an order. For a retailer, the visit can resolve questions about the scale of a stone, the appearance of a setting and the fit of a ring before the purchase is completed. This is useful where a photograph alone leaves an important design choice unsettled.
The retail task is to connect that visit with fulfilment. A customer may select a displayed design but require another size or metal finish, creating an order that has to move through sourcing and manufacture. Stores can support this process by agreeing the complete specification at sale and keeping product information consistent with the delivered piece. An organised network also provides a place for later service. These functions create value around the jewellery and help explain why location, assortment and operational follow-through belong within the same regional strategy.
How do varied jewellery preferences shape the opportunity in South India?
South India’s projected 13.2% CAGR from 2026 to 2036 sits alongside an established specialist retail presence. Avira lists Chennai locations in T. Nagar and Anna Nagar, together with stores in Bengaluru and Puducherry. [10] Its catalogue includes rings, earrings and bangles, demonstrating that the offer reaches several jewellery forms. For a retailer, this breadth creates a choice about which designs to hold locally and which to supply to order. The opportunity involves making those forms available in collections that customers can compare as complete pieces.
Different applications change the service required. A ring order may need fitting and a choice of centre-stone setting, while earrings involve a paired appearance and pendants need a coordinated chain. A store carrying representative pieces can make these differences visible before the customer commits. Custom work then extends the offer where the displayed assortment does not meet the requirement. The commercial balance is between useful variety and the cost of carrying many finished variants. Clear links between the local collection and the maker’s available specifications help maintain that balance as the offer develops.
How can retailers develop a workable jewellery offer in East India?
Kolkata provides a concrete retail base within East India’s projected 10.5% CAGR from 2026 to 2036. Jewelbox identifies Kolkata as the location of its first store and headquarters, and lists outlets on Camac Street and in Salt Lake. [14] The presence of a specialist business rooted in the city adds a local route for customers to examine the category. A retailer developing such an offer can begin with a focused collection and use actual orders to understand which specifications require greater depth.
The purchasing decision remains linked to availability and completion. Holding every version of a design ties up money before a sale, while supplying everything to order can make delivery harder to predict. A useful assortment gives customers enough finished examples to judge the collection and provides a clear route to alternatives. Product descriptions need to carry the laboratory-grown origin from the display into the quotation and final piece. This creates a basis for expansion through repeatable retail operations, with local stores providing both the initial purchase experience and a place for continuing service.
Who are the notable companies in the India lab grown diamond jewelry market?
Company coverage includes Greenlab Diamonds, AIGIRI Jewels, Emori, Titan, Avira Diamonds, Limelight Diamonds, Ouros Jewels and BlueStone. Their place in the market is best understood through the work surrounding a finished piece. Diamond growth produces laboratory-grown material; cutting and polishing prepare it for trade or jewellery; manufacture combines stones with settings and other materials; retail presents the design, product information and service. These activities can be connected within a business or through suppliers. The resulting competitive offer depends on how well those connections serve the intended buyer.
Greenlab’s CVD process description places it at the production end of the chain, while Titan’s beYon shows how an established lifestyle company can enter through a dedicated consumer brand. [5][8] Specialist retailers offer other combinations of collection and access. Limelight presents several jewellery applications through stores and online, Avira combines collections with bespoke orders, and Emori provides configurable engagement-ring options. [7][10][11] Ouros’s catalogue includes established ring styles alongside custom rings and other fine jewellery. [12] These are different ways of organising a sale around the stone, and they create different requirements for inventory, design work and fulfilment.
Competitive Benchmarking: India Lab Grown Diamond Jewelry Market
Table 5: Company Capabilities and Representative Commercial Roles
| Company | Relevant offer | Commercial capability |
|---|---|---|
| Greenlab Diamonds | CVD growth and subsequent rough-diamond processing [5] | Connect production with polished-stone specifications |
| Titan / beYon | Dedicated lab-grown jewellery brand; shaped solitaires and gold colour choices [8][9] | Use a coherent branded collection to address design preferences |
| Emori | Engagement-ring styles with configurable stone and metal choices [7] | Agree the complete specification before manufacture |
| Avira Diamonds | Jewellery collections, bespoke orders and southern stores [10] | Combine local presentation with ordered alternatives |
| Limelight Diamonds | Rings, earrings, pendants and other designs through stores and online [11] | Provide access across applications and locations |
| Ouros Jewels | Lab-grown jewellery, ring styles and custom rings [12] | Serve defined designs and individual specifications |
| Jewelbox | Kolkata stores and lab-grown diamond jewellery [14] | Provide a local specialist retail route |
Key Developments in the India Lab Grown Diamond Jewelry Market
- In its 26 December 2025 stock-exchange communication, Titan announced that beYon’s first exclusive store in Mumbai would open on 29 December 2025. The dedicated brand created a new route for Titan into lab-grown diamond jewellery and placed collection design and consumer presentation at the centre of its entry. [8]
- GIA announced on 26 August 2025 that revised laboratory-grown diamond services would begin on 1 October 2025, using Premium or Standard descriptions for eligible D-to-Z material. The change gives jewellery businesses a specific assessment format to explain when presenting stones carrying that documentation. [13]
- IIT Madras hosted iCDEM 2026 from 11 to 13 March 2026, with diamond-growth technologies, process monitoring and optimisation among the subjects covered. The event connected research with the industrial ecosystem around diamond materials, adding a technical development dimension to India’s production opportunity. [1]
- GJEPC export data reported for FY 2025-26 showed falling polished lab-grown diamond export value alongside rising gold jewellery exports containing those stones. The divergence drew attention to the different products sold by loose-stone suppliers and finished-jewellery manufacturers, including the contribution of settings and metal to the latter. [2]
Key Players in the India Lab Grown Diamond Jewelry Market
- Greenlab Diamonds
- AIGIRI Jewels
- Emori
- Titan
- Avira Diamonds
- Limelight Diamonds
- Ouros Jewels
- BlueStone
- Jewelbox, with documented Kolkata retail operations. [14]
India Lab Grown Diamond Jewelry Market - Report Scope
Table 6: Report Scope
| Coverage field | Report scope |
|---|---|
| Market | Jewellery incorporating laboratory-grown diamonds manufactured, distributed or sold in India for domestic use or export |
| Forecast period | 2026 to 2036 |
| Quantitative unit | USD million |
| Application | Rings, earrings, pendants and other jewellery |
| Growth technique | Chemical vapour deposition and high-pressure, high-temperature |
| Other classifications | Cut and shape; carat size |
| Regions | West, North, South and East India |
| Application detail | Rings, earrings, pendants, necklaces, bangles and other jewellery |
| Cut and shape | Faceted cuts; other cuts and shapes |
| Carat size | 1.00 carat; other carat sizes |
| Company coverage | Greenlab Diamonds; AIGIRI Jewels; Emori; Titan; Avira Diamonds; Limelight Diamonds; Ouros Jewels; BlueStone; additional documented Jewelbox coverage |
| Contextual indicators | Loose polished-stone and finished gold-jewellery exports; research and gemological services |
The national scope covers jewellery incorporating laboratory-grown diamonds manufactured, distributed or sold in India for domestic use or export. Applications, growth techniques, cuts and sizes describe the product along complementary dimensions. Regional coverage follows West, North, South and East India. Company analysis addresses the roles involved in growing stones, preparing them for jewellery, manufacturing pieces and reaching the customer. The supporting trade and technical discussion explains the operating environment around those activities.
India Lab Grown Diamond Jewelry Market - Research Methodology
Table 7: Research Methodology
| Method | Approach |
|---|---|
| Market presentation | Published 2026 and 2036 jewellery market values and stated forecast growth. |
| Prior-year estimate | Estimated prior-year market value for 2025. |
| Segment analysis | Application, technique, size and cut measures on their stated demand or volume bases. |
| Regional analysis | Four regional CAGRs for 2026 to 2036. |
| Industry context | Export reporting, official research material and gemological sources. [1][2][3][4] |
| Company analysis | Official company descriptions, catalogues, store information and dated announcements. [5]-[15] |
Export reporting supplies context for India’s trade in polished stones and finished gold jewellery. Research and gemological sources describe production and identification practices. [1][2][3][4] Company announcements establish particular developments, while catalogues and store pages establish the products and locations described. The forecast is presented for the national jewellery market and the four profiled regions, with segment figures kept in their stated units and bases.
India Lab Grown Diamond Jewelry Market by Segments
By Application
- Rings
- Earrings
- Pendants
- Necklaces
- Bangles
- Other jewellery
By Growth Technique
- Chemical vapour deposition
- High-pressure, high-temperature
By Cut and Shape
- Faceted cuts
- Other cuts and shapes
By Carat Size
- 1.00 carat
- Other carat sizes
India Lab Grown Diamond Jewelry Market by Region
- West India
- North India
- South India
- East India
Research Sources and Bibliography
- [1] Press Information Bureau, Government of India. IIT Madras Takes Indian Research on Diamond-based Technologies to the Global Stage. 31 March 2026.
- [2] Svar Media. India’s Gem and Jewellery Exports, FY 2025-26, Reporting GJEPC Data. April 2026.
- [3] Gemological Institute of America. Laboratory-Grown Diamonds: An Update on Identification and Products Evaluated at GIA. 2024.
- [4] Gemological Institute of America. Laboratory-Grown Diamond Services.
- [5] Greenlab Diamonds. India’s Finest Diamond Craftsmanship.
- [6] Greenlab Diamonds. Contact: Mumbai and Surat Locations.
- [7] Emori. Lab Diamond Engagement Rings for Women and Men.
- [8] Titan Company Limited. Intimation of Launch of Titan’s First Lab Grown Diamond Store in Mumbai. Stock-exchange communication, 26 December 2025.
- [9] Titan Company Limited. BeYon: Brand and Jewellery Collection.
- [10] Avira Diamonds. Lab Grown Diamond Jewellery, Bespoke Orders and Store Locations.
- [11] Limelight Diamonds. Find Limelight Diamonds Stores Near You.
- [12] Ouros Jewels. About Ouros Jewels and Jewellery Collections.
- [13] Gemological Institute of America. GIA Launches Updated Laboratory-Grown Diamond Services October 1. 26 August 2025.
- [14] Jewelbox. Lab-Grown Diamond Jewellery in Kolkata, West Bengal: Store Locations.
- [15] Titan Company Limited. BeYon from House of Titan Goes Online.
This Report Answers
- How large is India’s lab-grown diamond jewellery market in 2026, and what is forecast for 2036?
- How do application, growth technique, carat size and cut influence the finished jewellery offer?
- What do the four regional growth outlooks mean for retail access and supply relationships?
- How do company offers, customization and fulfilment shape competition?
- How do polished-stone exports and finished-jewellery exports differ commercially?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Rings
- Earrings
- Pendants
- Necklaces
- Bangles
- Other jewellery
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Growth Technique, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Growth Technique, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Growth Technique, 2026 to 2036
- Chemical vapour deposition
- High-pressure, high-temperature
- Y-o-Y Growth Trend Analysis By Growth Technique, 2021 to 2025
- Absolute $ Opportunity Analysis By Growth Technique, 2026 to 2036
- Global Market Analysis and Forecast, By Cut and Shape, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Cut and Shape, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Cut and Shape, 2026 to 2036
- Faceted cuts
- Other cuts and shapes
- Y-o-Y Growth Trend Analysis By Cut and Shape, 2021 to 2025
- Absolute $ Opportunity Analysis By Cut and Shape, 2026 to 2036
- Global Market Analysis and Forecast, By Carat Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Carat Size, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Carat Size, 2026 to 2036
- 1.00 carat
- Other carat sizes
- Y-o-Y Growth Trend Analysis By Carat Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Carat Size, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- India
- Market Attractiveness Analysis By Region
- India Market Analysis and Forecast, By Region
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Region
- West India
- North India
- South India
- East India
- By Application
- By Growth Technique
- By Cut and Shape
- By Carat Size
- By Region
- Market Attractiveness Analysis
- By Country
- By Application
- By Growth Technique
- By Cut and Shape
- By Carat Size
- Key Takeaways
- Key Regions Market Analysis
- West India
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Growth Technique
- By Cut and Shape
- By Carat Size
- North India
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Growth Technique
- By Cut and Shape
- By Carat Size
- South India
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Growth Technique
- By Cut and Shape
- By Carat Size
- East India
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Growth Technique
- By Cut and Shape
- By Carat Size
- West India
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Application
- By Growth Technique
- By Cut and Shape
- By Carat Size
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Greenlab Diamonds
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Titan / beYon
- Emori
- Avira Diamonds
- Limelight Diamonds
- Ouros Jewels
- Jewelbox
- AIGIRI Jewels
- Titan
- BlueStone
- Jewelbox, with documented Kolkata retail operations. [14]
- Greenlab Diamonds
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Growth Technique, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Cut and Shape, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Carat Size, 2021 to 2036
- Table 6: India Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 7: India Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 8: India Market Value (USD Million) Forecast by Growth Technique, 2021 to 2036
- Table 9: India Market Value (USD Million) Forecast by Cut and Shape, 2021 to 2036
- Table 10: India Market Value (USD Million) Forecast by Carat Size, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Application
- Figure 6: Global Market Value Share and BPS Analysis by Growth Technique, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Growth Technique, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Growth Technique
- Figure 9: Global Market Value Share and BPS Analysis by Cut and Shape, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Cut and Shape, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Cut and Shape
- Figure 12: Global Market Value Share and BPS Analysis by Carat Size, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Carat Size, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Carat Size
- Figure 15: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: India Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: India Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: India Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 21: India Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 22: India Market Attractiveness Analysis by Application
- Figure 23: India Market Value Share and BPS Analysis by Growth Technique, 2026 and 2036
- Figure 24: India Market Y-o-Y Growth Comparison by Growth Technique, 2026-2036
- Figure 25: India Market Attractiveness Analysis by Growth Technique
- Figure 26: India Market Value Share and BPS Analysis by Cut and Shape, 2026 and 2036
- Figure 27: India Market Y-o-Y Growth Comparison by Cut and Shape, 2026-2036
- Figure 28: India Market Attractiveness Analysis by Cut and Shape
- Figure 29: India Market Value Share and BPS Analysis by Carat Size, 2026 and 2036
- Figure 30: India Market Y-o-Y Growth Comparison by Carat Size, 2026-2036
- Figure 31: India Market Attractiveness Analysis by Carat Size
- Figure 32: Global Market - Tier Structure Analysis
- Figure 33: Global Market - Company Share Analysis
Frequently Asked Questions
How large is India’s lab-grown diamond jewellery market in 2026?
The market is estimated at USD 453.7 million in 2026. The estimated prior-year value is USD 395.3 million in 2025. The outlook concerns finished jewellery incorporating laboratory-grown diamonds, so the sold piece combines the stone with its setting, design, materials and retail service.
What is the market forecast for 2036?
The market is projected to reach USD 1,798.6 million in 2036, growing at a 14.8% CAGR from 2026 to 2036. The commercial opportunity spans production, jewellery manufacture and retail, with the finished assortment determining which purchasing occasions a business can address.
Which application and growth technique lead the stated segment measures?
Rings are expected to account for 36.2% of application demand in 2026, while chemical vapour deposition is projected to represent 58.7% of growth technique volume in 2026. A ring can combine a CVD-grown stone with several possible cuts, weights and settings, bringing different segment classifications into the same finished product.
What roles do carat size and cut play in selection?
The 1.00 carat segment is projected at 29.4% of demand by size in 2026, and faceted cuts are expected to represent 64.1% by volume in 2026 under the separate cut and shape classification. Weight establishes one part of the specification; shape, proportions and the mounting determine how that stone appears within the piece.
Which region has the fastest profiled growth outlook?
West India leads at 16.8% CAGR from 2026 to 2036. North India is forecast at 15.5%, South India at 13.2% and East India at 10.5% over the same period. The regional discussion combines these forecasts with documented company locations and retail access, including western supply relationships and specialist stores in northern, southern and eastern cities.
Which companies are covered in the market?
The company coverage includes Greenlab Diamonds, AIGIRI Jewels, Emori, Titan, Avira Diamonds, Limelight Diamonds, Ouros Jewels and BlueStone. Additional discussion includes Jewelbox’s Kolkata retail operations. [14] The company component examines how documented production, design, customization and store access contribute to a finished jewellery offer.
Why do jewellery export values differ from loose-stone export values?
A loose polished stone and gold jewellery containing that stone are different traded products. The finished piece includes metal, manufacturing and design as well as the diamond. The contrasting FY 2025–26 export movements therefore reflect activity in separate product series. [2] Manufacturers selling jewellery have additional purchasing and fulfilment decisions alongside their stone requirements.
What information connects an assessed stone with the finished piece?
GIA's current service includes laboratory-grown identification and an assessment number on the stone's girdle. [4] A jewellery order also describes the metal, mounting, size and agreed design. Keeping these details together connects the submitted stone's documentation with the piece made for the customer and gives service staff a usable record when a question arises after delivery.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
