

- Market Size (2026)
- USD 1.5 Bn
- Forecast (2036)
- USD 2.5 Bn
- CAGR (2026 to 2036)
- 5.4%
How big is Industrial Clamping Elements Market in 2026?
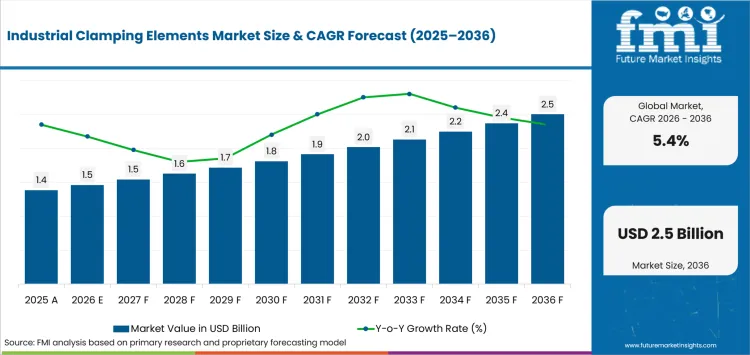
USD 1.5 billion in 2026 and USD 2.5 billion by 2036 at a 5.4% CAGR.
Sales of industrial clamping elements are projected to rise from USD 1.5 billion in 2026 to USD 2.5 billion by 2036 at a 5.4% CAGR. New machine tools and automated cells require dedicated fixtures, so equipment investment converts into specified clamps through fixture redesign and the USD 1.0 billion incremental opportunity. The International Federation of Robotics reported about 542,000 industrial robot installations for 2024 in September 2025.
Country demand diverges because manufacturing investment cycles and installed-base replacement schedules do not move together. UCIMU reported in April 2026 that Italian machine-tool orders rose 3.1% year over year during the first quarter. Domestic orders fell 28.8% while foreign orders increased 28.9%, leaving equipment programs on different investment schedules. Retrofit demand also rises as existing fixtures need faster changeovers for revised part families.
Key Takeaways
- Demand for industrial clamping elements follows machine-tool renewal and fixture redesign because every new or modified station requires a verified holding method.
- By element type, toggle clamps are estimated to hold 23.0% in 2026 owing to fast over-center locking in repetitive fixture operations.
- Manual actuation is projected to hold 39.0% share in 2026 attributable to fixtures that meet force and cycle requirements without powered utilities.
- In 2026, steel is expected to lead material with 45.0% share because stiffness and wear resistance suit high-load industrial fixtures.
- Adoption slows when engineers must revalidate clamp force, mounting geometry and safe sequencing before an established fixture component can be replaced.
- Key players in the industrial clamping elements market include DESTACO, KIPP, Jergens, JW Winco, Carr Lane, Elesa+Ganter, Bessey, Halder, AMF Andreas Maier, and Imao.
Analyst Perspective
"Industrial clamping elements earn a premium where faster loading preserves clamp force and fixture geometry already approved on the line. Powered and sensor-ready clamps need service access and repeatable position confirmation before setup savings justify added controls."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the industrial clamping elements market segmented?
The market is segmented by Element Type, Actuation, Material, End Use, Sales Channel and Region.
Element type covers toggle clamps, swing clamps, strap clamps, cam clamps, workholding clamps and hydraulic clamping elements while actuation includes manual, pneumatic, hydraulic, mechanical quick-action and electric formats. Material spans steel, stainless steel, aluminum, cast iron and engineered polymer while end use covers machine tools, welding fixtures, assembly jigs, packaging machinery and robotics - automation. Sales channels include industrial distributors, direct OEM supply, fixture builders and catalog - e-commerce routes under the stated regional taxonomy.
What makes toggle clamps central to the Element Type category?
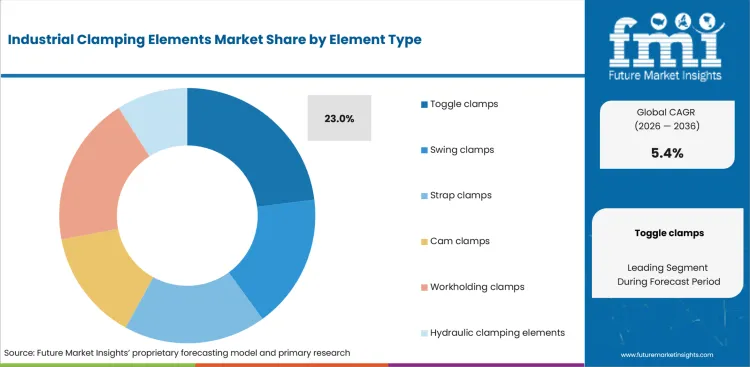
Toggle clamps use an over-center linkage to lock workpieces quickly without repeated threaded tightening during fixture loading. Compact geometry also fits machine tool spindles and fixture plates with limited mounting space.
- By element type, toggle clamps are estimated to hold 23.0% in 2026 owing to over-center locking that supports quick repetitive workpiece loading.
- Elesa+Ganter introduced GN 801.3 and GN 801.4 sensor holders for toggle clamps in February 2025. Automated cells can use the holders to confirm clamp state without replacing the mechanical fixture.
Why does manual actuation account for 39.0% of the Actuation category?
Manual clamps remain economical where an operator already loads the part and automatic sequencing is unnecessary. Avoiding compressed-air plumbing also limits installation work in industrial automation projects without powered sequencing.
- Manual actuation is likely to capture 39.0% share in 2026 attributable to fixtures that meet force and cycle requirements without powered utilities.
- Imao expanded its One-Touch Clamp range with wedge-lock swing and push variants in January 2025. The tool-less designs shorten fixture changeovers where operators already load workpieces manually during production.
How does steel support the Material category?
Steel suits fixtures that concentrate repeated contact loads through compact sections and require predictable stiffness. The material also tolerates impact and surface wear in welding equipment and consumables environments.
- Steel is projected to hold 45.0% share in 2026 owing to load capacity and wear resistance in industrial fixtures.
- JW Winco introduced increased-force clamping levers and knobs with bearing-supported steel parts in February 2026. Corrosion-resistant alternatives address harsher settings where washdown or environmental exposure changes material selection decisions.
Why do machine tools account for 30.0% of the End Use category?
Machining fixtures hold workpieces against cutting forces and return them to the same location after loading. CNC workholding systems also depend on repeatable locating geometry during fixture changes between production runs.
- In 2026, machine tools are expected to lead end use with 30.0% share because machining requires repeated fixture changes and repeatable location.
- Jergens launched cast-iron tooling columns with Ball Lock and QLS top mounting in May 2025. The columns shorten setup changes on horizontal machining platforms without replacing the complete fixture base.
What drives industrial distributors in the Sales Channel category?
Industrial distributors serve replacement orders and fixture projects that need fast technical matching in small quantities. Local stock reduces downtime when factory automation and industrial controls projects require known mounting patterns.
- By sales channel, industrial distributors are forecast to represent 39.0% in 2026 driven by local availability and broad part-number coverage.
- Carr Lane scheduled power-workholding training with ROEMHELD North America for distributors in September 2025. Channel teams received direct application instruction before supporting customer selections for powered fixture products.
What are the drivers, restraints and opportunities in the Industrial Clamping Elements Market?
Machine investment and high-mix production support fixture renewal, while qualification effort slows substitution and automated clamping offers selective opportunities where setup savings justify integration.
- Driver: New equipment and frequent product changeovers increase the number of fixtures that need fast and repeatable workpiece holding.
- Restraint: Clamp substitutions require force, geometry and safety validation before production teams can release a revised fixture for routine use.
- Opportunity: Powered or sensor-ready clamping can reduce manual setup work where cycle savings exceed installation and maintenance expense.
Machine investment raises clamping demand because each new machine or industrial robotics cell needs fixture positions with repeatable workpiece location. AMT reported in June 2026 that April metalworking machinery orders rose 33.2% from one year earlier. Fixture engineering converts equipment spending into clamping revenue once stations receive approved holding hardware for unattended or high-mix production.
Fixture substitution slows where engineers must recheck holding force and access before changing a qualified setup. VDW reported in August 2025 that German domestic machine-tool orders fell 14% in the second quarter as tariff and economic uncertainty delayed equipment decisions. Cautious equipment spending raises the burden on replacement projects because an alternative clamp must justify validation work and any added commissioning.
Setup reduction offers a revenue route without requiring every industrial fixture to adopt powered actuation. Elesa+Ganter introduced increased-force hand levers and knob nuts in January 2026 for repeated industrial fastening. Powered workholding fits high-cycle cells where setup savings justify controls and maintenance while mechanical quick-action upgrades suit operator-loaded fixtures without those extra systems.
Which country CAGRs are profiled in the Industrial Clamping Elements Market?
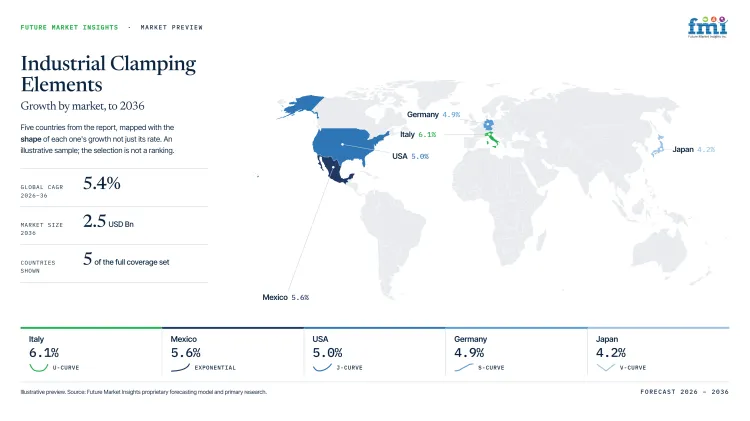
| Country | CAGR |
|---|---|
| Italy | 6.1% |
| Mexico | 5.6% |
| South Korea | 5.4% |
| USA | 5.0% |
| Germany | 4.9% |
| France | 4.8% |
| Japan | 4.2% |
How do country-level CAGRs compare in the Industrial Clamping Elements Market?
The seven country forecasts span 1.9 percentage points between Italy at 6.1% and Japan at 4.2%. Mexico and South Korea form a close second band above the tighter USA, Germany and France cluster. These differences describe forecast pace instead of absolute national revenue or installed manufacturing capacity in each country.
- Italy's forecast favors standard clamps that can be stocked before equipment orders recover fully enough to support custom fixture redesign.
- Mexico's outlook depends heavily on concentrated industrial corridors because technical coverage is less uniform outside major export-manufacturing clusters.
- South Korea pace favors compact clamp designs that preserve machine envelope during frequent model changes on automated assembly lines.
- USA demand rewards distributors that can match legacy mounting patterns without forcing plants to redesign complete fixture bases during maintenance.
- Germany forecast rewards documented standard components that reduce engineering review time during cautious equipment approval cycles.
- France outlook favors modular parts that integrators can specify early in robot projects before commissioning schedules become fixed.
- Japan's pace favors compact replacements that preserve fixture access during scheduled maintenance on mature machining equipment.
Narrow CAGR gaps make service coverage and qualification speed more useful than forecast order alone. The full report evaluates country growth with installed capacity, fixture replacement cycles and local sales channels affecting order conversion.
Country-wise Analysis
- Italian fixture demand follows machine-tool investment and export programs served by domestic equipment builders with dense local engineering networks. Industrial clamping element demand in Italy is projected to grow at 6.1% CAGR through 2036 driven by fixture renewal after delayed capital decisions. UCIMU reported in July 2025 that second-quarter machine-tool orders rose 22% year over year while domestic orders increased 70.3%. Investment uncertainty still makes project timing uneven even as domestic orders recover from a weak production-technology cycle. Workholding companies with local stock can respond faster once machine builders or welding guns require revised fixture geometry during equipment change programs.
- Mexican automotive plants run high-volume assembly programs that use dedicated fixtures and frequent line changes near export manufacturing corridors. Demand for industrial clamping elements in Mexico is forecast to rise at 5.6% CAGR over the forecast period owing to continued vehicle production and fixture replacement. INEGI reported in July 2026 that Mexico produced 354,221 light vehicles and exported 301,009 during June. Large volumes give fixture builders a clear installed customer base, but plant engineering resources vary outside mature manufacturing clusters. Workholding companies with regional stock can reduce changeover delays as robot systems are added during model updates without forcing fixture redesign.
- South Korean manufacturers operate highly automated machining and assembly lines where clamp confirmation and repeatability influence cell acceptance. Adoption of industrial clamping elements in South Korea is estimated to expand at 5.4% CAGR through 2036 supported by machinery investment and automated production. Korea's Ministry of Data and Statistics reported in August 2026 that domestic machinery orders increased 25.4% year over year during July. Integration thresholds remain high because new components must fit existing controls and maintenance practices inside automated cells. Workholding companies offering sensor-ready products can compete as robotics technologies extend into flexible production with frequent model changes and maintenance planning.
- USA workholding purchases span OEM projects and a large installed machine base that produces continuous replacement demand for standard fixture components. The USA is estimated to post 5.0% CAGR over the forecast period driven by manufacturing technology investment and routine retrofit activity. AMT reported in August 2026 that first-half manufacturing technology orders increased 36.0% from the first half of 2025. Project timing varies sharply by end market and plant utilization, which can postpone otherwise justified fixture changes during capital approval. Workholding companies that pair CAD data with domestic availability can win replacements without forcing manufacturers into unnecessary fixture redesign during capital planning.
- German clamping demand is closely tied to machine builders and automation integrators that specify workholding inside complete production equipment. The industrial clamping elements sector in Germany is projected to record 4.9% CAGR during the assessment period supported by replacement demand and selective capital recovery. VDW reported in June 2026 that first-quarter machine-tool orders rose 15% while production and employment continued to decline. Improved order intake has not removed capital caution, so fixture changes still need a clear operating case. Workholding manufacturers need configurable standard parts and credible application engineering because German factories often require documented integration before changing qualified fixtures.
- French plants increasingly evaluate clamping elements inside robotized machining and assembly projects where integrator time influences project economics. Industrial clamping element sales in France are forecast to expand at 4.8% CAGR by 2036 attributable to automation programs and modernization investment. France's Direction générale des Entreprises announced in June 2026 that 31 projects had been selected for robots and intelligent machines under France 2030. Project-based qualification can extend supplier approval before an order converts into hardware for production cells at commercial scale. Fixture manufacturers offering modular components and fast engineering response can reduce commissioning work for integrators serving varied production sites.
- Japanese manufacturers place tight emphasis on repeatability and compact fixture design because qualified machining processes often depend on stable workholding geometry. In Japan, industrial clamping element demand is predicted to advance at 4.2% CAGR through 2036 driven by precision-machining replacement and selective equipment renewal. JMTBA reported in April 2026 that February machine-tool orders increased 24.2% from one year earlier. Inflation and cautious capital budgeting can delay nonessential changes even when existing machines need setup improvements. Workholding companies with retrofit-compatible dimensions can fit beside existing tool holders without disturbing proven machine procedures during scheduled maintenance windows and documented tool-change planning.
Who are the notable companies in the Industrial Clamping Elements Market?
DESTACO, KIPP, Jergens, JW Winco, Carr Lane, Elesa+Ganter, Bessey, Halder, AMF Andreas Maier and Imao are notable companies serving this market.
Competition is fragmented because manual clamps, powered workholding and fixture-system integration follow different specification paths. Entry becomes harder where manufacturers require mounting compatibility and local application support before replacing qualified fixture components.
- Powered and integrated workholding: DESTACO and Jergens plus Carr Lane and AMF Andreas Maier serve system-level clamping roles.
- Standard machine-element platforms: KIPP, JW Winco and Elesa+Ganter supply configurable clamping parts for industrial fixtures.
- Focused manual and quick-action specialists: Bessey, Halder and Imao address fixture changes with concentrated workholding ranges.
Competitive Benchmarking: Industrial Clamping Elements Market
| Company | Current Clamping Development | Fixture Integration Depth | Application Support Breadth | Geographic Reach |
|---|---|---|---|---|
| DESTACO | High | High | High | Americas, Europe and Asia |
| KIPP | High | High | High | Europe with international distribution |
| Jergens | High | High | High | North America with international partner coverage |
| JW Winco | High | Medium | High | North America with international Ganter network |
| Carr Lane | High | High | High | North America with international distribution |
| Elesa+Ganter | High | Medium | High | Europe, Americas and Asia |
| Bessey | High | Low | Medium | Europe and North America with international distribution |
| Halder | Medium | High | Medium | Europe, North America and Asia through partners |
| AMF Andreas Maier | High | High | High | Europe-centered with international sales coverage |
| Imao | High | High | High | Japan-centered with international distribution partners |
Scoring basis: current clamping development rates documented 2025-2026 actions and never treats missing evidence as Low. High denotes multiple qualifying actions while Medium denotes one current action with direct clamping relevance. Low is reserved for one documented action with narrow clamping scope during the review period. Fixture integration depth compares powered or modular workholding coverage with narrower component-level clamping. Application support breadth reflects published engineering guidance and technical-channel coverage used to specify or maintain industrial fixtures.
Key Developments in the Industrial Clamping Elements Market
- In August 2026, Jergens introduced pneumatic self-centering vises for automated CNC machining applications requiring repeated clamping and unclamping. The launch targets unattended production where workholding must maintain centered part location without manual correction between machining cycles.
- In April 2026, KIPP received renewed ISO 9001:2015 certification covering clamping-technology development and manufacturing. The current quality-system record supports industrial fixture qualification without implying product-level approval for individual clamp models.
- In February 2026, BESSEY introduced the EZR360 one-handed table clamp with a rotating handle unit. The launch extends one-handed clamping into workbench setups that need flexible access without repositioning the complete fixture.
Key Players in the Industrial Clamping Elements Market
Powered and Integrated Workholding
- DESTACO
- Jergens
- Carr Lane
- AMF Andreas Maier
Standardized Machine-Element Platforms
- KIPP
- JW Winco
- Elesa+Ganter
Focused Manual and Quick-Action Specialists
- Bessey
- Halder
- Imao
Industrial Clamping Elements Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By element type, actuation, material, end use, sales channel and region. |
| Quantitative Units | USD billion. |
| Market Definition | Commercial revenue from discrete industrial clamping elements and clamp assemblies used to secure or release workpieces, fixtures, jigs or production-equipment components within the stated segmentation. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa. |
| Countries Covered | Italy, Mexico, South Korea, USA, Germany, France, Japan, and 20+ countries included in the full report. |
| Key Companies Profiled | DESTACO, KIPP, Jergens, JW Winco, Carr Lane, Elesa+Ganter, Bessey, Halder, AMF Andreas Maier and Imao. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Industrial Clamping Elements Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Industrial Clamping Elements Market by Segments
Industrial Clamping Elements Market segmented by Element Type:
- Toggle clamps
- Swing clamps
- Strap clamps
- Cam clamps
- Workholding clamps
- Hydraulic clamping elements
Industrial Clamping Elements Market segmented by Actuation:
- Manual
- Pneumatic
- Hydraulic
- Mechanical quick-action
- Electric
Industrial Clamping Elements Market segmented by Material:
- Steel
- Stainless steel
- Aluminum
- Cast iron
- Engineered polymer
Industrial Clamping Elements Market segmented by End Use:
- Machine tools
- Welding fixtures
- Assembly jigs
- Packaging machinery
- Robotics - automation
Industrial Clamping Elements Market segmented by Sales Channel:
- Industrial distributors
- Direct OEM supply
- Fixture builders
- Catalog - e-commerce
Industrial Clamping Elements Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- International Federation of Robotics. (2025, September 25). Global robot demand in factories doubles over 10 years.
- UCIMU-SISTEMI PER PRODURRE. (2026, April 21). UCIMU: In the first quarter 2026 machine tool orders on the rise (+3.1%); foreign orders (+28.9%); domestic orders (-28.8%).
- Elesa+Ganter. (2025, February 11). Precise attachment and reliable sensing: GN 801.3, GN 801.4.
- Imao Corporation. (2025, March). イマオNEWS 2025 No.03.
- JW Winco. (2026, February 25). Holding firm where it matters: Standard parts with increased clamping force.
- Jergens Inc. (2025, May 5). Jergens Inc. launches American-made cast iron tooling column additions.
- Carr Lane Manufacturing. (2025, September). 2025 Distributor Conference & Training.
- AMT - The Association For Manufacturing Technology. (2026, June 8). Manufacturing technology orders continued 2026 expansion through April.
- German Machine Tool Builders’ Association. (2025, August 12). Machine tool industry expecting no upturn until next year.
- Elesa+Ganter. (2026, January 28). Holding firm where it matters: Standard parts with increased clamping force GN 300.4, GN 300.7, GN 6335.9.
- UCIMU-SISTEMI PER PRODURRE. (2025, July 15). UCIMU: In the second quarter machine tool orders increased (+22%); foreign orders (+9.5%); domestic orders (+70.3%).
- Instituto Nacional de Estadística y Geografía (INEGI). (2026, July 7). Registro administrativo de la industria automotriz de vehículos ligeros. Junio de 2026.
- Ministry of Data and Statistics, Republic of Korea. (2026, August 31). Monthly industrial statistics, July 2026.
- AMT - The Association For Manufacturing Technology. (2026, August 10). 2026 manufacturing technology orders set half-year record.
- German Machine Tool Builders’ Association. (2026, June 23). Bottomed out - first quarter sees increase in orders for machine tool industry.
- Direction générale des Entreprises. (2026, June 18). France 2030: 31 new projects to accelerate the emergence of a French robotics and sovereign drones industry.
- Japan Machine Tool Builders’ Association. (2026, April 1). The current condition of the Japanese machine tool industry: Monthly machine tool orders, February 2026.
- Jergens Inc. (2026, August 3). Jergens Inc. introduces its pneumatic self-centering vise for automated CNC machining applications.
- KIPP. (2026, April 3). ISO 9001:2015 certificate for development, manufacturing, sales and logistics of clamping technology, standard elements and operating parts.
- BESSEY Tool GmbH & Co. KG. (2026, February). New one-handed table clamp with a 360° rotation mechanism.
- Elesa+Ganter. (2026, May 20). Quick release star knobs with increased clamping force GN 6336.9.
- Imao Corporation. (2026, June). イマオNEWS 2026 No.06.
- Carr Lane Manufacturing. (2025, April). MRO Americas 2025: Browse our new products.
- Imao Corporation. (2026, August). イマオNEWS 2026 No.08.
- JW Winco. (2025, July 30). Secure parts in seconds without tools - with quick release solutions.
- DESTACO. (2026, June 1). DESTACO 8800 Series Pneumatic Link Clamps for Flexible Manufacturing [LinkedIn post].
- KIPP. (2025, February 17). ISO 14001:2015 certificate for clamping technology, standard elements and operating parts.
- Jergens Inc. (2025, June 25). Jergens Inc. new Quick-Loc 2 combination pallet provides quick-change versatility.
- JW Winco. (2026, July 1). Product Spotlight 6/26: New adjustable hand levers GN 306 with special tips.
- Carr Lane Manufacturing. (2025, May). BUTECH 2025: Visit us to see our new product innovation.
- Elesa+Ganter. (2025, March 10). The ultimate solution for watertight clamping: MRY-SST-HVD.
- BESSEY Tool GmbH & Co. KG. (2025, March). New sizes of the EZ360 one-handed clamp series.
- Erwin Halder KG. (2026, June 18). Our new Quick Clamping Pins combine positioning and clamping functions in a single component [LinkedIn post].
- ANDREAS MAIER GmbH & Co. KG. (2026, January 1). The new AMF catalogues for 2026 are now available.
- Imao Corporation. (2026, August 24). 新着情報.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- What is the 2026 size and 2036 forecast for the industrial clamping elements market?
- Which machine-tool and automation investments support industrial clamping element demand?
- Why do toggle clamps hold 23.0% of element type demand?
- How does manual actuation affect fixture cost and powered-clamp economics?
- Why does steel hold 45.0% of material demand?
- How do CAGRs differ across the seven countries compared in the report?
- Which companies cover powered, standard and quick-action clamping?
- Which qualification requirements delay replacement of qualified industrial clamping elements in production fixtures?
Frequently Asked Questions
How big is the industrial clamping elements market in 2026?
The industrial clamping elements market is valued at USD 1.5 billion in 2026 and is projected to reach USD 2.5 billion by 2036. Growth follows machine investment and fixture redesign that convert new equipment into specified holding requirements.
What is the CAGR of the industrial clamping elements market from 2026 to 2036?
The industrial clamping elements market is projected to grow at a CAGR of 5.4% between 2026 and 2036. Expansion is supported by machine-tool renewal and higher setup pressure in automated or high-mix production.
Which element type leads the industrial clamping elements market?
The toggle clamps segment is expected to hold 23.0% of the industrial clamping elements market in 2026, attributable to rapid over-center locking. The format suits repetitive fixture access without requiring a slower threaded tightening cycle during every loading sequence.
How much incremental opportunity will the industrial clamping elements market create between 2026 and 2036?
The market is expected to add USD 1.0 billion in value between 2026 and 2036. The increase depends on new fixtures and retrofits converting equipment investment into qualified clamping components.
Which companies are active in the industrial clamping elements market?
Key companies operating in the market include DESTACO, KIPP, Jergens, JW Winco, Carr Lane, Elesa+Ganter, Bessey, Halder, AMF Andreas Maier, and Imao. Their roles cover powered workholding and fixture systems alongside standard elements or quick-action clamping for repeated industrial setups.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Element Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Element Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Element Type, 2026 to 2036
- Toggle clamps
- Swing clamps
- Strap clamps
- Cam clamps
- Workholding clamps
- Hydraulic clamping elements
- Toggle clamps
- Y-o-Y Growth Trend Analysis By Element Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Element Type, 2026 to 2036
- Global Market Analysis and Forecast, By Actuation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Actuation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Actuation, 2026 to 2036
- Manual
- Pneumatic
- Hydraulic
- Mechanical quick-action
- Electric
- Manual
- Y-o-Y Growth Trend Analysis By Actuation, 2021 to 2025
- Absolute $ Opportunity Analysis By Actuation, 2026 to 2036
- Global Market Analysis and Forecast, By Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material, 2026 to 2036
- Steel
- Stainless steel
- Aluminum
- Cast iron
- Engineered polymer
- Steel
- Y-o-Y Growth Trend Analysis By Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Material, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Machine tools
- Welding fixtures
- Assembly jigs
- Packaging machinery
- Robotics/automation
- Machine tools
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Industrial distributors
- Direct OEM supply
- Fixture builders
- Catalog/e-commerce
- Industrial distributors
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Element Type
- By Actuation
- By Material
- By End Use
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- DESTACO
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- KIPP
- Jergens
- JW Winco
- Carr Lane
- Elesa+Ganter
- Bessey
- Halder
- AMF Andreas Maier
- Imao
- DESTACO
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


