

- Market Size (2026)
- USD 2.9 Bn
- Forecast (2036)
- USD 5.2 Bn
- CAGR (2026 to 2036)
- 6.2%
How big is Non-Dairy Creamers Market in 2026?
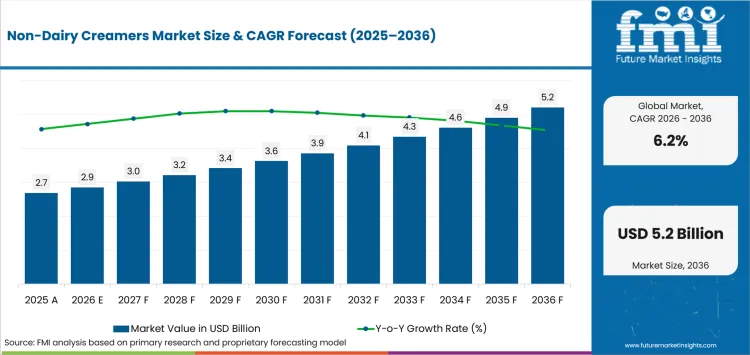
USD 2.9 billion in 2026 and USD 5.2 billion by 2036 at a 6.2% CAGR.
Demand for non-dairy creamers is projected to expand at 6.2% CAGR between 2026 and 2036. Valuation is expected to rise from USD 2.9 billion to USD 5.2 billion over the forecast period. Coffee consumption outside the home remains an important demand driver because cafés, restaurants, and beverage-service operators purchase creamers on a recurring basis. USDA Economic Research Service reported a 0.4% increase in real USA food-away-from-home spending during 2024. That service-channel resilience supports coffee creamer demand because cafés and restaurant beverage programs purchase creamer repeatedly.
Country adoption depends partly on how familiar consumers already are with dairy alternatives. The UK government reported in July 2025 that roughly 10% of surveyed people consumed plant-based drinks during 2019-2023. Oat was the most popular alternative in that assessment. This familiarity gives plant-based milk choices a clearer route into coffee customization than markets where alternative drinks require more consumer explanation.
Key Takeaways
- Shelf-stable preparation and repeated coffee occasions keep non-dairy creamers relevant to processors and foodservice operators serving predictable beverage programs.
- By form, powder is estimated to hold 62.0% in 2026 owing to ambient storage and repeatable dosing for dry beverage systems.
- In 2026, vegetable oil is expected to lead the base category with 55.0% share because spray-dried systems deliver controllable fat performance.
- Food and beverage processing is projected to hold 48.0% of end use in 2026 due to repeat qualification within scheduled production runs.
- Milk-derived caseinate can complicate non-dairy positioning because commercial labels still need accurate milk-allergen disclosure before distribution approval.
- Some of the key players in this market include Nestlé S.A., Danone S.A., TreeHouse Foods, Inc., Laird Superfood, Inc., Califia Farms, LLC, CROPP Cooperative (Organic Valley), Flora Food Group B.V., and Rich Products Corporation.
Analyst Perspective
"Creamer economics improve when a formulation survives the customer's actual coffee temperature and mixing process without repeated adjustment. The strongest commercial offers also reduce label review work while fitting the storage method used by the processor or café."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is theU.S. rules require non-dairy creamers to communicate intended coffee use without misleading consumers about dairy content. segmented?
The non-dairy creamers market is segmented by form, base, end use and distribution channel.
The non-dairy creamers market is segmented by form, base, end use and distribution channel. Form includes powder and liquid products. Base covers vegetable oil and plant-based milk. End use includes food and beverage processing, HoReCa/foodservice and household/retail. Distribution channel separates indirect sales/B2C from direct sales/B2B.
Why does Vegetable oil lead the Base category?
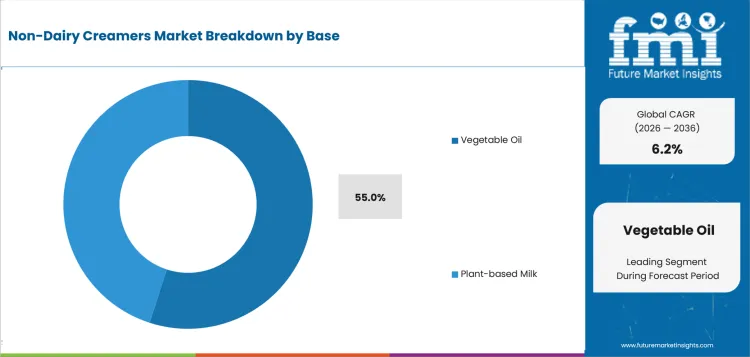
Vegetable-oil systems give formulators direct control over fat level and whitening in spray-dried creamers. Plant-based milk bases offer clearer dairy-free positioning. Almond milk alternatives still require separate work on flavor and emulsion stability before a customer approves substitution.
- By base, vegetable oil is estimated to hold 55.0% in 2026 owing to scalable fat delivery within established spray-drying processes.
- FDA Import Alert 99-22 was updated on April 15, 2026, and lists non-dairy creamer entries containing whey or caseinate with undeclared milk. The enforcement record keeps ingredient disclosure central to vegetable-oil formulations that use milk-derived proteins for emulsification or foam performance.
What makes Powder central to the Form category?
Powder reduces storage complexity in instant mixes and bulk processing because dry creamer can move without refrigerated distribution. Foaming creamer systems extend this advantage into vending and cappuccino preparation that requires consistent dispersion.
- Based on form, powder is projected to account for 62.0% in 2026 due to ambient handling and measured dosing during repeated beverage preparation.
- Laird Superfood filed its 2025 Form 10-K on March 30, 2026. The filing documents powdered and liquid coffee creamers plus 18-to-24-month shelf life for powdered products. That storage window strengthens powder economics for online orders and customers holding inventory between production cycles.
How does Food and Beverage processing lead the End Use category?
Processors qualify creamer against a finished formula before repeat orders begin. Stable dispersibility and flavor behavior therefore carry more weight than package appearance. Coconut milk formulations broaden dairy-free choices. Adjacent UHT coconut milk formats also show how ambient systems widen distribution beyond chilled networks.
- By end use, food and beverage processing is forecast to represent 48.0% in 2026 driven by repeated orders after formulation qualification.
- TreeHouse Foods filed its 2024 Form 10-K in February 2025 and identified non-dairy creamer within beverages and drink mixes. The filing also records grocery and food-away-from-home routes. Those channels give qualified formulations multiple outlets after industrial production is established.
What supports Indirect sales/B2C in the Distribution Channel category?
Indirect channels let branded creamers share the routine coffee shopping trip in grocery and online retail. Chilled liquids depend on store placement. Powder can travel efficiently through parcel networks. Oat milk formats also reach consumers already familiar with plant-based coffee preparation.
- In 2026, indirect sales/B2C is expected to lead distribution channel with 58.0% share because grocery and digital outlets aggregate household purchases.
- Organic Valley announced its first oat-based product line on January 14, 2025 with four oat creamer flavors entering nationwide grocery distribution. The launch gives indirect channels a current organic plant-based offer while direct B2B programs continue to serve processors and foodservice accounts.
What are the drivers, restraints and opportunities in the Non-Dairy Creamers Market?
Repeated coffee preparation supports demand while allergen controls limit some formulations. Plant-based recipes offer a larger commercial opening if they retain familiar coffee performance.
- Driver: More coffee occasions increase the need for creamers that fit home preparation and high-volume commercial beverage service.
- Restraint: Milk-derived ingredients can delay approval if non-dairy positioning is not matched by accurate allergen records and labels.
- Opportunity: Plant-based formulations can win additional listings once taste and foam performance meet the standards already expected from conventional creamers.
Coffee consumption gives the category a large repeat-use base instead of relying on occasional trial. The National Coffee Association reported in April 2026 that nearly 195 million USA adults drink coffee each week. Its data also show 82% of past-day drinkers prepare coffee at home. Those habits support out-of-home coffee programs plus retail creamer sales because the same consumer can purchase for different preparation settings.
Allergen records become a commercial barrier before product performance is tested if import documentation is incomplete. FDA issued a warning letter to Boba Factory on April 22, 2026 for failing to maintain required foreign-supplier verification records for imported non-dairy creamer and flavoring syrup. The case shows why importers need ingredient and supplier records ready before retail or foodservice customers approve a new formula.
Plant-based growth depends on matching simpler ingredient claims with coffee performance that survives everyday preparation. Califia Farms announced two additional Simple & Organic creamer flavors on January 22, 2026 and updated core creamer recipes without oils or gums. The launch gives plant-based food brands a current example of reformulation aimed at shorter ingredient lists without leaving the coffee occasion.
Which country CAGRs are profiled in the Non-Dairy Creamers Market?
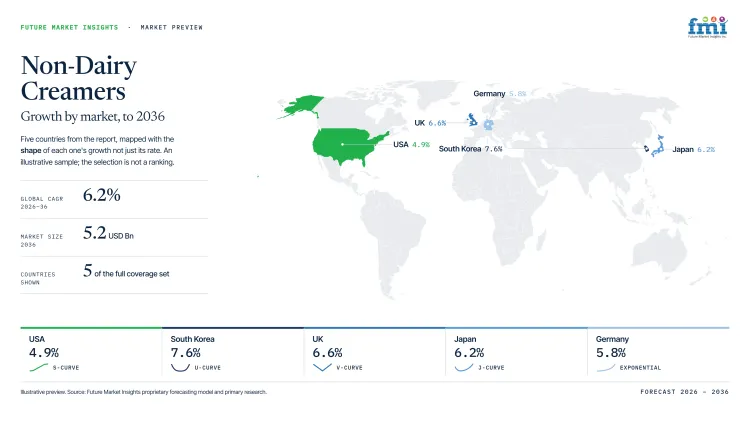
| Country | CAGR |
|---|---|
| South Korea | 7.6% |
| United Kingdom | 6.6% |
| Japan | 6.2% |
| Germany | 5.8% |
| USA | 4.9% |
How do country-level CAGRs compare in the Non-Dairy Creamers Market?
The profiled countries form a narrow 1.8 percentage-point range from South Korea at 7.6% to USA at 4.9%. South Korea and Poland make up the upper band. The United Kingdom and Japan occupy the middle. Germany follows closely. Small CAGR gaps therefore say less about entry conditions than local retail structure and product rules.
- South Korea rewards formats that fit rapid menu turnover within dense convenience and café networks.
- The United Kingdom has mature grocery exposure to alternative drinks and widespread home coffee customization.
- Japan places strong commercial weight on compact packs and clear preparation instructions for convenience-oriented shoppers.
- Germany requires plant-based products to communicate the intended coffee use without relying on protected dairy terminology.
- U.S. rules require non-dairy creamers to communicate intended coffee use without misleading consumers about dairy content.
Similar CAGRs can produce different order patterns because channel scale and qualification conditions vary by country. The full report provides country-level CAGR analysis across North America, Latin America, Europe, East Asia, South Asia, Oceania and the Middle East and Africa.
Country-wise Analysis
- South Korean café and convenience operators need creamers that mix quickly during frequent beverage menu changes. The South Korean non-dairy creamers sector is projected to record 7.6% CAGR during the assessment period tied to a large processed-food manufacturing base. The Ministry of Food and Drug Safety stated in May 2026 that 2025 food-industry production increased 4.3% from 2024. That scale gives local manufacturers an established route for packaged beverage production. Imported recipes still require Korean-language ingredient and allergen information. Companies that localize claims without slowing retail resets are better positioned for the fastest growth among the five profiled countries.
- UK cafés and grocery stores already operate in a market where plant-based beverages are familiar to many customers. Food Standards Agency guidance updated in March 2025 requires written allergen information to remain available for loose foods alongside staff communication. Retail creamer packs face a different labeling route but the same need for clear allergen information. The UK non-dairy creamers outlook is anticipated to advance at 6.6% CAGR over the assessment period helped by established alternative-drink familiarity. Products that make ingredient status easy to understand can reduce friction during listing reviews. Growth is less attractive for formulas whose dairy-free positioning becomes difficult to explain at shelf level.
- Japanese packaged-food rules make label design part of product preparation before a creamer reaches retail distribution. Adoption of non-dairy creamers in Japan is estimated to expand at 6.2% CAGR through 2036 given convenience-led coffee purchases and compact household formats. The Consumer Affairs Agency published its 2026 English booklet in April and requires ingredients on processed foods to appear in descending weight order. Milk is one of eight mandatory allergens and soybean disclosure is recommended. Clear ingredient statements favor transparent plant bases during distributor review. Caseinate users face a narrower margin for ambiguous non-dairy wording even where the technical formula performs well in coffee.
- German retailers operate under dairy naming rules that separate plant-based alternatives from products using protected milk terminology. Federal food-ministry guidance dated April 16, 2025 confirms that terms such as milk and cream generally cannot label plant-based substitutes. The restriction raises the importance of product naming before a national retailer reviews packaging. Germany is estimated to post 5.8% CAGR over the forecast period attributable to strong familiarity with alternative foods and established coffee consumption. Local demand can support plant-based creamers without borrowing protected dairy names. Companies with clear German-language use descriptions face fewer avoidable packaging revisions during broader distribution.
- U.S. retailers operate within food-labeling requirements that distinguish plant-based alternatives from conventional dairy products. Federal labeling rules require companies to use clear, truthful product descriptions and avoid labeling that could mislead consumers about a product’s composition. This requirement increases the importance of accurate product naming before national retailers review packaging. The U.S. Non-Dairy Creamers Market is estimated to post a 4.9% CAGR over the forecast period, attributable to strong coffee consumption, growing demand for dairy-free options, and broad availability of plant-based products. Local demand can support non-dairy creamers through clear alternative-dairy positioning without relying on potentially misleading dairy terminology. Companies using clear English-language descriptions and accurate ingredient communication can reduce avoidable packaging revisions during broader retail distribution.
Who are the notable companies in the Non-Dairy Creamers Market?
Nestlé S.A., Danone S.A., TreeHouse Foods, Inc., Laird Superfood, Inc., Califia Farms, LLC, CROPP Cooperative (Organic Valley), Flora Food Group B.V., and Rich Products Corporation.
Competition separates branded consumer platforms from private-label manufacturing and plant-based specialists. Entry requires more than flavor variety because retail brands need shelf access while manufacturing partners need repeatable formula control. Current evidence also shows that plant-based entrants are widening creamer portfolios instead of treating coffee as an extension of general milk alternatives.
- Nestlé S.A. and Danone S.A. operate large branded creamer platforms with national retail distribution and dedicated USA production capacity.
- TreeHouse Foods, Inc. provides private-label manufacturing while Laird Superfood, Inc. and Califia Farms, LLC compete with differentiated plant-based recipes.
- CROPP Cooperative (Organic Valley) and Flora Food Group B.V. have entered plant-based creamer lines while Rich Products Corporation serves foodservice beverage preparation.
Competitive Benchmarking: Non-Dairy Creamers Market
| Company | Format Breadth | Route-to-Market Breadth | Application Depth | Geographic Reach |
|---|---|---|---|---|
| Nestlé S.A. | High | High | High | Global |
| Danone S.A. | High | High | High | North America and Europe |
| TreeHouse Foods, Inc. | Medium | High | High | North America |
| Laird Superfood, Inc. | High | High | Medium | North America |
| Califia Farms, LLC | Medium | High | Medium | North America and United Kingdom |
| CROPP Cooperative (Organic Valley) | Low | Medium | Medium | United States |
| Flora Food Group B.V. | Low | High | High | United States and international food channels |
| Rich Products Corporation | Medium | High | High | North America and international foodservice |
Scoring basis: High format breadth requires two or more documented creamer forms or clearly separate creamer architectures. Medium identifies one creamer form plus adjacent preparation formats. Low identifies one documented creamer form. High route breadth requires multiple commercial channels. Medium requires two documented routes and Low identifies one. High application depth requires three or more documented beverage or processing uses. Medium requires two uses and Low identifies one.
Key Developments in the Non-Dairy Creamers Market
- In June 2026, Rich Products Corporation introduced updated packaging and a screw-cap format for All-In-One Creamer, improving handling and convenience during foodservice beverage preparation while maintaining the product’s multi-use positioning.
- In June 2025, Danone S.A. opened a USD 65 million production line in Jacksonville that supports International Delight creamers and other beverages. The line expands USA manufacturing capacity for a major branded creamer platform.
- In January 2025, Nestlé S.A. opened its Glendale beverage factory and distribution center for Coffee mate, natural bliss and Starbucks creamers. The site gives Nestlé additional USA capacity for refrigerated creamer production.
Key Players in the Non-Dairy Creamers Market
Branded Consumer Creamer Platforms
- Nestlé S.A.
- Danone S.A.
Private-Label and Functional Creamer Producers
- TreeHouse Foods, Inc.
- Laird Superfood, Inc.
- Califia Farms, LLC
Plant-Based and Foodservice Creamer Specialists
- CROPP Cooperative (Organic Valley)
- Flora Food Group B.V.
- Rich Products Corporation
Non-Dairy Creamers Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By form, base, end use, distribution channel and region. |
| Quantitative Units | USD Billion. |
| Market Definition | Commercial non-dairy creamer products sold as powder or liquid formats for food and beverage processing, foodservice and household coffee preparation. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | South Korea, Poland, United Kingdom, Japan, Germany, and 20+ countries included in the full report. |
| Key Companies Profiled | Nestlé S.A., Danone S.A., TreeHouse Foods, Inc., Laird Superfood, Inc., Califia Farms, LLC, CROPP Cooperative (Organic Valley), Flora Food Group B.V., and Rich Products Corporation. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Non-Dairy Creamers Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Non-Dairy Creamers Market by Segments
Non-Dairy Creamers Market segmented by Form:
- Powder
- Liquid
Non-Dairy Creamers Market segmented by Base:
- Vegetable Oil
- Plant-based Milk
Non-Dairy Creamers Market segmented by End Use:
- Food and Beverage Processing
- HoReCa/Foodservice
- Household/Retail
Non-Dairy Creamers Market segmented by Distribution Channel:
- Indirect Sales/B2C
- Direct Sales/B2B
Non-Dairy Creamers Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- USA Department of Agriculture, Economic Research Service. (2025, February 24). As food price inflation slowed in 2024, inflation-adjusted food spending rebounded.
- Office for Health Improvement and Disparities. (2025, July 16). Plant-based drinks: health benefits and risks.
- Laird Superfood, Inc. (2026, March 30). Annual report on Form 10-K for the fiscal year ended December 31, 2025.
- USA Food and Drug Administration. (2026, April 15). Import Alert 99-22.
- TreeHouse Foods, Inc. (2025, February 13). Annual report on Form 10-K for the fiscal year ended December 31, 2024.
- CROPP Cooperative. (2025, January 14). New Organic Valley creamers made with oats sourced directly from organic family farms.
- National Coffee Association. (2026, April 14). Coffee tops Americans’ beverage choices.
- USA Food and Drug Administration. (2026, April 22). Boba Factory Inc. - 728438 - 04/22/2026.
- Califia Farms. (2026, January 22). Califia Farms expands Simple & Organic portfolio with its first-ever soymilk launch.
- Ministry of Food and Drug Safety, Republic of Korea. (2026, May 29). 2025 food industry production performance increased 4.3% year over year.
- Statistics Poland. (2025, May 29). Poland in figures 2025.
- Food Standards Agency. (2025, March 5). Updated industry guidance issued for food allergen information in the out-of-home sector.
- Consumer Affairs Agency, Government of Japan. (2026, April). Booklet of the Consumer Affairs Agency: For informed food choices.
- Federal Ministry of Food and Agriculture, Germany. (2025, April 16). Questions and answers in connection with meat and milk alternatives.
- Rich Products Corporation. (2026, June 18). Rich’s beverage solutions: A fresh new look.
- Danone North America. (2025, June 17). Danone announces opening of new $65 million production line in Jacksonville, Florida.
- Nestlé USA. (2025, January 28). Nestlé expands USA manufacturing network with opening of state-of-the-art beverage factory and distribution center in Arizona.
- Laird Superfood, Inc. (2026, January 13). 2026 ICR conference presentation.
- Danone North America. (2025, December 3). International Delight and Paris Hilton introduce iconic creamers and cold foam that are anything but plain.
- Nestlé USA. (2025, August 18). Magical collaboration: Experience the Harry Potter x Coffee mate Honeydukes Cafe in Chicago.
- Danone North America. (2025, January 27). International Delight and Netflix’s Love Is Blind partner to introduce limited-edition creamers.
- TreeHouse Foods, Inc. (2026, February 11). Investindustrial completes acquisition of TreeHouse Foods.
- Laird Superfood, Inc. (2026, March 12). Laird Superfood completes acquisition of Navitas LLC.
- Califia Farms. (2025, August 5). Califia Farms launches its first organic seasonal creamers.
- CROPP Cooperative. (2025, September 10). An oat-standing innovation: Organic Valley introduces 2 new beverages made with organic oats.
- Flora Food Group B.V. (2026, March 27). Annual Report 2025.
- Oatly Group AB. (2026, March 5). Oat campus: Oatly invests $16 million in its Swedish production plant.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- How large is the non-dairy creamers market in 2026 and 2036?
- Which operating conditions sustain non-dairy creamer demand during the forecast period?
- Why does powder hold 62.0% of the form category in 2026?
- Why does vegetable oil hold 55.0% of the base category in 2026?
- Why does food and beverage processing lead the end-use category?
- How do growth rates differ among the five profiled countries?
- Which companies compete through branded products and contract manufacturing?
- How do allergen records affect commercial product approval?
Frequently Asked Questions
How big is the non-dairy creamers market in 2026?
The non-dairy creamers market is valued at USD 2.9 billion in 2026 and is projected to reach USD 5.2 billion by 2036. Repeated coffee preparation supports demand in household and commercial beverage channels.
What is the CAGR of the non-dairy creamers market from 2026 to 2036?
The non-dairy creamers market is projected to grow at a CAGR of 6.2% between 2026 and 2036. Expansion is supported by repeated coffee use and wider plant-based beverage choices.
Which form leads the non-dairy creamers market?
The powder segment is expected to hold 62.0% of the non-dairy creamers market in 2026, driven by ambient storage and repeatable dosing. Dry formats also fit instant beverage operations that require predictable handling.
Which base leads the non-dairy creamers market?
The vegetable oil segment is expected to hold 55.0% of the non-dairy creamers market in 2026, attributable to controllable fat delivery in spray-dried systems. Clear allergen records remain necessary for recipes containing milk-derived proteins.
Which countries are projected to record the highest growth in the non-dairy creamers market?
South Korea is projected to grow at 7.6% CAGR followed by Poland at 7.2% and the United Kingdom at 6.6% through 2036. Their growth routes differ through food manufacturing scale and retail familiarity with alternative drinks.
Which companies are active in the non-dairy creamers market?
Key companies operating in the market include Nestlé S.A., Danone S.A., TreeHouse Foods, Inc., Laird Superfood, Inc., Califia Farms, LLC, CROPP Cooperative (Organic Valley), Flora Food Group B.V., and Rich Products Corporation. They span branded retail and private-label manufacturing plus foodservice creamers.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Powder
- Liquid
- Powder
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Base, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Base, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Base, 2026 to 2036
- Vegetable Oil
- Plant-based Milk
- Vegetable Oil
- Y-o-Y Growth Trend Analysis By Base, 2021 to 2025
- Absolute $ Opportunity Analysis By Base, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Food and Beverage Processing
- HoReCa/Foodservice
- Household/Retail
- Food and Beverage Processing
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Indirect Sales/B2C
- Direct Sales/B2B
- Indirect Sales/B2C
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Form
- By Base
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Base
- By End Use
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Form
- By Base
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Base
- By End Use
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Form
- By Base
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Base
- By End Use
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Form
- By Base
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Base
- By End Use
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form
- By Base
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Base
- By End Use
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Form
- By Base
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Base
- By End Use
- By Distribution Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Form
- By Base
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Base
- By End Use
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Base
- By End Use
- By Distribution Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By Base
- By End Use
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nestlé S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- TreeHouse Foods Inc.
- The WhiteWave Foods Company
- Custom Food Group
- Compact Industries, Inc.
- DreamPak LLC
- FrieslandCampina Kievit BV
- Rich's Products Corp.
- Nestlé S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


