

- Market Size (2026)
- USD 147.1 Mn
- Forecast (2036)
- USD 230.6 Mn
- CAGR (2026 to 2036)
- 4.6%
How big is Popcorn Buckets Market in 2026?
Having recorded a market size of USD 140.6 million in 2025 and moving to USD 147.1 million in 2026, the global popcorn buckets market is projected to scale up to USD 230.6 million by the end of 2036, maintaining a 4.6% CAGR.
Multiplex cinema chains and quick-service restaurant operators are restructuring concession packaging programs to boost per-patron combo orders while replacing fluorinated grease treatments. In everyday lobby operations, buyers balance high-margin studio souvenir vessels against workhorse paperboard packaging tubs, where Standard Disposable Buckets are projected in 2026 to represent 38.4% of container-type volume for rapid counter dispensing. For instance in April 2026, AMC Entertainment delivered its highest five-day Easter global attendance mark and second-largest merchandise demand weekend in company history, led by collectible Yoshi and Luma popcorn buckets for The Super Mario Galaxy Movie [1]. Driven by this dual demand for everyday combo tubs and event-tied souvenir containers, global popcorn buckets market value totals USD 140.6 million in 2025 before reaching an estimated 2026 level of USD 147.1 million and a projected 2036 size of USD 230.6 million at a 4.6% CAGR, adding USD 83.5 million in decade-long market growth even as custom molding lead times restrain speculative ordering.
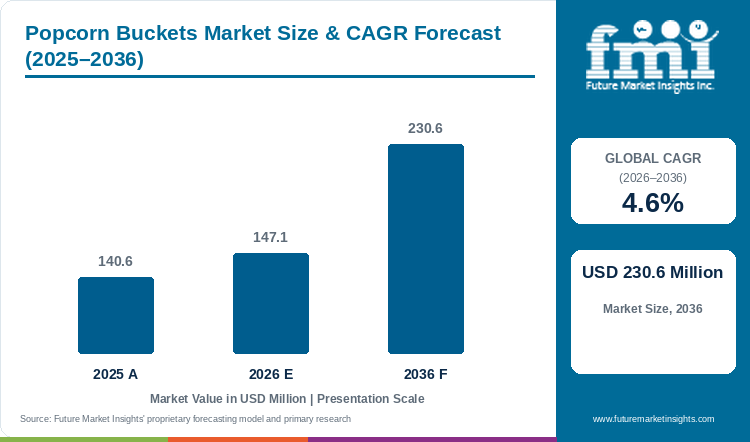
Key Market Trends & Insights
- By product type: Standard Disposable Buckets are projected in 2026 to represent 38.4% of container-type demand, supported by low piece cost and rapid counter dispensing.
- By material: In 2026, Paperboard is estimated at 46.2% of substrate volume through wide-web offset printability and established municipal fiber recovery streams.
- By format size: Within format size, Standard Sharing & Meal Buckets (85 to 130 oz) are expected in 2026 to reach 43.6% of tub-size demand because combo bundles favor deep-nested sleeves.
- By end use: Because multiplex counters earn high gross margins on freshly popped corn and themed refills, Cinemas & Theatrical Concessions are forecast in 2026 to make up 41.8% of venue consumption.
- By sales channel: Regional theater and quick-service operators consolidate tub and dome-lid deliveries onto weekly wholesale trucks, where Broadline Foodservice Distributors are anticipated in 2026 to supply 37.5% of distributor volume.
Regional Highlights
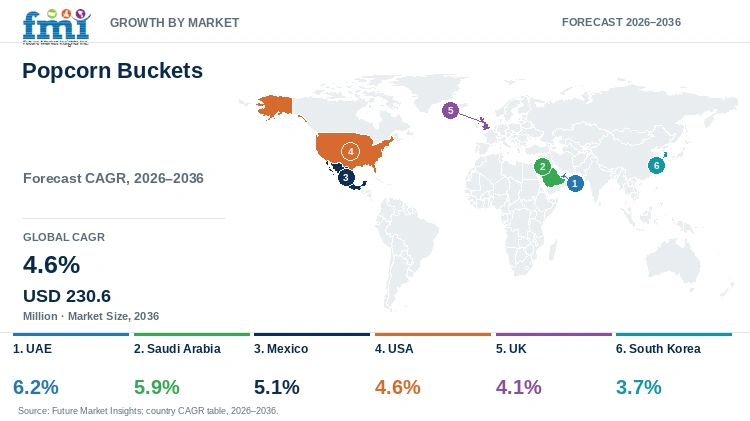
- Top national expansion: Luxury multiplex openings and mandatory single-use plastic foodware phase-outs position the UAE first among evaluated countries with a 6.2% CAGR over the 2026 to 2036 period.
- Multi-country growth outlook: Saudi Arabia advances at a 5.9% yearly pace followed by Mexico (5.1% CAGR) and the USA (4.6% CAGR), whereas the UK (4.1%) and South Korea (3.7%) reflect mature box-office attendance baselines.
Market Size & Forecast
Table 1: Market Size and Forecast for the Popcorn Buckets Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 140.6 million |
| Estimated Market Size in 2026 | USD 147.1 million |
| Projected Market Size by 2036 | USD 230.6 million |
| CAGR, 2026 to 2036 | 4.6% |
| Added Revenue, 2026 to 2036 | USD 83.5 million |
Regulatory phase-outs of legacy fluorochemical grease barriers are directly reshaping how paperboard mills and container converters qualify snack tubs for commercial concession accounts. Because freshly popped corn is dressed with warm coconut oil and clarified butter at the point of sale, any weakness in the internal coating causes side-seam wicking and rim softening during auditorium screenings. As a matter of fact, in January 2025, the U.S. Food and Drug Administration determined that 35 food-contact notifications related to per- and polyfluoroalkyl substances (PFAS) for grease-proofing paper and paperboard were no longer effective [2]. To avoid regulatory non-compliance across regional venues, multi-unit cinema and quick-service buyers are shifting annual supply contracts toward aqueous dispersion-coated paperboard and certified compostable foodservice packaging formats that preserve hot-oil holdout.
Concession-Unit and Container-Volume Sizing
Table 2: Concession-Unit and Container-Volume Sizing for the Popcorn Buckets Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 140.6 | 147.1 | 230.6 |
| Commercial bucket & tub shipments (million units) | 710.0 to 760.0 | 735.0 to 785.0 | 1,020.0 to 1,090.0 |
| Disposable paperboard & fiber buckets (million units) | 635.0 to 675.0 | 655.0 to 698.0 | 895.0 to 955.0 |
| Blended ex-converter realization (USD per unit) | 0.18 to 0.20 | 0.19 to 0.20 | 0.21 to 0.23 |
Operational note: Shipment ranges reconcile ex-factory converter realizations across high-volume printed paperboard buckets (USD 0.11 to USD 0.15 per unit) and custom-molded collectible souvenir tubs (USD 0.65 to USD 1.10 per unit), excluding retail popcorn food receipts.
Warehouse storage density and counter dispensing speed govern whether a multiplex or quick-service chain adopts a converter's bucket design across high-volume weekend shifts. When paperboard tubs have uneven taper angles or weak rim curls, nested sleeves jam inside vertical counter dispensers and slow down concession lines during peak movie intermissions. By engineering standardized tapered side-seam geometries with uniform rim stiffness, converters ship high-count corrugated cases that lower freight cost per thousand units and integrate smoothly with ready-to-eat food packaging distribution hubs.
Per Capita & Multiplex Venue Sizing
Table 3: Per Capita and Venue Spending Indicators for the Popcorn Buckets Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per 1,000 people (USD) | 17.1 | 17.7 | 25.6 |
| Annual bucket procurement per cinema screen (USD) | 270.0 to 310.0 | 280.0 to 320.0 | 415.0 to 465.0 |
| Collectible & promotional tub value share (%) | 28.0% to 30.5% | 29.0% to 31.5% | 33.5% to 36.5% |
Table 4: Venue & Concession Spending Indicators for the Popcorn Buckets Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 147.1 million | 2026 global converter revenue baseline |
| Commercial cinema screens & QSR snack outlets | 395.0 thousand | Global theatrical screen & chicken/snack QSR registry |
| Average annual bucket procurement per venue | USD 372.4 | Annualized B2B container expenditure per outlet |
| Cinemas & theatrical concessions revenue, 2026 | USD 61.5 million | 41.8% end-use segment allocation |
Per-venue annual bucket expenditure depends heavily on how effectively cinema and quick-service purchasing directors adapt snack containers for both dine-in auditoriums and off-premise home delivery. While open-top paperboard tubs work well for immediate auditorium carry-in, third-party courier delivery of popcorn and fried-chicken bundles requires rigid rim lockups that prevent heat loss and spilling in transit. Consequently, chain procurement teams pair custom-printed paperboard buckets with snap-fitting disposable cup lids and vented domes, which increases average container revenue per outlet while reducing delivery spoilage.
Analyst Perspective
"Concession and quick-service packaging buyers only award multi-year bucket contracts when a container combines fluorochemical-free grease holdout with high nesting density and rapid sleeve dispensing. Converters that pair recyclable dispersion-coated paperboard for everyday combos with short-run collectible molding capabilities will secure preferred supplier status across cinema and foodservice chains."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the popcorn buckets market segmented?
The popcorn buckets market is segmented by product type, material, format size, end use, and sales channel. In 2026, Standard Disposable Buckets are projected at 38.4%, Paperboard at 46.2%, Standard Sharing & Meal Buckets (85 to 130 oz) at 43.6%, Cinemas & Theatrical Concessions at 41.8%, and Broadline Foodservice Distributors at 37.5%.
By product type: Standard Disposable Buckets, Collectible & Promotional Tubs, Mini & Combo Buckets, and Refillable & Multi-Use Tubs.
By material: Paperboard, rPET & Polypropylene (PP), Molded Fiber & Bagasse, Compostable Bio-Polymers, and Aluminum & Tinplate.
By format size: Standard Sharing & Meal Buckets (85 to 130 oz), Family & Jumbo Tubs (150 to 170+ oz), and Single-Serve & Kid-Combo Cups (32 to 64 oz).
By end use: Cinemas & Theatrical Concessions, Quick-Service Restaurant (QSR) Chains, Theme Parks, Stadiums & Arenas, Supermarket Deli & Prepared-Food Counters, and Catering & Event Concessions.
By sales channel: Broadline Foodservice Distributors, Direct Chain & Exhibitor Contracts, Specialty Packaging & Concession Distributors, and Online B2B Portals.
Why do Standard Disposable Buckets lead the product type category?
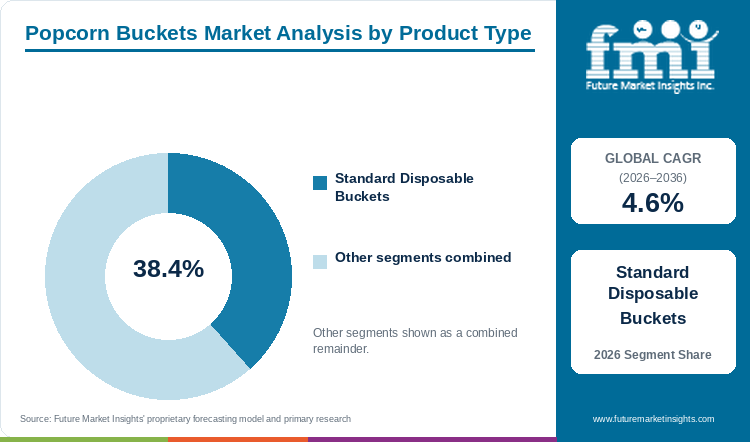
Standard Disposable Buckets are projected in 2026 to represent 38.4% of bucket-type shipments, driven by weekly replenishment across multiplexes and drive-thru counters.
Table 5: Product Type Share for the Popcorn Buckets Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Standard Disposable Buckets | 38.4% |
| Other Segments Combined | 61.6%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Popcorn Buckets Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.6% |
| Leading Segment | Standard Disposable Buckets |
Predictable unit economics and zero post-release inventory obsolescence keep everyday disposable buckets at the center of cinema and quick-service procurement budgets. While movie-specific souvenir tubs carry studio licensing royalties and stranding risk if a film underperforms at the box office, tapered disposable paper tubs separate cleanly from vertical counter dispensers and pair with molded fiber pulp trays across year-round menu programs.
- Standard Disposable Buckets are projected in 2026 to represent 38.4% of bucket-type volume because multiplexes and drive-thru chains reorder baseline paper tubs every week.
- To support this high-volume replacement shift, in June 2026, Graphic Packaging Holding Company released its 2025 Impact Report documenting 880 million plastic packages replaced with paperboard foodservice innovations in 2025 [3].
What positions Paperboard as the leading material segment?
In 2026, Paperboard is estimated at 46.2% of bucket-substrate demand on the strength of multi-color flexographic printability and fiber recyclability.
Brand merchandising teams and sustainability officers favor paperboard over rigid plastics because multi-ply fiber walls accept wrap-around promotional graphics while qualifying for municipal paper recycling streams. When converters pair water-based dispersion coatings with kafirin barrier coatings on solid bleached sulfate or recycled board, the resulting container resists rim buckling under hot buttered popcorn without triggering plastic packaging taxes.
- In 2026, Paperboard is estimated at 46.2% of bucket-substrate demand across everyday disposable tubs and custom-printed promotional combo vessels.
- For instance, in July 2026, Graphic Packaging Holding Company expanded North American circular fiber supply by launching its 100% recycled PaceSetter Ridgeline paperboard grade [4].
Why do Standard Sharing & Meal Buckets (85 to 130 oz) lead format size?
Within the format-size segment, Standard Sharing & Meal Buckets (85 to 130 oz) are expected in 2026 to reach 43.6% of tub-capacity volume due to balanced auditorium carry ergonomics.
Concession menu pricing strategies rely on 85-to-130-ounce buckets to steer couples and families toward high-margin two-drink combo bundles. This mid-large capacity fits comfortably in one hand during dark auditorium entry while avoiding the high freight cube of 170-ounce jumbo tubs, complementing paper beverage cups in both theater lobbies and drive-thru meal deals.
- Within the format-size breakdown, Standard Sharing & Meal Buckets (85 to 130 oz) are expected in 2026 to reach 43.6% of capacity demand as two-drink cinema bundles standardize around 85-to-130-ounce tubs.
- Reflecting converter innovation in this core size tier, in October 2026, Graphic Packaging International won three Paperboard Packaging Council awards for high-impact paperboard structural converting and foodservice pack design [5].
Why do Cinemas & Theatrical Concessions lead the end use category?
Because theater exhibitors rely on high-margin popcorn refills and studio tie-in tubs, Cinemas & Theatrical Concessions are forecast in 2026 to command 41.8% of venue demand.
Commercial theater circuits depend on freshly popped corn for their highest foodservice gross margins, making branded disposable buckets and studio-licensed souvenir tubs essential to venue profitability when ticket splits favor film distributors. Quick-service restaurant chains form the second-largest end-use pillar at 28.4% through bone-in chicken and fried-strip sharing buckets.
- Because commercial theater circuits anchor per-patron foodservice margins around large popcorn combos, Cinemas & Theatrical Concessions are forecast in 2026 to make up 41.8% of venue demand.
- To serve growing concession and quick-service accounts, in July 2026, the Office of the Governor of South Carolina announced Detpak USA's new Spartanburg County manufacturing operation for paper foodservice packaging [6].
How do Broadline Foodservice Distributors retain the sales channel lead?
Multi-site operators consolidate snack tubs and beverage cups onto weekly delivery trucks, where Broadline Foodservice Distributors are anticipated in 2026 to supply 37.5% of channel volume.
Limited back-of-house storage space inside shopping-mall multiplexes and urban quick-service outlets prevents venue managers from storing full truckloads of a single bucket SKU. Regional theater circuits and franchised restaurants procure buckets through broadline foodservice distributors to combine snack tubs and cold cups on a single weekly truck, while direct chain contracts account for 32.4% among top multinational brands.
- Regional venue buyers favor split-case warehouse replenishment, and Broadline Foodservice Distributors are anticipated in 2026 to supply 37.5% of wholesale channel shipments.
- As a matter of fact, in May 2026, Graphic Packaging Holding Company reported that U.S. paper cup and foodservice container recycling access reached 20% as distributors scaled recovery-ready paperboard lines [7].
What are the drivers, restraints, and opportunities in the popcorn buckets market?
Studio-licensed souvenir tubs and quick-service sharing bundles propel demand in the popcorn buckets market, whereas PFAS phase-outs and short theatrical windows elevate inventory risk and flat-pack bucket geometries create storage savings.
- Driver: Franchise movie releases and quick-service sharing bundles stimulate dual procurement of economical paperboard tubs and high-value collectible vessels.
- Restraint: Fluorochemical phase-outs and extended producer responsibility fees as well as short theatrical promotional windows elevate qualification costs and unsold stock exposure.
- Opportunity: Heavy-caliper recycled paperboard and aqueous barrier coatings reduce raw material cost while satisfying municipal plastic-ban mandates.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Higher menu prices at casual dining restaurants are steering families toward bundled cinema combos and quick-service sharing buckets that deliver lower per-person meal costs. Multiplex exhibitors capitalize on this value-seeking behavior by pairing admission tickets with sculpted and metallic-printed popcorn tubs that boost concession attachment even during uneven box-office months. According to the U.S. Department of Agriculture Economic Research Service in September 2026, food-away-from-home consumer prices rose 3.8% in 2025 and are projected to increase another 3.5% in 2026 [8]. Consequently, quick-service poultry and snack chains are expanding promotions around family-sized paperboard buckets paired with disposable beverage cups to capture off-premise dinner spending.
Risk Assessment of the Popcorn Buckets Market: Operational and Regulatory Friction
Fluorinated grease-treatment phase-outs and polyethylene-lining restrictions remain the toughest technical hurdles for bucket converters seeking hot-butter seam integrity. At the same time, modulated Extended Producer Responsibility fee schedules across Europe penalize composite and plastic-lined foodservice containers, squeezing margins on legacy poly-coated tubs. In June 2025, the UK Department for Environment, Food and Rural Affairs published 2025 to 2026 packaging Extended Producer Responsibility base fees setting paper and card at GBP 196 per tonne versus GBP 423 per tonne for plastic [9]. This steep fee gap is pushing converters to qualify suberin waterproof coatings and water-based barriers, while cinema buyers cap speculative print runs to avoid stranding movie-branded stock after a two-week theatrical run.
Commercial Opportunity Analysis: Format Engineering and Barrier Differentiation
Heavy-caliper 100% recycled paperboard formed into deep-drawn snack buckets gives packaging manufacturers a profitable way to lower raw fiber cost while meeting chain circularity goals. Virgin bleached cupstock carries high pulp cost exposure when concession operators specify oversized 130-to-170-ounce sharing tubs for family meal bundles. To capture this cost-conscious segment, in August 2026, Graphic Packaging Holding Company reported USD 2,199 million in second-quarter 2026 net sales as foodservice and beverage customers expanded commercial adoption of recycled paperboard containers [10]. Multi-ply recycled board paired with paper cup lids allows converters to win regional quick-service and stadium tenders.
Popcorn Buckets Market by Country (2026 to 2036)
Country-level concession comparisons show the UAE pacing national popcorn buckets demand with a 6.2% CAGR to 2036, while South Korea records a 3.7% compound annual growth rate. National growth differences reflect rapid multiplex screen additions and single-use plastic bans in Gulf Cooperation Council economies balanced against box-office attendance consolidation across East Asia and Western Europe.
Table 7: Country CAGR and Primary Growth Levers for the Popcorn Buckets Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| UAE | 6.2% | Dubai and Abu Dhabi single-use plastic bans and luxury mall multiplex collectibles |
| Saudi Arabia | 5.9% | Vision 2030 cinema screen expansion and family QSR sharing-bucket consumption |
| Mexico | 5.1% | High family cinema concession attach rates and local paperboard converting scale |
| USA | 4.6% | Blockbuster movie collector-tub merchandising and state PFAS-free barrier mandates |
| UK | 4.1% | PackUK EPR paperboard fee advantage and QSR recyclable fiber bucket conversions |
| South Korea | 3.7% | Premium format cinema merchandising and Ministry of Environment plastic restrictions |
Source: Future Market Insights analysis
UAE Popcorn Buckets Market Outlook (2026 to 2036)
What sets the UAE apart from mature Western cinema markets is the combination of luxury mall multiplexes and strict municipal bans on single-use plastic foodware. Cinema procurement teams and quick-service distributors across Dubai and Abu Dhabi are qualifying dispersion-coated paperboard buckets and washable polypropylene souvenir tubs to maintain venue compliance. In December 2025, Dubai Municipality confirmed that the fourth and final phase of its single-use plastic ban would take effect from January 2026 to prohibit disposable plastic foodservice cups and containers [11]. High tourist footfall and VIP dine-in auditoriums support a 6.2% projected CAGR in the UAE from 2026 to 2036, although imported virgin cupstock exposes converters to freight swings.
Key takeaway: In the UAE, Dubai's January 2026 single-use plastic foodware ban and VIP mall cinema merchandising are projected to accelerate adoption of compliant paperboard and reusable buckets.
Saudi Arabia Popcorn Buckets Market Outlook (2026 to 2036)
Unlike markets where cinema screen counts have plateaued, Saudi Arabia is experiencing rapid multiplex construction and family entertainment rollout under Vision 2030, positioning the country for an expected 5.9% CAGR in popcorn buckets demand between 2026 and 2036. Family-oriented cinema outings and drive-thru fried-chicken chains generate year-round orders for 85-to-130-ounce sharing tubs across Riyadh and Jeddah. Official box-office data from the Saudi Press Agency in September 2025 showed that domestic film ticket sales in Saudi Arabia jumped from SAR 56.8 million in 2024 to SAR 120.4 million by September 2025 across expanding commercial multiplexes [12]. However, extreme summer ambient heat during warehouse transit challenges conventional wax coatings, compelling regional distributors to specify rigid dispersion-coated paperboard buckets with high top-load crush resistance.
Key takeaway: In Saudi Arabia, expanding multiplex screen capacity and high family concession bundle orders are expected to sustain strong demand for heat-stable paperboard buckets.
Mexico Popcorn Buckets Market Outlook (2026 to 2036)
Cinema exhibition in Mexico stands out globally for its high multi-generational family attendance and strong weekend combo attachment across metropolitan shopping centers. At the same time, municipal circular-economy enforcement is tightening material rules for foodservice operators; in June 2025, the Mexico City Secretariat of the Environment (SEDEMA) marked two years of plastic reduction progress regulating single-use foodservice packaging across the capital [13]. Supported by domestic paperboard converting scale and high per-patron snack volume, the Mexico popcorn buckets market is forecast to post a 5.1% compound annual pace until 2036. Even so, ticket price sensitivity among middle-income households limits how aggressively exhibitors can raise souvenir tub prices, keeping standard printed paperboard buckets as the primary volume driver.
Key takeaway: In Mexico, high family cinema concession attachment and Mexico City circular-packaging rules are forecast to drive volume orders for recyclable printed paperboard buckets.
USA Popcorn Buckets Market Outlook (2026 to 2036)
Commercial demand across the USA is uniquely split between hundreds of millions of everyday bleached paperboard buckets and viral studio-licensed collectible vessels sold during tentpole movie openings. To capture domestic foodservice conversion toward fiber packaging, in July 2026, Detmold Group confirmed that its Detpak subsidiary had commenced paper foodservice packaging manufacturing in Spartanburg County in the USA to shorten lead times for North American quick-service and concession buyers [14]. Anchored by the world's largest revenue base for theatrical concessions and fried-chicken chains, the USA popcorn buckets sector is anticipated to register a 4.6% yearly growth rate to 2036 under state PFAS-free barrier mandates. Even so, two-week blockbuster theatrical windows create write-off risks if chains over-order custom movie tubs.
Key takeaway: In the USA, domestic paperboard converting investments and PFAS-free barrier compliance are anticipated to anchor steady replacement and promotional bucket procurement.
UK Popcorn Buckets Market Outlook (2026 to 2036)
Because total cinema footfall in the UK has stabilized near pre-existing levels, bucket demand growth depends on substrate switching and per-visit concession spend rather than new screen construction. According to official British Film Institute statistics released in February 2026, cinema admissions across the UK totaled 123.5 million in 2025, reflecting a 2.0% year-on-year dip even as box-office revenue edged higher [15]. Statutory Extended Producer Responsibility fee modulation that charges more than double per tonne for plastic versus paperboard shapes an estimated 4.1% CAGR outlook for the UK popcorn buckets market over the 2026 to 2036 period. Domestic die-cutting converters win multiplex and takeaway chicken tenders by engineering lightweight mono-material paperboard tubs that minimize producer levy exposure.
Key takeaway: In the UK, modest cinema admission trends and Extended Producer Responsibility fee differentials are estimated to favor lightweight recyclable paperboard bucket specifications.
South Korea Popcorn Buckets Market Outlook (2026 to 2036)
Multiplex operators in South Korea face a sharp divergence between contracting general admission headcounts and surging per-patron spending on premium auditorium formats and character merchandise. In fact, in March 2026, the Korean Film Council (KOFIC) reported that 2025 national cinema admissions in South Korea fell 13.8% year on year to 106.09 million tickets while IMAX and 4DX screen-linked merchandise programs expanded [16]. To protect concession profitability despite fewer standard ticket buyers, major chains in South Korea commission character-molded polypropylene collectible tubs and twin-flavor divided paperboard buckets. This merchandising shift supports a predicted 3.7% CAGR for commercial popcorn buckets demand in South Korea from 2026 to 2036, tempered by strict Ministry of Environment disposable-cup and plastic recovery rules.
Key takeaway: In South Korea, premium character-licensed collectible tubs and twin-compartment buckets are predicted to offset lower baseline cinema admission volumes.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the popcorn buckets market?
Graphic Packaging, Berry Global, Huhtamaki, Novolex, Sabert, Detmold Group, Dart Container, Pactiv Evergreen, Duni Group, and Genpak are the notable companies in the popcorn buckets market.
Category dynamics in the popcorn buckets sector divide between dedicated concession-bucket converters and diversified foodservice packaging groups. Vertically integrated paperboard leaders operate high-speed cup-and-bucket forming machines with in-house flexographic and offset printing for cinema and QSR chains. Meanwhile, global rigid-plastic and molded-fiber manufacturers supply reusable souvenir tubs and PFAS-free fiber sharing bowls across consolidated distribution networks following major 2025 corporate mergers.
- Dedicated Concession & Paper Bucket Converters: Graphic Packaging and Detmold Group (Detpak) market cataloged paperboard popcorn and snack buckets with custom grease-barrier and flat-pack options.
- Consolidated Multi-Substrate Packaging Platforms: Berry Global (combined with Amcor in April 2025) and Novolex (combined with Pactiv Evergreen in April 2025) supply injection-molded promotional tubs and broadline foodservice containers.
- Fiber & Specialty Foodservice Packaging Suppliers: Huhtamaki and Sabert along with Dart Container plus Duni Group and Genpak provide molded-fiber and paperboard food-to-go containers across wholesale hospitality channels.
Competitive Benchmarking: Popcorn Buckets Market
Table 8: Competitive Benchmarking for the Popcorn Buckets Market (qualitative capability ratings), 2026
| Company | Concession & Bucket Format Breadth | PFAS-Free & Barrier Coating Depth | Cinema & QSR Chain Access | Geographic Reach |
|---|---|---|---|---|
| Graphic Packaging | High | High | High | High |
| Berry Global (Amcor) | High | Medium | High | High |
| Huhtamaki | High | High | High | High |
| Novolex | High | High | High | Medium |
| Sabert | Medium | High | Medium | High |
| Detmold Group | High | High | High | High |
| Dart Container | Medium | Medium | High | Medium |
| Pactiv Evergreen (Novolex) | High | Medium | High | Medium |
| Duni Group | Medium | High | Medium | Medium |
| Genpak | Medium | Medium | Medium | Medium |
Scoring basis: Capability ratings evaluate documented popcorn and snack bucket SKUs across 32-to-170-ounce capacities and verified PFAS-free paperboard or reusable polymer barrier systems. Channel and geographic ratings reflect direct multiplex and QSR supply contracts plus multi-region converting plant footprints.
Key Developments in the Popcorn Buckets Market
- Amcor plc completed its all-stock combination with Berry Global on April 30, 2025, uniting Berry's North American injection-molded promotional stadium and cinema tub capabilities with Amcor's global packaging network [17].
- Huhtamaki Oyj separated its Fiber Foodservice Europe-Asia-Oceania business into distinct Fiber Packaging and Foodservice segments effective April 1, 2025 (announced February 14, 2025) to accelerate execution across molded-fiber and paperboard foodservice containers [18].
- Sabert Corporation acquired UK paperboard foodservice packaging specialist Colpac Limited on August 5, 2025, expanding European custom-printed paperboard container converting capacity [19].
- Dart Container Corporation announced a major molded-fiber packaging capacity expansion at its Lancaster County, Pennsylvania manufacturing facility on October 13, 2026 to meet rising foodservice demand for fiber containers in the USA [20].
Key Players in the Popcorn Buckets Market
Dedicated Concession & Paper Bucket Converters
- Graphic Packaging
- Detmold Group
Consolidated Multi-Substrate Foodservice Platforms
- Berry Global
- Novolex
- Pactiv Evergreen
- Huhtamaki
Molded-Fiber & Specialty Takeaway Container Suppliers
- Sabert
- Dart Container
- Duni Group
- Genpak
Popcorn Buckets Market - Report Scope
Table 9: Report Scope for the Popcorn Buckets Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Material; Format Size; End Use; Sales Channel; Region |
| Quantitative Units | USD Million |
| Market Definition | Includes B2B ex-converter revenue from disposable paperboard, molded-fiber, and bio-polymer popcorn buckets as well as injection-molded and tinplate collectible/refillable popcorn tubs (32 oz to 170+ oz). Category Scope Note: Excludes flexible microwave popcorn bags, retail pre-popped snack pouches, and commercial popcorn popping machines. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UAE, Saudi Arabia, Mexico, USA, UK, South Korea, and additional countries in the full report |
| Key Companies Covered | Graphic Packaging, Berry Global, Huhtamaki, Novolex, Sabert, Detmold Group, Dart Container, Pactiv Evergreen, Duni Group, Genpak |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Popcorn Buckets Market - Research Methodology
Table 10: Research Methodology for the Popcorn Buckets Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with cinema concession procurement directors, QSR packaging engineers, paperboard cupstock converters, and broadline foodservice distributors to validate unit realizations and collectible tub attach rates. |
| Secondary Research | Analysis of converter press releases, corporate M&A filings, national cinema admission yearbooks (BFI, KOFIC, Saudi Film Commission), and food-contact regulatory notices (U.S. FDA, DEFRA, Dubai Municipality, SEDEMA). |
| Market Sizing and Forecasting | Bottom-up container shipment modeling across disposable paperboard sleeves and custom-molded souvenir tubs reconciled against top-down theatrical screen and QSR outlet procurement budgets from 2026 to 2036. |
| Country Forecasting Model | Country CAGRs weight national multiplex screen additions, annual cinema ticket admissions, QSR fried-chicken outlet expansion, and statutory single-use plastic or EPR fee schedules across six evaluated markets. |
| Operational Benchmark Traceability | Unit volume and venue spending indicators in Tables 2, 3, and 4 trace to Graphic Packaging and Detpak container disclosures, AMC Entertainment merchandise filings, and national cinema statistical releases. |
| Data Triangulation and Validation | Converter revenue estimates are cross-checked against cupstock board tonnage and cinema concession packaging spend without double counting flexible pinch-bottom popcorn bags or retail ready-to-eat snack tubs. |
Popcorn Buckets Market by Segments
Popcorn Buckets Market segmented by Product Type:
- Standard Disposable Buckets
- Collectible & Promotional Tubs
- Mini & Combo Buckets
- Refillable & Multi-Use Tubs
Popcorn Buckets Market segmented by Material:
- Paperboard
- rPET & Polypropylene (PP)
- Molded Fiber & Bagasse
- Compostable Bio-Polymers
- Aluminum & Tinplate
Popcorn Buckets Market segmented by Format Size:
- Standard Sharing & Meal Buckets (85 to 130 oz)
- Family & Jumbo Tubs (150 to 170+ oz)
- Single-Serve & Kid-Combo Cups (32 to 64 oz)
Popcorn Buckets Market segmented by End Use:
- Cinemas & Theatrical Concessions
- Quick-Service Restaurant (QSR) Chains
- Theme Parks, Stadiums & Arenas
- Supermarket Deli & Prepared-Food Counters
- Catering & Event Concessions
Popcorn Buckets Market segmented by Sales Channel:
- Broadline Foodservice Distributors
- Direct Chain & Exhibitor Contracts
- Specialty Packaging & Concession Distributors
- Online B2B Portals
Popcorn Buckets Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries (UAE, Saudi Arabia)
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] AMC Entertainment Holdings, Inc. (2026, April 6). AMC Entertainment Delivers Best Ever Global Revenue Mark for a 5-Day Easter Weekend, Led by THE SUPER MARIO GALAXY MOVIE, Strong Merchandise Sales, and Solid Performances by Other Titles. AMC Theatres Investor Relations.
- [2] U.S. Food and Drug Administration. (2025, January 6). FDA Determines Authorization for 35 Food Contact Notifications Related to PFAS Are No Longer Effective. U.S. Department of Health and Human Services.
- [3] Graphic Packaging Holding Company. (2026, June 30). Graphic Packaging Releases 2025 Impact Report, Highlighting 880 Million Plastic Packages Replaced With Paperboard Innovations in 2025. Graphic Packaging Investor Relations.
- [4] Graphic Packaging Holding Company. (2026, July 13). Graphic Packaging Enters Uncoated Recycled Paperboard Market with Launch of PaceSetter Ridgeline. Graphic Packaging Newsroom.
- [5] Graphic Packaging Holding Company. (2026, October 2). Graphic Packaging International Celebrates Triple Success at the 2026 PPC Awards. Graphic Packaging Newsroom.
- [6] Office of the Governor of South Carolina. (2026, July 16). Detpak USA selects Spartanburg County for first US manufacturing operation. State of South Carolina.
- [7] Graphic Packaging Holding Company. (2026, May 8). Paper Cup Recycling Access Reaches 20% in U.S. Graphic Packaging Newsroom.
- [8] U.S. Department of Agriculture, Economic Research Service. (2026, September 25). Food Price Outlook - Summary Findings. U.S. Department of Agriculture.
- [9] UK Department for Environment, Food and Rural Affairs & PackUK. (2025, June 30). Extended producer responsibility for packaging: 2025 base fees. GOV.UK.
- [10] Graphic Packaging Holding Company. (2026, August 4). Graphic Packaging Holding Company Reports Second Quarter 2026 Financial Results. Graphic Packaging Investor Relations.
- [11] Dubai Municipality. (2025, December 24). Dubai to enforce final phase of single-use plastic ban from 2026. Government of Dubai.
- [12] Saudi Press Agency & Film Commission. (2025, September 30). Cinema Incentive Programs Boost Saudi Films, Attract over SAR1 Billion in Production Investments. Saudi Press Agency (SPA).
- [13] Secretaría del Medio Ambiente de la Ciudad de México (SEDEMA). (2025, June 11). La SEDEMA celebra dos años de avances hacia la circularidad en el sector de los plásticos con la PAP-CDMX. Gobierno de la Ciudad de México.
- [14] Detmold Group. (2026, July 20). Detpak Is Now Manufacturing in the United States. Detmold Packaging.
- [15] British Film Institute (BFI). (2026, February 5). Official BFI statistics reveal £6.8 billion film and high-end TV production spend in the UK. BFI Research and Statistics Unit.
- [16] Korean Film Council (KOFIC). (2026, March 4). Korean Box Office Holds the Line as Domestic Films Struggle and Premium Formats Surge in 2025. KOFIC Kobiz.
- [17] Amcor plc. (2025, April 30). Amcor completes combination with Berry Global; Positioned to significantly enhance value for customers and shareholders. Amcor Corporate News.
- [18] Huhtamaki Oyj. (2025, February 14). Huhtamaki to separate Fiber Foodservice business segment into two distinct segments: Fiber Packaging and Foodservice Europe-Asia-Oceania. Huhtamaki Global Releases.
- [19] Sabert Corporation Europe. (2025, August 5). Sabert acquires Colpac Limited. Sabert Corporation.
- [20] Dart Container Corporation. (2026, October 13). Dart Expands Molded Fiber Packaging Capacity at Pennsylvania Facility. Dart Container Newsroom.
- [21] Huhtamaki Oyj. (2025, July 16). Huhtamaki launches new compostable ice cream cups. Huhtamaki Global Releases.
- [22] Duni Group. (2025, June 3). Duni Group Acquires Majority Stake in LinePack Oy. Duni AB.
- [23] Amcor plc. (2026, April 21). Amcor Accelerates All-in-One Fiber Packaging Innovation Through Strategic Collaboration with Metsä Group and G. Mondini. Amcor Corporate News.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the popcorn buckets market in 2026 and what is forecast for 2036?
- Which concession and food-contact regulations shape popcorn bucket specifications?
- Why do Standard Disposable Buckets lead the product type category?
- Why does Paperboard remain the primary material choice for converters?
- How do growth rates compare across the UAE, Saudi Arabia, Mexico, and the USA?
- Which companies lead paperboard and collectible popcorn bucket manufacturing?
- What operational and regulatory restraints challenge bucket converters?
- Which barrier coatings and recycled paperboard grades open new tenders?
Frequently Asked Questions
How big is the popcorn buckets market in 2026, and what is forecast for 2036?
From a 2025 baseline of USD 140.6 million, global popcorn buckets market value reaches an estimated USD 147.1 million in 2026 and is forecast to hit USD 230.6 million by 2036 under a 4.6% compound annual rate.
Which product type and material segments hold the largest share in 2026?
Standard Disposable Buckets are projected in 2026 to represent 38.4% of product-type volume, while Paperboard is estimated at 46.2% of substrate demand.
Why is PFAS-free barrier coating critical for popcorn buckets?
Following the January 2025 U.S. FDA revocation of 35 PFAS grease-proofing food-contact notifications and EU PPWR restrictions, converters must use aqueous dispersion and bio-based barriers for hot butter and coconut oil holdout.
Which country grows fastest in the popcorn buckets market through 2036?
Luxury mall multiplex expansion and municipal plastic bans put the UAE first with a 6.2% CAGR through 2036, ahead of Saudi Arabia (5.9%) and Mexico (5.1%).
Who are the key players in the popcorn buckets market?
Graphic Packaging, Berry Global (Amcor), Huhtamaki, Novolex, Sabert, Detmold Group, Dart Container, Pactiv Evergreen, Duni Group, and Genpak are the key market participants.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Standard Disposable Buckets
- Collectible & Promotional Tubs
- Mini & Combo Buckets
- Refillable & Multi-Use Tubs
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Material, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Material, 2026 to 2036
- Paperboard
- rPET & Polypropylene (PP)
- Molded Fiber & Bagasse
- Compostable Bio-Polymers
- Aluminum & Tinplate
- Y-o-Y Growth Trend Analysis By Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Material, 2026 to 2036
- Global Market Analysis and Forecast, By Format Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Format Size, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Format Size, 2026 to 2036
- Standard Sharing & Meal Buckets (85 to 130 oz)
- Family & Jumbo Tubs (150 to 170+ oz)
- Single-Serve & Kid-Combo Cups (32 to 64 oz)
- Y-o-Y Growth Trend Analysis By Format Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Format Size, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- Cinemas & Theatrical Concessions
- Quick-Service Restaurant (QSR) Chains
- Theme Parks, Stadiums & Arenas
- Supermarket Deli & Prepared-Food Counters
- Catering & Event Concessions
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Broadline Foodservice Distributors
- Direct Chain & Exhibitor Contracts
- Specialty Packaging & Concession Distributors
- Online B2B Portals
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries (UAE, Saudi Arabia)
- South Africa
- Türkiye
- Israel
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Material
- By Format Size
- By End Use
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Graphic Packaging
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Berry Global (Amcor)
- Huhtamaki
- Novolex
- Sabert
- Detmold Group
- Dart Container
- Pactiv Evergreen (Novolex)
- Duni Group
- Genpak
- Berry Global
- Pactiv Evergreen
- Graphic Packaging
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


