

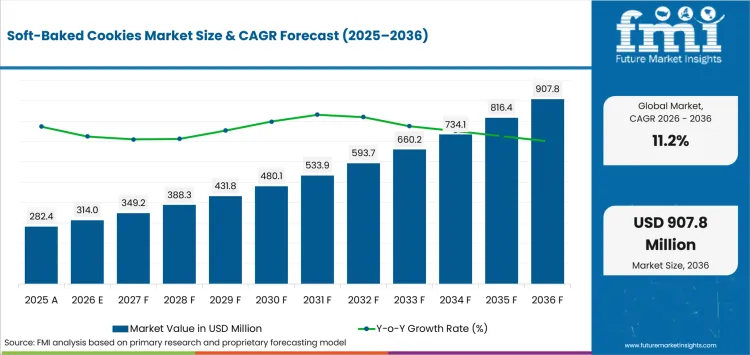
- Market Size (2026)
- USD 314.0 million
- Forecast (2036)
- USD 907.8 million
- CAGR (2026 to 2036)
- 11.2%
How big is Soft-Baked Cookies Market in 2026?
USD 314.0 million in 2026 and USD 907.8 million by 2036 at an 11.2% CAGR.
The demand for soft-baked cookies is projected to expand at an 11.2% CAGR from 2026 to 2036, rising from USD 314.0 million to USD 907.8 million as consumer preferences lean towards the comforting taste and texture of these delectable treats. August 2025 research from the Japan Society of Cookery Science found that higher-moisture soft cookies lose quality faster during storage than low-moisture crisp cookies. Manufacturers therefore need moisture control and packaging that keep the intended tender texture stable through routine retail distribution.
National rules can change how a packaged cookie is promoted even when retail sale remains available. United Kingdom guidance updated in June 2025 confirmed that qualifying less healthy foods face paid online advertising restrictions from January 2026. Brands within scope must make packaging and shelf recognition carry more conversion work when paid digital promotion is unavailable.
Key Takeaways
- Packaged demand rises as cookie brands preserve bakery-style softness through normal distribution and shelf handling.
- By product type, chocolate chip is estimated to hold 30.0% in 2026 owing to familiar inclusions that reduce trial risk.
- Based on claim - nature, conventional is projected to account for 55.0% in 2026 due to broader recipe flexibility for softness control.
- In 2026, fresh is expected to lead format with 36.0% share because short selling windows protect aroma and tender texture.
- Higher moisture can shorten shelf life and require stronger packaging controls before retailers accept wider distribution.
- Some of the key players in this market include Mondelēz International, pladis, Bahlsen, Lotus Bakeries, Walker's Shortbread, Kellanova (a Mars business), The Arnott's Group, Ferrero, Grupo Bimbo, and The Campbell's Company.
Analyst Perspective
"Soft-baked cookies can earn repeat purchase only if higher moisture survives the selling window without pushing pack cost beyond mainstream cookie economics. Retailers will give softer formats durable shelf space when texture stability and claim compliance hold during normal replenishment cycles."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the soft-baked cookies market segmented?
The soft-baked cookies market is segmented by product type, claim - nature, format, packaging format, sales channel and region.
Product type covers chocolate chip, filled & stuffed, assorted premium, and seasonal & decorated within the defined cookie range. Claim - nature separates conventional, clean label, organic, gluten-free, and high-protein - fortified recipes while format covers fresh, frozen, ambient packaged, chilled, and par-baked - thaw-and-serve products. Packaging format and sales channel distinguish pack structure from the retail or foodservice route used for commercial distribution.
Why does chocolate chip lead the product type category?
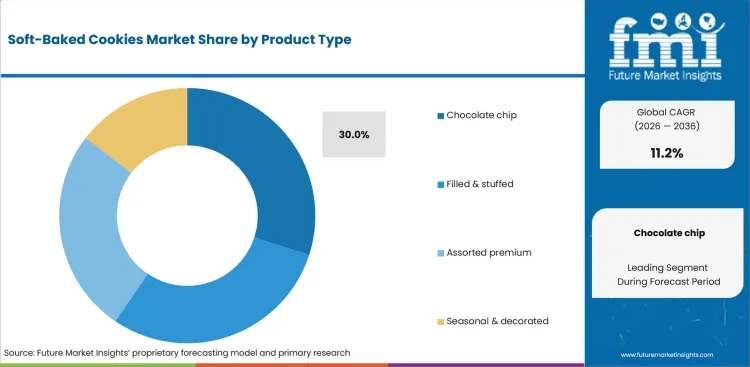
Chocolate chip gives soft cookies a familiar bakery cue because visible pieces signal indulgence before tasting. Retailers can place the variety beside mainstream chocolate chip cookies without teaching shoppers a new flavor during shelf selection.
- By product type, chocolate chip is estimated to hold 30.0% in 2026 owing to familiar indulgence cues within baking chocolate assortments.
- Ferrero expanded Keebler Chips Deluxe in May 2026 with a Brownie variety described by the company as a thick soft-baked chocolate chip cookie.
Why does conventional lead the claim - nature category?
Conventional recipes let bakery teams balance sugar and fats with humectants that protect softness during normal selling periods. That flexibility also lets formulators adjust moisture or flavor without switching the product into a claim-led recipe architecture.
- Conventional is expected to account for 55.0% of claim - nature in 2026, driven by recipe flexibility within mainstream bakery ingredients.
- Mondelēz Japan launched Oreo Bits Sandwich Strawberry nationwide in March 2026 as a new bite-size flavor extension. The launch keeps a mainstream biscuit format while changing flavor and portion size without adding a claim-led proposition.
Why does fresh lead the format category?
Fresh production shortens the interval between baking and consumption so tender texture and bakery aroma reach shoppers before longer holding periods intervene.
- In 2026, fresh is projected to represent 36.0% of format because shorter turnover protects bakery aroma within mainstream bakery products.
- Japan Society of Cookery Science research released in August 2025 examined how moisture content changes cookie quality during storage. The findings make moisture management a practical requirement when fresh-format products must travel beyond the bakery counter.
Why does multipack lead the packaging format category?
Multipacks limit repeated exposure after opening and preserve household value by keeping more cookies sealed until each eating occasion.
- Multipack is set to hold 37.0% of packaging format in 2026, supported by portion protection within common snack food packaging practices.
- FDA allergen guidance issued in January 2025 addresses labeling for individual units inside multiunit packages. Manufacturers therefore need the outer pack and any individually wrapped units to carry the required allergen information before national distribution.
Why do supermarkets & hypermarkets lead the sales channel category?
Large grocery stores place soft-baked cookies beside mainstream biscuits or fresh bakery displays while national chains can support several pack sizes and prices.
- Supermarkets & hypermarkets are estimated at 41.0% of sales channel in 2026, attributable to broad assortment space within routine biscuits and crackers shopping trips.
- Mondelēz India launched Oreo Golden in May 2026 and distributed the variant through neighborhood stores, supermarket chains and quick-commerce platforms. The channel mix shows how a national cookie launch can reach large grocery stores without relying on one retail format.
What are the drivers, restraints and opportunities in the Soft-Baked Cookies Market?
Bakery-style softness supports repeat purchase, shelf-life and disclosure requirements raise execution costs, and claim-led reformulation can reach additional shopper occasions.
- Driver: Manufacturers can make familiar cookie flavors feel different by delivering repeatable softness in packaged formats.
- Restraint: Higher moisture and nutrition disclosures can raise packaging or operating costs before routine distribution.
- Opportunity: Gluten-free and simpler recipes can reach more shoppers if reformulation preserves the tender bite.
Packaged growth depends on giving shoppers a familiar cookie with a distinct reason to try another pack. Mondelēz India announced in May 2026 that limited-edition Oreo and BTS cookies would enter the market through a branded collaboration. Cookie makers can pair recognizable flavors with cookie pieces and crumb inclusions to vary eating cues without changing the core soft-baked proposition.
Higher moisture raises shelf-life cost and foodservice sales add separate disclosure work for recipes sold outside the home. Saudi Arabia announced three foodservice nutrition regulations in February 2025 covering high-salt labeling plus caffeine and calorie-burn information from July. Operators serving those channels need menu-ready nutrition data while confectionery and dessert packaging still needs enough barrier performance to protect higher-moisture products.
Claim-led reformulation can reach new shoppers only when the recipe still delivers the texture that makes a softer cookie worth buying. Grupo Bimbo reported in June 2026 that it was removing artificial colors from its portfolio and simplifying recipes while maintaining taste and product experience. Soft-baked cookie makers can pursue similar recipe simplification or gluten-free products only after texture stability remains acceptable for the intended selling window.
Which country CAGRs are profiled in the Soft-Baked Cookies Market?
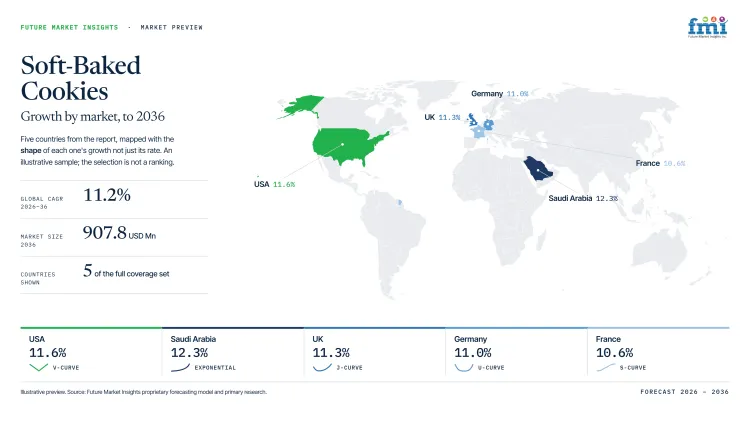
| Country | CAGR |
|---|---|
| UAE | 12.6% |
| Saudi Arabia | 12.3% |
| South Korea | 11.9% |
| USA | 11.6% |
| UK | 11.3% |
| Germany | 11.0% |
| France | 10.6% |
| Japan | 10.3% |
How do country-level CAGRs compare in the Soft-Baked Cookies Market?
The country CAGRs span 2.3 percentage points, but the commercial conditions behind that narrow range differ materially. Gulf markets pair imported snack ranges with expanding domestic food production that gives brands additional national distribution routes. Mature European and Asian markets place more weight on labeling rules plus price discipline and controlled assortments. Those differences alter launch costs even when the forecast rates remain close over the same period.
- UAE grocery shelves carry imported premium snacks beside expanding domestic production, giving new cookie formats several national distribution routes.
- Saudi Arabia combines modern grocery with foodservice and convenience channels, allowing household and single-serve cookie packs to reach different occasions.
- South Korea's dense convenience network gives snack brands frequent assortment resets, shortening the path from limited trial to wider national distribution.
- United States brands can scale packaged cookie launches through national grocery chains and e-commerce, supporting rapid availability after a flavor gains acceptance.
- United Kingdom brands compete inside a mature sweet-biscuit aisle, where restricted advertising increases the value of shelf recognition and pack communication.
- German discount and grocery channels provide broad access, but price discipline limits how far softer premium cookie formats can stretch pack economics.
- French grocery groups offer national reach while Nutri-Score presentation keeps recipe composition visible, forcing soft-cookie reformulation to protect eating quality.
- Japanese retailers favor compact packs and controlled presentation, so softer formats must preserve texture through centralized distribution and short assortment windows.
Similar CAGRs can therefore produce different launch economics because shelf access, labeling work and replenishment conditions vary by country. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- USA grocery teams can sell ready-to-eat soft-baked cookies through national stores and online channels without changing the core pack. USA demand is forecast to rise at 11.6% CAGR through 2036 as national distribution can scale an accepted flavor quickly. In January 2025 the FDA proposed a front-of-package Nutrition Info box for most packaged foods with descriptors for saturated fat plus sodium and added sugars. The proposal adds pack-review work for indulgent recipes while refrigerated cookie dough competes for shoppers seeking a fresh-baked cue. National chains therefore need soft-baked products that retain texture through routine warehouse and store replenishment.
- German retailers sell cookies into a mature biscuit category where nutrient composition receives close scrutiny from national reduction programs. Germany is projected to record 11.0% CAGR during the assessment period owing to broad grocery access and repeat demand for familiar formats. The federal reduction strategy published in March 2025 sets a 1.1 gram average salt target per 100 grams for packaged baked goods. It also recognizes technical roles for sugar during reformulation so softer recipes must protect texture as nutrition changes. Gut-friendly cookies compete for wellness shelf space while discount chains keep price points tight for new listings.
- French grocery groups give packaged cookies broad national reach and place visible nutrition information directly in front of shoppers. France is anticipated to advance at 10.6% CAGR over the assessment period as mainstream retail supports indulgent and portion-led variants. In March 2025 an official order introduced the revised Nutri-Score presentation for participating products. Recipe teams must test whether sugar or saturated-fat changes improve the displayed score without weakening soft-baked texture during repeat purchase.
- UK retailers manage a mature sweet-biscuit aisle with private label, national brands and frequent promotions. UK soft-baked cookie sales are forecast to expand at 11.3% CAGR by 2036 as texture differentiation gives shoppers another reason to buy within familiar snack missions. Government restrictions taking effect in January 2026 prohibit qualifying less healthy food advertising on television before 9 p.m. and paid online advertising at all times. National grocery coverage therefore puts more conversion pressure on package recognition and shelf execution.
- Large grocery stores in Saudi Arabia operate beside convenience outlets and foodservice channels that can support household and single-serve cookie packs. Saudi Arabia is forecast to expand at 12.3% CAGR during the forecast period as modern retail gives imported and regional brands several pack-size routes. The SFDA Food Labeling Calculator updated in February 2026 helps manufacturers prepare nutrition labels covering calories plus sugars and sodium. Importers still need accurate formulation data and moisture-stable packs before products move from regional warehouses into national retail replenishment.
- UAE food manufacturers and importers sell into a national grocery system that combines imported assortments with expanding local production. UAE demand is predicted to advance at 12.6% CAGR through 2036 as wider domestic food capacity can shorten supply routes for selected products. In May 2026 the Ministry of Industry and Advanced Technology said a new policy could support up to 200 food factories and raise local production capacity by 15% to 30%. Soft-baked cookie programs still need packs that protect texture when products move between factories, distribution centers and warm retail environments.
- Japanese retailers give close attention to package quality and portion control in compact snack assortments that leave little room for poor texture. Adoption of soft-baked cookies in Japan is estimated to expand at 10.3% CAGR through 2036 as softer Western-style formats gain room beside familiar biscuits. The Consumer Affairs Agency issued the fifth edition of its nutrition-labeling business guidelines in April 2025 and confirmed mandatory information for packaged processed foods. Claim-led products therefore need nutrient calculations and pack formats that protect texture until the final retail shelf.
- South Korean convenience and grocery channels refresh snack assortments quickly so novel textures can move from trial to wider distribution. Soft-baked cookie sales in South Korea are forecast to expand at 11.9% CAGR by 2036 as dense modern retail shortens product-test cycles. The Ministry of Food and Drug Safety amended food-labeling standards in April 2025 ahead of expanded mandatory nutrition labeling from January 2026. Manufacturers need compliant Korean labels and flexible formulations so flavor updates do not force a complete texture-validation restart.
Who are the notable companies in the Soft-Baked Cookies Market?
Mondelēz International, pladis, Bahlsen, Lotus Bakeries, Walker's Shortbread, Kellanova (a Mars business), The Arnott's Group, Ferrero, Grupo Bimbo, and The Campbell's Company are notable companies active in cookies, biscuits, baked snacks or adjacent routes relevant to this market.
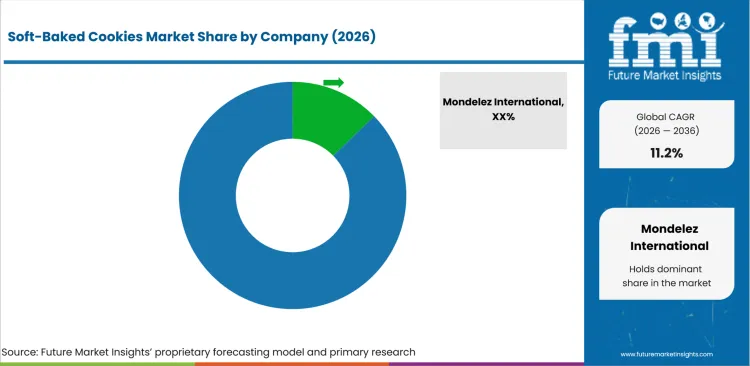
Competition spans direct cookie groups and broader snack companies with national retail routes for packaged cookies. Mondelēz International and Ferrero maintain direct cookie portfolios, while pladis, Bahlsen, Lotus Bakeries and Walker’s Shortbread specialize in biscuits. The Campbell’s Company and The Arnott’s Group add branded biscuit depth through wider snack platforms.
- Direct cookie and biscuit platforms include Mondelēz International and pladis alongside Bahlsen and Lotus Bakeries while Walker's Shortbread operates a specialist shortbread business with export routes.
- Broader snack and bakery platforms include Kellanova (a Mars business) and The Arnott's Group alongside Ferrero. Grupo Bimbo and The Campbell's Company bring bakery and branded-cookie businesses with wider retail distribution.
Competitive Benchmarking: Soft-Baked Cookies Market
| Company | Direct Cookie / Biscuit Fit | Retail Route Breadth | Claim or Format Breadth | Geographic Reach |
|---|---|---|---|---|
| Mondelēz International | High | High | Medium | Global |
| pladis | High | High | Medium | Europe and Middle East |
| Bahlsen | High | Medium | Low | Europe |
| Lotus Bakeries | High | High | Medium | Multi-region |
| Walker's Shortbread | High | Medium | Low | UK exports |
| Kellanova (a Mars business) | Medium | High | High | Global |
| The Arnott's Group | High | High | High | Asia-Pacific |
| Ferrero | High | High | Medium | Global |
| Grupo Bimbo | Medium | High | Medium | Multi-region |
| The Campbell's Company | High | High | Medium | North America |
Scoring basis: High direct fit requires a documented 2026 cookie or biscuit action while Medium identifies an immediately adjacent baked-snack action. Breadth ratings reflect documented current routes or variants: High requires at least three, Medium two and Low one.
Key Developments in the Soft-Baked Cookies Market
- In August 2026, Ferrero returned Keebler Spookie Fudge Stripes for Halloween with nationwide United States availability and an expanded zoo-themed digital activation.
- In July 2026, Mondelēz Japan announced a limited-edition Oreo BTS package for nationwide August release with receipt-based campaign participation.
- In May 2026, Lotus Bakeries and Tomorrowland introduced a limited-edition Biscoff Sandwich Cookie Espresso for a premium co-branded occasion.
Key Players in the Soft-Baked Cookies Market
Cookie and Biscuit Specialists
- Mondelēz International
- pladis
- Bahlsen
- Lotus Bakeries
- Walker's Shortbread
Broader Snack and Bakery Platforms
- Kellanova (a Mars business)
- The Arnott's Group
- Ferrero
- Grupo Bimbo
- The Campbell's Company
Soft-Baked Cookies Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, claim - nature, format, packaging format, sales channel and region. |
| Quantitative Units | USD million. |
| Market Definition | Revenue includes finished cookies sold with a soft, chewy, tender or moist-baked texture in fresh, frozen, ambient packaged, chilled and par-baked - thaw-and-serve formats. Crisp biscuits, raw cookie dough, brownies and downstream desserts are excluded unless the sold item itself is a soft-baked cookie. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | USA, Germany, France, UK, Saudi Arabia, UAE, Japan, South Korea, and 20+ countries included in the full report. |
| Key Companies Profiled | Mondelēz International, pladis, Bahlsen, Lotus Bakeries, Walker's Shortbread, Kellanova (a Mars business), The Arnott's Group, Ferrero, Grupo Bimbo, and The Campbell's Company. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Soft-Baked Cookies Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Soft-Baked Cookies Market by Segments
Soft-Baked Cookies Market segmented by Product Type:
- Chocolate chip
- Filled & stuffed
- Assorted premium
- Seasonal & decorated
Soft-Baked Cookies Market segmented by Claim - Nature:
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein - fortified
Soft-Baked Cookies Market segmented by Format:
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Par-baked - thaw-and-serve
Soft-Baked Cookies Market segmented by Packaging Format:
- Multipack
- Single-serve
- Family - loaf pack
- Bulk foodservice
Soft-Baked Cookies Market segmented by Sales Channel:
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
Soft-Baked Cookies Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Japan Society of Cookery Science. (2025, August 30). The effect of saccharides on the physical properties of soft cookies.
- Department of Health and Social Care. (2025, June 4). Restricting advertising of less healthy food or drink on TV and online: products in scope.
- Ferrero. (2026, May 5). Keebler Chips Deluxe is getting 'Deluxified' with more chips, more fudge, and new flavors across the full portfolio.
- Mondelēz Japan. (2026, March 30). 「オレオ ビッツサンド いちご」が2026年3月30日(月)より発売開始!.
- Japan Society of Cookery Science. (2025, August 30). Effect of moisture content on quality of candy and cookie.
- USA Food and Drug Administration. (2025, January). Guidance for Industry: Questions and Answers Regarding Food Allergen Labeling (Edition 5).
- Mondelēz India. (2026, May 11). Oreo Turns Golden with a Vanilla Twist!.
- Mondelēz India. (2026, May 26). The OREO Brand & BTS Movement is On! Introducing the Limited Edition OREO & BTS Cookies.
- Saudi Food and Drug Authority. (2025, February 27). The SFDA issues three new regulations to promote healthy community nutrition.
- Grupo Bimbo. (2026, June 10). Portfolio Free from Artificial Colors.
- USA Food and Drug Administration. (2025, January 14). FDA proposes requiring at-a-glance nutrition information on the front of packaged foods.
- Bundesministerium für Ernährung und Landwirtschaft. (2025, March 24). Nationale Reduktions- und Innovationsstrategie für Zucker, Fette und Salz in Fertigprodukten.
- République française. (2025, March 14). Arrêté du 14 mars 2025 fixant la forme de présentation complémentaire à la déclaration nutritionnelle recommandée par l'Etat en application des articles L. 3232-8 et R. 3232-7 du code de la santé publique.
- Department of Health and Social Care. (2026, January 5). Landmark junk food ad ban to protect kids' health.
- Saudi Food and Drug Authority. (2026, February 26). Food Labeling Calculator.
- UAE Ministry of Industry and Advanced Technology. (2026, May 7). Make it in the Emirates concludes largest edition yet.
- Consumer Affairs Agency. (2025, April). 食品表示法に基づく栄養成分表示のためのガイドライン 第5版.
- Ministry of Food and Drug Safety. (2025, April 21). 「식품등의 표시기준」 일부개정고시 (고시 제2025-27호, 25.4.21.).
- Ferrero. (2026, August 27). Keebler Spookie Fudge Stripes Return for Halloween 2026 with Nationwide Zoo Safari.
- Mondelēz Japan. (2026, July 27). OREO & BTS ムーブメント、始動!期間限定品「オレオ BTSパッケージ バニラクリーム 36枚」2026年8月3日より日本全国で発売開始!.
- Lotus Bakeries. (2026, May 4). BISCOFF AND TOMORROWLAND INTRODUCE A LIMITED EDITION BISCOFF SANDWICH COOKIE ESPRESSO.
- Mondelēz India. (2026, January 30). Oreo Turns India’s World Cup Dreams into a Nationwide Fan Movement with ‘Dream for the Team’.
- New Idea. (2026, April 8). A new Tim Tam flavour drops as two iconic biscuits join forces.
- Mondelēz India. (2026, March 26). Mondelez India Celebrates the Many Ways India Loves Biscoff with “Every Way to Biscoff”.
- pladis. (n.d.). Discover New Biscuit & Snack Innovations. Retrieved September 14, 2026.
- Scottish Grocer & Convenience Retailer. (2026, June 18). McVitie's unveils new Jaffa Cookies range.
- Ferrero. (2026, April 27). Mother's Cookies and Magnolia Bakery launch limited-edition Strawberry Banana Pudding collaboration for National Strawberry Month.
- New Idea. (2026, February 16). Your favourite chocolate biscuit just got a whole lot mintier.
- Mondelēz Japan. (2026, March 9). 「オレオ メガパック いちごクリーム 36枚」が2026年3月9日(月)より発売開始!.
- pladis. (2026, August 24). McVitie's unwraps its biggest Festive range yet, with first-ever Penguin Chocolate Treat and refreshed seasonal favourites.
- Bahlsen. (2026, August 15). Teilnahmebedingungen Bahlsen 15 Uhr Moment.
- Lotus Bakeries. (2026, May 12). Lotus Bakeries marks the start of the expansion of its Lembeke production site.
- Walker's Shortbread. (2026, June 12). Walker’s Shortbread Partners with ASPCA Through ‘Shortbread That Saves’.
- Mars, Incorporated. (2026, April 27). A Match Made for Fandom: Kellanova and the USA Soccer Federation Team Up to Launch an Exclusive Snack Lineup Celebrating Moments that Bring Your Pack Together.
- The Arnott's Group. (n.d.). Tim Tam. Retrieved September 14, 2026.
- Ferrero. (2026, March 2). Keebler Brings the Magic Back with Limited Edition Harry Potter Butterbeer Fudge Stripes Cookies.
- Grupo Bimbo. (2026, May 12). We achieved Positive Nutrition across 98% of our daily consumption portfolio.
- The Campbell's Company. (2026, June 18). Snack brands celebrate America’s 250th with limited-edition releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- How large is the soft-baked cookies market in 2026 and 2036?
- Which conditions support repeat purchases of packaged soft-baked cookies?
- Why does chocolate chip hold 30.0% of product type?
- How do conventional recipes affect softness and mainstream pricing?
- Why does fresh hold 36.0% of format in 2026?
- How do growth rates differ among the eight profiled countries?
- Which companies participate through cookies or adjacent baked snacks?
- How do moisture and nutrition rules affect product economics?
Frequently Asked Questions
How big is the Soft-Baked Cookies Market in 2026?
The soft-baked cookies market is valued at USD 314.0 million in 2026 and is projected to reach USD 907.8 million by 2036. Bakery-style softness must survive routine retail distribution without excessive packaging or replenishment costs for repeat purchase.
What is the CAGR of the Soft-Baked Cookies Market from 2026 to 2036?
The soft-baked cookies market is projected to grow at a CAGR of 11.2% between 2026 and 2036. Texture retention and broader retail availability support expansion as manufacturers keep reformulation commercially acceptable for mainstream assortments.
Which product type leads the Soft-Baked Cookies Market?
Chocolate chip is expected to hold 30.0% of product type in 2026 because familiar inclusions reinforce a recognizable bakery-style cue. Familiar flavor recognition lowers trial risk for shoppers comparing softer cookies with mainstream crisp-cookie products.
Which packaging format leads the Soft-Baked Cookies Market?
Multipack is expected to hold 37.0% of packaging format in 2026 because protected portions reduce repeated exposure after opening. Household value improves when each portion retains the intended texture during several consumption occasions.
Which companies are active in the Soft-Baked Cookies Market?
Key companies include Mondelēz International, pladis, Bahlsen, Lotus Bakeries, Walker's Shortbread, Kellanova (a Mars business), The Arnott's Group, Ferrero, Grupo Bimbo, and The Campbell's Company. Their cookie and baked-snack businesses cover specialist biscuit platforms plus broader retail distribution systems.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Chocolate chip
- Filled & stuffed
- Assorted premium
- Seasonal & decorated
- Chocolate chip
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Claim / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim / Nature, 2026 to 2036
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein / fortified
- Conventional
- Y-o-Y Growth Trend Analysis By Claim / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Format, 2026 to 2036
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Par-baked / thaw-and-serve
- Fresh
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packaging Format, 2026 to 2036
- Multipack
- Single-serve
- Family / loaf pack
- Bulk foodservice
- Multipack
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
- Supermarkets & hypermarkets
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Mondelez International
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- pladis
- Bahlsen
- Lotus Bakeries
- Walkers Shortbread
- Kellanova
- Arnott's
- Ferrero
- Grupo Bimbo
- Campbell Company
- Mondelez International
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


