

- Market Size (2026)
- USD 1.9 Bn
- Forecast (2036)
- USD 3.1 Bn
- CAGR (2026 to 2036)
- 5.2%
How big is Spray-On Bedliners Market in 2026?
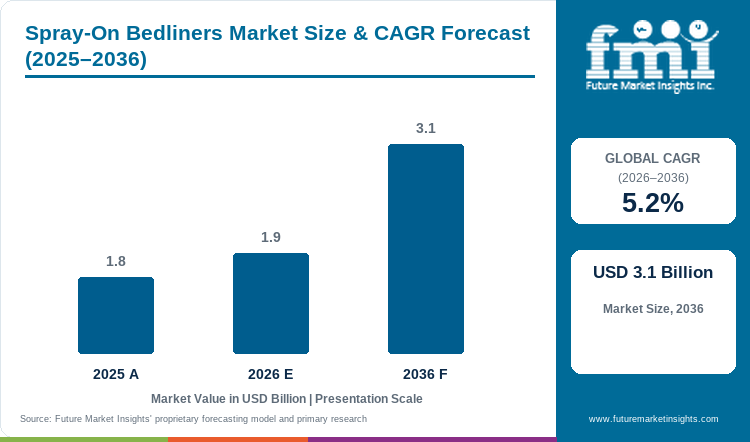
USD 1.9 billion in 2026 and USD 3.1 billion by 2036 at a 5.2% CAGR.
Sales of spray-on bedliners are estimated to rise at 5.2% CAGR through 2036, increasing valuation from USD 1.8 billion in 2025 to USD 1.9 billion in 2026, and reaching USD 3.1 billion by 2036. Pickup owners and fleet managers are moving protection spending closer to delivery when exposed cargo beds will enter regular work quickly. LINE-X reported in February 2025 that it had finalized five multi-location agreements representing 17 new stores and was targeting more than 20 USA states and Canadian provinces for expansion. Those agreements increase professional upfit capacity near buyers who prefer an installed surface before heavier cargo use begins.
Country growth diverges because pickup usage and accessory spending convert into professional installation at different rates. The USA is projected to grow at 4.8% CAGR while Japan is forecast at 3.6%. SEMA reported in June 2026 that nearly 13 million USA pickups were accessorized during 2025, confirming an active aftermarket buyer base for truck upgrades. Japan follows a more compact commercial-vehicle structure that requires smaller application packages and more selective specialist coverage. These operating differences affect how quickly protection spending reaches installers even when cargo-bed wear presents a similar functional need.
Key Takeaways
- Pickup owners and commercial fleets purchase spray-on bedliners when exposed cargo surfaces require durable abrasion and weather protection without a separate drop-in component.
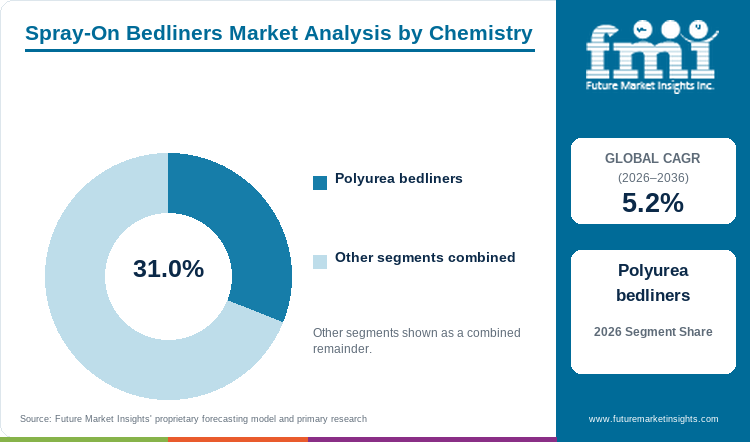
- Based on chemistry, polyurea bedliners are projected to account for 31.0% in 2026, driven by fast cure and resistance to repeated impact during working-vehicle use.
- By application method, professional spray shops are estimated to hold 52.0% in 2026, supported by preparation and spray-equipment control that shape the installed result.
- In 2026, pickup trucks are expected to lead vehicle type with 47.0% share, owing to open cargo beds facing direct loading wear and weather exposure.
- Application errors can delay vehicle return and raise rework costs because coating performance depends on preparation quality and controlled spray conditions.
- Some of the key players in this market include LINE-X, Rhino Linings, Bullet Liner, Scorpion Protective Coatings, Speedliner, ArmorThane, TOFF Spray On Bedliners, Ultimate Linings, PPG, and Sherwin-Williams.
Analyst Perspective
"Fleet buyers compare installed performance with vehicle downtime because the coating becomes useful only after preparation and cure are controlled at the shop. Brands with dependable applicator support can defend repeat business more effectively than chemistry suppliers that leave installation quality entirely to local practice."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the spray-on bedliners market segmented?
Chemistry, Application Method, Vehicle Type, End Use, Sales Channel and Region
The spray-on bedliners market is segmented by chemistry, application method, vehicle type, end use, sales channel and region. Chemistry includes polyurea, polyurethane, hybrid polyurea-polyurethane, aromatic and aliphatic UV-stable coatings, while application method covers professional shops, OEM application, mobile services and DIY kits. Vehicle type includes pickup trucks, utility bodies, flatbeds, commercial vans and off-road vehicles, while end use separates personal, fleet, construction, agriculture and municipal vehicles. Sales channels cover franchise applicators, independent spray shops, OEM programs and retail - e-commerce routes.
What makes polyurea bedliners central to the chemistry category?
Polyurea coatings fit professional bedliner work because rapid cure can return a truck to service without sacrificing abrasion resistance. PPG describes VERSAFLEX 250 UV as a rapid-curing pure polyurea coating intended for pickup spray-in bedliners and other protective applications. Professional applicators use that cure profile to shorten bay occupancy after surface preparation has been completed correctly. The chemistry also handles repeated impact and weather exposure that can damage painted cargo beds during normal work. That combination is useful for fleet accounts scheduling several vehicles around operating shifts because the shop can protect the bed without extending release times unnecessarily.
- By chemistry, polyurea bedliners are forecast to represent 31.0% in 2026, attributable to fast cure and resistance to repeated loading damage.
- Polyurethane coatings retain demand where applicators prefer longer working time or different finish behavior for less time-sensitive vehicle jobs.
Why do professional spray shops lead the application method category?
Professional application converts liquid coating into the finished bedliner at the vehicle, so surface preparation becomes part of the product outcome. Rhino Linings directs licensed applicators to clean and abrade the bed before masking adjacent panels and controlling the spray process. Trained shops can keep film build and equipment settings inside the supplier's process window during repeated jobs. Preparation mistakes can reduce adhesion or appearance after the customer has already paid for installation. Surface control also defines automotive refinish coatings where adhesion depends on preparation before material application. Professional shops therefore sell a controlled installation process alongside the coating chemistry and finished surface.
- Professional spray shops are likely to capture 52.0% share of application method demand in 2026, driven by controlled preparation that supports repeatable installed quality.
- Dealers and fleets use professional shops when predictable turnaround matters more than the lower entry cost available from occasional DIY application.
Why are pickup trucks central to the vehicle type category?
Pickup beds take direct contact from tools and building materials plus recreational cargo that can abrade painted metal during normal use. Stellantis made a spray-in bedliner standard on the refreshed Jeep Gladiator Rubicon in Australia during July 2025 after it had been optional. Factory inclusion moves protection into the vehicle specification before the owner schedules a separate aftermarket appointment. The open bed also exposes the coating to sunlight and water during ordinary use between cargo cycles. Bed protection therefore joins automotive paints and coatings as another specified surface system on selected pickups where working use makes durability visible to buyers.
- Pickup trucks are set to lead the vehicle type category with 47.0% share in 2026, supported by open beds facing repeated loading wear and weather exposure.
- Factory inclusion can move bedliner spending closer to vehicle delivery and reduce the separate scheduling step that aftermarket installation otherwise requires.
What supports personal vehicles within the end use category?
Personal truck owners often decide on a bedliner during customization because appearance and cargo protection are evaluated together after vehicle purchase. LINE-X said in March 2025 that its locations serve pickup owners with signature spray-on bedliners alongside other vehicle upgrades. Individual buyers can compare finish quality and installed price during the same visit that covers other truck modifications. The same appointment can place bed protection beside car accessories without changing the bedliner revenue boundary. Professional installers therefore gain a conversion advantage when owners can approve protective coating during early vehicle personalization instead of arranging a separate specialist visit later.
- Personal vehicles are projected to hold 32.0% share of end use demand in 2026, owing to owners combining bed protection with planned truck customization.
- Individual buyers remain sensitive to installed price and finish quality because the coating purchase is discretionary for lightly used trucks.
Why do franchise applicators lead the sales channel category?
Franchise and dealership applicators combine a recognized coating offer with trained local installation capacity and structured operating support. TOFF documents active bedliner programs in more than 500 dealerships and trains dealership teams to run the application process in-house. That structure keeps preparation and spraying near vehicle inventory while reducing the need to outsource every professional installation. Dealership staff can present bed protection during accessory discussions before the customer leaves with the truck. Dealers can therefore treat bedliners as automobile accessories that move through the same commercial location as the vehicle while still relying on defined application procedures and trained technicians.
- The sales channel category is forecast to be led by franchise applicators at 37.0% share in 2026, driven by trained local capacity and standardized application practices.
- Independent shops remain viable when local reputation is strong, but multi-location accounts place more value on consistent procedures and centralized coordination.
What are the drivers, restraints and opportunities in the Spray-On Bedliners Market?
Vehicle-delivery protection expands demand while installation control limits conversion, leaving fleet programs as the clearest route to repeatable volume.
- Driver: Factory and dealer fitment moves bed protection closer to the vehicle purchase and reduces a separate aftermarket appointment.
- Restraint: Surface preparation and spray-equipment control add labor, training and rework exposure before a professional installation can be released.
- Opportunity: Multi-location fleet programs can convert isolated bedliner jobs into scheduled volume where service standards remain consistent between shops.
Factory and Dealer Fitment Pulls Protection Forward
Bedliner demand is moving closer to vehicle purchase when automakers or dealers include cargo protection before the truck enters regular service. Ford stated in January 2025 that Brazilian F-150 specifications include a spray-in bedliner inside the cargo-box equipment package. That factory placement removes a separate search for an installer and gives buyers a finished protective surface at delivery. Professional installers still compete for vehicles without factory treatment and for owners replacing damaged protection after harder use. Corrosion protection coatings compete for some maintenance budgets but spray-on bedliners address the working cargo surface directly. This route works where pickup owners already expect accessories to be fitted during delivery preparation.
Process Control Raises Installation Cost
Professional spraying begins with substrate cleaning and abrasion because adhesion depends on preparation before the coating reaches service. Rhino Linings published bedliner guidance in July 2025 that specifies controlled chemical storage and disciplined equipment practices for professional application. Those controls add training time and equipment discipline to each installation even before cure speed becomes an advantage. Shops that miss temperature or spray-condition requirements risk finish defects and costly rework that extends vehicle downtime. DIY alternatives reduce equipment cost but place more preparation responsibility on the owner and cannot reproduce every professional process control. Dealers therefore compare installed price with warranty confidence and expected cargo-bed severity before recommending professional application.
Fleet Programs Reward Repeatable Local Execution
Fleet programs become more valuable when one coordinator can route similar upfit work to several trained locations. LINE-X joined the Merchants Fleet Preferred Upfit Network in July 2025 after a five-year commercial relationship. The agreement gives commercial fleets one route for consistent vehicle upfitting within the LINE-X franchise network. Bedliner volume can repeat when work orders specify preparation standards and shops can meet the same delivery schedule. Central coordination also reduces the vendor-management burden for fleets operating trucks in several states or provinces. Suppliers that combine local application capacity with documented service standards can pursue recurring fleet accounts without lowering installation control.
Which country CAGRs are profiled in the Spray-On Bedliners Market?
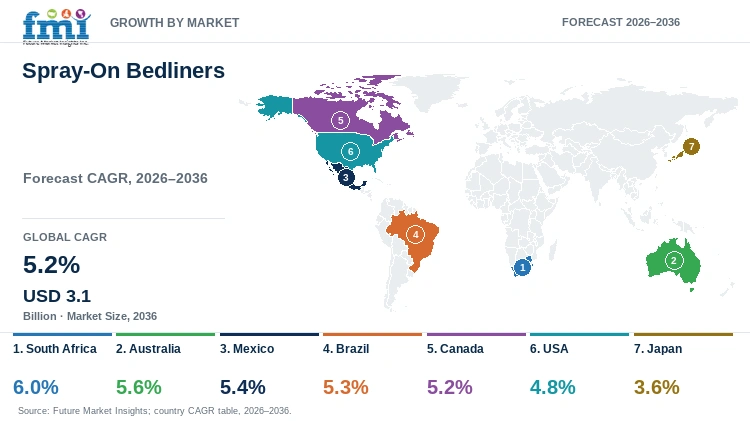
| Country | CAGR |
|---|---|
| South Africa | 6.0% |
| Australia | 5.6% |
| Mexico | 5.4% |
| Brazil | 5.3% |
| Canada | 5.2% |
| USA | 4.8% |
| Japan | 3.6% |
How do country-level CAGRs compare in the Spray-On Bedliners Market?
The country rates span 2.4 percentage points from South Africa at 6.0% to Japan at 3.6%. South Africa and Australia form the upper group while Mexico, Brazil and Canada occupy a narrow middle range. The USA follows at 4.8% while Japan's 3.6% rate completes the lower end of the displayed range. These figures describe forecast pace rather than current market size or installed applicator capacity.
- In South Africa, purchasing decisions often center on dealer-installed bedliner packages that align with the budgets of utility-focused pickup owners.
- Australia’s dispersed ute market rewards installation and service networks that can efficiently support customers in regional locations.
- Mexico offers OEM-linked opportunities, allowing bed-protection solutions to be integrated before vehicles reach commercial end users.
- In Brazil, installers must balance premium bedliner performance with vehicle values that vary widely across pickup segments.
- Seasonal conditions in Canada make application environments, curing control, and installation quality key considerations for suppliers.
- The USA’s mature aftermarket combines intense competition with a large customization culture, placing a premium on installation quality and durability.
- Japan’s compact commercial-truck market favors smaller application formats and specialized dealer support tailored to local vehicle designs.
Comparable CAGRs can still produce different entry conditions because vehicle formats, service density and buyer economics vary by country. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- South African bakkie use keeps cargo-bed protection tied to work vehicles that move tools and materials during regular commercial service. By 2036, South Africa is projected to grow at 6.0% CAGR, supported by light-commercial turnover that renews the addressable truck base. Naamsa recorded 75,219 light commercial bakkies and minibuses during the first half of 2026. The total was 10.1% above the comparable 2025 period and confirms sustained national activity in a vehicle class directly relevant to these installations. Installed price still competes with towing equipment and other practical upgrades for value-conscious pickup owners. Dealers that bundle professional spraying with new-vehicle accessories can keep preparation quality inside the purchase discussion and reduce a separate workshop visit.
- Australian ute ownership gives professional bedliner installers a buyer base that uses pickups for trade work and personal transport over long distances. Australia's spray-on bedliners outlook is anticipated to advance at 5.6% CAGR over the assessment period, driven by ute demand that keeps cargo protection visible during vehicle configuration. FCAI recorded 122,509 new vehicles in June 2025 and reported that utes occupied four positions in the monthly sales ranking. Regional distance can make trained spray capacity uneven outside major population centers and raise travel time for some buyers. Dealers and mobile applicators that maintain preparation standards can shorten the extra travel burden for owners who want professional protection before sustained cargo use begins.
- Mexican pickup production gives spray-on bedliner suppliers an OEM-facing route when coatings qualify for repeat vehicle programs. Spray-on bedliner demand in Mexico is forecast to rise at 5.4% CAGR over the forecast period, reinforced by light-truck manufacturing that renews factory and dealer fitment opportunities. INEGI reported that light trucks represented 79.6% of Mexican light-vehicle production during January-June 2026. Production scale does not guarantee bedliner take rates because each automaker decides which trims receive protection at the factory. Dealer coverage also determines whether coatings are offered during vehicle handover instead of after the customer has taken delivery. Coating producers that meet OEM process requirements can pursue repeat specifications while local applicators address trucks that leave assembly without factory bed protection.
- Brazilian light-commercial demand gives applicators a truck base spanning work fleets and personal pickups with different willingness to pay for professional spraying. Adoption of spray-on bedliners in Brazil is estimated to expand at 5.3% CAGR through 2036, supported by active light-commercial registrations and production. ANFAVEA recorded 52.3 thousand light-commercial registrations in March 2026 and 126.7 thousand during the first quarter. Those volumes document national activity in a vehicle category that includes pickups and vans relevant to professional bedliner services. Installed price still limits conversion when older pickups compete with lower-cost protection alternatives or delayed maintenance. Professional shops can improve conversion by matching coating thickness and finish to actual cargo use instead of selling one premium package to every pickup owner.
- Canadian pickup users operate within a large light-duty fleet that gives professional elastomeric coatings installers a broad service base in both personal and commercial use. The Canadian spray-on bedliners sector is projected to record 5.2% CAGR during the assessment period, influenced by a large light-duty vehicle base that supports replacement and customization spending. Statistics Canada counted 26.8 million road motor vehicles in 2024 and classified 91.6% as light-duty vehicles. Cold and wet seasons can delay preparation unless shops control surface temperature and moisture before spraying. Indoor application therefore protects cure consistency during the colder operating season and reduces seasonal scheduling risk for installers. Multi-location operators can serve fleets more consistently when controlled bays are available for professional installation.
- USA pickup owners support a mature customization channel where professional bedliners compete for spending with other car care products and functional truck upgrades. In the USA, spray-on bedliner demand is predicted to advance at 4.8% CAGR through 2036, supported by an established pickup base that sustains replacement and personalization work. SEMA reported in August 2026 that about 63 million pickups operate on USA roads and more than 20% were personalized during the prior year. Mature competition makes installed price and shop reputation important because owners can compare professional systems with DIY alternatives. Applicators that document preparation quality and predictable turnaround can defend repeat referrals without relying on chemistry claims alone.
- Japanese small and kei trucks give bedliner suppliers a commercial base that differs materially from North American full-size pickup use. Japan is estimated to post 3.6% CAGR over the forecast period, shaped by compact vehicle formats that keep professional spraying selective rather than universal. JAMA reported 12.01 million small and kei trucks and vans in use during its 2024 survey and noted that holdings declined from 2023. Smaller cargo areas reduce coating volume and can weaken the economics of a dedicated specialist visit. Suppliers that work with truck dealers or regional commercial-vehicle shops can fit application size and pricing to compact fleets without assuming full-size pickup economics.
Who are the notable companies in the Spray-On Bedliners Market?
LINE-X, Rhino Linings, Bullet Liner, Scorpion Protective Coatings, Speedliner, ArmorThane, TOFF Spray On Bedliners, Ultimate Linings, PPG, and Sherwin-Williams serve the spray-on bedliners market.
Competition is divided between branded installer networks and independent dealer systems plus broader coatings manufacturers serving different purchase routes. Network operators retain repeat accounts by pairing trained local application with documented processes and warranty support. Chemistry producers compete on cure behavior and substrate performance that determine whether installers can release vehicles on schedule. Entry becomes harder when a company must support equipment training and consistent application at many sites instead of only shipping coating material.
- Installed-network brands include LINE-X and Rhino Linings plus Speedliner and TOFF Spray On Bedliners because each supports professional application through organized locations or dealership programs.
- Dealer-system specialists include Bullet Liner and Scorpion Protective Coatings plus ArmorThane because training and local applicator access define their commercial routes.
- OEM and broader coating routes include Ultimate Linings and PPG plus Sherwin-Williams through factory systems or directly relevant professional and consumer bedliner chemistry.
Competitive Benchmarking: Spray-On Bedliners Market
| Company | Applicator / Dealer Network Depth | Fleet / OEM Integration | Bedliner Chemistry Range | Geographic Reach |
|---|---|---|---|---|
| LINE-X | High | High | Medium | United States, Canada and selected international markets |
| Rhino Linings | High | Medium | High | North America and nearly 80 countries |
| Bullet Liner | Medium | Medium | Medium | United States and international dealer markets |
| Scorpion Protective Coatings | High | Medium | High | United States and 20+ countries |
| Speedliner | High | Low | High | United States and international dealer markets |
| ArmorThane | High | Medium | Medium | United States and international applicator markets |
| TOFF Spray On Bedliners | High | Medium | Low | United States dealership network |
| Ultimate Linings | Medium | High | High | North America OEM and professional channels |
| PPG | Low | Medium | Medium | Global coatings footprint with USA and Canada bedliner products |
| Sherwin-Williams | Low | Low | Low | North America retail plus broader global coatings reach |
Scoring basis: High network depth requires documented national or multi-country access to trained bedliner installation locations and structured operating support. Medium network depth requires a narrower organized program while Low indicates no specialized network evidence in the reviewed public sources. High fleet or OEM integration requires a documented recurring program that supports repeated factory or commercial vehicle upfits. Medium integration reflects a proven commercial route while Low indicates no public evidence of a recurring fleet or OEM program. High chemistry range requires at least three documented bedliner-relevant system routes with distinct directly applicable formulation choices. Medium chemistry breadth requires two documented routes while Low identifies one directly documented bedliner chemistry route.
Key Developments in the Spray-On Bedliners Market
- In August 2025 Rhino Linings published Rhino Shine restoration guidance for sprayed polyurethane and polyurea bedliners. The update extended technical support into appearance maintenance after the initial professional installation and gave applicators a defined restoration route.
- In July 2025 LINE-X joined the Merchants Fleet Preferred Upfit Network after a five-year commercial relationship. Its franchise locations gained a coordinated route for repeat vehicle preparation and bedliner-related fleet work.
- In March 2025 Ultimate Linings detailed its new Tennessee manufacturing facility after relocating operations from Houston. The company said expanded raw-material buying capacity and larger finished-goods inventory now support customers that include bedliner shops and OEM accounts.
Key Players in the Spray-On Bedliners Market
Installed Applicator Networks
- LINE-X
- Rhino Linings
- Speedliner
- TOFF Spray On Bedliners
Dealer and Independent Applicator Systems
- Bullet Liner
- Scorpion Protective Coatings
- ArmorThane
OEM and Broader Coating Routes
- Ultimate Linings
- PPG
- Sherwin-Williams
Spray-On Bedliners Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By chemistry, application method, vehicle type, end use, sales channel and region. |
| Quantitative Units | USD billion. |
| Market Definition | Revenue from spray-applied bedliner coatings, bedliner kits and professional application services sold as bedliner solutions. Downstream vehicle revenue, drop-in liners, mats, tonneau covers, undercoatings and general-purpose non-bedliner coatings are excluded. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | South Africa, Australia, Mexico, Brazil, Canada, USA, Japan, and 20+ countries included in the full report. |
| Key Companies Profiled | LINE-X, Rhino Linings, Bullet Liner, Scorpion Protective Coatings, Speedliner, ArmorThane, TOFF Spray On Bedliners, Ultimate Linings, PPG, and Sherwin-Williams. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Spray-On Bedliners Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Spray-On Bedliners Market by Segments
Spray-On Bedliners Market segmented by Chemistry:
- Polyurea bedliners
- Polyurethane bedliners
- Hybrid polyurea-polyurethane
- Aromatic coatings
- Aliphatic UV-stable coatings
Spray-On Bedliners Market segmented by Application Method:
- Professional spray shop
- OEM-applied
- Mobile spray service
- DIY kit
Spray-On Bedliners Market segmented by Vehicle Type:
- Pickup trucks
- Utility bodies
- Flatbeds
- Commercial vans
- Off-road vehicles
Spray-On Bedliners Market segmented by End Use:
- Personal vehicles
- Fleet vehicles
- Construction trucks
- Agriculture trucks
- Municipal vehicles
Spray-On Bedliners Market segmented by Sales Channel:
- Franchise applicators
- Independent spray shops
- OEM programs
- Retail - e-commerce
Spray-On Bedliners Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- LINE-X. (2025, February 18). LINE-X Advances in 2025 with Strategic Focus on Long-Term Success.
- Specialty Equipment Market Association. (2026, June 30). SEMA Market Research: Off-Road Culture Continues to Drive Consumer Spending.
- PPG. (n.d.). VERSAFLEX® 250 UV. Retrieved September 16, 2026.
- Rhino Linings Corporation. (n.d.). Become an Automotive Partner. Retrieved September 16, 2026.
- Stellantis. (2025, July 22). Unleash Adventure: The Only Open-Air Ute in the Industry Gets Major Refresh.
- LINE-X. (2025, March 12). LINE-X Franchise: Q&A with Matt Labuda, VP of Marketing.
- TOFF Spray On Bedliners. (n.d.). TOFF Spray On Bedliners. Retrieved September 16, 2026.
- Ford Motor Company. (2025, January). Ford F-150 tem caçamba recheada de tecnologia e inovação.
- Rhino Linings Corporation. (2025, July 6). 12 Best Tips for Spraying Top Notch Rhino Liners.
- LINE-X. (2025, July 21). LINE-X and Merchants Fleet Sign Preferred Partnership Agreement.
- naamsa. (2026, July 1). Industry New Vehicle Sales - June 2026.
- Federal Chamber of Automotive Industries. (2025, July 3). Utes Dominate as Automotive Market Holds Strong.
- Instituto Nacional de Estadística y Geografía. (2026, July 7). Registro Administrativo de la Industria Automotriz de Vehículos Ligeros, June 2026.
- ANFAVEA. (2026, April). Carta da Anfavea - Abril 2026.
- Statistics Canada. (2025, October 17). Vehicle Registrations, 2024.
- Specialty Equipment Market Association. (2026, August). TORA Industry Insights: Pickups Power the Automotive Specialty Equipment Market.
- Japan Automobile Manufacturers Association. (2025, April 15). 2024年度小型・軽トラック市場動向調査について.
- Bullet Liner. (n.d.). Become a Dealer. Retrieved September 16, 2026.
- Scorpion Protective Coatings. (n.d.). Truck Bed Liners & Protective Coatings. Retrieved September 16, 2026.
- Simmons Industries, Inc. (n.d.). International Dealers. Retrieved September 16, 2026.
- ArmorThane. (2026, June). Bedliner Near Me: Find Certified Spray-On Bedliner Installers Near You.
- Ultimate Linings. (n.d.). Spray-On Bedliner Systems. Retrieved September 16, 2026.
- PPG. (n.d.). VERSAFLEX® 252. Retrieved September 16, 2026.
- Dupli-Color. (n.d.). Bed Armor® Truck Bed Coating. Retrieved September 16, 2026.
- The Sherwin-Williams Company. (n.d.). Our Brands. Retrieved September 16, 2026.
- Rhino Linings Corporation. (2025, August 3). Renewing Any Old Bedliner With Rhino Shine.
- Ultimate Linings. (2025, March 28). We Built This for You: The Future of Polyurea Starts Here.
- LINE-X. (2025, September 2). LINE-X Franchise Attracts Multi-Unit Owners.
- Ultimate Linings. (2025, May 1). Exciting Update: The Graco Fusion FX Gun Is Now Available for Polyurea Applications.
- Rhino Linings Corporation. (2026, February 12). Graco Fusion Gun Maintenance Tips to Prevent Bed Liner Issues.
- Ultimate Linings. (n.d.). Polyurea Science. Retrieved September 16, 2026.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the spray-on bedliners market in 2026 and 2036?
- Which operating conditions convert truck ownership into paid bedliner installations?
- Why do polyurea bedliners account for 31.0% of chemistry demand?
- Why do professional spray shops account for 52.0% of application-method demand?
- How do pickup trucks shape 47.0% of vehicle-type demand in 2026?
- How do country growth rates differ among the seven country markets?
- Which companies compete through installer networks, dealership programs and coating platforms?
- Which application controls limit conversion despite durable spray-on coating chemistry?
Frequently Asked Questions
How big is the spray-on bedliners market in 2026?
The spray-on bedliners market is valued at USD 1.9 billion in 2026 and is forecast to reach USD 3.1 billion by 2036. Professional application capacity converts protection needs into paid installations when shops can control preparation and turnaround.
What is the CAGR of the spray-on bedliners market from 2026 to 2036?
The spray-on bedliners market is projected to grow at a 5.2% CAGR between 2026 and 2036. Growth depends on pickup protection spending entering dealer, fleet and aftermarket workflows before cargo-bed wear requires more extensive repair.
Which chemistry segment leads the spray-on bedliners market?
The polyurea bedliners segment is estimated to hold 31.0% of chemistry demand in the spray-on bedliners market during 2026. Fast cure and abrasion resistance fit professional shops that must return working vehicles without extended downtime.
Which application method leads the spray-on bedliners market?
The professional spray shop segment is projected to hold 52.0% of application-method demand in the spray-on bedliners market during 2026. Trained installers control masking, preparation and equipment settings that directly affect adhesion and finish consistency.
How do the three upper country CAGRs compare in the spray-on bedliners market?
South Africa is projected at 6.0% CAGR followed by Australia at 5.6% and Mexico at 5.4% through 2036. Factory or dealer fitment gives these markets direct purchase points where bed protection can accompany vehicle delivery.
Which companies are active in the spray-on bedliners market?
Active companies include LINE-X, Rhino Linings, Bullet Liner, Scorpion Protective Coatings, Speedliner, ArmorThane, TOFF Spray On Bedliners, Ultimate Linings, PPG, and Sherwin-Williams. Their routes span installer networks and dealership programs as well as OEM supply and consumer truck-bed coatings for different buyer requirements.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Chemistry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Chemistry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Chemistry, 2026 to 2036
- Polyurea bedliners
- Polyurethane bedliners
- Hybrid polyurea-polyurethane
- Aromatic coatings
- Aliphatic UV-stable coatings
- Y-o-Y Growth Trend Analysis By Chemistry, 2021 to 2025
- Absolute $ Opportunity Analysis By Chemistry, 2026 to 2036
- Global Market Analysis and Forecast, By Application Method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application Method, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application Method, 2026 to 2036
- Professional spray shop
- OEM-applied
- Mobile spray service
- DIY kit
- Y-o-Y Growth Trend Analysis By Application Method, 2021 to 2025
- Absolute $ Opportunity Analysis By Application Method, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Pickup trucks
- Utility bodies
- Flatbeds
- Commercial vans
- Off-road vehicles
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Personal vehicles
- Fleet vehicles
- Construction trucks
- Agriculture trucks
- Municipal vehicles
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Franchise applicators
- Independent spray shops
- OEM programs
- Retail - e-commerce
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Chemistry
- By Application Method
- By Vehicle Type
- By End Use
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- LINE-X
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Rhino Linings
- Bullet Liner
- Scorpion Protective Coatings
- Speedliner
- ArmorThane
- TOFF Spray On Bedliners
- Ultimate Linings
- PPG
- Sherwin-Williams
- LINE-X
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


