

- Market Size (2026)
- USD 252.7 Bn
- Forecast (2036)
- USD 509.0 Bn
- CAGR (2026 to 2036)
- 7.3%
How big is Super Generics Market in 2026?
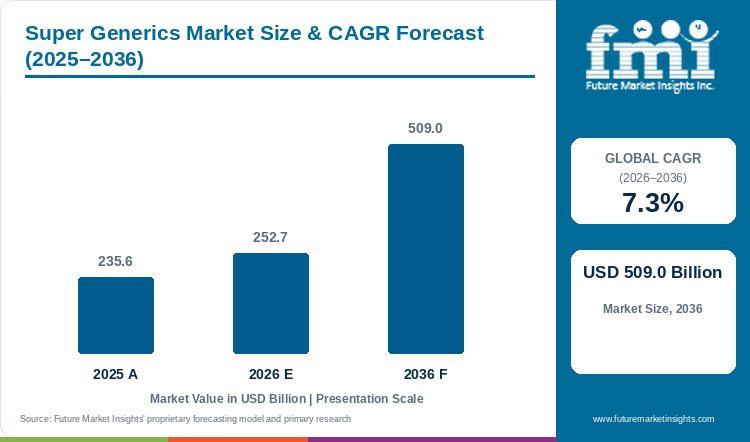
Demand is projected to expand at 7.3% CAGR from 2026 to 2036. Market value rises from USD 235.6 billion in 2025 to USD 252.69 billion in 2026 and USD 509.03 billion by 2036.
The super generics market is estimated at USD 252.69 billion in 2026 and is projected to reach USD 509.03 billion by 2036, with a CAGR of 7.3% over the forecast period. Demand concerns differentiated versions of established medicines, including changes in formulation, strength or delivery that need to address a practical treatment requirement. The commercial case depends on the evidence supporting the particular change, because a modified product does not automatically provide a clinical advantage or qualify for a single regulatory route. EMA’s hybrid-medicine framework illustrates how some applications differ from a conventional generic application and may require additional supporting studies. [2] For buyers, the relevant comparison includes the suitability of the dosage form, the expected use of the medicine and the cost of introducing it into routine care. NICE’s medicines-optimization guidance similarly emphasizes decisions that reflect the individual’s needs and the safe, effective use of medicines. [3] Growth is therefore expected to depend on products whose differentiation can be explained in treatment and purchasing terms, with reliable manufacturing and an appropriate regulatory package supporting access across hospital and retail channels.
Key Market Trends & Insights
- Formulation and delivery development is extending competition beyond conventional generic presentations, although the evidence required depends on the particular product change. [2]
- Oral products remain commercially relevant because dosing frequency, swallowing requirements and release characteristics can influence how an established medicine fits into daily treatment. [3]
- Development planning increasingly needs a clear distinction between a generic application and a hybrid or other differentiated application before the supporting evidence is assembled. [1][2]
Regional Highlights
- India’s pharmaceutical manufacturing base supports development of differentiated formulations, with companies seeking opportunities beyond conventional generic supply in domestic and export markets.
- Germany and the United Kingdom present established treatment markets where product differentiation needs to be considered alongside value, appropriate use and purchasing requirements. [3]
- Japan’s demand reflects the needs of an aging patient population and continuing interest in affordable treatment options, while product development remains subject to appropriate quality requirements. [4]
Market Size & Forecast
Table 1: Market Size and Forecast for Super Generics Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 market value | USD 235.6 billion |
| 2026 market value | USD 252.69 billion |
| 2036 market value | USD 509.03 billion |
| CAGR 2026 to 2036 | 7.3% |
| Revenue increase 2026 to 2036 | USD 256.34 billion |
| Market expansion 2026 to 2036 | 2.01 times |
The outlook through 2036 depends on whether differentiation addresses a need that clinicians, patients and purchasers can recognize in routine use. Hard gelatin capsules can support certain oral presentations, while injectable and inhaled products involve different manufacturing and delivery requirements. A stronger commercial position follows from matching the proposed change with an appropriate evidence package and a workable supply route, particularly where a buyer must justify a higher price than an established conventional generic alternative. [2][3]
What determines whether differentiated formulations create value?
The term super generic describes a commercial category rather than a universal regulatory classification, so the nature of the product change remains central to development. EMA distinguishes hybrid medicines from conventional generics, while FDA guidance addresses the circumstances relevant to different application routes. This makes early definition of the formulation, intended use and supporting evidence important to the investment case. [1][2]
Table 2: Industry evidence relevant to the super generics market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Product differentiation | Changes may involve dosage form, strength or delivery characteristics. | The proposed benefit needs to be specific to the product. | [2] |
| Application route | Hybrid applications can require additional studies. | Development effort cannot be inferred from the generic label alone. | [2] |
| Appropriate medicine use | NICE emphasizes patient needs and safe, effective use. | Convenience claims need a relevant treatment context. | [3] |
Analyst Perspective
"Super generics refer to versions of existing generic drugs that have been modified for better formulations, delivery mechanisms or therapeutic outcomes."
- Anurag Sharma, Principal Analyst at Future Market Insights
How is the Super Generics Market segmented?
The market is segmented by Drug Type, Therapeutic Area, Route of Administration, Distribution Channel, and Region.
Drug type identifies the formulation being developed, while route of administration describes how the resulting medicine is given, allowing oral solids, injectables, topical and inhaled presentations to be examined in their treatment context. Therapeutic-area differences matter because administration difficulties and the evidence needed to justify a change vary between oncology, respiratory disease and other conditions. Distribution channels locate the product within hospital or community dispensing, where access arrangements can influence its introduction. Together, these dimensions help distinguish a useful differentiated presentation from a change that adds development complexity without a clear role in treatment, with the product-specific evidence determining the strength of the commercial case. [2][3]
Why does the oral solid dosage forms segment lead demand by drug type?
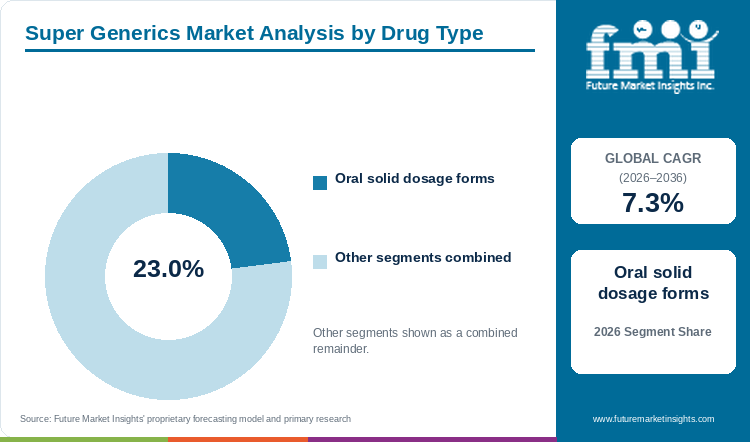
The Oral solid dosage forms segment is projected to account for 23.0% of drug type demand in 2026.
Table 3: Drug Type Share for Super Generics Market (percentage share), 2026
| Drug Type | Estimated share (2026) |
|---|---|
| Oral solid dosage forms | 23.0% |
| Other drug type segments | 77.0% |
| Total | 100.0% |
Table 4: Segment Position and Market Growth for Super Generics Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.3% |
| Profiled drug type segment | Oral solid dosage forms |
Oral solid dosage forms retain a substantial position because many established treatments are taken repeatedly outside a clinical facility, making the presentation relevant to everyday use. Differentiation may concern release characteristics or another formulation feature, but the purchasing case still needs to explain why the change is appropriate for the intended patient and medicine. NICE’s medicines-optimization approach places this assessment within safe and effective use rather than assuming that a modified presentation is universally preferable. [3] Manufacturing consistency and the evidence needed for the selected regulatory route also remain important. The category consequently supports development opportunities where formulation design can be connected to a clear treatment requirement and a practical dispensing arrangement. [2][4]
- Oral solid dosage forms are projected to represent 23.0% of drug-type demand in 2026, supported by repeated treatment requirements and scope for suitable release-profile or administration changes. [3]
- Oral formulation changes need an appropriate quality and regulatory package, with any proposed treatment advantage evaluated for the specific medicine and patient setting. [2][4]
Why does the oncology segment lead demand by therapeutic area?
The Oncology segment is projected to account for 40.0% of therapeutic area demand in 2026.
Table 5: Therapeutic Area Share for Super Generics Market (percentage share), 2026
| Therapeutic Area | Estimated share (2026) |
|---|---|
| Oncology | 40.0% |
| Other therapeutic area segments | 60.0% |
| Total | 100.0% |
Oncology leads the stated therapeutic-area mix because established cancer medicines can present demanding formulation, administration and access requirements, creating interest in differentiated versions where the change has a clear purpose. The development question is specific to the product: a new presentation may alter the supporting evidence needed and the way a medicine fits into an existing treatment pathway. EMA’s hybrid framework illustrates why a change cannot be assessed solely through the conventional generic model. [2] Hospitals and other purchasers also need dependable availability and a manageable introduction into care. The segment’s position therefore reflects the combination of treatment demand and product-development opportunities, with commercial success dependent on the relevance and evidence of each proposed formulation.
- Oncology is projected to hold 40.0% of therapeutic-area demand in 2026, where demanding formulation and administration requirements create opportunities for appropriately evidenced differentiated presentations. [2]
- Oncology differentiation must be assessed at product level, since a change in formulation or delivery does not establish improved clinical outcomes by itself. [2]
What are the drivers, restraints, and opportunities in the Super Generics Market?
A differentiated presentation needs a purchasing rationale that can be traced to the intended patient and treatment problem, particularly where an established generic offers a familiar lower-cost alternative. Developers can make that rationale clearer by defining the formulation objective early, assembling the evidence appropriate to the change and ensuring that manufacturing and dispensing arrangements support its practical introduction into care. [2][3][4]
Driver
Treatment requirements can sustain demand for differentiated established medicines when a change in formulation or delivery addresses a practical difficulty with the existing presentation. Pharmaceutical excipients contribute to formulation design, with the finished product requiring evidence appropriate to the intended change. [2][4] Developers also need to explain how that change fits safe and effective medicine use, giving prescribers and purchasers a clear reason to consider the proposed presentation within the relevant treatment setting. [3]
Restraint
Differentiation can add development and manufacturing requirements while leaving uncertainty about the premium a purchaser will accept over a conventional generic. The applicable evidence package depends on the nature of the change, with EMA hybrid applications illustrating circumstances where additional studies are needed. [2] Developers also need to avoid treating convenience as a substitute for demonstrated suitability, because the safe and effective use of a medicine depends on the patient, treatment and prescribing context. [3]
Opportunity
Oral controlled-release delivery offers one development route where the release profile or administration schedule presents a defined formulation objective, although the evidence remains specific to the medicine. [2] The commercial opportunity begins with understanding the difficulty faced by intended users, then connecting an appropriate product change with reliable manufacturing and a suitable dispensing channel. NICE’s medicines-optimization approach supports this attention to practical use, helping developers frame the proposition around the patient and treatment requirements that purchasers need to assess. [3][4]
Which country CAGRs are profiled in the Super Generics Market?
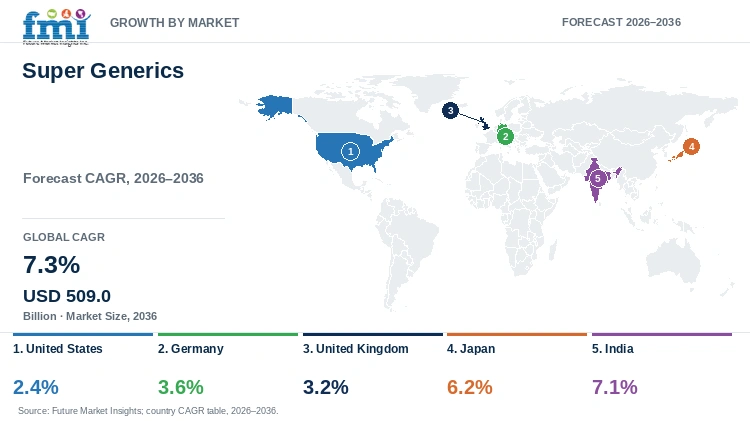
Table 6: Country CAGR Comparison for Super Generics Market (CAGR percentage), 2026 to 2036
| Country | CAGR | Forecast period |
|---|---|---|
| United States | 2.4% | 2026 to 2036 |
| Germany | 3.6% | 2026 to 2036 |
| United Kingdom | 3.2% | 2026 to 2036 |
| Japan | 6.2% | 2026 to 2036 |
| India | 7.1% | 2026 to 2036 |
Country-wise Analysis
United States Super Generics Market Outlook (2026 to 2036)
The United States market requires developers to distinguish the intended product change from a conventional generic application, because the nature of the evidence and the appropriate submission route depend on the proposal. FDA guidance on applications under section 505(b)(2) addresses this part of development planning, including situations where an applicant relies in part on existing findings or literature. [1] The market is projected to expand at a CAGR of 2.4% from 2026 to 2036. A commercially useful differentiated product still needs a clear role in treatment and a supply arrangement that purchasers can use. These requirements favor careful selection of development programs whose formulation or delivery characteristics can be explained without assuming an automatic clinical advantage.
Germany Super Generics Market Outlook (2026 to 2036)
Germany combines an established pharmaceutical market with interest in treatment options that can be evaluated on both quality and cost, making the rationale for a differentiated formulation particularly relevant. Under the European framework, hybrid applications may be needed when the proposed medicine differs from the reference in ways that require additional evidence, so the development route depends on the actual product. [2] Germany is projected at a CAGR of 3.6% from 2026 to 2036. Suppliers therefore need to connect formulation design with the requirements of prescribers and purchasers rather than rely on the super generic label. Consistent manufacturing and a clear explanation of the intended use support that comparison within established treatment pathways.
United Kingdom Super Generics Market Outlook (2026 to 2036)
Medicines optimization gives the United Kingdom market a useful framework for assessing differentiated established products, because NICE emphasizes decisions that reflect individual needs and safe, effective medicine use. [3] This makes the treatment rationale relevant when a new formulation is compared with a familiar generic alternative, particularly where a change affects the way a patient takes or manages therapy. The United Kingdom outlook is projected at a CAGR of 3.2% from 2026 to 2036. Buyers also need to consider how the proposed presentation fits prescribing, dispensing and follow-up arrangements. A clear product-level case is consequently more useful than broad claims that an improved delivery format will necessarily produce better outcomes across every patient group.
Japan Super Generics Market Outlook (2026 to 2036)
Japan’s aging patient population creates practical treatment considerations around the use of established medicines, including the suitability of the dosage form and the burden of repeated administration. These circumstances can support interest in differentiated formulations, but a product still needs evidence appropriate to its intended use and the applicable quality requirements. WHO’s guidance on multisource medicines illustrates the continuing importance of establishing acceptable product performance rather than assuming equivalence from a familiar active ingredient alone. [4] Japan is projected to record a CAGR of 6.2% from 2026 to 2036. Developers addressing the market therefore need to combine a relevant formulation objective with reliable supply and an understandable place within existing care.
India Super Generics Market Outlook (2026 to 2036)
India’s pharmaceutical manufacturing base gives local companies an established starting point for moving into differentiated formulations, with development extending beyond conventional generic supply. The commercial challenge is to select changes that address a practical treatment or administration requirement while remaining feasible to manufacture consistently. WHO guidance on multisource products underscores the need for an appropriate quality and interchangeability assessment, although the precise requirements depend on the product and market. [4] A 7.1% CAGR is projected for India from 2026 to 2036. Suppliers can draw on formulation and production capability, but successful access also requires a clear regulatory strategy and a convincing explanation of why the differentiated presentation belongs in the intended treatment pathway.
Who are the notable companies in the Super Generics Market?
Teva Pharmaceutical Industries; Dr. Reddy’s Laboratories; Sun Pharmaceutical Industries; Lupin Limited; Cipla Ltd.
Formulation platforms and therapeutic portfolios shape competition, with oral, inhaled and injectable presentations drawing on different development and production capabilities. Drug delivery technology becomes relevant when the proposed system can address the administration or release objective of a particular medicine. A purchaser can compare that intended role with the supporting regulatory evidence and manufacturing arrangements, while considering the dispensing route and price needed to introduce the product into routine care. [2][3][4]
Competitive Benchmarking: Super Generics Market
Table 7: Competitive positioning for the super generics market
| Company | Positioning | Commercial distinction |
|---|---|---|
| Teva Pharmaceutical Industries | Generic and differentiated medicines | Develops established-medicine portfolios and differentiated presentations. |
| Dr. Reddy’s Laboratories | Formulation and delivery development | Works on differentiated products across therapeutic categories including oncology and gastroenterology. |
| Sun Pharmaceutical Industries | Specialty and differentiated generics | Addresses dermatology, ophthalmology and chronic-care formulation requirements. |
| Lupin Limited | Complex generics and respiratory delivery | Participates in inhaled therapies and other differentiated formulations. |
| Cipla Ltd. | Respiratory and other established therapies | Develops products where delivery characteristics support treatment use. |
Key Developments in the Super Generics Market
- WHO issued its updated multisource pharmaceutical-product interchangeability guidance in April 2024, providing an official reference for the evidence used to establish appropriate product performance. [4]
- FDA’s August 2026 draft guidance addresses the choice between certain application routes, giving developers additional planning material while the document remains in draft form. [1]
- EMA’s hybrid-application resources distinguish these submissions from conventional generic applications and explain why the specific product difference determines the additional evidence required. [2]
Key Players in the Super Generics Market
Generic and differentiated medicines
- Teva Pharmaceutical Industries
Formulation and delivery development
- Dr. Reddy’s Laboratories
Specialty and differentiated generics
- Sun Pharmaceutical Industries
Complex generics and respiratory delivery
- Lupin Limited
Respiratory and other established therapies
- Cipla Ltd.
Super Generics Market - Report Scope
Table 8: Report Scope for Super Generics Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market | Super Generics Market |
| Historical reference year | 2025 |
| Base year | 2026 |
| Forecast period | 2026 to 2036 |
| Quantitative units | USD billion and percentage shares/CAGRs |
| 2026 market value | USD 252.69 billion |
| 2036 market value | USD 509.03 billion |
| Forecast CAGR | 7.3% from 2026 to 2036 |
| Segmentation | drug type, therapeutic area, route of administration, distribution channel |
| Country profiles | United States, Germany, United Kingdom, Japan, India |
Super Generics Market - Research Methodology
Table 9: Research Methodology for Super Generics Market, 2026 edition
| Method | Approach |
|---|---|
| Market definition | Products, services and commercial applications are separated according to their function and purchasing context. |
| Secondary research | FMI market coverage is assessed alongside official technical guidance, regulatory material and relevant first-party disclosures. |
| Segmentation | Demand is organized by the stated category axes, retaining the distinction between segment shares and growth rates. |
| Country assessment | Local care pathways, purchasing conditions and service availability inform the interpretation of each geographic outlook. |
| Competitive assessment | Participants are compared by relevant offering, customer setting and delivery capability rather than unsupported company rankings. |
| Consistency review | Market values, forecast periods, units, segment labels and country growth rates are checked for agreement throughout the analysis. |
Super Generics Market by Segments
Super Generics Market segmented by Drug Type:
- Oral solid dosage forms
- Injectables
- Topical dosage forms
- Inhalable dosage forms
- Others
Super Generics Market segmented by Therapeutic Area:
- Oncology
- Central Nervous System (CNS) Disorders
- Cardiovascular Diseases
- Chronic Pain
- Respiratory Disorders
- Others
Super Generics Market segmented by Route of Administration:
- Oral
- Injectable
- Topical
- Others
Super Generics Market segmented by Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Drug Stores
Super Generics Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] US Food and Drug Administration. Accessed 15 October 2026. Determining Whether to Submit an ANDA or a 505(b)(2) Application: Draft Guidance
- [2] European Medicines Agency. Accessed 15 October 2026. Generic and hybrid applications
- [3] National Institute for Health and Care Excellence. Accessed 15 October 2026. Medicines optimisation: recommendations
- [4] World Health Organization. Accessed 15 October 2026. Multisource pharmaceutical products: guidelines on registration requirements to establish interchangeability
This Report Answers
- How big is the super generics market in 2026?
- What is the market outlook through 2036?
- Which segments lead demand in 2026?
- Which countries are examined in the forecast?
- Which companies participate in the market?
Frequently Asked Questions
How big is the super generics market in 2026?
The market is estimated at USD 252.69 billion in 2026, compared with USD 235.6 billion in 2025.
What is the market outlook through 2036?
Market value is projected to reach USD 509.03 billion by 2036, with a CAGR of 7.3% from 2026 to 2036.
Which segments lead demand in 2026?
The Oral solid dosage forms segment is projected to hold 23% of drug type demand in 2026. Oncology is projected to hold 40% of therapeutic area demand in 2026.
Which countries are examined in the forecast?
The country analysis covers United States, Germany, United Kingdom, Japan, India, considering local demand conditions and the outlook from 2026 to 2036.
Which companies participate in the market?
Relevant participants include Teva Pharmaceutical Industries, Dr. Reddy’s Laboratories, Sun Pharmaceutical Industries, Lupin Limited, Cipla Ltd., whose portfolios serve different requirements within the market.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Drug Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Drug Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Drug Type, 2026 to 2036
- Oral solid dosage forms
- Injectables
- Topical dosage forms
- Inhalable dosage forms
- Others
- Y-o-Y Growth Trend Analysis By Drug Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Drug Type, 2026 to 2036
- Global Market Analysis and Forecast, By Therapeutic Area, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Therapeutic Area, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Therapeutic Area, 2026 to 2036
- Oncology
- Central Nervous System (CNS) Disorders
- Cardiovascular Diseases
- Chronic Pain
- Respiratory Disorders
- Others
- Y-o-Y Growth Trend Analysis By Therapeutic Area, 2021 to 2025
- Absolute $ Opportunity Analysis By Therapeutic Area, 2026 to 2036
- Global Market Analysis and Forecast, By Route of Administration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Route of Administration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Route of Administration, 2026 to 2036
- Oral
- Injectable
- Topical
- Others
- Y-o-Y Growth Trend Analysis By Route of Administration, 2021 to 2025
- Absolute $ Opportunity Analysis By Route of Administration, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Drug Stores
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Key Takeaways
- South Asia & Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Drug Type
- By Therapeutic Area
- By Route of Administration
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Teva Pharmaceutical Industries
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Dr. Reddy’s Laboratories
- Sun Pharmaceutical Industries
- Lupin Limited
- Cipla Ltd.
- Teva Pharmaceutical Industries
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


