
- Market Size (2026)
- USD 12.6 Bn
- Forecast (2036)
- USD 24.3 Bn
- CAGR (2026 to 2036)
- 6.8%
How big is Advance Wound Care Market in 2026?
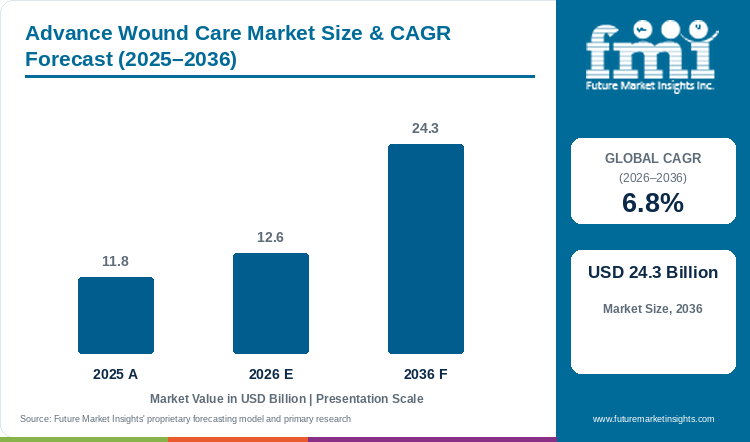
With a valuation of USD 11.8 billion in 2025 and moving to USD 12.6 billion in 2026, the advance wound care market is positioned to attain USD 24.3 billion by 2036, exhibiting a CAGR of 6.8%.
Hospital surgical departments, outpatient ulcer clinics, and home-health nursing agencies are shifting wound procurement from daily dry gauze changes toward multi-day exudate dressings and portable negative-pressure pumps that lower nursing visit frequency and prevent readmissions. The global advance wound care market size reached USD 11.8 billion in 2025 and is estimated to hit USD 12.6 billion in 2026. Total industry valuation is projected to reach USD 24.3 billion by 2036, expanding at a 6.8% CAGR between 2026 and 2036. Clinical adoption analysis by FMI indicates that Hydrocolloid Dressings is anticipated to capture 36.0% of product class demand in 2026, driven by self-adherent carboxymethylcellulose wafers that seal moderate-exudate ulcers for up to seven days without secondary tape trauma.
Procurement discipline is being reshaped by federal reimbursement rules, as the US Centers for Medicare and Medicaid Services announced in October 2025 that its Calendar Year 2026 Physician Fee Schedule reform for skin substitutes will reduce gross fee-for-service waste by USD 19.6 billion after stopping nearly USD 185 million in improper billing during 2025. That shift toward evidence-graded moist dressings and active negative-pressure therapy separates global multi-modality growth from mature regional advanced wound dressing formats expanding at a 4.3% CAGR, since integrated canisterless pumps and antimicrobial hydrofibers capture higher per-episode reimbursement. Major device manufacturers are introducing wear-time-extending platforms to capture outpatient conversions, highlighted when Smith+Nephew unveiled its ALLEVYN Complete Care dressing and RENASYS EDGE negative-pressure system at the May 2026 EWMA congress. Suppliers that pair randomized clinical closure evidence with simplified home-care dressing application are expected to secure multi-year hospital group purchasing contracts through 2036.
Key Market Trends & Insights
- By product class: Hydrocolloid Dressings holds an estimated 36.0% share in 2026 given that occlusive gel-forming wafers support autolytic debridement and multi-day wear across non-infected ulcers.
- By wound etiology: Chronic Diabetic Foot Ulcers represents 42.0% in 2026 since neuropathic lower-extremity wounds require prolonged exudate control and offloading therapy.
- By end-user care setting: Hospitals and Specialized Wound Clinics accounts for 58.0% in 2026 owing to inpatient surgical debridement and complex negative-pressure initiation.
- By exudate mechanism: Moist Wound Environment Dressings secures 54.0% in 2026 supported by clinical protocols favoring balanced hydration over traditional dry gauze.
- By procurement pathway: Hospital Group Purchasing Contracts commands 51.0% in 2026 through standardized health-system formulary tenders that bundle dressings with portable suction pumps.
Regional Highlights
- Top national expansion: The United Arab Emirates leads national growth projections at an 8.4% CAGR through 2036 under tertiary diabetic limb-salvage center investments.
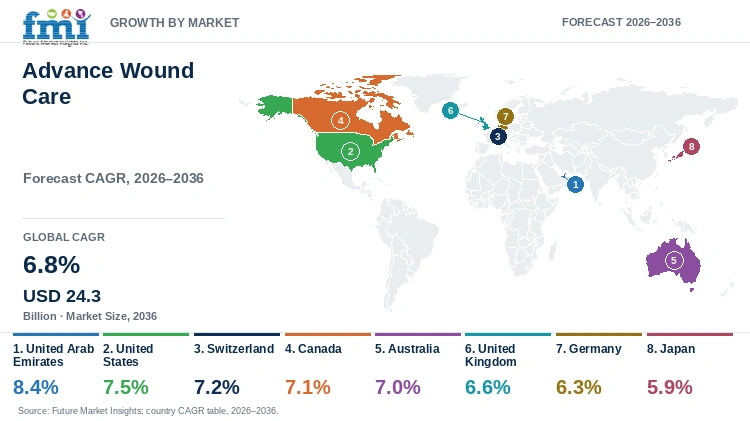
- Broader country progression: The United States tracks at a 7.5% CAGR ahead of Switzerland at 7.2% and Canada at 7.1%, while Australia records a 7.0% CAGR and Japan advances at a 5.9% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Advance Wound Care Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 11.8 billion |
| Estimated Market Size in 2026 | USD 12.6 billion |
| Projected Market Size by 2036 | USD 24.3 billion |
| CAGR, 2026 to 2036 | 6.8% |
| Added Revenue, 2026 to 2036 | USD 11.7 billion |
Vascular and podiatric wound teams confront high amputation and readmission risks when deep diabetic or venous ulcers accumulate excess matrix metalloproteinases and bacterial biofilm. Standard passive gauze requires twice-daily nursing changes that cool the wound bed and strip newly formed granulation epithelium. Clinical evidence published in Frontiers in Endocrinology in August 2026 substantiates the shift toward active modalities, confirming that negative-pressure wound therapy significantly accelerates granulation tissue closure and reduces amputation incidence compared with standard moist gauze in diabetic foot ulcer cohorts. Hospital value-analysis committees therefore pair hydrocolloid and silicone-foam border dressings with portable sub-atmospheric pumps to shorten inpatient length of stay.
Clinical Episode Volume & Dressing Utilization Sizing
Table 2: Clinical Episode Volume and Dressing Utilization Sizing for the Advance Wound Care Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 11.8 | 12.6 | 24.3 |
| Treated chronic & complex acute wound episodes (million) | 42.5 to 47.0 | 44.8 to 49.5 | 74.0 to 82.0 |
| Average dressing wear-time interval (days per change) | 3.2 to 4.5 | 3.5 to 5.0 | 5.0 to 7.0 |
| Medicare HCPCS A6248 hydrogel-alginate allowable (USD) | 22.40 to 26.85 | 23.15 to 27.76 | 28.50 to 34.20 |
Outpatient wound clinics and skilled nursing facilities structure their dressing formularies around annual Medicare Healthcare Common Procedure Coding System fee schedules. Per Solventum's 2026 Advanced Wound Dressing Coding Bulletin, calendar year 2026 Medicare allowables under code A6248 assign USD 23.15 to USD 27.76 per unit for Nu-Gel Hydrogel with Alginate ampoules while transparent absorbent acrylic dressings follow tiered surface-area reimbursement. Transparent fee-schedule benchmarks allow home-health agencies to calculate exact per-visit dressing supply margins under bundled 30-day patient episodes.
Care Setting Expenditure & Reimbursement Sizing
Table 3: Care Setting Expenditure and Reimbursement Indicators for the Advance Wound Care Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Hospital & specialty wound clinic revenue share (%) | 58.8% | 58.0% | 52.5% |
| Home healthcare & outpatient ASC care share (%) | 41.2% | 42.0% | 47.5% |
| Single-use disposable NPWT share of NPWT units (%) | 36.0% to 40.0% | 39.0% to 43.0% | 58.0% to 64.0% |
| Atraumatic silicone & hydrocolloid border adoption (%) | 51.0% | 54.0% | 67.0% |
Table 4: Institutional & Regulatory Reference Indicators for the Advance Wound Care Market (metrics and reference basis), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Global market size, 2026 | USD 12.6 billion | 2026 global clinical wound care baseline |
| CMS CY 2026 skin-substitute fee-for-service savings | USD 19.6 billion | CMS CY 2026 Physician Fee Schedule Final Rule |
| Convatec H1 2026 Advanced Wound Care revenue | USD 356 million | Convatec Group H1 2026 interim financial report |
| Hospital & Specialized Wound Clinic revenue, 2026 | USD 7.3 billion | 58.0% primary end-user care setting allocation |
Third-party payer reimbursement for active negative-pressure pumps and advanced matrices requires strict clinical documentation of prior conservative wound care. In February 2026, CMS updated its Medicare Provider Compliance guidance for Negative Pressure Wound Therapy, mandating documented wound measurements and necrotic debridement records plus nutritional evaluations before approving home or inpatient NPWT coverage for Stage 3 or Stage 4 ulcers. Those audit requirements compel dressing and device manufacturers to embed digital wound-measurement software into hospital electronic health record workflows.
Analyst Perspective
"Hospital wound care purchasing is no longer driven by unit dressing price alone; procurement teams buy nursing time saved per dressing change and verified audit compliance under tightened 2026 Medicare payment rules. Suppliers that combine seven-day wear silicone and hydrocolloid dressings with disposable canisterless negative-pressure therapy will capture health-system contracts through 2036."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the Advance Wound Care Market segmented?
The advance wound care market is segmented by product class, wound etiology, end-user care setting, exudate mechanism, and procurement pathway. In 2026, Hydrocolloid Dressings is projected at 36.0%, Chronic Diabetic Foot Ulcers at 42.0%, Hospitals and Specialized Wound Clinics at 58.0%, Moist Wound Environment Dressings at 54.0%, and Hospital Group Purchasing Contracts at 51.0%.
By product class: Hydrocolloid Dressings and Polyurethane Foam Dressings lead unit volume. Hydrogel Dressings and Alginate Dressings complete the segment with Collagen Scaffolds and Negative Pressure Wound Therapy Devices.
By wound etiology: Chronic Diabetic Foot Ulcers and Venous and Arterial Leg Ulcers anchor chronic demand. Pressure Ulcers and Bed Sores, Severe Surgical and Traumatic Wounds, and Burn Injury Care cover remaining indications.
By end-user care setting: Hospitals and Specialized Wound Clinics and Home Healthcare and Skilled Nursing Facilities dominate care delivery, ahead of Ambulatory Surgical Centers and Long-Term Care Centers.
By exudate mechanism: Moist Wound Environment Dressings and Active Antimicrobial and Silver-Ion Dressings lead clinical protocols, followed by Mechanical Sub-Atmospheric Suction Systems and Enzymatic Debridement Matrices.
By procurement pathway: Hospital Group Purchasing Contracts and Outpatient Specialty Medical Distributors account for primary sales, ahead of Home Health Durable Medical Equipment Suppliers and Retail Pharmacies.
Why do Hydrocolloid Dressings lead the product class category?
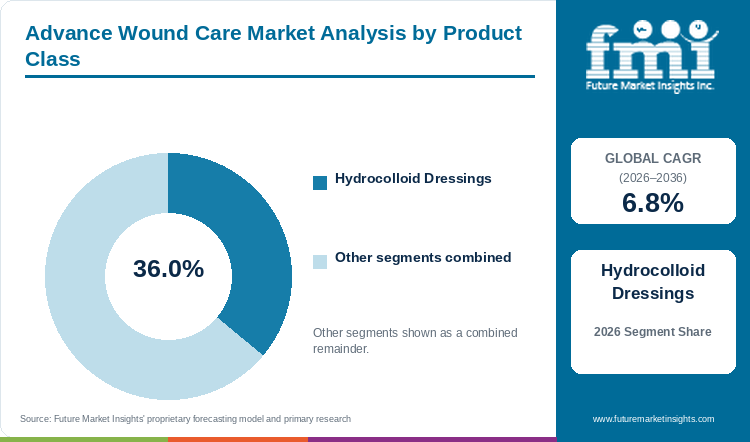
Hydrocolloid Dressings holds an estimated 36.0% of product class demand in 2026, anchored by autolytic debridement and multi-day waterproof barrier protection.
Table 5: Product Class Share for the Advance Wound Care Market (percentage share), 2026
| Product Class | Share (2026) |
|---|---|
| Hydrocolloid Dressings | 36.0% |
| Other Segments Combined | 64.0%* |
| Total | 100.0% |
*Note: Remaining product class categories account for the balance of 2026 global advance wound care demand.
Table 6: Product Class Leadership and Market Growth for the Advance Wound Care Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.8% |
| Leading Segment | Hydrocolloid Dressings |
Hydrocolloid Dressings hold primary volume leadership across hospital pressure-injury prevention protocols and outpatient ulcer kits because cross-linked carboxymethylcellulose, pectin, and gelatin matrices form a cohesive thermal-insulating gel upon absorbing wound exudate. Clinicians evaluating antimicrobial wound care dressings rely on waterproof bordered hydrocolloid wafers to facilitate painless autolytic debridement while blocking external bacterial or urinary contamination on sacral and heel ulcers. Heavy exudate saturation in deep cavitary wounds remains a functional limitation that prompts nurses to switch high-drainage cases to calcium alginates, hydrofibers, or polyurethane foams.
- Within the product class segment, Hydrocolloid Dressings is projected to account for a leading 36.0% share in 2026, supported by multi-day wear times that reduce nursing labor across acute and community settings.
- In August 2026, Convatec Group reported 3.4% organic growth in first-half 2026 Advanced Wound Care revenue ex-InnovaMatrix driven by ConvaFoam and Aquacel Ag+ Extra adoption plus June 2026 US FDA 510(k) clearance for its single-use ConvaVAC dressing.
What sustains Chronic Diabetic Foot Ulcers leadership in the wound etiology segment?
Chronic Diabetic Foot Ulcers represents 42.0% of the wound etiology category in 2026, supported by prolonged neuropathic ulcer treatment cycles and offloading protocols.
Chronic Diabetic Foot Ulcers represent the largest clinical expenditure pool in wound management given that peripheral neuropathy and microvascular ischemia impair leukocyte migration and stall natural epithelial closure for months. Multidisciplinary limb-salvage teams coordinating chronic wound care management combine serial sharp debridement and plantar pressure offloading with moisture-retentive dressings and negative-pressure suction to prevent osteomyelitis and lower-limb amputation. Updated clinical practice dossiers issued by the European Wound Management Association in June 2026 emphasize standardized vascular assessment, total-contact offloading, and stage-matched moist dressing selection to arrest diabetic foot ulcer progression.
- In 2026, Chronic Diabetic Foot Ulcers is anticipated to capture 42.0% of global wound etiology demand, reflecting high recurrence rates and multi-month dressing consumption per patient episode.
- Over the forecast period through 2036, Severe Surgical and Traumatic Wounds is projected to record rapid incremental uptake as prophylactic closed-incision negative-pressure dressings become standard protocol in high-risk orthopedic and cardiothoracic surgeries.
How do Hospitals and Specialized Wound Clinics lead the end-user care setting category?
Hospitals and Specialized Wound Clinics accounts for 58.0% of end-user care setting demand in 2026, driven by inpatient surgical debridement and NPWT initiation.
Hospitals and Specialized Wound Clinics command the majority of commercial purchasing because acute surgical debridement and skin-substitute grafting as well as negative-pressure therapy initiation require physician supervision and inpatient sterile infrastructure. Acute care nursing directors standardizing surgical wound care protocols procure multi-layer silicone foams, antimicrobial silver hydrofibers, and smart suction canisters through centralized hospital supply rooms before discharging stabilized patients to home health. Elevated inpatient bed costs and bundled surgical complication penalties continue to push health systems to transition routine dressing changes toward outpatient ambulatory centers and visiting nurse agencies.
- By end-user care setting, demand from Hospitals and Specialized Wound Clinics is estimated to reach 58.0% of total category share in 2026, driven by high-acuity surgical and chronic ulcer case volumes.
- In June 2026, federal Medicare officials released the July 2026 Ambulatory Surgical Center Payment System update under Change Request 14522, revising outpatient procedural and surgical supply payment rates that govern post-operative wound care migration.
Why do Moist Wound Environment Dressings lead the exudate mechanism category?
Moist Wound Environment Dressings secures 54.0% of exudate mechanism share in 2026, supported by faster epithelial migration and atraumatic dressing removal.
Moist Wound Environment Dressings anchor clinical wound-bed preparation protocols since maintaining a warm, moisture-balanced interface accelerates keratinocyte migration by up to 50% compared with desiccated eschar formation under dry gauze. Hospital formulary committees integrating hydro fiber wound pads with hydrocolloid and silicone-foam borders prioritize gentle adhesives that lock in exudate vertically without macerating fragile periwound skin. In September 2026, Mölnlycke Health Care and the World Union of Wound Healing Societies presented a new international clinical consensus in Kuala Lumpur demonstrating how atraumatic Safetac silicone contact layers prevent post-operative surgical incision blistering and skin stripping.
- Widespread protocol standardization across acute and community nursing places Moist Wound Environment Dressings on course to hold an estimated 54.0% share of the exudate mechanism category in 2026.
- While passive moisture-retentive wafers hold the largest volume base, Active Antimicrobial and Silver-Ion Dressings and nitric-oxide-releasing formats are forecast to gain share through 2036 across biofilm-colonized chronic ulcers.
What gives Hospital Group Purchasing Contracts the leading position in procurement pathway?
Hospital Group Purchasing Contracts commands 51.0% of procurement pathway value in 2026, anchored by multi-year health-system formulary bundling.
Hospital Group Purchasing Contracts govern more than half of global advanced wound care revenue because multi-hospital integrated delivery networks aggregate dressing and NPWT rental volume into sole-source or dual-source 3-year tender agreements to extract 15% to 30% unit price rebates. Suppliers competing for disposable negative pressure devices must clear clinical value-analysis committees by proving that a single-brand portfolio of hydrocolloids and foams as well as alginates and portable suction pumps reduces total nursing hours and pressure-injury incidence penalties. Long tender qualification cycles and strict hospital capitation budgets create high entry barriers for single-product startups lacking a comprehensive continuum-of-care catalog.
- Hospital Group Purchasing Contracts is predicted to secure 51.0% of procurement pathway demand in 2026, anchored by enterprise-wide clinical standardization across acute and affiliated outpatient clinics.
- In May 2026, Coloplast reported first-half 2025/26 group revenue of DKK 14,127 million with 6% organic growth and DKK 1,895 million in Wound and Tissue Repair sales supported by hospital and community contract execution.
What are the drivers, restraints, and opportunities in the Advance Wound Care Market?
In the advance wound care market, rising diabetic ulcer prevalence and home NPWT transitions are projected to drive adoption whereas 2026 Medicare skin-substitute payment cuts restrain overpriced biologics and FDA-cleared synthetic matrix-NPWT combinations create new growth avenues.
- Driver: Rising prevalence of diabetic foot ulcers, venous leg ulcers, and post-surgical incision complications across aging populations drives sustained hospital and home-care demand for moisture-retentive dressings and portable NPWT systems.
- Restraint: Stringent 2026 Medicare reimbursement cuts and local coverage evidentiary thresholds for cellular and tissue-based skin substitutes restrain high-priced biologic graft billing across outpatient clinics.
- Opportunity: FDA-cleared combinations of synthetic electrospun matrices with negative-pressure wound therapy and nitric-oxide-generating antimicrobial dressings create high-margin clinical adoption avenues.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Health systems managing rising diabetic and immobile elderly patient cohorts are expanding portable sub-atmospheric suction and extended-wear dressing deployment to move complex wound care out of costly inpatient beds into supervised home recovery. Care pathways utilizing negative pressure wound therapy allow clinicians to maintain continuous exudate removal and mechanical tissue approximation across open ulcers and dehisced surgical incisions without keeping patients hospitalized. In November 2025, the US Food and Drug Administration granted 510(k) clearance K250586 for the Prospera Spectruum Negative Pressure Wound Therapy System across acute and home-care management of diabetic and venous ulcers as well as closed surgical incisions. Broader regulatory clearances for lightweight home-compatible NPWT platforms directly boost recurring disposable canister and peel-and-place dressing kit sales.
Risk Assessment of the Advance Wound Care Market: Operational and Formulation Friction
Tightened reimbursement audits and steep Medicare fee-schedule reductions for cellular and tissue-based skin substitutes represent the primary financial restraint disrupting revenue mixes for biologic wound-matrix suppliers in 2026. Outpatient providers purchasing wound skin care products and biologic grafts now face strict Local Coverage Determinations that deny payment for products lacking randomized controlled trial superiority or prior four-week conservative moist-dressing documentation. In December 2025, Medicare authorities issued updated Final Local Coverage Determinations for skin substitute grafts in diabetic foot and venous leg ulcers ahead of the January 2026 payment transition to USD 127.28 per square centimeter. As a result, manufacturers heavily exposed to legacy high-priced placental allografts experienced sharp first-half 2026 revenue contractions and are rapidly shifting R&D toward cost-effective synthetic matrices and advanced foam-hydrofiber dressings.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Synthetic biomimetic electrospun scaffolds paired with active negative-pressure suction and biofilm-disrupting nitric-oxide dressings are opening premium clinical growth avenues that satisfy strict hospital cost-effectiveness gates. Rather than relying on fragile human allografts, wound surgeons pairing seaweed medical disposable dressings and synthetic polymeric matrices with sub-atmospheric therapy can granulate deep tendon-exposed wounds at a fraction of biologic graft cost. In October 2026, Solventum announced FDA 510(k) clearance for the combined clinical use of its Restrata synthetic electrospun wound matrix with Solventum V.A.C. Therapy to accelerate tissue granulation in complex wounds. These cleared combination protocols enable sales teams to bundle synthetic matrices directly into existing hospital V.A.C. therapy contracts through 2036.
Advance Wound Care Market by Country (2026 to 2036)
FMI country modeling indicates that the United Arab Emirates leads advance wound care expansion at an 8.4% CAGR through 2036, while the United States progresses at a 7.5% CAGR and Japan advances at a 5.9% CAGR. National growth variation across japanese advanced wound care and Western health systems reflects local diabetes prevalence, DRG surgical infection penalties, and outpatient home-nursing reimbursement.
Table 7: Country CAGR and Primary Growth Levers for the Advance Wound Care Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| United Arab Emirates | 8.4% | Tertiary diabetic limb-salvage centers and private hospital NPWT adoption |
| United States | 7.5% | 2026 CMS payment reform favoring evidence-supported dressings and single-use NPWT |
| Switzerland | 7.2% | Spitex home-nursing integration and two-step HydroTherapy wound kits |
| Canada | 7.1% | Provincial community wound clinic transitions across 15.6M ED visit base |
| Australia | 7.0% | AIHW hospital-acquired complication penalties and aged-care ulcer programs |
| United Kingdom | 6.6% | NHS district-nursing extended-wear dressing protocols and New Hospital Programme |
| Germany | 6.3% | G-BA clinical-evidence reimbursement alignment and outpatient vascular care |
| Japan | 5.9% | Geriatric decubitus ulcer management and MHLW home-nursing fee support |
Source: Future Market Insights analysis
United Arab Emirates Advance Wound Care Market Outlook (2026 to 2036)
Emirati hospital adoption of advance wound care is projected to expand at a leading 8.4% CAGR between 2026 and 2036 as tertiary medical networks in Dubai and Abu Dhabi scale specialized diabetic limb-salvage and burn-trauma centers. What distinguishes the UAE from mature European markets is the combination of high national type 2 diabetes prevalence and rapid private-hospital bed expansion under mandatory health insurance schemes that reimburse premium silicone foams and disposable NPWT systems. In mid-September 2026, Swedish medtech leader Mölnlycke announced a strategic corporate separation of its surgical solutions business from its regional media hub to focus core investment directly on its Advanced Wound Care division. High ambient Gulf humidity and multi-national clinical staffing also prompt Emirati hospital procurement officers to favor pre-packaged all-in-one peel-and-place dressings that standardize application technique across nursing shifts.
Key takeaway: In the United Arab Emirates, high diabetic foot ulcer care intensity and private tertiary hospital expansion are projected to drive leading adoption of silicone-foam and disposable NPWT systems.
United States Advance Wound Care Market Outlook (2026 to 2036)
In the United States, the advance wound care market is anticipated to progress at a 7.5% CAGR across the 2026 to 2036 forecast window, anchored by the world's largest installed base of outpatient wound-healing centers and home-health nursing agencies. American purchasing dynamics diverge from single-payer European tenders due to the transformative January 2026 Medicare Physician Fee Schedule overhaul, which cut skin-substitute spending by nearly 90% and redirected hospital demand toward FDA-cleared synthetic matrices and single-use NPWT devices. In November 2025, regenerative wound leader Organogenesis Holdings formally commended the CMS Calendar Year 2026 payment reform for curbing billing abuse and rewarding products supported by rigorous clinical trial evidence. Hospital penalty programs for surgical-site infections and Stage 3 or Stage 4 pressure injuries further compel US acute-care systems to mandate prophylactic sacral silicone-hydrocolloid dressings on intensive-care admissions.
Key takeaway: In the United States, 2026 CMS payment modernization and hospital pressure-injury penalty avoidance are anticipated to accelerate uptake of evidence-supported matrices and single-use NPWT.
Switzerland Advance Wound Care Market Outlook (2026 to 2036)
Swiss advance wound care expenditure is forecast to rise at a 7.2% CAGR between 2026 and 2036 across cantonal university hospitals, specialized vascular clinics, and decentralized Spitex home-care nursing organizations. Compared with price-capped European public tender markets, Switzerland's mandatory health insurance (OKP) MiGeL medical-device list and affluent aging demographic support rapid clinical adoption of dual-stage hydro-responsive wound dressings and connected ambulatory negative-pressure pumps. Per IVF HARTMANN AG's 2026 Swiss corporate strategy disclosures in Neuhausen, domestic hospitals and Spitex home-nursing providers prioritize simplified two-step HydroTherapy and pre-assembled sterile wound kits that reduce skilled nursing minutes per dressing change. Bilingual Swiss MedTech labeling and strict Swissmedic Medical Device Ordinance compliance remain essential prerequisites for international dressing manufacturers entering cantonal hospital formularies.
Key takeaway: In Switzerland, Spitex home-nursing integration and domestic preference for labor-saving hydro-responsive wound kits are forecast to sustain strong premium dressing demand.
Canada Advance Wound Care Market Outlook (2026 to 2036)
Canadian demand for advance wound care is estimated to grow at a 7.1% CAGR between 2026 and 2036 as provincial health ministries expand community home-care wound clinics to relieve acute inpatient bed congestion. Canadian market structure differs from the US private-payer system because provincial group purchasing organizations such as Mohawk MedBuy and HealthPRO award multi-year contracts that prioritize total episode cost reduction and rural telehealth wound-monitoring compatibility. In September 2026, the Canadian Institute for Health Information reported more than 15.6 million annual emergency department visits across NACRS facilities with 90th-percentile inpatient admission waits reaching 46.5 hours, underscoring the urgent provincial push to manage diabetic and venous ulcers in community clinics. Long winter transport distances across rural provinces also favor seven-day extended-wear hydrocolloid, foam, and antimicrobial dressings that minimize patient travel.
Key takeaway: In Canada, provincial hospital capacity pressures and community home-care transitions are estimated to drive sustained procurement of extended-wear dressings and portable NPWT.
Australia Advance Wound Care Market Outlook (2026 to 2036)
Australia's advance wound care market is slated to advance at a 7.0% CAGR through 2036, driven by federal chronic-wound consumable subsidies and strict hospital-acquired complication monitoring across public and private hospital networks. What sets Australia apart in the Asia-Pacific region is the national safety reporting framework administered by the Australian Institute of Health and Welfare, which tracks hospital-acquired pressure injuries and surgical infections as direct quality-funding benchmarks. In September 2026, the Australian Institute of Health and Welfare reported that hospital-acquired complications occurred in 171,000 public hospitalisations and 49,800 private hospitalisations in 2024 to 2025, with healthcare-associated infections representing 29% and surgical complications 12% of recorded events. Those national quality penalties incentivize Australian surgical and aged-care directors to standardize antimicrobial silver-alginate, hydrocolloid, and closed-incision NPWT protocols.
Key takeaway: In Australia, national hospital-acquired complication penalties and aged-care chronic ulcer programs are slated to support strong institutional demand for antimicrobial and prophylactic dressings.
United Kingdom Advance Wound Care Market Outlook (2026 to 2036)
Sales of advance wound care products in the United Kingdom are predicted to expand at a 6.6% CAGR during the 2026 to 2036 period across NHS acute trusts, community district-nursing teams, and NHS Supply Chain national frameworks. British wound care delivery diverges from hospital-centric continental models because community district nurses manage the majority of venous leg ulcers and pressure injuries in patient homes using NHS Drug Tariff Part IX approved hydrocolloids, superabsorbent foams, and compression systems. In July 2026, the UK Department of Health and Social Care published its New Hospital Programme Annual Report for 2025 to 2026 detailing ongoing NHS surgical infrastructure modernization and standardized infection-control pathways. Strict National Institute for Health and Care Excellence (NICE) medical-technology appraisals require suppliers to prove net NHS nursing-visit savings before securing Drug Tariff reimbursement.
Key takeaway: In the United Kingdom, NHS community district-nursing workloads and NICE cost-saving thresholds are predicted to favor extended-wear hydrocolloids and single-use NPWT.
Germany Advance Wound Care Market Outlook (2026 to 2036)
In Germany, advance wound care demand is expected to progress at a 6.3% CAGR from 2026 through 2036 within statutory health insurance (GKV) outpatient home-care networks and specialized hospital vascular centers. German market dynamics are shaped by the Federal Joint Committee (G-BA) reform of antimicrobial and phase-adapted wound dressing reimbursement, which requires manufacturers to submit dedicated clinical healing evidence for silver-containing and bioactive dressings to retain statutory prescription eligibility. In May 2026, Urgo Medical highlighted at the joint EWMA-DEWU 2026 congress in Bremen how German clinicians and industrial partners are aligning on evidence-based poly-absorbent and TLC-NOSF matrix dressings to shorten venous and diabetic ulcer closure times. While G-BA evidentiary rules restrain unsubstantiated antimicrobial SKUs, clinically proven moisture-retentive hydrocolloids and protease-modulating matrices continue to gain statutory prescription share.
Key takeaway: In Germany, statutory G-BA clinical-evidence mandates and outpatient vascular care protocols are expected to concentrate demand in clinically proven moisture-retentive and matrix dressings.
Japan Advance Wound Care Market Outlook (2026 to 2036)
With the world's oldest national demographic profile, the Japan advance wound care market is projected to grow at a 5.9% CAGR from 2026 to 2036 across acute hospitals and home-visit nursing stations. Japanese clinical practice differs from Western surgical graft heavy models through its strong emphasis on conservative pressure-ulcer (decubitus) moisture management using hydrocolloid and polyurethane foam dressings reimbursed under biennial Ministry of Health, Labour and Welfare (MHLW) medical-fee revisions. A November 2025 clinical study in MDPI Surgeries examining diabetic foot and chronic wound management underscored how structured negative-pressure therapy and moisture-retentive dressings reduce healing duration across aging patient cohorts. Because Japanese home-care nurses manage high volumes of immobile elderly patients with fragile skin, gentle silicone-bordered hydrocolloids and compact quiet NPWT pumps enjoy high repeat institutional ordering.
Key takeaway: In Japan, geriatric pressure-ulcer care across long-term facilities and biennial MHLW reimbursement support are projected to sustain steady adoption of atraumatic hydrocolloids and compact NPWT.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Advance Wound Care Market?
3M Company (Solventum Corporation), Smith and Nephew plc, Mölnlycke Health Care AB, ConvaTec Group plc, Coloplast AS, Integra LifeSciences Holdings Corp, Urgo Medical, PAUL HARTMANN AG, BBraun SE, and Organogenesis Holdings Inc. are the notable companies in the advance wound care market.
Competitive structure across the advance wound care industry brings together global multi-modality wound and negative-pressure leaders, specialized ostomy and chronic-exudate dressing manufacturers, and regenerative dermal-matrix innovators. Solventum Corporation, Mölnlycke Health Care, and Smith+Nephew plc operate comprehensive global portfolios spanning NPWT pumps and advanced surgical and chronic dressings. ConvaTec Group plc and Coloplast A/S lead hydrofiber and foam dressing supply with PAUL HARTMANN AG and BBraun SE. Integra LifeSciences, Urgo Medical, and Organogenesis Holdings specialize in bioactive scaffolds and regenerative matrices.
- Multi-Modality NPWT & Advanced Dressing Leaders: Solventum Corporation (3M spin-off), Smith+Nephew plc, and Mölnlycke Health Care AB supply negative-pressure wound therapy systems and surgical incision dressings globally.
- Exudate Management & Antimicrobial Dressing Specialists: ConvaTec Group plc and Coloplast A/S manufacture hydrocolloid, hydrofiber, and silicone-foam dressings with PAUL HARTMANN AG and BBraun SE across hospital channels.
- Bioactive Scaffold & Regenerative Matrix Innovators: Integra LifeSciences Holdings Corp, Urgo Medical, and Organogenesis Holdings Inc. engineer collagen matrices, TLC-NOSF oligosaccharide dressings, and cellular tissue-repair scaffolds for complex ulcers and burns.
Competitive Benchmarking: Advance Wound Care Market
Table 8: Competitive Benchmarking for the Advance Wound Care Market (qualitative capability ratings), 2026
| Company | Exudate & Dressing Portfolio | Active NPWT & Bioactive Depth | Home & Outpatient Fit | Geographic Reach |
|---|---|---|---|---|
| 3M Company (Solventum) | High | High | High | Global V.A.C. Therapy, Peel and Place, Tegaderm, and Restrata matrix network |
| Smith and Nephew plc | High | High | High | Global ALLEVYN foam, PICO single-use NPWT, and RENASYS EDGE footprint |
| Mölnlycke Health Care AB | High | Medium | High | Global Mepilex Safetac dressing leadership; new China Zhende JV in 2026 |
| ConvaTec Group plc | High | High | High | Global Aquacel ConvaFiber, ConvaFoam, ConvaNiox, and ConvaVAC network |
| Coloplast AS | High | Medium | High | European, North American, and global Biatain silicone and Kerecis fish-skin reach |
| Integra LifeSciences Corp | Medium | High | Medium | U.S. and international Integra dermal regeneration templates and PriMatrix scaffolds |
| Urgo Medical | High | Medium | High | European and international UrgoStart TLC-NOSF and poly-absorbent matrix network |
| PAUL HARTMANN AG | High | Medium | High | European and Swiss HydroTherapy, Zetuvit superabsorbent, and Spitex supply |
| BBraun SE | High | Medium | High | Global Prontosan biofilm irrigation, Askina dressings, and surgical care reach |
| Organogenesis Holdings Inc. | Medium | High | High | U.S. outpatient wound center leadership in Apligraf, Dermagraft, and PuraPly AM |
Evaluation basis: Exudate and Dressing Portfolio rates commercial breadth across hydrocolloid, foam, and antimicrobial hydrofiber lines. Active NPWT and Bioactive Depth evaluates cleared negative-pressure pumps and collagen or synthetic scaffolds, while Home and Outpatient Fit measures single-use portability and Medicare/G-BA reimbursement alignment.
Key Developments in the Advance Wound Care Market
- In May 2026, Convatec Group plc debuted its next-generation Aquacel ConvaFiber hydrofiber dressing and ConvaNiox nitric-oxide-generating dressing at the EWMA 2026 congress in Bremen ahead of European commercial scale-up.
- In May 2026, Mölnlycke Health Care AB and Zhende Medical formed a majority-owned joint venture headquartered in Shanghai to expand hospital and community access to advanced wound care dressings across China starting in Q3 2026.
- In February 2026, Integra LifeSciences Holdings Corporation reported full-year 2025 financial results highlighting sustained clinical demand across its Tissue Technologies wound reconstruction and burn-care matrix portfolio.
Key Players in the Advance Wound Care Market
Multi-Modality NPWT & Advanced Dressing Leaders
- 3M Company (Solventum Corporation)
- Smith and Nephew plc
- Mölnlycke Health Care AB
- Exudate Management & Antimicrobial Dressing Specialists
ConvaTec Group plc
- Coloplast AS
- PAUL HARTMANN AG
- BBraun SE
- Bioactive Scaffold & Regenerative Matrix Innovators
Integra LifeSciences Holdings Corp
- Urgo Medical
- Organogenesis Holdings Inc.
Advance Wound Care Market - Report Scope
Table 9: Report Scope for the Advance Wound Care Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Class; Wound Etiology; End-User Care Setting; Exudate Mechanism; Procurement Pathway |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial hospital, outpatient clinic, and home-health revenue from advanced moisture-retentive wound dressings (hydrocolloids, hydrogels, alginates, polyurethane foams, hydrofibers, and antimicrobial silver/nitric-oxide dressings), collagen and synthetic/cellular bioactive scaffolds, and negative-pressure wound therapy (NPWT) devices and disposable canisters/kits. Category Scope Note: Excludes traditional dry cotton gauze, adhesive first-aid bandages, and mechanical surgical sutures/staplers. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | United Arab Emirates, United States, Switzerland, Canada, Australia, United Kingdom, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | 3M Company (Solventum Corporation), Smith and Nephew plc, Mölnlycke Health Care AB, ConvaTec Group plc, Coloplast AS, Integra LifeSciences Holdings Corp, Urgo Medical, PAUL HARTMANN AG, BBraun SE, Organogenesis Holdings Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Advance Wound Care Market - Research Methodology
Table 10: Research Methodology for the Advance Wound Care Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with hospital vascular and plastic surgeons, certified wound ostomy continence nurses (WOCNs), home-health agency clinical directors, and GPO formulary managers to validate dressing change intervals and episode costs. |
| Secondary Research | Analysis of CMS Physician Fee Schedule and ASC payment rules, FDA 510(k) device clearances, CIHI and AIHW hospital complication registries, EWMA and WUWHS clinical consensus dossiers, and corporate financial filings. |
| Market Sizing and Forecasting | Top-down global medical device and wound management baselines reconciled against bottom-up treated chronic and acute wound episodes (44.8M to 49.5M in 2026) and per-episode dressing and NPWT rental/consumable expenditure from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight national diabetes and geriatric pressure-ulcer prevalence, hospital-acquired infection penalty rules, statutory reimbursement lists (Medicare HCPCS, Germany G-BA, UK Drug Tariff), and home-nursing transitions across eight countries. |
| Operational Benchmark Traceability | Episode volumes, wear-time intervals, and reimbursement allowables in Tables 2, 3, and 4 trace to CMS CY 2026 PFS Final Rule data, Solventum 2026 HCPCS coding bulletins, and Convatec and Coloplast 2026 interim financial disclosures. |
| Data Triangulation and Validation | Revenue estimates isolate advanced moisture-retentive dressings, bioactive scaffolds, and active NPWT systems while strictly excluding commodity woven gauze, surgical closure staples, and systemic antibiotics. |
Advance Wound Care Market by Segments
Advance Wound Care Market segmented by Product Class:
- Hydrocolloid Dressings
- Hydrogel Dressings
- Alginate Dressings
- Polyurethane Foam Dressings, Collagen Scaffolds, and NPWT Devices
Advance Wound Care Market segmented by Wound Etiology:
- Chronic Diabetic Foot Ulcers
- Venous and Arterial Leg Ulcers
- Pressure Ulcers and Bed Sores
- Severe Surgical, Traumatic, and Burn Wounds
Advance Wound Care Market segmented by End-User Care Setting:
- Hospitals and Specialized Wound Clinics
- Ambulatory Surgical Centers
- Home Healthcare and Skilled Nursing Facilities
- Long-Term Care and Rehabilitation Centers
- Community District Nursing Services
Advance Wound Care Market segmented by Exudate Mechanism:
- Moist Wound Environment Dressings
- Active Antimicrobial and Silver-Ion Dressings
- Mechanical Sub-Atmospheric Suction Systems
- Enzymatic and Autolytic Debridement Matrices
Advance Wound Care Market segmented by Procurement Pathway:
- Hospital Group Purchasing Contracts
- Outpatient Specialty Medical Distributors
- Home Health Durable Medical Equipment Suppliers
- Retail and Hospital Outpatient Pharmacies
Advance Wound Care Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Switzerland
- Italy and Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- United Arab Emirates and GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Centers for Medicare & Medicaid Services. (2025, October 31). CMS Modernizes Payment Accuracy and Significantly Cuts Spending Waste. U.S. Department of Health and Human Services.
- [2] Smith+Nephew plc. (2026, May 5). Smith+Nephew drives progress in chronic wound care with ALLEVYN Complete Care dressing and RENASYS EDGE tNPWT set to launch at EWMA 2026. Smith+Nephew Corporate Media Releases.
- [3] Zhang, L., et al. (2026, August 31). Negative Pressure Wound Therapy Versus Standard Moist Wound Care for Diabetic Foot Ulcers: Clinical Healing and Amputation Reduction Analysis. Frontiers in Endocrinology, 17, 1850122.
- [4] Solventum Corporation. (2026, January 15). 2026 Advanced Wound Dressing and Skin Care coding information. Solventum Medical Surgical Reimbursement Bulletin.
- [5] Centers for Medicare & Medicaid Services. (2026, February 11). Negative Pressure Wound Therapy: Medicare Provider Compliance Tips. U.S. Department of Health and Human Services MLN Compliance Series.
- [6] Convatec Group plc. (2026, August 4). Interim results for the six months ended 30 June 2026. Convatec Group Corporate Media Releases.
- [7] European Wound Management Association. (2026, June 10). Diabetic Foot: The Diabetic Foot Group Clinical Dossiers. European Wound Management Association.
- [8] Centers for Medicare & Medicaid Services. (2026, June 24). Ambulatory Surgical Center Payment System: July 2026 Update (MM14522, Transmittal R13836CP). U.S. Department of Health and Human Services.
- [9] Mölnlycke Health Care AB. (2026, September 30). New consensus document highlights need to address post-operative blistering to improve patient outcomes. Mölnlycke Health Care Global Newsroom.
- [10] Coloplast A/S. (2026, May 12). 2025/26 Interim financial results, H1 2025/26. Coloplast Investor Relations.
- [11] U.S. Food and Drug Administration. (2025, November 21). 510(k) Premarket Notification K250586: Prospera Spectruum Negative Pressure Wound Therapy System. FDA Center for Devices and Radiological Health.
- [12] Centers for Medicare & Medicaid Services. (2025, December 24). Final Local Coverage Determinations (LCDs) for Certain Skin Substitutes Withdrawn. U.S. Department of Health and Human Services.
- [13] Solventum Corporation. (2026, October 19). Solventum Announces FDA 510(k) Clearance for Combined Use of Restrata Matrix and Solventum V.A.C. Therapy. Solventum Investor Newsroom.
- [14] Mölnlycke Health Care AB. (2026, September 17). Mölnlycke to separate its surgical solutions business into a standalone company. Mölnlycke UAE Media Room.
- [15] Organogenesis Holdings Inc. (2025, November 3). Organogenesis Applauds CMS's Significant Step In Payment Reform. Organogenesis Investor Relations.
- [16] IVF HARTMANN AG. (2026, March 10). Strategie 2026: IVF HARTMANN AG. PAUL HARTMANN Group Switzerland.
- [17] Canadian Institute for Health Information. (2026, September 17). NACRS emergency department visits and lengths of stay. Canadian Institute for Health Information Statistical Release.
- [18] Australian Institute of Health and Welfare. (2026, September 7). Admitted patient safety and quality: Hospitals. Australian Government AIHW Report.
- [19] Department of Health and Social Care. (2026, July 8). New Hospital Programme annual report: financial year 2025 to 2026. UK Government Official Publications.
- [20] Urgo Medical. (2026, May 21). Urgo Medical at EWMA 2026: three days of exchange, innovation and commitment to advancing wound care. Urgo Medical Corporate Newsroom.
- [21] Tanaka, H., et al. (2025, November 1). Negative-Pressure Wound Therapy in Diabetic Foot Management: Synthesis of International Randomized Evidence over Two Decades. Surgeries, MDPI, 6(11), 126.
- [22] Convatec Group plc. (2026, May 5). Convatec's Advanced Wound Care innovation leads the industry at European Wound Management Association (EWMA) 2026. Convatec Group Corporate Media Releases.
- [23] Mölnlycke Health Care AB. (2026, May 21). Mölnlycke Health Care and Zhende Medical form pioneering joint venture to expand access to advanced wound care solutions in China. Mölnlycke Health Care Media Room.
- [24] Integra LifeSciences Holdings Corporation. (2026, February 26). Integra LifeSciences Reports Fourth Quarter and Full-Year 2025 Financial Results. Integra LifeSciences Investor Relations.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the advance wound care market in 2026 and what is forecast for 2036?
- Which diabetic ulcer and home-nursing drivers support demand for advance wound care?
- Why do Hydrocolloid Dressings lead the product class category?
- Why do Chronic Diabetic Foot Ulcers lead the wound etiology category globally?
- How do growth rates differ across the United Arab Emirates and the United States versus Canada and Germany?
- Which leading companies supply negative-pressure wound therapy systems versus moisture-retentive dressings and bioactive scaffolds?
- How do 2026 Medicare skin-substitute payment reforms reshape hospital and clinic purchasing?
- What should hospital value-analysis committees evaluate when selecting extended-wear dressings and portable NPWT?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Class, 2026 to 2036
- Hydrocolloid Dressings
- Hydrogel Dressings
- Alginate Dressings
- Polyurethane Foam Dressings, Collagen Scaffolds, and NPWT Devices
- Y-o-Y Growth Trend Analysis By Product Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Class, 2026 to 2036
- Global Market Analysis and Forecast, By Wound Etiology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Wound Etiology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Wound Etiology, 2026 to 2036
- Chronic Diabetic Foot Ulcers
- Venous and Arterial Leg Ulcers
- Pressure Ulcers and Bed Sores
- Severe Surgical, Traumatic, and Burn Wounds
- Y-o-Y Growth Trend Analysis By Wound Etiology, 2021 to 2025
- Absolute $ Opportunity Analysis By Wound Etiology, 2026 to 2036
- Global Market Analysis and Forecast, By End-User Care Setting, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-User Care Setting, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-User Care Setting, 2026 to 2036
- Hospitals and Specialized Wound Clinics
- Ambulatory Surgical Centers
- Home Healthcare and Skilled Nursing Facilities
- Long-Term Care and Rehabilitation Centers
- Community District Nursing Services
- Y-o-Y Growth Trend Analysis By End-User Care Setting, 2021 to 2025
- Absolute $ Opportunity Analysis By End-User Care Setting, 2026 to 2036
- Global Market Analysis and Forecast, By Exudate Mechanism, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Exudate Mechanism, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Exudate Mechanism, 2026 to 2036
- Moist Wound Environment Dressings
- Active Antimicrobial and Silver-Ion Dressings
- Mechanical Sub-Atmospheric Suction Systems
- Enzymatic and Autolytic Debridement Matrices
- Y-o-Y Growth Trend Analysis By Exudate Mechanism, 2021 to 2025
- Absolute $ Opportunity Analysis By Exudate Mechanism, 2026 to 2036
- Global Market Analysis and Forecast, By Procurement Pathway, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Procurement Pathway, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Procurement Pathway, 2026 to 2036
- Hospital Group Purchasing Contracts
- Outpatient Specialty Medical Distributors
- Home Health Durable Medical Equipment Suppliers
- Retail and Hospital Outpatient Pharmacies
- Y-o-Y Growth Trend Analysis By Procurement Pathway, 2021 to 2025
- Absolute $ Opportunity Analysis By Procurement Pathway, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Switzerland
- Italy and Spain
- Benelux
- Nordics
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Arab Emirates and GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- United Arab Emirates
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Class
- By Wound Etiology
- By End-User Care Setting
- By Exudate Mechanism
- By Procurement Pathway
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- 3M Company (Solventum)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Smith and Nephew plc
- Mölnlycke Health Care AB
- ConvaTec Group plc
- Coloplast AS
- Integra LifeSciences Corp
- Urgo Medical
- PAUL HARTMANN AG
- BBraun SE
- Organogenesis Holdings Inc.
- 3M Company (Solventum Corporation)
- Exudate Management & Antimicrobial Dressing Specialists
- Bioactive Scaffold & Regenerative Matrix Innovators
- 3M Company (Solventum)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Class, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Wound Etiology, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-User Care Setting, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Exudate Mechanism, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Procurement Pathway, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Class, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Wound Etiology, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-User Care Setting, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Exudate Mechanism, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Procurement Pathway, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Class, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Wound Etiology, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-User Care Setting, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Exudate Mechanism, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Procurement Pathway, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Class, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Wound Etiology, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-User Care Setting, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Exudate Mechanism, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Procurement Pathway, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Class, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Wound Etiology, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-User Care Setting, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Exudate Mechanism, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Procurement Pathway, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Class, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Wound Etiology, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-User Care Setting, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Exudate Mechanism, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Procurement Pathway, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Class, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Wound Etiology, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-User Care Setting, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Exudate Mechanism, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Procurement Pathway, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Class, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Wound Etiology, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-User Care Setting, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Exudate Mechanism, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Procurement Pathway, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Class, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Class, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Class
- Figure 6: Global Market Value Share and BPS Analysis by Wound Etiology, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Wound Etiology, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Wound Etiology
- Figure 9: Global Market Value Share and BPS Analysis by End-User Care Setting, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-User Care Setting, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-User Care Setting
- Figure 12: Global Market Value Share and BPS Analysis by Exudate Mechanism, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Exudate Mechanism, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Exudate Mechanism
- Figure 15: Global Market Value Share and BPS Analysis by Procurement Pathway, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Procurement Pathway, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Procurement Pathway
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Class, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Class, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Class
- Figure 32: North America Market Value Share and BPS Analysis by Wound Etiology, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Wound Etiology, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Wound Etiology
- Figure 35: North America Market Value Share and BPS Analysis by End-User Care Setting, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-User Care Setting, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-User Care Setting
- Figure 38: North America Market Value Share and BPS Analysis by Exudate Mechanism, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Exudate Mechanism, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Exudate Mechanism
- Figure 41: North America Market Value Share and BPS Analysis by Procurement Pathway, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Procurement Pathway, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Procurement Pathway
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Class, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Class, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Class
- Figure 48: Latin America Market Value Share and BPS Analysis by Wound Etiology, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Wound Etiology, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Wound Etiology
- Figure 51: Latin America Market Value Share and BPS Analysis by End-User Care Setting, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-User Care Setting, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-User Care Setting
- Figure 54: Latin America Market Value Share and BPS Analysis by Exudate Mechanism, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Exudate Mechanism, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Exudate Mechanism
- Figure 57: Latin America Market Value Share and BPS Analysis by Procurement Pathway, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Procurement Pathway, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Procurement Pathway
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Class, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Class, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Class
- Figure 64: Western Europe Market Value Share and BPS Analysis by Wound Etiology, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Wound Etiology, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Wound Etiology
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-User Care Setting, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-User Care Setting, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-User Care Setting
- Figure 70: Western Europe Market Value Share and BPS Analysis by Exudate Mechanism, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Exudate Mechanism, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Exudate Mechanism
- Figure 73: Western Europe Market Value Share and BPS Analysis by Procurement Pathway, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Procurement Pathway, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Procurement Pathway
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Class, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Class, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Class
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Wound Etiology, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Wound Etiology, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Wound Etiology
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-User Care Setting, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-User Care Setting, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-User Care Setting
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Exudate Mechanism, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Exudate Mechanism, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Exudate Mechanism
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Procurement Pathway, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Procurement Pathway, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Procurement Pathway
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Class, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Class, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Class
- Figure 96: East Asia Market Value Share and BPS Analysis by Wound Etiology, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Wound Etiology, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Wound Etiology
- Figure 99: East Asia Market Value Share and BPS Analysis by End-User Care Setting, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-User Care Setting, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-User Care Setting
- Figure 102: East Asia Market Value Share and BPS Analysis by Exudate Mechanism, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Exudate Mechanism, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Exudate Mechanism
- Figure 105: East Asia Market Value Share and BPS Analysis by Procurement Pathway, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Procurement Pathway, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Procurement Pathway
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Class, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Class, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Class
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Wound Etiology, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Wound Etiology, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Wound Etiology
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-User Care Setting, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-User Care Setting, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-User Care Setting
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Exudate Mechanism, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Exudate Mechanism, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Exudate Mechanism
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Procurement Pathway, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Procurement Pathway, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Procurement Pathway
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Class, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Class, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Class
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Wound Etiology, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Wound Etiology, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Wound Etiology
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-User Care Setting, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-User Care Setting, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-User Care Setting
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Exudate Mechanism, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Exudate Mechanism, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Exudate Mechanism
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Procurement Pathway, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Procurement Pathway, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Procurement Pathway
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Advance Wound Care Market in 2026, and what is forecast for 2036?
FMI estimates that global advance wound care demand stood at USD 11.8 billion in 2025 and reached USD 12.6 billion in 2026. Overall sector valuation is on track to hit USD 24.3 billion by 2036 as hospitals and home-care agencies standardize extended-wear dressings and portable NPWT.
What is the CAGR for the Advance Wound Care Market from 2026 to 2036?
The advance wound care sector is projected to expand at a 6.8% CAGR over the 2026 to 2036 forecast window, adding USD 11.7 billion in incremental revenue across hospital and home-health channels.
Which product class segment leads the Advance Wound Care Market?
Hydrocolloid Dressings is projected to hold 36.0% of product class demand in 2026 given that self-adherent moisture-retentive wafers support autolytic debridement and multi-day wear.
Which wound etiology segment leads the Advance Wound Care Market?
Chronic Diabetic Foot Ulcers is anticipated to represent 42.0% of the wound etiology category in 2026 since neuropathic lower-extremity ulcers require multi-week exudate management and offloading.
Which country has a notable growth outlook during the assessment period?
The United Arab Emirates leads national expansion projections at an 8.4% CAGR through 2036, followed by the United States at a 7.5% CAGR and Switzerland at a 7.2% CAGR.
Who are the key players in the market?
3M Company (Solventum Corporation), Smith and Nephew plc, and Mölnlycke Health Care AB lead commercial supply. ConvaTec Group plc, Coloplast AS, and Integra LifeSciences Holdings Corp compete across major regions. Urgo Medical and PAUL HARTMANN AG also participate with BBraun SE and Organogenesis Holdings Inc.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
