
- Market Size (2026)
- USD 5.8 Bn
- Forecast (2036)
- USD 19.3 Bn
- CAGR (2026 to 2036)
- 12.9%
How big is Automotive MEMS Sensor Market in 2026?
From 2026 to 2036 the automotive MEMS sensor CAGR is 12.9%. Automotive MEMS sensor sales were USD 5.1 billion for 2025. The estimate for 2026 reaches USD 5.8 billion, and the projection for 2036 reaches USD 19.3 billion.
The automotive MEMS sensor market is worth an estimated USD 5.8 billion in 2026, against USD 5.1 billion in 2025. On FMI figures, sales will grow at a CAGR of 12.9% from 2026 to 2036 and reach USD 19.3 billion by 2036.
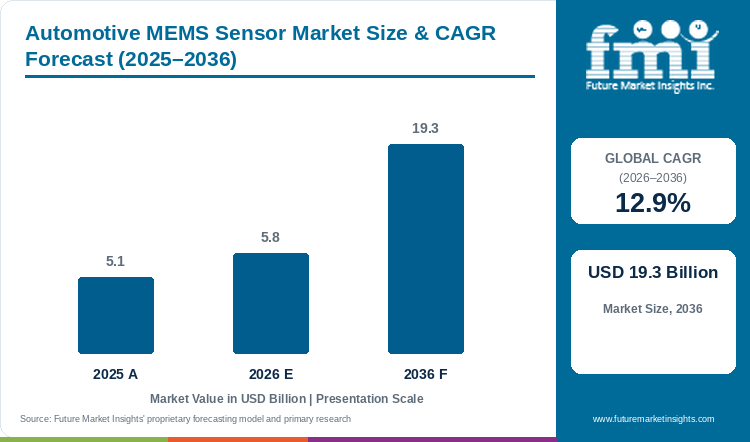
Every MEMS sensor is also a vehicle chip, and the automotive semiconductor market as a whole expands at a 6.8% CAGR from 2026 to 2036. At 12.9%, sensors will take a larger slice of each car's chip bill. Camera-based monitoring answers the same EU GSR 2 safety rules, and the driver monitoring system market moves on an 8.1% CAGR over the same years. MEMS grows faster because nearly all new vehicles need acceleration data for airbags and stability control, so accelerometers hold nearly 35% of 2026 sensor type sales.
MEMS sensor supply has become more concentrated. STMicroelectronics completed the purchase of the NXP MEMS sensors business on 2 February 2026, a business ST described as covering automotive safety and non-safety products.[1] Carmakers now have fewer independent sources for airbag, stability-control and tyre-pressure sensing.
Safety qualification slows new MEMS suppliers. Smaller fabs will face long safety checks before volume orders, so carmakers will qualify second sources early. The changing economics of demand will move margin toward fused inertial modules for assisted driving. The USA leads the profiled countries with a 14.2% CAGR, as driver-assistance programmes add inertial points on top of mandated stability sensing.
Key Market Trends & Insights
- Sensor type: accelerometers led with nearly 35% of 2026 sales, ahead of pressure sensors and gyroscopes.
- Distribution channel: OEM fitment led with roughly 86.5% (estimated) in 2026 on the strength of safety mandates in new vehicles.
- Application: powertrain held around 31% in 2026. TDK said temperature and pressure sensor sales rose in automotive in the quarter to June 2026.[2]
Regional Highlights
- The USA posts the fastest profiled CAGR, 14.2% from 2026 to 2036.
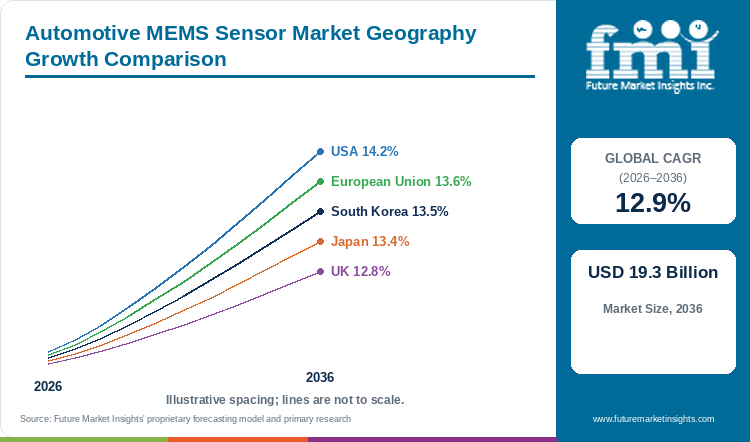
- The European Union posts a 13.6% CAGR over the same years, South Korea 13.5% and Japan 13.4%, and the UK records the lowest CAGR, 12.8%.
- From 7 July 2026, EU rules required automatic emergency braking on new vehicles to detect cyclists and pedestrians.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive MEMS Sensor Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 5.1 billion |
| Estimated Market Size in 2026 | USD 5.8 billion |
| Projected Market Size by 2036 | USD 19.3 billion |
| CAGR, 2026 to 2036 | 12.9% |
| Added Revenue, 2026 to 2036 | USD 13.5 billion |
| Market Expansion Multiple | 3.3x |
Sensor Content per Vehicle and Chip Supply
Automotive sensing is among the segments attracting greater investment, and chip makers reported rising automotive sales through mid-2026. NXP posted Q2 2026 automotive revenue of $1,938 million, up 12% on the year.[4] STMicroelectronics reported second-quarter net revenues of $3,487 million, up 26.0%, with growth led by CECP and Automotive.[5] ST also paid $895 million in the first half for the acquired MEMS sensor business.[5] Infineon closed the purchase of a non-optical analog and mixed-signal sensor portfolio from ams OSRAM on 1 July 2026.[6] The portfolio carries an annualised revenue run rate of about €230 million.[6] EU safety rule changes add sensing load per car. EU General Safety Regulation steps from 7 July 2026 brought attention monitoring and wider emergency braking to all new vehicles.[3] Supply will tighten around groups with safety-qualified MEMS lines, and FMI data show Bosch, ST and Infineon holding the three largest shares.
Table 2: Sensor Content and Semiconductor Supply Indicators for the Automotive MEMS Sensor Market (USD, EUR, yen and percentage), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| ST purchase of NXP MEMS sensors business | Completed 2 February 2026 | Safety-grade MEMS output moves into one supplier. | [1] |
| Expected contribution to ST Q1 2026 revenue | Mid-forties million dollars range | Scale of the acquired sensor line. | [1] |
| ST cash outflow for MEMS acquisition, H1 2026 | $895 million | Capital committed to automotive sensing. | [5] |
| ST AM&S revenue, Q2 2026 | $1,426 million, up 26.0% | MEMS forms part of the faster-growing group. | [5] |
| NXP automotive revenue, Q2 2026 | $1,938 million, up 12% | Automotive chip demand recovered in 2026. | [4] |
| Infineon sensor portfolio from ams OSRAM | About €230 million run rate, closed 1 July 2026 | Sensor capacity consolidates in Europe. | [6] |
| TDK Sensor Application Products, Q1 FY3/27 | ¥61.9 billion, up 33.3% | Pressure and temperature sensor sales to automotive rose. | [2] |
| EU GSR2 step, 7 July 2026 | Attention monitoring and wider AEB on new vehicles | Mandates raise sensor count per car. | [3] |
Analyst Perspective
“Fused inertial modules for assisted driving will, in my view, become the most valuable MEMS opportunity in a vehicle by the early 2030s. Suppliers that secure safety-qualified wafer capacity now will take the design slots that carmakers award for the 2028 to 2030 platform cycle.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Automotive MEMS Sensor Market segmented?
Three axes plus region frame the split. Accelerometers take nearly 35% of sensor type sales in 2026, powertrain claims around 31% of applications, and OEM fitment forms the larger channel.
By sensor type: accelerometer, pressure sensor, gyroscope, and others.
By distribution channel: OEM and aftermarket.
By application: classic and safety, body electronics, powertrain, infotainment, and others.
By region: Asia Pacific and Europe, then the Middle East and Africa, North America and Latin America.
Why do accelerometers lead sensor type sales?
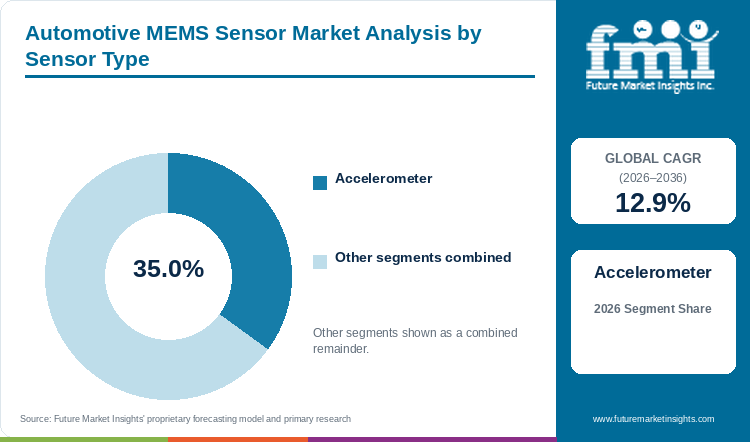
Accelerometers account for nearly 35% of sensor type sales in 2026, with pressure sensors and gyroscopes next.
Table 3: Sensor Type Share for the Automotive MEMS Sensor Market (percentage share), 2026
| Sensor Type | Estimated Share (2026) |
|---|---|
| Accelerometer | 35% |
| Pressure Sensor | 28.5% |
| Gyroscope | 22% |
| Others | 14.5% |
| Total | 100.0% |
Table 4: Sensor Type Leadership and Market Growth for the Automotive MEMS Sensor Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 12.9% |
| Leading Segment | Accelerometer |
Every airbag controller and stability system reads acceleration, so the accelerometer appears in nearly all new vehicles. According to FMI, accelerometers take nearly 35% of sensor type sales. Pressure sensors follow at an estimated 28.5%, gyroscopes at about 22% and other sensors at 14.5% (estimated). Gyroscopes will gain as lane keeping and route guidance need yaw data. The automotive airbag market will keep accelerometer volume steady, and inertial modules for assisted driving will add higher-value units.
- Pressure sensors serve tyre monitoring, braking and engine control.
- ST described the acquired NXP business as covering automotive safety and non-safety products.[1]
Why does OEM fitment lead distribution channel sales?
OEM channels carry an estimated 86.5% of 2026 sales, and the aftermarket the remaining smaller part.
Table 5: Distribution Channel Share for the Automotive MEMS Sensor Market (percentage share), 2026
| Distribution Channel | Estimated Share (2026) |
|---|---|
| OEM | 86.5% |
| Aftermarket | 13.5% |
| Total | 100.0% |
Safety sensors are designed into a vehicle years before launch and fitted on the assembly line. OEM fitment holds about 86.5% (estimated) of channel sales. Aftermarket demand forms an estimated 13.5%, mostly tyre pressure and replacement parts. FMI ties factory-fitted volume to safety mandates. Korean factories raised car output 11.3% to 352,000 units in July 2026, Ministry of Trade, Industry and Resources data show.[7] OEM fitment will keep the lead over the 13.5% aftermarket share, and replacement tyre pressure sensor sales will follow the ageing car fleet.
- Aftermarket buyers replace tyre pressure sensors at tyre change.
- Carmakers qualify MEMS parts per platform, which locks in suppliers for years.
Why does powertrain lead application sales?
Around 31% of 2026 application sales go to powertrain, with classic and safety uses second.
Table 6: Application Share for the Automotive MEMS Sensor Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Powertrain | 31% |
| Classic & Safety | 29.5% |
| Body Electronics | 18% |
| Infotainment | 12% |
| Others | 9.5% |
| Total | 100.0% |
TDK reported higher sales of temperature and pressure sensors to automotive in the quarter to June 2026.[2] Pressure and flow points in engines, transmissions and battery packs make powertrain the largest application. Powertrain holds around 31% as FMI reports. Classic and safety uses take an estimated 29.5%. Body electronics hold about 18%, infotainment 12% (estimated) and others an estimated 9.5%. Battery thermal and pressure monitoring will keep powertrain ahead of classic and safety uses as electric models gain share.
- Classic and safety uses gain from the July 2026 EU emergency braking and attention rules.
- The automotive pressure sensor market covers much of the powertrain sensing base.
What are the drivers, restraints, and opportunities in the Automotive MEMS Sensor Market?
Adoption of automotive MEMS sensors grows with driver assistance, vehicle electrification and safety regulation. Key challenges faced by manufacturers include high production costs, long safety certification and calibration stability in harsh conditions.
- Driver: EU GSR 2 mandates and electric platforms add sensors to each vehicle.
- Restraint: Certification under ISO 26262 and UNECE rules lengthens programme timelines.
- Opportunity: Fused inertial and pressure modules for assisted driving and battery packs.
Safety Mandates Raise the Sensor Count
EU regulators keep adding mandatory safety systems. Under GSR 2, all new vehicles from 7 July 2026 needed driver attention monitoring and emergency braking that detects cyclists and pedestrians.[3] Small-series vehicles of fewer than 1,500 a year had to carry the equipment that large-series models have needed since 2024.[3] Each mandated system needs inertial or pressure input for braking and stability control, and sensor content per car will rise with every GSR step.
Long Certification Cycles and Cost Pressure
ISO 26262 and UNECE rules lengthen the path from sample to series supply. Key challenges faced by manufacturers include certification time and price pressure. UK vehicle production fell 7.5% to 385,979 units in the first half of 2026, SMMT figures show.[8] Lower UK output will cut volume for suppliers with fixed fab costs. Single-axis accelerometers and basic pressure parts will face yearly price cuts from carmakers.
Sensor Fusion Opens a Higher-Value Tier
Infineon CEO Jochen Hanebeck said in August 2026 that automotive orders were picking up noticeably.[6] Sales potential is expected to emerge from modules that combine accelerometers, gyroscopes and pressure sensing with on-chip processing. Software-defined vehicles will need cleaner motion data for driver assistance. The automotive electronics market will carry the control units that read fused sensor modules.
Which country CAGRs are profiled in the Automotive MEMS Sensor Market?
Table 7: Country CAGR Comparison for the Automotive MEMS Sensor Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| USA | 14.2% |
| European Union | 13.6% |
| South Korea | 13.5% |
| Japan | 13.4% |
| UK | 12.8% |
How do country-level CAGRs compare in the Automotive MEMS Sensor Market?
Four of five profiled markets beat the 12.9% global CAGR for 2026 to 2036 in the FMI country table. The USA tops the list with a 14.2% CAGR from 2026 to 2036. The European Union, South Korea and Japan form a tight group with CAGRs between 13.4% and 13.6%. The UK posts a 12.8% CAGR, just under the global figure, so sensor suppliers will chase US design slots before UK ones.
- USA growth rides on ADAS, electric and autonomous programmes.
- The European Union adds safety mandates to premium electronics demand.
- South Korea combines carmaker volume with chip strength.
- Japan builds on sensor miniaturisation and electronics depth.
- The UK leans on luxury carmakers and autonomous vehicle trials.
Full report country CAGRs cover: five regions, from Asia Pacific and Europe to the two American blocks and the Middle East and Africa.
Country-wise Analysis
USA Automotive MEMS Sensor Market Outlook (2026 to 2036)
With a 14.2% CAGR from 2026 to 2036, the USA is the fastest of the profiled markets. Stability control and tyre pressure monitoring mandates set a high floor for sensor content. ADAS and electric vehicle programmes will add inertial and pressure points on top of the mandated stability and tyre pressure sensors. Autonomous driving trials will need high-grade gyroscopes. Domestic chip supply will become a sourcing factor for US carmakers.
Key takeaway: Mandated safety systems give the USA a high content floor, and autonomy work will add premium inertial units on top.
European Union Automotive MEMS Sensor Market Outlook (2026 to 2036)
EU rules from 7 July 2026 made attention monitoring and pedestrian-detecting emergency braking standard on all new vehicles.[3] The GSR 2 step raises the safety sensor load on every new EU model. Germany, France and Italy lead regional demand. European chip supply is close by, with ST and Infineon both adding sensor assets in 2026.[1][6] The EU posts a 13.6% CAGR from 2026 to 2036.
Key takeaway: GSR 2 rules and nearby ST and Infineon plants give EU carmakers short sourcing lines for safety sensors.
South Korea Automotive MEMS Sensor Market Outlook (2026 to 2036)
Korean auto exports reached $6.24 billion in July 2026, a July record, up 7%.[7] Eco-friendly vehicle exports rose 25.5% to $2.59 billion.[7] Hyundai and Kia drive the smart vehicle push, and local chip makers add supply depth. South Korea records a 13.5% CAGR from 2026 to 2036. Battery monitoring in export EVs will add pressure and thermal sensors.
Key takeaway: Export-led EV output makes South Korea a volume market for battery and safety sensing.
Japan Automotive MEMS Sensor Market Outlook (2026 to 2036)
Japan posts a 13.4% CAGR from 2026 to 2036 on electronics depth and sensor miniaturisation. TDK reported Sensor Application Products sales of ¥61.9 billion for Q1 FY3/27, up 33.3%.[2] The company said demand in the automotive market remained brisk.[2] TDK and Murata will keep a strong position in pressure and magnetic sensing for Japanese hybrids.
Key takeaway: Japanese sensor makers enter the decade with rising automotive sales and a deep electronics base.
UK Automotive MEMS Sensor Market Outlook (2026 to 2036)
UK factories built 385,979 vehicles between January and June 2026, down 7.5%.[8] Electrified cars made up around four in ten cars built.[8] Luxury and performance carmakers buy high-grade inertial sensors for stability and handling. UK autonomous vehicle investment will add trial demand for high-grade gyroscopes. The UK posts a 12.8% CAGR from 2026 to 2036, the slowest of the five.
Key takeaway: Lower UK output caps volume, and premium brands will keep sensor value per car high.
Who are the notable companies in the Automotive MEMS Sensor Market?
Robert Bosch GmbH, STMicroelectronics, Infineon Technologies AG, Texas Instruments Inc., NXP Semiconductors, TDK (InvenSense), Murata Manufacturing, Analog Devices, Sensata Technologies and onsemi supply automotive MEMS sensors.
Supply is concentrated among Bosch, STMicroelectronics, Infineon, Texas Instruments and NXP. FMI assigns Robert Bosch 18% to 22% of sales and STMicroelectronics 14% to 18%. Infineon holds 12% to 16%, Texas Instruments 8% to 12% and NXP 5% to 9%. Other players, including TDK, Murata, Analog Devices, Sensata and onsemi, take 35% to 45% combined.
Portfolio moves by ST and Infineon in 2026 point to a widening gap between market leaders and followers. NXP sold the MEMS sensors business to ST, which closed the deal on 2 February 2026.[1] Infineon added an ams OSRAM sensor portfolio on 1 July 2026.[6] TDK returned the MEMS sensor line to profit in the June 2026 quarter on higher motion sensor sales to ICT and industrial equipment.[2]
- Share-ranked leaders: Robert Bosch GmbH, STMicroelectronics, Infineon Technologies AG, Texas Instruments Inc. and NXP Semiconductors.
- Other key players: TDK (InvenSense), Murata Manufacturing, Analog Devices, Sensata Technologies and onsemi.
Competitive Benchmarking: Automotive MEMS Sensor Market
Table 8: Competitive Benchmarking for the Automotive MEMS Sensor Market (qualitative ratings), 2026
| Company | Sensor Portfolio Moves | Automotive Results Detail | Capacity Detail |
|---|---|---|---|
| STMicroelectronics | High | High | High |
| Infineon Technologies AG | High | Medium | Low |
| NXP Semiconductors | Medium | High | Low |
| TDK (InvenSense) | Low | High | Low |
Key Developments in the Automotive MEMS Sensor Market
- In February 2026, STMicroelectronics completed its acquisition of NXP Semiconductors’ MEMS sensors business for USD 950 million. The acquired portfolio, focused on automotive safety and non-safety sensors and industrial applications, is expected to contribute approximately USD 45 million to ST’s Q1 2026 revenue and moves ST from sixth to third place among global MEMS manufacturers [1].
- In July 2026, Infineon Technologies AG completed its acquisition of the non-optical analog and mixed-signal sensor portfolio from ams OSRAM Group for €570 million. The deal, announced in February 2026 and granted full regulatory clearance, adds approximately 230 employees and around €230 million in annual revenue, strengthening Infineon’s position across automotive, industrial, and medical sensing markets [2].
- In November 2026, STMicroelectronics introduced a set of automotive safety combination sensors for mass-market deployment, the first product launch following its NXP MEMS acquisition. The devices address crash protection, rollover detection, airbag deployment, and vehicle stability across vehicle categories from premium to mass-market, with a 15-year product availability commitment for automotive manufacturers [3].
Key Players in the Automotive MEMS Sensor Market
Share-Ranked Leaders
- Robert Bosch GmbH
- STMicroelectronics
- Infineon Technologies AG
- Texas Instruments Inc.
- NXP Semiconductors
Other Key Players
- TDK (InvenSense)
- Murata Manufacturing
- Analog Devices
- Sensata Technologies
- onsemi
Automotive MEMS Sensor Market - Report Scope
Table 9: Report Scope for the Automotive MEMS Sensor Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Sensor type; distribution channel; application; region |
| Quantitative units | USD billion |
| Market definition | MEMS accelerometers, pressure sensors, gyroscopes and other MEMS sensors used in vehicles across safety, powertrain, body electronics and infotainment functions, sold to carmakers and the aftermarket. |
| Regions covered | North America; Latin America; Europe; Asia Pacific; Middle East and Africa |
| Countries covered | USA; European Union; South Korea; Japan; UK |
| Key companies profiled | Robert Bosch GmbH, STMicroelectronics, Infineon Technologies AG, Texas Instruments Inc., NXP Semiconductors, TDK (InvenSense), Murata Manufacturing, Analog Devices, Sensata Technologies, onsemi |
| Forecast period | 2026 to 2036 |
Automotive MEMS Sensor Market - Research Methodology
Table 10: Research Methodology for the Automotive MEMS Sensor Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Chip maker filings, quarterly results, government safety notices and trade press dated May 2025 or later. |
| Desk Research | Coverage spans sensor acquisitions, automotive chip results, vehicle output and safety rule steps. |
| Market Sizing and Forecasting | The forecast builds on the 2025 base of USD 5.1 billion and the 12.9% CAGR for 2026 to 2036. |
| Data Validation | Revenue and output figures were matched to the issuing company or ministry for the same quarter. |
Automotive MEMS Sensor Market by Segments
Automotive MEMS Sensor Market segmented by Sensor Type:
- Accelerometer
- Pressure Sensor
- Gyroscope
- Others
Automotive MEMS Sensor Market segmented by Distribution Channel:
- OEM
- Aftermarket
Automotive MEMS Sensor Market segmented by Application:
- Classic & Safety
- Body Electronics
- Powertrain
- Infotainment
- Others
Automotive MEMS Sensor Market by Region
- North America
- Latin America
- Europe
- Asia Pacific
- Middle East and Africa
Research Sources and Bibliography
- [1] STMicroelectronics Official Press Announcement, February 2, 2026
- [2] Infineon Technologies AG Official Press Release, July 1, 2026
- [3] STMicroelectronics Official Product Launch Announcement, November 2, 2026
- [4] NXP Semiconductors N.V. (2026, July 28). NXP Semiconductors reports second quarter 2026 results. https://mfn.se/all/a/nxp-semiconductors/nxp-semiconductors-reports-second-quarter-2026-results-5d29ebc9
- [5] STMicroelectronics N.V. (2026, July 30). Report on Form 6-K, second quarter 2026. https://www.sec.gov/Archives/edgar/data/0000932787/000093278726000058/stm-6k_q2x2026.htm
- [6] Infineon Technologies AG. (2026, August 5). Infineon Technologies AG Q3 FY 2026 concluded with record sales driven by strong AI business. https://www.placera.se/pressmeddelanden/infineon-technologies-infineon-technolgies-ag-q3-fy-2026-concluded-with-record-sales-driven-by-strong-ai-business-further-significant-increase-in-revenue-and-margin-expected-in-q4-fy-2026-20260805
- [7] The Korea Times. (2026, August 13). Auto exports set new record, rising 7% in July. https://www.koreatimes.co.kr/economy/20260813/auto-exports-set-new-record-rising-7-in-july
- [8] The Manufacturer. (2026, July 30). Vehicle output stabilises but investment at risk without urgent action. https://www.themanufacturer.com/articles/vehicle-output-stabilises-but-investment-at-risk-without-urgent-action/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will automotive MEMS sensor sales total in 2026 and 2036?
- What CAGR will the market record from 2026 to 2036?
- Which sensor type will hold the largest share?
- Which application will carry the most sensor volume?
- Which countries will grow faster than the global rate?
- Which suppliers will control MEMS supply through 2036?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Sensor Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sensor Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sensor Type, 2026 to 2036
- Accelerometer
- Pressure Sensor
- Gyroscope
- Others
- Y-o-Y Growth Trend Analysis By Sensor Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Sensor Type, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- OEM
- Aftermarket
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Classic & Safety
- Body Electronics
- Powertrain
- Infotainment
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sensor Type
- By Distribution Channel
- By Application
- Market Attractiveness Analysis
- By Country
- By Sensor Type
- By Distribution Channel
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sensor Type
- By Distribution Channel
- By Application
- Market Attractiveness Analysis
- By Country
- By Sensor Type
- By Distribution Channel
- By Application
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Asia Pacific
- By Sensor Type
- By Distribution Channel
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Sensor Type
- By Distribution Channel
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sensor Type
- By Distribution Channel
- By Application
- Market Attractiveness Analysis
- By Country
- By Sensor Type
- By Distribution Channel
- By Application
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Type
- By Distribution Channel
- By Application
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Type
- By Distribution Channel
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Type
- By Distribution Channel
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Type
- By Distribution Channel
- By Application
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Type
- By Distribution Channel
- By Application
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Sensor Type
- By Distribution Channel
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- STMicroelectronics
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Infineon Technologies AG
- NXP Semiconductors
- TDK (InvenSense)
- Robert Bosch GmbH
- Texas Instruments Inc.
- Murata Manufacturing
- Analog Devices
- Sensata Technologies
- onsemi
- STMicroelectronics
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Sensor Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Sensor Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Sensor Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 13: Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Europe Market Value (USD Billion) Forecast by Sensor Type, 2021 to 2036
- Table 15: Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 16: Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 17: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Middle East and Africa Market Value (USD Billion) Forecast by Sensor Type, 2021 to 2036
- Table 19: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 20: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Sensor Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Sensor Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Sensor Type
- Figure 6: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Distribution Channel
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Sensor Type, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Sensor Type, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Sensor Type
- Figure 23: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Distribution Channel
- Figure 26: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Application
- Figure 29: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 30: Latin America Market Value Share and BPS Analysis by Sensor Type, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by Sensor Type, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by Sensor Type
- Figure 33: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 36: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Application
- Figure 39: Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 40: Europe Market Value Share and BPS Analysis by Sensor Type, 2026 and 2036
- Figure 41: Europe Market Y-o-Y Growth Comparison by Sensor Type, 2026-2036
- Figure 42: Europe Market Attractiveness Analysis by Sensor Type
- Figure 43: Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 44: Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 45: Europe Market Attractiveness Analysis by Distribution Channel
- Figure 46: Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 47: Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 48: Europe Market Attractiveness Analysis by Application
- Figure 49: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 50: Middle East and Africa Market Value Share and BPS Analysis by Sensor Type, 2026 and 2036
- Figure 51: Middle East and Africa Market Y-o-Y Growth Comparison by Sensor Type, 2026-2036
- Figure 52: Middle East and Africa Market Attractiveness Analysis by Sensor Type
- Figure 53: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 54: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 55: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 56: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 57: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 58: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 59: Global Market - Tier Structure Analysis
- Figure 60: Global Market - Company Share Analysis
Frequently Asked Questions
What is the size of the Automotive MEMS Sensor Market in 2026?
By FMI projections, 2026 will close with USD 5.8 billion in sales, and 2036 with USD 19.3 billion. At what rate will the automotive MEMS sensor market grow? Safety mandates and electric platforms will carry a 12.9% CAGR from 2026 to 2036.
Which sensor type will lead?
Accelerometers will take nearly 35% of sensor type sales in 2026, ahead of pressure sensors and gyroscopes.
Which application will carry the largest share?
Powertrain will account for around 31% of application sales in 2026, per FMI.
Which country will grow fastest?
Fastest growth will come from the USA, on a 14.2% CAGR from 2026 to 2036, top among the five profiled markets.
Which companies will hold the largest shares?
Bosch will hold 18% to 22% of sales, with STMicroelectronics at 14% to 18% and Infineon at 12% to 16%.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
