
- Market Size (2026)
- USD 39641.4 Mn
- Forecast (2036)
- USD 58117.1 Mn
- CAGR (2026 to 2036)
- 3.9%
How big is Automotive OEM Market in 2026?
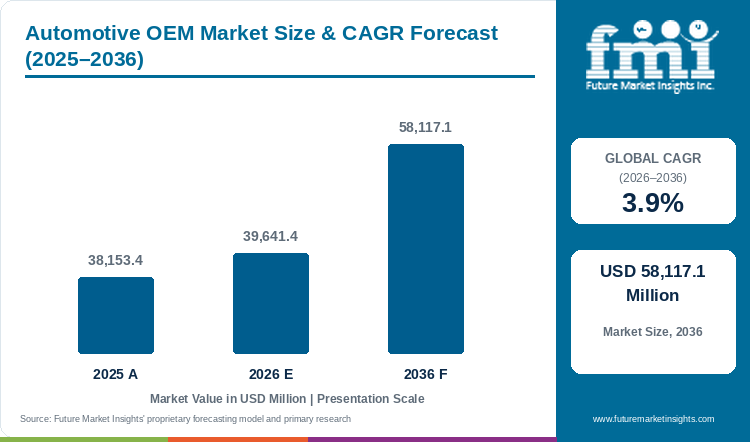
The automotive OEM market is estimated at USD 38.2 billion in 2025 and is likely to reach USD 39.6 billion in 2026. The market is predicted to grow at a 3.9% CAGR and reach USD 58.1 billion by 2036.
Automotive OEM market size is estimated at USD 38.2 billion in 2025, and FMI's numbers show sales likely to reach USD 39.6 billion in 2026. A 3.9% CAGR is forecast after that, with USD 58.1 billion expected by 2036. New-vehicle volumes are flat at several large carmakers, so genuine parts sold through dealer and distributor networks are turning into a steadier income line. Higher global sales and favourable exchange rates gave the Hyundai Mobis after-sales parts business a solid June quarter, and group operating profit grew 12.1% to KRW 975.2 billion, the company said on 24 July 2026.[1] Carmakers will defend genuine-part pricing and widen catalogue coverage for older models.
Of Porter's five forces for genuine parts, the threat of substitutes ranks first, because independent brands copy filters, brake parts and body panels for any garage outside the dealer network. A U.S. proclamation of 17 October 2025 set the parts tariff offset for carmakers assembling in the United States at 3.75% of the aggregate MSRP of those cars through 30 April 2030.[2] Carmakers with American assembly recover part of the parts duty, and independent importers of copy parts get no such offset. Buyer power ranks second, as fleet operators and large dealer groups buy in bulk and negotiate price per part number.
Key Market Trends & Insights
- Engines and gearboxes wear on a schedule, which gives powertrain parts an expected 32.8% of component sales in 2026, about 11 points more than chassis parts. Ford set a target of taking USD 1 billion of warranty and material costs out of the business in 2026.[3]
- The car parc gives passenger cars a projected 47.5% of vehicle type sales in 2026, and commercial vehicles and electric cars split the rest at 34.2% and 18.3%.
- Same-day delivery to workshops is expected to keep 41.6% of channel sales with distributor networks in 2026, and wholesalers handle about one third. Hyundai Mobis tied after-sales parts gains in Q2 2026 to higher global sales.[1]
Regional Highlights
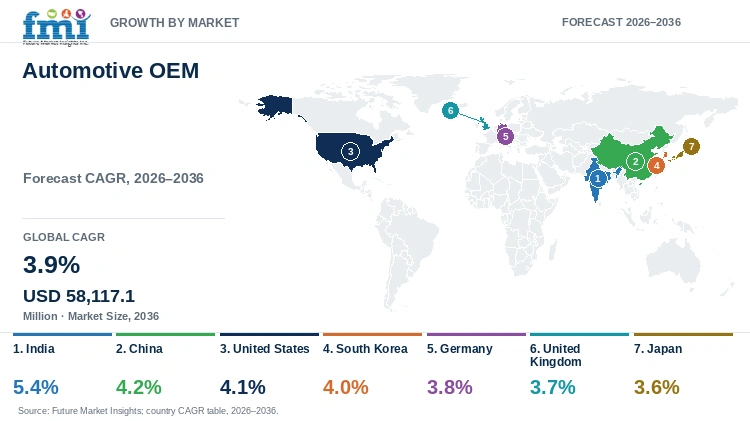
- Cars sold in the current Indian boom will come due for paid service, so India leads the seven at a 5.4% CAGR, 1.5 points over the global figure.
- Per FMI's country model, China, the United States and South Korea grow just above the global figure, at 4% to 4.2%. Germany and the United Kingdom fall just short of the global figure at 3.8% and 3.7%, and Japan is last in the country ranking at 3.6%.
- SMMT reported in April 2026 that the British car parc grew 1.4% to 36,676,185 during 2025 and the average age of a car reached 9.7 years.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive OEM Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 38,153.4 million |
| Estimated Market Size in 2026 | USD 39,641.4 million |
| Projected Market Size by 2036 | USD 58,117.1 million |
| CAGR, 2026 to 2036 | 3.9% |
| Added Revenue, 2026 to 2036 | USD 18,475.8 million |
| Market Expansion Multiple | 1.5x |
Genuine part orders follow the size and age of the car parc, because a part is bought when a car on the road wears out or is damaged. SMMT counted 36,676,185 cars in use in the United Kingdom in 2025, up 1.4%, with the average age up to 9.7 years from 9.5.[4] Older cars need more brake, suspension and cooling parts each year, and collision repair adds body work, with the OEM-approved collision repair adhesive systems market likely to expand at a 5.4% CAGR, 1.5 points faster than OEM parts, so body shops will order more OEM panels bonded to carmaker specification. In FMI's projection, the 2036 parts total is expected to exceed the 2026 figure by USD 18,475.8 million, close to half again the starting size. Tariff costs are the main risk, as Stellantis now estimates a full-year net tariff headwind of EUR 1.0 to 1.2 billion for 2026.[5]
Ageing Car Parcs, Tariffs and Electric Parts Catalogues
Tariffs are changing the plants that make genuine parts for American buyers. After a EUR 0.4 billion refund related to IEEPA tariffs, net tariff costs at Stellantis came to EUR 0.3 billion over January to June 2026.[5] The 3.75% MSRP offset for cars assembled in the United States runs from 5 April 2025 to 30 April 2030.[2] Carmakers will move more fast-moving service parts into North American plants to use the offset, and distributors will see fewer price increases on locally made items.
Electric models are adding new part numbers to carmaker catalogues, and FMI analysts expect that shift to show in parts sales once early electric cars leave warranty. Volkswagen Group said battery electric cars now make up over 30% of the European order bank, which rose by over 50%, and the Electric Urban Car Family received over 70,000 orders.[6] Electric cars carry fewer engine parts and more thermal, high-voltage and electronic parts, and sales in the battery electric vehicle (BEV) market are forecast to rise at a 15% CAGR, so electronics and electrical parts will gain share inside the OEM parts mix. Distributors will need trained staff and safe storage for high-voltage parts.
Table 2: Car Parc, Tariff and Electrification Indicators for the Automotive OEM Market (values, dates and growth), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| UK cars in use, 2025 | 36,676,185; average age 9.7 years | Older cars need more replacement parts. | [4] |
| U.S. auto parts offset | 3.75% of MSRP; to 30 April 2030 | Local assembly reduces parts duty. | [2] |
| Stellantis net tariff headwind, 2026 | EUR 1.0 to 1.2 billion | Imported parts cost more to land. | [5] |
| Hyundai Mobis operating profit, Q2 2026 | KRW 975.2 billion; up 12.1% | After-sales parts income is rising. | [1] |
| Volkswagen Group BEV order bank, Europe | Up over 50%; over 30% of orders | New electric part numbers enter catalogues. | [6] |
| Tata Motors domestic EV sales, Q1 FY27 | Up 112% to over 34,000 | Electric parts demand starts early in India. | [7] |
Analyst Perspective
“My highest-return bet is genuine parts for cars aged eight to twelve years, the age at which warranty ends and owners start choosing between dealer and independent garages. British cars now average 9.7 years, and carmakers pricing a second-line genuine range for that age band will keep owners inside the network. Dealer groups and distributors should stock those ranges first, ahead of premium accessories.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the automotive OEM market segmented?
The market is segmented into component, vehicle type, distribution channel, and region. Powertrain parts are expected to lead components with 32.8% share in 2026, and passenger cars lead vehicle types at 47.5%.
By component: powertrain, chassis, electronics and electrical, external body, and car interiors.
By vehicle type: passenger cars, commercial vehicles, and electric cars.
By distribution channel: retailers, wholesalers, and distributors.
By region: North America, Western Europe, East Asia, Latin America, Eastern Europe, South Asia and Pacific, and Middle East and Africa.
Why do powertrain parts lead the automotive OEM market by component?
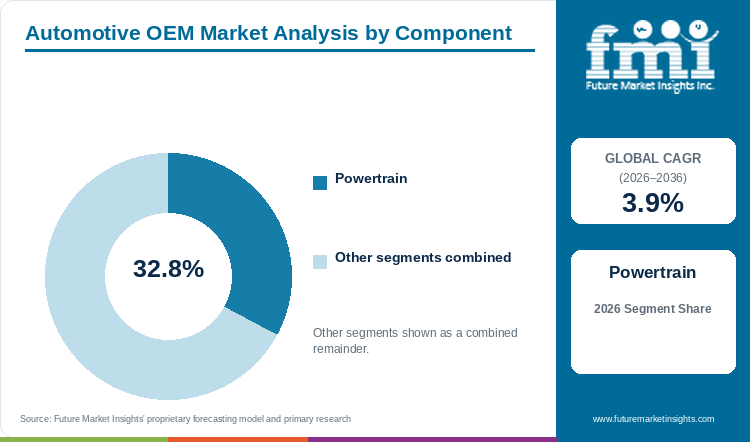
Powertrain parts are expected to lead component sales with 32.8% share in 2026, ahead of chassis at about 21.4%, electronics and electrical at about 19.6%, external body at about 14.3% and car interiors at about 11.9%.
Table 3: Component Share for the Automotive OEM Market (percentage share), 2026
| Component | Estimated Share (2026) |
|---|---|
| Powertrain | 32.8% |
| Chassis | 21.4% |
| Electronics and Electrical | 19.6% |
| External Body | 14.3% |
| Car Interiors | 11.9% |
| Total | 100.0% |
Table 4: Component Leadership and Market Growth for the Automotive OEM Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.9% |
| Leading Segment | Powertrain |
Engines and gearboxes, with the filters, pumps and belts fitted to them, wear on a schedule and carry the highest genuine-part price per service, so powertrain is expected to lead component sales with 32.8% share in 2026. Chassis parts, an estimated 21.4%, include brakes and suspension and sell in high volume, but independent brands compete hard on pads and shock absorbers. Electronics and electrical parts, about 19.6%, cost more per item but fail less often. External body parts, about 14.3%, sell after collisions, and insurers push repairers toward cheaper certified copies. Panels fitted after a crash also need paint, and the automotive refinish coatings market is predicted to increase at a 5.3% CAGR, a pace that keeps body-shop volume rising. Car interiors, near 11.9%, are replaced least often of the five. A dealer or distributor building stock will start with powertrain service parts, since every scheduled service needs them.
- Filters, timing belts, water pumps, clutch kits and transmission parts.
- Ford targets USD 1 billion of warranty and material cost reductions in 2026, the company said in second-quarter results on 28 July 2026.[3]
Why do passenger cars lead demand for OEM parts by vehicle type?
Passenger cars are expected to lead vehicle type sales with 47.5% share in 2026, with commercial vehicles at an estimated 34.2% and electric cars at about 18.3%.
Table 5: Vehicle Type Share for the Automotive OEM Market (percentage share), 2026
| Vehicle Type | Estimated Share (2026) |
|---|---|
| Passenger Cars | 47.5% |
| Commercial Vehicles | 34.2% |
| Electric Cars | 18.3% |
| Total | 100.0% |
The size of the car parc puts passenger cars first in vehicle type sales, at an expected 47.5% in 2026. Commercial vehicles, estimated at 34.2%, run more kilometres and need parts more often per vehicle, but there are far fewer trucks and vans than cars, and fleet workshops often buy from independent suppliers on contract. Couplings and towing parts wear fastest on tractor units and towed vehicles, and the automotive coupling replacement kit market is likely to grow at a CAGR of 4.3%, slightly faster than genuine parts as a whole. Electric cars, about 18.3%, are mostly young and still under warranty, so few owners buy parts outside the dealer before 2028. Passenger car owners will keep the largest share of parts purchases until electric cars age out of warranty after 2030.
- Hatchbacks, sedans, SUVs and pickups in private and company use.
- The UK car parc grew by more than half a million cars in 2025, and battery electric cars in use rose 34.7% to 1,797,809, SMMT said on 24 April 2026.[4]
Why do distributors lead automotive OEM parts sales by distribution channel?
Distributors are expected to lead channel sales with 41.6% share in 2026, ahead of wholesalers at about 33.1% and retailers at about 25.3%.
Table 6: Distribution Channel Share for the Automotive OEM Market (percentage share), 2026
| Distribution Channel | Estimated Share (2026) |
|---|---|
| Distributors | 41.6% |
| Wholesalers | 33.1% |
| Retailers | 25.3% |
| Total | 100.0% |
Carmakers appoint distributors to hold regional stock and deliver to dealer workshops several times a day, so distributors will lead channel sales in 2026 with 41.6%. Wholesalers, an estimated 33.1%, buy in bulk and resell to independent garages, but carmakers limit wholesale access for safety and electronic parts. Retailers, about 25.3%, sell accessories and fast-moving items to owners, and few owners fit genuine engine or brake parts at home. Recycled-content rules are also changing what distributors stock, and the OEM compliance grade PCR automotive material market is expected to expand at an 11.3% CAGR across the forecast period, so interior and trim parts made with recycled plastics will enter the genuine range. Carmakers will keep distributors at the centre of the network, because same-day delivery decides which garage keeps the job.
- Carmaker parts centres, appointed regional distributors and dealer-group warehouses.
- Hyundai Mobis earned KRW 975.2 billion of operating profit in the June quarter of 2026, 12.1% more than a year earlier, with after-sales parts a main contributor.[1]
What are the drivers, restraints, and opportunities in the automotive OEM market?
Ageing car parcs and longer ownership raise the number of cars needing replacement parts. Tariffs and material costs push genuine-part prices up and give independent brands an opening, and electric models bring new high-voltage and thermal part numbers into carmaker catalogues.
- Driver: Owners keep cars longer, so each car passes through more service visits and wear-part replacements before scrappage.
- Restraint: Tariff and material costs push up genuine-part prices, which sends price-sensitive owners of older cars to independent brands.
- Opportunity: Electric cars leaving warranty will need battery, thermal and high-voltage parts that only carmaker networks can supply at first.
Longer Ownership Raises Parts Demand per Car
Demand for genuine parts rises with the age of the cars on the road. The average car in the United Kingdom was 9.7 years old in 2025, up from 9.5 a year before, and cars in use grew 1.4%.[4] Hyundai Mobis linked the solid April to June result of the after-sales parts business to higher global sales.[1] Carmakers will extend parts catalogues for older models, because owners of cars past warranty are the largest group of parts buyers.
Tariffs and Material Costs Raise Genuine-Part Prices
Genuine-part pricing is held back by tariff costs and supply disruption, and FMI expects both to persist through 2027. Stellantis estimates a 2026 net tariff headwind of EUR 1.0 to 1.2 billion.[5] Ford Pro faced temporary aluminium supply chain disruptions over the spring of 2026, Ford said.[3] Carmakers passing these costs into part prices will lose price-sensitive owners to independent brands, mainly for brakes, filters and body panels.
Electric Cars Bring New Part Numbers
Electric cars leaving warranty will open the next pool of genuine-part sales. Tata Motors reported 112% growth in domestic EV sales to over 34,000 units for April to June 2026, with EV penetration at 19%.[7] Volkswagen Group reported a European BEV order bank up by over 50%.[6] Thermal pumps, chargers and high-voltage cables for these cars will be sold through carmaker networks for several years after launch.
Which country CAGRs are profiled in the automotive OEM market?
Table 7: Country CAGR Comparison for the Automotive OEM Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 5.4% |
| China | 4.2% |
| United States | 4.1% |
| South Korea | 4% |
| Germany | 3.8% |
| United Kingdom | 3.7% |
| Japan | 3.6% |
How do country-level CAGRs compare in the automotive OEM market?
American carmakers can offset part of the auto parts duty against 3.75% of the MSRP of cars assembled in the United States until April 2030.[2] In the FMI country forecast, the 3.9% global CAGR splits the seven markets four to three. Fast domestic car sales put India first at 5.4%, an ageing parc carries China to 4.2%, and tariff-driven local sourcing supports 4.1% in the United States. South Korea, at 4%, relies on export-led parts sales. Flat new-car volumes hold Germany to 3.8%, older British cars move to independent garages, and long service intervals leave Japan at 3.6%.
- Domestic passenger vehicle volumes at Tata Motors were 46% higher in the June 2026 quarter.
- Cars sold in China before 2022 are entering heavy service years.
- Genuine parts made in North American plants avoid most of the tariff cost.
- Hyundai Mobis ships after-sales parts to Hyundai owners in global markets.
- German group Volkswagen delivered 6.3% fewer vehicles over January to June 2026.
- British cars average 9.7 years old.
- Japanese owners service cars at dealers under long inspection cycles.
Full report country CAGRs cover: one South Asia and Pacific market (India), three East Asian markets (China, South Korea, Japan), the United States, and two Western European markets (Germany, the United Kingdom), with Latin America, Eastern Europe and Middle East and Africa shown only as region totals.
Country-wise Analysis
India Automotive OEM Market Outlook (2026 to 2036)
Domestic passenger vehicle sales at Tata Motors grew 64.8% in value and 46% in volume over the quarter to June 2026, with EVs at 19% of the mix.[7] Per FMI's country model, sales of OEM parts in India are expected to rise at a 5.4% CAGR, the best of the seven. Cars sold during the current sales jump will come due for paid services from 2028, and carmakers are expected to add parts depots in tier-two cities.
Key takeaway: Rapid new-car growth today becomes parts demand later, putting India first at 5.4%.
China Automotive OEM Market Outlook (2026 to 2036)
Volkswagen Group sold 31.6% fewer vehicles in China in H1 2026, against a market down by about 20%.[6] Sales of OEM parts in China are projected to increase at a 4.2% CAGR, 0.3 points over the global figure, because the large fleet sold before 2022 is now reaching heavy service years. Foreign brands with shrinking new-car sales will keep earning from parts for cars already on Chinese roads.
Key takeaway: The installed fleet, not new-car sales, drives China at 4.2%.
United States Automotive OEM Market Outlook (2026 to 2036)
North American net revenues at Stellantis grew 32% in Q2 2026, on U.S. sales 6% higher.[5] Importers of parts used for repair in the United States may declare them under either the auto parts or truck parts tariff.[2] FMI places American OEM parts sales at a 4.1% CAGR, a little above the global figure, as carmakers source more service parts from local plants.
Key takeaway: Tariffs favour genuine parts made in North America, keeping the United States at 4.1%.
South Korea Automotive OEM Market Outlook (2026 to 2036)
Hyundai Mobis earned KRW 1.7778 trillion of operating profit over the half to June 2026, 8% more than a year earlier, with after-sales parts helped by higher global sales.[1] Demand for OEM parts in South Korea is forecast at a 4% CAGR, level with the global figure after rounding. Korean parts centres ship genuine parts to owners abroad, so exports add to domestic service demand.
Key takeaway: A global after-sales network gives South Korea a 4% CAGR.
Germany Automotive OEM Market Outlook (2026 to 2036)
Volkswagen Group delivered 4.126 million vehicles in the six months to June 2026, 6.3% fewer than a year before, though Western European sales grew 1.3%.[6] Germany is forecast at a 3.8% CAGR, 0.1 points short of the global figure, because flat new-car volumes slow the inflow of cars into the service base.
Key takeaway: Flat new-car volumes hold Germany at 3.8%.
United Kingdom Automotive OEM Market Outlook (2026 to 2036)
British roads carried 36,676,185 cars in 2025, and 1,797,809 of them were battery electric, up 34.7%.[4] Jaguar Land Rover wholesales were 9.2% lower in the quarter to June 2026.[7] OEM parts sales in the United Kingdom are projected to expand at a 3.7% CAGR, as an older parc sends more owners to independent garages.
Key takeaway: Ageing British cars moving to independent garages hold the British rate to 3.7%.
Japan Automotive OEM Market Outlook (2026 to 2036)
Toyota sold 524 thousand vehicles at home over April to June 2026, 8.9% more than a year earlier, against 2,395 thousand on a consolidated basis, 0.7% fewer.[8] Japan, last in the country ranking, is likely to grow at a 3.6% CAGR because owners service cars at dealers on fixed inspection cycles and the car parc is barely growing.
Key takeaway: Stable dealer servicing and a flat parc keep Japanese growth at 3.6%.
Who are the notable companies in the automotive OEM market?
Toyota, Volkswagen Group, Hyundai Motor Company, Hyundai Mobis, General Motors, Ford, Honda, Stellantis, BMW Group, Renault Group and Tata Motors are the profiled companies.
Carmakers and carmaker-owned parts arms compete for every service visit after the warranty ends. After-sales parts helped Hyundai Mobis raise quarterly operating profit 12.1% in July 2026 results.[1] Ford is targeting USD 1 billion of warranty and material cost cuts in 2026 and reported 1.6 million paid customer subscriptions, up 50%.[3] Stellantis grew quarterly net revenues 13% and expects a 2026 net tariff headwind of EUR 1.0 to 1.2 billion.[5] Toyota, Volkswagen Group, General Motors, Honda, BMW Group, Renault Group and Tata Motors complete the profiled group.
- Japanese carmakers: Toyota and Honda.
- European carmakers: Volkswagen Group, Stellantis, BMW Group and Renault Group.
- American carmakers: General Motors and Ford.
- Korean and Indian groups: Hyundai Motor Company, Hyundai Mobis and Tata Motors.
Competitive Benchmarking: Automotive OEM Market
Table 8: Competitive Benchmarking for the Automotive OEM Market (qualitative documentation ratings), 2026
| Company | Parts Network | Electric Models | Tariff Disclosure | Recency |
|---|---|---|---|---|
| Hyundai Mobis | High | Medium | Low | High |
| Stellantis | Medium | Medium | High | High |
| Ford | Medium | Medium | Medium | High |
| Volkswagen Group | Medium | High | Medium | High |
| Toyota | High | Medium | Low | High |
More recent releases and filings on an attribute mean a higher grade, and no grade signals share of parts sales.
Key Developments in the Automotive OEM Market
- Tata Motors announced on 13 August 2026 a 112% rise in domestic EV sales for the June quarter.[7]
- On 4 August 2026, Toyota published first-quarter FY2027 results with consolidated vehicle sales of 2,395 thousand units.[8]
- On 30 July 2026, Stellantis put the 2026 net tariff headwind at EUR 1.0 to 1.2 billion.[5]
- On 28 July 2026, Ford raised the full-year adjusted EBIT outlook to USD 10 to 11 billion.[3]
- On 24 July 2026, Hyundai Mobis reported second-quarter operating profit of KRW 975.2 billion.[1]
- On 24 July 2026, Volkswagen Group reported first-half deliveries of 4.126 million vehicles, down 6.3%.[6]
- On 24 April 2026, SMMT reported a record 42,549,649 vehicles on UK roads.[4]
- On 17 October 2025, a U.S. presidential proclamation revised the auto parts tariff offset through April 2030.[2]
Key Players in the Automotive OEM Market
Japanese Carmakers
- Toyota
- Honda
European Carmakers
- Volkswagen Group
- Stellantis
- BMW Group
- Renault Group
American Carmakers
- General Motors
- Ford
Korean and Indian Groups
- Hyundai Motor Company
- Hyundai Mobis
- Tata Motors
Automotive OEM Market - Report Scope
Table 9: Report Scope for the Automotive OEM Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Component; vehicle type; distribution channel; region |
| Quantitative units | USD million |
| Market definition | Original-equipment parts sold under carmaker part numbers, covering powertrain, chassis, electronics and electrical, external body and interior components, distributed through distributors, wholesalers and retailers. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Toyota, Volkswagen Group, Hyundai Motor Company, Hyundai Mobis, General Motors, Ford, Honda, Stellantis, BMW Group, Renault Group, Tata Motors |
| Forecast period | 2026 to 2036 |
Automotive OEM Market - Research Methodology
Table 10: Research Methodology for the Automotive OEM Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Carmaker and parts-arm results, U.S. presidential proclamations, industry association data and trade press from May 2025 onward. |
| Desk Research | Desk research covers car parc age, tariff terms, after-sales results and electric order banks. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 38,153.4 million and the 3.9% CAGR for 2026 to 2036. |
| Data Validation | Company figures, tariff dates and parc counts were matched to the company, the White House or the association that published them. |
Automotive OEM Market by Segments
Automotive OEM Market segmented by Component:
- Powertrain
- Chassis
- Electronics and Electrical
- External Body
- Car Interiors
Automotive OEM Market segmented by Vehicle Type:
- Passenger Cars
- Commercial Vehicles
- Electric Cars
Automotive OEM Market segmented by Distribution Channel:
- Retailers
- Wholesalers
- Distributors
Automotive OEM Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Edaily. (2026, July 24). HyundaiMobis Reports Increased 2Q Revenue and Operating Profit, Up 2.4% and 12.1% Year-Over-Year. https://en.edaily.co.kr/news/eda202607245236
- [2] The White House. (2025, October 17). Adjusting Imports of Medium- and Heavy-Duty Vehicles, Medium- and Heavy-Duty Vehicle Parts, and Buses into the United States. https://www.whitehouse.gov/presidential-actions/2025/10/adjusting-imports-of-medium-and-heavy-duty-vehicles-medium-and-heavy-duty-vehicle-parts-and-buses-into-the-united-states/
- [3] Ford Motor Company. (2026, July 28). 4 Things to Know About Ford's Second-Quarter Results. https://www.fromtheroad.ford.com/us/en/articles/2026/ford-reports-second-quarter-2026-financial-results
- [4] Society of Motor Manufacturers and Traders. (2026, April 24). One in 22 vehicles now zero emission as UK fleet reaches record high. https://www.smmt.co.uk/one-in-22-vehicles-now-zero-emission-as-uk-fleet-reaches-record-high/
- [5] Stellantis N.V. (2026, July 30). Stellantis Reports Q2 2026 Financial Results. https://www.media.stellantis.com/em-en/corporate/press/stellantis-reports-q2-2026-financial-results
- [6] Volkswagen Group. (2026, July 24). Volkswagen Group stays on track in challenging environment and expects improved margin in the second half of the year. https://www.volkswagen-group.com/en/press-releases/volkswagen-group-stays-on-track-in-challenging-environment-and-expects-improved-margin-in-the-second-half-of-the-year-20542
- [7] Autocar Professional. (2026, August 13). Tata Motors Passenger Vehicles Q1 FY27 Profit Drops to Rs 859 Crore. https://www.autocarpro.in/news/tata-motors-pv-reports-93-percent-revenue-growth-in-q1-fy27-134080
- [8] Toyota Motor Corporation. (2026, August 4). FY2027 First Quarter Consolidated Financial Results (Form 6-K exhibit). https://www.sec.gov/Archives/edgar/data/0001094517/000119312526331392/d258414dex991.htm
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the automotive OEM market during 2026?
- What market size is projected by 2036?
- Which component holds notable share?
- Which vehicle type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Component, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Component, 2026 to 2036
- Powertrain
- Chassis
- Electronics and Electrical
- External Body
- Car Interiors
- Y-o-Y Growth Trend Analysis By Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Component, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars
- Commercial Vehicles
- Electric Cars
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Retailers
- Wholesalers
- Distributors
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Component
- By Vehicle Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Vehicle Type
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Component
- By Vehicle Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Vehicle Type
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Component
- By Vehicle Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Vehicle Type
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Component
- By Vehicle Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Vehicle Type
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Component
- By Vehicle Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Vehicle Type
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Component
- By Vehicle Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Vehicle Type
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Component
- By Vehicle Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Vehicle Type
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Vehicle Type
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Component
- By Vehicle Type
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Hyundai Mobis
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Stellantis
- Ford
- Volkswagen Group
- Toyota
- Honda
- BMW Group
- Renault Group
- General Motors
- Hyundai Motor Company
- Tata Motors
- Hyundai Mobis
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Component
- Figure 6: Global Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Vehicle Type
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Component
- Figure 26: North America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Vehicle Type
- Figure 29: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Distribution Channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Component
- Figure 36: Latin America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Vehicle Type
- Figure 39: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Component
- Figure 46: Western Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Vehicle Type
- Figure 49: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Component
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Vehicle Type
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Component
- Figure 66: East Asia Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Vehicle Type
- Figure 69: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Component
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Vehicle Type
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Component
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Vehicle Type
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the automotive OEM market expected in 2026?
Sales of OEM-branded parts are estimated at USD 39,641.4 million in 2026, up from USD 38,153.4 million in 2025. FMI projects USD 58,117.1 million by 2036.
What CAGR is projected for the automotive OEM market through 2036?
Parts sales are projected to grow at a 3.9% CAGR over 2026 to 2036. Older car parcs and new electric part numbers carry most of that growth.
Which component holds a notable market share in 2026?
At 32.8% of component sales in 2026, powertrain parts are expected to lead. Chassis parts follow at an estimated 21.4%.
Which vehicle type holds a notable market share in 2026?
With 47.5% of vehicle type sales in 2026, passenger cars are likely to lead. Commercial vehicles account for an estimated 34.2%.
Which country has a notable expansion outlook through 2036?
Indian demand grows fastest of the profiled countries in the FMI forecast, at a 5.4% CAGR. China is next at 4.2%.
Who are the key companies in the automotive OEM market?
Toyota, Volkswagen Group, Hyundai Motor Company, Hyundai Mobis, General Motors, Ford, Honda, Stellantis, BMW Group, Renault Group and Tata Motors are profiled. Hyundai Mobis is the parts affiliate of Hyundai Motor Company.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
