
- Market Size (2026)
- USD 4.9 Bn
- Forecast (2036)
- USD 10.3 Bn
- CAGR (2026 to 2036)
- 7.7%
How big is Battery Electrolytes Market in 2026?
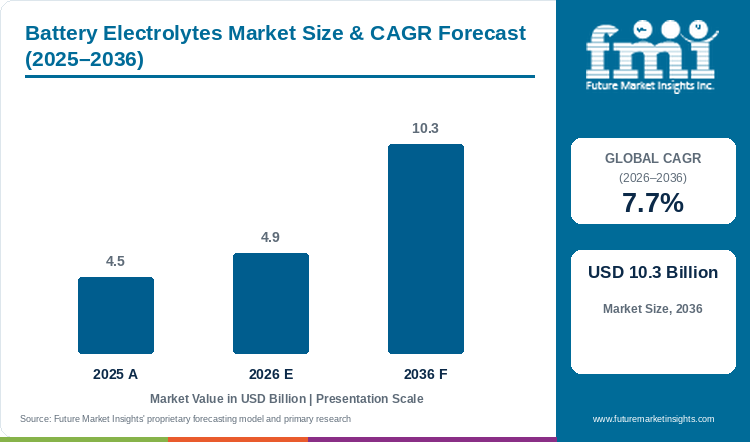
Demand for battery electrolytes is projected to expand at 7.7% CAGR between 2026 and 2036. Industry value grows from USD 4.55 billion in 2025 to USD 4.90 billion in 2026 and is projected to reach USD 10.29 billion by 2036.
The global battery electrolytes market was valued at USD 4.55 billion in 2025 and is projected to grow from USD 4.90 billion in 2026 to USD 10.29 billion by 2036, at 7.7% CAGR from 2026 to 2036. As per FMI, lithium-ion accounted for the leading 92% value share in 2026, as cell output for the lithium-ion battery supply chain continues to scale and lead-acid electrolyte carries comparatively low value per ton. SNE Research reported that electrolyte installed in electric vehicle batteries worldwide reached about 1,475 thousand tons in 2025, a rise of 37.3% over 2024.
The 7.7% value CAGR projected through 2036 is well below that 2025 volume growth rate because falling per-ton electrolyte prices, driven by added capacity and raw material competition, are expected to offset much of the volume gain in value terms. Chinese suppliers held 90.4% of that installed volume in the fourth quarter of 2025, with South Korean firms at 5.8% and Japanese firms at 3.8%. Global electric car sales grew about 20% in 2025 to more than 20 million units, close to one in four new cars sold. Capacity additions outside China and new electrolyte chemistries for high-power and fast-charge cells are expected to shape supplier competition through 2036.
Key Market Trends & Insights
- Lithium-ion held 92% of type demand in 2026 by value. Global electric car sales grew about 20% in 2025 to more than 20 million units, a trend that lifted demand for lithium-ion electrolyte formulations.
- Traction batteries remained the largest electrolyte sink, so automotive accounted for 54% of end use demand in 2026. Electrolyte installed in electric vehicles rose 45.2% year on year to about 616 thousand tons in the first half of 2025.
Regional Highlights
- The fastest profiled-country growth comes from China, at 9% CAGR to 2036.
- South Korea (8.5%) and India (8.4%) follow. Australia and New Zealand record the lowest profiled CAGR at 7.1%.
- In January 2026, Capchem announced a USD 260 million carbonate solvent plant in Saudi Arabia. The company also announced a second phase at the electrolyte plant in Śrem in Poland, adding 50,000 tons a year of capacity.
Market Size & Forecast
Table 1: Market Size and Forecast for the Battery Electrolytes Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4.55 billion |
| Estimated Market Size in 2026 | USD 4.90 billion |
| Projected Market Size by 2036 | USD 10.29 billion |
| CAGR, 2026 to 2036 | 7.7% |
| Added Revenue, 2026 to 2036 | USD 5.39 billion |
| Market Expansion Multiple | 2.1x |
Current demand follows cell manufacturing for vehicles and storage. The International Energy Agency expects global electric car sales of about 23 million in 2026, or 28% of total car sales. Electrolyte makers are building plants close to new cell hubs. Tinci signed an agreement in June 2025 for a facility in Morocco covering 150,000 tons a year of electrolytes and related battery materials, with an investment of approximately USD 282 million (MAD 2.6 billion). Stationary battery energy storage systems add a second demand stream. Australia recorded about 350,000 home battery installations in the first ten months of the Cheaper Home Batteries Program, which began in July 2025.
Slower electric vehicle adoption in some markets has already cancelled electrolyte projects. Enchem dropped a planned Tennessee plant in October 2025 after supply contracts were repeatedly delayed. FMI expects regional localisation and fast-charge chemistries to keep electrolyte demand ahead of the overall battery cycle over the forecast period. The moderate 7.7% CAGR reflects an assumption of continuing per-ton price deflation for formulated electrolyte, which offsets a large share of the faster volume growth seen in 2025 and 2026.
Supply Chain and Capacity Readiness
Volume, concentration and upstream capacity indicators show electrolyte supply concentration and the pace at which new capacity is being added.
Table 2: Supply Chain and Capacity Indicators for the Battery Electrolytes Market (tons, percentage and USD), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Significance | Source |
|---|---|---|---|
| EV battery electrolyte installed, 2025 | About 1,475 thousand tons, up 37.3% year on year | Confirms volume growth in the largest end use | |
| Share of Chinese suppliers in EV electrolyte, Q4 2025 | 90.4% | Shows supplier concentration and localisation risk for other regions | |
| Largest supplier volume, 2025 | Tinci at 343 thousand tons; Capchem at 224 thousand tons | Indicates scale advantage of leading formulators | |
| New carbonate solvent capacity, announced January 2026 | 200,000 tons a year at Yanbu, Saudi Arabia, with USD 260 million planned investment by Capchem | Shows formulators integrating backward into solvents that feed electrolyte cost | - |
| US LiPF6 salt capacity under DOE support | At least 10,000 tons a year planned at St. Gabriel, Louisiana | First domestic US source of the main lithium-ion electrolyte salt | - |
Analyst Perspective
“Electrolyte demand follows cell manufacturing locations, so suppliers with plants near new gigafactories in Europe, North America and India will gain share from imports. Formulators that pair salt and solvent integration with qualified additive packages for fast-charge and high-power cells will hold the strongest position with battery makers.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the battery electrolytes market segmented?
Battery electrolytes market is segmented by two primary commercial axes and region: type, end use, and region. In 2026, lithium-ion is projected at 92% by value and automotive at 54%.
By type: lead-acid, lithium-ion, and others.
By end use: automotive, consumer electronics, energy storage systems, and industrial and other uses.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does lithium-ion hold the leading type share?
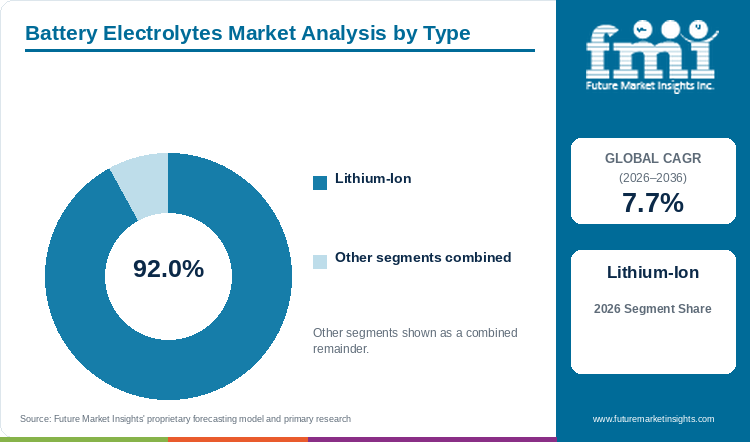
Lithium-ion is projected to hold 92% of type demand in 2026 by value, supported by high-volume cell production for vehicles, electronics and storage.
Table 3: Type Share for the Battery Electrolytes Market (percentage share), 2026
| Type | Share (2026) |
|---|---|
| Lithium-Ion | 92% |
| Other Segments Combined | 8%* |
| Total | 100% |
*Covers lead-acid, others and remaining segments not shown separately.
Table 4: Type Leadership and Market Growth for the Battery Electrolytes Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.7% |
| Leading Segment | Lithium-Ion |
Lithium-ion electrolytes account for 92% of type demand in 2026 by value. Product development is moving beyond standard carbonate blends. In June 2026, Asahi Kasei reported that EAS Batteries had begun selling a 22 Ah LFP cell using the acetonitrile-based Acetolyte electrolyte. Continuous discharge power for that cell is about 60% higher than for the same cell with a conventional electrolyte. Salt suppliers are also adding newer salts, as Nippon Shokubai plans a 3,000-ton-a-year LiFSI plant in Kitakyushu with commercial operation revised to December 2028 following a budget increase to approximately ¥43.0 billion announced in August 2026 [5]. As per FMI, lead-acid electrolyte remains tied to the lead acid battery base for starter and backup uses. Sodium-ion batteries and solid-state chemistries form part of the others category.
- Lithium-ion electrolytes account for 92% value share in 2026, supported by cell output for electric vehicles, electronics and storage and the much lower per-ton value of lead-acid electrolyte.
- High-power and fast-charge cell designs are widening the range of solvents and salts that formulators need to qualify.
Why does automotive lead end use demand?
Automotive is projected to hold 54% of end use demand in 2026, supported by the large electrolyte fill required per traction battery pack.
As per FMI, automotive accounts for 54% of battery electrolyte demand in 2026. Electrolyte installed in electric vehicle batteries reached about 616 thousand tons in the first half of 2025 alone, with Tinci, BYD and Capchem as the largest suppliers by volume. Demand growth tracks the electric vehicle battery build-out. The IEA expects that build-out to continue in 2026 with sales growth of over 50% in Asia Pacific outside China and about 20% in Europe. FMI treats energy storage systems as a separate end use, with a demand outlook tied to grid and residential battery programs instead of vehicle sales.
- Automotive accounts for 54% share in 2026, supported by electric car and plug-in hybrid battery production.
- Supplier qualification for automotive cells is lengthy, which favours formulators with existing approvals at large cell makers.
What are the drivers, restraints, and opportunities in the battery electrolytes market?
In the battery electrolytes market, electric vehicle and storage cell production drives volume growth, uneven regional EV demand and concentrated salt and solvent supply constrain new capacity, and localised production near new cell plants opens the principal commercial opportunity.
- Driver: Electrolyte installed in electric vehicles rose 37.3% in 2025.
- Restraint: Weaker EV demand in some regions has led to cancelled electrolyte plants.
- Opportunity: Local electrolyte, salt and solvent capacity near new gigafactories outside China.
Electrification Lifts Electrolyte Volumes
Battery electrolyte volume tracks cell production for vehicles and storage. SNE Research reported about 1,475 thousand tons of electrolyte installed in electric vehicle batteries in 2025. Installation outside China rose 32.6% to about 457 thousand tons, which leaves roughly 1,018 thousand tons in China.
Uneven Demand Slows Capacity Outside China
Electrolyte projects outside China rely on cell plants that are themselves being delayed. Enchem cancelled an electrolyte plant planned for Tennessee in October 2025. This followed the end of the US federal clean vehicle credit of up to USD 7,500, which is not available for vehicles acquired after 30 September 2025. In Europe, ACC confirmed in February 2026 that conditions to restart cell plant projects in Germany and Italy were unlikely to be met. These setbacks reduce near-term offtake for local electrolyte plants.
Localised Supply Creates the Main Opening
As per FMI, battery makers in Europe, North America and India are seeking supply that is not routed through China. E-Lyte Innovations opened a 20,000-ton-a-year electrolyte plant in Kaiserslautern in September 2024. This was the company's first electrolyte production site in Germany. In India, Neogen Chemicals reported in February 2026 that the 2,000-ton electrolyte plant at Dahej was fully commissioned. The company's Pakhajan plant uses MU Ionic Solutions technology and was nearing mechanical completion [8]. The EU Batteries Regulation adds traceability requirements, with battery passports for electric vehicle batteries required from February 2027.
Which country CAGRs are profiled in the battery electrolytes market?
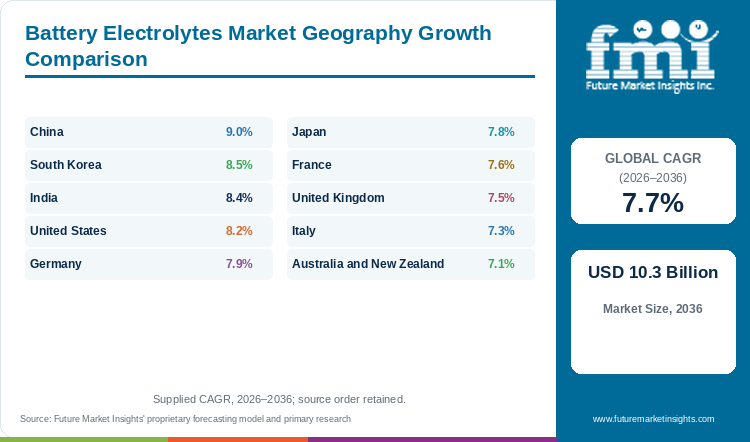
Table 5: Country CAGR Comparison for the Battery Electrolytes Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| China | 9% |
| South Korea | 8.5% |
| India | 8.4% |
| United States | 8.2% |
| Germany | 7.9% |
| Japan | 7.8% |
| France | 7.6% |
| United Kingdom | 7.5% |
| Italy | 7.3% |
| Australia and New Zealand | 7.1% |
How do country-level CAGRs compare in the battery electrolytes market?
Country growth differs with local cell production, the presence of domestic formulators and the pace of electric vehicle and storage adoption; near-term growth remains concentrated in Asia's established supply base even as formulators increasingly site new capacity near gigafactories in Europe, North America and India, a shift expected to narrow the gap only gradually. As per FMI analysis, the Asian manufacturing base leads with China at 9%, South Korea at 8.5% and India at 8.4%. The United States follows at 8.2%. European markets sit in a narrower band from Germany at 7.9% to Italy at 7.3%, with France at 7.6% and the United Kingdom at 7.5%. Japan records 7.8%. Australia and New Zealand record the lowest profiled rate at 7.1%.
- China demand gains from the largest concentration of cell and electrolyte production, which keeps growth highest.
- South Korea demand gains from the home production lines of Korean cell makers, which anchor local electrolyte purchases.
- India demand gains from new giga-scale cell plants that are qualifying domestic electrolyte and salt supply.
- United States demand gains from domestic salt projects that support local cell plants despite weaker EV incentives.
- Germany demand gains from local electrolyte output that now serves nearby European cell makers.
- Japan demand gains from specialty salts and new solvent systems that add value to a mature cell base.
- France demand gains from cell plants in the north of the country that create a local demand cluster.
- United Kingdom demand gains from the 2030 car phase-out, a deadline that sets the pace for any new domestic cell capacity.
- Italy demand gains from smaller battery producers, as cancelled cell projects limit large-scale purchases.
- Australia and New Zealand demand gains slowly, as limited cell manufacturing keeps growth the lowest of the profiled markets.
Country-wise Analysis
- The China battery electrolytes market is projected to grow at 9% CAGR through 2036. China is the largest producer of batteries and battery materials, and roughly 1,018 thousand tons of 2025 EV electrolyte installation was in China
- Chinese companies held 90.4% of global EV electrolyte installation in the fourth quarter of 2025. Tinci and Capchem alone installed about 567 thousand tons in 2025. Formulators supplying both domestic cell makers and new overseas plants keep China the fastest-growing profiled market.
- South Korea battery electrolytes market is anticipated to expand at 8.5% CAGR through 2036. Demand comes from the home production lines of Korean cell makers. Domestic formulators supply these lines and have also planned plants abroad, such as Enchem's site in Dunkirk, France. Korean suppliers held 5.8% of EV electrolyte installation in the fourth quarter of 2025, with Enchem at about 56 thousand tons and Soulbrain at about 34 thousand tons for the year. Although Korean suppliers' installed-volume share trails China's, continued qualification of new chemistries at home and additional overseas capacity are expected to keep Korean demand above the global rate even as localisation outside Asia advances only gradually.
- India battery electrolytes market is estimated to grow at 8.4% CAGR through 2036. In February 2026, Neogen Chemicals reported a fully commissioned 2,000-ton electrolyte plant at Dahej. The company also reported a long-term electrolyte supply approval from a giga-scale Indian customer. Domestic supply shortens qualification for new Indian cell plants. India's growth is tied to the pace at which announced gigafactories reach volume production.
- United States battery electrolytes market is projected to record 8.2% CAGR through 2036. The US Department of Energy completed an environmental review in June 2026 for a LiPF6 unit at St. Gabriel in Louisiana. The unit has capacity of at least 10,000 tons a year and is supported by a USD 100 million award [15]. Weaker EV demand led Enchem to cancel a planned Tennessee electrolyte plant in October 2025. Domestic salt supply gives US cell plants a local input, though vehicle demand will set the pace.
- Germany battery electrolytes market is predicted to rise at 7.9% CAGR through 2036. E-Lyte Innovations opened a 20,000-ton-a-year electrolyte plant in Kaiserslautern in September 2024. Local production reduces logistics for European cell makers. German growth hinges on whether planned cell plants in the region proceed after recent cancellations.
- Japan battery electrolytes market is forecast to expand at 7.8% CAGR through 2036. Nippon Shokubai plans a 3,000-ton-a-year LiFSI salt plant in Kitakyushu, with construction from January 2026 and commercial operation revised to December 2028. Asahi Kasei's acetonitrile-based electrolyte entered commercial use in a high-power cell in 2026. Japan's outlook relies on higher-value specialty salts and electrolytes more than on volume.
- France battery electrolytes market is projected to grow at 7.6% CAGR through 2036. Enchem announced a EUR 57 million electrolyte plant in Dunkirk with planned capacity of 150,000 tons a year. The site sits near cell plants in northern France. Demand in France follows the ramp-up of these nearby gigafactories.
- United Kingdom battery electrolytes market is anticipated to expand at 7.5% CAGR through 2036. The government confirmed in April 2025 that sales of new pure petrol and diesel cars will be phased out by 2030. Mitsubishi Chemical Group announced in December 2025 a planned transfer of the Billingham electrolyte plant to Green Energy Origin, originally targeted for completion around March 2026 subject to regulatory approval. UK growth will rely on new domestic cell capacity following the vehicle transition.
- Italy battery electrolytes market is estimated to grow at 7.3% CAGR through 2036. ACC confirmed in February 2026 that conditions to restart the paused Termoli cell plant were unlikely to be met. Without a large local cell plant, electrolyte purchases rest on smaller battery producers. Italy therefore ranks near the bottom of the profiled range.
- Australia and New Zealand battery electrolytes market is forecast to expand at 7.1% CAGR through 2036. Australia recorded about 350,000 battery installations and 4.6 GWh of capacity in the first ten months of the Cheaper Home Batteries Program, which began on 1 July 2025. FMI expects most of these batteries to arrive as finished products, so local electrolyte demand stays the lowest of the profiled markets unless cell or pack production is added in the region.
Who are the notable companies in the Battery Electrolytes Market?
Tinci, Capchem, Guotai-Huarong, Enchem, Soulbrain, BYD, Zhuhai Smoothway (Do-Fluoride), Mitsubishi Chemical (MU Ionic Solutions), Asahi Kasei, E-Lyte Innovations, Neogen Chemicals, Dongwha Electrolyte, Stella Chemifa, Nippon Shokubai, Koura (Orbia), Syensqo, Daikin Industries, Central Glass, and American Elements are key companies profiled in this market.
Supply is concentrated among Chinese formulators, which lead by volume; BYD also manufactures electrolyte in-house to supply its own vehicle and battery production, adding further to the volume held by Chinese suppliers. Korean and Japanese formulators held 5.8% and 3.8% of EV electrolyte installation in the fourth quarter of 2025. A second tier of regional producers is building capacity in Europe and India. Upstream salt and solvent capacity is also being added, with Capchem planning a carbonate solvent plant in Saudi Arabia and Nippon Shokubai a LiFSI plant in Japan. Solvay's battery materials platform passed to Syensqo when the separation took effect in December 2023. Syensqo and Axens formed Argylium in January 2026 to scale sulfide solid electrolytes for all-solid-state batteries. Stella Chemifa lists lithium hexafluorophosphate for lithium-ion batteries among core product lines, American Elements offers battery-grade LiPF6 solutions, and Daikin lists a fluoro ether for electrolyte additives and solvents under development.
- Large-scale formulated electrolyte suppliers: Tinci, Capchem, Guotai-Huarong, Enchem, Soulbrain, BYD, Zhuhai Smoothway (Do-Fluoride).
- Japanese and regional electrolyte formulators: Mitsubishi Chemical (MU Ionic Solutions), Asahi Kasei, E-Lyte Innovations, Neogen Chemicals, Dongwha Electrolyte.
- Salt, solvent and specialty material suppliers: Stella Chemifa, Nippon Shokubai, Koura (Orbia), Syensqo, Daikin Industries, American Elements, Central Glass.
Competitive Benchmarking: Battery Electrolytes Market
Table 6: Competitive Benchmarking for the Battery Electrolytes Market (qualitative capability ratings), 2026
| Company | Formulated Electrolyte Supply | Capacity Evidence 2024-2026 | Next-Generation Chemistry | Reach |
|---|---|---|---|---|
| Tinci | High | High | Medium | High |
| Capchem | High | High | Medium | High |
| Guotai-Huarong | High | Medium | Low | Medium |
| Enchem | High | Medium | Low | High |
| Soulbrain | High | Medium | Low | Medium |
| Mitsubishi Chemical (MU Ionic Solutions) | High | Medium | Low | High |
| Asahi Kasei | Medium | Medium | High | Medium |
| Neogen Chemicals | Medium | High | Low | Low |
| E-Lyte Innovations | Medium | Medium | Low | Low |
| Nippon Shokubai | Low | High | High | Medium |
| Koura (Orbia) | Low | Medium | Medium | Medium |
Each rating reflects disclosed electrolyte volumes, new plant capacity and commercial use of new chemistries for that capability, compared across formulators and salt and solvent suppliers.
Key Developments in the Battery Electrolytes Market
- In June 2026, Asahi Kasei reported that EAS Batteries had started selling a 22 Ah LFP cell using the Acetolyte electrolyte, following a licence signed in November 2025.
- In February 2026, Neogen Chemicals reported that the 2,000-ton Dahej electrolyte plant was fully commissioned and that the Pakhajan plant was nearing mechanical completion.
- In January 2026, Capchem announced a USD 260 million carbonate solvent plant in Saudi Arabia and a 50,000-ton-a-year expansion of the electrolyte plant in Poland.
- In December 2025, Mitsubishi Chemical Group announced a planned transfer of the Memphis and Billingham electrolyte plants to Green Energy Origin, originally targeted for completion around March 2026 subject to regulatory approval; FMI has not independently confirmed completion of the transfer.
Key Players in the Battery Electrolytes Market
Large-Scale Formulated Electrolyte Suppliers
- Tinci
- Capchem
- Guotai-Huarong
- Enchem
- Soulbrain
- BYD
- Zhuhai Smoothway (Do-Fluoride)
Japanese and Regional Electrolyte Formulators
- Mitsubishi Chemical (MU Ionic Solutions)
- Asahi Kasei
- E-Lyte Innovations
- Neogen Chemicals
- Dongwha Electrolyte
Salt, Solvent and Specialty Material Suppliers
- Stella Chemifa
- Nippon Shokubai
- Koura (Orbia)
- Syensqo
- Daikin Industries
- American Elements
- Central Glass
Battery Electrolytes Market - Report Scope
Table 7: Report Scope for the Battery Electrolytes Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Type; end use; region |
| Quantitative units | USD billion |
| Market definition | Value of electrolyte supplied to battery manufacturers, covering formulated liquid lithium-ion electrolyte, lead-acid electrolyte, and other electrolytes including gel, polymer, sodium-ion and solid-state types. Lithium salts, solvents and additives are counted within formulated electrolyte value; separators, electrodes, binders and finished cells are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | China; South Korea; India; United States; Germany; Japan; France; United Kingdom; Italy; Australia and New Zealand |
| Key companies profiled | Tinci; Capchem; Guotai-Huarong; Enchem; Soulbrain; BYD; Zhuhai Smoothway (Do-Fluoride); Mitsubishi Chemical (MU Ionic Solutions); Asahi Kasei; E-Lyte Innovations; Neogen Chemicals; Dongwha Electrolyte; Stella Chemifa; Nippon Shokubai; Koura (Orbia); Syensqo; Daikin Industries; Central Glass; American Elements |
| Forecast period | 2026 to 2036 |
| Approach | Bottom-up volume data and top-down estimates were cross-checked to reconcile cell production, electrolyte fill per cell, and supplier shipments within the defined revenue boundary. |
Battery Electrolytes Market - Research Methodology
Table 8: Research Methodology for the Battery Electrolytes Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with electrolyte formulators, salt and solvent producers, cell makers and distributors on volumes, pricing and qualification timelines. |
| Desk Research | Review of company releases, regulatory filings, government programs and industry tracking of electrolyte installation. |
| Market Sizing and Forecasting | Cell production by chemistry and end use converted to electrolyte demand, cross-checked with supplier volumes and price trends. |
| Data Validation | Triangulation of supply-side and demand-side estimates, with analyst review of outliers and segment balances. |
Battery Electrolytes Market by Segments
Battery Electrolytes Market segmented by Type:
- Lead-Acid
- Lithium-Ion
- Others
Battery Electrolytes Market segmented by End Use:
- Automotive
- Consumer Electronics
- Energy Storage Systems
- Industrial and Other Uses
Battery Electrolytes Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Roic.ai. (n.d.). Stella Chemifa Corporation (4109.T) company profile. https://www.roic.ai/quote/4109.T
- [2] International Energy Agency. (2026, May 20). Global EV Outlook 2026: Executive summary. https://www.iea.org/reports/global-ev-outlook-2026/executive-summary
- [3] Asahi Kasei. (2026, June 2). EAS Batteries starts sales of ultra-high-power cell using Asahi Kasei's novel electrolyte Acetolyte. https://www.asahi-kasei.com/news/2026/e260602
- [4] Chemical Week. (2025, April 18). Shokubai selects Kitakyushu for $263M electrolyte project. https://chemweek.mydigitalpublication.com/articles/shokubai-selects-kitakyushu-for-263m-electrolyte-project
- [5] Indian Chemical News. (2023, April 11). Neogen Chemicals signs agreement with MU Ionic Solutions. https://www.indianchemicalnews.com/technology/lite/neogen-chemicals-signs-agreement-with-mu-ionic-solutions-17060
- [6] Orbia. (2022, October 19). Orbia's fluorinated solutions business Koura receives $100M US Department of Energy award. https://www.orbia.com/this-is-orbia/news-and-stories/Orbia-Koura-received-100M-US-Department-of-Energy-Award/
- [7] Neogen Chemicals Limited. (2026, February 12). Press release on unaudited financial results for the quarter ended December 31, 2025. https://nsearchives.nseindia.com/corporate/NEOGEN_12022026001225_PR.pdf
- [8] American Elements. (n.d.). Lithium hexafluorophosphate solution, battery grade. https://americanelements.com/lithium-hexafluorophosphate-solution-21324-40-3
- [9] Daikin Chemicals. (n.d.). Battery materials. https://www.daikinchemicals.com/us/solutions/products/battery-materials.html
- [10] Battery-Tech Network. (2026, January 6). Capchem to invest $260M in Saudi plant, expand Polish output. https://battery-tech.net/battery-markets-news/capchem-to-invest-260m-in-saudi-plant-expand-polish-output/
- [11] Yicai Global. (2025, June 12). China's Tinci inks USD282 million deal to build lithium battery materials plant in Morocco. https://www.yicaiglobal.com/news/chinas-tinci-to-invest-usd282-million-in-lithium-battery-material-plant-in-morocco
- [12] ESS News. (2026, May 4). Australia adds 350,000 residential batteries and 4.6 GWh in 10 months under subsidy scheme. https://www.ess-news.com/?p=8843
- [13] Battery-News. (2025, October 7). Enchem abandons plans for electrolyte plant in USA. https://battery-news.de/?p=35070
- [14] US Department of Energy, National Energy Technology Laboratory. (2026, June 24). Finding of No Significant Impact for Lithium Hexafluorophosphate (LiPF6) Manufacturing Unit Project (DOE/EA-2236), St. Gabriel, Louisiana. https://www.netl.doe.gov/sites/default/files/2026-06/Mexichem_FONSI_6-24-2026_508.pdf
- [15] US Internal Revenue Service. (2026, July 13). Credits for new clean vehicles purchased in 2023 or after. https://www.irs.gov/credits-deductions/credits-for-new-clean-vehicles-purchased-in-2023-or-after
- [16] electrive. (2026, February 9). ACC permanently abandons battery projects in Germany and Italy. https://www.electrive.com/2026/02/09/acc-permanently-abandons-battery-projects-in-germany-and-italy/
- [17] Battery-Tech Network. (2024, September 13). E-Lyte Innovations inaugurates first German electrolyte production facility in Germany. https://battery-tech.net/e-lyte-innovations-inaugurates-first-german-electrolyte-production-facility-in-germany
- [18] Baker McKenzie. (2026, January 1). EU Sustainable Batteries Regulation. https://www.bakermckenzie.com/en/insight/publications/resources/product-risk-radar-articles/eu-sustainable-batteries-regulation
- [19] UK Department for Transport. (2025, April 7). Phasing out sales of new petrol and diesel cars from 2030 and supporting the ZEV transition: consultation outcome. https://www.gov.uk/government/consultations/phasing-out-sales-of-new-petrol-and-diesel-cars-from-2030-and-supporting-the-zev-transition
- [20] Nord France Invest. (2025, July 31). Enchem sets up electrolyte plant in Hauts-de-France. https://www.nordfranceinvest.com/success-story/enchem-sets-up-electrolyte-plant-in-hauts-de-france/
- [21] Chemical Processing. (2025, December 12). Mitsubishi Chemical to transfer electrolyte production to GEO, advance thermal management collaboration with Boston Materials. https://www.chemicalprocessing.com/industrynews/news/55338164/mitsubishi-chemical-to-transfer-electrolyte-production-to-geo-advance-thermal-management-collaboration-with-boston-materials
- [22] ICIS. (2023, December 8). Solvay spin-off business separation to come into effect. https://icis.com/explore/resources/news/2023/12/08/10952171/solvay-spin-off-business-separation-to-come-into-effect
- [23] Battery-Tech Network. (2026, January 12). Syensqo, Axens form Argylium to scale solid-state batteries. https://battery-tech.net/battery-markets-news/syensqo-axens-form-argylium-to-scale-solid-state-batteries
This Report Answers
- How big is the battery electrolytes market during 2026?
- What value is projected by 2036?
- Which type holds the leading share?
- Which end use holds the leading share?
- Which countries have the fastest growth?
- Which companies are key players in the market?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Type, 2026 to 2036
- Lead-Acid
- Lithium-Ion
- Others
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Automotive
- Consumer Electronics
- Energy Storage Systems
- Industrial and Other Uses
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Type
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Tinci
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Capchem
- Guotai-Huarong
- Enchem
- Soulbrain
- Mitsubishi Chemical (MU Ionic Solutions)
- Asahi Kasei
- Neogen Chemicals
- E-Lyte Innovations
- Nippon Shokubai
- Koura (Orbia)
- BYD
- Zhuhai Smoothway (Do-Fluoride)
- Dongwha Electrolyte
- Stella Chemifa
- Syensqo
- Daikin Industries
- American Elements
- Central Glass
- Tinci
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 4: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 7: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: Latin America Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 10: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 11: Western Europe Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 12: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 13: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Eastern Europe Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 15: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 16: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 18: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 22: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 23: Middle East and Africa Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 24: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Type
- Figure 6: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End Use
- Figure 9: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Type
- Figure 23: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by End Use
- Figure 26: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: Latin America Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 28: Latin America Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 29: Latin America Market Attractiveness Analysis by Type
- Figure 30: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by End Use
- Figure 33: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Western Europe Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 35: Western Europe Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 36: Western Europe Market Attractiveness Analysis by Type
- Figure 37: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 38: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 39: Western Europe Market Attractiveness Analysis by End Use
- Figure 40: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Eastern Europe Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 42: Eastern Europe Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 43: Eastern Europe Market Attractiveness Analysis by Type
- Figure 44: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 45: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 46: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 47: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 48: East Asia Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by Type
- Figure 51: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 52: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 53: East Asia Market Attractiveness Analysis by End Use
- Figure 54: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 55: South Asia and Pacific Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 56: South Asia and Pacific Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 57: South Asia and Pacific Market Attractiveness Analysis by Type
- Figure 58: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 59: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 60: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 61: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East and Africa Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 63: Middle East and Africa Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 64: Middle East and Africa Market Attractiveness Analysis by Type
- Figure 65: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 66: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 67: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 68: Global Market - Tier Structure Analysis
- Figure 69: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the battery electrolytes market expected in 2026?
Future Market Insights estimates that the battery electrolytes market will be valued at USD 4.90 billion in 2026. The market is projected to reach USD 10.29 billion by 2036, reflecting a 2.1x expansion over the forecast period.
What CAGR is projected for the battery electrolytes market through 2036?
As per FMI analysis, the battery electrolytes market is projected to grow at a CAGR of 7.7% from 2026 to 2036. Growth follows cell production for electric vehicles and stationary storage.
Which type holds the leading market share in 2026?
As per FMI, lithium-ion holds 92% of type demand in 2026 by value, since electric vehicle and storage cell output sets the volume base that electrolyte formulators supply and lead-acid electrolyte contributes comparatively little value despite higher unit counts.
Which end use holds the leading share in 2026?
Automotive holds 54% of end use demand in 2026, reflecting the volume of electrolyte used in traction batteries.
Which country has the fastest expansion outlook through 2036?
China has the highest profiled CAGR at 9% from 2026 to 2036, followed by South Korea at 8.5% and India at 8.4%.
Who are the key companies in the battery electrolytes market?
Notable companies include Tinci, Capchem, Guotai-Huarong, Enchem, Soulbrain, BYD, Zhuhai Smoothway (Do-Fluoride), Mitsubishi Chemical (MU Ionic Solutions), Asahi Kasei, E-Lyte Innovations, Neogen Chemicals, Dongwha Electrolyte, Stella Chemifa, Nippon Shokubai, Koura (Orbia), Syensqo, Daikin Industries, Central Glass, and American Elements.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
