
- Market Size (2026)
- USD 96.2 Bn
- Forecast (2036)
- USD 192.8 Bn
- CAGR (2026 to 2036)
- 7.2%
How big is Cans Market in 2026?
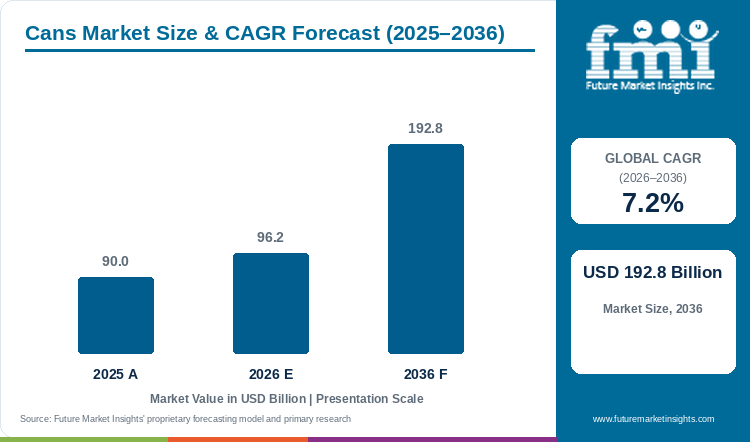
The cans market demonstrated steady progress from USD 90.0 billion in 2025 to USD 96.2 billion in 2026, building toward a targeted valuation of USD 192.8 billion by 2036 at a CAGR of 7.2%.
Brewery operations directors and preserved-food packers are shifting filling capacity from returnable glass and single-use plastic bottles into thin-wall metal cans to cut outbound freight weight and capture deposit-return scrap credits. The global cans market was valued at USD 90.0 billion in 2025 and is estimated to reach USD 96.2 billion in 2026. The market is projected to reach USD 192.8 billion by 2036, expanding at a compound annual growth rate (CAGR) of 7.2% between 2026 and 2036. Aluminum Alloy Body containers capture an estimated 53.5% share of 2026 substrate demand since 3000-series and 5000-series alloys run at 2,400 cans per minute without side-seam welding. Broader category expansion outpaces the beverage metal cans segment at 3.7% CAGR because preserved food packers and aerosol fillers are simultaneously converting glass jars and plastic tubes into coated metal formats. Regulatory bans on bisphenol A epoxy linings are also triggering fleet-wide coating upgrades, as toxicology researchers in Food Science and Nutrition confirmed in November 2025 that European Union Regulation 2024/3190 enforces strict bisphenol A non-intent compliance across food and drink cans. Canmakers are adding regional stamping lines to serve that demand, as Ball Corporation announced a new beverage can plant investment in Uttar Pradesh in September 2026. FMI market monitoring confirms that primary aluminum smelting energy surcharges and harvest-linked vegetable pack fluctuations restrain spot margin expansion for converters through 2036.
Key Market Trends & Insights
- By substrate material: Aluminum Alloy Body containers hold an estimated 53.5% share in 2026 as beverage brands prioritize lightweight chill-fast cans with high closed-loop scrap recovery.
- By manufacturing structure: Two-Piece Drawn and Wall Ironed DWI Cans represent 73.9% in 2026 because seamless cup-and-wall drawing eliminates side-seam soldering and reduces metal gauge thickness.
- By can format: 330 ml Standard Sleek Can profiles account for 30.7% in 2026 as sparkling water and functional drink marketers standardize slim shelf-ready multipacks.
- By end-use industry: Carbonated Soft Drinks and Beer command 42.7% in 2026 through high-speed rotary filling lines and retail cold-vault merchandising.
- By secondary end-use category: Canned Seafood and Meat with Chemical and Cosmetic Aerosols capture 57.3% combined in 2026 via retort-sterilized food tins and pressurized dispensers.
Regional Takeaways
- Top national expansion: Mexico leads national growth projections at an 8.5% CAGR through 2036 driven by export beer canning capacity and nearshoring beverage investments.
- Broader country progression: Poland tracks at a 7.9% CAGR ahead of the United Kingdom at 7.5% and the United States at 7.3%, while Germany records a 6.8% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Cans Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 90.0 billion |
| Estimated Market Size in 2026 | USD 96.2 billion |
| Projected Market Size by 2036 | USD 192.8 billion |
| CAGR, 2026 to 2036 | 7.2% |
| Added Market Value, 2026 to 2036 | USD 96.6 billion |
Global beverage bottlers and shelf-stable food processors face mounting retail deposit-return penalties on single-use polyethylene terephthalate bottles and heavy freight charges on returnable glass. Conversion of high-volume stock-keeping units into thin-walled aluminum and electrolytic tinplate cans increases pallet stacking density by over 30% and eliminates breakage losses in automated distribution centers. In February 2026, metallurgists publishing in Metals documented that non-heat-treatable aluminum alloys and multilayer iron-tin intermetallic phases in tinplate provide complete oxygen barriers and retort sterilization stability. Procurement directors consequently lock in multi-year coil allocation agreements for recyclable aluminum cans to protect seasonal summer beverage launches.
Metal Coil Tonnage and Filled Unit Sizing
Table 2: Metal Substrate Tonnage and Unit Volume Sizing for the Cans Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 90.0 | 96.2 | 192.8 |
| Metal can substrate consumption (million metric tons) | 18.4 to 20.2 | 19.5 to 21.4 | 36.0 to 39.8 |
| Commercial metal can shipments (billion units) | 585.0 to 630.0 | 620.0 to 668.0 | 1,180.0 to 1,275.0 |
| Average realization per 1,000 metal cans (USD) | 142.0 to 154.0 | 144.0 to 156.0 | 151.0 to 164.0 |
Operational note: Unit shipment ranges reflect commercial two-piece DWI beverage cans and three-piece welded food cans with monobloc or tinplate aerosol dispensers across global filling plants.
High-speed bodymakers draw and iron aluminum coil stock down to wall thicknesses below 95 microns while maintaining internal buckle resistance above 620 kilopascals for carbonated drinks. Food canneries rely on electrolytic tinplate packaging with sulfur-resistant internal lacquers to prevent black iron sulfide staining during 121-degree-Celsius steam retorting. In July 2025, food toxicologists reporting in Scientific Reports analyzed trace metal migration in canned tomato paste and olives, confirming why unbroken internal lacquer films remain mandatory for acidic food matrices. Cannery quality managers therefore require 100% vision-camera enamel inspection on coated tinplate ends before authorizing high-acid vegetable packs.
Per Capita & High-Speed Canning Line Sizing
Table 3: Per Capita and Canning Line Allocation Indicators for the Cans Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 10,975.6 | 11,590.4 | 21,422.2 |
| Annual can procurement per high-speed filling line (USD billion) | 0.011 to 0.013 | 0.012 to 0.014 | 0.021 to 0.025 |
| BPA-NI & epoxy-free internal coating share (%) | 68.0% to 73.0% | 74.0% to 79.0% | 94.0% to 98.0% |
Table 4: Industrial Canning & Sector Allocation Indicators for the Cans Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 96.2 billion | 2026 global valuation baseline |
| Active beverage, food & aerosol canning lines global | 7,800 lines | Rotary beverage fillers, food retorts & aerosol gassers |
| Annual can allocation per filling line | USD 0.0123 billion | Annualized metal container procurement per line |
| Carbonated Soft Drinks and Beer valuation, 2026 | USD 41.1 billion | 42.7% end-use industry allocation |
Phase-out of plastic shrink-wrap and six-pack rings around canned multipacks allows beverage brands to meet retail plastic-free aisle pledges without slowing down packer throughput. Canmakers pair two-piece metal cans with paperboard top-clip carriers so entire multipacks enter municipal curbside recycling streams intact. In October 2026, Smurfit Westrock plc fast-tracked a corrugated and paperboard multipack launch for Corona Cero alcohol-free beer as non-alcoholic beverage demand expanded across Latin America and Europe. Direct integration of high-speed can seaming with fiber multipack cartoning allows beverage co-packers to supply supermarket promotional aisles without secondary plastic wrap.
Analyst Perspective
"Beverage and preserved-food brands no longer treat metal cans as interchangeable commodity containers. Plant engineering directors buy guaranteed seaming speed and bisphenol A non-intent coating compliance with closed-loop recycled aluminum content that lowers scope-three packaging emissions. Canmakers that co-locate specialty sleek-can lines near regional breweries and co-packers will capture multi-year supply contracts through 2036."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the cans market segmented?
The cans market is segmented by substrate material, manufacturing structure, can format, and end-use industry. In 2026, Aluminum Alloy Body is projected at 53.5%, Two-Piece Drawn and Wall Ironed DWI Cans at 73.9%, 330 ml Standard Sleek Can at 30.7%, and Carbonated Soft Drinks and Beer at 42.7%.
By substrate material: Aluminum Alloy Body and Tinplate Coated Steel with Tin-Free Steel TFS.
By manufacturing structure: Two-Piece Drawn and Wall Ironed DWI Cans and Three-Piece Welded Body Cans.
By can format: 330 ml Standard Sleek Can and 500 ml King Can with 250 ml Slim Energy Can and Above 500 ml Preserved Food Can.
By end-use industry: Carbonated Soft Drinks and Beer and Canned Seafood and Meat with Chemical and Cosmetic Aerosols.
By region: North America and Latin America with Western Europe and Eastern Europe. Coverage also spans East Asia and South Asia and Pacific with Middle East and Africa.
Why does Aluminum Alloy Body lead the substrate material category?
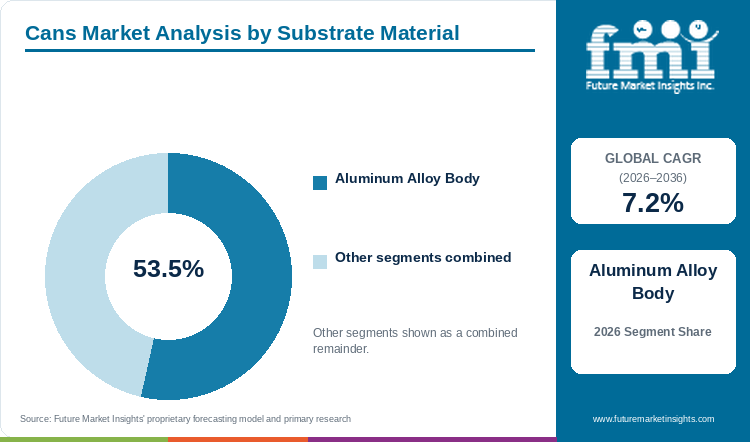
Aluminum Alloy Body containers hold an estimated 53.5% of substrate material demand in 2026, anchored by lightweight coil drawing and closed-loop recycling economics.
Table 5: Substrate Material Share for the Cans Market (percentage share), 2026
| Substrate Material | Share (2026) |
|---|---|
| Aluminum Alloy Body | 53.5% |
| Tinplate Coated Steel & TFS Combined | 46.5%* |
| Total | 100.0% |
Tinplate Coated Steel and Tin-Free Steel TFS make up the remaining 46.5% balance of 2026 global cans substrate material demand.
Table 6: Substrate Material Leadership and Market Growth for the Cans Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.2% |
| Leading Segment | Aluminum Alloy Body |
Beverage fillers and personal-care brands favor Aluminum Alloy Body containers because low metal density cuts outbound truckload weight and used beverage cans command high scrap buyback prices that subsidize coil conversion costs. Seamless aluminum bodies also accept 360-degree rotary dry-offset lithography and tactile matte overvarnishes across pressurized metal aerosol cans and craft beverage lines.
- Aluminum Alloy Body holds 53.5% of substrate material value in 2026 because high formability and closed-loop recycling economics favor aluminum across beverage and aerosol lines.
- Ball Corporation reported full-year 2025 results in February 2026, recording U.S. GAAP diluted earnings per share of USD 3.30 on strong global aluminum beverage can shipments. Sustained volume across aluminum can plants in North America and Europe confirms that brand owners continue prioritizing lightweight aluminum over heavier glass packaging.
What sustains Two-Piece Drawn and Wall Ironed DWI Cans leadership?
Two-Piece Drawn and Wall Ironed DWI Cans represent 73.9% of the manufacturing structure category in 2026, supported by 2,400-can-per-minute seamless bodymaking.
High-volume beverage and pet-food plants specify Two-Piece Drawn and Wall Ironed DWI Cans because punching a single metal cup and ironing its walls eliminates the longitudinal side seam and separate bottom end required by three-piece cans. Elimination of two seam junctions lowers metal consumption per container and prevents micro-leaks on hermetic metal food cans and carbonated drink lines.
- Two-Piece Drawn and Wall Ironed DWI Cans represent 73.9% of the manufacturing structure segment in 2026 as high-speed bodymakers minimize coil scrap and double-seam failure rates.
- Ball Corporation announced network optimization measures in February 2025 centered on its Florida two-piece aluminum can manufacturing operations in North America. Consolidation of DWI bodymaking capacity into high-speed regional megaplants lowers per-thousand-can conversion costs for high-volume beverage accounts.
How does 330 ml Standard Sleek Can lead the can format category?
330 ml Standard Sleek Can profiles account for 30.7% of can format volume in 2026, driven by slim retail multipacks and cold-vault shelf optics.
Brand marketers across carbonated soft drinks and ready-to-drink teas with hard seltzers converge on the 330 ml Standard Sleek Can because its narrower body diameter creates taller shelf facings while fitting existing vending machines and Euro-pallet layer patterns. Co-packers run 330-milliliter sleek bodies on dual-lane fillers and rigid metal packaging seaming turrets with minimal change-part downtime.
- 330 ml Standard Sleek Can formats account for 30.7% of can format demand in 2026 because single-serve portion control and tall shelf optics boost retail multipack velocity.
- Graphic Packaging Holding Company introduced its KeelClip paperboard multipack system for sleek beverage cans at PACK EXPO 2025 to replace plastic rings and shrink film. Automated paperboard clip applicators allow beverage fillers to run 330-milliliter sleek multipacks at full line speed while meeting supermarket plastic-elimination targets.
Why does Carbonated Soft Drinks and Beer lead end-use industry demand?
Carbonated Soft Drinks and Beer secure 42.7% of end-use industry value in 2026, supported by brewery and soft-drink plastic-to-metal pack conversions.
Global breweries and carbonated soft-drink bottlers anchor metal can procurement because pressurized dissolved carbon dioxide requires rigid containers that block oxygen ingress and UV light degradation. Retail grocery chains allocate premium cold-vault and end-cap space to twelve-pack and twenty-four-pack beverage cases equipped with easy-open resealable can ends and stay-on tabs.
- Carbonated Soft Drinks and Beer secure 42.7% of end-use industry value in 2026 as breweries and soft-drink brands shift pack mix from returnable glass into multipack cans.
- In February 2026, Sonoco Products Company reported full-year 2025 net value of USD 7.5 billion and projected 2026 adjusted EBITDA of USD 1.25 billion to USD 1.35 billion across its metal and paper packaging divisions. Multi-billion-dollar capital scale across integrated metal canmakers ensures uninterrupted container supply during peak summer beverage filling seasons.
How do Canned Seafood and Meat with Aerosols shape secondary end-use demand?
Canned Seafood and Meat with Chemical and Cosmetic Aerosols command 57.3% of 2026 end-use demand, anchored by retort food tins and pressurized dispensers.
Outside carbonated beverages, tuna and sardine canneries with meat processors and cosmetic aerosol fillers account for the majority of three-piece tinplate and impact-extruded aluminum can consumption. Shelf-stable protein packers rely on decorative specialty tin cans and easy-peel foil ends to market premium ambient seafood without cold-chain energy costs.
- Canned Seafood and Meat with Chemical and Cosmetic Aerosols represent 57.3% of 2026 end-use demand across food retorts and personal-care filling plants.
- In September 2025, materials scientists publishing in Chemistry engineered fluorinated anodic aluminum oxide nanopore coatings that protect steel and aluminum surfaces against corrosion. Advanced anti-corrosion surface treatments allow seafood canneries and aerosol fillers to extend ambient shelf life in coastal distribution lanes.
What are the drivers and restraints with opportunities in the cans market?
In the cans market, retail plastic-replacement pledges and closed-loop deposit-return recycling are projected to drive adoption whereas aluminum coil price volatility and seasonal crop swings restrain margins and BPA-NI internal coatings create compliance opportunities.
- Driver: Retail plastic-reduction commitments and superior deposit-return recycling rates compel beverage and food brands to shift filling volume into aluminum and tinplate cans.
- Restraint: London Metal Exchange aluminum price volatility and seasonal vegetable crop shortfalls create working-capital swings and temporary volume dips for food and beverage canmakers.
- Opportunity: Bisphenol A non-intent acrylic and polyester internal coatings with lightweight easy-open ends unlock regulatory compliance across European and United States food canneries.
Growth Analysis and Future Potential: Qualitative Demand Drivers
Beverage and food marketers are reallocating capital budgets toward high-speed canning lines because metal containers achieve recycling rates above 70% in deposit-return jurisdictions and eliminate microplastic shedding concerns. Cold-filled energy drinks and nitrogen-dosed coffees with RTD cocktails rely on monobloc aerosol cans and sleek DWI cans to preserve pressurized mouthfeel over twelve-month ambient shelf lives. In December 2025, Tetra Pak International SA and Garcia Carrion unveiled a barrier packaging rollout in Europe as beverage brands accelerated low-carbon container transitions. Heightened competition across low-carbon beverage formats pushes metal canmakers to further downgauge aluminum dome thicknesses and increase recycled ingot content.
Risk Assessment of the Cans Market: Operational and Formulation Friction
Seasonal agricultural harvest disruptions and metal tariff pass-through lags represent the primary operational risks restraining short-term earnings stability in the food and aerosol can sector. When heatwaves or droughts reduce pea and sweet-corn or tomato harvests, three-piece tinplate food can volumes contract sharply during the third-quarter peak packing window. In October 2026, Sonoco Products Company reported that third-quarter 2026 Consumer Packaging segment volume dipped 2.9% as adverse weather curtailed seasonal vegetable harvests across EMEA and the Americas, reducing metal food can demand. Canmakers counter harvest cyclicality by balancing seasonal vegetable tins against year-round pet food and beverage can contracts.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Canmakers and coating formulators capture price premiums by commercializing styrene-free, bisphenol A non-intent (BPA-NI) internal lacquers and chromium-free Electrolytic Chromium Coated Steel (ECCS) passivation layers. European Union food-contact legislation prohibits bisphenol A in newly coated food and beverage cans, forcing multinational canneries to qualify polyolefin dispersion and polyester coatings that survive acidic tomato and sulfur-rich seafood retorting. In April 2026, Amcor plc announced its participation at PRSE 2026 to demonstrate circular packaging and high-purity mechanical recycling technologies across European container streams. Suppliers that pre-qualify BPA-NI coil coatings across multiple food matrices lock in multi-year cannery accounts.
Cans Market by Country (2026 to 2036)
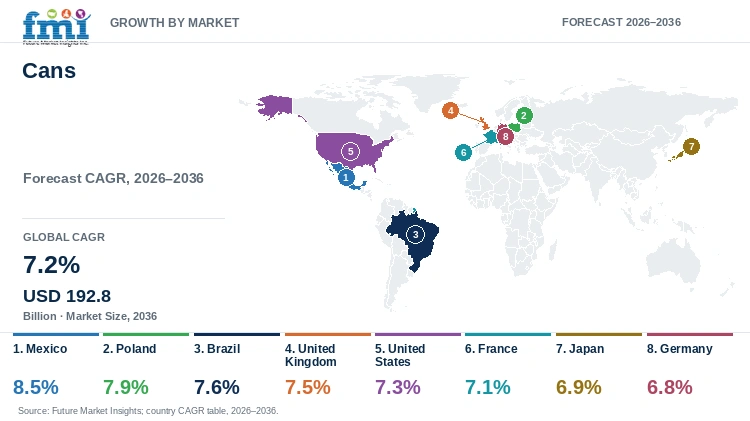
FMI country modeling indicates that Mexico leads cans market expansion at an 8.5% CAGR through 2036, followed by Poland at 7.9% and Brazil at 7.6%, while Germany advances at a 6.8% CAGR. National growth rates reflect brewery export capacity and preserved-food canning infrastructure with deposit-return container legislation.
Table 7: Country CAGR and Primary Growth Levers for the Cans Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Mexico | 8.5% | Export brewery DWI canning capacity and cross-border beverage co-packing |
| Poland | 7.9% | Central European energy-drink contract filling and preserved-food canning |
| Brazil | 7.6% | Closed-loop aluminum sheet recovery and high brewery can pack share |
| United Kingdom | 7.5% | Supermarket plastic-free aisle charters and RTD cocktail canning lines |
| United States | 7.3% | Sleek sparkling beverage multipacks and wet pet-food tinplate demand |
| France | 7.1% | BPA-NI vegetable and seafood cannery upgrades and monobloc cosmetic aerosols |
| Japan | 6.9% | Vending-machine RTD coffee bottle-cans and laminated tin-free steel cans |
| Germany | 6.8% | Mandatory Pfand deposit-return loop and industrial aerosol can manufacturing |
Source: Future Market Insights analysis
Mexico Cans Market Outlook (2026 to 2036)
Cans demand in Mexico will climb at a top-ranked 8.5% pace through 2036 as global beer exporters and nearshoring beverage co-packers are scaling two-piece aluminum canning lines across Monterrey and Guadalajara with northern border states. Unlike mature European markets where glass bottles retain high returnable bar share, export breweries in Mexico ship multipack sleek and standard 355-milliliter aluminum cans directly into United States grocery channels. In its November 2025 Mexico market briefing, United States Department of Agriculture FAS analysts noted that national gross domestic product exceeded USD 1.8 trillion as cross-border food and beverage trade accelerated. Domestic tinplate canmakers also supply three-piece welded cans for pickled jalapeno and tuna processors across coastal ports.
Key takeaway: In Mexico, export brewery canning expansions and cross-border beverage co-packing are projected to drive leading 8.5% CAGR growth for aluminum and tinplate cans.
Poland Cans Market Outlook (2026 to 2036)
Whereas Mexico benefits from export brewery trade, Poland acts as Central Europe's fastest-growing production base for private-label energy drinks and craft beer with thermally sterilized meat and fish tins. Industry valuation in Poland should advance at a 7.9% CAGR across the 2026 to 2036 decade while national deposit-return rules incentivize high-speed aluminum can collection. Based on July 2026 United States Department of Agriculture FAS grain and feed data, European Union agricultural processors are adjusting supply chains across Poland and Central Europe to stabilize food output. Regional beverage fillers in Krakow and Poznan specify 250-milliliter slim and 500-milliliter king cans with BPA-NI internal coatings for continental retail chains.
Key takeaway: In Poland, contract energy-drink filling and Central European preserved-food canning are forecast to sustain a 7.9% CAGR through 2036.
Brazil Cans Market Outlook (2026 to 2036)
In Brazil, tropical year-round beverage consumption and high domestic hydro-powered aluminum sheet recycling rates make two-piece aluminum cans the dominant package for beer and carbonated soft drinks. The cans market in Brazil is anticipated to advance at a 7.6% CAGR from 2026 through 2036 across Sao Paulo and Rio de Janeiro with southern agro-industrial states. Per the March 2026 USDA Foreign Agricultural Service oilseeds annual report, Brazil continues to post record agricultural commodity output that supports downstream edible-oil and meat canning industries. Local breweries and juice packers actively adopt 269-milliliter and 350-milliliter sleek cans to preserve cold-chain chill speed and lower highway freight costs across long interior routes.
Key takeaway: In Brazil, closed-loop aluminum beverage can recycling and high brewery filling shares are anticipated to support a 7.6% CAGR.
United Kingdom Cans Market Outlook (2026 to 2036)
Demand in the United Kingdom is shaped by supermarket plastic-elimination charters and rapid growth in canned RTD cocktails with ambient soup and baked-bean canning lines. Cans market value in the United Kingdom is estimated to progress at a 7.5% CAGR through 2036 as beverage fillers convert glass multipacks into lightweight aluminum cans. In December 2025, Amcor plc announced a circular packaging initiative noting that its Leamington Spa facility in the United Kingdom holds capacity to process nearly 40% of domestic rigid recovery streams. Canmakers in England and Wales also supply three-piece welded tinplate cans with easy-open ring-pull ends for household ambient grocery staples across retail chains.
Key takeaway: In the United Kingdom, supermarket plastic-free packaging targets and RTD beverage canning are estimated to drive a 7.5% CAGR.
United States Cans Market Outlook (2026 to 2036)
Unlike smaller national markets, the United States combines the world's largest installed base of two-piece DWI beverage can bodymakers with high-volume pet food and vegetable tinplate canneries. Metal can valuation across the United States will rise at a 7.3% CAGR during the decade through 2036 while sparkling water and wet pet-food brands lock in domestic can supply. Per Ball Corporation's Form 10-K annual report filed with the U.S. Securities and Exchange Commission for the period ended December 31, 2025, North and Central America beverage packaging remains the company's largest operating pillar. Canmakers across the Midwest and Southeast are retrofitting lines for quick diameter changeovers between standard 12-ounce and sleek formats.
Key takeaway: In the United States, multi-pack sparkling beverage demand and wet pet-food canning are projected to sustain a 7.3% CAGR across domestic bodymakers.
France Cans Market Outlook (2026 to 2036)
France differs from Anglo-Saxon beverage can markets because a large share of national metal packaging demand originates from thermally processed vegetables and seafood tins with luxury cosmetic aerosols in Brittany and the Loire valley. The cans market in France is slated to grow at a 7.1% CAGR across 2026 to 2036 as food canneries complete the statutory transition to bisphenol A non-intent internal coatings. In September 2026, Smurfit Westrock plc released a European consumer packaging separation study confirming high household sorting participation across France and Western Europe. Domestic cosmetic and pharmaceutical fillers also procure impact-extruded aluminum monobloc cans for pressurized thermal-spring water sprays and personal-care mousses.
Key takeaway: In France, BPA-NI food cannery upgrades and monobloc cosmetic aerosol production are slated to support a 7.1% CAGR through 2036.
Japan Cans Market Outlook (2026 to 2036)
In Japan, a nationwide network of hot-and-cold beverage vending machines and convenience-store RTD coffee with chuhai cocktail aisles sustains demand for precision two-piece aluminum and steel cans. Metal container valuation within Japan should progress at a 6.9% CAGR across the ten-year window to 2036 while domestic canmakers engineer ultra-lightweight bottle-cans and laminated tin-free steel formats. Per the April 2026 USDA Foreign Agricultural Service Food Processing Ingredients Annual report from Tokyo, Japan's food processing industry generated USD 174 billion in 2025 output across beverage and packaged food categories. Domestic beverage packers specify resealable threaded aluminum bottle-cans and polyester-film-laminated steel cans that eliminate liquid-lacquer curing emissions.
Key takeaway: In Japan, vending-machine RTD coffee and chuhai demand with film-laminated steel can engineering are forecast to maintain a 6.9% CAGR.
Germany Cans Market Outlook (2026 to 2036)
Demand in Germany is governed by the mandatory Pfand deposit-return system, which achieves near-total collection of used beverage cans and drives closed-loop coil-to-can recycling across domestic rolling mills. In Germany, metal can demand will grow at a 6.8% CAGR over the ten-year period to 2036 while discount supermarkets and breweries increase canned beer and energy-drink shelf allocations. In July 2026, Graphic Packaging Holding Company published its EU PPWR circularity and packaging compliance roadmap detailing recyclability grades that favor metal and fiber containers. Domestic automotive maintenance and industrial chemical producers also procure three-piece tinplate aerosol cans for technical sprays and pressurized polyurethane construction foams across regional plants.
Key takeaway: In Germany, closed-loop Pfand deposit-return recovery and industrial aerosol manufacturing are anticipated to underpin a 6.8% CAGR.
Full report country CAGRs cover: North America and Latin America with Western Europe and Eastern Europe. Coverage also includes East Asia and South Asia and Pacific with Middle East and Africa.
Who are the notable companies in the cans market?
Tetra Pak International SA, Smurfit Westrock plc, Amcor plc, Berry Global Group Inc., Sealed Air Corporation, Mondi Group plc, Sonoco Products Company, International Paper Company, Ball Corporation, and Crown Holdings, Inc. are the notable companies in the cans market.
Competitive positioning in the cans industry separates global metal beverage and food can manufacturers from diversified rigid and barrier packaging groups that supply complementary closures and multipack systems. Ball Corporation and Crown Holdings with Sonoco Products Company and Amcor plc manufacture two-piece DWI beverage cans and three-piece tinplate food cans with rigid aerosol containers. Mondi Group plc and Smurfit Westrock plc with International Paper Company supply automated corrugated and paperboard can-multipack carriers. Tetra Pak International SA and Berry Global Group with Sealed Air Corporation provide barrier liquid cartons and high-speed packaging equipment.
- Metal Beverage and Food Can Manufacturers: Ball Corporation and Crown Holdings with Sonoco Products Company produce two-piece aluminum DWI cans and three-piece welded tinplate food and aerosol cans.
- Rigid Container and Barrier Packaging Groups: Amcor plc and Berry Global Group with Tetra Pak International SA and Sealed Air Corporation supply rigid containers and barrier liquid packaging.
- Can Multipack and Secondary Transport System Providers: Mondi Group plc and Smurfit Westrock plc with International Paper Company engineer high-speed paperboard can clips and corrugated tray systems that replace plastic shrink film.
Competitive Benchmarking: Cans Market
Table 8: Competitive Benchmarking for the Cans Market (qualitative capability ratings), 2026
| Company | High-Speed Can Bodymaking | Coating & Barrier Engineering | Circular Recycling & Multipack Fit | Geographic Reach |
|---|---|---|---|---|
| Ball Corporation | High | High | High | Global pure-play aluminum beverage and personal-care aerosol can network |
| Crown Holdings, Inc. | High | High | High | Global two-piece beverage, three-piece food, and aerosol metal can plants |
| Sonoco Products Company | High | High | High | North American and EMEA metal food and aerosol cans with composite cans |
| Amcor plc | Medium | High | High | Global rigid containers, closures, and circular recycling across 40+ countries |
| Berry Global Group Inc. | Medium | High | High | Combined with Amcor in 2025; global aerosol overcaps and rigid closures |
| Smurfit Westrock plc | Unscored | High | High | Global corrugated cases and high-speed paperboard can multipack systems |
| International Paper Company | Unscored | Medium | High | North American and European containerboard trays for high-speed canning lines |
| Mondi Group plc | Unscored | High | High | European kraftliner and corrugated shrink-replacement multipacks for cans |
| Tetra Pak International SA | Unscored | High | High | Global aseptic beverage packaging and paper-based barrier systems |
| Sealed Air Corporation | Unscored | High | Medium | Global food barrier systems and automated high-speed packaging equipment |
Assessment basis: High-Speed Can Bodymaking evaluates installed two-piece DWI and three-piece welded metal can capacity, whereas Coating & Barrier Engineering rates BPA-NI internal lacquer and hermetic seaming capabilities. Circular Recycling & Multipack Fit measures closed-loop metal scrap integration and plastic-free multipack carrier compatibility.
Key Developments in the Cans Market
- Sonoco Products Company amended its credit agreement on September 25, 2026 to add USD 0.8 billion in term loan facilities supporting its global metal and industrial packaging operations. Expanded liquidity strengthens multi-plant tinplate coil purchasing and three-piece food can line automation across North America and EMEA.
- Amcor plc presented its expanded rigid and flexible container portfolio at Packaging Innovations 2026 in January 2026 following its integration of Berry Global. Combined closure and overcap tooling allows aerosol and beverage fillers to source matched actuators and container components from a single supplier.
- Tetra Pak International SA and Sterilgarda Alimenti launched a 1-liter aseptic beverage package with a paper-based barrier in April 2026 to lower packaging carbon footprints. Heightened low-carbon competition across ambient liquid aisles motivates metal canmakers to increase post-consumer recycled aluminum content above 75%.
Key Players in the Cans Market
Metal Beverage and Food Can Manufacturers
- Ball Corporation
- Crown Holdings
- Sonoco Products Company
- Rigid Container and Barrier Packaging Groups
Amcor plc
- Berry Global Group
- Tetra Pak International SA
- Sealed Air Corporation
- Can Multipack and Secondary Transport System Providers
Smurfit Westrock plc
- International Paper Company
- Mondi Group plc
Cans Market - Report Scope
Table 9: Report Scope for the Cans Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Substrate Material, Manufacturing Structure, Can Format, End-Use Industry |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer valuation from rigid metal cans across aluminum alloy, electrolytic tinplate coated steel, and tin-free steel (TFS) substrates, covering two-piece drawn and wall-ironed (DWI), two-piece drawn and redrawn (DRD), three-piece welded, and impact-extruded monobloc cans for beverages, preserved foods, and aerosols. Category Scope Note: Excludes industrial 55-gallon steel drums, flexible foil pouches, and bulk IBC totes. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa |
| Countries Covered | Mexico, Poland, Brazil, United Kingdom, United States, France, Japan, Germany, and additional countries in the full report |
| Key Companies Covered | Tetra Pak International SA, Smurfit Westrock plc, Amcor plc, Berry Global Group Inc., Sealed Air Corporation, Mondi Group plc, Sonoco Products Company, International Paper Company, Ball Corporation, Crown Holdings, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Cans Market - Research Methodology
Table 10: Research Methodology for the Cans Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with brewery packaging procurement directors, two-piece DWI plant engineering managers, tinplate food cannery quality heads, and internal coil-coating chemists to validate line speeds and BPA-NI conversion costs. |
| Secondary Research | Analysis of U.S. SEC Form 10-K filings (Ball, Crown, Sonoco, Sealed Air), European Union Regulation 2024/3190 BPA-NI dossiers, USDA Foreign Agricultural Service GAIN reports, and peer-reviewed metallurgy studies in PMC. |
| Market Sizing and Forecasting | Top-down global industrial and consumer packaging baselines (where metal cans represent 6.4% of the parent packaging universe) reconciled against bottom-up metal substrate tonnage (19.5M to 21.4M MT in 2026) and unit realizations from 2026 to 2036. |
| Country Forecasting Model | Econometric national models weight brewery and soft-drink canning line additions, retort vegetable and seafood pack volumes, and mandatory deposit-return recycling schemes across eight national markets. |
| Operational Benchmark Traceability | Substrate tonnage and canning line allocation metrics in Tables 2, 3, and 4 trace to SEC Form 10-K shipment disclosures, European Union food-contact migration studies, and USDA FAS national food processing reports. |
| Data Triangulation and Validation | Valuation estimates isolate rigid metal beverage, food, and aerosol cans and strictly exclude large industrial drums, intermediate bulk containers, and flexible foil laminates with zero hierarchy anomalies. |
Cans Market by Segments
Cans Market segmented by Substrate Material:
- Aluminum Alloy Body
- Tinplate Coated Steel
- Tin-Free Steel TFS
Cans Market segmented by Manufacturing Structure:
- Two-Piece Drawn and Wall Ironed DWI Cans
- Three-Piece Welded Body Cans
Cans Market segmented by Can Format:
- 330 ml Standard Sleek Can
- 500 ml King Can
- 250 ml Slim Energy Can
- Above 500 ml Preserved Food Can
Cans Market segmented by End-Use Industry:
- Carbonated Soft Drinks and Beer
- Canned Seafood and Meat
- Chemical and Cosmetic Aerosols
Cans Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Kim, H. & Park, J. (2025, November 19). Migration of Bisphenol A and Its Derivatives From Epoxy Coatings in Food and Beverage Cans Under Commission Regulation EU 2024/3190. Food Science and Nutrition (PMCID PMC12711388).
- [2] Ball Corporation. (2026, September 11). Ball Announces Investment in New Manufacturing Facility in Uttar Pradesh India. Ball Corporation Newsroom.
- [3] Rossi, M. & Bianchi, L. (2026, February 14). Metal Packaging: From Monolithic Containers to Hybrid Architectures in Aluminum and Tinplate. Metals (PMCID PMC13027902).
- [4] Hashemi, M. & Nazari, Z. (2025, July 1). Investigation of heavy metal levels in canned tomato paste and olives with pickles. Scientific Reports (PMCID PMC12216553).
- [5] Smurfit Westrock plc. (2026, October 14). Smurfit Westrock fast-tracks Corona Cero launch as demand rises for alcohol-free beer. Smurfit Westrock Press Releases.
- [6] Ball Corporation. (2026, February 3). Ball Reports Strong Fourth Quarter and Full-Year 2025 Results. Ball Corporation Investor News.
- [7] Ball Corporation. (2025, February 4). Ball Corporation Further Optimizes North American Network with Florida Can Manufacturing. Ball Corporation Newsroom.
- [8] Graphic Packaging Holding Company. (2025, September 29). Discover Paperboard Innovation at PACK EXPO 2025 with KeelClip Multipack Cartons for Cans. Graphic Packaging News and Events.
- [9] Sonoco Products Company. (2026, February 16). Sonoco Reports Fourth Quarter and Full Year 2025 Results. Sonoco Investor Relations.
- [10] Wang, L. & Chen, X. (2025, September 11). A Fluorinated Anodic Aluminum Oxide Nanopores Coating for Self-healing and Anti-corrosion. Chemistry A European Journal (PubMed PMID 40746216).
- [11] Tetra Pak International SA. (2025, December 10). Tetra Pak launches world-first paper-based barrier for juice packaging with Garcia Carrion. Tetra Pak News Archive.
- [12] Sonoco Products Company. (2026, January 20). Sonoco Products Company Current Report on Form 8-K. U.S. Securities and Exchange Commission EDGAR.
- [13] Amcor plc. (2026, April 30). Amcor to demonstrate circular capabilities at PRSE 2026. Amcor Media News.
- [14] USDA Foreign Agricultural Service. (2025, November 19). Mexico: Retail Foods Annual. U.S. Department of Agriculture GAIN Report.
- [15] USDA Foreign Agricultural Service. (2026, July 30). European Union: Grain and Feed Quarterly. U.S. Department of Agriculture GAIN Report.
- [16] USDA Foreign Agricultural Service. (2026, March 18). Brazil: Oilseeds and Products Annual. U.S. Department of Agriculture GAIN Report.
- [17] Amcor plc. (2025, December 16). Amcor Collaborates on Danish and UK Food Packaging Recycling Project. Amcor Media News.
- [18] Ball Corporation. (2026, February 20). Ball Corporation Annual Report on Form 10-K for the Fiscal Year Ended December 31 2025. U.S. Securities and Exchange Commission EDGAR.
- [19] Smurfit Westrock plc. (2026, September 3). New European study finds consumers are actively separating packaging for recycling. Smurfit Westrock Newsroom.
- [20] USDA Foreign Agricultural Service. (2026, April 15). Japan: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report JA2026-0012.
- [21] Graphic Packaging Holding Company. (2026, July 23). EU PPWR Packaging Regulation Infographic and Compliance Guide. Graphic Packaging News and Events.
- [22] Sonoco Products Company. (2026, September 28). Sonoco Products Company Form 10-Q Condensed Consolidated Financial Statements. U.S. Securities and Exchange Commission EDGAR.
- [23] Amcor plc. (2026, January 22). Amcor showcases expanded rigid and flexible packaging portfolio at Packaging Innovations 2026. Amcor Media News.
- [24] Tetra Pak International SA. (2026, April 22). Tetra Pak and Sterilgarda Alimenti Launch Industry-First 1-Litre Aseptic Carton with Paper-Based Barrier. Tetra Pak News Archive.
- [25] Crown Holdings. (2025, February 28). Crown Holdings Annual Report on Form 10-K. U.S. Securities and Exchange Commission EDGAR.
- [26] Sealed Air Corporation. (2026, February 25). Sealed Air Corporation Annual Report on Form 10-K for the Year Ended December 31 2025. U.S. Securities and Exchange Commission EDGAR.
- [27] Sonoco Products Company. (2026, June 1). Sonoco Releases Corporate Sustainability Report on Packaging Progress and Award-Winning Products. Sonoco Investor Relations.
- [28] Amcor plc. (2026, September 29). Amcor to present future-ready approach for food and drink packaging at Cibus Tec 2026. Amcor Media News.
- [29] Tetra Pak International SA. (2026, June 15). Tetra Pak advances food system resilience in 27th Sustainability Report as it cuts GHG emissions. Tetra Pak News Archive.
- [30] Mondi Group plc. (2026, August 4). Mondi report on rethinking sustainable food packaging for freshness and less waste. Mondi Group Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the cans market in 2026 and what is forecast for 2036?
- Which beverage plastic-substitution and closed-loop recycling drivers support demand for cans?
- Why does Aluminum Alloy Body lead the substrate material category?
- Why do Two-Piece Drawn and Wall Ironed DWI Cans lead manufacturing structure globally?
- How do growth rates differ across Mexico and Poland with the United Kingdom and the United States?
- Which leading companies supply metal beverage and food cans versus barrier and multipack systems?
- What limits coil margin stability or causes harvest-related volume swings in the cans market?
- What should food and drink packers evaluate before converting to BPA-NI internal can coatings?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Substrate Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Substrate Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Substrate Material, 2026 to 2036
- Aluminum Alloy Body
- Tinplate Coated Steel
- Tin-Free Steel TFS
- Y-o-Y Growth Trend Analysis By Substrate Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Substrate Material, 2026 to 2036
- Global Market Analysis and Forecast, By Manufacturing Structure, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Manufacturing Structure, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Manufacturing Structure, 2026 to 2036
- Two-Piece Drawn and Wall Ironed DWI Cans
- Three-Piece Welded Body Cans
- Y-o-Y Growth Trend Analysis By Manufacturing Structure, 2021 to 2025
- Absolute $ Opportunity Analysis By Manufacturing Structure, 2026 to 2036
- Global Market Analysis and Forecast, By Can Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Can Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Can Format, 2026 to 2036
- 330 ml Standard Sleek Can
- 500 ml King Can
- 250 ml Slim Energy Can
- Above 500 ml Preserved Food Can
- Y-o-Y Growth Trend Analysis By Can Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Can Format, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Carbonated Soft Drinks and Beer
- Canned Seafood and Meat
- Chemical and Cosmetic Aerosols
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Substrate Material
- By Manufacturing Structure
- By Can Format
- By End-Use Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Ball Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Crown Holdings, Inc.
- Sonoco Products Company
- Amcor plc
- Berry Global Group Inc.
- Smurfit Westrock plc
- International Paper Company
- Mondi Group plc
- Tetra Pak International SA
- Sealed Air Corporation
- Rigid Container and Barrier Packaging Groups
- Can Multipack and Secondary Transport System Providers
- Ball Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Substrate Material, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Manufacturing Structure, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Can Format, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Substrate Material, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Manufacturing Structure, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Can Format, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Substrate Material, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Manufacturing Structure, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Can Format, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Substrate Material, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Manufacturing Structure, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Can Format, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Substrate Material, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Manufacturing Structure, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Can Format, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Substrate Material, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Manufacturing Structure, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Can Format, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Substrate Material, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Manufacturing Structure, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Can Format, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Substrate Material, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Manufacturing Structure, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Can Format, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Substrate Material, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Substrate Material, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Substrate Material
- Figure 6: Global Market Value Share and BPS Analysis by Manufacturing Structure, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Manufacturing Structure, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Manufacturing Structure
- Figure 9: Global Market Value Share and BPS Analysis by Can Format, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Can Format, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Can Format
- Figure 12: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-Use Industry
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Substrate Material, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Substrate Material, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Substrate Material
- Figure 29: North America Market Value Share and BPS Analysis by Manufacturing Structure, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Manufacturing Structure, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Manufacturing Structure
- Figure 32: North America Market Value Share and BPS Analysis by Can Format, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Can Format, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Can Format
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Industry
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Substrate Material, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Substrate Material, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Substrate Material
- Figure 42: Latin America Market Value Share and BPS Analysis by Manufacturing Structure, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Manufacturing Structure, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Manufacturing Structure
- Figure 45: Latin America Market Value Share and BPS Analysis by Can Format, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Can Format, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Can Format
- Figure 48: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Substrate Material, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Substrate Material, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Substrate Material
- Figure 55: Western Europe Market Value Share and BPS Analysis by Manufacturing Structure, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Manufacturing Structure, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Manufacturing Structure
- Figure 58: Western Europe Market Value Share and BPS Analysis by Can Format, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Can Format, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Can Format
- Figure 61: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Substrate Material, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Substrate Material, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Substrate Material
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Manufacturing Structure, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Manufacturing Structure, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Manufacturing Structure
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Can Format, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Can Format, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Can Format
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Substrate Material, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Substrate Material, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Substrate Material
- Figure 81: East Asia Market Value Share and BPS Analysis by Manufacturing Structure, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Manufacturing Structure, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Manufacturing Structure
- Figure 84: East Asia Market Value Share and BPS Analysis by Can Format, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Can Format, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Can Format
- Figure 87: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Substrate Material, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Substrate Material, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Substrate Material
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Manufacturing Structure, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Manufacturing Structure, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Manufacturing Structure
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Can Format, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Can Format, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Can Format
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Substrate Material, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Substrate Material, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Substrate Material
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Manufacturing Structure, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Manufacturing Structure, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Manufacturing Structure
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Can Format, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Can Format, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Can Format
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by End-Use Industry
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the cans market in 2026, and what is forecast for 2036?
FMI estimates that the global cans market size stood at USD 90.0 billion in 2025 and reached USD 96.2 billion in 2026. Total industry valuation is projected to hit USD 192.8 billion by 2036 as beverage and food brands with aerosol fillers expand metal container filling.
What is the CAGR for the cans market from 2026 to 2036?
Global metal can demand will advance at a 7.2% CAGR across the ten-year horizon through 2036, generating USD 96.6 billion in net market value across global beverage and food canneries.
Which substrate material segment leads the cans market?
Aluminum Alloy Body containers capture 53.5% of substrate material demand in 2026 because low coil weight and rapid chilling with high used-beverage-can scrap value favor aluminum.
Which manufacturing structure leads the cans market?
Two-Piece Drawn and Wall Ironed DWI Cans represent 73.9% of manufacturing structure output in 2026 as seamless cup-and-wall drawing supports 2,400-can-per-minute beverage lines.
Which country has a notable growth outlook during the assessment period?
Mexico leads national growth projections at an 8.5% CAGR through 2036, followed by Poland at 7.9% and Brazil at 7.6% as export breweries and food packers add canning lines.
Who are the key players in the market?
Tetra Pak International SA and Smurfit Westrock plc with Amcor plc and Berry Global Group participate across global packaging supply. Sealed Air Corporation and Mondi Group plc with Sonoco Products Company and International Paper Company also anchor capacity with Ball Corporation and Crown Holdings.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
