
- Market Size (2026)
- USD 91.3 Bn
- Forecast (2036)
- USD 156.0 Bn
- CAGR (2026 to 2036)
- 5.5%
How big is Clinical Diagnostics Market in 2026?
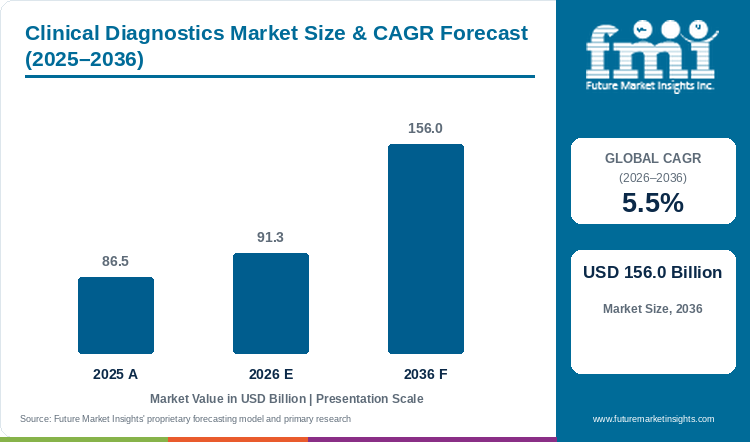
Assessed at USD 86.5 billion in 2025 and progressing to USD 91.3 billion in 2026, the clinical diagnostics laboratory and assay valuation is on course to reach USD 156.0 billion by 2036, supported by a forecast-period CAGR of 5.5%.
As per FMI, global clinical diagnostics market valuation stood at USD 86.5 billion during 2025 and progresses toward USD 91.3 billion for 2026. Across the ten-year horizon through 2036, total sector size climbs to USD 156.0 billion on a 5.5% CAGR while creating USD 64.7 billion in net decade expansion. Whereas the standalone immunochemistry analyzer platforms category is advancing at a 3.4% CAGR, the overall clinical diagnostics market is growing faster because hospitals and reference labs are adding rapid molecular PCR and cancer liquid biopsy tests on top of routine clinical chemistry and core-lab immunoassays, which hold 37.3% of modality share in 2026. Demand for diagnostic tests is supported by multi-year reagent-rental agreements where hospitals place automated track analyzers and buy proprietary barcoded reagent cartridges every week to handle rising patient loads. Specifically, Roche disclosed in its January 2026 full-year financial statement that the Roche Group achieved 7% constant-exchange-rate division growth in 2025 while delivering over 29 billion diagnostic tests globally as cardiac and chemistry cartridge placements expanded across hospital tracks. However, lower government reimbursement rates under Medicare fee schedules and strict European IVDR recertification rules remain major restraining factors that squeeze profit margins for smaller test makers. Even so, suppliers that offer high-speed automated lab tracks with broad test menus will continue to secure long-term hospital contracts through 2036.
Key Market Trends & Insights
- By test modality: Clinical chemistry and core-lab immunoassays secure 37.3% of modality share in 2026 because automated hospital lab modules handle first-line blood and heart screening on every patient admission.
- By product component: Consumable reagents and assay cartridges command 68.7% of component share in 2026 through closed-system barcode locks on installed hospital analyzers.
- By sample matrix: Venous whole blood and serum account for 58.9% of sample share in 2026 owing to standard blood collection tubes used across routine metabolic and immune tests.
- By clinical indication: Infectious and cardiometabolic diseases hold 41.3% of indication share in 2026 driven by multiplex respiratory PCR tests and routine diabetes and cholesterol screening.
- By end user: Hospital and academic medical center core labs represent 49.1% of end-user share in 2026 supported by 24-hour emergency testing and outpatient clinic referrals.
Regional Highlights
- High-growth Asian and Latin hubs: South Korea paces national expansion with a 6.7% ten-year CAGR up to 2036 ahead of Brazil (6.4%) and Australia (6.1%) on private reference lab automation.
- Established healthcare systems: Clinical testing in Canada progresses at a 5.4% CAGR up to 2036, while the United States registers 5.2% and the United Kingdom reaches 5.0%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Clinical Diagnostics Market (USD Billion and CAGR Percent), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 86.5 billion |
| Estimated Market Size in 2026 | USD 91.3 billion |
| Projected Market Size by 2036 | USD 156.0 billion |
| CAGR, 2026 to 2036 | 5.5% |
| Incremental Dollar Opportunity, 2026 to 2036 | USD 64.7 billion |
FMI estimates that annual clinical diagnostics market value climbs above its 2025 level of USD 86.5 billion and its 2026 figure of USD 91.3 billion to reach USD 156.0 billion in 2036, reflecting a 5.5% CAGR. Higher numbers of older patients with chronic diseases are surging the daily test load on hospital labs at a time when qualified lab technicians are in short supply. To process more patient samples without hiring extra staff, hospital directors are connecting automatic tube decappers and blood testing equipment onto conveyor tracks that run 24 hours a day. Meanwhile, insurance reimbursement rules are also shaping which tests labs buy, as shown by the U.S. Centers for Medicare & Medicaid Services updating national payment rates across thousands of chemistry and genetic test codes in its December 2025 Clinical Laboratory Fee Schedule update (MM14312).
Installed Analyzer Fleet and Annual Assay Volume Sizing
Table 2: Installed Analyzer Fleet and Assay Volume Sizing for the Clinical Diagnostics Market (USD Billion and Billion Tests), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 86.5 | 91.3 | 156.0 |
| Active clinical diagnostic analyzers installed (million) | 1.8 to 2.0 | 1.9 to 2.1 | 2.9 to 3.2 |
| Annual reportable clinical tests performed (billion) | 28.5 to 31.0 | 30.2 to 32.8 | 51.0 to 55.5 |
| Average reagent & assay spend per test (USD) | 2.8 to 3.0 | 2.8 to 3.0 | 2.9 to 3.1 |
Operational note: Installed analyzer and test volume ranges aggregate core-lab chemistry and immunoassay tracks with benchtop molecular cyclers across CLIA-certified and ISO 15189 laboratories.
Broad consolidation among regional hospital chains is changing how clinical laboratories buy diagnostic machines and daily test supplies. Instead of paying high upfront prices for separate analyzers, hospital purchasing teams prefer signing five-to-seven-year reagent-rental agreements where one vendor supplies chemistry and immunoassay plus blood-count machines for a fixed price per test. Under these contracts, hospitals bundle clinical diagnostic equipment maintenance with guaranteed four-hour repair service so their emergency lab lines never stop running.
Per Capita & Laboratory Facility Sizing
Table 3: Per Capita and Patient Testing Allocation Indicators for the Clinical Diagnostics Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Diagnostic market value per 1,000 people (USD) | 10,548.8 | 11,000.0 | 17,333.3 |
| Annual diagnostic spend per hospitalized patient (USD) | 185.0 to 220.0 | 195.0 to 230.0 | 280.0 to 335.0 |
| Reagent-rental consumable contract share (%) | 68.0% to 68.5% | 68.5% to 69.0% | 71.5% to 73.0% |
Table 4: Accredited Laboratory & Hospital Core-Lab Indicators for the Clinical Diagnostics Market (USD Billion), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 91.3 billion | 2026 global industry valuation baseline |
| Accredited hospital & reference labs | 540,000 laboratories | Global CLIA and ISO 15189 laboratory registry |
| Average annual IVD procurement per lab | USD 169,074.1 | Annualized reagent and analyzer budget |
| Hospital & academic core-lab allocation, 2026 | USD 44.8 billion | 49.1% end-user segment share allocation |
Strong patient demand for fast answers during a single doctor visit is driving outpatient clinics and urgent-care centers to install compact tabletop test machines. When a patient comes in with chest pain or a respiratory fever, doctors do not want to wait 24 hours for an outside reference lab to send back results. As a result, outpatient clinics are adopting point-of-care molecular diagnostics that deliver accurate results in 20 minutes and send the report straight into the hospital computer system.
Analyst Perspective
"Hospital lab purchasing has shifted from buying standalone machines to signing long-term contracts based on test turnaround time and reagent cost per patient. Diagnostic suppliers that lock barcoded reagent cartridges onto automated hospital lab tracks while adding fast cancer and infection tests are capturing the steadiest ten-year revenue streams."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the clinical diagnostics market segmented?
The clinical diagnostics market is segmented by test modality, product component, sample matrix, clinical indication, and end user, and region. In 2026, clinical chemistry & core-lab immunoassays are projected at 37.3%, consumable reagents, calibrators & assay cartridges at 68.7%, venous whole blood, serum & plasma at 58.9%, infectious & cardiometabolic diseases at 41.3%, and hospital & academic medical center core labs at 49.1%.
By test modality: clinical chemistry & core-lab immunoassays, molecular diagnostics PCR, NGS & liquid biopsy, hematology, coagulation & flow cytometry, and microbiology, mass spectrometry & point-of-care.
By product component: consumable reagents, calibrators & assay cartridges, automated benchtop & high-throughput track analyzers, and laboratory information & middleware software.
By sample matrix: venous whole blood, serum & plasma, urine & cerebral/synovial fluids, and tissue biopsy & swab specimens.
By clinical indication: infectious & cardiometabolic diseases, oncology companion diagnostics & minimal residual disease, and endocrinology, autoimmune & nephrology.
By end user: hospital & academic medical center core labs, independent commercial reference laboratories, and physician office labs & urgent care clinics.
Why do clinical chemistry and core-lab immunoassays account for a notable share of test modality demand?
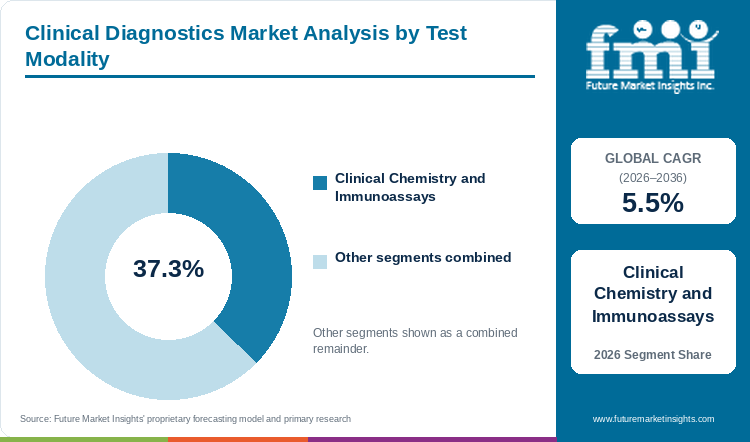
Clinical chemistry and core-lab immunoassays secure 37.3% of test modality share in 2026, anchored by high-speed serum work area automation.
Table 5: Test Modality Share for the Clinical Diagnostics Market (Percentage Share), 2026
| Test Modality | Share (2026) |
|---|---|
| Clinical Chemistry & Core-Lab Immunoassays | 37.3% |
| Other Test Modalities Combined | 62.7%* |
| Total | 100.0% |
*Note: Remaining test modalities sum to 100.0% of 2026 global clinical diagnostics market value.
Table 6: Test Modality Leadership and Growth for the Clinical Diagnostics Market (Segment and Value), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.5% |
| Leading Test Modality | Clinical Chemistry & Core-Lab Immunoassays |
FMI's modality assessment shows that high-speed serum work areas combining routine chemistry with immunoassay modules can run up to 4,000 tests an hour from a single tube of blood. Hospital labs link these core analyzers with automated molecular diagnostic testing systems so technicians can handle daily kidney and liver checks plus thyroid and heart panels on one track.
- Clinical chemistry and core-lab immunoassays capture 37.3% of modality share in 2026 because high-sensitivity cardiac troponin and hepatic-renal panels remain mandatory on acute admissions.
- In its January 2026 earnings release, Danaher Corporation reported that full-year 2025 revenue reached USD 24.6 billion, supported by steady repeat orders for Beckman Coulter clinical chemistry and immunoassay consumables across hospitals.
What supports consumable reagents and assay cartridges as a preferred choice by product component?
Consumable reagents and assay cartridges represent 68.7% of the product component category in 2026, sustained by closed-system reagent-rental analyzer contracts.
Diagnostic companies place analyzers in hospitals at low upfront prices and earn most of their money from the barcoded reagent packs and single-use test cartridges that labs must buy every week. To keep up with rising cartridge demand, major diagnostic brands also partner with in vitro diagnostic contract manufacturing suppliers for freeze-dried test reagents and calibration fluids.
- Consumable reagents and assay cartridges command 68.7% of component share in 2026 owing to multi-year reagent-rental agreements that tie assay volume to hospital bed occupancy.
- According to Thermo Fisher Scientific Inc. in its Form 10-K filed during February 2026, consolidated revenue reached USD 43.2 billion in 2025 as its Specialty Diagnostics division supplied recurring immunodiagnostic and microbiology test consumables to clinical labs.
How is venous whole blood, serum and plasma gaining use across sample matrix applications?
Venous whole blood and serum hold 58.9% of sample matrix share in 2026, reflecting standardized phlebotomy collection across core laboratories.
Standard blood-draw tubes allow hospital labs to run cholesterol and hormone panels plus blood-cell and cancer DNA tests from a single patient sample without taking a painful tissue biopsy. Hospital hematology labs also connect digital cell counters with flow cytometry analyzer systems to detect blood cancers and immune disorders quickly from venous blood.
- Venous whole blood and serum secure 58.9% of sample matrix share in 2026 driven by automated pneumatic tube transport and robotic serum centrifugation in hospital core labs.
- During November 2025, Siemens Healthineers AG disclosed in its fiscal year release that its Diagnostics division placed over 1,000 Atellica Solution and Atellica CI analyzer systems across hospital blood-testing labs in fiscal 2025.
Why are buyers selecting infectious and cardiometabolic diseases panels within clinical indications?
Infectious and cardiometabolic diseases generate 41.3% of clinical indication share in 2026, powered by multiplex respiratory PCR and chronic metabolic screening.
Hospitals run thousands of blood-sugar and cholesterol checks every day and run rapid PCR panels that test for flu and sepsis in one cartridge. Fast germ identification within a few hours helps doctors give the right antibiotic immediately and shorten intensive-care stays.
- Infectious and cardiometabolic diseases account for 41.3% of clinical indication share in 2026 supported by antimicrobial stewardship mandates and preventive cardiovascular screening.
- According to bioMerieux SA in its February 2026 investor presentation, fiscal 2025 organic sales grew 6.5% as cumulative global installations of BIOFIRE rapid infectious molecular systems passed 27,800 units.
Which market conditions keep hospital and academic medical center core labs relevant by end user?
Hospital and academic medical center core labs capture 49.1% of end-user share in 2026, supported by 24-hour inpatient stat testing and integrated health-system tracks.
Large hospital systems are bringing complex genetic and hormone panels plus blood-clotting tests back into their own central labs instead of paying outside commercial labs to run them. In-house test processing saves money and gives emergency-room doctors faster results, while specialized outpatient centers also account for 45.9% of clinical setting demand.
- Hospital and academic medical center core labs hold 49.1% of end-user share in 2026 attributable to consolidated multi-hospital track automation and 24-hour emergency stat turnaround requirements.
- Per Sysmex Corporation in its September 2026 Integrated Report, global reagent annuity sales grew across more than 85,000 active XR-Series blood-count tracks and coagulation analyzers in hospital core labs.
What are the drivers, restraints, and opportunities in the clinical diagnostics market?
Within the clinical diagnostics market, automated core-lab tracks and oncology liquid biopsies expand assay volumes whereas EU IVDR compliance costs restrain small lab margins and CLIA-waived point-of-care cartridges create decentralized revenue streams.
- Driver: Stricter cancer companion testing rules and multiplex infection panels compel hospital and reference labs to expand automated molecular and immunoassay capacity.
- Restraint: Strict EU IVDR recertification paperwork and Medicare PAMA fee cuts lengthen test launch timelines and squeeze laboratory profit margins.
- Opportunity: Blood-based liquid biopsy cancer tests and CLIA-waived 15-minute point-of-care molecular cartridges open high-margin outpatient revenue streams.
Growth Analysis and Future Potential: Liquid Biopsy and Multiplex Molecular Adoption
Future Market Insights notes that cancer doctors and infectious disease specialists are actively ordering blood-based tumor DNA tests and multiplex PCR cartridges so they can pick the right drug without putting patients through invasive surgical biopsies. Hospital cancer centers pair clinical oncology next-generation sequencing with automated blood-plasma DNA extractors to spot cancer relapse months before it shows up on a scan. Specifically, a January 2026 study by Chen and co-authors in Molecular Cancer showed that combining cell-free DNA mutation signals with methylation markers in blood tests significantly improves early multi-cancer detection. This shift toward simple blood draws for cancer monitoring is driving high-margin assay sales across oncology labs.
Risk Assessment of the Clinical Diagnostics Market: Regulatory Compliance and Reimbursement Friction
Higher regulatory approval costs under the European Union In Vitro Diagnostic Regulation (IVDR) and tighter rules on lab-developed tests in the United States are a major hurdle for diagnostic companies. Hospitals that run their own hematology diagnostics workflows and custom genetic tests now have to submit clinical validation files to keep insurance reimbursement. Per a November 2025 regulatory review by Vogelsang and Hoffmann in Journal of Laboratory Medicine, differences in quality-system and review rules between the United States and Europe are delaying the launch of specialty diagnostic assays. Smaller diagnostic firms often struggle to afford these long certification reviews, which slows down new test rollouts.
Commercial Opportunity Analysis: Near-Patient Point-of-Care and AI Bioinformatics
Outpatient surgery centers and cancer infusion clinics plus urgent-care chains are creating strong growth opportunities for compact tabletop analyzers that give lab-quality blood-count and infection results during a single patient visit. Direct clinic placement of cloud-connected point-of-care diagnostic instruments removes sample shipping delays and lets doctors adjust chemotherapy or antibiotic doses on the spot. Recent hospital validation data confirm this benefit, with February 2026 research from Katz and Levy in International Journal of Laboratory Hematology found that compact point-of-care hematology analyzers matched central hospital lab accuracy across outpatient oncology clinics. Vendors offering easy-to-use cartridge analyzers are winning new orders from decentralized clinics.
Clinical Diagnostics Market by Country (2026 to 2036)
As per FMI, country-level expansion across the clinical diagnostics sector depends on national health insurance test coverage and private reference laboratory consolidation. South Korea tops the eight evaluated nations with a 6.7% CAGR up to 2036, ahead of Brazil (6.4%) plus Australia (6.1%) and Canada (5.4%).
Table 7: Country CAGR and Primary Growth Levers for the Clinical Diagnostics Market (CAGR Percent), 2026 to 2036
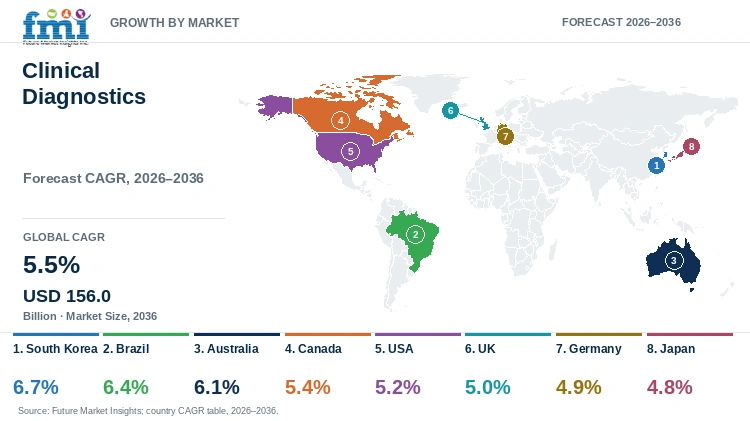
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 6.7% | National Health Insurance cancer screening and domestic multiplex PCR automation |
| Brazil | 6.4% | Private diagnostic mega-lab track consolidation and arbovirus/oncology molecular assays |
| Australia | 6.1% | MBS-funded molecular bowel/cervical screening and private pathology track consolidation |
| Canada | 5.4% | PHAC AMRNet 29-pathogen surveillance and provincial hospital reagent-rental tracks |
| USA | 5.2% | Oncology liquid biopsy reimbursement and CLIA-waived point-of-care molecular expansion |
| UK | 5.0% | NHS Community Diagnostic Centre rollouts and consolidated pathology network tenders |
| Germany | 4.9% | Automated MVZ laboratory networks and statutory EBM companion diagnostic coverage |
| Japan | 4.8% | Reimbursed oncology genomic profiling and super-aging neurology/cardiac biomarkers |
Source: Future Market Insights analysis
South Korea Clinical Diagnostics Market Outlook (2026 to 2036)
South Korea registers a 6.7% ten-year rate of CAGR through 2036, supported by universal National Health Insurance cancer screening checks and strong domestic production of molecular PCR test kits. University hospitals and commercial reference labs across the country run automated PCR and immunoassay tracks to handle nationwide stomach and liver plus lung cancer checkups. Per a September 2026 study by Euler and Abd El Wahed in Diagnostics, rapid molecular amplification test kits are expanding fast infection screening across Asia-Pacific outpatient clinics. Although government health insurance price caps limit how much labs can charge per routine blood test, local manufacturers like Seegene and SD Biosensor protect their margins by selling multi-pathogen PCR cartridges.
Key takeaway: In South Korea, national biennial cancer screening mandates and domestic multiplex PCR automation maintain a 6.7% ten-year CAGR.
Brazil Clinical Diagnostics Market Outlook (2026 to 2036)
Rapid expansion of large private hospital-and-lab chains such as Dasa and Fleury combined with public health fever surveillance is driving diagnostic demand across Brazil. Fueled by private health insurance outpatient checkups, clinical diagnostics demand across Brazil delivers a 6.4% CAGR over the decade to 2036. Central reference labs use high-speed conveyor tracks to test thousands of blood samples each day for dengue and Zika viruses plus diabetes and cancer markers. Per a January 2026 oncology diagnostics study by Alix-Panabieres and Pantel in Signal Transduction and Targeted Therapy, blood-based tumor DNA and protein panels improve early cancer staging across tertiary hospitals. Global vendors bottle reagents locally in Brazil to avoid import customs delays.
Key takeaway: In Brazil, private diagnostic mega-lab track automation and multiplex arbovirus and oncology testing secure a 6.4% ten-year CAGR.
Australia Clinical Diagnostics Market Outlook (2026 to 2036)
Medicare Benefits Schedule pathology funding and large private lab networks led by Sonic Healthcare and Healius set the pace for diagnostic purchasing across Australia. In an August 2025 study published in Healthcare, Crothers and Pathology Awareness Australia reported a strong rebound in private pathology test volumes as well as rising chronic disease and cancer biomarker orders across Australian clinics. Supported by national bowel and cervical molecular screening programs, diagnostic demand in Australia secures a 6.1% ten-year rate of CAGR up to 2036. Because long distances between rural towns and city labs raise sample transport costs and government bulk-billing fees are frozen, lab chains install automated sample-sorting tracks and rural point-of-care analyzers.
Key takeaway: In Australia, Medicare-funded molecular cancer screening and private pathology track consolidation support a 6.1% decade CAGR.
Canada Clinical Diagnostics Market Outlook (2026 to 2036)
Provincial public hospital labs working with community reference chains such as LifeLabs and Dynacare handle the bulk of diagnostic testing across metropolitan and rural provinces in Canada. In February 2026, the Public Health Agency of Canada AMRNet Working Group reported in Canada Communicable Disease Report that national lab surveillance now tracks 29 priority drug-resistant germs with capacity to capture 90% of priority isolates across provincial labs. Driven by multi-year reagent-rental track contracts and cancer liquid biopsy coverage, the clinical diagnostics sector in Canada expands at a 5.4% compound annual CAGR up to 2036. Automated sample-sorting lines help hospital labs handle rising test volumes despite tight provincial budgets and technician shortages.
Key takeaway: In Canada, PHAC national antimicrobial-resistance molecular surveillance and provincial reference lab automation anchor a 5.4% decade CAGR.
USA Clinical Diagnostics Market Outlook (2026 to 2036)
Clinical diagnostics demand across the United States posts a 5.2% CAGR during the 2026 to 2036 window, anchored by over 320,000 CLIA-certified lab sites and national commercial reference networks led by Quest Diagnostics and Labcorp. Unlike single-payer European health systems, private insurance and Medicare Advantage plans in the United States pay high rates for cancer minimal residual disease blood tests and rapid urgent-care molecular panels. According to U.S. Food and Drug Administration CDRH CLIA Waiver Decision Summaries updated in July 2026, rapid multi-virus respiratory and strep molecular tests continue to win clearance for doctor office labs. Hospitals install automated core-lab tracks to offset high lab technician wages.
Key takeaway: In the USA, oncology liquid biopsy reimbursement and CLIA-waived point-of-care molecular expansion power a 5.2% annual CAGR.
UK Clinical Diagnostics Market Outlook (2026 to 2036)
National Health Service investments in Community Diagnostic Centres outside busy hospital wards are reshaping how blood and infection tests are delivered across the United Kingdom. Laboratory sector valuation in the United Kingdom posts a 5.0% decade-long CAGR through 2036 via consolidated NHS pathology tenders and fast point-of-care testing in neighborhood health hubs. According to the Medicines and Healthcare products Regulatory Agency Corporate Plan updated in June 2025, faster UKCA diagnostic approval rules are helping hospitals adopt new genetic and infection tests sooner. Although tight NHS hospital budgets limit upfront equipment spending, regional pathology networks pool their orders onto shared high-speed analyzer tracks to cut the cost per test.
Key takeaway: In the UK, NHS Community Diagnostic Centre rollouts and consolidated pathology network tenders yield a 5.0% ten-year CAGR.
Germany Clinical Diagnostics Market Outlook (2026 to 2036)
Outpatient medical care centers (Medizinische Versorgungszentren) and large private lab groups such as Synlab and Limbach Gruppe drive clinical testing volumes across Germany. Labs across the country are investing in robotic tube-sorting lines and mass spectrometry machines while completing mandatory European Union IVDR certification for high-risk infection and cancer companion tests. Per an August 2025 article by Plebani and Lippi in Clinical Chemistry and Laboratory Medicine, adding blood-based liquid biopsy into routine pathology labs improves cancer treatment tracking. Supported by statutory public health insurance coverage for precision cancer and heart markers, consolidated laboratory demand across Germany secures a 4.9% CAGR across the ten-year forecast horizon.
Key takeaway: In Germany, automated MVZ reference laboratory networks and statutory precision oncology reimbursement produce a 4.9% decade CAGR.
Japan Clinical Diagnostics Market Outlook (2026 to 2036)
Strong demand from an aging population for Alzheimer blood tests and cancer relapse monitoring plus blood-clotting checks shapes the clinical diagnostics market across Japan. Large commercial reference labs such as SRL (Miraca Holdings) and BML run highly automated central labs and support university hospital pathology departments nationwide. Per a December 2025 oncology study by Sasaki and Watanabe in International Journal of Clinical Oncology, blood-based minimal residual disease testing and genomic cancer profiling are expanding rapidly across hospitals in Japan under national health insurance coverage. Even though government fee reviews trim routine blood-test prices every two years, analyzer upgrades from Sysmex and Fujirebio advance annual valuation in Japan at a 4.8% compound annual CAGR through 2036.
Key takeaway: In Japan, reimbursed oncology genomic profiling and super-aging cardiometabolic and neurology biomarker panels generate a 4.8% annual CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the clinical diagnostics market?
F. Hoffmann-La Roche Ltd, Abbott Laboratories, Danaher Corporation, Siemens Healthineers AG, Thermo Fisher Scientific Inc., Sysmex Corporation, bioMerieux SA, and Becton, Dickinson and Company are the notable companies in the clinical diagnostics market.
FMI analysis indicates that competition across the clinical diagnostics sector is moderately concentrated among global full-line core-lab and molecular IVD conglomerates, specialized molecular and life-science diagnostic innovators, and automated hematology and clinical microbiology leaders. Major diagnostic manufacturers are broadening their automated assay menus and point-of-care cartridges to lock in multi-year hospital lab contracts.
- Full-Line Core-Lab & Immunoassay Leaders: Roche Diagnostics and Abbott Laboratories with Danaher Corporation and Siemens Healthineers AG supply integrated chemistry and molecular track systems to hospital networks.
- Molecular, Genomic & Specialty IVD Innovators: Thermo Fisher Scientific Inc. and Becton, Dickinson and Company provide companion oncology NGS and automated blood-culture and molecular platforms.
- Hematology & Syndromic Microbiology Specialists: Sysmex Corporation and bioMerieux SA lead in automated cellular hematology with hemostasis coagulation tracks and rapid BIOFIRE syndromic infectious PCR panels.
Competitive Benchmarking: Clinical Diagnostics Market
Table 8: Competitive Benchmarking for the Clinical Diagnostics Market (Qualitative Capability Ratings), 2026
| Company | Core-Lab Chemistry & Immunoassay Breadth | Molecular PCR & Liquid Biopsy Depth | Total Lab Automation Connectivity | Geographic Reach |
|---|---|---|---|---|
| F. Hoffmann-La Roche Ltd | High | High | High | High |
| Abbott Laboratories | High | High | High | High |
| Danaher Corporation | High | High | High | High |
| Siemens Healthineers AG | High | Medium | High | High |
| Thermo Fisher Scientific Inc. | Medium | High | Medium | High |
| Sysmex Corporation | Medium | Medium | High | High |
| bioMerieux SA | Medium | High | High | High |
| Becton, Dickinson and Company | Medium | High | High | High |
Capability tiers evaluate core-lab chemistry and immunoassay menu breadth with molecular PCR and NGS depth as well as total laboratory automation connectivity and global service reach.
Key Developments in the Clinical Diagnostics Market
- In July 2026, Danaher Corporation published second-quarter 2026 financial results confirming sustained clinical diagnostics consumable growth across Cepheid GeneXpert molecular cartridges and Beckman Coulter immunoassay systems.
- In March 2026, Roche reported in its 2025 Annual Report that its Diagnostics division expanded installations of cobas pro integrated solutions and cobas mass spec analyzers across global hospital core labs.
- In November 2025, Becton, Dickinson and Company disclosed fiscal 2025 annual results documenting continued adoption of BD COR high-throughput molecular systems and BD BACTEC blood-culture automation across hospital microbiology labs.
Key Players in the Clinical Diagnostics Market
Global Core-Lab & Integrated IVD Leaders
- F. Hoffmann-La Roche Ltd
- Abbott Laboratories
- Danaher Corporation
Siemens Healthineers AG
- Molecular, Mass Spectrometry & Specialty IVD Leaders
- Thermo Fisher Scientific Inc.
- Becton, Dickinson and Company
Hematology, Coagulation & Microbiology Specialists
- Sysmex Corporation
- bioMerieux SA
Clinical Diagnostics Market - Report Scope
Table 9: Report Scope for the Clinical Diagnostics Market (Coverage Fields and Definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Test Modality; Product Component; Sample Matrix; Clinical Indication; End User; Clinical Setting |
| Quantitative Units | USD Billion |
| Market Definition | Covers global commercial valuation of clinical chemistry and immunoassay systems, molecular diagnostics (PCR, NGS, liquid biopsy), hematology/coagulation/flow cytometry, clinical microbiology, mass spectrometry, point-of-care analyzers, consumable reagents, and lab middleware. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea, Brazil, Australia, Canada, USA, UK, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Danaher Corporation, Siemens Healthineers AG, Thermo Fisher Scientific Inc., Sysmex Corporation, bioMerieux SA, Becton, Dickinson and Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation in USD Billion. |
Clinical Diagnostics Market - Research Methodology
Table 10: Research Methodology for the Clinical Diagnostics Market (Research Methods and Approach), 2026 to 2036
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from hospital core-lab pathology directors, commercial reference lab executives, molecular oncology laboratory managers, and IVD procurement teams examining analyzer evaluation, reagent-rental contracting, and regulatory approval barriers. |
| Desk Research | Desk research covered CMS Clinical Laboratory Fee Schedule updates, FDA CLIA waiver summaries, MHRA and EU IVDR regulatory publications, peer-reviewed pathology studies in PMC, SEC Form 10-K filings, and official IVD manufacturer disclosures. |
| Market Sizing and Forecasting | The market assessment combined the 2025 baseline valuation with installed analyzer fleet counts, annual consumable pull-through per instrument, assay pricing indicators, and country-level testing volumes from 2026 to 2036. |
| Country Forecasting Model | Country projections weight hospital bed density, CLIA and ISO 15189 laboratory accreditation counts, national cancer screening participation, and public/private assay reimbursement schedules. |
| Operational Benchmark Traceability | Analyzer fleet and test volume indicators in Tables 2, 3, and 4 trace to CMS CLIA laboratory registries, Roche and Danaher annual disclosures, and peer-reviewed pathology studies. |
| Data Validation | Estimates were checked against independent public health and corporate indicators and locked in USD Billion with zero mixing of million units, excluding overlapping life-science research revenues to prevent double counting. |
Clinical Diagnostics Market by Segments
Clinical Diagnostics Market segmented by Test Modality:
- Clinical Chemistry and Immunoassays
- Molecular Diagnostics and Biopsy
- Hematology and Flow Cytometry
- Microbiology and Point-of-Care
Clinical Diagnostics Market segmented by Product Component:
- Reagents and Assay Cartridges
- Automated Track Analyzers
- Laboratory Information Software
Clinical Diagnostics Market segmented by Sample Matrix:
- Venous Blood and Serum
- Urine and Synovial Fluids
- Tissue and Swab Specimens
Clinical Diagnostics Market segmented by Clinical Indication:
- Infectious and Cardiometabolic Diseases
- Oncology Companion Diagnostics
- Endocrinology and Nephrology
Clinical Diagnostics Market segmented by End User:
- Hospital Core Laboratories
- Commercial Reference Laboratories
- Physician Office Clinics
Clinical Diagnostics Market segmented by Clinical Setting:
- Outpatient and Ambulatory Centers
- Acute-Care Inpatient Hospitals
Clinical Diagnostics Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] F. Hoffmann-La Roche Ltd. (2026, January 29). Ad Hoc Announcement Pursuant to Art. 53 LR: Roche Reports Strong 2025 Results With 7% Group Sales Growth and Diagnostics Expansion. F. Hoffmann-La Roche Investor Updates.
- [2] Centers for Medicare & Medicaid Services (CMS). (2025, December 5). Clinical Laboratory Fee Schedule: 2026 Annual Update (MLN Matters Number MM14312). U.S. Department of Health and Human Services CMS.
- [3] Danaher Corporation. (2026, January 28). Danaher Reports Fourth Quarter and Full Year 2025 Results (Diagnostics and Molecular Revenue Performance). Danaher Investor Relations.
- [4] Thermo Fisher Scientific Inc. (2026, February 25). Annual Report on Form 10-K for the Fiscal Year Ended December 31, 2025 (Specialty Diagnostics Segment). U.S. Securities and Exchange Commission EDGAR.
- [5] Siemens Healthineers AG. (2025, November 5). Siemens Healthineers Successfully Closes 2025 Fiscal Year in Diagnostics and Imaging. Siemens Healthineers Press Releases.
- [6] bioMerieux SA. (2026, February 27). Full-Year 2025 Financial Results Investor Presentation: BIOFIRE Molecular and Clinical Microbiology Growth. bioMerieux Investor Relations.
- [7] Sysmex Corporation. (2026, September 29). Sysmex Report 2026 (Integrated Annual Report for the Fiscal Year Ended March 31, 2026). Sysmex Corporation Investor Library.
- [8] Chen, X., Wang, Y., & Liu, Z. (2026, January 12). Liquid Biopsy in Early Screening of Cancers: Multimodal Cell-Free DNA and Methylation Frameworks. Molecular Cancer, 25(1), 14 (PMC12839035).
- [9] Vogelsang, M., & Hoffmann, G. (2025, November 18). Regulation of laboratory-developed tests and in-house in vitro diagnostic medical devices in the USA and EU. Journal of Laboratory Medicine, 49(6), 245-258 (PMC12702205).
- [10] Katz, B. Z., & Levy, S. (2026, February 10). Clinical Evaluation of a Novel Point-of-Care Hematology Analyzer Across Integrated Healthcare Settings. International Journal of Laboratory Hematology, 48(1), 88-97 (PMC12956494).
- [11] Euler, M., & Abd El Wahed, A. (2026, September 1). Point of Care Testing and Recombinase Polymerase Amplification in Clinical Diagnostics. Diagnostics, 16(9), 1842 (PMC13531096).
- [12] Alix-Panabieres, C., & Pantel, K. (2026, January 12). Liquid biopsy in cancer diagnosis and prognosis: circulating tumor cells and ctDNA. Signal Transduction and Targeted Therapy, 11(1), 19 (PMC12832364).
- [13] Crothers, J., & Pathology Awareness Australia. (2025, August 15). Pandemic Disruptions and Recovery in Private Pathology Testing Uptake in Australia. Healthcare, 13(16), 1984 (PMC12389203).
- [14] Public Health Agency of Canada (PHAC) AMRNet Working Group. (2026, February 18). AMR Surveillance in Canada: Insights From the 2025 Priority Pathogen List and National Laboratory Network. Canada Communicable Disease Report, 52(2), 45-58 (PMC12915920).
- [15] U.S. Food and Drug Administration (FDA). (2026, July 24). CLIA Waiver by Application Decision Summaries for Point-of-Care Diagnostic Assays. U.S. Food and Drug Administration CDRH.
- [16] Medicines and Healthcare products Regulatory Agency (MHRA). (2025, June 25). Medicines and Healthcare Products Regulatory Agency Corporate Plan 2023 to 2026: Diagnostics and IVD Reform. UK Government Publishing Service.
- [17] Plebani, M., & Lippi, G. (2025, August 14). Liquid biopsy: a step forward in laboratory medicine and molecular pathology. Clinical Chemistry and Laboratory Medicine, 63(9), 1645-1654 (PMC12446909).
- [18] Sasaki, T., & Watanabe, M. (2025, December 16). Current Status and Future Challenges of Liquid Biopsy and Minimal Residual Disease Testing. International Journal of Clinical Oncology, 30(12), 2310-2322 (PMC12731910).
- [19] Danaher Corporation. (2026, July 21). Danaher Reports Second Quarter 2026 Results (Cepheid and Beckman Coulter Diagnostics). Danaher Investor Relations.
- [20] F. Hoffmann-La Roche Ltd. (2026, March 4). Roche Annual Report 2025: Diagnostics Division Core Lab and Molecular Solutions. F. Hoffmann-La Roche Corporate Reporting.
- [21] Becton, Dickinson and Company. (2025, November 25). Annual Report on Form 10-K for the Fiscal Year Ended September 30, 2025 (BD Life Sciences Diagnostic Solutions). U.S. Securities and Exchange Commission EDGAR.
- [22] Danaher Corporation. (2026, February 20). Annual Report on Form 10-K for the Fiscal Year Ended December 31, 2025. U.S. Securities and Exchange Commission EDGAR.
- [23] U.S. Food and Drug Administration (FDA). (2026, August 11). In Vitro Diagnostics Emergency Use Authorizations and 510(k) Transition Updates. U.S. Food and Drug Administration.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete citation list and detailed source mapping.
This Report Answers
- What is the valuation of the clinical diagnostics market in 2026 and 2036?
- How do reagent-rental track contracts lock in recurring consumable revenue?
- Why do clinical chemistry and immunoassays lead modality demand in 2026?
- Why do consumable reagents account for 68.7% of component demand?
- How do growth rates compare across South Korea, Brazil, and the USA?
- Which global IVD manufacturers lead core-lab automation and molecular diagnostics?
- How do Medicare PAMA updates and EU IVDR recertification affect margins?
- What assay throughput specifications guide hospital core-lab procurement through 2036?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Test Modality, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Test Modality, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Test Modality, 2026 to 2036
- Clinical Chemistry and Immunoassays
- Molecular Diagnostics and Biopsy
- Hematology and Flow Cytometry
- Microbiology and Point-of-Care
- Y-o-Y Growth Trend Analysis By Test Modality, 2021 to 2025
- Absolute $ Opportunity Analysis By Test Modality, 2026 to 2036
- Global Market Analysis and Forecast, By Product Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Component, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Component, 2026 to 2036
- Reagents and Assay Cartridges
- Automated Track Analyzers
- Laboratory Information Software
- Y-o-Y Growth Trend Analysis By Product Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Component, 2026 to 2036
- Global Market Analysis and Forecast, By Sample Matrix, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sample Matrix, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sample Matrix, 2026 to 2036
- Venous Blood and Serum
- Urine and Synovial Fluids
- Tissue and Swab Specimens
- Y-o-Y Growth Trend Analysis By Sample Matrix, 2021 to 2025
- Absolute $ Opportunity Analysis By Sample Matrix, 2026 to 2036
- Global Market Analysis and Forecast, By Clinical Indication, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Clinical Indication, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Clinical Indication, 2026 to 2036
- Infectious and Cardiometabolic Diseases
- Oncology Companion Diagnostics
- Endocrinology and Nephrology
- Y-o-Y Growth Trend Analysis By Clinical Indication, 2021 to 2025
- Absolute $ Opportunity Analysis By Clinical Indication, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Hospital Core Laboratories
- Commercial Reference Laboratories
- Physician Office Clinics
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Clinical Setting, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Clinical Setting, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Clinical Setting, 2026 to 2036
- Outpatient and Ambulatory Centers
- Acute-Care Inpatient Hospitals
- Y-o-Y Growth Trend Analysis By Clinical Setting, 2021 to 2025
- Absolute $ Opportunity Analysis By Clinical Setting, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- By Country
- Market Attractiveness Analysis
- By Country
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Test Modality
- By Product Component
- By Sample Matrix
- By Clinical Indication
- By End User
- By Clinical Setting
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- F. Hoffmann-La Roche Ltd
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Abbott Laboratories
- Danaher Corporation
- Siemens Healthineers AG
- Thermo Fisher Scientific Inc.
- Sysmex Corporation
- bioMerieux SA
- Becton, Dickinson and Company
- Molecular, Mass Spectrometry & Specialty IVD Leaders
- F. Hoffmann-La Roche Ltd
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Test Modality, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Product Component, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Sample Matrix, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 7: Global Market Value (USD Billion) Forecast by Clinical Setting, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Test Modality, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Product Component, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Sample Matrix, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 13: North America Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 14: North America Market Value (USD Billion) Forecast by Clinical Setting, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Test Modality, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Product Component, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Sample Matrix, 2021 to 2036
- Table 19: Latin America Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 20: Latin America Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 21: Latin America Market Value (USD Billion) Forecast by Clinical Setting, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Test Modality, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Product Component, 2021 to 2036
- Table 25: Western Europe Market Value (USD Billion) Forecast by Sample Matrix, 2021 to 2036
- Table 26: Western Europe Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 27: Western Europe Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 28: Western Europe Market Value (USD Billion) Forecast by Clinical Setting, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Test Modality, 2021 to 2036
- Table 31: Eastern Europe Market Value (USD Billion) Forecast by Product Component, 2021 to 2036
- Table 32: Eastern Europe Market Value (USD Billion) Forecast by Sample Matrix, 2021 to 2036
- Table 33: Eastern Europe Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 34: Eastern Europe Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 35: Eastern Europe Market Value (USD Billion) Forecast by Clinical Setting, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: East Asia Market Value (USD Billion) Forecast by Test Modality, 2021 to 2036
- Table 38: East Asia Market Value (USD Billion) Forecast by Product Component, 2021 to 2036
- Table 39: East Asia Market Value (USD Billion) Forecast by Sample Matrix, 2021 to 2036
- Table 40: East Asia Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 41: East Asia Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 42: East Asia Market Value (USD Billion) Forecast by Clinical Setting, 2021 to 2036
- Table 43: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: South Asia and Pacific Market Value (USD Billion) Forecast by Test Modality, 2021 to 2036
- Table 45: South Asia and Pacific Market Value (USD Billion) Forecast by Product Component, 2021 to 2036
- Table 46: South Asia and Pacific Market Value (USD Billion) Forecast by Sample Matrix, 2021 to 2036
- Table 47: South Asia and Pacific Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 48: South Asia and Pacific Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 49: South Asia and Pacific Market Value (USD Billion) Forecast by Clinical Setting, 2021 to 2036
- Table 50: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 51: Middle East and Africa Market Value (USD Billion) Forecast by Test Modality, 2021 to 2036
- Table 52: Middle East and Africa Market Value (USD Billion) Forecast by Product Component, 2021 to 2036
- Table 53: Middle East and Africa Market Value (USD Billion) Forecast by Sample Matrix, 2021 to 2036
- Table 54: Middle East and Africa Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 55: Middle East and Africa Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 56: Middle East and Africa Market Value (USD Billion) Forecast by Clinical Setting, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Test Modality, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Test Modality, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Test Modality
- Figure 6: Global Market Value Share and BPS Analysis by Product Component, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Product Component, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Product Component
- Figure 9: Global Market Value Share and BPS Analysis by Sample Matrix, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Sample Matrix, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Sample Matrix
- Figure 12: Global Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Clinical Indication
- Figure 15: Global Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by End User
- Figure 18: Global Market Value Share and BPS Analysis by Clinical Setting, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Clinical Setting, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Clinical Setting
- Figure 21: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 22: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 23: Global Market Attractiveness Analysis by Region
- Figure 24: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 29: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 30: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 31: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 32: North America Market Value Share and BPS Analysis by Test Modality, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Test Modality, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Test Modality
- Figure 35: North America Market Value Share and BPS Analysis by Product Component, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Product Component, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Product Component
- Figure 38: North America Market Value Share and BPS Analysis by Sample Matrix, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Sample Matrix, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Sample Matrix
- Figure 41: North America Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Clinical Indication
- Figure 44: North America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 45: North America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 46: North America Market Attractiveness Analysis by End User
- Figure 47: North America Market Value Share and BPS Analysis by Clinical Setting, 2026 and 2036
- Figure 48: North America Market Y-o-Y Growth Comparison by Clinical Setting, 2026-2036
- Figure 49: North America Market Attractiveness Analysis by Clinical Setting
- Figure 50: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 51: Latin America Market Value Share and BPS Analysis by Test Modality, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Test Modality, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Test Modality
- Figure 54: Latin America Market Value Share and BPS Analysis by Product Component, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Product Component, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Product Component
- Figure 57: Latin America Market Value Share and BPS Analysis by Sample Matrix, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Sample Matrix, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Sample Matrix
- Figure 60: Latin America Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 61: Latin America Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 62: Latin America Market Attractiveness Analysis by Clinical Indication
- Figure 63: Latin America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 64: Latin America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 65: Latin America Market Attractiveness Analysis by End User
- Figure 66: Latin America Market Value Share and BPS Analysis by Clinical Setting, 2026 and 2036
- Figure 67: Latin America Market Y-o-Y Growth Comparison by Clinical Setting, 2026-2036
- Figure 68: Latin America Market Attractiveness Analysis by Clinical Setting
- Figure 69: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 70: Western Europe Market Value Share and BPS Analysis by Test Modality, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Test Modality, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Test Modality
- Figure 73: Western Europe Market Value Share and BPS Analysis by Product Component, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Product Component, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Product Component
- Figure 76: Western Europe Market Value Share and BPS Analysis by Sample Matrix, 2026 and 2036
- Figure 77: Western Europe Market Y-o-Y Growth Comparison by Sample Matrix, 2026-2036
- Figure 78: Western Europe Market Attractiveness Analysis by Sample Matrix
- Figure 79: Western Europe Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 80: Western Europe Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 81: Western Europe Market Attractiveness Analysis by Clinical Indication
- Figure 82: Western Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 83: Western Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 84: Western Europe Market Attractiveness Analysis by End User
- Figure 85: Western Europe Market Value Share and BPS Analysis by Clinical Setting, 2026 and 2036
- Figure 86: Western Europe Market Y-o-Y Growth Comparison by Clinical Setting, 2026-2036
- Figure 87: Western Europe Market Attractiveness Analysis by Clinical Setting
- Figure 88: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Test Modality, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Test Modality, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Test Modality
- Figure 92: Eastern Europe Market Value Share and BPS Analysis by Product Component, 2026 and 2036
- Figure 93: Eastern Europe Market Y-o-Y Growth Comparison by Product Component, 2026-2036
- Figure 94: Eastern Europe Market Attractiveness Analysis by Product Component
- Figure 95: Eastern Europe Market Value Share and BPS Analysis by Sample Matrix, 2026 and 2036
- Figure 96: Eastern Europe Market Y-o-Y Growth Comparison by Sample Matrix, 2026-2036
- Figure 97: Eastern Europe Market Attractiveness Analysis by Sample Matrix
- Figure 98: Eastern Europe Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 99: Eastern Europe Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 100: Eastern Europe Market Attractiveness Analysis by Clinical Indication
- Figure 101: Eastern Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 102: Eastern Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 103: Eastern Europe Market Attractiveness Analysis by End User
- Figure 104: Eastern Europe Market Value Share and BPS Analysis by Clinical Setting, 2026 and 2036
- Figure 105: Eastern Europe Market Y-o-Y Growth Comparison by Clinical Setting, 2026-2036
- Figure 106: Eastern Europe Market Attractiveness Analysis by Clinical Setting
- Figure 107: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 108: East Asia Market Value Share and BPS Analysis by Test Modality, 2026 and 2036
- Figure 109: East Asia Market Y-o-Y Growth Comparison by Test Modality, 2026-2036
- Figure 110: East Asia Market Attractiveness Analysis by Test Modality
- Figure 111: East Asia Market Value Share and BPS Analysis by Product Component, 2026 and 2036
- Figure 112: East Asia Market Y-o-Y Growth Comparison by Product Component, 2026-2036
- Figure 113: East Asia Market Attractiveness Analysis by Product Component
- Figure 114: East Asia Market Value Share and BPS Analysis by Sample Matrix, 2026 and 2036
- Figure 115: East Asia Market Y-o-Y Growth Comparison by Sample Matrix, 2026-2036
- Figure 116: East Asia Market Attractiveness Analysis by Sample Matrix
- Figure 117: East Asia Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 118: East Asia Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 119: East Asia Market Attractiveness Analysis by Clinical Indication
- Figure 120: East Asia Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 121: East Asia Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 122: East Asia Market Attractiveness Analysis by End User
- Figure 123: East Asia Market Value Share and BPS Analysis by Clinical Setting, 2026 and 2036
- Figure 124: East Asia Market Y-o-Y Growth Comparison by Clinical Setting, 2026-2036
- Figure 125: East Asia Market Attractiveness Analysis by Clinical Setting
- Figure 126: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 127: South Asia and Pacific Market Value Share and BPS Analysis by Test Modality, 2026 and 2036
- Figure 128: South Asia and Pacific Market Y-o-Y Growth Comparison by Test Modality, 2026-2036
- Figure 129: South Asia and Pacific Market Attractiveness Analysis by Test Modality
- Figure 130: South Asia and Pacific Market Value Share and BPS Analysis by Product Component, 2026 and 2036
- Figure 131: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Component, 2026-2036
- Figure 132: South Asia and Pacific Market Attractiveness Analysis by Product Component
- Figure 133: South Asia and Pacific Market Value Share and BPS Analysis by Sample Matrix, 2026 and 2036
- Figure 134: South Asia and Pacific Market Y-o-Y Growth Comparison by Sample Matrix, 2026-2036
- Figure 135: South Asia and Pacific Market Attractiveness Analysis by Sample Matrix
- Figure 136: South Asia and Pacific Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 137: South Asia and Pacific Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 138: South Asia and Pacific Market Attractiveness Analysis by Clinical Indication
- Figure 139: South Asia and Pacific Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 140: South Asia and Pacific Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 141: South Asia and Pacific Market Attractiveness Analysis by End User
- Figure 142: South Asia and Pacific Market Value Share and BPS Analysis by Clinical Setting, 2026 and 2036
- Figure 143: South Asia and Pacific Market Y-o-Y Growth Comparison by Clinical Setting, 2026-2036
- Figure 144: South Asia and Pacific Market Attractiveness Analysis by Clinical Setting
- Figure 145: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 146: Middle East and Africa Market Value Share and BPS Analysis by Test Modality, 2026 and 2036
- Figure 147: Middle East and Africa Market Y-o-Y Growth Comparison by Test Modality, 2026-2036
- Figure 148: Middle East and Africa Market Attractiveness Analysis by Test Modality
- Figure 149: Middle East and Africa Market Value Share and BPS Analysis by Product Component, 2026 and 2036
- Figure 150: Middle East and Africa Market Y-o-Y Growth Comparison by Product Component, 2026-2036
- Figure 151: Middle East and Africa Market Attractiveness Analysis by Product Component
- Figure 152: Middle East and Africa Market Value Share and BPS Analysis by Sample Matrix, 2026 and 2036
- Figure 153: Middle East and Africa Market Y-o-Y Growth Comparison by Sample Matrix, 2026-2036
- Figure 154: Middle East and Africa Market Attractiveness Analysis by Sample Matrix
- Figure 155: Middle East and Africa Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 156: Middle East and Africa Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 157: Middle East and Africa Market Attractiveness Analysis by Clinical Indication
- Figure 158: Middle East and Africa Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 159: Middle East and Africa Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 160: Middle East and Africa Market Attractiveness Analysis by End User
- Figure 161: Middle East and Africa Market Value Share and BPS Analysis by Clinical Setting, 2026 and 2036
- Figure 162: Middle East and Africa Market Y-o-Y Growth Comparison by Clinical Setting, 2026-2036
- Figure 163: Middle East and Africa Market Attractiveness Analysis by Clinical Setting
- Figure 164: Global Market - Tier Structure Analysis
- Figure 165: Global Market - Company Share Analysis
Frequently Asked Questions
What is the estimated size of the clinical diagnostics market in 2026 and 2036?
In the FMI report, hospital and reference laboratory diagnostic valuation stands at USD 91.3 billion for 2026 above a 2025 baseline of USD 86.5 billion before climbing to USD 156.0 billion in 2036. At what rate will the clinical diagnostics market grow between 2026 and 2036? Future Market Insights projects a 5.5% compound annual growth rate across the clinical diagnostics sector from 2026 through 2036 that adds USD 64.7 billion in ten-year laboratory value.
Which test modality represents a notable segment in the clinical diagnostics market?
Clinical chemistry and core-lab immunoassays lead test modality demand at 37.3% in 2026 on the strength of automated inpatient metabolic and cardiac panels.
Which product component accounts for the majority of clinical diagnostics purchasing?
Consumable reagents and assay cartridges capture 68.7% of component demand in 2026 through closed-system reagent-rental contracts across hospital tracks.
Which country exhibits notable expansion in the clinical diagnostics market?
South Korea registers the fastest country-level diagnostic pace at a 6.7% CAGR through 2036 ahead of Brazil at 6.4% and Australia at 6.1%.
Who are the key players in the market?
F. Hoffmann-La Roche Ltd, Abbott Laboratories, Danaher Corporation, Siemens Healthineers AG, Thermo Fisher Scientific Inc., Sysmex Corporation, bioMerieux SA, and Becton, Dickinson and Company are the primary suppliers.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
