

- Market Size (2026)
- USD 137.2 Mn
- Forecast (2036)
- USD 352.5 Mn
- CAGR (2026 to 2036)
- 9.9%
How Big is the Crop Mulch Biopolymers Market in 2026?
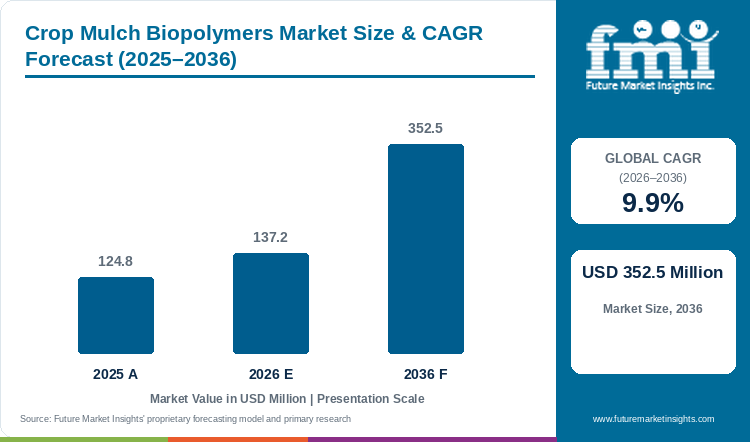
Grower and dealer purchases of crop mulch biopolymers, worth USD 124.8 Million in 2025, will reach USD 137.2 Million in 2026 before rising toward USD 352.5 Million by 2036 on a 9.9% CAGR, as projected by FMI.
Adoption of crop mulch biopolymers is projected to grow at 9.9% CAGR between 2026 and 2036, as per FMI. Industry value is estimated to reach USD 137.2 Million in 2026, up from USD 124.8 Million in 2025, and is projected to touch USD 352.5 Million by 2036, adding USD 215.3 Million over the forecast decade. Increasing drift and runoff controls on pesticide labels in the USA are supporting the demand for crop mulch biopolymers. Federal pesticide labels now carry mandatory runoff mitigation and spray drift management, with ecological buffers applicators can reduce through application techniques [1]. Due to this, growers are buying drift and deposition aids backed by documented field data to meet these label terms. Agri-input distributors are expected to hold 36.2% of demand by sales channel in 2026, and foliar tank-mix use is estimated at 39.1% by application method. California growers made nearly 3.2 million pesticide applications across over 3,200 products in 2025, and Rovensa Next reported VINTRE as the most widely applied adjuvant in the state [2]. As a result, each spray pass is bringing a repeat purchase for local dealers with agronomy staff.
Growth rates differ across the profiled countries, as the USA is projected at 9.6% CAGR on label-driven drift and runoff mitigation and Japan is forecast at 8% with drone-compatible registrations setting the pace. Adjacent spray additive categories are also adding sales potential for the same dealers and formulators. FMI's report values the agricultural adjuvant market at USD 4.2 Billion for 2026 and USD 7.5 Billion for 2036, a 6% CAGR worth USD 3.3 Billion in new revenue. Demand for spray deposition additives is projected to grow faster at 10% CAGR, from USD 318.2 Million to USD 825.4 Million, opening USD 507.2 Million. Sales of foliar penetration additives are estimated to increase from USD 234.6 Million to USD 555.3 Million at 9% CAGR. Dealers are expected to list crop mulch biopolymers on the same recommendation sheet as these adjacent lines. However, country listings and compatibility evidence will decide the speed of entry into each spray program. During the forecast period, adoption of crop mulch biopolymers is expected to increase as growers add drift and runoff controls to each spray program.
Key Takeaways
- Notable companies in the crop mulch biopolymers market include Loveland Products (Nutrien), Oro Agri (Rovensa), Croda, Clariant, Stepan Company, Evonik, Solvay (Syensqo) and Wilbur-Ellis.
- Based on product type, surfactant-based systems are projected to account for 49.1% in 2026, owing to wetting and spreading needs across foliar spray programs.
- By function, efficacy enhancement is estimated to hold 42.6% in 2026, and cereals and grains are expected at 43.6% by crop type, as growers link formulation aids to the result of the main treatment.
- The USA is projected at 9.6% CAGR through 2036, followed by South Korea at 9.3%, as label rules and crop-specific drone registrations open new spray programs.
Analyst Perspective
“Low-volume drone spraying will offer the clearest revenue opportunity in crop mulch biopolymers through 2036, as growers pay for carriers holding deposition and drift control at small water volumes. Suppliers pairing renewable surfactant chemistry with local field trials will receive the first large orders from registered drone programs in South Korea and Japan.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the Crop Mulch Biopolymers Market Segmented?
The crop mulch biopolymers market is segmented into product type, function, crop type, application method, sales channel and region.
According to FMI, the market is segmented by product type into surfactant-based, oil-based, polymer-based, mineral or carrier-based and other systems. By function, the market is segmented into efficacy enhancement, loss and drift reduction, handling and compatibility, and others. By crop type, the market is segmented into cereals and grains, fruits and vegetables, oilseeds and pulses, turf and ornamentals, and others. By application method, the market is segmented into foliar tank-mix, granule or dry blend, fertigation and others. By sales channel, the market is segmented into agri-input distributors, cooperatives, agri-retail chains, online or direct-to-farm, and others. The regional analysis covers seven regions and more than 30 countries.
Why Do Surfactant-Based Systems Lead the Crop Mulch Biopolymers Market by Product Type?
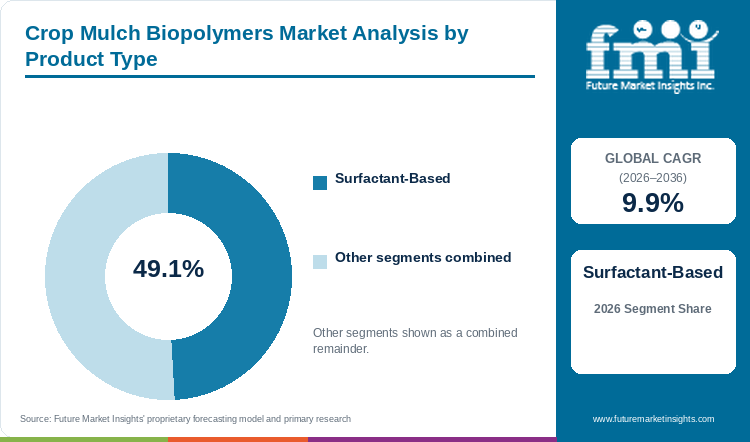
In 2026, surfactant-based systems will account for 49.1% of market share by product type.
Growers are buying more spray aids for each foliar pass, which is supporting the demand for crop mulch biopolymers in surfactant-based systems. A single surfactant platform can be adjusted to improve coverage, spread, leaf entry or droplet hold with many pesticide mixes, owing to which growers pay for one product serving the whole spray calendar. Surfactants also stop spray beading on glossy foliage with no reformulation of the pesticide, a need covered in the spray retention additives market. Oil-based systems sell in smaller volumes, mostly for leaf entry on hard or glossy crops. Polymer-based systems are bought as a narrower add-on for droplet size and drift control. Mineral or carrier-based products follow granular and dry-mix programs and see little foliar use. However, mixing stability with each pesticide partner will decide the surfactant grades listed by dealers.
- Surfactant-based systems are projected to account for 49.1% of demand by product type in 2026, owing to wetting and spreading needs across foliar spray programs.
- In December 2025, Stepan Company opened an agricultural laboratory in Piracicaba, Brazil, for formulation work on chemical and biological crop protection products, adjuvants and specialty fertilizers [3].
Why Does Efficacy Enhancement Lead the Crop Mulch Biopolymers Market by Function?
By function, efficacy enhancement will account for 42.6% of market share in 2026.
Efficacy enhancement is widely bought across foliar spray programs, supporting the demand for crop mulch biopolymers with this function. A grower sees the payback of an extra spray additive in stronger pest or disease control, owing to which efficacy products take the biggest share of adjuvant spending. Loss and drift reduction is gaining importance close to sensitive habitats and under recent buffer rules on labels, but orders come mainly for selected plots and weather conditions. Handling and compatibility products keep spray mixes stable as a secondary purchase, covered in the pesticide compatibility additives market. Other functions mostly serve niche requirements with modest spending. However, field results backing performance promises will decide the suppliers that can charge more.
- Efficacy enhancement is estimated to hold 42.6% of demand by function in 2026, supported by purchases tied directly to the result of the main treatment.
- In August 2026, Wilbur-Ellis Agribusiness published grower guidance linking fungicide performance with adjuvant choice and application timing [4].
Why Do Cereals and Grains Lead the Crop Mulch Biopolymers Market by Crop Type?
Based on crop type, cereals and grains will account for 43.6% of market share in 2026.
Grain growers spray large farms several times each season, supporting the demand for crop mulch biopolymers in cereals and grains. A modest gain in spray performance adds up over very large fields, owing to which grain growers buy formulation aids in the biggest volumes. Fruit and vegetable growers spend more on each hectare, but residue limits, special leaf surfaces and smaller planted land keep volumes lower. Oilseeds and pulses follow similar field-scale practices on fewer hectares, and turf and ornamentals form a niche handled by professional applicators. Grain programs are projected to take the largest portion of spray aid volume from the wider agrochemical additives category over the coming decade. However, new buffer rules on labels will decide the drift-control products chosen for big grain fields.
- Cereals and grains are expected to account for 43.6% of demand by crop type in 2026, owing to field-scale spraying across large treated areas.
- Increasing drift and runoff provisions on US pesticide labels are expected to add more droplet-control products to broad-acre cereal programs.
What are the Drivers, Restraints, and Opportunities in the Crop Mulch Biopolymers Market?
As per FMI's analysis, tighter label rules on drift and runoff will increase demand, country listing and use conditions will slow rollout, and drone and biological programs will open room for renewable carriers.
- Driver: Increasing label requirements on spray drift and runoff are supporting the demand for products keeping pesticides on target and improving efficacy.
- Restraint: Country-specific listing, compatibility evidence and use conditions are delaying launches and narrowing the range of eligible applications.
- Opportunity: Drone spraying and biological crop protection are creating room for biodegradable polymers, renewable surfactants and multifunctional carriers.
Pesticide labels are setting the key drivers of the crop mulch biopolymers market, as new EPA labels in the USA carry mandatory runoff mitigation points and spray drift management with ecological buffers [1]. Germany's agriculture ministry restated in May 2025 that only authorized plant protection products may be applied and that spray equipment needs a valid inspection mark [5]. Japan's agriculture ministry kept a list of pesticides suited to drone use current as of April 2026 and requires the registered crop, dilution and application method to be followed [6]. As a result, compliance work is slowing multi-country rollout, though the same rules favor suppliers holding local documentation and drone-ready carriers.
Which Country CAGRs are Profiled in the Crop Mulch Biopolymers Market?
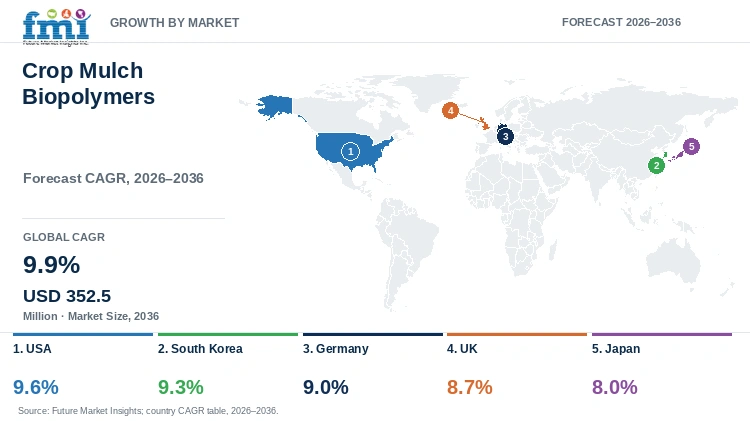
| Country | CAGR, 2026 to 2036 |
|---|---|
| USA | 9.6% |
| South Korea | 9.3% |
| Germany | 9% |
| UK | 8.7% |
| Japan | 8% |
How do Country-level CAGRs Compare in the Crop Mulch Biopolymers Market?
Demand for crop mulch biopolymers across the five profiled countries ranges from 9.6% CAGR in the USA to 8% in Japan, a spread of 1.6 percentage points, according to FMI's analysis. South Korea at 9.3% and Germany at 9% are placed in the middle, and the UK is projected next at 8.7%. A country with a lower CAGR can still account for more dealer sales in absolute terms through 2036.
- Label-driven drift and runoff mitigation will support demand for crop mulch biopolymers in the USA at 9.6%, the fastest pace among profiled countries.
- Demand in South Korea will rise at 9.3% as crop-specific drone registrations open new spray programs.
- Germany at 9% and the UK at 8.7% will reward suppliers holding national approvals.
- Japan is projected at 8%, the slowest pace, with drone-compatible registrations setting the speed of low-volume adoption.
Growth outlooks for more than 30 countries, grouped into seven regions, appear in the complete study beyond these five spray markets.
Country Outlook
- Federal labels are setting the commercial agenda for US spray programs, with mandatory runoff mitigation points and spray drift management written into pesticide labels [1]. Demand for crop mulch biopolymers in the USA is set for a 9.6% CAGR through 2036, the quickest rate in the profiled group. Growers buying through local agronomy channels will favor products backed by documented drift and deposition data.
- Crop-by-crop trials are opening drone spraying to fruit growers in South Korea, and the Rural Development Administration reported the first drone pesticide registration for sweet persimmon in May 2025 [7]. Sales of crop mulch biopolymers in South Korea will rise at a 9.3% CAGR till 2036. Low-volume spraying makes droplet behavior a buying criterion, so suppliers running local trials will gain early volume.
- National approval, specified mix partners and German-language use guidance are deciding the speed of adjuvant rollout on German farms. The federal agriculture ministry restated in May 2025 that only authorized plant protection products may be applied and that sprayers need a valid inspection mark [5]. Adoption in Germany is projected at 9% CAGR, and suppliers offering local technical support to professional applicators are expected to take the lead.
- UK sales will rise at an 8.7% CAGR from 2026 to 2036 inside an advisory market that checks tank partners and conditions of use before each application. Adjuvants enter the UK market through the Official List kept by the Health and Safety Executive, and each list entry carries conditions of use with authorised plant protection products. Suppliers with current list entries and clear distributor guidance will convert advice into orders faster.
- At 8% a year, Japan is the slowest of the profiled countries, though the pace still supports specialized low-volume products. The agriculture ministry kept information on drone-suited pesticides current as of April 2026 and requires the registered crop, dilution and application method to be followed [6]. Droplet-management evidence for locally registered drone programs will open the clearest route to repeat orders.
Who are the Notable Companies in the Crop Mulch Biopolymers Market?
Pricing power leans toward grower-channel owners Loveland Products (Nutrien), Oro Agri (Rovensa) and Wilbur-Ellis, as Croda, Clariant and Stepan Company compete on surfactant formulation and Evonik and Solvay (Syensqo) on bio-based carriers.
Grower-channel groups operate at the farm gate and chemical formulators supply from upstream, due to which supply of crop mulch biopolymers remains tiered and moderately fragmented. Loveland Products (Nutrien), Oro Agri (Rovensa) and Wilbur-Ellis have the closest grower access through agronomy and retail relationships, and Rovensa Next reported VINTRE as the most widely applied adjuvant in California in 2025 [2]. Croda, Clariant and Stepan Company are competing on surface chemistry and formulation services, and Evonik and Solvay (Syensqo) are offering renewable surfactants and biodegradable carriers. Country listings, compatibility testing and laboratory capacity are needed before entry, and Stepan opened a Piracicaba formulation laboratory in December 2025 [3]. Dealers check compatibility and listings for every new product before an agronomist adds the product to a spray recommendation, owing to which switching remains slow. Group ownership under Nutrien and Rovensa links chemistry with farm distribution, and channel owners are gaining pricing power. However, drone-ready and bio-based formulations are expected to bring specialty chemical makers into closer distributor partnerships through 2036.
- Integrated Grower-Channel Adjuvant Providers: Loveland Products (Nutrien), Oro Agri (Rovensa) and Wilbur-Ellis pair adjuvant portfolios with agronomy advice and farm distribution.
- Specialty Surfactant and Formulation Platforms: Croda, Clariant and Stepan Company combine surface chemistry with formulation development and application testing.
- Bio-Based Polymer and Interface Technology Specialists: Evonik and Solvay (Syensqo) focus on renewable surfactants, guar-based polymers and biodegradable carriers for crop use.
Competitive Benchmarking
| Company | Tank-Mix and Foliar Adjuvant Breadth | Bio-Based or Biopolymer Formulation Capability | Formulation and Application Support Depth | Geographic Reach |
|---|---|---|---|---|
| Loveland Products (Nutrien) | High | Medium | High | North America through Nutrien Ag Solutions |
| Oro Agri (Rovensa) | High | High | High | Americas, Europe and Asia through Rovensa Next |
| Croda | High | High | High | Americas, Europe and Asia-Pacific |
| Clariant | High | High | High | Global crop-solutions network with regional technical support |
| Stepan Company | High | Medium | High | North America, Latin America, Europe and Asia |
| Evonik | High | High | High | Global specialty-chemicals and crop-solutions presence |
| Solvay (Syensqo) | Medium | High | High | Africa and Middle East, Asia-Pacific, Europe, Latin America and North America |
| Wilbur-Ellis | High | Medium | High | United States and selected North American crop markets |
Scoring basis: Tank-Mix and Foliar Adjuvant Breadth rates documented wetting, spreading, penetration and drift functions. Bio-Based or Biopolymer Formulation Capability rates documented renewable surfactants, oils, guars, wax systems and biodegradable carriers. Formulation and Application Support Depth rates laboratories, formulation services and field programs. High marks broad documented capability, and Medium marks narrower coverage.
Key Developments
- In December 2025, Stepan Company opened an agricultural laboratory at Parque Tecnológico de Piracicaba in Brazil for formulation work on chemical and biological crop protection products, adjuvants and specialty fertilizers, and became an Innovation Corporate investor in PwC Agtech Innovation [3].
- In March 2026, Rovensa Next reported that VINTRE, a foliar adjuvant built on OROWET citrus-oil and surfactant technology, was the most widely applied adjuvant in California in 2025 [2].
- In April 2026, Rovensa Next launched a Global Training Academy and an AI knowledge platform with more than 10,000 articles from over 4,000 trials, introduced first in 15 countries [8].
Key Players
Integrated Grower-Channel Adjuvant Providers
- Loveland Products (Nutrien)
- Oro Agri (Rovensa)
- Wilbur-Ellis
Specialty Surfactant and Formulation Platforms
- Croda
- Clariant
- Stepan Company
Bio-Based Polymer and Interface Technology Specialists
- Evonik
- Solvay (Syensqo)
Report Scope and Methodology
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type (Surfactant-Based, Oil-Based, Polymer-Based, Mineral or Carrier-Based, Others), Function (Efficacy Enhancement, Loss and Drift Reduction, Handling and Compatibility, Others), Crop Type, Application Method, Sales Channel, and Region |
| Quantitative units | USD Million |
| Market definition | Revenue from crop-use biopolymer and formulation-aid products covered by the stated segmentation, spanning surfactant, oil, polymer and mineral or carrier systems used to improve application performance or crop-input delivery. Finished pesticides, fertilizers, seeds and standalone mulch products are excluded. |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries covered | The USA, the UK, Germany, Japan and South Korea are profiled within a coverage set of more than 30 countries. |
| Key companies profiled | Loveland Products (Nutrien), Oro Agri (Rovensa), Croda, Clariant, Stepan Company, Evonik, Solvay (Syensqo), and Wilbur-Ellis, drawn from a larger pool of adjuvant and carrier suppliers |
| Forecast period | 2026 to 2036 |
| Approach | Demand by application and supplier activity are reconciled in a combined bottom-up and top-down model built by FMI, with channel economics and country operating conditions used as cross-checks. |
Research Methodology
| Method | Approach |
|---|---|
| Primary research | Structured interviews with manufacturers, formulators, distributors, agronomists, farm operators and procurement teams test product selection, application practice, channel behavior and adoption barriers. |
| Desk research | The analysis reviews regulator guidance, official pesticide-use materials, company announcements, technical documents and trade sources, keeping only sources that support the defined scope or an identified driver of demand. |
| Market sizing and forecasting | The sizing framework combines supplier and channel indicators with demand by application, product-mix assumptions and country operating conditions across the forecast horizon. |
| Data validation | Estimates are cross-checked across source types and market participants. Duplicate revenue, unsupported claims, finished-product revenue and substitute categories are excluded. |
Crop Mulch Biopolymers Market by Segments
Crop Mulch Biopolymers Market Segmented by Product Type
- Surfactant-Based
- Oil-Based
- Polymer-Based
- Mineral / Carrier-Based
- Others
Crop Mulch Biopolymers Market Segmented by Function
- Efficacy Enhancement
- Loss & Drift Reduction
- Handling & Compatibility
- Others
Crop Mulch Biopolymers Market Segmented by Crop Type
- Cereals & Grains
- Fruits & Vegetables
- Oilseeds & Pulses
- Turf & Ornamentals
- Others
Crop Mulch Biopolymers Market Segmented by Application Method
- Foliar Tank-Mix
- Granule / Dry Blend
- Fertigation
- Others
Crop Mulch Biopolymers Market Segmented by Sales Channel
- Agri-Input Distributors
- Cooperatives
- Agri-Retail Chains
- Online / Direct-to-Farm
- Others
Crop Mulch Biopolymers Market Segmented by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
Research Sources and Bibliography
- [1] University of Florida IFAS Pesticide Information Office (2026, August 13). New EPA Pesticide Label Requirements: What Applicators Need to Know.
- [2] Rovensa Next (2026, March 17). VINTRE Named Most Widely Applied Adjuvant in California in 2025.
- [3] Global AgInvesting (2025, December 3). Stepan Debuts Ag Lab, Deepens Ties With PwC's Agtech Hub.
- [4] Wilbur-Ellis Agribusiness (2026, August 7). Better Fungicide Performance Starts with Adjuvants and Application Timing.
- [5] Federal Ministry of Agriculture, Food and Regional Identity (2025, May 13). Pflanzenschutzmittel sicher angewendet.
- [6] Ministry of Agriculture, Forestry and Fisheries of Japan (2026, April 1). Pesticides usable by drone.
- [7] Rural Development Administration of South Korea (2025, May 28). Sweet persimmon opens a new era for drone control in fruit crops.
- [8] Rovensa Next (2026, April 15). Rovensa Next strengthen biosolutions support for distribution partners and growers through global training and AI.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will grower and dealer spending on crop mulch biopolymers be in 2026, and what sales value will the market reach by 2036?
- What effect will drift and runoff label requirements have on demand for crop mulch biopolymers?
- Why will surfactant-based systems keep first place among product types in 2026 spray programs?
- Why will efficacy enhancement lead the Function category through the forecast period?
- Why will cereals and grains remain the largest crop type for formulation aids?
- Which of the USA, South Korea, Germany, the UK and Japan will expand fastest through 2036, and by what margin?
- In what ways will drone spraying and biological programs open room for renewable carriers?
- To what extent will country listing and compatibility rules slow commercial rollout?
- What will procurement and agronomy teams need to check before selecting a product?
Frequently Asked Questions
How Big Is the Crop Mulch Biopolymers Market Expected to Be in 2026?
Across the 2026 spray season, growers and dealers will spend USD 137.2 Million on crop mulch biopolymers, compared with USD 124.8 Million in 2025, as FMI estimates. By 2036, that spending will reach USD 352.5 Million as spray programs demand tighter control of deposition and drift.
What Is the CAGR of the Crop Mulch Biopolymers Market from 2026 to 2036?
For broad-acre and specialty spray programs alike, crop mulch biopolymer revenue is set to compound at 9.9% a year between 2026 and 2036. Low-volume drone spraying and biological crop protection will set the pace, since both make the carrier system more important to the field result.
Which Product Type Holds the Largest Share of the Crop Mulch Biopolymers Market?
On waxy-leaf crops and across most foliar passes, surfactant-based systems will hold 49.1% of market share by product type in 2026. Wetting, spreading and interface control will keep the chemistry relevant across a wide range of foliar programs.
Which Function Leads the Crop Mulch Biopolymers Market?
Efficacy enhancement will account for 42.6% of market share by function in 2026. Growers will keep paying for aids that improve the result of the main pesticide or biological treatment.
Which Country Is Expected to Grow Fastest in the Crop Mulch Biopolymers Market?
Driven by label-mandated drift and runoff controls on US farms, the USA will post the fastest CAGR of 9.6% till 2036, ahead of South Korea at 9.3%. Japanese drone spray programs will expand at 8%, the slowest rate among the five profiled countries.
What Notable Restraint Affects the Crop Mulch Biopolymers Market?
Key challenges will include country-specific listing and use conditions, which will slow the path from a viable formulation to a sale. Buyers will also ask for compatibility evidence covering the active ingredient, water condition and spray equipment.
Which Are the Key Companies in the Crop Mulch Biopolymers Market?
For grower and dealer spray programs, FMI tracks Loveland Products (Nutrien), Oro Agri (Rovensa), Croda, Clariant, Stepan Company, Evonik, Solvay (Syensqo) and Wilbur-Ellis as notable suppliers. The study sorts these suppliers into three strategy groups, ranging from grower-channel adjuvant providers to bio-based polymer specialists.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Surfactant-Based
- Oil-Based
- Polymer-Based
- Mineral / Carrier-Based
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Function, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Function, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Function, 2026 to 2036
- Efficacy Enhancement
- Loss & Drift Reduction
- Handling & Compatibility
- Others
- Y-o-Y Growth Trend Analysis By Function, 2021 to 2025
- Absolute $ Opportunity Analysis By Function, 2026 to 2036
- Global Market Analysis and Forecast, By Crop Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Crop Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Crop Type, 2026 to 2036
- Cereals & Grains
- Fruits & Vegetables
- Oilseeds & Pulses
- Turf & Ornamentals
- Others
- Y-o-Y Growth Trend Analysis By Crop Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Crop Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application Method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application Method, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application Method, 2026 to 2036
- Foliar Tank-Mix
- Granule / Dry Blend
- Fertigation
- Others
- Y-o-Y Growth Trend Analysis By Application Method, 2021 to 2025
- Absolute $ Opportunity Analysis By Application Method, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Agri-Input Distributors
- Cooperatives
- Agri-Retail Chains
- Online / Direct-to-Farm
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Function
- By Crop Type
- By Application Method
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Loveland Products (Nutrien)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Oro Agri (Rovensa)
- Croda
- Clariant
- Stepan Company
- Evonik
- Solvay (Syensqo)
- Wilbur-Ellis
- Loveland Products (Nutrien)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


