

- Market Size (2026)
- USD 89.3 Bn
- Forecast (2036)
- USD 121.1 Bn
- CAGR (2026 to 2036)
- 3.1%
How big is Eco Flooring Market in 2026?
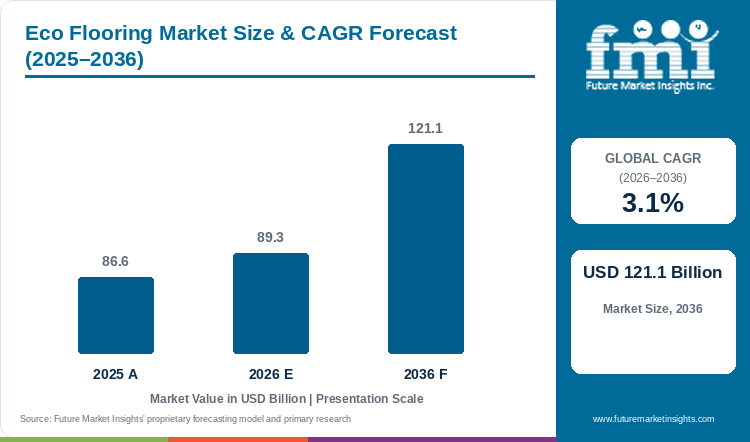
A 3.1% CAGR describes eco flooring sales over the 2026 to 2036 decade. The 2025 level was USD 86.6 billion. For 2026 the estimate stands near USD 89.3 billion. The 2036 projection lands at USD 121.1 billion.
Eco flooring sales come to an estimated USD 89.3 billion in 2026, up from USD 86.6 billion in 2025. Sales will grow at a CAGR of 3.1% from 2026 to 2036 and reach USD 121.1 billion by 2036, on FMI numbers.
Certified projects pick eco floors from the specifier lists that fill the green building materials market, on an 11.3% CAGR from 2026 to 2036. Floors are one line item in a green building, so eco flooring, at 3.1%, takes a shrinking part of each project budget. Bamboo floors draw cane from the bamboo products market, on a 5.6% CAGR over the same decade, so cane supply will grow ahead of floor demand.
Specifiers record a carbon figure for each approved floor, so recycled feedstock decides the listings. Tarkett said in April 2026 that recycled materials made up 20% of raw materials in 2025, or 160,000 tons, up from 10% in 2018.[1] Tarkett set a 30% goal for 2030,[1] so specifiers will expect a higher recycled share from low-carbon floors.
Public tenders apply stricter checks to bamboo and cork floors. Bamboo leads material sales on an estimated 21.4%, yet natural origin alone will not clear a tender. Bamboo and cork growers with sourcing and emissions records will turn market shifts into growth opportunities in public buildings. Households will judge on price, which keeps mid-range lines in front at an estimated 46.3% share.
Key Market Trends & Insights
- Material type: bamboo leads on an estimated 21.4%, with cork close behind on renewability and acoustic comfort.
- End use: residential floors take about 58.6% (estimated) in 2026. Private residential construction ran at a USD 859.0 billion annual rate in July 2026, the US Census Bureau reported.[2]
- Price range: mid-range lines hold an estimated 46.3%, ahead of premium and economy.
- Distribution channel: offline stores and distributors carry roughly 71.8% (estimated), and online sales grow from an estimated 28.2% base.
Regional Highlights
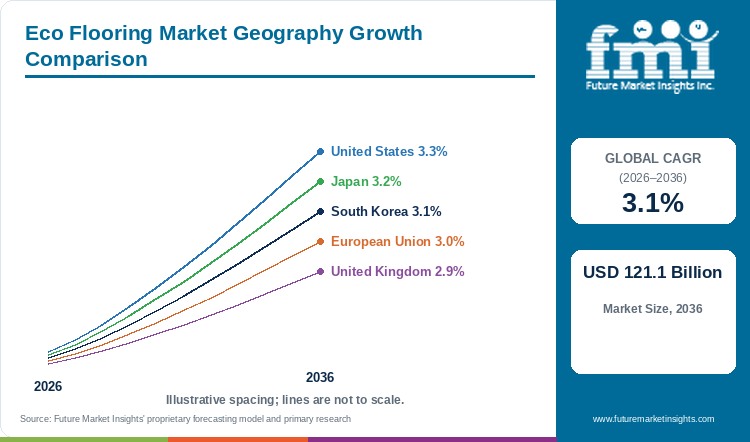
- FMI rates the United States highest among profiled countries, on a 3.3% CAGR over 2026 to 2036.
- Japan reaches 3.2% and South Korea 3.1%. The European Union bloc posts 3%, with the United Kingdom bottom of the table on 2.9%.
- Massachusetts held the top spot in the USGBC ranking of states for LEED in 2025 for a second straight year, PHCP Pros reported in March 2026.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Eco Flooring Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 86.6 billion |
| Estimated Market Size in 2026 | USD 89.3 billion |
| Projected Market Size by 2036 | USD 121.1 billion |
| CAGR, 2026 to 2036 | 3.1% |
| Added Revenue, 2026 to 2036 | USD 31.8 billion |
| Market Expansion Multiple | 1.4x |
Eco flooring grows slower than the wider pool of sustainable building inputs. The green building materials market records an 11.3% CAGR from 2026 to 2036. Eco flooring, on FMI figures, holds to a 3.1% CAGR for 2026 to 2036. Eco floors compete with vinyl and other conventional floors for each project in the wider flooring market. Replacement cycles for floors run long, so certified new buildings and LEED office refurbishments will decide eco flooring volume through 2036.
Certification, Indoor-Air Rules and Recycled-Content Lines
Building owners keep asking for third-party proof of health and carbon performance. The USGBC named the Top 10 States for LEED in 2025 on newly certified commercial space per capita, and several US projects earned LEED v5 early adopter certification.[3] The Empire State Building became the first in New York to achieve LEED v5 Platinum.[3] LEED and similar schemes reward low-VOC flooring, adhesives and finishes, so indoor-air rules shape LEED scores. ISO published the second edition of ISO 5684 in August 2025, a reference test for VOC, SVOC and aldehyde emissions from floor covering adhesives and installation products.[4] The chamber test produces data for classing low-emission adhesives during floor use.[4] The ISO 5684 chamber test will make adhesive emission claims easier to compare across suppliers. In the FMI view, green-certified homes are pushing builders toward eco flooring.
Manufacturers answered with recycled-content and take-back lines. Tarkett collected 129,000 tons of end-of-life flooring through ReStart over 16 years, across eight recycling centres and 29 countries.[1] The group cut value-chain greenhouse gas emissions by 27% over six years.[1] Interface reaffirmed in August 2026 a goal to become carbon negative by 2040 without offsets.[5] Interface also sells nora rubber flooring next to carpet tile and LVT.[5] Take-back volumes like the 129,000 tons collected through Tarkett ReStart will decide which producers can meet recycled-content clauses at scale.
Table 2: Certification and Recycled-Content Indicators for the Eco Flooring Market (percentage, tons, rankings and USD), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Tarkett recycled raw materials, 2025 | 20% (160,000 tons) | Recycled share in a large producer mix. | [1] |
| Tarkett recycled target, 2030 | 30% | Direction of recycled-content lines. | [1] |
| Tarkett ReStart collection, 16 years | 129,000 tons | Scale of flooring take-back. | [1] |
| USGBC Top 10 States for LEED, 2025 | Massachusetts first, Illinois second | States adding the most certified commercial space. | [3] |
| LEED v5 Platinum, Empire State Building | First in New York | Uptake of the newest LEED version. | [3] |
| ISO 5684 second edition, August 2025 | Chamber test for VOC, SVOC and aldehyde emissions from flooring adhesives | Common basis for low-emission adhesive claims. | [4] |
| Interface carbon goal | Carbon negative by 2040, no offsets | Carbon claims in contract flooring. | [5] |
| Interface Healthcare billings, Q2 2026 | Up 19% | Health-focused buyers order more flooring. | [5] |
| US private nonresidential construction, July 2026 | USD 755.2 billion annual rate | Size of the commercial build pipeline. | [2] |
Analyst Perspective
“Take-back programmes give producers the clearest opening in eco flooring, and I expect producers that close the loop on vinyl, rubber and carpet to gain the next round of public and healthcare contracts. Public and healthcare buyers want a recycled-content figure and a low-emission label on the same product sheet, and suppliers that offer both will set the price in certified projects.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the eco flooring market segmented?
Four product axes and region shape the eco flooring market. Bamboo carries an estimated 21.4% of material sales in 2026, residential use about 58.6% (estimated), mid-range pricing an estimated 46.3% and offline channels about 71.8% (estimated).
By material type: cork, wood, bamboo, linoleum, glass tiles, concrete, wool carpet, rubber, and leather.
By end use: residential and non-residential.
By price range: economy, mid-range, and premium.
By distribution channel: online and offline.
By region: Asian blocks (East Asia, South Asia & Pacific), European blocks (Western, Eastern), American blocks (North, Latin), and Middle East & Africa.
Why does bamboo lead material type sales?
An estimated 21.4% of 2026 material type sales goes to bamboo floors, with cork and wood next.
Table 3: Material Type Share for the Eco Flooring Market (percentage share), 2026
| Material Type | Estimated Share (2026) |
|---|---|
| Bamboo | 21.4% |
| Cork | 16.8% |
| Wood | 15.2% |
| Linoleum | 12.1% |
| Wool Carpet | 9.6% |
| Rubber | 8.3% |
| Concrete | 7.2% |
| Glass Tiles | 5.1% |
| Leather | 4.3% |
| Total | 100.0% |
Table 4: Material Type Leadership and Market Growth for the Eco Flooring Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.1% |
| Leading Segment | Bamboo |
Bamboo beats cork on strength and moisture resistance, and beats solid wood on renewal speed. Bamboo floors also suit underfloor heating and need little care. The material takes about 21.4% (estimated) of 2026 sales. Cork follows on an estimated 16.8% and wood on roughly 15.2% (estimated). Linoleum stands near 12.1% (estimated), wool carpet near 9.6% and rubber near 8.3% (both estimated). Concrete takes about 7.2%, glass tiles 5.1% and leather 4.3% (all estimated). Cane for bamboo floors comes from the wider bamboo products market, which advances at a 5.6% CAGR to 2036, so bamboo can keep the 21.4% material lead without a feedstock squeeze.
- Cork will gain in homes and schools for thermal insulation and sound absorption.
- Interface sells nora rubber flooring alongside carpet tile and LVT.[5]
Why do residential projects lead end use sales?
Homes take an estimated 58.6% of eco flooring by end use in 2026, against about 41.4% (estimated) for non-residential buildings.
Table 5: End Use Share for the Eco Flooring Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Residential | 58.6% |
| Non-Residential | 41.4% |
| Total | 100.0% |
Home renovation work feeds demand for residential eco floors, since homeowners pick a new floor with each refit. Residential use holds an estimated 58.6% share. Non-residential projects take about 41.4% (estimated), and LEED certification will drive demand for non-residential eco floors. US private residential construction ran 1.3% below the June level in July 2026, and private nonresidential construction rose 0.4%.[2] Certified commercial projects will push the 41.4% non-residential share higher as LEED v5 adoption spreads.
- Families will pay for low-emission floors in bedrooms and nurseries.
- July 2026 US construction outlays ran 3.8% under the July 2025 level.[2]
Why do mid-range products lead price range sales?
Mid-range lines take about 46.3% (estimated) of 2026 price-tier sales, with premium and economy tiers behind.
Table 6: Price Range Share for the Eco Flooring Market (percentage share), 2026
| Price Range | Estimated Share (2026) |
|---|---|
| Mid-range | 46.3% |
| Premium | 31.2% |
| Economy | 22.5% |
| Total | 100.0% |
A shopper weighing a certified floor against a conventional one will often settle in the middle of the price ladder. Mid-range products carry about 46.3% (estimated). Premium lines take an estimated 31.2%, and economy lines about 22.5% (estimated). Sustainable raw materials need special processing for durability and water resistance, and processing costs keep the economy tier near 22.5%. Mid-range ranges with recycled content will gain specification in housing and schools.
- Premium cork, leather and designer wood floors will serve high-end interiors.
- Interface raised full-year 2026 net sales guidance to USD 1.455 to 1.485 billion.[5]
Why do offline channels lead distribution channel sales?
Showrooms, distributors and other offline outlets move an estimated 71.8% of eco flooring in 2026. Online channels move about 28.2% (estimated).
Table 7: Distribution Channel Share for the Eco Flooring Market (percentage share), 2026
| Distribution Channel | Estimated Share (2026) |
|---|---|
| Offline | 71.8% |
| Online | 28.2% |
| Total | 100.0% |
Flooring buyers want to touch samples and book installers, so showrooms and distributors keep the lead. Offline sales hold an estimated 71.8%. Online sales stand at about 28.2% (estimated). Contractors buying for certified projects order through distributors that hold product declarations and test reports. Online eco flooring sales will grow from the 28.2% base with digital design tools and traceability data for each product.
- Sample kits and room visualisers will pull more first purchases online.
- Interface Education and Corporate Office billings each rose 5% in Q2 2026.[5]
What are the drivers, restraints, and opportunities in the eco flooring market?
Adoption of eco flooring follows green building certification, low-VOC demand and recycled-content lines. Sales of eco flooring are held back by high production costs and certification burden, and closed-loop recycling offers the main opening.
- Driver: LEED and similar ratings reward low-emission, low-carbon floors.
- Restraint: Sustainable raw materials cost more to source and process.
- Opportunity: Take-back and recycling programmes feed recycled-content lines.
Certified Space Pulls Low-Emission Floors into Specifications
Adoption of LEED-certified flooring keeps growing, as per FMI. Colorado rose six places to third in the USGBC Top 10 States for LEED in 2025.[3] Life sciences, data centres and advanced manufacturing drove growth in several top states.[3] Classification under ISO 5684 gives installers a test-based route to low-emission adhesive claims.[4] Each certified fit-out will specify low-VOC floors and adhesives, and low-emission bonding agents in the wood adhesives market will gain from the same low-VOC specifications.
Processing Costs Keep Prices High
Bamboo and cork need treatment for water resistance before installation. Key challenges faced by manufacturers include costly raw material processing and audits under LEED, FSC and FloorScore. Private residential construction in the United States slipped 1.3% from June to July 2026, the Census Bureau reported.[2] Softer US home building will make cost-conscious home buyers stick with conventional vinyl and laminate.
Closed-Loop Recycling Feeds New Product Lines
End-of-life vinyl floors can return to factories as raw material. Sales potential is expected to emerge from end-of-life flooring returned for recycling. Tarkett reported that an IKEA vinyl recovery effort reclaimed 86,000 square metres of end-of-life vinyl flooring in 14 European countries over six years.[1] Recovered vinyl will become a regular feedstock for recycled-content floors made by producers in the vinyl flooring market.
Which country CAGRs are profiled in the eco flooring market?
Table 8: Country CAGR Comparison for the Eco Flooring Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| United States | 3.3% |
| Japan | 3.2% |
| South Korea | 3.1% |
| European Union | 3% |
| United Kingdom | 2.9% |
How do country-level CAGRs compare in the eco flooring market?
Country CAGRs for eco flooring fall between 2.9% and 3.3%. The United States is ahead on a 3.3% CAGR over 2026 to 2036, and Japan follows on 3.2%. Korean sales match the 3.1% global CAGR. The European Union, profiled as one bloc, posts 3%. FMI data show the United Kingdom last on 2.9%.
- The United States combines certification demand with recycled and low-emission products.
- Japan builds energy-efficient homes under indoor air quality rules.
- South Korea backs sustainable housing with incentives and coatings.
- The European Union tightens environmental policy in Germany, France and Italy.
- The United Kingdom favours low-carbon construction and toxin-free adhesives.
Full report country CAGRs cover: Asian, European and American regional blocks, together with Middle East & Africa.
Country-wise Analysis
United States Eco Flooring Market Outlook (2026 to 2036)
Green certification, buyer demand and government mandates support US sales of recycled and low-emission floors. A 3.3% CAGR puts the United States first in the country table. Illinois held second place in the 2025 LEED ranking, and owners in New York, Illinois and Georgia use LEED to modernise existing offices.[3] LEED office upgrades in New York, Illinois and Georgia will create repeat orders for carpet tile and resilient floor replacements.
Key takeaway: Refurbished certified offices, campuses and hospitals will carry the 3.3% US CAGR.
Japan Eco Flooring Market Outlook (2026 to 2036)
Sustainable urban development and energy-efficient housing guide floor choices in Japan. Japan started 740,667 homes in 2025, down 6.5% and the lowest count in 62 years, on land ministry figures reported by Jiji Press.[6] Owner-occupied houses dropped 7.7% to 201,285 units.[6] Construction of energy-saving wooden homes was delayed after a law revision in April.[6] Fewer new homes will move demand for floors in Japan toward renovation of existing stock. Japanese sales grow at a 3.2% CAGR. Indoor air quality rules push builders toward low-emission materials. Compact homes will favour cork and engineered wood with thin profiles and good acoustic performance.
Key takeaway: Japanese demand will reward thin, quiet, low-emission floors for compact homes.
South Korea Eco Flooring Market Outlook (2026 to 2036)
Government incentives and environmental rules support sustainable housing in South Korea. Advanced coatings improve the durability of eco floors in apartments. South Korea posts a 3.1% CAGR, equal to the eco flooring market as a whole. A recovery in remodeling demand pushed LX Hausys to a second-quarter 2026 operating profit 329% above the prior year at KRW 54.9 billion, The Asia Business Daily reported.[7] Housing transactions from January to June totaled 396,274 units, up 10.6%.[7] Remodeling work will add floor replacement orders in older Korean apartments. Apartment builders will specify low-emission floors across whole complexes in single orders.
Key takeaway: Bulk apartment orders will give eco flooring suppliers scale in Korea, provided advanced coatings meet apartment durability needs.
European Union Eco Flooring Market Outlook (2026 to 2036)
Stricter environmental policy in Germany, France and Italy shapes EU demand. The bloc grows at a 3% CAGR. Tarkett reported vinyl flooring recovery with IKEA across 14 European countries.[1] Energy-efficient housing and promotion of low-carbon materials will widen the market for linoleum and recycled vinyl.
Key takeaway: Recovery networks and low-carbon policy will make the EU the testing ground for closed-loop flooring.
United Kingdom Eco Flooring Market Outlook (2026 to 2036)
FMI places the United Kingdom slowest, at 2.9%. UK sustainability policy and green architecture still support low-carbon construction. Toxin-free adhesives gain ground in homes and offices. Updated Approved Documents F (Ventilation) and L for England were published with confirmation of the Future Homes Standard, the Chartered Institute of Housing reported on 24 March 2026.[8] The standard takes effect for most homes in England on 24 March 2027, followed by a 12-month transition period.[8] New ventilation guidance will draw attention to emissions from floors and adhesives in new homes. Refurbishment of older UK homes will carry the 2.9% UK CAGR.
Key takeaway: UK sales will grow through refurbishment, with adhesive choice as a key specification point.
Who are the notable companies in the eco flooring market?
Mohawk Industries, Inc., Interface, Inc., Shaw Industries Group, Inc., Forbo Flooring Systems and Tarkett S.A. hold the largest shares, and Armstrong Flooring, Gerflor Group, Cali Bamboo, The Dixie Group and Green Building Supply also compete.
FMI puts Mohawk Industries at 17 to 21% of the market and Interface at 13 to 17%. Shaw Industries holds 10 to 14%, Forbo Flooring Systems 7 to 11% and Tarkett 5 to 9%. Other companies together account for 35 to 45%.
Contract flooring makers competing in the fast lane of healthcare saw billings from health-focused buyers rise in 2026. Interface lifted Q2 2026 net sales by 5.4% to USD 395.7 million, with global Healthcare billings up 19%.[5] Tarkett reported 43% of energy consumption from renewable sources in the 2025 statement.[1]
- Top five by share: Mohawk Industries, Inc., Interface, Inc., Shaw Industries Group, Inc., Forbo Flooring Systems, and Tarkett S.A.
- Other named suppliers: Armstrong Flooring, Gerflor Group, Cali Bamboo, The Dixie Group, and Green Building Supply.
Competitive Benchmarking: Eco Flooring Market
Table 9: Competitive Benchmarking for the Eco Flooring Market (qualitative documentation ratings), 2026
| Company | Recycled Content | Take-back | Carbon Targets | Disclosure |
|---|---|---|---|---|
| Tarkett S.A. | High | High | High | High |
| Interface, Inc. | Medium | Low | High | High |
| Mohawk Industries, Inc. | Low | Low | Low | Medium |
| Shaw Industries Group, Inc. | Low | Low | Low | Low |
| Forbo Flooring Systems | Low | Low | Low | Medium |
Ratings in the table (High, Medium, Low) reflect the depth of dated company reporting per column.
Key Developments in the Eco Flooring Market
- In September 2026, federal statisticians put July 2026 US construction outlays at a USD 2,157.6 billion annual rate.[2]
- In August 2026, Interface lifted full-year guidance after a USD 395.7 million second quarter.[5]
- In August 2026, The Asia Business Daily reported a 329% rise in LX Hausys second-quarter operating profit.[7]
- In April 2026, Tarkett published the 2025 Sustainability Statement with 20% recycled raw materials.[1]
- In March 2026, the USGBC named the Top 10 States for LEED in 2025.[3]
- In March 2026, the Future Homes Standard for England was confirmed with updated Approved Documents F and L.[8]
- In January 2026, Jiji Press reported 740,667 Japanese housing starts for 2025.[6]
- In August 2025, ISO published the second edition of ISO 5684 for low-VOC flooring adhesives.[4]
Key Players in the Eco Flooring Market
Top Five by Share
- Mohawk Industries, Inc.
- Interface, Inc.
- Shaw Industries Group, Inc.
- Forbo Flooring Systems
- Tarkett S.A.
Other Named Suppliers
- Armstrong Flooring
- Gerflor Group
- Cali Bamboo
- The Dixie Group
- Green Building Supply
Eco Flooring Market - Report Scope
Table 10: Report Scope for the Eco Flooring Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Material type; end use; price range; distribution channel; region |
| Quantitative units | USD billion |
| Market definition | Floor coverings made from renewable, recycled or low-emission materials, including cork, wood, bamboo, linoleum, glass tiles, concrete, wool carpet, rubber and leather, for residential and non-residential use. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia & Pacific; Middle East & Africa |
| Countries covered | United States; Japan; South Korea; European Union; United Kingdom |
| Key companies profiled | Mohawk Industries, Inc., Interface, Inc., Shaw Industries Group, Inc., Forbo Flooring Systems, Tarkett S.A., Armstrong Flooring, Gerflor Group, Cali Bamboo, The Dixie Group, Green Building Supply |
| Forecast period | 2026 to 2036 |
Eco Flooring Market - Research Methodology
Table 11: Research Methodology for the Eco Flooring Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Producer sustainability statements, quarterly results, green building council rankings and federal construction statistics dated May 2025 or later. |
| Desk Research | Certification trends, recycled-content targets, take-back volumes and construction activity were tracked for each profiled country. |
| Market Sizing and Forecasting | The model starts at USD 86.6 billion in 2025 and applies a 3.1% CAGR. |
| Data Validation | Producer claims were matched to the company release that carried them. |
Eco Flooring Market by Segments
Eco Flooring Market segmented by Material Type:
- Cork
- Wood
- Bamboo
- Linoleum
- Glass Tiles
- Concrete
- Wool Carpet
- Rubber
- Leather
Eco Flooring Market segmented by End Use:
- Residential
- Non-Residential
Eco Flooring Market segmented by Price Range:
- Economy
- Mid-range
- Premium
Eco Flooring Market segmented by Distribution Channel:
- Online
- Offline
Eco Flooring Market by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa
Research Sources and Bibliography
- [1] Tarkett. (2026, April 1). Tarkett delivers concrete climate progress, cutting value-chain emissions by 27% in line with its 2030 goals. https://www.tarkett-group.com/app/uploads/2026/03/31234825/press-release-1st-april2026-sustainability-statement.pdf
- [2] U.S. Census Bureau. (2026, September 1). Monthly Construction Spending, July 2026 (Release CB26-140). https://www.census.gov/construction/c30/pdf/pr202607.pdf
- [3] PHCP Pros. (2026, March 4). U.S. Green Building Council Announces Top 10 States for Green Building in 2025. https://www.phcppros.com/articles/23068-us-green-building-council-announces-top-10-states-for-green-building-in-2025
- [4] International Organization for Standardization. (2025, August). ISO 5684, Adhesives, Floor covering adhesives and products for flooring installation, Assessment and classification of low volatile organic compound (VOC) products, Edition 2. https://www.iso.org/standard/88053.html
- [5] Interface, Inc. (Form 8-K, SEC). (2026, August 7). Interface Reports Second Quarter 2026 Results. https://www.sec.gov/Archives/edgar/data/0000715787/000071578726000019/a991pressreleaseq22026.htm
- [6] Jiji Press, via Nippon.com. (2026, January 30). Japan Housing Starts Fall to 62-Year Low in 2025. https://www.nippon.com/en/news/yjj2026013001015
- [7] The Asia Business Daily. (2026, August 11). Building Materials Industry Outperforms in Q2, Raw Material Costs Loom as Second Half Challenge. https://view.asiae.co.kr/en/article/2026081016021017061
- [8] Chartered Institute of Housing. (2026, March 24). CIH welcomes confirmation of the Future Homes Standard. https://www.cih.org/news/cih-welcomes-confirmation-of-the-future-homes-standard/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will eco flooring sales reach in 2026 and 2036?
- At what CAGR will the market grow from 2026 to 2036?
- Which material type will hold the biggest share?
- Will residential or non-residential projects buy more eco flooring?
- Which country will post the fastest growth?
- Which producers will shape recycled-content and certified product lines?
Frequently Asked Questions
What is the size of the eco flooring market in 2026?
Roughly USD 89.3 billion of eco flooring will sell in 2026. FMI projections then point to USD 121.1 billion for 2036.
How fast will the eco flooring market grow?
Certification and recycled-content rules will keep growth near a 3.1% CAGR from 2026 to 2036.
Which material type will lead?
Bamboo will hold the top material position at an estimated 21.4%, with cork second.
Which end use will dominate?
Homes will remain the bigger end use, on an estimated 58.6% in 2026.
Which country will grow fastest?
US sales will lead the country table on a 3.3% CAGR, on FMI figures, with Japan next at 3.2%.
Who are the main companies?
Mohawk Industries, Interface, Shaw Industries, Forbo Flooring Systems and Tarkett will remain the five largest by share.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Type, 2026 to 2036
- Cork
- Wood
- Bamboo
- Linoleum
- Glass Tiles
- Concrete
- Wool Carpet
- Rubber
- Leather
- Y-o-Y Growth Trend Analysis By Material Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Residential
- Non-Residential
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Price Range, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price Range, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price Range, 2026 to 2036
- Economy
- Mid-range
- Premium
- Y-o-Y Growth Trend Analysis By Price Range, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Range, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Online
- Offline
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia & Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Key Takeaways
- South Asia & Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Type
- By End Use
- By Price Range
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Tarkett S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Interface, Inc.
- Mohawk Industries, Inc.
- Shaw Industries Group, Inc.
- Forbo Flooring Systems
- Armstrong Flooring
- Gerflor Group
- Cali Bamboo
- The Dixie Group
- Green Building Supply
- Tarkett S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


