
- Market Size (2026)
- USD 6.2 Bn
- Forecast (2036)
- USD 10.2 Bn
- CAGR (2026 to 2036)
- 5.1%
How big is Egg Packaging Market in 2026?
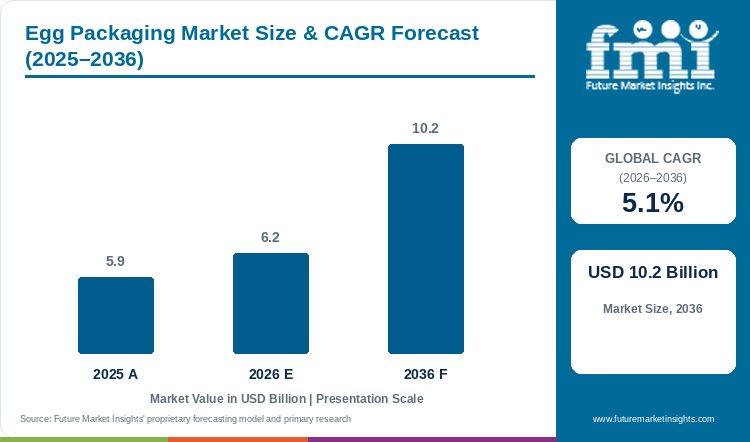
Demand for egg packaging is projected to expand at 5.1% CAGR between 2026 and 2036. Industry value grows from USD 5.9 billion in 2025 to USD 6.2 billion in 2026 and is projected to reach USD 10.2 billion by 2036.
According to Future Market Insights analysis, the global egg packaging market stands at USD 5.9 billion in 2025. It rises to USD 6.2 billion in 2026 and reaches USD 10.2 billion by 2036, generating USD 4.0 billion in added revenue. The 2026 to 2036 expansion rate stands at 5.1% CAGR. Grading lines keep raising throughput as fragile shells must survive packing, stacking, and retail handling without costly breakage.
In April 2026, USDA NASS poultry reports documented 105 billion United States eggs for 2025 [1]. That volume turns shell protection into continuous high-volume procurement across recyclable packaging systems and automated tray replenishment. Cartons hold the leading format position with 51.5% share in 2026, since closed cells limit shell contact through automated grading lines. Growth across evaluated economies spans 4.1% in Japan to 6.2% in Italy, though moisture sensitivity and denesting faults still slow conversion.
Key Market Trends & Insights
- By packaging format: Cartons are projected to account for 51.5% in 2026, driven by closed-cell protection and printable retail surfaces.
- By material substrate: Molded fiber is estimated to hold 35.6% in 2026, owing to recycled-paper feedstock and established recovery routes.
- By end-use channel: Retail channels are forecast to represent 34.0% in 2026, supported by branded dozen-pack sales and shelf turnover.
Regional Highlights
- Fastest-growing evaluated country: Italy, at 6.2% CAGR from 2026 to 2036.
- Follower countries: Spain at 5.7%, the UK at 5.3%, the USA at 4.9%, and Australia at 4.5%, while Japan records the lowest evaluated CAGR at 4.1%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Egg Packaging Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 5.9 billion |
| Estimated Market Size in 2026 | USD 6.2 billion |
| Projected Market Size by 2036 | USD 10.2 billion |
| CAGR, 2026 to 2036 | 5.1% |
| Added Revenue, 2026 to 2036 | USD 4.0 billion |
Adoption develops differently across countries because regional grading equipment standards and environmental packaging regulations drive distinct material replacement cycles. In February 2025, Regulation (EU) 2025/40 entered into force and established binding packaging recyclability rules across member states [2]. That timeline pushes commercial egg packers to transition toward molded fiber packaging that clears retailer audits without slowing packing line speeds. Fiber suppliers are developing lightweight pulp formulations that retain compression strength under varying cool-room humidity conditions.
Egg-Volume and Pack-Requirement Sizing
Table 2: Egg-Volume and Pack-Requirement Sizing for the Egg Packaging Market (USD billion and operational indicators), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 5.9 | 6.2 | 10.2 |
| United States shell-egg output (billion eggs) | 105 | 104 to 108 | 120 to 135 |
| Fiber carton share of format mix (%) | 50 to 52 | 51.5 | 53 to 56 |
| Average retail pack count (eggs per pack) | 10 to 12 | 10 to 12 | 10 to 12 |
Calculation basis: Pack volumes scale with graded shell-egg throughput and retail dozen-pack penetration. Ranges reflect flock-health and retail-mix scenarios and should be read as indicative bands.
Per-Capita and Facility Spending Indicators
Table 3: Per-Capita and Retail Spending Indicators for the Egg Packaging Market (USD and volume bands), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global shell-egg output (billion eggs) | 1,450 to 1,550 | 1,480 to 1,580 | 1,750 to 1,900 |
| Spend per 1,000 eggs (USD) | 3.80 to 4.20 | 3.90 to 4.30 | 5.30 to 5.90 |
| Spend per retail pack (USD cents) | 45 to 52 | 46 to 54 | 62 to 74 |
| Retail channel revenue (USD billion) | 2.0 | 2.1 | 3.5 |
Table 4: Facility and Channel Spending Indicators for the Egg Packaging Market (USD billion and counts), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 6.2 billion | Report value |
| Grading and packing facilities worldwide | 85,000 to 95,000 | 2024 secondary estimate |
| Market spend per facility (USD) | 65,000 to 73,000 | Calculated |
| Retail channel revenue, 2026 | USD 2.1 billion | 34.0% share |
Calculation basis: Global output bands combine FAO series with national flock reports. Spend ratios divide report values by egg and facility counts. Figures are scenario ranges for planning use.
Analyst Perspective
“Egg packs are becoming part of the grading system rather than a passive container. Fiber quality and denesting reliability will decide which formats scale without raising line losses.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Egg Packaging Market segmented?
The egg packaging market is segmented by packaging format, material substrate, and end-use channel. In 2026, cartons are projected at 51.5%, molded fiber at 35.6%, and retail channels at 34.0%.
By packaging format: Cartons, trays, bulk flats, clamshells, and specialty packs.
By material substrate: Molded fiber, recycled paperboard, PET, polypropylene, expanded polystyrene, and plant-fiber blends.
By end-use channel: Retail, foodservice, institutional buyers, egg processors, and hatcheries.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do cartons account for a notable share of packaging format demand?
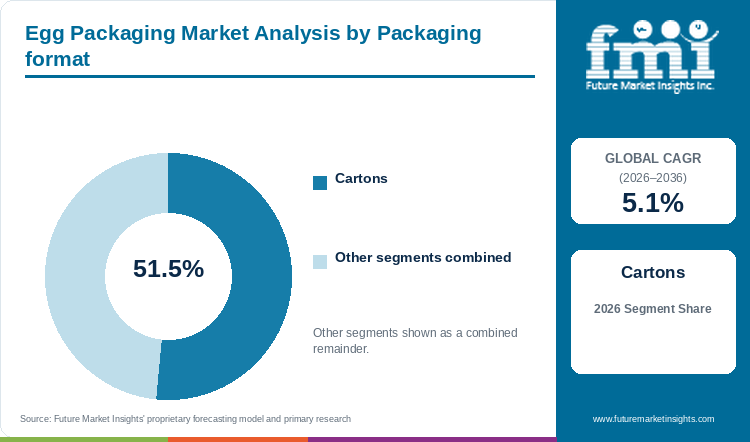
Based on packaging format, cartons are projected to account for 51.5% in 2026, driven by closed-cell cushioning and labeling space.
Table 5: Packaging Format Share for the Egg Packaging Market (percentage share), 2026
| Packaging Format | Share (2026) |
|---|---|
| Cartons | 51.5% |
| Other Formats Combined | 48.5%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Packaging Format Leadership and Market Growth for the Egg Packaging Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.1% |
| Leading Segment | Cartons |
Closed cartons protect shells while carrying grade and farm codes at retail. The format runs through installed grading equipment with limited changeovers. Buyers favor that fit, since line-tested packs lower breakage claims across sustainable fiber packaging operations.
- In 2026, cartons are expected to lead packaging format with 51.5% share, linked to retail-ready protection and labeling needs.
- Hartmann states that its molded-fiber egg cartons support grading efficiency, safe protection, and retail category appeal [3].
What supports molded fiber as a preferred material substrate choice?
By material substrate, molded fiber is estimated to hold 35.6% in 2026, owing to recycled-paper feedstock and established recovery routes.
Formed pulp pockets cushion shells and absorb surface moisture during cool storage. Households already sort paper packs through familiar curbside collection streams each week. That disposal clarity helps converters defend fiber specifications across retail food packaging programs.
- Molded fiber is likely to capture 35.6% share in 2026, consistent with buyer demand for curbside-recyclable cushioning.
- Hartmann reports that recycled paper forms the core raw material across its molded-fiber egg packaging [4].
How are retail channels gaining use within egg packaging demand?
In 2026, retail channels are expected to lead end use with 34.0% share, supported by dozen packs and shelf turnover.
Closed retail packs link protection with visible grade, size, and date information. Branded dozen formats suit shelf stacking and home delivery handling routines. That visibility supports repeat purchase decisions, reinforcing reliance on paper based packaging across supermarket aisles.
- The end-use category is forecast to be led by retail channels at 34.0% share in 2026, in line with branded dozen-pack turnover.
- In October 2025, US EPA packaging data placed paper and paperboard recovery near two-thirds of generated containers, keeping retail fiber packs inside familiar recycling streams [5].
What are the drivers, restraints, and opportunities in the Egg Packaging Market?
In the egg packaging market, the key driver is packaged egg volume, the key restraint is fiber and line variability, and the key opportunity is recyclable pack redesign.
- Driver: Higher graded egg throughput expands demand for packs that limit breakage between farms, distribution centers, and stores.
- Restraint: Moisture exposure and inconsistent fiber geometry can reduce stack strength or interrupt automated denesting on packing lines.
- Opportunity: Lightweight molded-fiber packs can lower material use while adding printable surfaces for traceability and retailer branding.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Graded egg volumes keep rising as protein demand supports flock expansion across major producing regions. FAO FAOSTAT food and agriculture data placed global shell-egg output above 1.4 trillion eggs in recent reporting years [6]. That flow converts cartons and trays into repeat orders tied to laying cycles. Packers schedule fiber supply against flock placements and seasonal retail peaks. Retailers add private-label dozen programs that widen shelf facings and stabilize weekly replenishment. Suppliers that match tooling to grader models secure longer supply agreements. FMI data suggests that throughput-linked demand keeps carton volumes resilient across protective transit packaging networks even when flock disease disrupts regional supply.
Risk Assessment of the Egg Packaging Market: Operational and Fiber-Strength Friction
Fiber packs lose stacking strength when cool-room condensation and transport humidity soften molded walls. ASTM box-compression protocols measure that failure point before pallets leave packing stations [7]. Denesting faults add a second risk when cartons stick inside magazines and stall grading lines. A short stoppage erases material savings from lightweighting within a single shift. Buyers therefore run qualification trials across humidity, closure, and print adhesion. Suppliers that document stable denesting keep approved-vendor status through seasonal peaks. Flock disease outbreaks tighten supply suddenly and raise cost pressure on every pack component. Converters answer with downgauged walls that hold compression ratings at lower fiber weights. Retailers accept those packs only after store-level damage audits stay flat.
Commercial Opportunity Analysis: Lightweight Differentiation and Retail-Ready Formats
Retailer recyclability targets open shelf space for lighter molded packs with clearer disposal labels. Huhtamaki 2025 reporting described fiber-packaging scale, cost control, and operating discipline across industrial pulp molding operations [8]. Converters can cut grammage while adding printable surfaces for traceability codes. Private labels adopt those surfaces for farm stories and QR provenance. Foodservice chains trial fiber trays that nest tighter and reduce inbound freight. Each format that passes line trials converts directly into multi-site supply contracts. Hatcheries and processors add steadier bulk-flat demand outside retail seasonality. Export lanes need stack-stable trays that survive warm-weather handling and repeated transfers. Suppliers that cover both retail and bulk formats spread tooling costs wider.
Egg Packaging Market by Country (2026 to 2036)
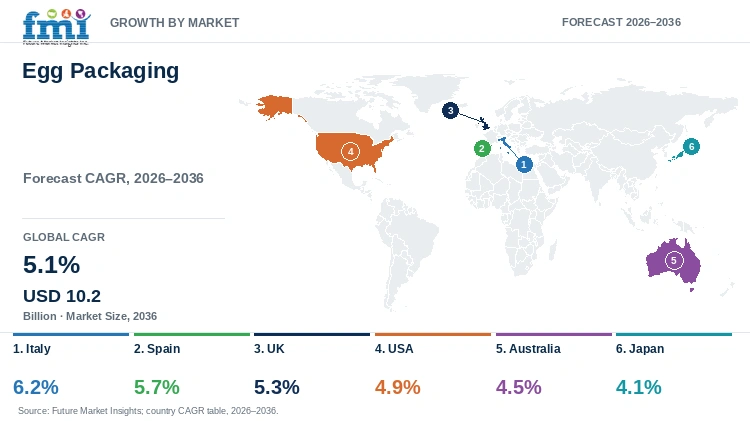
As per FMI, Italy represents the fastest-growing egg packaging market among the six evaluated countries, at a 6.2% CAGR from 2026 to 2036, while Japan records the slowest expansion at 4.1% CAGR. Across all six covered economies, commercial success is dictated by how effectively converters navigate recyclability rules, sustain grading-line compatibility, and overcome fiber cost pressure.
Table 7: Country CAGR and Primary Growth Levers for the Egg Packaging Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Italy | 6.2% | EU packaging rules and a large grocery channel |
| Spain | 5.7% | Packaged egg output and retailer fiber conversion |
| UK | 5.3% | Retail traceability and producer code visibility |
| USA | 4.9% | High shell-egg throughput and graded retail formats |
| Australia | 4.5% | Long distribution routes and free-range pack differentiation |
| Japan | 4.1% | Mature retail standards and compact high-count packs |
Source: Future Market Insights analysis
Italy Egg Packaging Market Outlook (2026 to 2036)
Italian grocery chains are converting egg aisles toward recyclable fiber cartons ahead of EU design rules. ISTAT 2025 agri-food accounts placed national shell-egg output above 750 thousand tonnes, keeping packing halls full across the Po Valley [9]. By 2036, Italy is projected to grow at 6.2% CAGR, supported by retailer fiber targets and private-label dozen growth. While varied regional grader fleets complicate single-format rollouts, converters answer with adjustable tooling and quick-change carton sizes. That flexibility lets packers standardize recyclable packs without replacing installed grading lines. National recovery streams already handle paper packs at scale, so households sort cartons without new instructions. Converters pair that advantage with water-based inks that meet food-contact print limits.
Key takeaway: In Italy, retailer recyclability targets and adjustable fiber tooling turn EU design rules into recurring carton orders.
Spain Egg Packaging Market Outlook (2026 to 2036)
Spanish egg flows travel long warm routes from farm belts to coastal cities and export buyers. MAPA 2025 balance sheets placed Spanish egg output above 900 thousand tonnes, with retail and export packs sharing grading capacity [10]. Spain's egg packaging outlook is anticipated to advance at 5.7% CAGR over the assessment period, driven by retail output and fiber conversion. Yet commercial uptake faces friction from heat and humidity that soften fiber walls during summer distribution. Suppliers respond with moisture-tolerant pulp blends and ventilated tray designs that hold stack strength. Those formats protect warm-lane shipments without shifting packers toward plastic. Regional converters keep delivery routes short, so custom counts reach packers within days.
Key takeaway: In Spain, warm-route handling needs and moisture-tolerant fiber designs convert export volumes into steady tray demand.
UK Egg Packaging Market Outlook (2026 to 2036)
British grocery shelves demand full traceability on every egg pack sold through major multiples. Defra 2025 quarterly statistics recorded UK packing volumes above 10 billion eggs, with lion-marked retail packs dominating throughput [11]. Egg packaging demand in the UK is forecast to rise at 5.3% CAGR over the forecast period, underpinned by code visibility and grocery turnover. However, print-clarity rules raise pre-press costs for smaller converters serving regional packers. Larger suppliers answer with high-definition plates and quick-approval artwork systems that shorten launch cycles. That service edge keeps branded and private-label programs inside fiber cartons. Online grocery growth adds protective stock-keeping pressure, since delivered packs face extra drops before reaching kitchens.
Key takeaway: In the UK, traceability print rules and grocery turnover lock branded volume into high-clarity fiber cartons.
USA Egg Packaging Market Outlook (2026 to 2036)
American shell-egg scale dwarfs other evaluated markets, with packing concentrated near Midwest laying belts. USDA ERS 2025 outlooks placed US per-capita egg availability near 280 eggs, sustaining year-round carton circulation [12]. Adoption of egg packaging in the USA is estimated to expand at 4.9% CAGR through 2036, linked to retail volumes and material shifts. Nonetheless, state-level plastic limits force rapid respecification across long retail supply chains. National converters answer with dual fiber and thermoformed plastic packaging lines that qualify packs for egg carton manufacturing and store programs. That breadth keeps supply steady when regional rules change mid-contract. Foodservice distributors add bulk-flat pull outside retail dozen cycles, smoothing plant utilization across quarters.
Key takeaway: In the USA, unmatched shell-egg scale and dual-material lines turn state rule shifts into managed pack conversions.
Australia Egg Packaging Market Outlook (2026 to 2036)
Australian eggs travel vast distances from rural sheds to metropolitan retailers across harsh summer conditions. ABARES 2025 agricultural accounts recorded national egg output above 350 million dozen, with free-range lines growing fastest [13]. The Australia egg packaging sector is projected to record 4.5% CAGR during the assessment period, influenced by long-haul protection and premium differentiation. The central commercial obstacle involves freight costs that punish heavy or bulky formats on interstate lanes. Converters respond with lightweight stack-stable trays and compact retail cartons that cut cube while outperforming standard rigid protective containers. Those designs protect free-range premiums without inflating delivered pack costs. Retailers reward damage-rate data with longer supply terms across private-label ranges.
Key takeaway: In Australia, long-haul freight pressure and free-range growth reward lightweight stack-stable tray designs.
Japan Egg Packaging Market Outlook (2026 to 2036)
Japanese retail buyers judge egg packs on presentation precision as much as on shell protection. MAFF 2025 supply tables placed Japanese egg output near 2.5 million tonnes, moved through dense daily distribution [14]. In Japan, egg packaging demand is predicted to advance at 4.1% CAGR through 2036, associated with compact formats and strict retail specifications. Nevertheless, high cleanliness standards lift qualification costs for recycled-fiber finishes in premium stores. Domestic suppliers answer with smooth-surface pulp blends and tight-tolerance lids that photograph well on shelves. That finish discipline keeps fiber cartons resident in convenience and supermarket sets. Smaller household sizes sustain demand for six-count and ten-count packs alongside standard dozens.
Key takeaway: In Japan, presentation-led retail standards steer fiber suppliers toward smooth compact premium-ready packs.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Egg Packaging Market?
Hartmann Packaging, Huhtamaki, Tekni-Plex, Pactiv Evergreen, CDL Omni-Pac, DFM Packaging Solutions, Cascades, and Primapack are notable companies operating in the egg packaging market.
Future Market Insights observes that fiber specialists and diversified converters split the order book by tooling depth. Dedicated pulp molders run egg-specific machines across continents with decades of tooling knowledge. Broader groups attach egg packs to foodservice portfolios through molded pulp packaging supply and retail distribution.
Molded-fiber specialists: Hartmann Packaging, Huhtamaki, CDL Omni-Pac, and DFM Packaging Solutions focus on protective pulp formats.
Multi-material packaging groups: Tekni-Plex, Pactiv Evergreen, and Cascades combine converting scale with broader food-packaging capabilities.
Regional carton suppliers: Primapack and other local converters compete through pack counts, colors, print, and shorter delivery routes.
Competitive Benchmarking: Egg Packaging Market
Table 8: Competitive Benchmarking for the Egg Packaging Market (qualitative capability ratings), 2026
| Company | Egg-Pack Breadth | Fiber Capability | Customer Access | Geographic Reach |
|---|---|---|---|---|
| Hartmann Packaging | High | High | High | High |
| Huhtamaki | High | High | High | High |
| Tekni-Plex | Medium | Medium | High | High |
| Pactiv Evergreen | Medium | Medium | High | Medium |
| CDL Omni-Pac | High | High | Medium | Medium |
| DFM Packaging Solutions | High | High | Medium | Medium |
| Cascades | Medium | High | High | Medium |
| Primapack | Medium | Medium | Medium | Low |
Key Developments in the Egg Packaging Market
- In March 2026, Huhtamäki Oyj published its 2025 Annual Report on the company’s investor website, reporting net sales totaling EUR 4.0 billion for the full year 2025. The report covers the company’s fiber and foodservice packaging segments, which include molded-fiber egg packaging supplied to retail and foodservice customers across multiple regions [16].
Key Players in the Egg Packaging Market
Molded-Fiber Egg-Pack Specialists
- Hartmann Packaging
- CDL Omni-Pac
- DFM Packaging Solutions
Diversified Packaging Converters
- Huhtamaki
- Tekni-Plex
- Pactiv Evergreen
- Cascades
Regional Egg-Pack Suppliers
- Primapack
Egg Packaging Market - Report Scope
Table 9: Report Scope for the Egg Packaging Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Packaging format; material substrate; end-use channel |
| Quantitative units | USD billion |
| Market definition | Supplier revenue from cartons, trays, flats, clamshells, and related protective packs made for shell eggs. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | Italy, Spain, UK, USA, Australia, Japan, and additional countries in the full report |
| Key companies covered | Hartmann Packaging, Huhtamaki, Tekni-Plex, Pactiv Evergreen, CDL Omni-Pac, DFM Packaging Solutions, Cascades, Primapack |
| Forecast period | 2026 to 2036 |
| Approach | Primary and desk research with sizing, triangulation, and validation. |
Egg Packaging Market - Research Methodology
Table 10: Research Methodology for the Egg Packaging Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. |
| Market Sizing and Forecasting | The forecast framework combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulation, purchasing cycles, supply availability, and barriers to wider market use. |
| Data Validation | Estimates were checked against public data, company activity, trade patterns, industry developments, and primary interviews. Validation tested whether products, applications, and company revenues fell within the market boundary. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct relevance were excluded. |
Egg Packaging Market by Segments
Egg Packaging Market segmented by Packaging format:
- Cartons
- Trays
- Bulk flats
- Clamshells
- Specialty packs
Egg Packaging Market segmented by Material substrate:
- Molded fiber
- Recycled paperboard
- PET
- Polypropylene
- Expanded polystyrene
-
Plant-fiber blends
Egg Packaging Market segmented by End-use channel:
- Retail
- Foodservice
- Institutional buyers
- Egg processors
- Hatcheries
Egg Packaging Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, April 30). Poultry - Production and Value: 2025 Summary.
- [2] European Commission. (2025). Packaging and Packaging Waste Regulation: Implementation and policy materials.
- [3] Hartmann Packaging. (2026). Egg cartons: Smart solutions for every need. Product information.
- [4] Hartmann Packaging. (2026). Sustainable moulded fibre egg packaging. Company sustainability profile.
- [5] U.S. Environmental Protection Agency. (2025, October). Containers and packaging: Product-specific data.
- [6] Food and Agriculture Organization of the United Nations. (2026). FAOSTAT: Crops and livestock products data.
- [8] Huhtamaki Oyj. (2025). Annual report 2024: Fiber and foodservice packaging operations.
- [9] Italian National Institute of Statistics. (2025). Agri-food production accounts: Poultry and eggs.
- [10] Ministry of Agriculture, Fisheries and Food (Spain). (2025). Egg production balance sheets.
- [11] Department for Environment, Food and Rural Affairs (UK). (2025). Quarterly egg statistics.
- [12] U.S. Department of Agriculture, Economic Research Service. (2025). Poultry and egg outlook: Per-capita availability tables.
- [13] Australian Bureau of Agricultural and Resource Economics and Sciences. (2025). Agricultural commodity statistics: Eggs.
- [14] Ministry of Agriculture, Forestry and Fisheries (Japan). (2025). Food supply and demand tables: Eggs.
- [15] Huhtamaki Oyj. (2026, March 3). Huhtamaki's 2025 Annual Report published. Press release.
- [16] Huhtamäki Oyj. (2026). Huhtamaki’s 2025 Annual Report published. Stock exchange release, 3 March 2026. https://www.huhtamaki.com/investors
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the egg packaging market in 2026 and 2036?
- Which demand conditions support global egg packaging sales through 2036?
- Why do cartons lead packaging format revenue in the egg packaging market?
- Why does molded fiber hold a notable material substrate share?
- Which countries show notable egg packaging expansion during the assessment period?
- Which companies supply cartons, trays, and molded-fiber egg packs?
- How do recyclability rules shape fiber pack conversion through 2036?
- What should buyers test before approving a new egg pack supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Packaging format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging format, 2026 to 2036
- Cartons
- Trays
- Bulk flats
- Clamshells
- Specialty packs
- Y-o-Y Growth Trend Analysis By Packaging format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging format, 2026 to 2036
- Global Market Analysis and Forecast, By Material substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material substrate, 2026 to 2036
- Molded fiber
- Recycled paperboard
- PET
- Polypropylene
- Expanded polystyrene
- Plant-fiber blends
- Y-o-Y Growth Trend Analysis By Material substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-use channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-use channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-use channel, 2026 to 2036
- Retail
- Foodservice
- Institutional buyers
- Egg processors
- Hatcheries
- Y-o-Y Growth Trend Analysis By End-use channel, 2021 to 2025
- Absolute $ Opportunity Analysis By End-use channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Packaging format
- By Material substrate
- By End-use channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Packaging format
- By Material substrate
- By End-use channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Packaging format
- By Material substrate
- By End-use channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Packaging format
- By Material substrate
- By End-use channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Packaging format
- By Material substrate
- By End-use channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Packaging format
- By Material substrate
- By End-use channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Packaging format
- By Material substrate
- By End-use channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Packaging format
- By Material substrate
- By End-use channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Hartmann Packaging
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Huhtamaki
- Tekni-Plex
- Pactiv Evergreen
- CDL Omni-Pac
- DFM Packaging Solutions
- Cascades
- Primapack
- Hartmann Packaging
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-use channel, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-use channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End-use channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End-use channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End-use channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End-use channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End-use channel, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End-use channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Packaging format
- Figure 6: Global Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Material substrate
- Figure 9: Global Market Value Share and BPS Analysis by End-use channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-use channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-use channel
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Packaging format
- Figure 26: North America Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Material substrate
- Figure 29: North America Market Value Share and BPS Analysis by End-use channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-use channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-use channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Packaging format
- Figure 36: Latin America Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Material substrate
- Figure 39: Latin America Market Value Share and BPS Analysis by End-use channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End-use channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End-use channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Packaging format
- Figure 46: Western Europe Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Material substrate
- Figure 49: Western Europe Market Value Share and BPS Analysis by End-use channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End-use channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End-use channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Packaging format
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Material substrate
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End-use channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End-use channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End-use channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Packaging format
- Figure 66: East Asia Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Material substrate
- Figure 69: East Asia Market Value Share and BPS Analysis by End-use channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End-use channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End-use channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Packaging format
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Material substrate
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End-use channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End-use channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End-use channel
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Packaging format
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Material substrate
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-use channel, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-use channel, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-use channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the egg packaging market in 2026?
Future Market Insights estimates the egg packaging market at USD 6.2 billion in 2026 and USD 10.2 billion by 2036.
What is the egg packaging market CAGR through 2036?
FMI notes the market is projected to expand at 5.1% CAGR from 2026 to 2036.
Which packaging format leads the market in 2026?
Cartons are projected to hold 51.5% of packaging format revenue in 2026.
Which material substrate has a notable 2026 share?
Molded fiber is estimated to account for 35.6% of material substrate revenue in 2026.
Which country has a notable growth outlook?
Italy is projected to record 6.2% CAGR during the 2026 to 2036 assessment period.
Who are notable egg packaging companies?
Notable suppliers include Hartmann Packaging, Huhtamaki, Tekni-Plex, Pactiv Evergreen, CDL Omni-Pac, DFM Packaging Solutions, Cascades, and Primapack.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
