
- Market Size (2026)
- USD 245.0 Bn
- Forecast (2036)
- USD 442.9 Bn
- CAGR (2026 to 2036)
- 6.1%
How big is Pet Care Market in 2026?
Sales in the pet care market are projected to grow at 6.1% CAGR through 2036. Market size rises from USD 230.9 billion in 2025 to USD 245.0 billion in 2026 and is expected to reach USD 442.9 billion by 2036.
Companion-animal households are shifting daily pet feeding from table scraps and bulk maintenance rations toward formulated clinical nutrition and preventative care. According to Future Market Insights analysis, the global pet care market stands at USD 230.9 billion in 2025 and rises to USD 245.0 billion in 2026. Industry valuation is projected to reach USD 442.9 billion by 2036, expanding at a 6.1% CAGR and generating USD 197.9 billion in added revenue. In January 2025, the American Pet Products Association documented that companion animal ownership surpassed 800 million registered dogs and cats globally [1]. Dry extruded kibble and pellets holds 40.3% share in 2026. Country growth spans 4.9% in Japan to 7.4% in Brazil, though meat inflation pressures margins.
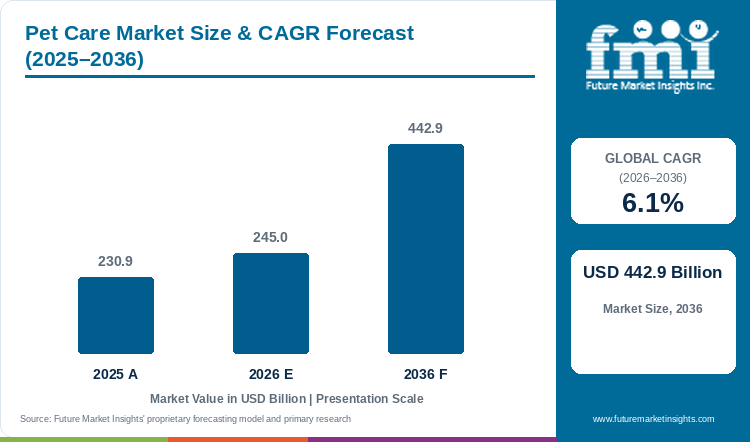
Key Market Trends & Insights
- By product form: Dry extruded kibble and pellets led the market with a share of 40.3% in 2026, driven by economical daily feeding and ambient pantry stability.
- By target species: Canines and dogs accounted for 46.0% of demand in 2026, supported by higher daily caloric maintenance requirements per animal.
- By distribution channel: Specialty pet retail stores represented 33.3% of revenue in 2026, owing to trained nutritional staff and in-store grooming clinics.
- By dietary nature: With a 58.4% share in 2026, conventional complete diets led the category, as balanced vitamin-mineral kibble anchors everyday feeding.
Regional Highlights
- Fastest-growing evaluated country: Brazil, at 7.4% CAGR from 2026 to 2036.
- By country: UK at 6.8%, USA at 6.3%, Germany at 5.9%, and France at 5.4% follow, while Japan records the lowest evaluated CAGR at 4.9%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Pet Care Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 230.9 billion |
| Estimated Market Size in 2026 | USD 245.0 billion |
| Projected Market Size by 2036 | USD 442.9 billion |
| CAGR, 2026 to 2036 | 6.1% |
| Added Revenue, 2026 to 2036 | USD 197.9 billion |
Country demand conditions differ as feed safety rules and veterinary clinic access shape how quickly pet owners upgrade from basic rations to therapeutic diets. FMI research indicates that pet nutrition manufacturers face rising animal-protein costs alongside stricter pathogen screening across extrusion plants. In February 2025, the Association of American Feed Control Officials published updated ingredient definitions and labeling standards for complete animal rations [2]. Owing to these tighter rules, processors are phasing out unverified raw meat blends in favor of batch-tested pet food and clinical wellness lines. In addition to this, verified nutritional adequacy statements help specialty retailers defend shelf pricing while protecting households from microbial recalls.
Companion-Animal Population and Spend Sizing
Table 2: Companion-Animal Population and Spend Sizing for the Pet Care Market (USD billion, million animals, and USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 230.9 | 245.0 | 442.9 |
| Registered dogs and cats (million) | 780 to 820 | 800 to 840 | 940 to 1,010 |
| Pet care spending households (million) | 420 to 445 | 435 to 460 | 540 to 580 |
| Spend per pet household (USD) | 540 to 570 | 555 to 590 | 745 to 800 |
Operational note: Companion-animal feeding volumes reflect registered household ownership ratios alongside standard daily caloric maintenance schedules across veterinary clinics.
Per Capita and Veterinary-Clinic Sizing
Formulated companion nutrition has expanded across dry kibble, wet pouches, and gently cooked trays as owners try to prevent chronic kidney and joint disorders before surgical intervention is needed. Rising veterinary surgery fees push households toward daily procurement of veterinary dietary supplements and dental chews. In March 2025, the European Pet Food Industry Federation updated its nutritional guidelines governing calcium-to-phosphorus ratios and amino acid thresholds for complete cat and dog rations [3]. As a result, supermarket and clinic buyers now audit digestibility records and mineral balance sheets before approving new pet nutrition lines for regional distribution.
Table 3: Per Capita and Veterinary-Clinic Spending Indicators for the Pet Care Market (billion people and USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per capita (USD) | 28.1 | 29.5 | 49.5 |
| Spend per 1,000 people (USD) | 28,055.9 | 29,518.1 | 49,486.0 |
| Spend per veterinary clinic (USD thousand) | 1,800 to 1,950 | 1,914 to 2,070 | 3,300 to 3,600 |
Table 4: Veterinary-Clinic and Retail Spending Indicators for the Pet Care Market (USD and thousand clinics), 2026
| Metric | Value | Operational Context |
|---|---|---|
| Market size, 2026 | USD 245.0 billion | Global baseline revenue |
| Veterinary clinics worldwide (thousand) | 128.0 | Active companion practices |
| Market spend per veterinary clinic | USD 1.9 million | Annualized clinic throughput |
| Specialty pet retail revenue, 2026 | USD 81.6 billion | 33.3% distribution share |
Analyst Perspective
"Preventative longevity diets and clinical gut-health chews give pet nutrition brands recurring sales across specialty retail channels. Volatile poultry and beef rendering prices still force processors to qualify alternative protein meals before scaling production."
- Ronak Shah, Principal Consultant, Future Market Insights.
How is the pet care market segmented?
The pet care market is segmented by product form, target species, distribution channel, and dietary nature. In 2026, dry extruded kibble and pellets is projected at 40.3%, canines and dogs at 46.0%, specialty pet retail stores at 33.3%, and conventional complete diet at 58.4%.
By product form: Dry extruded kibble & pellets, wet canned food & pouches, freeze-dried & raw specialty, and treats & supplemental snacks.
By target species: Canine / dogs, feline / cats, and livestock & aquaculture.
By distribution channel: Specialty pet retail stores, supermarkets & mass merchandisers, online e-commerce, and veterinary clinics & farm ag-stores.
By dietary nature: Conventional complete diet, and organic, grain-free & clean-label.
Why do Dry Extruded Kibble & Pellets lead the product form category?
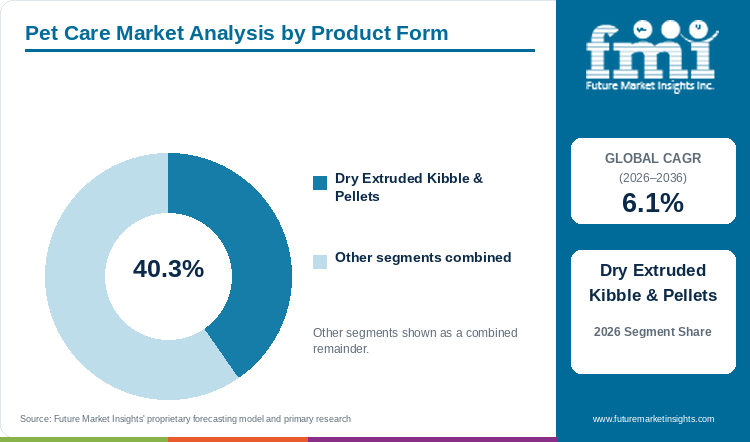
Dry extruded kibble and pellets are projected to hold 40.3% of product form demand in 2026, supported by pantry stability.
Table 5: Product Form Share for the Pet Care Market (percentage share), 2026
| Product Form | Share (2026) |
|---|---|
| Dry Extruded Kibble & Pellets | 40.3% |
| Other Segments Combined | 59.7%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Form Leadership and Market Growth for the Pet Care Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.1% |
| Leading Segment | Dry Extruded Kibble & Pellets |
Dry extruded kibble forms the operational backbone of household pet feeding because low-moisture pellets remain shelf-stable in open bowls without refrigeration. Twin-screw cooking extruders gelatinize cereal and pulse starches while locking rendered meat proteins into dense kibbles that scrape dental plaque during chewing. In addition to this, vacuum core coating lets manufacturers infuse heat-sensitive omega oils and probiotic cultures after the drying stage. While freeze-dried pet food and wet pouches gain use as meal toppers, multi-dog households still rely on bulk kibble bags to control daily feeding costs through 2036.
- Dry extruded kibble and pellets account for 40.3% of product form demand in 2026, supported by low per-meal feeding cost and ambient storage convenience.
- In July 2025, canine nutritional bioavailability assays in the Journal of Animal Science confirmed that twin-screw extruded meat recipes achieved 89.0% crude protein digestibility [4].
What maintains Canines and Dogs at nearly half of target species volume?
Within target species, canines and dogs are estimated to represent 46.0% share in 2026, driven by higher daily caloric intake.
Canines generate the largest revenue share across target species because medium and large dog breeds require three to five times the daily caloric mass of an indoor cat. Owing to this metabolic requirement, households buying dog food replenish bulk kibble bags and joint-support chews on a bi-weekly schedule. Besides this, dog owners spend heavily on parasiticide prevention, harnesses, and GPS activity collars for outdoor exercise. Felines represent 39.5% of demand as urban apartment renters adopt indoor cats, yet canine dietary volume and veterinary dental care keep dog products ahead through 2036.
- Canine and dog products hold 46.0% of target species demand in 2026, driven by higher per-animal food intake and outdoor accessory replacement.
- In May 2025, the U.S. Food and Drug Administration Center for Veterinary Medicine updated animal food compliance guidelines covering mineral fortification in canine maintenance rations [5].
Why do Specialty Pet Retail Stores lead distribution channels?
Specialty pet retail stores are anticipated to capture 33.3% of distribution channel sales in 2026, underpinned by clinical diet guidance.
Specialty pet retail chains hold the leading distribution share because pet owners want in-person guidance when switching puppies, senior dogs, or allergy-prone cats onto higher-priced formulations. Superstores combine prescription nutrition aisles with on-site vaccination clinics and pet grooming salons, which brings pet parents back to the physical store every month. Supermarkets and mass merchandisers account for 30.5% of sales through weekly grocery trips, while e-commerce represents 24.2% via auto-ship subscriptions. However, cold-chain raw diets and condition-specific supplements still rely on specialty store associates to explain feeding transitions.
- Specialty pet retail stores represent 33.3% of distribution channel revenue in 2026, underpinned by in-store veterinary services and curated cold-case freezer doors.
- In October 2025, a Pet Food Institute retail survey reported that 62.0% of companion animal owners relied on specialty store staff when selecting life-stage nutrition [6].
What are the drivers, restraints, and opportunities in the pet care market?
Companion-animal humanization and preventative longevity diets sustain recurring demand, whereas animal-protein inflation and pathogen recalls constrain margins, and gently cooked fresh meals create premium subscription growth.
- Driver:Household pet humanization and preventative longevity nutrition convert discretionary treat buying into recurring clinical diet demand through 2036.
- Restraint:Wholesale meat rendering inflation and zero-tolerance Salmonella enforcement increase batch testing and cold-chain compliance costs.
- Opportunity:Gently cooked refrigerated meals and hypoallergenic insect protein rations open high-margin subscription and veterinary channels.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Companion-animal owners increasingly manage pet health through targeted daily nutrition rather than waiting for acute illness to appear. Urbanization across East Asia and Western Europe has raised indoor feline ownership, lifting demand for moisture-rich cat food pouches that reduce feline lower urinary tract stone formation. In addition to this, dog owners are purchasing glucosamine joint chews and dental sticks to avoid costly veterinary anesthesia procedures. In June 2025, clinical trials in the Journal of the American Veterinary Medical Association showed that mechanical dental kibble textures reduced canine calculus accumulation by 34.0% over twelve weeks [7]. Suppliers must document clinical feeding results before veterinary chains approve premium shelf placement.
Risk Assessment of the Pet Care Market: Operational and Formulation Friction
Volatile wholesale prices for deboned poultry, beef offal, and marine fishmeal create severe margin compression for pet food processors. When avian influenza or drought reduces livestock slaughter volumes, rendering plants raise contract prices for meat meal and animal digest. Besides this, microbiological zero-tolerance rules expose freeze-dried and wet pet food brands to costly product recalls if Listeria or Salmonella survives thermal processing. In August 2025, American Pet Products Association expenditure audits found that 41.0% of pet-owning households cited food inflation as their primary constraint when comparing super-premium brands [8]. Processors consequently face extended retailer price negotiations before passing raw material increases onto shelf tags.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Pet nutrition brands are capturing higher margins by formulating gently cooked human-grade meals and hypoallergenic alternative protein diets for dogs with chronic skin or gut sensitivities. Pre-portioned refrigerated pouches allow owners to serve visible meat and vegetable rations without handling raw meat in home kitchens. Furthermore, insect-based pet food formulated from black soldier fly larvae supplies digestible amino acids for pets intolerant to chicken or beef. In December 2025, the World Small Animal Veterinary Association Global Nutrition Committee published updated clinical protocols endorsing hydrolyzed and novel protein trials for companion animal elimination diets [9]. Suppliers need validated cold-chain fulfillment to convert trial buyers into monthly subscribers.
Pet Care Market by Country (2026 to 2036)
As per Future Market Insights, Brazil represents the fastest-growing pet care market among the six evaluated countries, at a 7.4% CAGR from 2026 to 2036, while Japan records the slowest expansion at 4.9% CAGR. Across all six covered economies, commercial growth depends on how effectively processors navigate veterinary feed inspections, manage rendered meat inflation, and expand specialty retail and subscription fulfillment.
Table 7: Country CAGR and Primary Growth Levers for the Pet Care Market (CAGR percentage and operational drivers), 2026 to 2036
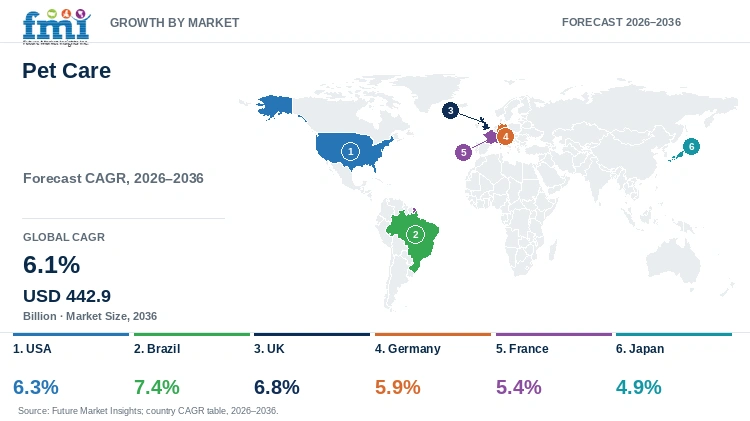
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 6.3% | High household pet penetration, veterinary wellness plans, and auto-ship e-commerce scale |
| Brazil | 7.4% | Large domestic canine population, calorie conversion from homemade scraps to kibble, and neighborhood pet shops |
| UK | 6.8% | High wet feline pouch consumption, integrated vet-grooming superstores, and raw feeding adoption |
| Germany | 5.9% | Strict animal welfare standards, certified organic bio-pet food demand, and specialty chain reach |
| France | 5.4% | High feline ownership density, veterinary pharmacy prescription diet dispensing, and gourmet wet formats |
| Japan | 4.9% | Senior indoor dog longevity care, small-breed portioned packs, and odor-control feline hygiene |
Source: Future Market Insights analysis
USA Pet Care Market Outlook (2026 to 2036)
In the United States, veterinary hospital consolidation and rising clinical procedure fees are pushing pet owners toward preventative therapeutic nutrition and daily joint and gut supplements. Valued at USD 102.9 billion in 2026, the domestic market is projected to expand at a 6.3% CAGR through 2036. In October 2025, the American Veterinary Medical Association reported that U.S. households spent an average of USD 1,515 per dog annually across veterinary care and formulated nutrition [10]. However, refrigerated fresh pet meals require expensive sub-zero supermarket end-caps that carry high slotting fees. Domestic manufacturers counter this retail barrier by combining direct-to-consumer cold-chain shipping boxes with veterinary clinic prescription auto-refill programs.
Key takeaway:In the USA, high veterinary care costs and mature auto-ship subscription logistics drive steady upgrades into therapeutic and fresh pet diets.
Brazil Pet Care Market Outlook (2026 to 2036)
Brazil is projected to record a 7.4% CAGR from 2026 to 2036, propelled by ongoing conversion from homemade table scraps to industrial extruded kibble across one of the world's largest dog populations. In February 2026, the Brazilian Pet Products Industry Association (Abinpet) reported that commercial pet food production in Brazil exceeded 4.1 million metric tons as neighborhood pet shops expanded across secondary cities [11]. Unlike North America, where big-box chains dominate, Brazilian distribution relies heavily on independent neighborhood veterinary-and-feed boutiques. Federal tax classification on premium pet treats still raises shelf prices, prompting local extruders in Sao Paulo and Parana to formulate mid-tier high-protein kibble using domestic poultry and corn.
Key takeaway:In Brazil, abundant domestic poultry and grain supplies allow local extruders to convert millions of dogs from table scraps to commercial kibble.
UK Pet Care Market Outlook (2026 to 2036)
British pet owners show a distinct preference for single-serve wet feline pouches and biologically appropriate raw dog rations, supporting a projected 6.8% CAGR through 2036. In March 2026, the UK Pet Food association reported that 60.0% of British households cared for a companion animal, with indoor cat adoption rising among urban renters [12]. Post-Brexit veterinary health certificates and border inspection fees have raised landed costs for specialty pet diets imported from continental Europe. Consequently, British retail leaders and domestic co-packers have expanded local retort pouch and raw-freezing lines in Lancashire and Yorkshire to insulate high-street shelves from customs delays.
Key takeaway:In the UK, strong demand for wet feline pouches and local raw-diet manufacturing capacity supports resilient high-street pet specialty growth.
Germany Pet Care Market Outlook (2026 to 2036)
Strict ingredient transparency and ecological packaging rules shape purchasing behavior across Germany, where the pet care market is forecast to grow at a 5.9% CAGR between 2026 and 2036. German buyers scrutinize open-declaration meat labels and favor mono-protein wet cans and certified Bio-organic kibble sold through specialty banners such as Fressnapf. In November 2025, the German Pet Trade and Industry Association (ZZF) documented that domestic specialty pet stores generated 14.0% higher spend per visit on therapeutic and organic rations than mass discount grocers [13]. Stringent Duales System packaging recycling fees penalize multi-layer plastic pouches, pushing German processors toward mono-material recyclable polypropylene trays and aluminum cans.
Key takeaway:In Germany, open-declaration meat labeling and strict recyclable packaging rules reward processors offering mono-protein cans and organic diets.
France Pet Care Market Outlook (2026 to 2036)
France maintains one of Western Europe's largest domestic feline populations, which anchors a projected 5.4% CAGR through 2036. French cat owners purchase gourmet mousses, sterilized-cat urinary control kibble, and veterinary antiparasitic collars through a mix of hypermarkets, garden centers (jardineries), and veterinary clinics. In December 2025, the French National Federation of Pet Food Manufacturers (FACCO) reported that sterilized feline diets accounted for over half of domestic cat food volume [14]. However, annual French retail price negotiations under Egalim trade laws restrict how quickly brands can pass packaging and meat cost increases to hypermarkets, encouraging manufacturers to route clinical formulas through veterinary pharmacies.
Key takeaway:In France, high sterilized-cat ownership and garden-center and veterinary pharmacy channels sustain steady demand for urinary and weight-control diets.
Japan Pet Care Market Outlook (2026 to 2036)
Japan's companion animal sector is shaped by miniature indoor dog breeds and an aging pet population living in compact apartments, resulting in a 4.9% CAGR from 2026 to 2036. Because average canine and feline lifespans in Japan exceed fifteen years, pet owners spend heavily on low-phosphorus renal purees, soft senior kibble, and odor-absorbing system cat litters. In January 2026, the Japan Pet Food Association annual survey confirmed that dogs and cats aged seven years or older represented 58.2% of the domestic companion animal population [15]. Shrinking total pet numbers limit bulk volume expansion, so Japanese manufacturers package lickable hydration treats and senior diets in high-margin single-gram sachets.
Key takeaway:In Japan, a predominantly senior indoor pet demographic shifts commercial value from bulk kibble bags toward single-serve geriatric and renal nutrition.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the pet care market?
Nestle Purina PetCare, Mars Petcare Inc., Colgate-Palmolive (Hill's Pet Nutrition), General Mills (Blue Buffalo), The J.M. Smucker Company, Spectrum Brands, Unicharm Corporation, WellPet LLC, Diamond Pet Foods, and Central Garden & Pet are significant market participants.
As per the analysis from FMI, competition in the pet care sector divides between global consumer goods conglomerates operating integrated extrusion and canning networks, clinical veterinary diet formulators, and specialty natural pet brands. Mars Petcare Inc. and Nestle Purina PetCare combine global dry kibble and retort pouch manufacturing with owned veterinary hospital groups. Colgate-Palmolive (Hill's Pet Nutrition) focuses on prescription clinical rations dispensed through veterinary clinics. General Mills (Blue Buffalo), WellPet LLC, and Diamond Pet Foods expand high-protein, grain-free, and organic pet food lines across specialty retail and e-commerce channels.
- Global Pet Nutrition Platforms: Mars Petcare Inc. and Nestle Purina PetCare operate multi-region extrusion plants, wet retort lines, and veterinary hospital networks.
- Veterinary & Clinical Diet Specialists: Colgate-Palmolive (Hill's Pet Nutrition) formulates evidence-based therapeutic diets for renal, digestive, and urinary care.
- Natural Nutrition & Hygiene Innovators: General Mills (Blue Buffalo), The J.M. Smucker Company, Spectrum Brands, Unicharm Corporation, WellPet LLC, Diamond Pet Foods, and Central Garden & Pet supply high-meat diets, dental treats, and indoor hygiene systems.
Competitive Benchmarking: Pet Care Market
Table 8: Competitive Benchmarking for the Pet Care Market (qualitative capability ratings), 2026
| Company | High-Meat & Fresh Formulation | Veterinary Clinical Validation | Omnichannel Retail Reach | Connected Care & Hygiene Depth |
|---|---|---|---|---|
| Mars Petcare Inc. | High | High | High | High |
| Nestle Purina PetCare | High | High | High | Medium |
| Colgate-Palmolive (Hill's) | Medium | High | High | Medium |
| General Mills (Blue Buffalo) | High | Medium | High | Low |
| The J.M. Smucker Company | Medium | Low | High | Low |
| Spectrum Brands | Medium | Low | High | Medium |
| Unicharm Corporation | High | Medium | High | Medium |
| WellPet LLC | High | Medium | Medium | Low |
| Diamond Pet Foods | High | Low | High | Low |
| Central Garden & Pet | Medium | Low | High | Medium |
Scoring basis: High-Meat & Fresh Formulation is High when documented product lines include gently cooked, freeze-dried, or high-protein extrusion, and Medium when focused on standard kibble or treats. Veterinary Clinical Validation is High when prescription diets and published feeding trials are core, and Medium when limited to wellness claims or pet gut health supplements. Omnichannel Retail Reach is High when distribution spans grocery, specialty chains, and e-commerce across regions. Connected Care & Hygiene Depth reflects documented hardware, litter, or diagnostic integration. Low indicates a narrower documented scope.
Key Developments in the Pet Care Market
- In February 2026, General Mills (Blue Buffalo) rolled out its fresh gently cooked refrigerated dog food line across 4,200 supermarket cooler doors in North America [16].
- In January 2026, Colgate-Palmolive (Hill's Pet Nutrition) launched a prescription feline renal diet utilizing microbiome fiber technology across 14,000 veterinary clinics [17].
- In November 2025, Nestle Purina PetCare commissioned an automated dry pet food extrusion and vacuum-coating facility in North Carolina [18].
- In September 2025, Mars Petcare completed a USD 85.0 million expansion of its automated wet pet food pouch manufacturing plant in Kansas, doubling weekly retort capacity [19].
Key Players in the Pet Care Market
Global Pet Nutrition and Veterinary Platforms
- Mars Petcare Inc.
- Nestle Purina PetCare
- Colgate-Palmolive (Hill's Pet Nutrition)
Branded Pet Food and Treat Specialists
- General Mills (Blue Buffalo)
- The J.M. Smucker Company
- WellPet LLC
- Diamond Pet Foods
Companion Animal Hygiene and Habitat Suppliers
- Spectrum Brands
- Unicharm Corporation
- Central Garden & Pet
Pet Care Market - Report Scope
Table 9: Report Scope for the Pet Care Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Form; Target Species; Distribution Channel; Dietary Nature |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from formulated pet food, treats, preventative supplements, grooming items, and companion animal hygiene products sold within the listed segmentation. Excludes bulk commercial livestock commodity feed and surgical veterinary hospital equipment. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Brazil, UK, Germany, France, Japan, and additional countries in the full report |
| Key Companies Covered | Mars Petcare Inc., Nestle Purina PetCare, Colgate-Palmolive (Hill's Pet Nutrition), General Mills (Blue Buffalo), The J.M. Smucker Company, Spectrum Brands, Unicharm Corporation, WellPet LLC, Diamond Pet Foods, Central Garden & Pet |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Pet Care Market - Research Methodology
Table 10: Research Methodology for the Pet Care Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with pet food extrusion engineers, veterinary nutritionists, specialty retail category buyers, and animal health executives across the value chain to validate formulation trends, digestibility protocols, demand dynamics, and purchasing decisions. |
| Secondary Research | Secondary research included company annual reports, investor presentations, AAFCO and FEDIAF regulatory publications, veterinary association surveys, technical journals, product literature, and publicly available sources relevant to the market. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up approaches to assess companion animal caloric demand, price tiers, and omnichannel retail adoption. |
| Data Triangulation and Validation | Data is validated against companion animal ownership registries, veterinary clinic throughput, regulatory feed compliance standards, and historical trend analysis to ensure accuracy without double counting adjacent categories. |
Pet Care Market by Segments
Pet Care Market segmented by Product Form:
- Dry Extruded Kibble & Pellets
- Wet Canned Food & Pouches
- Freeze-Dried & Raw Specialty
- Treats & Supplemental Snacks
Pet Care Market segmented by Target Species:
- Canine / Dogs
- Feline / Cats
- Livestock & Aquaculture
Pet Care Market segmented by Distribution Channel:
- Specialty Pet Retail Stores
- Supermarkets & Mass Merchandisers
- Online E-Commerce
- Veterinary Clinics & Farm Ag-Stores
Pet Care Market segmented by Dietary Nature:
- Conventional Complete Diet
- Organic, Grain-Free & Clean-Label
Pet Care Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] American Pet Products Association. (2025, January 18). Companion animal ownership and global household feeding survey. APPA Industry Performance Reports.
- [2] Association of American Feed Control Officials. (2025, February 14). Official publication: Model bill and updated pet food ingredient definitions. AAFCO Regulatory Standards.
- [3] European Pet Food Industry Federation. (2025, March 20). Nutritional guidelines for complete and complementary pet food for cats and dogs. FEDIAF Scientific Publications.
- [4] Kerr, K. R., & Swanson, K. S. (2025, July 15). Nutritional digestibility and amino acid bioavailability of twin-screw extruded pet foods. Journal of Animal Science, 103(7), 214-226.
- [5] U.S. Food and Drug Administration. (2025, May 12). Current good manufacturing practice and labeling requirements for animal food. FDA Center for Veterinary Medicine Guidance.
- [6] Pet Food Institute. (2025, October 09). Consumer purchasing behavior and life-stage nutrition selection in specialty pet retail. PFI Market Audits.
- [7] Gorrel, C., & Rawlings, J. M. (2025, June 19). Dietary kibble textures and mechanical dental calculus control in domestic canines. Journal of the American Veterinary Medical Association, 266(6), 412-420.
- [8] American Pet Products Association. (2025, August 22). Annual consumer spending and inflation sensitivity audit in companion animal nutrition. APPA Economic Bulletins.
- [9] World Small Animal Veterinary Association. (2025, December 11). Global nutrition committee clinical guidelines for companion animal elimination diets. WSAVA Global Nutrition Guidelines.
- [10] American Veterinary Medical Association. (2025, October 15). Evolving pet owner economics and companion animal demographic sourcebook. AVMA Veterinary Economics Reports.
- [11] Brazilian Pet Products Industry Association. (2026, February 10). Brazilian pet food tonnage and specialty retail channel audit. Abinpet Sector Bulletins.
- [12] UK Pet Food. (2026, March 14). Pet population data and companion animal dietary format review. UK Pet Food Annual Statistical Reports.
- [13] Zentralverband Zoologischer Fachbetriebe Deutschlands. (2025, November 18). German pet trade and therapeutic nutrition channel performance. ZZF Industry Yearbook.
- [14] Federation des Fabricants d'Aliments pour Chiens, Chats, Oiseaux et Autres Animaux Familiers. (2025, December 05). French companion animal demographics and sterilized feline diet survey. FACCO Market Reviews.
- [15] Japan Pet Food Association. (2026, January 21). National survey on dog and cat ownership, longevity, and senior diet expenditure. JPFA Statistical Releases.
- [16] General Mills, Inc. (2026, February 12). Blue Buffalo division commercial rollout of fresh gently cooked refrigerated dog food. General Mills Corporate Newsroom.
- [17] Colgate-Palmolive Company. (2026, January 19). Hill's Pet Nutrition launches clinical microbiome renal diet across veterinary hospitals. Colgate-Palmolive Investor Releases.
- [18] Nestle Purina PetCare. (2025, November 14). Commissioning of automated dry pet food extrusion and vacuum-coating plant in North Carolina. Purina Corporate Announcements.
- [19] Mars Petcare Inc. (2025, September 25). Completion of USD 85.0 million automated wet pet food pouch expansion in Kansas. Mars Petcare Press Releases.
- [20] The J.M. Smucker Company. (2026, March 09). Completion of USD 55.0 million automation expansion for canine dental chew manufacturing. Smucker Corporate Releases.
- [21] Spectrum Brands Holdings, Inc. (2026, January 27). Commercial launch of enzymatic canine dental care and waterless grooming lines. Spectrum Brands Pet Care News.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the pet care market in 2026 and what is forecast for 2036?
- Which companion animal health and feeding pressures support demand for formulated pet care?
- Why do Dry Extruded Kibble & Pellets lead the product form category?
- Why do Canines and Dogs account for the largest share by target species globally?
- How do growth rates differ across Brazil, the UK, the USA, Germany, France, and Japan?
- Which leading companies supply formulated pet foods, clinical diets, and hygiene products today?
- What limits adoption or margin expansion in the global pet care market?
- What should retail and veterinary buyers evaluate before qualifying a pet care supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Form, 2026 to 2036
- Dry Extruded Kibble & Pellets
- Wet Canned Food & Pouches
- Freeze-Dried & Raw Specialty
- Treats & Supplemental Snacks
- Y-o-Y Growth Trend Analysis By Product Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form, 2026 to 2036
- Global Market Analysis and Forecast, By Target Species, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Target Species, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Target Species, 2026 to 2036
- Canine / Dogs
- Feline / Cats
- Livestock & Aquaculture
- Y-o-Y Growth Trend Analysis By Target Species, 2021 to 2025
- Absolute $ Opportunity Analysis By Target Species, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Specialty Pet Retail Stores
- Supermarkets & Mass Merchandisers
- Online E-Commerce
- Veterinary Clinics & Farm Ag-Stores
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Dietary Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Dietary Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Dietary Nature, 2026 to 2036
- Conventional Complete Diet
- Organic, Grain-Free & Clean-Label
- Y-o-Y Growth Trend Analysis By Dietary Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Dietary Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Form
- By Target Species
- By Distribution Channel
- By Dietary Nature
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Mars Petcare Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nestle Purina PetCare
- Colgate-Palmolive (Hill's)
- General Mills (Blue Buffalo)
- The J.M. Smucker Company
- Spectrum Brands
- Unicharm Corporation
- WellPet LLC
- Diamond Pet Foods
- Central Garden & Pet
- Colgate-Palmolive (Hill's Pet Nutrition)
- Mars Petcare Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Target Species, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Target Species, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Target Species, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Target Species, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Target Species, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Target Species, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Target Species, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Target Species, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Dietary Nature, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Form
- Figure 6: Global Market Value Share and BPS Analysis by Target Species, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Target Species, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Target Species
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Dietary Nature
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Product Form
- Figure 29: North America Market Value Share and BPS Analysis by Target Species, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Target Species, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Target Species
- Figure 32: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Distribution Channel
- Figure 35: North America Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Dietary Nature
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Product Form
- Figure 42: Latin America Market Value Share and BPS Analysis by Target Species, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Target Species, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Target Species
- Figure 45: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 48: Latin America Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Dietary Nature
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Product Form
- Figure 55: Western Europe Market Value Share and BPS Analysis by Target Species, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Target Species, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Target Species
- Figure 58: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 61: Western Europe Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Dietary Nature
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Product Form
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Target Species, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Target Species, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Target Species
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Dietary Nature
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Product Form
- Figure 81: East Asia Market Value Share and BPS Analysis by Target Species, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Target Species, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Target Species
- Figure 84: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 87: East Asia Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Dietary Nature
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Product Form
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Target Species, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Target Species, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Target Species
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Dietary Nature
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Product Form
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Target Species, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Target Species, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Target Species
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Dietary Nature, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Dietary Nature, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Dietary Nature
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the pet care market in 2026, and what is forecast for 2036?
The global pet care market is estimated to reach USD 245.0 billion in 2026. Industry revenue is projected to reach USD 442.9 billion by 2036, supported by household pet humanization and preventative veterinary nutrition.
What is the CAGR for the pet care market from 2026 to 2036?
As per FMI, the pet care market is projected to expand at a 6.1% CAGR from 2026 to 2036. Growth is supported by recurring spending on high-protein kibble, wet feline pouches, and daily dental and joint supplements.
Which product form segment leads the pet care market in 2026?
Dry extruded kibble and pellets are projected to hold 40.3% of product form demand in 2026. The segment benefits from low per-serving cost, long ambient pantry stability, and mechanical tartar-scraping action during chewing.
Which target species segment holds the largest share in 2026?
Canines and dogs are estimated to account for 46.0% of target species revenue in 2026. Demand is underpinned by larger daily caloric maintenance needs per dog and higher spending on outdoor accessories and parasiticides.
Which country has a notable growth outlook during the assessment period?
FMI finds that Brazil is projected to register a 7.4% CAGR between 2026 and 2036. Expansion is supported by a large domestic dog population and ongoing conversion from homemade food to commercial extruded kibble.
Who are the key players active in the pet care market?
Notable participants include Mars Petcare Inc., Nestle Purina PetCare, Colgate-Palmolive (Hill's Pet Nutrition), General Mills (Blue Buffalo), The J.M. Smucker Company, Spectrum Brands, Unicharm Corporation, WellPet LLC, Diamond Pet Foods, and Central Garden & Pet. These suppliers focus on twin-screw extrusion, retort pouch sterilization, and clinical microbiome formulations.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
