

- Market Size (2026)
- USD 13.2 Bn
- Forecast (2036)
- USD 58.9 Bn
- CAGR (2026 to 2036)
- 16.1%
How big is Pet Insurance Market in 2026?
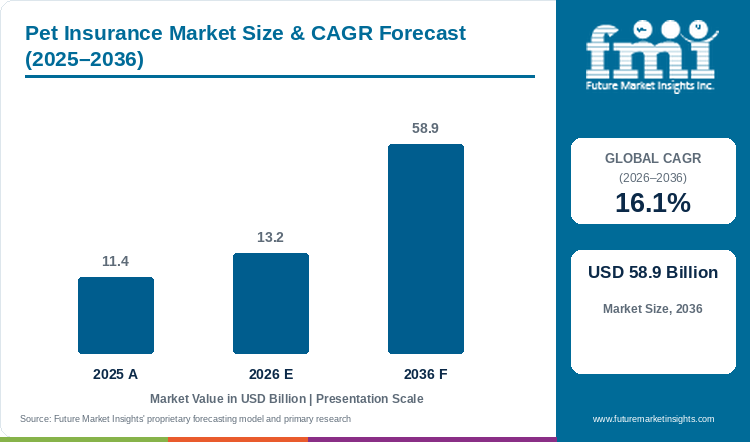
The pet insurance market is estimated at USD 11.4 billion in 2025 and is anticipated to reach USD 13.2 billion in 2026 and USD 58.9 billion by 2036, at a 16.1% CAGR.
Pet insurance premiums are estimated at USD 11.4 billion in 2025 and are projected to reach USD 13.2 billion in 2026. Sales are forecast to grow at a 16.1% CAGR and reach USD 58.9 billion by 2036. Owners are buying fuller cover for each animal, so premium grows faster than the insured pet count. Lemonade's pet in-force premium reached USD 543 million at June 2026, against USD 350 million at June 2025, and premium per pet customer rose to USD 839 from USD 752.[1] Households are swapping a surprise surgery bill for a larger monthly payment, which keeps accident and illness plans at 63.7% of 2026 policy sales.
Pet insurance in the United States is on a 16.6% CAGR path through 2036, ahead of 12.9% for the United Kingdom. NAPHIA counted 7.6 million insured pets across North America at the end of 2025, against 88.0 million dogs and 66.0 million cats kept in US homes in 2024.[2][3] Most US pets still have no policy, so app-based and direct insurers are signing first-time owners from a large uninsured base. Many dog and cat owners in the United Kingdom already hold cover, so British premium gains rest on renewals and on vet price rules that let insurers price claims against published lists.
Key Market Trends & Insights
- In policy type, accident and illness plans will lead with 63.7% share in 2026, against 22.5% for accident-only cover.
- Lifetime cover is predicted to lead coverage type with 41.5% share in 2026, and annual non-lifetime plans should follow at about 33.0%.
- Insurers selling direct are forecast to lead channel sales with 38.0% share in 2026, with online platforms near 27.5%. Lemonade reported about $85 million of pet in-force premium from cross-sales to existing customers at March 2026.[4]
- Dogs are likely to hold 55.4% of 2026 demand and cats 32.1%, and horses, exotic pets and other animals share the rest.
Regional Highlights
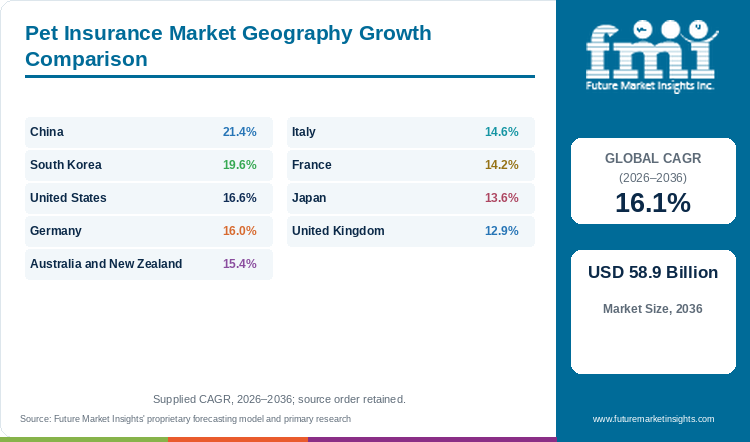
- Owners in China drive the fastest profiled growth, with sales of pet insurance forecast to grow at a 21.4% CAGR from 2026 to 2036, and South Korea follows at 19.6%.
- The United States grows close to the 16.1% global CAGR at 16.6%, and Germany (16.0%), Australia and New Zealand (15.4%), Italy (14.6%), France (14.2%) and Japan (13.6%) grow below the global rate, with the United Kingdom lowest at 12.9%.
- The UK competition regulator published the Veterinary Services Market Investigation Order in September 2026, with prescription fee caps of £21.40 for the first medicine.[5]
Market Size & Forecast
Table 1: Market Size and Forecast for the Pet Insurance Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 11.4 billion |
| Estimated Market Size in 2026 | USD 13.2 billion |
| Projected Market Size by 2036 | USD 58.9 billion |
| CAGR, 2026 to 2036 | 16.1% |
| Added Revenue, 2026 to 2036 | USD 45.7 billion |
| Market Expansion Multiple | 4.5x |
Most pet policies run for twelve months and reprice at each anniversary, which ties sales growth to renewal pricing as much as to new owners. Pet in-force premium at Lemonade reached $543 million at June 2026, up from $350 million a year earlier, and premium per pet customer rose to $839 from $752.[1] Insurers will keep raising renewal prices through 2027 as claim costs rise with each new diagnostic test. Owners who buy grooming services also budget for routine pet care, and the pet grooming market is expected to grow at a 9.1% CAGR from 2026 to 2036. FMI estimates the added size at USD 45.7 billion between 2026 and 2036, a 4.5x expansion of the 2026 base. Claims inflation is the main risk, and Lemonade's pet gross loss ratio rose to 74% in the quarter to June 2026 from 70% in the second quarter of 2025.[1]
Vet Price Rules and Claims Costs
UK vet groups now face rules on how prices are shown to pet owners. The CMA investigated veterinary services from September 2023 to March 2026 and published an Order in September 2026.[5] Large groups with 15 or more first opinion practices have three months to publish standard price lists and nine months to give written estimates for treatment likely to cost £500 or more.[6] Insurers will use the published price lists to set UK premiums by region and treatment, and owners will see the cost of a claim before treatment starts.
UK pet retailers are moving into insurance alongside the new vet price rules, FMI's research indicates. With 455 vet practices, Pets at Home reported an underlying loss of £5.2 million in the insurance business for the year to March 2026, from start-up investment in team and technology.[7] Launching and scaling a differentiated insurance proposition is named as a strategic priority in the same report.[7] UK owners will be offered cover at the vet counter and in store, which adds a new channel beside comparison sites.
Table 2: Claims, Pricing and Rule Indicators for the Pet Insurance Market (counts, ratios and dates), 2025 to 2028
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| North American insured pets, end of 2025 | 7.6 million, up 8.5% | Core buyer base. | [2] |
| Gross written premium growth in North America, 2025 | 19.4% | Premium growth ahead of pet count. | [2] |
| US dogs and cats owned, 2024 | 88.0 million dogs and 66.0 million cats | Room for new policies. | [3] |
| Lemonade pet gross loss ratio, quarter to June 2026 | 74%, against 70% in the second quarter of 2025 | Claim costs rising. | [1] |
| Lemonade premium per pet customer, June 2026 | $839, against $752 | Owners paying more per policy. | [1] |
| UK prescription fee cap | £21.40 first medicine, £12.70 each additional, to 31 March 2028 | Lower drug cost per claim. | [5] |
| UK written estimate threshold | £500 or more including VAT | Owners see claim size before treatment. | [6] |
| Pets at Home insurance business, year to March 2026 | £5.2 million underlying loss | New retail insurer in the UK. | [7] |
Analyst Perspective
“My product bet is accident and illness cover priced separately for cats, with lower premiums and a higher annual limit for chronic kidney and thyroid care. Cat owners still insure far less often than dog owners, and a plan built around feline claims will convert them. I expect this cat-first plan to outsell bundled wellness add-ons by 2030.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the pet insurance market segmented?
Policy type, coverage type, sales channel and end user break the market down, and region adds a fifth view. Accident and illness plans, lifetime cover, direct insurers and dogs are expected to lead the four axes in 2026.
By policy type: accident-only, accident and illness, wellness and routine care, and others.
By coverage type: lifetime coverage, non-lifetime coverage, time-limited coverage, and condition-based coverage.
By sales channel: insurance companies, brokers and agents, online platforms, veterinary clinics, and others.
By end user: dogs, cats, horse, exotic pets, and others.
By region: East Asia, Eastern Europe, North America, Latin America, Western Europe, South Asia and Pacific, and Middle East and Africa.
Why do accident and illness plans lead sales of pet insurance by policy type?
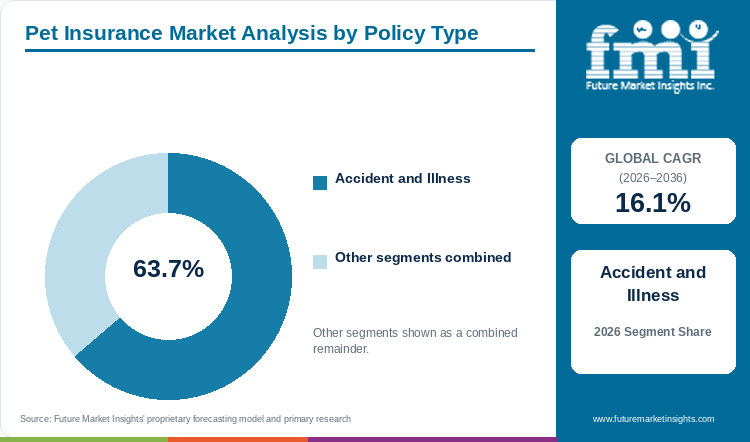
Of 2026 policy sales, accident and illness plans are estimated at 63.7%, ahead of accident-only cover at 22.5%.
Table 3: Policy Type Share for the Pet Insurance Market (percentage share), 2026
| Policy Type | Estimated Share (2026) |
|---|---|
| Accident and Illness | 63.7% |
| Accident-Only | 22.5% |
| Wellness and Routine Care | 10.6% |
| Others | 3.2% |
| Total | 100.0% |
Table 4: Policy Type Leadership and Market Growth for the Pet Insurance Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 16.1% |
| Leading Segment | Accident and Illness |
Accident and illness plans are expected to lead with 63.7% share in 2026, since illness claims for cancer, skin allergies and kidney disease cost more than most injuries and owners buy plans that cover both. Accident-only cover, at 22.5%, is cheaper but leaves the owner paying for the chronic conditions that drive most vet bills. Wellness and routine care plans should hold 10.6%, since vaccines and check-ups cost little and many owners prefer to pay those bills directly. Other products, about 3.2% in 2026, include breed-specific and senior-pet riders. Written estimates for UK treatment of £500 or more will show owners the size of an illness bill before treatment starts.[6]
- Accident and illness buyers include first-time puppy and kitten owners and owners of purebred dogs with known hereditary risks.
- The CMA's September 2026 guidance requires UK vets to give written estimates for treatment of £500 or more.[6]
Why does lifetime cover lead sales of pet insurance by coverage type?
Coverage sales in 2026 are projected to favour lifetime cover at 41.5%, ahead of non-lifetime plans at about 33.0%.
Table 5: Coverage Type Share for the Pet Insurance Market (percentage share), 2026
| Coverage Type | Estimated Share (2026) |
|---|---|
| Lifetime Coverage | 41.5% |
| Non-Lifetime Coverage | 33.0% |
| Time-Limited Coverage | 17.0% |
| Condition-Based Coverage | 8.5% |
| Total | 100.0% |
Lifetime cover is projected to lead with 41.5% share in 2026, because owners of pets with long-term conditions want the policy to keep paying every year. Non-lifetime annual plans, at about 33.0%, cost less but reset the limit each year and can exclude a condition after renewal. Time-limited cover, near 17.0%, pays for each condition for only 12 months and suits owners on tight budgets. Condition-based plans will hold roughly 8.5%, sold mainly for older pets that other plans exclude.
- Most lifetime buyers own pets with allergies or kidney disease.
- The CMA Order published in September 2026 caps UK prescription fees at £21.40 for the first medicine, a cost that recurs for chronic cases.[5]
Why do insurers selling direct lead sales of pet insurance by channel?
Insurance companies selling direct should hold 38.0% of 2026 channel sales, with online platforms second at about 27.5%.
Table 6: Sales Channel Share for the Pet Insurance Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| Insurance Companies | 38.0% |
| Online Platforms | 27.5% |
| Brokers and Agents | 17.5% |
| Veterinary Clinics | 12.0% |
| Others | 5.0% |
| Total | 100.0% |
Insurance companies selling direct are estimated to lead with 38.0% share in 2026, as pet owners searching for cover usually land on an insurer's own website or app. Online comparison and marketplace platforms, at about 27.5%, attract price-led buyers but pay commission on each policy. Brokers and agents are anticipated to hold 17.5%, mostly through employee benefit schemes in the USA. Veterinary clinics, at roughly 12.0%, sell at the moment of diagnosis, limited by vets who keep clinical advice apart from insurance sales. Other channels, about 5.0%, include breeders and pet stores selling dog food and accessories. Lemonade reported record-low LAE ratios in pet during the quarter to June 2026.[1] App-led direct insurers will use that cost edge to undercut broker-sold plans. Owners who buy GPS collars and pet cameras already manage pets through apps, and the pet gadgets market is forecast to grow at a 15.1% CAGR from 2026 to 2036, so app-based insurers will reach more of those owners.
- Direct sellers include specialist pet insurers, general insurers with pet lines and app-based insurers.
- Lemonade's February 2026 shareholder letter names pet as the largest line by in-force premium.[8]
Why do dogs lead sales of pet insurance by end user?
In end user, dogs are likely to account for 55.4% of 2026 demand, ahead of cats at 32.1%.
Table 7: End User Share for the Pet Insurance Market (percentage share), 2026
| End User | Estimated Share (2026) |
|---|---|
| Dogs | 55.4% |
| Cats | 32.1% |
| Horse | 6.5% |
| Exotic Pets | 4.0% |
| Others | 2.0% |
| Total | 100.0% |
Dogs will lead with 55.4% share in 2026, as dogs visit the vet more often than cats and suffer more joint and soft-tissue injuries. Cats, at 32.1%, are kept indoors more and see a vet less, so owners delay buying cover until a cat is older. Horses are near 6.5%, with high-value mortality and surgical cover bought mostly by sport and breeding owners. Exotic pets, about 4.0%, and other animals, near 2.0%, are limited by the small number of insurers that will price birds, reptiles and rabbits. NAPHIA counts 88.0 million dogs and 66.0 million cats owned in the United States in 2024.[3] Cat owners also buy specialist diets, and the cat food market is expected to grow at a 4.8% CAGR from 2026 to 2036, which keeps cat owners in regular contact with pet stores that can sell cover.
- Dog policies split into puppy plans, adult accident and illness plans and senior dog cover.
- NAPHIA's June 2026 State of the Industry Report counts 88.0 million dogs and 66.0 million cats in US homes in 2024.[3]
What are the drivers, restraints, and opportunities in the pet insurance market?
More owners are buying richer plans for dogs and cats. Rising claim costs squeeze insurer margins, and vet price rules in the UK open a new route for retail and vet-counter sales.
- Driver: Owners facing larger vet bills for chronic and surgical care are choosing plans with higher limits and lower deductibles, so premium per insured pet grows faster than the number of pets covered.
- Restraint: Vet treatment costs are rising faster than renewal prices, which squeezes underwriting margins and pushes some price-sensitive owners down to accident-only cover.
- Opportunity: Published vet price lists in the United Kingdom let insurers match policy prices to known treatment costs and offer cover at the vet counter alongside each estimate.
Richer Plans Raise Premium per Pet
Owners now treat cover as protection against large surgical bills, so insurers sell richer plans and premium per pet keeps rising. Pet in-force premium at Lemonade rose to $439 million at the end of 2025 from $283 million a year earlier, and pet became the company's largest line.[8] By March 2026 the figure reached $490 million, and premium per pet customer was $822.[4] Insurers will keep adding higher limits and lower deductibles because owners are willing to pay more per policy.
Claims Inflation Squeezes Insurer Margins
Rising claim costs are squeezing underwriting margins at US pet insurers such as Lemonade. Lemonade's pet gross loss ratio moved from 68% in the first quarter of 2025 to 69% in the first quarter of 2026 and 74% in the second quarter.[4][1] Insurers will file larger renewal increases in 2027, and some owners will drop to accident-only cover.
Vet Price Transparency Opens New Sales in the United Kingdom
Demand for pet insurance in the UK is opening at the vet counter as price rules take hold. Large vet groups are required to provide written estimates and itemised bills by June 2027 and supply comparison data to the RCVS within 12 months.[6] The RCVS will use the data to build an enhanced Find a Vet website.[6] Insurers will tie policy prices to published vet prices and sell cover alongside the estimate.
Which country CAGRs are profiled in the pet insurance market?
Table 8: Country CAGR Comparison for the Pet Insurance Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 21.4% |
| South Korea | 19.6% |
| United States | 16.6% |
| Germany | 16.0% |
| Australia and New Zealand | 15.4% |
| Italy | 14.6% |
| France | 14.2% |
| Japan | 13.6% |
| United Kingdom | 12.9% |
How do country-level CAGRs compare in the pet insurance market?
Prescription fee caps of £21.40 for the first medicine and £12.70 for each additional medicine now bind UK vet groups until 31 March 2028.[5] FMI estimates China's CAGR from 2026 to 2036 at 21.4% and South Korea's at 19.6%, both above the 16.1% global CAGR, as first-time buyers in both countries start from a small insured base. The United States, the largest profiled premium base, is close to the global rate at 16.6%, and Germany follows at 16.0%. Australia and New Zealand (15.4%), Italy (14.6%), France (14.2%) and Japan (13.6%) grow below the global rate, and the United Kingdom will grow at the lowest profiled CAGR, 12.9%, since many UK dog and cat owners already hold cover. Levers range from first-time urban buyers in China and app sales in the United States to vet price rules in the United Kingdom and employer cover in Germany.
- Chinese city owners will buy first policies for small dogs and cats through super-apps.
- US insurers sell through apps, employers and comparison sites.
- Owners in Australia and New Zealand will find cover through supermarket and bank brands as well as insurers.
- German dog owners with liability cover will add surgical plans.
- Owners in the United Kingdom will see vet prices published under the CMA Order.
- South Korean insurers will add pet riders to household policies.
- Japanese owners will favour plans that pay the clinic directly at the counter.
- French owners will buy surgery and illness cover through banks and mutuals.
- Italian insurers will sell pet cover as an add-on to home policies.
Full report country CAGRs cover: nine profiled countries, with China, Japan and South Korea within East Asia, the United States within North America, Australia and New Zealand within South Asia and Pacific, Germany, the United Kingdom, France and Italy within Western Europe, and regional tables for Latin America, Eastern Europe, and Middle East and Africa.
Country-wise Analysis
China Pet Insurance Market Outlook (2026 to 2036)
As per FMI's analysis, sales of pet insurance in China will grow at a 21.4% CAGR from 2026 to 2036, the highest profiled rate and 5.3 points above the global CAGR. Chinese owners in large cities keep small dogs and cats in apartments and will buy first policies through payment and shopping apps. The pet food market is anticipated to grow at a 6.5% CAGR from 2026 to 2036, and owners trading up to premium food will be the first to add illness cover.
Key takeaway: China is a first-purchase market, and low entry premiums will decide which insurers gain scale.
United States Pet Insurance Market Outlook (2026 to 2036)
NAPHIA reports 7.6 million insured pets in North America at the end of 2025, against 88.0 million dogs and 66.0 million cats owned in the United States in 2024.[2][3] Lemonade, an app-based insurer, grew pet in-force premium to $543 million by June 2026.[1] The updated report by FMI finds that sales in the United States will grow at a 16.6% CAGR from 2026 to 2036, close to the 16.1% global rate. US insurers will compete on app claims and employer benefit schemes.
Key takeaway: The uninsured US pet population is large, and digital sign-up will turn more owners into buyers.
Australia and New Zealand Pet Insurance Market Outlook (2026 to 2036)
Ranked fifth among the nine profiled countries, Australia and New Zealand are likely to see sales of pet insurance grow at a 15.4% CAGR from 2026 to 2036, below the 16.1% global rate. Supermarket and bank brands will widen the reach of white-label pet cover in Australia, and online sales will bring most new policies in New Zealand.
Key takeaway: Brand reach matters more than product range in Australia, and trans-Tasman insurers will serve New Zealand from Australian platforms.
Germany Pet Insurance Market Outlook (2026 to 2036)
FMI's 16.0% CAGR for Germany from 2026 to 2036 places the country fourth among the nine profiled countries, just under the global rate. Germany is one of the European markets named by Lemonade, together with the UK, the Netherlands and France.[4] German dog owners often hold liability cover, and insurers will cross-sell surgical and illness plans to the same households.
Key takeaway: Liability cover gives German insurers a ready base for illness plans.
United Kingdom Pet Insurance Market Outlook (2026 to 2036)
The CMA Order requires large vet groups to publish standard price lists within three months and to cap prescription fees.[6][5] Pets at Home grew Vet Group consumer revenue 5.0% to £688.1 million in the year to March 2026 and is building an insurance business.[7] According to FMI, sales in the United Kingdom will grow at a 12.9% CAGR from 2026 to 2036, the lowest profiled rate, because the UK already insures a large share of dogs and cats.
Key takeaway: Published vet prices will let UK insurers and retailers price claims more tightly.
South Korea Pet Insurance Market Outlook (2026 to 2036)
FMI expects pet insurance sales in South Korea to grow at a 19.6% CAGR from 2026 to 2036, second among the profiled countries. Insurers will add pet riders to household and car policies as more Korean households keep dogs.
Key takeaway: Bundled riders will drive demand in South Korea.
Japan Pet Insurance Market Outlook (2026 to 2036)
Japanese pet insurance sales are projected to grow at a 13.6% CAGR from 2026 to 2036, below the global rate. Japanese owners will favour plans that settle the bill directly at the clinic counter, and insurers with large clinic networks will gain. An ageing dog population will raise claims for chronic disease.
Key takeaway: Direct clinic settlement shapes Japanese buyer choice.
France Pet Insurance Market Outlook (2026 to 2036)
Demand in France is predicted to grow at a 14.2% CAGR from 2026 to 2036. France is one of the European markets named by Lemonade.[4] Banks and mutual insurers will offer pet cover to existing customers.
Key takeaway: Bank and mutual distribution will drive sales in France.
Italy Pet Insurance Market Outlook (2026 to 2036)
The Italian CAGR from 2026 to 2036 is 14.6%, under the 16.1% global rate. Home insurers will sell pet cover as an add-on, and stand-alone illness plans will grow slowly.
Key takeaway: Home insurers adding pet riders will drive growth in Italy.
Who are the notable companies in the pet insurance market?
Trupanion, Nationwide Pet Insurance, Embrace, Healthy Paws, ASPCA Pet Health Insurance, Figo, Lemonade and Pumpkin are the profiled companies, and Pets at Home is entering UK pet insurance.
Specialist insurers such as Trupanion and Embrace build products around vet direct payment and illness cover, and Lemonade sells pet cover inside an app alongside home and renters policies. Competitive pressure is reshaping the market around claims handling, and Lemonade reported record-low LAE ratios in pet during the quarter to June 2026.[1] Pets at Home will sell cover through 455 vet practices in the UK.[7]
- Specialist pet insurers: Trupanion, Embrace, Healthy Paws, Figo, and Pumpkin.
- Multi-line and app-based insurers: Nationwide Pet Insurance, ASPCA Pet Health Insurance, and Lemonade.
- Retail and vet group entrant: Pets at Home.
Competitive Benchmarking: Pet Insurance Market
Table 9: Competitive Benchmarking for the Pet Insurance Market (qualitative documentation ratings), 2026
| Company | Accident and Illness Range | Digital Sales | Vet Channel | Recency |
|---|---|---|---|---|
| Lemonade | Medium | High | Low | High |
| Trupanion | High | Medium | High | Low |
| Nationwide Pet Insurance | High | Medium | Low | Low |
| Embrace | High | High | Low | Low |
| Healthy Paws | High | High | Low | Low |
| Pets at Home | Low | Medium | High | High |
Pet insurers rated High show wider coverage in dated company and regulator documents, and the table makes no market-share claim.
Key Developments in the Pet Insurance Market
- In October 2026, the CMA published guidance for large veterinary businesses on complying with the Order.[5]
- In September 2026, the CMA updated vet guidance with the Veterinary Services Market Investigation Order 2026.[6]
- In July 2026, Lemonade reported pet in-force premium of $543 million for the second quarter.[1]
- In June 2026, NAPHIA reported 7.6 million insured pets in North America at the end of 2025.[2]
- In May 2026, Pets at Home signed the annual report showing start-up investment in the insurance business.[7]
- In April 2026, Lemonade reported pet in-force premium of $490 million for the first quarter.[4]
- In February 2026, Lemonade reported pet as the company's largest line by in-force premium.[8]
- In 2024, the AVMA counted 88.0 million dogs and 66.0 million cats in US homes, as cited by NAPHIA.[3]
Key Players in the Pet Insurance Market
Specialist Pet Insurers
- Trupanion
- Embrace
- Healthy Paws
- Figo
- Pumpkin
Multi-line and App-based Insurers
- Nationwide Pet Insurance
- ASPCA Pet Health Insurance
- Lemonade
Retail and Vet Group Entrant
- Pets at Home
Pet Insurance Market - Report Scope
Table 10: Report Scope for the Pet Insurance Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Policy type; coverage type; sales channel; end user; region |
| Quantitative units | USD billion |
| Market definition | Insurance policies that pay for veterinary treatment, accidents, illness and routine care for dogs, cats, horses and other companion animals. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Trupanion, Nationwide Pet Insurance, Embrace, Healthy Paws, ASPCA Pet Health Insurance, Figo, Lemonade, Pumpkin, Pets at Home |
| Forecast period | 2026 to 2036 |
Pet Insurance Market - Research Methodology
Table 11: Research Methodology for the Pet Insurance Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Insurer results, trade body statistics, competition regulator guidance and pet retailer reports from May 2025 onward. |
| Desk Research | Coverage of insured pet counts, premium growth, loss ratios, vet price rules and new insurance entrants. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 11.4 billion and the 16.1% CAGR from 2026 to 2036. |
| Data Validation | Loss ratios, fee caps and dates were matched to the insurer and CMA documents. |
Pet Insurance Market by Segments
Pet Insurance Market segmented by Policy Type:
- Accident-Only
- Accident and Illness
- Wellness and Routine Care
- Others
Pet Insurance Market segmented by Coverage Type:
- Lifetime Coverage
- Non-Lifetime Coverage
- Time-Limited Coverage
- Condition-Based Coverage
Pet Insurance Market segmented by Sales Channel:
- Insurance Companies
- Brokers and Agents
- Online Platforms
- Veterinary Clinics
- Others
Pet Insurance Market segmented by End User:
- Dogs
- Cats
- Horse
- Exotic Pets
- Others
Pet Insurance Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Lemonade, Inc. (2026, July 29). Q2 2026 Shareholder Letter. https://www.lemonade.com/investor-relations-bo/wp-content/uploads/docs/LMND-Shareholder-Letter-Q2-2026.pdf
- [2] North American Pet Health Insurance Association. (2026, June). State of the Industry Report 2026: Industry Data. https://naphia.org/industry-data/
- [3] North American Pet Health Insurance Association. (2026, June). State of the Industry Report 2026: Section 4, Penetration Rates. https://naphia.org/industry-data/section-4-penetration-rates/
- [4] Lemonade, Inc. (2026, April 29). Q1 2026 Shareholder Letter. https://www.lemonade.com/investor-relations-bo/wp-content/uploads/docs/LMND-Shareholder-Letter-Q1-2026.pdf
- [5] Competition and Markets Authority. (2026, October 13). Large veterinary businesses: complying with the CMA's Order. https://www.gov.uk/guidance/large-veterinary-businesses-complying-with-the-cmas-order
- [6] Competition and Markets Authority. (2026, September 22). What veterinary businesses and vets need to do following the CMA's final vets report. https://www.gov.uk/guidance/what-veterinary-businesses-and-vets-need-to-do-following-the-cmas-final-vets-report
- [7] Pets at Home Group plc. (2026, May 27). Annual Report and Financial Statements 2026. https://www.petsathomeplc.com/media/mcbjxmv1/pets-at-home-ar26-final-signed.pdf
- [8] Lemonade, Inc. (2026, February 19). Q4 2025 Shareholder Letter. https://www.lemonade.com/investor-relations-bo/wp-content/uploads/docs/LMND-Shareholder-Letter-Q4-25.pdf
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the pet insurance market during 2026?
- What market size is projected by 2036?
- Which policy type holds notable share?
- Which coverage type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the pet insurance market expected in 2026?
Pet owners will pay an estimated USD 13.2 billion for pet insurance in 2026, up from USD 11.4 billion in 2025. FMI projects USD 58.9 billion by 2036.
What CAGR is projected for the pet insurance market through 2036?
Premiums are forecast to grow at a 16.1% CAGR from 2026 to 2036. Illness costs for conditions such as cancer and kidney disease drive owners toward cover.
Which policy type holds a notable market share in 2026?
Accident and illness plans should lead with 63.7% share in 2026. Accident-only cover will hold 22.5%.
Which coverage type holds a notable market share in 2026?
Lifetime cover is likely to lead with 41.5% share in 2026. Annual non-lifetime plans are likely to follow at about 33.0%.
Which country has a notable expansion outlook through 2036?
Insurers in China lead the profiled table, with sales of pet insurance rising at a 21.4% CAGR from 2026 to 2036, as per FMI. The United Kingdom is lowest at 12.9%.
Who are the key companies in the pet insurance market?
Trupanion, Nationwide Pet Insurance, Embrace, Healthy Paws, ASPCA Pet Health Insurance, Figo, Lemonade and Pumpkin sell pet cover. Pets at Home is building an insurance business in the UK.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Policy Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Policy Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Policy Type, 2026 to 2036
- Accident-Only
- Accident and Illness
- Wellness and Routine Care
- Others
- Y-o-Y Growth Trend Analysis By Policy Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Policy Type, 2026 to 2036
- Global Market Analysis and Forecast, By Coverage Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Coverage Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Coverage Type, 2026 to 2036
- Lifetime Coverage
- Non-Lifetime Coverage
- Time-Limited Coverage
- Condition-Based Coverage
- Y-o-Y Growth Trend Analysis By Coverage Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Coverage Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Insurance Companies
- Brokers and Agents
- Online Platforms
- Veterinary Clinics
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Dogs
- Cats
- Horse
- Exotic Pets
- Others
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Policy Type
- By Coverage Type
- By Sales Channel
- By End User
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Lemonade
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Trupanion
- Nationwide Pet Insurance
- Embrace
- Healthy Paws
- Pets at Home
- Figo
- Pumpkin
- ASPCA Pet Health Insurance
- Lemonade
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


