

- Market Size (2026)
- USD 48.0 Bn
- Forecast (2036)
- USD 79.7 Bn
- CAGR (2026 to 2036)
- 5.2%
How big is the PET Packaging Market in 2026?
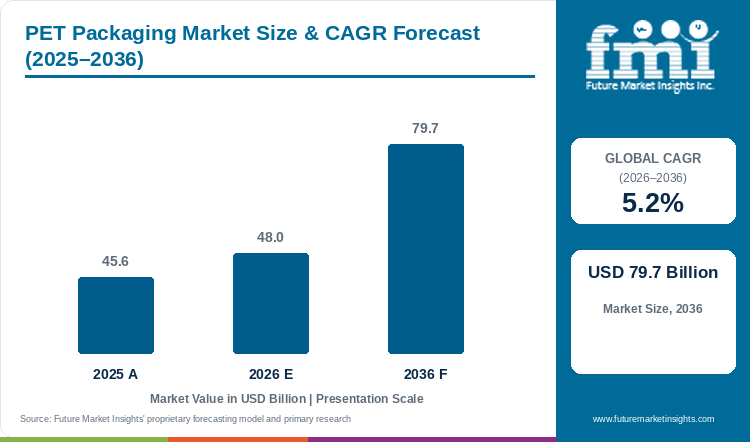
Demand for PET packaging is projected to expand at 5.2% CAGR between 2026 and 2036. Industry value grows from USD 45.6 billion in 2025 to USD 48.0 billion in 2026 and is projected to reach USD 79.7 billion by 2036.
According to Future Market Insights analysis, the global PET packaging market stands at USD 45.6 billion in 2025 and rises to USD 48.0 billion in 2026. Industry valuation is projected to reach USD 79.7 billion by 2036, expanding at a 5.2% CAGR and generating USD 31.7 billion in added revenue. Fast-moving consumer goods brand owners face severe carbon footprint constraints and packaging weight penalties when packaging liquid foods in heavy glass or aluminium containers. In April 2025, Berry Global and Nestlé Purina commercialized 100% mechanically recycled PET canisters, eliminating over 500 metric tonnes of virgin resin annually while lowering greenhouse emissions by 694 metric tonnes[1]. Rigid containers and bottles capture the leading position with 56.4% share in 2026, as preform blow-moulding provides superior barrier integrity at high line speeds. Growth across evaluated economies spans 4.2% in South Africa to 6.3% in the United Kingdom, although uneven food-grade rPET availability and optical haze during mechanical reprocessing continue to temper universal circularity.
Key Market Trends & Insights
- By packaging format: Rigid containers and bottles led with 56.4% share in 2026, because blow-moulded preforms withstand automated high-speed carbonated and aseptic filling lines.
- By material source: Virgin PET accounted for 55.5% in 2026, because sensitive pharmaceutical and baby nutrition applications mandate zero chemical migration risk.
- By end-use sector: Food and beverage represented 32.9% in 2026, due to massive commercial consumption across bottled water, ready-to-drink teas, and edible oil packaging.
Regional Highlights
- Fastest-growing evaluated country: United Kingdom, at 6.3% CAGR from 2026 to 2036.
- By country: Australia at 5.8%, Japan at 5.4%, and the USA at 5.0% follow, while Mexico at 4.6% and South Africa record 4.2% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the PET Packaging Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 45.6 billion |
| Estimated Market Size in 2026 | USD 48.0 billion |
| Projected Market Size by 2036 | USD 79.7 billion |
| CAGR, 2026 to 2036 | 5.2% |
| Added Revenue, 2026 to 2036 | USD 31.7 billion |
Future Market Insights research indicates that adoption develops differently across countries because statutory recycled-content penalties, bottle deposit return systems, and mass-balance accounting laws impose disparate fiscal burdens on brand owners. In November 2025, HM Revenue & Customs affirmed statutory revisions to the UK Plastic Packaging Tax, penalizing packaging containing under 30% recycled content while recognizing certified mass-balance allocations for chemical recycling[2]. Consequently, global beverage conglomerates are restructuring converter supply agreements, hedging resin supply volatility while deploying traceable food-contact resins across regional blow-moulding facilities.
Resin Consumption and Container Sizing Indicators
Table 2: Resin Consumption and Container Volume Sizing for the PET Packaging Market (million metric tonnes and billion units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 45.6 | 48.0 | 79.7 |
| Global PET resin demand (million metric tonnes) | 22.8 to 24.2 | 23.9 to 25.4 | 36.5 to 39.0 |
| Rigid bottle unit shipments (billion units) | 520 to 550 | 545 to 575 | 830 to 880 |
| Food-grade rPET penetration rate (%) | 14.5% to 16.0% | 16.2% to 18.0% | 29.0% to 33.5% |
Calculation basis: Container volume estimates apply global liquid food, beverage, and personal care packaging consumption against standard preform weights averaging 18 to 28 grams per 500 ml container. Recycled resin penetration estimates reflect audited post-consumer bale sorting and food-grade decontamination capacity. Figures are calculations and should be interpreted as scenario ranges, not audited global resin censuses.
Per Capita & Bottling Facility Sizing
Polyethylene terephthalate packaging has gained immense popularity in recent years due to its lightweight durability and superior barrier properties in protecting liquid consumer goods. Managing modern bottling plants requires balancing high-speed line efficiency with strict recycled-content mandates. Surging demand from FMCG brand owners converts daily liquid food consumption into recurring container procurement. Bottling facilities and contract converters represent central volume purchasers for certified food-grade preforms.
Table 3: Per Capita and Beverage Bottling Spending Indicators for the PET Packaging Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 5.54 | 5.78 | 8.91 |
| Spend per 1,000 people (USD) | 5,540.70 | 5,783.13 | 8,905.03 |
| Spend per packaging converter enterprise (USD) | 285,000 to 310,000 | 295,000 to 325,000 | 480,000 to 530,000 |
Table 4: Facility & Commercial Packaging Spending Indicators for the PET Packaging Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 48.0 billion | Report value |
| Commercial bottling and converting facilities worldwide | 155,000 | 2024 secondary industry estimate |
| Market spend per converting facility | USD 309,677.42 | Calculated |
| Food and beverage packaging revenue, 2026 | USD 15.79 billion | 32.9% share |
Analyst Perspective
“Bottle-to-bottle resin procurement is transforming into a decisive operational constraint as statutory recycled-content quotas outpace food-grade recycling infrastructure. Packaging converters that secure traceable decontamination streams and optimize preform lightweighting will maintain long-term supply agreements with global beverage conglomerates.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the PET Packaging Market segmented?
PET Packaging Market is segmented across three primary commercial axes and region: Packaging Format, Material Source, End-Use Sector, and Region. In 2026, rigid containers and bottles account for 56.4% of Packaging Format revenue, virgin PET 55.5% of Material Source, and food and beverage 32.9% of End-Use Sector demand.
- By packaging format: Rigid containers and bottles, flexible films, wraps, and pouches, trays, clamshells, and thermoformed packs, and closures and specialty components.
- By material source: Virgin PET, recycled PET, and bio-attributed and specialty PET.
- By end-use sector: Food and beverage, pharmaceuticals and healthcare, personal care and homecare, industrial and household chemicals, and other consumer and industrial uses.
Why do Rigid Containers and Bottles Anchor Packaging Format Demand?
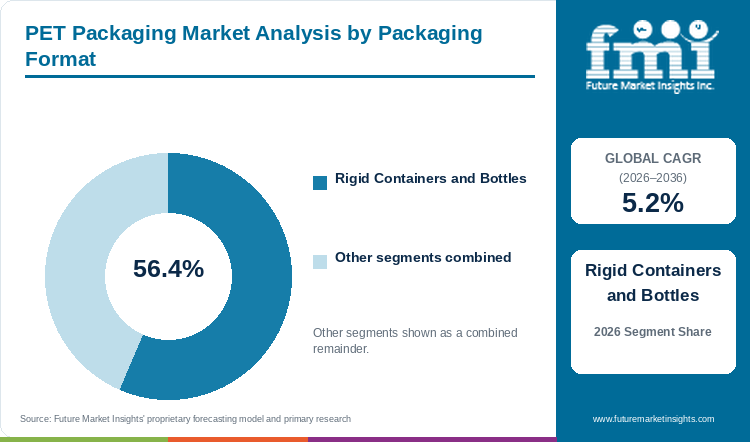
Rigid containers and bottles are projected to hold 56.4% of packaging format revenue in 2026, supported by high-speed filling line compatibility.
Table 5: Packaging Format Share for the PET Packaging Market (percentage share), 2026
| Packaging Format | Share (2026) |
|---|---|
| Rigid containers and bottles | 56.4% |
| Other Segments Combined | 43.6%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Packaging Format Leadership and Market Growth for the PET Packaging Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.2% |
| Leading Segment | Rigid containers and bottles |
FMI research indicates that stretch blow-moulded bottles and wide-mouth jars combine exceptional drop impact strength with gas-barrier protection required for pressurized beverages. Converting preforms near high-speed bottling lines reduces transport bulk while integrating food-grade recycled resin without compromising closure sealing performance or optical clarity across commercial retail shelves.
- Rigid containers and bottles account for 56.4% of packaging format revenue in 2026, supported by high-speed filling line compatibility and automated blow-moulding infrastructure.
- In May 2025, Amcor introduced five commercial PET bottle concepts across beverage, food, and healthcare channels incorporating post-consumer resin blends[3].
What Keeps Virgin PET Central to Material Source Demand?
Virgin PET is estimated to represent 55.5% of material source revenue in 2026, reflecting stringent pharmaceutical purity requirements.
Strict pharmacopeial regulations and infant nutrition purity standards require pristine virgin resin with zero non-intentionally added substance migration risks. Converters processing medical containers and hot-fill syrups mandate predictable intrinsic viscosity and uniform thermal crystallization windows that cannot yet be universally guaranteed across mechanical circular packaging formats, sustaining virgin resin leadership in sensitive applications.
- Virgin PET represents 55.5% of material source revenue in 2026, reflecting stringent pharmaceutical purity requirements and consistent processing viscosity.
- In March 2026, the U.S. Environmental Protection Agency published material-specific data confirming that plastic packaging represents 14.5 million tons in municipal solid waste streams[4].
How Does Food and Beverage Maintain the Leading End-Use Position?
Food and beverage is anticipated to command 32.9% of end-use revenue in 2026, driven by high-volume beverage bottling.
FMI data suggests that high-turnover liquid beverage categories concentrate recurring commercial resin consumption. Carbonated soft drinks, bottled spring waters, and aseptic dairy beverages rely on barrier-enhanced rigid plastic containers that prevent carbonation loss and oxygen ingress while surviving rapid multi-lane filling and pallet distribution without breakage.
- Food and beverage commands 32.9% of end-use revenue in 2026, driven by high-volume beverage bottling and broad retail beverage distribution.
- In July 2025, Japan’s Ministry of Economy, Trade and Industry published official design certification criteria for soft-drink PET bottles under national resource circulation guidelines[5].
What are the drivers, restraints, and opportunities in the PET Packaging Market?
Lightweight shatter resistance and high-speed filling drive commercial adoption, whereas food-grade decontamination bottlenecks constrain recycled resin quotas, and circular design innovations unlock premium growth across regulated packaging sectors.
- Driver: Lightweight container geometry, drop shatter-resistance, and automated blow-moulding compatibility drive primary packaging adoption across beverage and food sectors.
- Restraint: Contaminated post-consumer bale supplies and high decontamination capital expenditure constrain the global availability of food-contact certified recycled resin.
- Opportunity: Advanced chemical recycling, mass-balance accounting certifications, and design-for-recycling mono-material packaging open lucrative recurring contracts with multinational brand owners.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
An FMI analyst notes that beverage brand owners are systematically replacing glass and aluminium across secondary liquid product lines to achieve critical freight decarbonization milestones. Blow-moulding preforms directly adjacent to automated packaging lines slashes outbound logistics volume and prevents transit breakage, expanding commercial deployment of commercial plastic bottles. Amcor’s 2025 multi-market design suite confirmed that advanced lightweight bottle architectures reduce virgin material usage by up to 22% while preserving top-load compression strength[6], enabling bottlers to fulfill corporate environmental targets without slowing filling throughput.
Risk Assessment of the PET Packaging Market: Operational and Material Friction
Supply deficits of high-purity, food-grade post-consumer resin constitute the primary commercial bottleneck restricting mandatory circular packaging compliance. Mechanical recycling degrades PET polymer chain lengths, introducing acetaldehyde formation, optical haze, and drop impact brittleness into thermoformed containers. Official Australian government data revealed that out of 4.0 million tonnes of plastic packaging consumed annually, only 446 kilotonnes were successfully recovered[7]. The resulting 14% recovery gap forces converters to pay steep market premiums for certified food-contact flake, suppressing operating profit margins.
Commercial Opportunity Analysis: Regulatory Compliance and Circular Formats
Statutory traceability protocols and extended producer responsibility fee structures are creating lucrative commercial openings for converters offering verified chain-of-custody resin platforms. Deploying traceable post-consumer resin allows beverage giants to substantiate sustainability marketing while avoiding statutory non-compliance fines in high-speed beverage packaging. In March 2025, Australia’s Department of Climate Change and Environment released a revised national framework for recycled content traceability[8], providing transparent accounting mechanisms that accelerate industrial procurement of certified recycled polymers.
PET Packaging Market by Country (2026 to 2036)
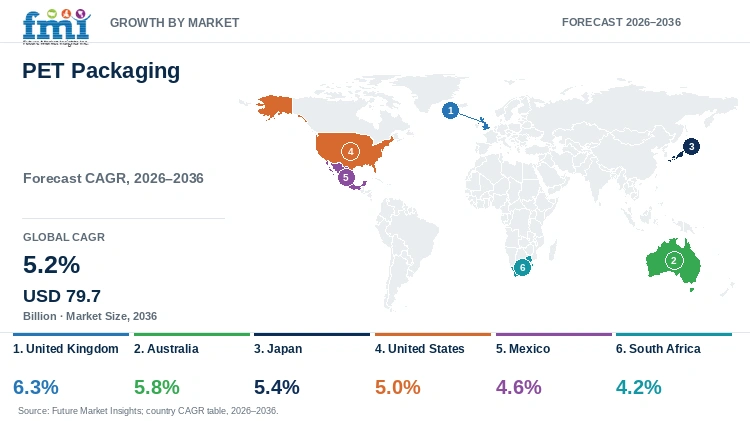
As per FMI, the United Kingdom represents the fastest-growing PET packaging market among evaluated economies at a 6.3% CAGR through 2036, while South Africa records 4.2% CAGR.
Table 7: Country CAGR and Primary Growth Levers for the PET Packaging Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| United Kingdom | 6.3% | Plastic packaging tax escalators and statutory 30% recycled content rules |
| Australia | 5.8% | National packaging covenant targets and recycled-content traceability rules |
| Japan | 5.4% | Plastic Resource Circulation Act certifications and Green Purchasing criteria |
| United States | 5.0% | State-level post-consumer resin mandates and FMCG brand sustainability pledges |
| Mexico | 4.6% | National Plastics Agreement commitments and industrial bottle recycling hubs |
| South Africa | 4.2% | Extended producer responsibility schemes and local bottle-to-bottle plant capacity |
Source: Future Market Insights analysis
United Kingdom PET Packaging Market Outlook (2026 to 2036)
Stringent fiscal mechanisms govern plastic packaging procurement across the United Kingdom, where statutory tax policy penalizes containers containing insufficient recycled resin. Section 78 of the UK Finance Act 2025 raised the statutory plastic packaging tax rate, intensifying financial liability on packaging with less than 30% recycled content[9]. This fiscal driver accelerates the domestic market at a 6.3% CAGR through 2036 while integrating protective food packaging. Converters that secure certified food-grade rPET flakes shield customers from tax liabilities, although domestic re-granulation deficits necessitate imported resin supplies.
Key takeaway: In the United Kingdom, statutory plastic packaging tax penalties and verified mass-balance chemical recycling accounting establish compelling financial incentives for converters utilizing certified recycled PET.
Australia PET Packaging Market Outlook (2026 to 2036)
National packaging targets established by the Australian Packaging Covenant Organisation mandate that domestic beverage packaging incorporate 30% average recycled content[10], supporting a forecasted 5.8% CAGR through 2036. The Australian Department of Climate Change published a national traceability framework in March 2025 to standardize chain-of-custody documentation for recycled resins[8]. However, low overall recovery rates across regional post-consumer streams restrict domestic flake supply, requiring converters to establish direct buy-back agreements with local beverage bottlers.
Key takeaway: In Australia, government-backed packaging covenant recycling targets and formal chain-of-custody traceability frameworks drive procurement toward audited food-grade recycled PET.
Japan PET Packaging Market Outlook (2026 to 2036)
Statutory design-for-recycling standards govern Japan’s packaging sector under the Plastic Resource Circulation Act. In February 2026, the Ministry of Economy, Trade and Industry awarded its first official certifications to 41 commercial plastic designs, including 100% recycled PET beverage bottles produced by Suntory and Coca-Cola[11]. This formal recognition propels the Japanese market at a 5.4% CAGR through 2036 while advancing regulated healthcare packaging. Certified packaging gains preferential procurement under national Green Purchasing programs, creating powerful commercial motivation for converters.
Key takeaway: In Japan, government certification under resource circulation laws directly links eco-design with public procurement preferences, accelerating commercial uptake of 100% recycled PET bottles.
USA PET Packaging Market Outlook (2026 to 2036)
In the United States, commercial scale and multi-state post-consumer resin mandates drive massive converter demand for food-grade recycled resins. The commercial conversion of Nestlé Purina pet treat containers to 100% mechanically recycled PET by Berry Global confirmed that large-format rigid packaging can successfully transition away from virgin polymers[12]. This momentum supports an anticipated 5.0% CAGR through 2036. However, fragmented municipal curbside recycling systems generate inconsistent bale quality, requiring industrial converters to invest heavily in secondary optical sorting and multi-stage vacuum washing systems.
Key takeaway: In the USA, brand-driven conversion programs and expanding state-level recycled-content mandates solidify rigid recycled PET as the leading format for retail consumer goods containers.
Mexico PET Packaging Market Outlook (2026 to 2036)
Voluntary brand agreements and highly organized bottle collection networks characterize the Mexican packaging sector. In September 2025, SEMARNAT reported that 77 signatory companies representing 51% of the national plastic packaging market achieved their recycled-content targets ahead of schedule[13]. This collaborative progress underpins a 4.6% CAGR through 2036 while consuming large volumes of post-consumer recycled plastic. Robust commercial bottle collection programs provide clean feedstock for domestic recycling facilities, though price volatility in imported virgin resin creates periodic margins pressure.
Key takeaway: In Mexico, strong voluntary brand pacts and mature domestic bottle collection infrastructure support consistent expansion in commercial recycled PET bottle conversion.
South Africa PET Packaging Market Outlook (2026 to 2036)
Expanding domestic bottle-to-bottle decontamination capacity and mandatory extended producer responsibility regulations define market expansion in South Africa. In 2025, ALPLA opened a major industrial PET recycling plant in Ballito following substantial capital investment, creating local capacity to supply 15,000 tonnes of food-grade recycled resin annually[14]. This domestic capacity fosters a 4.2% CAGR through 2036 while complementing flexible barrier packaging. Localizing resin production insulates converters from currency depreciation and international freight bottlenecks.
Key takeaway: In South Africa, substantial investment in localized bottle-to-bottle recycling plants and statutory EPR frameworks establish steady domestic supply of food-grade recycled PET.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the PET Packaging Market?
A few notable companies in the PET Packaging Market include Amcor plc, Berry Global Group, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Mondi plc, Sonoco Products Company, Smurfit Westrock plc, Ball Corporation, and Crown Holdings, Inc.
As per the analysis from FMI, competition divides between dedicated rigid plastics converters and diversified packaging conglomerates. Global rigid specialists compete on multi-cavity preform tooling, barrier coatings, and compatibility with high-volume bottling machinery. Meanwhile, paper and metal packaging producers offer competing alternatives in beverage and personal care. Brand owners evaluate suppliers on resin decontamination certification, light-weighting engineering, and localized converting infrastructure.
- Rigid PET Specialists: Amcor plc, Berry Global Group, and Silgan Holdings supply high-speed bottles, custom wide-mouth jars, and specialized closures.
- Diversified Packaging Groups: Huhtamaki Oyj, Mondi plc, Sonoco Products Company, and Smurfit Westrock compete across multi-material formats, thermoformed trays, and secondary packaging.
- Competing Metal Formats: Ball Corporation and Crown Holdings provide recyclable aluminium alternatives that compete directly against single-use plastic bottles in beverage dispensing.
Competitive Benchmarking: PET Packaging Market
Table 8: Competitive Benchmarking for the PET Packaging Market (qualitative capability ratings), 2026
| Company | PET Relevance | Portfolio Breadth | Geographic Reach | Current Activity |
|---|---|---|---|---|
| Amcor plc | High | High | High | High |
| Berry Global Group, Inc. | High | High | High | High |
| Silgan Holdings Inc. | High | High | Medium | Medium |
| Huhtamaki Oyj | Medium | Medium | High | Medium |
| Mondi plc | Medium | Medium | High | Medium |
| Sonoco Products Company | Medium | High | High | Medium |
| Smurfit Westrock plc | Medium | Medium | High | Medium |
| Ball Corporation | Medium | Medium | High | High |
| Crown Holdings, Inc. | Medium | Medium | High | High |
Scoring basis: High indicates broad evidenced commercial activity, multi-market production facilities, and specialized preform converting depth; Medium indicates focused regional presence or multi-material portfolio; Low indicates limited direct PET manufacturing. Ratings are qualitative capability assessments and not audited market-share rankings.
Key Developments in the PET Packaging Market
- In March 2026, Ball Corporation presented an industrial circularity initiative assessing aluminum cartridge substitution against single-use rigid PET containers[17].
- In May 2025, Amcor unveiled five commercial PET bottle concepts across beverage, food, and healthcare channels incorporating post-consumer resin blends[15].
- In April 2025, Berry Global and Nestlé Purina launched 100% mechanically recycled PET treat canisters to replace virgin plastic packaging[16].
Key Players in the PET Packaging Market
- Rigid PET Packaging Manufacturers: Amcor plc; Berry Global Group, Inc.; Silgan Holdings Inc.
- Diversified Packaging and Specialty Formats: Huhtamaki Oyj; Mondi plc; Sonoco Products Company; Smurfit Westrock plc.
- Competing Beverage Container Specialists: Ball Corporation; Crown Holdings, Inc.
PET Packaging Market - Report Scope
Table 9: Report Scope for the PET Packaging Market (coverage fields and definitions), 2026 to 2036
| Scope item | Definition |
|---|---|
| Market boundary | Primary PET packaging formats and components sold for product containment, protection, transport, or dispensing. |
| Included | Rigid PET bottles, jars, trays, clamshells, films, pouches, closures, specialty components, virgin PET, and recycled PET. |
| Excluded | PET resin sold for textile fibers, engineering plastics, and products not used as packaging. |
| Unit | USD billion. |
| Base year | 2025 |
| Estimate year | 2026 |
| Forecast period | 2026–2036 |
| Regions | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa. |
PET Packaging Market - Research Methodology
Table 10: Research Methodology for the PET Packaging Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Analysts gathered input from resin producers, preform converters, bottling plant managers, brand packaging engineers, and recycling operators. Interviews examined resin qualification cycles, barrier performance requirements, deposit return system impacts, and corporate circularity commitments. |
| Desk Research | Desk research covered national waste and recycling statistics, environmental agency publications, corporate sustainability reports, trade association records, and patent literature. Sources were verified for recency, regional scope, and alignment with defined market boundaries. |
| Market Sizing and Forecasting | The econometric model integrated baseline resin consumption with historical growth trends, end-use demand shifts, regulatory mandates, and country-level bottling production. Forecast assumptions accounted for preform lightweighting, rPET price premiums, and virgin substitution rates. |
| Data Validation | Estimates were cross-validated against public container shipment records, corporate financial filings, resin manufacturer sales, and primary interview findings to eliminate double-counting between raw resin and finished containers. |
PET Packaging Market by Segments
PET Packaging Market segmented by Packaging Format:
- Rigid Containers and Bottles
- Flexible Films, Wraps, and Pouches
- Trays, Clamshells, and Thermoformed Packs
- Closures and Specialty Components
PET Packaging Market segmented by Material Source:
- Virgin PET
- Recycled PET
- Bio-Attributed and Specialty PET
PET Packaging Market segmented by End-Use Sector:
- Food and Beverage
- Pharmaceuticals and Healthcare
- Personal Care and Homecare
- Industrial and Household Chemicals
- Other Consumer and Industrial Uses
PET Packaging Market by Region
- North America
- United States
- Canada
- Latin America
- Mexico
- Brazil
- Rest of Latin America
- Western Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Western Europe
- Eastern Europe
- Poland
- Romania
- Rest of Eastern Europe
- East Asia
- Japan
- South Korea
- Rest of East Asia
- South Asia and Pacific
- Australia
- ASEAN
- Rest of South Asia and Pacific
- Middle East and Africa
- South Africa
- GCC countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- [1] Amcor plc. (2025, April 29). Berry Global and Nestlé Purina PetCare launch 100% recycled content treat canisters. Amcor News & Media.
- [2] HM Revenue & Customs. (2025, November 26). Plastic Packaging Tax: Mass balance approach and removal of pre-consumer plastic. HMRC Guidance Publications.
- [3] Amcor plc. (2025, May 7). 2025 Bottles of the Year are must-see packaging designs. Amcor Commercial Portfolio.
- [4] U.S. Environmental Protection Agency. (2026, March 13). Plastics: Material-specific municipal solid waste data. EPA Facts and Figures.
- [5] Ministry of Economy, Trade and Industry, Japan. (2025, July 24). Design certification criteria for four plastic product fields under Resource Circulation Act. METI Policy Releases.
- [6] Amcor plc. (2025, May 7). Bottles of the Year commercial engineering programme. Amcor Technical Releases.
- [7] Department of Climate Change, Energy, the Environment and Water. (2025). Australian plastics flows and fates reporting. DCCEEW Waste Reports.
- [8] Department of Climate Change, Energy, the Environment and Water. (2025, March). National framework for recycled content traceability. Australian Government Publications.
- [9] UK Parliament. (2025). Finance Act 2025, Section 78: Rates of plastic packaging tax. The Stationery Office.
- [10] Department of Climate Change, Energy, the Environment and Water. (2026, September 11). Australian Packaging Covenant Organisation target assessment. DCCEEW Official Reviews.
- [11] Ministry of Economy, Trade and Industry, Japan. (2026, February 10). First certifications under the Plastic Resource Circulation Act. METI Press Notices.
- [12] Amcor plc. (2025, April 29). Berry Global and Nestlé Purina PetCare launch recycled PET canisters. Corporate Case Studies.
- [13] Secretariat of Environment and Natural Resources, Mexico. (2025, September 4). Fifth report of the National Agreement for the New Plastics Economy. SEMARNAT Informes Oficiales.
- [14] InvestSA. (2025). ALPLA Recycling SA Ballito plant officially opens. Department of Trade, Industry and Competition.
- [15] Amcor plc. (2025, May 7). 2025 Bottles of the Year portfolio overview. Amcor Media Releases.
- [16] Amcor plc. (2025, April 29). Recycled-content treat canisters technical performance report. Amcor Sustainability Documentation.
- [17] Ball Corporation. (2026, March 4). Ball collaborates to scale circular and low-carbon packaging. Ball Corporation Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- What is the PET packaging market value forecast through 2036?
- Which packaging format holds a notable PET market share?
- Which material source leads PET packaging revenue in 2026?
- Which end-use sector supports PET packaging demand in 2026?
- Which country shows a notable PET packaging expansion outlook?
- Which companies are profiled in the PET packaging market?
Frequently Asked Questions
How large is the PET packaging market in 2026?
Future Market Insights estimates the global PET packaging market at USD 48.0 billion in 2026. The market is projected to reach USD 79.7 billion by 2036, supported by beverage bottling demand.
What CAGR is expected from 2026 to 2036?
According to FMI, global PET packaging revenue is projected to expand at a 5.2% CAGR from 2026 to 2036. Growth is driven by preform lightweighting and recycled-content adoption.
Which packaging format has a notable share in 2026?
Rigid containers and bottles are projected to account for 56.4% of packaging format revenue in 2026. High-speed blow-moulding compatibility and closure integrity support this leading position.
Which material source has a notable share in 2026?
Virgin PET is estimated to hold 55.5% of material source revenue in 2026. Sensitive food and pharmaceutical applications require virgin resin to ensure barrier purity and avoid non-intentionally added substances.
Which country has a notable growth outlook?
The United Kingdom is projected to expand at a leading 6.3% CAGR from 2026 to 2036. National packaging tax penalties on virgin resin accelerate converter investments in verified recycled content.
Which companies are notable in this market?
Amcor, Berry Global, Silgan, Huhtamaki, Mondi, Sonoco, Smurfit Westrock, Ball, and Crown are notable participants. Converters prioritize post-consumer resin access, preform barrier enhancement, and automated blow-moulding efficiency.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Rigid Containers and Bottles
- Flexible Films, Wraps, and Pouches
- Trays, Clamshells, and Thermoformed Packs
- Closures and Specialty Components
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Material Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Source, 2026 to 2036
- Virgin PET
- Recycled PET
- Bio-Attributed and Specialty PET
- Y-o-Y Growth Trend Analysis By Material Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Source, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Food and Beverage
- Pharmaceuticals and Healthcare
- Personal Care and Homecare
- Industrial and Household Chemicals
- Other Consumer and Industrial Uses
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Packaging Format
- By Material Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Source
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Mexico
- Brazil
- Rest of Latin America
- By Packaging Format
- By Material Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Source
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Western Europe
- By Packaging Format
- By Material Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Source
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Romania
- Rest of Eastern Europe
- By Packaging Format
- By Material Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Source
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- Rest of East Asia
- By Packaging Format
- By Material Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Source
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- ASEAN
- Rest of South Asia and Pacific
- By Packaging Format
- By Material Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Source
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Africa
- GCC countries
- Rest of Middle East and Africa
- By Packaging Format
- By Material Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Source
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Source
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Packaging Format
- By Material Source
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Amcor plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Berry Global Group, Inc.
- Silgan Holdings Inc.
- Huhtamaki Oyj
- Mondi plc
- Sonoco Products Company
- Smurfit Westrock plc
- Ball Corporation
- Crown Holdings, Inc.
- Rigid PET Packaging Manufacturers: Amcor plc; Berry Global Group, Inc.; Silgan Holdings Inc.
- Diversified Packaging and Specialty Formats: Huhtamaki Oyj; Mondi plc; Sonoco Products Company; Smurfit Westrock plc.
- Competing Beverage Container Specialists: Ball Corporation; Crown Holdings, Inc.
- Amcor plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


