
- Market Size (2026)
- USD 2.7 Bn
- Forecast (2036)
- USD 5.7 Bn
- CAGR (2026 to 2036)
- 7.8%
How big is Organic Pet Food Market in 2026?
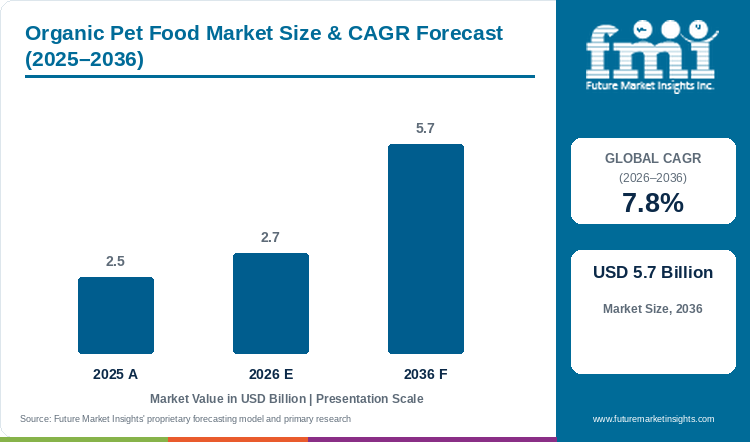
Sales in the organic pet food market are projected to grow at 7.8% CAGR, with the market size rising from USD 2.5 billion in 2025 to USD 2.7 billion in 2026 and reaching USD 5.7 billion by 2036.
Consumer scrutiny regarding commercial pet nutrition is accelerating a transition from broad natural claims toward certified organic formulations that verify supply chain traceability. Pet owners are increasingly holding animal diets to human-grade standards, requiring pet food processors to validate certified ingredient origins from farm to packaging bowl. According to Future Market Insights analysis, global organic pet food market valuation reached USD 2.5 billion in 2025 and rises to USD 2.7 billion in 2026.
The industry is projected to attain USD 5.7 billion by 2036, advancing at a 7.8% CAGR over the assessment period and generating USD 3.0 billion in added revenue. In June 2025, the Pet Food Institute reported that U.S. pet food manufacturing represents an annual domestic market exceeding USD 64 billion, with pet parents in 82 million households demanding certified ingredient transparency [1]. Dry food commands the leading position with 53.0% share in 2026, as ambient shelf stability and routine daily feeding routines facilitate wider retail distribution. This supports the hypothesis that organic premium adoption hinges on certified supply continuity; however, elevated organic protein procurement costs and batch segregation bottlenecks continue to compress manufacturing margins across mid-sized pet brands.
Key Market Trends & Insights
- By pet type: Dogs are projected to account for 37.0% share in 2026, supported by higher feeding volumes and strong premium nutrition spending.
- By food type: Dry food is estimated to hold 53.0% share in 2026, owing to convenient storage and established omnichannel availability.
- Novel organic proteins and insect-based formulations are expanding options for dogs with chronic grain or poultry food sensitivities.
- Specialty pet retail and automated direct-to-consumer delivery subscriptions anchor predictable recurring monthly revenue for premium organic brands.
- Strict statutory organic certification audits mandate dedicated manufacturing runs to prevent cross-contamination from conventional ingredients.
Regional Highlights
- Fastest-growing evaluated country: United States, at 7.4% CAGR from 2026 to 2036.
- By country: The UK follows at 6.5%, while Germany records 5.8% CAGR over the assessment period.
Market Size & Forecast
Table 1: Market Size and Forecast for the Organic Pet Food Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 2.5 billion |
| Estimated Market Size in 2026 | USD 2.7 billion |
| Projected Market Size by 2036 | USD 5.7 billion |
| CAGR, 2026 to 2036 | 7.8% |
| Added Revenue, 2026 to 2036 | USD 3.0 billion |
Commercial conditions differ across the profiled countries owing to distinct national organic certification rules and specialty retail penetration. Regulatory oversight transforms organic pet nutrition into a rigorous compliance-driven discipline. In February 2025, the USDA Agricultural Marketing Service delayed the National Organic Program pet food rule effective date to March 21, 2025, with the compliance deadline set for March 22, 2027, requiring processors to formalize organic ingredient handling protocols [2]. Companies formulating certified products must align supplier audit records, recipe testing, and packaging labels simultaneously. This validates that brand longevity is anchored to verified input security, whereas uncertified natural lines face consumer skepticism regarding ingredient authenticity.
Pet-Household and Revenue-Intensity Sizing
Table 2: Pet-Household and Revenue-Intensity Sizing for the Organic Pet Food Market (USD billion and scenario indicators), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 2.5 | 2.7 | 5.7 |
| Addressable pet households (million) | 94 to 95 | 95 to 97 | 104 to 112 |
| Organic market spend per pet household (USD) | 26.36 to 26.65 | 27.84 to 28.42 | 50.89 to 54.81 |
| Dry food revenue (USD billion) | 1.3 | 1.4 | 3.0 |
Per Capita and Certified-Supply Sizing
The addressable base is wide enough to support repeat demand, but ownership alone will not convert into organic sales. In March 2026, APPA reported 95 million U.S. pet-owning households from its national survey [3]. This gives brands a large pool of regular buyers; however, the category can gain only where certified recipes remain available, palatable and close enough to premium conventional food on pack price. Scaling demand also stimulates innovation in pet food packaging to protect nutrient stability.
Table 3: Per Capita Spending Indicators for the Organic Pet Food Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.304 | 0.325 | 0.637 |
| Spend per 1,000 people (USD) | 304.33 | 325.30 | 636.87 |
| Added revenue versus 2026 (USD billion) | - | - | 3.0 |
Table 4: Category Revenue Indicators for the Organic Pet Food Market (USD billion and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 2.7 billion | Report value |
| Dry food revenue, 2026 | USD 1.4 billion | 53.0% share |
| Dog segment revenue, 2026 | USD 1.0 billion | 37.0% share |
| 2026 to 2036 added revenue | USD 3.0 billion | Forecast difference |
Analyst Perspective
“Organic pet food growth now depends on certified supply continuity and transparent ingredient documentation. Brands that align formulation discipline with dependable availability can support premium expansion across retail channels.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Organic Pet Food Market segmented?
The organic pet food market is segmented by pet type and food type. In 2026, dogs are projected at 37% of pet type revenue, while dry food is projected at 53% of food type revenue.
By pet type: Dogs and cats.
By food type: Dry food, wet food, and frozen food.
Why does Dry Food lead the food type category?
Dry food is projected to hold 53.0% of food type revenue in 2026, supported by ambient shelf life and convenient daily feeding routines.
Table 5: Food Type Share for the Organic Pet Food Market (percentage share), 2026
| Food Type | Share (2026) |
|---|---|
| Dry Food | 53.0% |
| Other Segments Combined | 47.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Food Type Leadership and Market Growth for the Organic Pet Food Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.8% |
| Leading Segment | Dry Food |
Dry food is expected to lead with 53.0% share in 2026 because it solves the everyday issues that decide repeat buying. It can move through longer distribution routes, stays usable after opening and suits subscription orders, due to which certified kibble can reach more households than formats requiring cold storage. Formulators also incorporate animal nutrition chemicals to balance natural vitamins. According to the FEDIAF Facts & Figures 2025 report, released in June 2025, dry dog food represented 61% of all dog food produced in Europe by volume, confirming dry formats as the primary feeding choice across European households [6]. Wet and frozen products gain where visible meat content supports a higher price, but cold-chain delivery costs keep their scale lower.
- Dry food remains the primary commercial format as extruded kibble delivers cost-effective feeding across multi-pet households.
- In February 2025, Marsapet and Calysta launched MicroBell dry kibble using FeedKind fermented protein for European channels [4].
What supports Dogs as the preferred pet type?
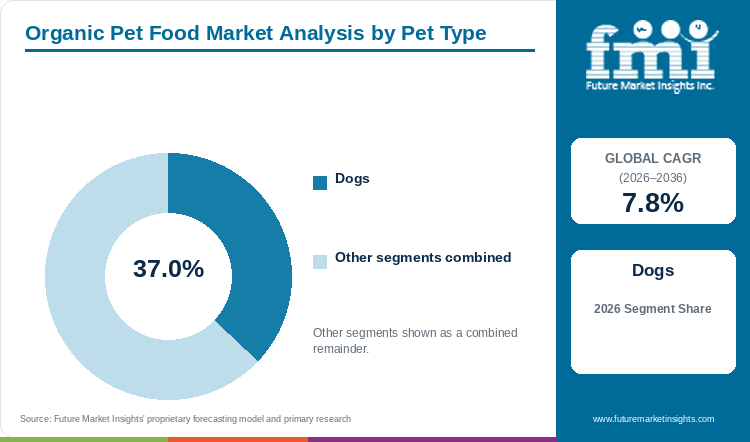
Dogs are estimated to account for 37.0% of pet type revenue in 2026, reflecting larger daily portion sizes and sustained premium health investments.
Dogs are projected to hold 37.0% share in 2026, mainly because the amount fed per day and the range of age, breed, and health-led recipes create a larger spending base. Owners routinely complement organic kibble with a pet joint health supplement to support mobility in older dogs. However, higher pack consumption also makes the organic premium more visible, due to which adoption can weaken when household budgets become tight.
- Higher daily caloric requirements make dog owners the primary contributors to annual organic pet food sales volume.
- According to APPA's 2026 Dog Report, dog ownership expanded to 53% of U.S. households, representing 71 million households and reinforcing the concentrated revenue base for certified canine nutrition [3].
What are the drivers, restraints, and opportunities in the Organic Pet Food Market?
In the organic pet food market, pet humanization and ingredient traceability drive certified diet demand, premium procurement costs and batch segregation restrain adoption, and novel sustainable proteins create high-value commercial formulation opportunities through 2036.
- Driver: Pet humanization and ingredient scrutiny increase demand for certified formulations with clear sourcing records.
- Restraint: Organic protein and crop inputs carry higher procurement costs and face tighter certified processing capacity.
- Opportunity: Brands can combine organic certification with novel proteins, functional nutrition, and dependable omnichannel availability.
Growth Analysis and Future Potential: Certification-Led Demand Catalysts
Pet owners are increasingly carrying their own dietary standards into pet feeding, which is supporting demand for cleaner records and recognized certification. In June 2025, the Pet Food Institute stated that its members supply dog and cat food to 82 million U.S. households and represent more than USD 64 billion in annual domestic sales [1]. Such a large regular-use base gives organic products room to grow, accelerating shelf placement for organic foods across mass and specialty pet channels. In May 2025, the Organic Trade Association recorded that organic pet food spending expanded by 6.8% across North American retail channels [10], reinforcing commercial category momentum.
Risk Assessment of the Organic Pet Food Market: Input and Compliance Friction
Organic formulations face pressure before the product reaches the shelf. Certified meat, crops, oils and supplements come from fewer approved suppliers, while shared plants need cleaning and segregation between conventional and organic runs. In February 2025, the USDA Agricultural Marketing Service delayed the National Organic Program pet food rule effective date to March 21, 2025, while organic operations must comply with all requirements by March 22, 2027 [2]. Regulatory uncertainty can delay capital investments across commercial wet pet food and dry processing facilities. In January 2025, the Association of American Feed Control Officials (AAFCO) released updated model regulations tightening nutrient adequacy verification for organic claims [9], elevating formulation costs.
Commercial Opportunity Analysis: Traceable Formats and Product Differentiation
Commercial opportunity is stronger where an organic claim is attached to a feeding reason rather than used alone. In February 2025, Colgate-Palmolive agreed to acquire Care TopCo Pty Ltd, the owner of fresh pet food brand Prime100, expanding Hill's Pet Nutrition into the premium fresh pet food segment in Australia [5], while Marsapet launched MicroBell using fermented FeedKind protein [4]. Expanding into certified pet treats, functional pet food, freeze-dried pet food and innovative plant-based pet food allows brands to justify premium pricing across omnichannel retail networks.
Organic Pet Food Market by Country (2026 to 2036)
As per Future Market Insights, the United States is projected to record the highest growth rate among the profiled countries at a 7.4% CAGR from 2026 to 2036, followed by the UK at 6.5% and Germany at 5.8%. Across these mature pet markets, commercial performance is dictated by organic ingredient availability, consumer willingness to absorb retail premiums, and channel access across veterinary clinics and specialty pet retailers.
Table 7: Country CAGR and Primary Growth Levers for the Organic Pet Food Market (CAGR percentage and operational drivers), 2026 to 2036
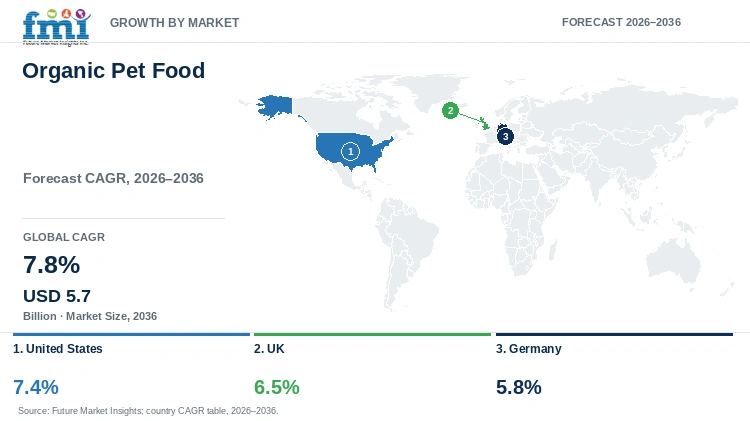
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| United States | 7.4% | Large pet-owning base and maturing organic certification |
| UK | 6.5% | Premium nutrition demand across specialty and online channels |
| Germany | 5.8% | Organic purchasing culture and specialist recipe positioning |
United States Organic Pet Food Market Outlook (2026 to 2036)
The United States is expected to expand at 7.4% CAGR during 2026 to 2036, which is the highest among the listed countries. Its advantage is not only the number of pet households but the presence of specialty retail, online delivery and buyers already used to paying for premium nutrition. In March 2026, APPA documented 95 million pet-owning households across the country [3]. Certified pet food processors benefit from expanding consumer interest in organic pet food products. However, compliance delays regarding federal organic pet food standards require companies to maintain rigorous audit trails for certified animal proteins and organic grains.
Key takeaway: In the United States, massive household pet ownership and mature specialty retail infrastructure drive consistent adoption of certified organic pet food.
UK Organic Pet Food Market Outlook (2026 to 2036)
The UK is projected to grow at 6.5% CAGR during 2026 to 2036. Demand builds through specialty pet shops, direct delivery and subscription models where smaller bag sizes lower the initial trial barrier. In September 2025, the UK Department for Environment, Food & Rural Affairs (Defra) reported that registered organic agricultural production expanded by 4.1%, supporting domestic organic pet ingredient procurement [7]. Clear certification and dependable online replenishment support repeat buying; however, when retail inflation widens the price gap against conventional natural brands, price-sensitive pet owners temporarily trade down.
Key takeaway: In the UK, premium direct-to-consumer pet subscription models and strict organic labeling standards support steady market expansion.
Germany Organic Pet Food Market Outlook (2026 to 2036)
Germany is expected to register 5.8% CAGR during 2026 to 2036. The country exhibits deep consumer familiarity with certified organic standards (Bio-Siegel), making documented ingredient origins easier to communicate in pet diets. In August 2025, the Federal Ministry of Food and Agriculture (BMEL) recorded that retail sales of certified organic products surpassed EUR 16 billion [8]. Growth is supported by specialist retailers and single-protein formulations where organic meat sourcing remains transparent. However, German pet owners scrutinize analytical constituents and nutritional completeness, requiring brands to prove balanced amino acid profiles.
Key takeaway: In Germany, established organic food purchasing habits and rigorous Bio-Siegel credibility foster a loyal consumer base for certified pet nutrition.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Organic Pet Food Market?
Nestle Purina, Mars Petcare, Primal Pet Foods, Hill’s Pet Nutrition, PetGuard Holdings, and Marsapet are notable companies operating in this market.
Future Market Insights analysis indicates that competition is divided between multinational pet care conglomerates with expansive distribution reach and agile specialists with dedicated clean-label formulations. Nestle Purina, Mars Petcare, and Hill’s leverage extensive retail logistics and veterinary endorsements to scale organic offerings. Conversely, Primal Pet Foods, PetGuard, and Marsapet focus on raw frozen, single-origin meat, and alternative protein innovations. Retail buyers evaluate suppliers based on verified organic certifications, guaranteed supply continuity, and shelf turnover velocity.
- Global pet nutrition platforms: Nestle Purina, Mars Petcare, and Hill’s Pet Nutrition command widespread supermarket and pet superstore shelf space.
- Premium and specialist suppliers: Primal Pet Foods, PetGuard Holdings, and Marsapet differentiate through minimally processed, freeze-dried, and novel protein formulations.
Competitive Benchmarking: Organic Pet Food Market
Table 8: Competitive Benchmarking for the Organic Pet Food Market (qualitative capability ratings), 2026
| Company | Format Breadth | Certified / Traceable Sourcing | Retail Access | Geographic Reach |
|---|---|---|---|---|
| Nestle Purina | High | Medium | High | High |
| Mars Petcare | High | Medium | High | High |
| Primal Pet Foods | Medium | High | Medium | Medium |
| Hill’s Pet Nutrition | High | Medium | High | High |
| PetGuard Holdings | Medium | High | Medium | Low |
| Marsapet | Medium | Medium | Medium | Medium |
Scoring basis: High indicates broad public evidence across the capability. Medium indicates a narrower documented range. Low indicates concentrated geographic or channel coverage. Ratings describe observable portfolio positioning and do not rank financial performance.
Key Developments in the Organic Pet Food Market
- In February 2025, Colgate-Palmolive agreed to acquire Prime100, adding a premium fresh pet food platform to Hill’s Pet Nutrition [5].
- In February 2025, Marsapet and Calysta launched MicroBell dry kibble featuring FeedKind fermented protein, available in European pet food stores and online [4].
- In February 2025, the USDA Agricultural Marketing Service published an updated implementation schedule for the National Organic Program pet food rule [2].
Key Players in the Organic Pet Food Market
Global Pet Nutrition Platforms
- Nestle Purina
- Mars Petcare
- Hill’s Pet Nutrition
Premium and Specialist Suppliers
- Primal Pet Foods
- PetGuard Holdings
- Marsapet
Organic Pet Food Market - Report Scope
Table 9: Report Scope for the Organic Pet Food Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Pet Type; Food Type |
| Quantitative Units | USD billion |
| Market Definition | Revenue from pet food carrying verified organic certification or equivalent recognized organic claims within the listed taxonomy. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | United States, UK, Germany, and additional countries in the full report |
| Key Companies Covered | Nestle Purina, Mars Petcare, Primal Pet Foods, Hill’s Pet Nutrition, PetGuard Holdings, Marsapet |
| Forecast Period | 2026 to 2036 |
Organic Pet Food Market - Research Methodology
Table 10: Research Methodology for the Organic Pet Food Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with pet food manufacturers, organic crop suppliers, distributors, retailers, animal nutritionists, and industry experts validate demand conditions and purchasing criteria. |
| Secondary Research | Company annual reports, investor presentations, regulatory publications, pet product industry associations, technical papers, trade journals, and public agricultural statistics are reviewed. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess organic pet food revenue, pet ownership trends, feeding formats, price points, and premium adoption trajectories for 2026 to 2036. |
| Data Triangulation and Validation | Data is validated against macroeconomic indicators, pet demographics, organic agricultural supply chains, and historical retail market performance to eliminate double counting. |
Organic Pet Food Market by Segments
Organic Pet Food Market segmented by Pet Type:
- Dogs
- Cats
Organic Pet Food Market segmented by Food Type:
- Dry Food
- Wet Food
- Frozen Food
Organic Pet Food Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Western Europe
- Germany
- UK
- France
- Italy
- Spain
- Eastern Europe
- Poland
- Hungary
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
Research Sources and Bibliography
- [1] Pet Food Institute. (2025, June 11). Comments on the National Organic Program market development rule for pet food. PFI Regulatory Submissions.
- [2] U.S. Department of Agriculture, Agricultural Marketing Service. (2025, February 10). National Organic Program: Market development for mushrooms and pet food, delay of effective date. Federal Register, 90(28), 9205-9208.
- [3] American Pet Products Association. (2026, March 18). Pet industry market size, trends, and National Pet Owners Survey statistics. APPA Publications.
- [4] Calysta and Marsapet GmbH. (2025, February 27). Marsapet launches first dog food featuring FeedKind Pet protein. Commercial Press Releases.
- [5] Colgate-Palmolive Company. (2025, February 18). Agreement to acquire Care TopCo Pty Ltd, owner of Prime100. Investor Disclosures.
- [6] European Pet Food Industry Federation (FEDIAF). (2025, June 20). European pet food industry facts and figures annual report. FEDIAF Publications.
- [7] Department for Environment, Food & Rural Affairs. (2025, September 15). Organic farming and food production statistics in the United Kingdom. Defra Official Statistics.
- [8] Federal Ministry of Food and Agriculture (BMEL). (2025, August 28). Organic agriculture and certified retail market development in Germany. BMEL Government Reports.
- [9] Association of American Feed Control Officials (AAFCO). (2025, January 10). Official publication: Guidelines on pet food label claims and ingredient standards. AAFCO Manuals.
- [10] Organic Trade Association. (2025, May 22). Organic industry survey: Market overview and organic pet food growth trajectories. OTA Economic Reports.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the organic pet food market in 2026 and what is forecast for 2036?
- Which certification and consumer pressures support organic pet food demand?
- Why does dry food lead the food type category?
- Why do dogs lead the pet type category?
- How do growth rates differ across the United States, UK, and Germany?
- Which companies supply relevant organic and premium pet food categories?
- What limits organic pet food adoption or supplier switching?
- What should buyers assess before selecting an organic pet food supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Pet Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Pet Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Pet Type, 2026 to 2036
- Dogs
- Cats
- Y-o-Y Growth Trend Analysis By Pet Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Pet Type, 2026 to 2036
- Global Market Analysis and Forecast, By Food Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Food Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Food Type, 2026 to 2036
- Dry Food
- Wet Food
- Frozen Food
- Y-o-Y Growth Trend Analysis By Food Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Food Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Pet Type
- By Food Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pet Type
- By Food Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- By Pet Type
- By Food Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pet Type
- By Food Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- France
- Italy
- Spain
- By Pet Type
- By Food Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pet Type
- By Food Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Hungary
- By Pet Type
- By Food Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pet Type
- By Food Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Pet Type
- By Food Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pet Type
- By Food Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Pet Type
- By Food Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pet Type
- By Food Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- By Pet Type
- By Food Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pet Type
- By Food Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Pet Type
- By Food Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Pet Type
- By Food Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nestle Purina
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Mars Petcare
- Primal Pet Foods
- Hill’s Pet Nutrition
- PetGuard Holdings
- Marsapet
- Nestle Purina
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Pet Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Food Type, 2021 to 2036
- Table 4: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Pet Type, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Food Type, 2021 to 2036
- Table 7: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: Latin America Market Value (USD Billion) Forecast by Pet Type, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Food Type, 2021 to 2036
- Table 10: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 11: Western Europe Market Value (USD Billion) Forecast by Pet Type, 2021 to 2036
- Table 12: Western Europe Market Value (USD Billion) Forecast by Food Type, 2021 to 2036
- Table 13: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Eastern Europe Market Value (USD Billion) Forecast by Pet Type, 2021 to 2036
- Table 15: Eastern Europe Market Value (USD Billion) Forecast by Food Type, 2021 to 2036
- Table 16: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Billion) Forecast by Pet Type, 2021 to 2036
- Table 18: East Asia Market Value (USD Billion) Forecast by Food Type, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Billion) Forecast by Pet Type, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Billion) Forecast by Food Type, 2021 to 2036
- Table 22: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 23: Middle East and Africa Market Value (USD Billion) Forecast by Pet Type, 2021 to 2036
- Table 24: Middle East and Africa Market Value (USD Billion) Forecast by Food Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Pet Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Pet Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Pet Type
- Figure 6: Global Market Value Share and BPS Analysis by Food Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Food Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Food Type
- Figure 9: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Pet Type, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Pet Type, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Pet Type
- Figure 23: North America Market Value Share and BPS Analysis by Food Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Food Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Food Type
- Figure 26: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: Latin America Market Value Share and BPS Analysis by Pet Type, 2026 and 2036
- Figure 28: Latin America Market Y-o-Y Growth Comparison by Pet Type, 2026-2036
- Figure 29: Latin America Market Attractiveness Analysis by Pet Type
- Figure 30: Latin America Market Value Share and BPS Analysis by Food Type, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by Food Type, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by Food Type
- Figure 33: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Western Europe Market Value Share and BPS Analysis by Pet Type, 2026 and 2036
- Figure 35: Western Europe Market Y-o-Y Growth Comparison by Pet Type, 2026-2036
- Figure 36: Western Europe Market Attractiveness Analysis by Pet Type
- Figure 37: Western Europe Market Value Share and BPS Analysis by Food Type, 2026 and 2036
- Figure 38: Western Europe Market Y-o-Y Growth Comparison by Food Type, 2026-2036
- Figure 39: Western Europe Market Attractiveness Analysis by Food Type
- Figure 40: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Eastern Europe Market Value Share and BPS Analysis by Pet Type, 2026 and 2036
- Figure 42: Eastern Europe Market Y-o-Y Growth Comparison by Pet Type, 2026-2036
- Figure 43: Eastern Europe Market Attractiveness Analysis by Pet Type
- Figure 44: Eastern Europe Market Value Share and BPS Analysis by Food Type, 2026 and 2036
- Figure 45: Eastern Europe Market Y-o-Y Growth Comparison by Food Type, 2026-2036
- Figure 46: Eastern Europe Market Attractiveness Analysis by Food Type
- Figure 47: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 48: East Asia Market Value Share and BPS Analysis by Pet Type, 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by Pet Type, 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by Pet Type
- Figure 51: East Asia Market Value Share and BPS Analysis by Food Type, 2026 and 2036
- Figure 52: East Asia Market Y-o-Y Growth Comparison by Food Type, 2026-2036
- Figure 53: East Asia Market Attractiveness Analysis by Food Type
- Figure 54: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 55: South Asia and Pacific Market Value Share and BPS Analysis by Pet Type, 2026 and 2036
- Figure 56: South Asia and Pacific Market Y-o-Y Growth Comparison by Pet Type, 2026-2036
- Figure 57: South Asia and Pacific Market Attractiveness Analysis by Pet Type
- Figure 58: South Asia and Pacific Market Value Share and BPS Analysis by Food Type, 2026 and 2036
- Figure 59: South Asia and Pacific Market Y-o-Y Growth Comparison by Food Type, 2026-2036
- Figure 60: South Asia and Pacific Market Attractiveness Analysis by Food Type
- Figure 61: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East and Africa Market Value Share and BPS Analysis by Pet Type, 2026 and 2036
- Figure 63: Middle East and Africa Market Y-o-Y Growth Comparison by Pet Type, 2026-2036
- Figure 64: Middle East and Africa Market Attractiveness Analysis by Pet Type
- Figure 65: Middle East and Africa Market Value Share and BPS Analysis by Food Type, 2026 and 2036
- Figure 66: Middle East and Africa Market Y-o-Y Growth Comparison by Food Type, 2026-2036
- Figure 67: Middle East and Africa Market Attractiveness Analysis by Food Type
- Figure 68: Global Market - Tier Structure Analysis
- Figure 69: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the organic pet food market in 2026, and what is forecast for 2036?
Future Market Insights estimates the market at USD 2.7 billion in 2026. It is projected to reach USD 5.7 billion by 2036.
What is the CAGR from 2026 to 2036?
As per FMI, the market is projected to expand at a 7.8% CAGR over the assessment period, driven by pet humanization and certified ingredient transparency.
Which food type leads the market?
Future Market Insights projects that dry food will hold 53.0% of food type revenue in 2026, supported by convenient ambient storage, wide omnichannel distribution, and routine feeding practices.
Which pet type leads the market?
Dogs are projected to account for 37.0% share in 2026, supported by feeding volume and premium health spending.
Which country has the strongest listed growth outlook?
The United States is projected to register a leading 7.4% CAGR from 2026 to 2036.
Who are the key players?
Key participants include Nestle Purina, Mars Petcare, Primal Pet Foods, Hill’s Pet Nutrition, PetGuard Holdings, and Marsapet.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
