
- Market Size (2026)
- USD 303.5 Mn
- Forecast (2036)
- USD 893.3 Mn
- CAGR (2026 to 2036)
- 11.4%
How Big Is the Liquid Sourdough Market in 2026?
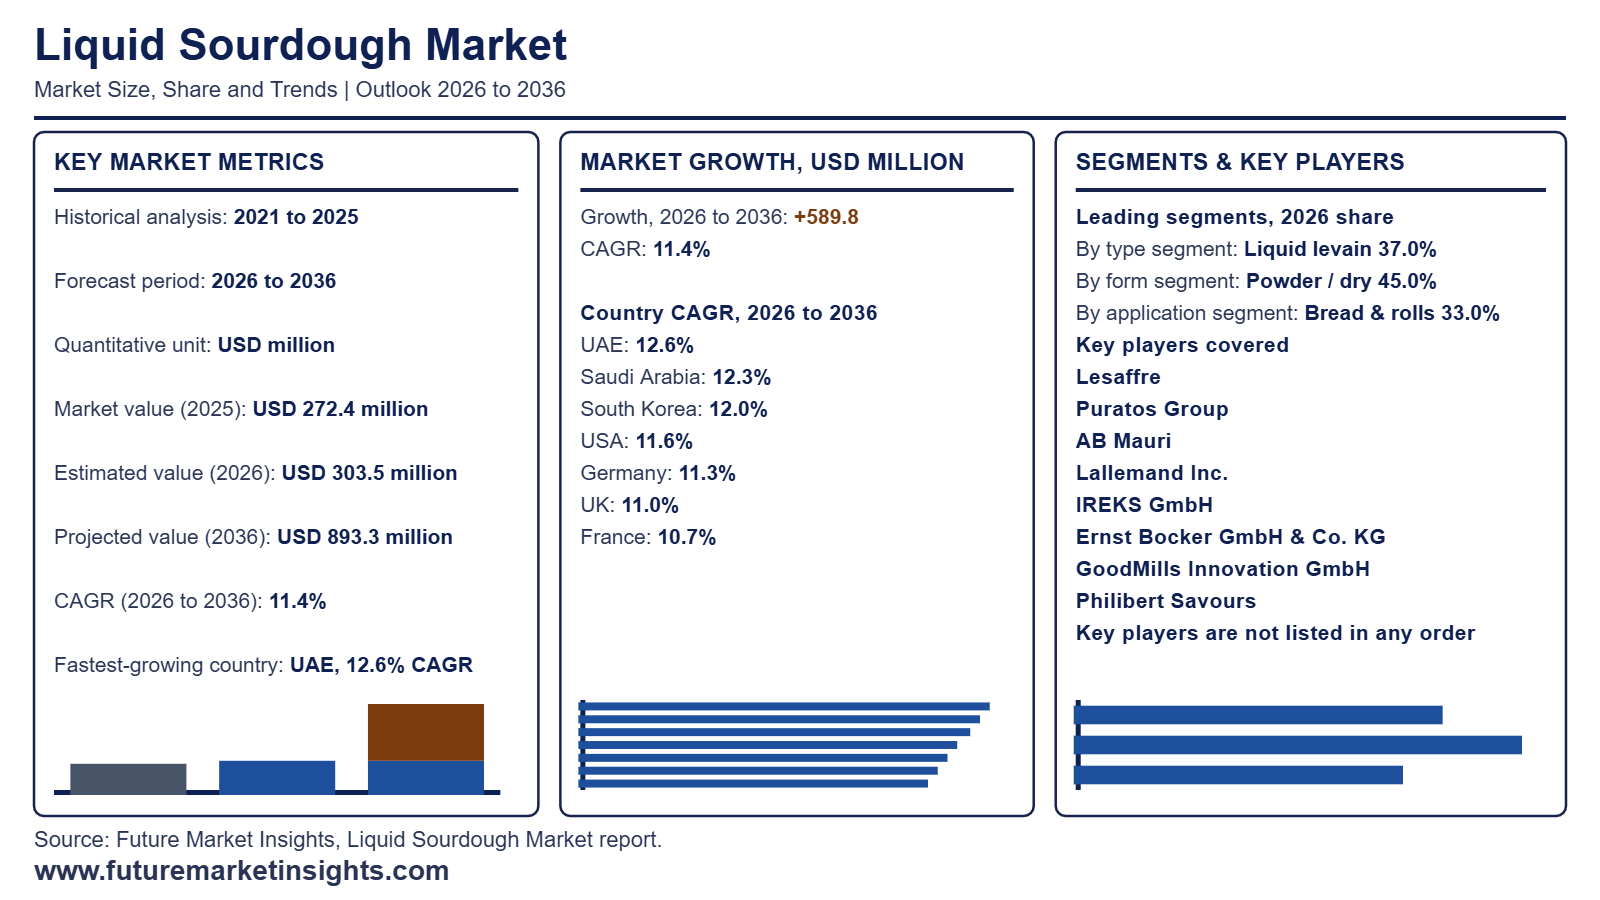
Global liquid sourdough market valuation was valued at USD 272.4 million in 2025 to USD 303.5 million in 2026 and is estimated to reach USD 893.3 million by 2036, expanding at an 11.4% CAGR during the forecast period. As per FMI, the category will generate USD 589.8 million in incremental dollar opportunity over the decade as commercial bakeries standardize fermentation flavor.
| Market Metric | Valuation / Share / Forecast Benchmark |
|---|---|
| 2025 Market Size (Historical) | USD 272.4 million |
| 2026 Market Size (Estimated) | USD 303.5 million |
| 2036 Market Size (Projected) | USD 893.3 million |
| Compound Annual Growth Rate (2026 to 2036) | 11.4% CAGR |
| Incremental Dollar Opportunity (2026 to 2036) | USD 589.8 million |
| Dominant Type Segment (2026 Share) | Liquid levain (37.0% share in 2026) |
| Dominant Form Segment (2026 Share) | Powder / dry (45.0% share in 2026) |
| Dominant Application Segment (2026 Share) | Bread & rolls (33.0% share in 2026) |
| Dominant Claim & Sales Channel (2026 Share) | Conventional (46.0% share) | Direct to industrial bakeries (52.0% share) |
| Largest Country Markets (2026 Global Share) | USA (24.0%), Germany (18.0%), France (14.0%), UK (10.0%) |
| Fastest-Growing Country Markets (2026 to 2036) | UAE (12.6% CAGR), Saudi Arabia (12.3% CAGR), South Korea (12.0% CAGR) |
| Leading Tier-1 Companies | Lesaffre, Puratos Group, AB Mauri, Lallemand Inc., IREKS GmbH, Ernst Bocker GmbH & Co. KG, GoodMills Innovation GmbH, Philibert Savours |
Source: Future Market Insights analysis of the liquid sourdough market, 2026.
This Report Answers
- How large the liquid sourdough market is in 2026 and what it reaches by 2036
- Which type, form and application segments lead in 2026
- What is driving demand and what is holding the category back
- Which countries grow fastest between 2026 and 2036
- What Lesaffre and other leading players have launched
- How the liquid sourdough market is defined, segmented and measured
Executive Market Overview
Automated industrial bakeries pump live or pasteurized liquid sourdough directly into continuous dough kneaders, guaranteeing consistent lactic-to-acetic acid ratios across large-scale sandwich bread and artisan loaf production. crumb acidity across high-speed bread lines. FMI finds that plant managers are shifting procurement toward pumpable liquid cultures and stabilized cereal ferments owing to skilled baker shortages and the high cost of floor fermentation tanks. Rather than dedicating 16 to 24 hours of tank residence time to spontaneous dough acidification, commercial plants meter standardized sourdough ingredients directly into spiral and continuous mixers. In 2026, Associated British Foods (January 2026) confirmed that AB Mauri commissioned the United Kingdom's largest dedicated liquid sourdough manufacturing facility to supply industrial bread makers with tailored fermented grain profiles. Meanwhile, milling data from the USDA National Agricultural Statistics Service (May 2026) shows that United States mills ground 907 million bushels of wheat to produce 419 million hundredweight of wheat flour in 2025, sustaining a massive industrial baking base that pairs liquid starters with whole-wheat flour for premium retail loaves.
Pricing power across fermentation ingredient contracts depends on proving microbial stability and consistent lactic-to-acetic acid ratios under changing flour harvest conditions. In FMI's view, ingredient suppliers lift unit margins by bundling active starter cultures with technical application testing and bakery enzymes that keep crumb softness intact across extended supermarket shelf life. In June 2026, Puratos Group (June 2026) opened its dedicated Flour Competence Center in Groot-Bijgaarden, Belgium, equipping baking technologists with analytical tools to calibrate sourdough formulations and bread improvers against crop-year flour fluctuations. Market sizing covers commercially sold fermented sourdough preparations, active liquid levain starters, paste ferments, and in-scope dried sourdough formats supplied to B2B bakery buyers, while excluding finished baked goods, ordinary baker's yeast, standalone chemical leavening agents, and unfermented acidulants.
Analyst Perspective
"Liquid sourdough suppliers will expand contract value faster than raw flour volume because industrial bakeries are paying for pumpable, pre-acidified starter systems that eliminate 18-hour in-house fermentation cycles. The primary commercial risk is cold-chain pH drift during summer distribution, which can force mid-sized plants to fall back on ambient dry ferments."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights (FMI)
Key Market Trends & Insights
- Pumpable Liquid Levain Systems Replace In-House Fermentation Tanks:Industrial bread manufacturers are decommissioning labor-intensive multi-stage fermentation rooms in favor of chilled bulk liquid levain totes connected directly to automated dough-dosing skids. FMI observes that automated liquid dosing cuts batch changeover times while preserving authentic lactic and acetic organic acid profiles required for artisan-style hearth loaves and European sourdough specialties. Microbiological research published by MDPI Fermentation (August 2025) demonstrated that selected starter-based Type II liquid sourdoughs formulated at 60% starter inoculation and incubated at 30 degrees Celsius for 24 hours delivered superior bio-preservation and mold inhibition in commercial bread loaves.
- Alternative Legume and Ancient Grain Substrates Expand Formulation Scope:Bakery product developers are moving beyond standard wheat and rye starters by fermenting high-protein pulse and buckwheat flours flours to boost amino acid density and roasted crust notes. FMI believes substrate diversification allows commercial bakeries to command higher retail prices in grocery aisles in combination with fermented and cultured flour blends. Applied fermentation trials released by Lesaffre (February 2026) evaluated two commercial LIVENDO starter cultures across eight distinct flour substrates, including chickpea and hulless barley, confirming that tailored starter strains prevent off-flavors in high-protein legume breads.
- Strain-Specific Volatile Profiling Standardizes Sensory Benchmarks:Large grocery chains and quick-service restaurant buyers now specify exact titratable acidity and volatile aroma thresholds before approving a sourdough supplier for national rollouts. FMI's analysis indicates that suppliers using gas-chromatography sensory mapping win multi-year industrial contracts attributed to lower batch rejection rates when blending starters with sourdough flavor systems. Sensory mapping published by Lesaffre (March 2026) identified specific non-volatile and volatile aromatic signatures generated by yeast-bacteria consortia, enabling industrial bakers to dial in fruity or roasted cereal notes on standard proof-and-bake lines.
What Are the Main Drivers, Restraints, and Opportunities?
Labor-saving fermentation automation and sodium-reduction reformulation drive core ingredient orders, while cold-chain viability drift and plant qualification hurdles restrain rapid switching, leaving pulse-flour co-fermentation and clean-label bio-preservation as primary margin opportunities through 2036.
Driver: Bakery Labor Shortages and Sodium-Reduction Reformulation Mandates
Commercial bakeries are adopting standardized liquid sourdough preparations to maintain loaf flavor and crumb elasticity while cutting skilled night-shift fermentation labor and meeting national salt-reduction targets. FMI finds that organic acids and glutamate compounds produced during controlled lactic fermentation compensate for reduced salt levels in staple pan breads and dough conditioners programs. Experimental breadmaking data published by MDPI Foods (February 2025) confirmed that liquid sourdough fermented with Lactiplantibacillus plantarum ITM21B for 14 hours at 37 degrees Celsius at 5 log CFU per gram enriched bioactive polyphenols and organic acids in salt-reduced bread, with Firmicutes accounting for 97.2% of the active microbial population.
Restraint: Cold-Chain Acidity Drift and Multi-Week Plant Qualification Cycles
Active liquid sourdough starters remain biologically sensitive to temperature excursions during tanker or IBC tote transit, which can shift pH levels, depress yeast gas production, and spoil entire dough batches. FMI notes that industrial bakeries must validate cold-storage holding windows, pump shear tolerance, and cross-batch titratable acidity before converting a plant trial into a recurring supply contract. Laboratory stability trials published in theInternational Journal of Food Microbiology (January 2025) demonstrated that fermentation length and flour composition directly govern cell survival and organic acid drift in liquid sourdough starters during refrigerated storage, forcing bakeries without chilled dosing tanks to retain dry alternatives.
Opportunity: Synergistic Yeast-Bacteria Consortia and Clean-Label Shelf-Life Extension
Retailers eliminating synthetic calcium propionate from packaged sliced bread are creating high-margin demand for liquid sourdoughs engineered with antifungal lactic acid bacteria and propionate-producing cultures. FMI expects fermentation suppliers that co-develop custom starter blends with clean-label ingredients to capture premium supply agreements across Europe and Asia-Pacific. Microbiological research released by Lesaffre (February 2026) on synthetic sourdough ecosystems showed how targeted metabolic cross-feeding between Saccharomyces cerevisiae and heterofermentative lactic acid bacteria stabilizes dough leavening speed and extends mold-free shelf life in packaged bakery items.
How Is the Liquid Sourdough Market Segmented?
Liquid Sourdough Market is segmented by Type, Form, Application, Claim, Sales Channel, and Region. Forecast period from 2026 to 2036.
| Segmentation Axis | Dominant Sub-Segment (2026 Share) | Other Segment Combined (Remainder) | Total Market Share & Sub-Segments |
|---|---|---|---|
| Type | Liquid levain (37.0%) | Other Segment Combined (63.0%) | Total (100.0%): Liquid levain, Dried sourdough, Ready starters, Flavor concentrates |
| Form | Powder / dry (45.0%) | Other Segment Combined (55.0%) | Total (100.0%): Powder / dry, Liquid, Paste / semi-solid, Granules / pieces |
| Application | Bread & rolls (33.0%) | Other Segment Combined (67.0%) | Total (100.0%): Bread & rolls, Cakes & muffins, Biscuits & cookies, Viennoiserie & pastry, Other bakery & snacks |
| Claim | Conventional (46.0%) | Other Segment Combined (54.0%) | Total (100.0%): Conventional, Clean label, Organic, Non-GMO / identity preserved |
| Sales Channel | Direct to industrial bakeries (52.0%) | Other Segment Combined (48.0%) | Total (100.0%): Direct to industrial bakeries, Ingredient distributors, Foodservice & artisan supply, Online B2B |
Source: Future Market Insights analysis of the liquid sourdough market, 2026.
Why Does Liquid levain Anchor the Type Category?
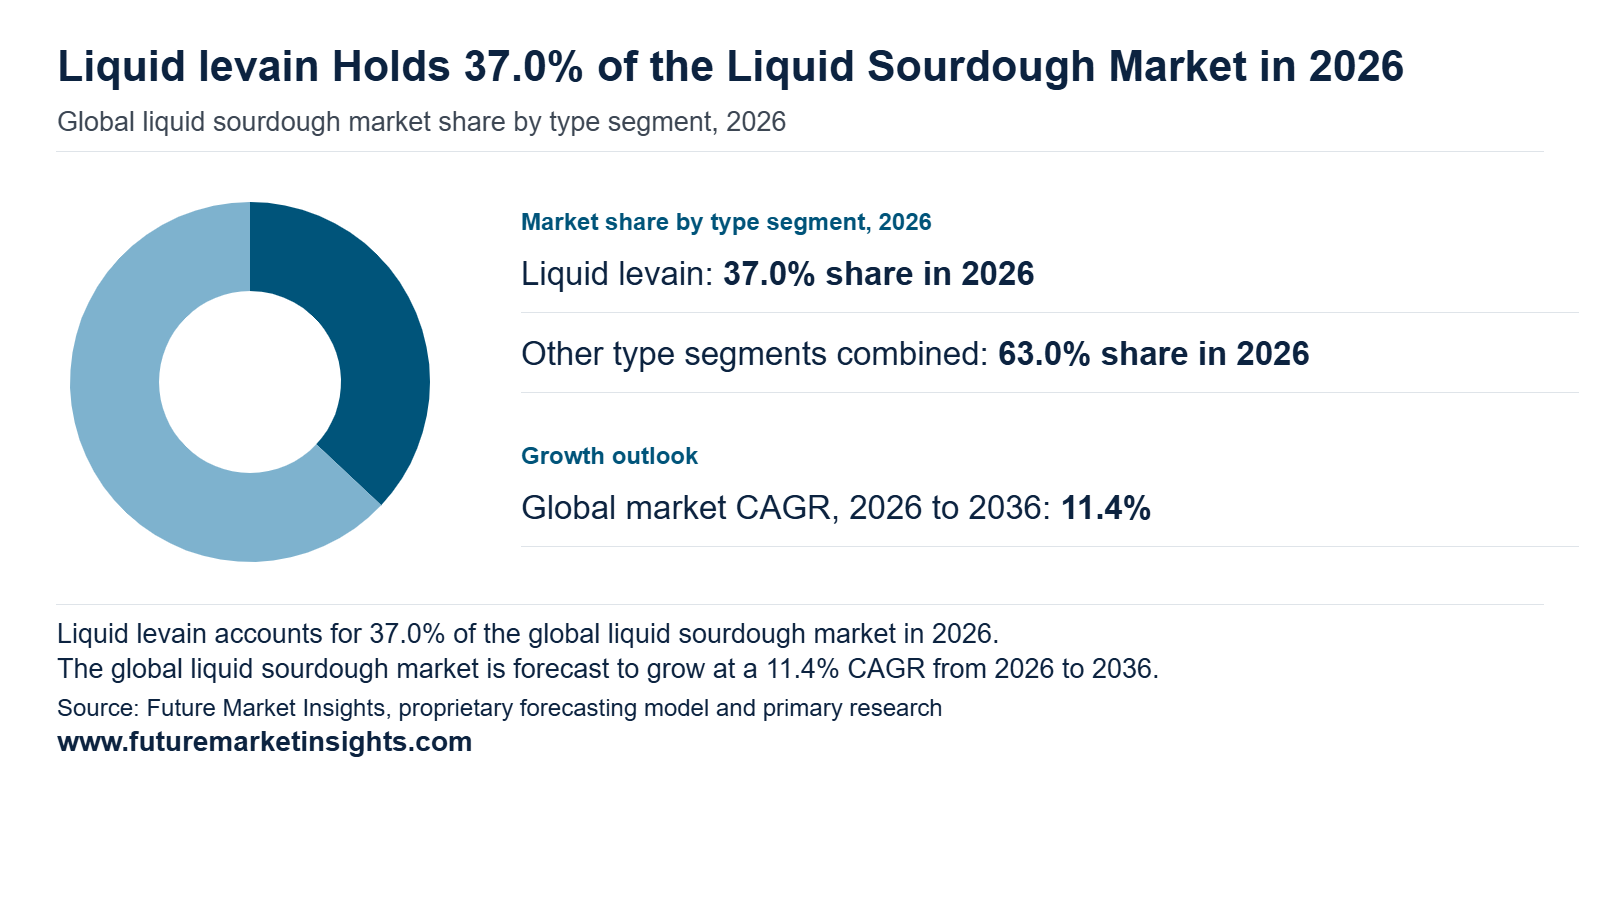
Liquid levain varieties secure a leading 37.0% share of Type revenue in 2026, favored by commercial bakeries for immediate dispersion in high-hydration doughs and active live bacterial cultures combined with bakery ingredients. In January 2026, Lallemand Baking (January 2026) highlighted its Florapan fermentation cultures and baking application support at BakingTECH 2026 (February 16 to 18, 2026), helping commercial bakeries standardize active liquid levain acidification.
What Sustains Powder / dry Preference Within the Form Category?
Powder and dry sourdough formats capture 45.0% of Form revenue in 2026, leading processing demand through ambient room-temperature storage, 12-month stability, and compatibility with automated bulk micro-dosing systems. Multi-line bakeries frequently run dry cereal ferments on standard pan-bread lines while reserving chilled liquid totes for flagship artisan SKUs. Preservation research published by MDPI Foods (July 2025) on Type I sourdough preservation strategies confirmed that optimized spray-drying and freeze-drying protocols allow ingredient suppliers to stabilize organic acid titers for export distribution.
How Does Bread & rolls Shape Application Demand?
Bread & rolls lines contribute 33.0% of the Application segment in 2026, serving as the main commercial driver as industrial bakeries dose liquid sourdough directly into high-volume dough troughs. In FMI's view, Bread & rolls anchors commercial application volume driven by high-frequency daily production runs where buyers specify sourdough inputs to improve dough machinability and natural mold resistance mold resistance. Pizza pizza crusts and hearth rolls rolls provide predictable repeat order volumes that justify plant-scale dosing qualification in combination with bakery ingredients and flour improvers. In February 2026, Lallemand Baking (February 2026) introduced clean-label sourdough mixes and dough relaxers for Pizza Expo 2026 (March 24 to 26, 2026) to reduce dough snap-back and improve freeze-thaw stability in commercial crust and roll lines.
Why Does Conventional Retain the Claim Lead?
Conventional sourdough preparations account for 46.0% of Claim sales in 2026, dominating commercial bakery contracts through stable flour feedstock supplies and favorable batch economics. While clean-label and organic claims are expanding in premium retail tiers, conventional ferments allow industrial bakers to hit tight unit cost targets while still declaring authentic sourdough on ingredient panels. Regulatory compliance rules issued by the U.S. Food and Drug Administration (May 2025) under Compliance Program 7321.005 enforce strict allergen and fermented gluten-free threshold verification below 20 parts per million, reinforcing rigorous specification checks across all claim tiers.
Why Do Direct to industrial bakeries Relationships Lead Sales Channel?
Direct contracts with industrial bakeries generate 52.0% of Sales Channel sales in 2026, supported by collaborative on-site recipe development, metered pump integration, and bulk tank replenishment. Before signing annual supply contracts, plant engineering teams work directly with fermentation suppliers to integrate metered peristaltic pumps and CIP sanitation cycles. In May 2025, DSM-Firmenich (May 2025) inaugurated its Princeton Baking Innovation Center in New Jersey to conduct direct pilot-scale dough testing and collaborative recipe validation with industrial bakery accounts.
Regional & Country Outlook
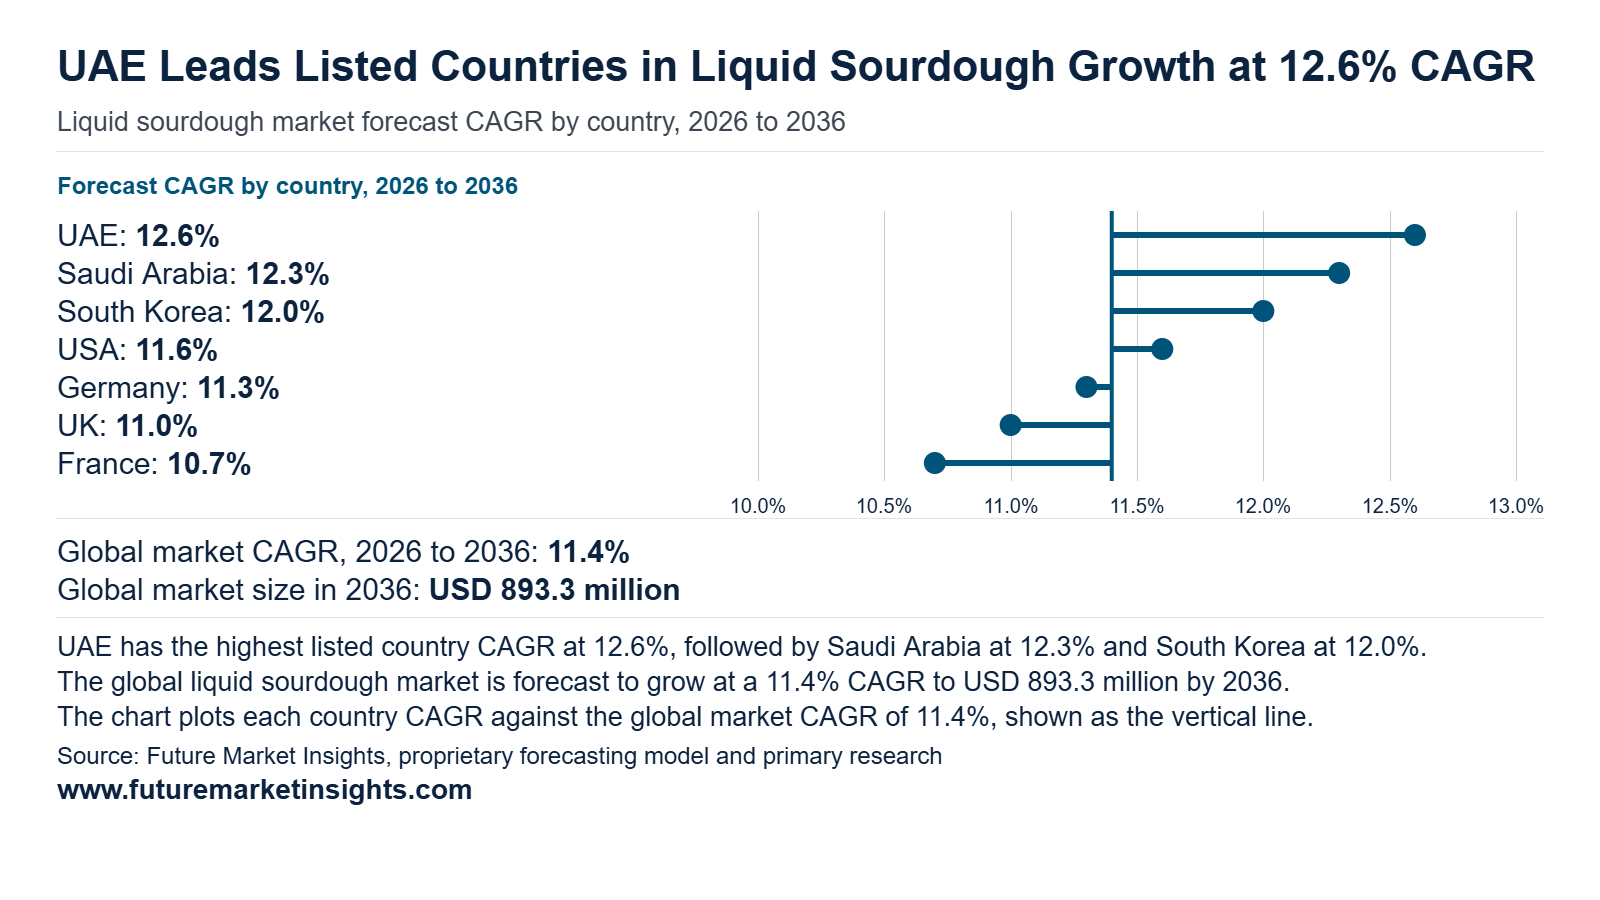
Western Europe and North America anchor current global liquid sourdough revenue in 2026, whereas GCC and East Asian markets record the fastest percentage growth through 2036 as modern retail bakeries and hotel foodservice chains scale automated bread production. FMI projects the eight core countries profiled below to account for92.0% of global market value in 2026 (USD 279.2 million), expanding to USD 818.2 million by 2036. Across the United States, represents the single largest national market at 24.0% global share in 2026 (USD 72.8 million), followed by Germany at 18.0% (USD 54.6 million) and France at 14.0% (USD 42.5 million). Meanwhile, the UAE (12.6% CAGR) and Saudi Arabia (12.3% CAGR) lead growth velocity as Gulf food processors adopt climate-controlled fermentation systems and ASEAN sourdough and Middle Eastern bakery networks modernize.
| Country | 2026 Revenue | 2036 Revenue | 10-Year Addition | 2026 to 2036 CAGR | Global Share (2026 -> 2036) |
|---|---|---|---|---|---|
| UAE | USD 12.1 million | USD 39.7 million | +USD 27.6 million | 12.6% | 4.0% -> 4.4% |
| Saudi Arabia | USD 15.2 million | USD 48.5 million | +USD 33.3 million | 12.3% | 5.0% -> 5.4% |
| South Korea | USD 24.3 million | USD 75.5 million | +USD 51.2 million | 12.0% | 8.0% -> 8.5% |
| USA | USD 72.8 million | USD 218.1 million | +USD 145.3 million | 11.6% | 24.0% -> 24.4% |
| Germany | USD 54.6 million | USD 159.3 million | +USD 104.7 million | 11.3% | 18.0% -> 17.8% |
| UK | USD 30.4 million | USD 86.3 million | +USD 55.9 million | 11.0% | 10.0% -> 9.7% |
| France | USD 42.5 million | USD 117.4 million | +USD 74.9 million | 10.7% | 14.0% -> 13.1% |
| Japan | USD 27.3 million | USD 73.4 million | +USD 46.1 million | 10.4% | 9.0% -> 8.2% |
Source: Future Market Insights analysis of the liquid sourdough market, 2026.
UAE
Demand for liquid sourdough in UAE is projected to rise from USD 12.1 million in 2026 to USD 39.7 million by 2036, advancing at a 12.6% CAGR and adding USD 27.6 million in new revenue. FMI finds that commercial bakeries and hospitality commissaries in Dubai and Abu Dhabi prefer ready-to-use liquid and paste starters owing to high ambient heat and full reliance on imported milling grains that complicate scratch mother-dough maintenance. Trade figures published by the USDA Foreign Agricultural Service (July 2026) confirm that over 570 food and beverage processors in the UAE produce 5.96 million metric tons of food annually while foodservice outlets grew 2.0% to reach 17,751 locations in 2025. FMI expects cold-chain distributor partnerships and hotel bakery expansion to sustain rapid contract orders across the UAE through 2036.
Saudi Arabia
Buyer adoption of liquid sourdough across Saudi Arabia is estimated to expand from USD 15.2 million in 2026 to USD 48.5 million by 2036, spurred by a 12.3% CAGR and generating USD 33.3 million in commercial expansion. In FMI's view, mandatory menu-nutrition transparency and sodium-reduction rules are accelerating bakery reformulation toward fermented sourdough flavor systems that preserve bread taste at lower salt dosages. According to the Saudi Food and Drug Authority (June 2025), foodservice establishments across the Kingdom have been legally required since July 1, 2025 to display high-sodium saltshaker warning icons on physical and digital menus in combination with WHO guidance capping adult daily intake at 5 grams of salt. FMI projects that institutional bread plants and quick-service bakery suppliers reformulating recipes to avoid high-sodium labels will drive strong liquid sourdough adoption in Saudi Arabia through 2036.
South Korea
Liquid sourdough industry in South Korea is set to scale from USD 24.3 million in 2026 to USD 75.5 million by 2036, driven by a 12.0% CAGR and adding USD 51.2 million in incremental market value. FMI observes that South Korean industrial bakeries and cafe bakery chains are testing strain-specific liquid starters to improve crumb elasticity and fermentation aroma in hybrid wheat and domestic rice-flour breads. Official program data from the Ministry of Agriculture, Food and Rural Affairs, South Korea (April 2025) shows that approximately 100 commercial and artisan bakeries participated in the national floury-rice recipe development competition in April 2025 to commercialize non-wheat baked goods. FMI believes ongoing government backing for domestic grain baking and premium retail cafe menus will support sustained liquid starter demand across South Korea through 2036.
USA
Sales of liquid sourdough throughout USA are projected to increase from USD 72.8 million in 2026 to USD 218.1 million by 2036, progressing at a 11.6% CAGR and creating USD 145.3 million in additional revenue. FMI's analysis indicates that large North American wholesale bakeries are converting pan-bread and pizza-crust lines lines to automated liquid levain dosing attributed to consumer demand for clean-label fermented bread without artificial preservatives. Quarterly milling statistics from the USDA National Agricultural Statistics Service (August 2026) confirm that United States whole wheat flour output reached 4.21 million hundredweight in the second quarter of 2026, up 1.0% from the second quarter of 2025. In FMI's view, supermarket in-store bakery upgrades and frozen dough manufacturing will anchor long-term bulk liquid sourdough contracts across the USA through 2036.
Germany
Consumption of liquid sourdough across Germany is estimated to climb from USD 54.6 million in 2026 to USD 159.3 million by 2036, reflecting a 11.3% CAGR and contributing USD 104.7 million over the forecast decade. FMI believes ongoing consolidation among German craft bakeries into larger multi-branch baking plants is shifting demand from manual three-stage rye sours to standardized pumpable liquid starters that lower night-shift labor costs. Industry census figures from the Central Association of the German Bakers' Trade (April 2025) and updated Zentralverband des Deutschen Baeckerhandwerks (January 2026) records show that German craft bakery enterprises consolidated from 8,912 businesses in 2024 to 8,659 businesses in 2025, while average staffing rose to 26.8 employees per business. FMI expects larger regional baking centers to expand automated liquid sourdough dosing across Germany through 2036.
UK
Revenue generated by liquid sourdough suppliers in UK is forecast to expand from USD 30.4 million in 2026 to USD 86.3 million by 2036, anchored by a 11.0% CAGR and generating USD 55.9 million in new category sales. FMI finds that British plant bakeries and retail sandwich-bread producers are reformulating standard loaves with active and pasteurized liquid sourdoughs due to rising supermarket competition in premium wrapped bread and updated national flour composition rules. Regulatory guidance published by the UK Department for Environment, Food and Rural Affairs (April 2025) sets updated bread and flour labeling and fortification standards coming into force on 13 December 2026, requiring 0.250 milligrams of folic acid and at least 2.10 milligrams of iron per 100 grams of common wheat flour. FMI anticipates domestic liquid fermentation capacity additions to accelerate UK bakery contract conversion through 2036.
France
Buyer procurement of liquid sourdough throughout France is tracking from USD 42.5 million in 2026 to USD 117.4 million by 2036, exhibiting a 10.7% CAGR and contributing USD 74.9 million to national market value. FMI observes that French industrial boulangeries and par-baked frozen baguette manufacturers rely on live liquid levain starters to meet strict legal pH thresholds for pain au levain while preserving taste under national salt-reduction pledges. Official monitoring published by the Ministere de l'Agriculture, de l'Agro-alimentaire et de la Souverainete alimentaire (June 2026) confirmed that the Observatoire de l'alimentation validated the May 2026 public-health assessment of progressive salt reductions across French bread categories through 2025. FMI projects that clean-label French bakery chains using active liquid starters to maintain aromatic intensity at lower salt levels will sustain steady order growth through 2036.
Japan
Demand for liquid sourdough in Japan is projected to rise from USD 27.3 million in 2026 to USD 73.4 million by 2036, advancing at a 10.4% CAGR and adding USD 46.1 million in new revenue. In FMI's view, Japanese wholesale bakeries and convenience-store sandwich suppliers are adopting mild, lactic-dominant liquid sourdoughs to improve crumb softness and moisture retention without overpowering delicate wheat aromas. Trade and industry data from the USDA Foreign Agricultural Service (April 2026) shows that supermarkets capture 45.0% and convenience stores account for 28.0% of retail food distribution in Japan, while hotel and restaurant foodservice demand rose 16.0% in 2025. FMI expects high-hydration shokupan and European-style cafe bread launches to drive steady liquid starter procurement across Japan through 2036.
Competitive Environment and Notable Companies
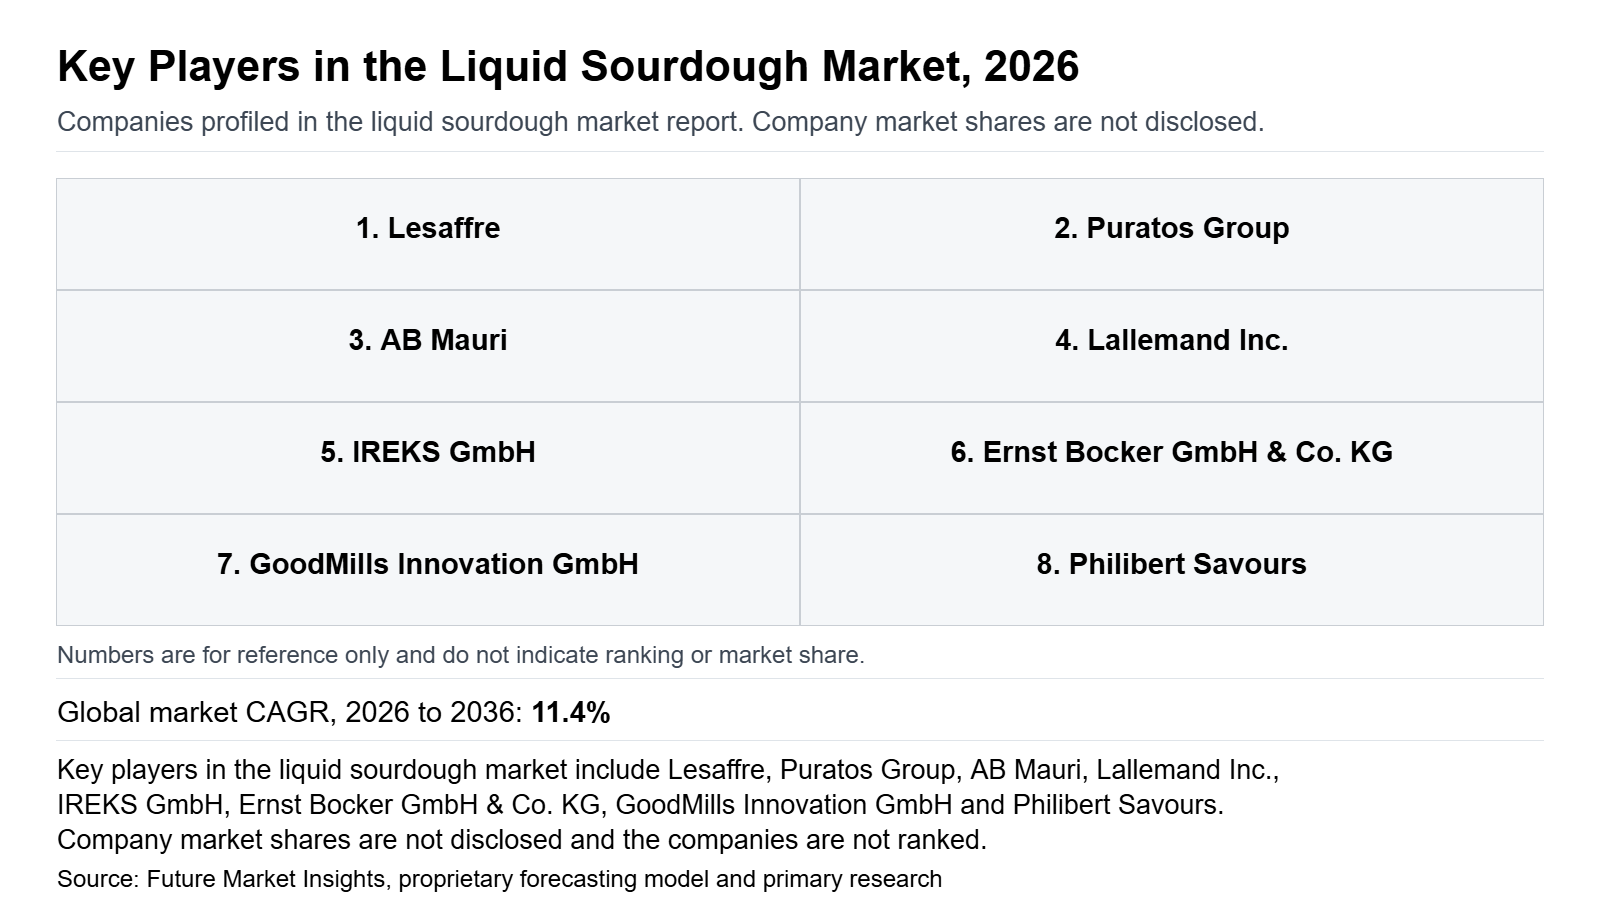
Competition in the global liquid sourdough market centers on fermentation-culture specialists and integrated bakery-ingredient manufacturers that combine proprietary strain banks with industrial dosing and flour-testing infrastructure. Profiled companies include Lesaffre, Puratos Group, AB Mauri, Lallemand Inc., IREKS GmbH, Ernst Bocker GmbH & Co. KG, GoodMills Innovation GmbH, and Philibert Savours. Rather than competing on commodity acidulant price, Tier-1 suppliers differentiate through starter culture biodiversity, pumpable liquid stability, and application laboratories that qualify recipes on customer lines in combination withorganic yeast and specialty grain blends.
How Are Companies Positioned in the Liquid Sourdough Market?
Market leaders segment into global fermentation multinationals and European pure-play sourdough specialists. Lesaffre marketsLivendo liquid starters and microbial consortia research, Puratos Group supplies Sapore liquid and devitalized sourdoughs anchored by its March 2026 agreement to acquire Dawn Foods (Puratos Group, March 2026), and AB Mauri operates dedicated UK liquid sourdough manufacturing (Associated British Foods, January 2026). Meanwhile, Ernst Bocker GmbH & Co. KG, IREKS GmbH, GoodMills Innovation GmbH, and Philibert Savours specialize in clean-label wheat and rye sourdough systems sourdough systems for European and export bakeries.
What Matters When a Buyer Selects a Liquid Sourdough Supplier?
Industrial bakery procurement and quality-assurance teams evaluate suppliers on batch-to-batch titratable acidity (TTA) consistency, refrigerated shelf-life stability, viscosity compatibility with peristaltic dosing pumps, and rapid technical troubleshooting when new wheat harvests alter dough rheology. Asdemonstrated when Puratos Group (June 2026) opened its Flour Competence Center in Belgium in June 2026, suppliers that test customer flour lots directly against starter acidification curves shorten factory qualification timelines and reduce dough waste.
Which Capabilities Distinguish Product Offers?
Product portfolios diverge across live fermentative leavening power versus devitalized flavor-and-acidity standardization, substrate diversity, and clean-label certification. Lallemand Inc. suppliesFlorapan selected lactic acid bacteria and yeast cultures for controlled tank fermentation, whereas Philibert Savours offers Phil Levain active liquid sourdoughs and Perspective 100% natural spontaneous wheat sourdough (Philibert Savours, October 2026). IREKS GmbH and GoodMills Innovation GmbH differentiate by combining sprouted grains, wholemeal oat sourdoughs, and pre-ferments tailored to high-speed bread and roll lines.
How Does Geographic Reach Affect Competition?
Because active liquid sourdoughs carry higher freight weight and cold-chain sensitivity than dry powders, local manufacturing and regional application centers determine competitive win rates. AB Mauri strengthened its domestic UK supply position by building the country's largest liquid sourdough plant (Associated British Foods, January 2026), while Lallemand Inc. expanded its European and international bakery formulation footprint through its July 2025 acquisition of AIT Ingredients (Lallemand Inc., July 2025).
| Verified Company Evidence (2025 to 2026) | Commercial Effect | Buyer Action |
|---|---|---|
| June 2026: Puratos Group opened its Flour Competence Center in Groot-Bijgaarden, Belgium to link flour variability analytics directly to sourdough and improver formulations (Puratos Group, June 2026). | Reduces batch failure rates when commercial bakeries switch wheat harvest lots on automated sourdough bread lines. | Request supplier flour-matching audits before locking in annual liquid sourdough dosing specifications. |
| March 2026: Puratos Group signed a definitive agreement to acquire Dawn Foods, combining Sapore sourdough technology with Dawn's North American and global bakery distribution (Puratos Group, March 2026). | Expands direct technical sales coverage for fermented bakery ingredients across sweet goods, bread, and foodservice accounts. | Evaluate bundled procurement contracts across sourdough starters, sweet bakery mixes, and technical line support. |
| January 2026: Associated British Foods documented the startup of AB Mauri's new UK liquid sourdough plant, the largest liquid sourdough manufacturing site in the UK (Associated British Foods, January 2026). | Shortens chilled lead times and custom grain-ferment co-development for British industrial bread and roll manufacturers. | Qualify domestic bulk liquid sourdough supply to reduce cross-border cold-chain freight exposure. |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
| Company | Core Positioning | Verified Activity & Source Attribution |
|---|---|---|
| Lesaffre | Active and devitalized liquid sourdoughs, starter cultures, and yeast-bacteria fermentation research (Livendo) | Published multi-substrate liquid sourdough trials across eight alternative grain and legume flours in February 2026 and aromatic signature mapping in March 2026 (Lesaffre, February & March 2026). |
| Puratos Group | Liquid and powdered sourdoughs, clean-label bread fermentation bases, and flour analytics (Sapore, O-tentic) | Entered definitive agreement to acquire Dawn Foods in March 2026 and opened its Belgium Flour Competence Center in June 2026 (Puratos Group, March & June 2026). |
| AB Mauri | Pumpable liquid sourdoughs, cereal ferments, and sprouted-grain sourdough pastes (Aromaferm, Acti Levain) | Commissioned the UK's largest dedicated liquid sourdough production plant to supply industrial bread makers (Associated British Foods, January 2026). |
| Lallemand Inc. | Selected lactic acid bacteria and yeast starter cultures for industrial sourdough fermentation (Florapan) | Acquired European bakery ingredients specialist AIT Ingredients in July 2025 and showcased clean-label sourdough solutions at Pizza Expo 2026 in February 2026 (Lallemand Inc., July 2025 & February 2026). |
| IREKS GmbH | Ready-to-use liquid and dried wheat, rye, spelt, and wholemeal oat sourdoughs | Presented wholemeal oat sourdough and Craft Master durum fermentation concepts for commercial bakers at iba 2025 (IREKS GmbH, May 2025). |
| Ernst Bocker GmbH & Co. KG | Pure-culture starter sourdoughs, pumpable liquid sourdoughs, and gluten-free fermented baking ingredients (Bocker Reinzucht-Sauerteig) | Expanded fifth-generation executive leadership in 2026 and showcased clean-label vegan and GMO-free liquid sourdough systems for Südback and Fi Europe 2026 (Ernst Bocker GmbH & Co. KG, October 2026). |
| GoodMills Innovation GmbH | Fermented grain pre-doughs, slow-milled baking ferments, and functional sourdough systems (Ferment'tic, Ferment'Arome) | Unveiled process-stable artisan baking and Ferment'tic fermentation solutions for südback 2026 in Hamburg (GoodMills Innovation GmbH, August 2026). |
| Philibert Savours | Artisanal active liquid sourdoughs and spontaneous wheat starters for French tradition breads (Phil Levain, Perspective) | Presented its patented Perspective 100% natural active sourdough and Phil Levain liquid sourdough range at SIAL Paris in October 2026 (Philibert Savours, October 2026). |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
Key takeaways
- Valued at USD 303.5 million in 2026, on course for USD 893.3 million by 2036.
- The decade adds USD 589.8 million in new value at an 11.4% CAGR.
- The type segment is led by Liquid levain at 37.0% of 2026 revenue.
- 45.0% of form revenue goes to Powder / dry in 2026.
- The UAE grows fastest at 12.6% CAGR, ahead of Saudi Arabia at 12.3%.
Liquid Sourdough Market Report Scope and Research Methodology
FMI sizes the global liquid sourdough market using a bottom-up and top-down triangulation model that reconciles commercial bakery flour consumption, industrial sourdough dosing rates (typically 2.0% to15.0% on flour weight), and average B2B contract selling prices across each region. Primary research incorporates structured interviews with industrial bakery R&D directors, fermentation microbiologists, plant procurement managers, and bulk dosing equipment engineers. Desk research cross-checks national flour milling records, food-labeling regulations, peer-reviewed fermentation stability studies, and verified corporate plant disclosures from 2025 and 2026. Revenue is counted strictly at the B2B ingredient sale level and excludes downstream retail bread sales, ordinary baker's yeast, standalone chemical leavening agents, and unfermented acidulants.
| Coverage Field | Report Scope |
|---|---|
| Market Breakdown | Type; Form; Application; Claim; Sales Channel; Region |
| Quantitative Units | USD million for revenue valuation; percentage (%) for segment share and 10-year CAGR |
| Base, Estimated & Forecast Years | 2025 (Historical); 2026 (Estimated); 2026 to 2036 (Forecast Period) |
| Market Definition | B2B revenue from commercially sold fermented liquid sourdough starters, liquid levain preparations, paste ferments, and in-scope dried sourdough ingredient systems supplied to commercial bakeries and foodservice operators. |
| Type Segmentation | Liquid levain (37.0% in 2026); Other Segment Combined (63.0%: Dried sourdough, Ready starters, Flavor concentrates) |
| Form Segmentation | Powder / dry (45.0% in 2026); Other Segment Combined (55.0%: Liquid, Paste / semi-solid, Granules / pieces) |
| Application Segmentation | Bread & rolls (33.0% in 2026); Other Segment Combined (67.0%: Cakes & muffins, Biscuits & cookies, Viennoiserie & pastry, Other bakery & snacks) |
| Claim Segmentation | Conventional (46.0% in 2026); Other Segment Combined (54.0%: Clean label, Organic, Non-GMO / identity preserved) |
| Sales Channel Segmentation | Direct to industrial bakeries (52.0% in 2026); Other Segment Combined (48.0%: Ingredient distributors, Foodservice & artisan supply, Online B2B) |
| Exclusions | Finished retail and foodservice bread and pastries, ordinary baker's yeast (Saccharomyces cerevisiae sold as standard yeast), chemical leaveners, and non-fermented dough acidulants. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Profiled | UAE, Saudi Arabia, South Korea, USA, Germany, UK, France, and Japan |
| Companies Profiled | Lesaffre, Puratos Group, AB Mauri, Lallemand Inc., IREKS GmbH, Ernst Bocker GmbH & Co. KG, GoodMills Innovation GmbH, Philibert Savours |
| Research Methodology | Primary interviews with bakery procurement and fermentation specialists combined with secondary desk research and bottom-up/top-down market triangulation. |
Source: Future Market Insights analysis of the liquid sourdough market, 2026.
Research Sources and Bibliography
- Associated British Foods. (2026, January 15).AB Mauri: Building UK sourdough capability (2026 Annual Report). https://www.abf.co.uk/our-businesses/our-businesses-in-action/2026/ab-mauri-building-capability-in-uk-sourdough
- Central Association of the German Bakers' Trade. (2025, April 14).Baeckerhandwerk beweist Resilienz: Betriebsruckgang, aber stabile Zahl an Neugrundungen und mehr Azubis. https://www.baeckerhandwerk.de/aktuelles/blog-beitrag/baeckerhandwerk-beweist-resilienz-betriebsrueckgang-aber-stabile-zahl-an-neugruendungen-und-mehr-azubis
- DSM-Firmenich. (2025, May 20).On the rise: dsm-firmenich opens Princeton Baking Innovation Center in Princeton, NJ. https://www.dsm-firmenich.com/en/businesses/taste-texture-health/news-events/press-releases/on-the-rise-dsm-firmenich-opens-state-of-the-art-princeton-baking-Innovation-center-in-princeton-nj.html
- Ernst Bocker GmbH & Co. KG. (2026, October 19).About Bocker: Fermentation experts and sourdough specialists (5th generation leadership 2026). https://sauerteig.de/en/about-us/
- GoodMills Innovation GmbH. (2026, August 25).Enrichment, naturalness and process efficiency: GoodMills Innovation to present contemporary solutions for the baking trade at sudback 2026. https://www.goodmillsinnovation.com/en/2026/08/enrichment-naturalness-and-process-efficiency-goodmills-innovation-to-present-contemporary-solutions-for-the-baking-trade-at/
- International Journal of Food Microbiology. (2025, January 2).The impact of fermentation length and dough composition on the stability of liquid sourdough starters. https://www.sciencedirect.com/science/article/pii/S0168160524003763
- IREKS GmbH. (2025, May 18).iba 2025: It's your choice (Wholemeal oat sourdough and Craft Master durum concepts). https://www.ireks.com/en/ireks-news/iba-2025/iba-2025-its-your-choice
- Lallemand Baking. (2026, January 13).Lallemand Baking at BakingTECH 2026. https://www.lallemandbaking.com/en/united-states/resources/news-blog/lallemand-baking-at-bakingtech-2026/
- Lallemand Baking. (2026, February 26).Lallemand Baking at Pizza Expo 2026: Clean-label sourdough mixes and dough performance solutions. https://www.lallemandbaking.com/en/asia/resources/news-blog/lallemand-baking-at-pizza-expo-2026/
- Lallemand Inc. (2025, July 4).Lallemand acquires AIT Ingredients. https://www.lallemand.com/en/news/lallemand-acquires-ait-ingredients/
- Lesaffre. (2026, February 25).Sourdough: New advances in yeast-bacteria synergies that shape bread quality. https://www.lesaffre.com/newsroom/innovation-solutions/sourdough-new-advances-yeast-bacteria-synergies-shape-bread-quality/
- Lesaffre. (2026, February 25).Sustainability and nutrition: Rethinking sourdough beyond wheat and rye. https://www.lesaffre.com/newsroom/innovation-solutions/sustainability-nutrition-rethinking-sourdough-beyond-wheat-rye/
- Lesaffre. (2026, March 4).Beyond volatile molecules: Revealing the aromatic signatures that make sourdough truly rich. https://www.lesaffre.com/newsroom/innovation-solutions/sourdough-aroma-aromatic-compounds/
- MDPI Fermentation. (2025, August 1).Impact of selected starter-based sourdough types on fermentation performance and bio-preservation of bread. https://www.mdpi.com/2311-5637/11/8/449
- MDPI Foods. (2025, February 1).Microbial ecology and nutritional features in liquid sourdough fermented with Lactiplantibacillus plantarum ITM21B. https://www.mdpi.com/2304-8158/14/3/469
- MDPI Foods. (2025, July 26).Type I sourdough preservation strategies and the contribution of microbial biological resource centers to biodiversity protection. https://www.mdpi.com/2304-8158/14/15/2624
- Ministere de l'Agriculture, de l'Agro-alimentaire et de la Souverainete alimentaire. (2026, June 1).Accord collectif sur la reduction du sel dans le pain: Un bilan positif pour la sante publique. https://agriculture.gouv.fr/accord-collectif-sur-la-reduction-du-sel-dans-le-pain-un-bilan-positif-pour-la-sante-publique
- Ministry of Agriculture, Food and Rural Affairs, South Korea. (2025, April 2).Invigorating the floury rice industry: A win-win situation for both bakeries and farmers. https://www.mafra.go.kr/bbs/english/25/573781/artclView.do
- Philibert Savours. (2026, October 17).Liquid sourdough for professionals: Phil Levain and Perspective active sourdough solutions at SIAL 2026. https://www.philibertsavours.com/gb/14-liquid-sourdough-professionals-phil-levain
- Puratos Group. (2026, March 10).Puratos to acquire Dawn Foods, bringing together complementary capabilities in professional bakery. https://www.puratos.com/news/puratos-to-acquire-dawn-foods
- Puratos Group. (2026, June 15).Puratos opens new research center to tackle flour variability. https://www.puratos.com/press/press-release/puratos-opens-new-research-center-to-tackle-flour-variability---
- Saudi Food and Drug Authority. (2025, June 18).SFDA to implement new food rules for transparency and consumer health. https://www.sfda.gov.sa/en/news/18680
- UK Department for Environment, Food and Rural Affairs. (2025, April 23).Bread and flour: Labelling and composition. https://www.gov.uk/guidance/bread-and-flour-labelling-and-composition
- U.S. Food and Drug Administration. (2025, May 9).Compliance Program 7321.005: General food labeling requirements and allergen compliance. https://www.fda.gov/media/71690/download
- USDA Foreign Agricultural Service. (2026, April 1).Japan: Food Processing Ingredients Annual (JA2026-0012). https://www.fas.usda.gov/data/gain-report/2026/04/Food%20Processing%20Ingredients%20Annual_Tokyo%20ATO_Japan_JA2026-0012.pdf
- USDA Foreign Agricultural Service. (2026, July 3).United Arab Emirates: Exporter Guide Annual (TC2026-0007). https://www.fas.usda.gov/data/gain-report/2026/07/Exporter%20Guide%20Annual_Dubai_United%20Arab%20Emirates_TC2026-0007.pdf
- USDA National Agricultural Statistics Service. (2026, May 1).Flour Milling Products 2025 Summary. https://esmis.nal.usda.gov/sites/default/release-files/795889/caflan26.pdf
- USDA National Agricultural Statistics Service. (2026, August 3).Flour Milling Products (Q2 2026 Report). https://esmis.nal.usda.gov/sites/default/release-files/796004/cafl0726.pdf
- Zentralverband des Deutschen Baeckerhandwerks. (2026, January 15).Zahlen rund ums Baeckerhandwerk (2025 Enterprise and Employment Statistics). https://www.baeckerhandwerk.de/zahlen-fakten
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Type, 2026 to 2036
- Liquid levain (37.0%)
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Powder / dry (45.0%)
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Bread & rolls (33.0%)
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Claim, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim, 2026 to 2036
- Conventional (46.0%)
- Y-o-Y Growth Trend Analysis By Claim, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct to industrial bakeries (52.0%)
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Western Europe
- East Asia
- South Asia and Pacific
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia
- Rest of world aggregate
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Lesaffre
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Puratos Group
- AB Mauri
- Lallemand Inc.
- IREKS GmbH
- Ernst Bocker GmbH & Co. KG
- GoodMills Innovation GmbH
- Philibert Savours
- Lesaffre
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Claim, 2021 to 2036
- Table 6: Global Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 11: North America Market Value (USD Million) Forecast by Claim, 2021 to 2036
- Table 12: North America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 17: Western Europe Market Value (USD Million) Forecast by Claim, 2021 to 2036
- Table 18: Western Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 19: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: East Asia Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Claim, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 29: South Asia and Pacific Market Value (USD Million) Forecast by Claim, 2021 to 2036
- Table 30: South Asia and Pacific Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Type
- Figure 6: Global Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Form
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Claim
- Figure 15: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Sales Channel
- Figure 18: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Type
- Figure 29: North America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Form
- Figure 32: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Application
- Figure 35: North America Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Claim
- Figure 38: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Sales Channel
- Figure 41: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 42: Western Europe Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 43: Western Europe Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 44: Western Europe Market Attractiveness Analysis by Type
- Figure 45: Western Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 46: Western Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 47: Western Europe Market Attractiveness Analysis by Form
- Figure 48: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 49: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 50: Western Europe Market Attractiveness Analysis by Application
- Figure 51: Western Europe Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 52: Western Europe Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 53: Western Europe Market Attractiveness Analysis by Claim
- Figure 54: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 55: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 56: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 57: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 58: East Asia Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 59: East Asia Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 60: East Asia Market Attractiveness Analysis by Type
- Figure 61: East Asia Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 62: East Asia Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 63: East Asia Market Attractiveness Analysis by Form
- Figure 64: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 65: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 66: East Asia Market Attractiveness Analysis by Application
- Figure 67: East Asia Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 68: East Asia Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 69: East Asia Market Attractiveness Analysis by Claim
- Figure 70: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 71: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 72: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 74: South Asia and Pacific Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 75: South Asia and Pacific Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 76: South Asia and Pacific Market Attractiveness Analysis by Type
- Figure 77: South Asia and Pacific Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 78: South Asia and Pacific Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 79: South Asia and Pacific Market Attractiveness Analysis by Form
- Figure 80: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 81: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 82: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 83: South Asia and Pacific Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 84: South Asia and Pacific Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 85: South Asia and Pacific Market Attractiveness Analysis by Claim
- Figure 86: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 87: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 88: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 89: Global Market - Tier Structure Analysis
- Figure 90: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the liquid sourdough market in 2026?
Future Market Insights estimates the global liquid sourdough market valuation at USD 303.5 million in 2026, advancing from USD 272.4 million in 2025 as industrial bakeries standardize dough acidification.
What CAGR is forecast for the liquid sourdough market from 2026 to 2036?
FMI projects the global liquid sourdough market to expand at an11.4% CAGR between 2026 and 2036, reaching USD 893.3 million by 2036 and generating USD 589.8 million in incremental revenue.
Which Type segment leads the liquid sourdough market?
Liquid levain segment leads the Type category with37.0% revenue share in 202663.0%, driven by direct pumpable dosing in automated bread mixing lines.
Which Form segment accounts for the largest share in the liquid sourdough market?
Powder / dry segment accounts for45.0% of the Form category in 202655.0%, reflecting ambient storage convenience across multi-format bakery ingredient programs.
Which Application segment leads the liquid sourdough market?
Bread & rolls segment leads the Application category at33.0% share in 202667.0%, corroborated by high-frequency daily loaf and roll production.
Which Sales Channel leads the liquid sourdough market?
Direct to industrial bakeries channel commands 52.0% of global sales in 2026, supported by bulk tanker contracts and automated dispensing support, because factory qualification requires on-site pilot bakes and dosing calibration.
Which countries are expected to grow fastest in the liquid sourdough market?
Within the UAE, (12.6% CAGR, reaching USD 39.7 million by 2036), Saudi Arabia (12.3% CAGR, reaching USD 48.5 million), and South Korea (12.0% CAGR, reaching USD 75.5 million) are projected to grow fastest.
Which companies are profiled in the liquid sourdough market?
Notable companies operating in the liquid sourdough market include Lesaffre, Puratos Group, AB Mauri, Lallemand Inc., IREKS GmbH, Ernst Bocker GmbH & Co. KG, GoodMills Innovation GmbH, and Philibert Savours.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
