

- Market Size (2026)
- USD 593.8 Mn
- Forecast (2036)
- USD 1418.7 Mn
- CAGR (2026 to 2036)
- 9.1%
How big is Sub & Hoagie Rolls Market in 2026?
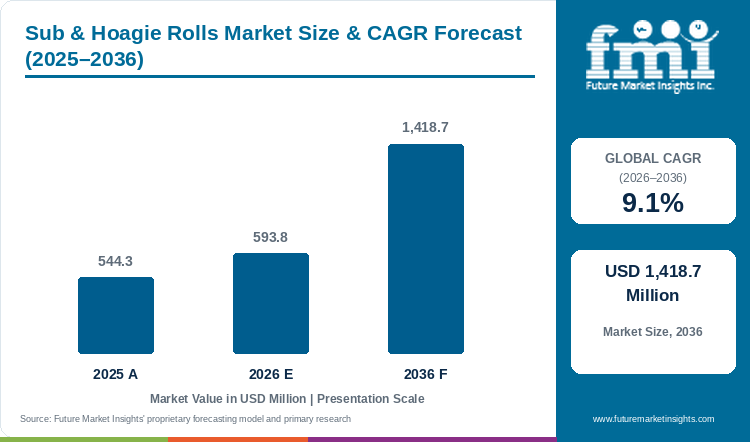
Accounting for USD 544.3 million in 2025 and rising to USD 593.8 million in 2026, the global sub & hoagie rolls market is projected to expand to USD 1,418.7 million by 2036, advancing at a CAGR of 9.1%.
Higher out-of-home lunch traffic and the expansion of quick-service sandwich chains have created a steady need for portion-controlled bread rolls that hold hot meats and dressings without turning soggy. Because restaurant operators and supermarket deli counters rely on repeatable sandwich assembly to protect store margins, they are signing long-term supply agreements with commercial bakeries. For example, June 2026 USDA Economic Research Service data showed away-from-home dining making up 56.3% of total USA food budgets in 2025, which directly supports bulk procurement of standardized sandwich carriers [1]. This sustained commercial demand lifts the global sub and hoagie rolls market value from USD 544.3 million in 2025 to an estimated 2026 mark of USD 593.8 million and an industry valuation of USD 1,418.7 million by 2036, expanding at a 9.1% CAGR to deliver USD 824.9 million in net valuation expansion over the decade. Classic / Original rolls are expected to hold a 34.0% share of the product type category in 2026 as industrial bakers pair par-baked bread formats with soft wheat doughs. However, issues such as short fresh selling windows and mandatory sesame allergen line segregation continue to restrain how quickly buyers can switch suppliers.
Key Market Trends & Insights
- By product type: Classic / Original is expected to hold a 34.0% share in 2026, driven by uniform 6-inch and 12-inch trough dimensions that fit automated sandwich slicing guides.
- By claim / nature: Conventional is estimated to hold 55.0% of 2026 category demand, attributable to predictable gluten development and lower per-case ingredient costs for multi-unit deli chains.
- By format: Fresh is projected to account for a 31.0% share in 2026, supported by direct-store-delivery bakery fleets that replenish grocery deli counters every morning.
- By packaging format: Multipack is anticipated to garner a 34.0% share in 2026, linked to four-count and six-count pillow bags designed for planned household sandwich preparation.
- By sales channel: Supermarkets & hypermarkets are forecast to capture 27.0% of 2026 distribution share, enabled by perimeter in-store bakery tables positioned adjacent to sliced charcuterie.
Regional Highlights
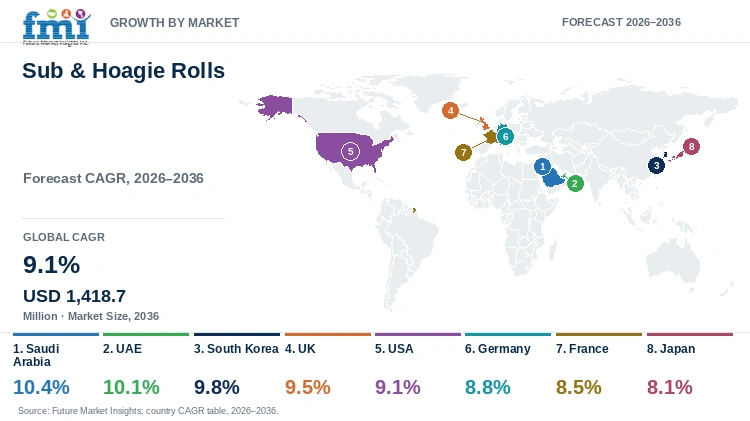
- Gulf hospitality expansion: Saudi Arabia is projected to top country growth at a 10.4% CAGR through 2036 ahead of the UAE at 10.1% as airport catering commissaries and hotel chains expand portable sandwich menus.
- Asian and European channel progression: South Korea is expected to advance at a 9.8% CAGR and the UK at 9.5% ahead of the USA at 9.1%, while Germany at 8.8% and France at 8.5% precede Japan at 8.1% across bake-off and convenience channels.
Market Size & Forecast
Table 1: Market Size and Forecast for the Sub & Hoagie Rolls Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 544.3 million |
| Estimated Market Size in 2026 | USD 593.8 million |
| Projected Market Size by 2036 | USD 1,418.7 million |
| CAGR, 2026 to 2036 | 9.1% |
| Added Revenue, 2026 to 2036 | USD 824.9 million |
Higher food and labor expenses in commercial dining are forcing sandwich shop operators and grocery delis to cut end-of-day bread waste. When fresh rolls go unsold at the end of a shift, those write-offs directly erode store profitability. As a matter of fact, in August 2025, the UK Office for National Statistics reported that annual food price inflation stood at 4.9% in July 2025 while restaurant and hotel price inflation reached 3.4% [2]. Because of this persistent cost pressure, European sandwich counters are shifting their orders toward par-baked frozen bakery items that staff can thaw or finish in small batches during peak lunch hours. As a result, wholesale bakeries that supply pre-cut frozen rolls with reliable crust recovery are winning multi-year foodservice distribution contracts.
Carrier Volume and Bakery Throughput Sizing
Table 2: Commercial Carrier Volume and Bakery Throughput Sizing for the Sub & Hoagie Rolls Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 544.3 | 593.8 | 1,418.7 |
| Commercial sub & hoagie roll volume (million units) | 2,180 to 2,360 | 2,350 to 2,540 | 5,120 to 5,560 |
| Industrial tunnel-oven output (thousand metric tons) | 196.2 to 212.4 | 211.5 to 228.6 | 460.8 to 500.4 |
| Average wholesale realization per roll (USD) | 0.23 to 0.25 | 0.23 to 0.25 | 0.26 to 0.28 |
Operational note: Carrier unit ranges apply standard 85-gram to 95-gram elongated roll weights across retail multipacks and foodservice cases while excluding downstream sandwich fillings.
Expansion of national sandwich franchises is compelling wholesale bakeries to scale up roll output while keeping unit weights and lengths uniform across every case. If roll dimensions vary between batches, restaurant wrapping stations slow down and portion costs rise. To overcome this bottleneck, large commissaries are investing in automated bakery processing lines that eliminate manual dividing errors and lower per-unit baking costs, which is propelling overall market growth.
Per Capita & Foodservice Outlet Sizing
Table 3: Per Capita and Sandwich Outlet Procurement Indicators for the Sub & Hoagie Rolls Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 66.4 | 71.5 | 157.6 |
| Annual roll procurement per sandwich outlet (USD) | 1,420 to 1,680 | 1,510 to 1,790 | 2,850 to 3,340 |
| Frozen & par-baked foodservice case share (%) | 42.5% to 45.5% | 44.0% to 47.0% | 52.0% to 56.0% |
Table 4: Bakery & Foodservice Channel Indicators for the Sub & Hoagie Rolls Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 593.8 million | 2026 global wholesale carrier baseline |
| Organized sandwich & deli outlets globally | 365,000 outlets | Franchise QSR, grocery deli & catering registry |
| Average annual carrier spend per outlet | USD 1,626.8 | Annualized wholesale bread-carrier allocation |
| Classic / Original segment allocation, 2026 | USD 201.9 million | 34.0% primary product-type share allocation |
Supermarket category buyers and sandwich chains evaluate roll suppliers on how many days a packaged loaf stays soft on the shelf before markdowns are required. Longer ambient softness directly reduces retailer shrink and improves store reorder frequency. Consequently, bakeries are expanding their assortments of enzyme-conditioned sub loaves and commercial brioche rolls that stay pliable for five to seven days, which is opening new retail shelf placements.
Analyst Perspective
"Wholesale sandwich-roll contracts are won on hinge integrity and uniform trough geometry paired with zero-waste thaw-and-serve execution rather than recipe novelty alone. Industrial bakeries that pair clean-label crumb softeners with shock-frozen pre-sliced formats will secure multi-year supply agreements across grocery delis and quick-service sandwich chains."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the sub & hoagie rolls market segmented?
The sub & hoagie rolls market is segmented by product type, claim / nature, format, packaging format, and sales channel. In 2026, Classic / Original is projected at 34.0%, Conventional at 55.0%, Fresh at 31.0%, Multipack at 34.0%, and Supermarkets & Hypermarkets at 27.0%.
By product type: Classic / Original, Whole Grain & Seeded, Flavored & Filled, Mini & Snacking Formats, and Premium / Artisan.
By claim / nature: Conventional, Clean Label, Organic, Gluten-Free, and High-Protein / Fortified.
By format: Fresh, Frozen, Ambient Packaged, Chilled, and Par-Baked / Thaw-and-Serve.
By packaging format: Multipack, Single-Serve, Family / Loaf Pack, and Bulk Foodservice.
By sales channel: Supermarkets & Hypermarkets, Artisan & Specialty Bakeries, Convenience & Forecourt, Online & DTC, and Foodservice Distributors.
Why does Classic / original remain the principal Product Type?
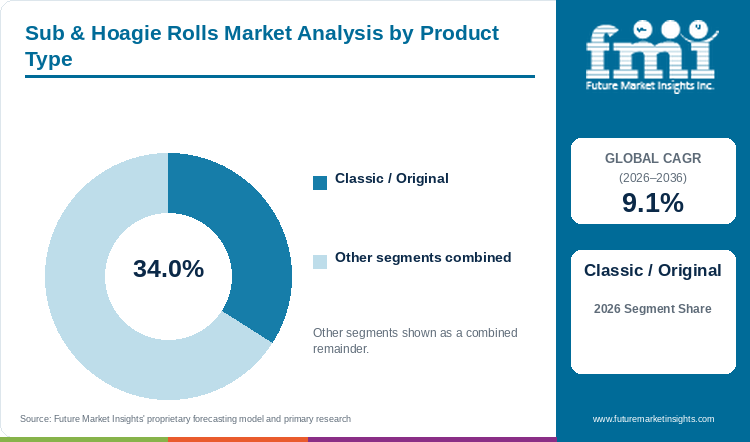
Classic / Original rolls are expected to hold a 34.0% share of product type demand in 2026, driven by menu versatility.
Table 5: Product Type Share for the Sub & Hoagie Rolls Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Classic / Original | 34.0% |
| Other Segments Combined* | 66.0% |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Sub & Hoagie Rolls Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.1% |
| Leading Segment | Classic / Original |
Sandwich chains and grocery delis rely on Classic / Original sub rolls for the majority of their volume because one neutral roll SKU can serve dozens of hot and cold sandwich recipes without menu complexity. At the same time, bakery brands are using this familiar elongated roll shape to introduce higher-margin whole-grain options for retail shoppers. To capture this premium household lunch demand, Flowers Foods rolled out Dave's Killer Bread Organic Sandwich Rolls in two whole-grain variants across national grocery stores in April 2025 [3]. Even with these new retail launches, multi-unit restaurant chains still concentrate base orders in classic white wheat sub rolls formulated with industrial food enzymes that keep pre-sliced hinges from splitting during assembly.
- Submarine sandwich chains keep Classic / Original at an expected 34.0% product-type share in 2026 to avoid seed-allergen changeovers on shared baking lines.
- Automated band-slicing blades require uniform 6-inch and 12-inch crust geometry so filled submarine rolls fold cleanly without splitting along the hinge spine.
What keeps Conventional in front within Claim / Nature?
Order patterns across foodservice tenders keep Conventional at an estimated 55.0% claim share in 2026, owing to chain cost efficiency.
Cost-sensitive foodservice distributors and institutional cafeterias favor conventional enriched-wheat hoagie rolls because organic grain certification and segregated milling add substantial price premiums to bulk bread tenders. A predictable per-roll cost is essential for sandwich chains running national value menus. However, consumer scrutiny of artificial additives is pushing mainstream bakers to upgrade their conventional recipes with clean-label ingredients so they can retain retail and school-nutrition accounts without raising prices to organic tiers.
- Grupo Bimbo announced in July 2025 a company-wide program removing synthetic dyes across all bread and roll lines before year-end 2026 while preserving core conventional pricing tiers [4].
- Commercial bakery purchasing places Conventional at an estimated 55.0% share within 2026 claim / nature demand, attributable to standardized flour specifications and rapid divider throughput.
Why does Fresh retain leadership across Format?
Within the format mix, Fresh rolls are projected to account for a 31.0% share in 2026, enabled by daily store delivery.
Fresh sub rolls remain the preferred choice for high-traffic urban sandwich shops and supermarket perimeter delis because shoppers associate warm aroma and soft crust spring with made-to-order quality. Daily ambient deliveries also allow busy delis to assemble sandwiches immediately without waiting for frozen dough to thaw or bake. However, daily van deliveries are expensive for remote outlets with lower turnover, which is prompting bakeries to formulate thaw-and-serve rolls with food emulsifiers so distant accounts can match fresh eating quality.
- FDA Edition 5 Food Allergen Labeling Guidance issued in January 2025 confirms that multiunit bakery packs must declare wheat and sesame allergens clearly on outer labels [5].
- Morning route drops across metropolitan supermarkets keep Fresh at a projected 31.0% format share in 2026 without requiring store-level thawing.
How does Multipack lead Packaging Format?
Household purchasing patterns give Multipack units an anticipated 34.0% packaging share in 2026, linked to weekly meal planning.
Retail demand for sub and hoagie rolls is heavily driven by families buying four-count and six-count multipacks for weekly lunchbox and dinner preparation. Multi-roll packs lower packaging film cost per roll and give supermarkets a higher ring per basket than single loose rolls. To keep pace with this growing retail multipack demand, leading bakers are expanding their automated production capacity. In July 2025, Georgia state economic development officials confirmed a USD 54 million capital program by King's Hawaiian to add a new baking line and 140 jobs at its Oakwood plant [6]. Through such capacity additions, branded bakeries can keep supermarket deli and bread aisles stocked during peak back-to-school and summer grilling seasons.
- Multipack is anticipated to garner a 34.0% share of the packaging format category in 2026, stemming from family meal bundling and lower packaging film cost per roll.
- Automated horizontal bagging lines wrap pre-sliced elongated rolls in barrier polyolefin films that prevent leathery crust toughening after primary bag opening.
Why are Supermarkets & hypermarkets the largest Sales Channel?
Retail channel velocity places Supermarkets & hypermarkets at 27.0% of 2026 sales-channel demand, forecast on strong perimeter deli-counter adjacency.
Supermarkets and hypermarkets capture the largest share of retail sub-roll sales because shoppers prefer to buy sandwich rolls in the same trip as sliced deli meats and cheeses. Placing packaged sub rolls on perimeter deli tables directly increases impulse basket additions compared with standard center-store bread aisles. To protect shelf productivity, supermarket category managers require suppliers to deliver barcoded shelf-ready trays and maintain strong weekly scan velocity.
- In August 2026, the UK Office for National Statistics reported that Great Britain retail sales volumes rose 1.1% in the three months to July 2026 and increased 3.0% year-on-year on resilient supermarket food store demand [7].
- Supermarkets & hypermarkets are forecast to register a 27.0% share of the sales channel category in 2026, influenced by weekly household grocery consolidation and perimeter bakery promotions.
What are the drivers, restraints, and opportunities in the sub & hoagie rolls market?
Recurring quick-service sandwich throughput and household lunch preparation drive carrier volume, whereas rapid ambient staling and sesame allergen compliance restrain switching and pre-sliced thaw-and-serve formats create margin expansion opportunities.
- Driver: Expanding quick-service sandwich chain footprints and off-premise catering orders sustain high-frequency contract procurement of portion-calibrated elongated rolls.
- Restraint: Short ambient selling windows and statutory sesame allergen labeling rules elevate bakery line sanitation costs and retail shrink penalties.
- Opportunity: Pre-sliced blast-frozen and par-baked artisan sub rolls enable convenience stores and cafés to serve warm carriers with near-zero end-of-shift waste.
Growth Analysis and Future Potential: Quick-Service Sandwich Throughput and Carrier Standardization
Rapid expansion of quick-service sandwich franchises and supermarket grab-and-go counters is the primary factor driving global demand for standardized sub and hoagie rolls. Multi-unit restaurant chains require every 6-inch and 12-inch roll to match exact weight and hinge specifications so kitchen staff can assemble sandwiches quickly and keep food costs predictable. Because foodservice chains prefer vendors that can supply identical rolls across multiple countries, large bakery groups are committing major capital to automated oven capacity. In March 2026, Europastry disclosed that 2025 group turnover reached EUR 1.63 billion after EUR 134 million in global plant upgrades that included EUR 38 million at Azuqueca de Henares [8]. These capacity upgrades allow industrial bakers to link high-speed ovens with commercial bakery products cold-chain hubs and win multi-region restaurant contracts.
Risk Assessment of the Sub & Hoagie Rolls Market: Staling Shrink and Sesame Allergen Governance
Short fresh shelf life and strict allergen compliance rules are the main factors restraining profit margins and complicating production schedules in the sub and hoagie rolls market. Fresh bread rolls begin losing crust crispness and crumb softness within 48 hours, while seeded variants create severe allergen cross-contact risks on shared baking lines. Under the USA FASTER Act enforced by the Food and Drug Administration, sesame is regulated as the ninth major food allergen and requires explicit label declarations and validated line sanitation [9]. Because running sesame-topped hoagie rolls on shared tunnel ovens requires hours of washdown downtime between runs, many bakeries face higher operating costs or risk product recalls. To mitigate both allergen exposure and staling losses, suppliers are sealing rolls in barrier flexible food packaging films on dedicated production lines.
Commercial Opportunity Analysis: Pre-Cut Thaw-and-Serve and Clean-Label Sourdough Carriers
Persistent kitchen labor shortages in cafés, travel plazas, and convenience stores are creating a major growth opportunity for pre-cut thaw-and-serve sub rolls. When rolls arrive pre-sliced from the bakery plant, foodservice workers avoid manual knife slicing and can thaw exact tray counts in 20 to 30 minutes to match shift traffic. At the same time, new environmental packaging rules are prompting bakeries to pair convenient roll formats with compliant, recyclable bags. For instance, in August 2026, the European Commission confirmed that the EU Packaging and Packaging Waste Regulation entered into application with strict PFAS limits on food-contact wrappers and bakery bags [10]. Suppliers that combine PFAS-free packaging and pre-sliced thaw-and-serve convenience with artisanal sourdough breads fermentation are capturing higher margins across premium foodservice accounts.
Sub & Hoagie Rolls Market by Country (2026 to 2036)
Regional consumption patterns show Saudi Arabia leading national sub and hoagie roll expansion at a 10.4% CAGR through 2036, whereas Japan is forecast to progress at an 8.1% annual pace. Commercial performance across Gulf hospitality hubs, East Asian franchise networks, and Western European grocery channels depends on cold-chain bake-off infrastructure and retail multipack turnover.
Table 7: Country CAGR and Primary Growth Levers for the Sub & Hoagie Rolls Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Saudi Arabia | 10.4% | Tourism hospitality catering expansion and QSR sandwich franchise rollouts |
| UAE | 10.1% | International hotel traffic and blast-frozen thaw-and-serve commissary supply |
| South Korea | 9.8% | Organized sandwich and burger franchise chain case standardization |
| UK | 9.5% | Supermarket meal-deal multipacks and brioche sub carrier premiumization |
| USA | 9.1% | High food-away-from-home sandwich share and organic retail roll innovation |
| Germany | 8.8% | Restaurant waste-reduction shift toward par-baked frozen sandwich carriers |
| France | 8.5% | Boulangerie snacking growth and pre-sliced supermarket brioche sub packs |
| Japan | 8.1% | Convenience-store chilled grab-and-go throughput and portioned roll packs |
Source: Future Market Insights analysis
Saudi Arabia Sub & Hoagie Rolls Market Outlook (2026 to 2036)
Unlike mature Western bread markets driven by household grocery replenishment, demand in Saudi Arabia is fueled by religious and leisure tourism catering paired with rapid drive-thru sandwich chain expansion. In June 2026, the Saudi Ministry of Tourism reported via the Saudi Press Agency that domestic and inbound tourists reached 123 million in 2025 and total visitor spending hit SAR 304 billion [11]. This hospitality surge is projected to lift sub and hoagie roll demand in Saudi Arabia at a leading 10.4% CAGR from 2026 to 2036 across Riyadh and Jeddah. However, extreme desert heat can dry out fresh bread during long-haul transport, forcing wholesale bakeries to invest in moisture-barrier packaging and refrigerated delivery fleets.
Key takeaway: In Saudi Arabia, surging tourism catering demand and international sandwich franchise expansion are projected to anchor bulk procurement of climate-stabilized sub rolls.
UAE Sub & Hoagie Rolls Market Outlook (2026 to 2036)
The UAE differs from domestic baking markets because its large aviation catering and international hotel or quick-service sectors rely heavily on imported blast-frozen bread carriers. Commercial sub and hoagie roll consumption in the UAE is expected to climb at a 10.1% annual rate through 2036 on the back of hotel and gourmet deli menu standardization. In June 2025, the Government of Dubai Media Office reported that Dubai welcomed 7.15 million international overnight visitors between January and April 2025 across 153,534 hotel rooms [12]. Because this visitor volume creates sharp seasonal catering peaks while municipal port rules enforce strict shelf-life and Arabic-label checks, suppliers with 12-month frozen pre-sliced sub cases capture the highest contract volume.
Key takeaway: In the UAE, high international hotel occupancy and institutional flight catering are expected to favor blast-frozen pre-sliced sub rolls with verified thaw resilience.
South Korea Sub & Hoagie Rolls Market Outlook (2026 to 2036)
In South Korea, sub and hoagie roll adoption is shaped by dense urban sandwich franchises and convenience stores where consumers strongly prefer soft, lightly sweet bread over hard European crusts. Demand for sub and hoagie rolls in South Korea is forecast to advance at a 9.8% yearly pace between 2026 and 2036 owing to custom-assembled sub chain openings near office and university districts. This convenience-dining shift is reflected in October 2026 trade data from USDA Foreign Agricultural Service analysts in Seoul showing importers in South Korea purchasing USD 6.0 billion in USA consumer-oriented foods in 2025 [13]. However, high urban store rents limit back-of-house baking space, compelling chains to buy frozen pre-hinged rolls tailored for rapid toaster-oven finishing.
Key takeaway: In South Korea, dense quick-service sandwich franchise networks are forecast to drive centralized commissary contracts for soft-crumb frozen hoagie carriers.
UK Sub & Hoagie Rolls Market Outlook (2026 to 2036)
What distinguishes the UK market is the dominance of supermarket lunchtime meal deals and strict allergen labeling rules that push shoppers and delis toward pre-packaged multipack rolls. Under UK Food Standards Agency rules updated in June 2025 for prepacked-for-direct-sale foods, sandwich counters packaging rolls on-site must print full ingredient lists with emphasized allergens [14]. Because compliance raises labor and labeling costs for small delis, many operators and consumers are shifting to factory-packed sub rolls, lifting UK volume at an anticipated 9.5% CAGR through 2036. Plant bakers that offer pre-sliced glazed and brioche sub multipacks with seven-day ambient softness are winning shelf space from standard white loaves.
Key takeaway: In the UK, grocery lunch-deal competition and strict allergen labeling standards are anticipated to accelerate retail multipack sales of pre-sliced sub and brioche rolls.
USA Sub & Hoagie Rolls Market Outlook (2026 to 2036)
Because the USA already has high per-capita sandwich consumption across regional hoagie chains and grocery delis, market growth depends on trading household shoppers up from basic white buns to premium organic and clean-label sub rolls. Commercial demand in the USA is estimated to grow at a 9.1% annual rate from 2026 to 2036 across foodservice distributor and supermarket perimeter channels. Illustrating this premiumization strategy, Flowers Foods announced in May 2026 that first-quarter 2026 net sales climbed 1.1% to USD 1.572 billion following its national grocery rollout of organic sandwich rolls and relaunched loaves [15]. However, strict federal sesame-allergen enforcement restrains shared-line baking and favors large automated plants.
Key takeaway: In the USA, high off-premise sandwich consumption and branded organic roll launches are estimated to sustain volume growth across grocery and foodservice channels.
Germany Sub & Hoagie Rolls Market Outlook (2026 to 2036)
Unlike countries where soft white sub rolls are a household staple, Germany has a deep artisan crusty-bread culture and high discount-grocery competition that squeezes bakery margins. Demand for sub and hoagie rolls in Germany is predicted to expand at an 8.8% CAGR between 2026 and 2036 through transit-hub snack bars and supermarket bake-off stations adopting convenient sandwich carriers. In September 2025, agricultural attaché data from USDA Foreign Agricultural Service offices in Berlin showed food retail turnover in Germany totaling USD 293 billion with private-label lines holding 36.2% [16]. Because high private-label share and rising restaurant wages penalize unsold fresh bread, buyers in Germany favor par-baked frozen sub rolls baked in small batches.
Key takeaway: In Germany, restaurant margin pressure and in-store bake-off infrastructure are predicted to shift procurement toward par-baked frozen elongated sandwich rolls.
France Sub & Hoagie Rolls Market Outlook (2026 to 2036)
In France, traditional crusty baguettes still dominate street-corner boulangerie ham-and-butter sandwiches, meaning soft sub and hoagie rolls must carve out growth through hypermarket viennoiserie aisles and fast-casual sub chains. Commercial sub and hoagie roll demand in France is slated to rise at an 8.5% annual rate through 2036 amid a steady weekday shift toward hot-held and portable lunch carriers. According to USDA Foreign Agricultural Service data published in September 2026, hypermarkets and supermarkets generated 58.6% of 2025 food retail turnover in France compared with 20.4% for commercial artisans [17]. This strong supermarket channel share allows industrial bakers to scale pre-sliced brioche and soft hoagie multipacks for suburban family shoppers.
Key takeaway: In France, expanding lunchtime fast-casual snacking is slated to support supermarket and foodservice adoption of pre-sliced brioche and soft sub rolls.
Japan Sub & Hoagie Rolls Market Outlook (2026 to 2036)
Japan stands apart from Western markets because small urban household sizes and daily convenience-store meal shopping limit demand for large six-count or twelve-count family roll bags. Instead, sub and hoagie roll turnover in Japan is projected to advance at an 8.1% CAGR from 2026 to 2036 due to commuters buying single-serve chilled sub sandwiches and twin-pack soft koppepan rolls. In April 2026, the Ministry of Economy Trade and Industry reported that retail sales in Japan expanded for a fifth consecutive year in 2025, supported by supermarket and convenience-store food demand [18]. To win listings in this high-turnover channel, domestic bakers must deliver pillow-soft crumb texture across strict 48-hour shelf rotation cycles.
Key takeaway: In Japan, dense convenience-store food traffic and supermarket bakery growth are projected to sustain demand for ultra-soft single-serve and twin-pack elongated rolls.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the sub & hoagie rolls market?
Grupo Bimbo, Flowers Foods, Aryzta, Lantmannen Unibake, Vandemoortele, Yamazaki Baking, Warburtons, King's Hawaiian, Europastry, and St Pierre Groupe are the notable companies in the sub & hoagie rolls market.
Competitive positioning in the sub and hoagie rolls sector divides between high-speed direct-store-delivery bread networks, multinational frozen bake-off specialists, and branded enriched-roll innovators. Retail bakery leaders compete on shelf-ready multipack velocity and clean-label reformulation, whereas foodservice bakery platforms win chain accounts through blast-frozen pre-sliced sub rolls that minimize kitchen labor and staling waste.
- Broad packaged-bakery and retail networks: Grupo Bimbo and Flowers Foods operate high-speed North America tunnel ovens, while Warburtons runs national packaged roll routes across the UK.
- Frozen bakery and bake-off supply platforms: Aryzta and Lantmannen Unibake supply par-baked carriers for quick-service sandwich chains, while Vandemoortele and Europastry scale European frozen dough lines.
- Differentiated consumer and regional roll portfolios: King's Hawaiian and St Pierre Groupe market branded sweet and brioche sub packs, while Yamazaki Baking anchors convenience bakery shelves in Japan.
Competitive Benchmarking: Sub & Hoagie Rolls Market
Table 8: Competitive Benchmarking for the Sub & Hoagie Rolls Market (qualitative capability ratings), 2026
| Company | Elongated sub-roll evidence | Frozen / bake-off handling | Retail-ready roll packs | Geographic Reach |
|---|---|---|---|---|
| Grupo Bimbo | High | Medium | High | High |
| Flowers Foods | High | Medium | High | Medium |
| Aryzta | Medium | High | Medium | High |
| Lantmannen Unibake | High | High | Medium | High |
| Vandemoortele | Medium | High | Medium | Medium |
| Yamazaki Baking | Medium | Medium | High | Medium |
| Warburtons | Medium | Medium | High | Medium |
| King's Hawaiian | High | Medium | High | Medium |
| Europastry | High | High | Medium | High |
| St Pierre Groupe | High | Medium | High | High |
Scoring basis: Capability tiers evaluate documented elongated sub-roll SKU breadth and blast-frozen foodservice execution across retail and commissary bakery networks.
Key Developments in the Sub & Hoagie Rolls Market
- In its 2025 annual share and financial disclosures, ARYZTA documented strengthened European and Asia-Pacific bake-off bakery operations with CHF 1.28 billion market capitalization and diluted earnings of 425 EUR cents per post-consolidation share [19].
- Vandemoortele announced in March 2026 that 2025 Bakery Products division turnover rose 10% to EUR 1,500 million after integrating Lizzi and Délifrance [20].
- In February 2025, St Pierre Groupe launched its Above-the-Line Eat Avec Respect campaign across USA retail and digital channels to accelerate supermarket velocity for its pre-sliced brioche sub rolls [21].
Key Players in the Sub & Hoagie Rolls Market
Broad packaged-bakery and retail networks
- Grupo Bimbo
- Flowers Foods
- Warburtons
Frozen bakery and bake-off supply platforms
- Aryzta
- Lantmannen Unibake
- Vandemoortele
- Europastry
Differentiated consumer and regional roll portfolios
- Yamazaki Baking
- King's Hawaiian
- St Pierre Groupe
Sub & Hoagie Rolls Market - Report Scope
Table 9: Report Scope for the Sub & Hoagie Rolls Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Claim / Nature; Format; Packaging Format; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Includes commercial wholesale and retail supplier revenue from elongated bread rolls engineered as sub, hoagie, grinder, or torpedo sandwich carriers. Category Scope Note: Excludes assembled sandwich revenue, meat or cheese fillings, ordinary sliced bread loaves, round hamburger buns, and downstream restaurant service markups. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Saudi Arabia, UAE, South Korea, UK, USA, Germany, France, Japan, and additional countries in the full report |
| Key Companies Covered | Grupo Bimbo, Flowers Foods, Aryzta, Lantmannen Unibake, Vandemoortele, Yamazaki Baking, Warburtons, King's Hawaiian, Europastry, St Pierre Groupe |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Sub & Hoagie Rolls Market - Research Methodology
Table 10: Research Methodology for the Sub & Hoagie Rolls Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with commercial tunnel-oven plant directors, QSR sandwich chain bakery buyers, grocery in-store bakery category managers, and cold-chain foodservice distributors to validate case pricing and staling shrink tolerances. |
| Secondary Research | Audit of USDA Economic Research Service food-away-from-home expenditure datasets, Destatis and INSEE hospitality and bakery trade bulletins, UK ONS inflation releases, Statistics Korea franchise censuses, and corporate bakery filings. |
| Market Sizing and Forecasting | Top-down wholesale bakery roll production budgets reconciled against bottom-up sandwich outlet carrier volumes and household multipack scan velocity from 2025 to 2036. |
| Country Forecasting Model | Econometric national projections weight quick-service sandwich store expansion, tourism hospitality catering volume, and supermarket bake-off adoption across eight focal countries and seven global regions. |
| Operational Benchmark Traceability | Carrier unit volumes, tunnel-oven tonnage, and per-outlet procurement indicators in Tables 2, 3, and 4 trace to USDA ERS, Statistics Korea, INSEE, and corporate bakery line disclosures. |
| Data Triangulation and Validation | Segment and regional estimates are cross-checked against wholesale bakery case shipments while stripping out assembled sandwich prices, sliced bread loaves, and round burger buns to eliminate double counting. |
Sub & Hoagie Rolls Market by Segments
Sub & Hoagie Rolls Market segmented by Product Type:
- Classic / Original
- Whole Grain & Seeded
- Flavored & Filled
- Mini & Snacking Formats
- Premium / Artisan
Sub & Hoagie Rolls Market segmented by Claim / Nature:
- Conventional
- Clean Label
- Organic
- Gluten-Free
- High-Protein / Fortified
Sub & Hoagie Rolls Market segmented by Format:
- Fresh
- Frozen
- Ambient Packaged
- Chilled
- Par-Baked / Thaw-and-Serve
Sub & Hoagie Rolls Market segmented by Packaging Format:
- Multipack
- Single-Serve
- Family / Loaf Pack
- Bulk Foodservice
Sub & Hoagie Rolls Market segmented by Sales Channel:
- Supermarkets & Hypermarkets
- Artisan & Specialty Bakeries
- Convenience & Forecourt
- Online & DTC
- Foodservice Distributors
Sub & Hoagie Rolls Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] USDA Economic Research Service. (2026, June 11). Total U.S. food spending reached $2.51 trillion in 2025 | Economic Research Service. U.S. Department of Agriculture.
- [2] UK Office for National Statistics. (2025, August 20). Consumer price inflation, UK: July 2025 - Office for National Statistics. Office for National Statistics.
- [3] Flowers Foods, Inc. (2025, April 16). Flowers Foods Launches New Products and Line Expansions to Meet Consumer Needs - Flowers Foods. Flowers Foods Newsroom.
- [4] Grupo Bimbo, S.A.B. de C.V. (2025, July 29). We are committed to removing artificial colorants from all our products by the end of 2026 | Grupo Bimbo. Grupo Bimbo Press Releases.
- [5] U.S. Food and Drug Administration. (2025, January 6). Guidance for Industry: Questions and Answers Regarding Food Allergen Labeling (Edition 5) | FDA. FDA Center for Food Safety and Applied Nutrition.
- [6] Office of the Governor of Georgia. (2025, July 17). Gov. Kemp: King's Hawaiian to Invest $54 Million in Hall County Expansion | Governor Brian P. Kemp Office of the Governor. State of Georgia Official Press Releases.
- [7] UK Office for National Statistics. (2026, August 21). Retail sales, Great Britain - Office for National Statistics. Office for National Statistics.
- [8] Europastry, S.A. (2026, March 25). Europastry continues to grow and reaches €1.63 billion in revenue in 2025, an 8% increase compared to 2024 - Corporate. Europastry Corporate Newsroom.
- [9] U.S. Food and Drug Administration. (2025, January 15). The FASTER Act: Sesame Is the Ninth Major Food Allergen | FDA. FDA Center for Food Safety and Applied Nutrition.
- [10] European Commission. (2026, August 11). New EU rules on packaging enter into application - Environment. Directorate-General for Environment.
- [11] Saudi Press Agency. (2026, June 18). Ministry of Tourism Releases 2025 Annual Statistical Report, Announcing Record SAR304 Billion in Total Tourism Spending. Saudi Press Agency Official Portal.
- [12] Government of Dubai Media Office. (2025, June 11). Dubai Department of Economy and Tourism Highlights Community Effort and Industry Growth Momentum at First City Briefing of 2025. Government of Dubai.
- [13] USDA Foreign Agricultural Service. (2026, October 5). South Korea: Retail Foods Annual | USDA Foreign Agricultural Service. U.S. Department of Agriculture GAIN.
- [14] UK Food Standards Agency. (2025, June 17). Labelling guidance for prepacked for direct sale (PPDS) food products - GOV.UK. Food Standards Agency.
- [15] Flowers Foods, Inc. (2026, May 21). FLOWERS FOODS, INC. REPORTS FIRST QUARTER 2026 RESULTS - Flowers Foods. Flowers Foods Newsroom.
- [16] USDA Foreign Agricultural Service. (2025, September 24). Germany: Retail Foods Annual | USDA Foreign Agricultural Service. U.S. Department of Agriculture GAIN.
- [17] USDA Foreign Agricultural Service. (2026, September 30). France: Retail Foods Annual | USDA Foreign Agricultural Service. U.S. Department of Agriculture GAIN.
- [18] Ministry of Economy, Trade and Industry of Japan (METI). (2026, April 14). 2025年小売業販売を振り返る;5年連続の増加となった小売業販売|経済解析室ニュース(METI/経済産業省). METI Statistics Division.
- [19] ARYZTA AG. (2026, January 22). Share information - ARYZTA. ARYZTA Investor Center.
- [20] Vandemoortele NV. (2026, March 30). PRESS RELEASE - Vandemoortele. Vandemoortele Corporate Newsroom.
- [21] St Pierre Groupe. (2025, February 13). St Pierre Launched Eat Avec Respect Campaign - St Pierre Trade. St Pierre Trade Newsroom.
- [22] Bimbo Bakeries USA. (2026, July 2). BIMBO BAKERIES USA ANNOUNCES SWEEPING PORTFOLIO COMMITMENTS TO ADVANCE NUTRITION AND CLEANER LABEL | Bimbo Bakeries USA. Bimbo Bakeries USA Press Releases.
- [23] USDA Foreign Agricultural Service. (2025, December 31). United Kingdom: Food Service - Hotel Restaurant Institutional Annual | USDA Foreign Agricultural Service. U.S. Department of Agriculture GAIN.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the sub & hoagie rolls market in 2026 and what is forecast for 2036?
- Which foodservice assembly and retail merchandising pressures support sub & hoagie roll demand?
- Why does Classic / Original lead the product type category?
- Why does Conventional hold the largest share in claim / nature?
- How do growth rates compare across Saudi Arabia, the UAE, South Korea, and the USA?
- Which bakery companies supply elongated sub rolls and frozen bake-off carriers today?
- What limits fresh-roll shelf life and complicates allergen line changeovers?
- Which hinge-strength, thawing, and packaging specifications should buyers audit before contracting?
Frequently Asked Questions
How big is the sub & hoagie rolls market in 2026, and what is forecast for 2036?
Global sub and hoagie rolls wholesale turnover rises from USD 544.3 million in 2025 to USD 593.8 million in 2026 and reaches USD 1,418.7 million by 2036 across retail and foodservice bakery channels.
What is the CAGR for the sub & hoagie rolls market from 2026 to 2036?
The global sub and hoagie rolls sector is projected to expand at a 9.1% compound annual growth rate between 2026 and 2036, generating USD 824.9 million in incremental annual bread-carrier revenue.
Which product type segment leads the sub & hoagie rolls market?
Classic / Original is expected to hold a 34.0% share of the product type category in 2026, driven by neutral crumb resilience that accommodates hot and cold fillings across sandwich chains.
Which claim / nature segment leads the sub & hoagie rolls market?
Conventional is estimated to hold a 55.0% share of the claim / nature category in 2026, attributable to predictable tunnel-oven dough machining and cost efficiency for high-volume deli buyers.
Which country shows the fastest growth outlook through 2036?
Saudi Arabia is projected to pace national growth at a 10.4% CAGR from 2026 to 2036 ahead of the UAE at 10.1%, supported by hospitality catering expansion and quick-service sandwich store openings.
Who are the key players in the sub & hoagie rolls market?
Grupo Bimbo, Flowers Foods, Aryzta, Lantmannen Unibake, Vandemoortele, Yamazaki Baking, Warburtons, King's Hawaiian, Europastry, and St Pierre Groupe are the notable companies in the sub & hoagie rolls market.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Classic / Original
- Whole Grain & Seeded
- Flavored & Filled
- Mini & Snacking Formats
- Premium / Artisan
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Claim / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim / Nature, 2026 to 2036
- Conventional
- Clean Label
- Organic
- Gluten-Free
- High-Protein / Fortified
- Y-o-Y Growth Trend Analysis By Claim / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Format, 2026 to 2036
- Fresh
- Frozen
- Ambient Packaged
- Chilled
- Par-Baked / Thaw-and-Serve
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packaging Format, 2026 to 2036
- Multipack
- Single-Serve
- Family / Loaf Pack
- Bulk Foodservice
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Artisan & Specialty Bakeries
- Convenience & Forecourt
- Online & DTC
- Foodservice Distributors
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Grupo Bimbo
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Flowers Foods
- Aryzta
- Lantmannen Unibake
- Vandemoortele
- Yamazaki Baking
- Warburtons
- King's Hawaiian
- Europastry
- St Pierre Groupe
- Grupo Bimbo
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


