
- Market Size (2026)
- USD 92.0 Bn
- Forecast (2036)
- USD 290.9 Bn
- CAGR (2026 to 2036)
- 12.2%
How big is Wireless Connectivity Market in 2026?
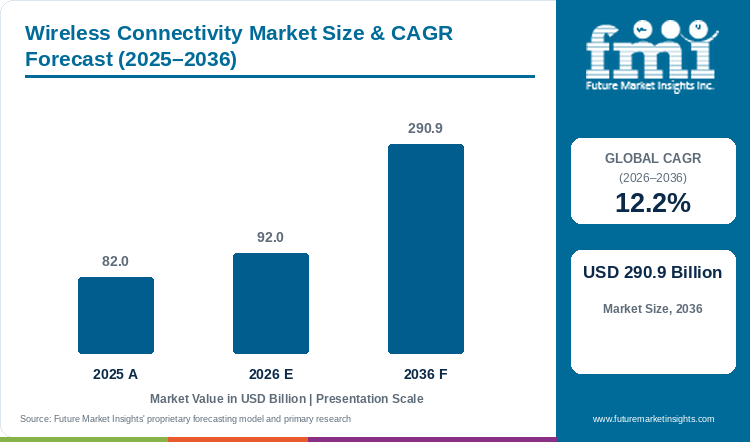
The wireless connectivity market establishes its foundation at USD 82.0 billion in 2025, advances to USD 92.0 billion in 2026, and is forecast to scale to USD 290.9 billion by 2036 at a CAGR of 12.2%.
Table 1: Market Size and Forecast for the Wireless Connectivity Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 82.0 billion |
| Estimated Market Size in 2026 | USD 92.0 billion |
| Projected Market Size by 2036 | USD 290.9 billion |
| CAGR, 2026 to 2036 | 12.2% |
| Added Revenue, 2026 to 2036 | USD 198.9 billion |
The global wireless connectivity market was valued at USD 82.0 billion in 2025 and is estimated to reach USD 92.0 billion in 2026. Total industry valuation is projected to reach USD 290.9 billion by 2036, expanding at a compound annual growth rate (CAGR) of 12.2% between 2026 and 2036. Wi-Fi 7 and 6E Standards capture an estimated 42.0% share of 2026 technology demand, given that handset OEMs and enterprise IT departments are upgrading to 320 MHz channels and Multi-Link Operation across unlicensed 6 GHz bands. FMI semiconductor analysis finds that device manufacturers are purchasing multi-radio combo silicon per board at a rising rate as smart-home appliances and industrial sensors combine Wi-Fi, Bluetooth Low Energy, and Thread on one die. That multi-radio content expansion separates the broader sector from standalone Wi-Fi semiconductor chipsets expanding at a 4.9% CAGR, since single-protocol WLAN chips track PC replacement cycles whereas integrated wireless connectivity revenue captures ultra-wideband and cellular IoT attach rates across billions of edge nodes. Demand for high-throughput wireless silicon is supported by shipment benchmarks from the Wi-Fi Alliance, which reported in 2025 that 3.9 billion Wi-Fi devices shipped annually with 81.6 million Wi-Fi 6E and 98.7 million Wi-Fi 7 access points. Semiconductor suppliers are introducing ultra-low-power AI-enabled wireless architectures to capture that edge volume, seen when Nordic Semiconductor launched its nRF71 Series combo SoC in November 2026 achieving twenty-fold lower standby power for battery devices. Equipment OEMs lock in multi-year silicon supply contracts when combo transceivers pass global 6 GHz spectrum certifications and Matter interoperability tests on a single hardware footprint through 2036.
Key Market Trends & Insights
- By technology standard: Wi-Fi 7 and 6E Standards hold an estimated 42.0% share in 2026 since 6 GHz spectrum releases and 4096-QAM modulation support multi-gigabit enterprise and residential gateways.
- By hardware component: Wireless Connectivity Chipsets and SoCs represent an estimated 58.0% share in 2026 given that OEMs favor monolithic Wi-Fi, Bluetooth, and 802.15.4 combo silicon to shrink board area.
- By end-use application: Consumer Electronics and Wearables accounts for an estimated 46.0% share in 2026 owing to annual smartphone refresh cycles and spatial-audio wearable attachments.
- By network range: Short-Range Wireless Networks secures an estimated 54.0% share in 2026 driven by high-density indoor Wi-Fi, Bluetooth Low Energy, and Matter mesh installations.
- By deployment environment: Indoor Consumer and Campus Networks command an estimated 61.0% share in 2026 through smart-home automation hubs, office access points, and retail electronic shelf labels.
Regional Highlights
- Top national expansion: Saudi Arabia leads national growth projections at an estimated 15.3% CAGR through 2036 under 6 GHz unlicensed spectrum allocation and giga-project smart-building wireless deployments.
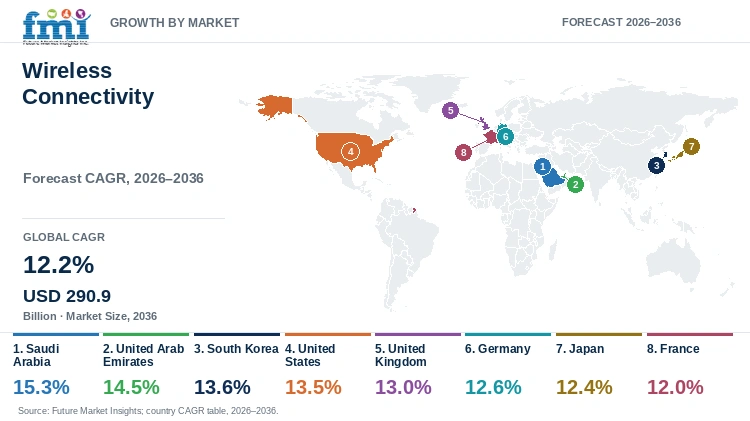
- Broader country progression: The United Arab Emirates tracks at an estimated 14.5% CAGR ahead of South Korea at 13.6% and the United States at 13.5%, while the United Kingdom advances at 13.0% and France records 12.0%.
Market Size & Forecast
Handset manufacturers, automotive tier-one suppliers, and industrial automation engineers face intense pressure to pack multiple radio protocols onto compact printed circuit boards without causing co-channel interference. When consumer gateways and factory sensors transmit simultaneously across crowded 2.4 GHz and 5 GHz spectrum bands, packet collisions degrade latency for real-time video and robotic control loops. Technical validation published on arXiv in July 2025 on IEEE 802.11be Extremely High Throughput (Wi-Fi 7) confirms that combining 320 MHz channel bandwidth with Multi-Link Operation delivers up to 30 Gbps throughput and deterministic low latency compared with legacy Wi-Fi 6 links. Consequently, hardware architects pair tri-band combo chipsets with radio frequency front-end modules to isolate coexisting signals.
Global Connected Device Shipments & Multi-Radio Silicon Sizing
Table 2: Connected Device Shipments and Multi-Radio Silicon Sizing for the Wireless Connectivity Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 82.0 | 92.0 | 290.9 |
| Annual Wi-Fi device shipments globally (billion units) | 3.8 to 4.0 | 4.1 to 4.4 | 7.2 to 7.8 |
| Annual Bluetooth-enabled product shipments (billion units) | 6.4 to 6.8 | 7.0 to 7.3 | 13.5 to 14.8 |
| Blended wireless silicon & RF content per connected device (USD) | 5.80 to 6.40 | 6.10 to 6.80 | 10.20 to 11.60 |
Operational note: Annual wireless connectivity silicon and module shipments cover standalone and combo Wi-Fi, Bluetooth LE, and cellular IoT chipsets across consumer and industrial equipment.
Battery-powered medical patches, electronic shelf labels, and smart-home locks require sub-milliwatt sleep currents with fast wake-up synchronization so coin-cell batteries last for five to ten years. System designers integrate Bluetooth Low Energy chipsets with energy-harvesting power management integrated circuits to eliminate manual battery replacements across commercial buildings. Industry roadmap documentation from Renesas Electronics confirms that global annual shipments of Bluetooth-enabled products are projected to reach 7.6 billion units by 2027, supported by Auracast broadcast audio and Periodic Advertisement with Response for retail electronic shelf labels.
Enterprise Access Point & Protocol Attach Rate Indicators
Table 3: Enterprise Access Point and Protocol Attach Rate Indicators for the Wireless Connectivity Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Wi-Fi 6E & Wi-Fi 7 access point shipments (million units) | 175.0 to 185.0 | 220.0 to 245.0 | 640.0 to 710.0 |
| Multi-protocol combo SoC share of chipset shipments (%) | 55.0% to 57.0% | 57.0% to 59.0% | 72.0% to 76.0% |
| Average wireless silicon content per connected vehicle (USD) | 48.0 to 56.0 | 55.0 to 64.0 | 135.0 to 160.0 |
| Short-Range Wireless Networks revenue share (%) | 53.0% to 54.5% | 53.5% to 55.0% | 56.0% to 59.0% |
Table 4: Semiconductor & Application Spending Indicators for the Wireless Connectivity Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 92.0 billion | 2026 global wireless connectivity silicon & module baseline |
| Annual Wi-Fi device shipments benchmark | 3.9 billion units | Wi-Fi Alliance 2025 global momentum shipment report |
| Projected Bluetooth annual device shipments by 2027 | 7.6 billion units | Bluetooth SIG & Renesas wireless connectivity benchmark |
| Consumer Electronics and Wearables revenue, 2026 | USD 42.32 billion | 46.0% end-use application allocation across handsets & wearables |
Evolution of broadband gateways and enterprise access points into intelligent edge service platforms requires dedicated neural processing cores embedded directly inside wireless baseband silicon. Telecom operators and enterprise IT buyers deploy AI-assisted radio resource management with millimeter-wave RF transceivers to steer client traffic dynamically across 2.4 GHz, 5 GHz, and 6 GHz channels. Product disclosures released by Qualcomm Technologies in October 2026 ahead of Network X 2026 substantiate this architectural shift, introducing the Dragonwing NPro A8 Elite platform with a Wi-Fi 8 foundation and integrated security management for AI-native broadband gateways.
Analyst Perspective
"Equipment makers no longer purchase isolated single-protocol radios; they specify monolithic tri-radio and quad-radio SoCs that run Wi-Fi 7, Bluetooth Channel Sounding, and Matter over Thread concurrently with on-chip edge AI. Semiconductor vendors that solve 2.4 GHz and 6 GHz coexistence while cutting standby current will win high-volume automotive, smart-home, and industrial design slots through 2036."
- Sudip Saha, Principal Consultant, Future Market Insights.
How is the wireless connectivity market segmented?
The wireless connectivity market is segmented by technology standard, hardware component, end-use application, network range, and deployment environment. In 2026, Wi-Fi 7 and 6E Standards are projected at 42.0%, Wireless Connectivity Chipsets and SoCs at 58.0%, Consumer Electronics and Wearables at 46.0%, Short-Range Wireless Networks at 54.0%, and Indoor Consumer and Campus Networks at 61.0%.
By technology standard: Wi-Fi 7 and 6E Standards, Bluetooth Low Energy and Classic, Zigbee Thread Matter and UWB and Cellular IoT and GNSS Positioning.
By hardware component: Wireless Connectivity Chipsets and SoCs, Integrated RF Modules and Transceivers, Embedded Antennas and Front-End Modules and Baseband Processors and Power Amplifiers.
By end-use application: Consumer Electronics and Wearables, Automotive Connected V2X Systems, Smart Home Appliances and Thermostats, Industrial IoT and Asset Trackers, and Smart Healthcare Patient Monitors.
By network range: Short-Range Wireless Networks, Low-Power Wide-Area Networks, Cellular Wide-Area IoT Networks and Satellite and GNSS Links.
By deployment environment: Indoor Consumer and Campus Networks, Industrial Plant and Warehouse Mesh, Automotive In-Cabin Telematics Networks and Outdoor Smart Grid Infrastructure.
Why do Wi-Fi 7 and 6E Standards lead the technology standard category?
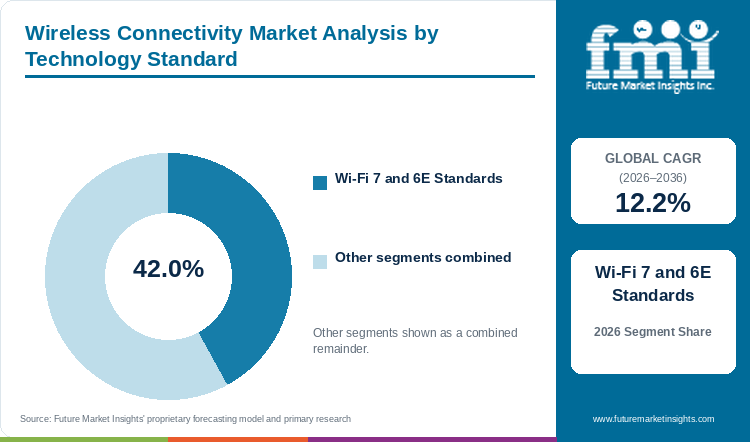
Wi-Fi 7 and 6E Standards hold an estimated 42.0% of technology standard demand in 2026, anchored by tri-band 6 GHz spectrum adoption across gateways, enterprise access points, and smartphones.
Table 5: Technology Standard Share for the Wireless Connectivity Market (percentage share), 2026
| Technology Standard | Share (2026) |
|---|---|
| Wi-Fi 7 and 6E Standards | 42.0% |
| Other Segments Combined | 58.0%* |
| Total | 100.0% |
*Note: Remaining technology standard categories account for the balance of 2026 global wireless connectivity demand.
Table 6: Technology Standard Leadership and Market Growth for the Wireless Connectivity Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 12.2% |
| Leading Segment | Wi-Fi 7 and 6E Standards |
Wi-Fi 7 and 6E Standards command the largest share of technology standard revenue since high-density enterprise campuses, residential fiber gateways, and flagship smartphones require multi-gigabit wireless backhaul that low-rate personal area networks cannot carry. Authorization of the 6 GHz band for unlicensed operation allows tri-band WLAN chipsets to utilize contiguous 160 MHz and 320 MHz channels with minimal legacy interference paired with wireless local area network silicon. Commercial rollouts of multi-link operation across enterprise routers and handsets continue to sustain premium pricing for tri-band silicon.
- Within the technology standard segment, Wi-Fi 7 and 6E Standards are projected to account for a leading 42.0% share in 2026, driven by higher average selling prices for tri-band 6 GHz silicon.
- Ultra-Wideband precision tracking and Bluetooth High Data Throughput standards are forecast to gain incremental share through 2036 as centimeter-level ranging and lossless audio scale across vehicles and wearables.
What sustains Wireless Connectivity Chipsets and SoCs leadership in the hardware component segment?
Wireless Connectivity Chipsets and SoCs represent an estimated 58.0% of the hardware component category in 2026, supported by monolithic Wi-Fi, Bluetooth, and 802.15.4 integration.
Wireless Connectivity Chipsets and SoCs dominate component expenditure since integrating the RF transceiver, baseband modem, and power management unit onto a single 22nm or 16nm CMOS die lowers bill-of-materials cost for high-volume OEMs. While smaller industrial device makers purchase pre-certified RF modules to bypass FCC and CE radio testing, tier-one smartphone and appliance brands buy bare combo SoCs in multi-million-unit reels and pair them with short-range ZigBee mesh modules on custom motherboards. Supply-chain complexity around advanced wafer foundry nodes remains the primary constraint for smaller fabless chipmakers.
- In 2026, Wireless Connectivity Chipsets and SoCs are anticipated to capture 58.0% of global hardware component demand, reflecting OEM preference for monolithic multi-protocol silicon.
- Product launches from Silicon Labs in August 2026 with its ultra-low-power BG2B Bluetooth LE SoC demonstrate how integrated security vaults and high power efficiency win space-constrained medical and retail sensor designs.
How does Consumer Electronics and Wearables lead the end-use application category?
Consumer Electronics and Wearables accounts for an estimated 46.0% of end-use application value in 2026, driven by high-volume handset, PC, and LE Audio wearable production.
Consumer Electronics and Wearables represents the largest end-use application buyer given that more than 1.2 billion smartphones, 400 million notebooks, and hundreds of millions of wireless earbuds and smartwatches ship every year with multi-protocol wireless combo chips inside. Flagship smartphones now incorporate Wi-Fi 7, dual-mode Bluetooth 5.4, and Ultra-Wideband digital car keys on every handset build. Technical specifications released by the Bluetooth Special Interest Group in November 2026 on Bluetooth High Data Throughput (HDT) confirm that next-generation spectral efficiency upgrades are designed to power lossless wireless audio, immersive AR/VR computing, and AI-enabled wearable peripherals. Device makers also embed ultra-wideband anchors and tags for peer-to-peer spatial finding.
- By end-use application, demand from Consumer Electronics and Wearables is estimated to reach 46.0% of total category share in 2026 as flagship and mid-tier handsets standardize Wi-Fi 7 and Bluetooth LE Audio.
- Over the forecast horizon, automotive V2X telematics and industrial factory automation are projected to record faster compound growth rates as connected vehicle production and wireless plant retrofits expand.
Why does Short-Range Wireless Networks lead the network range category?
Short-Range Wireless Networks secures an estimated 54.0% of network range demand in 2026, supported by license-free indoor Wi-Fi, Bluetooth LE, and Matter mesh deployments.
Short-Range Wireless Networks accounts for the majority of network range revenue since over 80% of global IP and sensor data originates or terminates indoors within 10 to 100 meters of a local access point or smart-home border router. Short-range unlicensed WLAN and WPAN protocols operate without recurring cellular SIM subscription fees, making them the default choice for connected home automation systems and enterprise office peripherals. Signal attenuation through reinforced concrete walls and 2.4 GHz microwave congestion remain practical operational hurdles that require self-healing Thread and Zigbee mesh topologies.
- High attachment density across home, office, and wearable devices places Short-Range Wireless Networks on course to hold an estimated 54.0% share of the network range category in 2026.
- Commercial deployment updates from the Connectivity Standards Alliance (CSA-IoT) for Matter Open Day 2026 confirm that major global appliance and smart-home brands are standardizing Matter over Wi-Fi and Thread across distribution channels.
What gives Indoor Consumer and Campus Networks the leading position in deployment environment?
Indoor Consumer and Campus Networks command an estimated 61.0% of deployment environment share in 2026, anchored by residential fiber gateways, office Wi-Fi 7 upgrades, and smart-home devices.
Indoor Consumer and Campus Networks command the largest share of deployment environment spending under conditions where corporate offices, hospitals, and multi-room residences require dense multi-band access point grids and millions of connected client endpoints. Deployment of enterprise Wi-Fi 7 access points simultaneously triggers demand for multi-gigabit PoE switches, embedded Bluetooth LE location beacons, and spectrum monitoring test equipment to guarantee interference-free voice and video roaming. Financial results published by Broadcom in September 2026 for its third quarter of fiscal year 2026, projecting a 66 percent non-GAAP operating income margin on strong enterprise networking and AI connectivity demand, reflect sustained capital investment in high-capacity campus and data-center infrastructure.
- Indoor Consumer and Campus Networks are predicted to secure 61.0% of deployment environment demand in 2026, supported by enterprise Wi-Fi 7 access point refresh cycles and smart-building sensor retrofits.
- Outdoor smart-grid metering and industrial plant floor mesh deployments are forecast to expand rapidly through 2036 as utilities and factories replace wired fieldbus cabling with ruggedized wireless transceivers.
What are the drivers, restraints, and opportunities in the wireless connectivity market?
In the wireless connectivity market, 6 GHz Wi-Fi 7/8 upgrades and Matter smart-home unification are projected to drive adoption whereas upper 6 GHz spectrum-sharing disputes and multi-radio interference restrain uniform design and edge-AI BLE/Wi-Fi combo SoCs open battery-powered IoT markets.
- Driver: Global 6 GHz unlicensed spectrum releases, Matter smart-home unification, and automotive digital-cockpit and UWB key adoption drive high-volume shipments of multi-protocol wireless combo SoCs.
- Restraint: Spectrum-sharing disputes between mobile 6G operators and unlicensed Wi-Fi in the upper 6 GHz band combined with multi-radio RF front-end coexistence complexity restrain uniform hardware design.
- Opportunity: Integration of neural edge-AI accelerators, Bluetooth Channel Sounding centimeter ranging, and ambient IoT energy harvesting into ultra-low-power wireless SoCs creates new industrial and medical revenue streams.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Regulatory allocation of unlicensed 6 GHz spectrum and the commercial convergence of Wi-Fi, Bluetooth, and 802.15.4 Thread onto unified Matter-certified silicon are propelling global wireless connectivity orders through 2036. When smart-appliance manufacturers and building automation integrators adopt multi-protocol combo modules, a single hardware SKU can join major smart-home platforms without custom gateway bridges. Product releases from Nordic Semiconductor in September 2026 expanding the 22 nm nRF54L Series with the nRF54LC10A multiprotocol SoC confirm how concurrent Bluetooth LE, Matter over Thread, and Zigbee radios operating at 4.0 mA receive current cut OEM board complexity. Concurrently, industrial buyers are pairing local mesh sensors with fifth-generation cellular IoT endpoints for wide-area backhaul.
Risk Assessment of the Wireless Connectivity Market: Operational and Formulation Friction
Divergent national spectrum allocations across the upper 6 GHz band (6425 to 7125 MHz) and intense RF interference inside compact multi-antenna devices represent key technical and regulatory hurdles restraining global hardware standardization. While the United States opened the full 1,200 MHz of 6 GHz spectrum for unlicensed Wi-Fi, European and Asian regulators continue evaluating shared mobile 6G and Wi-Fi licensing rules that require complex Automated Frequency Coordination (AFC) databases. In July 2026, UK telecom regulator Ofcom published its statement on commercial mobile and Wi-Fi access in the 6 GHz band, proposing high-density urban mobile priority zones with indoor Wi-Fi sharing constraints. Hardware OEMs must consequently maintain regional RF filter variants and firmware power tables to pass country-by-country type approvals.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Semiconductor manufacturers are capturing premium average selling prices by combining sub-nanosecond channel sounding, edge machine-learning inference, and automotive-grade Ultra-Wideband ranging inside next-generation wireless SoCs. In October 2025, Nordic Semiconductor became the first supplier to bring Bluetooth Channel Sounding to an open-source Android app using its nRF54L Series and the Google Pixel 10, enabling centimeter-accurate ranging for digital keys and warehouse asset tags. Furthermore, academic wireless channel research published on arXiv in November 2026 on ray-tracing dynamic channel sounding for Wi-Fi 7 demonstrates how AI-assisted channel prediction improves link reliability across mobile industrial environments.
Wireless Connectivity Market by Country (2026 to 2036)
FMI country modeling indicates that Saudi Arabia leads wireless connectivity expansion at an estimated 15.3% CAGR through 2036, followed by the United Arab Emirates at 14.5% and South Korea at 13.6%. National growth variations reflect 6 GHz spectrum policy, domestic semiconductor and electronics manufacturing, and smart-city and automotive wireless investments.
Table 7: Country CAGR and Primary Growth Levers for the Wireless Connectivity Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Saudi Arabia | 15.3% | CST full 6 GHz unlicensed spectrum release and giga-project smart-city wireless buildouts |
| United Arab Emirates | 14.5% | Smart-hospitality Wi-Fi 7 campus upgrades and automated port and retail ESL deployments |
| South Korea | 13.6% | Flagship smartphone, appliance, and EV combo SoC manufacturing and 10G home gateways |
| United States | 13.5% | FCC 6 GHz AFC standard-power Wi-Fi 7 rollouts and enterprise campus and medical wearables |
| United Kingdom | 13.0% | Ofcom Upper 6 GHz spectrum-sharing framework and commercial smart-building retrofits |
| Germany | 12.6% | Automotive OEM connected-vehicle partnerships and Industry 4.0 factory wireless automation |
| Japan | 12.4% | MIC 6 GHz WLAN authorization and robotics and medical device RF module integration |
| France | 12.0% | Arcep eco-design energy-efficient Wi-Fi 7 gateways and Matter smart-building retrofits |
Source: Future Market Insights analysis
Saudi Arabia Wireless Connectivity Market Outlook (2026 to 2036)
Demand for wireless connectivity in Saudi Arabia is projected to expand at a leading 15.3% CAGR between 2026 and 2036 across giga-project smart buildings, automated logistics corridors, and enterprise Wi-Fi 7 campus networks. Domestic demand is anchored by greenfield installation of millions of Wi-Fi 7 access points and cellular IoT utility meters across Riyadh, Jeddah, and Red Sea urban developments. Early authorization of the full 6 GHz unlicensed spectrum band by the Saudi Communications, Space and Technology Commission (CST) aligns with regulatory momentum documented by the U.S. Federal Communications Commission for next-generation gigabit Wi-Fi connectivity. Local system integrators prioritize ruggedized tri-band outdoor access points and industrial asset-tracking tags.
Key takeaway: In Saudi Arabia, full 6 GHz unlicensed spectrum availability and greenfield smart-city and industrial IoT buildouts are projected to drive global-leading wireless connectivity demand.
United Arab Emirates Wireless Connectivity Market Outlook (2026 to 2036)
Across the United Arab Emirates, smart-hospitality resorts and automated seaport and airport terminals are deploying high-density Wi-Fi 7 and Ultra-Wideband infrastructure. Consequently, national wireless connectivity adoption is anticipated to advance at a 14.5% CAGR through 2036, outpacing global baseline averages due to aggressive enterprise campus upgrades in Dubai and Abu Dhabi. Industry IoT adoption benchmarks published by Zoho in June 2026 show how rapid enterprise digital scaling across smart cities, energy utilities, and connected warehouses drives demand for low-power wireless sensor networks and cloud-integrated gateways. Emirati hospitality and retail operators lead regional deployment of Bluetooth LE electronic shelf labels and UWB indoor navigation.
Key takeaway: In the United Arab Emirates, smart-hospitality Wi-Fi 7 upgrades and automated port and retail wireless tracking are anticipated to sustain strong procurement of multi-protocol modules.
South Korea Wireless Connectivity Market Outlook (2026 to 2036)
South Korea's wireless connectivity sector is forecast to progress at a 13.6% CAGR from 2026 to 2036, anchored by massive domestic production of flagship smartphones and connected vehicles. Korean electronics giants specify tens of millions of Wi-Fi 7 and UWB combo chipsets directly into export-bound devices while rolling out 10-gigabit residential broadband gateways domestically. Global semiconductor industry benchmarks from the Semiconductor Industry Association (SIA) and World Semiconductor Trade Statistics confirm the scale of Asia-Pacific electronics demand that underpins Korean wireless wafer and packaging consumption. Korean automotive OEMs are also standardizing UWB digital key modules and V2X telematics across electric vehicle platforms.
Key takeaway: In South Korea, flagship smartphone and electric-vehicle manufacturing paired with 6 GHz home gateways are forecast to propel high-volume combo SoC procurement.
United States Wireless Connectivity Market Outlook (2026 to 2036)
Commercial wireless connectivity expenditure in the United States is estimated to progress at a 13.5% CAGR between 2026 and 2036 across hyperscale enterprise campuses, fiber broadband operators, and connected healthcare facilities. What sets the United States apart from European markets is FCC authorization of Automated Frequency Coordination (AFC) standard-power operation across the entire 6 GHz band, enabling long-range outdoor and stadium Wi-Fi 7 deployments. Technical analyses published by the Wi-Fi Alliance on 6 GHz spectrum utilization document how wide contiguous channels support low-latency extended reality and industrial IoT across U.S. enterprises.
Key takeaway: In the United States, FCC 6 GHz standard-power AFC operation and enterprise Wi-Fi 7 and wearable medical device upgrades are estimated to anchor high-value silicon and module sales.
United Kingdom Wireless Connectivity Market Outlook (2026 to 2036)
Spectrum policy reforms and smart-building energy retrofits in the United Kingdom are shaping how telecom carriers and enterprise IT directors deploy next-generation wireless networks. FMI country modeling indicates that wireless connectivity growth in the United Kingdom is slated to track at a 13.0% CAGR over the 2026 to 2036 forecast period. In August 2026, UK telecom regulator Ofcom opened its formal consultation on future mobile use and incumbent Wi-Fi users in the 6425 to 7125 MHz band, proposing spectrum-sharing rules so high-density urban mobile networks and indoor enterprise Wi-Fi routers can coexist efficiently.
Key takeaway: In the United Kingdom, Ofcom Upper 6 GHz spectrum-sharing rules and enterprise smart-building and retail ESL retrofits are slated to support steady multi-protocol wireless adoption.
Germany Wireless Connectivity Market Outlook (2026 to 2036)
Germany's automotive OEMs, industrial machinery builders, and factory automation integrators represent Europe's largest buyer pool for ruggedized industrial wireless modules and automotive V2X/UWB transceivers. Demand for wireless connectivity in Germany is likely to increase at a 12.6% CAGR through 2036, diverging from consumer-heavy regional markets due to deep Industry 4.0 factory sensor integration and sovereign automotive semiconductor partnerships. On October 26, 2026, NXP Semiconductors announced a strategic semiconductor partnership with the Volkswagen Group to co-develop next-generation connected vehicle and zonal electronic architectures. German industrial plant operators also pair private 5G campus networks with IEEE 802.15.4 and Bluetooth LE sensor meshes for predictive maintenance.
Key takeaway: In Germany, automotive OEM semiconductor partnerships and Industry 4.0 factory automation retrofits are likely to drive sustained demand for automotive UWB and industrial wireless modules.
Japan Wireless Connectivity Market Outlook (2026 to 2036)
Japanese robotics manufacturers, precision medical device makers, and automotive electronics suppliers prioritize compact low-noise RF modules and long-lifecycle industrial wireless chipsets. Procurement of wireless connectivity in Japan is predicted to advance at a 12.4% CAGR between 2026 and 2036 following Ministry of Internal Affairs and Communications (MIC) authorization of 6 GHz WLAN operation across domestic enterprises. Official labor and demographic statistics published by Japan's Ministry of Internal Affairs and Communications (MIC) in October 2026 confirm the acute workforce aging pressures that compel Japanese factories, warehouses, and hospitals to automate operations using wireless mobile robots and remote patient monitors. Domestic buyers favor pre-certified shielded RF front-end and combo modules.
Key takeaway: In Japan, labor-saving factory and hospital automation combined with MIC 6 GHz WLAN authorization are predicted to sustain high-reliability RF module and combo SoC demand.
France Wireless Connectivity Market Outlook (2026 to 2036)
French telecommunications operators, aerospace and automotive manufacturers, and commercial building owners are upgrading legacy wireless local area networks toward energy-efficient Wi-Fi 7 and Matter smart-building standards. Consequently, wireless connectivity sales in France are expected to expand at a 12.0% CAGR between 2026 and 2036 as enterprise buyers balance multi-gigabit capacity with strict environmental power-consumption targets. In May 2026, French telecom regulator Arcep published its annual 'Pour un numérique soutenable' (Achieving Digital Sustainability) survey covering 23 terminal equipment manufacturers and 160 data centers, documenting rising regulatory focus on terminal energy efficiency and eco-designed wireless gateways. French residential fiber boxes and corporate campuses lead continental adoption of low-standby-power Wi-Fi 7 gateways.
Key takeaway: In France, Arcep eco-design energy-efficiency benchmarks and fiber-gateway Wi-Fi 7 upgrades are expected to guide enterprise and telecom procurement toward low-power wireless silicon.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the wireless connectivity market?
Qualcomm Incorporated, Broadcom Inc., MediaTek Inc., NXP Semiconductors N.V., Texas Instruments Incorporated, Silicon Laboratories Inc., Nordic Semiconductor ASA, Infineon Technologies AG, STMicroelectronics N.V., and Renesas Electronics Corporation are the notable companies in the wireless connectivity market.
Competitive positioning in the wireless connectivity industry divides into high-throughput Wi-Fi 7 and broadband SoC leaders, ultra-low-power Bluetooth LE and industrial wireless specialists, and embedded microcontroller and industrial RF solution providers. Qualcomm and Broadcom dominate smartphone, PC, and enterprise access-point combo chipsets while MediaTek and NXP Semiconductors scale tri-band client and automotive platforms. Texas Instruments and Silicon Labs lead battery-operated Bluetooth LE and Matter silicon with Nordic Semiconductor and Infineon Technologies. In addition, STMicroelectronics and Renesas Electronics supply integrated wireless MCUs and industrial connectivity solutions.
- High-Throughput Wi-Fi 7 and Broadband SoC Leaders: Qualcomm, Broadcom, MediaTek and NXP Semiconductors engineer tri-band Wi-Fi 7/8 and UWB combo chipsets for handsets and gateways.
- Ultra-Low-Power Bluetooth LE and Industrial Wireless Specialists: Texas Instruments, Silicon Labs, Nordic Semiconductor and Infineon Technologies supply multi-protocol BLE and low-power Wi-Fi SoCs for IoT edge devices.
- Embedded Microcontroller and Industrial RF Solution Providers: STMicroelectronics and Renesas Electronics integrate wireless connectivity and secure NFC across industrial, medical, and consumer microcontroller families.
Competitive Benchmarking: Wireless Connectivity Market
Table 8: Competitive Benchmarking for the Wireless Connectivity Market (qualitative capability ratings), 2026
| Company | Multi-Gigabit Wi-Fi 7/8 & 6 GHz Capability | Ultra-Low-Power BLE & Matter Mesh Integration | Automotive & Industrial Qualification | Geographic Reach |
|---|---|---|---|---|
| Qualcomm Incorporated | High | High | High | Global FastConnect mobile combo and Dragonwing NPro A8 Elite Wi-Fi 8 broadband footprint |
| Broadcom Inc. | High | High | Medium | Global enterprise access point (BCM43740) and flagship handset Wi-Fi 7/Bluetooth combo leader |
| MediaTek Inc. | High | High | Medium | Global Filogic Wi-Fi 7 and CES 2026 Filogic 8000 Wi-Fi 8 portfolio across routers, TVs, and PCs |
| NXP Semiconductors N.V. | High | High | High | 30+ country footprint; RW610 tri-radio Matter SoCs and Oct 2026 Volkswagen automotive partnership |
| Texas Instruments Incorporated | Medium | High | High | Global SimpleLink Wi-Fi 6 and Bluetooth LE industrial and automotive wireless MCU portfolio |
| Silicon Laboratories Inc. | Medium | High | High | Global IoT pure-play; launched ultra-low-power BG2B Bluetooth LE SoC in August 2026 |
| Nordic Semiconductor ASA | Medium | High | High | Global BLE leader; launched nRF71 edge-AI Wi-Fi/BLE SoC in Nov 2026 and proved Bluetooth HDT in Oct 2026 |
| Infineon Technologies AG | Medium | High | High | Global AIROC Wi-Fi, Bluetooth, and Matter over Thread automotive and smart-home solutions |
| STMicroelectronics N.V. | Medium | High | High | Global STM32WBA wireless MCUs, secure NFC, and LEO/industrial RF; USD 3.76B Q3 2026 revenue |
| Renesas Electronics Corporation | Medium | High | High | Global BLE, Wi-Fi, and NFC IoT solutions supporting Auracast and retail Electronic Shelf Labels |
Evaluation basis: Multi-Gigabit Wi-Fi 7/8 & 6 GHz Capability rates tri-band 320 MHz, Multi-Link Operation, and AFC gateway silicon maturity. Ultra-Low-Power BLE & Matter Mesh Integration evaluates sleep-current efficiency and concurrent 802.15.4/Thread protocol stacks, while Automotive & Industrial Qualification measures AEC-Q100 grade temperature reliability and long-term supply assurance.
Key Developments in the Wireless Connectivity Market
- STMicroelectronics reported third-quarter 2026 net revenues of USD 3.76 billion on November 2, 2026 (up 17.9% year over year) and guided full-year 2026 revenue to approximately USD 14.5 billion on recovering personal electronics and connected communications demand.
- Biomedical engineering researchers demonstrated multi-channel Bluetooth haptic medical stimulation testbeds on November 3, 2026 as wearable healthcare device makers expanded low-latency wireless sensor procurement.
- MediaTek expanded its mainstream Wi-Fi 7 connectivity portfolio with the Filogic 360 single-chip Wi-Fi 7 2x2 and dual Bluetooth 5.4 combo SoC delivering 2.9 Gbps speed and Hybrid Multi-Link Operation ahead of its CES 2026 Filogic 8000 demonstration.
Key Players in the Wireless Connectivity Market
High-Throughput Wi-Fi 7 and Broadband SoC Leaders
- Qualcomm Incorporated
- Broadcom Inc.
- MediaTek Inc.
- NXP Semiconductors N.V.
Ultra-Low-Power Bluetooth LE and Industrial Wireless Specialists
- Texas Instruments Incorporated
- Silicon Laboratories Inc.
- Nordic Semiconductor ASA
- Infineon Technologies AG
Embedded Microcontroller and Industrial RF Solution Providers
- STMicroelectronics N.V.
- Renesas Electronics Corporation
Wireless Connectivity Market - Report Scope
Table 9: Report Scope for the Wireless Connectivity Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Technology Standard; Hardware Component; End-Use Application; Network Range; Deployment Environment |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial semiconductor and hardware supplier revenue from wireless connectivity chipsets and system-on-chips (SoCs), integrated RF modules and transceivers, embedded antennas, and wireless RF front-end modules operating across Wi-Fi (802.11a/b/g/n/ac/ax/be/bn), Bluetooth Classic and Low Energy, IEEE 802.15.4 (Zigbee, Thread, Matter), Ultra-Wideband (UWB), Cellular IoT (NB-IoT, LTE-M, 5G RedCap), and GNSS positioning protocols. Category Scope Note: Excludes recurring cellular telecom carrier subscription fees, fiber-optic cable infrastructure, and standalone host application processors. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Saudi Arabia, United Arab Emirates, South Korea, United States, United Kingdom, Germany, Japan, France, and additional countries in the full report |
| Key Companies Covered | Qualcomm Incorporated, Broadcom Inc., MediaTek Inc., NXP Semiconductors N.V., Texas Instruments Incorporated, Silicon Laboratories Inc., Nordic Semiconductor ASA, Infineon Technologies AG, STMicroelectronics N.V., Renesas Electronics Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Wireless Connectivity Market - Research Methodology
Table 10: Research Methodology for the Wireless Connectivity Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with wireless semiconductor product directors, RF front-end module architects, enterprise WLAN access-point OEMs, and automotive telematics engineers to validate combo SoC pricing and protocol attach rates. |
| Secondary Research | Analysis of FCC 6 GHz spectrum orders, UK Ofcom Upper 6 GHz consultations, French Arcep sustainability reports, Wi-Fi Alliance and Bluetooth SIG shipment benchmarks, IEEE 802.11be arXiv studies, and semiconductor Q3 2026 filings. |
| Market Sizing and Forecasting | Top-down global semiconductor and RF module baselines reconciled against bottom-up annual connected device shipments (3.9B+ Wi-Fi and 7.0B+ Bluetooth units) and blended wireless silicon content per board from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight 6 GHz unlicensed spectrum availability, domestic smartphone/appliance/automotive manufacturing output, smart-city building mandates, and factory automation density across eight countries. |
| Operational Benchmark Traceability | Device shipment, access point, and silicon content indicators in Tables 2, 3, and 4 trace to Wi-Fi Alliance 2025 momentum data, Bluetooth SIG/Renesas 7.6B shipment forecasts, and Broadcom, NXP, and STMicroelectronics 2026 disclosures. |
| Data Triangulation and Validation | Revenue estimates isolate wireless baseband/RF chipsets, pre-certified connectivity modules, and wireless RF front-ends while strictly excluding telecom operator service plans, passive Ethernet cabling, and non-wireless microcontrollers. |
Wireless Connectivity Market by Segments
Wireless Connectivity Market segmented by Technology Standard:
- Wi-Fi 7 and 6E Standards
- Bluetooth Low Energy and Classic
- Zigbee Thread Matter and UWB
- Cellular IoT and GNSS Positioning
Wireless Connectivity Market segmented by Hardware Component:
- Wireless Connectivity Chipsets and SoCs
- Integrated RF Modules and Transceivers
- Embedded Antennas and Front-End Modules
- Baseband Processors and Power Amplifiers
Wireless Connectivity Market segmented by End-Use Application:
- Consumer Electronics and Wearables
- Automotive Connected V2X Systems
- Smart Home Appliances and Thermostats
- Industrial IoT and Asset Trackers
- Smart Healthcare Patient Monitors
Wireless Connectivity Market segmented by Network Range:
- Short-Range Wireless Networks
- Low-Power Wide-Area Networks
- Cellular Wide-Area IoT Networks
- Satellite and GNSS Links
Wireless Connectivity Market segmented by Deployment Environment:
- Indoor Consumer and Campus Networks
- Industrial Plant and Warehouse Mesh
- Automotive In-Cabin Telematics Networks
- Outdoor Smart Grid Infrastructure
Wireless Connectivity Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Autorité de Régulation des Communications Électroniques (Arcep). (2026, May 21). Annual Survey 'Pour un Numérique Soutenable' (Edition 2026): Environmental Footprint of Digital Terminals and Data Centers. Arcep Official Publications.
- Biomedical Haptics Research Group. (2026, November 3). OUCH: Objective, Uniform, Controlled Haptic Stimulation Testbed Over Multi-Channel Bluetooth. arXiv Quantitative Biology and Medical Devices Archive.
- Bluetooth Special Interest Group (SIG). (2026, November 5). Bluetooth High Data Throughput (HDT) Will Power the Next Generation of Wireless Experiences. Bluetooth SIG Technical Blog.
- Broadcom Inc. (2026, September 2). Broadcom Inc. Announces Third Quarter Fiscal Year 2026 Financial Results and Fourth Quarter Outlook. Broadcom Investor Relations.
- Connectivity Standards Alliance (CSA). (2026, June 15). Matter Open Day 2026: Global Smart Home Interoperability and Commercial Expansion. Connectivity Standards Alliance.
- Federal Communications Commission (FCC). (2024, November 15). FCC Votes to Enable Better, Faster Wi-Fi and Next-Gen Connectivity in the 6 GHz Band. U.S. Federal Communications Commission.
- Lukaszewski, C. (2025, April 10). Wi-Fi 6E and 6 GHz Spectrum: The Technical Details You Need to Know. Wi-Fi Alliance Beacon.
- MediaTek Inc. (2024, November 19). MediaTek Expands Wi-Fi 7 Portfolio with New Filogic 360 Chipsets for Mainstream Devices. MediaTek Press Room.
- Ministry of Internal Affairs and Communications (MIC). (2026, October 2). Statistical Survey Release on Labor Force and Industrial Automation Context in Japan (August 2026 Results). Ministry of Internal Affairs and Communications, Japan.
- MIMO Channel Research Contributors. (2026, November 5). Ray-Tracing-Based Dynamic Channel Sounding and Prediction in Single-STA Wi-Fi 7 Links. arXiv Wireless Communications Archive.
- Nordic Semiconductor ASA. (2025, October 28). Nordic Semiconductor First to Bring Bluetooth Channel Sounding to Open-Source Android App Using nRF54L Series and Google Pixel 10. Nordic Semiconductor Newsroom.
- Nordic Semiconductor ASA. (2026, September 15). Nordic Semiconductor Continues nRF54L Series Expansion with New Multiprotocol SoC for Size- and Cost-Effective IoT Devices. Nordic Semiconductor Newsroom.
- Nordic Semiconductor ASA. (2026, November 3). Nordic Brings Edge AI to Battery-Powered Wi-Fi Devices, Achieving Twenty Times Lower Standby Power with nRF71 Series. Nordic Semiconductor Newsroom.
- NXP Semiconductors N.V. (2026, October 6). NXP Semiconductors Financial Updates and Strategic Automotive Semiconductor Partnership with Volkswagen Group. NXP Semiconductors Newsroom.
- Ofcom. (2026, July 20). Statement: Expanding Access to the 6 GHz Band for Commercial Mobile and Wi-Fi Services. UK Office of Communications (Ofcom).
- Ofcom. (2026, August 3). Consultation: Expanding Access to the 6 GHz Band for Future Mobile Use and Incumbent Wi-Fi Users. UK Office of Communications (Ofcom).
- Qualcomm Technologies, Inc. (2026, October 12). Qualcomm Unveils AI-Native Broadband Innovations Across Fiber, Wi-Fi 8, Fixed Wireless, and Network Security at Network X 2026. Qualcomm Press Releases.
- Renesas Electronics Corporation. (2025, June 12). Simplifying the Connected Future: Navigating Complexity in the IoT with Bluetooth LE, Auracast, and Matter. Renesas Technical Whitepaper.
- Semiconductor Industry Association (SIA). (2025, March 10). Global Semiconductor Sales and WSTS Regional Industry Forecast Benchmarks. Semiconductor Industry Association.
- Silicon Laboratories Inc. (2026, August 4). Silicon Labs Unveils BG2B, Its Lowest-Power Bluetooth LE SoC with Industry-Leading Power Efficiency and Security. Silicon Labs Media Room.
- STMicroelectronics N.V. (2026, November 2). STMicroelectronics Reports 2026 Third Quarter Financial Results and USD 14.5 Billion Full-Year Revenue Outlook. STMicroelectronics Media Center.
- Wi-Fi Alliance. (2025, February 18). Powering a Connected World: Wi-Fi Momentum in 2025 and 6 GHz Device Shipment Forecast. Wi-Fi Alliance Beacon.
- Wireless Networking Research Group. (2025, July 24). IEEE 802.11be Wi-Fi 7: Feature Summary and Performance Validation of 30 Gbps Extremely High Throughput. arXiv Electrical Engineering and Systems Science Archive.
- Zoho Corporation. (2026, June 17). 2026 IoT Connectivity Trends: Enterprise Scalability, Smart Cities, and Industrial Automation. Zoho IoT Hub Research.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the wireless connectivity market in 2026 and what is forecast for 2036?
- Which 6 GHz Wi-Fi 7/8 upgrades and Matter multi-protocol IoT deployments support demand for wireless connectivity?
- Why do Wi-Fi 7 and 6E Standards lead the technology standard category?
- Why do Wireless Connectivity Chipsets and SoCs lead the hardware component category globally?
- How do growth rates differ across Saudi Arabia, the United Arab Emirates, and South Korea?
- Which leading companies supply high-throughput Wi-Fi 7/8 combo SoCs versus ultra-low-power BLE and mesh silicon today?
- What upper 6 GHz spectrum-sharing rules or multi-radio coexistence challenges restrain uniform hardware design?
- What should device OEMs evaluate when selecting between bare wireless combo SoCs and pre-certified RF modules?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Technology Standard, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology Standard, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology Standard, 2026 to 2036
- Wi-Fi 7 and 6E Standards
- Bluetooth Low Energy and Classic
- Zigbee Thread Matter and UWB
- Cellular IoT and GNSS Positioning
- Y-o-Y Growth Trend Analysis By Technology Standard, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology Standard, 2026 to 2036
- Global Market Analysis and Forecast, By Hardware Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Hardware Component, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Hardware Component, 2026 to 2036
- Wireless Connectivity Chipsets and SoCs
- Integrated RF Modules and Transceivers
- Embedded Antennas and Front-End Modules
- Baseband Processors and Power Amplifiers
- Y-o-Y Growth Trend Analysis By Hardware Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Hardware Component, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Consumer Electronics and Wearables
- Automotive Connected V2X Systems
- Smart Home Appliances and Thermostats
- Industrial IoT and Asset Trackers
- Smart Healthcare Patient Monitors
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Network Range, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Network Range, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Network Range, 2026 to 2036
- Short-Range Wireless Networks
- Low-Power Wide-Area Networks
- Cellular Wide-Area IoT Networks
- Satellite and GNSS Links
- Y-o-Y Growth Trend Analysis By Network Range, 2021 to 2025
- Absolute $ Opportunity Analysis By Network Range, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment Environment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Deployment Environment, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Deployment Environment, 2026 to 2036
- Indoor Consumer and Campus Networks
- Industrial Plant and Warehouse Mesh
- Automotive In-Cabin Telematics Networks
- Outdoor Smart Grid Infrastructure
- Y-o-Y Growth Trend Analysis By Deployment Environment, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment Environment, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- United Arab Emirates
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Technology Standard
- By Hardware Component
- By End-Use Application
- By Network Range
- By Deployment Environment
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Qualcomm Incorporated
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Broadcom Inc.
- MediaTek Inc.
- NXP Semiconductors N.V.
- Texas Instruments Incorporated
- Silicon Laboratories Inc.
- Nordic Semiconductor ASA
- Infineon Technologies AG
- STMicroelectronics N.V.
- Renesas Electronics Corporation
- Qualcomm Incorporated
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Technology Standard, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Hardware Component, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Network Range, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Deployment Environment, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Technology Standard, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Hardware Component, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Network Range, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Deployment Environment, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Technology Standard, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Hardware Component, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Network Range, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Deployment Environment, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Technology Standard, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Hardware Component, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Network Range, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Deployment Environment, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Technology Standard, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Hardware Component, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Network Range, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Deployment Environment, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Technology Standard, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Hardware Component, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Network Range, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Deployment Environment, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Technology Standard, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Hardware Component, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Network Range, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Deployment Environment, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Technology Standard, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Hardware Component, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Network Range, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Deployment Environment, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Technology Standard, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Technology Standard, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Technology Standard
- Figure 6: Global Market Value Share and BPS Analysis by Hardware Component, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Hardware Component, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Hardware Component
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Application
- Figure 12: Global Market Value Share and BPS Analysis by Network Range, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Network Range, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Network Range
- Figure 15: Global Market Value Share and BPS Analysis by Deployment Environment, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Deployment Environment, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Deployment Environment
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Technology Standard, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Technology Standard, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Technology Standard
- Figure 32: North America Market Value Share and BPS Analysis by Hardware Component, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Hardware Component, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Hardware Component
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Application
- Figure 38: North America Market Value Share and BPS Analysis by Network Range, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Network Range, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Network Range
- Figure 41: North America Market Value Share and BPS Analysis by Deployment Environment, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Deployment Environment, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Deployment Environment
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Technology Standard, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Technology Standard, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Technology Standard
- Figure 48: Latin America Market Value Share and BPS Analysis by Hardware Component, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Hardware Component, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Hardware Component
- Figure 51: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 54: Latin America Market Value Share and BPS Analysis by Network Range, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Network Range, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Network Range
- Figure 57: Latin America Market Value Share and BPS Analysis by Deployment Environment, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Deployment Environment, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Deployment Environment
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Technology Standard, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Technology Standard, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Technology Standard
- Figure 64: Western Europe Market Value Share and BPS Analysis by Hardware Component, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Hardware Component, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Hardware Component
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by Network Range, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Network Range, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Network Range
- Figure 73: Western Europe Market Value Share and BPS Analysis by Deployment Environment, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Deployment Environment, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Deployment Environment
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Technology Standard, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Technology Standard, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Technology Standard
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Hardware Component, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Hardware Component, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Hardware Component
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Network Range, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Network Range, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Network Range
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Deployment Environment, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Deployment Environment, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Deployment Environment
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Technology Standard, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Technology Standard, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Technology Standard
- Figure 96: East Asia Market Value Share and BPS Analysis by Hardware Component, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Hardware Component, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Hardware Component
- Figure 99: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 102: East Asia Market Value Share and BPS Analysis by Network Range, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Network Range, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Network Range
- Figure 105: East Asia Market Value Share and BPS Analysis by Deployment Environment, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Deployment Environment, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Deployment Environment
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Technology Standard, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Technology Standard, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Technology Standard
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Hardware Component, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Hardware Component, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Hardware Component
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Network Range, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Network Range, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Network Range
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Deployment Environment, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Deployment Environment, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Deployment Environment
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Technology Standard, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Technology Standard, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Technology Standard
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Hardware Component, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Hardware Component, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Hardware Component
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Network Range, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Network Range, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Network Range
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Deployment Environment, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Deployment Environment, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Deployment Environment
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the wireless connectivity market in 2026, and what is forecast for 2036?
FMI estimates that the global wireless connectivity market size stood at USD 82.0 billion in 2025 and reached USD 92.0 billion in 2026. Valuation is projected to hit USD 290.9 billion by 2036.
What is the CAGR for the wireless connectivity market from 2026 to 2036?
The wireless connectivity sector is projected to expand at a 12.2% CAGR over the 2026 to 2036 window, generating USD 198.9 billion in incremental revenue across global semiconductor and module suppliers.
Which technology standard segment leads the wireless connectivity market?
Wi-Fi 7 and 6E Standards hold an estimated 42.0% of technology standard demand in 2026 since 6 GHz spectrum channels and Multi-Link Operation power high-capacity gateways and handsets.
Which hardware component segment leads the wireless connectivity market?
Wireless Connectivity Chipsets and SoCs represent an estimated 58.0% of the hardware component category in 2026 given that OEMs standardize monolithic multi-protocol combo silicon.
Which country has a notable growth outlook during the assessment period?
Saudi Arabia leads national expansion projections at an estimated 15.3% CAGR through 2036, driven by full 6 GHz unlicensed spectrum availability and smart-city and industrial IoT deployments.
Who are the key players in the market?
Qualcomm, Broadcom, MediaTek and NXP Semiconductors lead Wi-Fi 7 and automotive combo silicon. Texas Instruments, Silicon Labs and Nordic Semiconductor lead BLE SoCs. Infineon, STMicroelectronics and Renesas supply IoT and MCU radios.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
