
- Market Size (2026)
- USD 12.6 Bn
- Forecast (2036)
- USD 24.3 Bn
- CAGR (2026 to 2036)
- 6.8%
How big is Wood Pellets Market in 2026?
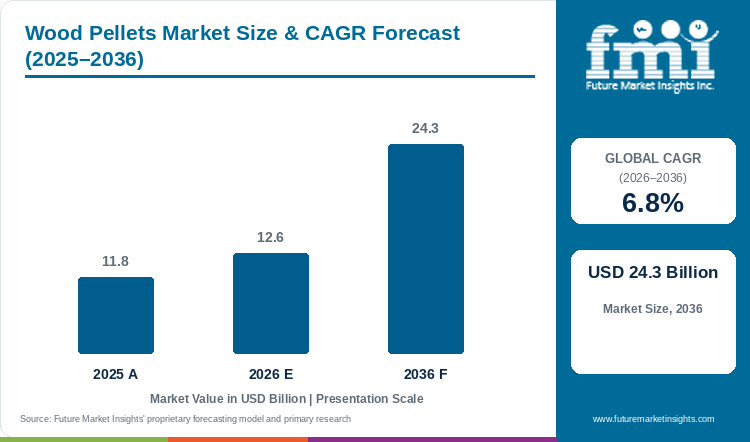
Starting from USD 11.8 billion in 2025, the wood pellets market valuation advanced to USD 12.6 billion in 2026, with projections pointing toward USD 24.3 billion by 2036 at a CAGR of 6.8%.
Global wood pellets industry valuation reached USD 11.8 billion in 2025 and is projected to hit USD 12.6 billion in 2026. Over the forecast horizon, the market size is anticipated to climb to USD 24.3 billion by 2036, advancing at a compound annual growth rate (CAGR) of 6.8% from 2026 to 2036. Procurement analysis by FMI finds that Industrial Utility-Grade High-Volume Pellets (I1 and I2) are expected to secure 53.8% of 2026 demand, while residential heating appliances capture the highest per-tonne price realization across European and North American retail channels. Buyer consumption of densified wood fuel is propelled by dual fuel-switching economics, given that households replace fossil heating oil and gas boilers to capture a 21% to 45% retail heating cost savings while utilities lock in dispatchable baseload power, lifting global production by 10% in 2025 to a record 53.5 million tonnes according to Bioenergy Europe.
That recurring fuel replenishment cycle distinguishes consumable pellet trade from capital equipment sales of woody biomass boilers expanding at a 9.1% CAGR, where upfront appliance subsidies trigger multi-decade fuel burn. Pellet producers and utilities are restructuring supply chains to secure fiber availability, as Graanul Invest launched its 07 Graanul household pellet brand in October 2026 to broaden raw material sourcing, NB Power signed multi-year Canadian pellet supply agreements in September 2026 to convert its Belledune coal station, and Drax Group produced a record 4.2 million tonnes of pellets during 2025. Mills that pair sawmill residue offtake with verified deforestation-free chain-of-custody documentation retain utility and retail distributor contracts through 2036.
Key Market Trends & Insights
- By pellet grade: Industrial Utility-Grade High-Volume Pellets (I1 and I2) are expected to hold an estimated 53.8% share in 2026 owing to multi-million-tonne seaborne utility imports in the United Kingdom, Japan, and South Korea.
- By feedstock sourcing: Sawmill Sawdust and Wood Shavings Residues are projected to represent 56.4% in 2026 since clean planer shavings require lower drying energy and yield low-ash pellets.
- By end-use application: Residential Pellet Stoves and Home Biomass Boilers are anticipated to account for 38.4% of value in 2026 given that bagged and blown ENplus A1 heating fuel commands a substantial price premium over bulk utility tonnage.
- By certification standard: Sustainable Biomass Program (SBP) Certified Pellets are estimated to secure 39.5% in 2026 as European and Asian utilities mandate audited carbon and legality compliance for subsidy eligibility.
- By distribution format: Bulk Ocean Vessel and Rail Hopper Shipments are forecast to command 51.6% in 2026 through deep-water port terminals and automated unit-train discharge corridors.
Regional Highlights
- Top national expansion: Brazil leads national growth projections at an 8.4% CAGR through 2036 supported by fast-growing planted acacia and pine estates serving transatlantic utility and heating exports.
- Broader country progression: South Korea tracks at a 7.9% CAGR ahead of Japan at 7.6% and the United States at 6.9%, while the United Kingdom advances at a 5.2% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Wood Pellets Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 11.8 billion |
| Estimated Market Size in 2026 | USD 12.6 billion |
| Projected Market Size by 2036 | USD 24.3 billion |
| CAGR, 2026 to 2036 | 6.8% |
| Added Revenue, 2026 to 2036 | USD 11.7 billion |
Municipal district heating operators, independent power producers, and rural homeowners confront volatile fossil natural gas tariffs and rising carbon emissions taxes across Europe and East Asia. When thermal plants and residential boilers switch to standardized industrial biomass pellets, automated auger feeding systems deliver uniform calorific output around 4.8 megawatt-hours per tonne. According to the Food and Agriculture Organization of the United Nations in December 2025, nearly two-thirds of global wood pellet output crosses international borders, with 31 million tonnes traded internationally to bridge regional fiber surpluses with utility and heating demand.
Global Production Tonnage and Wholesale Realization Sizing
Table 2: Global Production Tonnage and Wholesale Price Sizing for the Wood Pellets Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 11.8 | 12.6 | 24.3 |
| Global wood pellet production (million metric tons) | 53.5 | 56.2 to 57.5 | 96.0 to 102.0 |
| Global wood pellet consumption (million metric tons) | 51.5 | 54.0 to 55.4 | 93.5 to 99.0 |
| Weighted wholesale realization per metric ton (USD) | 220.6 | 222.0 to 228.0 | 240.0 to 255.0 |
According to the U.S. Energy Information Administration Monthly Densified Biomass Fuel Report in October 2026, 74 operating American pellet mills held 13.2 million tons of annual capacity in July 2026, realizing an average domestic heating price of USD 243.39 per short ton and an export utility price of USD 210.91 per short ton. Meanwhile, European biomass pellets producers are modernizing dry-hammermill and ring-die lines to maintain margin spreads as competition for clean softwood sawdust intensifies.
Household Heating Stock & Seaborne Utility Trade Indicators
Table 3: Certified Production and Heating Cost Indicators for the Wood Pellets Market (million tonnes, EUR, and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| SBP-certified industrial biomass volume (million tonnes) | 22.8 | 24.5 to 25.8 | 46.0 to 50.0 |
| ENplus-certified heating pellet volume (million tonnes) | 14.5 | 15.1 to 15.6 | 26.5 to 29.0 |
| European household pellet heating consumption (million tonnes) | 15.3 | 15.9 to 16.4 | 24.0 to 26.5 |
| German ENplus A1 cost savings vs. heating oil / gas (%) | 40.0% / 31.0% | 45.0% / 21.0% | 35.0% to 45.0% |
Table 4: Regional Production & Seaborne Trade Indicators for the Wood Pellets Market (million tonnes and USD), 2025 to 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 12.6 billion | 2026 global revenue baseline |
| U.S. densified biomass capacity, July 2026 | 13.2 million tons/year | U.S. EIA Monthly Densified Biomass Report (74 mills) |
| EU27 wood pellet consumption, 2026 forecast | 23.2 million metric tons | USDA FAS GAIN Report E42026-0048 (+500,000 MT YoY) |
| Bulk Ocean Vessel & Rail Hopper revenue, 2026 | USD 6.5 billion | 51.6% distribution format allocation |
As per the USDA Foreign Agricultural Service European Union Wood Pellets Annual report published in July 2026, European Union pellet consumption reached 22.7 million metric tons in 2025 and is forecast to climb by 500,000 metric tons to 23.2 million metric tons in 2026, supported by USD 1.04 billion in extra-EU imports. At the same time, the European Pellet Council confirmed in May 2026 that global ENplus certified production surpassed 14.5 million tonnes in 2025, reinforcing certified biomass pellets as the mandatory quality baseline for European stove and boiler warranties.
Analyst Perspective
"Pellet mill economics over the next decade will be decided at the fiber gate rather than the pellet die. Producers that co-locate ring-die plants beside captive softwood sawmills or fast-rotation plantation forests while holding dual SBP and ENplus certifications will lock in premium utility and heating margins as deforestation traceability rules tighten."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Wood Pellets Market segmented?
The wood pellets market is segmented by pellet grade, feedstock sourcing, end-use application, certification standard, and distribution format. In 2026, Industrial Utility-Grade High-Volume Pellets (I1 and I2) are projected at 53.8%, Sawmill Sawdust and Wood Shavings Residues at 56.4%, Residential Pellet Stoves and Home Biomass Boilers at 38.4%, Sustainable Biomass Program (SBP) Certified Pellets at 39.5%, and Bulk Ocean Vessel and Rail Hopper Shipments at 51.6%.
By pellet grade: Industrial Utility-Grade High-Volume Pellets (I1 and I2), Industrial Co-Firing Grade Pellets (I3), Premium Residential Certified Pellets (ENplus A1 and DINplus), and Commercial Heating Certified Pellets (ENplus A2 and B).
By feedstock sourcing: Sawmill Sawdust and Wood Shavings Residues, Forestry Harvest Residues and Slash Tops, Dedicated Energy Crop Roundwood Logs, and Agricultural and Woody Biomass Blends.
By end-use application: Residential Pellet Stoves and Home Biomass Boilers, Large-Scale Biomass Thermal Power Plants, Combined Heat and Power (CHP) Installations, Commercial District Heating Networks, and Industrial Process Steam Boilers.
By certification standard: Sustainable Biomass Program (SBP) Certified Pellets, ENplus and DINplus Certified Quality Pellets, FSC, PEFC, and National Standard Graded Pellets, and Standard Uncertified Industrial and Local Pellets.
By distribution format: Bulk Ocean Vessel and Rail Hopper Shipments, Bagged Palletized Retail Packs (15 kg to 20 kg), Pneumatic Blown Tanker Delivery, and Intermediate Bulk Container Tote Bags.
Why do Industrial Utility-Grade High-Volume Pellets (I1 and I2) lead the pellet grade category?
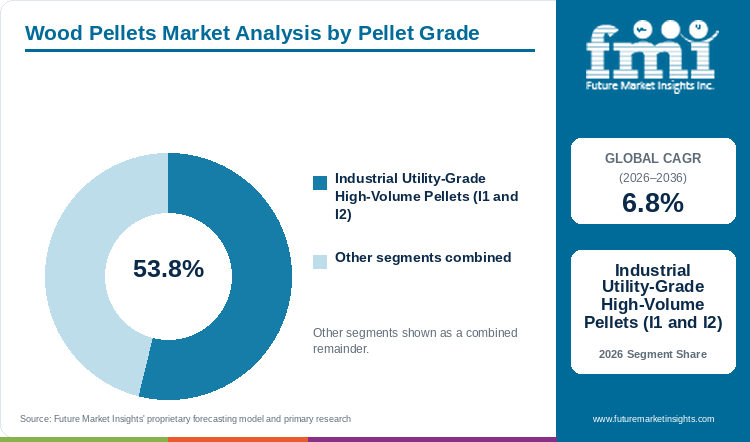
Industrial Utility-Grade High-Volume Pellets (I1 and I2) hold an estimated 53.8% of pellet grade demand in 2026, anchored by seaborne power generation and CHP contracts.
Table 5: Pellet Grade Share for the Wood Pellets Market (percentage share), 2026
| Pellet Grade | Share (2026) |
|---|---|
| Industrial Utility-Grade High-Volume Pellets (I1 and I2) | 53.8% |
| Other Segments Combined | 46.2%* |
| Total | 100.0% |
Table 6: Pellet Grade Leadership and Market Growth for the Wood Pellets Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.8% |
| Leading Segment | Industrial Utility-Grade High-Volume Pellets (I1 and I2) |
Industrial Utility-Grade High-Volume Pellets (I1 and I2) anchor global seaborne demand because pulverized-fuel utility boilers and large cogeneration plants consume multi-vessel shiploads under ten-to-fifteen-year take-or-pay contracts. Utility buyers in the United Kingdom, Japan, South Korea, Denmark, and the Netherlands specify ISO 17225-2 industrial grades with controlled durability and fines tolerances so pneumatic port unloaders and ball mills operate without dust explosions or slagging, while also evaluating black and wood pellets for outdoor coal-yard storage. Policy transitions from baseload renewable obligations toward flexible peaking contracts in Northwestern Europe represent the primary commercial hurdle requiring industrial producers to diversify into Asian utility and industrial steam accounts.
- Within the pellet grade breakdown, Industrial Utility-Grade High-Volume Pellets (I1 and I2) are projected to capture 53.8% of global demand in 2026 on the back of seaborne power generation offtake.
- According to UK Department for Transport port freight statistics released in October 2026, major British ports handled 9,900 thousand tonnes of wood pellets in 2025, with 77% originating from industrial mills in the United States.
What sustains Sawmill Sawdust and Wood Shavings Residues leadership in the feedstock sourcing segment?
Sawmill Sawdust and Wood Shavings Residues represent 56.4% of the feedstock sourcing category in 2026, supported by low bark content and reduced thermal drying costs.
Sawmill Sawdust and Wood Shavings Residues remain the preferred raw material for pellet manufacturers since debarked planer shavings and sawdust arrive from lumber mills with low bark content and fine particle size, reducing hammermill grinding and rotary-dryer thermal energy requirements. In July 2026, the German Pellet Institute reported that sawmill by-products accounted for 93.1% of German wood pellet feedstock in the second quarter of 2026, compared to just 6.9% from non-sawable roundwood. Even so, cyclical slowdowns in residential lumber sawing can tighten local sawdust supply and force pellet plants to blend forestry thinnings, prompting producers like Graanul Invest to introduce its 07 Graanul brand in October 2026 using a wider spectrum of certified woody residues.
- By feedstock sourcing, Sawmill Sawdust and Wood Shavings Residues are estimated to represent 56.4% of global demand in 2026 owing to superior ash chemistry and co-located sawmill economics.
- Mercer International initiated an operational capacity adjustment at its Torgau facility in August 2026 in response to intense competition among European bioenergy producers for regional sawmill residuals.
How do Residential Pellet Stoves and Home Biomass Boilers lead the end-use application category?
Residential Pellet Stoves and Home Biomass Boilers account for 38.4% of end-use application value in 2026, driven by premium bagged and blown ENplus A1 pricing across >6.5M European homes.
Residential Pellet Stoves and Home Biomass Boilers generate the largest share of global market value because bagged and pneumatic-tanker residential fuel commands a significant per-tonne price premium over bulk industrial utility shipments. Homeowners across Italy, France, Germany, Austria, and the Northeastern United States rely on automated wood pellet heating systems for space and water heating because wood pellets consistently undercut retail heating oil and natural gas tariffs. Seasonal winter weather variability and upfront boiler installation costs during periods of reduced government heating grants remain the main hurdles moderating annual residential appliance additions.
- In the end-use application category, Residential Pellet Stoves and Home Biomass Boilers are anticipated to secure a leading 38.4% share in 2026 supported by premium bagged and blown fuel realizations.
- Bioenergy Europe reported in June 2026 that more than 6,500,000 European households now heat with wood pellets, consuming 15,300 thousand tonnes in the residential sector alone during 2025.
Why do Sustainable Biomass Program (SBP) Certified Pellets lead the certification standard category?
Sustainable Biomass Program (SBP) Certified Pellets secure 39.5% of certification standard value in 2026, supported by mandatory EU RED III, UK Ofgem, and Japanese METI sustainability audits.
Sustainable Biomass Program (SBP) Certified Pellets lead global certification volume and value because utility generators in the European Union, the United Kingdom, and Japan cannot claim renewable power subsidies or zero-rated carbon allowances without audited feedstock legality and lifecycle greenhouse gas data. In April 2026, the Sustainable Biomass Program reported that 22,800 thousand tonnes of SBP-certified biomass were produced and sold across 405 certificate holders in 35 countries during 2025, following formal recognition under the revised European Union Renewable Energy Directive. Stringent geolocation mapping requirements for every forest harvest parcel under upcoming deforestation regulations represent a major administrative hurdle for smaller independent mills.
- Across certification standards, Sustainable Biomass Program (SBP) Certified Pellets are forecast to hold 39.5% of 2026 demand as transoceanic utilities enforce strict carbon and forest-origin audits.
- ENplus and DINplus Certified Quality Pellets follow closely in value share, with the European Pellet Council confirming in May 2026 that 91% of its 14,500-thousand-tonne certified output met the top ENplus A1 residential quality class.
What gives Bulk Ocean Vessel and Rail Hopper Shipments the leading position in distribution format?
Bulk Ocean Vessel and Rail Hopper Shipments command 51.6% of distribution format share in 2026, anchored by 31M+ tonnes of international dry-bulk trade.
Bulk Ocean Vessel and Rail Hopper Shipments dominate physical logistics because transoceanic utility trade from the United States, Canada, the Baltics, Brazil, and Vietnam to power plants in Europe and East Asia moves in Handymax and Panamax dry-bulk carriers. Dedicated port silos, covered conveyor galleries, and automated unit-train hopper cars minimize handling cost per tonne while preventing moisture absorption that would cause compressed pellets to swell and disintegrate. Specialized self-heating temperature sensors and inert-gas ventilation systems in vessel holds remain mandatory operational requirements to prevent off-gassing and spontaneous combustion during ocean transit.
- By distribution format, Bulk Ocean Vessel and Rail Hopper Shipments are slated to command 51.6% of global demand in 2026 driven by long-haul utility and industrial CHP supply corridors.
- According to UK Forest Research trade statistics published in October 2026, British bulk wood pellet imports rose to 9,761 thousand tonnes in 2025, with 74% shipped from United States Gulf and Atlantic ports, 12% from Latvia, and 9% from Canada.
What are the drivers, restraints, and opportunities in the Wood Pellets Market?
In the wood pellets market, household heating cost savings over oil and gas with East Asian utility biomass mandates are projected to drive adoption whereas sawmill residue competition and EUDR traceability costs restrain high-cost mills and coal-plant conversions unlock new demand.
- Driver: Retail heating cost savings of 21% to 45% over fossil oil and gas with Asian utility biomass power mandates propel global consumption beyond 51.5 million tonnes.
- Restraint: Tightening sawmill residue supplies, EUDR parcel-level geolocation compliance burdens, and UK post-2027 baseload-to-peaking subsidy shifts constrain high-cost mills.
- Opportunity: Coal-to-pellet utility conversions in Canada and East Asia, torrefied black pellets for steel and industrial steam, and diversified low-ash household blends unlock new demand.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Structural cost advantages in residential space heating and binding utility decarbonization targets in East Asia are driving sustained expansion across the global wood pellets industry. When homeowners and district heating utilities install automated commercial biomass boilers, locally produced wood pellets insulate heating budgets from imported fossil gas volatility while cutting net carbon emissions. According to the German Pellet Institute in October 2026, German ENplus A1 wood pellets maintained a 45% retail heating cost advantage over heating oil and a 21% advantage over natural gas, after boiler installations climbed 14% in 2025 to 35,000 units. Simultaneously, the Wood Pellet Association of Canada reported in September 2026 that Japan reached 8.7 gigawatts of installed biomass power capacity by December 2025, lifting annual Japanese wood pellet imports above 8.0 million metric tons.
Risk Assessment of the Wood Pellets Market: Operational and Formulation Friction
Sawmill fiber competition, parcel-level deforestation traceability rules, and evolving European utility subsidy structures represent the primary operational restraints challenging pellet producers. Because sawmills generate sawdust in proportion to construction lumber demand, housing slowdowns squeeze residual fiber supply and push raw material costs higher for standalone pellet plants processing lignocellulosic biomass feedstocks. In April 2026, spatial equilibrium modeling by the U.S. Forest Service Southern Research Station showed that compliance and segregation costs under the European Union Deforestation Regulation could reduce American wood pellet exports to the European Union by 22% to 36% by 2030 while redirecting trade toward non-EU Asian buyers. Furthermore, Drax Group recorded a GBP 337 million impairment on its Canadian pellet business in February 2026 and closed its Williams Lake mill after British Columbia sawmill curtailments restricted fiber availability.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Producers are capturing new growth avenues by supplying domestic coal-station conversions, engineering moisture-resistant torrefied black pellets, and expanding ring-die pellet machine systems into fast-rotation Southern Hemisphere forestry plantations. Utilities facing statutory coal phase-outs can convert existing pulverized-coal boilers to burn densified biomass at a fraction of the capital cost of new nuclear or gas plants. In September 2026, Canadian utility NB Power signed multi-year fuel supply agreements to convert its Belledune Generating Station from coal to sustainably sourced Canadian wood and agricultural hemp pellets ahead of Canada's 2030 coal phase-out. On the residential side, Lignetics Group launched its national PelletHeat.com consumer education platform in December 2025 across its 29-mill North American network to accelerate household stove and boiler conversions.
Wood Pellets Market by Country (2026 to 2036)
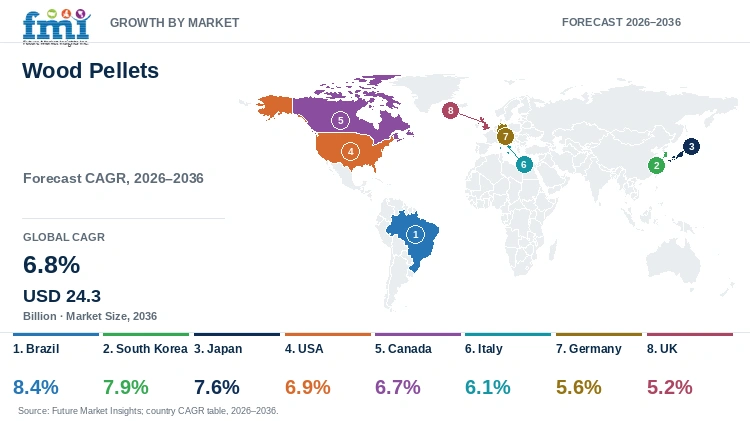
FMI country modeling indicates that Brazil leads national wood pellets expansion at an 8.4% CAGR through 2036, followed by South Korea at 7.9% and Japan at 7.6%, while the United Kingdom progresses at a 5.2% CAGR. National growth trajectories reflect differences in planted forest rotation speeds, utility co-firing tariffs, and residential heating appliance density.
Table 7: Country CAGR and Primary Growth Levers for the Wood Pellets Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 8.4% | Fast-rotation 7-year planted acacia and pine estates and 454,000 MT EU exports |
| South Korea | 7.9% | 3.7M MT annual utility co-firing and industrial CHP import tenders under RPS |
| Japan | 7.6% | 8.7 GW installed biomass power capacity and >8.0M MT annual certified imports |
| USA | 6.9% | 13.2M tons/year capacity across 74 mills supplying 74%-77% of UK and 40% of EU imports |
| Canada | 6.7% | Domestic coal-to-pellet utility conversions (Belledune) and Japanese FIP contracts |
| Italy | 6.1% | >2.3M residential pellet stoves consuming 3.0M MT with 1.91M MT bagged imports |
| Germany | 5.6% | 4.0M MT domestic output and 777,500 heating systems with 21%-45% fuel savings |
| UK | 5.2% | 9.89M MT consumption and post-2027 dispatchable CfD transition at Drax Selby |
Source: Future Market Insights analysis
Brazil Wood Pellets Market Outlook (2026 to 2036)
Wood pellets production and export demand in Brazil are projected to expand at a market-leading 8.4% CAGR from 2026 to 2036 as European and Asian buyers lock in fast-growing plantation fiber. Brazilian mill economics differ fundamentally from Northern Hemisphere producers because planted black wattle, pine, and eucalyptus forests reach harvest maturity in seven years, providing abundant year-round fiber independent of temperate housing cycles. According to the USDA Foreign Agricultural Service in July 2026, European Union imports of Brazilian wood pellets climbed from 174,000 metric tons in 2020 to 454,000 metric tons in 2025. Furthermore, the European Pellet Council confirmed in May 2026 that Brazil now operates 29 ENplus-certified producers manufacturing 465,338 tonnes of certified fuel annually, though inland trucking distances to southern export ports remain a key logistical hurdle.
Key takeaway: In Brazil, seven-year planted pine and acacia harvest rotations and rising ENplus mill certifications are projected to drive rapid export-led expansion.
South Korea Wood Pellets Market Outlook (2026 to 2036)
South Korea is anticipated to record a 7.9% CAGR in wood pellets demand between 2026 and 2036, propelled by Renewable Portfolio Standard co-firing obligations and industrial combined-heat-and-power boilers. Korean procurement is distinguished by its heavy reliance on spot and medium-term seaborne tenders sourced from Vietnam, Indonesia, Malaysia, Russia, and Canada rather than domestic sawmill production. In April 2026, U.S. Forest Service trade analysis documented that South Korea imported 3,700 thousand metric tons of wood pellets annually, with Asian buyer demand forecast to absorb an increasing share of Southeast Asian and North American export tonnage through 2030. Recent government adjustments to Renewable Energy Certificate weightings for imported wood biomass versus domestic forestry thinnings remain the central policy variable shaping Korean utility procurement.
Key takeaway: In South Korea, utility Renewable Portfolio Standard mandates and industrial cogeneration conversions are anticipated to sustain strong seaborne import growth.
Japan Wood Pellets Market Outlook (2026 to 2036)
Demand for wood pellets in Japan is forecast to grow at a 7.6% CAGR through 2036 as dedicated coastal biomass power plants and coal co-firing stations operate under twenty-year Feed-in Tariff and Feed-in Premium contracts. Japan stands out globally because its utility sector has expanded from minimal import volumes a decade ago to become the world's fastest-growing buyers of SBP-certified and FSC-certified industrial pellets. According to a Wood Pellet Association of Canada and METI conference report in September 2026, Japan reached 8.7 gigawatts of installed biomass power capacity by December 2025, pushing annual wood pellet imports past 8,000 thousand metric tons in 2025. Long-term decarbonized power auction contracts and managing foreign-exchange fuel import costs remain the primary challenges for Japanese independent power producers.
Key takeaway: In Japan, more than 8.7 gigawatts of operating biomass power capacity and long-term decarbonization auctions are forecast to anchor large-volume long-term import contracts.
USA Wood Pellets Market Outlook (2026 to 2036)
The United States wood pellets market is estimated to advance at a 6.9% CAGR from 2026 to 2036 across large Gulf and Atlantic export mills and regional bagged heating markets in New England and the Mountain West. No other nation matches the scale of the U.S. Southeast pine basket, which supplies over one-third of all internationally traded wood pellets while also supporting a 2,000-thousand-ton domestic residential heating sector. In October 2026, the U.S. Energy Information Administration reported that 74 active American densified biomass plants operated 13,200 thousand tons of annual capacity and sold 1,000 thousand tons in July 2026 alone. After its December 2024 financial restructuring emergence, leading exporter Enviva Inc. resumed construction on its giant Epes, Alabama mill to serve long-term European and Japanese utility contracts.
Key takeaway: In the USA, abundant Southern yellow pine mill residuals and deep-water export terminals are estimated to sustain global export leadership with steady domestic stove demand.
Canada Wood Pellets Market Outlook (2026 to 2036)
Canadian wood pellets demand and export activity are slated to progress at a 6.7% CAGR between 2026 and 2036 as producers pivot toward Pacific Rim utility contracts and domestic coal-plant conversions. Canada's industry is uniquely bifurcated between British Columbia mills shipping via Pacific ports to Japan and Eastern Canadian mills supplying Europe and domestic heating markets. According to Natural Resources Canada in September 2026, domestic consumption stands at 100,000 to 200,000 tonnes annually, but domestic utility demand is set to jump as provinces retire coal power by 2030. In September 2026, New Brunswick utility NB Power signed multi-year fuel contracts with Canadian producers to convert its Belledune station from coal to wood and hemp pellets, helping offset sawmill fiber curtailments in interior British Columbia.
Key takeaway: In Canada, domestic coal-to-biomass utility conversions and long-term Japanese utility shipments are slated to counterbalance Western sawmill fiber constraints.
Italy Wood Pellets Market Outlook (2026 to 2036)
Italy is predicted to expand at a 6.1% CAGR across the 2026 to 2036 horizon, anchored by Europe's largest installed fleet of residential pellet stoves and Hydronic heating boilers. Italian consumption differs sharply from northern utility markets because over eighty-five percent of Italian tonnage is sold in fifteen-kilogram retail bags to households rather than burned in power stations. In June 2026, Bioenergy Europe reported that Italy operates more than 2,300,000 residential pellet appliances, while USDA Foreign Agricultural Service data from July 2026 confirmed that Italy consumed 3,000 thousand metric tons in 2025 and imported 1,912 thousand metric tons due to limited domestic forest harvesting. Regional air-quality rules in the Po Valley requiring five-star low-particulate stove replacements remain the key regulatory driver shaping Italian demand.
Key takeaway: In Italy, fuel replenishment across more than 2,300,000 household pellet stoves and growing bagged imports from Austria and Brazil are predicted to drive steady demand.
Germany Wood Pellets Market Outlook (2026 to 2036)
Sales of wood pellets in Germany are expected to increase at a 5.6% CAGR from 2026 to 2036 as the European Union's largest pellet producer expands domestic central-heating boiler installations. Germany operates a highly self-sufficient internal market where sixty domestic plants co-located with softwood sawmills produce 4,000 thousand metric tons annually and supply pneumatic tanker fleets directly to homes and municipal buildings. In July 2026, the German Pellet Institute reported that second-quarter 2026 domestic output climbed to 1,034,000 tonnes, with 98.4% certified to ENplus A1 quality and 74.5% delivered in bulk silos. Furthermore, the total German installed base is projected to reach 777,500 pellet heating systems in 2026, saving 4,600 thousand tonnes of carbon dioxide equivalent annually.
Key takeaway: In Germany, a domestic base of 777,500 pellet boilers and strong sawmill-integrated ENplus A1 production are expected to support resilient domestic consumption.
UK Wood Pellets Market Outlook (2026 to 2036)
The United Kingdom wood pellets market is projected to register a 5.2% CAGR between 2026 and 2036 as the world's largest single-country industrial pellet consumer transitions toward flexible dispatchable generation and carbon capture. Over ninety-three percent of British wood pellet demand is concentrated at Drax Power Station in Selby and Lynemouth Power Station, supported by nearly 10,000 thousand tonnes of annual transoceanic imports. In July 2026, Drax Group reported 7.0 terawatt-hours of first-half 2026 UK biomass generation supplying roughly 6% of national electricity while preparing for its post-April 2027 low-carbon dispatchable Contract for Difference covering up to 2.6 gigawatts. The shift from baseload generation to higher-value flexible grid dispatch and bioenergy with carbon capture and storage governs the long-term British outlook.
Key takeaway: In the UK, nearly 10,000 thousand tonnes of utility port imports and post-2027 dispatchable biomass power contracts are projected to anchor Europe's largest industrial fuel market.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Wood Pellets Market?
Drax Group plc, Enviva Inc., AS Graanul Invest, Fram Renewable Fuels LLC, Lignetics, Inc., Pfeifer Holding GmbH, Mercer International Inc., The Westervelt Company, Highland Pellets LLC, and Sumitomo Corporation are the notable companies in the wood pellets market.
Competitive positioning in the wood pellets industry divides into utility-scale seaborne pellet producers, integrated sawmill and residential heating pellet manufacturers, and regional export and biomass supply chain specialists. Drax Group plc and Enviva Inc. with AS Graanul Invest and Fram Renewable Fuels LLC operate multi-plant industrial pellet networks and deep-water port terminals supplying UK, European, and Japanese power utilities. Lignetics, Inc. and Pfeifer Holding GmbH and Mercer International Inc. and The Westervelt Company convert captive and regional sawmill residuals into ENplus A1, PFI, and SBP certified heating and utility pellets, while Highland Pellets LLC and Sumitomo Corporation anchor transoceanic export production and Japanese biomass power trading.
- Utility-Scale Seaborne Pellet Producers: Drax Group plc, Enviva Inc., AS Graanul Invest, and Fram Renewable Fuels LLC manufacture millions of tonnes of SBP-certified industrial pellets for transoceanic power and CHP contracts.
- Integrated Sawmill and Residential Heating Pellet Manufacturers: Lignetics, Inc., Pfeifer Holding GmbH, Mercer International Inc., and The Westervelt Company upcycle sawmill sawdust and shavings into bagged, blown, and bulk pellets.
- Regional Export and Biomass Supply Chain Specialists: Highland Pellets LLC and Sumitomo Corporation operate large industrial export mills, biomass power plants, and international certified fuel trading networks.
Competitive Benchmarking: Wood Pellets Market
Table 8: Competitive Benchmarking for the Wood Pellets Market (qualitative capability ratings), 2026
| Company | Captive Sawmill & Fiber Integration | Seaborne Port & Bulk Logistics | Dual SBP & ENplus Certification Fit | Geographic Reach |
|---|---|---|---|---|
| Drax Group plc | High | High | High | UK, USA, and Canada (4.2M tonnes FY25 output) |
| Enviva Inc. | Medium | High | High | U.S. Southeast (>6.2M MT capacity across 10+ mills and 5 deep-water ports) |
| AS Graanul Invest | High | High | High | Estonia, Latvia, Lithuania, and Texas, USA (~2.7M tonnes capacity; launched 07 Graanul) |
| Fram Renewable Fuels LLC | Medium | High | High | Georgia, USA industrial utility exports and 120,000 MT/yr ENplus A1 heating pellets |
| Lignetics, Inc. | High | Medium | High | USA and Canada (29 mills, 2.0M tons/yr residential heating and industrial pellets) |
| Pfeifer Holding GmbH | High | Medium | High | Austria, Germany, and Czechia (620,000 tonnes/yr pure spruce ENplus A1 pellets across 6 sites) |
| Mercer International Inc. | High | Medium | High | Germany and Canada (Mercer Torgau ENplus A1 wood pellets and sawmill residuals) |
| The Westervelt Company | High | High | High | Alabama, USA integrated southern yellow pine sawmills and Aliceville export pellet plant |
| Highland Pellets LLC | Medium | High | High | Pine Bluff, Arkansas, USA (600,000+ MT/yr SBP/FSC/PEFC industrial export facility) |
| Sumitomo Corporation | High | High | High | Japan and Brazil biomass power plants, certified pellet trading, and Raizen Biomassa |
Key Developments in the Wood Pellets Market
- In July 2026, Drax Group plc reported first-half 2026 results for its Pellet Production segment, recording output of 1.9 million tonnes and an adjusted EBITDA of GBP 64 million. The year-on-year decline from 2.1 million tonnes in H1 2025 reflected the closure of the Williams Lake facility in British Columbia and production weighted toward the second half of the year. Full-year 2025 output had reached a record 4.2 million tonnes [25].
- In May 2026, AS Graanul Invest announced the appointment of Lars Christian Bacher, a senior energy industry executive, as its Chief Executive Officer. The company, Europe’s largest sustainable wood pellet producer by volume, made the appointment to advance its strategic position in European pellet supply and energy security amid continued recovery in residential and industrial pellet demand across Baltic and European markets [26].
- In August 2026, Mercer International Inc. reported operational restructuring at its Torgau softwood sawmill in Germany, citing elevated fiber costs driven by intense competition for sawmill residuals from biomass and energy producers. The Torgau facility produces lumber, pulp, and wood pellets and briquettes; restructuring included workforce reductions of approximately 350 positions through mid-2027 as part of efforts to align operational capacity with current market conditions [27].
Key Players in the Wood Pellets Market
Utility-Scale Seaborne Pellet Producers
- Drax Group plc
- Enviva Inc.
- Graanul Invest AS
- Fram Renewable Fuels LLC
Integrated Sawmill and Residential Heating Pellet Manufacturers
- Lignetics, Inc.
- Pfeifer Holding GmbH
- Mercer International Inc.
- The Westervelt Company
Regional Export and Biomass Supply Chain Specialists
- Highland Pellets LLC
- Sumitomo Corporation
Wood Pellets Market - Report Scope
Table 9: Report Scope for the Wood Pellets Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Pellet Grade; Feedstock Sourcing; End-Use Application; Certification Standard; Distribution Format |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial producer wholesale and export revenue from densified woody biomass pellets (white wood pellets and torrefied black wood pellets) manufactured from sawmill residuals, forestry harvest residues, and energy roundwood for power generation, CHP, district heating, and residential stoves/boilers. Category Scope Note: Excludes unpelletized raw wood chips, firewood logs, charcoal briquettes, and animal bedding pellets. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, South Korea, Japan, USA, Canada, Italy, Germany, UK, and additional countries in the full report |
| Key Companies Covered | Drax Group plc, Enviva Inc., Graanul Invest AS, Fram Renewable Fuels LLC, Lignetics, Inc., Pfeifer Holding GmbH, Mercer International Inc., The Westervelt Company, Highland Pellets LLC, Sumitomo Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Wood Pellets Market - Research Methodology
Table 10: Research Methodology for the Wood Pellets Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with ring-die pellet mill directors, utility biomass fuel procurement officers, port terminal operators, and European ENplus heating distributors to validate FOB and CIF price realizations. |
| Secondary Research | Analysis of U.S. EIA Monthly Densified Biomass Fuel Reports, USDA FAS Wood Pellets Annual GAIN dossiers (EU27 and UK), FAO forestry trade statistics, Bioenergy Europe and DEPV market reports, SBP/ENplus registries, and corporate filings. |
| Market Sizing and Forecasting | Top-down global biomass energy baselines reconciled against bottom-up physical wood pellet production (53.5M tonnes in 2025) and weighted utility and residential wholesale prices per metric ton from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight installed residential pellet appliance stocks, utility FIT/FIP and RPS co-firing mandates, domestic coal phase-out timelines, and sawmill residual fiber availability across eight countries. |
| Operational Benchmark Traceability | Production, certification, and price indicators in Tables 2, 3, and 4 trace to Bioenergy Europe 2026 statistical releases, U.S. EIA July 2026 facility data, USDA FAS E42026-0048, and SBP/ENplus 2025 annual reviews. |
| Data Triangulation and Validation | Revenue estimates isolate densified wood fuel pellets across industrial bulk and residential bagged/blown channels while strictly excluding raw wood chips, non-fuel polymer fillers, and boiler hardware. |
Wood Pellets Market by Segments
Wood Pellets Market segmented by Pellet Grade:
- Industrial Utility-Grade High-Volume Pellets (I1 and I2)
- Industrial Co-Firing Grade Pellets (I3)
- Premium Residential Certified Pellets (ENplus A1 and DINplus)
- Commercial Heating Certified Pellets (ENplus A2 and B)
Wood Pellets Market segmented by Feedstock Sourcing:
- Sawmill Sawdust and Wood Shavings Residues
- Forestry Harvest Residues and Slash Tops
- Dedicated Energy Crop Roundwood Logs
- Agricultural and Woody Biomass Blends
Wood Pellets Market segmented by End-Use Application:
- Residential Pellet Stoves and Home Biomass Boilers
- Large-Scale Biomass Thermal Power Plants
- Combined Heat and Power (CHP) Installations
- Commercial District Heating Networks
- Industrial Process Steam Boilers
Wood Pellets Market segmented by Certification Standard:
- Sustainable Biomass Program (SBP) Certified Pellets
- ENplus and DINplus Certified Quality Pellets
- FSC, PEFC, and National Standard Graded Pellets
- Standard Uncertified Industrial and Local Pellets
Wood Pellets Market segmented by Distribution Format:
- Bulk Ocean Vessel and Rail Hopper Shipments
- Bagged Palletized Retail Packs (15 kg to 20 kg)
- Pneumatic Blown Tanker Delivery
- Intermediate Bulk Container Tote Bags
Wood Pellets Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Energy Information Administration. (2026, October 8). Monthly Densified Biomass Fuel Report, July 2026 Data. U.S. Department of Energy EIA Biofuels Data.
- [2] USDA Foreign Agricultural Service. (2026, July 7). European Union: Wood Pellets Annual (Report E42026-0048). U.S. Department of Agriculture GAIN Reports.
- [3] USDA Foreign Agricultural Service. (2026, July 7). Wood Pellets Annual: The Hague European Union Full Statistical Dossier (E42026-0048 PDF). U.S. Department of Agriculture Foreign Agricultural Service.
- [4] USDA Foreign Agricultural Service. (2025, December 3). Wood Pellets Annual: London United Kingdom (Report UK2025-0032 PDF). U.S. Department of Agriculture Foreign Agricultural Service.
- [5] U.S. Forest Service Southern Research Station. (2026, April 16). Wood pellet market restructuring under the European Union deforestation regulation: A dynamic spatial equilibrium analysis. Biomass and Bioenergy, 213, 109427 (USDA Treesearch 80469).
- [6] UK Department for Transport. (2026, October 27). Port freight annual statistics 2025: Cargo trends. GOV.UK Official Maritime Statistics.
- [7] UK Forest Research. (2026, October 22). Forestry Statistics 2026 - Chapter 3: Timber and Wood Pellet Trade. Forestry Commission UK Statistical Series.
- [8] Natural Resources Canada. (2026, September 16). Wood pellets - Forest industry and international trade overview. Government of Canada Canadian Forest Service.
- [9] Food and Agriculture Organization of the United Nations. (2025, December 24). Global forest products trade and production show signs of recovery in 2024. FAO Forestry Statistical Newsroom.
- [10] Bioenergy Europe. (2026, June 24). Global Pellet Market Hits New High as Europe Weighs Its Clean Heat Options (2026 Statistical Report). Bioenergy Europe Brussels Publications.
- [11] European Pellet Council. (2026, May 26). Record year for ENplus as certified pellet production exceeds 14.5 million tonnes in 2025. ENplus International Certification Scheme.
- [12] European Pellet Council. (2026, May 15). ENplus Latest Certified Production Statistics by Country and Quality Class. ENplus Certification Registry.
- [13] Sustainable Biomass Program. (2026, April 16). SBP Publishes Annual Review 2025: 22.8 Million Tonnes of Certified Biomass. Sustainable Biomass Program Official Reports.
- [14] Wood Pellet Association of Canada. (2026, September 22). Status of Biomass Power Implementation under FIT and FIP Scheme in Japan (2026 Conference Report). WPAC and METI Japan Energy Transition Series.
- [15] Deutscher Energieholz- und Pellet-Verband. (2026, October 16). Pelletpreis im Oktober steigt weniger stark. DEPV German Pellet Institute Market Reports.
- [16] Deutscher Energieholz- und Pellet-Verband. (2026, July 30). Deutsche Pelletproduktion steigt im 2. Quartal 2026 weiter an. DEPV Production Statistics.
- [17] Deutscher Energieholz- und Pellet-Verband. (2026, February 25). Wachstum bei Pelletheizungen und Pelletproduktion. DEPV Annual Heating Market Assessment.
- [18] Drax Group plc. (2026, July 30). Half year results for the six months ended 30 June 2026. Drax Group Financial Regulatory Filings.
- [19] Drax Group plc. (2026, February 26). Full year results for the twelve months ended 31 December 2025. Drax Group Annual Financial Statements.
- [20] Enviva Inc. (2024, December 6). Enviva Announces Successful Emergence from Financial Restructuring Process Positioned for Sustainable Growth. Enviva Corporate Disclosures.
- [21] Graanul Invest AS. (2026, October 9). Graanul Invest launches new 07 Graanul pellet brand. Graanul Invest Corporate News.
- [22] Mercer International Inc. (2026, August 6). Mercer International Inc. reports second quarter 2026 results. Mercer International Investor Relations.
- [23] NB Power. (2026, September 17). NB Power Advances Belledune Clean Fuel Project with Canadian Pellet Supply Agreements. New Brunswick Power Corporation Media Centre.
- [24] Lignetics, Inc. (2025, December 10). PelletHeat.com Launches as Online Resource for Pellet Heating Education. Lignetics Group Official Releases.
- [25] Drax Group plc. (2026). Half Year Results for the Six Months Ended 30 June 2026. https://www.drax.com/wp-content/uploads/2026/07/Drax-Half-Year-Results-RNS-30.07.2026.pdf
- [26] AS Graanul Invest. (2026). AS Graanul Invest Appoints Energy Industry Veteran Lars Christian Bacher as Chief Executive Officer. https://www.businesswire.com/news/home/20260514182250/en/
- [27] Mercer International Inc. (2026). Mercer International Inc. Reports Second Quarter 2026 Results. https://mercerint.com/investors (official investor relations; Q2 2026 results released 6 August 2026, confirmed from https://quartr.com/events/mercer-international-inc-merc-q2-2026_ofxt2qqc)
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the wood pellets market in 2026 and what is forecast for 2036?
- Which residential heating cost spreads and Asian utility mandates support demand for wood pellets?
- Why do Industrial Utility-Grade High-Volume Pellets (I1 and I2) lead the pellet grade category?
- Why do Sawmill Sawdust and Wood Shavings Residues lead the feedstock sourcing category globally?
- How do growth rates differ across Brazil, South Korea, Japan, and the United States?
- Which leading companies supply transoceanic utility pellets versus bagged residential heating fuel today?
- What sawmill fiber shortages and deforestation traceability rules restrain the wood pellets market?
- What should utility fuel buyers evaluate before signing long-term SBP-certified pellet offtake agreements?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Pellet Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Pellet Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Pellet Grade, 2026 to 2036
- Industrial Utility-Grade High-Volume Pellets (I1 and I2)
- Industrial Co-Firing Grade Pellets (I3)
- Premium Residential Certified Pellets (ENplus A1 and DINplus)
- Commercial Heating Certified Pellets (ENplus A2 and B)
- Y-o-Y Growth Trend Analysis By Pellet Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Pellet Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Feedstock Sourcing, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Feedstock Sourcing, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Feedstock Sourcing, 2026 to 2036
- Sawmill Sawdust and Wood Shavings Residues
- Forestry Harvest Residues and Slash Tops
- Dedicated Energy Crop Roundwood Logs
- Agricultural and Woody Biomass Blends
- Y-o-Y Growth Trend Analysis By Feedstock Sourcing, 2021 to 2025
- Absolute $ Opportunity Analysis By Feedstock Sourcing, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Residential Pellet Stoves and Home Biomass Boilers
- Large-Scale Biomass Thermal Power Plants
- Combined Heat and Power (CHP) Installations
- Commercial District Heating Networks
- Industrial Process Steam Boilers
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Certification Standard, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Certification Standard, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Certification Standard, 2026 to 2036
- Sustainable Biomass Program (SBP) Certified Pellets
- ENplus and DINplus Certified Quality Pellets
- FSC, PEFC, and National Standard Graded Pellets
- Standard Uncertified Industrial and Local Pellets
- Y-o-Y Growth Trend Analysis By Certification Standard, 2021 to 2025
- Absolute $ Opportunity Analysis By Certification Standard, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Format, 2026 to 2036
- Bulk Ocean Vessel and Rail Hopper Shipments
- Bagged Palletized Retail Packs (15 kg to 20 kg)
- Pneumatic Blown Tanker Delivery
- Intermediate Bulk Container Tote Bags
- Y-o-Y Growth Trend Analysis By Distribution Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Format, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Pellet Grade
- By Feedstock Sourcing
- By End-Use Application
- By Certification Standard
- By Distribution Format
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Drax Group plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Enviva Inc.
- Graanul Invest AS
- Fram Renewable Fuels LLC
- Lignetics, Inc.
- Pfeifer Holding GmbH
- Mercer International Inc.
- The Westervelt Company
- Highland Pellets LLC
- Sumitomo Corporation
- Drax Group plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Pellet Grade, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Feedstock Sourcing, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Distribution Format, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Pellet Grade, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Feedstock Sourcing, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Format, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Pellet Grade, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Feedstock Sourcing, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Distribution Format, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Pellet Grade, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Feedstock Sourcing, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Distribution Format, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Pellet Grade, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Feedstock Sourcing, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Distribution Format, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Pellet Grade, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Feedstock Sourcing, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Distribution Format, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Pellet Grade, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Feedstock Sourcing, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Format, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Pellet Grade, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Feedstock Sourcing, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Format, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Pellet Grade, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Pellet Grade, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Pellet Grade
- Figure 6: Global Market Value Share and BPS Analysis by Feedstock Sourcing, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Feedstock Sourcing, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Feedstock Sourcing
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Application
- Figure 12: Global Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Certification Standard
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Format, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Format, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Format
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Pellet Grade, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Pellet Grade, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Pellet Grade
- Figure 32: North America Market Value Share and BPS Analysis by Feedstock Sourcing, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Feedstock Sourcing, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Feedstock Sourcing
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Application
- Figure 38: North America Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Certification Standard
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Format, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Format, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Format
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Pellet Grade, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Pellet Grade, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Pellet Grade
- Figure 48: Latin America Market Value Share and BPS Analysis by Feedstock Sourcing, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Feedstock Sourcing, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Feedstock Sourcing
- Figure 51: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 54: Latin America Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Certification Standard
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Format, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Format, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Format
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Pellet Grade, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Pellet Grade, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Pellet Grade
- Figure 64: Western Europe Market Value Share and BPS Analysis by Feedstock Sourcing, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Feedstock Sourcing, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Feedstock Sourcing
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Certification Standard
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Format, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Format, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Format
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Pellet Grade, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Pellet Grade, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Pellet Grade
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Feedstock Sourcing, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Feedstock Sourcing, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Feedstock Sourcing
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Certification Standard
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Format, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Format, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Format
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Pellet Grade, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Pellet Grade, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Pellet Grade
- Figure 96: East Asia Market Value Share and BPS Analysis by Feedstock Sourcing, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Feedstock Sourcing, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Feedstock Sourcing
- Figure 99: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 102: East Asia Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Certification Standard
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Format, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Format, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Format
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Pellet Grade, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Pellet Grade, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Pellet Grade
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Feedstock Sourcing, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Feedstock Sourcing, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Feedstock Sourcing
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Certification Standard
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Format, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Format, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Format
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Pellet Grade, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Pellet Grade, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Pellet Grade
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Feedstock Sourcing, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Feedstock Sourcing, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Feedstock Sourcing
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Certification Standard
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Format, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Format, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Format
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Wood Pellets Market in 2026, and what is forecast for 2036?
FMI estimates that the global wood pellets market size stood at USD 11.8 billion in 2025 and is projected to reach USD 12.6 billion in 2026. Overall industry valuation is on track to hit USD 24.3 billion by 2036 as European heating households and Asian biomass power plants expand certified pellet consumption.
What is the CAGR for the Wood Pellets Market from 2026 to 2036?
The wood pellets sector is projected to expand at a 6.8% CAGR over the 2026 to 2036 window, adding USD 11.7 billion across bulk utility and bagged residential fuel channels.
Which pellet grade segment leads the Wood Pellets Market?
Industrial Utility-Grade High-Volume Pellets (I1 and I2) are projected to hold 53.8% of pellet grade demand in 2026 since seaborne power stations and cogeneration plants procure multi-million-tonne bulk shipments.
Which feedstock sourcing segment leads the Wood Pellets Market?
Sawmill Sawdust and Wood Shavings Residues are anticipated to represent 56.4% of the feedstock sourcing category in 2026 as clean planer residues minimize drying energy and ash content.
Which country has a notable growth outlook during the assessment period?
Brazil leads national expansion projections at an 8.4% CAGR through 2036, driven by fast-rotation planted pine and acacia estates and rising ENplus certified export capacity.
Who are the key players in the market?
Drax Group plc, Enviva Inc., Graanul Invest AS, Fram Renewable Fuels LLC, Lignetics, Inc., Pfeifer Holding GmbH, Mercer International Inc., The Westervelt Company, Highland Pellets LLC, and Sumitomo Corporation lead commercial supply across utility and residential pellet channels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
