

- Market Size (2026)
- USD 39.2 Bn
- Forecast (2036)
- USD 64.4 Bn
- CAGR (2026 to 2036)
- 5.1%
How big is Automotive Air Intake Manifold Market in 2026?
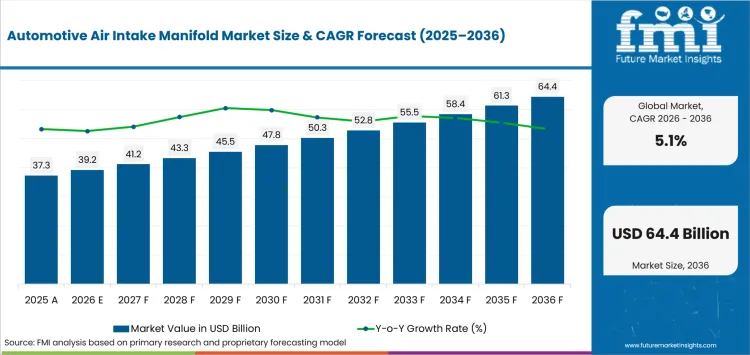
USD 39.2 billion in 2026 and USD 64.4 billion by 2036 at a 5.1% CAGR.
Demand for automotive air intake manifolds is projected to expand at 5.1% CAGR between 2026 and 2036, increasing valuation from USD 39.2 billion in 2026 to USD 64.4 billion by 2036. Hybrid-electric vehicles continue to support production of engine-side air-management components even as vehicle electrification advances. ACEA counted 3,733,325 new hybrid-electric car registrations in the European Union during 2025, equal to 34.5% of registrations. That volume keeps automotive air filter and manifold hardware in production on models that pair an engine with electrification, but each manifold still requires airflow and sealing validation before series production.
Battery-electric substitution is progressing at different speeds across major European vehicle markets, changing how quickly future engine programs lose conventional intake-manifold content. ACEA reported in June 2026 that battery-electric registrations rose 75.7% in Italy and 55.4% in France, versus 40.9% in Germany during the first five months. Automotive air flow meter specifications and manifold absolute pressure sensor interfaces still shape retained-engine calibration. The forecast adds USD 25,168.0 million in modelled value over the ten-year period.
Key Takeaways
- Demand is sustained by gasoline and hybrid vehicle programs that retain internal combustion engines and require application-specific airflow hardware.
- Based on manifold type, dual plane is projected to account for 46.9% in 2026 due to its broad low-to-mid-speed operating range across road-oriented engine programs.
- In 2026, passenger cars & sport cars are expected to lead vehicle type with 71.0% share because gasoline and hybrid engine applications remain concentrated in passenger platforms.
- By material type, AL alloy is forecast to represent 49.1% in 2026 driven by flange stiffness and thermal stability across demanding engine environments.
- Battery-electric vehicle adoption removes the conventional intake manifold from affected platforms and reduces the addressable program pool for component manufacturers.
- Some of the key players in this market include MoldTecs Group, MAHLE GmbH, Sogefi S.p.A., Toyota Boshoku Corporation, AISIN Corporation, Röchling Automotive, Montaplast GmbH, and Holley Performance Products, Inc.
Analyst Perspective
"OEM sourcing decisions should start with engine-specific flow validation and the remaining production life of each combustion or hybrid program. Manufacturers that localize tooling near assembly plants can cut engineering response time without carrying stranded capacity across short-lived engine platforms."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the automotive air intake manifold market segmented?
The automotive air intake manifold market is segmented by manifold type, vehicle type, material type, sales channel and region.
Manifold type covers dual plane, HI-RAM, single plane and supercharger intake. Vehicle type includes passenger cars & sport cars, LCVs and HCVs. Material type covers AL alloy, high performance plastics & composites, cast iron and magnesium alloy. Sales channel separates OEM from aftermarket demand. Region covers North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Why does dual plane lead demand within the manifold type category?
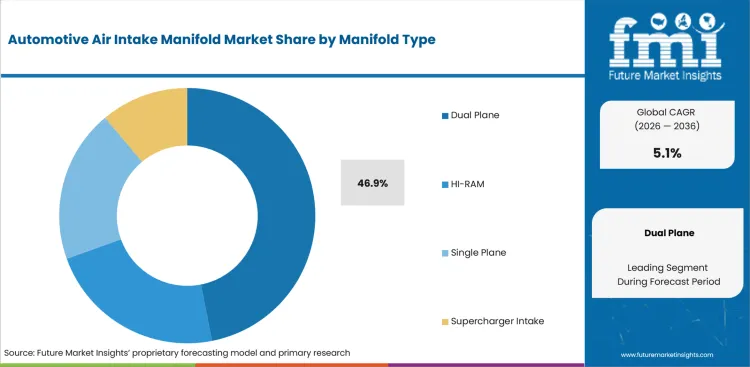
Dual-plane manifolds separate plenum feeding paths to preserve intake velocity across low and mid engine speeds. That operating range suits road-focused torque delivery more widely than high-rpm automotive performance parts applications.
- Based on manifold type, dual plane is projected to account for 46.9% in 2026 due to its useful low-to-mid-speed range across road-oriented engine programs.
- Holley introduced its Big Block Chevy Hi-Ram EFI intake manifold in May 2026 for 396-502 V8 engines. The launch illustrates how a competing architecture targets higher-rpm operation and narrower performance use.
Why do passenger cars & sport cars lead the vehicle type category?
Passenger platforms pair high unit volumes with compact engine bays and frequent model updates. Those conditions multiply manifold variants as automotive hoses and other interfaces tighten packaging around gasoline and hybrid engines in production.
- In 2026, passenger cars & sport cars are expected to lead vehicle type with 71.0% share because engine-containing applications remain concentrated in passenger platforms.
- ACEA reported in July 2026 that hybrid-electric cars reached 37.3% of first-half European Union registrations. That mix preserves substantial engine-air content inside the region’s largest new-vehicle segment.
Why does AL alloy lead demand within the material type category?
Manifold engineers choose AL alloy when flange rigidity and thermal stability outweigh the lower mass of engineered polymers. Automotive lightweight materials and automotive composites compete more strongly on programs that prioritize mass reduction.
- By material type, AL alloy is forecast to represent 49.1% in 2026 driven by established casting routes for demanding engine environments.
- An April 2025 Aluminum Association life-cycle assessment found aluminum-optimized city vehicles cut weight by 9% against status-quo designs. The result reinforces vehicle-level lightweighting pressure that also shapes material choices in the automotive plastic market.
Why does OEM lead demand within the sales channel category?
OEM manifold sourcing starts before series production because runner geometry and interfaces must match a defined engine program. Charge air cooler integration can also increase coordination across intake-system engineering during packaging.
- OEM is projected to hold 89.9% share in 2026 owing to tooling and validation commitments made during vehicle development.
- MAHLE reported in April 2026 that air intake modules were among the largest contributors to new 2025 OEM orders representing €1.9 billion in average annual sales. Those awards confirm multi-year series activity for engine-air modules.
What are the drivers, restraints and opportunities in the Automotive Air Intake Manifold Market?
Combustion-containing vehicle programs sustain demand while battery-electric substitution removes manifold content and regional module integration raises value on retained engine platforms.
- Driver: Hybrid and combustion programs require engine-specific intake hardware across awarded passenger and commercial vehicle production cycles.
- Restraint: Battery-electric platforms eliminate conventional intake manifolds and reduce the eligible program base for manufacturers with combustion-focused capacity.
- Opportunity: Regional air-system supply can capture more engineering content on hybrid and retained combustion programs with stable production lives.
Commercial Vehicle Programs Preserve Intake-Manifold Demand
Commercial vans preserve intake-manifold demand in fleets where diesel engines still dominate new purchasing. ACEA reported in January 2026 that diesel accounted for 80.7% of new European Union van registrations during 2025. Turbocharged diesel programs also retain intake-manifold hardware alongside automotive turbocharger systems, but each manifold must clear program-specific airflow and quality validation before series revenue begins.
Battery-Electric Substitution Narrows the Program Pool
Battery-electric vehicles remove the combustion engine and eliminate conventional intake manifolds from affected passenger-car programs. ACEA reported in April 2026 that battery-electric cars reached 19.4% of European Union registrations during the first quarter. Manufacturers therefore need enough scheduled engine-program volume to recover tooling and validation costs before platform substitution cuts the production run.
Localized Air-System Engineering Raises Program Value
Regional air-system work raises the value of retained combustion and hybrid programs by placing engineering closer to the assembly plant. Röchling Automotive said in July 2026 that Leapmotor International nominated it for European airflow-management components produced in Spain. Local development gives component makers faster access to program changes and adjacent air-management work.
Which country CAGRs are profiled in the Automotive Air Intake Manifold Market?
| Country | CAGR |
|---|---|
| Mexico | 5.3% |
| South Korea | 3.9% |
| Germany | 3.7% |
| Japan | 3.6% |
| United States | 3.3% |
How do country-level CAGRs compare in the Automotive Air Intake Manifold Market?
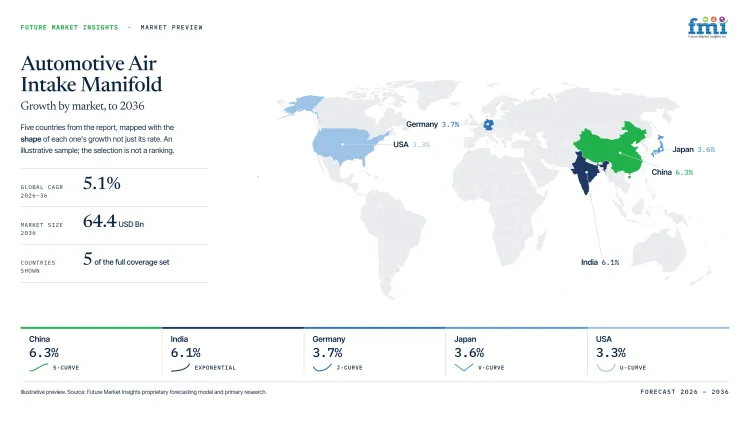
Mexico forms a clear upper tier at 5.3% CAGR, while South Korea, Germany and Japan cluster between 3.6% and 3.9%. The United States follows at 3.3%, where its large installed fleet supports replacement demand. This spacing reflects different exposure to new engine programs and battery-electric substitution rather than current market size alone.
- Mexico rewards localized tooling near export plants serving tightly scheduled North American vehicle programs.
- South Korea concentrates hybrid output within export-oriented automotive groups facing rapid powertrain changes.
- Germany prizes lightweight validated hardware as battery-electric adoption reduces future combustion-engine awards.
- Japan rewards long qualification records across hybrid and efficient combustion vehicle programs.
- United States replacement demand offsets slower growth in new combustion-program awards.
Comparable CAGRs therefore mask different program access and replacement conditions across these markets. The full report provides country-level CAGR analysis across North America, Latin America, Europe, East Asia, South Asia, Oceania and the Middle East and Africa.
Country-wise Analysis
- Mexico’s northern and central assembly corridors reward intake-manifold manufacturers that can support tooling changes near export plants and respond quickly to model revisions without disrupting cross-border series schedules for North American customers. Automotive air intake manifold demand in Mexico is forecast to expand at 5.3% CAGR through 2036, driven by localized engine programs that keep tooling close to high-volume assembly operations and major export routes and regional logistics hubs. INEGI reported 311,457 light vehicles produced and 247,945 exported in February 2026, but that export exposure also leaves local capacity vulnerable to border disruption and trade-policy shifts that can delay tooling recovery.
- South Korean intake programs sit inside export-focused automaker groups that can change hybrid and battery-electric allocation quickly between successive launches while local engineering teams support several destination-market specifications from concentrated domestic production sites. The Ministry of Trade, Industry and Resources reported July 2026 hybrid exports of USD 1.65 billion with 22.2% year-on-year growth, giving manifold producers a measurable engine-containing export base alongside rapid electrification pressures. South Korea is estimated to post 3.9% CAGR over the forecast period, supported by flexible domestic engineering capacity while fast powertrain shifts can strand dedicated tooling before planned volumes are recovered across export-heavy vehicle programs.
- German manifold awards are decided within dense OEM and Tier-1 engineering networks that place weight control and validation history ahead of launch timing across premium and volume vehicle programs built for European markets. The German automotive air intake manifold sector is projected to record 3.7% CAGR during the assessment period, supported by hybrid and efficient combustion programs that still require lightweight validated intake hardware. VDA reported 4.15 million passenger cars produced in Germany during 2025, yet production scale does not offset faster battery-electric substitution or the qualification costs faced by entrants without local application engineering and established quality control records.
- Japanese automakers use long qualification cycles and tightly integrated engineering relationships that reward proven process control while new entrants must earn access through local technical support and consistent manufacturing records across vehicle programs. Honda began Japan sales of the all-new e:HEV Prelude in September 2025, providing a current engine-containing hybrid program while exacting qualification standards still restrict suppliers without established engineering teams and long operating histories. Automotive air intake manifold demand in Japan is forecast to rise at 3.6% CAGR over the forecast period, influenced by hybrid programs that preserve engine-air hardware even as mature domestic volumes limit rapid expansion.
- United States demand spans new OEM engine programs and a broad service base that keeps replacement manifolds relevant across domestic and imported nameplates while distributors carry many model-specific applications over long vehicle service lifecycles. By 2036, the United States is projected to grow at 3.3% CAGR, attributed to its installed gasoline and hybrid fleet even as battery-electric platforms remove conventional intake content from new models. The Department of Energy counted 240.7 million gasoline light-duty vehicles and 13.9 million hybrids in its 2025 registration data, but that breadth also raises aftermarket inventory complexity and the cost of sustaining engine-specific aftermarket application coverage.
Who are the notable companies in the Automotive Air Intake Manifold Market?
MoldTecs Group, MAHLE GmbH, Sogefi S.p.A., Toyota Boshoku Corporation, AISIN Corporation, Röchling Automotive, Montaplast GmbH, and Holley Performance Products, Inc.
Series-program access separates direct manifold manufacturers from adjacent powertrain suppliers and aftermarket specialists. MoldTecs Group, MAHLE GmbH, Sogefi S.p.A. and Toyota Boshoku Corporation document direct manifold activity. AISIN Corporation and Röchling Automotive cover engine-air or powertrain integration, while Montaplast GmbH and Holley Performance Products, Inc. serve molded production and performance replacement routes.
- MoldTecs Group, MAHLE GmbH and Sogefi S.p.A. pursue direct OEM intake-manifold programs across regional vehicle platforms.
- Toyota Boshoku Corporation, AISIN Corporation and Röchling Automotive cover powertrain integration and airflow engineering across current OEM programs.
- Montaplast GmbH and Holley Performance Products, Inc. address molded OEM production and performance aftermarket demand.
Competitive Benchmarking: Automotive Air Intake Manifold Market
| Company | Exact-Market Relevance | Program Integration | Commercial Channel Depth | Geographic Reach |
|---|---|---|---|---|
| MoldTecs Group | High | High | High | Europe, North America and Asia |
| MAHLE GmbH | High | High | High | Global |
| Sogefi S.p.A. | High | High | High | Europe, Americas and Asia |
| Toyota Boshoku Corporation | High | High | High | Asia and Americas |
| AISIN Corporation | Medium | High | High | Asia and global OEM network |
| Röchling Automotive | Medium | High | High | Europe, Asia and North America |
| Montaplast GmbH | Medium | Medium | Medium | Europe, North America and Asia |
| Holley Performance Products, Inc. | High | Low | Low | North America and international aftermarket |
Scoring basis: High exact-market relevance requires documented intake-manifold production or a dated award. Medium covers adjacent engine-air activity. Low marks a verified role without direct manifold production. High program integration requires a vehicle award or manufacturing operation. Medium reflects production capability without a named program, while Low identifies aftermarket-only fitment. High channel depth requires OEM or multi-region supply evidence. Medium covers one regional channel, while Low marks standalone aftermarket sales.
Key Developments in the Automotive Air Intake Manifold Market
- In August 2026, Holley Performance Products, Inc. introduced EFI top-end kits pairing intake manifolds with injectors and throttle-body hardware for popular engine families.
- In June 2026, MoldTecs Group began USA air intake manifold production at Auburn Hills for a high-volume American vehicle program.
- In March 2025, Sogefi S.p.A. secured intake-manifold contracts in Europe and NAFTA for hybrid and gasoline vehicle programs.
Key Players in the Automotive Air Intake Manifold Market
Direct Intake-Manifold Program Manufacturers
- MoldTecs Group
- MAHLE GmbH
- Sogefi S.p.A.
- Toyota Boshoku Corporation
Powertrain and Airflow Integration Manufacturers
- AISIN Corporation
- Röchling Automotive
- Montaplast GmbH
Performance Aftermarket Manifold Specialist
- Holley Performance Products, Inc.
Automotive Air Intake Manifold Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By manifold type, vehicle type, material type, sales channel and region. |
| Quantitative Units | USD billion. |
| Market Definition | Automotive intake manifolds used to distribute intake air from the throttle or charge path to engine cylinders across passenger and commercial combustion-containing powertrains. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Mexico, South Korea, Germany, Japan, United States, and 20+ countries included in the full report. |
| Key Companies Profiled | MoldTecs Group, MAHLE GmbH, Sogefi S.p.A., Toyota Boshoku Corporation, AISIN Corporation, Röchling Automotive, Montaplast GmbH, and Holley Performance Products, Inc. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Automotive Air Intake Manifold Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Automotive Air Intake Manifold Market by Segments
Automotive Air Intake Manifold Market segmented by Manifold Type:
- Dual Plane
- HI-RAM
- Single Plane
- Supercharger Intake
Automotive Air Intake Manifold Market segmented by Vehicle Type:
- Passenger Cars & Sport Cars
- LCVs
- HCVs
Automotive Air Intake Manifold Market segmented by Material Type:
- AL Alloy
- High Performance Plastics & Composites
- Cast Iron
- Magnesium Alloy
Automotive Air Intake Manifold Market segmented by Sales Channel:
- OEM
- Aftermarket
Automotive Air Intake Manifold Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- European Automobile Manufacturers’ Association. (2026, January 27). New car registrations: +1.8% in 2025; battery-electric 17.4% market share.
- European Automobile Manufacturers’ Association. (2026, June 23). New car registrations: +4% in May 2026 year-to-date; battery-electric 20% market share.
- Holley Performance Products. (2026, May 8). Holley Big Block Chevy Hi-Ram EFI Intake Manifold: High-performance power for 396-502 V8s.
- European Automobile Manufacturers’ Association. (2026, July 23). New car registrations: +5.7% in H1 2026; battery-electric 20.7% market share.
- Sphera Solutions and The Aluminum Association. (2025, April 30). Aluminum in Battery Electric Vehicles (BEVs) - A Life Cycle Assessment Report.
- MAHLE GmbH. (2026, April 15). MAHLE improves operating result in 2025.
- European Automobile Manufacturers’ Association. (2026, January 29). New commercial vehicle registrations: vans -8.8%, trucks -6.2%, buses +7.5% in 2025.
- European Automobile Manufacturers’ Association. (2026, April 23). New car registrations: +4% in Q1 2026; battery-electric 19.4% market share.
- Röchling Automotive. (2026, July 28). Leapmotor International selects Röchling Automotive for European vehicle programs.
- Instituto Nacional de Estadística y Geografía. (2026, March). Administrative Record of the Light Vehicle Automotive Industry: February 2026 results.
- Ministry of Trade, Industry and Resources, Republic of Korea. (2026, August 14). Automobile exports hit record high for July.
- German Association of the Automotive Industry. (2026, January 5). Pkw-Produktion 2025 leicht über Vorjahresniveau.
- Honda Motor Co., Ltd. (2025, September 4). Honda to Begin Sales of All-new Prelude.
- USA Department of Energy, Alternative Fuels Data Center. (2026). Vehicle registration counts by state: 2025 light-duty vehicle registrations.
- MoldTecs Group. (2026, June 1). A historic milestone for MoldTecs.
- Sogefi S.p.A. (2025, March 26). Sogefi STAR Conference 2025.
- Toyota Boshoku America, Inc. (2025, December 2). TOYOTA BOSHOKU AMERICA, INC. ACQUIRES FULL OWNERSHIP OF TBDN TENNESSEE COMPANY, REBRANDS AS TOYOTA BOSHOKU JACKSON TENNESSEE, LLC.
- AISIN Corporation. (2025). Integrated Report 2025.
- Montaplast GmbH. (2026). Quality.
- MoldTecs Group. (2026). Sustainability and certification documents.
- Holley Performance Products. (2026, August 4). Holley EFI top end kits simplify engine swaps with matched intake, injectors and throttle body.
- MoldTecs Group. (2026, January 26). Strategic new award for MoldTecs.
- Röchling Group. (2026, May 28). Röchling Strengthens Profitability Once Again Despite Headwinds.
- Sogefi S.p.A. (2026, July 27). Results for first half 2026.
- MAHLE GmbH. (2025, July 23). MAHLE goes full speed ahead with decarbonization.
- AISIN Corporation. (2025, April 24). AISIN begins contract production of hybrid units for Guangzhou Automobile Group.
- Holley Performance Brands. (2025, August 12). Holley Performance Brands and Callaway Cars partner on new line of performance packages.
- MANN+HUMMEL. (2026, July 14). Nanofiber Power for Commercial Vehicles.
- Sogefi S.p.A. (2026, April 24). Interim Financial Report as at March 31, 2026.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- What are the 2026 and 2036 values?
- Which powertrains sustain manifold demand?
- Why does dual plane lead?
- Why do passenger cars lead?
- Why does AL alloy lead?
- Why does OEM lead?
- How do country CAGRs compare?
- Which companies compete here?
Frequently Asked Questions
How big is the automotive air intake manifold market in 2026?
The automotive air intake manifold market is valued at USD 39.2 billion in 2026 and is projected to reach USD 64.4 billion by 2036. Hybrid programs retain combustion-engine intake hardware.
What is the CAGR of the automotive air intake manifold market from 2026 to 2036?
The automotive air intake manifold market is projected to grow at 5.1% CAGR between 2026 and 2036. Hybrid and commercial vehicle programs retain combustion engines.
Which manifold type leads the automotive air intake manifold market?
The dual plane segment is expected to hold 46.9% of the automotive air intake manifold market in 2026, driven by low-to-mid-speed torque coverage. Road programs favor this operating range.
Which sales channel leads the automotive air intake manifold market?
The OEM segment is expected to hold 89.9% of the automotive air intake manifold market in 2026, supported by engine-specific tooling and validation. Vehicle manufacturers fix manifold geometry before production.
How much value will the automotive air intake manifold market add between 2026 and 2036?
The automotive air intake manifold market is expected to add USD 25.2 billion between 2026 and 2036. Retained combustion and hybrid programs support this incremental opportunity.
Which countries are projected to record the highest growth in the automotive air intake manifold market?
Mexico is projected to grow at 5.3% CAGR, followed by South Korea at 3.9% and Germany at 3.7% through 2036. Export production and powertrain mix shape growth.
Which companies are active in the automotive air intake manifold market?
Key companies operating in the automotive air intake manifold market include MoldTecs Group, MAHLE GmbH, Sogefi S.p.A., Toyota Boshoku Corporation, AISIN Corporation, Röchling Automotive, Montaplast GmbH, and Holley Performance Products, Inc. Their positions differ across OEM and aftermarket routes.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Manifold Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Manifold Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Manifold Type, 2026 to 2036
- Dual Plane
- HI-RAM
- Single Plane
- Supercharger Intake
- Dual Plane
- Y-o-Y Growth Trend Analysis By Manifold Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Manifold Type, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars & Sport Cars
- LCVs
- HCVs
- Passenger Cars & Sport Cars
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Material Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Type, 2026 to 2036
- AL Alloy
- High Performance Plastics & Composites
- Cast Iron
- Magnesium Alloy
- AL Alloy
- Y-o-Y Growth Trend Analysis By Material Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM
- Aftermarket
- OEM
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Manifold Type
- By Vehicle Type
- By Material Type
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Mahle GmbH
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- MANN+HUMMEL
- Röchling Automotive
- Sogefi S.p.A.
- Toyota Boshoku Corporation
- AISIN Corporation
- DENSO Corporation
- Continental AG
- Rheinmetall Automotive
- Marelli Holdings
- Mahle GmbH
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


