

- Market Size (2026)
- USD 1029.4 Mn
- Forecast (2036)
- USD 2743.8 Mn
- CAGR (2026 to 2036)
- 10.3%
How big is Automotive Bioplastic Market in 2026?
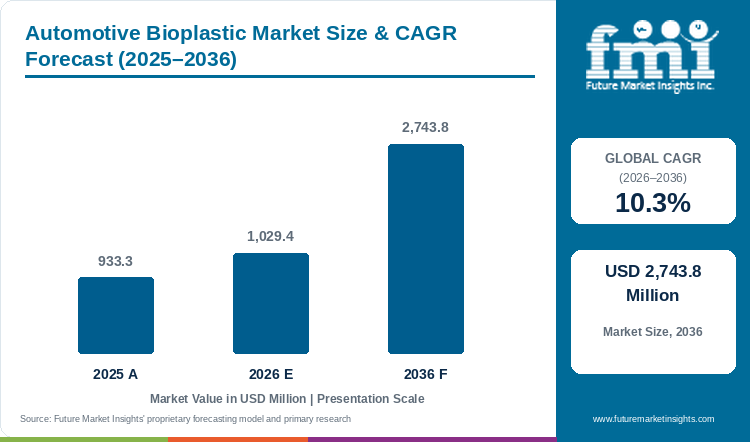
Automotive bioplastic demand rises from USD 933.3 million in 2025 to USD 1,029.4 million in 2026, and FMI forecasts USD 2,743.8 million by 2036 at a 10.3% CAGR as automakers move bio-based polymers from trim into functional parts.
FMI values automotive bioplastics at USD 933.3 million for 2025, USD 1,029.4 million for 2026 and USD 2,743.8 million for 2036, a 10.3% compound rate over the forecast decade. Automotive and transport took 0.24 million tonnes of the 2.31 million tonnes of global bioplastics capacity in 2025, or 10.3% of applications, as world vehicle output reached 96.4 million units, up 3.9% [1][2].
Average bioplastic content works out to about 2.5 kg per vehicle produced, against 428 pounds, or roughly 194 kg, of plastics and polymer composites in the average North American light vehicle in 2025. Bio-based grades cover close to 1.3% of in-vehicle plastic mass. A Dutch government study judged substitution of 5% to 10% of vehicle plastics feasible in the short term and put the technical ceiling near 70% [3]. Applied to 194 kg and 96.4 million vehicles, the 5% to 10% band gives an addressable pool of 0.94 to 1.87 million tonnes, 3.9 to 7.8 times the 2025 automotive volume, a pool far larger than current demand.
Resin suppliers are converting this headroom through named vehicle programmes. Mitsubishi Chemical's isosorbide-based DURABIO forms the instrument panels of Honda's N-ONE e:, launched in September 2025, and the AI speaker housing of the Dongfeng Nissan Teana announced in China in January 2026 [4]. Arkema reports a carbon footprint of 1.3 kg CO2e per kg for castor-based Rilsan PA11 from the start of 2025, and a Singapore plant raised global PA11 capacity by 50% [5]. TotalEnergies Corbion and Benvic began jointly marketing Luminy PLA compounds to automotive OEMs as replacements for ABS, PS and PP in March 2025. FMI expects suppliers holding documented OEM part approvals and certified carbon footprints to take most new nominations as vehicle platforms are renewed through 2036.
Key Market Trends & Insights
- By material, bio PP led with an estimated 59.7% in 2026, reflecting polypropylene's largest share of vehicle plastic mass and the availability of commercial drop-in bio-PP grades. Bio PET remains a smaller slice at about 8.0%, as sugarcane bio-MEG feeds polyester for seats and carpets; Toyota Tsusho lists GLOBIO bio-PET for automotive interior surfaces including seats and carpets [6].
- By application, interior parts stay ahead on FMI estimates, with dashboards, consoles and pillars on the Kia EV9 using bioplastic made from vegetable oils, corn, sawdust and sugarcane.
- By vehicle type, passenger cars accounted for 70.0% in 2026, with SUVs as the leading body style within the category, on higher trim and textile area per vehicle.
- By propulsion, battery-electric launches carry the most visible bio-based content, from DURABIO dashboards in the N-ONE e: to bio-PU upholstery in the EV9.
Regional Highlights
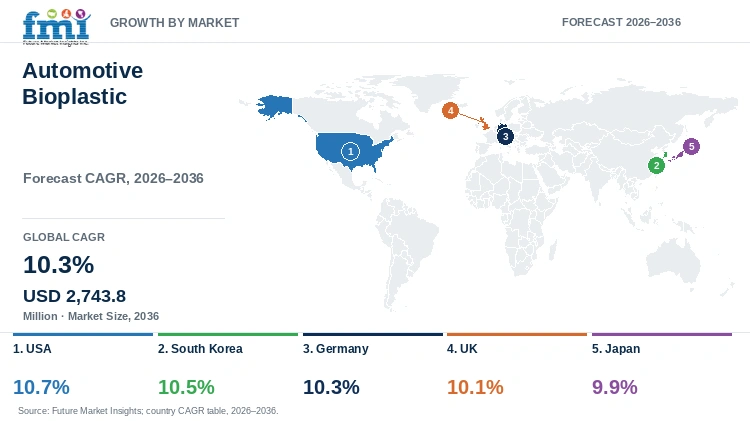
- The USA heads the five-country set at 10.7% CAGR over 2026 to 2036.
- South Korea (10.5%) and Germany (10.3%) follow, and Japan closes the set at 9.9%.
- Regulation (EU) 2026/1738, binding since 13 August 2026, sets recycled plastic floors of 15% from September 2032 and 25% from September 2036 for new vehicle types.
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive Bioplastic Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 933.3 million |
| Estimated Market Size in 2026 | USD 1,029.4 million |
| Projected Market Size by 2036 | USD 2,743.8 million |
| CAGR, 2026 to 2036 | 10.3% |
| Added Revenue, 2026 to 2036 | USD 1,714.4 million |
| Market Expansion Multiple | 2.7x |
Polymer mix decides how quickly bio content can scale. Polypropylene makes up 37% of plastics in end-of-life cars, polyurethane 15%, polyamide 12%, polyethylene 8% and PET 5%, and drop-in bio-based versions already exist for PE, PP, PET and ABS [3]. Castor-derived polyamides fill a second route into fuel lines, quick connectors and cable jacketing, alongside wider automotive plastic and castor oil supply chains [7]. Regulation (EU) 2026/1738 on end-of-life vehicles leaves bio-based plastics out of the recycled-content targets, deferring that treatment to a Commission review within 72 months of entry into force. Drop-in PP and PE grades are expected to lead volume gains once price gaps narrow, with novel polymers holding the higher-value technical parts.
Vehicle-level Bioplastic Content and Substitution Potential
Six indicators pair current bioplastic volume per vehicle with plastic content, substitution studies and EU rules, using 2024 to 2026 disclosures.
Table 2: Vehicle-level Bioplastic Content and Substitution Indicators for the Automotive Bioplastic Market (mixed units), mixed reporting years from 2024 to 2026
| Indicator | Data Point | Why It Matters | Source |
|---|---|---|---|
| Automotive and transport bioplastics, 2025 | 0.24 Mt, 10.3% of 2.31 Mt global capacity | Sets the current volume base | [1] |
| Bioplastic per vehicle, 2025 | About 2.5 kg per vehicle across 96.4 million vehicles produced in 2025 | Benchmarks current content per unit | [1][2] |
| Plastics per North American vehicle, 2025 | 428 lb (about 194 kg), 9.6% of vehicle weight, up 18% in a decade | Bio share near 1.3% of plastic mass in 2025 | - |
| EU vehicle plastics and substitution potential | About 2,200 kt a year; 5% to 10% (111 to 222 kt) feasible short term; about 70% technical | Gives a published substitution band | [3] |
| Addressable pool at 5% to 10% substitution | 9.7 to 19.4 kg per vehicle; 0.94 to 1.87 Mt globally; 3.9x to 7.8x 2025 volume | Sizes headroom for resin suppliers | [1][2][3] |
| EU recycled-plastic floors, Regulation (EU) 2026/1738 | 15% from 1 September 2032, 25% from 1 September 2036; bio-based excluded pending review | Competes with bio content for the same plastic budget | - |
Analyst Perspective
“Bio-based polymers cover close to 1.3% of the plastic in a typical car today. A Dutch government study treats 5% to 10% as feasible in the near term. Suppliers that can show OEM-approved parts at a certified footprint per kilogram, as Mitsubishi Chemical and Arkema now do, are best positioned to close that gap through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Automotive Bioplastic Market segmented?
Automotive bioplastic market is segmented by four primary commercial axes and region: material, application, vehicle type, propulsion, and region. In 2026, bio PP is projected at an estimated 59.7% and passenger cars at 70.0%, with SUVs the leading body style, and interior parts form the largest application.
By material: bio PA, bio PTT, bio PET, bio PBS, bio PP, bio PE, and others (PLA, bio-PU and bio-based PC).
By application: exterior (bumper, tailgate, liftgate and hood, body hardware, others), interior (seats, dashboard, air ducts, HVAC, others), and engine surrounding (engine and valve covers, fuel hoses and lines, others).
By vehicle type: passenger cars (compact, mid size, luxury, SUVs), LCV, and HCV.
By propulsion: internal combustion, hybrid electric (HEV), plug-in hybrid (PHEV), and battery electric (BEV).
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Bio PP lead material demand?
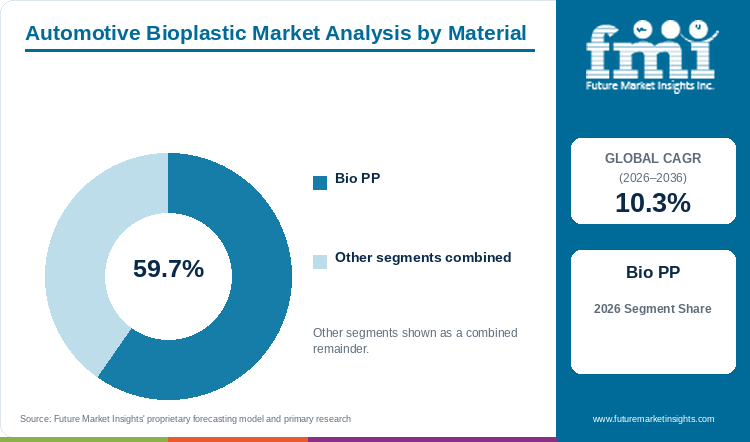
Bio PP is projected to lead material demand at an estimated 59.7% in 2026, as polypropylene's dominant share of vehicle plastic mass and commercial drop-in grades convert fastest to bio-based content.
Table 3: Material Share for the Automotive Bioplastic Market (percentage share), 2026
| Material | Share (2026) |
|---|---|
| Bio PP | 59.7% |
| Other Segments Combined | 40.3%* |
| Total | 100.0% |
*Represents the combined share held by all other materials besides Bio PP.
Table 4: Material Leadership and Market Growth for the Automotive Bioplastic Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 10.3% |
| Leading Segment | Bio PP |
Bio PP accounts for an estimated 59.7% of material demand in 2026. Polypropylene makes up the largest single share of plastic mass in end-of-life cars, at 37%, and commercial drop-in bio-PP grades already exist, giving the material the broadest base to convert [3]. Bio PET remains a smaller slice, at about 8.0%, as PET makes up only 5% of plastic mass in end-of-life cars; GLOBIO combines bio-MEG from sugarcane ethanol with PTA for seats and carpets [3][6], but Kia's move to 100% recycled PET in carpets on newer EV lines puts recycled and bio-based polyester in direct competition for the same parts [9]. FMI expects bio PA to gain share fastest from a smaller base as engineering grades, tracked alongside polylactic acid, move into under-hood and structural trim.
- Bio PP accounts for an estimated 59.7% share in 2026, led by polypropylene's dominant share of vehicle plastic mass.
- Castor-based polyamides, including Rilsan PA11, VESTAMID Terra PA1010 and Ultramid S Balance PA6.10, compete for fuel lines, cable jackets and connectors.
Why do passenger cars hold most vehicle-type demand?
Passenger cars are projected to take 70.0% of vehicle-type demand in 2026, with SUVs as the leading body style, as larger interiors carry more panels, fabrics and foam per vehicle.
Passenger cars hold 70.0% of vehicle-type demand in 2026, with SUVs as the leading body style in the category. The Kia EV9, a three-row SUV, uses bioplastic in the dashboard, centre console, pillars and garnishes, bio-PU in seats and coverings, and bio-PU foam in headrests [9]. Compact cars take a smaller slice, although Honda's N-ONE e: mini EV shows that bio-based engineering plastics now reach entry models [10]. SUV content per unit is expected to rise further as EV platforms replace paint and chrome with molded-in-colour bio-based surfaces.
- Passenger cars account for 70.0% in 2026 on cabin area and trim count, with SUVs leading the body-style mix.
- LCV and HCV use remains limited to seat foams and cable sheathing.
What keeps interior parts the main application?
Interior parts lead application demand, as low heat load and visible surfaces favour bio-based resins with surface finish advantages.
As per FMI, interior applications lead automotive bioplastic demand. DURABIO avoids a separate coating step because colourants mixed into the resin give a gloss finish, reaching 92% total light transmittance in the Teana speaker housing [4]. Exterior use is growing more slowly, with BMW planning a flax-fibre roof for the next M3 that cuts production CO2e by around 40%, a fibre route counted here only for the polymer matrix. Engine-surrounding parts are expected to remain the narrowest application, served mainly by heat-resistant castor polyamides.
- Interior parts lead on dashboards, consoles, seats and air ducts.
- Natural-fibre reinforcement is tracked separately in the natural fiber composites market.
What are the drivers, restraints, and opportunities in the Automotive Bioplastic Market?
In the automotive bioplastic market, OEM carbon-footprint targets drive resin switching, recycled-content rules and cost gaps constrain bio-based volume, and drop-in PP and PE grades open the principal commercial opportunity.
- Driver: Supplier-certified carbon footprints accepted in OEM sourcing.
- Restraint: EU recycled-plastic floors that exclude bio-based grades.
- Opportunity: Drop-in bio PP and bio PE for the largest polymer families in a vehicle.
Certified footprints enter part sourcing
Arkema now quotes 1.3 kg CO2e per kg for Rilsan PA11 under ISO 14067, below a 2 kg target set in 2023. Braskem's October 2025 life cycle update gives a net benefit of about 5 kg CO2e per kg for the bio-based HDPE against fossil grades. Buyers chasing lightweight and low-carbon materials are expected to rank bio-based grades by verified kilograms of CO2e per part.
Recycled-content rules take the plastic budget
Regulation (EU) 2026/1738 was published on 24 July 2026 and requires 15% post-consumer recycled plastic in new vehicle types from September 2032, with at least 20% of that from end-of-life vehicles. Bio-based plastics do not count toward the targets, and a Commission review of that treatment is due within 72 months. FMI expects European OEMs to prioritise recycled PP in the early 2030s, which may slow bio PP adoption in the region.
Drop-in polymers widen the addressable base
PP, PE and PET together make up half of end-of-life vehicle plastic mass, and each has a drop-in bio-based version [3]. CE Delft modelled a combined target design that would let recycled or bio-based plastic count toward a single 25% threshold, with bio content capped at around 10% [3]. Drop-in grades are expected to set the pace of volume growth if the 2030s review admits bio-based content.
Which country CAGRs are profiled in the Automotive Bioplastic market?
Table 5: Country CAGR Comparison for the Automotive Bioplastic Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| USA | 10.7% |
| South Korea | 10.5% |
| Germany | 10.3% |
| UK | 10.1% |
| Japan | 9.9% |
How do country-level CAGRs compare in the Automotive Bioplastic market?
The profiled rates sit within 0.8 percentage points, as all five producers source from the same global resin suppliers. As per FMI, the USA (10.7%) and South Korea (10.5%) move ahead on SUV-heavy output and EV interior programmes, Germany (10.3%) tracks the global rate under recycled-content rules, and the UK (10.1%) and Japan (9.9%) grow from smaller or flatter production bases.
- The USA builds high plastic content into each light vehicle.
- South Korea pairs export-led output with bio-based EV interiors.
- Germany balances bio content against recycled plastic floors.
- The UK grows from a reduced production base.
- Japan's bio-based engineering plastic adoption centres on DURABIO in the Honda N-ONE e:, within the slowest-growing economy in the profiled set.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- The USA tops the profiled set with automotive bioplastic demand forecast to expand at 10.7% CAGR through 2036. US plants built 10.24 million vehicles in 2025, and the average North American vehicle carried 428 pounds of plastics and polymer composites, 18% more than a decade earlier [2][11].
- South Korea is anticipated to grow at 10.5% CAGR through 2036. Vehicle output reached approximately 4.1 million units in 2025 per South Korea's Ministry of Trade, Industry and Energy, and export value rose 2% to USD 72.0 billion. Kia has applied a list of ten sustainable materials to all new model lines since the EV9 in 2023, including bioplastic trim and bio-PU upholstery [8].
- Germany demand is projected to record 10.3% CAGR through 2036, level with the global rate. Germany hosted a major share of EU car output in 2025, and Regulation (EU) 2026/1738 entered into force in August 2026 with recycled plastic floors that leave bio-based grades outside the count [12]. About 2,200 kt of plastics enter EU vehicles each year, so a 5% bio-based share across the bloc would equal about 111 kt [3].
- The UK automotive bioplastic market is estimated to rise at 10.1% CAGR through 2036. UK car production fell 8% to 717,371 units in 2025, and commercial vehicle output dropped 62.3%. A smaller build base caps near-term volume, leaving growth tied to new EV programmes.
- Japan is forecast to expand at 9.9% CAGR through 2036, the lowest in the profiled set. Output reached 8.41 million vehicles in 2025 [2]. Honda's N-ONE e: carries DURABIO instrument panels, and Toyota Tsusho's group company Planic supplied recycled shredder-residue plastic for the Crown Sport fender seal in July 2025, a sign that recycled and bio-based grades now compete in the same Japanese supply chains [13].
Who are the notable companies in the Automotive Bioplastic Market?
BASF, Mitsubishi Chemical, Arkema, Evonik, Envalior, Toyota Tsusho, NatureWorks, TotalEnergies Corbion, Braskem, and Covestro (XRG) form the profiled company set for automotive bioplastics.
Engineering-polymer producers with castor or isosorbide chemistry hold the documented OEM part approvals, and commodity bio-resin makers supply PET, PLA and PE that compounders convert for interiors. Ownership and names have changed recently, with XRG completing an 81.77% stake purchase in Covestro on 10 December 2025, Total Corbion PLA now trading as TotalEnergies Corbion, and Danimer Scientific's assets sold to Teknor Apex for USD 19 million in June 2025 after a Chapter 11 filing [14][15].
- Bio-based engineering polymers: BASF, Mitsubishi Chemical, Arkema, Evonik, Envalior.
- Bio-PET, PLA and bio-PE resin producers: Toyota Tsusho, NatureWorks, TotalEnergies Corbion, Braskem.
- Bio-based coatings and polyurethane systems: Covestro (XRG).
Competitive Benchmarking: Automotive Bioplastic Market
Table 6: Competitive Benchmarking for the Automotive Bioplastic Market (qualitative capability ratings), 2026
| Company | Bio-based Engineering Polymers | Bio PET, PLA and PE | Documented OEM Parts | Reach |
|---|---|---|---|---|
| BASF | High | Low | Medium | High |
| Mitsubishi Chemical | High | Low | High | High |
| Arkema | High | Low | Medium | High |
| Evonik | Medium | Low | Low | Medium |
| Envalior | Medium | Low | Medium | Medium |
| Toyota Tsusho | Low | Medium | Low | Medium |
| NatureWorks | Low | High | Low | Medium |
| TotalEnergies Corbion | Low | High | Low | Medium |
| Braskem | Low | Medium | Low | Medium |
| Covestro (XRG) | Low | Low | Low | High |
High reflects a wide published OEM part record, Medium a documented but narrower record, and Low limited public documentation.
Key Developments in the Automotive Bioplastic Market
- In August 2026, Regulation (EU) 2026/1738 on end-of-life vehicles entered into force, with recycled plastic floors of 15% from 2032 and 25% from 2036.
- In April 2026, NatureWorks opened an integrated Ingeo PLA plant in Nakhon Sawan, Thailand, with about 75,000 tonnes of annual capacity.
- In January 2026, Mitsubishi Chemical announced DURABIO in the AI speaker of the Dongfeng Nissan Teana launched in China.
- In December 2025, XRG closed the purchase of an 81.77% stake in Covestro's share capital.
Key Players in the Automotive Bioplastic Market
Bio-based Engineering Polymers
- BASF
- Mitsubishi Chemical
- Arkema
- Evonik
- Envalior
Bio-PET, PLA and Bio-PE Resin Producers
- Toyota Tsusho
- NatureWorks
- TotalEnergies Corbion
- Braskem
Bio-based Coatings and Polyurethane Systems
- Covestro (XRG)
Automotive Bioplastic Market - Report Scope
Table 7: Report Scope for the Automotive Bioplastic Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Material; application; vehicle type; propulsion; region |
| Quantitative units | USD million |
| Market definition | Revenue from fully or partly bio-based polymer resins and compounds supplied for vehicle components, covering drop-in bio PE, bio PP and bio PET, and bio PA, bio PTT, bio PBS, PLA, bio-PU and bio-based polycarbonate; counts the polymer content only; excludes natural-fibre reinforcement, recycled fossil plastics, bio-based rubbers and tyres, and finished part value |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | USA; South Korea; Germany; UK; Japan |
| Key companies profiled | BASF; Mitsubishi Chemical; Arkema; Evonik; Envalior; Toyota Tsusho; NatureWorks; TotalEnergies Corbion; Braskem; Covestro (XRG) |
| Forecast period | 2026 to 2036 |
| Approach | Bottom-up volume data and top-down estimates were cross-checked to reconcile vehicle production, plastic content per vehicle, bio-based substitution rates and resin pricing within the defined revenue boundary. |
Automotive Bioplastic Market - Research Methodology
Table 8: Research Methodology for the Automotive Bioplastic Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with OEM materials engineers, tier-one part suppliers, compounders and bio-resin producers. |
| Desk Research | Review of vehicle production statistics, bioplastics capacity data, OEM material disclosures, supplier releases and EU regulation. |
| Market Sizing and Forecasting | Vehicle-level content modelling by material, application and vehicle type, linked to production forecasts and resin prices. |
| Data Validation | Triangulation of model outputs against capacity data and supplier disclosures, with analyst review of outliers. |
Automotive Bioplastic Market by Segments
Automotive Bioplastic Market segmented by Material:
- Bio PA
- Bio PTT
- Bio PET
- Bio PBS
- Bio PP
- Bio PE
- Others (PLA, Bio-PU and Bio-based PC)
Automotive Bioplastic Market segmented by Application:
- Exterior
- Interior
- Engine Surrounding
Automotive Bioplastic Market segmented by Vehicle Type:
- Passenger Cars (Compact, Mid Size, Luxury, SUVs)
- LCV
- HCV
Automotive Bioplastic Market segmented by Propulsion:
- Internal Combustion
- Hybrid Electric (HEV)
- Plug-in Hybrid (PHEV)
- Battery Electric (BEV)
Automotive Bioplastic Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] European Bioplastics. (2025, December 2). Bioplastics market development update 2025 (press release). https://docs.european-bioplastics.org/PR/2025/EUBP_Press_Release_Market_data_2025.pdf
- [2] OICA. (2026, April 23). Auto industry growth shifted east in 2025 amid global repositioning. https://oica.net/auto-industry-growth-shifted-east-in-2025-amid-global-repositioning/
- [3] CE Delft for the Ministry of Infrastructure and Water Management. (2024, June 30). Biobased plastics in vehicles. https://government.nl/binaries/government/documenten/reports/2024/06/30/biobased-plastics-in-vehicles/biobased-plastics-in-vehicles.pdf
- [4] Plabase. (2026, April 14). Plant-derived resin adopted for a new vehicle's AI speaker that lights up in 256 colors. https://en.plabase.com/media/articles/news-2604-durabio
- [5] Singapore Economic Development Board. (n.d.). Arkema opens Rilsan plant in Singapore for Asia. https://www.edb.gov.sg/en/about-edb/media-releases-publications/arkema-opens-rilsan-plant-in-singapore-for-asia.html
- [6] SpecialChem. (n.d.). GLOBIO by Toyota Tsusho. https://www.specialchem.com/plastics/supplier/toyota-tsusho/globio
- [7] Evonik. (n.d.). VESTAMID Terra bio-polyamide protects high-performance cables. https://corporate.evonik.com/en/media/press-releases/corporate/vestamid-terra-bio-polyamide-protects-high-performance-cables-106577.html
- [8] Hyundai Motor Group. (2023, October 12). Kia EV3 and EV4 concept models utilize leading-edge sustainable materials to deliver a step change in interior design. https://www.hyundaimotorgroup.com/en/news/CONT0000000000116439
- [9] Hyundai Motor Group. (2023, May 17). Kia takes a bold step towards scalable sustainability with its flagship EV9. https://www.hyundaimotorgroup.com/en/news/CONT0000000000092713
- [10] ChemXplore. (2025, December 17). Bio-based engineering plastic DURABIO adopted for Honda's new mini passenger EV N-ONE e:. https://chemxplore.com/news/bio-based-engineering-plastic-durabio-adopted-for-honda-s-new-mini-passenger-ev-n-one-e
- [11] Repairer Driven News. (2026, August 18). Council finds safer, smarter, more efficient vehicles reliant on plastics. https://www.repairerdrivennews.com/2026/08/18/council-finds-safer-smarter-more-efficient-vehicles-reliant-on-plastics/
- [12] Rematec. (2026, August 25). Regulation (EU) 2026/1738 on end-of-life vehicles. https://www.rematec.com/news/industry-players-and-markets/regulation-1738
- [13] Toyota Tsusho. (2025, July 18). Recycled plastic from automotive shredder residue by Planic adopted in a Toyota vehicle. https://www.toyota-tsusho.com/english/press/detail/250718_006644.html
- [14] Renewable Carbon News. (2025, April 11). TotalEnergies Corbion and Benvic team up to expand low-carbon Luminy PLA compounds for automotive and electronics. https://renewable-carbon.eu/news/totalenergies-corbion-and-benvic-team-up-to-expand-low-carbon-luminy-pla-compounds-for-automotive-and-electronics/
- [15] Green Chemicals Blog. (2025, June 11). Teknor Apex acquires Danimer. https://greenchemicalsblog.com/?p=30908
- [16] PlasticsToday. (2026, March 2). EU publishes provisional end-of-life vehicle regulations. https://www.plasticstoday.com/automotive-mobility/eu-publishes-provisional-end-of-life-vehicle-regulations
- [17] Arkema. (2025, May 7). Arkema showcases at Automotive Engineering Expo 2025 in Yokohama. https://hpp.arkema.com/en/media/newslist/news/non-global/countries/japan/2025/20250521-automotive-engineering-expo-2025-yokohama
- [18] BASF. (n.d.). Fossil resource substitution in automotive. https://plastics-rubber.basf.com/global/en/performance_polymers/industries/pp_automotive/transportation_sustainability/fossil-resource-substitution-automotive
- [19] Envalior. (n.d.). EcoPaXX automotive. https://envalior.com/en-us/products/ecopaxx/ecopaxx-automotive.html
- [20] Automotive Interiors World. (2025, June 18). BMW brings natural fiber composites to series production models. https://www.automotiveinteriorsworld.com/news/materials/bmw-brings-natural-fiber-composites-to-series-production-models.html
- [21] NatureWorks. (2026, April 29). NatureWorks announces grand opening of fully integrated Ingeo biopolymer manufacturing facility in Thailand. https://www.businesswire.com/news/home/20260429217577/en/NatureWorks-Announces-Grand-Opening-of-Fully-Integrated-Ingeo-Biopolymer-Manufacturing-Facility-in-Thailand
- [22] MarketScreener. (2025, December 10). XRG P.J.S.C. completed the acquisition of 81.77% stake in Covestro AG. https://uk.marketscreener.com/news/xrg-p-j-s-c-completed-the-acquisition-of-81-77-stake-in-covestro-ag-for-9-6-billion-ce7d50dbdf8dff2c
- [23] Just Auto. (2026, January 16). South Korea reports record vehicle exports in 2025. https://www.just-auto.com/?p=188884
- [24] Motor Trade Association. (2026, January 29). UK automotive output 2025. https://www.mta.org.uk/resources/uk-automotive-output-2025/
- [25] ACEA. (2026, April 2). Economic and market report: Global and EU auto industry, full year 2025. https://www.acea.auto/publication/economic-and-market-report-global-and-eu-auto-industry-full-year-2025/
- [26] Euwid Recycling. (2026, June 30). ELVR adopted by Council of the EU. https://www.euwid-recycling.com/news/policy/elvr-adopted-by-council-of-the-eu-300626/
- [27] Braskem. (2025, October 7). Braskem unveils updated life cycle assessments for I'm green bio-based portfolio. https://www.businesswire.com/news/home/20251007904046/en/Braskem&
This Report Answers
- How big is the automotive bioplastic market during 2026?
- What value is projected by 2036?
- Which material holds leading share?
- Which vehicle type holds leading share?
- Which countries have the fastest growth?
- Which companies are key in the market?
Frequently Asked Questions
How large is the automotive bioplastic market expected in 2026?
FMI puts the automotive bioplastic market at USD 1,029.4 million in 2026, climbing to USD 2,743.8 million by 2036, about 2.7 times the 2026 level.
What CAGR is projected for the automotive bioplastic market through 2036?
As per FMI, the market compounds at 10.3% a year from 2026 to 2036. Bio content near 1.3% of vehicle plastic mass in 2025 leaves a wide gap to the 5% to 10% substitution band judged feasible by CE Delft.
Which material holds a leading market share in 2026?
Bio PP, at an estimated 59.7% of material demand in 2026, through polypropylene's dominant share of vehicle plastic mass and commercial drop-in bio-PP grades. Bio PET, bio PA, bio PE and the remaining materials share the other 40.3%.
Which vehicle type holds a leading share in 2026?
Passenger cars, at 70.0% of vehicle-type demand in 2026, with SUVs as the leading body style. Bio-based trim on three-row SUVs such as the Kia EV9 spans dashboards, consoles, pillars, seats and headrests.
Which country has the fastest expansion outlook through 2036?
The USA, at 10.7% CAGR from 2026 to 2036, ahead of South Korea at 10.5%. US output reached 10.24 million vehicles in 2025. Notable companies include BASF, Mitsubishi Chemical, Arkema, Evonik, Envalior, Toyota Tsusho, NatureWorks, TotalEnergies Corbion, Braskem, and Covestro (XRG).
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Material, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Material, 2026 to 2036
- Bio PA
- Bio PTT
- Bio PET
- Bio PBS
- Bio PP
- Bio PE
- Others (PLA, Bio-PU and Bio-based PC)
- Y-o-Y Growth Trend Analysis By Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Material, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Exterior
- Interior
- Engine Surrounding
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars (Compact, Mid Size, Luxury, SUVs)
- LCV
- HCV
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Propulsion, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Propulsion, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Propulsion, 2026 to 2036
- Internal Combustion
- Hybrid Electric (HEV)
- Plug-in Hybrid (PHEV)
- Battery Electric (BEV)
- Y-o-Y Growth Trend Analysis By Propulsion, 2021 to 2025
- Absolute $ Opportunity Analysis By Propulsion, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material
- By Application
- By Vehicle Type
- By Propulsion
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- BASF
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Mitsubishi Chemical
- Arkema
- Evonik
- Envalior
- Toyota Tsusho
- NatureWorks
- TotalEnergies Corbion
- Braskem
- Covestro (XRG)
- BASF
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


