
- Market Size (2026)
- USD 65.0 Bn
- Forecast (2036)
- USD 91.7 Bn
- CAGR (2026 to 2036)
- 3.5%
How big is Automotive Pumps Market in 2026?
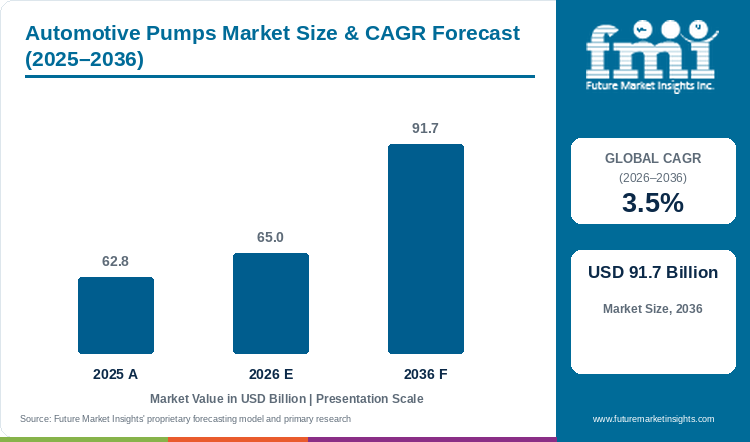
The automotive pumps market is estimated at USD 62.8 billion in 2025 and is forecast to reach USD 65.0 billion in 2026. Sales of automotive pumps are projected to grow at a 3.5% CAGR and reach USD 91.7 billion by 2036.
Demand for automotive pumps is likely to reach USD 91.7 billion by 2036, from USD 65.0 billion in 2026 and USD 62.8 billion in 2025, a CAGR of 3.5%. This is roughly three times the growth of the vehicle base it serves, with global light vehicle sales forecast to grow about 1% a year to 2029. The difference lies in content per vehicle: electrified powertrains replace mechanical belt-driven pumps with electric coolant, oil and vacuum units, and a hybrid keeps the engine pumps while adding electric pumps for the battery and power electronics. Hybrid-electric cars made up 37.3% of EU new car registrations in January to June 2026, battery-electric cars 20.7%, and petrol registrations fell 17.2%. The uplift has a ceiling, as a fully electric vehicle drops the engine pump set and cuts content per car. Demand will therefore be determined by the powertrain mix of new vehicles and the pump content each type carries.
Hybrid passenger cars carry the heaviest pump content, as each one runs a fuel feed pump, an engine oil pump and two or more electric coolant circuits. In segment terms, fuel supply pumps hold an expected 44% of 2026 pump type sales, and electric designs carry an estimated 55% of technology sales. By comparison, battery-electric cars drop the fuel and oil pumps but add high-voltage coolant pumps, so the mix shifts toward electric units with higher prices per piece. For makers able to supply both engine and battery cooling circuits, hybrid thermal modules are giving engine pump plants a second life.
Key Market Trends & Insights
- In-tank fuel supply pumps are expected to lead pump type sales at 44% in 2026. Fuel injection pumps follow near 14.5%, and coolant pumps hold about 10.5%.
- Electric drive is likely to cover 55% of technology sales in 2026, leaving mechanical designs an estimated 45%. On the high-voltage side, Rheinmetall secured a double-digit million euro order in June 2025 for CWA 2000 high-voltage coolant pumps for electric trucks.[2] Orders of that scale move engineering budgets at pump makers toward 800V designs.
- Factory fitment through OEM supply is projected to keep 74% of 2026 channel sales, and the aftermarket about 26%.
- Passenger cars carry an estimated 66% of vehicle type sales in 2026, with light commercial vehicles near 18.5%. Hybrid growth is adding pump content within that segment. For example, Kia sold 178,000 hybrids in Q2 2026, up 61%.[3] Each extra hybrid adds electric coolant pumps to a car that still needs an engine pump set.
Regional Highlights
- India is forecast to grow at 5.1% in FMI's outlook, 1.6 points over the market rate of 3.5%, as car and two-wheeler output rises.
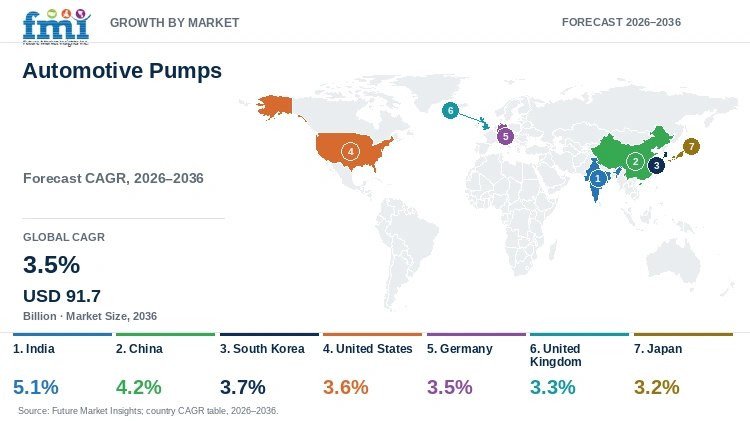
- China is expected to grow at 4.2% on electrified car output, and South Korea at 3.7% on hybrid exports. Behind these, the United States reaches 3.6%, Germany matches the global rate at 3.5%, and the United Kingdom (3.3%) and Japan (3.2%) grow slowest.
- Indian supplier results show how fast local vehicle output is rising. Bosch Limited reported 22% revenue growth for the June 2026 quarter, with Power Solutions sales up 29%.[4] Growth at that pace favours suppliers with local fuel pump and engine management plants.
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive Pumps Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 62.8 billion |
| Estimated Market Size in 2026 | USD 65.0 billion |
| Projected Market Size by 2036 | USD 91.7 billion |
| CAGR, 2026 to 2036 | 3.5% |
| Added Revenue, 2026 to 2036 | USD 26.7 billion |
| Market Expansion Multiple | 1.4x |
Demand for automotive pumps is holding up on hybrid and diesel programmes even as European engine volumes fall. For instance, PHINIA reported Fuel Systems sales of USD 584 million in Q2 2026, against USD 556 million a year earlier.[5] Fuel system sales still rising at a specialist show that combustion and hybrid platforms keep fuel pump orders firm in the near term. At the same time, Rheinmetall agreed in June 2026 to sell Power Systems, home of the Pierburg brand, to AEQUITA for a provisional EUR 350 million.[6] Ownership of a major pump maker is moving to a financial investor, which may speed plant consolidation in engine parts. High-pressure fuel pumps are part of injection systems, and the fuel injection system market carries a projected 9% CAGR. Overall, the automotive pumps market is projected in FMI analysis to add about USD 26.7 billion in sales over the decade, a 1.4x multiple on the 2026 base. However, fewer combustion engines in Europe after 2030 is the main risk to fuel and oil pump volumes.
Fuel Systems, Electric Coolant Pumps and Supplier Change
Fuel pumps still carry the largest part of sales. On the diesel side, PHINIA secured a complete common rail program covering rail, pump, injectors and ECU for agricultural engines in Q2 2026.[5] Off-road diesel engines will therefore keep high-pressure pump demand alive after car diesel declines. Field reliability is the main exposure for fuel pump suppliers. On the other hand, Ford recalled 850,318 US vehicles in July 2025 over low-pressure fuel pumps that could fail and stall the engine.[7] Recalls like this push carmakers to tighten pump validation and replace supplier parts in the field.
Electric coolant pumps are the fastest-changing line. In particular, Rheinmetall's CWA 2000 order covers a mid-six-figure quantity of 850V-capable pumps for battery-electric medium and heavy trucks, with deliveries starting in 2028 and running until 2035.[2] A delivery window that long ties the truck maker to one electric pump design for most of the forecast period. Alongside this, MAHLE reported EUR 6.1 billion of 2025 sales in Thermal and Fluid Systems, which includes thermal management and engine peripherals.[8] Across the sector, thermal suppliers are moving capacity from belt-driven water pumps to electric units.
Table 2: Fuel System, Electric Pump and Supplier Indicators for the Automotive Pumps Market (sales, orders and shares), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| PHINIA Fuel Systems sales, Q2 2026 | USD 584 million; from USD 556 million | Fuel pump and injection demand | [5] |
| PHINIA Aftermarket sales, Q2 2026 | USD 356 million; from USD 334 million | Replacement fuel system parts | [5] |
| Rheinmetall Power Systems sale, June 2026 | EUR 350 million provisional; about EUR 2 billion 2025 sales | Ownership change at Pierburg | [6] |
| Rheinmetall CWA 2000 order, June 2025 | Mid-six-figure quantity, 2028 until 2035 | High-voltage coolant pumps for trucks | [2] |
| EU hybrid-electric share, H1 2026 | 37.3% of new car registrations | Electric pump content per car | [1] |
| Kia hybrid sales, Q2 2026 | 178,000; up 61% | Hybrid pump demand in Korean platforms | [3] |
| MAHLE Thermal and Fluid Systems sales, 2025 | EUR 6.1 billion | Thermal and engine peripheral parts | [8] |
Analyst Perspective
“Pump makers are living through a mix change. Hybrids keep the fuel and oil pumps and add electric coolant pumps, and I see that as the most profitable decade the pump business will have before full electrification thins out engine parts. Converting engine pump plants into electric pump lines now is the surest way for suppliers to keep customers through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the automotive pumps market segmented?
The market is segmented into pump type, technology, sales channel, vehicle type, and region. Fuel supply pumps are expected to lead pump type with 44% share in 2026, and electric designs lead technology with 55%.
By pump type: fuel supply pump, fuel injection pump, transmission oil pump, conventional engine oil pump, variable engine oil pump, steering pump, coolant pump, windshield washer pump, and vacuum pump.
By technology: electric and mechanical.
By sales channel: OEM and aftermarket.
By vehicle type: passenger cars, light commercial vehicles, heavy commercial vehicles, and two wheeler.
By region: vehicle assembly and parts markets in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do fuel supply pumps lead automotive pumps sales by pump type?
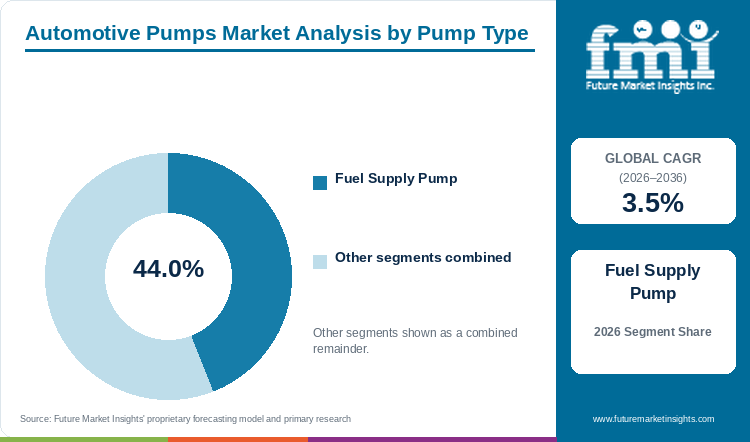
Fuel supply pumps are expected to lead pump type sales with 44% share in 2026, ahead of fuel injection pumps at about 14.5% and coolant pumps at an estimated 10.5%.
Table 3: Pump Type Share for the Automotive Pumps Market (percentage share), 2026
| Pump Type | Estimated Share (2026) |
|---|---|
| Fuel Supply Pump | 44% |
| Fuel Injection Pump | 14.5% |
| Coolant Pump | 10.5% |
| Conventional Engine Oil Pump | 7.5% |
| Variable Engine Oil Pump | 6% |
| Transmission Oil Pump | 5.5% |
| Steering Pump | 4.5% |
| Vacuum Pump | 4.5% |
| Windshield Washer Pump | 3% |
| Total | 100.0% |
Table 4: Pump Type Leadership and Market Growth for the Automotive Pumps Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.5% |
| Leading Segment | Fuel Supply Pump |
Each petrol, diesel and hybrid vehicle needs an in-tank module to move fuel to the engine, so fuel supply pumps are expected to lead pump type sales in 2026, at 44%. Fuel injection pumps, near 14.5%, by comparison cost more per unit but serve only direct-injection petrol and diesel engines. Meanwhile, coolant pumps, an estimated 10.5%, are moving from belt drive to electric drive. Conventional and variable engine oil pumps (7.5% and 6%) and transmission oil pumps (5.5%) follow the engine and gearbox count. Steering pumps (4.5%) are fading as electric power steering spreads, and vacuum (4.5%) and washer pumps (3%) are low-value parts. Volume concentration also raises risk for fuel pump suppliers. On the quality side, Ford's July 2025 recall covered 850,318 vehicles with low-pressure fuel pumps.[7] A single fuel pump programme can span several model lines, so one defect can reach hundreds of thousands of cars and push carmakers toward dual sourcing. On this basis, fuel supply pumps will keep the lead as long as combustion and hybrid cars dominate new builds.
- In-tank electric feed pumps, pump modules with level senders and low-pressure diesel transfer units fall under fuel supply pumps.
- Demand at fuel system specialists has kept growing with combustion and hybrid builds. Net sales at PHINIA rose 5.6% to USD 940 million in Q2 2026.[5] A rising top line of that kind indicates in-tank and high-pressure pump demand is still growing.
Why do electric pumps lead automotive pumps sales by technology?
Electric pumps are likely to lead technology sales with 55% share in 2026, against mechanical designs at an estimated 45%.
Table 5: Technology Share for the Automotive Pumps Market (percentage share), 2026
| Technology | Estimated Share (2026) |
|---|---|
| Electric | 55% |
| Mechanical | 45% |
| Total | 100.0% |
Electric pumps run only when needed and save fuel, so carmakers fit them for fuel feed, coolant, oil and vacuum duties, and electric designs are likely to hold 55% in 2026. Mechanical pumps, about 45%, are cheaper and simple, and mechanical units still drive oil, water and high-pressure fuel on many combustion engines. For instance, hybrid-electric cars made up 37.3% of EU registrations in H1 2026, and each one adds electric coolant circuits.[1] Over the forecast period, growth of the hybrid vehicles market, projected at a 21.5% CAGR, will keep shifting pump orders toward electric designs.
- Electric fuel feed pumps, electric water pumps, electric oil pumps and electric vacuum pumps make up the electric group.
- High-voltage platforms need pumps designed for the battery circuit. The CWA 2000 coolant pump allows operating voltages of up to 850V.[2] Voltage capability at that level suits the 800V truck and car architectures now spreading in premium electric models.
Why does OEM supply lead automotive pumps sales by sales channel?
OEM supply is projected to lead sales channel demand with 74% share in 2026, and the aftermarket holds about 26%.
Table 6: Sales Channel Share for the Automotive Pumps Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| OEM | 74% |
| Aftermarket | 26% |
| Total | 100.0% |
Every new vehicle leaves the plant with a full pump set, so OEM supply is projected to lead in 2026 with 74% share. The smaller aftermarket, near 26%, covers replacement water pumps, fuel pumps and washer pumps on cars past warranty, and replacement intervals are long. Ageing fleets are still raising replacement volume. A case in point is PHINIA, which grew Aftermarket sales to USD 356 million in Q2 2026 from USD 334 million.[5] In addition, older cars on European and US roads keep the aftermarket steady. Replacement pumps are often fitted during coolant and oil service, and the synthetic lubricants and functional fluids market, forecast at a 5.4% CAGR, gains from the same service visits. Even so, OEM orders will still set most volume.
- Factory-fitted fuel modules, engine oil pumps, coolant pumps and vacuum pumps for new vehicles form the OEM channel.
- Aftermarket brands are changing owners along with engine pump plants. The Motorservice parts brand stays with Power Systems under the agreed sale to AEQUITA.[6] Workshops buying Motorservice pumps can expect continuity of supply, with pricing set by the new owner.
Why do passenger cars lead automotive pumps sales by vehicle type?
Passenger cars are expected to lead vehicle type sales with 66% share in 2026, ahead of light commercial vehicles at about 18.5% and heavy commercial vehicles at an estimated 11%.
Table 7: Vehicle Type Share for the Automotive Pumps Market (percentage share), 2026
| Vehicle Type | Estimated Share (2026) |
|---|---|
| Passenger Cars | 66% |
| Light Commercial Vehicles | 18.5% |
| Heavy Commercial Vehicles | 11% |
| Two Wheeler | 4.5% |
| Total | 100.0% |
Passenger cars are expected to hold a 66% lead share in 2026, as cars make up most vehicles built each year. Light commercial vehicles, near 18.5%, use similar pump sets but sell in smaller numbers. Heavy commercial vehicles, about 11%, need larger and costlier pumps on far fewer units, and electric trucks add high-voltage coolant pumps. As a result, truck thermal circuits are growing in value, and the commercial vehicle automotive thermal system market has a projected 4.4% CAGR, so truck pump sets will grow in step. At the small end, two wheelers, an estimated 4.5%, use a fuel pump and sometimes an oil pump. Hybrid mix is raising pump value per car fastest. Back in passenger cars, Kia's hybrid sales rose 61% in Q2 2026.[3] Each of those hybrids adds electric pumps to a passenger car. Above all, rising car builds will hold passenger vehicles in the lead.
- Sedans, SUVs and hatchbacks with combustion, hybrid and electric drives account for passenger car pump sets.
- Fuel injection is spreading on Indian motorcycles under emission rules. Bosch Limited two-wheeler sales grew 41.4% in the June 2026 quarter, led by engine management products.[4] Each fuel-injected motorcycle needs an electric fuel pump, which adds volume to the smallest vehicle segment.
What are the drivers, restraints, and opportunities in the automotive pumps market?
Hybrid cars carry more pumps per vehicle and keep orders growing. The long decline of combustion engines in Europe limits fuel and oil pump demand, and electric coolant pumps for EVs and trucks open new programmes.
- Driver: Hybrids keep the engine pump set and add electric coolant and oil pumps, which raises pump value per vehicle.
- Restraint: Fewer new combustion engines in Europe will cut orders for fuel injection and mechanical oil pumps over the decade.
- Opportunity: Battery-electric cars and electric trucks need high-voltage coolant pumps for batteries, motors and inverters, which gives electric pump makers new contracts.
Hybrids Raise Pump Content per Vehicle
Adoption of hybrid powertrains is raising the number of pumps in each new car. For example, Kia reported electrified sales of 296,000 units in Q2 2026, 35.3% of the total.[3] A third of a major carmaker's volume in electrified models means pump sets with both engine and electric units. Likewise, hybrid-electric cars reached 37.3% of EU new car registrations in H1 2026.[1] As a result, each hybrid model awards new electric pump contracts on top of the engine set.
Fewer Combustion Engines Limit Fuel and Oil Pumps
Producers of fuel and oil pumps face a shrinking engine base in Europe. On FMI's forecast, fuel injection and mechanical oil pumps will grow slowest among pump types. Evidence of this comes from ACEA data, as petrol registrations fell 17.2% and diesel registrations 16.5% in the EU in H1 2026.[1] Lower combustion registrations cut the build rate for injection pumps and mechanical oil pumps first. Among suppliers, Rheinmetall's decision to sell Power Systems in June 2026 shows a defence group stepping out of combustion parts.[6] Consequently, engine pump makers will consolidate plants.
Electric Coolant Pumps Open New Programmes
New sales of automotive pumps will come from battery and power electronics cooling. On the truck side, Rheinmetall's CWA 2000 deal covers deliveries between 2028 and 2035 for battery-electric medium and heavy trucks.[2] Long delivery windows of this kind secure electric pump volume into the next decade. Meanwhile, battery-electric cars accounted for 20.7% of EU registrations in H1 2026.[1] Growth of the battery electric vehicle market, at a 15% CAGR, will therefore keep electric pump lines busy.
Which country CAGRs are profiled in the automotive pumps market?
Table 8: Country CAGR Comparison for the Automotive Pumps Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 5.1% |
| China | 4.2% |
| South Korea | 3.7% |
| United States | 3.6% |
| Germany | 3.5% |
| United Kingdom | 3.3% |
| Japan | 3.2% |
How do country-level CAGRs compare in the automotive pumps market?
Rising vehicle output in India is showing up in supplier results. Bosch Limited grew automotive product sales 25.7% in the June 2026 quarter, and FMI projects the fastest growth for India, at 5.1%.[4] Local sourcing of pumps for cars and two-wheelers grows with that output. China follows at 4.2%, as hybrid and electric car output keeps adding electric pumps. Next, South Korea, at 3.7%, builds many hybrids for export. Close behind, the United States, on 3.6%, gains from pickup and SUV builds and replacement demand. Germany then equals the 3.5% global rate. Of the two mature producers at the low end, the United Kingdom is 0.1 points ahead of Japan's 3.2%.
- Car and two-wheeler output in India is rising, and fuel injection on motorcycles is adding electric fuel pumps to the smallest vehicles. Suppliers with local plants and low-cost pump modules gain most from that volume.
- Chinese plants build the most hybrid and battery-electric cars, so Chinese demand is shifting fast to electric coolant pumps. Global suppliers face local makers that compete hard on price for these contracts.
- On Korean hybrid exports, engine pumps and electric pumps ride on the same car, raising content per vehicle for pump makers tied to Hyundai and Kia platforms.
- Pickups and SUVs with large engines keep US pump content per vehicle high, and an ageing fleet adds replacement demand. For suppliers, aftermarket reach matters almost as much as OEM awards.
- German carmakers are moving output to battery-electric models, and engine pump lines are being converted or closed. New electric pump awards therefore replace fuel and oil pump volume at German suppliers instead of adding new volume.
- Lower UK vehicle output leaves replacement water and fuel pumps for older cars as a larger part of demand, so the aftermarket counts for more there than in the other six countries.
- With hybrids already common in Japan, electric pump content is high and new growth comes mostly from model changes. Suppliers compete for each model renewal instead of new volume.
Full report country CAGRs cover: India and China as the two fastest countries, South Korea and the United States a little over the 3.5% global figure, Germany level with that figure, the United Kingdom and Japan below, and the rest of the standard list by region.
Country-wise Analysis
India Automotive Pumps Market Outlook (2026 to 2036)
India is forecast at a 5.1% CAGR, the fastest country rate for automotive pumps, as vehicle output grows. Evidence of this comes from Bosch Limited, which reported Q1 FY2026-27 revenue from operations of INR 5,842 crore, up 22%, with two-wheeler sales up 41.4%.[4] Local fuel pump and engine management supply for cars and motorcycles will therefore grow with output.
Key takeaway: Rising vehicle builds keep Indian pump demand ahead.
China Automotive Pumps Market Outlook (2026 to 2036)
Chinese carmakers build the largest number of hybrid and battery-electric cars, and each model needs electric coolant pumps for battery and motor circuits. At the same time, local pump makers compete hard on price with global suppliers. China ranks second at 4.2%.
Key takeaway: Electric pumps gain fastest in China.
South Korea Automotive Pumps Market Outlook (2026 to 2036)
Korean carmakers are selling more hybrids abroad, especially in the United States. Kia reported Q2 2026 wholesale sales of 851,639 units, and hybrids reached 29.6% of the company's US sales.[3] These Korean hybrid exports carry both engine and electric pump sets. On that basis, FMI projects South Korea at 3.7%.
Key takeaway: Hybrid exports raise Korean pump content.
United States Automotive Pumps Market Outlook (2026 to 2036)
US pump demand is shaped by large vehicles and by field quality issues. Ford's July 2025 fuel pump recall covered 850,318 vehicles, including Bronco, Explorer and Super Duty models.[7] A recall of that size adds replacement pump volume and pushes carmakers to tighten supplier validation. On the replacement side, PHINIA's Aftermarket sales grew to USD 356 million in Q2 2026.[5] Large trucks and SUVs keep pump content high, and the United States is expected at a 3.6% CAGR.
Key takeaway: Large vehicles and repairs keep US demand steady.
Germany Automotive Pumps Market Outlook (2026 to 2036)
The German car mix is moving quickly toward battery-electric models. Battery-electric registrations in Germany rose 48% and hybrid-electric registrations 6.9% in H1 2026, and petrol registrations fell 18.2%.[1] That mix cuts fuel and oil pump demand and adds high-voltage coolant pumps. On the supply side, Rheinmetall agreed to sell the Pierburg business to AEQUITA, with closing targeted for Q4 2026.[6] A new owner for Pierburg is likely to review German engine pump plants. Taken together, Germany is forecast at 3.5%, level with the global rate.
Key takeaway: Electric pumps replace engine pumps in Germany.
United Kingdom Automotive Pumps Market Outlook (2026 to 2036)
UK car plants build fewer vehicles than a decade ago, and new models are mostly hybrid or electric. As a result, replacement water and fuel pumps for older cars make up a larger part of demand. Accordingly, FMI's outlook for the United Kingdom is 3.3%.
Key takeaway: Replacement parts weigh more in UK demand.
Japan Automotive Pumps Market Outlook (2026 to 2036)
Japanese carmakers already build hybrids in large numbers, so electric pump content is high and growth comes mainly from model replacement. In addition, domestic vehicle output is flat. Japan grows slowest of the seven countries, at 3.2%.
Key takeaway: Mature hybrid output slows Japan.
Who are the notable companies in the automotive pumps market?
Bosch, Denso, Aisin, Astemo, ZF, PHINIA (Delphi), Pierburg, MAHLE, Valeo and Schaeffler are the profiled companies.
In FMI analysis, tier-one system suppliers, fuel and engine specialists and thermal suppliers make up the field, and most compete for both combustion and electric pump awards. Among them, PHINIA guided 2026 net sales of USD 3.57 billion to USD 3.67 billion in July 2026.[5] Guidance in that range points to stable fuel system volume through 2026. Power Systems, the Rheinmetall division that includes Pierburg, generated about EUR 2 billion of sales in 2025.[6] A unit of that size changing hands is the largest ownership shift among pump makers this year. In addition, MAHLE's Powertrain and Charging sales were EUR 3.9 billion in 2025, up 1.9% adjusted for currency.[8] Modest growth in engine-related sales shows how slowly combustion parts are fading in the near term. Bosch, Denso, Aisin, Astemo, ZF, Valeo and Schaeffler complete the group.
- Tier-one system suppliers: Bosch, Denso, Aisin, Astemo and ZF.
- Fuel and engine specialists: PHINIA (Delphi), Pierburg and MAHLE.
- Thermal and electrification suppliers: Valeo and Schaeffler.
Competitive Benchmarking: Automotive Pumps Market
Table 9: Competitive Benchmarking for the Automotive Pumps Market (qualitative ratings), 2026
| Company | Fuel Pumps | Coolant and Oil Pumps | High-Voltage Pumps | Aftermarket |
|---|---|---|---|---|
| PHINIA (Delphi) | High | Low | Low | High |
| Pierburg | Medium | High | High | Medium |
| MAHLE | Low | Medium | Medium | Medium |
| Bosch | High | Medium | Low | Medium |
| Denso | Medium | Medium | Low | Low |
Ratings compare the companies on fuel pumps, coolant and oil pumps, high-voltage pumps and aftermarket reach.
Key Developments in the Automotive Pumps Market
- Bosch Limited reported on 10 August 2026 a 29% rise in Power Solutions sales for the June 2026 quarter, pointing to strong fuel and engine system orders in India.[4]
- A complete common rail program, including the pump, appeared among the Q2 2026 new business awards PHINIA listed on 30 July 2026; for diesel pump lines this means off-road work offsets weaker car demand.[5]
- Kia put Q2 2026 hybrid sales at 178,000 units in results of 24 July 2026, a level that raises electric pump content across the Kia range.[3]
- ACEA figures of 23 July 2026 put the EU hybrid-electric share of H1 2026 car registrations at 37.3%, which signals more electric coolant circuits per new car.[1]
- On 3 June 2026, Rheinmetall agreed to sell Power Systems, including Pierburg, to AEQUITA, moving a major pump maker to a focused investor.[6]
- In 2025 results published on 15 April 2026, MAHLE showed Thermal and Fluid Systems sales of EUR 6.1 billion, a base that can be turned toward electric pumps as engine work fades.[8]
- Ford recalled 850,318 US vehicles over low-pressure fuel pumps, as reported on 12 July 2025, a reminder that one fuel pump defect can reach a large fleet quickly.[7]
- On 10 June 2025, Rheinmetall announced a CWA 2000 high-voltage coolant pump order from a North American truck maker, giving high-voltage pump demand a firm truck base.[2]
Key Players in the Automotive Pumps Market
Tier-One System Suppliers
- Bosch
- Denso
- Aisin
- Astemo
- ZF
Fuel and Engine Specialists
- PHINIA (Delphi)
- Pierburg
- MAHLE
Thermal and Electrification Suppliers
- Valeo
- Schaeffler
Automotive Pumps Market - Report Scope
Table 10: Report Scope for the Automotive Pumps Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Pump type; technology; sales channel; vehicle type; region |
| Quantitative units | USD billion |
| Market definition | Fuel supply and injection pumps, engine and transmission oil pumps, coolant, steering, vacuum and washer pumps, in mechanical and electric versions, fitted to cars, commercial vehicles and two wheelers or sold as replacement parts. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Bosch, Denso, Aisin, Astemo, ZF, PHINIA (Delphi), Pierburg, MAHLE, Valeo, Schaeffler |
| Forecast period | 2026 to 2036 |
Automotive Pumps Market - Research Methodology
Table 11: Research Methodology for the Automotive Pumps Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Desk research covers fuel system sales, electric coolant pump orders, hybrid and electric car registrations and supplier ownership changes. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 65.0 billion and the 3.5% CAGR for 2026 to 2036. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Automotive Pumps Market by Segments
Automotive Pumps Market segmented by Pump Type:
- Fuel Supply Pump
- Fuel Injection Pump
- Transmission Oil Pump
- Conventional Engine Oil Pump
- Variable Engine Oil Pump
- Steering Pump
- Coolant Pump
- Windshield Washer Pump
- Vacuum Pump
Automotive Pumps Market segmented by Technology:
- Electric
- Mechanical
Automotive Pumps Market segmented by Sales Channel:
- OEM
- Aftermarket
Automotive Pumps Market segmented by Vehicle Type:
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Two Wheeler
Automotive Pumps Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] European Automobile Manufacturers' Association. (2026, July 23). New car registrations: +5.7% in H1 2026; battery-electric 20.7% market share. https://www.acea.auto/pc-registrations/new-car-registrations-5-7-in-h1-2026-battery-electric-20-7-market-share/
- [2] Rheinmetall AG. (2025, June 10). Double-digit million euro order for Rheinmetall: Renowned North American manufacturer orders CWA 2000 coolant pump for battery-powered electric trucks. https://www.rheinmetall.com/en/media/news-watch/news/2025/06/2025-06-10-rheinmetall-cwa-2000
- [3] The Financial News. (2026, July 24). Kia posts record quarterly sales and revenue in Q2, but operating profit falls 4.9%. https://en.fnnews.com/news/202607241424065696
- [4] Bosch Limited. (2026, August 10). Quarter 01 FY 2026-27 financial results. https://www.bosch-presse.de/pressportal/in/en/press-release-8129.html
- [5] PHINIA Inc. (2026, July 30). PHINIA Reports Second Quarter 2026 Results. https://www.sec.gov/Archives/edgar/data/0001968915/000196891526000109/q220268kex991pressrelease.htm
- [6] Rheinmetall AG. (2026, June 3). Deal finalised: Rheinmetall divests its civilian division and focuses on its defence business. https://www.rheinmetall.com/en/media/news-watch/news/2026/06/2026-06-03-deal-finalised-rheinmetall-divests-its-civilian-division
- [7] ABC7 Los Angeles. (2025, July 12). Ford recalls over 850,000 cars in the US due to potential fuel pump failure. https://abc7.com/post/ford-recall-impacts-850000-cars-including-certain-broncos-explorers-150s-lincoln-aviators-navigators/17085099/
- [8] MAHLE GmbH. (2026, April 15). MAHLE Improves Operating Result in 2025. https://newsroom.mahle.com/press/en/press-releases/mahle-improves-operating-result-in-2025-111936
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the automotive pumps market during 2026?
- What market size is projected by 2036?
- Which pump type holds notable share?
- Which technology holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Pump Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Pump Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Pump Type, 2026 to 2036
- Fuel Supply Pump
- Fuel Injection Pump
- Transmission Oil Pump
- Conventional Engine Oil Pump
- Variable Engine Oil Pump
- Steering Pump
- Coolant Pump
- Windshield Washer Pump
- Vacuum Pump
- Y-o-Y Growth Trend Analysis By Pump Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Pump Type, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Electric
- Mechanical
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM
- Aftermarket
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Two Wheeler
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Pump Type
- By Technology
- By Sales Channel
- By Vehicle Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- PHINIA (Delphi)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Pierburg
- MAHLE
- Bosch
- Denso
- Aisin
- Astemo
- ZF
- Valeo
- Schaeffler
- PHINIA (Delphi)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Pump Type, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Pump Type
- Figure 6: Global Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Technology
- Figure 9: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Sales Channel
- Figure 12: Global Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Vehicle Type
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Pump Type
- Figure 29: North America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Technology
- Figure 32: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Sales Channel
- Figure 35: North America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Vehicle Type
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Pump Type
- Figure 42: Latin America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Technology
- Figure 45: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 48: Latin America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Vehicle Type
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Pump Type
- Figure 55: Western Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Technology
- Figure 58: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 61: Western Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Vehicle Type
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Pump Type
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Technology
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Vehicle Type
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Pump Type
- Figure 81: East Asia Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Technology
- Figure 84: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 87: East Asia Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Vehicle Type
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Pump Type
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Technology
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Vehicle Type
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Pump Type, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Pump Type, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Pump Type
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Technology
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Vehicle Type
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the automotive pumps market expected in 2026?
The automotive pumps market is forecast at USD 65.0 billion in 2026 by FMI, from USD 62.8 billion in 2025. Sales of automotive pumps are projected to reach USD 91.7 billion by 2036.
What CAGR is projected for the automotive pumps market through 2036?
Sales of automotive pumps are expected to grow at a 3.5% CAGR from 2026 to 2036. Hybrid cars and electric coolant pumps for batteries and trucks support that growth.
Which pump type holds a notable market share in 2026?
Fuel supply pumps are expected to lead with 44% share in 2026. Fuel injection pumps follow at about 14.5%.
Which technology holds a notable market share in 2026?
Electric pumps are likely to lead with 55% share in 2026. Mechanical pumps hold an estimated 45%.
Which country has a notable expansion outlook through 2036?
FMI projects India to grow fastest, at a 5.1% CAGR. China follows at 4.2%.
Who are the key companies in the automotive pumps market?
Bosch, Denso, Aisin, Astemo and ZF lead the tier-one system suppliers, and PHINIA (Delphi), Pierburg and MAHLE lead the fuel and engine specialists. Valeo and Schaeffler complete the profiled companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
