

- Market Size (2026)
- USD 30.0 Bn
- Forecast (2036)
- USD 53.7 Bn
- CAGR (2026 to 2036)
- 6.0%
How big is Botanical Ingredient Market in 2026?
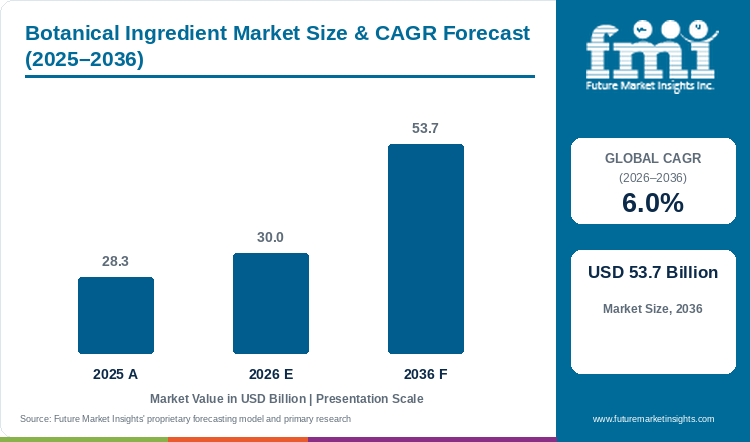
Sales in the botanical ingredient market are projected to grow at 6.0% CAGR, with the market size rising from USD 28.3 billion in 2025 to USD 30.0 billion in 2026 and reaching USD 53.7 billion by 2036.
Eliminating batch-to-batch potency drift in raw milled herbs and reducing the capsule bulk required for clinical nutraceutical dosing have pushed supplement makers toward concentrated plant fractions. Global demand for botanical ingredients advances at a 6.0% CAGR from USD 28.3 billion in 2025 and USD 30.0 billion in 2026 to reach USD 53.7 billion by 2036, creating USD 23.7 billion in incremental value as Standard Commercial Grade captures 46.0% of 2026 grade demand at the B2B bulk ingredient tier, supplying concentrated actives for downstream finished consumer formulations. National Institutes of Health Office of Dietary Supplements fact sheets in May 2025 documented that commercial ashwagandha formulations rely on standardized root extracts to achieve reproducible stress-relief dosing [1]. Supplement compounders still reject raw herb lots when monsoon moisture or soil heavy metals exceed pharmacopeial limits.
Key Market Trends & Insights
- By product type / grade: Standard commercial grade represented 46.0% of revenue in 2026, because uniform bioactive marker ratios prevent potency drift during high-speed tablet compression.
- By processing state: With a 52.4% share in 2026, fresh / ambient packaged led the category as foil-lined fiber drums protect dehydrated extracts without refrigerated ocean freight.
- By end-use application: Direct retail consumer consumption held the leading share of 37.0% in 2026, driven by household purchasing of medicinal tea bags, tinctures, and smoothie powders.
Regional Highlights
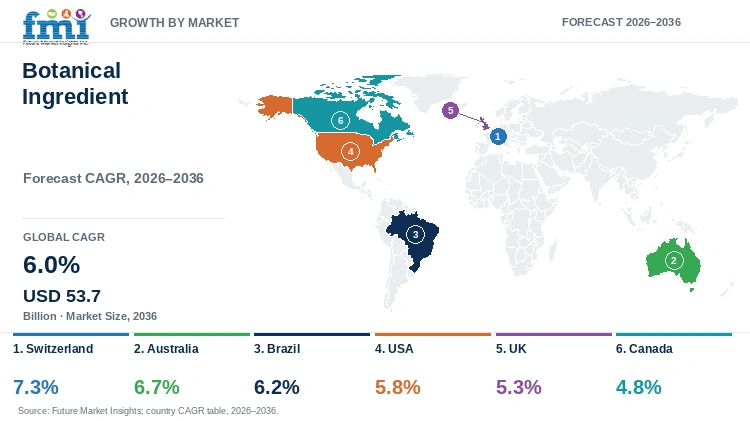
- Fastest-growing evaluated country: Switzerland, at 7.3% CAGR from 2026 to 2036.
- By country: Australia at 6.7%, Brazil at 6.2%, the USA at 5.8%, and the UK at 5.3% follow, while Canada records the lowest evaluated CAGR at 4.8%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Botanical Ingredient Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 28.3 billion |
| Estimated Market Size in 2026 | USD 30.0 billion |
| Projected Market Size by 2036 | USD 53.7 billion |
| CAGR, 2026 to 2036 | 6.0% |
| Added Revenue, 2026 to 2036 | USD 23.7 billion |
Pharmacopeial phytotherapy licensing in Switzerland and Germany operates alongside strict pre-market Natural Product Number registrations in Canada and Therapeutic Goods Administration audits in Australia, dictating which plant fractions clear customs. Importers in the United States and the European Union also run forensic identity screens before unloading raw roots and leaves into percolation tanks. U.S. Food and Drug Administration updates in December 2025 tightened botanical raw material authentication and multi-component characterization for clinical and supplement products [2]. Supplement compounders are therefore replacing unverified spot-market herbs with standardized botanical extracts backed by DNA barcoding and liquid chromatography certificates.
Phyto-Chemical Extraction and Active Marker Standardization Metrics
Table 2: Phyto-Chemical Extraction and Active Marker Standardization Metrics for the Botanical Ingredient Market (USD billion and operational parameters), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 28.3 | 30.0 | 53.7 |
| Commercial botanical biomass processing volume (thousand metric tons) | 480.0 | 515.0 | 950.0 |
| Active marker compound standardization minimum (dry weight %) | 5.0 to 12.0 | 6.0 to 14.0 | 8.0 to 18.0 |
| Supercritical carbon dioxide extraction pressure threshold (bar) | 250 to 350 | 280 to 380 | 300 to 420 |
Assay scope: Marker standardization percentages and supercritical pressure ranges reflect industrial hydro-ethanolic percolation and CO2 fractionation benchmarks.
Facility Capital Expenditure & Processing Yardstick Metrics
Preserving heat-labile polyphenols and volatile terpenes requires counter-current percolation extractors paired with low-temperature vacuum band dryers. Solvent recovery columns condense and recycle food-grade ethanol inside closed loops so extraction refineries lower per-kilogram utility costs and stay below industrial emissions caps. Multi-year supply tenders for herbs and spices extracts also compel processors to build positive-pressure milling rooms with validated allergen and cross-species washdown protocols.
Table 3: Facility Capital Expenditure and Processing Yardstick Metrics for the Botanical Ingredient Market (USD and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Certified botanical extraction plants globally (units) | 320 | 350 | 620 |
| Supercritical fluid carbon dioxide extraction skid spend (USD million) | 2.5 to 4.2 | 2.8 to 4.5 | 4.2 to 6.8 |
| Continuous vacuum band dryer line outlay (USD million) | 1.8 to 3.0 | 2.0 to 3.4 | 3.2 to 5.0 |
| Botanical species DNA barcoding and purity assay cost (USD) | 180 to 280 | 190 to 310 | 280 to 420 |
Table 4: Facility & Operational Cost Benchmark Metrics for the Botanical Ingredient Market (USD and unit parameters), mixed reporting years from 2024 to 2026
| Operational Cost Indicator | 2024 | 2025 | 2026 |
|---|---|---|---|
| Certified organic botanical raw biomass outlay per ton (USD) | 1800 to 3200 | 1900 to 3400 | 2000 to 3600 |
| Extraction-grade food ethanol solvent cost per liter (USD) | 1.25 to 1.80 | 1.30 to 1.90 | 1.35 to 2.00 |
| Electrical energy expense per batch extraction cycle (USD) | 450 to 680 | 480 to 720 | 510 to 760 |
| Drum packaging with food-grade foil liner cost per unit (USD) | 24 to 38 | 26 to 40 | 28 to 44 |
Analyst Perspective
"Binding lipophilic plant actives to sunflower phospholipids solves the gut-absorption bottleneck that once limited botanical clinical efficacy. Rejecting wild-harvested lots contaminated with pyrrolizidine alkaloids or heavy metals remains the toughest cost hurdle for extractors."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the botanical ingredient market segmented?
The botanical ingredient market is segmented by product type / grade, processing state, end-use application, and region. In 2026, standard commercial grade is projected at 46.0%, fresh / ambient packaged at 52.4%, and direct retail consumer consumption at 37.0%.
By product type / grade: Standard Commercial Grade, standardized pharmacopeial grade, and certified organic grade.
By processing state: Fresh / Ambient Packaged, spray-dried powder, and liquid extract & tincture.
By end-use application: Direct Retail Consumer Consumption, dietary supplements & nutraceuticals, functional foods & beverages, and personal care & cosmetics.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Standard Commercial Grade lead the product type category?
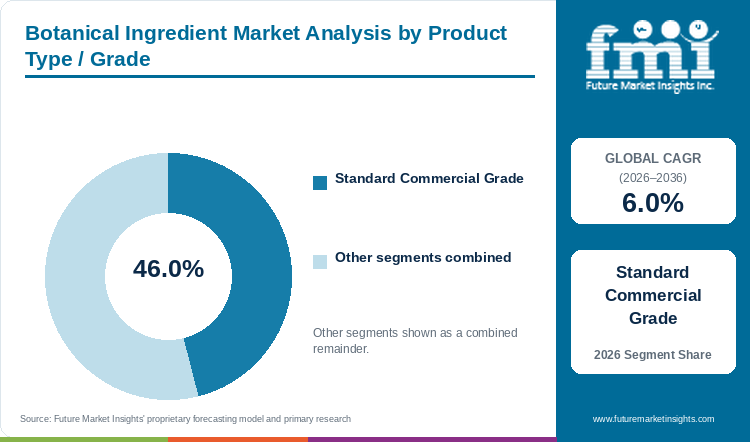
Standard commercial grade is expected to account for 46.0% of product type revenue in 2026, underpinned by consistent marker potency.
Table 5: Product Type / Grade Share for the Botanical Ingredient Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 46.0% |
| Other Segments Combined | 54.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type / Grade Leadership and Market Growth for the Botanical Ingredient Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.0% |
| Leading Segment | Standard Commercial Grade |
High-volume gummy, capsule, and functional tea lines specify standard commercial grade extracts because these lots guarantee reproducible active-marker percentages without the regulatory dossier fees attached to pharmacopeial drug monographs. Compounding facilities blend hydro-ethanolic powders with supercritical CO2 extracts so batch color, particle flowability, and polyphenol assay stay locked across million-bottle runs. That predictable potency lets wellness brands print exact milligram claims on retail labels while keeping unit cost competitive. Formulators still monitor maltodextrin and acacia carrier ratios closely so hygroscopic plant solids do not gum up rotary tablet punches.
- Standard commercial grade accounts for 46.0% of product type revenue in 2026, underpinned by balanced bioactive marker potency and broad blending compatibility.
- In April 2025, the United States Pharmacopeial Convention expanded reference standard monographs for standardized botanical extracts to prevent commercial marker dilution [3].
What keeps Fresh / Ambient Packaged ahead by processing state?
Fresh and ambient packaged is projected to capture 52.4% of processing state demand in 2026, driven by moisture-barrier drum stability.
Shipping botanical extracts across oceans in refrigerated containers adds heavy freight surcharges and risks condensation damage whenever pallets wait on tropical customs docks. Export refiners solve this logistics problem by sealing dehydrated roots, leaves, and milled powders inside nitrogen-flushed aluminum-foil bags housed in rigid fiber drums. North American and European supplement packers routinely import twenty-foot dry containers of ashwagandha root extract, chamomile, and valerian that hold full assay potency for twenty-four months at room temperature. Quality teams still verify that water activity sits below 0.45 before drum closure to block microbial growth.
- Fresh / ambient packaged represents 52.4% of processing state demand in 2026, driven by extended warehouse stability and lower ocean freight costs.
- International Botanical Extracts Council trials in July 2025 demonstrated that nitrogen-flushed foil-lined drums reduced polyphenol degradation during cross-border sea shipping [4].
Why does Direct Retail Consumer Consumption lead the end-use application category?
Direct retail consumer consumption is set to hold 37.0% of end-use application sales in 2026, reinforced by home herbal routines.
Daily household steeping of medicinal herb infusions, sublingual dropper tinctures, and spoonable wellness powders places direct retail consumer consumption ahead of industrial applications. Pharmacy chains and natural grocers allocate full aisles to single-origin chamomile, elderberry syrups, and aloe vera extracts that shoppers add to evening sleep or digestive routines without a physician visit. QR-coded farm provenance and USDA or EU organic seals further boost repeat basket conversion among ingredient-conscious buyers. Because concentrated root alkaloids taste intensely bitter in plain water, consumer brands rely on natural citrus and honey flavor modulators to keep daily adherence high.
- Direct retail consumer consumption holds 37.0% of end-use application revenue in 2026, reinforced by household herbal tea brewing and daily tincture use.
- In October 2025, Givaudan Taste & Wellbeing expanded its co-creation nutraceutical botanical platform to improve palatability in consumer-ready herbal drinks and supplements [5].
What are the drivers, restraints, and opportunities in the botanical ingredient market?
Consumer demand for standardized adaptogens and clean-label phytotherapy elevates extract volume, whereas wild-harvest supply volatility and heavy-metal limits constrain raw biomass qualification, and subcritical water and phytosome delivery systems unlock premium clinical margins.
- Driver: Preventive consumer wellness habits and clean-label reformulation across supplements and beverages expand demand for standardized adaptogenic and antioxidant plant extracts.
- Restraint: Erratic wild-harvest crop yields, synthetic adulteration risks, and strict pesticide and pyrrolizidine alkaloid limits trigger costly raw-material lot rejections.
- Opportunity: Green subcritical water extraction and phospholipid-bound phytosome complexes improve cellular bioavailability and command premium pricing in clinical channels.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Shoppers seeking non-habit-forming sleep, cortisol management, and joint comfort are moving away from synthetic over-the-counter pills toward standardized plant bioactives. Nutraceutical formulators now specify exact withanolide, curcuminoid, and bacoside percentages across herbal dietary supplements so a single two-gram gummy or capsule matches clinical study dosages. Multi-herb adaptogenic stacks are also replacing single-vitamin jars across pharmacy endcaps. Food and Agriculture Organization commodity reviews in October 2025 tracked expanding global cultivation and trade monitoring for agricultural and aromatic plant commodities [6]. Extractors must supply lot-specific chromatographic certificates before contract tableting lines approve delivery.
Risk Assessment of the Botanical Ingredient Market: Operational and Formulation Friction
Harvesting medicinal roots and barks from wild ecosystems exposes botanical refiners to erratic weather, soil heavy-metal uptake, and toxic weed co-harvesting. Droughts or unseasonal rains shift alkaloid profiles in harvested roots, while trace contamination from lead, arsenic, or hepatotoxic weeds can force a processor to incinerate an entire container load. Buyers sourcing high-value standardized ginseng extracts or bilberry powders must also guard against spiking with synthetic dyes or cheaper leaf fractions. In March 2025, the European Food Safety Authority reinforced safety evaluation guidelines for concentrated botanical preparations containing pyrrolizidine alkaloids [7]. Running LC-MS/MS contaminant panels on every farm lot lengthens quarantine hold times.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Poor water solubility and rapid liver metabolism have historically prevented fat-soluble plant polyphenols from reaching therapeutic blood levels unless patients swallowed handfuls of capsules. Phytochemistry houses solve this bioavailability barrier by complexing turmeric curcumin extracts, boswellia, and quercetin with dietary phospholipids or extracting them via subcritical water cavitation. In January 2026, dsm-firmenich and Indena advanced their strategic commercialization of pioneering biotic and Phytosome botanical combination solutions for targeted human health applications [8]. Delivering cold-water-dispersible, taste-masked micro-powders lets supplement brands launch compact daily wellness shots at premium clinical margins.
Botanical Ingredient Market by Country (2026 to 2036)
FMI data suggests that Switzerland leads growth among the six evaluated countries at a 7.3% CAGR from 2026 to 2036, while Canada expands at a steady 4.8% CAGR. Country-level performance reflects how national regulators enforce pharmacopeial registration, how processors manage indigenous crop cultivation, and how supplement brands source certified organic fractions.
Table 7: Country CAGR and Primary Growth Levers for the Botanical Ingredient Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Switzerland | 7.3% | Pharmaceutical phytotherapy registration and high-precision alpine extraction hubs |
| Australia | 6.7% | TGA Listed Medicine quality standards and indigenous botanical commercialization |
| Brazil | 6.2% | Amazonian and Cerrado bioactive valorization with spray-dried superfruit exports |
| USA | 5.8% | Large dietary supplement base and adaptogenic beverage and gummy formulation |
| UK | 5.3% | Traditional Herbal Registration (THR) pharmacy trust and organic tincture demand |
| Canada | 4.8% | Health Canada Natural Health Product (NHP) licensing and prairie herb cultivation |
Source: Future Market Insights analysis
Switzerland Botanical Ingredient Market Outlook (2026 to 2036)
Pharmaceutical-grade phytotherapy manufacturing and alpine contract cultivation anchor Switzerland's position as Europe's high-assay botanical extraction center, with national revenue forecast to rise at a 7.3% CAGR through 2036. Global flavor and bioactive groups headquartered in Vernier and Kaiseraugst run supercritical CO2 and membrane purification suites directly inside Swiss cantons. Swiss Federal Office of Public Health registries in October 2025 documented an 11.0% increase in registered phyto-medicinal preparations dispensed across domestic healthcare channels [9]. High mountain farm wages and scarce valley land preclude bulk commodity herb growing, so Swiss refiners focus on high-margin pharmacopeial isolates and clinical research partnerships.
Key takeaway: In Switzerland, statutory reimbursement for registered phytotherapy and domestic bioactive R&D centers propel a 7.3% CAGR.
Australia Botanical Ingredient Market Outlook (2026 to 2036)
Commercializing high-antioxidant indigenous flora such as Kakadu plum, lemon myrtle, and Davidson plum places Australia on a 6.7% CAGR path from 2026 to 2036. Domestic extractors operate under Therapeutic Goods Administration (TGA) Listed Medicine rules that subject botanical ingredients to pharmaceutical-grade GMP inspections, making Australian extracts highly prized across Asian export markets. Australian Therapeutic Goods Administration records in August 2025 showed a 14.0% rise in export certifications for standardized complementary medicine ingredients [10]. Outback droughts and bushfire seasons still threaten wild bush harvests, leading processors to co-finance irrigated indigenous plantation cooperatives.
Key takeaway: In Australia, TGA pharmaceutical-grade GMP auditing and irrigated native-plant plantations sustain strong export demand.
Brazil Botanical Ingredient Market Outlook (2026 to 2036)
By 2036, Brazil is projected to grow at a 6.2% CAGR, supported by industrial fractionation of Amazonian and Cerrado species including guarana, acai, catuaba, and jaborandi leaves. Rather than shipping raw frozen fruit pulp overseas, domestic processors are installing spray-drying towers and hydro-alcoholic extractors near regional collection cooperatives to capture higher export value. Brazilian Association of the Phytotherapy Industry surveys in September 2025 recorded a 10.0% expansion in domestic revenue from standardized phyto-actives and sustainable forest extracts [11]. Long barge transit along Amazonian tributaries and high humidity require mobile vacuum-drying units at forest collection points.
Key takeaway: In Brazil, local spray-drying of guarana and acai bioactives near forest cooperatives converts biodiversity into high-value export powders.
USA Botanical Ingredient Market Outlook (2026 to 2036)
Adaptogenic stress gummies, mushroom-herbal coffee alternatives, and condition-specific supplement capsules drive heavy raw-material turnover in the United States, where botanical ingredient demand is estimated to expand at a 5.8% CAGR through 2036. Updated December 2025 guidance from the U.S. Food and Drug Administration emphasized identity verification and cGMP compliance across botanical supply chains [12]. Import tariff swings on Asian botanicals and retail class-action lawsuits over synthetic adulterants create compliance risk for contract compounders. U.S. extractors protect brand clients by running in-house HPTLC botanical fingerprinting and holding multi-origin safety stocks.
Key takeaway: In the USA, high-volume adaptogenic gummy and beverage compounding relies on domestic HPTLC identity testing to prevent adulteration.
UK Botanical Ingredient Market Outlook (2026 to 2036)
The outlook for botanical ingredients in the United Kingdom remains positive, with sales projected to increase at a 5.3% CAGR through 2036 as high-street pharmacies expand shelf space for sleep tinctures, valerian tablets, and botanical nootropic drinks. British consumers look specifically for the Traditional Herbal Registration (THR) quality seal when selecting over-the-counter plant remedies. British Herbal Medicine Association pharmacy audits in November 2025 noted an 8.0% annual rise in retail demand for quality-assured traditional herbal medicinal products [13]. Post-Brexit phytosanitary border inspections still slow continental herb shipments, prompting UK blenders to hold larger bonded warehouse inventories.
Key takeaway: In the UK, shopper reliance on THR-certified pharmacy remedies and botanical wellness drinks underpins steady ingredient imports.
Canada Botanical Ingredient Market Outlook (2026 to 2036)
Health Canada's mandatory Natural Health Product (NHP) licensing regime requires every commercial herbal product to secure a pre-market Natural Product Number (NPN), supporting a 4.8% CAGR in Canada from 2026 to 2036. Because NPN dossiers demand validated active-marker assays, Canadian brand owners procure standardized extracts rather than ungraded raw powders. Canadian Health Food Association consumer polling in December 2025 found that 80.0% of surveyed Canadian adults used licensed natural health products to support immunity and wellness [14]. Short northern frost-free seasons restrict open-field warm-herb farming, so domestic growers focus on Ontario ginseng, prairie echinacea, and cranberry polyphenols.
Key takeaway: In Canada, pre-market NPN dossier rules and domestic ginseng and cranberry extraction create a highly structured buyer base.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the botanical ingredient market?
Givaudan SA, DSM-Firmenich, Kerry Group plc, Symrise AG, International Flavors & Fragrances (IFF), Martin Bauer Group, Nexira, Indena S.p.A., Sabinsa Corporation, and Arjuna Natural are the notable companies in this market.
Winning multi-year supply contracts with global supplement and beverage brands requires both farm-level organic traceability and taste-masking application labs. Givaudan, DSM-Firmenich, Kerry Group, Symrise, and IFF pair multi-continent herb procurement with bitter-blocking flavor systems so food makers can dose active botanicals into gummies and drinks. Meanwhile, Indena, Sabinsa, and Arjuna Natural isolate high-assay pharmacopeial actives and phospholipid complexes for herbal medicinal products and clinical supplements, while Martin Bauer Group and Nexira anchor global leaf milling, tea percolation, and acacia-fiber encapsulation.
- Global Flavor, Bioactive & Nutrition Platforms: Givaudan SA, DSM-Firmenich, Kerry Group plc, Symrise AG, and International Flavors & Fragrances (IFF) integrate botanical extraction with sensory masking.
- Clinical Phytochemistry & Standardized Active Specialists: Indena S.p.A., Sabinsa Corporation, and Arjuna Natural engineer patented phospholipid complexes and USP-grade curcumin and ashwagandha extracts.
- Botanical Tea, Hydrocolloid & Herbal Milling Leaders: Martin Bauer Group and Nexira manage traceable farm-to-drum herb milling, percolation, and synergistic plant fiber platforms.
Competitive Benchmarking: Botanical Ingredient Market
Table 8: Competitive Benchmarking for the Botanical Ingredient Market (qualitative capability ratings), 2026
| Company | Botanical Extract Breadth | Active Marker Standardization Depth | Clinical & Nutraceutical Access | Geographic Reach |
|---|---|---|---|---|
| Givaudan SA | High | High | High | High |
| DSM-Firmenich | High | High | High | High |
| Kerry Group plc | High | Medium | High | High |
| Symrise AG | High | High | High | High |
| International Flavors & Fragrances | High | High | High | High |
| Martin Bauer Group | High | Medium | High | High |
| Nexira | Medium | High | High | High |
| Indena S.p.A. | Medium | High | High | High |
| Sabinsa Corporation | Medium | High | High | High |
| Arjuna Natural | Medium | High | Medium | Medium |
Scoring basis: Suppliers receive a High mark in Botanical Extract Breadth when they process hundreds of root, leaf, bark, and superfruit species into both dry powders and liquid concentrates, and Medium when specialized in select plant families. Active Marker Standardization Depth is scored High where HPLC-verified bioactives, USP monographs, or phospholipid complexes for functional nutraceutical ingredients form the core catalog. Clinical & Nutraceutical Access reflects published human pharmacokinetic trials and pharmacy customer reach, while Geographic Reach separates suppliers operating extraction refineries across three or more continents from regional origin extractors.
Key Developments in the Botanical Ingredient Market
- In October 2026, Givaudan Taste & Wellbeing expanded its dedicated nutraceutical co-creation and standardized botanical extraction platform to accelerate clean-label supplement formulation [15].
- In March 2026, dsm-firmenich and Indena introduced updated biotic and Phytosome botanical combination concepts targeting gut, cognitive, and healthy-aging supplement brands [16].
- In May 2025, Martin Bauer Group commissioned an upgraded continuous herbal percolation and gentle vacuum-drying line in Germany to expand standardized tea and root extract capacity [17].
Key Players in the Botanical Ingredient Market
Global Flavor, Bioactive & Nutrition Platforms
- Givaudan SA
- DSM-Firmenich
- Kerry Group plc
- Symrise AG
- International Flavors & Fragrances (IFF)
Clinical Phytochemistry & Standardized Active Specialists
- Indena S.p.A.
- Sabinsa Corporation
- Arjuna Natural
Botanical Tea, Hydrocolloid & Herbal Milling Leaders
- Martin Bauer Group
- Nexira
Botanical Ingredient Market - Report Scope
Table 9: Report Scope for the Botanical Ingredient Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier revenue from botanical extracts, standardized phyto-actives, milled medicinal herbs, spray-dried botanical powders, and liquid tinctures sold at the B2B ingredient supply tier within the listed segmentation. Excludes finished retail consumer packaged goods, synthetic pharmaceutical drugs, unrefined culinary bulk grains, and fresh cut ornamental flowers. Category Scope Note: Ingredient valuations measure upstream B2B raw extract and active fraction sales; downstream specialized phyto-active markets (such as retail-formulated curcumin supplements, consumer nutraceuticals, and functional foods) represent finished consumer product market boundaries with multi-tier value addition. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Switzerland, Australia, Brazil, USA, UK, Canada, and additional countries in the full report |
| Key Companies Covered | Givaudan SA, DSM-Firmenich, Kerry Group plc, Symrise AG, International Flavors & Fragrances (IFF), Martin Bauer Group, Nexira, Indena S.p.A., Sabinsa Corporation, Arjuna Natural |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Botanical Ingredient Market - Research Methodology
Table 10: Research Methodology for the Botanical Ingredient Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with phytochemists, extraction plant directors, pharmacopeia compliance heads, and nutraceutical procurement executives across the value chain to validate marker standardization, solvent recovery, and pricing trends. |
| Secondary Research | Secondary research included company annual reports, FDA and EFSA botanical guidance, NIH Office of Dietary Supplements fact sheets, USP compendium updates, FAO plant trade statistics, and peer-reviewed phytomedicine literature. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up models pairing commercial herb extraction throughput with grade-level pricing and end-use formulation adoption. |
| Data Triangulation and Validation | Data is validated against macro-economic indicators, raw medicinal plant import registries, supercritical CO2 equipment installations, and supplement retail scanner data to ensure accuracy without double counting downstream finished goods. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's phyto-pharmaceutical econometric model, calibrating evaluated national growth rates against the 6.0% global baseline through verified herbal pharmacopeia regulations, nutraceutical manufacturing capacity, and dietary supplement export demand. |
| Operational Benchmark Traceability | Operational benchmarks (botanical biomass extraction tonnages, solvent extraction yields, and pharmacopeial compliance assay costs) represent modeled estimates synthesized from NIH ODS monographs, FDA botanical drug guidance, and primary commercial extractor disclosures. |
Botanical Ingredient Market by Segments
Botanical Ingredient Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Standardized Pharmacopeial Grade
- Certified Organic Grade
Botanical Ingredient Market segmented by Processing State:
- Fresh / Ambient Packaged
- Spray-Dried Powder
- Liquid Extract & Tincture
Botanical Ingredient Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Dietary Supplements & Nutraceuticals
- Functional Foods & Beverages
- Personal Care & Cosmetics
Botanical Ingredient Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Colombia
- Western Europe
- Switzerland
- Germany
- United Kingdom
- France
- Italy
- Eastern Europe
- Poland
- Czech Republic
- East Asia
- Japan
- China
- South Korea
- South Asia and Pacific
- Australia
- India
- New Zealand
- Middle East and Africa
- South Africa
- GCC Countries
Research Sources and Bibliography
- [1] National Institutes of Health. (2025, May 02). Ashwagandha: Is it helpful for stress, anxiety, or sleep? Health professional fact sheet. NIH Office of Dietary Supplements.
- [2] U.S. Food and Drug Administration. (2025, December 12). Frequently asked questions on botanical drug and dietary supplement product development. Center for Drug Evaluation and Research.
- [3] United States Pharmacopeial Convention. (2025, April 18). USP-NF dietary supplements compendium: Standardized botanical reference standards. USP Scientific Bulletin, 48(2), 110-128.
- [4] International Botanical Extracts Council. (2025, July 15). Quality assurance, moisture-barrier drum stability, and marker standardization in commercial extracts. IBEC Technical Bulletin, 18, 42-58.
- [5] Givaudan SA. (2025, October 03). Harnessing nature to deliver standardized botanical actives and taste solutions for nutraceuticals. Givaudan Taste & Wellbeing Reports.
- [6] Food and Agriculture Organization. (2025, October 16). World review of agricultural, medicinal, and aromatic plant production and supply balances. FAO World Food and Crop Situation.
- [7] European Food Safety Authority. (2025, March 27). Scientific opinion on safety assessment guidelines and alkaloid limits for concentrated botanical preparations. EFSA Journal, 23(3), 8825.
- [8] dsm-firmenich & Indena S.p.A. (2026, January 20). Strategic partnership update: Pioneering biotic and Phytosome botanical solutions for human health. dsm-firmenich Health, Nutrition & Care Releases.
- [9] Swiss Federal Office of Public Health. (2025, October 14). Phytotherapy consumption and registration of herbal medicinal products in Switzerland. BAG Statistical Report, 29, 35-50.
- [10] Australian Therapeutic Goods Administration. (2025, August 21). Listed complementary medicines: Export certifications and GMP quality standards for herbal ingredients. TGA Technical Guide, 22, 50-68.
- [11] Brazilian Association of the Phytotherapy Industry. (2025, September 19). Biodiversity valorization and spray-dried extract supply chains in Brazil. ABIFISA Review, 16, 25-42.
- [12] U.S. Food and Drug Administration. (2025, December 11). Dietary supplements guidance documents and regulatory information for botanical identity testing. FDA Food and Dietary Supplements Guidance.
- [13] British Herbal Medicine Association. (2025, November 12). Annual review of Traditional Herbal Registration compliance and UK pharmacy purchasing. BHMA Overview, 31, 18-34.
- [14] Canadian Health Food Association. (2025, December 04). Natural health product consumer utilization trends and NPN regulatory overview. CHFA Industry Report, 27, 40-55.
- [15] Givaudan Taste & Wellbeing. (2026, October 03). Expansion of global nutraceutical botanical co-creation and extraction capabilities. Givaudan Corporate Announcements.
- [16] dsm-firmenich. (2026, March 15). Launch of next-generation biotic and botanical combination concepts with Indena. Corporate Press Releases.
- [17] Martin Bauer Group. (2025, May 22). Commissioning of advanced herbal percolation and vacuum-drying center for standardized extracts. Martin Bauer Corporate News.
- [18] Indena S.p.A. (2025, September 18). Completion of multi-million-euro production expansion for phospholipid Phytosome botanical complexes in Milan. Indena Press Room.
- [19] Kerry Group plc. (2025, November 11). Expansion of clinical botanical extract and proactive health ingredient portfolio for functional beverages. Kerry Group Investor Releases.
- [20] Sabinsa Corporation. (2026, February 09). New USP-aligned standardization capacity for curcuminoid and ashwagandha root bioactives. Sabinsa Corporate Bulletins.
- [21] Symrise AG. (2025, July 29). Traceable organic botanical sourcing and green extraction upgrade across European processing sites. Symrise Corporate Reports.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the botanical ingredient market in 2026 and what is forecast for 2036?
- Why does standard commercial grade lead the product type category?
- What keeps fresh / ambient packaged ahead across the processing state category?
- Why does direct retail consumer consumption command the largest end-use share?
- How do growth rates differ across Switzerland, Australia, Brazil, and the USA?
- Which notable companies supply standardized botanical extracts and phyto-actives today?
- What contaminant screening and wild-harvest pressures restrain botanical extractors?
- What should supplement and beverage buyers evaluate before qualifying a botanical supplier?
Frequently Asked Questions
How big is the botanical ingredient market in 2026, and what is forecast for 2036?
The global botanical ingredient market is projected to reach USD 30.0 billion in 2026 and expand to USD 53.7 billion by 2036, driven by consumer demand for standardized herbal supplements and clean-label functional beverages.
What is the CAGR for the botanical ingredient market from 2026 to 2036?
According to FMI, the botanical ingredient market will expand at a 6.0% CAGR between 2026 and 2036, propelled by supercritical CO2 extraction adoption and verified bioactive marker standardization.
Which product grade segment leads the botanical ingredient market in 2026?
Standard commercial grade is projected to hold 46.0% of product type demand in 2026. Consistent active marker potency, high-speed tableting compatibility, and balanced formulation cost keep this grade ahead.
Which processing state holds the largest botanical ingredient share in 2026?
Fresh / ambient packaged is estimated to account for 52.4% of processing state demand in 2026. Demand is underpinned by nitrogen-flushed foil-lined drums that protect extracts from moisture without cold-chain shipping.
Which country has the fastest botanical ingredient growth outlook through 2036?
In the FMI report, Switzerland leads with a 7.3% CAGR from 2026 to 2036, backed by pharmaceutical phytotherapy manufacturing and alpine botanical extraction R&D.
Who are the notable companies active in the botanical ingredient market?
Active suppliers in the market include Givaudan SA, DSM-Firmenich, Kerry Group plc, Symrise AG, International Flavors & Fragrances (IFF), Martin Bauer Group, Nexira, Indena S.p.A., Sabinsa Corporation, and Arjuna Natural.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Standardized Pharmacopeial Grade
- Certified Organic Grade
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Spray-Dried Powder
- Liquid Extract & Tincture
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Dietary Supplements & Nutraceuticals
- Functional Foods & Beverages
- Personal Care & Cosmetics
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Colombia
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Switzerland
- Germany
- United Kingdom
- France
- Italy
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- China
- South Korea
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- India
- New Zealand
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Africa
- GCC Countries
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Givaudan SA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- DSM-Firmenich
- Kerry Group plc
- Symrise AG
- International Flavors & Fragrances
- Martin Bauer Group
- Nexira
- Indena S.p.A.
- Sabinsa Corporation
- Arjuna Natural
- International Flavors & Fragrances (IFF)
- Givaudan SA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


