

- Market Size (2026)
- USD 4.5 Bn
- Forecast (2036)
- USD 7.7 Bn
- CAGR (2026 to 2036)
- 5.5%
How big is Calcium Supplements Market in 2026?
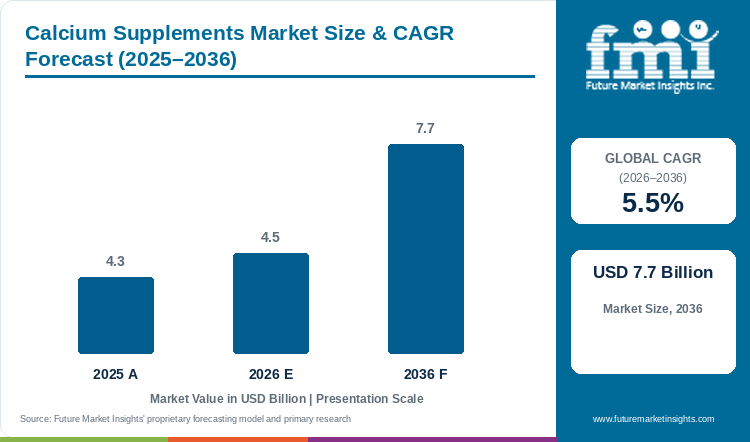
Sales in the calcium supplements market are projected to grow at 5.5% CAGR, with the market size rising from USD 4.3 billion in 2025 to USD 4.5 billion in 2026 and reaching USD 7.7 billion by 2036.
Growing clinical focus on preventive geriatric bone care and the need to lower age-related hip fractures have led to wider hospital and pharmacy reliance on standardized mineral supplementation. According to Future Market Insights analysis, the global calcium supplements market grows from USD 4.3 billion in 2025 to USD 4.5 billion in 2026 and is projected to reach USD 7.7 billion by 2036, advancing at a 5.5% CAGR over the 2026 to 2036 period and generating USD 3.2 billion in added revenue. In January 2025, the National Institutes of Health Office of Dietary Supplements reported that adults aged 50 and older require 1,000 to 1,200 milligrams of daily elemental intake to preserve trabecular bone density [1]. Owing to the advantages associated with particle uniformity, fine powder and micronized crystals hold 46.9% of form demand in 2026 across bone health supplements. However, issues such as chalky taste and slow tablet disintegration continue to challenge standard mineral formulations.
Key Market Trends & Insights
- By form / physical state: Fine powder and micronized crystals led the market with a share of 46.9% in 2026, supported by rapid dissolution kinetics in high-speed rotary presses.
- By source / nature: Conventional farm source accounted for 38.6% of demand in 2026, owing to established mineral limestone refining networks supplying cost-effective raw ingredients.
- By application sector: Dietary supplements and nutraceuticals represented 41.0% of revenue in 2026, reflecting clinical bone density regimens that require measured daily elemental intake.
- By sales channel: With a 55.4% share in 2026, B2B direct industrial food manufacturers led the category, underpinned by multi-year contracts for fortified dairy and cereals.
Regional Highlights
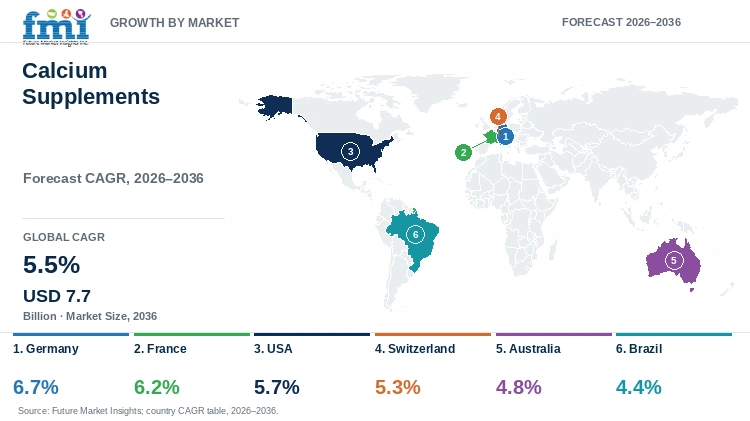
- Fastest-growing evaluated country: Germany, at 6.7% CAGR from 2026 to 2036.
- By country: France at 6.2%, USA at 5.7%, and Switzerland at 5.3% follow, while Brazil records the lowest evaluated CAGR at 4.4%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Calcium Supplements Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4.3 billion |
| Estimated Market Size in 2026 | USD 4.5 billion |
| Projected Market Size by 2036 | USD 7.7 billion |
| CAGR, 2026 to 2036 | 5.5% |
| Added Revenue, 2026 to 2036 | USD 3.2 billion |
Country demand conditions differ as national pharmacy reimbursement rules and elemental labeling standards shape how supplement brands formulate finished caplets. FMI research indicates that contract manufacturers face recurring patient drop-off when high-dose mineral tablets cause abdominal bloating or fail dissolution checks. In February 2025, the U.S. Food and Drug Administration updated its dietary supplement labeling guidance requiring explicit elemental mineral weight declarations per serving [2]. In addition to this, formulators are blending organic citrate malate salts with dietary supplements that absorb without requiring elevated stomach acid, which directly alters batch compression sizing across pharmaceutical plants.
Elemental Fractionation and Pharmaceutical Compression Batch Sizing
Table 2: Elemental Fractionation and Pharmaceutical Compression Batch Sizing for the Calcium Supplements Market (USD billion and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 4.3 | 4.5 | 7.7 |
| Commercial supplement tablet production (billion units) | 35.8 to 38.5 | 37.5 to 40.2 | 64.2 to 68.8 |
| Annual pharmaceutical mineral consumption (thousand metric tons) | 43.0 to 46.2 | 45.0 to 48.3 | 77.0 to 82.5 |
| Wholesale realization per production batch (USD thousand) | 12.8 to 14.2 | 13.5 to 14.8 | 21.4 to 23.5 |
Operational note: Production estimates reflect standard 1,000-milligram finished caplets containing 500 milligrams of elemental mineral across commercial tableting runs.
Per Capita Consumption and Retail Channel Sizing
Preventive bone health regimens have gained steady traction in recent years as older adults seek daily mineral replenishment that supports skeletal strength without causing digestive upset. Managing long-term osteopenia requires balancing elemental dosage density with gastric solubility across clinical nutrition channels. Surging prescriptions from geriatric clinics convert demographic aging into recurring pharmacy orders, while retail health chains expand shelf space for chelated mineral caplets.
Table 3: Per Capita and Preventive Health Spending Indicators for the Calcium Supplements Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per capita (USD) | 0.5 | 0.5 | 0.9 |
| Spend per 1,000 people (USD) | 522.5 | 542.2 | 860.3 |
| Senior demographic annual spend (USD) | 48.5 to 54.0 | 51.0 to 56.5 | 78.0 to 86.5 |
Table 4: Facility & Institutional Channel Sizing Indicators for the Calcium Supplements Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 4.5 billion | Report value |
| Commercial retail pharmacy dispensaries worldwide | 340.0 thousand | 2025 healthcare census |
| Average annual revenue per dispensary outlet | USD 13.2 thousand | Industry benchmark |
| B2B industrial manufacturer revenue, 2026 | USD 2.5 billion | 55.4% share |
Analyst Perspective
"Micro-milled citrate and marine mineral grades let formulators deliver high elemental doses in smaller tablets. Batch dissolution testing remains essential before pharmacy chains approve wider private-label supply."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the calcium supplements market segmented?
The calcium supplements market is segmented by form / physical state, source / nature, application sector, and sales channel. In 2026, Fine Powder & Micronized Crystals is projected at 46.9%, conventional farm source at 38.6%, dietary supplements & nutraceuticals at 41.0%, and B2B direct industrial food manufacturers at 55.4%.
By form / physical state: Fine powder and micronized crystals, standardized granules and pellets, and liquid extract and tincture.
By source / nature: Conventional farm source, certified organic and non-GMO, and fermentation / bio-synthesized.
By application sector: Dietary supplements and nutraceuticals, functional food and beverages, cosmetics and topical personal care, and animal nutrition.
By sales channel: B2B direct industrial food manufacturers, retail packaged health stores, and online DTC brands.
Why does Fine Powder & Micronized Crystals lead the form / physical state category?
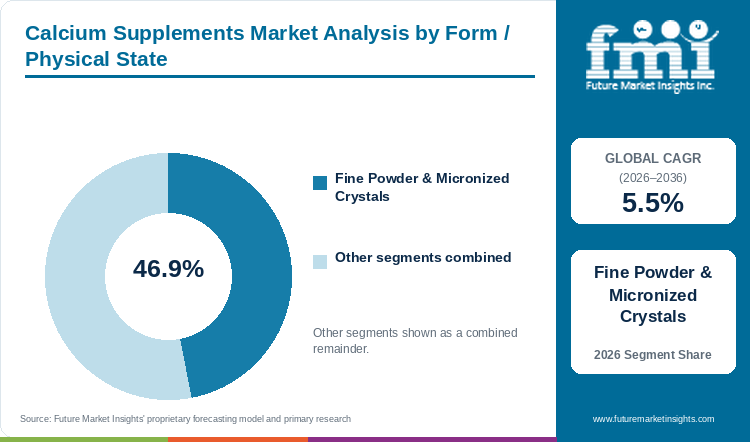
Fine powder and micronized crystals are expected to account for 46.9% of form / physical state demand in 2026, supported by rapid dissolution.
Table 5: Form / Physical State Share for the Calcium Supplements Market (percentage share), 2026
| Form / Physical State | Share (2026) |
|---|---|
| Fine Powder & Micronized Crystals | 46.9% |
| Other Segments Combined | 53.1%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Form / Physical State Leadership and Market Growth for the Calcium Supplements Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.5% |
| Leading Segment | Fine Powder & Micronized Crystals |
Pharmaceutical tableting engineers rely on micronized crystal powders because uniform particle size prevents die-wall friction and tablet capping during high-speed rotary compression. When coarse mineral grains are used, tablets frequently crack or leave gritty sediment in beverage mixes. Owing to the advantages associated with particle reduction below 15 microns, ground and precipitated calcium carbonate disperses evenly inside dry premixes and dissolves rapidly in gastric fluid. In addition to this, contract packagers check bulk tap density before locking in annual supply.
- Fine powder and micronized crystals are projected to hold 46.9% share in 2026, supported by uniform particle dispersion that accelerates automated encapsulation.
- In March 2025, the European Food Safety Authority Panel on Nutrition confirmed that micro-milled carbonate grades achieved faster intestinal ion release than unmilled mineral granules [3].
Why does Conventional Farm Source define the largest source category?
Conventional farm source is estimated to represent 38.6% of the source / nature category in 2026, underpinned by established limestone refining.
Conventional mineral refining commands the largest volume share because national pharmacy chains require thousands of metric tons of standardized salts at stable unit costs. While organic algal grades appeal to specialty buyers, mined and refined mineral deposits yield 40% elemental concentration by weight, which keeps tablet counts low for daily regimens. Furthermore, processors pair carbonate with calcium phosphate to balance elemental phosphorus ratios in clinical bone formulas. However, issues such as natural lead and cadmium trace residues require acid-wash purification before USP release.
- Conventional farm source is forecast to maintain 38.6% share in 2026, attributable to high elemental density and predictable bulk refining economics.
- In April 2025, World Health Organization musculoskeletal health guidelines noted that purified elemental mineral salts remain the primary baseline therapy for public osteoporosis programs [4].
What keeps Dietary Supplements & Nutraceuticals ahead by application sector?
Dietary supplements and nutraceuticals are projected to capture 41.0% of application sector revenue in 2026, driven by daily geriatric bone regimens.
Nutraceutical brands generate the largest share of application revenue because clinicians routinely advise post-menopausal women and older adults to maintain daily mineral intake alongside vitamin D3. Unlike seasonal wellness products, bone density regimens require continuous year-round adherence to prevent cortical bone loss. Owing to this recurring consumption pattern, manufacturers are expanding nutraceutical gummies and effervescent sachets for patients who struggle to swallow large coated caplets. Besides this, brands must verify cofactor stability across 24-month pharmacy shelf cycles.
- Dietary supplements and nutraceuticals account for 41.0% share in 2026, enabled by clinical screening programs targeting age-related bone mineral loss.
- In May 2025, the United States Pharmacopeial Convention published updated compendium standards validating dissolution testing for combined mineral and vitamin D3 tablets [5].
What gives B2B Direct Industrial Food Manufacturers the leading position in sales channel?
With an estimated 55.4% share in 2026, B2B direct industrial food manufacturers lead sales channel demand, owing to bulk fortification contracts.
Direct B2B supply contracts dominate channel revenue because multinational food and beverage processors procure mineral salts in multi-ton Silo shipments to fortify breakfast cereals and dairy alternatives. When processors formulate plant-based milk, they must match the 120 milligrams per 100 milliliters elemental benchmark of cow's milk without causing chalky sedimentation at the bottom of the carton. Consequently, buyers source calcium caseinate and colloidal suspension grades directly from primary chemical refiners under annual quality audits.
- B2B direct industrial food manufacturers represent 55.4% share in 2026, reinforced by multi-year procurement agreements across fortified food and beverage plants.
- In June 2026, Archer Daniels Midland Company expanded industrial production of high-solubility mineral fortification blends for commercial bakery and beverage processors [6].
What are the drivers, restraints, and opportunities in the calcium supplements market?
In the Calcium Supplements Market, geriatric osteoporosis screening will continue to support demand, gastrointestinal intolerance will constrain high-dose adherence, and marine algae mineral complexes are expected to expand premium formulations through 2036.
- Driver: Expanding geriatric bone density screening and commercial dairy-alternative fortification will continue to drive routine mineral procurement through 2036.
- Restraint: Gastric bloating, constipation, and unabsorbed vascular mineral deposition will continue to limit patient adherence to standard carbonate tablets through 2036.
- Opportunity: Porous marine algae mineral complexes and chelated vitamin K2 co-formulations are expected to unlock higher-margin pharmacy contracts through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Rising hospital admissions for osteoporotic hip and vertebral fractures are compelling public health agencies to integrate daily mineral supplementation into primary geriatric care. FMI data suggests that clinical nutrition buyers are moving away from chalky bulk powders toward bioavailable citrate and malate grades that absorb effectively even in older patients with reduced gastric acid secretion. In May 2025, the International Osteoporosis Foundation reported that targeted daily calcium and vitamin D supplementation reduces institutional hip fracture incidence by 16% among screened seniors [7]. Furthermore, hospital pediatric and adult wards rely on soluble calcium gluconate for rapid electrolyte replenishment before transitioning patients to oral maintenance tablets.
Risk Assessment of the Calcium Supplements Market: Operational and Formulation Friction
Gastrointestinal discomfort and clinical scrutiny over vascular calcification remain the primary barriers restricting long-term patient compliance. High single doses of insoluble carbonate salts neutralize stomach acid and release carbon dioxide gas, which causes bloating and leads nearly one-third of older patients to discontinue daily tablets within six months. In February 2025, a clinical safety review indexed by the National Library of Medicine found that bolus elemental doses exceeding 500 milligrams without vitamin K2 cofactors increase unabsorbed serum mineral spikes [8]. As a result, supplement formulators must split dosages or invest in micro-encapsulated carriers, which raises raw material and tableting costs.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Significant commercial upside exists for ingredient suppliers that replace mined rock salts with porous plant-derived mineral matrices and easy-to-swallow delivery formats. Harvested red marine algae (Lithothamnion) provides a honeycomb mineral structure with natural trace magnesium that dissolves smoothly at neutral pH without causing gastric irritation. In April 2026, Cargill, Incorporated expanded its specialized micronutrient suspension portfolio for fortified dairy and clinical nutrition brands [9]. Developing algae-based supplements alongside menaquinone-7 cofactors allows supplement brands to command premium retail pricing while addressing clinician concerns over arterial mineral retention.
Calcium Supplements Market by Country (2026 to 2036)
As per FMI, Germany represents the fastest-growing calcium supplements market among the evaluated economies, recording a 6.7% CAGR from 2026 to 2036, while Brazil posts the slowest expansion at 4.4% CAGR. Across all evaluated countries, commercial growth depends on how effectively manufacturers overcome tablet swallowing fatigue, comply with national heavy-metal pharmacopeia thresholds, and secure retail pharmacy shelf distribution.
Table 7: Country CAGR and Primary Growth Levers for the Calcium Supplements Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Germany | 6.7% | Aging demographic density and pharmacy-led preventive osteoporosis supplementation |
| France | 6.2% | Clinical geriatric wellness programs and prescription bone density co-therapies |
| USA | 5.7% | Mainstream OTC retail pharmacy placement and plant-based beverage fortification |
| Switzerland | 5.3% | Premium clinical nutrition standards and high consumer spending on chelated minerals |
| Australia | 4.8% | Active senior lifestyle trends and TGA-listed complementary medicine exports |
| Brazil | 4.4% | Expanding urban private pharmacy networks and staple food mineral fortification |
Source: Future Market Insights analysis
Germany Calcium Supplements Market Outlook (2026 to 2036)
Germany leads European expansion because community pharmacies (Apotheken) serve as the primary counseling channel for geriatric bone health and fast-dissolving effervescent mineral tubes. In September 2025, the Federal Statistical Office (Destatis) reported that citizens aged 65 and older reached 22.4% of the national population, expanding the patient pool requiring daily osteopenia management [10]. By 2036, Germany is projected to grow at 6.7% CAGR, supported by physician-guided preventive supplementation. However, strict Federal Institute for Drugs and Medical Devices impurity audits penalize high-lead mineral batches, prompting German formulators to qualify ultra-pure citrate and lactate-gluconate salts for domestic pharmacy chains.
Key takeaway: In Germany, high geriatric demographic density and pharmacist-led counseling drive strong demand for pharmaceutical-grade effervescent mineral formulations.
France Calcium Supplements Market Outlook (2026 to 2036)
Clinical fall-prevention protocols across French geriatric hospitals and nursing homes anchor steady demand for combined mineral and cholecalciferol regimens. The France calcium supplements sector is projected to record 6.2% CAGR during the assessment period, propelled by parapharmacy retail expansion and single-dose oral powder sachets. In July 2025, the National Institute of Health and Medical Research (INSERM) documented that structured vitamin D3 and calcium co-administration reduced nursing home fracture hospitalizations by 14.5% across regional cohorts [11]. Statutory delisting of generic OTC vitamins from social security reimbursement creates price pressure, so French laboratories differentiate through high-absorption pidolate and marine mineral sachets.
Key takeaway: In France, hospital fall-prevention guidelines and parapharmacy merchandising favor single-dose powder sachets and bioavailable organic salts.
USA Calcium Supplements Market Outlook (2026 to 2036)
In the United States, large-scale club store retailing and commercial beverage fortification sustain the largest national volume base for elemental mineral salts. Adoption of calcium supplements in the USA is estimated to expand at 5.7% CAGR through 2036, underpinned by private-label pharmacy programs and fortified plant-milk production. In October 2025, the Centers for Disease Control and Prevention reported that 18.8% of American women aged 50 and older exhibit osteoporosis of the femur neck or lumbar spine [12]. Because California Proposition 65 lead thresholds trigger litigation risks for mined carbonate, American brands increasingly blend USP-verified calcium chloride and chelated citrate into clean-label gummies and hydration mixes.
Key takeaway: In the USA, strict Proposition 65 heavy-metal compliance and club-store private-label scale push suppliers toward verified low-lead citrate and algal minerals.
Switzerland Calcium Supplements Market Outlook (2026 to 2036)
Swiss consumers prioritize clinically documented bioavailability and pure alpine or marine mineral sourcing over low-price commodity tablets. Demand for calcium supplements in Switzerland is anticipated to grow at 5.3% CAGR between 2026 and 2036, owing to high per-capita preventive health expenditure across Zurich, Basel, and Geneva. In August 2025, the Swiss Federal Food Safety and Veterinary Office updated micronutrient maximum daily intake levels to require clear cofactor bioavailability disclosures on supplement packaging [13]. High domestic cleanroom labor costs restrict low-margin tableting, leading Swiss contract manufacturers to focus on micro-encapsulated bisglycinate and K2-fortified longevity capsules exported across Europe.
Key takeaway: In Switzerland, affluent preventive-health buyers and strict federal labeling standards reward high-purity chelated mineral and vitamin K2 combinations.
Australia Calcium Supplements Market Outlook (2026 to 2036)
Australia benefits from a deeply established complementary medicine export engine where domestic pharmacy brands supply both local seniors and cross-border Asia-Pacific e-commerce channels. Sales of calcium supplements in Australia are forecast to expand at 4.8% CAGR through 2036, attributable to mandatory Therapeutic Goods Administration (TGA) AUST L listing standards that reinforce buyer trust. In November 2025, the Therapeutic Goods Administration implemented updated stability audit protocols for listed mineral tablets sold in high-humidity tropical zones [14]. Because imported bulk excipients face maritime freight delays, Australian formulators lock in multi-year supply agreements with certified mineral refiners to keep blister-pack lines running.
Key takeaway: In Australia, rigorous TGA listing credentials and cross-border Asia-Pacific retail demand sustain premium positioning for domestically blister-packed mineral supplements.
Brazil Calcium Supplements Market Outlook (2026 to 2036)
Expanding private health plan enrollment and rapid drugstore chain consolidation across Sao Paulo and Rio de Janeiro are widening access to preventive bone care in Brazil. Between 2026 and 2036, the Brazil market is expected to progress at 4.4% CAGR, aided by municipal maternal and geriatric nutrition programs. In December 2025, the Brazilian Health Regulatory Agency (Anvisa) revised its regulatory framework for food supplements to streamline registration of chelated mineral compounds [15]. Currency volatility and import duties on specialty organic salts still squeeze retail margins, so domestic laboratories rely on locally refined limestone carbonate for mass-market pharmacy lines while reserving imported chelates for upper-income clinics.
Key takeaway: In Brazil, drugstore chain expansion and updated Anvisa supplement rules support steady volume growth for locally tableted carbonate and targeted chelated lines.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the calcium supplements market?
Archer Daniels Midland Company (ADM), Cargill, Incorporated, Bunge Global SA, Kerry Group plc, Ingredion Incorporated, Tate & Lyle PLC, Glanbia plc, and Ashland Inc. are the significant market players in this market.
An FMI analyst notes that competition in the calcium supplements market splits across three operational groups. Multinational agricultural and mineral processors run high-tonnage purification plants that supply bulk food-grade and USP-grade mineral salts. Specialty formulation houses engineer taste-masked premixes, colloidal suspension systems, and organic chelated carriers for beverage and nutraceutical brands. Excipient and clinical nutrition specialists provide direct-compression binders and clinically tested marine mineral complexes. Procurement teams evaluate suppliers on heavy-metal assay consistency, particle size distribution, and multi-region regulatory documentation.
- Global Mineral Refiners and Agribusiness Giants: Archer Daniels Midland Company (ADM), Cargill, Incorporated, and Bunge Global SA supply bulk purified mineral salts and industrial fortification ingredients.
- Specialized Nutrition and Taste Innovators: Kerry Group plc, Ingredion Incorporated, and Tate & Lyle PLC develop soluble mineral premixes, suspension starches, and flavor-masked fortification systems.
- Clinical Dosage and Performance Manufacturers: Glanbia plc and Ashland Inc. provide bioavailable marine mineral complexes and direct-compression pharmaceutical tableting excipients.
Competitive Benchmarking: Calcium Supplements Market
Table 8: Competitive Benchmarking for the Calcium Supplements Market (qualitative capability ratings), 2026
| Company | Mineral Purification Breadth | Bioavailability Technology Depth | Pharmaceutical Distribution Access | Geographic Reach |
|---|---|---|---|---|
| Archer Daniels Midland Company (ADM) | High | High | High | High |
| Cargill, Incorporated | High | High | High | High |
| Bunge Global SA | High | Medium | High | High |
| Kerry Group plc | High | High | High | High |
| Ingredion Incorporated | Medium | High | Medium | Medium |
| Tate & Lyle PLC | Medium | High | High | Medium |
| Glanbia plc | High | High | High | High |
| Ashland Inc. | High | High | High | Medium |
Scoring basis: Mineral Purification Breadth is High when a supplier offers multiple food and pharmacopeial mineral grades, and Medium when focused on selected derivatives. Bioavailability Technology Depth is High when micronized, chelated, or marine complexes are documented. Pharmaceutical Distribution Access reflects supply reach into contract tableting and clinical channels. It does not rank companies by market share.
Key Developments in the Calcium Supplements Market
- In March 2026, Archer Daniels Midland Company commissioned an expanded pharmaceutical-grade mineral refining line in Illinois, increasing high-purity carbonate output by 25% for contract tableting buyers [16].
- In January 2026, Kerry Group plc launched a taste-masked micronized mineral fortification premix engineered to prevent chalky sedimentation in plant-based beverages and chewable tablets [17].
- In November 2025, Glanbia plc completed a clinical bioavailability study confirming higher trabecular bone mineral uptake for its organic marine algae mineral complex [18].
- In August 2025, Ashland Inc. expanded its European pharmaceutical excipient manufacturing line to supply co-processed direct-compression binders for high-load mineral caplets [19].
Key Players in the Calcium Supplements Market
Global Mineral Refiners and Agribusiness Giants
- Archer Daniels Midland Company (ADM)
- Cargill, Incorporated
- Bunge Global SA
Specialized Nutrition and Taste Innovators
- Kerry Group plc
- Ingredion Incorporated
- Tate & Lyle PLC
Clinical Dosage and Performance Manufacturers
- Glanbia plc
- Ashland Inc.
Calcium Supplements Market - Report Scope
Table 9: Report Scope for the Calcium Supplements Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form / Physical State; Source / Nature; Application Sector; Sales Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from elemental calcium salts, chelated organic mineral carriers, and standardized calcium supplement formulations sold across the listed segmentation. Excludes unrefined construction limestone and industrial cement minerals outside nutritional or personal care use. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Germany, France, USA, Switzerland, Australia, Brazil, and additional countries in the full report |
| Key Companies Covered | Archer Daniels Midland Company (ADM), Cargill, Incorporated, Bunge Global SA, Kerry Group plc, Ingredion Incorporated, Tate & Lyle PLC, Glanbia plc, Ashland Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Calcium Supplements Market - Research Methodology
Table 10: Research Methodology for the Calcium Supplements Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with pharmaceutical formulation chemists, supplement brand executives, clinical dietitians, and wholesale pharmacy procurement managers across key regions. |
| Secondary Research | Secondary research synthesized pharmacopeial purity monographs, clinical bone health registries, corporate financial disclosures, and regulatory guidance documents relevant to dietary mineral supplementation. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period combined top-down and bottom-up assessments of food-grade and pharmaceutical mineral volumes, dosage pricing, and channel adoption. |
| Data Triangulation and Validation | Estimates were cross-checked against osteoporosis prevalence indicators, regulatory compliance filings, and corporate segment revenues to ensure consistency without double counting. |
Calcium Supplements Market by Segments
Calcium Supplements Market segmented by Form / Physical State:
- Fine Powder & Micronized Crystals
- Standardized Granules & Pellets
- Liquid Extract & Tincture
Calcium Supplements Market segmented by Source / Nature:
- Conventional Farm Source
- Certified Organic & Non-GMO
- Fermentation / Bio-Synthesized
Calcium Supplements Market segmented by Application Sector:
- Dietary Supplements & Nutraceuticals
- Functional Food & Beverages
- Cosmetics & Topical Personal Care
- Animal Nutrition
Calcium Supplements Market segmented by Sales Channel:
- B2B Direct Industrial Food Manufacturers
- Retail Packaged Health Stores
- Online DTC Brands
Calcium Supplements Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Israel
- Turkiye
Research Sources and Bibliography
- [1] National Institutes of Health Office of Dietary Supplements. (2025, January 16). Calcium and bone health: Fact sheet for health professionals. U.S. Department of Health and Human Services Clinical Fact Sheet.
- [2] Center for Food Safety and Applied Nutrition. (2025, February 20). Guidance for industry: Elemental mineral labeling and dissolution testing for dietary supplement tablets. U.S. Food and Drug Administration Regulatory Guidance.
- [3] European Food Safety Authority Panel on Nutrition. (2025, March 14). Scientific opinion on the bioavailability and gastrointestinal tolerability of micronized mineral salts. EFSA Journal, 23(3), e08445.
- [4] World Health Organization Department of Nutrition. (2025, April 22). Prevention and management of osteoporosis in aging populations: Global public health guidelines. WHO Technical Report Series, 1045.
- [5] United States Pharmacopeial Convention. (2025, May 18). Dietary supplements compendium: Standardized monographs for calcium salts and vitamin D3 cofactors. USP Technical Bulletin, 48(2), 210-226.
- [6] Archer Daniels Midland Company. (2026, June 12). Expansion of high-solubility food-grade mineral fortification blends for commercial beverage manufacturers. ADM Corporate Press Release.
- [7] International Osteoporosis Foundation. (2025, May 05). Global epidemiological audit: Nutritional strategies for fracture reduction in older adults. IOF Technical Monograph, 38, 45-68.
- [8] National Library of Medicine Clinical Nutrition Group. (2025, February 12). Calcium supplementation efficacy, bolus dosing limits, and vascular safety in older adults. PubMed Central Clinical Review, PMC11821691.
- [9] Cargill, Incorporated. (2026, April 16). Global food and nutrition portfolio update: Micronutrient suspension systems for dairy alternatives. Cargill Technical Release.
- [10] Federal Statistical Office (Destatis). (2025, September 10). Demographic aging and senior population share in Germany: 2025 microcensus evaluation. Statistisches Bundesamt Demographic Bulletin, 18-34.
- [11] National Institute of Health and Medical Research (INSERM). (2025, July 19). Geriatric fracture prevention protocols and combined mineral adherence in French care cohorts. INSERM Clinical Nutrition Review, 44(4), 112-128.
- [12] Centers for Disease Control and Prevention. (2025, October 15). Osteoporosis surveillance report: Prevalence of low bone mass among adults aged 50 and older. CDC National Center for Health Statistics FastStats.
- [13] Swiss Federal Food Safety and Veterinary Office. (2025, August 25). Micronutrient intake thresholds and cofactor labeling standards for food supplements in Switzerland. Swiss Federal Health Bulletin, 2025-08.
- [14] Therapeutic Goods Administration. (2025, November 18). Australian regulatory guidelines for complementary medicines: Listed mineral stability and quality standards. Australian Government Department of Health and Aged Care Guidance.
- [15] Brazilian Health Regulatory Agency (Anvisa). (2025, December 08). Technical framework for chelated mineral dietary supplements and pharmaceutical tablet registration. Anvisa Regulatory Assessment, 2025-12.
- [16] Archer Daniels Midland Company. (2026, March 20). Commissioning of expanded pharmaceutical-grade calcium carbonate refining unit in Illinois. ADM Commercial Operations Bulletin.
- [17] Kerry Group plc. (2026, January 25). Launch of taste-masked micronized mineral fortification premix for plant-based beverages and chewable tablets. Kerry Ingredients Portfolio Announcement.
- [18] Glanbia plc. (2025, November 12). Clinical bioavailability trial results for organic marine algae mineral complexes in bone health regimens. Glanbia Nutritionals Research Bulletin.
- [19] Ashland Inc. (2025, August 19). Expansion of European pharmaceutical excipient manufacturing capacity for direct-compression mineral tablets. Ashland Pharmaceutical Manufacturing Release.
- [20] Ingredion Incorporated. (2026, February 14). Scaling of specialty suspension starch excipients for mineral-fortified functional beverages. Ingredion Technical Application Note.
- [21] Tate & Lyle PLC. (2025, June 22). Clean-label stabilization systems for calcium-fortified dairy alternatives and nutritional drinks. Tate & Lyle Global Food Technology Report.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the calcium supplements market in 2026 and what is forecast for 2036?
- Which clinical and demographic drivers support demand for calcium supplements?
- Why does Fine Powder & Micronized Crystals lead the form / physical state category?
- Why does conventional farm source lead the raw source category globally?
- How do growth rates differ across Germany, France, USA, and Switzerland?
- Which leading companies supply relevant calcium supplement categories today?
- What limits adoption or patient compliance in the calcium supplements market?
- What should pharmaceutical buyers evaluate before procuring a mineral supplement line?
Frequently Asked Questions
How big is the calcium supplements market in 2026, and what is forecast for 2036?
The global calcium supplements market is estimated to reach USD 4.5 billion in 2026. Valuation is projected to expand further and reach USD 7.7 billion by 2036, supported by geriatric bone density management.
What is the CAGR for the calcium supplements market from 2026 to 2036?
As per FMI, the calcium supplements market is projected to grow at a 5.5% CAGR from 2026 to 2036. Expansion is underpinned by preventive osteoporosis screening and commercial beverage fortification.
Which form segment leads the calcium supplements market in 2026?
Fine Powder & Micronized Crystals is projected to hold 46.9% of form / physical state demand in 2026. The segment benefits from uniform particle dispersion and lower die-wall friction on high-speed rotary tableting lines.
Which raw source segment holds the largest share in 2026?
Conventional farm source is estimated to account for 38.6% of source / nature revenue in 2026. Demand is supported by high elemental mineral concentration and established limestone refining capacity.
Which country has a notable growth outlook during the assessment period?
FMI finds that Germany is projected to expand at a 6.7% CAGR between 2026 and 2036. Growth is reinforced by a large senior demographic and pharmacist-guided preventive bone supplementation.
Who are the key players active in the calcium supplements market?
Notable companies include Archer Daniels Midland Company (ADM), Cargill, Incorporated, Bunge Global SA, Kerry Group plc, Ingredion Incorporated, Tate & Lyle PLC, Glanbia plc, and Ashland Inc. These suppliers focus on heavy-metal purification, micronized particle engineering, and organic chelated mineral formats.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form / Physical State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form / Physical State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form / Physical State, 2026 to 2036
- Fine Powder & Micronized Crystals
- Standardized Granules & Pellets
- Liquid Extract & Tincture
- Y-o-Y Growth Trend Analysis By Form / Physical State, 2021 to 2025
- Absolute $ Opportunity Analysis By Form / Physical State, 2026 to 2036
- Global Market Analysis and Forecast, By Source / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source / Nature, 2026 to 2036
- Conventional Farm Source
- Certified Organic & Non-GMO
- Fermentation / Bio-Synthesized
- Y-o-Y Growth Trend Analysis By Source / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Source / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Application Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application Sector, 2026 to 2036
- Dietary Supplements & Nutraceuticals
- Functional Food & Beverages
- Cosmetics & Topical Personal Care
- Animal Nutrition
- Y-o-Y Growth Trend Analysis By Application Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By Application Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- B2B Direct Industrial Food Manufacturers
- Retail Packaged Health Stores
- Online DTC Brands
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Nordics
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Israel
- Turkiye
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form / Physical State
- By Source / Nature
- By Application Sector
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Archer Daniels Midland Company (ADM)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill, Incorporated
- Bunge Global SA
- Kerry Group plc
- Ingredion Incorporated
- Tate & Lyle PLC
- Glanbia plc
- Ashland Inc.
- Archer Daniels Midland Company (ADM)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


