

- Market Size (2026)
- USD 416.8 Mn
- Forecast (2036)
- USD 1249.0 Mn
- CAGR (2026 to 2036)
- 11.6%
How big is Chocolate Chips & Chunks Market in 2026?
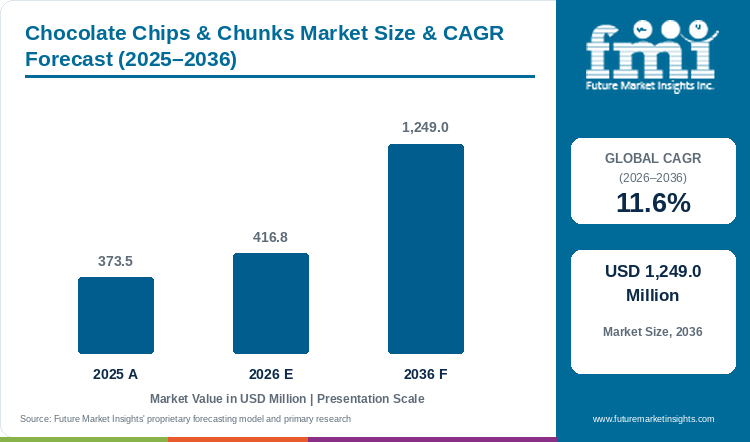
Accounting for USD 373.5 million in 2025 and rising to USD 416.8 million in 2026, the chocolate chips & chunks market is projected to expand to USD 1,249.0 million by 2036, advancing at a CAGR of 11.6%.
Chip supply just went local in two continents at once, and bakery buyers now award contracts against freight resilience before cocoa spread. Irca commissioned its St. Louis chocolate facility in February 2025 for domestic US chip and chunk production [5], while Barry Callebaut opened a USD 104 million Brantford plant in November 2025 and committed EUR 375 million across its Belgian sites [9] [10]. The global chocolate chips & chunks market was valued at USD 373.5 million in 2025 and is estimated to reach USD 832.2 million in 2026. The market is projected to reach USD 1,249.0 million by 2036, expanding at a compound annual growth rate (CAGR) of 11.6% between 2026 and 2036. Dark formats are projected to capture 38.0% of 2026 type demand, as higher non-fat cocoa solids deliver flavor intensity and heat resilience in oven conditions milk coatings cannot survive [3]. That performance edge runs ahead of the industrial chocolate market at 6.1% CAGR, since broad chocolate demand follows confectionery appetites while baking chips follow cocoa-cost hedging and clean-label cookie reformulation together [6]. Corporate moves keep compounding, with Puratos pairing Belcolade chocolate and patisserie research behind its March 2026 Dawn Foods agreement to weld inclusion supply to North American bakery distribution [8]. Cookie and quick-bread manufacturers buy coverage from chip makers who hold both domestic roasting capacity and cocoa futures discipline, and that resilience pricing sets the category through 2036.
Key Market Trends & Insights
- By product type: The Dark segment is projected to capture 38.0% of the product type segment in 2026 because higher non-fat cocoa solids deliver strong flavor and visual contrast.
- By form: The Powder / Dry segment is estimated to command 48.0% of the form segment in 2026 because dry-metered chips feed directly through automated gravimetric hoppers.
- By application: The Bread & Rolls segment is expected to concentrate 40.0% of the application segment in 2026 because high-speed brioche and sweet-roll lines run continuous shifts.
- By claim: The Conventional segment is forecast to generate 54.0% of the claim segment in 2026 owing to cost-effective dextrose and lecithin formulation latitude.
- By sales channel: The Direct to Industrial Bakeries segment is anticipated to account for 53.0% of the sales channel segment in 2026 through plant-validated particle and melt specifications.
Regional Highlights
- Top national expansion: The UAE is projected to lead evaluated national markets at a 12.8% CAGR through 2036 under strict food-import registration and hotel patisserie expansion.
- Broader country progression: Saudi Arabia is expected to expand at a 12.4% CAGR ahead of South Korea at 12.1% and the USA at 11.8%, while Japan is forecast to advance at a 10.5% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Chocolate Chips & Chunks Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 373.5 million |
| Estimated Market Size in 2026 | USD 416.8 million |
| Projected Market Size by 2036 | USD 1,249.0 million |
| CAGR, 2026 to 2036 | 11.6% |
| Incremental Market Value, 2026 to 2036 | USD 832.2 million |
Industrial cookie and brioche plants cannot tolerate chocolate pieces that fracture in pneumatic conveyors or melt into indistinct smears during oven expansion. Formulators control Casson yield stress by adjusting particle refinement between 20 and 35 microns and replacing a fraction of sucrose with dextrose so drops hold their profile through baking. In August 2026, lipid-structuring trials published in Food Chemistry demonstrated that blending 10% to 20% mango kernel fat stearin and soybean oil structured fat with cocoa butter raised dark-chocolate solid fat content at 35 degrees Celsius up to 30.03% and lifted melting completion temperatures to 49.50 degrees Celsius [2]. Bakery procurement teams pair these heat-stable chunk specifications with cocoa forward contracts to stabilize recipe margins.
Chip-and-Chunk Tonnage and Piece-Count Sizing
Table 2: Tonnage and Piece-Count Sizing for the Chocolate Chips & Chunks Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 373.5 | 416.8 | 1,249.0 |
| Qualifying chip & chunk volume (thousand metric tons) | 68.0 to 75.0 | 74.0 to 82.0 | 195.0 to 218.0 |
| Standard piece-count grade (pieces per kilogram) | 2,200 to 22,000 | 2,200 to 22,000 | 2,200 to 25,000 |
| Average industrial contract price per kilogram (USD) | 5.1 to 5.6 | 5.2 to 5.8 | 5.8 to 6.4 |
Operational note: Piece-count grades correspond to industrial 1,000-count (approx. 2,200 pieces/kg) through 10,000-count (approx. 22,000 pieces/kg) baking chips and rotary-cut chunks dosed at 6% to 18% of dough weight.
Controlling polymorphic beta-V crystallization during cooling-tunnel deposition prevents fat bloom when packaged baked goods move through warm warehouse chains. Solid-state carbon-13 NMR spectroscopy studies published in Food Chemistry in September 2026 confirmed that 40-degree-Celsius thermal pretreatment accelerates direct triclinic beta-crystal formation in dark and milk chocolates [3], guiding baking chocolate tempering lines.
Per Capita & Industrial Bakery Account Sizing
Table 3: Per Capita and Account Spending Indicators for the Chocolate Chips & Chunks Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per 1,000 people (USD) | 45.5 | 50.2 | 138.8 |
| Annual chip & chunk spend per qualified bakery plant (USD thousand) | 19.5 to 22.0 | 21.5 to 24.2 | 58.0 to 66.0 |
| Direct multi-quarter plant contract share (%) | 51.5% to 53.5% | 52.0% to 54.0% | 56.5% to 59.5% |
Table 4: Bakery Account & Channel Spending Indicators for the Chocolate Chips & Chunks Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 416.8 million | 2026 global market value baseline |
| Qualified industrial & commercial bakery accounts | 18,200 plants & commissaries | Global commercial sweet-bakery manufacturing base |
| Market spend per bakery account | USD 22,901.1 | Annualized B2B chip & chunk procurement |
| Direct to industrial bakeries value, 2026 | USD 220.9 million | 53.0% sales-channel segment allocation |
Particle size refinement and fat percentage govern how molten chocolate droplets behave during depositor cutoff and subsequent oven baking. Procurement teams benchmark real-chocolate chunk specifications against compound chocolate drops and couverture batons to protect visible piece counts per cookie.
Analyst Perspective
"Industrial bakeries do not buy chocolate chips and chunks on spot cocoa price alone; they qualify suppliers on piece-count uniformity and non-smearing mixer durability with oven shape retention. Manufacturers that pair domestic deposit-line capacity with verified EUDR and allergen documentation secure recurring plant volume."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the chocolate chips & chunks market segmented?
The chocolate chips & chunks market is segmented by product type, form, application, claim, and sales channel. In 2026, Dark is projected at 38.0%, Powder / Dry at 48.0%, Bread & Rolls at 40.0%, Conventional at 54.0%, and Direct to Industrial Bakeries at 53.0%.
By product type: Dark, Milk, White & Blond, and Sugar-Free & Specialty.
By form: Powder / Dry, Liquid, Paste / Semi-Solid, and Granules / Pieces.
By application: Bread & Rolls, Cakes & Muffins, Biscuits & Cookies, Viennoiserie & Pastry, and Other Bakery & Snacks.
By claim: Conventional, Clean Label, Organic, and Non-GMO / Identity Preserved.
By sales channel: Direct to Industrial Bakeries, Ingredient Distributors, Foodservice & Artisan Supply, and Online B2B.
Why does Dark anchor the product type segment?
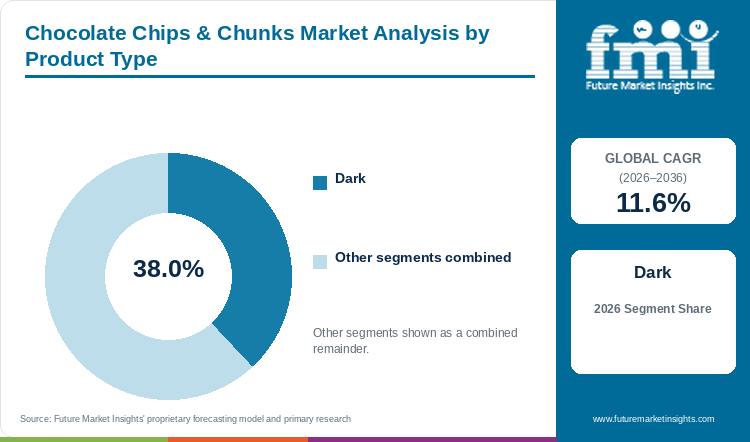
Dark chocolate chips and chunks are projected to capture 38.0% of the product type segment in 2026, supported by lower carbon footprint and higher thermal yield value.
Table 5: Product Type Share for the Chocolate Chips & Chunks Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Dark | 38.0% |
| Other Segments Combined | 62.0%* |
| Total | 100.0% |
*Note: Remaining product type subsegments (Milk, White & Blond, and Sugar-Free & Specialty) sum to 100.0% of 2026 chocolate chips & chunks market value.
Table 6: Product Type Leadership and Market Growth for the Chocolate Chips & Chunks Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 11.6% |
| Leading Segment | Dark |
Dark chocolate chunks containing 45% to 70% cocoa solids provide high visual contrast against golden bread and cookie doughs while avoiding the lower scorching threshold of milk-powder-heavy white or milk drops. Eliminating whole milk powder also lowers raw-material carbon intensity and simplifies dairy-free line scheduling across bake-stable chocolate fillings and inclusion plants.
- Dark is projected to account for 38.0% of the product type segment in 2026 because high cocoa-solid particulates retain sharp edge definition and roast aroma through high-heat baking.
- Factory-level life cycle assessments published in Science of the Total Environment in February 2026 across four major chocolate types confirmed that dark chocolate recorded the lowest global warming potential at 2.32 kg CO2-eq per kilogram versus 4.06 kg CO2-eq per kilogram for white chocolate [4].
How does Powder / Dry support the form segment?
Powder / Dry handling formats are estimated to secure 48.0% of the form segment in 2026, driven by ambient-to-cool dry hopper feeding and zero-pump sanitation.
Within the contracting taxonomy of this market, the Powder / Dry classification covers free-flowing solid chips and chunks metered through dry gravimetric hoppers rather than standalone cocoa powders or bulk liquid tanks. Dry-dosed inclusions let plant engineers run rapid SKU changeovers with bakery mixes without flushing heated chocolate pipelines.
- Powder / Dry is estimated to command 48.0% of the form segment in 2026 because dry-metered solid inclusions prevent pipeline blockages and simplify multi-shift allergen sanitation.
- In February 2025, Irca Group commissioned its operational St. Louis, Missouri chocolate facility and announced domestic U.S. production of baking chips and chunks with its RENO X chocolate range [5].
What makes Bread & Rolls the largest application segment?
Bread & Rolls are expected to command 40.0% of the application segment in 2026, reflecting continuous industrial runs of chocolate-chip brioche and sweet rolls.
Packaged chocolate-chip brioche loaves and sweet breakfast rolls run on continuous multi-ton tunnel ovens that generate predictable weekly reorders for calibrated chips and chunks. Pieces must balance mass and aspect ratio so chunks stay suspended in fermented doughs without sinking or puncturing gas cells stabilized by bread improvers.
- Bread & Rolls are expected to hold 40.0% of the application segment in 2026 because year-round retail brioche and sweet-roll programs consume bulk tote deliveries.
- Rheological evaluations published in Food Chemistry in April 2026 across dark and milk chocolate matrices (26% to 36% fat and 19 to 40 micron particle sizes) proved that roller-refined bimodal particle distributions reduce plastic viscosity and yield stress during processing [6].
Why does Conventional remain central within the claim segment?
Conventional specifications are forecast to generate 54.0% of the claim segment in 2026, owing to unrestricted lecithin and dextrose formulation latitude.
Standardizing depositor cutoff weight and bake-stability across seasonal cocoa harvests requires precise soy or sunflower lecithin dosing and dextrose-to-sucrose balancing. Conventional procurement avoids the segregated silo fees and organic certification audits required by specialty-claim programs.
- Conventional options are forecast to account for 54.0% of the claim segment in 2026 because standard emulsifier and sugar systems minimize per-kilogram conversion cost.
- Genome-resolved metagenomic fermentation trials published in Nature Microbiology in September 2025 established that defined bacterial and fungal starter consortia reproduce fine-flavor chocolate attributes consistently across variable farm bean lots [7].
Why are Direct to Industrial Bakeries contracts the largest sales channel segment?
Direct to Industrial Bakeries is anticipated to account for 53.0% of the sales channel segment in 2026, reinforced by plant-specific thermal qualification and forward volume contracting.
Large commercial bakeries purchase chips and chunks directly from chocolate processors under forward volume agreements that specify piece count per kilogram and Casson viscosity with allergen cross-contact limits. Direct plant relationships allow joint trials at supplier innovation centers before locking in annual bills of materials.
- Direct to Industrial Bakeries is anticipated to capture 53.0% of the sales channel segment in 2026 because multi-plant bakeries require custom particle-count tolerances and direct cocoa-hedging terms.
- In March 2026, Puratos and Dawn Foods announced a definitive agreement for Puratos to acquire Dawn Foods, combining Puratos Belcolade chocolate and patisserie R&D with Dawn Foods industrial bakery distribution in North America [8].
What are the drivers, restraints, and opportunities in the chocolate chips & chunks market?
In the chocolate chips & chunks market, automated sweet-bakery dosing and domestic capacity additions propel demand whereas cocoa price volatility and EUDR / allergen compliance restrain switching and structured-fat or cultured-cocoa innovations unlock formulation opportunities.
- Driver: High-speed brioche and cookie lines require calibrated chocolate chips and chunks that deliver identical piece counts and visual contrast across shifts.
- Restraint: Cocoa bean price swings and EU Deforestation Regulation traceability mandates combine with FDA allergen-labeling rules to raise supplier-switching barriers.
- Opportunity: Regional baking-chip manufacturing and shea or mango structured-fat extenders with cultured-cocoa professional chocolates reduce supply friction for industrial bakers.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Industrial bakeries rely on geometry-locked chocolate chips and rotary-cut chunks to guarantee identical piece visibility and cocoa release across millions of packaged loaves and cookies. Once a 4,000-count dark chip passes pneumatic conveyor attrition and tunnel-oven bake tests, plant managers lock the SKU into automated bill-of-materials replenishment with sugar and chocolate decorations. To serve bakery and food manufacturers in North America with shorter lead times, Barry Callebaut opened its third Canadian chocolate factory in Brantford, Ontario in November 2025 following a USD 104 million capital investment [9]. also Barry Callebaut committed EUR 250 million to modernize its Wieze chocolate factory in Belgium and EUR 125 million to its Halle plant in February 2026 [10]. Dedicated regional molding lines insulate contract bakeries from transoceanic container delays.
Risk Assessment of the Chocolate Chips & Chunks Market: Operational and Formulation Friction
Raw-material cost pressure and tightening statutory compliance rules create substantial friction whenever a bakery attempts to reformulate or switch inclusion vendors. In March 2026, University of Tübingen researchers reported in Waste Management that high-carbohydrate dried-bakery waste streams in Germany require specialized chain-elongation bioreactors when off-spec baked goods fail retail quality checks [11]. On the regulatory front, the U.S. Food and Drug Administration issued Edition 5 of its Food Allergen Labeling Guidance in January 2025 covering milk and soy cross-contact [12], while the European Commission adopted updated product scope and IT rules for the EU Deforestation Regulation (EUDR) in July 2026 ahead of the 30 December 2026 compliance deadline [13]. When R&D teams evaluate cocoa butter extenders such as shea butter or palm oil to cut costs, April 2026 Food Chemistry mixture-design trials showed that shea butter elevates Casson viscosity and alters linalool aroma release with food emulsifiers [14]. Every formulation change consequently requires full plant re-qualification.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Chocolate processors are unlocking new margin tiers by combining regional application lines with cocoa-extender and cultured-cocoa innovations that stabilize long-term customer supply. In September 2025, Dawn Foods expanded its Royal Steensma pastry and inclusion product line across North America to simplify turn-key sweet bakery production [15]. In February 2026, Barry Callebaut opened its Global Innovation Center in Singapore housing its first Artificial Intelligence Center of Excellence and a Cacao Coatings Center of Excellence [16], while Puratos announced in February 2026 that it will launch the first professional chocolate containing California Cultured cell-cultured cocoa in the USA by late 2026 [17]. Pairing local pilot-line verification with cell-cultured cocoa butter and cacao and traceable conventional chunks lets suppliers win multi-year bakery contracts on risk reduction rather than spot price alone.
Chocolate Chips & Chunks Market by Country (2026 to 2036)
As per FMI, the UAE is projected to lead chocolate chips & chunks expansion across evaluated countries at a 12.8% CAGR through 2036, whereas Japan is forecast to advance at a 10.5% CAGR. National growth variation reflects the contrast between rapidly expanding Gulf foodservice and bakery inspection ecosystems and mature confectionery-bakery plants in Western Europe and Japan.
Table 7: Country CAGR and Primary Growth Levers for the Chocolate Chips & Chunks Market (CAGR percentage and operational drivers), 2026 to 2036
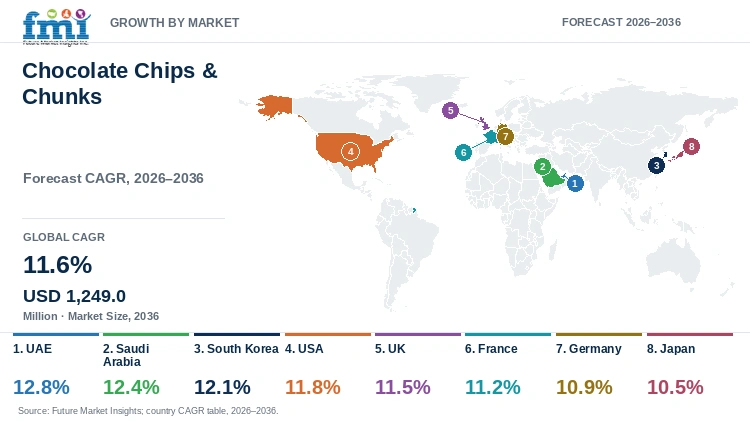
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| UAE | 12.8% | Digital port food-registration throughput and heat-stable hospitality patisserie demand |
| Saudi Arabia | 12.4% | SFDA-inspected domestic bakery factory expansion and modern-trade sweet-goods growth |
| South Korea | 12.1% | Standardized processed-food manufacturing scale and premium bakery-café cookie launches |
| USA | 11.8% | High-capacity commercial bread and cookie shipments supported by new domestic chip lines |
| UK | 11.5% | Record food-import reliance driving multi-site retail bakery contingency contracting |
| France | 11.2% | Artisan boulangerie-pâtisserie outlets plus industrial viennoiserie and INRAE research |
| Germany | 10.9% | Bakery-waste reduction discipline and EUDR-traceable industrial baking chunk contracts |
| Japan | 10.5% | Precision particle-size tolerances and controlled polymorphic stability in packaged bakes |
Source: Future Market Insights analysis
UAE Chocolate Chips & Chunks Market Outlook (2026 to 2036)
The UAE is projected to expand at a leading 12.8% CAGR from 2026 to 2036 across hotel patisseries and industrial bakeries. Unlike temperate European markets, bakery buyers in the UAE require chocolate chips and chunks engineered with higher melting completion temperatures to resist fat bloom during warm distribution. In July 2025, Dubai Municipality reported conducting 34,700 food-establishment inspections and clearing 173,775 port food shipments totaling 4.9 million tons during the first half of 2025 while registering 77,700 new food products across 2,336 newly opened food establishments [18]. Suppliers that pre-register Arabic-compliant labels and stock heat-stable dark chunks in Jebel Ali free-zone cold stores capture rapid reorder velocity.
Key takeaway: In the UAE, rapid food-establishment openings and digital port registration are projected to reward suppliers of bloom-resistant baking chips and chunks.
Saudi Arabia Chocolate Chips & Chunks Market Outlook (2026 to 2036)
Demand in the Saudi Arabia chocolate chips & chunks market is expected to rise at a 12.4% CAGR over the 2026 to 2036 assessment window. Expanding domestic bread and cookie factories across Riyadh and Dammam are shifting procurement from small spot-import cartons toward palletized industrial tote contracts with multi-quarter delivery schedules. In January 2026, the Saudi Food and Drug Authority reported an 18% increase in licensed factories and warehouses during 2025 to reach 7,610 facilities with 55,616 inspection visits across the Kingdom [19]. Because high-temperature summer inland freight exposes bulk chocolate inclusions to severe thermal cycling, international producers must partner with SFDA-licensed cold-chain distributors to pass plant qualification.
Key takeaway: In Saudi Arabia, SFDA factory-inspection standards and domestic sweet-bakery scaling are expected to favor traceable and temperature-controlled chip supply.
South Korea Chocolate Chips & Chunks Market Outlook (2026 to 2036)
South Korea's highly consolidated food-processing and franchise bakery-café sector demands tight lot-to-lot granulometry and rapid new-product turnaround across Seoul and Gyeonggi province. In June 2026, clinical and food-science investigators from Myongji University and U.S. partner institutes published crossover trial data in Clinical Nutrition ESPEN evaluating daily intake of 43 grams of dark chocolate and 18 grams of cocoa [20]. Valuation in the South Korea chocolate chips & chunks market is forecast to progress at a 12.1% CAGR between 2026 and 2036, driven by commercial bakeries expanding dark-chocolate cookie and filled-bun lines. Elevated imported cocoa duties and strict allergen declarations in South Korea still require foreign suppliers to provide localized technical service.
Key takeaway: In South Korea, franchise bakery-café cookie innovation and dark-chocolate formulation demand are forecast to drive precision-graded chunk imports.
USA Chocolate Chips & Chunks Market Outlook (2026 to 2036)
Large-scale automated cookie and sweet-roll plants make the USA the anchor market for baking-chip tonnage in North America. In February 2025, Irca Group announced that its new chocolate manufacturing facility near St. Louis, Missouri was operational and scheduled domestic production of baking chips and chunks with its RENO X range [5]. The USA chocolate chips & chunks market value is anticipated to climb at an 11.8% CAGR from 2026 to 2036, reinforced by Barry Callebaut's USD 104 million capacity expansion in Brantford in November 2025 [9]. Strict plant audits under the January 2025 FDA Edition 5 allergen labeling guidance for milk and soy lecithin govern multi-plant vendor onboarding [12].
Key takeaway: In the USA, new domestic chocolate-chip molding capacity and automated bakery line scale are anticipated to sustain multi-year supply contracts.
UK Chocolate Chips & Chunks Market Outlook (2026 to 2036)
Heavy reliance on cross-Channel food imports and concentrated supermarket private-label bakery specifications define procurement strategy across the UK. In March 2026, the Food and Drink Federation reported in its 2025 Trade Snapshot that UK food and drink imports reached a record GBP 66.9 billion in 2025 (up 5.9% year over year) while exports reached GBP 25.6 billion [21]. To insulate national grocery bakery programs from border friction and test cocoa-optimized recipes on working equipment, Dawn Foods expanded its Royal Steensma pastry and inclusion portfolio in September 2025 [15]. so the UK chocolate chips & chunks market is estimated to advance at an 11.5% CAGR through 2036 across commercial bakeries.
Key takeaway: In the UK, record food-import dependence and turnkey pastry inclusion portfolios are estimated to drive multi-route qualification of bake-stable chocolate chunks.
France Chocolate Chips & Chunks Market Outlook (2026 to 2036)
France pairs Europe's densest network of artisan boulangerie-pâtisserie shops with export-scale industrial viennoiserie plants, creating dual demand for high-cocoa pain au chocolat batons and rotary-cut dark chunks. In January 2026, investigators at Université Clermont Auvergne and INRAE in France published bread-digestion metabolomics trials in the Journal of Proteome Research comparing artisan and industrial baking processes [22]. Sensory-chronology trials conducted by CIRAD and INRAE in Montpellier and Dijon published in Food Research International in August 2026 demonstrated how cocoa-butter extender ratios reshape temporal aroma release and melting perception in chocolate [23]. Supported by strict European pure-cocoa-butter composition rules, the France chocolate chips & chunks market is projected to grow at an 11.2% CAGR from 2026 to 2036.
Key takeaway: In France, craft boulangeries and strict pure-cocoa-butter viennoiserie standards are projected to sustain demand for dark chocolate chunks and batons.
Germany Chocolate Chips & Chunks Market Outlook (2026 to 2036)
Bakery-waste reduction pressures and upcoming deforestation due-diligence rules dominate industrial bakery procurement reviews across Germany. In March 2026, University of Tübingen researchers reported in Waste Management that high-carbohydrate dried-bakery waste streams in Germany require specialized valorization [11], while the European Commission finalized updated EUDR product-scope and information-system tools in July 2026 ahead of the December 2026 compliance gate [13]. Industrial bakers in Germany are responding by locking in traceable Cocoa Horizons or Cacao-Trace dark chunks and optimizing piece aspect ratios to preserve top-crust chocolate visibility at lower weight dosing. The Germany chocolate chips & chunks market is slated to progress at a 10.9% CAGR through 2036.
Key takeaway: In Germany, bakery-waste controls and December 2026 EUDR traceability mandates are slated to steer buyers toward certified and dosage-efficient chunks.
Japan Chocolate Chips & Chunks Market Outlook (2026 to 2036)
Japan is forecast to record a 10.5% CAGR between 2026 and 2036, representing the most technically demanding quality environment among the eight evaluated countries. Industrial bakeries and convenience-store dessert suppliers in Japan enforce narrow tolerances on chip diameter and clean snap-to-melt transitions in packaged melonpan and soft cookies across metropolitan retail chains. In February 2026, Barry Callebaut opened its Callebaut Global Innovation Center and pilot lab in Singapore to accelerate AI-assisted flavor design and regional AMEA bakery co-creation [16]. Once an ingredient supplier's calibrated particle specification passes rigorous shelf-life and sensory qualification trials in Japan, multi-year commercial procurement loyalty remains exceptionally high across national packaged bakery and convenience-store groups.
Key takeaway: In Japan, strict convenience-store appearance standards and regional AMEA R&D co-creation are forecast to anchor long-term contracts for precision-molded chips.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the chocolate chips & chunks market?
Barry Callebaut, Puratos, Dawn Foods, Zeelandia, CSM Ingredients, Bakels, AGRANA, Zentis, Fabbri 1905, and Irca Group are the notable companies in the chocolate chips & chunks market.
FMI analysis indicates that competition is structured across three operational tiers. Barry Callebaut and Puratos (via Belcolade) with Bakels and Irca Group manufacture documented chocolate chips and particulate inclusions supported by industrial molding and tempering assets. Dawn Foods and Zeelandia with CSM Ingredients compete through integrated bakery distribution and application centers, whereas AGRANA and Zentis with Fabbri 1905 supply chocolate-containing splits and dessert inclusions.
- Chocolate and Particulate Inclusion Specialists: Barry Callebaut and Puratos with Bakels and Irca Group operate dedicated chocolate refining and chunk-cutting lines for industrial bakeries.
- Bakery Ingredient and Application-Solution Providers: Dawn Foods and Zeelandia with CSM Ingredients connect bakery customers with qualified inclusions and multi-region distribution.
- Textured Preparations and Dessert Inclusion Suppliers: AGRANA and Zentis with Fabbri 1905 formulate chocolate-piece preparations and crunchy inclusions across bakery and adjacent dessert channels.
Competitive Benchmarking: Chocolate Chips & Chunks Market
Table 8: Competitive Benchmarking for the Chocolate Chips & Chunks Market (qualitative capability ratings), 2026
| Company | Chips & Chunks Portfolio | Bakery Technical Support | Claim & Traceability Options | Geographic Reach |
|---|---|---|---|---|
| Barry Callebaut | High | High | High | High |
| Puratos | High | High | High | High |
| Dawn Foods | Medium | High | Medium | High |
| Zeelandia | Medium | High | Medium | Medium |
| CSM Ingredients | High | High | Medium | High |
| Bakels | Medium | High | Medium | High |
| AGRANA | Medium | Medium | Medium | High |
| Zentis | Medium | Medium | Medium | Medium |
| Fabbri 1905 | Medium | Medium | Medium | Medium |
| Irca Group | High | High | Medium | High |
Scoring basis: Capability tiers evaluate published bake-stable chocolate chip and chunk specifications (1,000-count to 10,000-count drops and rotary-cut chunks) with pilot test-bakery infrastructure. Traceability and geographic ratings reflect EUDR and allergen documentation (Cocoa Horizons and Cacao-Trace) and multi-region manufacturing reach.
Key Developments in the Chocolate Chips & Chunks Market
- In February 2025, Irca Group commissioned its operational St. Louis, Missouri chocolate facility and announced domestic U.S. production of baking chips and chunks with its RENO X chocolate range [5].
- In March 2026, Puratos and Dawn Foods announced a definitive agreement for Puratos to acquire Dawn Foods, pairing Puratos Belcolade chocolate and patisserie R&D with Dawn Foods industrial bakery distribution in North America [8].
- In November 2025 and February 2026, Barry Callebaut opened its USD 104 million Brantford chocolate factory in Ontario [9] while committing EUR 375 million across its Wieze and Halle plants in Belgium and opening its Singapore Global Innovation Center [10] [16].
Key Players in the Chocolate Chips & Chunks Market
Chocolate and Particulate Inclusion Specialists
- Barry Callebaut
- Puratos
- Bakels
- Irca Group
Bakery Ingredient and Application-Solution Providers
- Dawn Foods
- Zeelandia
- CSM Ingredients
Textured Preparations and Dessert Inclusion Suppliers
- AGRANA
- Zentis
- Fabbri 1905
Chocolate Chips & Chunks Market - Report Scope
Table 9: Report Scope for the Chocolate Chips & Chunks Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Form; Application; Claim; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Includes B2B supplier value from chocolate chips and chunks sold as discrete bake-stable ingredient particulates into commercial bakery and snack manufacturing. Category Scope Note: Excludes finished retail bakery product value, standalone cocoa powder, bulk liquid couverture not formed into chips or chunks, homogeneous spreads or ganaches, and cocoa-free sunflower-seed alternatives. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UAE, Saudi Arabia, South Korea, USA, UK, France, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | Barry Callebaut, Puratos, Dawn Foods, Zeelandia, CSM Ingredients, Bakels, AGRANA, Zentis, Fabbri 1905, Irca Group |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Chocolate Chips & Chunks Market - Research Methodology
Table 10: Research Methodology for the Chocolate Chips & Chunks Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with industrial bakery QA managers, chocolate depositing engineers, cocoa procurement directors, and B2B ingredient distributors to validate piece-count grades (2,200 to 22,000 pieces/kg), oven-smear tolerances, and contract pricing. |
| Secondary Research | Audit of International Cocoa Organization (ICCO) quarterly bulletins, FDA Edition 5 allergen labeling guidance, European Commission EUDR implementation acts, national statistical releases (FDF, Dubai Municipality, SFDA), and PubMed chocolate-rheology studies. |
| Market Sizing and Forecasting | Top-down vertical disaggregation from the parent Bakery Inclusions Market (USD 915.6 million in 2026) and Industrial Chocolate Market reconciled against bottom-up chip and chunk tonnage from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight industrial bread and cookie shipment scale, licensed factory counts, port food-inspection throughput, and wholesale cocoa price indices across eight evaluated countries. |
| Operational Benchmark Traceability | Tonnage, piece-count grades, and per-account spending indicators in Tables 2, 3, and 4 trace to Food Chemistry and Science of the Total Environment chocolate studies, ICCO grindings logs, and supplier technical specification sheets. |
| Data Triangulation and Validation | Valuation estimates are restricted strictly to qualifying chocolate chips and chunks, excluding bulk liquid chocolate, standalone cocoa powders, smooth ganaches, and non-cocoa sunflower alternatives (such as ChoViva) to prevent double counting. |
Chocolate Chips & Chunks Market by Segments
Chocolate Chips & Chunks Market segmented by Product Type:
- Dark
- Milk
- White & Blond
- Sugar-Free & Specialty
Chocolate Chips & Chunks Market segmented by Form:
- Powder / Dry
- Liquid
- Paste / Semi-Solid
- Granules / Pieces
Chocolate Chips & Chunks Market segmented by Application:
- Bread & Rolls
- Cakes & Muffins
- Biscuits & Cookies
- Viennoiserie & Pastry
- Other Bakery & Snacks
Chocolate Chips & Chunks Market segmented by Claim:
- Conventional
- Clean Label
- Organic
- Non-GMO / Identity Preserved
Chocolate Chips & Chunks Market segmented by Sales Channel:
- Direct to Industrial Bakeries
- Ingredient Distributors
- Foodservice & Artisan Supply
- Online B2B
Chocolate Chips & Chunks Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Cocoa Organization (ICCO). (2025, November 28). November 2025 Quarterly Bulletin of Cocoa Statistics. ICCO Volume LI, Issue No. 4, Abidjan.
- [2] Aondoakaa, I. P., Martini, S., & Akoh, C. C. (2026, August 27). Development of heat-stable dark chocolate using ternary blends of cocoa butter, mango kernel fat stearin, and soybean oil-based structured fat. Food Chemistry, 527, 150926 (PubMed PMID 42667775).
- [3] Tobias, T. J., Marinho, M. O., Santos, Y. F., Queiroz Júnior, L. H. K., & Colnago, L. A. (2026, September 25). Monitoring the crystallization process and polymorphism in cocoa-based products via solid-state 13C NMR. Food Chemistry, 530, 151235 (PubMed PMID 42801902).
- [4] Konar, N., Fidan, M., Atalar, I., Palabiyik, I., Sanli, T., Marasli, S., Gorgulu, A., Sagdic, O., & Toker, O. S. (2026, February 25). Life cycle hotspots in chocolate production: Ingredient formulation, processing technologies, and pathways toward sustainable confectionery systems. Science of the Total Environment, 1018, 181500 (PubMed PMID 41679024).
- [5] IRCA Group. (2025, February 18). Crafted in Italy, Produced in the USA: IRCA Group Strengthens Its Presence in the Americas with Investment in U.S. Factory and the Launch of Domestic RENO X Chocolate Range. IRCA Group Inside News.
- [6] Gallery, C., & Agoda-Tandjawa, G. (2026, April 1). Impact of grinding technology and particle size on rheological behavior and tribological properties of chocolate compound matrices. Food Chemistry, 507, 148244 (PubMed PMID 41650769).
- [7] Gopaulchan, D., Moore, C., Ali, N., Sukha, D., Florez González, S. L., Herrera Rocha, F. E., Yang, N., Lim, M., Dew, T. P., González Barrios, A. F., Umaharan, P., Salt, D. E., & Castrillo, G. (2025, September). A defined microbial community reproduces attributes of fine flavour chocolate fermentation. Nature Microbiology, 10(9), 2130-2152 (PubMed PMID 40825855).
- [8] Puratos Group. (2026, March 10). Puratos to Acquire Dawn Foods, Bringing Together Complementary Capabilities in Professional Bakery. Puratos Official Newsroom.
- [9] Barry Callebaut. (2025, November 13). Barry Callebaut Opens Third Canadian Chocolate Factory in Brantford, Ontario. Barry Callebaut Media News Stories.
- [10] Barry Callebaut. (2026, February 5). Barry Callebaut reinforces commitment to Wieze with detailed investment plan of € 250 million. Barry Callebaut Media News Stories.
- [11] Ntihuga, J.-N., Feldmann, C., & Angenent, L. T. [University of Tübingen, Germany]. (2026, March 13). Dried-bakery waste as a substrate for n-caproate and n-caprylate production via chain elongation. Waste Management, 216, 115454 (PubMed PMID 41830699).
- [12] U.S. Food and Drug Administration. (2025, January 6). FDA Releases Allergen, Food Safety, and Plant-Based Alternative Labeling Guidances. FDA HFP Constituent Updates.
- [13] European Commission, Directorate-General for Environment. (2026, July 13). Commission updates product scope and digital tools to support implementation of EU Deforestation Regulation. European Commission Environment News.
- [14] Molard, B., Maraval, I., Deuscher, Z., Goli, T., Boulanger, R., & Lecomte, J. (2026, April 30). Effect of palm oil and shea butter addition on chocolate rheology, aroma release and sensory perception: a mixture design of experiment approach. Food Chemistry, 509, 148561 (PubMed PMID 41740385).
- [15] Dawn Foods. (2025, September 13). Dawn Foods Expands Royal Steensma Product Line in North America With Four New Premium, Easy-to-use Products. Dawn Foods Official News & Press.
- [16] Barry Callebaut. (2026, February 10). Barry Callebaut Opens Global Innovation Center in Singapore, Pioneering the Future of Chocolate Through AI and Advanced Innovation. Barry Callebaut Media News Stories.
- [17] Puratos Group. (2026, February 24). Puratos to Launch First Professional Chocolate Product with Cultured Cocoa. Puratos Official Press Releases.
- [18] Dubai Municipality. (2025, July 30). Over 34,000 food inspections conducted in first half of 2025: Dubai Municipality conducts 34,700 food inspections in the first half of 2025, supporting rapid sector growth. Government of Dubai Media Center.
- [19] Saudi Food and Drug Authority (SFDA). (2026, January 26). SFDA Reports 18% Growth in Licensed Factories and Warehouses During 2025. SFDA Official Regulatory News.
- [20] Riley, T. M., Nagpal, R., Dawson, M. A., Hughes, D., Lee, Y., Kris-Etherton, P. M., & Berryman, C. E. (2026, June 19). Associations of almond, dark chocolate, and cocoa consumption with stool microbial diversity and composition among adults with overweight or obesity: An analysis of secondary outcomes from a 4-period crossover clinical trial. Clinical Nutrition ESPEN, 75, 103414 (PubMed PMID 42320568).
- [21] Food and Drink Federation (FDF). (2026, March 31). 2025 Trade Snapshot: UK food & drink trade report. The Food and Drink Federation Publications, London.
- [22] Zhour, H., Savary, A., & Comte, B. [Université Clermont Auvergne & INRAE, France]. (2026, January 2). Untargeted Metabolomics for Wheat Bread In Vitro Digestate Assessment. Journal of Proteome Research, 25(1), 84-98 (PubMed PMID 41359829).
- [23] Molard, B., Forestier-Chiron, N., Deuscher, Z., Troncho, T., Schlich, P., Lecomte, J., & Boulanger, R. (2026, August 9). Beyond cocoa butter: How partial substitution with cocoa butter extenders reshapes temporal dominance of sensations and aroma release in chocolate. Food Research International, 243(Pt 2), 120345 (PubMed PMID 42705721).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the chocolate chips & chunks market in 2026 and what is forecast for 2036?
- Which industrial-bakery dosing and oven-stability pressures support demand for chocolate pieces?
- Why does Dark lead the product type segment?
- What makes Powder / Dry the largest reported form segment?
- How do forecast growth rates compare across the UAE and Saudi Arabia versus the USA?
- Which evaluated companies manufacture chocolate chips and chunks versus broader bakery systems?
- What cocoa-volatility and allergen barriers delay qualification and supplier switching?
- Which particle-count and EUDR criteria should buyers verify before purchasing?
Frequently Asked Questions
How big is the chocolate chips & chunks market in 2026 and what is forecast for 2036?
According to FMI, the chocolate chips & chunks market valuation reached USD 416.8 million in 2026 from USD 373.5 million in 2025. The market value is forecast to hit USD 1,249.0 million by 2036, covering qualifying B2B inclusion value rather than finished retail baked goods.
What is the CAGR for the chocolate chips & chunks market from 2026 to 2036?
Future Market Insights projects an 11.6% CAGR between 2026 and 2036, generating USD 832.2 million in incremental market value across industrial and foodservice bakery accounts.
Which product type segment leads the chocolate chips & chunks market?
Dark is projected to capture 38.0% of the product type segment in 2026 because higher cocoa solids provide sharp visual contrast and intense roast flavor with lower carbon intensity than milk or white alternatives.
Which form segment leads the chocolate chips & chunks market?
Powder / Dry is estimated to hold 48.0% of the form segment in 2026, representing solid chips and chunks metered through dry gravimetric hoppers while excluding standalone cocoa powders.
Which country has the fastest growth outlook during the assessment period?
The UAE is projected to lead national expansion at a 12.8% CAGR through 2036, followed by Saudi Arabia at 12.4% and South Korea at 12.1% under expanding hospitality patisseries and industrial bakery investments.
Who are the key players in the market?
Barry Callebaut and Puratos with Bakels and Irca Group manufacture documented baking chips and chunks for industrial bakeries. Dawn Foods and Zeelandia with CSM Ingredients provide bakery application support, while AGRANA and Zentis with Fabbri 1905 supply textured inclusions.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Dark
- Milk
- White & Blond
- Sugar-Free & Specialty
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Powder / Dry
- Liquid
- Paste / Semi-Solid
- Granules / Pieces
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Bread & Rolls
- Cakes & Muffins
- Biscuits & Cookies
- Viennoiserie & Pastry
- Other Bakery & Snacks
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Claim, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim, 2026 to 2036
- Conventional
- Clean Label
- Organic
- Non-GMO / Identity Preserved
- Y-o-Y Growth Trend Analysis By Claim, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct to Industrial Bakeries
- Ingredient Distributors
- Foodservice & Artisan Supply
- Online B2B
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Barry Callebaut
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Puratos
- Dawn Foods
- Zeelandia
- CSM Ingredients
- Bakels
- AGRANA
- Zentis
- Fabbri 1905
- Irca Group
- Barry Callebaut
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


