

- Market Size (2026)
- USD 12.8 Bn
- Forecast (2036)
- USD 23.6 Bn
- CAGR (2026 to 2036)
- 6.3%
How big is Commercial Seaweed Market in 2026?
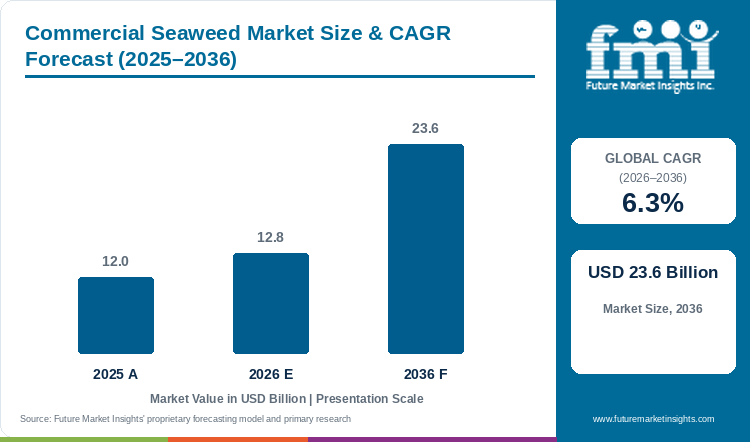
Global commercial seaweed market value is projected to rise from USD 12.0 billion during 2025 to USD 12.8 billion for 2026, advancing at an anticipated 6.3% CAGR to reach a USD 23.6 billion industry valuation by 2036.
Global trade in farmed and wild macroalgae has shifted toward higher-value food and hydrocolloid grades over the past year. During April 2026, the FAO GLOBEFISH quarterly seaweed analysis reported that world seaweed export value climbed 9.4% between January and September 2025 as average export prices rose from 3.92 dollars per kilogram to 4.48 dollars per kilogram despite a 4.4% drop in shipping volume [1]. Because food processors and coastal refiners are paying more for reliable gel-forming raw material, global commercial seaweed market size is estimated to climb from USD 12.0 billion during 2025 to USD 12.8 billion for 2026. Over the next decade, overall market valuation is forecast to reach USD 23.6 billion by 2036 at an anticipated 6.3% CAGR, which generates USD 10.8 billion in added annual market value. Within this total, Red Seaweed is projected to capture 45.7% of species valuation during 2026 because dairy and processed meat manufacturers rely on carrageenan and agar to keep textures stable. Even so, warmer tropical waters and bacterial crop bleaching still disrupt farm harvests and push formulators to evaluate seaweed-derived carrageenan alternatives in everyday recipes.
Key Market Trends & Insights
- By macroalgae species: Red Seaweed is projected to capture 45.7% of 2026 species valuation because farmed Kappaphycus and Eucheuma supply consistent carrageenan and agar gels for food plants.
- By form: Dried Flakes, Sheets & Powders are estimated to command 47.3% of 2026 form market size as coastal drying below 15% moisture protects bulk ocean shipments from mold.
- By end use: Human Food & Snacks are expected to concentrate 49.3% of 2026 culinary valuation through steady grocery demand for roasted gim sheets and wakame soups.
- By harvesting method: Rope, Net & Longline Coastal Mariculture is forecast to represent 49.1% of 2026 harvesting market share owing to low-cost line farming across sheltered bays.
- By processing grade: Food-Grade Dehydrated & Roasted is anticipated to account for 51.3% of 2026 grade market value through automated freshwater washing and optical sorting.
Regional Highlights
- Top national expansion: Indonesia is projected to lead major cultivating countries at a 7.6% CAGR through 2036 under national downstreaming policies that encourage local carrageenan refining.
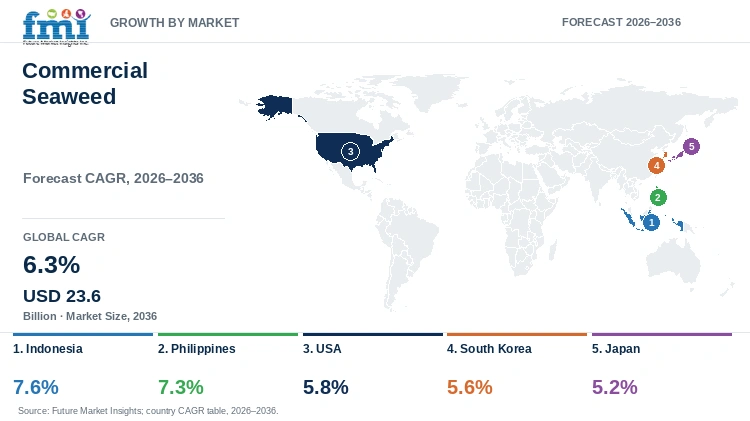
- Broader country progression: Philippine mariculture is expected to expand at 7.3% CAGR ahead of the USA at 5.8% and South Korea at 5.6%, while Japan is forecast to advance at a 5.2% yearly pace.
Market Size & Forecast
Table 1: Market Size and Forecast for the Commercial Seaweed Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 12.0 billion |
| Estimated Market Size in 2026 | USD 12.8 billion |
| Projected Market Size by 2036 | USD 23.6 billion |
| CAGR, 2026 to 2036 | 6.3% |
| Added Annual Market Value, 2026 to 2036 | USD 10.8 billion |
Food ingredient buyers and agricultural input makers face stricter marine traceability rules while wild kelp harvests fluctuate along temperate coasts. When processors depend on uncertified wild harvests, they often run into seasonal viscosity swings and unwanted arsenic or cadmium residues. During June 2026, the FAO State of World Fisheries and Aquaculture 2026 report confirmed that farmed algae output reached 38.9 million tonnes wet weight valued at USD 19.9 billion in 2024, making up 96.8% of world algae tonnage as Indonesia added 619,300 tonnes [2]. Because of this shift toward farmed supply, ingredient buyers are signing multi-year contracts for cultivated refined seaweed hydrocolloids so dairy and confectionery plants receive uniform gel strength in every batch.
Cultivated Biomass and Dry-Tonnage Sizing
Table 2: Cultivated Biomass and Dry-Equivalent Tonnage Indicators for the Commercial Seaweed Market (USD billion and million tonnes), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 12.0 | 12.8 | 23.6 |
| Commercial wet-weight harvest (million tonnes) | 39.4 to 40.8 | 40.6 to 42.1 | 56.0 to 59.5 |
| Dry-equivalent processed tonnage (million tonnes) | 4.2 to 4.5 | 4.4 to 4.7 | 6.8 to 7.4 |
| Average realized dry-tonnage value (USD per tonne) | 2,720 to 2,860 | 2,780 to 2,920 | 3,250 to 3,470 |
Operational note: Dry-equivalent tonnage benchmarks apply an 8:1 to 10:1 wet-to-dry moisture conversion across farmed red and brown seaweeds and green macroalgae entering commercial dehydration and extraction plants.
Coastal drying hubs and extraction refineries need raw seaweed dried below 18% moisture right after harvest so natural enzymes do not break down the gel fibers during barge transport. Because of this requirement, integrated processors now place solar tunnel dryers right next to coastal farm sites and supply foliar crop biostimulants as well as food-grade carrageenan powders.
Per Capita & Refinery Valuation Sizing
Table 3: Per Capita and Refinery Valuation Indicators for the Commercial Seaweed Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 1,463.4 | 1,542.2 | 2,622.2 |
| Annual valuation per commercial refinery (USD million) | 14.2 to 16.5 | 15.1 to 17.6 | 25.5 to 29.8 |
| Contracted mariculture supply share (%) | 71.0% to 75.0% | 73.0% to 77.0% | 82.0% to 86.0% |
Table 4: Refinery & Processing Plant Valuation Indicators for the Commercial Seaweed Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 12.8 billion | 2026 global valuation baseline |
| Commercial macroalgae processing & extraction plants | 780 facilities | Global hydrocolloid & nori processing registry |
| Market value per processing facility | USD 16.4 million | Annualized plant valuation realization |
| Human food & snacks market value, 2026 | USD 6.3 billion | 49.3% end-use segment allocation |
Modern seaweed refineries must balance fresh wash-water use with high gel recovery across stainless-steel press lines. At the retail end, specialty food importers combine roasted nori sheets with processed culinary macroalgae to build wider Asian snack sections across Western supermarkets.
Analyst Perspective
"Hydrocolloid refiners and culinary sheet roasters can no longer rely on spot artisanal harvests to pass multinational food safety audits. Suppliers that pair heat-tolerant red seaweed seedstock with closed-loop alkali recovery will win multi-year supply contracts across dairy and snack accounts and farm biostimulant programs."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the commercial seaweed market segmented?
The commercial seaweed market is segmented by macroalgae species, form, end use, harvesting method, processing grade, and region. In 2026, Red Seaweed is projected at 45.7%, Dried Flakes, Sheets & Powders at 47.3%, Human Food & Snacks at 49.3%, Rope, Net & Longline Coastal Mariculture at 49.1%, and Food-Grade Dehydrated & Roasted at 51.3%.
By macroalgae species: Red Seaweed, Brown Seaweed, and Green Seaweed.
By form: Dried Flakes, Sheets & Powders, Hydrocolloid Extracts, and Fresh & Salted Seaweed.
By end use: Human Food & Snacks, Hydrocolloid Texturizers, Agricultural Biostimulants & Low-Methane Feed, and Bio-Packaging & Personal Care.
By harvesting method: Rope, Net & Longline Coastal Mariculture, Offshore Integrated Multi-Trophic Aquaculture, and Sustainable Intertidal Wild Mechanical Harvest.
By processing grade: Food-Grade Dehydrated & Roasted, Refined & Semi-Refined Hydrocolloid Extraction Grade, and Cold-Pressed Liquid Biostimulant Extract.
Why does Red Seaweed lead the macroalgae species category?
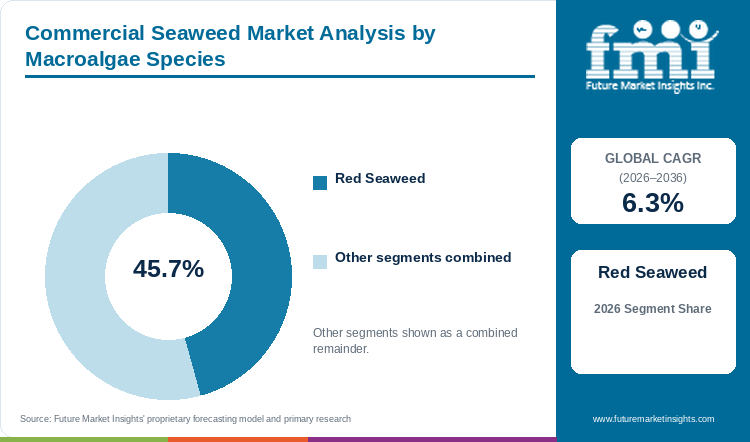
Red Seaweed is projected to capture 45.7% of macroalgae species valuation during 2026, supported by carrageenan and agar extraction.
Table 5: Macroalgae Species Share for the Commercial Seaweed Market (percentage share), 2026
| Macroalgae Species | Share (2026) |
|---|---|
| Red Seaweed | 45.7% |
| Other Segments Combined | 54.3%* |
| Total | 100.0% |
*Note: Remaining macroalgae species categories (Brown Seaweed and Green Seaweed) sum to 100.0% of 2026 market valuation.
Table 6: Macroalgae Species Leadership and Market Growth for the Commercial Seaweed Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.3% |
| Leading Segment | Red Seaweed |
Dairy and processed meat formulators and nori snack roasters prefer red seaweed varieties such as Kappaphycus and Eucheuma (or cold-water Pyropia) because their natural fibers form strong gels at very low dosage levels. In addition to this, farmed tropical red seaweeds reach full harvest size in just 45 days and go straight into kappa carrageenan texturizers and roasted sushi-sheet factories.
- Red Seaweed is projected to secure 45.7% of macroalgae species market value during 2026 because fast 45-day tropical farm cycles support both carrageenan extraction and culinary sheet roasting.
- During June 2026, Gelymar S.A. technical disclosures on Chilean red seaweeds documented annual harvests of 71,643 tonnes of Gracilaria chilensis and 24,331 tonnes of Sarcothalia crispata yielding 40% dry-weight carrageenan [3].
Why do Dried Flakes, Sheets & Powders define the largest form segment?
Dried Flakes, Sheets & Powders are estimated to secure 47.3% of form valuation during 2026, driven by ambient export stability.
Freshly harvested seaweeds hold 75% to 90% water by weight and spoil within 24 hours unless coastal crews dry them right after landing. When processors bring moisture below 15%, they cut ocean container weight by four-fifths and provide shelf-stable feedstock for bacteriological and food agar refineries and dry seasoning blenders.
- Dried Flakes, Sheets & Powders are estimated to command 47.3% of the form category during 2026 because dry bales travel in standard shipping containers without costly refrigeration.
- An October 2025 food safety evaluation published in Marine Drugs verified that European Union purity rules require loss on drying at or below 15% for food-grade seaweed polysaccharides [4].
What keeps Human Food & Snacks ahead by end use?
Human Food & Snacks are expected to command 49.3% of end-use market size during 2026, reflecting roasted sheet demand.
Direct food use across East Asian convenience stores and Western grocery aisles earns a much higher price per dry kilogram than bulk industrial extraction. Consumer food brands roast thin Pyropia sheets in sesame or avocado oil and blend kelp flakes into savory plant-based snacks so shoppers get natural umami taste with less sodium.
- Human Food & Snacks are expected to hold 49.3% of end-use market value during 2026 because seasoned nori multipacks and wakame soups generate steady weekly grocery repeat purchases.
- During October 2026, FAO GLOBEFISH trade records confirmed that global imports of seaweed for direct human food use reached 323,310 tonnes while culinary exports totaled 286,040 tonnes in 2025 [5].
Why does Rope, Net & Longline Coastal Mariculture lead the harvesting method category?
Rope, Net & Longline Coastal Mariculture is forecast to generate 49.1% of 2026 harvest demand, owing to nearshore scalability.
Suspended nylon ropes and floating bamboo rafts in calm coastal bays let village cooperatives grow uniform seaweed cuttings without heavy workboats or seabed dredging. When compared with wild kelp cutting that faces strict seasonal harvest bans, nearshore rope grids deliver predictable harvests every six to eight weeks across Southeast Asian and East Asian bays.
- Rope, Net & Longline Coastal Mariculture is forecast to account for 49.1% of harvesting method valuation during 2026 as coastal family farms expand line spacing and nursery output.
- During June 2026, the FAO Asia-Pacific regional aquaculture assessment reported that Asian coastal mariculture produced 97% of global algae supply across nearly 40 million harvested tonnes [6].
What gives Food-Grade Dehydrated & Roasted the leading position in processing grade?
Food-Grade Dehydrated & Roasted grades are anticipated to capture 51.3% of 2026 processing valuation, reinforced by microbiological purity standards.
Culinary sheet makers and soup manufacturers pay a clear premium for washed and optically sorted seaweed leaves that are oven-roasted free of shell grit and sand. To pass supermarket quality audits, plants run closed-loop freshwater washing and metal detection before sealing each pack with nitrogen.
- Food-Grade Dehydrated & Roasted output is anticipated to capture 51.3% of processing grade market size during 2026 because retail and foodservice buyers require certified heavy-metal and pathogen clearance.
- During June 2026, IFF launched its Danisco Grindsted DuoGel carrageenan-pectin stabilizer system in Europe to give plant-based gummy and confectionery makers uniform heat stability [7].
What are the drivers, restraints, and opportunities in the commercial seaweed market?
In the commercial seaweed market, clean-label hydrocolloid reformulation and foliar biostimulant adoption are projected to expand processor order books whereas marine heatwaves restrain farm yields and low-methane livestock feed supplements create high-margin opportunities.
- Driver: Clean-label replacement of animal gelatin and synthetic stabilizers in dairy and plant-based foods turns red and brown seaweed extracts into everyday ingredient staples.
- Restraint: Marine heatwaves and bacterial ice-ice bleaching combined with strict arsenic and iodine limits cause seasonal raw-material shortages and compliance rejections.
- Opportunity: Cold-pressed Ascophyllum crop biostimulants and standardized Asparagopsis livestock feed additives open higher-margin agricultural valuation streams.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Dairy and confectionery brands and farm input suppliers are replacing synthetic chemical sprays and animal-derived pork gelatin with marine hydrocolloids and cold-pressed kelp extracts. When food makers formulate vegan desserts or farmers treat drought-stressed row crops, they rely on natural seaweed sugars and carrageenan chains for consistent performance. Future Market Insights notes that stricter fertilizer runoff rules across Europe are speeding up farm adoption of liquid kelp sprays and functional aquafeed additives in coastal fish farming. During June 2026, Groupe Roullier reported EUR 2.9 billion in 2025 consolidated business activity and 4.4 million tonnes of finished agrosupply and marine biostimulant shipments across 109 industrial sites [8]. Because of this steady demand, ingredient processors are signing multi-season farm support contracts to lock in traceable wet seaweed supply.
Risk Assessment of the Commercial Seaweed Market: Operational and Cultivation Friction
Warmer coastal water temperatures and seasonal algae fouling coupled with natural heavy-metal uptake remain the main hurdles squeezing processor margins. When shallow tropical lagoon waters warm past 31 degrees Celsius during El Nino months, bacteria trigger ice-ice bleaching that ruins the gel-rich outer layer of red seaweed before harvest. During March 2025, a metabolomic study of the red seaweed Asparagopsis taxiformis published in Science of the Total Environment confirmed that seasonal temperature and salinity swings significantly change active bromoform levels across subtropical coastal waters [9]. At the same time, food safety agencies in Europe and North America enforce tight limits on inorganic arsenic and cadmium across edible films and coatings and dried kelp flakes, which forces refiners to pay for extra washing and laboratory batch testing.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Refinery margins improve noticeably when processors turn the entire seaweed plant into multiple products instead of selling raw sun-dried bales. Traditional alkaline carrageenan extraction throws away up to 60% of the seaweed plant as solid filter cake. Modern biorefineries now use gentle enzyme breakdown to turn that leftover fiber into soluble food ingredients and dehydrated culinary seasonings for food and crop buyers. During April 2026, Groupe Roullier announced its 2025-2026 Innovation Awards winners under the Sea to Farm program, granting a EUR 300,000 research partnership to the SEA4FEED project and EUR 10,000 to the BIOMAT-MAERL open-sea cultivation initiative [10]. This in turn helps processors that combine offshore spore-seeded farming with zero-waste filtration win long-term supply agreements with global food and agriculture brands.
Commercial Seaweed Market by Country (2026 to 2036)
Indonesian mariculture leads all five commercial seaweed nations in Table 7 with a projected 7.6% CAGR through 2036, while Japanese market growth is forecast to progress at a 5.2% annual pace. Performance across Southeast Asian island farms and East Asian or North American processing centers depends on coastal lease permits and local refining investments paired with heat-tolerant nursery seedstock.
Table 7: Country CAGR and Primary Growth Levers for the Commercial Seaweed Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Indonesia | 7.6% | National downstreaming policy and Sulawesi/Nusa Tenggara Eucheuma refinery expansion |
| Philippines | 7.3% | FAO Hand-in-Hand USD 57.4M farm investment portfolio and semi-refined carrageenan exports |
| USA | 5.8% | Maine and Alaska kelp mariculture leases and clean-label snack and biostimulant demand |
| South Korea | 5.6% | Record roasted gim export value and mechanized offshore Pyropia dryer upgrades |
| Japan | 5.2% | High-value nori and wakame retail gastronomy paired with heat-resistant cultivar breeding |
Source: Future Market Insights analysis
Indonesia Commercial Seaweed Market Outlook (2026 to 2036)
Unlike cold-water kelp markets that rely on seasonal wild harvests, Indonesia runs a year-round tropical farming economy built on family longline plots across South Sulawesi and East Nusa Tenggara out to Maluku. According to the June 2026 FAO State of World Fisheries and Aquaculture report, Indonesia added 619,300 tonnes of farmed algae output between 2022 and 2024, accounting for 25.8% of total global aquaculture growth [11]. Because of this farm scale, domestic commercial seaweed market value is projected to climb at a leading 7.6% CAGR through 2036 as local industrial parks process raw Kappaphycus into refined carrageenan. Whilst inter-island barge freight costs and seasonal bleaching still challenge small farmers, national downstreaming rules continue to attract foreign refinery joint ventures.
Key takeaway: In Indonesia, national downstream processing incentives and year-round Sulawesi longline harvests are projected to drive global carrageenan refinery expansion.
Philippines Commercial Seaweed Market Outlook (2026 to 2036)
Export-focused alkali treatment plants in Cebu and Zamboanga make the Philippines a primary global supplier of food-grade semi-refined carrageenan and meat-binding blends. At the October 2026 FAO World Food Forum Hand-in-Hand Investment Forum in Rome, the Philippine delegation presented a USD 57.4 million farm investment portfolio focused on modernizing the commercial seaweed value chain and raising coastal family incomes [12]. Supported by these upgrades, Philippine commercial seaweed industry valuation is expected to advance at a 7.3% annual rate over the 2026 to 2036 period as laboratory-grown seedlings replace older cuttings. However, frequent typhoon damage across Mindanao and Palawan nurseries still requires processors to fund deeper-water tubular net systems.
Key takeaway: In the Philippines, multilateral farm modernization funding and Cebu carrageenan refining capacity are expected to sustain strong export valuation growth.
USA Commercial Seaweed Market Outlook (2026 to 2036)
When compared with Asian mass-volume farming, United States commercial seaweed demand comes mainly from domestic food stabilizer blending and organic crop biostimulants for retail snack and farm brands. During May 2026, Tate & Lyle PLC reported full-year results confirming the completed operational integration of U.S.-based hydrocolloid producer CP Kelco, delivering USD 24 million in cost savings and reaching its USD 50 million run-rate savings target one year early [13]. Driven by these ingredient platforms, United States commercial seaweed market size is anticipated to expand at a 5.8% CAGR through 2036 across food and farm applications and personal-care product lines. Even so, slow coastal permitting in California and Washington still pushes most new domestic kelp farms toward Maine and Alaska.
Key takeaway: In the USA, integrated hydrocolloid blending platforms and expanding Gulf of Maine kelp leases are anticipated to sustain long-term domestic demand.
South Korea Commercial Seaweed Market Outlook (2026 to 2036)
Mechanized offshore Pyropia net farms and automated sheet-roasting factories across Jeonnam province make South Korea the world's leading exporter of branded roasted gim snacks. Agricultural attaché findings in the September 2026 Korea Seafood Market Update highlighted expanding domestic marine aquaculture supplies and brisk international seafood and marine food trade across South Korean ports [14]. Because global grocery chains continue to expand Asian snack shelves, South Korean commercial seaweed market valuation is forecast to rise at a 5.6% yearly rate from 2026 to 2036 across organic and seasoned multipacks. At the same time, warmer coastal waters and seasonal red-tide blooms require Korean hatcheries to breed heat-tolerant seed strains.
Key takeaway: In South Korea, automated gim roasting plants and wider supermarket distribution across Western markets are forecast to support long-term valuation gains.
Japan Commercial Seaweed Market Outlook (2026 to 2036)
Japan stands apart from export-focused Southeast Asian producers through its deep domestic consumption of premium nori and kombu and wakame sheets as well as high-purity sodium alginate manufacturing. According to the April 2026 FAO GLOBEFISH species analysis, higher international prices for edible red and brown seaweeds reflect tighter East Asian coastal harvests and steady convenience-store rice-ball wrapper buying [15]. Consequently, Japanese commercial seaweed market value is predicted to grow at a 5.2% annual pace through 2036 across retail food and restaurant dining and medical alginate wound dressings. Older coastal cooperative workforces and winter nutrient drops in the Ariake Sea still limit local wet harvests, which leads Japanese packers to supplement domestic supply with imported Korean sheets.
Key takeaway: In Japan, steady convenience-store nori demand and pharmaceutical alginate production are predicted to maintain value growth despite smaller coastal workforces.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the commercial seaweed market?
Cargill, Incorporated, CP Kelco U.S., Inc. (Tate & Lyle plc), IFF (International Flavors & Fragrances Inc.), Acadian Seaplants Limited, Groupe Roullier, Gelymar S.A., Ocean's Halo (New Frontier Foods Inc.), and KIMICA Corporation are the notable companies in the commercial seaweed market.
FMI analysis shows that industry competition spans multinational hydrocolloid ingredient blenders and regional carrageenan or alginate extractors and marine biostimulant or snack brands. Global ingredient suppliers run multi-continent application labs that blend red-seaweed carrageenan with pectin and locust bean gum for dairy and meat customers. Meanwhile, regional extraction specialists build refineries right next to Chilean and Indonesian landing ports and Japanese harbors, whereas biostimulant and snack makers focus on cold-pressed brown kelp extracts and organic roasted nori sheets.
- Global Hydrocolloid & Texturizer Platforms: Cargill Incorporated and CP Kelco (along with IFF) supply standardized carrageenan and alginate stabilizer systems to multinational food and personal-care manufacturers.
- Regional Carrageenan & Alginate Extraction Specialists: Gelymar S.A. and KIMICA Corporation run coastal extraction plants in Chile and Japan focused on cold-water red-seaweed carrageenan and pharmaceutical-grade alginates.
- Marine Biostimulant & Culinary Seaweed Innovators: Acadian Seaplants Limited and Groupe Roullier (along with Ocean's Halo) produce cold-pressed crop biostimulants and certified organic roasted seaweed snacks.
Competitive Benchmarking: Commercial Seaweed Market
Table 8: Competitive Benchmarking for the Commercial Seaweed Market (qualitative capability ratings), 2026
| Company | Species & Extract Breadth | Refining & Formulation Depth | Mariculture Traceability | Geographic Reach |
|---|---|---|---|---|
| Cargill, Incorporated | High | High | High | High |
| CP Kelco U.S., Inc. (Tate & Lyle plc) | High | High | High | High |
| IFF (International Flavors & Fragrances Inc.) | High | High | High | High |
| Acadian Seaplants Limited | Medium | High | High | High |
| Groupe Roullier | Medium | High | High | High |
| Gelymar S.A. | Medium | High | High | Medium |
| Ocean's Halo (New Frontier Foods Inc.) | Medium | Medium | High | Medium |
| KIMICA Corporation | Medium | High | High | High |
Scoring basis: Capability tiers evaluate documented product breadth across red and brown seaweed derivatives and green macroalgae extracts with custom hydrocolloid or biostimulant formulation depth. Traceability and geographic ratings reflect verified sustainable harvest certifications (such as the ASC-MSC Seaweed Standard) and multi-region distribution networks.
Key Developments in the Commercial Seaweed Market
- During July 2026, Cargill Incorporated issued its 2026 Annual Report detailing food ingredient co-innovation and animal nutrition plant upgrades in Austria and India serving customers across 70 countries [16].
- Acadian Seaplants Limited submitted its 2026 United Nations Global Compact Communication on Progress in May 2026 after publishing its inaugural Sustainability Report and EcoVadis assessment covering Ascophyllum nodosum harvesting across 80 export markets [17].
- Ocean's Halo (New Frontier Foods Inc.) expanded its USDA Organic trayless seaweed snack portfolio across Whole Foods Market and Walmart in 2025 and 2026 by launching extra-large Sea Salt & Avocado Oil and Thai Sweet Chili formats and 50-count Sushi Nori packs [18].
Key Players in the Commercial Seaweed Market
Global Hydrocolloid & Texturizer Platforms
- Cargill, Incorporated
- CP Kelco U.S., Inc. (Tate & Lyle plc)
- IFF (International Flavors & Fragrances Inc.)
Regional Carrageenan & Alginate Extraction Specialists
- Gelymar S.A.
- KIMICA Corporation
Marine Biostimulant & Culinary Seaweed Innovators
- Acadian Seaplants Limited
- Groupe Roullier
- Ocean's Halo (New Frontier Foods Inc.)
Commercial Seaweed Market - Report Scope
Table 9: Report Scope for the Commercial Seaweed Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Macroalgae Species; Form; End Use; Harvesting Method; Processing Grade; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial processor and B2B/retail supplier market value from cultivated and wild-harvested marine macroalgae (red, brown, and green seaweeds) sold as dried flakes, roasted culinary sheets, refined and semi-refined hydrocolloid extracts (carrageenan, agar, alginates), fresh/salted thalli, and liquid biostimulant extracts. Category Scope Note: Excludes freshwater unicellular microalgae (such as Spirulina and Chlorella), unharvested wild marine carbon-offset credits, and synthetic petroleum-derived soil conditioners. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Indonesia, Philippines, USA, South Korea, Japan, and additional countries in the full report |
| Key Companies Covered | Cargill, Incorporated, CP Kelco U.S., Inc. (Tate & Lyle plc), IFF (International Flavors & Fragrances Inc.), Acadian Seaplants Limited, Groupe Roullier, Gelymar S.A., Ocean's Halo (New Frontier Foods Inc.), KIMICA Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Commercial Seaweed Market - Research Methodology
Table 10: Research Methodology for the Commercial Seaweed Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with coastal mariculture cooperative directors, carrageenan and alginate refinery engineers, culinary nori processors, and agricultural biostimulant formulators to validate wet-to-dry conversion yields and contract pricing. |
| Secondary Research | Analysis of FAO SOFIA and GLOBEFISH trade databases, USDA Foreign Agricultural Service seafood reports, peer-reviewed phycology journals, and corporate sustainability and financial filings. |
| Market Sizing and Forecasting | Top-down processor valuation models reconciled against bottom-up wet-weight harvest tonnage and dry-equivalent hydrocolloid and culinary sheet realizations from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight mariculture concession expansion, domestic carrageenan refining capacity, roasted gim export velocity, and foliar biostimulant adoption across five national markets. |
| Operational Benchmark Traceability | Biomass, dry-equivalent tonnage, and facility valuation indicators in Tables 2, 3, and 4 trace to FAO SOFIA 2026 aquaculture statistics, GLOBEFISH trade records, and commercial hydrocolloid refinery registries. |
| Data Triangulation and Validation | Demand estimates are cross-checked against national customs export declarations and industrial hydrocolloid procurement volumes without double counting freshwater microalgae. |
Commercial Seaweed Market by Segments
Commercial Seaweed Market segmented by Macroalgae Species:
- Red Seaweed
- Brown Seaweed
- Green Seaweed
Commercial Seaweed Market segmented by Form:
- Dried Flakes, Sheets & Powders
- Hydrocolloid Extracts
- Fresh & Salted Seaweed
Commercial Seaweed Market segmented by End Use:
- Human Food & Snacks
- Hydrocolloid Texturizers
- Agricultural Biostimulants & Low-Methane Feed
- Bio-Packaging & Personal Care
Commercial Seaweed Market segmented by Harvesting Method:
- Rope, Net & Longline Coastal Mariculture
- Offshore Integrated Multi-Trophic Aquaculture
- Sustainable Intertidal Wild Mechanical Harvest
Commercial Seaweed Market segmented by Processing Grade:
- Food-Grade Dehydrated & Roasted
- Refined & Semi-Refined Hydrocolloid Extraction Grade
- Cold-Pressed Liquid Biostimulant Extract
Commercial Seaweed Market by Region
- North America
- United States
- Canada
- Latin America
- Chile
- Brazil
- Mexico
- Peru
- Western Europe
- France
- Norway
- United Kingdom
- Ireland
- Spain
- Eastern Europe
- Poland
- Czech Republic
- Romania
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- Indonesia
- Philippines
- India
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Tanzania
- Morocco
Research Sources and Bibliography
- [1] Food and Agriculture Organization of the United Nations (FAO). (2026, April 17). FAO GLOBEFISH launches new quarterly species analysis on seaweed. FAO GLOBEFISH.
- [2] Food and Agriculture Organization of the United Nations (FAO). (2026, June 16). Aquaculture production. The State of World Fisheries and Aquaculture 2026 (SOFIA).
- [3] Zamorano, J. (2026, June 15). Red seaweeds from Chile: the phyconomy behind carrageenan and sustainable hydrocolloids. Gelymar S.A.
- [4] Cotas, J., Lomartire, S., Pacheco, D., & Pereira, L. (2025, October 22). Seaweed Polysaccharides: A Rational Approach for Food Safety Studies. Marine Drugs, 23(11), 412.
- [5] Food and Agriculture Organization of the United Nations (FAO). (2026, October 15). Seaweed | Globefish | FAO Food and Agriculture Organization of the United Nations. FAO GLOBEFISH Species Analysis.
- [6] Food and Agriculture Organization of the United Nations (FAO). (2026, June 16). Asia drives global aquatic production to record high, powered by aquaculture expansion. FAO Regional Office for Asia and the Pacific.
- [7] International Flavors & Fragrances Inc. (IFF). (2026, June 23). IFF launches first-of-its-kind stabilizer system in Europe, the Middle East and Africa. IFF Media Newsroom.
- [8] Groupe Roullier. (2026, June 22). 2025 Activity Report: discover a year of commitment and action. Groupe Roullier Corporate Publications.
- [9] Chen, Y.-T., Lin, H.-J., & Wang, W.-L. (2025, March 07). Metabolomic analysis of methane-reducing seaweed Asparagopsis taxiformis for sustainable production in Taiwan. Science of the Total Environment, 971, 179045 (PubMed PMID 40056866).
- [10] Groupe Roullier. (2026, April 02). The Innovation Awards Roullier reveal their 2025-2026 winners. Groupe Roullier Innovation.
- [11] Food and Agriculture Organization of the United Nations (FAO). (2026, June 16). The State of World Fisheries and Aquaculture 2026: Blue Transformation in Action (Indonesian Algae Production Series). FAO Fisheries and Aquaculture Division.
- [12] Food and Agriculture Organization of the United Nations (FAO). (2026, October 13). World Food Forum 2026: FAO's Hand-in-Hand Investment Forum opens with record $20.16 billion in proposed investments. FAO Newsroom.
- [13] Tate & Lyle PLC. (2026, May 21). Tate & Lyle PLC: Results for the Year Ended 31 March 2026. Tate & Lyle Investor Relations.
- [14] USDA Foreign Agricultural Service (FAS). (2026, September 29). Korea Seafood Market Update 2026 - Rising Aquaculture Supplies and Protein Demand (Report KS2026-0038). United States Department of Agriculture GAIN.
- [15] Food and Agriculture Organization of the United Nations (FAO). (2026, April 17). GLOBEFISH Highlights: Quarterly Macroalgae Export Price and East Asian Nori Supply Review. FAO GLOBEFISH.
- [16] Cargill, Incorporated. (2026, July 01). Cargill 2026 Annual Report: Food, Agriculture, Innovation and Supply Chain Progress | Cargill. Cargill, Incorporated.
- [17] Acadian Seaplants Limited. (2026, May 08). Acadian Seaplants Submits 2026 Communication on Progress. Acadian Seaplants Newsroom.
- [18] Ocean's Halo (New Frontier Foods Inc.). (2026, February 12). Ocean's Halo, The BFY Asian Brand, Disrupts Snack Category with XL Seaweed Formats and Walmart Flavor Expansion. Ocean's Halo Newsroom.
- [19] Cargill, Incorporated. (2026, March 18). Hydrocolloids Ingredients: Carrageenan and Alginate Texturizer Portfolio Update. Cargill Food & Beverage North America.
- [20] KIMICA Corporation. (2025, November 12). Pharmaceutical and Food-Grade Sodium Alginate Refining Sustainability Update. KIMICA Corporation Tokyo.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the commercial seaweed market in 2026 and what is forecast for 2036?
- Which hydrocolloid and biostimulant pressures support demand for commercial seaweed?
- Why does Red Seaweed lead the macroalgae species category?
- Why do Dried Flakes, Sheets & Powders lead the form category globally?
- How do growth rates differ across Indonesia, the Philippines, the USA, South Korea, and Japan?
- Which leading companies refine and supply commercial seaweed products today?
- What limits adoption or farm-yield consistency in the commercial seaweed market?
- What should food and agricultural buyers evaluate before procuring commercial seaweed?
Frequently Asked Questions
How big is the commercial seaweed market in 2026, and what is forecast for 2036?
According to FMI, global commercial seaweed market size is estimated to reach USD 12.8 billion during 2026 from USD 12.0 billion in 2025. Industry valuation is forecast to hit USD 23.6 billion by 2036 as food processors and agricultural formulators expand hydrocolloid and biostimulant buying.
What is the CAGR for the commercial seaweed market from 2026 to 2036?
Future Market Insights projects a 6.3% compound annual growth rate between 2026 and 2036, generating an anticipated USD 10.8 billion increase in annual market value across culinary and hydrocolloid channels and crop biostimulant products.
Which macroalgae species segment leads the commercial seaweed market?
Red Seaweed is projected to capture 45.7% of macroalgae species valuation during 2026 because farmed Kappaphycus and Eucheuma (along with Pyropia) supply both carrageenan extraction plants and roasted nori sheet lines.
Which form segment leads the commercial seaweed market?
Dried Flakes, Sheets & Powders are estimated to secure 47.3% of the form category during 2026 as coastal dryers keep moisture below 15% for stable ocean shipping.
Which country has a notable growth outlook during the assessment period?
Indonesia is projected to pace national market growth at a 7.6% CAGR through 2036, supported by Sulawesi and Nusa Tenggara longline farms and domestic carrageenan refinery investments.
Who are the key players in the market?
Cargill, Incorporated, CP Kelco U.S., Inc. (Tate & Lyle plc), IFF (International Flavors & Fragrances Inc.), Acadian Seaplants Limited, Groupe Roullier, Gelymar S.A., Ocean's Halo (New Frontier Foods Inc.), and KIMICA Corporation lead commercial supply across hydrocolloid refining and crop biostimulants and roasted snack channels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Macroalgae Species, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Macroalgae Species, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Macroalgae Species, 2026 to 2036
- Red Seaweed
- Brown Seaweed
- Green Seaweed
- Y-o-Y Growth Trend Analysis By Macroalgae Species, 2021 to 2025
- Absolute $ Opportunity Analysis By Macroalgae Species, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Dried Flakes, Sheets & Powders
- Hydrocolloid Extracts
- Fresh & Salted Seaweed
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Human Food & Snacks
- Hydrocolloid Texturizers
- Agricultural Biostimulants & Low-Methane Feed
- Bio-Packaging & Personal Care
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Harvesting Method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Harvesting Method, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Harvesting Method, 2026 to 2036
- Rope, Net & Longline Coastal Mariculture
- Offshore Integrated Multi-Trophic Aquaculture
- Sustainable Intertidal Wild Mechanical Harvest
- Y-o-Y Growth Trend Analysis By Harvesting Method, 2021 to 2025
- Absolute $ Opportunity Analysis By Harvesting Method, 2026 to 2036
- Global Market Analysis and Forecast, By Processing Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing Grade, 2026 to 2036
- Food-Grade Dehydrated & Roasted
- Refined & Semi-Refined Hydrocolloid Extraction Grade
- Cold-Pressed Liquid Biostimulant Extract
- Y-o-Y Growth Trend Analysis By Processing Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Chile
- Brazil
- Mexico
- Peru
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- France
- Norway
- United Kingdom
- Ireland
- Spain
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Indonesia
- Philippines
- India
- Australia and New Zealand
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Tanzania
- Morocco
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Indonesia
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Philippines
- Pricing Analysis
- Market Share Analysis, 2025
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Macroalgae Species
- By Form
- By End Use
- By Harvesting Method
- By Processing Grade
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cargill, Incorporated
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- CP Kelco U.S., Inc. (Tate & Lyle plc)
- IFF (International Flavors & Fragrances Inc.)
- Acadian Seaplants Limited
- Groupe Roullier
- Gelymar S.A.
- Ocean's Halo (New Frontier Foods Inc.)
- KIMICA Corporation
- Cargill, Incorporated
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


