
- Market Size (2026)
- USD 4.20 Bn
- Forecast (2036)
- USD 6.40 Bn
- CAGR (2026 to 2036)
- 4.4%
How Big Is the Cordial Drink Market in 2026?
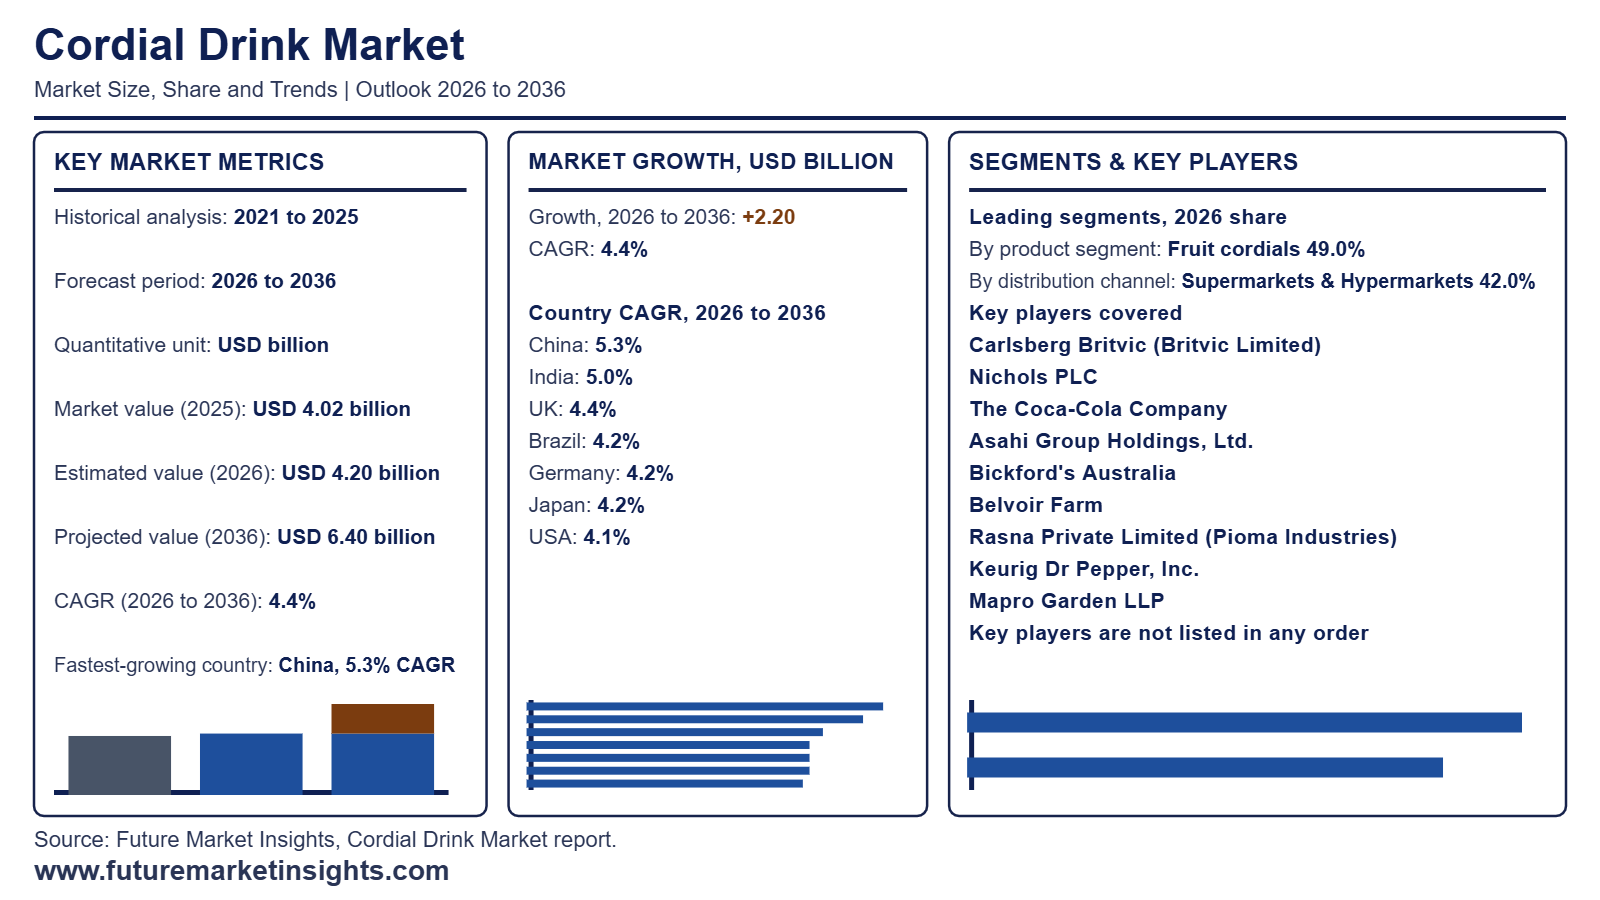
Registering a value of USD 4.02 billion in 2025, the global cordial drink market expanded to USD 4.20 billion in 2026 and is anticipated by Future Market Insights (FMI) to achieve USD 6.40 billion by 2036, driven by a 4.4% CAGR that generates USD 2.20 billion in incremental opportunity.
| Market Metric | Valuation / Share / Forecast Benchmark |
|---|---|
| 2025 Market Size (Historical) | USD 4.02 billion |
| 2026 Market Size (Estimated) | USD 4.20 billion |
| 2036 Market Size (Projected) | USD 6.40 billion |
| Compound Annual Growth Rate (2026 to 2036) | 4.4% CAGR |
| Incremental Dollar Opportunity (2026 to 2036) | USD 2.20 billion |
| Dominant Product Segment (2026 Share) | Fruit cordials (49.0% share in 2026) | Other Segment Combined (51.0% share) |
| Fastest-Growing Product Segment | Herbs & spices cordials (5.2% CAGR from 2026 to 2036) |
| Dominant Distribution Channel (2026 Share) | Supermarkets & Hypermarkets (42.0% share in 2026) |
| Fastest-Growing Distribution Channel | Online (5.8% CAGR from 2026 to 2036) |
| Largest Country Markets (2026 Global Share) | UK (22.0%), USA (16.0%), China (12.0%) |
| Fastest-Growing Country Markets (2026 to 2036) | China (5.3% CAGR), India (5.0% CAGR), UK (4.4% CAGR) |
| Leading Tier-1 Companies | Carlsberg Britvic (Britvic Limited), Nichols PLC, The Coca-Cola Company, Asahi Group Holdings, Ltd., Bickford's Australia, Belvoir Farm, Rasna Private Limited (Pioma Industries), Keurig Dr Pepper, Inc., Mapro Garden LLP, Monin Incorporated |
Source: Future Market Insights analysis of the cordial drink market, 2026.
This Report Answers
- How large the cordial drink market is in 2026 and what it reaches by 2036
- Which product and distribution channel segments lead in 2026
- What is driving demand and what is holding the category back
- Which countries grow fastest between 2026 and 2036
- What Carlsberg Britvic (Britvic Limited) and other leading players have launched
- How the cordial drink market is defined, segmented and measured
Executive Market Overview
Concentrated fruit squashes and dilutable cordials offer economical multi-serving hydration for family households, reducing single-use plastic container waste while providing customizable beverage intensity. As per FMI's assessment of retail category resets, household buyers judge liquid concentrates on prepared cost per glass and verified sugar content per diluted serving, owing to strict national nutrition-labeling and sugar-levy regimes across Europe and Commonwealth markets. In March 2026, Carlsberg Britvic (March 2026) expanded its adult squash portfolio in the United Kingdom with Robinsons Fruit Creations Strawberry and Cherry Lime in 1-litre grocery bottles, building on Robinsons household penetration across nearly 40% of British homes. Producers are simultaneously widening distribution across squash and squash drinks as global brewer consolidation reshapes route-to-market execution following Carlsberg Group (January 2025) completing its acquisition of Britvic plc in January 2025.
Standard high-sugar fruit syrups face intensifying retail margin pressure because grocery chains prioritize no-added-sugar concentrates and fortified family dilutables on eye-level shelves.FMI believes concentrate manufacturers are capturing higher unit realizations by formulating vitamin-fortified squashes and zero-sugar hospitality syrups using global fruit concentrates puree and naturally derived sweeteners. In March 2025, MONIN India (March 2025) launched its zero-added-sugar PURE concentrate range across Mint and Peach Apricot profiles for professional cafés and bars, while Bickford's Group (July 2025) consolidated its Australian health-conscious line into a unified No Added Sugar Cordial range in 750 ml bottles. Market sizing covers packaged nonalcoholic liquid cordials and beverage squash concentrates sold for dilution, while excluding ready-to-drink beverages, dry powder mixes, alcoholic liqueurs, and prepared bar drink receipts.
Analyst Perspective
"Cordial and squash manufacturers will expand margin faster through double-concentrate bottles, vitamin-fortified family blends, and zero-sugar café syrups than through standard full-sugar dilutables, because retailers allocate shelf space by yield per bottle and diluted sugar compliance. The primary commercial risk is post-dilution sugar taxation and European packaging-waste compliance costs."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights (FMI)
Key Market Trends & Insights
- Double-Concentrate and Adult Botanical Formats Lift Grocery Shelf Value:Supermarket buyers in mature squash markets are shifting shelf space toward double-strength concentrates and complex dual-fruit profiles that reduce plastic packaging weight per prepared litre while appealing to adult shoppers. FMI observes that entertainment-linked seasonal launches and adult mocktail extensions keep household penetration high across grocery and convenience channels. Official release disclosures from Carlsberg Britvic (March 2026) confirm the April 2026 rollout of 1-litre Robinsons Double Concentrate limited-edition flavours following its October 2025 seasonal convenience campaign documented by Carlsberg Britvic (October 2025).
- Micronutrient Fortification and Co-Created Flavors Expand Family Replenishment:Household cordial brands are differentiating core no-added-sugar squashes by adding vitamins C and D with iron and zinc to capture morning breakfast and after-school hydration occasions. FMI finds that functional fortification allows branded dilutables to defend price premiums against supermarket private-label squash. Corporate disclosures from Nichols PLC (2025) highlight the 2025 launch of Vimto Wonderfuel functional no-added-sugar squash, while Nichols PLC (July 2025) reported a 15.9% adjusted operating profit margin in the first half of 2025 and Nichols PLC (February 2026) introduced co-created Vimto Fans' Edition variants in February 2026.
- Zero-Sugar Professional Concentrates Accelerate Foodservice Menu Adoption:Coffee chains and quick-service restaurants increasingly require concentrated flavoring syrups that deliver standardized fruit and herbal intensity without adding sucrose calories to iced teas and mocktails. FMI notes that clean-label concentrates formulated without artificial preservatives simplify allergen and calorie menu boards for multi-site foodservice operators. In March 2025, Monin Americas (March 2025) introduced Yuzu Pineapple Syrup produced with fruit harvested from its own sustainable Portuguese orchard, while MONIN India (March 2025) demonstrated commercial zero-sugar beverage dosing systems for hospitality buyers at AAHAR 2025.
What Are the Main Drivers, Restraints, and Opportunities?
Multi-serve household dilution value and foodservice menu customization drive concentrate purchases, whereas post-dilution sugar levies and mandatory nutrition warnings restrain full-sugar recipes, leaving no-added-sugar and botanical cordials as the primary growth opportunity.
Driver: Multi-Serve Prepared Beverage Economy and High-Intensity Concentrates
Household shoppers purchase bottled liquid cordials because a single 750 ml or 1-litre concentrate bottle yields 20 to 40 prepared glasses of flavoured hydration at a fraction of the cost of canned soft drinks concentrates and bottled juices. FMI believes clear dilution instructions and concentrated portable formats help brand owners defend supermarket facings during periods of food price inflation, anchored by strong repeat purchase cycles among families with children. In July 2025, Nichols PLC (July 2025) confirmed nationwide distribution of its vitamin-fortified Vimto squash across major United Kingdom grocers as half-year adjusted operating profit rose to 15.9% of group revenue.
Restraint: Post-Dilution Sugar Levies and Front-of-Pack Nutrition Mandates
Beverage concentrate producers face complex cross-border formulation barriers because tax authorities assess sugar levies on the diluted drink according to stated mixing ratios rather than the raw syrup alone.In FMI's view, diverging national added-sugar thresholds force exporters to maintain separate recipes and back-label declarations across jurisdictions, due to stricter fiscal and food-safety enforcement and hydration boosters. Policy updates published by HM Revenue & Customs (October 2026) lower the United Kingdom Soft Drinks Industry Levy threshold to 4.5 grams of sugar per 100 milliliters from January 2028, while the Food Safety and Standards Authority of India (September 2025) updated its Version VIII Labelling and Display compendium governing added-sugar and fruit-content disclosures.
Opportunity: No-Added-Sugar Fruit and Botanical Cordials for Retail and HoReCa
Formulating fruit and elderflower or ginger cordials without added sucrose unlocks shelf placement in health-food aisles and premium cocktail bars that pair concentrates with flavored syrups and specialty syrup bases. FMI expects botanical and no-added-sugar cordials to capture higher retail prices per bottle as adult consumers trade up from artificial fruit squashes, helped by natural stevia and real fruit-juice blending. In July 2025, Bickford's Group (July 2025) rolled out its reformulated No Added Sugar Cordial range across Lime and Raspberry variants, while Belvoir Farm (2025) refreshed its No Added Sugar Sicilian Lemon and Cherries & Berries cordial lineup across UK and export grocers.
How Is the Cordial Drink Market Segmented?
Cordial Drink Market is segmented by Product, Distribution Channel, and Region. Forecast period from 2026 to 2036.
| Segmentation Axis | Sub-Segments Covered | 2026 Leading Segment & Share | Remainder & Total Alignment (2026 to 2036) |
|---|---|---|---|
| Product | Fruit cordials, Vegetable cordials, Herbs & spices cordials | Fruit cordials (49.0% share in 2026) | Other Segment Combined (51.0% share) | Total (100.0%) |
| Distribution Channel | Supermarkets & Hypermarkets, Convenience Stores, Foodservice/HoReCa, Online | Supermarkets & Hypermarkets (42.0% share in 2026) | Other Segment Combined (58.0% share) | Total (100.0%) |
| Region | North America, Western Europe, East Asia, South Asia and Pacific, Latin America, Eastern Europe, Middle East and Africa | Western Europe & North America (Leading regional revenue bases in 2026) | China (5.3% CAGR) & India (5.0% CAGR) lead national growth through 2036 |
Source: Future Market Insights analysis of the cordial drink market, 2026.
Why Does the Fruit Cordials Segment Lead by Product?
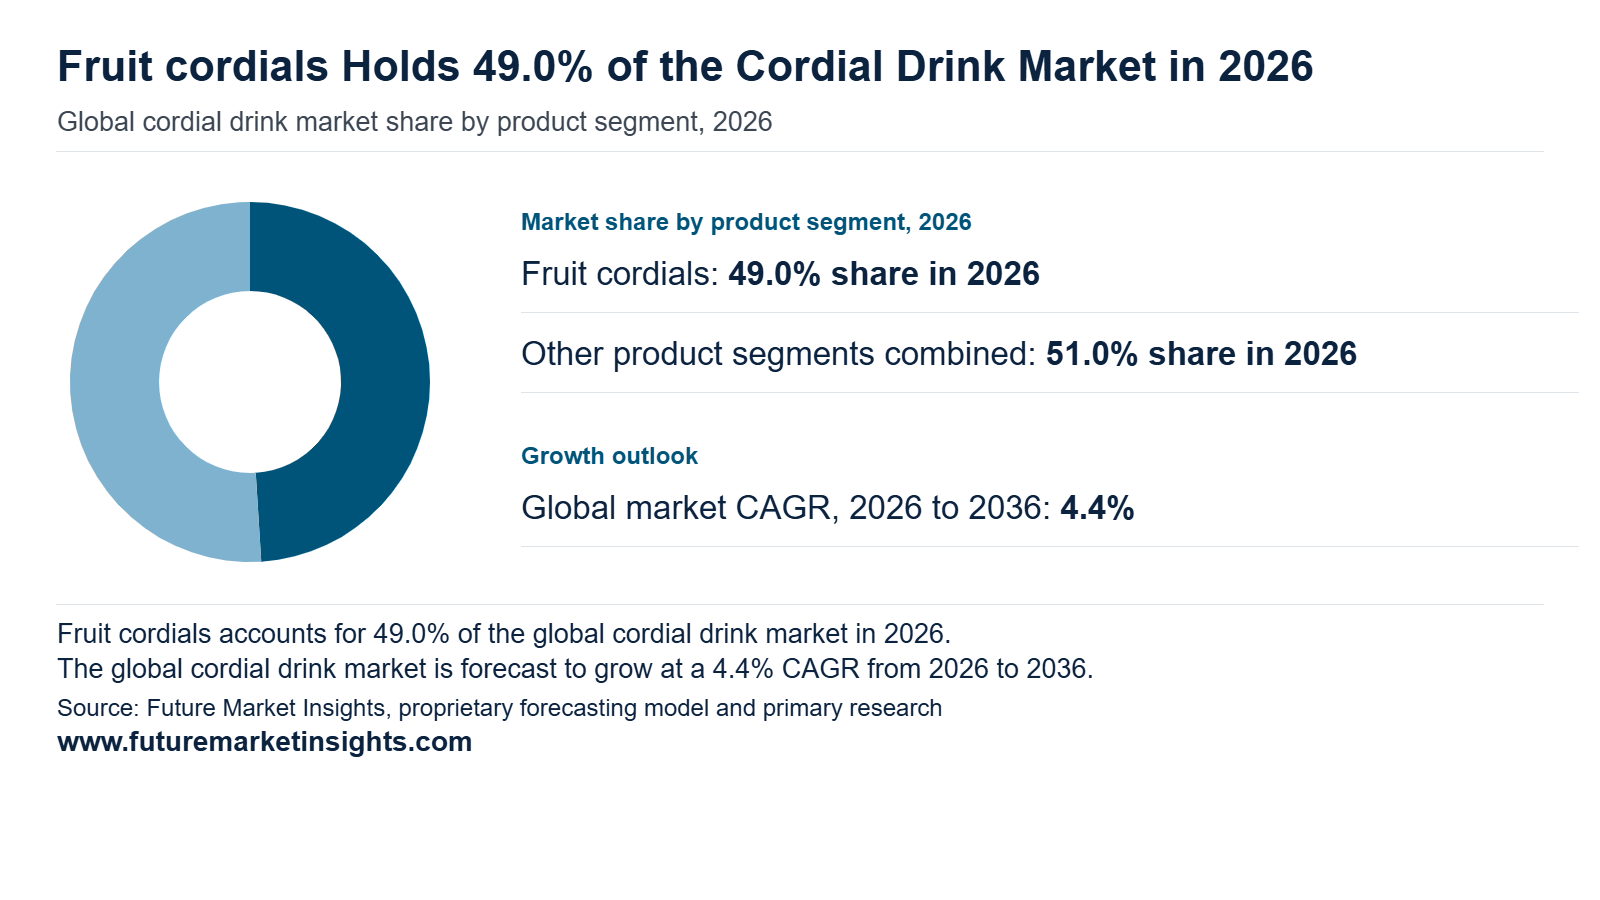
Fruit cordials capture 49.0% of product revenue in 2026, leading consumer demand as households and beverage bars mix versatile fruit concentrates with sparkling water and cocktails, serving as a staple bar syrup bases. While herbs and spices cordials such as elderflower and spiced jeera masala command higher unit prices in specialty retail, everyday household replenishment remains centered on citrus and berry recipes. Product launches from Carlsberg Britvic (March 2026) introducing Robinsons Fruit Creations Strawberry and Cherry Lime and Bickford's Australia (2025) expanding No Added Sugar Lemon juice cordials confirm that fruit-forward concentrates will remain the primary revenue contributor through 2036.
Why Do Supermarkets & Hypermarkets Lead by Distribution Channel?
Supermarkets and hypermarkets account for 42.0% of distribution channel revenue in 2026, leading volume sales through dedicated summer beverage displays and family-size cordial promotions sweetened with sugar or organic stevia sweetened beverages. Convenience stores capture top-up neighbourhood purchases and Foodservice/HoReCa accounts procure 750 ml and 1-litre professional dosing bottles for bars and cafés. Commercial rollouts by Carlsberg Britvic (March 2026) placing 1-litre Robinsons Double Concentrate packs across national grocery aisles and MONIN India (March 2025) servicing hospitality accounts illustrate how supermarkets anchor household volume while foodservice and online channels expand through 2036.
Regional & Country Outlook
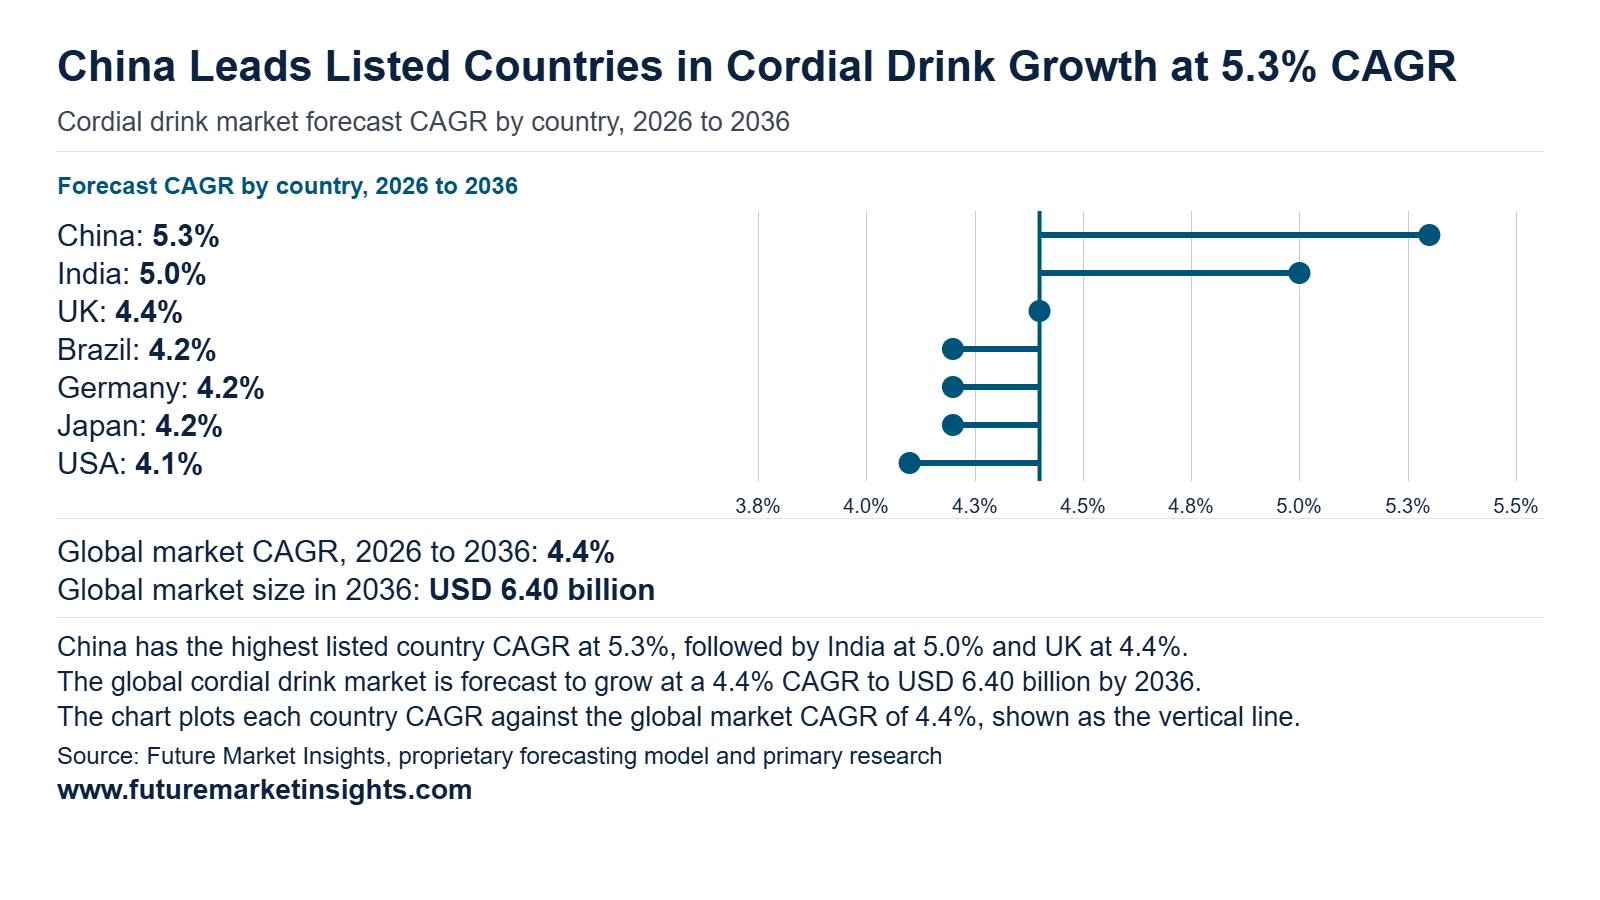
Western Europe and North America represent the largest regional revenue bases in the global cordial drink market in 2026, whereas East Asia and South Asia and Pacific record the fastest compound annual growth through 2036. FMI projects the seven core profiled countries, the United Kingdom, the United States and China, to account for 76.0% of global revenue in 2026, rising from USD 3.19 billion in 2026 to USD 4.91 billion by 2036. China leads national growth at a 5.3% CAGR and India follows at a 5.0% CAGR, while the United Kingdom remains the single largest country market at USD 0.92 billion in 2026 and USD 1.42 billion by 2036.
| Country | 2026 Revenue | 2036 Revenue | 10-Year Addition | 2026 to 2036 CAGR | Global Share (2026 -> 2036) |
|---|---|---|---|---|---|
| China | USD 0.50 billion | USD 0.84 billion | +USD 0.34 billion | 5.3% | 11.9% -> 13.1% |
| India | USD 0.38 billion | USD 0.62 billion | +USD 0.24 billion | 5.0% | 9.0% -> 9.7% |
| UK | USD 0.92 billion | USD 1.42 billion | +USD 0.50 billion | 4.4% | 21.9% -> 22.2% |
| Brazil | USD 0.25 billion | USD 0.38 billion | +USD 0.13 billion | 4.2% | 6.0% -> 5.9% |
| Germany | USD 0.30 billion | USD 0.45 billion | +USD 0.15 billion | 4.2% | 7.1% -> 7.0% |
| Japan | USD 0.17 billion | USD 0.26 billion | +USD 0.09 billion | 4.2% | 4.0% -> 4.1% |
| USA | USD 0.67 billion | USD 1.00 billion | +USD 0.33 billion | 4.1% | 16.0% -> 15.6% |
Source: Future Market Insights analysis of the cordial drink market, 2026.
China
Demand for cordial drink in China is projected to rise from USD 0.50 billion in 2026 to USD 0.84 billion by 2036, advancing at a 5.3% CAGR and adding USD 0.34 billion in new revenue. FMI finds that demand in China is driven by specialty tea-shop chains and urban e-commerce shoppers purchasing concentrated citrus and botanical syrups for home sparkling-water makers and iced beverage preparation. Official retail figures from the National Bureau of Statistics of China (January 2026) confirm that online sales of food products rose 14.5% in 2025 while national catering revenue increased 3.2%. FMI expects rapid e-commerce flavor discovery and standardized café syrup dosing to sustain strong cordial sales expansion across China through 2036.
India
Buyer adoption of cordial drink across India is estimated to expand from USD 0.38 billion in 2026 to USD 0.62 billion by 2036, spurred by a 5.0% CAGR and generating USD 0.24 billion in commercial expansion. In FMI's assessment, Indian household summer hydration habits and hotel welcome-drink service support high-volume purchases of fruit squashes and spiced sharbats formulated with botanical ingredients. Regulatory standards updated by the Food Safety and Standards Authority of India (September 2025) and product assortments from Mapro Garden LLP (2026) and MONIN India (March 2025) show domestic suppliers expanding both traditional fruit squashes and zero-sugar professional concentrates. FMI projects modern grocery expansion and foodservice mocktail menus to drive sustained cordial order volumes in India through 2036.
UK
Cordial drink industry in UK is set to scale from USD 0.92 billion in 2026 to USD 1.42 billion by 2036, driven by a 4.4% CAGR and adding USD 0.50 billion in incremental market value. FMI believes British households treat dilutable squash and cordial as an everyday pantry staple, with revenue growth attributed to shoppers trading up to double-concentrate bottles and vitamin-enriched squashes. In January 2025, Carlsberg Group (January 2025) completed its acquisition of Britvic plc to form Carlsberg Britvic, which subsequently launched Robinsons Fruit Creations in March 2026 per Carlsberg Britvic (March 2026) ahead of the HM Revenue & Customs (October 2026) 4.5g per 100 ml levy threshold shift. In FMI's view, ongoing no-added-sugar innovation from Robinsons and Vimto as well as Belvoir Farm will preserve the United Kingdom's position as the largest national cordial market through 2036.
Brazil
Sales of cordial drink throughout Brazil are projected to increase from USD 0.25 billion in 2026 to USD 0.38 billion by 2036, progressing at a 4.2% CAGR and creating USD 0.13 billion in additional revenue. FMI observes that Brazilian demand is anchored by household consumption of tropical fruit concentrates such as passionfruit and cashew dilutables under front-of-pack added-sugar labeling rules enforced by Agencia Nacional de Vigilancia Sanitaria (October 2020). On 9 November 2026, Carlsberg Group (November 2026) announced an agreement to sell Britvic Brazil, including the Maguary and Dafruta concentrate brands, to Grupo JAV to focus on core bottling operations. FMI expects local ownership under Grupo JAV and reformulated reduced-sugar tropical concentrates to sustain Brazilian supermarket demand through 2036.
Germany
Consumption of cordial drink across Germany is estimated to climb from USD 0.30 billion in 2026 to USD 0.45 billion by 2036, reflecting a 4.2% CAGR and contributing USD 0.15 billion over the forecast decade. FMI notes that German foodservice operators and households use fruit and herbal syrups to flavor sparkling tap water and seasonal spritzers, helped by reusable glass bottle systems as European packaging rules tighten. Regulatory updates from the European Commission (August 2026) confirm that the EU Packaging and Packaging Waste Regulation entered into application in August 2026, while Statistisches Bundesamt Destatis (February 2026) reported a 2.1% real decline in 2025 German hospitality receipts that encourages cost-effective concentrated drink prep. FMI anticipates recyclable glass packaging and natural botanical syrups to support steady German retail and café reorders through 2036.
Japan
Revenue generated by cordial drink suppliers in Japan is forecast to expand from USD 0.17 billion in 2026 to USD 0.26 billion by 2036, anchored by a 4.2% CAGR and generating USD 0.09 billion in new category sales. FMI's analysis indicates that Japanese cafés and households purchase yuzu and ginger cordials for hot winter dilutions and chilled soda mixes blended with natural flavours. Tourism statistics from the Japan National Tourism Organization (January 2026) documenting 42,683,600 inbound visitors in 2025 and food-processing benchmarks from the USDA Foreign Agricultural Service (April 2026) confirm rising beverage service demand across Japanese hospitality venues. FMI projects portion-controlled café syrups and domestic craft citrus cordials to drive steady value expansion in Japan through 2036.
USA
Buyer procurement of cordial drink throughout USA is tracking from USD 0.67 billion in 2026 to USD 1.00 billion by 2036, exhibiting a 4.1% CAGR and contributing USD 0.33 billion to national market value. FMI believes United States demand is fueled by bar and restaurant procurement of lime cordials and specialty fruit concentrates for craft cocktails and dirty sodas, governed by mandatory added-sugar labeling from the US Food and Drug Administration (2025) and corroborated by global stevia reformulation. In March 2025, Monin Americas (March 2025) launched its Yuzu Pineapple Syrup across North American foodservice and online channels, complementing Keurig Dr Pepper (2026) distribution of Rose's lime and grenadine mixers. FMI expects specialty coffee chain menu rotation and home cocktail preparation to sustain United States cordial revenue growth through 2036.
Competitive Environment and Notable Companies
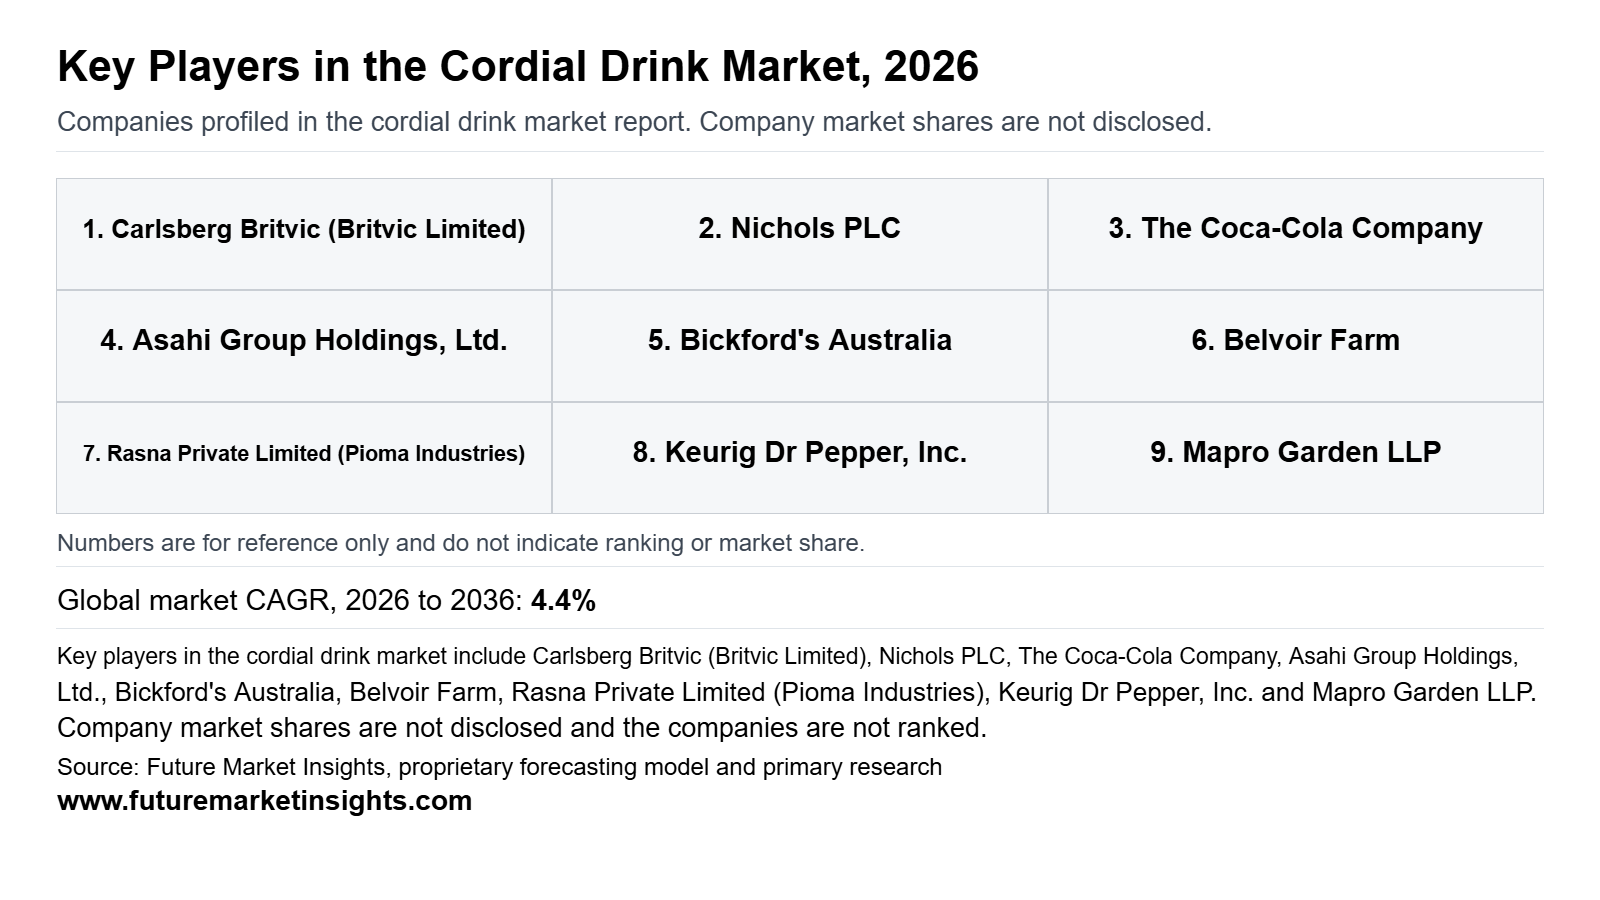
Competition in the global cordial drink market combines household dilutable squash leaders including Carlsberg Britvic (Britvic Limited) and Nichols PLC with multi-brand beverage groups such as The Coca-Cola Company and Asahi Group Holdings, Ltd., as well as regional fruit and foodservice specialists including Bickford's Australia, Belvoir Farm, Mapro Garden LLP, and Monin Incorporated.
How Are Companies Positioned in the Cordial Drink Market?
Carlsberg Britvic (Robinsons, Maguary, Dafruta) and Nichols PLC (Vimto) lead mass-grocery household squash volume through single-concentrate and vitamin-fortified double-concentrate ranges. Bickford's Australia and Belvoir Farm occupy premium glass-bottled fruit and floral cordial tiers, Mapro Garden LLP and Rasna Private Limited supply Indian fruit squashes and sharbats, Keurig Dr Pepper, Inc. markets Rose's cocktail cordials, The Coca-Cola Company licenses Mazoe concentrates in Africa perSchweppes Holdings Africa Limited (2025), and Monin Incorporated leads professional foodservice dosing syrups.
What Matters When a Buyer Selects a Cordial Drink Supplier?
Supermarket buyers and foodservice procurement managers evaluate cordial suppliers on diluted taste stability, added-sugar tax compliance per prepared 100 ml serving, bottle yield clarity, and shelf-life stability after opening. In jurisdictions enforcing post-dilution sugar levies such as the United Kingdom underHM Revenue & Customs (October 2026) and India under Food Safety and Standards Authority of India (September 2025), suppliers must provide audited brix and fruit-juice percentages and clear dilution ratios.
Which Capabilities Distinguish Product Offers?
Leading suppliers differentiate through sugar-reduction formulation and micronutrient fortification paired with orchard-to-bottle fruit traceability.Nichols PLC (2025) fortifies its Vimto Wonderfuel squash with vitamins C and D plus iron and zinc; MONIN India (March 2025) formulates its PURE concentrate line with zero added sugar or artificial sweeteners; and Bickford's Group (July 2025) blends up to 35% real fruit juice in its traditional cordials and a unified No Added Sugar range.
How Does Geographic Reach Affect Competition?
Corporate M&A and licensing agreements actively shape regional market access.Carlsberg Group (January 2025) integrated Britvic into Carlsberg Britvic in the UK in January 2025 before agreeing in November 2026 to divest Britvic Brazil to Grupo JAV per Carlsberg Group (November 2026). Meanwhile, Asahi Beverages (2025) anchors Australian grocery shelves with Cottee's and Schweppes cordials, while Nichols PLC and Bickford's Group export across the Middle East and Europe.
| Verified Company Evidence (2025 to 2026) | Commercial Effect | Buyer Action |
|---|---|---|
| 9 March 2026 & 31 March 2026: Carlsberg Britvic launched Robinsons Fruit Creations Strawberry and Cherry Lime (1L) and limited-edition Double Concentrate flavours across UK grocery and convenience channels (Carlsberg Britvic, March 2026). | Drives adult squash trade-up and high-margin double-concentrate turn across UK retailers. | Allocate eye-level grocery and convenience facings to double-concentrate and adult fruit creations. |
| 5 March 2025 & 25 March 2025: MONIN India launched its zero-added-sugar PURE concentrate range and Monin Americas debuted Yuzu Pineapple Syrup from its Portuguese orchard (MONIN India, March 2025; Monin Americas, March 2025). | Expands clean-label, zero-sugar and traceable fruit dosing options for cafés, bars, and QSR chains. | Trial zero-added-sugar PURE concentrates in low-calorie mocktail and iced-tea menu programs. |
| July 2025: Bickford's Group consolidated its reduced-sugar portfolio into the reformulated Bickford's No Added Sugar Cordial range in 750 ml glass bottles (Bickford's Group, July 2025). | Streamlines health-conscious retail SKU counts into a single zero-added-sugar cordial platform. | Replace legacy diet and sugar-free cordial SKUs with unified No Added Sugar 750 ml facings. |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
| Company | Core Positioning | Verified Activity & Source Attribution |
|---|---|---|
| Carlsberg Britvic (Britvic Limited) | UK household squash and cordial leader (Robinsons, Robinsons Fruit & Barley, Fruit Creations) | Acquired by Carlsberg Group in Jan 2025; launched Robinsons Fruit Creations and Double Concentrate extensions in March 2026 (Carlsberg Britvic, March 2026). |
| Nichols PLC | UK and international Vimto squash and cordial portfolio | Launched Vimto Wonderfuel functional squash in 2025, reported 15.9% H1 2025 operating margin, and released Vimto Fans' Edition in Feb 2026 (Nichols PLC, July 2025; February 2026). |
| Bickford's Australia (Bickford's Group) | Australian traditional fruit cordials and No Added Sugar 750 ml glass range | Launched reformulated No Added Sugar Cordial range across Lime, Lemon, Raspberry, and Tropical in mid-2025 (Bickford's Group, July 2025). |
| Monin Incorporated | Global foodservice and retail beverage syrups and zero-sugar concentrates | Launched MONIN PURE zero-added-sugar range in India (March 2025) and sustainable-orchard Yuzu Pineapple Syrup in the US (Monin Americas, March 2025). |
| Belvoir Farm | UK premium elderflower, ginger, and no-added-sugar fruit and floral cordials | Completed 2025 brand refresh across its No Added Sugar and organic cordial lines in 500 ml glass bottles (Belvoir Farm, 2025). |
| Asahi Group Holdings, Ltd. (Asahi Beverages) | Australian Cottee's household cordials and Schweppes mixer cordials | Transitioned Australian plastic soft-drink and cordial bottle lines to 100% recycled PET by August 2026 (Asahi Beverages, August 2026). |
| The Coca-Cola Company | Licensed Mazoe orange and fruit crushes/cordials in Southern Africa | Produces and distributes Mazoe concentrated fruit cordials via Schweppes Holdings Africa (Schweppes Holdings Africa Limited, 2025). |
| Keurig Dr Pepper, Inc. | United States Rose's lime cordial and grenadine mixer concentrates | Maintains Rose's cordial distribution across North American retail and hospitality channels (Keurig Dr Pepper, 2026). |
| Mapro Garden LLP | Indian fruit squashes, crushes, and spiced jeera masala cordials | Markets Santra Mantra Orange, Kala Khatta, and Lemon Ginger squashes across Indian retail and D2C storefronts (Mapro Garden LLP, 2026). |
| Rasna Private Limited (Pioma Industries) | Indian mass-market fruit squash and bottled syrup concentrates | Supplies Kool Drink and fruit squash concentrates across Indian household grocery channels (Rasna Private Limited, 2025). |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
Key takeaways
- Valued at USD 4.20 billion in 2026, on course for USD 6.40 billion by 2036.
- The decade adds USD 2.20 billion in new value at a 4.4% CAGR.
- The product segment is led by Fruit cordials at 49.0% of 2026 revenue.
- 42.0% of distribution channel revenue goes to Supermarkets & Hypermarkets in 2026.
- China grows fastest at 5.3% CAGR, ahead of India at 5.0%.
Cordial Drink Market Report Scope and Research Methodology
FMI sizes the global cordial drink market using a hybrid bottom-up and top-down modeling methodology that cross-checks grocery scanner sales and foodservice syrup procurement volumes against producer financial filings and national beverage production registries. Market valuation captures packaged nonalcoholic liquid cordials and flavor squash concentrates at the point of concentrate sale across retail and foodservice channels. Ready-to-drink beverages, powdered drink mixes, alcoholic cordials or liqueurs, and downstream prepared-drink bar receipts are excluded to prevent double counting, ensuring all segment and country figures sum to the global total from 2025 to 2036.
| Coverage Field | Report Scope |
|---|---|
| Market definition | Revenue from packaged nonalcoholic liquid cordials and flavor squash concentrates sold for dilution into beverages. |
| Product segmentation | Fruit cordials; Vegetable cordials; Herbs & spices cordials (Other Segment Combined). |
| Distribution channels | Supermarkets & Hypermarkets; Convenience Stores; Foodservice/HoReCa; Online (Other Segment Combined). |
| Concentrate formats | Single-concentrate, double-concentrate, ultra-concentrate mini packs, and 750 ml to 1L glass or PET dosing bottles. |
| Formulation types | Standard sugar-sweetened, no-added-sugar (stevia/sucralose), vitamin-fortified, and organic botanical cordials. |
| Exclusions | Ready-to-drink (RTD) beverages, dry powdered drink mixes, alcoholic cordials and liqueurs, dessert toppings, and prepared drink receipts. |
| Quantitative units | USD billion for global and national market valuation. |
| Base and historical years | 2025 (Historical) and 2026 (Estimated Base Year). |
| Forecast period | 2026 to 2036 (10-year projection window). |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa. |
| Profiled countries | China, India, UK, Brazil, Germany, Japan, and USA (plus extended regional taxonomy across Canada, Mexico, Argentina, Chile, France, Italy, Spain, Benelux, Nordics, Poland, Czech Republic, Romania, Hungary, South Korea, ASEAN, Australia and New Zealand, GCC Countries, South Africa, Turkiye, and Israel). |
| Companies profiled | Carlsberg Britvic (Britvic Limited), Nichols PLC, The Coca-Cola Company, Asahi Group Holdings, Ltd., Bickford's Australia, Belvoir Farm, Rasna Private Limited (Pioma Industries), Keurig Dr Pepper, Inc., Mapro Garden LLP, and Monin Incorporated. |
| Primary research inputs | Interviews with supermarket beverage buyers, HoReCa beverage directors, concentrate formulators, and regional bottlers. |
| Secondary research sources | Official government and regulatory portals (HMRC, US FDA, FSSAI India, Anvisa Brazil, European Commission, NBS China, Destatis, USDA FAS) and corporate disclosures. |
Source: Future Market Insights analysis of the cordial drink market, 2026.
Research Sources and Bibliography
- Agencia Nacional de Vigilancia Sanitaria. (2020, October 22).Rotulagem nutricional de alimentos embalados. https://www.gov.br/anvisa/pt-br/assuntos/alimentos/rotulagem/rotulagem-nutricional/
- Asahi Beverages. (2025).Water and Cordial Brand Portfolio: Cottee's and Schweppes. https://www.asahi.com.au/brands/water-cordial
- Asahi Beverages. (2026, August 19).Asahi switches to recycled material for all plastic soft drink bottles in major sustainability milestone. https://www.asahibeverages.com/news-and-media/asahi-switches-to-recycled-material-for-all-plastic-soft-drink-bottles-in-major-sustainability-milestone
- Belvoir Farm. (2025).About Us: 2025 Brand Refresh Across No Added Sugar and Cordial Range. https://belvoirfarm.co.uk/about-us/
- Bickford's Australia. (2025, June).No Added Sugar Lemon Juice Cordial 750mL Specifications. https://www.bickfords.net/products/cordial/no-added-sugar-lemon/
- Bickford's Group. (2025, July).Bickford's International Product Portfolio 2025: Traditional and No Added Sugar Cordials. https://www.bickfordsgroup.com/wp-content/uploads/2025/07/Bickfords-International-Product-Portfolio-2025.pdf
- Carlsberg Britvic. (2025, October 14).Robinsons and Universal Pictures defy gravity again for Wicked: For Good. https://help.carlsbergbritvic.co.uk/hc/en-gb/articles/31022829569437-14-10-25-Robinsons-and-Universal-Pictures-defy-gravity-again-for-Wicked-For-Good-with-Fruit-Shoot-joining-the-magic
- Carlsberg Britvic. (2026, March 9).Robinsons dials up adult squash occasions with new Fruit Creations flavour. https://carlsbergbritvic.co.uk/newsroom-and-tcs/robinsons-dials-up-adult-squash-occasions-with-new-fruit-creations-flavour/
- Carlsberg Britvic. (2026, March 31).Discover a galaxy of refreshment: Robinsons joins forces with Star Wars The Mandalorian and Grogu. https://carlsbergbritvic.co.uk/newsroom-and-tcs/discover-a-galaxy-of-refreshment-robinsons-joins-forces-with-star-wars-the-mandalorian-and-grogu/
- Carlsberg Group. (2025, January 17).Carlsberg Group completes acquisition of Britvic plc. https://www.carlsberggroup.com/newsroom/carlsberg-group-completes-acquisition-of-britvic-plc/
- Carlsberg Group. (2026, November 9).Carlsberg Group Announces Agreement to Sell Britvic Brazil. https://www.carlsberggroup.com/newsroom/carlsberg-group-announces-agreement-to-sell-britvic-brazil/
- European Commission. (2026, August 11).New EU rules on packaging enter into application. https://environment.ec.europa.eu/news/new-eu-rules-packaging-enter-application-2026-08-11_en
- Food Safety and Standards Authority of India. (2025, September 9).Food Safety and Standards (Labelling and Display) Regulations 2020 Compendium Version VIII. https://fssai.gov.in/docs/food-law/regulations/Comp_Labelling%20Display_Version%20VIII_09_09_2025.pdf
- HM Revenue & Customs. (2026, October 28).Soft Drink Industry Levy changes. https://www.gov.uk/government/publications/changes-to-the-soft-drinks-industry-levy/soft-drink-industry-levy-changes
- Japan National Tourism Organization. (2026, January 21).Visitor Arrivals for December 2025 and Full Year 2025. https://www.jnto.go.jp/news/press/20260121_monthly.html
- Keurig Dr Pepper. (2026).Brands Portfolio: Rose's Mixers and Beverage Concentrates. https://www.keurigdrpepper.com/brands/
- Mapro Garden LLP. (2026).Mapro Squashes, Crushes and Jeera Masala Cordial Collection. https://www.mapro.com/collections/squash
- Monin Americas. (2025, March 25).Monin Debuts First-Ever Syrup Made with Fruit from the Company's Own Sustainable Orchard. https://monin.us/blogs/news/monin-debuts-syrup-from-sustainable-orchard
- MONIN India. (2025, March 5).MONIN Launches PURE Range: 100% Natural Taste with Zero Added Sugar. https://monin.in/blogs/products/monin-launches-pure-range-100-natural-taste
- MONIN India. (2025, March 15).MONIN India at AAHAR 2025: Shaping the Future of India's F&B Industry. https://monin.in/blogs/our-events/monin-india-at-aahar-2025-shaping-the-future-of-india-f-b-industry
- National Bureau of Statistics of China. (2026, January 20).Total Retail Sales of Consumer Goods in December 2025. https://www.stats.gov.cn/english/PressRelease/202601/t20260120_1962354.html
- Nichols PLC. (2025).Vimto: Shaking up the squash category with vitamin fortification and Vimto Wonderfuel. https://www.nicholsplc.co.uk/vimto-shaking-up-the-squash-category-with-vitamin-fortification-2/
- Nichols PLC. (2025, July 31).Nichols announces 2025 Interim Results. https://www.nicholsplc.co.uk/2025-interim-result-2/
- Nichols PLC. (2026, February 18).Vimto celebrates its fans with co-created limited editions. https://www.nicholsplc.co.uk/nichols-launches-vimto-energy-tropical-cooler-targeting-the-convenience-and-wholesale-channels-3-2/
- Rasna Private Limited. (2025).Rasna Kool Drink and Fruit Squash Concentrate Range. https://rasnainternational.com/product-category/kool-drink-range/
- Schweppes Holdings Africa Limited. (2025).Mazoe Story: Concentrated Orange and Fruit Crushes. https://schweppes.co.zw/mazoe-story/
- Statistisches Bundesamt Destatis. (2026, February 19).Gastgewerbeumsatz 2025 real 2.1% niedriger als im Vorjahr. https://www.destatis.de/DE/Presse/Pressemitteilungen/2026/02/PD26_054_45213.html
- US Food and Drug Administration. (2025).Added Sugars on the Nutrition Facts Label. https://www.fda.gov/food/nutrition-facts-label/added-sugars-nutrition-facts-label
- USDA Foreign Agricultural Service. (2026, April 1).Japan: Food Processing Ingredients Annual. https://www.fas.usda.gov/data/gain/2026/04/japan-food-processing-ingredients-annual
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Fruit cordials
- Vegetable cordials
- Herbs & spices cordials
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Convenience Stores
- Foodservice/HoReCa
- Online
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Western Europe
- East Asia
- South Asia and Pacific
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- By Product
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia
- Rest of world aggregate
- By Product
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Carlsberg Britvic (Britvic Limited)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nichols PLC
- Bickford's Australia (Bickford's Group)
- Monin Incorporated
- Belvoir Farm
- Asahi Group Holdings, Ltd. (Asahi Beverages)
- The Coca-Cola Company
- Keurig Dr Pepper, Inc.
- Mapro Garden LLP
- Rasna Private Limited (Pioma Industries)
- Carlsberg Britvic (Britvic Limited)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 4: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 7: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: Western Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 9: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 10: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 11: East Asia Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 12: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: South Asia and Pacific Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 15: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product
- Figure 6: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Distribution Channel
- Figure 9: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 17: North America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 18: North America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 19: North America Market Attractiveness Analysis by Product
- Figure 20: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Distribution Channel
- Figure 23: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 24: Western Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 25: Western Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 26: Western Europe Market Attractiveness Analysis by Product
- Figure 27: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 28: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 29: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 30: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 31: East Asia Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 32: East Asia Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 33: East Asia Market Attractiveness Analysis by Product
- Figure 34: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 35: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 36: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 37: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 38: South Asia and Pacific Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 39: South Asia and Pacific Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 40: South Asia and Pacific Market Attractiveness Analysis by Product
- Figure 41: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 44: Global Market - Tier Structure Analysis
- Figure 45: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the cordial drink market in 2026?
Future Market Insights estimates the global cordial drink market valuation at USD 4.20 billion in 2026, rising from USD 4.02 billion in 2025.
What CAGR is projected for the cordial drink market from 2026 to 2036?
FMI projects the global cordial drink market to grow at a4.4% CAGR from 2026 to 2036, reaching USD 6.40 billion by 2036 and adding USD 2.20 billion in new revenue.
Which product segment leads the cordial drink market in 2026?
Fruit cordials lead the product segment with 49.0% of global revenue in 2026.
Which distribution channel leads cordial drink sales in 2026?
Supermarkets & Hypermarkets lead distribution channel sales with a 42.0% share in 2026.
Which country is the largest cordial drink market globally?
United Kingdom is the largest national cordial drink market globally, generating USD 0.92 billion in 2026 (21.9% global share) and projected to reach USD 1.42 billion by 2036.
Which countries record the fastest cordial drink growth through 2036?
China records the fastest national growth rate at a 5.3% CAGR from 2026 to 2036, followed by India at a 5.0% CAGR and the United Kingdom at 4.4%.
How does the UK Soft Drinks Industry Levy apply to cordial drinks?
HM Revenue & Customs assesses concentrated and dilutable soft drinks on their prepared post-dilution sugar content, with the lower levy threshold scheduled to drop to 4.5 grams of sugar per 100 milliliters on 1 January 2028.
Which companies are profiled in the cordial drink market?
Profiled companies in the cordial drink market include Carlsberg Britvic (Britvic Limited), Nichols PLC, The Coca-Cola Company, Asahi Group Holdings, Ltd., Bickford's Australia, Belvoir Farm, Rasna Private Limited (Pioma Industries), Keurig Dr Pepper, Inc., Mapro Garden LLP, and Monin Incorporated.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
