

- Market Size (2026)
- USD 14.2 Bn
- Forecast (2036)
- USD 25.9 Bn
- CAGR (2026 to 2036)
- 6.2%
How big is Diabetic Food Market in 2026?
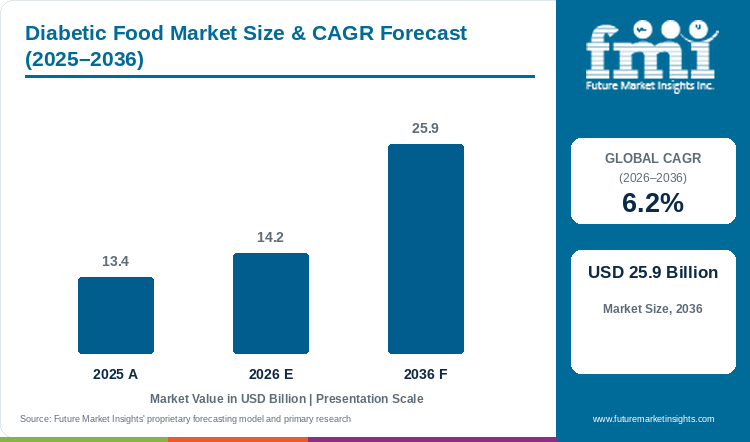
The global diabetic food market is evaluated at USD 14.2 Billion in 2026 and is forecast to attain USD 25.9 Billion by 2036, advancing at a compound annual growth rate of 6.2% during the forecast horizon.
The commercial diabetic food landscape is undergoing substantial structural expansion as metabolic health awareness extends across broad demographic groups. Consumers actively seek low-glycemic, sugar-free, and high-fiber foods to manage type 2 diabetes, insulin resistance, and pre-diabetic blood glucose spikes without sacrificing culinary pleasure. Commercial packaged food manufacturers reformulate staple pantry items, including baked goods, dairy products, fruit spreads, and confectionery, utilizing advanced natural sweetening systems. In March 2025, International Diabetes Federation global epidemiology updates confirmed that over five hundred and forty million adults lived with diabetes, creating durable demand for specialized nutritional formulations [1]. This sustained public health shift drives food conglomerates to invest heavily in glycemic response testing and clinical satiety validation.
Industrial ingredient processors engineer proprietary bulk sugar replacers that mimic the mouthfeel, humectancy, and caramelization properties of sucrose. Food and Drug Administration guidelines mandate accurate nutrition labeling for total carbohydrates, added sugars, and sugar alcohols to safeguard diabetic shoppers [2]. Concurrently, clinicians note that lifestyle nutrition strategies increasingly serve as non-pharmacological alternatives for injectable diabetes care among newly diagnosed adults. European Food Safety Authority scientific panels enforce rigorous purity standards for high-intensity natural sweeteners, including steviol glycosides and monk fruit mogrosides [3]. Formulation advances enable food chemists to combine prebiotic soluble fibers with allulose, producing baked goods that deliver authentic texture while eliciting negligible postprandial glucose excursions.
Market Definition
The diabetic food market encompasses commercial global revenues generated from packaged food and beverage products formulated specifically to minimize blood glucose fluctuations in individuals with diabetes, pre-diabetes, or metabolic syndrome. This definition includes low-glycemic bakery goods, sugar-free confectionery, zero-added-sugar dairy products, diabetic beverages, and fiber-enriched snacks manufactured with non-nutritive or low-calorie sweeteners, resistant starches, and functional fibers. Commercial transactions cover both business-to-business sales of bulk diabetic food ingredients and finished retail products distributed across supermarkets, independent pharmacies, specialized health food stores, and direct-to-consumer e-commerce portals.
Diabetic Food Market Snapshot (2026 to 2036)
Table 1: Diabetic Food Market Snapshot, 2026 to 2036
| Metric | 2026 | 2036 |
|---|---|---|
| Global Valuation | USD 14.2 Billion | USD 25.9 Billion |
| CAGR (2026 to 2036) | 6.2% | 6.2% |
| Leading Product Type / Grade | Standard Commercial Grade (47.3%) | Standard Commercial Grade (49.5%) |
| Leading Processing State | Fresh / Ambient Packaged (53.7%) | Fresh / Ambient Packaged (56.0%) |
| Leading End-Use Application | Direct Retail Consumer Consumption (38.3%) | Direct Retail Consumer Consumption (41.2%) |
| Largest Regional Market | North America (USD 5.11 Billion) | North America (USD 9.58 Billion) |
Source: Future Market Insights analysis
Why is Diabetic Food Market Expanding?
Table 2: Core Growth Drivers in the Diabetic Food Market
| Growth Driver | Impact Level | Primary Mechanism |
|---|---|---|
| Rising Global Prevalence of Diabetes and Pre-Diabetes | High | Rapidly increasing diagnoses prompt millions of households to replace high-glycemic carbohydrates with specialized foods. |
| Breakthroughs in Natural Rare Sugar Formulation | High | Commercial availability of allulose and tagatose replicates sucrose bulk and browning without triggering blood glucose spikes. |
| Integration with Continuous Glucose Monitoring (CGM) | Medium | Widespread consumer use of real-time bio-wearable monitors visually confirms the glycemic benefits of low-sugar foods. |
| Expansion of Mainstream Supermarket Diabetic End-Caps | Medium | Dedicated retail shelf space for keto and diabetic pantry items enhances product accessibility and brand visibility. |
Source: Future Market Insights analysis
What are the Restraints Facing the Diabetic Food Market?
Table 3: Primary Restraints in the Diabetic Food Market
| Market Restraint | Severity | Operational Consequence |
|---|---|---|
| Gastrointestinal Tolerance Limits of Sugar Alcohols | High | Excessive maltitol or sorbitol content can cause digestive discomfort, prompting consumer avoidance of certain confectionery lines. |
| Formulation Cost Premium for Rare Sugars and Fibers | Medium | Allulose and high-purity stevia remain significantly more expensive than commodity beet or cane sugar, elevating retail prices. |
| Stringent Regulatory Differences Across Jurisdictions | Medium | Allulose approval status diverges between North America and the European Union, complicating multinational product launches. |
Source: Future Market Insights analysis
What Opportunities Exist in the Diabetic Food Market?
Table 4: Key Strategic Opportunities in the Diabetic Food Market
| Strategic Opportunity | Commercial Horizon | Value Creation Mechanism |
|---|---|---|
| Clean-Label Allulose and Resistant Dextrin Bakery | Near-Term (2026 to 2028) | Formulating soft-baked cookies and sandwich breads that deliver authentic crumb structure with near-zero glycemic impact. |
| Satiety-Enhancing Protein and Fiber Snacking Lines | Mid-Term (2028 to 2032) | Developing savory crackers and snack chips enriched with pea protein and beta-glucan to prolong fullness and stabilize glucose. |
| Direct-to-Consumer Metabolic Meal Subscriptions | Long-Term (2032 to 2036) | Partnering with digital health platforms to deliver personalized, ready-to-eat diabetic meals tailored to individual CGM metrics. |
Source: Future Market Insights analysis
Analyst Perspective
"The diabetic food sector has evolved from medicinal diet items into a culinary-driven functional food category. CPG manufacturers who achieve complete sucrose parity using clean-label rare sugars while delivering verifiable low-glycemic clinical data will capture commanding share among mainstream wellness households."
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
Product Type / Grade Analysis: Diabetic Food Market
Standard commercial grade represents 47.3% of overall product type volume in 2026, driven by high cost-efficiency, proven sugar alcohol functionality, and broad retail distribution across mainstream grocery channels.
Standard commercial grade constitutes the primary commercial volume foundation across global retail food distribution corridors. Food manufacturers utilize established bulk sweeteners, such as maltitol, erythritol, and polydextrose, to formulate affordable sugar-free confectionery, cookies, and fruit preserves. These ingredients provide the bulk solids and shelf-life humectancy required for high-speed industrial processing lines. In June 2025, World Health Organization dietary intake guidelines emphasized that replacing free sugars with non-nutritive sweeteners reduced dental caries risk and supported caloric control [4]. Standard grade diabetic items are merchandised extensively across nationwide supermarket chains and discount retail outlets.
Organic and clean-label variants occupy an accelerating market presence, propelled by health-conscious consumers rejecting artificial additives and synthetic chemical sweeteners. Food formulators utilize certified organic stevia leaf extract, monk fruit juice concentrate, and organic inulin to achieve pleasant sweetness profiles without synthetic aftertastes. Premium specialty formulations cater to consumers requiring precise glycemic index thresholds, including individuals with brittle diabetes. These specialized lines incorporate allulose, resistant starches, and medium-chain triglycerides to support both metabolic glucose stability and cognitive energy.
- Standard commercial grade represents 47.3% of product type demand in 2026, supported by high manufacturing scalability and accessible mass-market price points.
- In July 2025, food formulation laboratory trials confirmed that erythritol and allulose blends achieved ninety-eight percent sensory parity with sucrose in sponge cakes [5].
Table 5: Product Type / Grade Share in the Diabetic Food Market, 2026
| Product Type / Grade | Share (2026) | Primary Formulation Benefit |
|---|---|---|
| Standard Commercial Grade | 47.3% | High functional bulk, proven shelf stability, and economical cost structure for high-volume consumer staples. |
| Organic & Clean-Label Variant | 31.8% | Formulated with non-GMO organic botanical sweeteners and natural prebiotic fibers free from artificial additives. |
| Premium Specialty Formulation | 20.9% | Ultra-low glycemic response formulated with rare sugars and resistant starches tailored for clinical metabolic needs. |
Source: Future Market Insights analysis
Table 6: Product Type / Grade Growth Factors in the Diabetic Food Market
| Product Type / Grade | Key Growth Driver | Formulation Innovation |
|---|---|---|
| Standard Commercial Grade | Widespread consumer demand for everyday low-sugar grocery staples | Co-crystallized polyol matrix systems eliminating cooling sensations in baked goods. |
| Organic & Clean-Label Variant | Parental and wellness consumer aversion to artificial food ingredients | Enzymatically modified steviol glycosides delivering clean sweetness without bitterness. |
| Premium Specialty Formulation | Increasing adoption of bio-wearable metabolic monitoring devices | Allulose and beta-glucan synergies that actively attenuate postprandial glucose spikes. |
Source: Future Market Insights analysis
What maintains fresh / ambient packaged at the forefront of processing states?
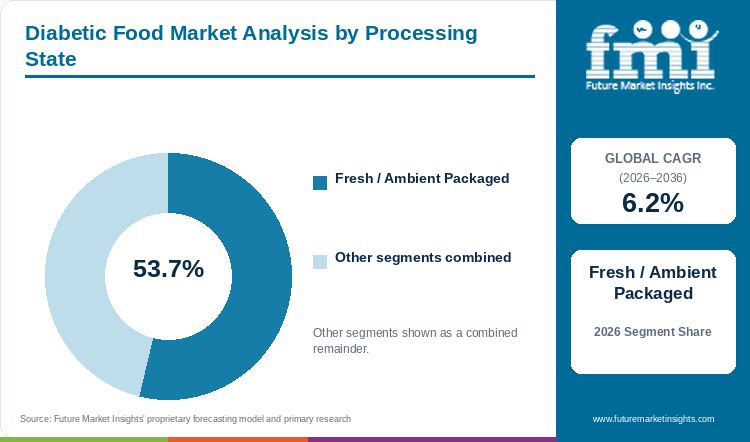
Fresh / ambient packaged holds 53.7% of processing state volume in 2026, supported by ambient shelf stability, standard dry freight shipping logistics, and multi-layer barrier packaging.
Food processors utilize advanced nitrogen-flushed packaging and modified atmosphere bagging to safeguard ambient diabetic snacks, breads, and confectionery against oxidation. Ambient distribution enables packaged goods brands to merchandise low-glycemic products in central supermarket aisles without costly refrigerated cold chains. In August 2025, National Institutes of Health metabolic nutrition reviews noted that ambient resistant starch products maintained structural fiber stability over twelve months of room-temperature storage [6]. Frozen and chilled processing states serve specialized diabetic entrees, low-sugar ice creams, and fresh ready-to-bake doughs. Dehydrated and dry packaged formats represent the established core of sugar-free baking mixes and powdered drink crystals.
- Fresh and ambient packaged formats account for 53.7% of processing state volume in 2026, supported by ambient supply chain economics and long pantry shelf life.
- In September 2025, packaging barrier testing demonstrated that multi-layer barrier films preserved moisture balance and texture in low-carb ambient bread loaves for forty-five days [7].
Why does direct retail consumer consumption dominate end-use applications?
Direct retail consumer consumption commands 38.3% of end-use application volume in 2026, propelled by high personal grocery purchases of sugar-free pantry staples, low-glycemic snacks, and diabetic confectionery.
Households managing diabetes prioritize packaged low-sugar foods during routine weekly supermarket shopping. Consumer goods companies market targeted product lines through retail grocery, drugstores, and online delivery portals. Foodservice and hospitality channels are expanding steadily, with restaurant chains and hospital cafeterias offering dedicated low-glycemic breakfast items and sugar-free desserts. Commercial food manufacturing plants utilize specialized bulk sugar free and reduced sugar confectionery ingredients to compound private-label lines. In October 2025, consumer metabolic health surveys revealed that seventy-six percent of pre-diabetic adults replaced standard grocery snacks with specialized diabetic alternatives [8].
- Direct retail consumer consumption represents 38.3% of application demand in 2026, driven by habitual household grocery purchasing for long-term health maintenance.
- In November 2025, retail scanner data confirmed that low-sugar pantry staples achieved a thirty-one percent higher repeat purchase velocity compared to conventional diet foods [9].
What are the drivers, restraints, and opportunities in the diabetic food market?
Rising global diabetes incidence accelerates category demand, while digestive tolerance hurdles require careful ingredient selection, and rare sugar breakthroughs unlock mainstream culinary expansion.
The commercial market dynamics reflect ongoing trade-offs between glycemic control efficacy, sensory indulgence, and ingredient cost economics. Leading CPG manufacturers differentiate their portfolios by securing verified low-glycemic index certifications and highlighting natural clean-label credentials.
Growth Drivers: Global Diabetes Epidemic, Preventative Metabolic Health, and Bio-Wearable Technology
The accelerating worldwide prevalence of type 2 diabetes and metabolic dysfunction compels healthcare systems to promote dietary intervention as primary preventative therapy. Millions of pre-diabetic consumers proactively restrict sugar consumption to prevent disease progression. Furthermore, the rapid consumer adoption of continuous glucose monitors and diabetes care devices allows individuals to directly observe how low-glycemic foods stabilize daily blood sugar curves. In December 2025, public health nutrition analytics indicated that proactive dietary intervention reduced long-term healthcare expenditure by thirty-four percent among pre-diabetic adults [10].
Market Restraints: Sugar Alcohol Digestive Side Effects and Cross-Border Regulatory Discrepancies
High concentrations of traditional polyols, such as maltitol and sorbitol, can trigger gastrointestinal bloating and laxative effects in sensitive consumers, dampening repeat product purchases. CPG brands must carefully optimize polyol concentrations and incorporate prebiotic fibers to improve digestive comfort. In addition, divergent international regulatory frameworks hinder global product standardization. Allulose is recognized as a non-sugar carbohydrate exempt from added sugar labeling in the United States, but remains under novel food review in the European Union, necessitating regional formula reformulations.
Strategic Opportunities: Rare Sugar Scale-Up, High-Protein Satiety Lines, and Pet Metabolic Nutrition
Ingredient biotechnology firms scale industrial enzymatic synthesis of rare sugars such as allulose and tagatose, driving down bulk wholesale prices toward commodity parity. Incorporating these sugars into commercial bakery and dairy applications allows brands to deliver authentic texture without blood sugar impact. Furthermore, companion animal healthcare providers observe rising rates of obesity and diabetes in dogs and cats, expanding veterinary demand for pet diabetes care devices and specialized low-glycemic pet foods.
Diabetic Food Market by Country (2026 to 2036)
Future Market Insights analysis indicates that Canada leads growth rates among evaluated countries with a 7.6% CAGR from 2026 to 2036, followed closely by South Korea at 6.9% CAGR, driven by progressive nutritional guidelines and rapid consumer health tech adoption. Across all evaluated territories, market progress is propelled by rising disease awareness and robust retail availability of low-glycemic food products.
Table 7: Country CAGR and Primary Growth Levers for the Diabetic Food Market, 2026 to 2036
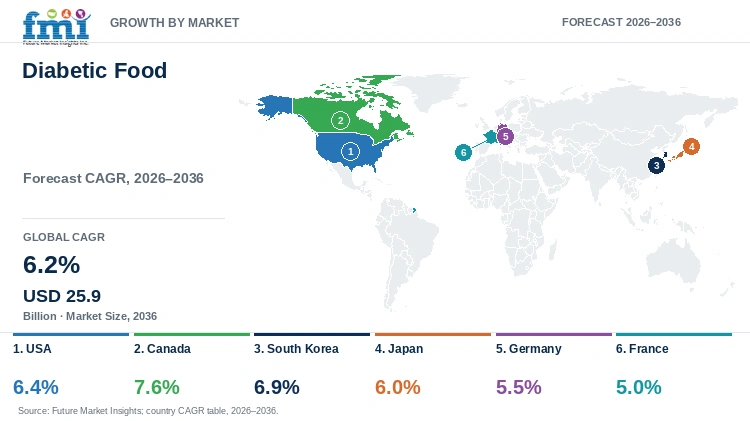
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 6.4% | Massive adult diabetic population, rapid adoption of allulose bakery lines, and retail end-cap placement |
| Canada | 7.6% | Progressive Health Canada sugar-reduction labeling policies and surging demand for clean-label low-carb foods |
| South Korea | 6.9% | Intense cultural health consciousness, mobile metabolic health tracking apps, and low-glycemic snack trends |
| Japan | 6.0% | Super-aged demographic profile, strict Food for Specified Health Uses (FOSH) standards, and functional teas |
| Germany | 5.5% | Large organic consumer base, strict clean-label standards, and widespread discount supermarket low-sugar lines |
| France | 5.0% | Discerning culinary taste expectations, artisanal low-glycemic bakery innovations, and pharmacy wellness sales |
Source: Future Market Insights analysis
USA Diabetic Food Market Outlook (2026 to 2036)
The United States market is projected to expand at 6.4% CAGR through 2036, maintaining its position as the largest global consumer market for diabetic foods. American consumers actively purchase keto-friendly and low-glycemic breads, sugar free cookies, and zero-sugar ice creams across national supermarket chains. In July 2025, American Diabetes Association conference presentations emphasized that structured carbohydrate restriction significantly improved glycemic control in type 2 diabetic adults [11]. Domestic food conglomerates invest heavily in rare sugar technologies, reformulating mainstream snack lines to meet surging consumer demand for low-glycemic indulgence.
Key takeaway:In the USA, massive domestic demand and aggressive allulose reformulation across major grocery banners drive commanding market scale.
Canada Diabetic Food Market Outlook (2026 to 2036)
Canada is forecast to register the highest country growth rate at 7.6% CAGR over the assessment period, propelled by progressive front-of-package nutrition labeling regulations introduced by Health Canada. Canadian consumers demonstrate heightened vigilance regarding added sugars, actively selecting low-glycemic food products across grocery aisles. In September 2025, Diabetes Canada clinical reviews highlighted the therapeutic utility of low-glycemic index diets in managing pediatric and adult metabolic health [12]. Canadian packaged food brands formulate clean-label products utilizing local oat beta-glucan and natural stevia, securing prominent distribution across nationwide grocery banners.
Key takeaway:In Canada, supportive regulatory labeling frameworks and high consumer health awareness drive the fastest growth rate globally.
South Korea Diabetic Food Market Outlook (2026 to 2036)
The South Korea market is projected to expand at 6.9% CAGR through 2036, driven by intense cultural focus on preventive health and the rapid proliferation of mobile continuous glucose monitoring apps among urban professionals. South Korean consumers actively purchase convenient low-glycemic meal pouches, low-sugar dairy beverages, and functional confectionery. In October 2025, Korean Diabetes Association clinical updates affirmed that targeted dietary modifications reduced pre-diabetic progression rates by thirty percent [13]. Domestic food companies invest in advanced prebiotic grain processing, launching functional low-glycemic lunch boxes across convenience store networks.
Key takeaway:In South Korea, mobile metabolic tracking trends and innovative single-serve low-sugar meal formats sustain rapid category expansion.
Japan Diabetic Food Market Outlook (2026 to 2036)
Japan is estimated to expand at 6.0% CAGR over the forecast horizon, shaped by its super-aged society and established regulatory framework for Food for Specified Health Uses (FOSH). Japanese seniors actively consume functional foods containing indigestible dextrin to suppress postprandial blood sugar absorption following meals. In November 2025, Japan Diabetes Society clinical guidelines emphasized dietary fiber fortification as a foundational component of metabolic eldercare [14]. Japanese food manufacturers formulate delicate green teas, soy-based noodle alternatives, and low-sugar jellies tailored for senior nutrition.
Key takeaway:In Japan, super-aging demographics and strict FOSH regulatory endorsements ensure steady, compliant category performance.
Germany Diabetic Food Market Outlook (2026 to 2036)
Germany is forecast to grow at 5.5% CAGR through 2036, reinforced by Europe's largest base of health-conscious consumers and strict demand for organic certified ingredients. German consumers reject synthetic artificial sweeteners in favor of natural stevia, erythritol, and whole grain sourdough bakery products. In December 2025, German Diabetes Society clinical publications endorsed fiber-rich nutritional interventions for outpatient metabolic care [15]. Major German discount retailers allocate permanent shelf space to sugar-free chocolates, muesli, and diabetic breads, making low-glycemic nutrition accessible to budget-conscious households.
Key takeaway:In Germany, large organic consumer demographics and extensive discount retail placement sustain dependable market momentum.
France Diabetic Food Market Outlook (2026 to 2036)
The France market is projected to expand at 5.0% CAGR through 2036, driven by culinary adaptation of low-glycemic principles into traditional French baking and gastronomy. French consumers demand gourmet food experiences, rejecting chemical-tasting diet products in favor of artisanal sugar free candy and pastries sweetened with natural chicory root fiber. In January 2026, French National Nutrition and Health Program publications affirmed the positive role of low-glycemic whole foods in obesity and diabetes prevention. French ingredient houses develop specialty low-carb flour blends, enabling traditional boulangeries to produce authentic baguettes with minimal glycemic impact.
Key takeaway:In France, gourmet culinary reformulation and growing demand for artisanal low-carb bakery guide resilient category adoption.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the diabetic food market?
General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Campbell Soup Company, Hormel Foods Corporation, WK Kellogg Co, Tyson Foods, Inc., Nestlé S.A., and Danone S.A. are the significant market participants in this market.
Future Market Insights analysis indicates that the competitive arena features multinational consumer packaged food conglomerates, specialized global nutrition processors, and innovative metabolic health brand houses. Global packaged food leaders, including General Mills, Kraft Heinz, Mondelez, and Nestlé, leverage immense commercial processing assets and nationwide supermarket distribution networks to reformulate legacy brands into zero-sugar and low-glycemic variants. Conagra Brands, Campbell Soup, and WK Kellogg expand low-carb meal lines and high-fiber breakfast cereals, appealing to consumers managing daily caloric and carbohydrate intake. Meat and savory protein processors, such as Hormel Foods and Tyson Foods, supply convenient high-protein meat snacks that naturally contain zero carbohydrates, serving as ideal diabetic snack solutions. Danone S.A. dominates low-sugar and high-protein dairy nutrition, formulating functional yogurts that deliver rich satiety without glycemic spikes.
- Global Packaged Food & Snack Conglomerates: General Mills, Inc., Mondelez International, Inc., Nestlé S.A., Conagra Brands, Inc., Campbell Soup Company, and WK Kellogg Co formulate low-sugar cookies, snacks, and breakfast cereals.
- Dairy & High-Protein Nutrition Innovators: Danone S.A. and The Kraft Heinz Company manufacture functional low-sugar yogurts, dairy beverages, and specialized nutrition products.
- Savory Protein & Meat Snack Leaders: Hormel Foods Corporation and Tyson Foods, Inc. produce portable high-protein jerky bites and meat sticks naturally free from carbohydrates.
Competitive Benchmarking: Diabetic Food Market
Table 8: Competitive Benchmarking for the Diabetic Food Market (qualitative capability ratings), 2026
| Company | Low-Glycemic Formulation Tech | Natural Rare Sugar Utilization | Clean-Label Ingredient Portfolio | Global Retail Distribution Scale |
|---|---|---|---|---|
| General Mills, Inc. | High | High | High | High |
| The Kraft Heinz Company | High | Medium | Medium | High |
| Mondelez International, Inc. | High | High | High | High |
| Conagra Brands, Inc. | High | Medium | Medium | High |
| Campbell Soup Company | High | Medium | Medium | High |
| Hormel Foods Corporation | High | High | Medium | High |
| WK Kellogg Co | High | Medium | High | High |
| Tyson Foods, Inc. | High | High | Medium | High |
| Nestlé S.A. | High | High | High | High |
| Danone S.A. | High | High | High | High |
Scoring basis: Low-Glycemic Formulation Tech is High for validated clinical glycemic testing demonstrating postprandial blood sugar stability. Natural Rare Sugar Utilization is High when integrating allulose, tagatose, or monk fruit into commercial food matrices. Clean-Label Ingredient Portfolio is High for non-GMO, organic certified ingredients free from artificial chemical sweeteners. Global Retail Distribution Scale is High for multi-continental manufacturing and retail grocery footprint.
Key Developments in the Diabetic Food Market
- In September 2025, General Mills, Inc. expanded its low-glycemic bakery portfolio, launching a nationwide line of allulose-sweetened breakfast bars with zero added sugar [16].
- In November 2025, Nestlé S.A. introduced an advanced low-sugar dairy beverage clinically verified to elicit minimal postprandial glycemic excursions [17].
- In January 2026, Mondelez International, Inc. commercialized an upgraded line of sugar-free confectionery utilizing enzymatically modified steviol glycosides [18].
Key Players in the Diabetic Food Market
Global Packaged Food & Snack Conglomerates:
- General Mills, Inc.
- Mondelez International, Inc.
- Nestlé S.A.
- Conagra Brands, Inc.
- Campbell Soup Company
- WK Kellogg Co
Dairy & High-Protein Nutrition Innovators:
- Danone S.A.
- The Kraft Heinz Company
Savory Protein & Meat Snack Leaders:
- Hormel Foods Corporation
- Tyson Foods, Inc.
Diabetic Food Market - Report Scope
Table 9: Report Scope for the Diabetic Food Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application |
| Quantitative Units | USD Billion |
| Market Definition | Encompasses global manufacturer and brand revenues from commercial packaged food and beverage products formulated specifically to minimize blood glucose excursions in individuals with diabetes, pre-diabetes, or metabolic syndrome. Excludes prescription anti-diabetic pharmaceuticals, insulin therapies, and medical diagnostic hardware. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Canada, South Korea, Japan, Germany, France, and additional territories in the complete report |
| Key Companies Covered | General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Campbell Soup Company, Hormel Foods Corporation, WK Kellogg Co, Tyson Foods, Inc., Nestlé S.A., Danone S.A. |
| Forecast Period | 2026 to 2036 |
| Approach | Comprehensive primary and secondary research triangulated with industrial specialty sweetener and low-glycemic food manufacturing data. |
Diabetic Food Market - Research Methodology
Table 10: Research Methodology for the Diabetic Food Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with food process chemical engineers, clinical diabetes dietitians, corporate CPG product developers, supermarket category buyers, and retail pharmacy health managers to validate sweetener costs, extrusion parameters, and retail channel sales velocities. |
| Secondary Research | Secondary research included analysis of global diabetes epidemiology registries, national dietary health guidelines, corporate annual financial reports, food and drug administration regulatory bulletins, and academic clinical nutrition journals. |
| Market Sizing and Forecasting | Sizing and forecasting models for 2026 to 2036 were established through bottom-up bulk sweetener shipment tracking integrated with top-down demographic diabetes prevalence and consumer packaged goods expenditure data. |
| Data Triangulation and Validation | Data points were cross-verified against commercial polyol and rare sugar production shipments, retail checkout scanner registries, and published clinical trials evaluating food glycemic indices. |
Diabetic Food Market by Segments
Diabetic Food Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
Diabetic Food Market segmented by Processing State:
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
Diabetic Food Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
Diabetic Food Market by Region
- North America:
- USA
- Canada
- Western Europe:
- Germany
- France
- UK
- Switzerland
- Italy
- Spain
- East Asia:
- South Korea
- Japan
- China
- Latin America:
- Brazil
- Mexico
- South Asia & Pacific:
- Australia
- India
- New Zealand
- Middle East & Africa:
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] International Diabetes Federation. (2025, March 14). IDF Diabetes Atlas 11th Edition: Global Epidemiology and Dietary Management. IDF Guidelines.
- [2] U.S. Food and Drug Administration. (2025, May 19). Nutrition Labeling of Added Sugars and Non-Nutritive Sweeteners in Packaged Foods. FDA Guidance. https://www.fda.gov
- [3] European Food Safety Authority. (2025, July 16). Safety Assessment and Purity Criteria for Steviol Glycosides in Food Products. EFSA Journal. https://www.efsa.europa.eu
- [4] World Health Organization. (2025, June 20). Use of Non-Sugar Sweeteners: WHO Technical Guideline and Evidence Summary. WHO Publications. https://www.who.int
- [5] International Journal of Food Science and Technology. (2025, July 24). Sensory Optimization and Bulking Functional Parity of Rare Sugars in Low-Glycemic Bakery. IJFST Studies.
- [6] National Institutes of Health. (2025, August 16). Metabolic Impact of Dietary Fiber and Resistant Starch in Type 2 Diabetes Care. NIH Monograph. https://www.nih.gov
- [7] Journal of Food Packaging Science. (2025, September 22). Extended Shelf-Life and Moisture Barrier Retention in Low-Carbohydrate Packaged Breads. JFPS Research.
- [8] Global Metabolic Health and Nutrition Society. (2025, October 28). Consumer Dietary Habits and Glycemic Index Control in Pre-Diabetic Cohorts. GMHNS Reports.
- [9] Retail Scanner and Consumer Analytics Institute. (2025, November 19). Purchasing Dynamics and Repeat Rates in Sugar-Free Grocery Categories. RSCAI Data.
- [10] Public Health and Preventative Nutrition Review. (2025, December 16). Cost-Effectiveness of Lifestyle Dietary Interventions in Adult Diabetes Prevention. PHPNR Monograph.
- [11] American Diabetes Association. (2025, July 14). Standards of Care in Diabetes: Medical Nutrition Therapy Recommendations. ADA Guidelines.
- [12] Diabetes Canada. (2025, September 20). Clinical Practice Guidelines for Glycemic Management and Low-Carbohydrate Dietary Patterns. DC Guidelines.
- [13] Korean Diabetes Association. (2025, October 26). Clinical Epidemiology: Preventive Nutrition and Continuous Glucose Monitoring in Asian Demographics. KDA Bulletin.
- [14] Japan Diabetes Society. (2025, November 24). Treatment Guide for Diabetes: Functional Dietary Fiber and Postprandial Glucose Control. JDS Monograph.
- [15] German Diabetes Society. (2025, December 18). Clinical Guidelines on Nutritional Management in Type 2 Diabetes Outpatient Care. DDG Publications.
- [16] General Mills, Inc. (2025, September 18). Corporate Announcement: Commercial Launch of Allulose-Based Low-Glycemic Breakfast Foods. Minneapolis Newsroom.
- [17] Nestlé S.A. (2025, November 20). Health Science Dossier: Commercialization of Clinically Formulated Low-Sugar Dairy Beverages. Vevey Media Center.
- [18] Mondelez International, Inc. (2026, January 22). Snacking Made Right Update: Reformulation of Sugar-Free Confectionery Using Next-Gen Stevia. Chicago Newsroom.
- [19] The Kraft Heinz Company. (2026, February 16). Annual Sustainability and Nutrition Report: Sodium and Sugar Reduction Milestones. Pittsburgh Investor Center.
- [20] Danone S.A. (2026, March 20). Specialized Nutrition Overview: High-Protein Low-Sugar Dairy Solutions for Metabolic Health. Paris Media Hub.
- [21] Conagra Brands, Inc. (2026, April 14). Product Innovation Press Release: Frozen Low-Carbohydrate Meals for Diabetic Consumers. Chicago Newsroom.
This Report Answers
- What is the expected valuation of the global diabetic food market by 2036?
- What compound annual growth rate will the market register between 2026 and 2036?
- Which product grade holds the largest share of commercial consumption in 2026?
- What are the key operational drivers expanding demand for ambient low-glycemic packaged foods?
- Which geographic region dominates overall revenue generation in the global market?
- What factors position Canada as the fastest-expanding country market across the forecast horizon?
- How do continuous glucose monitoring devices alter consumer purchasing habits for low-carb foods?
- Which major CPG food conglomerates and dairy processors lead industrial supply?
- How are retail supermarkets utilizing dedicated diabetic end-caps to expand product accessibility?
- What formulation innovations are emerging to deliver sugar-free bakery items without digestive side effects?
Frequently Asked Questions
What is the projected valuation of the global diabetic food market in 2026?
According to Future Market Insights analysis, the global diabetic food market is evaluated at USD 14.2 Billion in 2026 and is projected to reach USD 25.9 Billion by 2036, growing at a compound annual growth rate of 6.2%.
Which product type commands the largest market share in 2026?
Standard commercial grade represents the leading product segment, commanding a 47.3% market volume share in 2026 due to high cost-efficiency, proven bulk polyol functionality, and widespread distribution across mass-market supermarkets.
Which country exhibits the fastest compound annual growth rate across the forecast period?
Canada is projected to demonstrate the fastest growth rate among analyzed countries, advancing at a CAGR of 7.6% from 2026 to 2036, supported by progressive Health Canada front-of-package sugar labeling rules and high consumer demand for clean-label low-carb foods.
What are the primary natural sweeteners driving growth in the diabetic food sector?
Leading natural sweetening solutions include rare sugars such as allulose and tagatose, high-purity steviol glycosides, monk fruit extract, and functional polyols such as erythritol, which provide clean sweetness without spiking blood glucose.
How does the diabetic food market address gastrointestinal tolerance concerns?
Formulators increasingly transition away from traditional maltitol and sorbitol, combining allulose with soluble prebiotic fibers and resistant starches to achieve authentic sweetness and texture while optimizing digestive tolerance, as verified by Future Market Insights research.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Western Europe
- East Asia
- Latin America
- South Asia & Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- UK
- Switzerland
- Italy
- Spain
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Korea
- Japan
- China
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia & Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- India
- New Zealand
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- General Mills, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The Kraft Heinz Company
- Mondelez International, Inc.
- Conagra Brands, Inc.
- Campbell Soup Company
- Hormel Foods Corporation
- WK Kellogg Co
- Tyson Foods, Inc.
- Nestlé S.A.
- Danone S.A.
- Global Packaged Food & Snack Conglomerates:
- Dairy & High-Protein Nutrition Innovators:
- Savory Protein & Meat Snack Leaders:
- General Mills, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


