
- Market Size (2026)
- USD 244.8 Bn
- Forecast (2036)
- USD 369.4 Bn
- CAGR (2026 to 2036)
- 4.2%
How big is Fish Processing Market in 2026?
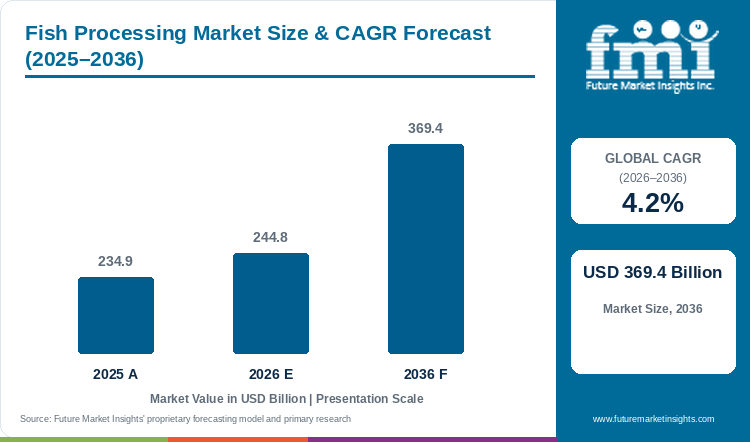
The fish processing market establishes its foundation at USD 234.9 billion in 2025, advances to USD 244.8 billion in 2026, and is forecast to scale to USD 369.4 billion by 2036 at a CAGR of 4.2%.
The global fish processing market was valued at USD 234.9 billion in 2025 and is estimated to reach USD 244.8 billion in 2026. As per the analysis from FMI, the industry valuation is projected to reach USD 369.4 billion by 2036, expanding at a 4.2% CAGR between 2026 and 2036 and outpacing dockside commercial marine and farmed seafood landings as retail chains shift toward factory-trimmed portions. Frozen filleting, glazing & IQF processing are projected to account for 48.3% of preservation & processing method demand in 2026 as supermarkets and restaurant groups replace wet-ice whole fish counters with portion-controlled fillets that cut kitchen prep labor and spoilage waste. The demand for processed fillets is supported by year-round aquaculture harvesting, with the Norwegian Seafood Council reporting in January 2026 that 2.8 million tonnes of seafood were exported in 2025 and farmed harvests supplied 1.5 million tonnes or 73% of export value [1]. Manufacturers are also investing in downstream consumer portioning plants to capture higher retail margins. For instance, Mowi ASA reported a record 559,000-tonne salmon harvest and 265,000 tonnes of value-added Consumer Products volume in February 2026 while guiding 605,000 tonnes for 2026 [2]. However, wild demersal quota cuts and strict Listeria sanitation rules restrain plant margins, meaning long-term expansion depends on automated pin-bone removal and captive farmed supply.
Key Market Trends & Insights
- By preservation & processing method: Based on preservation & processing method, frozen filleting, glazing & IQF processing are projected to account for 48.3% in 2026, driven by cellular moisture lock.
- By species group: By species group, finfish salmon, tuna, pollock, cod & pangasius are estimated to hold 61.9% in 2026, supported by uniform fillet geometry.
- By raw material origin: In 2026, farmed aquaculture harvest is expected to lead raw material origin with 54.9% share, underpinned by year-round coastal cage slaughter.
- By processing equipment: By processing equipment, automated heading, gutting, filleting & pin-boning is forecast to represent 42.3% in 2026, reinforced by X-ray bone detection.
- By end-use channel: Retail supermarkets & hypermarkets are likely to capture 52.8% end-use channel share in 2026, enabled by vacuum skin-packed chilled and IQF trays.
Regional Highlights
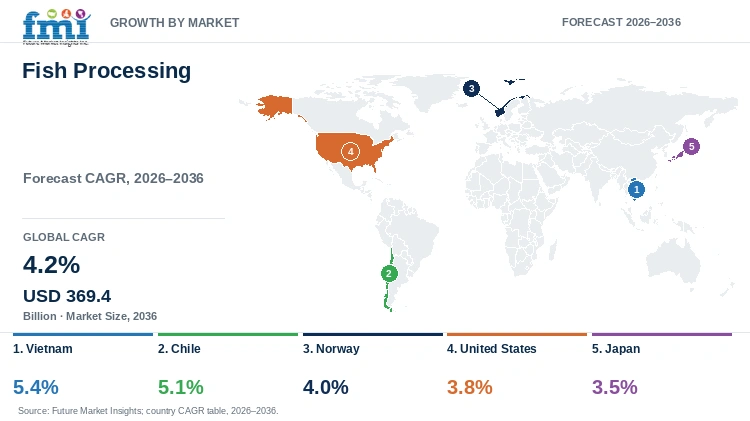
- National growth momentum: Vietnam is projected to expand at a 5.4% CAGR through 2036 on pangasius and whiteleg shrimp filleting, while Chile advances at 5.1% CAGR through Patagonian salmon processing.
- Broader country progression: Norway is expected to progress at 4.0% CAGR ahead of the United States at 3.8% and Japan at 3.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Fish Processing Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 234.9 billion |
| Estimated Market Size in 2026 | USD 244.8 billion |
| Projected Market Size by 2036 | USD 369.4 billion |
| CAGR, 2026 to 2036 | 4.2% |
| Added Valuation, 2026 to 2036 | USD 124.6 billion |
Growing supermarket demand for firm, drip-free fillets is prompting coastal slaughterhouses and wellboats to replace flaked ice with sub-chilled seawater cooling before filleting. National growth patterns differ between export-oriented pangasius and shrimp freezing plants in Vietnam at 5.4% CAGR and automated Atlantic salmon portioning hubs in Chile at 5.1% CAGR. According to a July 2025 study in Scientific Reports, storing whole gutted Atlantic salmon for seven days in minus 1 degree Celsius refrigerated seawater preserved 91.3% water-holding capacity compared with 85.4% on ice [3]. Higher moisture retention reduces fillet gaping and boosts wholesale recovery across flash-frozen fish fillets.
Slaughter-Line Throughput and Fillet-Yield Sizing
Table 2: Slaughter-Line Throughput and Fillet-Yield Sizing for the Fish Processing Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 234.9 | 244.8 | 369.4 |
| Processed edible volume (million MT) | 66.5 to 70.0 | 68.5 to 72.5 | 92.0 to 98.0 |
| Average edible fillet yield (%) | 54.0% to 58.0% | 55.0% to 59.0% | 60.0% to 64.0 |
| Wholesale value per processed kg (USD) | 3.35 to 3.55 | 3.40 to 3.60 | 3.75 to 4.05 |
Operational note: Throughput and yield ranges reflect head-on gutted conversion into skinless pin-bone-out fillets, canned loins, and washed surimi blocks.
Rising household demand for affordable, ready-to-eat marine protein is driving supermarket and institutional orders for hermetic cans and easy-open retort pouches. Canned fish requires no refrigeration during shipping and gives families a long-lasting pantry staple. According to a January 2025 review published in Foods, canned fish production accounts for 19.5 million tons or 11% of global fishery output, using 115 to 130 degree Celsius retort sterilization to keep histamine levels below the 200 mg/kg safety limit [4]. Canneries are also converting fish skin and bone trimmings into marine collagen and oil to improve plant profitability across shelf-stable canned tuna lines.
Per Capita & Processing Plant Sizing
Table 3: Per Capita and Plant Throughput Indicators for the Fish Processing Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Processed fish value per person (USD) | 28.6 | 29.5 | 41.0 |
| Annual output per industrial plant (USD million) | 18.5 to 22.0 | 19.2 to 23.0 | 27.5 to 33.0 |
| Farmed aquaculture raw material share (%) | 54.0% to 54.8% | 54.5% to 55.3% | 58.5% to 60.5% |
Table 4: Plant & Line Utilization Indicators for the Fish Processing Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 244.8 billion | 2026 global market valuation baseline |
| Industrial seafood processing plants | 11,600 plants | Global inspected coastal and vessel plants |
| Annual valuation per plant | USD 21.1 million | Mean plant output across frozen & canned lines |
| Frozen and IQF value, 2026 | USD 118.2 billion | 48.3% preservation method allocation |
Expanding consumption of crabsticks, fish cakes, and convenient seafood snacks across Asia, Europe, and North America is increasing processor demand for high-whiteness refined whitefish surimi paste. Because traditional multi-stage freshwater washing loses valuable fish protein into plant wastewater, processors are adopting single-stage salt-washing protocols to keep yields high. In October 2025, a Food Chemistry X study demonstrated that a single 0.6% salt wash preserved a 76.40% surimi recovery yield while improving paste whiteness from 71.04 to 76.47 [5]. Higher protein recovery lowers raw fish consumption per ton of finished surimi blocks.
Analyst Perspective
"Wild-catch quota reductions have made raw material recovery the primary margin lever in commercial fish processing. Coastal plants that pair X-ray pin-boning and water-jet portioning with year-round farmed salmon and pangasius supply protect operating profit even when marine landing prices fluctuate."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the fish processing market segmented?
The fish processing market is segmented by five primary commercial axes and region, covering preservation & processing method, species group, raw material origin, processing equipment, end-use channel, and region. In 2026, frozen filleting, glazing & IQF processing is projected at 48.3%, finfish at 61.9%, farmed aquaculture harvest at 54.9%, automated heading, gutting, filleting & pin-boning at 42.3%, and retail supermarkets & hypermarkets at 52.8%.
By preservation & processing method: Frozen Filleting, Glazing & IQF Processing, Hermetic Canning, Retort Pouches & Jars, Cold/Hot Smoking, Curing, Salting & Drying, and Surimi, Battered/Breaded Portions & Ready Meals.
By species group: Finfish Salmon, Tuna, Pollock, Cod & Pangasius, Crustaceans Whiteleg Shrimp, Crab & Lobster, and Cephalopods & Bivalve Mollusks.
By raw material origin: Farmed Aquaculture Harvest and Wild-Caught Marine Fisheries.
By processing equipment: Automated Heading, Gutting, Filleting & Pin-Boning, Skinning, Portion Water-Jet Cutting & Grading, and IQF Spiral Freezers, Brining & Smokehouses.
By end-use channel: Retail Supermarkets & Hypermarkets, Foodservice & Restaurant Chains, and Institutional Catering & Export Re-Processors.
Why does frozen filleting & IQF lead preservation method demand?
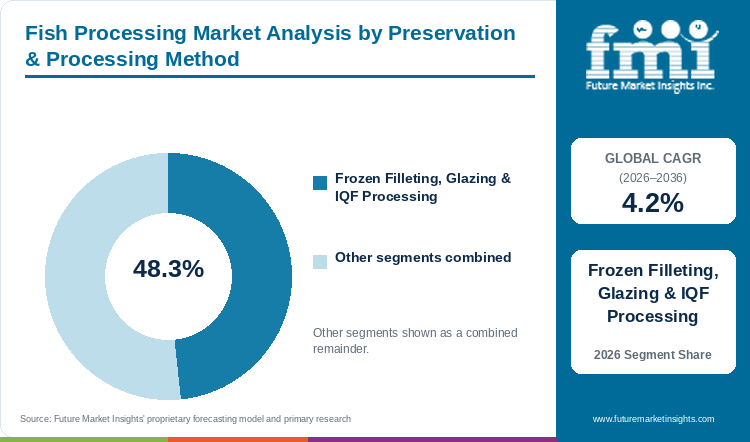
By preservation & processing method, frozen filleting, glazing & IQF processing is estimated to hold 48.3% in 2026, preserving moisture.
Table 5: Preservation & Processing Method Share for the Fish Processing Market (percentage share), 2026
| Preservation & Processing Method | Share (2026) |
|---|---|
| Frozen Filleting, Glazing & IQF Processing | 48.3% |
| Other Segments Combined | 51.7%* |
| Total | 100.0% |
*Note: Other preservation methods covering hermetic canning and smoking as well as surimi and breaded portions sum to 100.0%.
Table 6: Preservation Method Leadership and Market Growth for the Fish Processing Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.2% |
| Leading Segment | Frozen Filleting, Glazing & IQF Processing |
In the FMI report, individual quick freezing and protective water glazing allow coastal plants to ship peeled whiteleg shrimp and skinless salmon portions via ocean container rather than air freight. Rapid freezing locks in natural moisture and prevents fillet shrinkage upon thawing.
- Based on preservation & processing method, frozen filleting, glazing & IQF processing are projected to account for 48.3% in 2026, supported by container export logistics.
- In May 2026, Mowi ASA reported that its expanded feed and processing network across seven farming countries is on track to support 605,000 tonnes of salmon harvest and 650,000 tonnes of feed volume in 2026 [6].
What supports finfish salmon and tuna in the species group category?
In 2026, finfish salmon, tuna, pollock, cod & pangasius is expected to lead species group with 61.9% share, aiding portioning.
Atlantic salmon and skipjack tuna as well as Alaska pollock and pangasius provide uniform body geometry suited for mechanical filleting and onboard brine freezing aboard factory trawlers. Finfish trimmings also supply high-protein mince for breaded fish fingers.
- Finfish salmon, tuna, pollock, cod & pangasius are set to lead the species group category with 61.9% share in 2026, underpinned by automated trimming yields.
- In April 2026, the Norwegian Seafood Council reported that rising Atlantic salmon volumes and elevated wild whitefish prices drove strong March 2026 export growth [7].
How is farmed aquaculture harvest gaining use by raw material origin?
By raw material origin, farmed aquaculture harvest is forecast to represent 54.9% in 2026, reinforced by year-round cage harvesting schedules.
FMI research indicates that marine net-pen salmon farms and inland pangasius and shrimp ponds deliver scheduled daily live harvests that keep coastal filleting lines running above 85% of installed capacity. Wild marine fisheries experience seasonal landing spikes and tightening biological quotas.
- Within raw material origin, farmed aquaculture harvest is anticipated to maintain the leading position with 54.9% share in 2026, owing to uniform harvest weights.
- In August 2026, the USDA Foreign Agricultural Service reported H1 2026 Vietnamese aquaculture harvests of 935.4 thousand MT pangasius and 494.3 thousand MT whiteleg shrimp [8].
Why are buyers selecting automated filleting lines within processing equipment?
Automated heading, gutting, filleting & pin-boning is likely to capture 42.3% equipment share in 2026, enabled by X-ray inspection.
Primary evisceration and pin-bone removal represent the main labor bottleneck on seafood factory floors prior to mechanical tunnel freezers and liquid nitrogen freezing systems. Dual-lane servo filleting machines adjust blade angles dynamically to each fish's spine profile.
- The processing equipment category is forecast to be led by automated heading, gutting, filleting & pin-boning at 42.3% share in 2026, driven by yield recovery.
- In October 2025, a Gels study showed that adding 0.1 wt% microbial transglutaminase restored 6-month frozen silver carp surimi gel strength after a 36.2% unfortified drop [9].
Which market conditions keep retail supermarkets relevant in the end-use channel?
Retail supermarkets & hypermarkets are set to lead end-use channel with 52.8% share in 2026, owing to skin-pack trays.
Supermarket seafood departments increasingly replace wet-ice whole fish counters with case-ready vacuum skin packs and multi-layer retort pouches that eliminate store-level filleting labor. Pre-portioned retail packs carry barcode origin traceability and 10-day chilled shelf life.
- Within the end-use channel category, retail supermarkets & hypermarkets are expected to command 52.8% in 2026, reinforced by oven-ready marinated fish portions.
- In May 2026, NOAA Fisheries issued Marine Mammal Protection Act comparability determinations governing foreign wild and farmed seafood admissibility into U.S. retail channels [10].
What are the drivers, restraints, and opportunities in the fish processing market?
In the fish processing market, the key driver is aquaculture automation, the key restraint is Listeria compliance, and the key opportunity is protamine surimi.
- Driver: Year-round aquaculture harvests and automated X-ray pin-boning lines raise fillet recovery yields and stabilize retail supply contracts.
- Restraint: Strict Listeria monocytogenes limits in smoked fish and wild demersal quota reductions compress processor operating margins.
- Opportunity: Fungal polysaccharide cryoprotectants and protamine-fortified low-salt surimi create clean-label value-added seafood portions.
Natural Cryoprotectants and Frozen Fillet Quality
Growing retail demand for frozen fish portions and crabsticks that do not taste overly sweet is prompting seafood processors to replace refined sugar and sorbitol cryoprotectants with natural polysaccharides during ocean export storage. In November 2025, an International Journal of Biological Macromolecules study showed that Naematelia aurantialba fungal polysaccharides outperformed standard 4% sucrose and 4% sorbitol mixtures in protecting surimi protein structure over 30 days of minus 20 degree Celsius storage [11]. Preventing ice crystal damage without added sugars lowers caloric content and helps frozen seafood brands win health-conscious supermarket listings across Europe and North America.
Listeria Sanitation Hurdles in Smoked Loins
Strict food-safety recalls and bacterial testing rules on ready-to-eat cold-smoked salmon loins and chilled vacuum-packed fillets are a major operational restraint for coastal smokehouses. In March 2025, a Journal of Applied Microbiology study of commercial cold-smoked salmon brined to 3.8% salt at pH 5.9 and 0.95 water activity confirmed that mild smoking temperatures do not eliminate bacteria already present on incoming raw fillets [12]. As a result, processors must invest in automated skinning sanitation and hold finished batches in cold storage pending microbiological clearance to stay under the European Union 100 cfu/g Listeria limit, which raises working capital costs.
Protamine Fortification in Reduced-Sodium Surimi
Rising consumer preference for low-sodium seafood snacks, fish sausages, and school cafeteria fish portions is creating strong commercial opportunities for processors that maintain firm texture at reduced salt levels. Normally, cutting salt weakens protein binding and causes water loss during cooking. In September 2026, a Food Chemistry study showed that reducing surimi salt from 2.0% to 1.0% raised cooking water loss from 9.72% to 19.75%, whereas adding 8 grams per 100 grams of natural fish protamine more than doubled gel strength to 3,919.59 g-cm and lowered cooking loss to 11.58% [13]. Natural protamine lets processors win low-sodium catering contracts.
Fish Processing Market by Country (2026 to 2036)
As per FMI, national demand across evaluated economies is shaped by export-oriented pangasius and shrimp freezing hubs in Southeast Asia, Patagonian and Nordic salmon slaughterhouses, and automated surimi and whitefish plants in the United States and Japan. Commercial performance depends on how effectively processors secure year-round aquaculture biomass, automate pin-bone removal, and satisfy import traceability mandates.
Table 7: Country CAGR and Primary Growth Levers for the Fish Processing Market (CAGR percentage and operational growth levers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Vietnam | 5.4% | Mekong Delta IQF pangasius and whiteleg shrimp filleting and export re-processing |
| Chile | 5.1% | Patagonian Atlantic and Coho salmon automated filleting and smoked loin exports |
| Norway | 4.0% | Sub-chilled wellboat salmon slaughterhouses and high-value consumer portion packs |
| United States | 3.8% | North Pacific wild Alaska pollock surimi vessels and value-added foodservice nuggets |
| Japan | 3.5% | Automated kamaboko surimi plants and convenience-store ready-to-eat fish entrees |
Source: Future Market Insights analysis
Vietnam Fish Processing Market Outlook (2026 to 2036)
Per the August 2026 USDA Foreign Agricultural Service GAIN report VM2026-0030, Vietnam's H1 2026 seafood exports rose 13% year-on-year to USD 5.8 billion, led by whiteleg shrimp shipments at USD 2.3 billion and Mekong Delta pangasius fillets at USD 1.1 billion [8]. A July 2026 USDA trade briefing further documented that Vietnam's broader food processing sector reached USD 88.0 billion in 2025 while U.S. raw seafood exports to Vietnam for filleting and re-export jumped 77% to USD 114 million [14]. By 2036, Vietnam is projected to grow at 5.4% CAGR, driven by IQF glazing and breaded shrimp lines. Yet rising pond feed costs squeeze primary margins, pushing plants toward toll re-processing.
Key takeaway: In Vietnam, Mekong Delta IQF pangasius and shrimp filleting and export re-processing are projected to drive a 5.4% CAGR through 2036.
Chile Fish Processing Market Outlook (2026 to 2036)
Long refrigerated air- and ocean-freight distances from southern Chilean fjords in Puerto Montt and Chiloé to North American and Brazilian grocery distribution centers require precision super-chilling and vacuum skin packaging. According to the March 2026 NOAA Fisheries report on U.S. fishery trade, Chile and Canada supply the largest shares of the 6.3 billion pounds of edible processed seafood imported annually by the United States [15]. Chile's fish processing outlook is anticipated to advance at 5.1% CAGR over the assessment period, supported by automated pin-bone-out Atlantic and Coho salmon filleting lines. Tighter benthic environmental rules in Patagonian concessions nevertheless cap smolt stocking density, encouraging higher-value smoked loin exports.
Key takeaway: In Chile, automated Patagonian salmon portioning and vacuum-packed North American shipments are forecast to support a 5.1% CAGR through 2036.
Norway Fish Processing Market Outlook (2026 to 2036)
Norwegian coastal seafood processors are expanding domestic secondary filleting, portioning, and consumer tray packing to capture higher value onshore rather than shipping whole gutted fish to continental European re-processors. Following the January 2026 Norwegian Seafood Council audit of 2.8 million tonnes of 2025 exports [1], September 2026 council trade records confirmed sustained salmon value expansion into European and Asian retail channels [16]. Fish processing demand in Norway is forecast to rise at 4.0% CAGR over the forecast period, underpinned by sub-chilled wellboat slaughterhouses and robotic water-jet trimming lines. However, resource rent taxation on coastal net-pen farming restrains greenfield cage licensing, shifting capex toward onshore fillet yield recovery.
Key takeaway: In Norway, robotic coastal filleting and sub-chilled salmon retail tray lines are expected to sustain a 4.0% CAGR through 2036.
United States Fish Processing Market Outlook (2026 to 2036)
According to the March 2026 NOAA Fisheries report, domestic U.S. processed fishery products generated USD 12.0 billion across edible fillets, canned tuna, and breaded portions as well as USD 745.5 million in industrial fishmeal and oil [15]. Bering Sea factory trawlers and Pacific Northwest shore plants convert wild Alaska pollock, Pacific cod, and sockeye salmon into frozen fillet blocks, surimi paste, and battered foodservice nuggets. Adoption of fish processing systems in the United States is estimated to expand at 3.8% CAGR through 2036, reinforced by automated vision-guided portioning and school nutrition contracts. Chronic coastal cannery labor shortages still raise operating wages, accelerating investment in automated heading and pin-boning equipment.
Key takeaway: In the United States, wild Alaska pollock surimi trawlers and battered foodservice portions are estimated to deliver a 3.8% CAGR through 2036.
Japan Fish Processing Market Outlook (2026 to 2036)
Shrinking domestic coastal fishing crews and aging single-person household demographics across Japan have reduced raw wet-fish home preparation while accelerating convenience-store and supermarket demand for bone-free microwaveable fish entrees. Per Nissui Corporation's FY2025 interim operational briefing, new domestic chilled and frozen marine processing plant capacity ramps to full-scale commercial production in August 2026 to supply prepared retail trays and high-elasticity surimi kamaboko [17]. The Japan fish processing sector is projected to record 3.5% CAGR during the assessment period, aided by X-ray bone-detection lines and low-sodium surimi formulations. Elevated imported frozen Alaska pollock and salmon procurement costs nevertheless pressure domestic processor margins, prompting robotic fillet yield optimization.
Key takeaway: In Japan, convenience-store ready-to-eat fish entrees and robotic kamaboko surimi plants are projected to generate a 3.5% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the fish processing market?
Mowi ASA, Thai Union Group PCL, Maruha Nichiro Corporation, Nissui Corporation, Trident Seafoods Corporation, SalMar ASA, and Cooke Inc. are the notable companies in the fish processing market.
FMI data suggests that the global fish processing industry is moderately fragmented across regional species specialties, with top-tier concentration in farmed Atlantic salmon, ambient canned tuna, and North Pacific wild pollock. Vertically integrated aquaculture groups control coastal slaughterhouses and consumer skin-pack plants, whereas ambient cannery leaders and factory-trawler fleets compete on long-term supermarket private-label and foodservice tenders.
- Vertically Integrated Salmon & Aquaculture Processors: Mowi ASA, SalMar ASA, and Cooke Inc. integrate marine net-pen salmon farming with sub-chilled wellboats, coastal slaughterhouses, and retail skin-pack plants.
- Global Ambient Tuna & Frozen Shrimp Platforms: Thai Union Group PCL runs high-capacity hermetic canning, multi-layer retort pouch, and IQF whiteleg shrimp processing facilities across three continents.
- Wild-Catch Whitefish & Surimi Leaders: Maruha Nichiro Corporation, Nissui Corporation, and Trident Seafoods Corporation run factory trawlers, surimi extrusion plants, and breaded whitefish lines.
Competitive Benchmarking: Fish Processing Market
Table 8: Competitive Benchmarking for the Fish Processing Market (qualitative capability ratings), 2026
| Company | Automated Filleting & IQF | Raw Material Integration | Retail & Foodservice Access | Geographic Reach |
|---|---|---|---|---|
| Mowi ASA | High | High | High | High |
| Thai Union Group PCL | High | Medium | High | High |
| Maruha Nichiro Corporation | High | High | High | High |
| Nissui Corporation | High | High | High | High |
| Trident Seafoods Corporation | High | High | High | Medium |
| SalMar ASA | High | High | Medium | Medium |
| Cooke Inc. | High | High | High | High |
Scoring basis: Qualitative ratings measure installed robotic filleting and IQF freezing lines, captive aquaculture or wild-catch quota access, retail and foodservice supply contracts, and global footprint. Ratings of High, Medium, and Low reflect evidenced operational scope rather than market-share rank.
Key Developments in the Fish Processing Market
- In August 2026, SalMar ASA reported a Q2 2026 salmon harvest of 81,800 tonnes, raised its full-year 2026 harvest guidance by 20,000 tonnes to 350,000 tonnes (up 16%), and agreed to acquire a 70% controlling stake in Måsøval AS [18].
- In August 2026, Thai Union Group PCL delivered a record 21.4% Q2 2026 gross profit margin and a 14.3% higher dividend payout as ambient canned and pouch seafood volume expanded 4.4% year-on-year [19].
- In March 2026, Trident Seafoods Corporation won Best New Foodservice Product at the 2026 Seafood Excellence Awards in Boston for its Crispy Battered Sauceable Wild Alaska Pollock Nuggets [20].
Key Players in the Fish Processing Market
Vertically Integrated Salmon & Aquaculture Processors
- Mowi ASA
- SalMar ASA
- Cooke Inc.
Global Ambient Tuna & Frozen Shrimp Platforms
- Thai Union Group PCL
Wild-Catch Whitefish & Surimi Leaders
- Maruha Nichiro Corporation
- Nissui Corporation
- Trident Seafoods Corporation
Fish Processing Market - Report Scope
Table 9: Report Scope for the Fish Processing Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Preservation & Processing Method; Species Group; Raw Material Origin; Processing Equipment; End-Use Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial processor valuation from primary and secondary processed finfish, crustaceans, and mollusks across frozen IQF fillets, canned and retorted seafood, smoked and cured fish, surimi, and breaded portions, as well as commercial fish processing equipment. Segment shares and forecast estimates are FMI proprietary analytical estimates. Excludes live or un-gutted whole wet fish sold at dockside auctions. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Vietnam, Chile, Norway, United States, Japan, and additional countries in the full report |
| Key Companies Covered | Mowi ASA, Thai Union Group PCL, Maruha Nichiro Corporation, Nissui Corporation, Trident Seafoods Corporation, SalMar ASA, Cooke Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Fish Processing Market - Research Methodology
Table 10: Research Methodology for the Fish Processing Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, suppliers, distributors, industry executives, and category specialists across the value chain to validate product trends, specification protocols, demand dynamics, and commercial purchasing decisions. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, company annual filings, investor presentations, and official corporate announcements reviewed for relevance and scope consistency. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period combined baseline valuation with historical performance, segment structure, pricing and volume indicators, company participation, and country demand conditions using top-down and bottom-up models. |
| Country Forecasting Model | National projections weighted demographic cohorts, domestic production and processing capacity, import and export trade flows, and statutory tax or regulatory frameworks across evaluated economies before reconciling regional totals. |
| Operational Benchmark Traceability | Operational and facility sizing indicators in Tables 2, 3, and 4 trace to verified trade association registries, national agricultural and fisheries databases, and peer-reviewed technical studies. |
| Data Triangulation and Validation | Estimates were cross-checked against public trade data, corporate segment disclosures, and primary interview findings to exclude adjacent categories, eliminate double counting, and maintain consistency across segments and countries. |
Fish Processing Market by Segments
Fish Processing Market segmented by Preservation & Processing Method:
- Frozen Filleting, Glazing & IQF Processing
- Hermetic Canning, Retort Pouches & Jars
- Cold/Hot Smoking, Curing, Salting & Drying
- Surimi, Battered/Breaded Portions & Ready Meals
Fish Processing Market segmented by Species Group:
- Finfish Salmon, Tuna, Pollock, Cod & Pangasius
- Crustaceans Whiteleg Shrimp, Crab & Lobster
- Cephalopods & Bivalve Mollusks
Fish Processing Market segmented by Raw Material Origin:
- Farmed Aquaculture Harvest
- Wild-Caught Marine Fisheries
Fish Processing Market segmented by Processing Equipment:
- Automated Heading, Gutting, Filleting & Pin-Boning
- Skinning, Portion Water-Jet Cutting & Grading
- IQF Spiral Freezers, Brining & Smokehouses
Fish Processing Market segmented by End-Use Channel:
- Retail Supermarkets & Hypermarkets
- Foodservice & Restaurant Chains
- Institutional Catering & Export Re-Processors
Fish Processing Market by Region
- North America
- United States
- Canada
- Latin America
- Chile
- Brazil
- Mexico
- Argentina
- Western Europe
- Norway
- United Kingdom
- Germany
- France
- Spain
- Italy
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- China
- South Korea
- South Asia and Pacific
- Vietnam
- ASEAN
- India
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Norwegian Seafood Council. (2026, January 6). Price growth for wild fish and increased salmon volume resulted in record value for Norwegian seafood exports in 2025. Norwegian Seafood Council.
- [2] Mowi ASA. (2026, February 11). A record fourth quarter ends a record year for Mowi. Mowi ASA.
- [3] Chan, S. S., Rotabakk, B. T., Løvdal, T., Sone, I., & Roth, B. (2025, July 8). Sub-chilling methods for Atlantic salmon with 7 days in refrigerated seawater and subsequent sub-chilled storage. Scientific Reports, 15, 24382 (PubMed PMID 40628920).
- [4] Pais-Costa, A. J., Marques, A., Oliveira, H., Gonçalves, A., Camacho, C., Augusto, H. C., & Nunes, M. L. (2025, January 2). New Perspectives on Canned Fish Quality and Safety on the Road to Sustainability. Foods, 14(1), 99 (PubMed PMID 39796393).
- [5] Senphan, T., Mungmueang, N., Hoque, M. S., Sriket, C., Benjakul, S., Buamard, N., Leelapongwattana, K., & Nalinanon, S. (2025, October 6). Optimization of salt washing protocols for surimi production from invasive blackchin tilapia (Sarotherodon melanotheron): Molecular and functional properties. Food Chemistry: X, 31, 103127 (PubMed PMID 41140590).
- [6] Mowi ASA. (2026, May 13). Second-best operational profit for a first quarter for Mowi on seasonally record-high revenues and volumes. Mowi ASA.
- [7] Norwegian Seafood Council. (2026, April 8). Increased salmon volumes and high wild fish prices drove growth in seafood exports in March. Norwegian Seafood Council.
- [8] USDA Foreign Agricultural Service. (2026, August 4). Vietnam: Grain and Feed Quarterly and Aquaculture Update (GAIN Report VM2026-0030). United States Department of Agriculture.
- [9] Yang, J., Chen, S., Tong, T., & Yu, C. (2025, October 9). Assessment of Frozen Stored Silver Carp Surimi Gel Quality Using Synthetic Data-Driven Machine Learning (SDDML) Model. Gels, 11(10), 810 (PubMed PMID 41149415).
- [10] NOAA Fisheries. (2026, May 11). Marine Mammal Protection Act Comparability Finding Determinations for Harvesting Nations. National Oceanic and Atmospheric Administration.
- [11] Ma, Y., Xu, X., Mao, S., Wang, R., Gu, Y., Qiu, Y., Sun, L., Xu, H., Zhou, Q., & Lei, P. (2025, November 1). Freeze-denaturation mitigation in surimi by Naematelia aurantialba polysaccharides: structural stabilization and ice recrystallization inhibition. International Journal of Biological Macromolecules, 330(Pt 3), 148084 (PubMed PMID 41046892).
- [12] Maughan, L., Whyte, P., & Bolton, D. (2025, March 3). The bacterial quality and safety of cold smoked salmon during production and subsequent chilled storage. Journal of Applied Microbiology, 136(3), lxaf035 (PubMed PMID 39953903).
- [13] Su, H., Lin, S., Jiang, C., Zhang, Y., Yu, J., He, W., & Tang, Y. (2026, September 20). The dual enhancement of gel properties and storage stability by protamine in low-salt silver carp (Hypophthalmichthys molitrix) surimi. Food Chemistry, 530, 151225 (PubMed PMID 42785029).
- [14] USDA Foreign Agricultural Service. (2026, July 9). Expanding U.S. Agricultural Exports in Vietnam's Rising Market. United States Department of Agriculture.
- [15] NOAA Fisheries. (2026, March 3). Fisheries of the United States: Processed Fishery Products and Trade. National Oceanic and Atmospheric Administration.
- [16] Norwegian Seafood Council. (2026, September 3). Value growth for salmon led to a strong month for Norwegian seafood exports. Norwegian Seafood Council.
- [17] Nissui Corporation. (2025, November 14). Supplemental Information for the Interim Term of FY2025. Nissui Corporation.
- [18] SalMar ASA. (2026, August 25). SalMar: Record-strong biological performance. SalMar ASA.
- [19] Thai Union Group PCL. (2026, August 3). Thai Union delivers record-high 21.4% gross profit margin, 14.3% higher dividend payout, and a lower debt-to-equity ratio. Thai Union Group PCL.
- [20] Trident Seafoods Corporation. (2026, March 15). Trident Seafoods Wins Best New Foodservice Product at 2026 Seafood Excellence Awards. Trident Seafoods Corporation.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the fish processing market in 2026 and 2036?
- Which aquaculture and automation factors support demand for processed fish fillets?
- Why does frozen filleting, glazing & IQF lead preservation methods?
- Why do finfish salmon, tuna, and pollock hold 61.9% share?
- How do growth rates differ across Vietnam, Chile, Norway, and Japan?
- Which notable companies operate salmon slaughterhouses, tuna canneries, and surimi trawlers?
- What biological quota and Listeria food-safety hurdles limit processor margins?
- What water-holding capacity and glazing specifications should retail buyers evaluate first?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Preservation & Processing Method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Preservation & Processing Method, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Preservation & Processing Method, 2026 to 2036
- Frozen Filleting, Glazing & IQF Processing
- Hermetic Canning, Retort Pouches & Jars
- Cold/Hot Smoking, Curing, Salting & Drying
- Surimi, Battered/Breaded Portions & Ready Meals
- Y-o-Y Growth Trend Analysis By Preservation & Processing Method, 2021 to 2025
- Absolute $ Opportunity Analysis By Preservation & Processing Method, 2026 to 2036
- Global Market Analysis and Forecast, By Species Group, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Species Group, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Species Group, 2026 to 2036
- Finfish Salmon, Tuna, Pollock, Cod & Pangasius
- Crustaceans Whiteleg Shrimp, Crab & Lobster
- Cephalopods & Bivalve Mollusks
- Y-o-Y Growth Trend Analysis By Species Group, 2021 to 2025
- Absolute $ Opportunity Analysis By Species Group, 2026 to 2036
- Global Market Analysis and Forecast, By Raw Material Origin, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Raw Material Origin, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Raw Material Origin, 2026 to 2036
- Farmed Aquaculture Harvest
- Wild-Caught Marine Fisheries
- Y-o-Y Growth Trend Analysis By Raw Material Origin, 2021 to 2025
- Absolute $ Opportunity Analysis By Raw Material Origin, 2026 to 2036
- Global Market Analysis and Forecast, By Processing Equipment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing Equipment, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing Equipment, 2026 to 2036
- Automated Heading, Gutting, Filleting & Pin-Boning
- Skinning, Portion Water-Jet Cutting & Grading
- IQF Spiral Freezers, Brining & Smokehouses
- Y-o-Y Growth Trend Analysis By Processing Equipment, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing Equipment, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Channel, 2026 to 2036
- Retail Supermarkets & Hypermarkets
- Foodservice & Restaurant Chains
- Institutional Catering & Export Re-Processors
- Y-o-Y Growth Trend Analysis By End-Use Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Chile
- Brazil
- Mexico
- Argentina
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Norway
- United Kingdom
- Germany
- France
- Spain
- Italy
- Benelux
- Nordics
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- China
- South Korea
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Vietnam
- ASEAN
- India
- Australia and New Zealand
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Vietnam
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Norway
- Pricing Analysis
- Market Share Analysis, 2025
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Preservation & Processing Method
- By Species Group
- By Raw Material Origin
- By Processing Equipment
- By End-Use Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Mowi ASA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Thai Union Group PCL
- Maruha Nichiro Corporation
- Nissui Corporation
- Trident Seafoods Corporation
- SalMar ASA
- Cooke Inc.
- Mowi ASA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Preservation & Processing Method, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Species Group, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Raw Material Origin, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Processing Equipment, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by End-Use Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Preservation & Processing Method, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Species Group, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Raw Material Origin, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Processing Equipment, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by End-Use Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Preservation & Processing Method, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Species Group, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Raw Material Origin, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Processing Equipment, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by End-Use Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Preservation & Processing Method, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Species Group, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Raw Material Origin, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Processing Equipment, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by End-Use Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Preservation & Processing Method, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Species Group, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Raw Material Origin, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Processing Equipment, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by End-Use Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Preservation & Processing Method, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Species Group, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Raw Material Origin, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Processing Equipment, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by End-Use Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Preservation & Processing Method, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Species Group, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Raw Material Origin, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Processing Equipment, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Preservation & Processing Method, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Species Group, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Raw Material Origin, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Processing Equipment, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Preservation & Processing Method, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Preservation & Processing Method, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Preservation & Processing Method
- Figure 6: Global Market Value Share and BPS Analysis by Species Group, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Species Group, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Species Group
- Figure 9: Global Market Value Share and BPS Analysis by Raw Material Origin, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Raw Material Origin, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Raw Material Origin
- Figure 12: Global Market Value Share and BPS Analysis by Processing Equipment, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Processing Equipment, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Processing Equipment
- Figure 15: Global Market Value Share and BPS Analysis by End-Use Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by End-Use Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by End-Use Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Preservation & Processing Method, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Preservation & Processing Method, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Preservation & Processing Method
- Figure 32: North America Market Value Share and BPS Analysis by Species Group, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Species Group, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Species Group
- Figure 35: North America Market Value Share and BPS Analysis by Raw Material Origin, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Raw Material Origin, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Raw Material Origin
- Figure 38: North America Market Value Share and BPS Analysis by Processing Equipment, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Processing Equipment, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Processing Equipment
- Figure 41: North America Market Value Share and BPS Analysis by End-Use Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by End-Use Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by End-Use Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Preservation & Processing Method, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Preservation & Processing Method, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Preservation & Processing Method
- Figure 48: Latin America Market Value Share and BPS Analysis by Species Group, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Species Group, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Species Group
- Figure 51: Latin America Market Value Share and BPS Analysis by Raw Material Origin, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Raw Material Origin, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Raw Material Origin
- Figure 54: Latin America Market Value Share and BPS Analysis by Processing Equipment, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Processing Equipment, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Processing Equipment
- Figure 57: Latin America Market Value Share and BPS Analysis by End-Use Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by End-Use Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by End-Use Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Preservation & Processing Method, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Preservation & Processing Method, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Preservation & Processing Method
- Figure 64: Western Europe Market Value Share and BPS Analysis by Species Group, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Species Group, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Species Group
- Figure 67: Western Europe Market Value Share and BPS Analysis by Raw Material Origin, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Raw Material Origin, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Raw Material Origin
- Figure 70: Western Europe Market Value Share and BPS Analysis by Processing Equipment, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Processing Equipment, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Processing Equipment
- Figure 73: Western Europe Market Value Share and BPS Analysis by End-Use Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by End-Use Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by End-Use Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Preservation & Processing Method, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Preservation & Processing Method, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Preservation & Processing Method
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Species Group, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Species Group, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Species Group
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Raw Material Origin, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Raw Material Origin, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Raw Material Origin
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Processing Equipment, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Processing Equipment, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Processing Equipment
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by End-Use Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by End-Use Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Preservation & Processing Method, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Preservation & Processing Method, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Preservation & Processing Method
- Figure 96: East Asia Market Value Share and BPS Analysis by Species Group, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Species Group, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Species Group
- Figure 99: East Asia Market Value Share and BPS Analysis by Raw Material Origin, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Raw Material Origin, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Raw Material Origin
- Figure 102: East Asia Market Value Share and BPS Analysis by Processing Equipment, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Processing Equipment, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Processing Equipment
- Figure 105: East Asia Market Value Share and BPS Analysis by End-Use Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by End-Use Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by End-Use Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Preservation & Processing Method, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Preservation & Processing Method, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Preservation & Processing Method
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Species Group, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Species Group, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Species Group
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Raw Material Origin, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Raw Material Origin, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Raw Material Origin
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Processing Equipment, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing Equipment, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Processing Equipment
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by End-Use Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Preservation & Processing Method, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Preservation & Processing Method, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Preservation & Processing Method
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Species Group, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Species Group, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Species Group
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Raw Material Origin, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Raw Material Origin, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Raw Material Origin
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Processing Equipment, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Processing Equipment, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Processing Equipment
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by End-Use Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by End-Use Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the fish processing market in 2026, and what is forecast for 2036?
According to FMI, global fish processing market value is estimated to reach USD 244.8 billion in 2026 from USD 234.9 billion in 2025 and attain USD 369.4 billion by 2036.
What is the CAGR for the fish processing market from 2026 to 2036?
As noted by FMI, the fish processing market is projected to expand at a 4.2% compound annual growth rate between 2026 and 2036, adding USD 124.6 billion.
Which preservation method segment leads the fish processing market?
Frozen filleting, glazing & IQF processing are projected to capture 48.3% of preservation & processing method demand in 2026.
Which species group leads the fish processing market?
Finfish salmon, tuna, pollock, cod & pangasius are estimated to command 61.9% of species group demand in 2026.
Which country has a notable growth outlook during the assessment period?
Vietnam is projected to expand at a 5.4% CAGR through 2036, supported by Mekong Delta pangasius and whiteleg shrimp processing.
Who are the key players in the market?
Mowi ASA, Thai Union Group PCL, Maruha Nichiro Corporation, Nissui Corporation, Trident Seafoods Corporation, SalMar ASA, and Cooke Inc. are the key players.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
