
- Market Size (2026)
- USD 14.3 Bn
- Forecast (2036)
- USD 34.1 Bn
- CAGR (2026 to 2036)
- 9.1%
How big is Floating Power Plant Market in 2026?
The global floating power plant market is estimated at USD 13.1 billion in 2025 and is expected to reach USD 14.3 billion in 2026. Demand for floating power plants is forecast to grow at a CAGR of 9.1% between 2026 and 2036, taking the market to USD 34.1 billion by 2036. In FMI analysis, renewable-based systems lead source with an estimated 46% share in 2026.
Demand for floating power plants is rising as coastal countries short of electricity need new supply within weeks. A case in point is sub-Saharan Africa, home to 85% of the over 666 million people without electricity in 2023, according to Tracking SDG7 [1]. Coastal states in that region are therefore the main buyers of power from ships and barges. Sales of powerships are also gaining from larger fleets. Karpowership, for example, now runs over 8,000 MW of capacity through 45 Powerships [2]. Adoption of bigger vessels is the next step for fleet owners, and Karpowership and Seatrium signed a contract on 23 October 2026 to integrate five Whale Class Powerships, each designed for up to 600 MW [3]. FMI analysis indicates that larger ships lower the cost of short-term power, which helps operators secure national supply contracts.
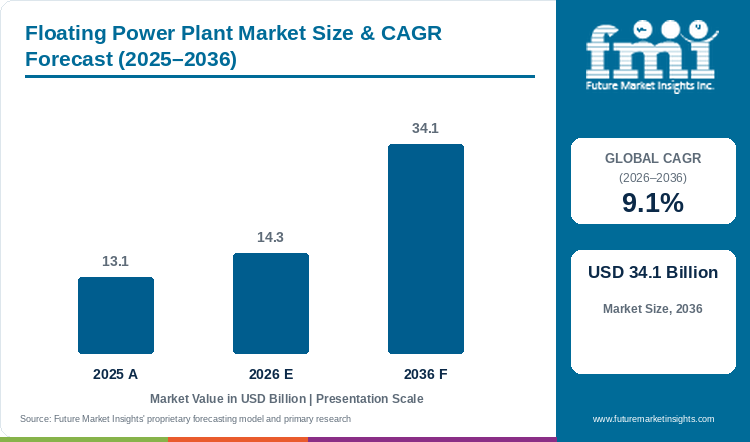
Table 1: Floating Power Plant Market Size and Forecast (USD billion), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 market size | USD 13.1 billion |
| Estimated market size in 2026 | USD 14.3 billion |
| Projected market size by 2036 | USD 34.1 billion |
| CAGR (2026 to 2036) | 9.1% |
| Added sales, 2026 to 2036 | USD 19.8 billion |
Key Market Trends & Insights
- By source: Renewable-based floating systems, mainly solar and wind units, will hold 46% of 2026 sales, as utilities with little spare land place panels on reservoirs and calm coasts.
- By capacity: Systems up to 20 MW account for 38% of 2026 sales, since islands, ports and remote mines need small amounts of power that can arrive quickly.
- By type: With an estimated 44.8% share in 2026, barges lead the type mix, as flat hulls cost less to build and moor easily in rivers and harbours.
Regional Highlights
- Fastest-growing country: At a 9.3% CAGR over 2026 to 2036, the United States has the highest rate among profiled countries, as utilities float solar panels on reservoirs and keep power barges ready after storms.
- Growth across other countries: South Korea and ASEAN are both projected at 9.2%, just over the 9.1% world figure, helped by busy shipyards and island grids. Japan is projected at 9%, the United Kingdom at 8.9% and South Africa at 8.8%, as reservoir solar, deep-water wind and coastal gas projects add orders. Brazil, which relies on hydropower, has the lowest rate at an 8.6% CAGR.
Growth of the floating power plant market depends on shipyard space, which decides how fast new plants reach customers. Karpowership has four 300 MW Sea Lion Powerships under construction at the HSG Sungdong shipyard, with delivery between January and May 2028 [2]. Hence, about 1,200 MW of new floating capacity is already booked before the end of the decade. Supply of gas is also being built into the same fleet. Seatrium completed a seven-vessel FSRU conversion programme for Karpowership with the sailaway of LNGT Türkiye in September 2026 [4]. These floating units turn LNG back into gas, so powerships can burn gas at ports that have no import terminal. Owners can therefore move customers from oil-based fuels to cheaper gas.
Bank and bond finance decides how many projects go ahead, since each powership needs heavy investment before the first sale. Karpowership affiliate Sea World Energy Holdings secured a USD 400 million syndicated portfolio financing led by Mauritius Commercial Bank in November 2025 [5]. Bank loans of this kind lower the cost of funding power leases in Africa. In addition, Kinetics, a Karpowership initiative, completed a USD 400 million four-year senior secured bond to fund the conversion of three LNG terminal ships [6]. A bond of this size shows that investors are willing to fund floating energy assets. Cheaper funding in turn lets operators offer lower power prices in new tenders.
The ability to burn different fuels is the next technical step for floating power. Kinetics partnered with Amogy in December 2025 on technology that cracks ammonia into hydrogen on-site for floating power and data center infrastructure [7]. Consequently, floating plants may gain a lower-carbon fuel option in the 2030s. Gas switching is already cutting emissions, as the 240 MW Deniz Sultan in Gabon moved from liquid fuels to domestic natural gas. The company linked the switch to a 35% reduction in annual carbon dioxide emissions [8]. Buyer preference for lower-emission powerships is strong in countries with climate targets, which makes these ships easier to approve. Utilities can therefore keep floating units for longer as onshore plants are built.
Table 2: Supporting Industry Indicators for the Floating Power Plant Market, 2023 to 2026
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| Electricity access gap | Over 666 million people without electricity in 2023; 85% in sub-Saharan Africa | Core demand for fast-deployed power | [1] |
| Renewable additions | 585 GW of renewable capacity added in 2024; total 4,448 GW at end-2024 | Renewable floating systems ride broader capacity growth | [9] |
| Solar capacity | Solar reached 1,865 GW in 2024 and made up over three-quarters of additions | Solar is the main source for floating renewable units | [9] |
| Powership fleet | Over 8,000 MW through 45 Powerships (June 2026) | Scale of the largest floating fleet | [2] |
| New builds | Four 300 MW Sea Lion Powerships due between January and May 2028 | Pipeline of new floating capacity | [2] |
| Whale Class contract | Five Whale Class Powerships of up to 600 MW each; first vessel due at the yard in December 2027 | Larger units per vessel | [3] |
| FSRU conversions | Seven-vessel FSRU conversion programme completed in September 2026 | LNG supply for gas-fired powerships | [4] |
| Portfolio financing | USD 400 million syndicated facility led by Mauritius Commercial Bank (November 2025) | Bank debt for African projects | [5] |
| Bond financing | USD 400 million four-year senior secured bond (November 2025) | Capital markets fund floating LNG assets | [6] |
| Fuel switching | 240 MW Powership in Gabon moved to domestic gas; 35% lower annual carbon dioxide emissions (September 2025) | Lower-emission bridging power | [8] |
| Ammonia-to-power | Kinetics and Amogy partnership on ammonia cracking for floating power (December 2025) | Low-carbon fuel options for future fleets | [7] |
Demand Intensity Analysis
The largest powership fleet gives a useful check on the estimate. Karpowership reported over 8,000 MW of capacity through 45 Powerships in June 2026 [2]. The market is estimated at USD 13.1 billion in 2025, or about USD 1.64 million for every megawatt in that fleet. The two figures cover different things, since the estimate also covers floating solar and wind, barges from other owners and equipment sales. Even so, the ratio shows that sales are spread across many more plants than one operator runs. The supplier field is therefore wide and split among many players.
The electricity access gap gives a useful demand-side check on the estimate. Grid access remained out of reach for over 666 million people in 2023 [1]. At USD 13.1 billion, the market is estimated at roughly USD 19.7 for each person without access. Many of those people live far from coasts and will get power from local mini-grids instead. Still, the low value per person shows how much room remains for floating plants in coastal Africa and Asia.
New renewable capacity gives a reference point for the leading source segment. IRENA reported 585 GW of renewable capacity added in 2024, taking the total to 4,448 GW [9]. At a 46% share of the USD 14.3 billion estimated for 2026, renewable floating systems come to about USD 6.58 billion. That equals about USD 11.2 million for each GW added in 2024, though the two figures cover different periods. Floating units therefore remain a small, higher-cost niche within the wider renewable build-out.
The speed of renewable growth gives a check on the forecast CAGR. The 585 GW added in 2024 equals growth of about 15.1% on the capacity in place a year earlier [9]. Set against the 9.1% CAGR for 2026 to 2036, the gap implies that floating plant value shrinks at a CAGR of about 5.2% relative to renewable capacity. The forecast thus assumes that floating systems keep a narrow role at islands, ports and grids short of land. Gas-fired powerships used as stopgap supply make up part of the difference.
Table 3: Demand Intensity Metrics for the Floating Power Plant Market, 2023 to 2026 Data Against 2025 and 2026 Market Values
| Demand intensity metric | Value | Basis |
|---|---|---|
| Karpowership fleet capacity, 2026 | Over 8,000 MW | Karpowership, June 2026 release |
| Market value per MW of the Karpowership fleet | USD 1.64 million | Calculated from Karpowership fleet capacity and the 2025 market value |
| People without electricity, 2023 | Over 666 million | International Energy Agency, Tracking SDG7 2025 |
| Market value per person without electricity | USD 19.7 | Calculated from Tracking SDG7 figures and the 2025 market value |
| Renewable capacity added, 2024 | 585 GW | IRENA, Renewable Capacity Statistics 2025 |
| Renewable segment value per GW of 2024 additions | USD 11.2 million | Calculated from IRENA additions and the 2026 renewable share |
| Renewable capacity growth, 2024 | 15.1% | Calculated from IRENA 2024 additions and year-end capacity |
| Implied annual change in floating value relative to renewable capacity | -5.2% | Calculated from the 9.1% CAGR and IRENA 2024 capacity growth |
Analyst Perspective
“Floating power is moving from emergency rental to planned supply. Bigger gas-fired ships with dedicated LNG units now support coastal grids for years at a time, and floating solar is spreading on reservoirs. Operators that bring fuel, finance and fast delivery together will hold the strongest position through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the floating power plant market segmented?
The market is segmented into source, capacity, type, and region. Renewable-based systems are expected to lead source with 46% share in 2026, and systems up to 20 MW lead capacity with an estimated 38%.
By source: renewable (solar and wind), gas turbines, and IC engines.
By capacity: up to 20 MW, 20 MW to 100 MW, 100 MW to 250 MW, and above 250 MW.
By type: barges, ships, and others such as platforms.
By region: utilities, ports and island grids across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do renewable-based systems lead by source?
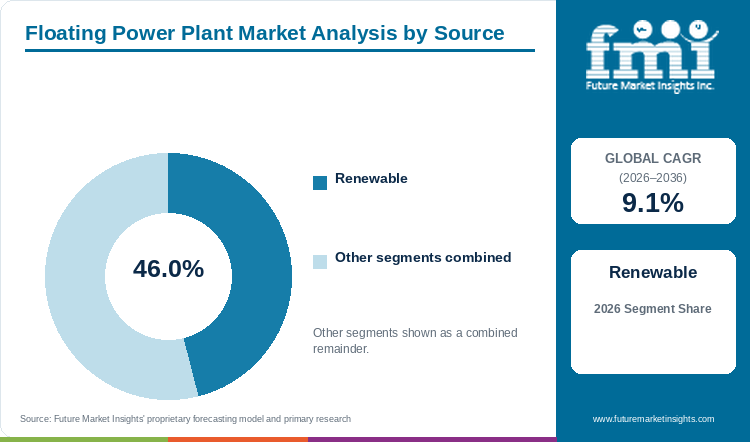
Renewable-based systems are expected to lead source sales with 46% share in 2026, ahead of gas turbines at an estimated 30.2% and IC engines near 23.8%.
Table 4: Source Share for the Floating Power Plant Market (percentage share), 2026
| Source | Estimated Share (2026) |
|---|---|
| Renewable | 46% |
| Gas Turbines | 30.2% |
| IC Engines | 23.8% |
| Total | 100.0% |
Table 5: Source Leadership and Market Growth for the Floating Power Plant Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.1% |
| Leading Segment | Renewable |
Adoption of floating solar and wind is spreading, as units on water add capacity without taking farmland. FMI puts renewable systems at 46% of 2026 sales, against 30.2% for gas turbines and 23.8% for IC engines. Use of gas turbines centres on large short-term supply contracts, and IC engines power smaller barges that start quickly. Solar dominates new capacity, making up over three-quarters of the 585 GW of renewable capacity added in 2024 [9]. Supply of panels and floats is widening with fast solar growth, which supports the renewable lead. Floating solar is already a sizeable business, as the floating solar PV market is estimated at USD 7.8 billion in 2025. Renewable units are likely to keep the lead as more reservoirs and coastal sites host panels.
- Floating solar arrays, floating offshore wind units and hybrid solar-storage platforms make up the renewable segment.
- Developers are testing new fuels for floating power, and Kinetics partnered with Amogy in December 2025 on ammonia-to-power technology [7]. Cleaner fuels could narrow the emissions gap between gas-fired ships and renewable units.
Why do systems up to 20 MW lead by capacity?
Systems up to 20 MW are expected to lead capacity sales with 38% share in 2026. Units of 20 MW to 100 MW come next at an estimated 27.6%, and 100 MW to 250 MW units hold about 19.3%.
Table 6: Capacity Share for the Floating Power Plant Market (percentage share), 2026
| Capacity | Estimated Share (2026) |
|---|---|
| Up to 20 MW | 38% |
| 20 MW to 100 MW | 27.6% |
| 100 MW to 250 MW | 19.3% |
| Above 250 MW | 15.1% |
| Total | 100.0% |
Small systems up to 20 MW lead with 38% of 2026 sales, as islands, ports, mines and remote towns need only small amounts of power. Units of 20 MW to 100 MW hold about 27.6%, plants of 100 MW to 250 MW near 19.3% and units above 250 MW about 15.1%. Large vessels serve national grids short of capacity, and in Gabon the 240 MW Deniz Sultan raised the country's floating supply from 70 MW to 150 MW in September 2025 [8]. Large ships of this kind add a lot of capacity in one step, which keeps the bigger size bands growing. On current trends, small systems keep the lead as floating solar spreads across many small reservoirs. Growth in the larger bands will come from new Whale Class and Sea Lion ships.
- Floating solar on reservoirs, small barges for ports and diesel or gas engine units for islands make up the up to 20 MW band.
- The largest ships are getting bigger, and each Whale Class Powership under the October 2026 Seatrium contract is designed for up to 600 MW [3]. Ships of this size move sales toward the above 250 MW band.
Why do barges lead by type?
Barges are expected to lead type sales with 44.8% share in 2026, ahead of ships at an estimated 39.5% and platforms and others near 15.7%.
Table 7: Type Share for the Floating Power Plant Market (percentage share), 2026
| Type | Estimated Share (2026) |
|---|---|
| Barges | 44.8% |
| Ships | 39.5% |
| Others (Platforms) | 15.7% |
| Total | 100.0% |
Barges hold an estimated 44.8% of 2026 sales, as flat hulls cost less to build and moor easily in rivers, harbours and lagoons. Use of ships suits the largest gas-fired plants, which can sail between countries, and ships hold near 39.5%. Platforms and other floating designs make up the remaining 15.7% or so. Ship-based fleets are expanding, and Karpowership has four Sea Lion Powerships of 300 MW each under construction for delivery in 2028 [2]. New ships on this scale keep ships close behind barges. Gas power is a much larger field on land, as the combined cycle power plant market is estimated at USD 35.0 billion in 2025 with a 5.5% CAGR to 2035. FMI expects barges to keep a narrow lead through 2036.
- Engine barges, turbine barges and floating solar pontoons make up the barge segment.
- Ship conversions depend on yard space, and Seatrium has delivered seven FSRU conversion projects to Karpowership since 2018 [4]. Experienced yards cut delivery times for new floating plants.
What are the drivers, restraints, and opportunities in the floating power plant market?
Key drivers of the floating power plant market include power shortages in coastal countries that need plants to arrive fast. Fuel costs, funding risk and local opposition slow some projects. Bundled LNG supply and new fuels open the way to new contracts.
- Driver: Coastal countries short of power need supply within weeks, so floating plants fill the gap until onshore plants are finished.
- Restraint: Fuel costs, weak local currencies and worries about relying on leased ships for years slow new contracts.
- Opportunity: Bundled LNG supply, mixed solar and storage platforms and low-carbon fuels let operators offer cleaner, longer contracts.
Power Shortages Drive Fast Floating Capacity
In countries with grids that cannot keep up with need, demand for floating power plants rises fastest. Sub-Saharan Africa holds 85% of the 666 million people without electricity, and 18 of the 20 countries with the largest access deficits are in the region [1]. Large gaps in coastal states favour power plants that can arrive by sea. FMI views access gaps and grid shortfalls as the main driver through 2036. Utilities will keep leasing vessels until onshore plants catch up.
Fuel and Financing Risks Slow Contracts
Finance remains the main restraint, since many host utilities have weak credit and pay in local currency. Lenders remain active, and Sea World Energy Holdings arranged a USD 400 million portfolio facility led by Mauritius Commercial Bank, the group's first portfolio financing [5]. Pooling several projects in one loan spreads country risk, which makes lending to riskier markets easier. In practice, operators with diversified fleets will secure finance on better terms. Floating gas plants form a related niche, as the floating LNG power vessel market is projected to reach USD 1.1 billion by 2034 at a 3.4% CAGR.
LNG Integration and New Fuels Open Contracts
Unlike earlier rental deals, new contracts often sell fuel and power together, and growth of the floating power plant market will depend more and more on such bundles. Kinetics completed a USD 400 million bond in November 2025 to fund the conversion of three LNG terminal ships [6]. Owning these ships lets operators supply both gas and power at ports that have no LNG terminal. Offshore generation is expanding in parallel, and the offshore wind market is projected to reach USD 360.0 billion by 2035. Operators that sell LNG and power together are likely to secure longer contracts.
Which country CAGRs are profiled in the floating power plant market?
Table 8: Country CAGR Comparison for the Floating Power Plant Market (CAGR percentage), 2026 to 2036
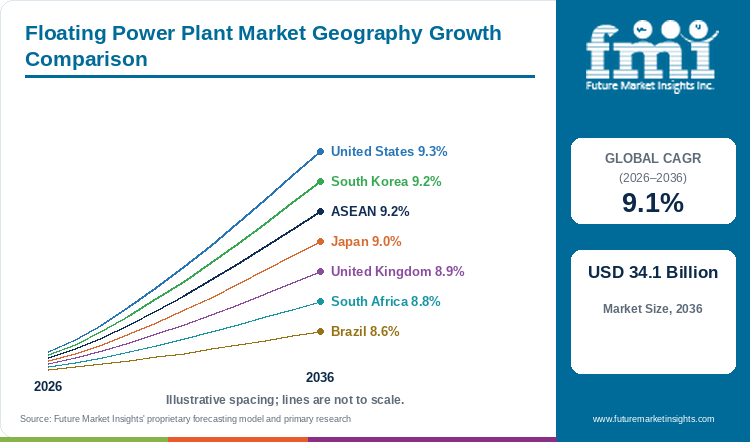
| Country | CAGR |
|---|---|
| United States | 9.3% |
| South Korea | 9.2% |
| ASEAN | 9.2% |
| Japan | 9% |
| United Kingdom | 8.9% |
| South Africa | 8.8% |
| Brazil | 8.6% |
How do country-level CAGRs compare in the floating power plant market?
The United States heads the FMI country table at 9.3%, 0.2 points over the 9.1% global CAGR, as utilities add reservoir solar and storm-recovery barges. South Korea and ASEAN share second place at 9.2%, helped by shipyards and island grids. Japan (9%), the United Kingdom (8.9%) and South Africa (8.8%) form a close middle group. Brazil is lowest at 8.6%, and the narrow 0.7-point spread reflects ships that move between regions as contracts end.
- In the United States, floating solar on reservoirs and emergency power after storms support demand, which rewards suppliers that can move quickly.
- South Korean shipyards build many of the world's powerships, so local demand gains from strong engineering skills and yard space.
- Island grids across ASEAN are hard to link by cable, so plants moored near towns offer a faster option. Operators with barges sized for small ports gain most.
- Limited flat land in Japan pushes solar onto reservoirs and ponds, steering suppliers toward small floating arrays.
- In the United Kingdom, offshore wind plans favour floating platforms for deep waters, though planning approvals move slowly.
- South Africa faces power shortfalls, and coastal gas-to-power projects create openings for operators that can meet local permit rules.
- Brazil grows at the slowest pace, as hydropower supplies most of the grid and floating units serve mainly remote river towns.
Full report country CAGRs cover: seven profiled rates within a 0.7-point band, from 8.6% in Brazil to 9.3% in the United States, with regional tables for every other standard country.
Country-wise Analysis
United States Floating Power Plant Market Outlook (2026 to 2036)
On drinking water reservoirs and irrigation ponds across the United States, utilities are adding floating solar, and the panels also reduce evaporation. Mobile power barges also help restore supply to coastal towns after hurricanes. The United States is projected to grow at a 9.3% CAGR, the highest rate among the profiled countries.
Key takeaway: Demand for floating plants in the United States will come mainly from utilities that add solar on reservoirs and keep barges ready after storms.
South Korea Floating Power Plant Market Outlook (2026 to 2036)
South Korean yards build many of the powerships used by global owners. Karpowership has four Sea Lion vessels under construction at the HSG Sungdong shipyard [2]. Domestic engineering capacity also supports floating solar on reservoirs and dams. Korean floating plant demand is set for 9.2% annual growth. Export builds also add to the income of local equipment suppliers.
Key takeaway: South Korean shipyards that build powerships for global owners will keep local demand for floating power equipment above the global rate.
ASEAN Floating Power Plant Market Outlook (2026 to 2036)
Indonesia and the Philippines run thousands of island grids that are costly to connect by cable. Floating plants moored near island towns supply power without long transmission lines. ASEAN demand is set to grow at a 9.2% CAGR, just above the global figure.
Key takeaway: Sales of floating plants in ASEAN will grow as island utilities in Indonesia and the Philippines choose moored plants over long undersea cables.
Japan Floating Power Plant Market Outlook (2026 to 2036)
With little flat land to spare, Japanese developers install solar arrays on irrigation ponds and reservoirs. Floating offshore wind projects add a second, longer-term source of demand. FMI projects a 9% CAGR for floating plants in Japan, slightly below the global rate.
Key takeaway: In Japan, developers short of flat land will keep buying floating solar for ponds and reservoirs, which holds growth near the global pace.
United Kingdom Floating Power Plant Market Outlook (2026 to 2036)
UK developers favour floating platforms for deep-water wind sites. Long planning approvals delay building, though reservoirs host smaller floating solar arrays. British demand is forecast to rise at an 8.9% CAGR.
Key takeaway: UK developers want floating platforms for deep-water wind, but slow planning approvals will keep growth a little below the global rate.
South Africa Floating Power Plant Market Outlook (2026 to 2036)
South Africa lies in a region with the world's largest access gap. About 85% of people without electricity live in sub-Saharan Africa, according to Tracking SDG7 [1]. Demand for coastal gas-to-power projects, including floating plants, is supported by shortages across the region. South African demand is set to expand at an 8.8% CAGR through 2036. Permit and grid connection rules will decide how fast projects move.
Key takeaway: Utilities in South Africa and nearby coastal states are likely to lease floating gas plants to cover power shortages as new onshore plants are built.
Brazil Floating Power Plant Market Outlook (2026 to 2036)
Buyer preference for hydropower in Brazil limits the need for floating plants as temporary supply, since dams supply most of the country's electricity. Floating solar on hydro reservoirs and power barges for Amazon towns offer smaller, niche demand. Brazilian demand is expected to rise at an 8.6% CAGR, the lowest in the table.
Key takeaway: With dams already supplying most of the grid, Brazilian buyers will order floating plants mainly for remote river towns and hydro reservoirs.
Who are the notable companies in the floating power plant market?
Karpowership, GE Power, Siemens Energy, MAN Energy Solutions, Caterpillar, Wärtsilä, Keppel Offshore & Marine, BW Offshore, Wison Offshore & Marine, MOL Group, Sevan Marine and NOV are the profiled companies.
The floating power plant market's top suppliers include operators, power equipment makers and offshore builders, and FMI sees bundled fuel and power as the main edge. Karpowership signed a contract with Seatrium in October 2026 for five Whale Class Powerships [3]. Larger ships strengthen the operator's lead in national supply contracts, which raises the bar for smaller rivals. Equipment makers compete on engines and turbines, and shipyards compete on hull conversion speed. Seatrium completed seven FSRU conversions for Karpowership by September 2026 [4]. Yard experience shortens the time from contract to first power, which favours established builders. Competition through 2036 will turn on fuel supply, financing and delivery speed.
- Floating plant operators: Karpowership and BW Offshore.
- Engine and turbine suppliers for floating hulls: GE Power, Siemens Energy, MAN Energy Solutions, Caterpillar and Wärtsilä.
- Offshore builders and marine groups: Keppel Offshore & Marine, Wison Offshore & Marine, MOL Group, Sevan Marine and NOV.
Competitive Benchmarking: Floating Power Plant Market
Table 9: Competitive Benchmarking for the Floating Power Plant Market (qualitative ratings), 2026
| Company | Fleet Scale | Fuel Integration | Engineering Depth | Recent Activity |
|---|---|---|---|---|
| Karpowership | High | High | Medium | High |
| Siemens Energy | Low | Medium | High | Medium |
| GE Power | Low | Medium | High | Medium |
| Wärtsilä | Low | Medium | High | Medium |
| BW Offshore | Medium | Medium | Medium | Low |
| Keppel Offshore & Marine | Low | High | High | High |
Ratings compare the companies on fleet scale, fuel integration, engineering depth and recent activity.
Key Developments in the Floating Power Plant Market
- Karpowership and Seatrium signed a contract on 23 October 2026 for five Whale Class Powership conversion and integration projects [3]. Ships of up to 600 MW raise the most power a single vessel can supply.
- In September 2026, Seatrium marked the sailaway of LNGT Türkiye, completing a seven-vessel FSRU programme for Karpowership [4]. Gas supply now travels with the power fleet, which lets powerships run at ports without LNG terminals.
- Karpowership announced four 300 MW Sea Lion Powerships in June 2026, due for delivery between January and May 2028 [2]. A new mid-size class lets the fleet bid for a wider range of contracts.
- Kinetics teamed up with Amogy in December 2025 on ammonia-to-power solutions for floating power [7]. Low-carbon fuels could keep floating fleets in use for longer.
- A USD 400 million portfolio financing for Sea World Energy Holdings, led by Mauritius Commercial Bank, was announced in November 2025 [5]. Bank interest in African power assets supports new power leases.
- On 5 November 2025, Kinetics completed a USD 400 million bond to fund three LNG terminal ship conversions [6]. Bond investors now fund the fuel side of floating power as well.
- The 240 MW Deniz Sultan arrived in Libreville in September 2025 and moved to domestic gas [8]. Host countries gain temporary power that costs less and emits less carbon.
Key Players in the Floating Power Plant Market
Floating Plant Operators
- Karpowership
- BW Offshore
Power Equipment Makers
- GE Power
- Siemens Energy
- MAN Energy Solutions
- Caterpillar
- Wärtsilä
Offshore Builders and Marine Groups
- Keppel Offshore & Marine
- Wison Offshore & Marine
- MOL Group
- Sevan Marine
- NOV
Floating Power Plant Market - Report Scope
Table 10: Report Scope for the Floating Power Plant Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Source; capacity; type; region |
| Quantitative units | USD billion |
| Market definition | Power generation plants mounted on ships, barges or floating platforms, including gas turbine, engine, solar and wind units, supplied for utility, industrial and emergency use. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | ASEAN; South Africa; United States; South Korea; Japan; United Kingdom; Brazil |
| Key companies profiled | Karpowership, GE Power, Siemens Energy, MAN Energy Solutions, Caterpillar, Wärtsilä, Keppel Offshore & Marine, BW Offshore, Wison Offshore & Marine, MOL Group, Sevan Marine, NOV |
| Forecast period | 2026 to 2036 |
Floating Power Plant Market - Research Methodology
Table 11: Research Methodology for the Floating Power Plant Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Coverage spans powership fleets, floating renewables, LNG supply, energy access and project finance. |
| Market Sizing | Market value covers floating generation plants and related equipment across sources, capacities, types and regions. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Floating Power Plant Market by Segments
Floating Power Plant Market segmented by Source:
- Renewable
- Gas Turbines
- IC Engines
Floating Power Plant Market segmented by Capacity:
- Up to 20 MW
- 20 MW to 100 MW
- 100 MW to 250 MW
- Above 250 MW
Floating Power Plant Market segmented by Type:
- Barges
- Ships
- Others (Platforms)
Floating Power Plant Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Energy Agency. (2025, June 25). Energy access improving, but international financial support still needed to boost progress and address disparities. https://www.iea.org/news/energy-access-improving-but-international-financial-support-still-needed-to-boost-progress-and-address-disparities
- [2] Karpowership. (2026, June 30). Karpowership Expands Global Fleet with New 300 MW "Sea Lion" Class Powerships. https://www.aap.com.au/aapreleases/cision20260630ae94265/
- [3] Karpowership. (2026, October 23). Karpowership and Seatrium Sign Contract for a Series of Whale Class Powership Conversion and Integration Projects. https://karpowership.com/media/0dxb3ram/seatrium-and-karpowership-sign-contract-for-a-series-of-whale-class-powership-conversion-and-integration-projects.pdf
- [4] Karpowership. (2026, September 23). Seatrium and Karpowership Mark Sailaway of LNGT Türkiye & Completion of Seven-Vessel FSRU Conversion Programme. https://karpowership.com/media/zqzjktwz/seatrium-and-karpowership-mark-sailaway-of-lngt-turkiye.pdf
- [5] Karpowership. (2025, November 14). Sea World Energy Holdings Secures USD 400 Million Syndicated Portfolio Financing Led by Mauritius Commercial Bank. https://karpowership.com/media/guvdup4v/sea-world_mcb-loan-pr.pdf
- [6] Kinetics. (2025, November 5). Kinetics Successfully Completes $400 Million Bond Issuance. https://karpowership.com/media/zwtbbfi3/kinetics_bond-issuance.pdf
- [7] Amogy. (2025, December 3). Kinetics Partners with Amogy to Advance Clean Energy Solutions for Floating Power and Data Center Infrastructure. https://karpowership.com/media/42xox2zz/kinetics-partners-with-amogy-to-advance-clean-energy-solutions-for-floating-power-and-data-center-infrastructure.pdf
- [8] Karpowership. (2025, September 5). Karpowership's 'Deniz Sultan' Arrives in Libreville: Doubling Capacity and Transitioning to Native Gas. https://karpowership.com/media/jaeju1ip/ga_pr_deniz-sultan-arrival_05092025.pdf
- [9] International Renewable Energy Agency. (2025, March 26). Record-Breaking Annual Growth in Renewable Power Capacity. https://www.irena.org/News/pressreleases/2025/Mar/Record-Breaking-Annual-Growth-in-Renewable-Power-Capacity
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the floating power plant market during 2026?
- What market size is projected by 2036?
- Which source holds notable share?
- Which capacity holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Renewable
- Gas Turbines
- IC Engines
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Capacity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Capacity, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Capacity, 2026 to 2036
- Up to 20 MW
- 20 MW to 100 MW
- 100 MW to 250 MW
- Above 250 MW
- Y-o-Y Growth Trend Analysis By Capacity, 2021 to 2025
- Absolute $ Opportunity Analysis By Capacity, 2026 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Type, 2026 to 2036
- Barges
- Ships
- Others (Platforms)
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Source
- By Capacity
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Capacity
- By Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Source
- By Capacity
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Capacity
- By Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Source
- By Capacity
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Capacity
- By Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Source
- By Capacity
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Capacity
- By Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Source
- By Capacity
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Capacity
- By Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Source
- By Capacity
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Capacity
- By Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Source
- By Capacity
- By Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Capacity
- By Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Capacity
- By Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Source
- By Capacity
- By Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Karpowership
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Siemens Energy
- GE Power
- Wärtsilä
- BW Offshore
- Keppel Offshore & Marine
- MAN Energy Solutions
- Caterpillar
- Wison Offshore & Marine
- MOL Group
- Sevan Marine
- NOV
- Karpowership
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Type, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Source
- Figure 6: Global Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Capacity
- Figure 9: Global Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Type
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Source
- Figure 26: North America Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Capacity
- Figure 29: North America Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Type
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Source
- Figure 36: Latin America Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Capacity
- Figure 39: Latin America Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Type
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Source
- Figure 46: Western Europe Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Capacity
- Figure 49: Western Europe Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Type
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Source
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Capacity
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Type
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Source
- Figure 66: East Asia Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Capacity
- Figure 69: East Asia Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Type
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Source
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Capacity
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Type
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Source
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Capacity
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Type
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the floating power plant market expected in 2026?
At USD 14.3 billion in 2026, up from USD 13.1 billion in 2025, the floating power plant market is growing on FMI estimates, as coastal countries lease plants that arrive fast to cover shortages.
What CAGR is projected for the floating power plant market through 2036?
A 9.1% CAGR is projected, taking sales of floating power plants to USD 34.1 billion by 2036, since power gaps and bundled LNG and power deals keep new contracts coming.
Which source holds a notable market share in 2026?
Renewable-based systems are expected to hold 46% share in 2026, given rapid growth of solar arrays on reservoirs. Gas turbines follow at about 30.2%.
Which capacity holds a notable market share in 2026?
Systems up to 20 MW are expected to hold 38%, as islands, ports and mines need small blocks of power. Units of 20 MW to 100 MW hold about 27.6%.
Which country has a notable expansion outlook through 2036?
The United States leads the FMI country outlook at a 9.3% CAGR, as utilities add reservoir solar and keep barges ready for storm recovery. South Korea and ASEAN are next at 9.2%.
Who are the key companies in the floating power plant market?
Karpowership leads the operators, and GE Power, Siemens Energy, MAN Energy Solutions, Caterpillar and Wärtsilä supply engines and turbines. Keppel Offshore & Marine, Wison and BW Offshore build and run hulls, given deep offshore engineering experience.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
