
- Market Size (2026)
- USD 725.7 Mn
- Forecast (2036)
- USD 2713.9 Mn
- CAGR (2026 to 2036)
- 14.1%
How big is Immersion Cooling Market in 2026?
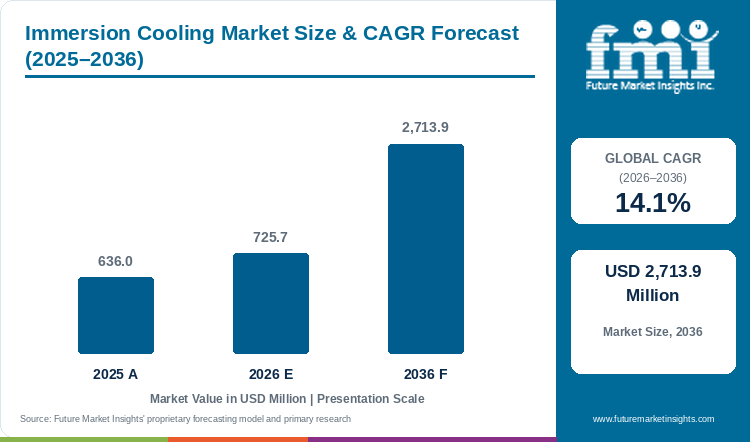
The immersion cooling market is estimated at USD 636.0 million in 2025 and is projected to reach USD 725.7 million in 2026. Sales of immersion cooling are forecast to grow at a 14.1% CAGR between 2026 and 2036 and reach USD 2,713.9 million by 2036.
Key trends in the immersion cooling market point to fluid makers moving out of the laboratory and into live server halls. With live-hall trials under way, the immersion cooling market is estimated at USD 636.0 million for 2025 and USD 725.7 million for 2026, as first tank fills reach colocation sites. FMI's model shows sales of immersion cooling expanding at a 14.1% CAGR to USD 2,713.9 million by 2036. Shell Singapore and the connectivity division of Keppel agreed in April 2026 to run Shell's gas-to-liquids immersion fluid in a server tank at an operating Keppel data centre for 12 months.[1] Shell's own benchmarks claim up to 48% better energy efficiency than air cooling and up to 40% lower capital and operating costs.[1]
For data center operators, a twelve-month test inside a working facility gives procurement teams field data on fluid life and server warranties before any hall-wide order. New-build halls, expected to account for 41% of deployment sales in 2026, let owners design tanks, floor loading and heat rejection around immersion from the first drawing. Operators retrofitting older halls face longer approval cycles, since every tank row needs structural checks. Shell and other fluid makers with published field results will hold the stronger position in supply talks, as hyperscale buyers want proven fluid behaviour before multi-year terms.
Key Market Trends & Insights
- Synthetic hydrocarbons are expected to lead fluid chemistry with 55% share in 2026, as gas-to-liquids and PAO fluids cost less per litre than fluorinated grades, which hold an estimated 13.6%.
- Adoption of immersion tanks is highest in new-build data centers, likely to account for 41% of deployment sales in 2026, against about 24.6% for retrofits in existing halls. Chemours and 2CRSi signed a joint development agreement in February 2026 for two-phase cooling of 15 kW, 1U GPU servers.[2]
- By application, AI training and inference clusters hold an estimated 31.4% in 2026 and high-performance computing about 22.7%, as GPU racks run far above the heat limits of room air.
Regional Highlights
- India comes first of the countries covered, with a 17.3% CAGR, as Infosys and ExxonMobil build immersion programmes for AI data centres and Navin Fluorine prepares two-phase fluid output.
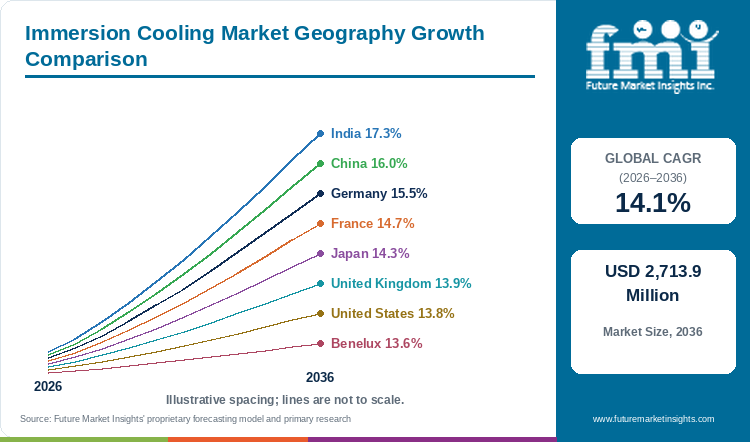
- China follows on 16%, ahead of Germany on 15.5%, and France and Japan stay close to the global pace. The United Kingdom and the United States are a fraction behind the 14.1% figure, and Benelux, at 13.6%, is lowest in the table.
- Cosmo Lubricants in Japan added Cosmo Thermal Fluid for data centers in January 2026 and plans a type with a flash point of 250°C or higher to meet the Fire Service Act.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Immersion Cooling Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 636.0 million |
| Estimated Market Size in 2026 | USD 725.7 million |
| Projected Market Size by 2036 | USD 2,713.9 million |
| CAGR, 2026 to 2036 | 14.1% |
| Added Revenue, 2026 to 2036 | USD 1,988.3 million |
| Market Expansion Multiple | 3.7x |
Orders for immersion systems arrive as a first fill of fluid and tanks for each new hall, followed by top-ups and fluid swaps over the server life. Chemours set commercial production of the Opteon two-phase fluid for 2026 through a manufacturing agreement with Navin Fluorine.[4] Castrol said in May 2026 that the Castrol ON DC 15 and DC 20 immersion fluids are expected to follow PG 25 into the OCP Marketplace.[5] Dielectric coolants for direct-to-chip and immersion loops share base stocks, and the liquid cooling dielectrics market is on a 7.4% CAGR forecast, about half the pace of tank-based systems, so fluid blenders will steer new capacity toward immersion grades. The forecast implies USD 1,988.3 million of new immersion cooling sales over the decade, and the FMI outlook gives a 2036 immersion cooling market 3.7 times the 2026 level. Slow server warranty approvals remain the main risk, since operators will not fill a tank without vendor sign-off.
Fluid Qualification, Server Partnerships and Supply
Fluid qualification is the gate to volume. Chemours qualified Opteon 2P50 in current 2CRSi servers after several years of testing on the Atlantis and Octopus platforms, and the two companies formalised a joint development agreement on 24 February 2026.[2] Fuchs launched RENOLIN FECC 10 SYN in August 2025 as a single-phase fluid certified to UL 2417 and meeting Open Compute Project requirements.[6] Certified fluids shorten the safety review for colocation landlords, who insure halls against fire and electrical faults.
Server and service partnerships carry fluid into new accounts. Infosys expanded the collaboration with ExxonMobil in February 2026 to develop and deploy ExxonMobil Data Center Immersion Fluids through Infosys Topaz and Infosys Cobalt.[7] Submer added Hammer Distribution and Boston Ltd. as UK partners in March 2026 to widen liquid cooling sales.[8] Distributors and integrators bundling tanks, fluid and monitoring will reach enterprise buyers faster than fluid makers selling alone.
Table 2: Qualification, Partnership and Supply Indicators for the Immersion Cooling Market (dates, claims and sales), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Shell and Keppel immersion pilot, April 2026 | 12-month test; up to 48% better energy efficiency claimed | Live data centre proof for GTL fluid | [1] |
| Chemours and Navin Fluorine, May 2025 | Opteon two-phase fluid production from 2026; GWP of 10 | New two-phase fluid supply | [4] |
| Chemours and 2CRSi, February 2026 | Joint development agreement; 15 kW 1U GPU servers | Server qualification for two-phase | [2] |
| Fuchs RENOLIN FECC 10 SYN, August 2025 | UL 2417 certified single-phase fluid | Faster safety approval | [6] |
| Castrol ON fluids, May 2026 | DC 15 and DC 20 immersion fluids to follow PG 25 | Open Compute supply channel | [5] |
| Cosmo Lubricants, January 2026 | Flash point type of 250°C or higher planned | Fire code fit in Japan | [3] |
| Fuchs group, H1 2026 | Sales of EUR 2,003 million, up 11% | Lubricant group capacity behind fluids | [9] |
Analyst Perspective
“I see the next five years of immersion cooling decided inside server warranties, since the first fluid approved for a GPU platform travels with that platform into every hall. Retrofit halls fitted with single-phase tanks are opening a refill annuity for synthetic hydrocarbon suppliers, and I would expect the suppliers with OEM approvals to keep those accounts through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the immersion cooling market segmented?
The market is segmented into fluid chemistry, deployment model, application, and region. GTL and PAO base stocks give synthetic hydrocarbons the fluid lead at 55% in 2026, and AI clusters are ahead by application at an estimated 31.4%.
By fluid chemistry: synthetic hydrocarbons, silicone oils, fluorinated fluids, esters and specialty dielectric blends, and others.
By deployment model: new-build data centers, retrofit in existing halls, on-premises HPC labs and universities, and edge micro-sites and containers.
By application: high-performance computing, AI training and inference clusters, cryptocurrency mining, edge, telecom and MEC, enterprise and colocation general compute, and others.
By region: hyperscale, colocation, research and edge sites in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do synthetic hydrocarbons lead immersion cooling sales by fluid chemistry?
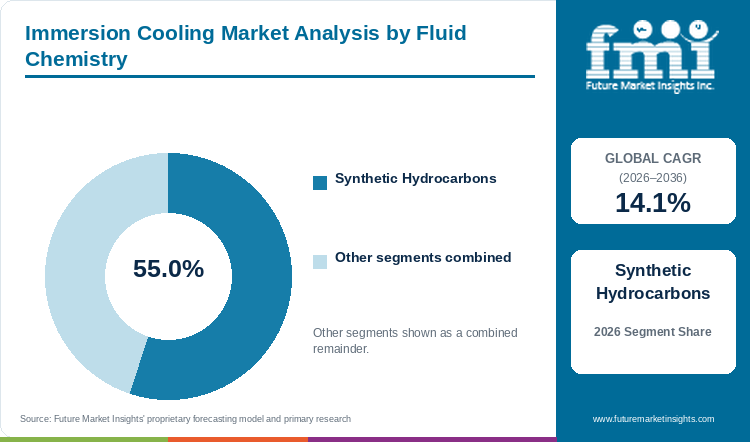
Synthetic hydrocarbons are expected to lead fluid chemistry sales with 55% share in 2026, ahead of esters and specialty dielectric blends at an estimated 14.2% and fluorinated fluids at about 13.6%.
Table 3: Fluid Chemistry Share for the Immersion Cooling Market (percentage share), 2026
| Fluid Chemistry | Estimated Share (2026) |
|---|---|
| Synthetic Hydrocarbons | 55% |
| Esters and Specialty Dielectric Blends | 14.2% |
| Fluorinated Fluids | 13.6% |
| Silicone Oils | 11.4% |
| Others | 5.8% |
| Total | 100.0% |
Table 4: Fluid Chemistry Leadership and Market Growth for the Immersion Cooling Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 14.1% |
| Leading Segment | Synthetic Hydrocarbons |
Single-phase tanks need a stable, low-cost oil that stays liquid, and gas-to-liquids and PAO fluids from Shell, ExxonMobil and Fuchs meet that need, so synthetic hydrocarbons are expected to lead in 2026, at a 55% share. Bio-based feedstocks and a high flash point give esters and specialty dielectric blends an estimated 14.2%, though fewer server makers have approved them. Fluorinated fluids, at about 13.6%, boil at low temperature to remove heat in two-phase tanks, and Chemours rates the Opteon fluid at a global warming potential of 10.[4] Those fluids cost far more per litre, and PFAS scrutiny makes some buyers cautious. Sealed edge units favour silicone oils, near 11.4%, and other chemistries hold 5.8%. Electric vehicle battery packs use the same dielectric logic, and the automotive immersion cooling dielectric fluid market has an expected 17.4% CAGR, which gives fluid makers a second outlet for the same base stocks. Data center buyers will keep choosing hydrocarbon fluids for large halls and reserve two-phase fluids for the densest GPU racks.
- GTL fluids, PAO blends and hydrotreated synthetic oils make up most single-phase volume.
- RENOLIN FECC 10 SYN from Fuchs was described in August 2025 as the first immersion coolant certified to UL 2417.[6]
Why do new-build data centers lead immersion cooling sales by deployment model?
New-build data centers are likely to lead deployment sales with 41% share in 2026, with retrofits in existing halls near 24.6% and on-premises HPC labs and universities at about 19.8%.
Table 5: Deployment Model Share for the Immersion Cooling Market (percentage share), 2026
| Deployment Model | Estimated Share (2026) |
|---|---|
| New-Build Data Centers | 41% |
| Retrofit in Existing Halls | 24.6% |
| On-Premises HPC Labs and Universities | 19.8% |
| Edge Micro-Sites and Containers | 14.6% |
| Total | 100.0% |
Designers of a new hall can drop raised floors, size heat rejection for warm fluid and place tanks from the start, so new-build data centers are likely to lead in 2026, holding a 41% share. Floor loading limits and running air systems slow retrofits in existing halls, which account for an estimated 24.6%. Research budgets set the timing for on-premises HPC labs and universities, and a typical order of a few tanks for one cluster keeps that group near 19.8%. Telecom huts and remote sites call for sealed units, and small order sizes hold edge micro-sites and containers to about 14.6%. Prefabricated halls shipped as blocks are part of this pattern, and the modular data center market is forecast near a 13.8% CAGR, close to the immersion pace, so tank makers will design units that fit factory-built modules. Submer said in March 2026 that the company's designs achieve zero direct water consumption.[8] Developers will choose immersion at the design stage, and retrofit buyers will follow once server warranties cover immersion.
- Hyperscale campuses, AI colocation halls and sovereign compute sites form the new-build base.
- Shell and Keppel planned the Shell fluid pilot inside an operating Keppel facility from May 2026, a retrofit-style test in a live hall.[1]
Why do AI training and inference clusters lead immersion cooling sales by application?
AI training and inference clusters are projected to lead application sales with an estimated 31.4% share in 2026, ahead of high-performance computing at about 22.7% and cryptocurrency mining near 18.3%.
Table 6: Application Share for the Immersion Cooling Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| AI Training and Inference Clusters | 31.4% |
| High-Performance Computing | 22.7% |
| Cryptocurrency Mining | 18.3% |
| Enterprise and Colocation General Compute | 13.2% |
| Edge, Telecom and MEC | 8.9% |
| Others | 5.5% |
| Total | 100.0% |
GPU servers built for training large models pack eight accelerators into a few rack units, and room air cannot carry that heat away, so AI training and inference clusters will lead in 2026 at an estimated 31.4% share. National labs have used liquid cooling for years, but long replacement cycles hold high-performance computing to about 22.7%. ASIC rigs went into tanks early, and swings in coin prices leave cryptocurrency mining near 18.3% with uneven orders. Lower rack power keeps most enterprise and colocation general compute on air, at an estimated 13.2%. Compact sealed units serve edge, telecom and MEC sites at 8.9%, and other uses add 5.5%. The 2CRSi Atlas 1.8GG 2PIC server carries eight NVIDIA H200 GPUs in a 1U format for two-phase immersion.[2] AI hosting firms will keep ordering the largest tank volumes, as each new GPU generation raises rack heat again.
- Model training halls, inference clusters and GPU-as-a-service hosts form the core AI demand.
- Infosys named hyperscalers, telecom, financial services and government among the targets for immersion programmes with ExxonMobil in February 2026.[7]
What are the drivers, restraints, and opportunities in the immersion cooling market?
Rising rack heat from AI accelerators is pushing operators past the limits of air cooling. Server warranty approvals and the higher first cost of tanks slow adoption, and retrofits of older halls open a large second market for fluid and tank suppliers.
- Driver: Each new GPU generation raises heat per rack, and operators who reach the limit of air handling move straight to liquid in the tank or on the chip.
- Restraint: Server makers still approve only a few fluids for warranty cover, so operators hesitate to submerge expensive accelerators in an unlisted coolant.
- Opportunity: Older halls with spare floor area but limited air capacity can add tank rows, giving fluid makers and integrators a retrofit channel alongside new campuses.
Rising Rack Heat Moves Operators to Liquid
Sales of immersion systems grow each time chip makers raise the power of a server board. Chemours targets 15 kW 1U servers powered by NVIDIA GPUs with 2CRSi, a heat load that room air handlers cannot remove.[2] Castrol's Peter Huang said in May 2026 that liquid cooling is on pace to become the primary cooling method for data centers within two years.[5] Operators planning the next GPU refresh will budget for liquid at the design stage.
Warranty Approval Slows Fluid Adoption
Producers of immersion fluid face a qualification queue at each server maker. Chemours and 2CRSi needed several years of testing on the Atlantis and Octopus servers before signing a development agreement.[2] Fuchs pursued UL 2417 certification for RENOLIN FECC 10 SYN to give insurers and landlords an independent safety mark.[6] Due to this, buyers will keep shortlists to fluids with OEM approval, and newcomers will need two to three years to enter a hyperscale account.
Retrofits and Fluid Refills Open a Second Market
Sales of immersion cooling will also come from halls that already exist. Keppel chose an operating data centre for the Shell pilot, which tests immersion inside a site built for air.[1] Cosmo Lubricants plans a low-viscosity type for higher cooling efficiency alongside the Fire Service Act grade.[3] As a result, fluid makers will compete for refill contracts in retrofit halls, as a first fill leads to years of top-ups.
Which country CAGRs are profiled in the immersion cooling market?
Table 7: Country CAGR Comparison for the Immersion Cooling Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 17.3% |
| China | 16% |
| Germany | 15.5% |
| France | 14.7% |
| Japan | 14.3% |
| United Kingdom | 13.9% |
| United States | 13.8% |
| Benelux | 13.6% |
How do country-level CAGRs compare in the immersion cooling market?
Navin Fluorine in India is set to manufacture Chemours' Opteon two-phase fluid, with commercial production planned from 2026.[4] On FMI's model, India grows at 17.3%, first among the countries covered, as Infosys and ExxonMobil develop immersion programmes for AI data centres. China, at 16%, adds AI computing halls in western provinces with power to spare. Germany follows at 15.5%, about 1.4 points clear of the 14.1% global CAGR, on tight efficiency rules for new halls. France, 14.7%, and Japan, 14.3%, run just above the global line. The United Kingdom grows at 13.9%, and the United States is a tenth of a point lower at 13.8%, both a shade short of the 14.1% rate for the market as a whole, since large air-cooled fleets in both countries slow conversion. Benelux, at 13.6%, is held back by grid limits on new data centers around Amsterdam.
- Two-phase fluid manufacturing and AI hosting push India to the top of the table.
- Large AI computing parks in western provinces drive tank orders in China.
- Strict efficiency targets for new halls favour liquid cooling in Germany.
- French server maker 2CRSi is qualifying two-phase immersion for GPU servers.
- Japanese fire rules shape the flash point of fluids sold in Japan.
- New UK distribution partners are bringing immersion to enterprise buyers in the United Kingdom.
- American hyperscalers hold the largest installed base, and conversions in the United States follow GPU refresh cycles.
- Grid caps around Amsterdam limit new halls in Benelux.
Full report country CAGRs cover: India at the top with 17.3%, Benelux at the floor with 13.6%, six further profiled rates between them, and each standard-list country grouped by region.
Country-wise Analysis
India Immersion Cooling Market Outlook (2026 to 2036)
Infosys announced from Bengaluru on 12 February 2026 an expanded collaboration with ExxonMobil to develop and deploy immersion fluids through the Infosys Topaz and Infosys Cobalt platforms.[7] Chemours chose Navin Fluorine to manufacture the Opteon two-phase fluid, so India will host fluid supply as well as demand.[4] India's 17.3% CAGR is the highest in the table.
Key takeaway: Local fluid output and services partners such as Infosys make India the fastest market for immersion cooling.
China Immersion Cooling Market Outlook (2026 to 2036)
Cloud groups and state computing parks in China are building AI clusters in western provinces with cheap power and dry air. Domestic tank makers supply many of those halls, and local lubricant groups blend hydrocarbon fluids. FMI's forecast for China is a 16% CAGR, with GPU density setting the pace of tank orders.
Key takeaway: AI park construction keeps China second in the table.
Germany Immersion Cooling Market Outlook (2026 to 2036)
Mannheim-based Fuchs, maker of the RENOLIN FECC 10 SYN immersion fluid, reported first-half 2026 sales of EUR 2,003 million, up 11%, and raised the EBIT outlook for 2026.[9] German halls face strict energy efficiency targets and heat reuse rules, and immersion tanks return warm fluid that district heating networks can use. Fluid formulators supplying German sites also serve industrial customers, and the synthetic lubricants and functional fluids market is predicted to expand 5.4% on a CAGR basis, so data center grades will carry the faster growth inside those product ranges. FMI projects a 15.5% CAGR for Germany.
Key takeaway: Efficiency and heat reuse rules make Germany the fastest-growing profiled market in Western Europe.
France Immersion Cooling Market Outlook (2026 to 2036)
Strasbourg-based 2CRSi qualified Chemours' Opteon 2P50 fluid in current servers and signed a joint development agreement on 24 February 2026.[2] A domestic server maker with qualified two-phase designs gives French operators a local route to dense GPU racks. FMI's figure for France is a 14.7% CAGR.
Key takeaway: A local server maker brings two-phase immersion to French halls.
Japan Immersion Cooling Market Outlook (2026 to 2036)
Japan's Fire Service Act governs flammable liquids in buildings, so Cosmo Lubricants plans a Cosmo Thermal Fluid type with a flash point of 250°C or higher.[3] Cosmo already supplies thermal greases and gap fillers to electronics makers, and a 5.1% CAGR is expected for the thermal interface material market, which leaves immersion fluid as the faster-growing line for Japanese thermal suppliers. Japanese operators are expected to raise immersion cooling purchases at a 14.3% CAGR, as fire-rated fluids reach the market.
Key takeaway: Fire code compliance decides which fluids Japanese operators buy.
United Kingdom Immersion Cooling Market Outlook (2026 to 2036)
Submer added Hammer Distribution and Boston Ltd. as partners on 4 March 2026 to expand liquid cooling sales in the United Kingdom.[8] Castrol plans to place the Castrol ON DC 15 and DC 20 immersion fluids in the OCP Marketplace.[5] Submer named financial services, healthcare and higher education as growing sources of UK demand.[8] Those buyers will set the pace, and the 13.9% CAGR forecast for the United Kingdom reflects a large air-cooled base.
Key takeaway: Distribution partners widen access to immersion for British enterprise buyers.
United States Immersion Cooling Market Outlook (2026 to 2036)
In the United States, Chemours set commercial production of Opteon two-phase fluid for 2026 and says cooling energy use could fall by up to 90%.[4] American hyperscalers run the largest fleet of air-cooled halls, so conversion moves one GPU refresh at a time. On the largest base of immersion cooling sales, the United States will grow at 13.8% on a CAGR basis.
Key takeaway: A vast installed base makes the United States the volume anchor, growing near the global pace.
Benelux Immersion Cooling Market Outlook (2026 to 2036)
Grid operators around Amsterdam have limited connections for new data centers, which pushes developers toward denser halls on existing plots. Dense halls favour liquid cooling, but fewer new sites cap the volume. Benelux closes the table, with FMI placing growth at a 13.6% CAGR.
Key takeaway: Grid limits keep Benelux at the bottom of the table despite steady orders for dense cooling.
Who are the notable companies in the immersion cooling market?
Shell, ExxonMobil, Dow, Fuchs, Castrol, Chemours, Lubrizol, Engineered Fluids, M&I Materials, Cosmo Lubricants, Green Revolution Cooling and Submer are the profiled companies.
Top companies operating in the immersion cooling market fall into oil majors with synthetic base stocks, specialty chemical makers with dielectric and fluorinated fluids, and tank integrators. Shell is running a 12-month pilot with Keppel in Singapore.[1] Chemours is working with Navin Fluorine on supply and with 2CRSi on server qualification.[4][2] Fuchs certified a single-phase fluid to UL 2417, and Castrol is placing Castrol ON immersion fluids in the OCP Marketplace.[6][5] FMI's model shows these partnerships between fluid makers, server makers and integrators shaping which fluids enter hyperscale halls.
- Oil majors and lubricant groups: Shell, ExxonMobil, Fuchs, Castrol and Cosmo Lubricants.
- Specialty chemical makers: Chemours, Dow, Lubrizol, Engineered Fluids and M&I Materials.
- Tank and system integrators: Green Revolution Cooling and Submer.
Competitive Benchmarking: Immersion Cooling Market
Table 8: Competitive Benchmarking for the Immersion Cooling Market (qualitative documentation ratings), 2026
| Company | Single-Phase Fluids | Two-Phase Fluids | Server Partnerships | Recency |
|---|---|---|---|---|
| Shell | High | Low | High | High |
| Chemours | Low | High | High | High |
| Fuchs | High | Low | Medium | Medium |
| Castrol | High | Low | Medium | High |
| Submer | Medium | Low | High | High |
Ratings follow the volume of dated 2025 and 2026 company evidence on fluids and server partnerships, with no link to market share.
Key Developments in the Immersion Cooling Market
- On 31 July 2026, Fuchs reported first-half sales of EUR 2,003 million and raised the 2026 EBIT outlook to EUR 460 million to EUR 480 million.[9]
- On 6 May 2026, Castrol said the Castrol ON DC 15 and DC 20 immersion fluids are expected to follow PG 25 into the OCP Marketplace.[5]
- On 20 April 2026, Shell Singapore and Keppel announced an immersion cooling testbed using Shell GTL fluid.[1]
- On 4 March 2026, Submer named Hammer Distribution and Boston Ltd. as UK partners.[8]
- On 24 February 2026, Chemours and 2CRSi formalised a joint development agreement on two-phase cooling.[2]
- On 12 February 2026, Infosys expanded the ExxonMobil collaboration on data center immersion fluids.[7]
- On 27 January 2026, Cosmo Lubricants added Cosmo Thermal Fluid to the Cosmo Thermal series.[3]
- On 8 August 2025, Fuchs launched RENOLIN FECC 10 SYN.[6]
- On 6 May 2025, Chemours signed Navin Fluorine to manufacture Opteon two-phase fluid.[4]
Key Players in the Immersion Cooling Market
Oil Majors and Lubricant Groups
- Shell
- ExxonMobil
- Fuchs
- Castrol
- Cosmo Lubricants
Specialty Chemical Makers
- Chemours
- Dow
- Lubrizol
- Engineered Fluids
- M&I Materials
Tank and System Integrators
- Green Revolution Cooling
- Submer
Immersion Cooling Market - Report Scope
Table 9: Report Scope for the Immersion Cooling Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Fluid chemistry; deployment model; application; region |
| Quantitative units | USD million |
| Market definition | Single-phase and two-phase dielectric fluids and immersion systems that cool servers, GPUs and network equipment by submerging them in a non-conductive liquid in data centers, research labs and edge sites. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Shell, ExxonMobil, Fuchs, Castrol, Cosmo Lubricants, Chemours, Dow, Lubrizol, Engineered Fluids, M&I Materials, Green Revolution Cooling, Submer |
| Forecast period | 2026 to 2036 |
Immersion Cooling Market - Research Methodology
Table 10: Research Methodology for the Immersion Cooling Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Fluid maker and server maker releases, technology services announcements, lubricant group results and data center trade press from May 2025 onward. |
| Desk Research | Desk research covers fluid chemistry, server qualification, fire and safety certification, retrofit practice and data center construction. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 725.7 million and the 14.1% CAGR for 2026 to 2036. |
| Data Validation | Product claims, dates and sales figures were matched to the release or article that first published them. |
Immersion Cooling Market by Segments
Immersion Cooling Market segmented by Fluid Chemistry:
- Synthetic Hydrocarbons
- Silicone Oils
- Fluorinated Fluids
- Esters and Specialty Dielectric Blends
- Others
Immersion Cooling Market segmented by Deployment Model:
- New-Build Data Centers
- Retrofit in Existing Halls
- On-Premises HPC Labs and Universities
- Edge Micro-Sites and Containers
Immersion Cooling Market segmented by Application:
- High-Performance Computing
- AI Training and Inference Clusters
- Cryptocurrency Mining
- Edge, Telecom and MEC
- Enterprise and Colocation General Compute
- Others
Immersion Cooling Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Shell Singapore. (2026, April 20). Shell and Keppel to launch advanced immersion liquid cooling testbed for more sustainable data centres. https://www.shell.com.sg/about-us/news-and-insights/media/2026-media-releases/shell-keppel-advanced-immersion-liquid-cooling-testbed-sustainable-data-centres.html
- [2] 2CRSi and The Chemours Company. (2026, February 24). Chemours and 2CRSi join forces to accelerate deployment of two-phase liquid cooling. https://investors.2crsi.com/wp-content/uploads/2026/02/Chemours-and-2CRSi-join-forces-to-accelerate-deployment-of-two-phase-liquid-cooling.pdf
- [3] Cosmo Energy Holdings. (2026, January 27). Cosmo Lubricants adds Cosmo Thermal Fluid immersion cooling fluid for data centers. https://www.cosmo-energy.co.jp/content/dam/corp/jp/ja/press/2026/260127-01/260127jp_01.pdf
- [4] The Chemours Company. (2025, May 6). Chemours and Navin Fluorine Announce Agreement to Manufacture New Liquid Cooling Product as a Part of Chemours Expanded Liquid Cooling Venture. Business Wire. https://www.businesswire.com/news/home/20250506107731/en/Chemours-and-Navin-Fluorine-Announce-Agreement-to-Manufacture-New-Liquid-Cooling-Product-as-a-Part-of-Chemours-Expanded-Liquid-Cooling-Venture
- [5] StorageNewsletter. (2026, May 6). OCP EMEA Summit 2026: Castrol ON advances liquid cooling strategy with OCP Inspired portfolio. https://www.storagenewsletter.com/2026/05/06/ocp-emea-summit-2026-castrol-on-advances-liquid-cooling-strategy-with-ocp-inspired-portfolio/
- [6] DatacenterDynamics. (2025, August 8). Fuchs Lubricants Co. launches RENOLIN FECC 10 SYN. https://www.datacenterdynamics.com/en/product-news/fuchs-lubricants-co-launches-renolin-fecc-10-syn/
- [7] Infosys. (2026, February 12). Infosys Collaborates with ExxonMobil to Advance Immersion Cooling for Sustainable AI Infrastructure. https://www.infosys.com/newsroom/press-releases/2026/collaborates-advance-immersion-cooling.html
- [8] Submer. (2026, March 4). Submer strengthens UK presence with new partners to accelerate liquid cooling adoption. https://submer.com/blog/press/strengthening-uk-presence-with-new-partners-to-accelerate-liquid-cooling-adoption/
- [9] FUCHS SE. (2026, July 31). FUCHS reports strong first half of 2026. https://www.fuchs.com/group/press/press-releases/company-business-finances/news-detail/view/10377-FUCHS-reports-strong-first-half-of-2026/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the immersion cooling market during 2026?
- What market size is projected by 2036?
- Which fluid chemistry holds notable share?
- Which deployment model holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Fluid Chemistry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Fluid Chemistry, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Fluid Chemistry, 2026 to 2036
- Synthetic Hydrocarbons
- Silicone Oils
- Fluorinated Fluids
- Esters and Specialty Dielectric Blends
- Others
- Y-o-Y Growth Trend Analysis By Fluid Chemistry, 2021 to 2025
- Absolute $ Opportunity Analysis By Fluid Chemistry, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment Model, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Deployment Model, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Deployment Model, 2026 to 2036
- New-Build Data Centers
- Retrofit in Existing Halls
- On-Premises HPC Labs and Universities
- Edge Micro-Sites and Containers
- Y-o-Y Growth Trend Analysis By Deployment Model, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment Model, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- High-Performance Computing
- AI Training and Inference Clusters
- Cryptocurrency Mining
- Edge, Telecom and MEC
- Enterprise and Colocation General Compute
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Fluid Chemistry
- By Deployment Model
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Fluid Chemistry
- By Deployment Model
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Fluid Chemistry
- By Deployment Model
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Fluid Chemistry
- By Deployment Model
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Fluid Chemistry
- By Deployment Model
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Fluid Chemistry
- By Deployment Model
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Fluid Chemistry
- By Deployment Model
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Fluid Chemistry
- By Deployment Model
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Fluid Chemistry
- By Deployment Model
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Fluid Chemistry
- By Deployment Model
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Fluid Chemistry
- By Deployment Model
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Fluid Chemistry
- By Deployment Model
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Fluid Chemistry
- By Deployment Model
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Fluid Chemistry
- By Deployment Model
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- Benelux
- Pricing Analysis
- Market Share Analysis, 2025
- By Fluid Chemistry
- By Deployment Model
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Fluid Chemistry
- By Deployment Model
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Shell
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Chemours
- Fuchs
- Castrol
- Submer
- ExxonMobil
- Cosmo Lubricants
- Dow
- Lubrizol
- Engineered Fluids
- M&I Materials
- Green Revolution Cooling
- Shell
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Fluid Chemistry, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Deployment Model, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Fluid Chemistry, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Deployment Model, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by Fluid Chemistry, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Deployment Model, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Fluid Chemistry, 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Deployment Model, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Million) Forecast by Fluid Chemistry, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Million) Forecast by Deployment Model, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Fluid Chemistry, 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Deployment Model, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Fluid Chemistry, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Deployment Model, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Million) Forecast by Fluid Chemistry, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Million) Forecast by Deployment Model, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Million) Forecast by Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Fluid Chemistry, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Fluid Chemistry, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Fluid Chemistry
- Figure 6: Global Market Value Share and BPS Analysis by Deployment Model, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Deployment Model, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Deployment Model
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Fluid Chemistry, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Fluid Chemistry, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Fluid Chemistry
- Figure 26: North America Market Value Share and BPS Analysis by Deployment Model, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Deployment Model, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Deployment Model
- Figure 29: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Application
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Fluid Chemistry, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Fluid Chemistry, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Fluid Chemistry
- Figure 36: Latin America Market Value Share and BPS Analysis by Deployment Model, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Deployment Model, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Deployment Model
- Figure 39: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Application
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Fluid Chemistry, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Fluid Chemistry, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Fluid Chemistry
- Figure 46: Western Europe Market Value Share and BPS Analysis by Deployment Model, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Deployment Model, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Deployment Model
- Figure 49: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Application
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Fluid Chemistry, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Fluid Chemistry, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Fluid Chemistry
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Deployment Model, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Deployment Model, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Deployment Model
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Application
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Fluid Chemistry, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Fluid Chemistry, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Fluid Chemistry
- Figure 66: East Asia Market Value Share and BPS Analysis by Deployment Model, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Deployment Model, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Deployment Model
- Figure 69: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Application
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Fluid Chemistry, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Fluid Chemistry, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Fluid Chemistry
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Deployment Model, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Deployment Model, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Deployment Model
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Fluid Chemistry, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Fluid Chemistry, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Fluid Chemistry
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Deployment Model, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Deployment Model, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Deployment Model
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the immersion cooling market expected in 2026?
FMI sizes the immersion cooling market at USD 725.7 million in 2026, up from USD 636.0 million in 2025. The immersion cooling market is projected to reach USD 2,713.9 million by 2036.
What CAGR is projected for the immersion cooling market through 2036?
Sales of immersion cooling are expected to grow at a 14.1% CAGR from 2026 to 2036. Rising heat from AI accelerators is the main driver of that growth.
Which fluid chemistry holds a notable market share in 2026?
Synthetic hydrocarbons are expected to lead with 55% share in 2026. Esters and specialty dielectric blends follow at an estimated 14.2%.
Which deployment model holds a notable market share in 2026?
New-build data centers are likely to lead with 41% share. Retrofits in existing halls hold about 24.6%.
Which country has a notable expansion outlook through 2036?
India grows fastest at a 17.3% CAGR in FMI's country ranking. China is next at 16%.
Who are the key companies in the immersion cooling market?
Shell, ExxonMobil, Fuchs, Castrol and Cosmo Lubricants supply hydrocarbon fluids, and Chemours, Dow, Lubrizol, Engineered Fluids and M&I Materials supply specialty fluids. Green Revolution Cooling and Submer build tanks and systems.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
