

- Market Size (2026)
- USD 689.4 Mn
- Forecast (2036)
- USD 1587.7 Mn
- CAGR (2026 to 2036)
- 8.7%
How big is Madeleines Market in 2026?
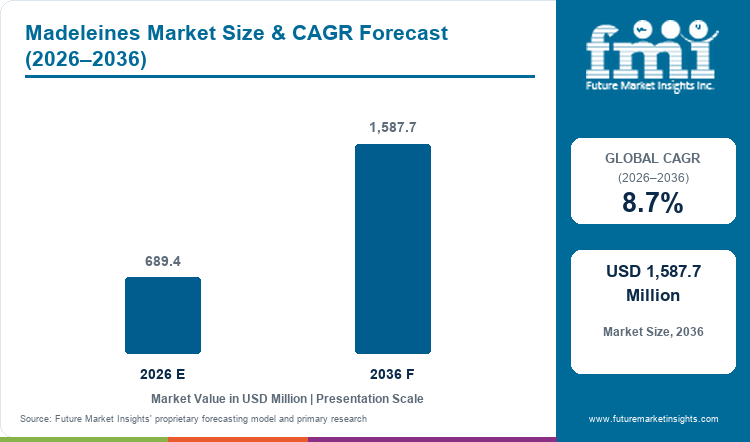
USD 689.4 million in 2026 and USD 1,587.7 million by 2036 at an 8.7% CAGR.
Demand for madeleines is projected to expand at 8.7% CAGR between 2026 and 2036, increasing valuation from USD 689.4 million in 2026 to USD 1,587.7 million by 2036. Retail and foodservice growth depends on portioned bakery outlets can stage without specialist pastry labor. Dessert Holdings returned to IDDBA in May 2025 with thaw-and-serve desserts for retail and foodservice customers.
Japan uses a different route from specialist-bakery markets because convenience stores give compact sweet bakery repeated food-to-go exposure. METI counted 56,557 Japanese convenience stores in April 2026, up 1.1% from the prior year. Madeleines fit that retail density if packaging protects crumb softness and serving economics during frequent assortment resets.
Key Takeaways
- Retailers and foodservice operators can widen madeleine occasions with compact portions that require limited finishing and preserve familiar bakery quality.
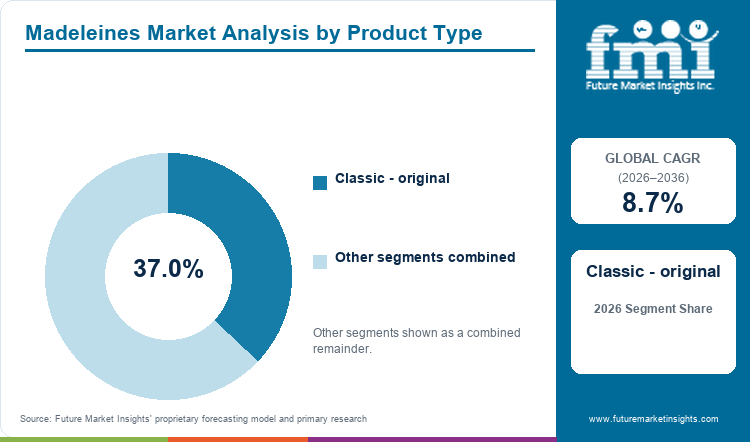
- By product type, classic - original is estimated to hold 37.0% in 2026 owing to familiar shell shape and simple flavor expectations at repeat purchase.
- Conventional is projected to hold 59.0% share in 2026 attributable to the standard butter-rich recipe and expected browning profile.
- In 2026, fresh is expected to lead format with 30.0% share because immediate softness and bakery aroma remain visible at purchase.
- Shelf-life extension weakens margin if moisture loss or reformulation removes the sensory qualities that justify a madeleine listing.
- Some of the key players in this market include Rich Products, Sara Lee Frozen Bakery, Dessert Holdings, Emmi Desserts, Finsbury Food Group, Premier Foods, McKee Foods, Hostess (The J.M. Smucker Co.), Bauli, and Dr. Oetker.
Analyst Perspective
"Madeleines earn repeat listings when the served crumb still reads as fresh after storage and handling. Commercial advantage comes from protecting butter aroma and portion cost as the product moves between frozen inventory, in-store bakery, and foodservice service."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the madeleines market segmented?
The madeleines market is analyzed by Product Type, Claim - Nature, Format, Packaging Format, Sales Channel, and Region.
Product type covers classic - original, whole grain and seeded, flavored and filled, mini and snacking formats, and premium - artisan. Claim - nature includes conventional, clean label, organic, gluten-free, and high-protein - fortified. Format covers fresh, frozen, ambient packaged, chilled, and par-baked - thaw-and-serve. Packaging format includes single-serve, multipack, family - loaf pack, and bulk foodservice. Sales channel covers supermarkets and hypermarkets, artisan and specialty bakeries, convenience and forecourt, online and DTC, and foodservice distributors.
What makes classic - original central to the product type category?
Classic madeleines give retailers a familiar shape and flavor reference while nearby bakery products change with fillings and seasonal variants during routine retail and foodservice assortment planning.
- By product type, classic - original is estimated to hold 37.0% in 2026 owing to familiar butter flavor and low explanation needs at purchase.
- Bauli introduced Pandorì in March 2025 as an everyday soft pastry offered in plain and filled versions. The launch shows how a familiar bakery base can support flavor extensions without changing the everyday eating occasion.
Why does conventional remain central within the claim - nature category?
Conventional recipes preserve madeleine browning and tender crumb while low-sugar bakery products require tighter formulation trade-offs. Standard recipes give commercial bakers more room to protect the expected eating experience during routine production.
- Conventional is projected to hold 59.0% share in 2026 attributable to recipe familiarity and fewer changes to expected texture.
- Premier Foods launched non-HFSS Mr Kipling Lunchbox Slices in March 2025 with controlled portions for lunchbox occasions. The launch shows how familiar cake brands change portion architecture as nutrition rules influence retail merchandising.
How does fresh shape selection within the format category?
Fresh madeleines compete with danish pastries where shoppers judge aroma and crumb before storage convenience. Immediate sensory quality gives fresh formats a clear selling role in specialist and in-store bakery.
- In 2026, fresh is expected to lead format with 30.0% share because immediate crumb softness and bakery aroma influence purchase at the counter.
- INSEE reported bakeries and pastry shops represented 8.1% of French food retail value in 2025. Dense specialist retail keeps fresh sweet bakery visible and gives packaged madeleines a demanding comparison.
What supports single-serve within the packaging format category?
Single-serve packs protect one madeleine without cutting or repacking the product at the outlet. Foodservice teams can release smaller batches and track serving cost more closely during service.
- By packaging format, single-serve is forecast to represent 29.0% in 2026 driven by controlled portions that fit portable eating occasions.
- McKee Foods announced a single-serve Little Debbie Strawberry Shortcake Roll in December 2025 for convenience-store shoppers. Individually wrapped bakery follows the same handling logic as better-for-you snacks where pack size supports portable use and serving control.
What drives supermarkets and hypermarkets within the sales channel category?
Large retailers place madeleines in packaged or in-store bakery while cake pops benchmark small-cake shelf productivity. Several merchandising positions let grocery teams test repeat purchase without changing the category's basic serving format.
- Supermarkets and hypermarkets are set to lead sales channel with 27.0% share in 2026 due to shopper frequency and several merchandising positions within food retail.
- Finsbury Food Group launched Little Big Cake through Tesco in January 2026 with a compact cake-and-cupcake box that directly tested small-cake demand against existing supermarket bakery ranges.
What are the drivers, restraints and opportunities in the Madeleines Market?
Portion-controlled foodservice and retail occasions support expansion, while shelf-life and recipe constraints can raise execution costs, leaving room for differentiated mini and premium formats.
- Driver: Foodservice operators can list thaw-and-serve or protected madeleines without adding specialist pastry labor at every outlet, which expands the practical account base.
- Restraint: Recipe changes and retail promotion rules can reduce merchandising flexibility once a sweeter bakery item must also preserve recognizable texture and flavor.
- Opportunity: Mini and filled madeleines can target coffee pairing or impulse occasions provided that portion economics and handling stay simple for the selling channel.
Foodservice outlets widen the account base for portioned frozen bakery when products can be staged with limited finishing. USDA measured food away from home at 56.3% of United States food expenditures in 2025. Madeleines still need reliable thawed texture and case yield before operators can justify repeat orders.
Retail rules can change how indulgent bakery earns visibility without removing the underlying consumer occasion. England restricted volume-price promotions for qualifying less-healthy products from October 1 2025 and changed the merchandising options available to covered foods. Madeleine companies may need smaller packs or bakery ingredients that protect texture once a product falls within the covered criteria.
Premium formats earn attention when they change the selling occasion instead of merely adding another flavor. Emmi Desserts introduced the Moi consumer brand in May 2026 through its Mademoiselle Desserts business, starting with French Mini Beignets for retail. Madeleine companies can use similar personalized bakery products to test premium portions without complicating routine handling.
Which country CAGRs are profiled in the Madeleines Market?
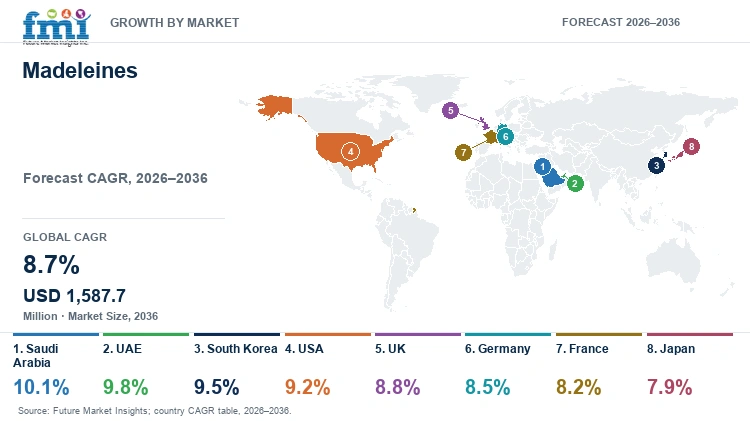
| Country | CAGR |
|---|---|
| Saudi Arabia | 10.1% |
| UAE | 9.8% |
| South Korea | 9.5% |
| USA | 9.2% |
| UK | 8.8% |
| Germany | 8.5% |
| France | 8.2% |
| Japan | 7.9% |
How do country-level CAGRs compare in the Madeleines Market?
Country forecasts separate into two commercial bands shaped by channel expansion and bakery competition. Saudi Arabia and the UAE form the upper Gulf group at 10.1% and 9.8% CAGR. South Korea and the USA follow while UK and Germany grow beside France and Japan more steadily because mature bakery choice slows conversion.
- Saudi Arabia and the UAE favor hospitality channels that protect bakery portions during distribution.
- South Korea rewards snack testing while USA retail scale favors reliable replenishment of portions.
- UK and Germany retailers compare dense bakery assortments, making weak differentiation costly during range reviews.
- France and Japan impose distinct sensory standards that raise execution requirements for packaged madeleine formats.
Comparable CAGRs produce different account economics because listing friction and service conditions vary by country.
The full report compares North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Country-wise Analysis
- United States grocery and foodservice channels give madeleines repeat-purchase routes through packaged shelves and in-store bakery counters. USDA's August 2026 retail data show grocery stores held 56.2% of food-at-home sales in 2025 while warehouse clubs and supercenters held 26.4%. Madeleine sales in the USA are forecast to rise at 9.2% CAGR through 2036, driven by scaled retail distribution and food-away-from-home spending. In-store bakery teams can use bakery mixes to cut preparation steps during routine retail service. Cookies and snack cakes pressure shelf space, so repeat orders depend on shelf life and clear sensory distinction during assortment resets.
- German supermarkets give sweet bakery broad national exposure while shoppers compare familiar cakes and biscuits beside newer French-style formats. Germany is estimated to post 8.5% CAGR over the forecast period, driven by retailer scale and commercial baking capacity. Destatis reported in March 2026 that real food-retail sales rose 2.2% year over year in January as mixed-food retailers increased 1.8%. Mature bakery choice raises the entry bar because national retailers compare many familiar alternatives in every range review and compare predictable portion value. Madeleine listings need stable distribution performance without flattening the soft crumb consumers expect from the format.
- French consumers compare packaged madeleines directly with specialist bakery and pastry products during routine food purchases. INSEE national facilities data count 50,122 bakery and pastry shops in France during 2025. France is positioned to record 8.2% CAGR during the assessment period, attributable to familiar product traditions and several routes for fresh or protected bakery. Dense specialist coverage keeps baked freshness close to consumers and sets a demanding sensory reference for packaged products. Protected madeleines need enough shelf life for supermarket distribution without losing the crumb and butter profile associated with the format during routine replenishment cycles for retailers.
- United Kingdom households buy cakes and pastries regularly while crowded supermarket ranges shape new sweet-bakery listings. UK madeleine sales are forecast to expand at 8.8% CAGR by 2036, supported by portable formats suited to lunchbox and snack occasions. DEFRA's November 2025 Family Food release measured cakes and pastry purchases at 159 grams per person per week in FYE 2024 with volume down 1.2%. Softer household volume makes disciplined portions more important because madeleines must earn shelf space through texture and occasion fit. Retailers can widen listings once product performance justifies replacing familiar cakes or pastries during routine assortment resets.
- Saudi Arabia's licensed hospitality base is expanding the number of hotel and foodservice accounts able to serve portioned premium bakery. GASTAT reported in April 2026 that licensed tourist hospitality facilities reached 5,937 in Q4 2025 and were 34.2% above the prior-year quarter. Heat-sensitive distribution raises execution risk because protected madeleines need documented storage performance before distributors broaden hotel and café placement. By 2036 Saudi Arabia is projected to grow at 10.1% CAGR, driven by tourism activity and a larger national hospitality base. Cold-chain coverage gives bakery distributors a practical route to serve national accounts beyond main urban centers.
- UAE hotel and travel channels give compact sweet bakery a premium serving occasion beyond household grocery purchases. The Ministry of Economy and Tourism reported in April 2026 that UAE hotels welcomed 32.34 million guests during 2025 and guest count rose 5.2%. Adoption of madeleines in the UAE is estimated to expand at 9.8% CAGR through 2036, supported by tourism volumes and higher-value hospitality menus. Service expectations leave little room for moisture loss or damaged presentation before bakery reaches guests. Hotel groups can extend one madeleine format through several outlets if handling instructions protect appearance between kitchen and service.
- Japanese convenience stores place compact bakery beside ready-to-eat foods under frequent assortment rotation and strict expectations for portion consistency. Madeleine demand in Japan is predicted to advance at 7.9% CAGR through 2036, supported by food-to-go retail and centralized supply models for frozen baked goods. METI reported in April 2026 that convenience-store sales increased 3.4% in 2025 as sales per store and store count improved nationally. Dense confectionery competition gives shoppers many substitute snack choices during the same convenience-store visit. Imported or licensed madeleines need consistent texture and Japanese-ready labeling before retailers commit repeat shelf space during routine assortment reviews.
- South Korea's dense convenience network operates beside a fast-growing online channel that exposes packaged snacks to rapid product discovery. MOTIR reported in January 2026 that online sales among major retailers grew 11.8% during 2025 while large-supermarket sales fell 4.2%. South Korea is on track to deliver 9.5% CAGR through 2036, attributable to digital retail growth and fast turnover among portioned snack products. Parcel delivery raises the risk of texture loss before the product reaches consumers. Convenience stores give madeleines another route to trial, but repeat purchase depends on shelf-stable quality and flavor choices that fit local expectations.
Who are the notable companies in the Madeleines Market?
Rich Products, Sara Lee Frozen Bakery, Dessert Holdings, Emmi Desserts, Finsbury Food Group, Premier Foods, McKee Foods, Hostess (The J.M. Smucker Co.), Bauli, and Dr. Oetker are active in madeleines or closely adjacent sweet-bakery categories.
Madeleine competition includes direct patisserie businesses and broader sweet-bakery groups serving retail or foodservice accounts. Product fit and channel execution determine account relevance more directly than corporate scale alone.
- Sara Lee Frozen Bakery and Emmi Desserts supply madeleines through frozen and patisserie channels serving retail and foodservice accounts.
- Rich Products and Dessert Holdings serve portioned desserts, while Finsbury Food Group and Bauli cover broader cake and pastry ranges.
- Premier Foods and McKee Foods cover branded sweet bakery, while Hostess (The J.M. Smucker Co.) and Dr. Oetker serve packaged cake occasions.
Competitive Benchmarking: Madeleines Market
| Company | Sweet-Bakery Focus | Channel Breadth | Frozen or Ready-Service Fit | Geographic Reach |
|---|---|---|---|---|
| Rich Products | High | High | High | Global |
| Sara Lee Frozen Bakery | High | High | High | North America |
| Dessert Holdings | High | High | High | North America |
| Emmi Desserts | High | High | High | Europe and international |
| Finsbury Food Group | High | High | Medium | UK and Europe |
| Premier Foods | Medium | High | Low | United Kingdom |
| McKee Foods | Medium | Medium | Low | North America |
| Hostess (The J.M. Smucker Co.) | Medium | High | Low | North America |
| Bauli | High | High | Medium | Europe and international |
| Dr. Oetker | High | High | Medium | Global |
Scoring basis: High sweet-bakery focus requires a cake or pastry-led business and Medium marks material bakery participation. High channel breadth requires verified retail and foodservice activity while Medium covers narrower routes and Low one route. High service fit requires frozen or thaw-and-serve evidence while Medium covers ready-service bakery and Low covers packaged formats.
Key Developments in the Madeleines Market
- In April 2026, Finsbury Food Group acquired Flower & White to expand light sweet treats into direct-to-consumer and foodservice channels.
- In March 2026, Emmi Group introduced Emmi Desserts as the unified identity for its global dessert business.
- In January 2026, McKee Foods introduced Little Debbie Ice Cream Sandwiches for frozen dessert occasions sold through major retailers.
Key Players in the Madeleines Market
Madeleine and Patisserie Specialists
- Sara Lee Frozen Bakery
- Emmi Desserts
Scaled Bakery and Dessert Platforms
- Rich Products
- Dessert Holdings
- Finsbury Food Group
- Bauli
- Dr. Oetker
Packaged Sweet-Bakery Brand Owners
- Premier Foods
- McKee Foods
- Hostess (The J.M. Smucker Co.)
Madeleines Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, claim - nature, format, packaging format, sales channel, and region. |
| Quantitative Units | USD million. |
| Market Definition | Commercial madeleine products sold through retail and foodservice in fresh, frozen, chilled, ambient, or thaw-and-serve formats. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Saudi Arabia, UAE, South Korea, USA, UK, Germany, France, Japan, and 30+ countries included in the full report. |
| Key Companies Profiled | Rich Products, Sara Lee Frozen Bakery, Dessert Holdings, Emmi Desserts, Finsbury Food Group, Premier Foods, McKee Foods, Hostess (The J.M. Smucker Co.), Bauli, Dr. Oetker. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Madeleines Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Madeleines Market by Segments
Madeleines Market segmented by Product Type:
- Classic - original
- Whole grain & seeded
- Flavored & filled
- Mini & snacking formats
- Premium - artisan
Madeleines Market segmented by Claim - Nature:
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein - fortified
Madeleines Market segmented by Format:
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Par-baked - thaw-and-serve
Madeleines Market segmented by Packaging Format:
- Single-serve
- Multipack
- Family - loaf pack
- Bulk foodservice
Madeleines Market segmented by Sales Channel:
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
Madeleines Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Dessert Holdings. (2025, May 30). Dessert Holdings Returns to IDDBA Ahead of 10-Year Anniversary
- Ministry of Economy, Trade and Industry, Tohoku Bureau. (2026, June 23). 統計表 コンビニエンスストア、家電大型専門店、ドラッグストア、ホームセンターの各販売額の推移(東北、全国)
- Bauli Group. (2025, April 9). The Bauli Group focuses on innovation as a strategic lever for growth and differentiation
- Premier Foods. (2025, March 24). Mr Kipling launches new lunchbox slices
- INSEE. (2026, June 18). Parts de marché du commerce de détail selon la forme de vente
- McKee Foods Corporation. (2025, December 9). Little Debbie Single Serve Strawberry Shortcake Roll
- Finsbury Food Group. (2026, January 19). Introducing Little Big Cake
- USDA Economic Research Service. (2026, June 11). Total USA food spending reached $2.51 trillion in 2025
- Department of Health and Social Care. (2025, October 1). Restricting volume price promotions of HFSS products
- Mademoiselle Desserts. (2026, May 15). Introducing Our Newest Venture
- USDA Economic Research Service. (2026, August 17). Retailing & Wholesaling - Retail Trends
- Statistisches Bundesamt. (2026, March 2). KORREKTUR: Einzelhandelsumsatz im Januar 2026 real um 0,9 % niedriger als im Vormonat
- INSEE. (2026, August 6). Full set of local data - France
- Department for Environment, Food & Rural Affairs. (2025, November 6). Family Food FYE 2024
- General Authority for Statistics. (2026, April 12). Tourism Establishments Statistics - Q4 of 2025
- UAE Ministry of Economy and Tourism. (2026, April 13). Emirates Tourism Council discusses new action plans to enhance the growth and resilience of the sector in the coming period
- Ministry of Economy, Trade and Industry. (2026, April 14). 2025年小売業販売を振り返る
- Ministry of Trade, Industry and Resources. (2026, January 28). 2025 Annual and December Sales Trends for Major Retailers
- Finsbury Food Group. (2026, April 30). Finsbury Food Group Acquires Flower & White To Boost DTC And Healthy Snacking Growth
- Emmi Group. (2026, March 26). Emmi Group launches "Emmi Desserts" as the unified name for its global dessert business
- McKee Foods Corporation. (2026, January 14). Little Debbie Ice Cream Sandwiches
- Rich Products Corporation. (2025, April 10). Rich Products and Funfetti extend partnership
- Finsbury Food Group. (2026, September 8). Finsbury conjures up new Harry Potter-Inspired Celebration Cake in celebration of 25 Years of Magic
- Finsbury Food Group. (2026, June 2). Finsbury Food Group launches limited edition cupcakes
- McKee Foods Corporation. (2025, March 3). Introducing a New Pastry Staple - Fieldstone Bakery Donut Sticks
- Dr. Oetker. (2026, April 16). Business Year 2025: Dr. Oetker and Coppenrath & Wiese
- Rich Products Corporation. (2026, July 6). Rich Products Introduces Mini Cakes
- Cal-Maine Foods. (2026, May 12). Cal-Maine Foods and Sara Lee Frozen Bakery announce Cal-Maine Foods' acquisition of Van's Foods brand
- Dessert Holdings. (2025, July 14). Dessert Holdings Acquires Willamette Valley Pie Co.
- Emmi Group. (2025, November 25). Emmi Group makes bolt-on acquisition and strengthens its desserts business in England
- Finsbury Food Group. (2026, September 1). Finsbury adds strawberry matcha flavour to Little Big Cake range
- Premier Foods. (2026, May 29). Mr Kipling unveils exceedingly good innovation
- McKee Foods Corporation. (2025, April 25). Little Debbie Snacks Launches Big Pack Nutty Buddy Cakes - A Fresh Take on a Classic Favorite!
- The J.M. Smucker Co. (2025, March 3). The J.M. Smucker Co. Completes the Divestiture of Certain Value Brands to JTM Foods, LLC
- Bauli Group. (2025, May 15). Olivieri 1882 joins the Bauli Group
- Dr. Oetker. (2026, June 24). Air fryer - A whole new world of cooking
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How do foodservice formats affect madeleine demand?
- Why does classic - original retain share?
- Why do conventional recipes retain share?
- Why does fresh remain commercially important?
- How does single-serve change handling?
- Why do country CAGRs differ?
- What reduces madeleine margins?
- What should operators test before repeat purchase?
Frequently Asked Questions
How big is the madeleines market in 2026?
The madeleines market is valued at USD 689.4 million in 2026 and is projected to reach USD 1,587.7 million by 2036. Retail and foodservice use expands as portioned formats preserve texture while keeping preparation and serving requirements manageable for operators.
What is the CAGR of the madeleines market from 2026 to 2036?
The madeleines market is projected to grow at a CAGR of 8.7% between 2026 and 2036. Expansion depends on portion-controlled bakery that can move between packaged retail and foodservice with limited finishing.
Which product type leads the madeleines market?
The classic - original segment is expected to hold 37.0% of the madeleines market in 2026, driven by familiar butter flavor and low explanation needs. Retailers can use the format as a stable everyday base before adding filled or premium variants to the assortment.
Which claim - nature segment holds the supported dominant share in the madeleines market?
The conventional segment is projected to account for 59.0% of the madeleines market in 2026, attributable to familiar recipes that preserve expected browning and crumb. Claim-led variants need comparable sensory performance before retailers can replace the standard recipe base in everyday assortments.
Which countries occupy the upper CAGR band in the madeleines market?
Saudi Arabia is projected to grow at 10.1% CAGR, followed by the UAE at 9.8% and South Korea at 9.5% through 2036. Hospitality expansion and digital retail provide different routes for premium portions and snack discovery.
Which companies are active in the madeleines market?
Key companies operating in the madeleines market include Rich Products, Sara Lee Frozen Bakery, Dessert Holdings, Emmi Desserts, Finsbury Food Group, Premier Foods, McKee Foods, Hostess (The J.M. Smucker Co.), Bauli, and Dr. Oetker. Their participation spans direct patisserie supply and adjacent sweet bakery sold through retail or foodservice channels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Classic - original
- Whole grain & seeded
- Flavored & filled
- Mini & snacking formats
- Premium - artisan
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Claim - Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim - Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim - Nature, 2026 to 2036
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein - fortified
- Y-o-Y Growth Trend Analysis By Claim - Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim - Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Format, 2026 to 2036
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Par-baked - thaw-and-serve
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packaging Format, 2026 to 2036
- Single-serve
- Multipack
- Family - loaf pack
- Bulk foodservice
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Claim - Nature
- By Format
- By Packaging Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Rich Products
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Sara Lee Frozen Bakery
- Dessert Holdings
- Emmi Desserts
- Finsbury Food Group
- Premier Foods
- McKee Foods
- Hostess (The J.M. Smucker Co.)
- Bauli
- Dr. Oetker
- Rich Products
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


