

- Market Size (2026)
- USD 13.7 Bn
- Forecast (2036)
- USD 112.2 Bn
- CAGR (2026 to 2036)
- 23.4%
How big is AI Consulting Services Market in 2026?
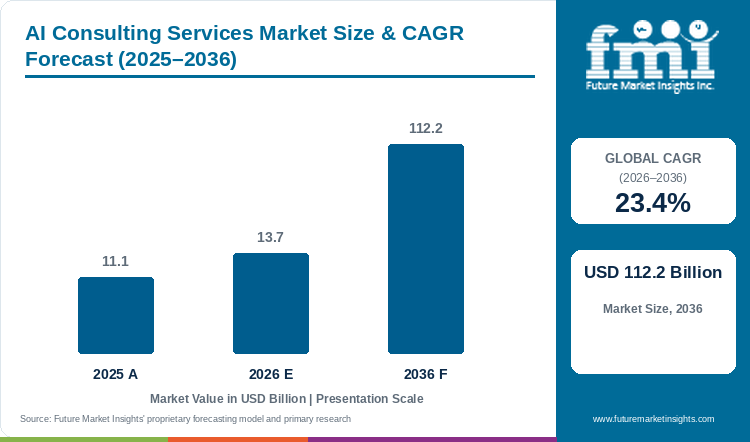
Starting from USD 11.1 billion in 2025, the AI consulting services market valuation advanced to USD 13.7 billion in 2026, with projections pointing toward USD 112.2 billion by 2036 at a CAGR of 23.4%.
Corporate buyers moving artificial intelligence out of isolated sandbox pilots into live banking and manufacturing workflows are driving rapid expansion in the global AI consulting services market. The market valuation stood at USD 11.1 billion in 2025 and is estimated to reach USD 13.7 billion in 2026, with projections pointing toward USD 112.2 billion by 2036 at a 23.4% CAGR. Legacy database remediation and governance audits govern consulting contract awards. AI Strategy Advisory captures 38.4% of service scope demand in 2026 because corporate boards require clear return-on-investment roadmaps and token budget controls before integrating enterprise generative models, which expand at a faster 30.8% CAGR through self-serve cloud APIs. According to the U.S. Census Bureau in its May 2026 Business Trends and Outlook Survey release across 1.2 million employer businesses, enterprises are embedding artificial intelligence across core task workflows and biweekly operating plans [1]. Even so, steep hourly billing rates for senior machine-learning architects and multi-quarter delays in cleaning scattered on-premise records continue to restrain faster deployment among mid-sized firms.
Key Market Trends & Insights
- By service scope: AI Strategy Advisory is projected to capture 38.4% in 2026 because corporate boards mandate ROI roadmaps and compute budget audits prior to multi-year implementation contracts.
- By AI technology: Generative Foundation Models are estimated to command 49.2% in 2026 as enterprises fine-tune domain-specific large language models and retrieval-augmented generation pipelines.
- By enterprise size: Large Enterprises are expected to concentrate 71.8% in 2026 because multi-cloud data modernization and cross-border compliance require dedicated multi-disciplinary consulting squads.
- By vertical: BFSI Sector is forecast to generate 27.5% in 2026 owing to strict model-risk validation rules across retail banking, underwriting, and capital markets.
- By delivery model: Project-Based Advisory is anticipated to account for 56.4% in 2026 through fixed-milestone architecture assessments and pilot-to-production deployment sprints.
Regional Highlights
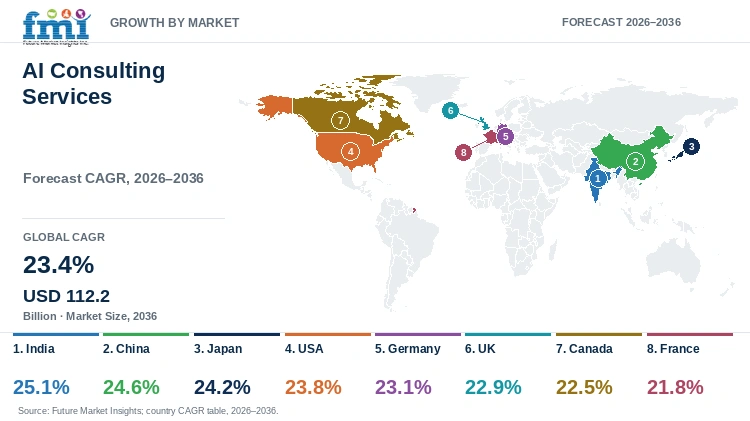
- Top national expansion: India is projected to lead major consulting markets at a 25.1% CAGR through 2036 under global capability center expansion, ahead of China at 24.6% and Japan at 24.2%.
- Broader country progression: The USA is expected to expand at a 23.8% CAGR ahead of Germany at 23.1%, the UK at 22.9%, Canada at 22.5% and France at 21.8%.
Market Size & Forecast
Table 1: Market Size and Forecast for the AI Consulting Services Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 11.1 billion |
| Estimated Market Size in 2026 | USD 13.7 billion |
| Projected Market Size by 2036 | USD 112.2 billion |
| CAGR, 2026 to 2036 | 23.4% |
| Added Valuation, 2026 to 2036 | USD 98.5 billion |
Corporate IT departments confront acute internal shortages of machine-learning architects and data-governance engineers when moving models from test sandboxes into regulated production environments. Hiring external advisory teams bridges this execution gap while transferring architecture patterns to internal staff. In August 2026, McKinsey & Company reported in its global State of AI survey that organizations scaling autonomous agents and rewiring core business workflows on enterprise AI platforms capture measurable operating-profit gains [2].
Enterprise Client Pool and Engagement Sizing
Table 2: Enterprise Client Pool and Engagement Sizing for the AI Consulting Services Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 11.1 | 13.7 | 112.2 |
| Active enterprise AI transformation programs (thousand) | 38.0 to 44.0 | 46.0 to 53.0 | 210.0 to 245.0 |
| Deployed production AI / agentic workflows (thousand) | 95.0 to 115.0 | 130.0 to 155.0 | 880.0 to 1,050.0 |
| Average annual advisory spend per program (USD) | 250,000 to 290,000 | 260,000 to 300,000 | 455,000 to 535,000 |
Operational note: Enterprise engagement ranges apply active corporate AI transformation programs against documented systems-integrator contract values and multi-quarter implementation schedules.
Global systems integrators structure multi-phase transformation contracts that pair upfront data-lakehouse migration with continuous model-drift monitoring across hybrid cloud estates. Bundling upfront architecture roadmaps with managed machine learning platforms lets enterprise CIOs cap unbudgeted GPU inference bills and maintain verifiable audit trails.
Per-Enterprise & Consultant Billing Sizing
Table 3: Per-Enterprise Spend and Engagement Indicators for the AI Consulting Services Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global enterprise IT & digital services pool (USD billion) | 1,420.0 | 1,540.0 | 3,180.0 |
| AI consulting share of digital services (%) | 0.8% | 0.9% | 3.5% |
| Average hourly AI architect billing rate (USD) | 240.0 to 380.0 | 255.0 to 410.0 | 340.0 to 550.0 |
| Multi-year managed & outcome contract share (%) | 41.0% to 44.0% | 43.6% to 46.5% | 58.0% to 63.0% |
Table 4: Enterprise Consulting Spend & Segment Allocation Indicators for the AI Consulting Services Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 13.7 billion | 2026 global AI consulting services baseline |
| Large enterprise share, 2026 | USD 9.8 billion | 71.8% enterprise size segment allocation |
| Generative foundation model advisory, 2026 | USD 6.7 billion | 49.2% AI technology segment allocation |
| BFSI sector advisory demand, 2026 | USD 3.8 billion | 27.5% vertical segment allocation |
Running autonomous agentic workflows in production requires connecting proprietary ERP databases to low-latency vector indexes while blocking prompt-injection leaks. Advisory practices embed automated model security suites directly into client cloud landing zones so enterprise deployments pass board-level cybersecurity and regulatory inspections.
Analyst Perspective
"Enterprise buyers no longer fund standalone generative AI proofs of concept; procurement committees demand integrated architecture roadmaps that link legacy data modernization and model governance to verifiable operating-margin expansion."
- Sudip Saha, Co-founder, FMI
How is the AI consulting services market segmented?
The AI consulting services market is segmented by service scope, AI technology, enterprise size, vertical, and delivery model. In 2026, AI Strategy Advisory is projected at 38.4%, Generative Foundation Models at 49.2%, Large Enterprises at 71.8%, BFSI Sector at 27.5%, and Project-Based Advisory at 56.4%.
By service scope: AI Strategy Advisory, Custom Agentic Workflows, MLOps and Governance, and Legacy Data Modernization.
By AI technology: Generative Foundation Models, Predictive Machine Learning, and Vision and NLP.
By enterprise size: Large Enterprises and Small Mid-Sized Enterprises.
By vertical: BFSI Sector, Manufacturing Energy Telecom, Healthcare Life Sciences, and Retail and Hospitality.
By delivery model: Project-Based Advisory, Dedicated Managed Teams, and Outcome-Based Contracting.
Why does AI Strategy Advisory lead the service scope category?
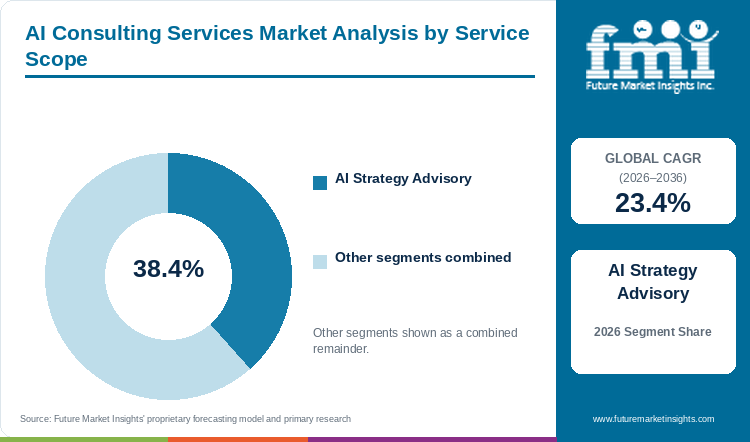
AI Strategy Advisory is projected to capture 38.4% of service scope demand in 2026, supported by board-level ROI roadmaps and data readiness audits.
Table 5: Service Scope Share for the AI Consulting Services Market (percentage share), 2026
| Service Scope | Share (2026) |
|---|---|
| AI Strategy Advisory | 38.4% |
| Other Segments Combined | 61.6%* |
| Total | 100.0% |
*Note: Remaining service scope categories sum to 100.0% of 2026 advisory billings.
Table 6: Service Scope Leadership and Market Growth for the AI Consulting Services Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 23.4% |
| Leading Segment | AI Strategy Advisory |
Corporate boards and chief financial officers require use-case prioritization and compute cost modeling before authorizing multi-year software engineering commitments. Strategy consultants audit existing cloud data pipelines and deploy automated data observability software to prevent unstructured data quality gaps from derailing downstream model training.
- AI Strategy Advisory is projected to secure 38.4% of service scope billings (USD 5.3 billion) in 2026 by aligning executive capital allocation with verifiable workflow automation returns.
- In June 2026, Boston Consulting Group published its AI at Work survey, finding that organizations pairing executive strategy coaching with workflow redesign achieve more than double the employee adoption of tool-only rollouts [3].
Why do Generative Foundation Models define the largest AI technology segment?
Generative Foundation Models are estimated to secure 49.2% of the AI technology category in 2026, driven by retrieval-augmented generation and custom agentic workflows.
Enterprise buyers are shifting consulting budgets toward fine-tuning foundational large language models and multi-agent reasoning systems on private corporate knowledge bases without exposing trade secrets. Advisory architects pair retrieval-augmented generation with autonomous workflow software agents to automate multi-step procurement and customer service tasks.
- Generative Foundation Models are estimated to command 49.2% of the AI technology segment (USD 6.7 billion) in 2026 as corporations move beyond basic chat interfaces into domain-tuned production models.
- In September 2025, Accenture plc reported fiscal 2025 new bookings of USD 80.6 billion in its fourth-quarter earnings release, including USD 5.9 billion in generative AI consulting and implementation bookings across global enterprise accounts [4].
What keeps Large Enterprises ahead by enterprise size?
Large Enterprises are expected to command 71.8% of enterprise size demand in 2026, reflecting multi-cloud data modernization and cross-border compliance programs.
Multinational corporations operating across fragmented ERP instances and multi-country regulatory regimes require large consulting squads to coordinate enterprise-wide AI rollouts. Systems integrators install data center operations software to optimize GPU cluster efficiency and cross-cloud inference routing for Fortune 500 clients.
- Large Enterprises are expected to hold 71.8% of enterprise size demand (USD 9.8 billion) in 2026 because multi-year core modernization programs carry contract values exceeding USD 0.01 billion per client.
- In February 2026, International Business Machines Corporation disclosed in its 2025 Annual Report (Form 10-K) that its generative AI book of business surpassed USD 12.5 billion, led by IBM Consulting enterprise transformation engagements [5].
Why does BFSI Sector lead the vertical category?
BFSI Sector is forecast to generate 27.5% of vertical demand in 2026, owing to automated underwriting, fraud surveillance, and model-risk validation mandates.
Commercial banks and insurance carriers face intense competitive pressure to automate credit underwriting and anti-money-laundering surveillance while preserving explainable audit logs. Financial institutions retain external advisory practices to validate model fairness and stress-test training data ahead of central-bank supervisory examinations.
- BFSI Sector is forecast to account for 27.5% of vertical demand (USD 3.8 billion) in 2026 as tier-one banks modernize legacy core banking repositories for real-time agentic decisioning.
- In September 2026, Boston Consulting Group reported in its global AI value study that almost 50% of surveyed companies now generate measurable financial returns as AI budgets expand to 3.3% of revenue outside traditional IT departments [6].
What gives Project-Based Advisory the leading position in delivery model?
Project-Based Advisory is anticipated to account for 56.4% of delivery model demand in 2026, reinforced by milestone-gated architecture and pilot-to-production contracts.
Chief procurement officers favor fixed-scope, milestone-gated consulting contracts when commissioning initial data readiness audits and minimum-viable-product builds. Defined statement-of-work agreements protect corporate budgets from open-ended time-and-materials overruns while locking in clear architectural blueprints before full production scaling.
- Project-Based Advisory is anticipated to capture 56.4% of delivery model demand (USD 7.7 billion) in 2026 because enterprise buyers mandate discrete phase-gate sign-offs prior to long-term managed operations.
- In January 2026, Deloitte Touche Tohmatsu Limited released its 2026 State of AI in the Enterprise report, confirming that enterprise executives rely heavily on project-based advisory partners to close internal architecture and governance skills gaps [7].
What are the drivers, restraints, and opportunities in the AI consulting services market?
In the AI consulting services market, enterprise transitions from sandbox pilots to agentic workflows expand advisory bookings whereas legacy data silos restrain deployment speed and EU AI Act compliance audits create high-margin governance opportunities.
- Driver: Rapid corporate transition from standalone chat pilots to multi-agent production workflows forces enterprises to hire external architecture and systems-integration specialists.
- Restraint: Escalating token inference costs, legacy data silos, and severe shortages of Principal ML architects delay full-scale production rollouts across mid-sized organizations.
- Opportunity: Mandatory compliance with the European Union AI Act and NIST risk frameworks creates high-margin recurring demand for automated model auditing and responsible AI governance practices.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Chief information officers are reallocating funds from departmental chat pilots toward cross-functional agentic systems that run end-to-end supply chain and finance workflows. In August 2026, Deloitte Touche Tohmatsu Limited published its AI Readiness and Agentic AI survey, revealing that 74% of leaders expect nearly half of business processes to be redesigned around AI agents within four years despite only 21% having process-ready legacy systems today [8]. Advisory teams combine custom agent orchestration with automated research intelligence tools to compress product development and market analysis cycles.
Risk Assessment of the AI Consulting Services Market: Operational and Commercial Friction
Fragmented on-premise data silos and unpredictable cloud GPU inference bills remain the primary operational hurdles slowing enterprise-wide scaling. In March 2026, McKinsey & Company reported in its State of AI Trust study that security and governance risks top the barrier list as organizations scramble to govern agentic tools [9]. Connecting natural language processing systems to legacy mainframes frequently requires 12 to 18 months of master-data cleanup before autonomous agents can execute transactions safely.
Commercial Opportunity Analysis: Service Differentiation and Value-Add Formats
Binding compliance deadlines under the European Union Artificial Intelligence Act and sector-specific financial supervisory rules are creating high-margin consulting demand in algorithmic auditing and red-teaming. In April 2026, the U.S. National Institute of Standards and Technology released its updated AI Risk Management Framework (AI RMF) concept note for trustworthy AI in critical infrastructure, setting formal benchmarks for adversarial testing and vendor governance [10]. Consultancies that bundle regulatory compliance toolkits with cloud contact center automation secure multi-year retainer agreements across banking and healthcare clients.
AI Consulting Services Market by Country (2026 to 2036)
As per FMI, India is projected to lead AI consulting services expansion across evaluated national markets at a 25.1% CAGR through 2036, whereas France is forecast to advance at a 21.8% CAGR. Commercial adoption across Asia-Pacific, North America and Western Europe tracks enterprise cloud modernization, sovereign AI compute subsidies and mandatory algorithmic governance audits.
Table 7: Country CAGR and Primary Growth Levers for the AI Consulting Services Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| India | 25.1% | Multinational Global Capability Center (GCC) expansion and IndiaAI Mission engineering hubs |
| China | 24.6% | Industrial foundation-model integration and mandatory domestic algorithm filing compliance |
| Japan | 24.2% | Demographic workforce shrinkage driving COBOL mainframe retirement and bilingual agentic automation |
| USA | 23.8% | Fortune 500 agentic workflow scaling, hyperscaler co-delivery, and NIST AI RMF governance |
| Germany | 23.1% | Mittelstand and automotive digital-twin integration with EU AI Act conformity assessments |
| UK | 22.9% | City of London financial services algorithmic auditing and NHS clinical documentation copilots |
| Canada | 22.5% | Toronto banking automation, federal sovereign compute, and Quebec Law 25 governance compliance |
| France | 21.8% | CAC 40 sovereign open-weight model deployments and CNIL-compliant enterprise RAG architectures |
Source: Future Market Insights analysis
India AI Consulting Services Market Outlook (2026 to 2036)
India is the global delivery engine for enterprise AI consulting because multinational corporations pair domestic digital transformation with vast Global Capability Center (GCC) engineering hubs in Bengaluru, Hyderabad, and Pune. India is projected to expand at a leading 25.1% CAGR from 2026 through 2036 as global systems integrators retrain hundreds of thousands of engineers in agentic orchestration and vector database indexing. In April 2026, the Stanford Institute for Human-Centered Artificial Intelligence (HAI) highlighted in its 2026 AI Index Report that rapid capability gains and cross-border developer ecosystems are reshaping how enterprises measure and manage production AI [11]. Subsidized GPU clusters under the IndiaAI Mission and multilingual voice deployments across public banking accelerate domestic billings, though high attrition among senior solution architects in tier-one cities inflates delivery payrolls.
Key takeaway: In India, multinational Global Capability Center expansion and large-scale agentic engineering delivery hubs anchor a 25.1% CAGR through 2036.
China AI Consulting Services Market Outlook (2026 to 2036)
Unlike Western consulting markets built around hyperscaler SaaS integrations, China's AI advisory demand is driven by state-backed 'Artificial Intelligence Plus' industrial policies and domestic open-weight model deployments across manufacturing and logistics. Market demand in China is forecast to advance at a 24.6% CAGR between 2026 and 2036 as state-owned industrial groups and private e-commerce platforms hire local consultancies to embed reasoning models into factory ERP and supply-chain systems. A February 2026 econometric study of 4,144 listed Chinese enterprises published in Scientific Reports confirmed that national AI innovation pilot policies significantly raise corporate supply-chain resilience across manufacturing hubs [12]. However, Cyberspace Administration of China algorithm filing mandates and U.S. export controls on high-density accelerator chips compel consultants to engineer multi-chip domestic compute workarounds.
Key takeaway: In China, industrial foundation-model integration and mandatory domestic algorithm filing rules support a 24.6% CAGR through 2036.
Japan AI Consulting Services Market Outlook (2026 to 2036)
Japan's demand for AI consulting is uniquely dictated by an aging workforce shrinkage and a looming 'digital cliff' of decades-old COBOL mainframes across Tokyo and Osaka conglomerates. Over the 2026 to 2036 forecast period, Japan is expected to record a 24.2% CAGR as banks and industrial manufacturers retain external systems integrators to automate legacy code migration and deploy bilingual back-office copilots. In July 2026, Japan's Ministry of Economy, Trade and Industry (METI) signed a bilateral Memorandum of Cooperation on Artificial Intelligence with India to expand joint AI engineering talent and industrial deployment standards [13]. Even so, consensus-heavy ringisho corporate procurement cycles and an acute shortage of bilingual Japanese data architects slow down initial contract sign-offs.
Key takeaway: In Japan, demographic labor deficits and legacy mainframe retirement programs drive a 24.2% CAGR through 2036.
USA AI Consulting Services Market Outlook (2026 to 2036)
The USA anchors the largest share of global AI consulting billings because Fortune 500 boards in New York, California, and Texas sign multi-year outcome-based contracts tying advisory fees directly to operating-margin expansion. Consequently, the USA is projected to advance at a 23.8% CAGR from 2026 to 2036 as enterprises move generative models out of sandbox trials into core customer-service, underwriting, and software-engineering pipelines. In April 2026, IBM reported in its first-quarter Form 8-K earnings release that strong enterprise demand for hybrid-cloud consulting and AI governance continued to expand its consulting book of business [14]. Strict NIST AI RMF governance expectations and board scrutiny over runaway cloud token bills nevertheless force consultancies to prove hard cost savings within the first two quarters of deployment.
Key takeaway: In the USA, Fortune 500 agentic workflow scaling and NIST governance compliance sustain a 23.8% CAGR through 2036.
Germany AI Consulting Services Market Outlook (2026 to 2036)
Germany's AI consulting market centers on industrial engineering, digital-twin integration, and shop-floor predictive maintenance across automotive OEMs and export-oriented Mittelstand machinery makers in Munich and Stuttgart. Germany is forecast to grow at a 23.1% CAGR between 2026 and 2036 as manufacturers modernize factory data pipelines while preparing for mandatory European Union AI Act high-risk system conformity assessments. The OECD's May 2025 cross-country study on The Adoption of Artificial Intelligence in Firms confirmed that industrial process integration and complementary workforce skills determine whether firms capture productivity gains from AI [15]. In Germany, mandatory works-council (Betriebsrat) co-determination reviews on any software that monitors employee output can add three to six months to enterprise rollout timelines.
Key takeaway: In Germany, industrial digital-twin modernization and EU AI Act conformity assessments underpin a 23.1% CAGR through 2036.
UK AI Consulting Services Market Outlook (2026 to 2036)
Demand for AI consulting in the UK is heavily concentrated in City of London financial services algorithmic auditing, Golden Triangle life sciences discovery, and National Health Service clinical documentation pilots. Market value in the UK is projected to climb at a 22.9% CAGR from 2026 through 2036 as banks retain advisory firms to validate credit and underwriting models under Financial Conduct Authority Consumer Duty rules. In February 2026, the UK Department for Science, Innovation and Technology (DSIT) published its AI Adoption Research showing that while 75% of adopting UK businesses report improved workforce productivity, only 54% feel ready to scale without external technical support and 77% have yet to see direct revenue gains [16]. That readiness gap directly fuels demand for third-party implementation and P&L redesign partners.
Key takeaway: In the UK, financial services algorithmic auditing and public-sector AI safety modernization drive a 22.9% CAGR through 2036.
Canada AI Consulting Services Market Outlook (2026 to 2036)
Canada bridges world-renowned academic deep-learning institutes, Vector in Toronto, Mila in Montreal, and Amii in Edmonton, with commercial banking and natural-resource enterprise modernization in Toronto and Calgary. Between 2026 and 2036, Canada is anticipated to expand at a 22.5% CAGR as domestic corporations hire consulting teams to convert academic research into production fraud-detection and grid-optimization workflows. In October 2026, Innovation, Science and Economic Development Canada (ISED) announced Canada's CAD 1.0 billion Venture and Growth Capital driver Initiative starting in 2026–2027 to scale domestic technology and AI commercialization [17]. Strict provincial privacy statutes, especially Quebec's Law 25 rules governing automated decision transparency, require consultancies to build bilingual explainability logs into every consumer-facing model.
Key takeaway: In Canada, banking workflow automation and federal AI commercialization programs support a 22.5% CAGR through 2036.
France AI Consulting Services Market Outlook (2026 to 2036)
France's enterprise AI consulting market is shaped by strong state and CAC 40 corporate preference for sovereign open-weight foundation models that keep proprietary aerospace, luxury retail, and nuclear engineering data on French soil. As a result, France is expected to progress at a 21.8% CAGR over the 2026 to 2036 assessment window as Paris and Toulouse industrial groups deploy on-premise retrieval-augmented generation architectures compliant with CNIL privacy directives. In September 2026, Accenture and Google Cloud launched the Accenture Gemini Enterprise Business Group to help global and European enterprises scale governed agentic workflows [18]. Stringent CNIL data-protection audits and complex French labor consultations around automated workflow changes remain the primary hurdles pacing enterprise-wide contract execution.
Key takeaway: In France, CAC 40 sovereign-model deployments and CNIL-compliant enterprise architectures sustain a 21.8% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the AI consulting services market?
Accenture plc, International Business Machines Corporation, Deloitte Touche Tohmatsu Limited, McKinsey & Company, Boston Consulting Group, Capgemini SE, PricewaterhouseCoopers International Limited, and Cognizant Technology Solutions are the notable companies in the AI consulting services market.
FMI analysis indicates that the competitive arena divides between global end-to-end systems integrators, elite executive strategy partnerships, and cloud-native engineering consultancies.
- Global Systems Integrators & Audit Networks: Accenture plc, International Business Machines Corporation, and Deloitte Touche Tohmatsu Limited combine global cloud delivery centers with proprietary agentic orchestration platforms.
- Tier-One Strategy & Transformation Partnerships: McKinsey & Company (QuantumBlack) and Boston Consulting Group (BCG X) advise corporate boards on enterprise AI capital allocation, operating-model redesign, and custom algorithm builds.
- European & Enterprise Engineering Leaders: Capgemini SE, PricewaterhouseCoopers International Limited, and Cognizant Technology Solutions specialize in sovereign cloud migration, industrial engineering AI, and regulated sector compliance.
Competitive Benchmarking: AI Consulting Services Market
Table 8: Competitive Benchmarking for the AI Consulting Services Market (qualitative capability ratings), 2026
| Company | Strategy & Roadmap Depth | Agentic & LLM Engineering | Governance & MLOps Tooling | Geographic Reach |
|---|---|---|---|---|
| Accenture plc | High | High | High | High |
| International Business Machines Corporation | High | High | High | High |
| Deloitte Touche Tohmatsu Limited | High | High | High | High |
| McKinsey & Company | High | High | Medium | High |
| Boston Consulting Group | High | High | Medium | High |
| Capgemini SE | Medium | High | High | High |
| PricewaterhouseCoopers International Limited | High | Medium | High | High |
| Cognizant Technology Solutions | Medium | High | High | High |
Scoring basis: Capability tiers evaluate documented generative and agentic AI booking volumes, proprietary accelerator platforms, cloud hyperscaler alliance depth and global delivery headcount.
Key Developments in the AI Consulting Services Market
- In April 2026, Accenture plc and Google Cloud expanded their strategic alliance to scale agentic transformation for global enterprises using Gemini Enterprise and Accenture engineering teams [19].
- In April 2026, Deloitte Touche Tohmatsu Limited launched its Google Cloud Agentic Transformation Practice, dedicating certified cloud architects to build multi-agent enterprise workflows across banking, retail, and healthcare [20].
- In June 2026, International Business Machines Corporation published its global study of 2,000 CIOs and CTOs showing that organizations embedding automated AI governance experience 25% fewer agent incidents as AI spend climbs toward 25% of IT budgets [21].
Key Players in the AI Consulting Services Market
Global Systems Integrators & Audit Networks
- Accenture plc
- International Business Machines Corporation
- Deloitte Touche Tohmatsu Limited
Tier-One Strategy & Transformation Partnerships
- McKinsey & Company
- Boston Consulting Group
- PricewaterhouseCoopers International Limited
Enterprise Cloud & Engineering Consultancies
- Capgemini SE
- Cognizant Technology Solutions
AI Consulting Services Market - Report Scope
Table 9: Report Scope for the AI Consulting Services Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Service Scope; AI Technology; Enterprise Size; Vertical; Delivery Model |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial advisory, architecture design, custom model/agentic workflow implementation, MLOps governance auditing, and AI-specific data modernization billings. Category Scope Note: Excludes standalone cloud GPU infrastructure IaaS rentals, off-the-shelf SaaS seat licenses, and non-AI BPO clerical staffing. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | India, China, Japan, USA, Germany, UK, Canada, France, and additional national markets in the full dataset |
| Key Companies Covered | Accenture plc, International Business Machines Corporation, Deloitte Touche Tohmatsu Limited, McKinsey & Company, Boston Consulting Group, Capgemini SE, PricewaterhouseCoopers International Limited, Cognizant Technology Solutions |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
AI Consulting Services Market - Research Methodology
Table 10: Research Methodology for the AI Consulting Services Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with Fortune 2000 chief information officers, chief data officers, systems-integrator practice partners, and hyperscaler alliance directors to validate project billing rates and pilot-to-production conversion ratios. |
| Secondary Research | Analysis of SEC Form 10-K and 8-K filings, Accenture and IBM generative AI booking disclosures, Stanford HAI and OECD adoption indices, and national AI regulatory frameworks. |
| Market Sizing and Forecasting | Top-down enterprise digital transformation budget models reconciled against bottom-up AI consulting headcount, use rates, and average engagement contract values from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight enterprise cloud maturity, Global Capability Center engineering benches, sovereign AI compute subsidies, and EU AI Act / NIST regulatory enforcement across eight national markets. |
| Operational Benchmark Traceability | Enterprise program pools and billing indicators in Tables 2, 3, and 4 trace to U.S. Census Bureau BTOS surveys, McKinsey and BCG enterprise adoption benchmarks, and audited systems-integrator booking disclosures. |
| Data Triangulation and Validation | Demand estimates are cross-checked against reported generative AI consulting books of business and practice headcount without double counting underlying cloud compute infrastructure fees. |
AI Consulting Services Market by Segments
AI Consulting Services Market segmented by Service Scope:
- AI Strategy Advisory
- Custom Agentic Workflows
- MLOps and Governance
- Legacy Data Modernization
AI Consulting Services Market segmented by AI Technology:
- Generative Foundation Models
- Predictive Machine Learning
- Vision and NLP
- Graph Neural Networks
AI Consulting Services Market segmented by Enterprise Size:
- Large Enterprises
- Small Mid-Sized Enterprises
- Public Sector Entities
AI Consulting Services Market segmented by Vertical:
- BFSI Sector
- Manufacturing Energy Telecom
- Healthcare Life Sciences
- Retail and Hospitality
AI Consulting Services Market segmented by Delivery Model:
- Project-Based Advisory
- Dedicated Managed Teams
- Outcome-Based Contracting
- Hybrid Co-Delivery
AI Consulting Services Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Census Bureau. (2026, May 7). Business Trends and Outlook Survey Data Release — May 7, 2026 (CB26-TPS.28). U.S. Department of Commerce.
- [2] McKinsey & Company. (2026, August 25). The State of AI: Global Survey 2026. McKinsey & Company (QuantumBlack).
- [3] Boston Consulting Group (BCG). (2026, June 3). AI at Work: Why Strategy Matters More Than Tools. Boston Consulting Group.
- [4] Accenture plc. (2025, September 25). Accenture Reports Fourth-Quarter and Full-Year Fiscal 2025 Results. Accenture Newsroom.
- [5] International Business Machines Corporation (IBM). (2026, February 24). IBM 2025 Annual Report on Form 10-K. U.S. Securities and Exchange Commission.
- [6] Boston Consulting Group (BCG). (2026, September 30). AI Is Starting to Pay Off: Almost 50% of Companies Now Generate Value. Boston Consulting Group Press Room.
- [7] Deloitte Touche Tohmatsu Limited. (2026, January 18). The State of AI in the Enterprise — 2026 AI Report. Deloitte AI Institute.
- [8] Deloitte Touche Tohmatsu Limited. (2026, August 12). AI Agents Are Only the Beginning: Deloitte Survey Examines the AI Readiness Gap and Reveals How Enterprises Can Prepare for Agentic Success. Deloitte Press Room.
- [9] McKinsey & Company. (2026, March 25). State of AI Trust in 2026: Shifting to the Agentic Era. McKinsey Technology Insights.
- [10] National Institute of Standards and Technology (NIST). (2026, April 7). AI Risk Management Framework (AI RMF). U.S. Department of Commerce.
- [11] Stanford Institute for Human-Centered Artificial Intelligence (HAI). (2026, April 14). Inside the AI Index: 12 Takeaways from the 2026 Report. Stanford University.
- [12] Cheng, G., & Zhang, H. (2026, February 7). The Impact of China's Artificial Intelligence Pilot Policies on Enterprise Supply Chain Resilience. Scientific Reports, 16, 5382 (PMCID: PMC12886830).
- [13] Ministry of Economy, Trade and Industry (METI). (2026, July 3). The Governments of Japan and the Republic of India Sign Memorandum of Cooperation in the Field of Artificial Intelligence. Government of Japan.
- [14] International Business Machines Corporation (IBM). (2026, April 22). IBM Reports First-Quarter 2026 Results (Form 8-K Exhibit 99.1). U.S. Securities and Exchange Commission.
- [15] Organisation for Economic Co-operation and Development (OECD). (2025, May 2). The Adoption of Artificial Intelligence in Firms: New Evidence for Policymaking. OECD Publishing.
- [16] Department for Science, Innovation and Technology (DSIT). (2026, February 13). AI Adoption Research. UK Government.
- [17] Innovation, Science and Economic Development Canada (ISED). (2026, October 23). Government of Canada Announces Canada's Venture and Growth Capital Plan. Government of Canada.
- [18] Accenture plc. (2026, September 8). Accenture and Google Cloud Deepen Partnership with Formation of New Accenture Gemini Enterprise Business Group. Accenture Newsroom.
- [19] Accenture plc. (2026, April 22). Accenture and Google Cloud Expand Partnership to Scale Agentic Transformation for Global Enterprises with Gemini Enterprise. Accenture Newsroom.
- [20] Deloitte Touche Tohmatsu Limited. (2026, April 22). Deloitte Launches Google Cloud Agentic Transformation Practice. Deloitte Press Room.
- [21] International Business Machines Corporation (IBM). (2026, June 8). New IBM Study Finds CIOs and CTOs Face Growing AI Control Gap as Enterprise Deployment Scales. IBM Newsroom.
- [22] Accenture plc. (2026, July 7). Accenture Edge and Google Cloud Bring Scalable Agentic AI Solutions to Mid-Market Companies. Accenture Newsroom.
- [23] Capgemini SE. (2026, January 15). The Multi-Year AI Advantage: Building the Enterprise of Tomorrow (AI Perspectives 2026). Capgemini Research Institute.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list across all primary and secondary sources consulted during the assessment.
This Report Answers
- How large is the AI consulting services market in 2026 and what is forecast for 2036?
- Which enterprise workflow and governance pressures drive demand for AI consulting services?
- Why does AI Strategy Advisory lead the service scope category?
- Why do Generative Foundation Models lead the AI technology category globally?
- How do growth rates differ across India, China, Japan and the USA?
- Which leading consultancies and systems integrators dominate enterprise AI transformation today?
- What limits production scaling or supplier switching in the AI consulting services market?
- What should chief information officers evaluate before contracting an AI consulting partner?
Frequently Asked Questions
How big is the AI consulting services market in 2026, and what is forecast for 2036?
According to FMI, global AI consulting services market value is estimated to reach USD 13.7 billion in 2026 from USD 11.1 billion in 2025 and is projected to climb to USD 112.2 billion by 2036.
What is the CAGR for the AI consulting services market from 2026 to 2036?
Future Market Insights projects a 23.4% compound annual growth rate between 2026 and 2036, representing an anticipated USD 98.5 billion in incremental advisory and implementation value over the decade.
Which service scope segment leads the AI consulting services market?
AI Strategy Advisory is projected to capture 38.4% of service scope demand in 2026 because enterprise boards require feasibility roadmaps, data readiness audits, and token cost models before approving full production rollouts.
Which AI technology segment leads the AI consulting services market?
Generative Foundation Models are estimated to secure 49.2% of the AI technology category in 2026 as corporations deploy retrieval-augmented generation and multi-agent reasoning across core business workflows.
Which country has a notable growth outlook during the assessment period?
India is projected to lead national growth at a 25.1% CAGR through 2036, supported by multinational Global Capability Center expansion and large-scale agentic engineering delivery hubs.
Who are the key players in the market?
Accenture plc, International Business Machines Corporation, Deloitte Touche Tohmatsu Limited, McKinsey & Company, Boston Consulting Group, Capgemini SE, PricewaterhouseCoopers International Limited, and Cognizant Technology Solutions are the key players evaluated in the market.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Service Scope, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Service Scope, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Service Scope, 2026 to 2036
- AI Strategy Advisory
- Custom Agentic Workflows
- MLOps and Governance
- Legacy Data Modernization
- Y-o-Y Growth Trend Analysis By Service Scope, 2021 to 2025
- Absolute $ Opportunity Analysis By Service Scope, 2026 to 2036
- Global Market Analysis and Forecast, By AI Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By AI Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By AI Technology, 2026 to 2036
- Generative Foundation Models
- Predictive Machine Learning
- Vision and NLP
- Graph Neural Networks
- Y-o-Y Growth Trend Analysis By AI Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By AI Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Enterprise Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Enterprise Size, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Enterprise Size, 2026 to 2036
- Large Enterprises
- Small Mid-Sized Enterprises
- Public Sector Entities
- Y-o-Y Growth Trend Analysis By Enterprise Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Enterprise Size, 2026 to 2036
- Global Market Analysis and Forecast, By Vertical, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vertical, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vertical, 2026 to 2036
- BFSI Sector
- Manufacturing Energy Telecom
- Healthcare Life Sciences
- Retail and Hospitality
- Y-o-Y Growth Trend Analysis By Vertical, 2021 to 2025
- Absolute $ Opportunity Analysis By Vertical, 2026 to 2036
- Global Market Analysis and Forecast, By Delivery Model, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Delivery Model, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Delivery Model, 2026 to 2036
- Project-Based Advisory
- Dedicated Managed Teams
- Outcome-Based Contracting
- Hybrid Co-Delivery
- Y-o-Y Growth Trend Analysis By Delivery Model, 2021 to 2025
- Absolute $ Opportunity Analysis By Delivery Model, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Service Scope
- By AI Technology
- By Enterprise Size
- By Vertical
- By Delivery Model
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Accenture plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- International Business Machines Corporation
- Deloitte Touche Tohmatsu Limited
- McKinsey & Company
- Boston Consulting Group
- Capgemini SE
- PricewaterhouseCoopers International Limited
- Cognizant Technology Solutions
- Accenture plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


