

- Market Size (2026)
- USD 71090.7 Mn
- Forecast (2036)
- USD 100280.5 Mn
- CAGR (2026 to 2036)
- 3.5%
How big is Automotive Body-in-White Market in 2026?
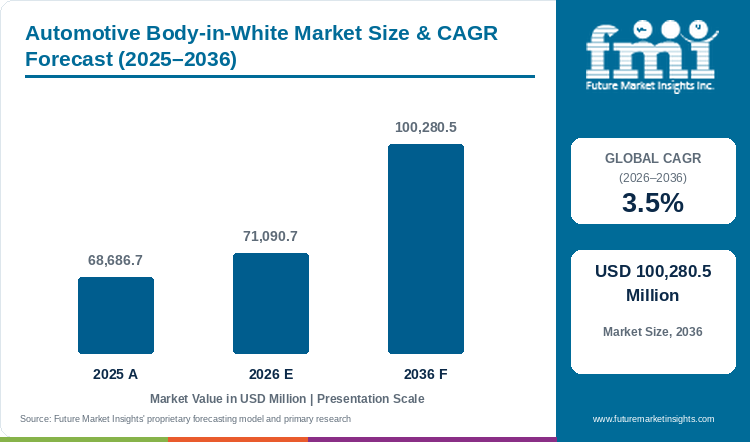
The automotive body-in-white market is estimated at USD 68.7 billion in 2025 and is forecast to reach USD 71.1 billion in 2026. Sales are projected to grow at a 3.5% CAGR and reach USD 100.3 billion by 2036.
Automotive body-in-white sales are predicted to increase at a 3.5% CAGR through 2036, from USD 68.7 billion in 2025 and USD 71.1 billion in 2026 to USD 100.3 billion by 2036. Carmakers are replacing welded rear structures with single large castings on new electric models. Volvo Cars started EX60 production at Torslanda in April 2026, the first Volvo built with megacasting, and one casting replaced 60 to 100 welded steel rear parts.[1] Each casting removes dozens of stampings from a body, so new body content flows toward suppliers with large die-casting cells.
Buyer power and supplier power weigh most on body-in-white margins among the five forces. Carmakers award body work one programme at a time and pick suppliers able to stamp, weld and assemble a full structure close to the car plant. On the input side, the European Parliament adopted a steel import regime on 19 May 2026 that roughly halves tariff quota volumes and doubles the out-of-quota tariff to 50% from 1 July.[2] Body suppliers now sit between a few large carmakers and domestic mills facing less import competition, so steel indexation clauses that pass sheet costs to the carmaker become the main defence of margin.
Key Market Trends & Insights
- Body structures will lead product type with 46.8% share in 2026, ahead of body components at about 31.4%. Gestamp kept a group EBITDA margin of 11.2% in the first half of 2026.[3]
- Passenger vehicles are set to lead vehicle type with 58.3% share in 2026, and light commercial vehicles should hold about 27.5%.
Regional Highlights
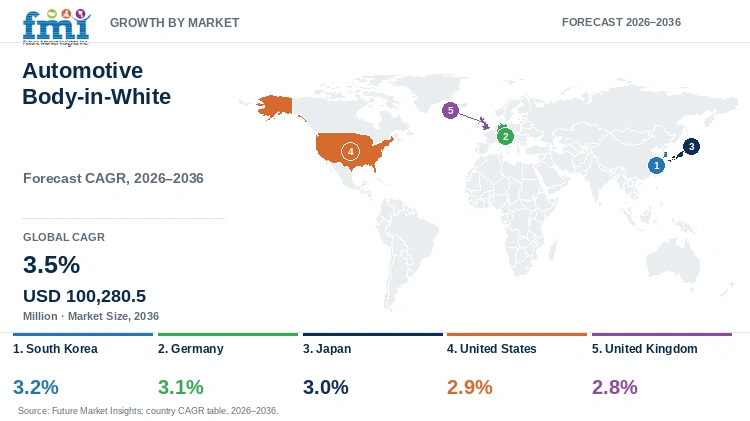
- Sales of body-in-white parts in South Korea are projected to grow at the top profiled CAGR, 3.2% from 2026 to 2036.
- Next come Germany at 3.1%, Japan at 3% and the United States at 2.9%, with the United Kingdom last at 2.8%.
- US tariffs on steel, aluminium and derivative articles rose from 25% to 50% on 4 June 2025, and UK articles stayed at 25%.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive Body-in-White Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 68,686.7 million |
| Estimated Market Size in 2026 | USD 71,090.7 million |
| Projected Market Size by 2036 | USD 100,280.5 million |
| CAGR, 2026 to 2036 | 3.5% |
| Added Revenue, 2026 to 2036 | USD 29,189.8 million |
| Market Expansion Multiple | 1.4x |
Body-in-white orders are released programme by programme, and each award ships only after the vehicle enters production. Martinrea secured new structural component work in the Lightweight Structures group with Ford and Volkswagen/Scout in the second quarter of 2026.[5] Martinrea also said industry light vehicle production rose about 1% in North America and fell about 3% in Europe in that quarter.[5] Casting cells need large presses before the first part ships, and the gigacasting presses market is expected to grow at a 13% CAGR from 2026 to 2036, so press orders signal the casting programmes due two to three years later. FMI estimates USD 29,189.8 million of added sales from 2026 to 2036, leaving 2036 sales 1.4x the 2026 level. A drop in European vehicle builds is the largest near-term risk, since stamping lines run below capacity when model volumes fall.
Steel Import Rules and Cast Aluminium Body Structures
US and EU tariff rules raised the border cost of imported car-body steel during 2025 and 2026, as FMI's review finds. The US raised tariffs on steel, aluminium and derivative articles from 25% to 50% with effect from 4 June 2025.[4] The European Parliament adopted a new steel import regime on 19 May 2026 that roughly halves tariff quota volumes and doubles the out-of-quota tariff to 50% from 1 July.[2] Body shops buying imported coated sheet will move more tonnage to domestic mills in each region, and long supply contracts will replace spot purchases.
Volvo Cars and the Lexus unit of Toyota are both adopting large aluminium castings in 2026 and 2027. Volvo Cars invested around SEK 10 billion at Torslanda, including mega casting, a battery assembly plant and a refurbished paint shop.[6] Lexus will use Gigacast integrated die-casting on a next-generation electric SUV at a new Shanghai plant, with assembly reported to begin in the second half of 2027.[7] The same report said the process could cut weight in some body structures by up to 20%.[7] Martinrea said higher aluminium costs linked to the Middle East situation reduced the adjusted operating income margin in the second quarter of 2026.[5]
Table 2: Steel Rule and Casting Indicators for the Automotive Body-in-White Market (rates, dates and counts), 2025 to 2027
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| US steel and aluminium tariff, 4 June 2025 | Raised from 25% to 50% | Imported sheet costs more for US body shops. | [4] |
| EU steel import regime, adopted 19 May 2026 | Quotas roughly halved, out-of-quota tariff 50% from 1 July | European body plants buy more domestic steel. | [2] |
| Volvo EX60 megacasting, April 2026 | 60 to 100 welded steel parts replaced by one casting | Fewer stampings per rear structure. | [1] |
| Volvo Torslanda upgrade | Around SEK 10 billion | Casting moves into European car plants. | [6] |
| Lexus Shanghai Gigacast plant | Assembly from second half of 2027 | Japanese carmakers adopt casting in China. | [7] |
| Gestamp first half 2026 | Revenue €5.7 billion, EBITDA margin 11.2% | Margins hold despite lower revenue. | [3] |
| India passenger vehicles, FY2025-26 | 46.43 lakh units, up 7.9% | India adds body-in-white volume. | [8] |
Analyst Perspective
“My pick for body-in-white volume growth over the next decade is India, because passenger vehicle sales and exports there are rising together and every new model needs a fresh stamped and welded body. European plants face flat builds and dearer imported steel, so I expect the biggest new press and welding lines of this decade to be commissioned in India. Suppliers adding hot-forming and assembly capacity in India by 2028 will serve export programmes as well as domestic ones.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the automotive body-in-white market segmented?
Two axes, product type and vehicle type, divide body-in-white sales alongside region. Body structures are expected to lead product type with 46.8% share in 2026, and passenger vehicles are projected to lead vehicle type with 58.3%.
By product type: body structure, body component, and chassis.
By vehicle type: passenger vehicles, light commercial vehicles (LCVs), and heavy commercial vehicles (HCVs).
By region: body-in-white coverage spans Western Europe, East Asia, North America, Eastern Europe, South Asia and Pacific, Latin America, and Middle East and Africa.
Why do body structures lead product sales of automotive body-in-white parts?
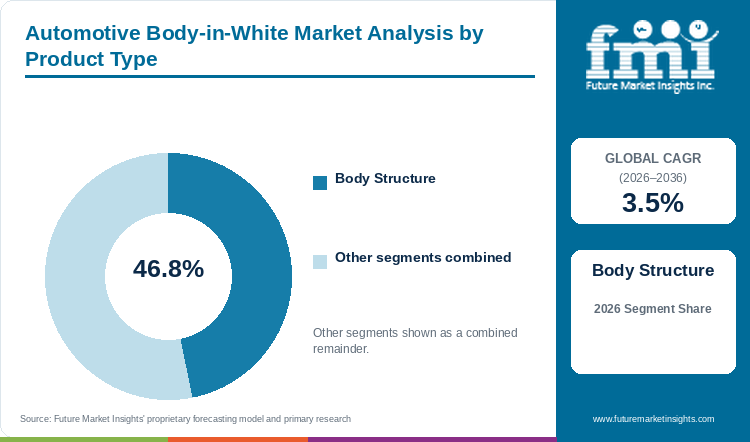
Of 2026 product sales, body structures are estimated at 46.8%, ahead of body components at about 31.4%.
Table 3: Product Type Share for the Automotive Body-in-White Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Body Structure | 46.8% |
| Body Component | 31.4% |
| Chassis | 21.8% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Automotive Body-in-White Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.5% |
| Leading Segment | Body Structure |
Body structures are expected to lead with 46.8% share in 2026, because the floor, roof rails, pillars and crash members carry crash loads and carmakers buy floors and pillars in the most expensive hot-formed and high-strength grades. Body components, at about 31.4%, cover doors, hoods, fenders and tailgates, which are lighter parts made in mild steel or aluminium and priced lower per vehicle. Chassis parts are likely to hold 21.8%, since subframes and crossmembers weigh less than a full safety cage, and the automotive battery pack crossmembers market is forecast to grow at a 7.1% CAGR from 2026 to 2036 as electric floors add battery-carrying members. Pillars carry side-impact loads in every body, and the automotive pillars market is set to grow at a 3.2% CAGR from 2026 to 2036, near the 3.5% body-in-white rate. Carmakers changing to castings will cut stamped structure parts first, so body structures will face the most substitution by 2036.
- Body structure parts include floor panels, roof rails, A, B and C pillars, and front and rear crash members.
- Volvo replaced 60 to 100 welded steel rear structure parts with one casting on the EX60.[1]
Why do passenger vehicles lead vehicle type sales of body-in-white parts?
Vehicle type sales in 2026 are likely to favour passenger vehicles at 58.3%, with light commercial vehicles at about 27.5%.
Table 5: Vehicle Type Share for the Automotive Body-in-White Market (percentage share), 2026
| Vehicle Type | Estimated Share (2026) |
|---|---|
| Passenger Vehicles | 58.3% |
| Light Commercial Vehicles (LCVs) | 27.5% |
| Heavy Commercial Vehicles (HCVs) | 14.2% |
| Total | 100.0% |
Passenger vehicles are projected to lead with 58.3% share in 2026, as car and SUV builds far outnumber van and truck builds. India sold 46.43 lakh passenger vehicles in FY2025-26, up 7.9%, against 10.80 lakh commercial vehicles.[8] Light commercial vehicles are anticipated to hold 27.5%, because vans and pickups share many body parts across long model lives. Heavy commercial vehicles are near 14.2%, since a truck buyer pays for a cab and frame but no full closed body. Electric car platforms will add cast and composite content, and the automotive composites market is anticipated to grow at a 12.3% CAGR from 2026 to 2036, which will move value toward passenger car bodies.
- Passenger orders come mainly from compact SUVs, sedans and electric crossovers.
- Volvo Cars started production of the EX60 electric SUV in April 2026.[6]
What are the drivers, restraints, and opportunities in the automotive body-in-white market?
Large castings in electric car bodies and growing vehicle output in South Asia drive demand for body-in-white parts. Steel import rules in the United States and Europe raise sheet costs for body plants.
- Driver: Carmakers moving the rear sections of electric models to single large castings shift body content toward suppliers with big die-casting cells and away from stampers of many small welded parts.
- Restraint: Tighter steel import rules in Europe and the United States raise the cost of coated and high-strength sheet, which squeezes body plant margins until indexation clauses pass the cost on to carmakers.
- Opportunity: Rising domestic car sales and exports in India call for new stamping and assembly lines, so body suppliers adding local capacity can secure both home and export programmes.
Castings Enter European and Chinese Electric Car Bodies
Adoption of gigacasting for auto body rear sections is moving from Tesla to European and Japanese carmakers. Volvo increased 2026 EX60 production volumes on demand in Sweden, Germany and other European markets.[6] Lexus plans about 1,000 Gigacast-built electric SUVs a month in the first year at the Shanghai plant.[7] Battery-carrying members gain body content as well, with the automotive battery pack crossmembers market forecast to grow at a 7.1% CAGR over 2026 to 2036. Casting suppliers will gain programme content in each new electric platform, and stamping suppliers will shift work to front structures and closures.
Steel Import Rules Raise Sheet Costs
The EU's new steel import regime is raising the cost bar for imported flat steel from 1 July 2026, with quota volumes roughly halved.[2] Due to this, European body-in-white plants will pay more for coated and high-strength sheet bought outside the quota. US rules already set steel and derivative tariffs at 50% from June 2025.[4] Body suppliers will pass part of the cost to carmakers through steel indexation clauses.
Indian Vehicle Output Opens New Body Lines
Indian body plants are expected to add the most new body-in-white sales, with passenger vehicle exports up 17.5% in FY2025-26.[8] SIAM credited GST 2.0 reforms and repo rate cuts for the growth.[8] As per FMI's analysis, all five profiled countries grow below the 3.5% global CAGR, which points to India and China as the main volume adders. Indian stamping and assembly lines will take export body programmes from 2027 onward.
Which country CAGRs are profiled in the automotive body-in-white market?
Table 6: Country CAGR Comparison for the Automotive Body-in-White Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| South Korea | 3.2% |
| Germany | 3.1% |
| Japan | 3% |
| United States | 2.9% |
| United Kingdom | 2.8% |
How do country-level CAGRs compare in the automotive body-in-white market?
UK steel and derivative articles kept a 25% US tariff after June 2025, half the 50% rate on most other countries.[4] The FMI report forecasts South Korea to grow at 3.2%, Germany at 3.1%, Japan at 3%, the United States at 2.9% and the United Kingdom at 2.8%, all from 2026 to 2036. Every profiled rate is below the 3.5% global CAGR, because India and China add more vehicle builds than these mature producers. Levers differ, with casting adoption and EU steel quotas in Germany, steel tariffs in the United States and electric platforms at Korean and Japanese carmakers.
- Korean carmakers add electric platforms that need new body shops.
- Body plants in Germany face halved EU steel import quotas from July 2026.
- Japanese carmakers take Gigacast methods to new plants in China.
- US body shops pay 50% tariffs on most imported steel.
- Body plants in the United Kingdom build fewer models, which keeps the United Kingdom rate lowest.
Full report country CAGRs cover: Korean and Japanese rates within East Asia, Germany and the United Kingdom within Western Europe, the United States within North America, and regional tables for Latin America, Eastern Europe, South Asia and Pacific, and Middle East and Africa.
Country-wise Analysis
South Korea Automotive Body-in-White Market Outlook (2026 to 2036)
FMI expects demand for body-in-white parts in South Korea to grow at a 3.2% CAGR from 2026 to 2036, the top profiled rate. Korean carmakers will launch more electric models on dedicated platforms, and each launch will need new floor, battery tray and crash member tooling.
Key takeaway: Electric platform launches will give Korea the highest profiled growth.
Germany Automotive Body-in-White Market Outlook (2026 to 2036)
Body suppliers serving German carmakers now need casting cells beside stamping lines, as the one-piece EX60 rear structure shows. Volvo raised 2026 EX60 volumes on demand in Sweden, Germany and other European markets.[6] The new EU steel regime cuts import quotas from 1 July 2026, which raises sheet costs at German body plants.[2] FMI projects sales of body-in-white parts in Germany to grow at a 3.1% CAGR from 2026 to 2036, and casting suppliers will bid on the rear structure of every new electric body.
Key takeaway: Dearer imported steel and new casting lines will change which suppliers take body awards in Germany.
Japan Automotive Body-in-White Market Outlook (2026 to 2036)
Toyota's Lexus unit will build a Gigacast electric SUV in Shanghai, with output planned to rise to tens of thousands of units a year from 2028.[7] Domestic Japanese body plants will keep welded steel shells for most current models. FMI sees sales in Japan growing at a 3% CAGR from 2026 to 2036.
Key takeaway: Japanese casting volume will start in China before home plants.
United States Automotive Body-in-White Market Outlook (2026 to 2036)
US body shops buying imported steel pay a 50% tariff since June 2025.[4] Martinrea secured structural component work with Ford and Volkswagen/Scout in the second quarter of 2026, and North American light vehicle production rose about 1% in that quarter.[5] Gestamp raised the North American EBITDA margin to 8% in the first half of 2026 from 7.1%.[3] FMI points to a 2.9% CAGR for the United States from 2026 to 2036.
Key takeaway: US body suppliers are restoring margins through local steel and new truck and SUV awards.
United Kingdom Automotive Body-in-White Market Outlook (2026 to 2036)
At 2.8%, the United Kingdom CAGR from 2026 to 2036 is the lowest profiled rate. UK steel articles kept a 25% US tariff after June 2025, and the Commerce Secretary may set UK quotas under the US-UK Economic Prosperity Deal.[4] UK body plants will rely on a few high-volume models.
Key takeaway: Sales of body-in-white parts in the United Kingdom will move with the number of models built in UK plants.
Who are the notable companies in the automotive body-in-white market?
Gestamp, Magna International, Benteler, Martinrea International, KIRCHHOFF Automotive, voestalpine and Tata AutoComp Systems are the profiled companies.
Carmakers award body-in-white work to suppliers that can stamp, hot-form, weld and assemble a full structure close to the car plant. Gestamp reported first-half 2026 revenue of €5.7 billion, down 0.9% on adverse exchange rates, and net income rose 47% to €110 million.[3] Gestamp cut net debt by 17% to €1.7 billion in the same period.[3] Martinrea's second-quarter 2026 sales fell 5.9%, and new awards in Lightweight Structures came from Ford and Volkswagen/Scout.[5]
- Global body and chassis suppliers: Gestamp, Magna International, and Benteler.
- Structure and lightweight specialists: Martinrea International, and KIRCHHOFF Automotive.
- Steel-based and regional suppliers: voestalpine, and Tata AutoComp Systems.
Competitive Benchmarking: Automotive Body-in-White Market
Table 7: Competitive Benchmarking for the Automotive Body-in-White Market (qualitative documentation ratings), 2026
| Company | Hot Forming and Stamping | Aluminium and Casting | North America Reach | Recency |
|---|---|---|---|---|
| Gestamp | High | Medium | High | High |
| Magna International | High | High | High | Low |
| Benteler | High | Medium | Medium | Low |
| Martinrea International | Medium | Medium | High | High |
| KIRCHHOFF Automotive | Medium | Low | Medium | Low |
| voestalpine | High | Low | Medium | Low |
| Tata AutoComp Systems | Medium | Low | Low | Low |
Scores count the dated releases behind each rating, and no score ranks companies by share.
Key Developments in the Automotive Body-in-White Market
- On 28 August 2026, CnEVPost reported that Lexus will use Gigacast die-casting at the new Shanghai plant.[7]
- In August 2026, Martinrea reported Lightweight Structures awards with Ford and Volkswagen/Scout.[5]
- In July 2026, Gestamp reported first-half revenue of €5.7 billion and an 11.2% EBITDA margin.[3]
- In May 2026, the European Parliament adopted the new EU steel import regime.[2]
- In April 2026, Volvo Cars started EX60 production at Torslanda with mega casting.[6][1]
- In April 2026, SIAM reported FY2025-26 passenger vehicle sales of 46.43 lakh units in India.[8]
- In June 2025, the US raised steel and aluminium tariffs to 50%.[4]
Key Players in the Automotive Body-in-White Market
Global Body and Chassis Suppliers
- Gestamp
- Magna International
- Benteler
Structure and Lightweight Specialists
- Martinrea International
- KIRCHHOFF Automotive
Steel-Based and Regional Suppliers
- voestalpine
- Tata AutoComp Systems
Automotive Body-in-White Market - Report Scope
Table 8: Report Scope for the Automotive Body-in-White Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; vehicle type; region |
| Quantitative units | USD million |
| Market definition | Welded, cast and assembled body structures, body components and chassis parts that form the unpainted vehicle body. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Gestamp, Magna International, Benteler, Martinrea International, KIRCHHOFF Automotive, voestalpine, Tata AutoComp Systems |
| Forecast period | 2026 to 2036 |
Automotive Body-in-White Market - Research Methodology
Table 9: Research Methodology for the Automotive Body-in-White Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Supplier results, carmaker releases, trade rulings and automotive trade press from May 2025 onward. |
| Desk Research | Desk work covers casting launches, steel tariffs and quotas, vehicle sales and supplier awards. |
| Market Sizing and Forecasting | The 2026 base of USD 71,090.7 million is projected at a 3.5% CAGR to 2036. |
| Data Validation | Tariff rates and production dates were matched to the proclamation, parliament vote or carmaker release. |
Automotive Body-in-White Market by Segments
Automotive Body-in-White Market segmented by Product Type:
- Body Structure
- Body Component
- Chassis
Automotive Body-in-White Market segmented by Vehicle Type:
- Passenger Vehicles
- Light Commercial Vehicles (LCVs)
- Heavy Commercial Vehicles (HCVs)
Automotive Body-in-White Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Repairer Driven News. (2026, April 28). Volvo starts production of first vehicle with megacasting. https://www.repairerdrivennews.com/2026/04/28/volvo-starts-production-of-first-vehicle-with-megacasting/
- [2] Eurometal. (2026, May 19). New EU steel import regime enters law, effective 1 July. https://eurometal.net/new-eu-steel-import-regime-enters-law-effective-1-july/
- [3] Gestamp. (2026, July 30). Gestamp reports revenues of €5.7bn for H1 2026 and remains on track to deliver its full-year guidance. https://www.gestamp.com/Media/News/Press-Releases/2026/Gestamp-reports-revenues-of-€5-7bn-for-H12026-and-remains-on-track-to-deliver-its-full-year-guidance
- [4] The White House. (2025, June 3). Adjusting Imports of Aluminum and Steel into the United States. https://www.whitehouse.gov/presidential-actions/2025/06/adjusting-imports-of-aluminum-and-steel-into-the-united-states/
- [5] Martinrea International. (2026, August 4). Q2 2026 Results Press Release. https://www.martinrea.com/wp-content/uploads/Q2-2026-Results-Press-Release.pdf
- [6] Volvo Cars. (2026, April 22). Volvo Cars starts production of game-changing EX60 electric SUV. https://www.volvocars.com/intl/media/press-releases/24928A8C5C6C5E4E/
- [7] CnEVPost. (2026, August 28). Toyota to begin China production of Lexus electric SUV in H2 2027. https://cnevpost.com/2026/08/28/toyota-to-begin-china-production-lexus-electric-suv-h2-2027/
- [8] Autoguide India. (2026, April 15). Indian Auto Industry Records Strong Growth in Q4 FY2025-26 and Full Year Performance: SIAM. https://www.autoguideindia.com/statistics/indian-auto-industry-performance-q4-fy2025-26-siam-sales/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the automotive body-in-white market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which vehicle type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the automotive body-in-white market expected in 2026?
Carmakers will buy USD 71,090.7 million of body-in-white parts in 2026, up from USD 68,686.7 million in 2025. FMI expects USD 100,280.5 million by 2036.
What CAGR is projected for the automotive body-in-white market through 2036?
Body-in-white sales will grow at a 3.5% CAGR from 2026 to 2036. The added USD 29,189.8 million will come mostly from electric platforms and vehicle output in India.
Which product type holds a notable market share in 2026?
Body structures should lead with 46.8% share in 2026. Body components will hold about 31.4%.
Which vehicle type holds a notable market share in 2026?
Passenger vehicles will lead with 58.3% share in 2026. Light commercial vehicles are likely to hold about 27.5%.
Which country has a notable expansion outlook through 2036?
Korea will grow at a 3.2% CAGR from 2026 to 2036, the first among profiled countries, as per FMI. The United Kingdom comes last at 2.8%.
Who are the key companies in the automotive body-in-white market?
Among the main suppliers are Gestamp, Magna International, Benteler and Martinrea International. KIRCHHOFF Automotive, voestalpine and Tata AutoComp Systems also supply stamped and assembled body parts.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Body Structure
- Body Component
- Chassis
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Vehicles
- Light Commercial Vehicles (LCVs)
- Heavy Commercial Vehicles (HCVs)
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Vehicle Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Vehicle Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Vehicle Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Gestamp
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Magna International
- Benteler
- Martinrea International
- KIRCHHOFF Automotive
- voestalpine
- Tata AutoComp Systems
- Gestamp
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


