
- Market Size (2026)
- USD 11.7 Bn
- Forecast (2036)
- USD 37.4 Bn
- CAGR (2026 to 2036)
- 12.3%
How big is Automotive Composites Market in 2026?
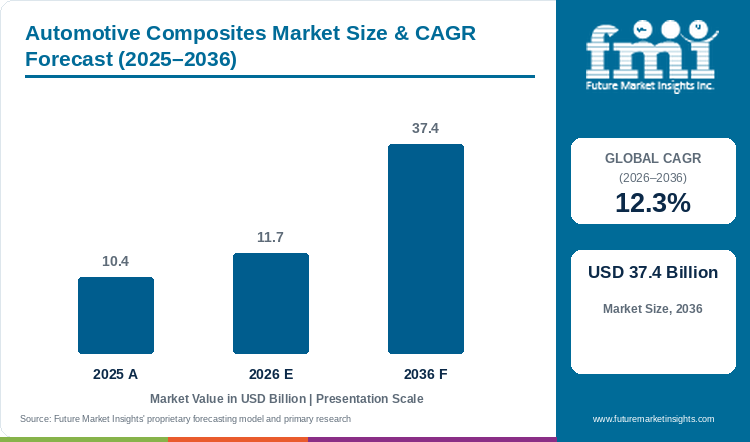
Sales of automotive composites will grow at a CAGR of 12.3% from 2026 to 2036. Market size was USD 10.4 billion in 2025 and is projected to reach USD 11.7 billion in 2026 and USD 37.4 billion by 2036.
Automotive composites market size stood at USD 10.4 billion in 2025, is estimated at USD 11.7 billion in 2026 and is projected to reach USD 37.4 billion by 2036. Glass fiber composites hold 56% of material type sales, interior parts hold 30% of application sales and passenger cars hold 65% of vehicle type sales in 2026, FMI data show.
Vehicle makers are signing material partnerships. Hyundai Motor Group and Toray signed a joint development agreement on 24 October 2025 to develop composites for high-performance vehicles and special-purpose mobility.[1] Partnerships of this kind will move composites from interior trim into structural parts.
Fuel economy rules in the USA give limited reason to pay for lighter parts. Passenger car standards rise 0.90% a year through model year 2029 and 1% a year through model year 2031, and NHTSA puts the model year 2031 fleet average at roughly 34.9 mpg.[2] Sales of automotive composites will therefore grow at a CAGR of 12.3% from 2026 to 2036 on the strength of vehicle programmes.
Key Market Trends & Insights
- By material type, glass fiber composites led with 56% of sales in 2026. Owens Corning completed the sale of the glass reinforcements business to Praana Group in April 2026.[3]
- By application, interior parts led with 30% of sales in 2026, ahead of exterior, underbody and chassis applications.
- By resin, thermoplastic systems led with 55% of sales in 2026. Envalior reported in May 2026 that a sustainable Tepex grade built on polypropylene and continuous glass fiber carries a carbon footprint about 50% below the conventional version.[4]
- By vehicle type, passenger cars led with 65% of sales in 2026. The UK mandate sets zero emission vehicles at 33% of new car registrations for 2026.[5]
- By end use, OEM manufacturers led with an estimated 70% of sales in 2026. Hyundai Motor Group and Toray signed a joint development agreement on 24 October 2025.[1]
Regional Highlights
- Fastest-growing profiled country: the USA (13.6% CAGR, 2026 to 2036).
- By country: the EU (13.2%), South Korea (12.8%) and the UK (12.5%) follow, and Japan records the lowest profiled CAGR at 11.9%.
- Industrial applications of the Toray carbon fiber composite materials unit came to JPY 153.5 billion in the year to March 2026, against JPY 165.6 billion a year earlier.[6]
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive Composites Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 10.4 billion |
| Estimated Market Size in 2026 | USD 11.7 billion |
| Projected Market Size by 2036 | USD 37.4 billion |
| CAGR, 2026 to 2036 | 12.3% |
| Added Revenue, 2026 to 2036 | USD 25.7 billion |
| Market Expansion Multiple | 3.2x |
Market size is projected to add USD 25.7 billion between 2026 and 2036, which is 3.2 times the 2026 level. FMI ties the build to automaker lightweighting for EV range and to recyclable thermoplastic systems. Passenger platforms carry most of the load, and the passenger vehicles market covers the vehicle base those parts are specified into. Resin feedstock cost and limited recycling routes hold part cost above metal. Bucci Composites licensed double diaphragm forming from Syensqo in July 2026 to meet OEM calls for higher-volume structural parts, bodywork components and battery enclosures.[7]
Lightweighting Cost-Benefit and Emission Rules
Rule pressure differs across the signals in Table 2. The USA raises passenger car fuel economy standards by 0.90% a year through model year 2029 and by 1% a year through model year 2031, and NHTSA puts the model year 2031 fleet average at roughly 34.9 mpg.[2] The EU proposal leaves the final 10% of the 2035 car CO2 cut to be offset with EU-made low-carbon steel, e-fuels or biofuels.[8] Low-carbon steel is the metal that composites have to beat on cost per kilogram saved, so the offset route gives automakers a second way to reach the same target. The UK sets zero emission vehicles at 33% of new car registrations in 2026 and 80% by 2030, and range is the argument for each kilogram removed from an electric car.[5]
Suppliers show the cost side of the same trade. Toray held carbon fiber composite materials sales near JPY 300.1 billion in the year to March 2026, yet core operating income fell 21.7% to JPY 17.6 billion.[6] SGL Carbon reported Fiber Composites sales of EUR 99.4 million for the first half of 2026, against EUR 152.6 million a year earlier, as loss-making carbon fiber activities were discontinued, and the Fiber Composites segment adjusted EBITDA improved to EUR 18.9 million, with a segment EBITDA margin of 19.0%.[9] Envalior says the sustainable glass fiber Tepex grade is a drop-in replacement that needs no requalification.[4] Margin follows discipline and drop-in grades. A buyer who accepts a higher price per kilogram saved needs a range or crash-structure reason to do so.
Table 2: Lightweighting Rule and Supplier Cost Indicators for the Automotive Composites Market (percentage, JPY, EUR and USD values), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| US SAFE Vehicles Rule III | Published 30 September 2026; effective 30 November 2026; model years 2022 to 2031 | The rule recalibrates the CAFE program for passenger cars and light trucks. | [10] |
| US passenger car stringency | 0.90% a year to model year 2029, then 1% a year to model year 2031; about 34.9 mpg fleet average in model year 2031 | Annual steps are small for weight reduction. | [2] |
| US fleet reclassification from model year 2030 | Fleet mix moves from about 70% light trucks to about 70% passenger cars | Passenger cars carry more of the fleet standard. | [2] |
| EU 2035 car CO2 proposal, 17 December 2025 | Target relaxed from 100% to 90% against the 2021 baseline | The proposal lowers the compliance push on weight. | [8] |
| EU offset route | Remaining 10% offset with EU-made low-carbon steel, e-fuels or biofuels | Steel becomes a compliance tool against composites. | [8] |
| UK zero emission vehicle mandate | 28% of new car registrations in 2025; 33% in 2026; 80% by 2030 | The quota rises each year and raises demand for range. | [5] |
| Toray carbon fiber composite materials, year to March 2026 | Sales JPY 300.1 billion; core operating income JPY 17.6 billion, down 21.7% | Flat sales came with lower profit. | [6] |
| Toray industrial applications, year to March 2026 | JPY 153.5 billion against JPY 165.6 billion | Industrial uses entered an adjustment phase. | [6] |
| SGL Carbon Fiber Composites, first half of 2026 | Sales EUR 99.4 million against EUR 152.6 million; adjusted EBITDA margin 19% | Sales fell after loss-making activities were discontinued. | [9] |
| Owens Corning glass reinforcements sale | Enterprise value USD 645 million; cash proceeds about USD 280 million | Terms were announced on 15 April 2026. | [3] |
| Envalior Tepex grade, May 2026 | Polypropylene with continuous glass fiber; carbon footprint about 50% lower | The grade needs no requalification. | [4] |
| Syensqo licence to Bucci Composites, July 2026 | Double diaphragm forming for structural parts, bodywork and battery enclosures | The licence targets higher-volume production. | [7] |
Analyst Perspective
“Rule relief in the USA and EU removes part of the compliance push, so lightweighting now has to pay for itself in range and part cost. Glass fiber thermoplastics that drop into existing lines will carry most of the 12.3% growth through 2036, and carbon fiber will stay with programs that can fund the premium.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Automotive Composites Market segmented?
The automotive composites market is segmented into material type, application, resin, vehicle type, and end use, and region. In 2026, glass fiber composites hold 56% of material type sales, interior parts hold 30% of application sales, thermoplastic holds 55% of resin sales, passenger cars hold 65% of vehicle type sales and OEM manufacturers hold an estimated 70% of end use sales.
By material type: glass fiber, carbon fiber, natural fiber, aramid fiber, and others.
By application: interior, exterior, underbody, chassis, power train, engine components, structural components, underbody components, and others.
By resin: thermoplastic, thermoset, and bio-based.
By vehicle type: passenger cars, LCV, HCV, agricultural vehicles, electric vehicles, and performance vehicles.
By end use: OEM manufacturers, aftermarket, and tier suppliers.
By region: North America, Latin America, Europe, Asia Pacific, and Middle East and Africa.
Why do glass fiber composites lead material type sales?
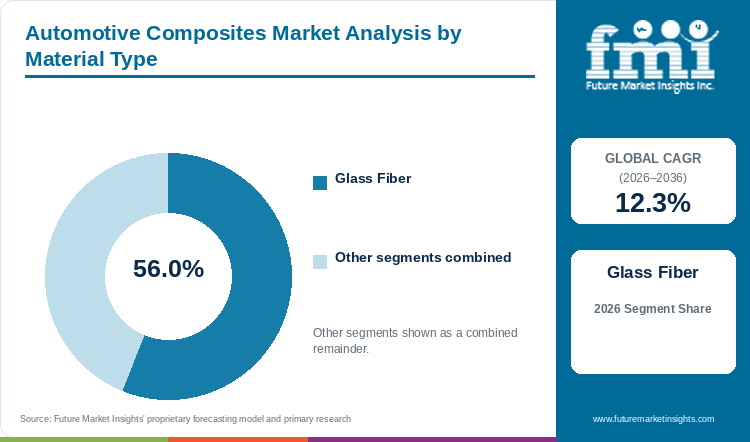
Glass fiber composites account for 56% of material type sales in 2026, ahead of carbon fiber, natural fiber, aramid fiber and other materials.
Table 3: Material Type Share for the Automotive Composites Market (percentage share), 2026
| Material Type | Estimated Share (2026) |
|---|---|
| Glass Fiber Composites | 56% |
| Carbon Fiber Composites | 24% |
| Natural Fiber Composites | 9% |
| Aramid Fiber Composites | 4% |
| Others | 7% |
| Total | 100.0% |
Table 4: Material Type Leadership and Market Growth for the Automotive Composites Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 12.3% |
| Leading Segment | Glass Fiber Composites |
Cost sets the order of the material split. FMI traces the glass fiber lead to sheet molding compounds and long fiber thermoplastics, which give lightweighting at a mass-market price. Carbon fiber suppliers show the other side of the choice. Toray held carbon fiber composite materials sales at JPY 300.1 billion in the year to March 2026, and core operating income fell 21.7%.[6] Owens Corning completed the sale of the glass reinforcements business to Praana Group in April 2026, with terms announced on 15 April.[3] Carbon fiber stays confined to parts with a price premium that is easy to defend.
- Mass-market cost keeps glass fiber in interior and under-hood parts.
- SGL Carbon cut Fiber Composites sales to EUR 99.4 million in the first half of 2026 by ending loss-making activities, and adjusted EBITDA margin reached 19%.[9]
What keeps interior parts ahead of other applications?
Interior parts account for 30% of application sales in 2026, ahead of exterior, underbody, chassis and other applications.
Dashboards and seats fall under interior applications. Envalior lists front-end carriers and seat pans among the uses of the glass fiber Tepex composite, announced on 19 May 2026.[4] The release calls the grade a drop-in replacement without requalification, which shortens the path into cabin programs. The passenger car seat market follows the same seat structures from the seat maker side. A material change that avoids requalification is the one an interior program can approve in a single model cycle.
- Dashboards and seats anchor the interior segment.
- Bucci Composites targets bodywork components and structural parts under the Syensqo licence of July 2026.[7]
Which resin system gives thermoplastics the lead?
Thermoplastic resins account for 55% of resin sales in 2026, ahead of thermoset and bio-based systems.
Payback speed puts thermoplastics ahead of thermosets in volume lines. FMI lists polypropylene, polyamide and polycarbonate under thermoplastic resins and names recyclable, high-cycle materials in the analyst view. Envalior announced on 19 May 2026 a Tepex grade built from glass fibers made from glass waste and bio-circular polypropylene, with a carbon footprint about 50% below the conventional grade.[4] Recyclability becomes a purchasing test next to cycle time, because end-of-life limits constrain thermoset use in volume vehicles.
- Polypropylene, polyamide and polycarbonate form the thermoplastic resin group.
- The sustainable origin of the new Tepex grade is verified under ISCC Plus on a mass-balance basis.[4]
Why do passenger cars carry most vehicle type sales?
Passenger cars account for 65% of vehicle type sales in 2026, ahead of LCVs, HCVs and the other vehicle groups.
Hatchbacks, sedans and SUVs make up the passenger car group and absorb most composite parts. US rules point the same way. The reclassification from model year 2030 would move the fleet mix from about 70% light trucks and 30% passenger vehicles to about 70% passenger cars and 30% light trucks.[2] The UK sets 33% of new car registrations as zero emission in 2026.[5] OEMs call for higher-volume structural parts, and battery enclosures are among the uses named in the Bucci Composites licence of July 2026.[7] The automotive battery pack crossmembers market covers the pack structures involved. LCVs, HCVs, agricultural vehicles, electric vehicles and performance vehicles make up the other vehicle groups.
- Sedans, SUVs and hatchbacks form the volume base for composite parts.
- Hyundai Motor Group and Toray agreed on 24 October 2025 to develop composites for high-performance vehicles and special-purpose mobility.[1]
What puts OEM manufacturers first in end use sourcing?
OEM manufacturers account for an estimated 70% of end use sales in 2026, ahead of the aftermarket and tier suppliers.
Specification happens at platform design, so the OEM program calendar sets sourcing order. Mass-market and premium OEMs are the two OEM groups listed, and performance vehicles cover sports and luxury cars. Hyundai Motor Group handles vehicle-level design and evaluation under the October 2025 agreement with Toray, and Toray supplies intermediate materials and moulded products.[1] Tier suppliers carry process expertise, as the July 2026 Syensqo licence to Bucci Composites shows, since the pair aim to qualify material solutions jointly with OEMs.[7] Aftermarket sales stay secondary.
- Aftermarket and tier suppliers complete the end use split.
- Toray production for the Hyundai agreement runs through subsidiaries in Korea, the Netherlands and Germany.[1]
What are the drivers, restraints, and opportunities in the Automotive Composites Market?
In the automotive composites market, automaker lightweighting for EV range and emission targets drives sales, resin feedstock cost and limited recycling routes restrain adoption against metal, and recyclable thermoplastic systems open the main opportunity.
- Driver: Lightweighting of passenger platforms for EV range and quotas such as the UK 33% zero emission share in 2026 support sales.[5]
- Restraint: Resin feedstock cost, limited recycling routes and competition from advanced high-strength metals keep part cost above metal.
- Opportunity: Recyclable thermoplastic systems address the end-of-life limits that constrain thermoset use in volume vehicles.
Range and Quota Pressure Support Lightweighting
Quota steps in the UK rise from 28% of new car registrations in 2025 to 33% in 2026 and 80% by 2030.[5] The EU proposal of 17 December 2025 still sets a 90% cut for 2035.[8] The US rule published on 30 September 2026 takes effect on 30 November 2026 and ends CAFE credit trading from model year 2028.[2][10] Range remains the common argument across the three markets, and weight reduction is one of the cheaper levers.
Part Cost and Margin Pressure Limit Adoption
Core operating income of JPY 17.6 billion for Toray carbon fiber composite materials in the year to March 2026 was down 21.7%, and the company described industrial applications as entering an adjustment phase.[6] SGL Carbon ended loss-making activities in the Fiber Composites unit, and first half sales for 2026 fell to EUR 99.4 million.[9] Owens Corning sold the glass reinforcements business at an enterprise value of USD 645 million in April 2026.[3] Suppliers with thin margins have less room to fund price cuts against steel.
Recyclable Thermoplastics and Drop-in Grades Open Room
Toray forecasts carbon fiber composite materials sales of JPY 345.0 billion for the year to March 2027 and expects demand recovery in regular tow in the U.S. and Europe, particularly for pressure vessel and automotive applications.[6] Envalior positions a recycled-content Tepex grade with a carbon footprint about 50% lower than the conventional version.[4] Body structures covered in the automotive pillar market are a natural place for such grades to compete with metal. Recyclable thermoplastic systems answer the end-of-life concerns that limit volume use.
Which country CAGRs are profiled in the Automotive Composites Market?
Table 5: Country CAGR Comparison for the Automotive Composites Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| USA | 13.6% |
| EU | 13.2% |
| South Korea | 12.8% |
| UK | 12.5% |
| Japan | 11.9% |
How do country-level CAGRs compare in the automotive composites market?
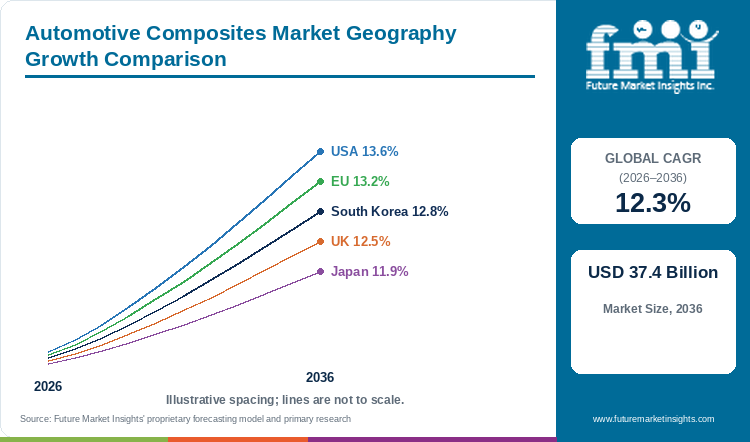
Growth of the automotive composites market differs by country owing to reshoring, emission rules and supplier networks. As per the analysis from FMI, the USA is projected to grow at a CAGR of 13.6% from 2026 to 2036, followed by the EU at 13.2% and South Korea at 12.8%. The UK is projected at 12.5%, and Japan at 11.9%. Four of the five profiled countries rank above the global CAGR of 12.3%, and the spread from first to last is 1.7 points.
- The USA pairs reshoring investment and EV platform expansion with a shallow fuel economy slope.
- The EU combines emission rules and circular-economy mandates with a relaxed 2035 car target.
- South Korea draws on Hyundai and domestic OEM networks.
- Premium and performance carmakers using more carbon fiber tie UK growth.
- Japan links keiretsu supplier networks with thermoplastic composite integration.
Full report country CAGRs cover: North America; Latin America; Europe; Asia Pacific; Middle East and Africa.
Country-wise Analysis
USA Automotive Composites Market Outlook (2026 to 2036)
Owens Corning completed the sale of the glass reinforcements business to Praana Group in April 2026, at an enterprise value of USD 645 million and with cash proceeds of about USD 280 million.[3] Domestic composite capacity is tied to reshoring investment and EV platform expansion, and the USA is projected to grow at a CAGR of 13.6% from 2026 to 2036, the fastest of the five profiled countries. The final fuel economy rule is softer on weight, since passenger car standards rise 0.90% a year through model year 2029 and credit trading ends from model year 2028.[2] Toray expects demand recovery in regular tow in the U.S., particularly for pressure vessel and automotive applications.[6]
Key takeaway: US growth of 13.6% comes from domestic capacity and EV platforms, not from regulatory pressure on weight.
EU Automotive Composites Market Outlook (2026 to 2036)
Emission rules and circular-economy mandates are the levers FMI names for the EU, which is projected to grow at a CAGR of 13.2% from 2026 to 2036. The proposal of 17 December 2025 would relax the 2035 car CO2 target from 100% to 90% and let automakers offset the remaining 10% with EU-made low-carbon steel, e-fuels or biofuels.[8] Envalior reported in May 2026 a Tepex grade with a carbon footprint about 50% below the conventional version, on a comparison representative of materials supplied to the European market.[4] SGL Carbon reported Fiber Composites sales of EUR 99.4 million for the first half of 2026.[9]
Key takeaway: A softer 2035 target moves the EU weight argument toward recycled content, with a 50% lower carbon footprint already claimed.
South Korea Automotive Composites Market Outlook (2026 to 2036)
Toray Advanced Materials Korea is one of three Toray subsidiaries named to produce intermediate materials and moulded products for Hyundai Motor Group under the agreement signed in Seoul on 24 October 2025.[1] The other two are Toray Advanced Composites in the Netherlands and Euro Advanced Carbon Fiber Composites in Germany.[1] Hyundai and domestic OEM networks are the stated lever, and South Korea is projected to grow at a CAGR of 12.8% from 2026 to 2036. The agreement builds on an April 2024 cooperation deal and covers research through commercialisation.[1]
Key takeaway: Korean demand follows the Hyundai program calendar, and the Toray agreement ties that calendar to a named Korean production base.
UK Automotive Composites Market Outlook (2026 to 2036)
The UK is projected to grow at a CAGR of 12.5% from 2026 to 2036, carried by premium and performance carmakers that are expanding carbon fiber use, according to FMI. The zero emission vehicle mandate rises from 28% of new car registrations in 2025 to 33% in 2026 and 80% by 2030.[5] Compliance payments of GBP 12,000 per car apply from 2025.[5] Low-volume makers receive a different treatment, since manufacturers under 1,000 registrations get a 0% target automatically.[5]
Key takeaway: Carbon fiber use among premium makers carries the UK growth of 12.5%, and the micro-volume exemption means the quota binds hardest on volume groups.
Japan Automotive Composites Market Outlook (2026 to 2036)
Toray, the Japanese carbon fiber supplier, reported carbon fiber composite materials sales of JPY 300.1 billion for the year to March 2026 in results issued on 13 May 2026.[6] Core operating income fell to JPY 17.6 billion, and the company forecasts sales of JPY 345.0 billion for the year to March 2027.[6] Keiretsu supplier networks integrating thermoplastic composites drive demand, and Japan is projected to grow at a CAGR of 11.9% from 2026 to 2036, the lowest of the five profiled countries and below the global 12.3%.
Key takeaway: Japan is the only profiled country below the global CAGR, and the keiretsu route places thermoplastic integration in the hands of supplier groups.
Who are the notable companies in the Automotive Composites Market?
Toray Industries, SGL Carbon, Teijin, Hexcel, Owens Corning, Huntsman, Solvay, BASF, Gurit, Mitsubishi Chemical Group, and Continental Structural Plastics are notable companies profiled in this market.
FMI rates Toray Industries and SGL Carbon High on material breadth and molding depth. Toray reported carbon fiber composite materials sales of JPY 300.1 billion for the year to March 2026 and signed a joint development agreement with Hyundai Motor Group on 24 October 2025.[6][1] SGL Carbon cut Fiber Composites sales to EUR 99.4 million in the first half of 2026 as loss-making activities ended.[9] Owens Corning completed the sale of the glass reinforcements business in April 2026.[3] Teijin, Hexcel, Huntsman, Solvay, BASF, Gurit, Mitsubishi Chemical Group and Continental Structural Plastics also compete for vehicle programs. Portfolio pruning at SGL Carbon and Owens Corning contrasts with the program build-out at Toray.
- Global fiber and composite producers: Toray Industries, SGL Carbon, and Teijin.
- Resin and material specialists: Hexcel, Owens Corning, Huntsman, Solvay, and BASF.
- Emerging and niche players: Gurit, Mitsubishi Chemical Group, and Continental Structural Plastics.
- Producers with documented 2025 and 2026 activity outside the list: Envalior and Syensqo.
Competitive Benchmarking: Automotive Composites Market
Table 6: Competitive Benchmarking for the Automotive Composites Market (qualitative documentation ratings), 2026
| Company | Material detail | Automotive link | Recent activity | Disclosure |
|---|---|---|---|---|
| Toray Industries | High | High | High | High |
| SGL Carbon | Medium | Low | High | High |
| Owens Corning | Low | Low | High | Medium |
| Envalior | Medium | High | High | Medium |
| Syensqo | Medium | High | Medium | Medium |
High indicates wider documentation in company filings and releases, Medium indicates limited documentation, and Low indicates less direct documentation. Ratings do not indicate product quality, market share or company rank.
Key Developments in the Automotive Composites Market
- On 30 September 2026, the US Federal Register published the SAFE Vehicles Rule III for model years 2022 to 2031, effective 30 November 2026.[10]
- On 6 August 2026, SGL Carbon reported Fiber Composites sales of EUR 99.4 million for the first half of 2026, with adjusted EBITDA of EUR 18.9 million.[9]
- In July 2026, Syensqo licensed double diaphragm forming to Bucci Composites for automotive structural parts, bodywork and battery enclosures.[7]
- On 19 May 2026, Envalior announced a Tepex grade with a carbon footprint about 50% below the conventional version.[4]
- On 13 May 2026, Toray reported carbon fiber composite materials sales of JPY 300.1 billion for the year to March 2026.[6]
- In April 2026, Owens Corning completed the sale of the glass reinforcements business to Praana Group.[3]
- On 17 December 2025, the EU automotive package proposed relaxing the 2035 car CO2 target from 100% to 90%.[8]
- On 24 October 2025, Hyundai Motor Group and Toray signed a joint development agreement on advanced materials for future mobility.[1]
Key Players in the Automotive Composites Market
Global Fiber and Composite Producers
- Toray Industries
- SGL Carbon
- Teijin Limited
Resin and Material Specialists
- Hexcel Corporation
- Owens Corning
- Huntsman Corporation
- Solvay
- BASF SE
Emerging and Niche Players
- Gurit
- Mitsubishi Chemical Group
- Continental Structural Plastics
Producers with Documented 2025 to 2026 Activity
- Envalior
- Syensqo
Automotive Composites Market - Report Scope
Table 7: Report Scope for the Automotive Composites Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Material type; application; resin; vehicle type; end use; region |
| Quantitative units | USD billion |
| Market definition | Automotive composites market covering fiber-reinforced composite materials and parts used in automotive interior, structural and under-hood applications, including glass and carbon fiber with thermoset and thermoplastic resins. |
| Regions covered | North America; Latin America; Europe; Asia Pacific; Middle East and Africa |
| Countries covered | USA; EU; South Korea; UK; Japan |
| Key companies profiled | Toray Industries, SGL Carbon, Teijin, Hexcel, Owens Corning, Huntsman, Solvay, BASF, Gurit, Mitsubishi Chemical Group, Continental Structural Plastics |
| Forecast period | 2026 to 2036 |
Automotive Composites Market - Research Methodology
Table 8: Research Methodology for the Automotive Composites Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Rule and supplier facts come from regulator notices, company filings, press releases and trade press dated May 2025 or later. |
| Desk Research | Desk research covers fuel economy and CO2 rule texts, company results and releases, and trade press on composite programs. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base market size of USD 10.4 billion and the 12.3% CAGR. |
| Data Validation | Rule dates and supplier results are checked against regulator texts and company releases. |
Automotive Composites Market by Segments
Automotive Composites Market segmented by Material Type:
- Glass Fiber
- Carbon Fiber
- Natural Fiber
- Aramid Fiber
- Others
Automotive Composites Market segmented by Application:
- Interior
- Exterior
- Underbody
- Chassis
- Power Train
- Engine Components
- Structural Components
- Underbody Components
- Others
Automotive Composites Market segmented by Resin:
- Thermoplastic
- Thermoset
- Bio-Based
Automotive Composites Market segmented by Vehicle Type:
- Passenger Cars
- LCV
- HCV
- Agricultural Vehicles
- Electric Vehicles
- Performance Vehicles
Automotive Composites Market segmented by End Use:
- OEM Manufacturers
- Aftermarket
- Tier Suppliers
Automotive Composites Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- Middle East and Africa
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] Hyundai Motor Group. (2025, October 27). Hyundai Motor Group and Toray Group Strengthen Ties to Develop Advanced Materials for Future Mobility.
- [2] U.S. Department of Transportation, National Highway Traffic Safety Administration. (2026, September 30). The Safer Affordable Fuel-Efficient (SAFE) Vehicles Rule III for Model Years 2022 to 2031 Passenger Cars and Light Trucks (Federal Register 2026-19964).
- [3] Owens Corning (Business Wire). (2026, April 30). Owens Corning Completes Sale of Glass Reinforcements Business to Praana Group. https://www.businesswire.com/news/home/20260430997267/en/Owens-Corning-Completes-Sale-of-Glass-Reinforcements-Business-to-Praana-Group
- [4] Envalior. (2026, May 21). New Tepex composite delivers identical performance with 50% lower carbon footprint. https://www.envalior.com/en-us/insights/press-release/new-tepex-composite-delivers-identical-performance-with-50-lower-carbon-footprint
- [5] UK Department for Transport. (2025, October 17). Updates to the Vehicle Emissions Trading Schemes (VETS) Order 2023. https://www.gov.uk/government/publications/vehicle-emissions-trading-schemes-vets-order-2023-updates/updates-to-the-vehicle-emissions-trading-schemes-vets-order-2023
- [6] Toray Industries, Inc. (2026, May 13). Announcement of Business Results for the Fiscal Year Ended March 2026 and Business Forecast for the Fiscal Year Ending March 2027. https://finance-frontend-pc-dist.west.edge.storage-yahoo.jp/disclosure/20260513/20260512525243.pdf
- [7] PlasticsToday. (2026, July 6). Syensqo Licenses Composite Forming Technology to Bucci. https://www.plasticstoday.com/automotive-mobility/syensqo-licenses-composite-forming-technology-to-bucci
- [8] DieselNet. (2025, December 17). EU Commission releases Automotive Package proposals. https://dieselnet.com/news/2025/12eu.php
- [9] SGL Carbon SE. (2026, August 6). Still on track to meet its 2026 annual targets (press release). https://www.sglcarbon.com/en/newsroom/news/press-report/still-on-track-to-meet-its-2026-annual-targets/
- [10] U.S. Department of Transportation, National Highway Traffic Safety Administration. (2026, September 30). The Safer Affordable Fuel-Efficient (SAFE) Vehicles Rule III for Model Years 2022 to 2031 Passenger Cars and Light Trucks (Federal Register 2026-19964). https://www.transportation.gov/regulations/federal-register-documents/2026-19964
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the automotive composites market during 2026?
- What market size is projected by 2036?
- Which material type holds notable share?
- Which resin holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Type, 2026 to 2036
- Glass Fiber
- Carbon Fiber
- Natural Fiber
- Aramid Fiber
- Others
- Y-o-Y Growth Trend Analysis By Material Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Interior
- Exterior
- Underbody
- Chassis
- Power Train
- Engine Components
- Structural Components
- Underbody Components
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Resin, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Resin, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Resin, 2026 to 2036
- Thermoplastic
- Thermoset
- Bio-Based
- Y-o-Y Growth Trend Analysis By Resin, 2021 to 2025
- Absolute $ Opportunity Analysis By Resin, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars
- LCV
- HCV
- Agricultural Vehicles
- Electric Vehicles
- Performance Vehicles
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- OEM Manufacturers
- Aftermarket
- Tier Suppliers
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- EU
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Type
- By Application
- By Resin
- By Vehicle Type
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Toray Industries
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- SGL Carbon
- Owens Corning
- Envalior
- Syensqo
- Teijin Limited
- Hexcel Corporation
- Huntsman Corporation
- Solvay
- BASF SE
- Gurit
- Mitsubishi Chemical Group
- Continental Structural Plastics
- Toray Industries
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Resin, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Resin, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Resin, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 19: Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Europe Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 21: Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 22: Europe Market Value (USD Billion) Forecast by Resin, 2021 to 2036
- Table 23: Europe Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 24: Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 25: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Middle East and Africa Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 27: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 28: Middle East and Africa Market Value (USD Billion) Forecast by Resin, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Material Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by Resin, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Resin, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Resin
- Figure 12: Global Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Vehicle Type
- Figure 15: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by End Use
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Material Type
- Figure 29: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Application
- Figure 32: North America Market Value Share and BPS Analysis by Resin, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Resin, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Resin
- Figure 35: North America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Vehicle Type
- Figure 38: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End Use
- Figure 41: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 42: Latin America Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Material Type
- Figure 45: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Application
- Figure 48: Latin America Market Value Share and BPS Analysis by Resin, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Resin, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Resin
- Figure 51: Latin America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Vehicle Type
- Figure 54: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by End Use
- Figure 57: Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 58: Europe Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 59: Europe Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 60: Europe Market Attractiveness Analysis by Material Type
- Figure 61: Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 62: Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 63: Europe Market Attractiveness Analysis by Application
- Figure 64: Europe Market Value Share and BPS Analysis by Resin, 2026 and 2036
- Figure 65: Europe Market Y-o-Y Growth Comparison by Resin, 2026-2036
- Figure 66: Europe Market Attractiveness Analysis by Resin
- Figure 67: Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 68: Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 69: Europe Market Attractiveness Analysis by Vehicle Type
- Figure 70: Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 71: Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 72: Europe Market Attractiveness Analysis by End Use
- Figure 73: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 74: Middle East and Africa Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 75: Middle East and Africa Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 76: Middle East and Africa Market Attractiveness Analysis by Material Type
- Figure 77: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 78: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 79: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 80: Middle East and Africa Market Value Share and BPS Analysis by Resin, 2026 and 2036
- Figure 81: Middle East and Africa Market Y-o-Y Growth Comparison by Resin, 2026-2036
- Figure 82: Middle East and Africa Market Attractiveness Analysis by Resin
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Vehicle Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 89: Global Market - Tier Structure Analysis
- Figure 90: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the automotive composites market expected in 2026?
As per Future Market Insights, market size is projected to reach USD 11.7 billion in 2026 and USD 37.4 billion by 2036. Market size was USD 10.4 billion in 2025.
What CAGR is projected for the automotive composites market through 2036?
As per FMI analysis, sales of automotive composites will grow at a CAGR of 12.3% from 2026 to 2036. Automaker lightweighting for EV range and emission targets, and the shift toward thermoplastics, support the outlook.
Which material type and resin hold a notable market share in 2026?
Material type sales are led by glass fiber composites at 56% in 2026, and thermoplastic resins account for 55% of resin sales.
Which application and vehicle type hold notable market shares in 2026?
Interior parts account for 30% of application sales in 2026. Passenger cars account for 65% of vehicle type sales.
Which country has a notable expansion outlook through 2036?
Fastest growth is projected for the USA at a CAGR of 13.6% from 2026 to 2036, according to FMI. Reshoring investment and EV platform expansion are the stated levers.
Who are the key companies in the automotive composites market?
Notable companies include Toray Industries, SGL Carbon, Teijin, Hexcel, Owens Corning, Huntsman, Solvay, BASF, Gurit, Mitsubishi Chemical Group, and Continental Structural Plastics.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
