
- Industry Size (2026)
- USD 9.00 Bn
- Forecast (2036)
- USD 14.11 Bn
- CAGR (2026 to 2036)
- 4.6%
How Big Is the Automotive Control Arm Assemblies Market in 2026?
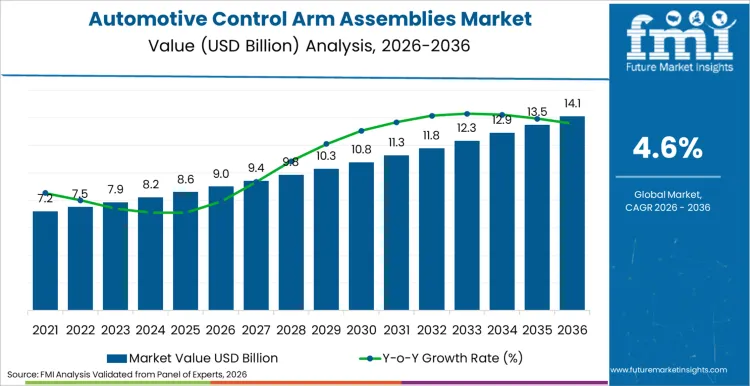
The global automotive control arm assemblies market is valued at USD 9.00 billion in 2026, up from USD 8.62 billion in 2025, and is projected by Future Market Insights (FMI) to reach USD 14.11 billion by 2036, expanding at a 4.6% CAGR from 2026 to 2036 and generating USD 5.11 billion in incremental revenue over the 10-year forecast period.
| Market Metric | Valuation / Share / Forecast Benchmark |
|---|---|
| 2025 Market Size (Historical) | USD 8.62 billion |
| 2026 Market Size (Estimated) | USD 9.00 billion |
| 2036 Market Size (Projected) | USD 14.11 billion |
| Compound Annual Growth Rate (2026 to 2036) | 4.6% CAGR |
| Incremental Dollar Opportunity (2026 to 2036) | USD 5.11 billion |
| Dominant Product Type (2026 to 2036 Share) | Steel control arms (64.3% in 2026, falling to 61.3% by 2036) |
| Leading & Fastest-Growing Variants | Passenger cars (42.1% share in 2026; 4.3% CAGR) | Battery electric vehicles (7.4% CAGR) |
| Leading & Fastest-Growing Channels | OEM fitment (71.0% share in 2026; 4.5% CAGR) | Aftermarket replacement (4.9% CAGR) |
| Largest Country Markets (2026 Global Share) | China (30.0%), United States (18.0%), Germany (9.0%) |
| Fastest-Growing Country Markets (2026 to 2036) | India (5.5% CAGR), China (5.3% CAGR), Germany (5.1% CAGR) |
| Leading Tier-1 Companies | ZF Friedrichshafen, Benteler, ILJIN, Raufoss Technology, Tenneco (DRiV) |
Source: Future Market Insights analysis of the automotive control arm assemblies market, 2026.
Executive Market Overview
Revenue from automotive control arm assemblies reaches USD 9.00 billion in 2026 and USD 14.11 billion by 2036, a 4.6% CAGR that adds USD 5.11 billion. The market covers upper and lower control arms, wishbones, trailing arms and integrated link assemblies with bushings and ball joints, in stamped steel, forged steel, forged or extruded aluminum and hybrid designs. Steel holds 64.3% of 2026 material value because it is cheap and durable across high volume platforms. Passenger cars account for 42.1% of demand, while SUVs, pickups and commercial vehicles make up much of the rest.
Aluminum is gaining ground as EV batteries add weight. ILJIN is investing about USD 100 million in an aluminum forging plant in Auburn, Alabama to make forged aluminum control arms for US automakers, and Raufoss started a fully automated aluminum control arm extrusion line in Suzhou in September 2025 to supply Li Auto, with output of 1.17 million units planned for 2026. Aftermarket demand stays steady as aging vehicles need replacement arms and ball joints. India grows fastest at a 5.5% CAGR, ahead of Germany at 5.1% and the USA at 4.2%. Scope excludes tie rods, stabilizer links sold alone and suspension knuckles.
Analyst Perspective
"Control arms are a commodity in steel but a design problem in aluminum, where forging and extrusion capacity close to vehicle plants decides awards. Suppliers that can offer both materials and handle heavier EV loads without adding mass will win the next platform cycle."
Nikhil Kaitwade, Principal Consultant, Future Market Insights (FMI)
Summary of Automotive Control Arm Assemblies Market
What is the growth outlook on the automotive control arm assemblies market? Future Market Insights projects the market to grow at a 4.6% CAGR from 2026 to 2036, expanding from USD 9.0 billion to USD 13.6 billion.
FMI research approach: Bottom-up automotive component revenue modeling, material cost analysis, vehicle production assessment, and suspension system performance evaluation.
How do FMI analysts perceive the automotive control arm assemblies market to evolve? The market is expected to move from basic stamped steel mechanisms toward advanced multi-material assemblies integrating lightweight construction and enhanced performance features.
FMI research approach: Material innovation trend analysis, suspension technology integration mapping, automotive performance demand assessment, and component durability benchmarking.
Which country holds the largest share in the automotive control arm assemblies market? China accounts for the largest global value share with a projected CAGR of 5.9%.
FMI research approach: Country-level production and consumption modeling, automotive industry concentration analysis, component sourcing evaluation, and manufacturing capacity assessment.
How large will the automotive control arm assemblies market be by 2036? The global market is forecast to reach USD 13.6 billion by 2036.
FMI research approach: Long-term forecasting by material type and application focus, demand scaling analysis, regional growth validation, and historical consumption patterns.
What is the market definition of automotive control arm assemblies? It covers suspension components designed for vehicle wheel positioning and steering control through precision-engineered mounting systems across various automotive applications.
FMI research approach: Product taxonomy validation, application scope mapping, material classification by vehicle category, and suspension mechanism functionality assessment.
What globally unique trends are shaping the automotive control arm assemblies market? Key trends include lightweight material adoption, precision manufacturing technology integration, and regulatory compliance advancement for vehicle safety applications.
FMI research approach: Technology adoption tracking, material science development analysis, regulatory requirement monitoring, and competitive innovation assessment.
Automotive Control Arm Assemblies Market Key Takeaways
| Metric | Value |
|---|---|
| Market Value (2026) | USD 9.0 billion |
| Market Forecast Value (2036) | USD 13.6 billion |
| Forecast CAGR (2026-2036) | 4.6% |
Source: Future Market Insights (FMI) analysis, based on proprietary forecasting model and primary research
What is Driving the Demand for Automotive Control Arm Assemblies?
Demand for automotive control arm assemblies is being propelled by the broad automotive industry shift toward enhanced vehicle dynamics and the escalating complexity of suspension systems requiring precision-engineered components. The increasing preference for improved handling characteristics in passenger vehicles, commercial trucks, and electric vehicles has amplified demand for high-performance suspension solutions that minimize weight while enhancing structural integrity and operational reliability.
The regulatory momentum toward vehicle safety standards, exemplified by updated IIHS guidelines for crashworthiness and NHTSA requirements for suspension component durability, is driving widespread adoption of enhanced control arm designs and safety-optimized suspension systems in automotive manufacturing workflows. Manufacturers are responding to these requirements through specialized design features that integrate compliance measures without compromising performance characteristics. The expanding electric vehicle market globally is shifting production toward lightweight, high-strength assemblies, underscoring a sustained demand trajectory rooted in performance optimization and energy efficiency requirements.
How is the Automotive Control Arm Assemblies Market Segmented?
The automotive control arm assemblies market has been segmented based on material type, vehicle type, and sales channel. In terms of material type, the market is divided into steel, aluminum, composite materials, and forged components. By vehicle type, the market includes passenger cars, commercial vehicles, electric vehicles, and performance vehicles. By sales channel, the market is segmented into OEM suppliers, aftermarket distributors, online retail, and direct sales. Regionally, the market spans North America, Europe, East Asia, South Asia, Latin America, and Middle East and Africa.
Why Do Steel Materials Dominate the Automotive Control Arm Assemblies Market?
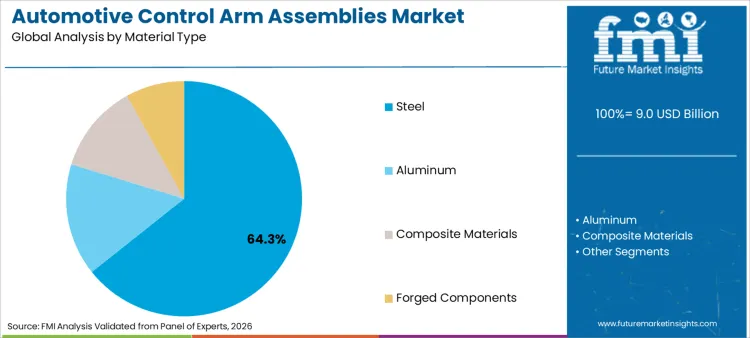
Steel materials continue to lead the market, accounting for 64.3% of the share, driven by their proven durability in automotive applications, cost-effectiveness, and adaptability to various vehicle platforms. This material type offers the strength needed for complex suspension loads while maintaining structural integrity across different operating conditions, making it essential for passenger car, commercial vehicle, and performance automotive applications. Steel assemblies provide manufacturers with design flexibility for custom specifications and performance requirements while supporting large-scale production demands.
Aluminum components capture a growing portion of the market, supporting lightweight vehicle design where reduced unsprung weight and enhanced fuel efficiency are critical factors. Composite materials remain popular for specific applications requiring weight reduction and corrosion resistance, particularly in electric vehicle and premium automotive segments where performance optimization and material innovation justify higher component costs.
How Do Vehicle Type Requirements Influence Control Arm Assembly Design Selection?
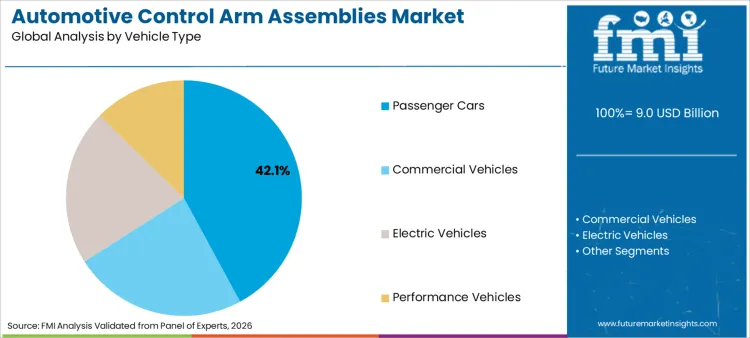
Passenger car applications stand as the dominant segment, commanding 42.1% of the market share. Automotive control arm assemblies remain centered on passenger vehicle applications due to the exceptional performance these components offer in handling optimization and ride quality enhancement. Passenger vehicles often require precise suspension geometry and extended service life protection, making control arm assemblies ideal for maintaining vehicle stability while ensuring comfort throughout the operational period.
The market is shaped by the development of vehicle-specific materials and enhanced manufacturing technologies that require rigorous testing to establish performance compliance and extended durability. Commercial vehicle applications demand specialized assemblies that integrate heavy-duty construction and enhanced load capacity to prevent component failure while ensuring reliable operation under demanding conditions. Companies are expanding their capabilities to address these specialized requirements. Advanced testing protocols help developers optimize component durability and ensure consistent performance across different vehicle platforms, making these validation services essential for automotive certification and market acceptance.
How Is Technological Evolution Reshaping Automotive Control Arm Assemblies?
The automotive control arm assemblies sector is shifting from traditional stamped steel mechanisms to integrated precision platforms that combine lightweight construction, enhanced durability, and improved performance characteristics. Strategic partnerships between component manufacturers and automotive suppliers are accelerating this transition toward more sophisticated suspension solutions. This evolution brings control arm assemblies closer to performance-grade standards by enabling more predictable handling characteristics and enhanced safety features using advanced engineering and material science innovations.
Improved assembly design reduces vehicle weight during production cycles and enhances driving satisfaction through smoother operation and consistent suspension performance. The ability to customize load characteristics and incorporate advanced mounting systems is reshaping vehicle development decisions, allowing manufacturers to address specific performance requirements while maintaining cost efficiency and manufacturing scalability.
How Is the Automotive Control Arm Assemblies Market Evolving Globally?
Global demand for automotive control arm assemblies is increasing as manufacturers expand vehicle portfolios while addressing performance requirements, weight optimization specifications, and regulatory compliance across passenger car, commercial vehicle, and electric vehicle applications. Growth demonstrates rising adoption of automated production systems, application-specific design positioning, and performance-optimized suspension mechanisms across automotive manufacturers, tier-1 suppliers, and component specialists. Design selection focuses on assembly reliability, cost efficiency, and regulatory compliance under various vehicle operating scenarios.
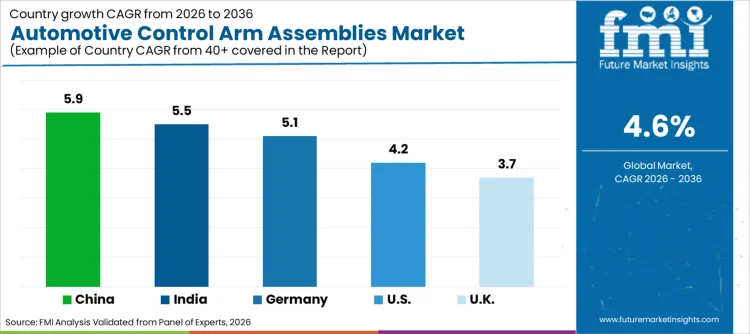
China records 5.9% CAGR, India records 5.5% CAGR, Germany records 5.1% CAGR, USA records 4.2% CAGR, and UK records 3.7% CAGR. Adoption remains driven by performance requirements and regulatory compliance rather than volume expansion alone.
| Country | CAGR (2026-2036) |
|---|---|
| China | 5.9% |
| India | 5.5% |
| Germany | 5.1% |
| USA | 4.2% |
| UK | 3.7% |
Source: FMI historical analysis and forecast data
China: How is Manufacturing Infrastructure Expansion Driving Market Growth?
The primary driver in China is the significant expansion of automotive manufacturing capabilities and automated production infrastructure. With the growth of domestic electric vehicle and commercial vehicle industries, Chinese manufacturing centers are experiencing substantial increases in suspension component demand, making traditional manufacturing methods insufficient for current production volumes. This has promoted advanced assembly technology adoption for domestic automotive manufacturing to ensure component quality and operational efficiency.
Driven by this national scale of manufacturing expansion, the Chinese automotive control arm assemblies market is set to grow at a 5.9% CAGR during the study period, led by massive demand in electric vehicle and commercial vehicle sectors. Over the next five years, the most significant opportunity lies in the integration of automated production systems with precision assembly mechanisms. As China targets leadership in automotive manufacturing, there is growing demand for cost-effective solutions that support complex vehicle platforms and high-volume production requirements.
India: Is the Automotive Industry Expansion Bolstering Component Standards?
In India, the market is dominated by the evolution toward premium component standards and performance-positioned automotive products. This quality-first approach is essential for Indian manufacturers competing with international brands in domestic automotive applications. The Indian automotive control arm assemblies market is projected to grow at a 5.5% CAGR during the study period.
Over the next five years, the rise of organized automotive retail and expanding middle-class vehicle ownership will necessitate high-quality suspension solutions for passenger cars and commercial vehicles. India's growing role as a manufacturing hub for global automotive brands creates opportunities for cost-effective assembly solutions that meet international quality standards while addressing local market preferences and price sensitivity requirements.
Germany: Will Engineering Excellence Drive Premium Assembly Adoption?
Germany's automotive control arm assemblies market is shaped by precision engineering capabilities and quality-focused manufacturing standards. German manufacturers are adopting advanced suspension technologies that integrate reliability assurance with innovative design features for premium market positioning. The German automotive control arm assemblies market is expected to grow at a 5.1% CAGR during the study period.
Over the next five years, opportunities exist in developing specialized assemblies for electric vehicle and premium automotive applications. As German companies maintain leadership in precision manufacturing, there is significant demand for assemblies that integrate advanced performance features, regulatory compliance, and premium functionality to serve both domestic and export markets effectively.
UK: How is the Electric Vehicle Transition Reinforcing the Demand for Advanced Control Arm Assemblies?
The growth of the automotive control arm assemblies market in the UK is primarily driven by a convergence of electric vehicle adoption and the rising popularity of performance-oriented suspension systems. As UK automotive manufacturers increasingly focus on electric vehicle production, brands are shifting toward lightweight suspension formats, such as aluminum control arms, composite assemblies, and advanced bushing systems, which rely on precision engineering to offer enhanced performance without the weight penalty of traditional steel components.
This trend is accelerated by stringent UK regulations like the Zero Emission Vehicle Mandate, pushing manufacturers to innovate with lightweight designs made from advanced alloys, integrated damping systems, or carbon fiber composites, thereby balancing performance requirements with weight reduction objectives. The UK automotive control arm assemblies market is set to grow at 3.7% CAGR during the study period.
The market is being propelled by the mainstream adoption of advanced suspension technologies, a sector no longer limited to premium vehicles but now expanding into mass-market electric cars, performance hybrids, and commercial electric vehicles. High-profile success stories have normalized the lightweight revolution, proving that consumers are willing to pay a premium for durable aluminum or composite control arm systems that enhance vehicle dynamics while supporting electrification goals. This shift is further supported by a demand for track-ready and performance-compliant formats, where precision-engineered, lightweight control arm assemblies offer enhanced handling characteristics, effectively merging regulatory compliance with high-performance vehicle dynamics.
USA: How is Innovation Leadership Shaping Premium Assembly Development?
The USA market focuses on innovation and specialized applications for performance automotive and commercial vehicle products. This approach emphasizes regulatory compliance and advanced functionality while maintaining competitive positioning in global markets. The USA automotive control arm assemblies market is set to grow at a 4.2% CAGR during the study period.
Over the next five years, opportunities lie in developing specialized assemblies for electric vehicles and premium automotive applications. As regulatory requirements become more stringent for automotive safety applications, there is growing demand for assemblies that integrate enhanced performance features, precise load characteristics, and advanced material functionality while maintaining manufacturing efficiency and cost competitiveness.
Who are the Major Players Active in the Automotive Control Arm Assemblies Market?
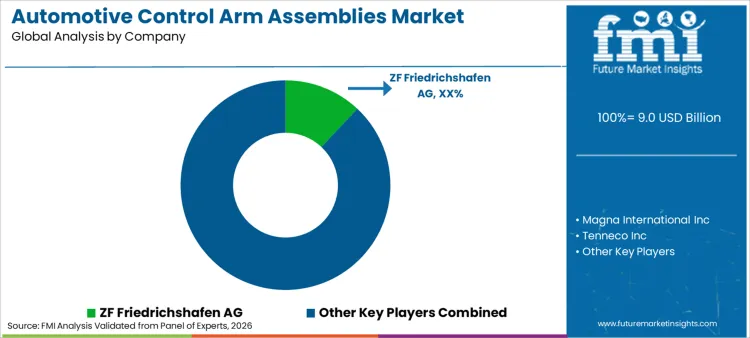
With automotive platforms becoming more sophisticated and performance requirements being more stringent, major players like ZF Friedrichshafen AG, Magna International Inc, and Tenneco Inc are competing on their ability to offer comprehensive suspension solutions that integrate assembly precision with regulatory compliance. These industry leaders are investing in advanced manufacturing technologies and material innovations to provide seamless integration capabilities, allowing automotive manufacturers to focus on vehicle development while outsourcing specialized suspension component requirements.
The market is observing distinct regional specialization in competitive strategy. While North American firms like Moog Inc and TRW Automotive Holdings maintain leadership through performance expertise and proximity to major automotive manufacturers, European players like ThyssenKrupp AG are advancing precision engineering and automated production capabilities. This has created an innovation cycle where suspension providers are diversifying into specialized applications such as electric vehicle assemblies and performance-optimized systems to address the complex requirements of premium and regulated automotive products.
Key Industry Developments:
- In April 2025, Tenneco LLC completed the previously announced strategic investment into its Clean Air and Powertrain businesses from Apollo Fund X, with American Industrial Partners (AIP) investing alongside.
- In June 2023, Magna acquired Veoneer Active Safety from SSW Partners.
Key Players in the Automotive Control Arm Assemblies Market
- ZF Friedrichshafen AG
- Magna International Inc
- Tenneco Inc
- Moog Inc
- TRW Automotive Holdings
- ThyssenKrupp AG
- Continental AG
- Benteler International AG
- Schaeffler Group
Market Definition
The automotive control arm assemblies market refers to the global automotive applications of specialized suspension components designed to support controlled wheel positioning and steering geometry through precision-engineered mounting systems. It includes both standard and performance assembly offerings, with segments that cater to various vehicle requirements such as passenger cars, commercial vehicles, and electric vehicles. The market size is measured in USD billion and analyzed over the 2026 to 2036 period.
The automotive control arm assemblies market includes suspension components categorized by material type, vehicle configuration, and sales channel, utilized through automotive manufacturing and aftermarket replacement applications. The market is expanding due to growing demand for enhanced vehicle dynamics, component innovation requirements, and evolving automotive preferences toward precision suspension control and reduced vehicle weight capabilities.
Market Inclusion
Included in the automotive control arm assemblies market scope are suspension components categorized by material type (steel, aluminum, composite materials, forged components), vehicle type (passenger cars, commercial vehicles, electric vehicles, performance vehicles), and sales channel (OEM suppliers, aftermarket distributors, online retail, direct sales). The scope includes suspension assemblies with focus on controlled performance, vehicle dynamics, and regulatory compliance, particularly those marketed through automotive manufacturers, tier-1 suppliers, and component specialists.
Geographically, the market encompasses key regions such as North America, Europe, East Asia, South Asia, Latin America, and the Middle East and Africa, with country-level analysis for significant markets like China, India, Germany, Brazil, USA, UK, and Japan.
Market Exclusion
Excluded from the automotive control arm assemblies market scope are non-suspension automotive components and parts not designed for vehicle wheel positioning, such as basic chassis brackets, steering components for non-suspension applications, and brake system assemblies. Additionally, components not intended for automotive suspension applications are not included.
The market excludes non-automotive suspension products, as well as components that are not marketed as control arm systems, such as shock absorbers or anti-roll bars. Products with non-compliant material specifications or those that do not meet regional safety standards for automotive applications are outside the market's defined scope.
Scope of the Report
| Items | Values |
|---|---|
| Quantitative Units | USD 9.0 billion |
| Material Type | Steel; Aluminum; Composite Materials; Forged Components |
| Vehicle Type | Passenger Cars; Commercial Vehicles; Electric Vehicles; Performance Vehicles |
| Sales Channel | OEM Suppliers; Aftermarket Distributors; Online Retail; Direct Sales |
| Regions Covered | North America, Europe, East Asia, South Asia, Latin America, Middle East & Africa |
| Countries Covered | China, India, Germany, Brazil, USA, UK, Japan, and 40+ countries |
| Key Companies Profiled | ZF Friedrichshafen AG; Magna International Inc; Tenneco Inc; Moog Inc; TRW Automotive Holdings; Others |
| Additional Attributes | Revenue analysis by material type and vehicle type; performance in automotive applications and dynamics capabilities across automotive manufacturers, tier-1 suppliers, and component specialists; suspension efficiency enhancement, vehicle dynamics optimization, and assembly reliability under various operating scenarios; impact on vehicle performance, driving satisfaction, and component differentiation during procurement processes; compatibility with vehicle platforms and automotive preferences; procurement dynamics driven by performance positioning, regulatory compliance programs, and long-term supply partnerships. |
Automotive Control Arm Assemblies Market by Segment
Material Type:
- Steel
- Aluminum
- Composite Materials
- Forged Components
Vehicle Type:
- Passenger Cars
- Commercial Vehicles
- Electric Vehicles
- Performance Vehicles
Sales Channel:
- OEM Suppliers
- Aftermarket Distributors
- Online Retail
- Direct Sales
Region:
- East Asia
- China
- Japan
- South Korea
- Taiwan
- Rest of East Asia
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- BENELUX
- Nordic
- Rest of Europe
- North America
- U.S.
- Canada
- Mexico
- South Asia
- India
- Australia & New Zealand
- Southeast Asia
- Rest of South Asia
- Latin America
- Brazil
- Chile
- Colombia
- Argentina
- Rest of Latin America
- Middle East & Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkey
- South Africa
- Other African Union
- Rest of Middle East & Africa
Bibliography
- AlCircle. (2024). ILJIN marks its foray into the aluminium forging market with new facility in Alabama. https://www.alcircle.com/news/iljin-marks-its-foray-into-the-aluminium-forging-market-with-new-facility-in-alabama-112151
- Hirschvogel. (2025, November 24). Impressive by performance, light by design: Hirschvogel Aluminium GmbH. https://www.hirschvogel.com/en/news-media/press/detail/impressive-by-performance-light-by-design-hirschvogel-aluminium-gmbh/
- SMM. (2025, September 22). Rofos aluminum profile control arm extrusion production line put into production. https://news.metal.com/newscontent/103540787-Rofos-aluminum-profile-control-arm-extrusion-production-line-put-into-production
- Tenneco. (2025, April 30). Tenneco announces completion of strategic investment to accelerate growth. https://tenneco.com/news-and-features/newsroom/current-news/2025/04/tenneco-announces-completion-of-strategic-investment-to-accelerate-growth
Table of Content
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
Read More...
- Market Background
- Market Dynamics
- Drivers
- Restraints
- Opportunity
- Trends
- Scenario Forecast
- Demand in Optimistic Scenario
- Demand in Likely Scenario
- Demand in Conservative Scenario
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter’s Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Market Dynamics
- Global Market Analysis 2021 to 2025 and Forecast, 2026 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis 2021 to 2025 and Forecast 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Material Type
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Material Type , 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Material Type , 2026 to 2036
- Steel
- Aluminum
- Composite Materials
- Forged Components
- Steel
- Y-o-Y Growth Trend Analysis By Material Type , 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type , 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Vehicle Type
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars
- Commercial Vehicles
- Electric Vehicles
- Performance Vehicles
- Passenger Cars
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Sales Channel
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM Suppliers
- Aftermarket Distributors
- Online Retail
- Direct Sales
- OEM Suppliers
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Region
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- Mexico
- By Material Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Material Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Material Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Material Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Material Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Material Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- Turkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Type
- By Vehicle Type
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Type
- By Vehicle Type
- By Sales Channel
- Competition Analysis
- Competition Deep Dive
- ZF Friedrichshafen AG
- Overview
- Product Portfolio
- Profitability by Market Segments (Product/Age /Sales Channel/Region)
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Magna International Inc
- Tenneco Inc
- Moog Inc
- TRW Automotive Holdings
- ThyssenKrupp AG
- Continental AG
- Benteler International AG
- Schaeffler Group
- ZF Friedrichshafen AG
- Competition Deep Dive
- Assumptions & Acronyms Used
- Research Methodology
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Material Type , 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Material Type , 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by Material Type , 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Material Type , 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Million) Forecast by Material Type , 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Material Type , 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Material Type , 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 29: Middle East & Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East & Africa Market Value (USD Million) Forecast by Material Type , 2021 to 2036
- Table 31: Middle East & Africa Market Value (USD Million) Forecast by Vehicle Type, 2021 to 2036
- Table 32: Middle East & Africa Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Material Type , 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Material Type , 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Material Type
- Figure 6: Global Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Vehicle Type
- Figure 9: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Sales Channel
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East & Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Material Type , 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Material Type , 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Material Type
- Figure 26: North America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Vehicle Type
- Figure 29: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Sales Channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Material Type , 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Material Type , 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Material Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Vehicle Type
- Figure 39: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Material Type , 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Material Type , 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Material Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Vehicle Type
- Figure 49: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Material Type , 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Material Type , 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Material Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Vehicle Type
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Material Type , 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Material Type , 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Material Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Vehicle Type
- Figure 69: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Material Type , 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Type , 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Material Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Vehicle Type
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 82: Middle East & Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East & Africa Market Value Share and BPS Analysis by Material Type , 2026 and 2036
- Figure 84: Middle East & Africa Market Y-o-Y Growth Comparison by Material Type , 2026-2036
- Figure 85: Middle East & Africa Market Attractiveness Analysis by Material Type
- Figure 86: Middle East & Africa Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 87: Middle East & Africa Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 88: Middle East & Africa Market Attractiveness Analysis by Vehicle Type
- Figure 89: Middle East & Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Middle East & Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Middle East & Africa Market Attractiveness Analysis by Sales Channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the automotive control arm assemblies market in 2026?
Future Market Insights estimates the global automotive control arm assemblies market at USD 9.00 billion in 2026, up from USD 8.62 billion in 2025.
How fast is the automotive control arm assemblies market expected to grow through 2036?
FMI projects a 4.6% CAGR from 2026 to 2036, taking the global automotive control arm assemblies market to USD 14.11 billion by 2036 and generating USD 5.11 billion in incremental revenue.
Which material leads the automotive control arm assemblies market?
Steel holds 64.3% of 2026 value because it is low cost and durable on high volume platforms. Forged and extruded aluminum gains share as automakers cut unsprung weight in EVs.
Which vehicle type leads the automotive control arm assemblies market?
Passenger cars account for 42.1% of 2026 demand, growing at a 4.3% CAGR. Battery electric vehicles grow fastest at a 7.4% CAGR because heavier packs need stronger, lighter arms.
Which sales channel leads the automotive control arm assemblies market?
OEM fitment represents 71.0% of 2026 value, growing at a 4.5% CAGR. Aftermarket replacement grows slightly faster at a 4.9% CAGR as the average vehicle age rises and bushings and ball joints wear out.
Which country is the largest automotive control arm assemblies market?
China leads the automotive control arm assemblies market, capturing 30.0% of global revenue in 2026 (USD 2.70 billion), followed by the United States at 18.0% (USD 1.62 billion) and Germany at 9.0% (USD 810.0 million).
Which countries are expected to grow fastest in the automotive control arm assemblies market?
India and China are projected to grow fastest, expanding at 5.5% and 5.3% CAGRs from 2026 to 2036, followed by Germany at 5.1%.
What drives demand for automotive control arm assemblies?
Drivers include global vehicle output, heavier electric vehicles that need stronger suspension parts, lightweighting targets that favor aluminum, and replacement demand from aging fleets. Restraints include steel and aluminum price swings, price pressure from automakers, tariff costs on imported parts, and low cost aftermarket imports of uneven quality.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
