

- Market Size (2026)
- USD 144.4 Mn
- Forecast (2036)
- USD 217.9 Mn
- CAGR (2026 to 2036)
- 4.2%
How big is Automotive Die Casting Lubricants Market in 2026?
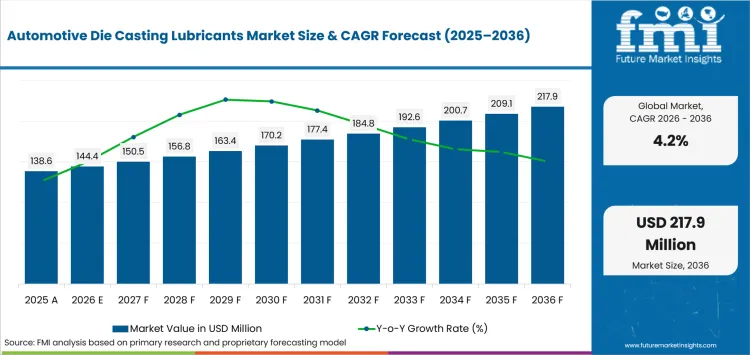
USD 144.4 million in 2026 and USD 217.9 million by 2036 at a 4.2% CAGR.
Demand for automotive die casting lubricants is projected to expand at 4.2% CAGR between 2026 and 2036, increasing valuation from USD 144.4 million in 2026 to USD 217.9 million by 2036. Commercial demand is tied to repeat-use casting cycles, where lubricant selection affects part release, die protection, spray control and the cost per accepted casting.
Electrified and lightweight vehicle programs increase the technical demands placed on aluminum die-casting cells. China produced 16.626 million new energy vehicles in 2025, according to the State Council Information Office. Larger housings and structural parts can increase die surface area and make release-film consistency more consequential, while suppliers still have to pass die-specific trials before a formulation enters recurring production.
Key Takeaways of Automotive Die Casting Lubricants Market
- Recurring demand follows casting shot volume because die-face release and plunger lubrication are consumed during normal automotive production rather than embedded once in the finished vehicle.
- Die-release Lubricants are projected at 72.0% share in 2026 because clean separation from the die is required across repeated casting cycles.
- Water-based formulations are estimated at 71.0% of carrier demand in 2026 owing to established dilution, cooling and automated spray practices.
- Aluminum is forecast at 78.0% of metal-cast demand in 2026 as powertrain, structural and electrified-vehicle parts sustain high-pressure casting activity.
- Die-specific qualification, spray settings and downstream residue requirements can slow supplier switching even when a lower-cost formulation is available.
- Quaker Houghton, FUCHS SE, Chem-Trend L.P., CONDAT Group, PETROFER Chemie H. R. Fischer GmbH + Co. KG, MotulTech, Henkel AG & Co. KGaA, Lubgraf Synoils Pvt. Ltd., MORESCO Corporation and Hardcastle Petrofer Private Limited serve the market through die-casting lubricants or related process support.
Analyst Perspective
"A die-casting lubricant earns repeat business when it lowers total cost per accepted casting without disturbing a validated process. Teams should test release stability, spray control and downstream cleanliness on the actual die before approving a supplier for recurring production."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the Automotive Die Casting Lubricants Market segmented?
The automotive die casting lubricants market is segmented by lubricant type, carrier, metal cast, die casting process, vehicle component and region.
Lubricant type separates die-face release products from plunger, ladle / tip and auxiliary lubricants. Carrier distinguishes water-based, oil-based and water-free / synthetic systems. Metal cast covers aluminum, magnesium and zinc. Die casting process includes high-pressure, low-pressure and gravity / other routes. Vehicle component covers powertrain, structural / body, chassis, EV components and others.
Why do water-based formulations account for 71.0% of the carrier category?
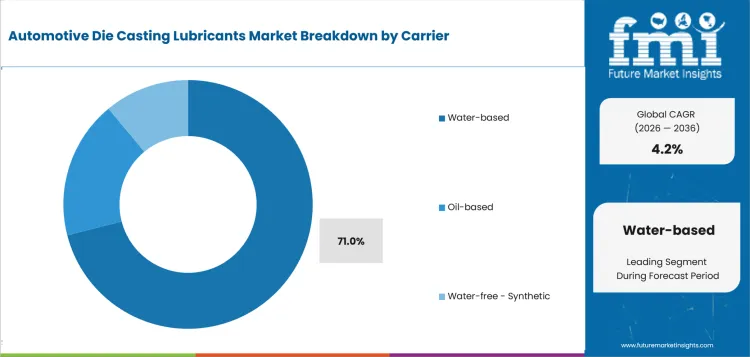
Water-based release agents fit established high-volume spray practices because dilution lets foundries tune concentration while water contributes cooling during application. The trade-off is tighter control of dilution, water quality and residual moisture. Chem-Trend states that water-based release agents are diluted for application and that concentration has to reflect casting complexity, die temperature and cooling requirements.
- Water-based formulations are estimated at 71.0% of carrier demand in 2026 because they align with established dilution and automated spray routines while contributing controllable cooling at the die surface.
- Chem-Trend notes that water-based die-release agents require controlled dilution because an unsuitable concentration can affect release quality and process stability.
Why do die-release Lubricants account for 72.0% of the lubricant type category?
Die-release chemistry acts at the interface where molten metal must separate cleanly from a hot die after every casting cycle. This repeated function links lubricant performance to line continuity, surface quality and die protection. FUCHS SE describes LUBRODAL products for die release alongside plunger lubrication, ladle protection, ejector lubrication and anti-soldering duties, showing the different operating roles within the casting cell.
- Die-release Lubricants are projected to account for 72.0% in 2026 because their die-face function is repeated through each casting cycle and directly affects part release.
- FUCHS SE documents die-release agents together with plunger lubricants, ladle coatings, ejector lubricants and anti-soldering products for die-casting operations.
Why does aluminum account for 78.0% of the metal cast category?
Aluminum supports recurring lubricant use across powertrain housings, structural parts and electrified-vehicle components produced through pressure casting. Its combination of low density and established automotive casting routes makes release-film stability important across high shot volumes. Quaker Houghton identifies engine blocks, e-motor housings, battery housings and shock towers among complex die-cast components addressed by integrated lubricant and process support.
- Aluminum is forecast at 78.0% of metal-cast demand in 2026 as automotive lightweighting and established high-pressure casting practices concentrate repeat-use lubricant demand around aluminum components.
- FUCHS documents water-miscible LUBRODAL products for pressure die casting of aluminum and other non-ferrous metals, while Quaker Houghton links its DieCast iQ platform with complex aluminum component programs.
Why does high-pressure account for 74.0% of the die casting process category?
High-pressure die casting combines rapid injection, elevated die temperature and repeated release requirements across thin-wall and complex geometries. Large structural castings increase die surface area and make film coverage or downstream cleanliness more sensitive. Chem-Trend and SurTec have highlighted structural components, giga casting, new aluminum alloys and microspray as connected process topics for automotive die casting.
- High-pressure die casting is projected at 74.0% of process demand in 2026 because rapid cyclic operation makes release and plunger lubrication central to throughput and part consistency.
- Chem-Trend and SurTec connect structural casting and microspray with downstream cleaning and passivation, showing why lubricant selection must fit the wider manufacturing process.
Why does powertrain account for 32.0% of the vehicle component category?
Powertrain programs create recurring lubricant demand through engine blocks, transmission housings and electrified-drive housings produced in repeated casting cycles. These parts must meet dimensional and porosity requirements, so lubricant changes are normally tested against the actual die and process settings. Quaker Houghton identifies engine blocks and e-motor housings among the components supported through its DieCast iQ approach.
- Powertrain is estimated at 32.0% of vehicle-component demand in 2026 because engine, transmission and e-drive housing programs sustain repeated lubricant consumption across established casting cells.
- Quaker Houghton identifies engine blocks and e-motor housings alongside battery housings and structural parts within its die-casting process-support portfolio.
What are the drivers, restraints and opportunities in the Automotive Die Casting Lubricants Market?
Lightweight casting programs support recurring lubricant use, while die-specific qualification and application control restrain switching as minimum-quantity and water-free systems create process-efficiency opportunities.
- Driver: Complex aluminum powertrain, structural and EV casting programs increase the number and technical intensity of lubricant-consuming die-casting cycles.
- Restraint: Lubricants must be qualified against each die and alloy, while spray pattern and downstream surface requirements make uncontrolled substitution costly.
- Opportunity: Minimum-quantity, water-free, microspray and electrostatic methods can reduce water handling or spray volume where repeatable application supports the process economics.
Automotive electrification changes the mix of cast parts even when total vehicle production is uneven. China produced 16.626 million new energy vehicles in 2025. Battery housings, e-motor housings and structural parts can increase the need for stable release films and controlled application on the casting lines that win these programs, although vehicle electrification is not a one-for-one measure of lubricant demand.
The main purchasing friction appears during qualification and line control. Chem-Trend states that release-agent dilution depends on part complexity, die temperature and cooling needs, while an unsuitable choice can contribute to sticking, rejection or downtime. Procurement therefore has to assess total process cost rather than concentrate price alone, which can extend switching cycles for validated lines.
The technical opening is to reduce water or lubricant applied per shot without weakening release reliability. Quaker Houghton documents water-free minimum-quantity systems that can reduce spray volume and avoid the effluent stream associated with conventional water-based products. Chem-Trend has also highlighted microspray as a route to more controlled application in structural and high-pressure casting environments.
Which country CAGRs are assessed in the Automotive Die Casting Lubricants Market?
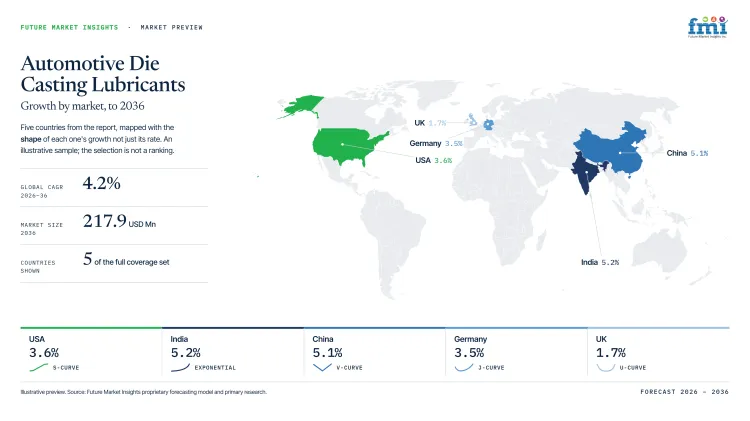
| Country | CAGR |
|---|---|
| USA | 3.6% |
| China | 5.1% |
| India | 5.2% |
| Germany | 3.5% |
| UK | 1.7% |
| Japan | 4.4% |
| Brazil | 4.9% |
How do country-level CAGRs compare in the Automotive Die Casting Lubricants Market?
The seven assessed CAGRs span 3.5 percentage points between 1.7% and 5.2% across automotive manufacturing systems with different casting intensity, investment cycles and supplier-access conditions. The spacing measures expected revenue expansion rather than current market size or installed die-casting capacity.
- India is forecast at 5.2%, 0.1 percentage point above China, as automotive investment and localization create more opportunities for qualified casting-process inputs.
- China records 5.1%, 0.2 percentage point above Brazil, with high new-energy-vehicle production increasing the importance of repeatable lubricant performance across scaled casting programs.
- Brazil is projected at 4.9%, 0.5 percentage point above Japan, supported by vehicle-production activity and preparation for more local hybrid and electric manufacturing.
- Japan is forecast at 4.4%, 0.8 percentage point above the USA, while established qualification practices keep process stability central to supplier selection.
- The USA records 3.6%, 0.1 percentage point above Germany, with a broad installed automotive manufacturing base supporting recurring die-casting lubricant use.
- Germany is projected at 3.5%, 1.8 percentage points above the UK, as electrified vehicle production sustains complex casting demand within a mature qualification environment.
- The UK is forecast at 1.7%, reflecting a slower expansion path during vehicle-production restructuring and model transitions.
Comparable CAGRs can produce different market-entry conditions. Supplier decisions therefore need to pair expected growth with active casting programs, component mix, local inventory, technical-service coverage and the cost of qualifying a formulation on production equipment.
Country-wise Analysis
- USA automotive die casters serve a broad installed manufacturing base and generally validate lubricants against individual lines or part programs. The USA market is forecast to expand at 3.6% CAGR from 2026 to 2036. SelectUSA reports that the country produced 10.6 million motor vehicles in 2024, indicating the scale of the downstream production system. Suppliers need local application support and documented total-cost gains when a process change could affect scrap or uptime.
- China combines high-volume automotive casting with rapid electrified-vehicle production, which raises the cost of spray inconsistency across scaled programs. The China market is forecast to expand at 5.1% CAGR from 2026 to 2036. The State Council Information Office reported 16.626 million new energy vehicles produced in 2025. Local technical coverage and repeatable dosing become important when larger housings or structural parts enter sustained production.
- India combines manufacturing investment with strong localization and operating-cost requirements. The India market is forecast to expand at 5.2% CAGR from 2026 to 2036. The Press Information Bureau reported in July 2026 that cumulative investment under the PLI scheme for Automobile and Auto Components reached INR 44,326 crore by March 31, 2026. Suppliers still have to prove value through consumption, scrap, maintenance or cycle economics on the customer's casting line.
- Germany operates within a mature automotive system where quality control and downstream surface compatibility carry substantial weight. The Germany market is forecast to expand at 3.5% CAGR from 2026 to 2036. VDA reported that Germany produced about 864,000 electric cars in the first half of 2025 and that electrified models represented 40% of passenger-car production. Engineering support matters because a lubricant change can alter residue, release behavior or validated process settings.
- UK purchasing conditions are shaped by a smaller production base moving through plant restructuring and electrified-model transitions. The UK market is forecast to expand at 1.7% CAGR from 2026 to 2036. SMMT reported 764,715 vehicles produced in 2025, down 15.5% from the prior year. Suppliers need to focus on active casting programs and demonstrate operating savings without adding qualification risk.
- Japan emphasizes long-run process stability, which makes dependable qualification and technical channels important for repeat orders. The Japan market is forecast to expand at 4.4% CAGR from 2026 to 2036. METI has stated a policy target for all new passenger-vehicle sales to be electrified by 2035. Advanced release methods therefore need to show stable cycle economics alongside compatibility with established production practices.
- Brazil is developing vehicle production while preparing for more domestic hybrid and electric manufacturing. The Brazil market is forecast to expand at 4.9% CAGR from 2026 to 2036. ANFAVEA reported 2.644 million vehicles produced in 2025 and indicated that additional domestic hybrid and electric production was expected during 2026. Local supply and responsive technical service remain important where manufacturers are sensitive to per-part operating cost.
Who are the notable companies in the Automotive Die Casting Lubricants Market?
Quaker Houghton, FUCHS SE, Chem-Trend L.P., CONDAT Group, PETROFER Chemie H. R. Fischer GmbH + Co. KG, MotulTech, Henkel AG & Co. KGaA, Lubgraf Synoils Pvt. Ltd., MORESCO Corporation and Hardcastle Petrofer Private Limited are notable companies serving the automotive die casting lubricants market.
Competition separates by lubricant breadth, application method and the depth of support available during die-specific qualification. Integrated process-fluid suppliers can cover die-face, plunger and auxiliary needs, while specialist providers compete through release chemistry or minimum-quantity application methods. Local service and inventory can matter as much as corporate reach when a casting line requires a controlled trial or rapid troubleshooting.
- Integrated die-casting fluid and process-support platforms include Quaker Houghton, FUCHS SE, CONDAT Group and PETROFER Chemie H. R. Fischer GmbH + Co. KG.
- Release-agent and application specialists include Chem-Trend L.P., MotulTech, Henkel AG & Co. KGaA and MORESCO Corporation.
- India-centered formulation and service suppliers include Lubgraf Synoils Pvt. Ltd. and Hardcastle Petrofer Private Limited
Competitive Benchmarking: Automotive Die Casting Lubricants Market
| Company | Die-casting Lubricant Breadth | Advanced Method | Process-support Integration | Geographic Reach |
|---|---|---|---|---|
| Quaker Houghton | High | High | High | Global; operations in more than 25 countries |
| FUCHS SE | High | Medium | Medium | Global; major automotive manufacturing regions |
| Chem-Trend L.P. | Medium | High | Medium | Global; Americas, Europe and Asia |
| CONDAT Group | High | Medium | High | Europe-centered with international industrial distribution |
| PETROFER Chemie H. R. Fischer GmbH + Co. KG | High | High | Medium | Europe, Asia, the Americas and other industrial markets |
| MotulTech | Medium | High | High | Industrial products marketed in 60 countries |
| Henkel AG & Co. KGaA | Medium | Medium | Unscored | Global |
| Lubgraf Synoils Pvt. Ltd. | Medium | Unscored | Unscored | India-centered |
| MORESCO Corporation | High | High | Medium | Japan, North America and Asia |
| Hardcastle Petrofer Private Limited | High | Unscored | Medium | India-centered |
Key Developments in the Automotive Die Casting Lubricants Market
- In February 2025, FUCHS LUBRICANTS SOUTH AFRICA detailed its LUBRODAL die-casting solution set, including AL 75, AL 100 and AL 125 together with plunger lubrication, ladle protection, ejector lubricants and anti-soldering products.
- In November 2024, MORESCO Corporation announced CoatMap, a smartphone application designed to help measure the applied film thickness of its MQ-W minimum-quantity die-release agent.
- In October 2024, Motul acquired Chem Arrow Corp., adding industrial lubricant and metalworking-fluid capabilities to a group whose MotulTech products were marketed across 60 countries.
Key Players in the Automotive Die Casting Lubricants Market
Integrated Die-casting Fluid and Process-support Platforms
- Quaker Houghton
- FUCHS SE
- CONDAT Group
- PETROFER Chemie H. R. Fischer GmbH + Co. KG
Release-agent and Application Specialists
- Chem-Trend L.P.
- MotulTech
- Henkel AG & Co. KGaA
- MORESCO Corporation
India-centered Formulation and Service Suppliers
- Lubgraf Synoils Pvt. Ltd.
- Hardcastle Petrofer Private Limited
Automotive Die Casting Lubricants Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By lubricant type, carrier, metal cast, die casting process, vehicle component and region. |
| Quantitative Units | Revenue in USD million and CAGR in %. |
| Market Definition | Revenue from automotive die-casting lubricants sold for die-release, plunger, ladle / tip and other auxiliary lubrication in automotive die-casting operations. Finished cast components, vehicles, die-casting equipment, non-automotive die-casting lubricants and adjacent fluids outside the stated scope are excluded. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | USA, China, India, Germany, UK, Japan, Brazil and 20+ countries included in the full report. |
| Key Companies | Quaker Houghton, FUCHS SE, Chem-Trend L.P., CONDAT Group, PETROFER Chemie H. R. Fischer GmbH + Co. KG, MotulTech, Henkel AG & Co. KGaA, Lubgraf Synoils Pvt. Ltd., MORESCO Corporation and Hardcastle Petrofer Private Limited |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Automotive Die Casting Lubricants Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from lubricant manufacturers, distributors, technical-service teams, die-casting operators, automotive procurement teams and subject-matter experts. Interviews examined product qualification, purchasing criteria, operating barriers, pricing considerations and the evidence required before a trial becomes recurring line use. |
| Desk Research | Desk research covered government production data, industry-association publications, company filings, product information, technical literature and official corporate announcements. Sources were reviewed for relevance, publication date and consistency with the stated automotive die-casting lubricant boundary. |
| Market Sizing and Forecasting | The market model combined the baseline value with segment structure, casting-process intensity, lubricant consumption behavior, automotive component mix, supplier participation and country demand conditions. Forecast assumptions considered manufacturing investment, vehicle-program changes, qualification cycles, application technology and barriers to wider adoption. |
| Data Validation | Estimates were checked against independent indicators including automotive production data, supplier activity, technical product coverage and country manufacturing developments. Validation excluded duplicate revenue, finished die-cast component value, unrelated metalworking fluids and activities outside the market definition. |
Automotive Die Casting Lubricants Market by Segments
Automotive Die Casting Lubricants Market segmented by Lubricant Type:
- Die-release Lubricants
- Plunger Lubricants
- Ladle / Tip Lubricants
- Other Auxiliary Lubricants
Automotive Die Casting Lubricants Market segmented by Carrier:
- Water-based
- Oil-based
- Water-free / Synthetic
Automotive Die Casting Lubricants Market segmented by Metal Cast:
- Aluminum
- Magnesium
- Zinc
Automotive Die Casting Lubricants Market segmented by Die Casting Process:
- High-pressure
- Low-pressure
- Gravity / Other
Automotive Die Casting Lubricants Market segmented by Vehicle Component:
- Powertrain
- Structural / Body
- Chassis
- EV Components
- Others
Automotive Die Casting Lubricants Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Chile
- Mexico
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- State Council Information Office. (2026, January 14). China's auto output, sales reach new highs in 2025.
- Press Information Bureau, Government of India. (2026, July 21). PLI Scheme for Automobile and Auto Components and Battery Storage.
- VDA. (2025, August 4). Electric car production at record levels in first half of the year.
- Society of Motor Manufacturers and Traders. (2026, January 29). Tough year for Auto but new models and Industrial Strategy can deliver growth.
- International Trade Administration. (n.d.). SelectUSA Automotive Industry.
- Agency for Natural Resources and Energy, METI. (2024, June 24). Subsidies Upgraded for the Purchase of Clean Energy Vehicles toward the Realization of GX in the Automobile Sector.
- ANFAVEA. (2026, January 15). Produção e venda de autoveículos crescem em 2025 e Anfavea projeta nova alta em 2026.
- Quaker Houghton. (2025, March 28). Water-based, Water-free and Electrostatic die release lubricants for High Pressure Die Casting.
- Quaker Houghton. (2022, April 13). DieCast iQ - Intelligent die casting solutions from Quaker Houghton.
- FUCHS LUBRICANTS SOUTH AFRICA. (2025, February 11). FUCHS LUBRICANTS offers complete solutions for the die casting industry.
- Chem-Trend L.P. (2025, January 15). How to Choose the Right Die Casting Release Agent for Your Production Needs.
- Chem-Trend L.P. and SurTec. (2023, November 30). Chem-Trend and SurTec at Euroguss 2024.
- Motul. (2024, October 16). Motul Acquires Chem Arrow Corp.
- MORESCO Corporation. (2024, November 20). CoatMap minimum-quantity die-release film-thickness measurement application announcement.
- CONDAT Group. (n.d.). Die casting lubricants and lubricant solutions for die casting.
- PETROFER. (n.d.). Die Casting.
- Henkel Adhesives. (n.d.). BONDERITE L-CA CP 503.
- Lubgraf Synoils Pvt. Ltd. (n.d.). Die Casting Lubricants.
- Hardcastle Petrofer Private Limited (n.d.). Die Casting Lubricants.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How is recurring demand tied to automotive die-casting cycle intensity?
- Which operating conditions shape release-agent qualification across dies and alloys?
- How does carrier choice affect spray control and water handling?
- Why does aluminum casting shape lubricant formulation requirements?
- How do high-pressure casting requirements affect supplier selection?
- How do country manufacturing conditions change qualification and service needs?
- Which supplier capabilities matter during process trials and recurring production?
- Which application methods can reduce water or spray volume without weakening release reliability?
Frequently Asked Questions
How big is the Automotive Die Casting Lubricants Market in 2026?
USD 144.4 million represents the automotive die casting lubricants market value in 2026. The market is forecast to reach USD 217.9 million by 2036 as recurring die-release, plunger and auxiliary lubricant demand follows automotive casting activity and process qualification.
What is the CAGR of the Automotive Die Casting Lubricants Market from 2026 to 2036?
A 4.2% CAGR is projected for the automotive die casting lubricants market between 2026 and 2036. Growth depends on casting shot volume, aluminum component programs, qualification cycles and adoption of application methods that improve process control.
Which lubricant type segment is projected to account for 72.0% of the Automotive Die Casting Lubricants Market?
Die-release Lubricants are projected to account for 72.0% of lubricant-type demand in 2026. Their recurring die-face role links formulation performance directly with part separation, die condition and line continuity.
How much will the Automotive Die Casting Lubricants Market add between 2026 and 2036?
USD 73.5 million is expected to be added to the automotive die casting lubricants market between 2026 and 2036. The increase reflects recurring process-fluid demand rather than the value of finished castings or vehicles.
Which companies are active in the Automotive Die Casting Lubricants Market?
Quaker Houghton, FUCHS SE, Chem-Trend L.P., CONDAT Group, PETROFER Chemie H. R. Fischer GmbH + Co. KG, MotulTech, Henkel AG & Co. KGaA, Lubgraf Synoils Pvt. Ltd., MORESCO Corporation and Hardcastle Petrofer Private Limited are active through die-release products, plunger lubrication, casting-cell fluids or related process support.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Lubricant Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Lubricant Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Lubricant Type, 2026 to 2036
- Die-release Lubricants
- Plunger Lubricants
- Ladle - Tip Lubricants
- Other Auxiliary Lubricants
- Die-release Lubricants
- Y-o-Y Growth Trend Analysis By Lubricant Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Lubricant Type, 2026 to 2036
- Global Market Analysis and Forecast, By Carrier, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Carrier, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Carrier, 2026 to 2036
- Water-based
- Oil-based
- Water-free - Synthetic
- Water-based
- Y-o-Y Growth Trend Analysis By Carrier, 2021 to 2025
- Absolute $ Opportunity Analysis By Carrier, 2026 to 2036
- Global Market Analysis and Forecast, By Metal Cast, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Metal Cast, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Metal Cast, 2026 to 2036
- Aluminum
- Magnesium
- Zinc
- Aluminum
- Y-o-Y Growth Trend Analysis By Metal Cast, 2021 to 2025
- Absolute $ Opportunity Analysis By Metal Cast, 2026 to 2036
- Global Market Analysis and Forecast, By Die Casting Process, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Die Casting Process, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Die Casting Process, 2026 to 2036
- High-pressure
- Low-pressure
- Gravity - Other
- High-pressure
- Y-o-Y Growth Trend Analysis By Die Casting Process, 2021 to 2025
- Absolute $ Opportunity Analysis By Die Casting Process, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Vehicle Component, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Vehicle Component, 2026 to 2036
- Powertrain
- Structural - Body
- Chassis
- EV Components
- Others
- Powertrain
- Y-o-Y Growth Trend Analysis By Vehicle Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Component, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- By Country
- Market Attractiveness Analysis
- By Country
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- By Country
- Market Attractiveness Analysis
- By Country
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- By Country
- Market Attractiveness Analysis
- By Country
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- By Country
- Market Attractiveness Analysis
- By Country
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- By Country
- Market Attractiveness Analysis
- By Country
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- By Country
- Market Attractiveness Analysis
- By Country
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- By Country
- Market Attractiveness Analysis
- By Country
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Lubricant Type
- By Carrier
- By Metal Cast
- By Die Casting Process
- By Vehicle Component
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Quaker Houghton
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- FUCHS SE
- Chem-Trend L.P.
- CONDAT Group
- PETROFER Chemie H.R. Fischer GmbH + Co. KG
- MotulTech
- Henkel AG & Co. KGaA
- Lubgraf Synoils Pvt. Ltd.
- MORESCO Corporation
- Hardcastle Petrofer Pvt. Ltd.
- Quaker Houghton
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


