

- Market Size (2026)
- USD 282989.3 Mn
- Forecast (2036)
- USD 443697.4 Mn
- CAGR (2026 to 2036)
- 4.6%
How big is Automotive Electronics Market in 2026?
Demand for automotive electronics will grow at a CAGR of 4.6% from 2026 to 2036, according to FMI. Market size was USD 270,544.3 million in 2025 and is projected to reach USD 282,989.3 million in 2026 and USD 443,697.4 million by 2036.
Demand for automotive electronics will grow at a CAGR of 4.6% from 2026 to 2036. Market size stood at USD 270,544.3 million in 2025, is estimated at USD 282,989.3 million in 2026 and is projected to reach USD 443,697.4 million by 2036.
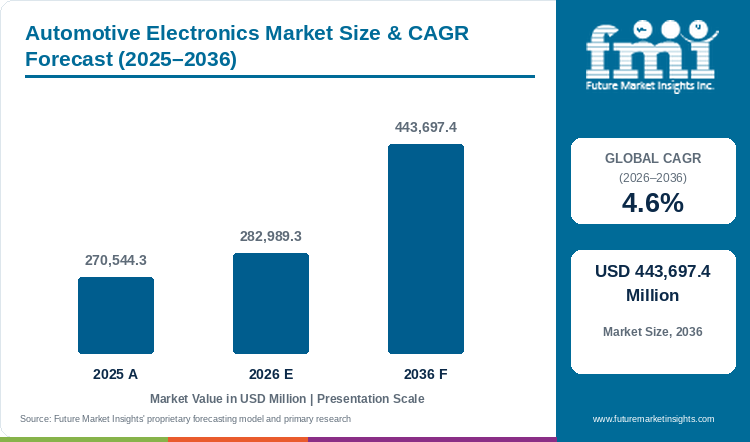
Safety regulation is the clearest trend. NHTSA requested comments on 28 May 2026 on adding rear automatic braking with pedestrian avoidance to the recommended ADAS technologies[1]. Each feature on the list needs cameras, radar and control units, so ADAS content per car will rise as rules widen. A longer list will pull features from premium models into mid-priced cars.
Chip supply and cost pressure on vehicle makers are the challenges. Suppliers need to qualify sensors and software for each new rule, and long approval cycles will slow launches.
Electric vehicles and domain controllers are the opportunities, as both will raise electronics content per car. Tier-one suppliers with ADAS software and sensor fusion capability will hold the largest share of added sales, and smaller suppliers will partner with them to reach vehicle programmes. Growth at a moderate pace suits a market of this size, and content per car will add to sales in every year of the forecast.
Key Market Trends & Insights
- By application, ADAS led the market with a share of 32.6% in 2026, supported by safety regulation. NHTSA requested comments on 28 May 2026 on adding rear automatic braking with pedestrian avoidance to recommended ADAS technologies.[1]
- By vehicle type, passenger cars accounted for 69.5% of sales in 2026 across compact, mid-size, luxury and SUV models. UK battery electric cars took a 28.3% share of September 2026 registrations.[2]
Regional Highlights
- Fastest-growing profiled country: USA (4.8% CAGR, 2026 to 2036).
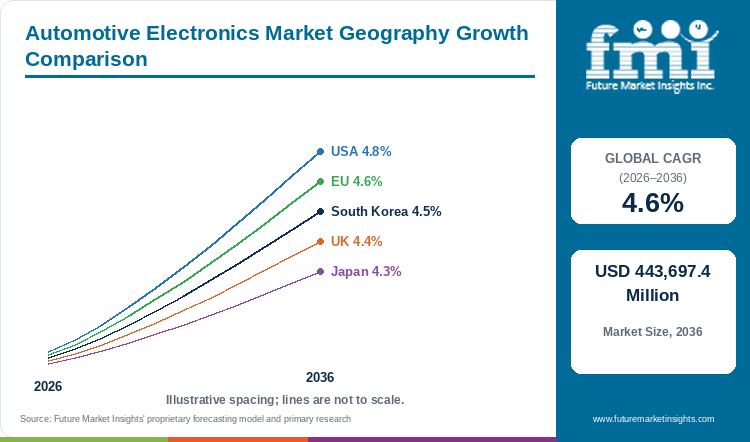
- By country: the EU (4.6%) and South Korea (4.5%) follow, with the UK at 4.4% and Japan recording the lowest profiled CAGR at 4.3%.
- UK new car registrations rose 12% to 350,536 units in September 2026, SMMT reported.[2]
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive Electronics Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 270,544.3 million |
| Projected Market Size in 2026 | USD 282,989.3 million |
| Projected Market Size by 2036 | USD 443,697.4 million |
| CAGR, 2026 to 2036 | 4.6% |
| Added Revenue, 2026 to 2036 | USD 160,708.1 million |
| Market Expansion Multiple | 1.6x |
Sales of automotive electronics follow the powertrain mix, since every powertrain carries control units and sensors. Allegro MicroSystems states that internal combustion powertrains are expected to persist for the foreseeable future, either as standalone systems or as part of hybrid electric vehicles.[3] Hybrid platforms keep combustion engines in service, which ties electronics to the automotive turbocharger market. As per FMI, vehicles carry more than 100 million lines of code, and software-associated recalls rose 22% globally in 2023. Suppliers with power, sensing and software content across several powertrains face steadier demand than suppliers tied to one powertrain.
Electronics Content per Vehicle by Powertrain
Content per vehicle in the automotive electronics market is not set by vehicle volume alone. Powertrain, safety rules and architecture decide the number of motors, sensors and chips on each model. Company filings show higher content on electrified models, and combustion and hybrid models continue to carry control units and sensors.
Table 2: Electronics Content Indicators by Powertrain for the Automotive Electronics Market (units, percentage and company statements), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Battery electric vehicle production, 2025 | 14.5 million units, against 11.3 million units in 2024 | Electric drive adds power and battery electronics to each vehicle. | [4] |
| Lear content statement | Electrification of the vehicle powertrain adds significant content per vehicle for Lear products | A supplier links electrified drive to higher content. | [4] |
| NXP semiconductor statement | Increasing penetration of electrified vehicles, which have much higher semiconductor content | Chip content is higher on electrified models. | [5] |
| NXP regulation statement | Semiconductor content per vehicle continues to increase due to government regulation of safety and emissions | Rules widen content across powertrains. | [5] |
| Aptiv investor day, November 2025 | Supporting transition from ICE to HEV/PHEV to BEV, requiring higher power, high voltage solutions | Electrified drive needs high-voltage electronics. | [6] |
| Allegro MicroSystems 10-K, fiscal 2026 | xEVs require a growing number of motors for pumps, fans and safety-critical systems | More motors raise demand for motor control and sensing. | [3] |
| Bosch SiC chips, April 2026 | Third generation with 20% higher performance; over 60 million SiC chips delivered since 2021 | Power semiconductors for electric vehicles are scaling. | [7] |
| UK registrations, September 2026 | Battery electric 28.3%, plug-in hybrid 17%, hybrid 13.1% | Several powertrains share the market and carry electronics. | [2] |
Analyst Perspective
“Electronics content per vehicle is expected to rise fastest on models that add electric drive, driver assistance and zonal computing. Suppliers with power, sensing and software positions across several powertrains are likely to hold the steadiest growth through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Automotive Electronics Market segmented?
The automotive electronics market is segmented into application and vehicle type, and region. In 2026, ADAS holds 32.6% of application sales and passenger cars hold 69.5% of vehicle type sales.
By application: ADAS, body electronics, infotainment and entertainment, powertrain, and safety systems.
By vehicle type: passenger cars, light commercial vehicles, and heavy commercial vehicles.
By region: North America, Latin America, Europe, Asia Pacific, and Middle East and Africa.
Why does ADAS lead application sales?
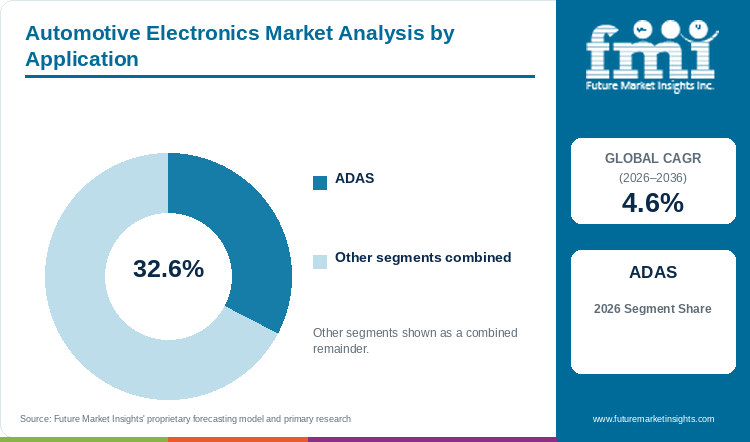
ADAS accounts for 32.6% of application sales in 2026, supported by safety regulation.
Table 3: Application Share for the Automotive Electronics Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| ADAS | 32.6% |
| Body Electronics | 22.0% |
| Infotainment and Entertainment | 15.5% |
| Powertrain | 17.0% |
| Safety Systems | 12.9% |
| Total | 100.0% |
Table 4: Application Leadership and Market Growth for the Automotive Electronics Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.6% |
| Leading Segment | ADAS |
ADAS leads application sales at 32.6% in 2026. As per FMI, over 58% of newly registered cars worldwide carry at least one Level 1 ADAS feature. NHTSA requested comments on 28 May 2026 on adding rear automatic braking with pedestrian avoidance to the recommended ADAS technologies.[1] Hyundai Motor Group put the Data Flywheel into full operation on 13 September 2026 and targets NVIDIA-based Level 2+ production vehicles in the first half of 2028.[8] Federal standards and carmaker programs tie ADAS sales to dated rule and launch schedules, so suppliers track those dates closely.
- ADAS sales in Europe have almost hit 70%, as per the FMI report.
- Sensing intensity per system is increasing, Allegro MicroSystems states.[3]
Why do passenger cars form the largest vehicle category?
Passenger cars account for 69.5% of vehicle type sales in 2026, spanning compact, mid-size, luxury and SUV models.
Passenger car electronics lead vehicle type sales at 69.5% in 2026. UK battery electric cars took a 28.3% share of 350,536 registrations in September 2026.[2] The IEA reported on 20 May 2026 that global electric car sales fell by 8% in the first quarter of 2026 following policy changes in China and the United States, while European sales increased by close to 30% over the same period.[9] Sealing and bonding of sensor and controller housings links vehicle electronics to the silicone adhesives and sealants market. Electrified share differs by market, so electronics content per car follows local registrations.
- Compact, mid-size, luxury and SUV models make up the passenger car category.
- Light commercial and heavy commercial vehicles complete the vehicle type split.
What are the drivers, restraints, and opportunities in the Automotive Electronics Market?
In the automotive electronics market, electrification, safety rules and software-defined platforms drive sales, software complexity and chip supply constrain growth, and zonal computing opens the principal commercial opportunity.
- Driver: Electrification, safety regulation and connected services raise electronics content per vehicle.
- Restraint: Software integration complexity and semiconductor supply disruption slow platform launches.
- Opportunity: Zonal controllers, centralized computing and wider ADAS fitment widen content per vehicle.
Electrification and Safety Rules Raise Content
Key drivers of the automotive electronics market begin with electrified drive. Allegro MicroSystems states that xEVs require a growing number of motors to support pumps, fans and safety-critical systems.[3] Traction and auxiliary motors link demand to the magnetic materials market. Bosch announced on 22 April 2026 the start of third-generation silicon carbide chips with 20% higher performance, after delivering more than 60 million SiC chips since 2021.[7] NXP adds that semiconductor content per vehicle continues to increase due to government regulation of safety and emissions.[5] Electrified drive and safety rules together set the largest share of added content per vehicle.
Software Complexity and Chip Supply Limit Growth
Key challenges in the automotive electronics market lie in software and supply. As per the FMI report, the chip shortage between 2021 and 2023 had a drastic impact on the timely delivery of ADAS and infotainment systems, and EV power electronics such as IGBTs and SiC modules face long lead times. Lear reported that the adoption of electrified vehicles has been slower than anticipated, particularly in the United States.[4] Slower adoption in one region delays electronics content tied to electric drive there. Supply security and software testing set platform launch timing in the early forecast years.
Zonal Architectures Open the Opportunity
Zonal and centralized computing draw attention across carmakers. Aptiv called zonal architectures the north star for most OEMs at the investor day on 18 November 2025.[6] Lear points to the transition to zone-based vehicle electrical architectures.[4] Adaptive headlamps that reshape beams to driving conditions need cameras, sensors and controllers, which links the market to the adaptive front lighting market. Average North American spending on in-vehicle digital content rose 26% in 2023, as per FMI. Carmakers that adopt zonal computing open new content for software and power distribution suppliers.
Which country CAGRs are profiled in the Automotive Electronics Market?
Table 5: Country CAGR Comparison for the Automotive Electronics Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| USA | 4.8% |
| EU | 4.6% |
| South Korea | 4.5% |
| UK | 4.4% |
| Japan | 4.3% |
How do country-level CAGRs compare in the Automotive Electronics Market?
Growth across the five profiled countries differs owing to safety rules, electrification pace and vehicle mix. As per the analysis from FMI, the USA is projected at 4.8% CAGR from 2026 to 2036, followed by the EU at 4.6% and South Korea at 4.5%. The UK is estimated at 4.4%, and Japan is projected at 4.3%. The gap between the USA and Japan is 0.5 percentage points.
- The USA pairs ADAS fitment and EV powertrain electronics with federal safety standards.
- The EU combines safety and emissions mandates with control unit and battery management content.
- South Korea links EV battery and drive control electronics to government technology policy and local chipmaker support.
- UK sales draw on compact-car safety and body modules, a connected car roadmap and the ADAS retrofit aftermarket.
- Japan links hybrid and regenerative braking electronics to radar, lidar and camera development.
The full report profiles country CAGRs across North America, Latin America, Europe, Asia Pacific, and Middle East and Africa.
Country-wise Analysis
USA Automotive Electronics Market Outlook (2026 to 2036)
Federal safety rules and hybrid demand shape the US electronics base. NHTSA requested comments on 28 May 2026 on adding rear automatic braking with pedestrian avoidance to the recommended ADAS technologies.[1] On 27 August 2026, BluE Nexus, AISIN and DENSO announced a two-motor hybrid drive module for the new Jeep Cherokee, with the inverter made by DENSO Manufacturing Tennessee.[10] Bosch is investing up to USD 1.9 billion to transform its Roseville, California facility for silicon carbide semiconductor production, supported by USD 225 million in funding from the U.S. Department of Commerce announced in July 2026. Lear reported that adoption of electrified vehicles has been slower than anticipated, particularly in the United States.[4] The USA is projected at 4.8% CAGR from 2026 to 2036, with ADAS and premium infotainment as key demand drivers.
Key takeaway: US growth of 4.8% draws on safety rule changes and hybrid electronics built in Tennessee, with slower battery electric adoption as the counterweight.
EU Automotive Electronics Market Outlook (2026 to 2036)
The EU is projected at 4.6% CAGR from 2026 to 2036, with safety and emissions mandates and V2X on EU-wide platforms as growth drivers. The IEA reported that sales in Europe increased by close to 30% year-on-year.[9] Aptiv lists a slower transition in North America and Europe on the software-defined architecture slide.[6] Bosch makes third-generation SiC chips on 200-millimeter wafers in Reutlingen, Germany.[7] European buyers therefore pair fast electrified demand with a cautious move to new architectures.
Key takeaway: EU growth of 4.6% pairs strong electric car sales with a slower move to software-defined architectures.
South Korea Automotive Electronics Market Outlook (2026 to 2036)
Hyundai Motor Group put the Data Flywheel into full operation at 42dot headquarters in Gyeonggi Province on 13 September 2026.[8] The group targets NVIDIA-based Level 2+ production vehicles in the first half of 2028 and Level 2++ in the second half of 2028.[8] Hyundai Motor and Kia sell more than 7 million vehicles annually across approximately 190 countries and regions worldwide.[8] EV battery and drive control electronics and local chipmaker support boost growth, and South Korea is projected at 4.5% CAGR from 2026 to 2036.
Key takeaway: South Korea at 4.5% CAGR is shaped by one carmaker group, so the Hyundai launch schedule for 2028 sets the pace for ADAS electronics.
UK Automotive Electronics Market Outlook (2026 to 2036)
UK new car registrations rose 12% to 350,536 units in September 2026, and battery electric cars took a 28.3% share.[2] The year-to-date battery electric share of 26.2% is significantly below the 33% mandated for 2026.[2] Plug-in hybrids held 17% and hybrids 13.1% of the month.[2] Compact cars with cost-efficient safety and body modules, a connected car roadmap and an ADAS retrofit aftermarket shape UK demand, and the country is projected at 4.4% CAGR from 2026 to 2036.
Key takeaway: UK growth of 4.4% draws on a mixed powertrain base, and the gap to the 33% mandate keeps hybrid and combustion electronics in demand.
Japan Automotive Electronics Market Outlook (2026 to 2036)
Hybrid powertrain and regenerative braking electronics lead demand in Japan, which is projected at 4.3% CAGR from 2026 to 2036, the lowest of the five profiled countries. DENSO, with AISIN and BluE Nexus, announced a two-motor hybrid drive module for the Jeep Cherokee on 27 August 2026, and the module supports the expansion of hybrid electric vehicles in the North American market.[10] Allegro MicroSystems states that internal combustion powertrains are expected to persist, as standalone systems or as part of hybrids.[3] Denso holds an estimated 10% to 13% share of the automotive electronics market. Radar, lidar and camera development and a crash prevention focus complete the Japanese picture.
Key takeaway: Japan records the lowest profiled CAGR at 4.3%, and hybrid drive modules for North America are the growth channel to watch.
Who are the notable companies in the Automotive Electronics Market?
Bosch, Continental, Denso, Aptiv, ZF, Valeo, Hitachi Astemo, Panasonic Automotive Systems, Mitsubishi Electric, Infineon, Texas Instruments, NXP, Analog Devices, Visteon, and Renesas are notable companies profiled in this market.
Bosch leads automotive electronics company shares at 14% to 18%, followed by Continental at 11% to 15%, Denso at 10% to 13%, Aptiv at 6% to 9% and ZF at 5% to 8%, as per FMI. Other companies together hold 40% to 50%. Companies differ by powertrain exposure. Bosch is introducing third-generation SiC chips, Denso supplies the inverter in a North American hybrid module, and Aptiv positions high-voltage and zonal solutions. Suppliers with power, sensing and compute content reach more platforms per carmaker, and single-function suppliers compete on price.
- Leading share-estimate suppliers: Bosch, Continental, Denso, Aptiv, and ZF.
- Other key suppliers: Valeo, Hitachi Astemo, Panasonic Automotive Systems, Mitsubishi Electric, Infineon, Texas Instruments, NXP, Analog Devices, Visteon, and Renesas.
- Suppliers with documented activity in 2025 and 2026: Bosch, Denso, Aptiv, NXP, Lear, and Allegro MicroSystems.
Competitive Benchmarking: Automotive Electronics Market
Table 6: Competitive Benchmarking for the Automotive Electronics Market (qualitative documentation ratings), 2026
| Company | Electrification | Sensing | Architecture | Disclosure |
|---|---|---|---|---|
| Bosch | High | Low | Low | Medium |
| Denso | High | Low | Low | Medium |
| Aptiv | High | Low | High | High |
| NXP | Medium | Medium | High | High |
| Lear | High | Low | High | High |
| Allegro MicroSystems | High | High | Low | High |
High indicates wider documentation in company filings and releases, Medium indicates limited documentation, and Low indicates less direct documentation. Ratings do not indicate product quality, market share or company rank.
Key Developments in the Automotive Electronics Market
- In October 2026, SMMT reported UK September registrations of 350,536 units, with battery electric cars at a 28.3% share.[2]
- In September 2026, Hyundai Motor Group put the Data Flywheel into full operation at 42dot headquarters, with NVIDIA-based Level 2+ production targeted for the first half of 2028.[8]
- In August 2026, BluE Nexus, AISIN and DENSO announced a two-motor hybrid drive module installed in the new Jeep Cherokee.[10]
- In May 2026, NHTSA requested comments on adding rear automatic braking with pedestrian avoidance to recommended ADAS technologies.[1]
- In April 2026, Bosch announced the start of third-generation SiC chips with 20% higher performance.[7]
Key Players in the Automotive Electronics Market
Leading Share-estimate Suppliers
- Robert Bosch GmbH
- Continental AG
- Denso Corporation
- Aptiv PLC
- ZF Friedrichshafen AG
Other Key Suppliers
- Valeo
- Hitachi Astemo
- Panasonic Automotive Systems
- Mitsubishi Electric
- Infineon Technologies
- Texas Instruments
- NXP Semiconductors
- Analog Devices
- Visteon
- Renesas Electronics
Suppliers with Documented 2025 to 2026 Activity
- Lear Corporation
- Allegro MicroSystems
Automotive Electronics Market - Report Scope
Table 7: Report Scope for the Automotive Electronics Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Application; vehicle type; region |
| Quantitative units | USD million |
| Market segmentation | Electronic systems fitted to passenger cars and commercial vehicles, tracked by application and vehicle type. |
| Regions covered | North America; Latin America; Europe; Asia Pacific; Middle East and Africa |
| Countries covered | USA; EU; South Korea; UK; Japan |
| Key companies profiled | Bosch, Continental, Denso, Aptiv, ZF, Valeo, Hitachi Astemo, Panasonic Automotive Systems, Mitsubishi Electric, Infineon, Texas Instruments, NXP, Analog Devices, Visteon, Renesas |
| Forecast period | 2026 to 2036 |
Automotive Electronics Market - Research Methodology
Table 8: Research Methodology for the Automotive Electronics Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Market sizes, segment shares, country CAGRs and company shares are drawn from the forecast model. Supplier and regulation facts come from company filings, press releases, regulator notices and trade bodies dated May 2025 or later. |
| Desk Research | Desk research covers company filings, official press releases, regulator notices and registration releases on powertrain mix, ADAS and vehicle architecture. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base market size of USD 270,544.3 million and the 4.6% CAGR. |
| Data Validation | Supplier and regulation facts are tested against at least one dated filing, notice or release. |
Automotive Electronics Market by Segments
Automotive Electronics Market segmented by Application:
- ADAS
- Body Electronics
- Infotainment and Entertainment
- Powertrain
- Safety Systems
Automotive Electronics Market segmented by Vehicle Type:
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
Automotive Electronics Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Europe
- Germany
- Italy
- France
- United Kingdom
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- Middle East and Africa
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] National Highway Traffic Safety Administration (Federal Register). (2026, May 28). New Car Assessment Program. https://www.federalregister.gov/documents/2026/05/28/2026-10611/new-car-assessment-program
- [2] SMMT. (2026, October 5). Record electric car market powers bumper September. https://www.smmt.co.uk/record-electric-car-market-powers-bumper-september/
- [3] Allegro MicroSystems, Inc. (SEC Form 10-K). (2026). Annual Report on Form 10-K for the fiscal year ended March 27, 2026. https://www.sec.gov/Archives/edgar/data/866291/000119312526233537/algm-20260327.htm
- [4] Lear Corporation (SEC Form 10-K). (2026). Annual Report on Form 10-K for the fiscal year ended December 31, 2025. https://www.sec.gov/Archives/edgar/data/842162/000084216226000011/lear-20251231.htm
- [5] NXP Semiconductors N.V. (SEC Form 10-K). (2026). Annual Report on Form 10-K for the fiscal year ended December 31, 2025. https://www.sec.gov/Archives/edgar/data/1413447/000141344726000008/nxpi-20251231.htm
- [6] Aptiv PLC. (2025, November 18). Aptiv 2025 Investor Day Presentation. https://s21.q4cdn.com/440699111/files/doc_presentations/2025/11/24/Aptiv-2025-Investor-Day-Presentation-FINAL.pdf
- [7] Robert Bosch GmbH. (2026, April 22). A leap in semiconductor efficiency: Bosch introduces third generation of SiC chips. https://www.bosch-presse.de/pressportal/de/en/a-leap-in-semiconductor-efficiency-bosch-introduces-third-generation-of-sic-chips-282432.html
- [8] Hyundai Motor Group. (2026, September 13). Hyundai Motor Group Accelerates Autonomous Driving Innovation with AI-Powered Data Flywheel. https://www.hyundai.com/worldwide/en/newsroom/detail/0000001273
- [9] International Energy Agency. (2026, May 20). Close to 30% of cars sold this year are set to be electric as countries and consumers respond to energy crisis. https://www.iea.org/news/close-to-30-of-cars-sold-this-year-are-set-to-be-electric-as-countries-and-consumers-respond-to-energy-crisis
- [10] DENSO Corporation. (2026, August 27). Newly Developed "Two-Motor Hybrid Drive Module" Adopted for STELLANTIS New "Jeep Cherokee". https://www.denso.com/global/en/newsroom/news/2026/20260827-g01
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the automotive electronics market during 2026?
- What market size is projected by 2036?
- Which application holds notable share?
- Which vehicle type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the Automotive Electronics Market expected in 2026?
Future Market Insights projects automotive electronics market size to reach USD 282,989.3 million in 2026. Market size is projected to reach USD 443,697.4 million by 2036, reflecting steady growth over the forecast period.
What CAGR is projected for the Automotive Electronics Market through 2036?
As per FMI analysis, automotive electronics sales are projected to grow at a 4.6% CAGR from 2026 to 2036. Electrification, safety regulation and software-defined platforms support demand.
Which application holds a notable market share?
ADAS accounts for 32.6% of application sales in 2026. Safety regulation supports the leading position.
Which vehicle type holds a notable market share?
Passenger cars account for 69.5% of vehicle type sales in 2026, spanning compact, mid-size, luxury and SUV models.
Which country has a notable expansion outlook through 2036?
The USA is projected to record the fastest growth at 4.8% CAGR from 2026 to 2036, according to FMI. Federal safety standards, ADAS and EV powertrain electronics drive US demand.
Who are the key companies in the Automotive Electronics Market?
Notable companies include Bosch, Continental, Denso, Aptiv, ZF, Valeo, Hitachi Astemo, Panasonic Automotive Systems, Mitsubishi Electric, Infineon, Texas Instruments, NXP, Analog Devices, Visteon, and Renesas.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- ADAS
- Body Electronics
- Infotainment and Entertainment
- Powertrain
- Safety Systems
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Application
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Vehicle Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- By Application
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Vehicle Type
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- Italy
- France
- United Kingdom
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- By Application
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Vehicle Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Application
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Vehicle Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- EU
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Vehicle Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Application
- By Vehicle Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Bosch
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Denso
- Aptiv
- NXP
- Lear
- Allegro MicroSystems
- Robert Bosch GmbH
- Continental AG
- Denso Corporation
- Aptiv PLC
- ZF Friedrichshafen AG
- Valeo
- Hitachi Astemo
- Panasonic Automotive Systems
- Mitsubishi Electric
- Infineon Technologies
- Texas Instruments
- NXP Semiconductors
- Analog Devices
- Visteon
- Renesas Electronics
- Lear Corporation
- Bosch
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


